

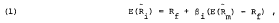
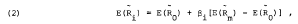
 = expected rate of return on asset i,
 = expected return on the market portfolio,
 = expected return on any “zero-beta” asset or portfolio of such assests, and
 = relative risk of asset i in the market portfolio of assests.

Crossref Citations

This article has been cited by the following publications. This list is generated based on data provided by Crossref.
Luce, Fernando Bins
and
Moraes Jr., Jorge Queiroz de
1979.
O modelo de formação de preços de ativos: (capital asset pricing model) teoria e evidência.
Revista de Administração de Empresas,
Vol. 19,
Issue. 4,
p.
31.
Friend, Irwin
and
Westerfield, Randolph
1981.
Risk and capital asset prices.
Journal of Banking & Finance,
Vol. 5,
Issue. 3,
p.
291.
Elgers, Pieter
Hill, Joanne M
and
Schneeweis, Thomas
1982.
Research design for systematic risk prediction.
The Journal of Portfolio Management,
Vol. 8,
Issue. 3,
p.
43.
Fried, Dov
and
Givoly, Dan
1982.
Financial analysts' forecasts of earnings.
Journal of Accounting and Economics,
Vol. 4,
Issue. 2,
p.
85.
Pari, Robert A.
and
Chen, Son‐Nan
1984.
AN EMPIRICAL TEST OF THE ARBITRAGE PRICING THEORY.
Journal of Financial Research,
Vol. 7,
Issue. 2,
p.
121.
Sinclair, N.A.
1987.
Multifactor Asset Pricing Models.
Accounting & Finance,
Vol. 27,
Issue. 1,
p.
17.
Calvet, A.L.
and
Lefoll, J.
1988.
RISK AND RETURN ON CANADIAN CAPITAL MARKETS.
Canadian Journal of Administrative Sciences / Revue Canadienne des Sciences de l'Administration,
Vol. 5,
Issue. 1,
p.
1.
Klemkosky, Robert C.
and
Resnik, Bruce G.
1989.
An analysis of variance test for linearity of the two-parameter asset pricing model.
Journal of Economics and Business,
Vol. 41,
Issue. 4,
p.
265.
Guo, Hui
and
Qiu, Buhui
2009.