
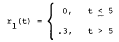

Hostname: page-component-7b7567c8c-kwt9d Total loading time: 0 Render date: 2026-11-14T03:39:19.742Z Has data issue: false hasContentIssue false

A Note on Modeling Simple Dynamic Cash Balance Problem: Errata

Published online by Cambridge University Press:  06 April 2009

Extract

In [2], I gave a solution of an extended cash balance problem which disallows overdrafts and shortselling. This solution is incorrect. To show this, we produce a counterexample constructed by Carl Norstrøm. In the notation of the note [2], let x0 = 0, y0 = 3, d(t) = 0, α = 0, T = 10, M1 = M2 = ∞

and r2 (t) = .1. Applying the procedure in [2] to this problem, we obtain the policy of impulse-selling all the securities at t = 0. On the other hand, it is obvious by inspection that the optimal policy is to keep the securities until t = 5, at which time, turn them into cash by an impulse-sale. We note, in passing, that the solution by inspection in this case is possible because there is no bounds on the control variable.

Information

Type
Research Article
Copyright
Copyright © School of Business Administration, University of Washington 1978

Access options

Get access to the full version of this content by using one of the access options below. (Log in options will check for institutional or personal access. Content may require purchase if you do not have access.)

Article purchase

Temporarily unavailable