

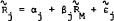
 is return on a market index, and
 is the company-specific component of return such that
 and
 . The coefficient β
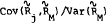 . It is known as market responsiveness, volatility, systematic risk, and, more commonly, simply as “beta.” It has been widely accepted as a measure of nondiversifiable risk and incorporated in popular performance measures. Many stock information services now provide estimates of beta.

Crossref Citations

This article has been cited by the following publications. This list is generated based on data provided by Crossref.
ALEXANDER, GORDON J.
STOVER, ROGER D.
and
KUHNAU, DAVID B.
1979.
Market Timing Strategies in Convertible Debt Financing.
The Journal of Finance,
Vol. 34,
Issue. 1,
p.
143.
Chance, Don M.
and
Lane, William R.
1980.
A RE‐EXAMINATION OF INTEREST RATE SENSITIVITY IN THE COMMON STOCKS OF FINANCIAL INSTITUTIONS.
Journal of Financial Research,
Vol. 3,
Issue. 1,
p.
49.
Foster, George
1981.
Intra-industry information transfers associated with earnings releases.
Journal of Accounting and Economics,
Vol. 3,
Issue. 3,
p.
201.
Wardrep, Bruce N.
and
Buck, James F.
1982.
The efficacy of hedging with financial futures: A historical perspective.
Journal of Futures Markets,
Vol. 2,
Issue. 3,
p.
243.
Lee, Cheng F.
1984.
Random coefficient and errors-in-variables models for beta estimates: Methods and applications.
Journal of Business Research,
Vol. 12,
Issue. 4,
p.
505.
Booth, James R.
Officer, Dennis T.
and
Henderson, Glenn V.
1985.
Commercial bank stocks, interest rates, and systematic risk.
Journal of Economics and Business,
Vol. 37,
Issue. 4,
p.
303.
Booth, James R.
and
Officer, Dennis T.
1985.
EXPECTATIONS, INTEREST RATES, AND COMMERCIAL BANK STOCKS.
Journal of Financial Research,
Vol. 8,
Issue. 1,
p.
51.
Yagil, Joseph
1986.
Growth, Risk and the Yield On Common Stocks In the Context of the Dividend‐Growth Model.
Journal of Business Finance & Accounting,
Vol. 13,
Issue. 2,
p.
251.
Scott, William L.
and
Peterson, Richard L
1986.
INTEREST RATE RISK AND EQUITY VALUES OF HEDGED AND UNHEDGED FINANCIAL INTERMEDIARIES.
Journal of Financial Research,
Vol. 9,
Issue. 4,
p.
325.
Martin, John D.
and
Keown, Arthur J.
1987.
One-bank holding company formation and the 1970 Bank Holding Company Act Amendment.
Journal of Banking & Finance,
Vol. 11,
Issue. 2,
p.
213.
Johnson, Larry J.
Brick, John R.
and
Price, Kelly
1987.
The interest rate sensitivity of equity prices with respect to systematic risk and leverage.
Journal of Business Research,
Vol. 15,
Issue. 1,
p.
85.
Kane, Edward J.
and
Unal, Haluk
1988.
Change in market assessments of deposit-institution riskiness.
Journal of Financial Services Research,
Vol. 1,
Issue. 3,
p.
207.
Chen, Carl R.
and
Chan, Anthony
1989.
Interest Rate Sensitivity, Asymmetry, and the Stock Returns of Financial Institutions.
Financial Review,
Vol. 24,
Issue. 3,
p.
457.
Fraser, Donald R.
and
Kolari, James W.
1990.
THE 1982 DEPOSITORY INSTITUTIONS ACT AND SECURITY RETURNS IN THE SAVINGS AND LOAN INDUSTRY.
Journal of Financial Research,
Vol. 13,
Issue. 4,
p.
339.
KANE, EDWARD J.
and
UNAL, HALUK
1990.
Modeling Structural and Temporal Variation in the Market's Valuation of Banking Firms.
The Journal of Finance,
Vol. 45,
Issue. 1,
p.
113.
Bae, Sung C.
1990.
INTEREST RATE CHANGES AND COMMON STOCK RETURNS OF FINANCIAL INSTITUTIONS: REVISITED.
Journal of Financial Research,
Vol. 13,
Issue. 1,
p.
71.
Kyle, Steven C.
and
Wirick, Ronald G.
1990.
The impact of sovereign risk on the market valuation of U.S. bank equities.
Journal of Banking & Finance,
Vol. 14,
Issue. 4,
p.
761.
Gordon, D. A.
Gordon, M. J.
and
Gould, L. I.
1990.
The Interest Rate Component of Systematic Risk.
Journal of Accounting, Auditing & Finance,
Vol. 5,
Issue. 4,
p.
573.
Choi, Dosoung
and
Jen, Frank C.
1991.
The relation between stock returns and short-term interest rates.
Review of Quantitative Finance and Accounting,
Vol. 1,
Issue. 1,
p.
75.
Ehrhardt, Michael C.
1991.
Diversification and Interest Rate Risk.
Journal of Business Finance & Accounting,
Vol. 18,
Issue. 1,
p.
43.