

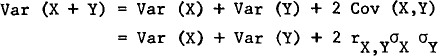 where rX, Y is the correlation coefficient of X, Y, and −1 ≤ rX, Y ≤ 1.

Crossref Citations

This article has been cited by the following publications. This list is generated based on data provided by Crossref.
Müller, Horst
1970.
Portfolio Selection als Entscheidungsmodell deutscher Investmentgesellschaften.
p.
33.
Barth, James
Kraft, John
and
Wiest, Philip
1975.
A PORTFOLIO THEORETIC APPROACH TO INDUSTRIAL DIVERSIFICATION AND REGIONAL EMPLOYMENT*.
Journal of Regional Science,
Vol. 15,
Issue. 1,
p.
9.
Cáceres, Luis René
1979.
Economic integration and export instability in central America: A portfolio model.
The Journal of Development Studies,
Vol. 15,
Issue. 3,
p.
141.
Pastore, Mario H.
1988.
Mean-variance analysis of portfolios of dependent investments: An extension.
Journal of Economics and Business,
Vol. 40,
Issue. 2,
p.
147.
Emel, Ahmet Burak
Oral, Muhittin
Reisman, Arnold
and
Yolalan, Reha
2003.
A credit scoring approach for the commercial banking sector.
Socio-Economic Planning Sciences,
Vol. 37,
Issue. 2,
p.
103.
Fernandes, Mário
2017.