



No CrossRef data available.
Article contents
Natural extensions of probability measure in function space
Published online by Cambridge University Press: 09 April 2009
Extract
Core share and HTML view are not available for this content. However, as you have access to this content, a full PDF is available via the 'Save PDF' action button.
Let {Xt}t ∈ T be a family of real (R) random variable defined on a probability space (Ω, A P) and having the ranges in a subset S of R, that is, Xt (Ω) ⊂ S for all t. Let X be the mapping of Ω into the function space St such that for any ω ∈ Ω
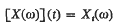 We shall write X = {Xt}t ∈ T and call X the random fundtion arising from {Xt}t ∈ T. It is well-known that any finite subfamily of {Xt}t∈T induces a “finite joint distribution” in ST, and according to Kolmogorov (1933) these finite joint distributions can be simultaneously extended to a probability measure Po on the Borel class Bo of subsets of ST. This extension is natural in the sense that for any B∈B0P0(B) turns out to be exactly P[X−1(B)]. The Kolmogorov extension Po has however a shortcoming in that its domain B0 is not broad enough to include many events of practical interest.
Information
- Type
- Research Article
- Information
- Copyright
- Copyright © Australian Mathematical Society 1975
References
Doob, J. L. (1947), ‘Probability in function space’, Bull. Amer. Math. Soc. 53, 15–30.CrossRefGoogle Scholar
Doob, J. L. (1937), ‘Stochastic processes depending on continuous parameter, Trans. Amer. Math. Soc. 42, 107–140.CrossRefGoogle Scholar
Shizuo, Kakutani (1943), Notes on infinite product spaces II, Proc. Imp. Acad. Tokto 19, 184–188.Google Scholar
Kolmogorov, A. (1933), (Grundbegriffe der Wahrscheinlichkeitsrechnung, Springer Berlin).CrossRefGoogle Scholar
Nelson, Edward (1959), Regular probability mesaures on function space, Ann. of Math. (2) 69, 630–643.CrossRefGoogle Scholar
 You have Access