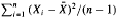
Hostname: page-component-7b7567c8c-z4zkx Total loading time: 0 Render date: 2026-11-16T18:03:22.409Z Has data issue: false hasContentIssue false

Normal characterization by zero correlations

Published online by Cambridge University Press:  09 April 2009

Eugene Seneta
Affiliation:
School of Mathematics and Statistics University of SydneyNSW 2006Australia e-mail: eseneta@maths.usyd.edu.au
Gabor J. Szekely
Affiliation:
Department of Mathematics and Statistics Bowling Green State UniversityBowling Green OH 43403USA e-mail: gabors@bgnet.bgsu.edu
Rights & Permissions [Opens in a new window]

Abstract

Core share and HTML view are not available for this content. However, as you have access to this content, a full PDF is available via the 'Save PDF' action button.

Suppose Xi, i = 1,…,n are indepedent and identically distributed with E/X1/r < ∞, r = 1,2,…. If Cov (( − μ)r, S2) = 0 for r = 1, 2,…, where μ = EX1, S2 = , and , then we show X1 ~ N (μ, σ2), where σ2 = Var(X1). This covariance zero condition charaterizes the normal distribution. It is a moment analogue, by an elementary approach, of the classical characterization of the normal distribution by independence of and S2 using semi invariants. More generally, if Cov = 0 for r = 1,…, k, then E((X1 − μ)/σ)r+2 = EZr+2 for r = 1,… k, where Z ~ N(0, 1). Conversely Corr may be arbitrarily close to unity in absolute value, but for unimodal X1, Corr2( < 15/16, and this bound is the best possible.

Information

Type
Research Article
Copyright
Copyright © Australian Mathematical Society 2006
