


1. Introduction
Persistent inflation is difficult to explain with nominal rigidities alone whenever an inelastic real input also serves as a speculative store of value. Urban land has that property: it enters firms’ cost structure through rents, affects wage formation through housing costs, and attracts portfolio demand when households view it as protection against future inflation. These two roles—productive input and inflation hedge—create a bidirectional feedback that standard New Keynesian models miss. When inflation expectations rise, households reallocate portfolios toward land, raising land prices (Brunnermeier and Julliard Reference Brunnermeier and Julliard2008); higher land prices raise firms’ marginal costs and feed into current inflation through the Phillips curve (Gagliardone et al. Reference Gagliardone, Gertler, Lenzu and Tielens2025), which in turn validates the initial expectation. This self-reinforcing loop can sustain multiple inflation levels as rational expectations equilibria and generate persistence that survives even after the original shock dissipates. A coherent theory of inflation persistence must therefore allow land prices to move inflation and inflation to move land prices—and must confront the possibility that this feedback is strong enough to be self-validating.
The mechanisms explored in this paper are particularly relevant for emerging economies facing persistent inflation and limited financial depth. In contexts where capital markets are underdeveloped or subject to capital controls—such as Argentina—agents frequently resort to real estate and land as alternative stores of value. This behavior amplifies the feedback loop between speculative land demand and aggregate prices. Consequently, the framework presented in this paper, which demonstrates how land speculation can generate multiple equilibria and inflation hysteresis, provides a theoretical rationale for the persistence of high-inflation regimes in economies where standard monetary policy entails significant output-exposure costs.
The paper contributes to three active literatures. The first is the literature on land and credit in macroeconomic models. Iacoviello (Reference Iacoviello2005) and Iacoviello and Neri (Reference Iacoviello and Neri2010) establish the quantitative importance of housing collateral in the transmission of monetary policy. More recently, Hirano and Stiglitz (Reference Hirano and Stiglitz2024) show in an endogenous growth framework with credit frictions that expansionary monetary policy can encourage land speculation at the expense of productive investment and that financial regulations and sector-specific credit policies are therefore essential complements to monetary policy. Hirano and Stiglitz (Reference Hirano and Stiglitz2025) extend this analysis to show that land speculation can generate recurrent fluctuations and multiple rational expectations trajectories, a finding that parallels the multiplicity results derived below in a New Keynesian setting.
The second literature concerns bubbles and monetary policy in New Keynesian frameworks. Galí (Reference Galí2021) shows that introducing overlapping generations of finite-lived agents into the standard NK model allows for rational expectations equilibria with asset price bubbles and that the conventional Taylor principle may no longer guarantee a unique equilibrium in such settings. Plantin (Reference Plantin2023) establishes a complementary result: in a menu-cost model, a standard Taylor rule generates multiple equilibria across which price rigidity, inflation, and asset bubbles co-exist. Bonchi and Nisticò (Reference Bonchi and Nisticò2024) characterize optimal monetary policy in the presence of rational bubbles and show that inflation targeting is generally suboptimal when bubbly fluctuations affect the cross-sectional distribution of consumption. Ikeda (Reference Ikeda2022) examines rational asset price bubbles in an OLG model with nominal rigidities and finds that a systematic interest rate response to a growing bubble can amplify rather than dampen bubble fluctuations. The broader macroeconomics of rational bubbles, including their interaction with credit and overlapping-generations structures, is surveyed in Martin and Ventura (Reference Martin and Ventura2018). The present paper differs from this literature in focusing on the speculative component of land demand as a cost-push channel into the Phillips curve, rather than on rational bubbles as aggregate demand shifters. This distinction matters for the policy prescription: the two instruments operate through different structural margins. Multiplicity driven by expectations and animal spirits, rather than by asset-price speculation per se, is analyzed in Farmer (Reference Farmer2012), whose confidence-based equilibria share the feature that sunspot shocks can move the economy across steady states—a mechanism structurally related to the hysteresis result in Proposition 3.
A closely related contribution is Lustenhouwer (Reference Lustenhouwer2021), who studies a New Keynesian model with bounded rationality and heterogeneous expectations in which multiple locally stable steady states can emerge and negative shocks can trigger self-reinforcing liquidity traps. The present paper shares the focus on multiplicity and basin-of-attraction geometry in a NK framework but differs along three dimensions that are substantive rather than merely technical. First, the source of multiplicity here is a real cost-push channel—speculative land demand feeding into firms’ marginal costs through the Phillips curve—rather than expectational heterogeneity per se; this grounds the multiplicity result in an observable market friction rather than in the distribution of beliefs. Second, the stability analysis is conducted under adaptive learning following Evans and Honkapohja (Reference Evans and Honkapohja2001), which yields a single well-defined T-map whose monotonicity properties (Lemma B) allow a complete global characterization of basins of attraction without relying on local linearization. Third, and most directly relevant for policy, the model delivers an explicit complementarity result between monetary and fiscal instruments (Proposition 4): a tax on speculative land demand is a first-order improvement in the local stabilization metric around the low stable regime for any weighting of inflation and output, a result that has no counterpart in Lustenhouwer (Reference Lustenhouwer2021) because that framework does not feature a correctable market distortion in asset demand.
The third literature concerns the policy debate over whether central banks should respond to asset prices. Bernanke and Gertler (Reference Bernanke and Gertler2001) argue that monetary policy should react to asset prices only to the extent that they signal future inflation pressures. Cecchetti et al. (Reference Cecchetti, Genberg, Lipsky and Wadhwani2000) take the opposite view, arguing that central banks should lean against asset price misalignments. The framework developed here bridges these positions: the monetary response to land prices is warranted because land prices directly enter the cost-push channel of the Phillips curve, but a tax on speculative demand is also a first-order local stabilization improvement in the neighborhood of the low stable regime—it lowers the local amplification coefficient without the output-exposure cost that a larger
 $\eta _{q}$
entails (Proposition 4). This complementarity result is related to Agur (Reference Agur2019), who shows that monetary and macroprudential policy can be substitutes or complements depending on the number of equilibria in the economy, and to Farhi and Werning (Reference Farhi and Werning2016), who establish conditions under which macroprudential instruments and monetary policy play distinct, non-redundant roles in economies with nominal rigidities. Bianchi et al. (Reference Bianchi, McKay and Mehrotra2024) provide a welfare analysis of optimal monetary policy in a housing model that motivates the separation of instruments; the present result shows that the fiscal instrument dominates locally around the low stable regime for any relative weight on inflation and output stabilization within the local stabilization metric used below. The inefficiency of unregulated credit booms that fuel asset-price cycles, emphasized by Lorenzoni (Reference Lorenzoni2008), further motivates the inclusion of a corrective fiscal wedge.
This paper makes two additional modeling choices that deserve motivation. First, speculative demand follows a threshold logistic rule rather than a proportional rule. A standard logistic rule whose argument is proportional to expected inflation and demographic pressure operates only on the concave half of the logistic curve in the economically relevant region of non-negative values and therefore cannot produce three non-negative fixed points. The explicit threshold
 $\xi$
introduced here has a natural economic interpretation: speculators do not shift aggressively into land as soon as inflation rises above zero, but only after the perceived inflation-hedge motive is strong enough to offset transactions costs, regulatory frictions, or organizational inertia—consistent with the threshold behavior documented in urban housing markets by Brunnermeier and Julliard (Reference Brunnermeier and Julliard2008). Second, land-price pass-through enters the Phillips curve additively and separately from the Calvo slope
 $\kappa$
. This separable specification is consistent with the micro-level evidence of Gagliardone et al. (Reference Gagliardone, Gertler, Lenzu and Tielens2025), who find that cost-push channels operate through a mechanism structurally distinct from the frequency-of-price-adjustment component, and avoids the internal inconsistency that arises when the two are conflated.
The stability and hysteresis analysis is conducted under adaptive learning, following Evans and Honkapohja (Reference Evans and Honkapohja2001) and Branch and Evans (Reference Branch and Evans2007). The learning dynamics are modeled as direct iteration of the T-map derived from agents’ constant-inflation PLM. The model remains deliberately parsimonious: a stationary demographic-pressure state, a two-period overlapping-generations structure, a reduced-form New Keynesian Phillips curve, and a Taylor rule that may respond to land prices. The entire steady-state system collapses to a one-dimensional fixed-point problem for inflation, which allows precise global results.
2. The model
2.1 Stationary demographic pressure and land fundamentals
The model works with a demographic-pressure index rather than raw population levels. Let total demographic pressure be decomposed as:
 \begin{equation*} \begin{array}{l} d_{t}= \,\bar{\kern-3pt d}+\,\tilde{\kern-3pt d}_{t} , \,\bar{\kern-3pt d}\gt 0 \end{array} \end{equation*}
where
 $\,\bar{\kern-3pt d}$
captures the long-run average pressure on central urban land and
 $\ \tilde{\kern-3pt d}_{t}$
is a stationary cyclical deviation satisfying:
 \begin{equation*} \ \tilde{\kern-3pt d}_{t+1}=\rho _{d}\ \tilde{\kern-3pt d}_{t}+\varepsilon _{t+1,| {\rho _{d}}| \lt 1} \end{equation*}
The state
 $d_{t}$
summarizes total urban demand pressure on central land. It can represent net urbanization, migration pressure, or any demand shifter that raises the shadow value of central locations. The component
 $\,\bar{\kern-3pt d}$
captures the secular level of urban land demand, while
 $\ \tilde{\kern-3pt d}_{t}$
captures transitory cyclical deviations around that level. Stationarity therefore applies to
 $\ \tilde{\kern-3pt d}_{t}$
, not to the total level
 $d_{t}$
.
The fundamental component of the real land price is:
 \begin{equation*} {q}_{t}^{\,f}=\psi d_{t}=\psi (\,\bar{\kern-3pt d}+\ \tilde{\kern-3pt d}_{t}), \psi \gt 0 \end{equation*}
In the non-stochastic steady state,
 $\ \tilde{\kern-3pt d}=0$
and therefore
 $d=\,\bar{\kern-3pt d}\gt 0$
. Thus, the model has a well-defined stationary steady state without requiring fundamental land demand to vanish in steady state. This distinction is important because the positive mean
 $\,\bar{\kern-3pt d}$
captures the long-run urban pressure that generates positive fundamental land values and positive steady-state inflation in equilibrium.
Stronger demographic pressure raises the fundamental value of land, consistent with the spatial equilibrium models of Alonso (Reference Alonso1964), Mills (Reference Mills1967), and Muth (Reference Muth1969), and with the structural analysis of urban land markets in Brueckner (Reference Brueckner and Brueckner1987).
2.2 Households, land market clearing, and threshold speculative demand
In each period a unit mass of young households is born, works, saves, and consumes when old. The two-period overlapping-generations structure follows Diamond (Reference Diamond1965) and Tirole (Reference Tirole1985). A young household receives wage income
 $w_{t}$
, consumes
 $c_{t}$
, and saves
 $a_{t}=w_{t}-c_{t}$
. Savings are allocated between one-period nominal bonds and land. Let
 $\gamma _{t}\in (0,1)$
denote the portfolio share placed in land, so the household holds
 $\gamma _{t}a_{t}/q_{t}$
units of land and
 $(1-\gamma _{t})a_{t}$
units of bonds.
2.2.1 Land market clearing
The aggregate supply of land is normalized to one unit, so market clearing requires
 \begin{equation*} \frac{\gamma _{t}a_{t}}{q_{t}}=1. \end{equation*}
Following the reduced-form approach of Iacoviello (Reference Iacoviello2005), Brunnermeier and Julliard (Reference Brunnermeier and Julliard2008), and Bekiros et al. (Reference Bekiros, Nilavongse and Uddin2020), aggregate savings are approximated at their steady-state value
 $\,\bar{\kern-3pt a}$
, yielding
 $q_{t}=\gamma _{t}\,\bar{\kern-3pt a}$
. Decomposing the portfolio share into a fundamental component and a speculative component and absorbing
 $\,\bar{\kern-3pt a}$
into the scaling parameters, gives
 \begin{equation*} q_{t}={q}_{t}^{\,f}+\nu \left(1-\tau _{t}\right){\gamma }_{t}^{s}, \end{equation*}
where
 ${\gamma }_{t}^{s}$
is the aggregate participation-adjusted speculative share,
 $\nu \gt 0$
scales the market-clearing effect of speculative demand, and
 $\tau _{t}\in [0,1)$
is a proportional tax on speculative land demand.Footnote
1
This steady-state savings approximation is standard in reduced-form OLG land-market models. Fully endogenizing aggregate savings would explicitly model an additional dynamic savings response, but that response is not the source of the fixed-point geometry studied below. The multiplicity, hysteresis, and policy-complementarity results are generated by the interaction between speculative land demand, land-price pass-through into marginal costs, and the policy rule.
2.2.2 Threshold speculative demand
Aggregate speculative demand follows a threshold logistic rule:
 \begin{equation*} {\gamma }_{t}^{s}=\Theta \left(\Delta _{t}\right),\quad \quad \Theta \left(z\right)=\frac{1}{1+e^{-z}}, \end{equation*}
 \begin{equation*} \Delta _{t}=\chi _{\pi }E_{t}\pi _{t+1}+\chi _{d}d_{t}-\xi , \end{equation*}
with
 $\chi _{\pi }\gt 0$
,
 $\chi _{d}\gt 0$
, and
 $\xi \gt 0$
. The threshold
 $\xi$
is the minimum strength of the inflation-hedge motive required to trigger aggressive reallocations toward land (Brunnermeier and Julliard, Reference Brunnermeier and Julliard2008). A formal derivation of Equation (1) from a portfolio optimization problem with idiosyncratic entry costs is provided in Appendix A.
Combining these equations:
 \begin{equation}q_{t}=\psi d_{t}+\nu \left(1-\tau _{t}\right)\,\Theta \big(\chi _{\pi }E_{t}\pi _{t+1}+\chi _{d}d_{t}-\xi \big).\end{equation}
2.2.3 Robustness note on functional form
The logistic function is adopted for analytical tractability. The qualitative results—amplification, the existence of a multiplicity region, the hysteresis mechanism, and the complementarity of instruments—hold for any smooth sigmoidal
 $\Theta$
satisfying
 $\Theta \mathrm{'}\gt 0$
,
 $\Theta ''\lt 0$
above the inflection, and
 $\Theta ''\gt 0$
below it. The quantitative threshold in Proposition 1 equals
 $1/\max _{z}\Theta \mathrm{'}(z)$
; for the logistic,
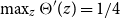 $\max _{z}\Theta \mathrm{'}(z)=1/4$
, giving a threshold of 4. Under any other sigmoid with maximal derivative
 $M$
, the threshold would be
 $1/M$
, and should be estimated empirically rather than treated as a structural constant.
2.3 Firms, the Phillips curve, and monetary policy
Intermediate firms produce differentiated goods under Calvo (Reference Calvo1983) price rigidity. Real marginal cost depends on the output gap and on the real land price, because land enters production through rents and affects wage formation through housing costs.Footnote
2
Land-price pass-through enters the Phillips curve additively and separately from the Calvo slope
 $\kappa$
, consistent with the micro evidence of Gagliardone et al. (Reference Gagliardone, Gertler, Lenzu and Tielens2025), who show that cost-push channels operate through a margin structurally distinct from the frequency-of-price-adjustment component that determines
 $\kappa$
:
 \begin{equation}\pi _{t}=\beta E_{t}\pi _{t+1}+\kappa x_{t}+\varphi _{q}q_{t},\end{equation}
where
 $x_{t}$
is the output gap and
 $\varphi _{q}\gt 0$
is the pass-through coefficient. The dynamic IS equation is
 \begin{equation}x_{t}=E_{t}x_{t+1}-\sigma ^{-1}\left(i_{t}-E_{t}\pi _{t+1}-{r}_{t}^{n}\right),\quad \quad \sigma \gt 0.\end{equation}
Equation (3) is used as a reduced-form aggregate-demand closure for the New Keynesian block, following Clarida et al. (Reference Clarida, Galí and Gertler1999). The OLG structure in Section 2.2 is not intended to microfound the entire intertemporal demand side of the economy. Its role is narrower and asset-market specific: it provides the land-market clearing condition and the speculative portfolio-demand channel through which inflation expectations affect land prices.
The model is therefore modular by design. The OLG block determines how inflation expectations and demographic pressure affect speculative land demand and land prices, while the NK block determines how aggregate demand, monetary policy, and marginal costs map land prices into inflation. Closely related NK frameworks with overlapping-generations or asset-price feedbacks adopt analogous modular structures—Galí (Reference Galí2021) and Plantin (Reference Plantin2023) are two relevant examples.
A fully integrated OLG-NK model with endogenous savings and multiple assets would explicitly model the intertemporal consumption-saving margin together with the portfolio-allocation margin. That extension is valuable but not necessary for the mechanism isolated here. The purpose of the present paper is not to provide a fully integrated OLG-NK model but to isolate the land-speculation cost-push channel in the most parsimonious structure capable of delivering global analytical results. The fixed-point geometry generated by Equations (1), (2), and (4) is therefore the central object of analysis.
Appendix C shows that this modular structure is consistent with the two distinct optimality margins of a multiple-asset household problem: the intertemporal margin underlying the dynamic IS equation and the portfolio participation margin underlying speculative land demand.
Monetary policy follows the extended Taylor rule of Clarida et al. (Reference Clarida, Galí and Gertler1999), augmented with a direct response to land prices:
 \begin{equation}i_{t}=\eta _{\pi }\pi _{t}+\eta _{x}x_{t}+\eta _{q}q_{t},\end{equation}
with
 $\eta _{\pi }\gt 1$
,
 $\eta _{x}\gt 0$
, and
 $\eta _{q}\geq 0$
. The Taylor principle (
 $\eta _{\pi }\gt 1$
) is necessary but, as shown in Section 3, not sufficient to guarantee a unique equilibrium once speculative land demand is sufficiently strong—a result related to the multiplicity findings of Benhabib et al. (Reference Benhabib, Schmitt-Grohé and Uribe2001), who show that Taylor rules can generate unintended inflationary traps. The present model contributes a specific channel—land as a cost-push factor—that justifies a non-zero
 $\eta _{q}$
independently of any bubble-stabilization motive.
2.4 Steady-state reduction
In a non-stochastic steady state with
 $\ \tilde{\kern-3pt d}=0$
, so that
 $d=\,\bar{\kern-3pt d}\gt 0$
, with
 $\tau _{t}=\tau$
, fulfilled expectations (
 $E_{t}\pi _{t+1}=\pi$
,
 $E_{t}x_{t+1}=x$
), and
 ${r}_{t}^{n}=0$
, the IS equation reduces to
 $i=\pi$
. Substituting into (4) gives
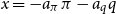 $x=-a_{\pi }\pi -a_{q}q$
, with
 \begin{equation*} a_{\pi }=\frac{\eta _{\pi }-1}{\eta _{x}}\gt 0,\quad \quad a_{q}=\frac{\eta _{q}}{\eta _{x}}\geq 0. \end{equation*}
Substituting into (2) and using
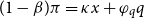 $(1-\beta )\pi =\kappa x+\varphi _{q}q$
yields the static land-inflation relation
 \begin{equation}\pi =B(\eta _{q})\,q,\end{equation}
whereFootnote 3
 \begin{equation*} B(\eta _{q})=\frac{\varphi _{q}-\kappa a_{q}}{1-\beta +\kappa a_{\pi }}=\frac{\varphi _{q}-\kappa \eta _{q}/\eta _{x}}{1-\beta +\kappa \left(\eta _{\pi }-1\right)/\eta _{x}}. \end{equation*}
The maintained restriction
 \begin{equation}0\leq \kappa a_{q}\lt \varphi _{q}\end{equation}
ensures
 $B(\eta _{q})\gt 0$
, so land prices raise inflation. Combining (5) with (1) gives the steady-state fixed-point problem
 \begin{equation}\pi =Ad+C\,\Theta (\chi _{\pi }\pi +\chi _{d}d-\xi )\equiv g(\pi ;\,d,\eta _{q},\tau ,\xi ),\end{equation}
where
 $A=B(\eta _{q})\psi$
and
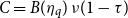 $C=B(\eta _{q})\,\nu (1-\tau )$
. Define the excess function
 $F=g-\pi$
. A steady state is any non-negative zero of
 $F$
.
2.5 T-map, adaptive learning, and equilibrium stability
2.5.1 Derivation of the T-map
Expectations are formed under adaptive learning in the sense of Evans and Honkapohja (Reference Evans and Honkapohja2001). Agents hold a perceived law of motion (PLM) in which inflation is approximated by a time-varying constant
 $\mu _{t}$
, updated period by period. This is steady-state learning: agents learn the mean inflation level associated with the stationary equilibrium rather than the coefficients of a dynamic forecasting rule.
The one-dimensional PLM is deliberately restricted. The minimal perceived state is
 $\mu _{t}$
. Land prices are not included as an independently forecasted state in the inflation PLM because, given
 $\mu _{t}$
and
 $d_{t}$
, land prices are determined by the land-market clearing condition and the speculative demand rule in Equation (1). Similarly, the output gap is not endowed with a separate perceived law of motion. Conditional on the inflation forecast
 $\mu _{t}$
, the IS equation and the Taylor rule jointly determine the contemporaneous output gap consistent with the perceived steady state.
The resulting learning dynamics are therefore a restricted perceptions equilibrium (RPE) in the sense of Evans and Honkapohja (Reference Evans and Honkapohja2001). Agents use a restricted but internally consistent PLM tailored to the one-dimensional steady-state learning problem: they learn
 $\mu _{t}$
, while
 $q_{t}$
and
 $x_{t}$
are eliminated through market clearing, the Phillips curve, and the policy rule. This restriction is not a static-expectations assumption about output. Rather, it reflects the fact that the paper studies the stability of steady-state inflation beliefs, and the output gap entering the T-map is the value implied by the perceived steady state associated with
 $\mu _{t}$
.
Formally, agents hold the constant inflation forecast
 $E_{t}\pi _{t+1}=\mu _{t}$
. Evaluating the IS block at the perceived steady state conditional on
 $\mu _{t}$
, so that
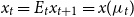 $x_{t}=E_{t}x_{t+1}=x(\mu _{t})$
, and setting the natural rate of interest
 ${r}_{t}^{n}=0$
, the IS equation gives
 \begin{equation}i_{t}=\mu _{t}.\end{equation}
Substituting (8) into (4) and solving for
 $x_{t}$
:
 \begin{equation}x_{t}=\frac{\mu _{t}-\eta _{\pi }\pi _{t}-\eta _{q}q_{t}\left(\mu _{t}\right)}{\eta _{x}}.\end{equation}
 \begin{equation*} \pi _{t}=\beta \mu _{t}+\kappa \cdot \frac{\mu _{t}-\eta _{\pi }\pi _{t}-\eta _{q}q_{t}\left(\mu _{t}\right)}{\eta _{x}}+\varphi _{q}q_{t}\left(\mu _{t}\right)\!. \end{equation*}
Collecting terms in
 $\pi _{t}$
:
 \begin{equation*} \pi _{t}\left(1+\frac{\kappa \eta _{\pi }}{\eta _{x}}\right)=\left(\beta +\frac{\kappa }{\eta _{x}}\right)\mu _{t}+\left(\varphi _{q}-\frac{\kappa \eta _{q}}{\eta _{x}}\right)q_{t}\left(\mu _{t}\right)\!, \end{equation*}
which defines the T-map
 \begin{equation}T\left(\mu _{t}\right)\equiv \frac{\left(\beta \eta _{x}+\kappa \right)\,\mu _{t}\,+\,(\varphi _{q}\eta _{x}-\kappa \eta _{q})\,q\left(\mu _{t}\right)}{\eta _{x}+\kappa \eta _{\pi }},\end{equation}
where
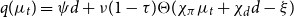 $q(\mu _{t})=\psi d+\nu (1-\tau )\Theta (\chi _{\pi }\mu _{t}+\chi _{d}d-\xi )$
.
2.5.2 Learning dynamics and E-stability
Following Evans and Honkapohja (Reference Evans and Honkapohja2001, Ch. 2), the out-of-equilibrium dynamics are modeled as direct iteration of the T-map:
 $\mu _{t+1}=T(\mu _{t})$
.Footnote
4
The fixed points of
 $T$
are the rational expectations equilibria, and a fixed point
 $\,\bar{\kern-3pt \pi }$
is E-stable—and locally learnable—if and only if
 $T\mathrm{'}(\,\bar{\kern-3pt \pi })\lt 1$
.
Lemma A. (Fixed-point equivalence and E-stability). (i)
 $\,\bar{\kern-3pt \pi }$
is a non-negative steady state (fixed point of
 $g$
in (7)) if and only if
 $T(\,\bar{\kern-3pt \pi })=\,\bar{\kern-3pt \pi }$
. (ii)
 $T\mathrm{'}(\,\bar{\kern-3pt \pi })\lt 1$
if and only if
 $g\mathrm{'}(\,\bar{\kern-3pt \pi })\lt 1$
.
Proof.
(i) At any
 $\,\bar{\kern-3pt \pi }$
with
 $T(\,\bar{\kern-3pt \pi })=\,\bar{\kern-3pt \pi }$
:
 \begin{equation*} \left(\beta \eta _{x}+\kappa \right)\,\bar{\kern-3pt \pi }+(\varphi _{q}\eta _{x}-\kappa \eta _{q})q\left(\,\bar{\kern-3pt \pi }\right)=\left(\eta _{x}+\kappa \eta _{\pi }\right)\,\bar{\kern-3pt \pi }, \end{equation*}
 \begin{equation*} (\varphi _{q}\eta _{x}-\kappa \eta _{q})q\left(\,\bar{\kern-3pt \pi }\right)=\left[\eta _{x}\left(1-\beta \right)+\kappa \left(\eta _{\pi }-1\right)\right]\,\,\bar{\kern-3pt \pi }=\eta _{x}\left(1-\beta +\kappa a_{\pi }\right)\,\,\bar{\kern-3pt \pi }, \end{equation*}
 \begin{equation*} \,\bar{\kern-3pt \pi }=\frac{\varphi _{q}-\kappa a_{q}}{1-\beta +\kappa a_{\pi }}\,q\left(\,\bar{\kern-3pt \pi }\right)=B(\eta _{q})\,q\left(\,\bar{\kern-3pt \pi }\right)=g\left(\,\bar{\kern-3pt \pi }\right).\mathrm{\checkmark } \end{equation*}
(ii) Differentiating (10):
 \begin{equation*} T\mathrm{'}\left(\mu \right)=\frac{\left(\beta \eta _{x}+\kappa \right)+(\varphi _{q}\eta _{x}-\kappa \eta _{q})\,\nu \left(1-\tau \right)\chi _{\pi }\Theta \mathrm{'}(\chi _{\pi }\mu +\chi _{d}d-\xi )}{\eta _{x}+\kappa \eta _{\pi }}. \end{equation*}
 $T\mathrm{'}(\,\bar{\kern-3pt \pi })\lt 1$
iff
 \begin{equation*} (\varphi _{q}\eta _{x}-\kappa \eta _{q})\,\nu \left(1-\tau \right)\chi _{\pi }\Theta \mathrm{'}\left(\cdot \right)\lt \eta _{x}\left(1-\beta \right)+\kappa \left(\eta _{\pi }-1\right), \end{equation*}
 \begin{align*} \frac{(\varphi _{q}-\kappa a_{q})\,\nu \left(1-\tau \right)\chi _{\pi }\Theta \mathrm{'}\left(\cdot \right)}{1-\beta +\kappa a_{\pi }}\lt 1,\\[-6pt] \end{align*}
 \begin{equation*} B(\eta _{q})\,\nu \left(1-\tau \right)\chi _{\pi }\Theta \mathrm{'}\left(\cdot \right)\lt 1,\quad \quad \mathrm{i}.\mathrm{e}.,\quad m\,\Theta \mathrm{'}\left(\cdot \right)\lt 1,\quad \quad \mathrm{i}.\mathrm{e}.,\quad g\mathrm{'}\left(\,\bar{\kern-3pt \pi }\right)\lt 1.\mathrm{\checkmark } \end{equation*}
Lemma B. (Monotonicity of T under restriction (6)). Under restriction (6),
 $T(\,\cdot \,;\,d)$
is strictly increasing in
 $\mu$
for all
 $\mu \geq 0$
and
 $d\geq 0$
.
Proof. Differentiating (10):
 \begin{equation*} T\mathrm{'}\left(\mu \right)=\frac{\left(\beta \eta _{x}+\kappa \right)+(\varphi _{q}\eta _{x}-\kappa \eta _{q})\,\nu \left(1-\tau \right)\chi _{\pi }\Theta \mathrm{'}(\chi _{\pi }\mu +\chi _{d}d-\xi )}{\eta _{x}+\kappa \eta _{\pi }}. \end{equation*}
The denominator
 $\eta _{x}+\kappa \eta _{\pi }\gt 0$
; the first numerator term
 $\beta \eta _{x}+\kappa \gt 0$
; and
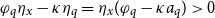 $\varphi _{q}\eta _{x}-\kappa \eta _{q}=\eta _{x}(\varphi _{q}-\kappa a_{q})\gt 0$
under (6). Since
 $\Theta \mathrm{'}(\cdot )\gt 0$
and
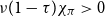 $\nu (1-\tau )\chi _{\pi }\gt 0$
, every term in the numerator is strictly positive, so
 $T\mathrm{'}(\mu )\gt 0$
for all
 $\mu$
.
Remark.
 $T$
and
 $g$
are distinct functions (
 $T\mathrm{'}\neq g\mathrm{'}$
in general), but by Lemma A they share every fixed point and agree on the sign of
 $T\mathrm{'}-1$
at every fixed point. By Lemma B,
 $T$
is strictly monotone increasing under restriction (6). A strictly monotone increasing map with three fixed points
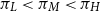 $\pi _{L}\lt \pi _{M}\lt \pi _{H}$
satisfying
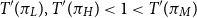 $T\mathrm{'}(\pi _{L}),T\mathrm{'}(\pi _{H})\lt 1\lt T\mathrm{'}(\pi _{M})$
has the property that:
 $T(\mu )\lt \mu$
for
 $\mu \in (\pi _{L},\pi _{M})$
and
 $T(\mu )\gt \mu$
for
 $\mu \in (\pi _{M},\pi _{H})$
, so that
 $\pi _{M}$
is the unique separator. Trajectories of T-map iteration starting below
 $\pi _{M}$
converge to
 $\pi _{L}$
, and those starting above
 $\pi _{M}$
converge to
 $\pi _{H}$
. At every steady state,
 $\mu =T(\mu )=\,\bar{\kern-3pt \pi }$
, consistent with rational expectations on the equilibrium path.
3. Steady states and multiplicity
3.1 Amplification in the unique-equilibrium region
Corollary 1 (Land-price amplification). Suppose
 $B(\eta _{q})\gt 0$
. At any stable non-negative steady state
 $\,\bar{\kern-3pt \pi }$
, we have
 $\,\bar{\kern-3pt \pi }\gt 0$
for all
 $d\gt 0$
. Moreover,
 $\,\bar{\kern-3pt \pi }$
is strictly increasing in
 $\psi$
,
 $\nu$
,
 $\varphi _{q}$
, and
 $\chi _{\pi }$
, and strictly decreasing in
 $\tau$
and
 $\eta _{q}$
.
Proof.
At any fixed point,
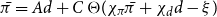 $\,\bar{\kern-3pt \pi }=Ad+C\,\Theta (\chi _{\pi }\,\bar{\kern-3pt \pi }+\chi _{d}d-\xi )$
. Since
 $A,C,\Theta \gt 0$
and
 $d\gt 0$
, we have
 $\,\bar{\kern-3pt \pi }\gt 0$
. Comparative statics follow from the implicit function theorem applied to
 $F(\pi )=0$
: at any stable steady state
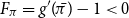 $F_{\pi }=g\mathrm{'}(\,\bar{\kern-3pt \pi })-1\lt 0$
(by Lemma A(ii)), so
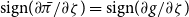 $\text{sign}(\partial \,\bar{\kern-3pt \pi }/\partial \zeta )=\text{sign}(\partial g/\partial \zeta )$
. In particular,
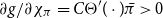 $\partial g/\partial \chi _{\pi }=C\Theta \mathrm{'}(\cdot )\,\bar{\kern-3pt \pi }\gt 0$
since
 $\,\bar{\kern-3pt \pi }\gt 0$
and
 $C,\Theta \mathrm{'}\gt 0$
; and
 $\partial g/\partial \eta _{q}\lt 0$
since
 $\partial B/\partial \eta _{q}\lt 0$
(established in Proposition 2). All other signs are immediate.
The amplification mechanism underlying Corollary 1 operates through a mutual feedback between inflation expectations and speculative land demand. When
 $\chi _{\pi }$
is large, a rise in
 $E_{t}\pi _{(t+1)}$
triggers a pronounced portfolio reallocation toward land, consistent with the threshold reallocation behavior documented in urban housing markets by Brunnermeier and Julliard (Reference Brunnermeier and Julliard2008). This additional speculative demand raises
 $q_{t}$
through land market clearing, which in turn raises firms’ real marginal cost and feeds into
 $\pi _{t}$
through the Phillips curve. The higher current inflation validates and reinforces the initial expectation, closing the feedback loop. Steady-state inflation therefore exceeds the level implied by demographic fundamentals alone—
 $Ad$
in Equation (7)—by an amplification term that is strictly increasing in
 $\chi _{\pi }$
,
 $v$
,
 $\varphi _{q}$
and
 $\psi$
, and strictly decreasing in the monetary response coefficient
 $\eta _{q}$
. This mechanism is qualitatively related to the speculative amplification identified by Hirano and Stiglitz (Reference Hirano and Stiglitz2025) in an endogenous growth framework with land and is quantitatively relevant in economies where shallow capital markets make real estate a substitute for financial assets, as documented by Iacoviello and Neri (Reference Iacoviello and Neri2010). The strict convex decrease of
 $\pi ^{*}$
in
 $\tau$
shown in Figure 1 reflects that the fiscal instrument acts directly on this amplification channel: by reducing the net return to speculative land demand,
 $\tau$
interrupts the feedback before it propagates into prices.
Steady-state inflation and the speculative-demand tax. Unique-equilibrium region under the baseline calibration.

Figure 1 illustrates Corollary 1: steady-state inflation decreases strictly and convexly in the speculative demand tax
 $\tau$
, demonstrating that a fiscal instrument targeting speculative land demand is effective at dampening inflationary pressures even in the unique-equilibrium region.
3.2 Global uniqueness and multiplicity conditions
Proposition 1 (Global uniqueness and multiplicity). Assume
 $B(\eta _{q})\gt 0$
,
 $d\geq 0$
, and let
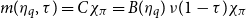 $m(\eta _{q},\tau )=C\chi _{\pi }=B(\eta _{q})\,\nu (1-\tau )\chi _{\pi }$
.
Part (i). If
 $m(\eta _{q},\tau )\leq 4$
, the fixed-point equation has a unique non-negative steady state.
Part (ii). If
 $m(\eta _{q},\tau )\gt 4$
, define
 \begin{equation*} s_{1}=\frac{1-\sqrt{1-4/m}}{2},\quad \quad s_{2}=\frac{1+\sqrt{1-4/m}}{2}, \end{equation*}
 \begin{equation*} z_{1}=\ln \left(\frac{s_{1}}{1-s_{1}}\right)\lt 0,\quad \quad z_{2}=\ln \left(\frac{s_{2}}{1-s_{2}}\right)\gt 0, \end{equation*}
 \begin{equation*} p_{1}=\frac{z_{1}-\chi _{d}d+\xi }{\chi _{\pi }},\quad \quad p_{2}=\frac{z_{2}-\chi _{d}d+\xi }{\chi _{\pi }}. \end{equation*}
If the following four conditions hold:
 \begin{equation*} p_{1}\gt 0, \end{equation*}
 \begin{equation*} F(0;\,d,\eta _{q},\tau ,\xi)\gt 0, \end{equation*}
 \begin{equation*} F(p_{1};\,d,\eta _{q},\tau ,\xi)\lt 0, \end{equation*}
 \begin{equation*} F(p_{2};\,d,\eta _{q},\tau ,\xi)\gt 0, \end{equation*}
then there exist exactly three non-negative steady states
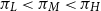 $\pi _{L}\lt \pi _{M}\lt \pi _{H}$
. Under T-map iteration,
 $\pi _{L}$
and
 $\pi _{H}$
are E-stable and
 $\pi _{M}$
is E-unstable.
The threshold
 $m=4$
equals
 $1/\max _{z}\Theta \mathrm{'}(z)$
and is specific to the logistic benchmark. Under any alternative smooth sigmoidal function with maximal derivative
 $M$
, the threshold is
 $1/M$
.
The composite parameter
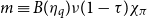 $m\equiv B(\eta _{q})\nu (1-\tau )\chi _{\pi }$
has a natural interpretation as the open-loop gain of the land-inflation feedback. Starting from any inflation level, a marginal increase in
 $\pi$
raises speculative land demand by
 $\chi _{\pi }\def\lumina\hspace{0pt}\Theta '(\cdot )$
, which raises
 $q$
by
 $\nu (1-\tau )$
, which raises
 $\pi$
in the next pass through the Phillips curve and Taylor rule by
 $B(\eta _{q})$
. The product of these three amplification stages is
 $m\Theta '(\cdot )$
, which equals the slope
 $g'(\pi )$
of the fixed-point map. Multiplicity arises when this open-loop gain exceeds unity at some interior inflation level—that is, when the feedback is strong enough to be self-validating at a point where speculative demand is still responding to inflation expectations. Since
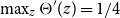 $\max _{z} \Theta '(z)=1/4$
for the logistic, the critical threshold is
 $m=4$
: below it,
 $g'(\pi )\lt 1$
everywhere and the feedback never becomes self-validating; above it, there exist two inflation levels at which
 $g'(\pi )=1$
, creating the local maximum and minimum of
 $F(\pi )$
that allow three distinct steady states. The threshold
 $m=4$
is therefore not a numerical coincidence but the reciprocal of the maximum slope of the speculative demand function—a quantity that should be estimated empirically under any alternative sigmoidal specification, as noted in Proposition 1.
Proof.
Since
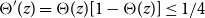 $\Theta \mathrm{'}(z)=\Theta (z)[1-\Theta (z)]\leq 1/4$
for all
 $z$
, with equality at
 $z=0$
, we have
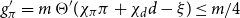 $g'_{\pi }=m\,\Theta \mathrm{'}(\chi _{\pi }\pi +\chi _{d}d-\xi )\leq m/4$
.
Part (i). Since
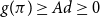 $g(\pi )\geq Ad\geq 0$
and
 $g(\pi )\rightarrow C+Ad\lt \mathrm{\infty }$
while
 $\pi \rightarrow \mathrm{\infty }$
, we have
 $F(\pi )\rightarrow -\mathrm{\infty }$
, so at least one zero exists. When
 $m\lt 4$
,
 $g\mathrm{'}(\pi )\lt 1$
everywhere, so
 $F\mathrm{'}(\pi )\lt 0$
everywhere and
 $F$
is strictly decreasing: the zero is unique. When
 $m=4$
,
 $g\mathrm{'}(\pi )\leq 1$
with equality at the single point
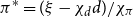 $\pi ^{\mathrm{*}}=(\xi -\chi _{d}d)/\chi _{\pi }$
(where
 $z=0$
); thus
 $F\mathrm{'}\leq 0$
with
 $F\mathrm{'}=0$
at most at one point.
 $F$
is non-increasing, strictly so except at the single point
 $\pi ^{\mathrm{*}}$
, and has a unique non-negative zero in both cases.
Part (ii). For
 $m\gt 4$
,
 $g\mathrm{'}(\pi )=1$
at exactly two points
 $p_{1}\lt p_{2}$
(solutions to
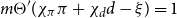 $m\Theta \mathrm{'}(\chi _{\pi }\pi +\chi _{d}d-\xi )=1$
), so
 $F$
has a unique local minimum at
 $p_{1}$
and a unique local maximum at
 $p_{2}$
. Conditions (C1)–(C4) ensure all three sign changes occur in the non-negative domain:
-
•
 $F(0)\gt 0$
and
$F(p_{1})\lt 0$
imply a zero
$\pi _{L}\in (0,p_{1})$
.
-
•
$F(p_{1})\lt 0$
and
$F(p_{2})\gt 0$
imply a zero
$\pi _{M}\in (p_{1},p_{2})$
. -
•
$F(p_{2})\gt 0$
and
$F(\pi )\rightarrow -\mathrm{\infty }$
imply a zero
$\pi _{H}\in (p_{2},\mathrm{\infty })$
.


Exactly three roots follow from the intermediate value theorem and the fact that
 $F$
has at most two local extrema. E-stability follows from Lemma A(ii):
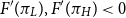 $F\mathrm{'}(\pi _{L}),F\mathrm{'}(\pi _{H})\lt 0$
iff
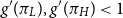 $g\mathrm{'}(\pi _{L}),g\mathrm{'}(\pi _{H})\lt 1$
iff
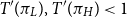 $T\mathrm{'}(\pi _{L}),T\mathrm{'}(\pi _{H})\lt 1$
; similarly
 $F\mathrm{'}(\pi _{M})\gt 0$
iff
 $T\mathrm{'}(\pi _{M})\gt 1$
.
Remark on condition (C2). Since
 $A,C\gt 0$
and
 $d\geq 0$
, we have
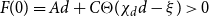 $F(0)=Ad+C\Theta (\chi _{d}d-\xi )\gt 0$
for all
 $d\geq 0$
, since
 $C\gt 0$
and
 $\Theta (\mathrm{z})\gt 0$
for all finite
 $\mathrm{z}$
; the term
 $Ad\geq 0$
is non-negative but not the binding reason when
 $d=0$
. Condition (C2) is therefore automatically satisfied and is listed only for completeness; the binding conditions for multiplicity are (C1), (C3), and (C4).
Numerical illustration. Set
 $\beta =0.99$
,
 $\kappa =0.1$
,
 $\varphi _{q}=0.08$
,
 $\eta _{\pi }=1.5$
,
 $\eta _{x}=0.5$
,
 $\eta _{q}=0.1$
,
 $\nu =5$
,
 $\chi _{\pi }=3$
,
 $\chi _{d}=1$
,
 $\xi =4$
,
 $\psi =0.5$
,
 $\tau =0$
,
 $d=0.5$
. Then
 $a_{\pi }=1$
,
 $a_{q}=0.2$
,
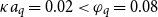 $\kappa a_{q}=0.02\lt \varphi _{q}=0.08$
(restriction (6) holds),
 $B\approx 0.5455$
,
 $C\approx 2.727$
,
 $m\approx 8.18\gt 4$
.
The turning-point quantities are:
 $s_{1}\approx 0.1425$
,
 $z_{1}\approx -1.794$
,
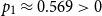 $p_{1}\approx 0.569\gt 0$
(C1 ✓);
 $s_{2}\approx 0.8575$
,
 $z_{2}\approx 1.794$
,
 $p_{2}\approx 1.765$
. The four conditions are verified by direct calculation:
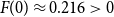 $F(0)\approx 0.216\gt 0$
(C2 ✓, automatic);
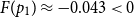 $F(p_{1})\approx -0.043\lt 0$
(C3 ✓);
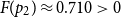 $F(p_{2})\approx 0.710\gt 0$
(C4 ✓). The three steady states are approximately
 $\pi _{L}\approx 0.358$
,
 $\pi _{M}\approx 0.764$
, and
 $\pi _{H}\approx 2.846$
, with
 $g\mathrm{'}(\pi _{L})\approx 0.610$
,
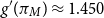 $g\mathrm{'}(\pi _{M})\approx 1.450$
, and
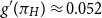 $g\mathrm{'}(\pi _{H})\approx 0.052$
, confirming stability of
 $\pi _{L}$
and
 $\pi _{H}$
and instability of
 $\pi _{M}$
(Lemma A(ii)).
Steady-state map and three fixed points. S-shaped map crosses the 45° line three times.

Figure 2 illustrates Proposition 1, showing the S-shaped map
 $g$
crossing the diagonal three times. Figure 3 shows the corresponding T-map iteration dynamics: trajectories starting below
 $\pi _{M}$
converge to
 $\pi _{L}$
, while those starting above it converge to
 $\pi _{H}$
.
T-map dynamics and basin of attraction.

4. Global uniqueness and the policy mix
Proposition 1 establishes that multiple steady states can arise when the open-loop gain
 $m$
exceeds four, but it does not characterize how far current policy parameters are from that threshold, nor how monetary and fiscal instruments can jointly ensure that the threshold is never crossed. This is the question addressed in this section. The sufficient condition derived in Proposition 2 translates the multiplicity criterion into an operational policy constraint: a schedule
 $\eta _{q}\def\lumina\hspace{0pt}(\tau )$
that maps any given tax rate on speculative demand into the minimum monetary response to land prices required to guarantee a unique equilibrium. The schedule is downward sloping—a stronger fiscal stance relaxes the monetary requirement—formalizing the sense in which the two instruments are substitutes in global regime control. For policymakers in economies where speculative land demand is highly elastic to inflation expectations, the relevant quantity to monitor is not
 $\eta _{\pi }$
alone but the composite
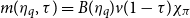 $m(\eta _{q},\tau )=B(\eta _{q})v(1-\tau )\chi _{\pi }$
, which aggregates pass-through, market-clearing amplification, fiscal stance, and speculative sensitivity into a single sufficient statistic for regime uniqueness.
Proposition 2 (General sufficient condition for global uniqueness). Suppose
 $\Theta$
is continuously differentiable, strictly increasing, and has bounded slope
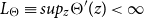 $L_{\Theta }\equiv sup_{z}\Theta '(z)\lt \infty$
. Suppose also that
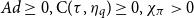 $Ad\geq 0,\mathrm{C}(\tau ,\eta _{q})\geq 0,\chi _{\pi }\gt 0$
, and restriction (6) holds.
If
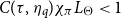 $C(\tau ,\eta _{q})\chi _{\pi }L_{\Theta }\lt 1$
, then the steady-state map
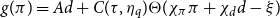 $g(\pi )=Ad+C(\tau ,\eta _{q})\Theta (\chi _{\pi }\pi +\chi _{d}d-\xi )$
has a unique non-negative fixed point.
The left-hand side
 $C(\tau ,\eta _{q})\chi _{\pi }L_{\Theta }$
is strictly decreasing in
 $\tau$
and, under restriction (6), strictly decreasing in
 $\eta _{q}$
.
Corollary 2 (Logistic benchmark). If
 $\Theta$
is the standard logistic function, then
 $L_{\Theta }=1/4$
. Hence a sufficient condition for global uniqueness is
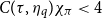 $C(\tau ,\eta _{q})\chi _{\pi }\lt 4$
.
Proof. Under the logistic benchmark, the minimum land-price response coefficient satisfying this sufficient condition is
 \begin{equation*} \,\bar{\kern-3pt \eta }_{q}\left(\tau \right)=\max \def\lumina\hspace{0pt}\left\{0,\,\frac{\eta _{x}}{\kappa }\def\lumina\hspace{0pt}\left[\varphi _{q}-\frac{4\left(1-\beta +\kappa \left(\eta _{\pi }-1\right)/\eta _{x}\right)}{\nu \left(1-\tau \right)\chi _{\pi }}\right]\right\}, \end{equation*}
which is weakly decreasing in τ and strictly so whenever the interior expression is positive.
Corollary 3 (Local E-stability in the unique regime). The unique fixed point
 $\,\bar{\kern-3pt \pi }$
guaranteed by Proposition 2 is locally E-stable under direct T-map iteration.
Proof.
Let
 $F(\pi )\equiv g(\pi )-\pi$
. Since
 $Ad\geq 0$
and
 $\Theta \gt 0$
, we have
 $F(0)\gt 0$
, while
 $F(\pi )\rightarrow -\mathrm{\infty }$
as
 $\pi \rightarrow \mathrm{\infty }$
. Thus at least one non-negative zero exists. Moreover,
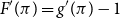 $F\mathrm{'}(\pi )=g\mathrm{'}(\pi )-1$
, and
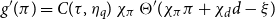 $g\mathrm{'}(\pi )=C(\tau ,\eta _{q})\,\chi _{\pi }\,\Theta \mathrm{'}(\chi _{\pi }\pi +\chi _{d}d-\xi )$
. Therefore
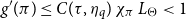 $g\mathrm{'}(\pi )\leq C(\tau ,\eta _{q})\,\chi _{\pi }\,L_{\Theta }\lt 1$
for all
 $\pi$
, so
 $F\mathrm{'}(\pi )\lt 0$
everywhere. Hence
 $F$
is strictly decreasing and has a unique non-negative zero. Monotonicity of the sufficient condition in
 $\tau$
follows because
 $C$
is proportional to
 $(1-\tau )$
. Monotonicity in
 $\eta _{q}$
follows because, under restriction
 $(6)$
,
 $B(\eta _{q})$
and therefore
 $C(\tau ,\eta _{q})$
are strictly decreasing in
 $\eta _{q}$
. Corollary 2 is immediate from
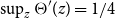 $\sup _{z}\Theta \mathrm{'}(z)=1/4$
for the logistic. Corollary 3 follows from Lemma A(ii):
 $| T_{\mu }(\,\bar{\kern-3pt \pi },\,\bar{\kern-3pt d})| \lt 1$
is exactly the local E-stability condition under direct T-map iteration.
Numerical illustration (continued). With the parameters above and the logistic benchmark, the sufficient uniqueness schedule
 $\,\bar{\kern-3pt \eta }_{q}(\tau )$
is the one plotted in Figure 5. It should be interpreted as a sufficient policy schedule under the maintained logistic specification, not as the exact boundary between uniqueness and multiplicity for arbitrary sigmoidal demand functions.
5. Temporary demographic shocks and hysteresis
Proposition 3
(Temporary shocks can generate permanent regime shifts). Suppose the baseline parameter vector lies in the multiplicity region, with steady states
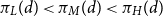 $\pi _{L}(d)\lt \pi _{M}(d)\lt \pi _{H}(d)$
, and let the economy start at
 $\pi _{L}(d)$
. Suppose
 $d_{t}=d+\varepsilon$
for
 $t=0,\ldots ,T$
and
 $d_{t}=d$
for
 $t\gt T$
, with
 $\varepsilon \gt 0$
. Then there exists
 $\varepsilon ^{\mathrm{*}}(T)\gt 0$
such that:
-
1. if
$\varepsilon \lt \varepsilon ^{\mathrm{*}}(T)$
, the economy converges back to
$\pi _{L}(d)$
; -
2. if
$\varepsilon \gt \varepsilon ^{\mathrm{*}}(T)$
, the economy converges to
$\pi _{H}(d)$
; -
3.
$\varepsilon ^{\mathrm{*}}(T)$
is weakly decreasing in
$T$
.


Proof.
The proof proceeds in terms of the T-map dynamics
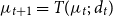 $\mu _{t+1}=T(\mu _{t};\,d_{t})$
. By Lemma B,
 $T(\,\cdot \,;\,d)$
is strictly increasing in
 $\mu$
for all
 $d$
. Moreover,
 $T(\mu ;\,d)$
is strictly increasing in
 $d$
: differentiating (
 $T$
),
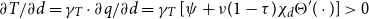 $\partial T/\partial d=\gamma _{T}\cdot \partial q/\partial d=\gamma _{T}\,[\psi +\nu (1-\tau )\chi _{d}\Theta \mathrm{'}(\cdot )]\gt 0$
, where
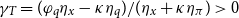 $\gamma _{T}=(\varphi _{q}\eta _{x}-\kappa \eta _{q})/(\eta _{x}+\kappa \eta _{\pi })\gt 0$
under restriction (6).
Define
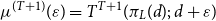 $\mu ^{(T+1)}(\varepsilon )=T^{T+1}(\pi _{L}(d);\,d+\varepsilon )$
, where
 $T^{T+1}$
denotes
 $(T+1)$
-fold composition of
 $T(\,\cdot \,;\,d+\varepsilon )$
. By strict monotonicity of
 $T$
in both arguments,
 $\mu ^{(T+1)}(\varepsilon )$
is continuous and strictly increasing in
 $\varepsilon$
and weakly increasing in
 $T$
.
At
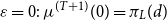 $\varepsilon =0 :\, \mu ^{(T+1)}(0)=\pi _{L}(d)$
since
 $\pi _{L}(d)$
is a fixed point of
 $T(\,\cdot \,;\,d)$
(Lemma A(i)).
For large
 $\varepsilon$
: since
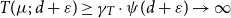 $T(\mu ;\,d+\varepsilon )\geq \gamma _{T}\cdot \psi (d+\varepsilon )\rightarrow \mathrm{\infty }$
as
 $\varepsilon \rightarrow \mathrm{\infty }$
, uniformly in
 $\mu$
on any bounded set, iterating
 $T+1$
times starting from the finite point
 $\pi _{L}(d)$
yields a sequence that eventually exceeds the finite threshold
 $\pi _{M}(d)$
for
 $\varepsilon$
large enough.
Once the orbit after the shock period exceeds
 $\pi _{M}(d)$
, the subsequent dynamics with
 $d_{t}=d$
satisfy:
 $T(\mu ;\,d)\gt \mu$
for
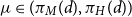 $\mu \in (\pi _{M}(d),\pi _{H}(d))$
and
 $T\mathrm{'}(\pi _{H}(d))\lt 1$
(E-stability), so by the basin-of-attraction characterization in the Remark following Lemma B, the orbit converges to
 $\pi _{H}(d)$
.
By the intermediate value theorem applied to
 $\varepsilon \mapsto \mu ^{(T+1)}(\varepsilon )$
, there exists
 $\varepsilon ^{\mathrm{*}}(T)\gt 0$
such that
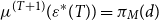 $\mu ^{(T+1)}(\varepsilon ^{\mathrm{*}}(T))=\pi _{M}(d)$
.
It remains to show that
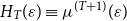 $H_{T}(\varepsilon )\equiv \mu ^{(T+1)}(\varepsilon )$
is weakly increasing in
 $T$
for each fixed
 $\varepsilon \gt 0$
, which implies
 $\varepsilon ^{\mathrm{*}}(T)$
is weakly decreasing in
 $T$
. The argument is by induction.
Base step:
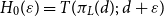 $H_{0}(\varepsilon )=T(\pi _{L}(d);\,d+\varepsilon )$
. Since
 $T$
is strictly increasing in
 $d$
(Lemma B) and
 $\varepsilon \gt 0$
, we have
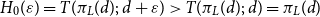 $H_{0}(\varepsilon )=T(\pi _{L}(d);\,d+\varepsilon )\gt T(\pi _{L}(d);\,d)=\pi _{L}(d)$
. Therefore
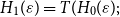 $H_{1}(\varepsilon )=T(H_{0}(\varepsilon );$
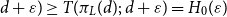 $d+\varepsilon )\geq T(\pi _{L}(d);\,d+\varepsilon )=H_{0}(\varepsilon )$
, where the inequality uses that
 $T$
is strictly increasing in
 $\mu$
(Lemma B) and
 $H_{0}(\varepsilon )\geq \pi _{L}(d)$
.
Inductive step: Assume
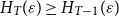 $H_{T}(\varepsilon )\geq H_{T-1}(\varepsilon )$
. Then
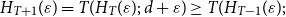 $H_{T+1}(\varepsilon )=T(H_{T}(\varepsilon );\,d+\varepsilon )\geq T(H_{T-1}(\varepsilon );$
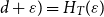 $d+\varepsilon )=H_{T}(\varepsilon )$
, again by monotonicity of
 $T$
in
 $\mu$
.
Hence
 $H_{T}(\varepsilon )$
is non-decreasing in
 $T$
for all
 $\varepsilon \gt 0$
. Since
 $\varepsilon ^{\mathrm{*}}(T)$
is defined by
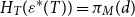 $H_{T}(\varepsilon ^{\mathrm{*}}(T))=\pi _{M}(d)$
, and
 $H_{T}$
is non-decreasing in
 $T$
,
 $\varepsilon ^{\mathrm{*}}(T)$
must be weakly decreasing in
 $T$
.
The hysteresis result is global and requires no local linearization. It follows entirely from the monotone structure of the T-map and the basin geometry established in Section 2.5. This is the sense in which the result is in the spirit of the phase-transition analysis of Hirano and Stiglitz (Reference Hirano and Stiglitz2025).
Hysteresis after a temporary demographic shock. Small vs. large shocks imply different long-run regimes.

Sufficient uniqueness schedule
 $\,\bar{\kern-3pt \eta }_{q}(\tau )$
. Corollary 2 under the logistic benchmark.

Numerical illustration: with the parameters of Section 3.2, the critical shock magnitude for
 $T=3$
is
 $\varepsilon ^{\mathrm{*}}(3)\approx 1.63$
: a shock of
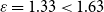 $\varepsilon =1.33\lt 1.63$
returns to
 $\pi _{L}\approx 0.358$
, while a shock of
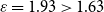 $\varepsilon =1.93\gt 1.63$
induces permanent convergence to
 $\pi _{H}\approx 2.846$
(verified numerically). Figure 4 illustrates: a small demographic shock produces a temporary inflation increase that reverts to
 $\pi _{L}$
; a large shock crosses
 $\pi _{M}$
and the economy converges permanently to
 $\pi _{H}$
.
Proposition 3 formalizes a mechanism of inflation hysteresis that is distinct from the standard persistence generated by nominal rigidities. The key insight is that the basin of attraction of the low stable regime
 $\pi _{L}$
is bounded above by the unstable threshold
 $\pi _{M}$
: once the learning dynamics carry the economy above
 $\pi _{M}$
, the T-map iteration converges to
 $\pi _{H}$
regardless of whether the original shock has dissipated. A sufficiently large or persistent demographic shock raises speculative land demand—through the
 $\chi _{d}d_{t}$
term in
 $\Delta _{t}$
—which pushes
 $q_{t}$
up, feeds
 $\pi _{t}$
through the Phillips curve, and shifts agents’ inflation forecasts upward. If this shift is large enough to carry
 $\mu _{t}$
above
 $\pi _{M}$
before the shock reverses, the economy enters the basin of attraction of
 $\pi _{H}$
and remains there permanently, even after demographic pressure returns to its baseline level
 $d$
. The asymmetry between shock size and shock persistence captured by the monotone decrease of
 ${\varepsilon }_{T}^{*}$
in
 $T$
reflects that duration and magnitude are substitutes in crossing the threshold: a moderate shock sustained long enough is equivalent to a large transient shock. This mechanism provides a theoretical account of the inflation regime shifts observed in economies where speculative land demand is quantitatively important—including emerging economies with shallow financial markets and recurrent episodes of high inflation, of the kind analyzed empirically by Hirano and Stiglitz (Reference Hirano and Stiglitz2025)—without requiring any change in the underlying structural parameters or policy rule.
6. Policy mix
To study within-regime stabilization, consider a small persistent disturbance
 $\delta d$
to demographic pressure around the low stable steady state
 $\pi _{L}$
. Linearizing the T-map around
 $(\pi _{L},\,\bar{\kern-3pt d})$
yields local equilibrium sensitivities
 \begin{equation*} K_{\pi }\equiv \partial \hat{\pi }/\partial d=T_{d}(\hat{\pi },\,\bar{\kern-3pt d})/(1-T_{\mu }(\hat{\pi },\,\bar{\kern-3pt d})), \end{equation*}
 \begin{equation*} K_{x}\equiv \partial \hat{x}/\partial d=-c(\eta _{q})K_{\pi }, \end{equation*}
 \begin{equation*} W_{\delta d}(\eta _{q},\tau )\equiv (\delta d)^{2}\left({K}_{\pi }^{2}+\lambda _{x}{K}_{x}^{2}\right)+\lambda _{\tau }\tau ^{2},\quad \lambda _{x}\geq 0,\,\lambda _{\tau }\geq 0. \end{equation*}
This metric is explicitly local and within-regime: it captures how a small persistent disturbance is transmitted around
 $\pi _{L}$
and does not incorporate the global probability of crossing the unstable threshold
 $\pi _{M}$
, which is analyzed separately in Proposition 3. Both instruments affect
 $W_{\delta d}$
through distinct structural channels. A larger
 $\eta _{q}$
raises
 $a_{q}$
, increasing
 $c(\eta _{q})$
and therefore the output-exposure term for given
 $K_{\pi }$
. A higher
 $\tau$
leaves
 $a_{q}$
and
 $c(\eta _{q})$
unchanged at fixed
 $\eta _{q}$
, but can reduce the local amplification term
 $K_{\pi }$
.
Proposition 4
(Complementarity and local stabilization dominance of fiscal policy). Suppose restriction (6) holds,
 $\eta _{x}\gt 0$
,
 $\lambda _{x}\geq 0$
,
 $\lambda _{\tau }\geq 0$
, and evaluate local dynamics around the low stable steady state
 $\pi _{L}$
.
-
1. The set
$S=\{(\eta _{q},\tau )\colon C(\tau ,\eta _{q})\,\chi _{\pi }\lt 4\}$
is non-empty. -
2. On the boundary of
$S$
,
$\,\bar{\kern-3pt \eta }_{q}(\tau )$
is weakly decreasing in
$\tau$
and strictly so whenever
$\,\bar{\kern-3pt \eta }_{q}(\tau )\gt 0$
. -
3. Along any iso-
$m$
schedule, increasing
$\tau$
and simultaneously reducing
$\eta _{q}$
to keep
$m$
constant strictly reduces the output-gap sensitivity to land-price fluctuations:
$\left.\partial a_{q}/\partial \tau \right| _{m=\text{const}}\lt 0$
. -
4. At any fixed
$\eta _{q}\geq 0$
, the right-derivative of
$W_{\delta d}$
with respect to
$\tau$
at
$\tau =0$
is strictly negative around
$\pi _{L}$
for any
$\lambda _{x}\geq 0$
and any finite
$\lambda _{\tau }\geq 0$
. Hence a sufficiently small increase in
$\tau$
from zero is a first-order improvement in the local stabilization metric
$W_{\delta d}$
near the low stable regime.
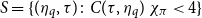


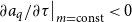


Proof.
Parts 1 and 2 follow from Proposition 2 and Corollary 2. For Part 3, on any iso-
 $m$
schedule
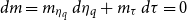 $dm=m_{{\eta _{q}}}\,d\eta _{q}+m_{\tau }\,d\tau =0$
gives
 \begin{equation*} \left.\frac{d\eta _{q}}{d\tau }\right| _{m=\text{const}}=-\frac{m_{\tau }}{m_{{\eta _{q}}}}. \end{equation*}
Both
 $m_{\tau }\lt 0$
and
 $m_{{\eta _{q}}}\lt 0$
. Therefore
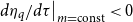 $\left.d\eta _{q}/d\tau \right| _{m=\text{const}}\lt 0$
: on iso-
 $m$
,
 $\tau \uparrow$
requires
 $\eta _{q}\downarrow$
, so
 $a_{q}=\eta _{q}/\eta _{x}$
strictly decreases.
For Part 4, fix
 $\eta _{q}$
and evaluate local dynamics around
 $\hat{\pi }=\pi _{L}$
, with
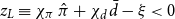 $z_{L}\equiv \chi _{\pi }\,\hat{\pi }+\chi _{d}\,\,\bar{\kern-3pt d}-\xi \lt 0$
. The proof proceeds in four steps.
-
Step 1. At fixed
$\eta _{q}$
,
$c(\eta _{q})=a_{\pi }+a_{q}/B(\eta _{q})$
is constant with respect to
$\tau$
. -
Step 2. By Corollary 1,
$\partial \hat{\pi }/\partial \tau \lt 0$
at fixed
$\eta _{q}$
. Therefore
$z_{L}$
falls with
$\tau$
. -
Step 3. Let
$T_{\mu }\equiv \partial T/\partial \mu$
and
$T_{d}\equiv \partial T/\partial d$
, both evaluated at
$(\hat{\pi },\,\bar{\kern-3pt d})$
. Differentiating the T-map with respect to
$\tau$
at fixed
$\eta _{q}$
:

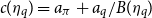


 \begin{equation*} \frac{\partial T_{\mu }}{\partial \tau }=\frac{\varphi _{q}\eta _{x}-\kappa \eta _{q}}{\eta _{x}+\kappa \eta _{\pi }}\left[-\nu \chi _{\pi }\Theta \mathrm{'}\left(z_{L}\right)+\nu \left(1-\tau \right){\chi }_{\pi }^{2}\Theta ''\left(z_{L}\right)\,\frac{\partial \hat{\pi }}{\partial \tau }\right]. \end{equation*}
Both bracket terms are negative: the first because
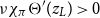 $\nu \chi _{\pi }\Theta \mathrm{'}(z_{L})\gt 0$
; the second because
 $\Theta ''(z_{L})\gt 0$
(since
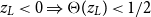 $z_{L}\lt 0\Rightarrow \Theta (z_{L})\lt 1/2$
) and
 $\partial \hat{\pi }/\partial \tau \lt 0$
(Step 2). Hence
 $T_{\mu ,\tau }\lt 0$
. An identical argument gives
 $T_{d,\tau }\lt 0$
.
Since
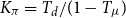 $K_{\pi }=T_{d}/(1-T_{\mu })$
:
 \begin{equation*} \frac{\partial K_{\pi }}{\partial \tau }=\frac{T_{d,\tau }(1-T_{\mu })+T_{d}\,T_{\mu ,\tau }}{(1-T_{\mu })^{2}}\lt 0, \end{equation*}
because the numerator has two strictly negative terms:
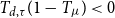 $T_{d,\tau }(1-T_{\mu })\lt 0$
(since
 $T_{d,\tau }\lt 0$
and
 $1-T_{\mu }\gt 0$
) and
 $T_{d}T_{\mu ,\tau }\lt 0$
(since
 $T_{d}\gt 0$
and
 $T_{\mu ,\tau }\lt 0$
), with
 $(1-T_{\mu })^{2}\gt 0$
at the E-stable low steady state where
 $T_{\mu }\lt 1$
.
Step 4. Since
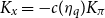 $K_{x}=-c(\eta _{q})K_{\pi }$
and
 $c(\eta _{q})$
is constant at fixed
 $\eta _{q}$
,
 $| K_{x}|$
also declines with
 $\tau$
. Therefore:
 \begin{equation*} \left.\frac{\partial W_{\delta d}}{\partial \tau }\right| _{\left\{\tau ={0^{+}}\right\}}=2(\delta d)^{2}K_{\pi }\left(\frac{\partial K_{\pi }}{\partial \tau }\right)[1+\lambda _{x}c(\eta _{q})^{2}]\lt 0 \end{equation*}
for any
 $\lambda _{x}\geq 0$
and any finite
 $\lambda _{\tau }\geq 0$
. Hence a sufficiently small increase in
 $\tau$
from zero strictly lowers the local quadratic stabilization loss
 $W_{\delta d}$
.
Figure 5 maps the policy schedule
 $\,\bar{\kern-3pt \eta }_{q}(\tau )$
from Corollary 2. The frontier is weakly decreasing: strictly so while the expression inside the max operator is positive, and flat at zero thereafter. This schedule captures the sufficient global-uniqueness margin under the maintained logistic specification. Proposition 4 adds a distinct local result: around the low stable regime,
 $\tau$
also improves the within-regime stabilization metric
 $W_{\delta d}$
as a standalone tool.
The complementarity result in Proposition 4 turns on a structural asymmetry in how the two instruments enter the local stabilization metric
 $W_{\delta d}$
.
 $\eta _{q}$
reduces the local amplification coefficient
 $K_{\pi }$
—because a stronger monetary response to land prices dampens the feedback—but simultaneously raises
 $a_{q}=\eta _{q}/\eta _{x}$
and therefore
 $c(\eta _{q})$
, increasing the output-gap sensitivity of the economy to land-price fluctuations. The fiscal instrument
 $\tau$
has no such trade-off: at fixed monetary policy, a higher tax on speculative demand reduces
 $K_{\pi }$
by directly compressing the net return to speculation—lowering
 $\Theta '(.)$
and hence
 $T_{\mu }$
and
 $T_{d}$
simultaneously, as shown in Steps 2 and 3 of the proof—without altering
 $a_{q}$
or
 $c(\eta _{q})$
. In this within-regime sense,
 $\tau$
provides first-order stabilization relief that
 $\eta _{q}$
cannot replicate without an output cost. The two instruments are therefore genuine complements rather than substitutes:
 $\eta _{q}$
and
 $\tau$
jointly determine the global uniqueness margin through
 $m(\eta _{q},\tau )\lt 4$
(Proposition 2), while
 $\tau$
additionally provides local stabilization improvement around
 $\pi _{L}$
that is independent of the monetary stance. This separation of roles—global regime control shared between instruments, local amplification reduction assigned to the fiscal instrument—is consistent with the broader principle established by Farhi and Werning (Reference Farhi and Werning2016) that monetary and macroprudential instruments play distinct, non-redundant roles in economies with nominal rigidities.
This result is local by construction. It does not claim global welfare dominance once regime-switch risk is taken into account; Proposition 3 addresses that separate margin. Its point is narrower but still important: around the low stable regime,
 $\tau$
and
 $\eta _{q}$
operate through different local channels. Raising
 $\eta _{q}$
can reduce amplification but also raises
 $a_{q}$
and therefore
 $c(\eta _{q})$
, increasing the output-exposure term in the local loss. Raising
 $\tau$
reduces the local amplification coefficient
 $K_{\pi }$
without changing
 $a_{q}$
or
 $c(\eta _{q})$
at fixed monetary policy. In this within-regime sense, the fiscal instrument is a first-order local stabilization improvement from
 $\tau =0$
.
7. Policy Implications
The four results established above—amplification, multiplicity, hysteresis, and instrument complementarity—form a coherent account of why inflation can be both persistent and difficult to control in economies where land markets are active and financially shallow. Taken together, they describe a progression: land prices amplify steady-state inflation even when the equilibrium is unique (Corollary 1); under sufficiently strong speculative demand, the economy can sustain multiple inflation levels simultaneously (Proposition 1); a transitory shock can permanently displace the economy from a low- to a high-inflation regime without any change in structural parameters or policy (Proposition 3); and the appropriate policy response combines monetary and fiscal instruments in a way that standard single-instrument analysis misses (Proposition 4). This section draws out the empirical and policy implications of this progression.
The theory yields several testable implications. First, economies with more inelastic urban land supply (larger
 $\psi$
) should display stronger pass-through from demographic pressure to land prices and therefore higher steady-state inflation for a given policy rule. This follows from Corollary 1 and is consistent with the empirical evidence in Iacoviello and Neri (Reference Iacoviello and Neri2010) and Bekiros et al. (Reference Bekiros, Nilavongse and Uddin2020).
Second, multiplicity requires not only strong speculative responsiveness but also an interior threshold configuration—conditions (C1), (C3), and (C4). Empirically, regime shifts should be more likely where land speculation becomes highly elastic only after inflation or demographic pressure crosses a salient threshold, consistent with the housing market evidence of Brunnermeier and Julliard (Reference Brunnermeier and Julliard2008) and with the recurrent fluctuations in land speculation economies analyzed by Hirano and Stiglitz (Reference Hirano and Stiglitz2025).
Third, the model predicts threshold behavior rather than a linear amplification mechanism. Small shocks dissipate in the low-inflation regime while sufficiently large or persistent shocks induce a permanent transition to the high-inflation regime. This nonlinearity is consistent with the asymmetric price-setting evidence in Bunn et al. (Reference Bunn, Anayi, Barnes, Bloom, Jalca, Mizen, Thwaites and Yotzov2024) and with the post-pandemic inflation surge analyzed by Gagliardone et al. (Reference Gagliardone, Gertler, Lenzu and Tielens2025).
Fourth, policy evaluation should not focus solely on the inflation coefficient in the Taylor rule. The relevant global statistic for multiplicity prevention is the composite slope bound
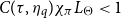 $C(\tau ,\eta _{q})\chi _{\pi }L_{\Theta }\lt 1$
, which under the logistic benchmark becomes
 $m\lt 4$
(Proposition 2 and Corollary 2). The numerical threshold 4 is a benchmark ceiling, not a universal target; under any alternative smooth sigmoidal demand function with maximal slope
 $M$
, the threshold is
 $1/M$
and must be estimated empirically. Moreover, Proposition 4 establishes that, around the low stable regime, a tax on speculative land demand is a first-order improvement in the local stabilization metric
 $W_{\delta d}$
for any weighting of inflation and output, because it lowers the local amplification coefficient
 $K_{\pi }$
without raising output-gap sensitivity to land prices. Standard linearized impulse-response analysis around a single equilibrium misses both the multiplicity dimension and this instrument asymmetry, systematically understating the value of a policy mix that combines monetary and fiscal tools.
Fifth, the mechanism in Appendix A.3 links the speculative sensitivity
 $\chi _{\pi }$
to the structure of financial intermediation: to the extent that policy-rate increases are absorbed by intermediation spreads and channeled into public-sector debt rather than passed through to depositors, the model implies a higher
 $\chi _{\pi }$
and a correspondingly larger multiplicity region. This yields a testable cross-country implication: if the mechanism proposed here is operative, inflation hysteresis of the kind characterized in Proposition 3 should be more likely in economies combining shallow deposit markets with a strong sovereign–bank nexus, and less likely where deposit rates track the policy rate closely. The framework thus generates a prediction that distinguishes it from models in which the Taylor coefficient alone governs regime uniqueness; evaluating it empirically—for instance, by relating measures of deposit-rate pass-through to the incidence of persistent inflation regimes—is beyond the scope of this paper and is left for future work.
These implications are particularly relevant for emerging economies with shallow financial markets, where real estate and urban land serve as primary stores of value in the absence of deep capital markets. In such economies—including several in Latin America, Sub-Saharan Africa, and South and Southeast Asia—the speculative sensitivity
 $\chi _{\pi }$
is likely to be high, the fiscal instrument
 $\tau$
may be easier to implement than a finely calibrated monetary response to land prices, and the risk of permanent regime transitions following demographic or terms-of-trade shocks is empirically relevant. The framework developed here provides a theoretical foundation for the observation, documented across multiple high-inflation episodes, that stabilization requires more than a sufficiently aggressive Taylor rule: it requires a coordinated policy mix that directly addresses the speculative land demand channel through which inflation expectations become self-fulfilling.
8. Conclusion
This paper develops a theory of inflation persistence grounded in a market friction that standard New Keynesian models abstract from: the dual role of urban land as a productive input and a speculative store of value. When households treat land as a hedge against inflation, a bidirectional feedback emerges between inflation expectations and land prices that can sustain multiple inflation levels as learnable rational expectations equilibria, generate permanent regime transitions from transitory shocks, and render standard single-instrument monetary policy insufficient for stabilization. The framework is deliberately parsimonious—a reduced-form OLG structure for asset markets embedded in a standard NK block—so that the fixed-point geometry of the inflation map can be characterized analytically and the conditions for multiplicity, hysteresis, and instrument complementarity can be stated as closed-form restrictions on observable parameters. The central policy message is that the relevant sufficient statistic for regime uniqueness is not the Taylor coefficient
 $\eta _{\pi }$
alone but the composite
 $m(\eta _{q},\tau )$
, which aggregates monetary responsiveness to land prices, the fiscal stance on speculative demand, market-clearing amplification, and speculative sensitivity into a single object. Monitoring and targeting
 $m$
below the critical threshold—rather than relying on
 $\eta _{\pi }$
to do all the stabilization work—is the operational implication of the complementarity result in Proposition 4, and is particularly relevant for economies where speculative land demand is quantitatively important and financial markets are shallow.
The main findings are as follows. Land prices amplify steady-state inflation even when the equilibrium is unique (Corollary 1). A general bounded-slope condition guarantees global uniqueness; under the logistic benchmark this yields the sufficient threshold
 $m\lt 4$
and the associated policy schedule
 $\,\bar{\kern-3pt \eta }_{q}(\tau )$
(Proposition 2 and Corollary 2). Multiple non-negative steady states arise only when the composite slope exceeds one around an interior inflection point and the turning-point sign conditions hold (Proposition 1); condition (C2) is automatically satisfied, and the binding restrictions are (C1), (C3), and (C4). Temporary demographic-pressure shocks can generate persistent transitions to high inflation only when parameters lie in the three-steady-state region (Proposition 3). Around the low stable regime, a tax on speculative land demand is a first-order improvement in the local stabilization metric
 $W_{\delta d}$
for any weighting of inflation and output: at fixed monetary policy, it strictly lowers
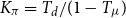 $K_{\pi }=T_{d}/(1-T_{\mu })$
without the output-exposure cost that raising
 $\eta _{q}$
entails (Proposition 4). The two instruments are genuine complements: they jointly relax the sufficient global uniqueness condition, and the fiscal instrument additionally provides local stabilization relief around the low regime.
Natural extensions include incorporating financial frictions of the kind analyzed by Hirano and Stiglitz (Reference Hirano and Stiglitz2024, Reference Hirano and Stiglitz2025), embedding the model within an OLG-NK framework with rational bubbles following Galí (Reference Galí2021), and estimating the shape of speculative demand empirically to calibrate the threshold
 $\xi$
and the sensitivity
 $\chi _{\pi }$
from housing market data. Appendices A and B provide microfoundations for Equations (1) and (2) respectively; a natural next step is to embed those microfoundations in a fully estimated structural model that disciplines the deeper parameters—including the distribution of entry costs
 $F_{i}$
and the land cost share
 $\alpha _{q}$
—against disaggregated firm and household data.
Appendix A
Microfoundation of Speculative Land Demand (Equation 1).
A.1 Portfolio problem and participation decision
Consider the two-period overlapping-generations structure introduced in Section 2.2. A young household born in period
 $t$
receives wage income
 $w_{t}$
, consumes
 $c_{t}$
, and saves
 $a_{t}=w_{t}-c_{t}$
. Savings can be allocated between one-period nominal bonds, with gross nominal return
 ${R}_{t}^{n}$
, and urban land.
Let
 $\gamma _{t}\in [0,1]$
denote the portfolio share placed in land. The household holds
 $\gamma _{t}a_{t}/q_{t}$
units of land and
 $(1-\gamma _{t})a_{t}$
units of nominal bonds. The nominal gross return on land between
 $t$
and
 $t+1$
is:
 \begin{equation}{R}_{t}^{\text{land}}=\frac{q_{t+1}\left(1+\pi _{t+1}\right)}{q_{t}}\end{equation}
where
 $q_{t}$
is the real land price and
 $\pi _{t+1}$
is the inflation rate between
 $t$
and
 $t+1$
. Consumption when old equals portfolio wealth:
 \begin{equation}{c}_{t+1}^{\mathrm{old}}=\gamma _{t}a_{t}{R}_{t}^{\text{land}}+\left(1-\gamma _{t}\right)a_{t}{R}_{t}^{\mathrm{n}}\end{equation}
A.2 Idiosyncratic entry costs and the participation margin
Entering the speculative land market entails a household-specific cost
 $F_{i}$
, which captures transaction costs, regulatory frictions, organizational inertia, or informational barriers. This heterogeneity is consistent with the threshold behavior documented in urban housing markets by Brunnermeier and Julliard (Reference Brunnermeier and Julliard2008). The entry cost is measured in return-equivalent units, normalized by the household’s potential speculative exposure.
Formally, household
 $i$
chooses whether to enter the speculative land market. Let
 $I_{it}\in \{0,1\}$
denote participation. The participation decision can be written as:
 \begin{equation*} \max _{I_{\text{it}}\in \left\{0,1\right\}} I_{it}\big[E_{t}\big({R}_{t}^{land}\big)-{R}_{t}^{n}-F_{i}\big] \end{equation*}
The solution to this binary choice problem implies that household
 $i$
participates in speculative land demand if and only if the expected excess return covers its entry cost:
 \begin{equation*} I_{it}=1\Longleftrightarrow E_{t}\big({R}_{t}^{land}\big)-{R}_{t}^{n}\geq F_{i} \end{equation*}
Suppose that household
 $i$
faces a participation cost
 $F_{i}=\,\bar{\kern-3pt F}+\ \tilde{\kern-3pt F}_{i}$
, where
 $\,\bar{\kern-3pt F}$
denotes the average participation cost and
 $\ \tilde{\kern-3pt F}_{i}$
is independently and identically distributed across households according to a standard logistic distribution with scale normalized to one. A household participates in speculative land demand whenever the expected excess return from land exceeds its participation cost. Hence
 \begin{equation} {\gamma }_{t}^{\mathrm{s}}=\Pr \big[\,\bar{\kern-3pt F}+\ \tilde{\kern-3pt F}_{i}\leq E_{t}\big({R}_{t}^{land}\big)-{R}_{t}^{n}\big] \end{equation}
Using the logistic distribution, this becomes
 \begin{equation}{\gamma }_{t}^{\mathrm{s}}=\Theta \big(E_{t}\big({R}_{t}^{land}\big)-{R}_{t}^{\mathrm{n}}-\,\bar{\kern-3pt F}\,\big)\end{equation}
where
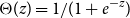 $\Theta (z)=1/(1+e^{-z})$
is the standard logistic CDF. The constant terms in the log-linearized expected excess return—including the steady-state real bond return, the average participation cost
 $\,\bar{\! F}$
, and other institutional or informational participation frictions—are absorbed into the composite threshold parameter
 $\xi$
. Thus the speculative participation rule can be written as
 \begin{equation*} {\gamma }_{t}^{\mathrm{s}}=\Theta (\chi _{\pi }E_{t}\pi _{t+1}+\chi _{d}d_{t}-\xi ) \end{equation*}
The parameter
 $\xi$
should therefore be interpreted as a composite participation threshold: it captures the minimum strength of the inflation-hedge motive required to trigger aggressive reallocation toward land after accounting for fixed costs, return differentials, and institutional frictions. The logistic functional form is adopted for analytical tractability; the qualitative results hold for any smooth sigmoidal
 $\Theta$
satisfying
 $\Theta \mathrm{'}\gt 0$
and bounded slope.
A.3 Restricted perceptions equilibrium for land prices
To make (A.4) operational, one must specify how agents form
 $E_{t}[{R}_{t}^{land}]$
. The argument of
 $\Theta$
depends on
 $E_{t}[q_{t+1}]$
, which is itself endogenous to the distribution of speculative participation: under full rational expectations, agents would solve for the equilibrium map
 $q_{t}({\gamma }_{t}^{s},d_{t})$
and invert it to form
 $E_{t}[q_{t+1}]$
, introducing a fixed-point argument in which
 ${\gamma }_{t}^{s}$
depends on
 $E_{t}[q_{t+1}]$
, which itself depends on
 ${\gamma }_{t+1}^{s}$
. While this system is well-defined in principle, it generates additional nonlinearities that substantially complicate the derivation of the T-map and the global stability results of Propositions 1 and 3 without altering any of the qualitative conclusions. We therefore follow the adaptive-learning approach of Evans and Honkapohja (Reference Evans and Honkapohja2001) and model agents as holding a restricted PLM in which
 $q_{t+1}$
is projected linearly onto variables observable at
 $t$
: current demographic pressure
 $d_{t}$
and expected inflation
 $E_{t}[\pi _{t+1}]$
. This RPE approach is fully consistent with the learning foundation of the paper and avoids the circularity of the full rational expectations fixed point.
Formally, agents hold the perceived law of motion:
 \begin{equation}E_{t}q_{t+1}=\alpha _{d}d_{t}+\alpha _{\pi }E_{t}\pi _{t+1}\end{equation}
Log-linearizing the nominal land return around the non-stochastic steady state (
 $\,\bar{\kern-3pt q}, \,\bar{\kern-3pt \pi}, \,\bar{\kern-3pt R}{^n}$
) and substituting (A.5):
 \begin{equation}E_{t}\big[{R}_{t}^{\text{land}}\big]-{R}_{t}^{\mathrm{n}}\approx \left(\frac{\alpha _{\pi }}{\,\bar{\kern-3pt q}}+1\right)E_{t}\pi _{t+1}+\frac{\alpha _{d}}{\,\bar{\kern-3pt q}}d_{t}-\,\bar{\kern-3pt r}\end{equation}
Defining
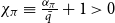 $\chi _{\pi }\equiv \frac{\alpha _{\pi }}{\,\bar{\kern-3pt q}}+1\gt 0$
,
 $\chi _{d}\equiv \frac{\alpha _{d}}{\,\bar{\kern-3pt q}}\gt 0$
, and absorbing the constant terms in the expected excess return—including the steady-state bond-return component, the average participation cost
 $\,\bar{\! F}$
, and other institutional or informational frictions—into the composite threshold
 $\xi$
, equation (A.4) becomes:
 \begin{equation}{\gamma }_{t}^{\mathrm{s}}=\Theta \left(\chi _{\pi }E_{t}\pi _{t+1}+\chi _{d}d_{t}-\xi \right)\end{equation}
This is exactly the threshold speculative demand rule used in the paper, with
 $\chi _{\pi }$
and
 $\chi _{d}$
interpreted as functions of the PLM coefficients (
 $\alpha _{\pi }$
,
 $\alpha _{d}$
) and the steady-state real land price
 $\,\bar{\kern-3pt q}$
, and with
 $\xi$
interpreted as a composite participation threshold rather than as a single primitive return parameter.
A remark on the bond return is warranted. The linearization in (A.6) treats the return relevant to the household’s outside option as a constant absorbed into the composite threshold
 $\xi$
. Under a literal reading in which households’ alternative asset pays the policy rate
 $i_{t}$
from the Taylor rule (4), this would be restrictive: with
 $\eta _{\pi }\gt 1$
, the nominal bond return rises more than one-for-one with inflation, which would dampen—and could in principle reverse—the sensitivity of the expected excess land return to
 $E_{t}\pi _{t+1}$
. The specification
 $\chi _{\pi }\gt 0$
therefore embeds the assumption that the pass-through from the policy rate to the savings instruments actually available to households is incomplete. This assumption is not merely a reduced-form convenience; it reflects a structural feature of the financially shallow, high-inflation economies that motivate the paper. In such environments, policy-rate increases are largely appropriated by the banking system rather than transmitted to depositors: under fiscal dominance and elevated sovereign financing needs, holding remunerated central-bank paper and short-term government debt becomes the dominant—often the only viable—use of bank funding, so the spread between the policy rate and the deposit rates actually available to households widens precisely when the policy rate rises. The crowding of bank balance sheets into public-sector assets, a manifestation of the sovereign–bank nexus and of financial repression more broadly, thus makes the pass-through incompleteness endogenous to the high-inflation regime itself: household savings remain in cash, low-remuneration deposits, or foreign currency, while the marginal return to the policy tightening accrues to intermediaries. Under these conditions, land is the household sector’s residual inflation hedge, and the sensitivity
 $\chi _{\pi }$
is correspondingly high. It is also consistent with the money-illusion evidence of Brunnermeier and Julliard (Reference Brunnermeier and Julliard2008), who document that households evaluate housing returns in nominal terms and systematically fail to net out the inflation component of the alternative asset’s yield. Formally, if the household-relevant bond return satisfies
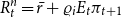 ${R}_{t}^{n}=\,\bar{\kern-3pt r}+\varrho _{i}E_{t}\pi _{t+1}$
with pass-through
 $\varrho _{i}\in [0,1)$
, the derivation in (A.6) goes through with
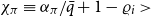 $\chi _{\pi }\equiv \alpha _{\pi }/\,\bar{\kern-3pt q}+1-\varrho _{i}\gt$
0, and
 $\chi _{\pi }$
inherits the additional interpretation of an inverse measure of financial depth: economies with more complete pass-through (
 $\varrho _{i}$
closer to one) exhibit weaker speculative sensitivity, a smaller open-loop gain
 $m$
, and a correspondingly smaller multiplicity region. The benchmark
 $\varrho _{i}$
maintained in the text is thus the polar case appropriate for the financially shallow economies on which the analysis focuses. The mechanism further suggests that
 $\varrho _{i}$
is itself decreasing in the inflation environment—intermediation spreads and the reallocation of bank assets toward public debt widen in high-inflation episodes—so that the effective speculative sensitivity is strongest precisely in the region of the state space where the multiplicity and hysteresis results operate. Formalizing a state-dependent
 $\varrho _{i}(\pi )$
is left for future work.
A.4 Consistency of the restricted perceptions equilibrium
The PLM coefficients (
 $\alpha _{\pi }$
,
 $\alpha _{d}$
) are not free parameters: in a restricted perceptions equilibrium they must be consistent with the actual law of motion of
 $q_{t}$
. Total demographic pressure is:
 \begin{equation*} d_{t}=\,\bar{\kern-3pt d}+\ \tilde{\kern-3pt d}_{t} \end{equation*}
where
 $\,\bar{\kern-3pt d}\gt 0$
is the long-run average pressure on central urban land and
 $\ \tilde{\kern-3pt d}_{t}$
is the stationary cyclical component. The latter satisfies:
 \begin{equation*} E_{t}\ \tilde{\kern-3pt d}_{t+1}=\rho _{d}\ \tilde{\kern-3pt d}_{t} \end{equation*}
Equivalently, since
 $\ \tilde{\kern-3pt d}_{t}=d_{t}-\,\bar{\kern-3pt d}$
, it follows that:
 \begin{equation*} E_{t}d_{t+1}=\,\bar{\kern-3pt d}+\rho _{d}(d_{t}-\,\bar{\kern-3pt d}) \end{equation*}
The perceived law of motion is therefore written in deviations from the non-stochastic steady state:
 \begin{equation}E_{t}q_{t+1}=\,\bar{\kern-3pt q}+\alpha _{d}(d_{t}-\,\bar{\kern-3pt d})+\alpha _{\pi }\left(E_{t}\pi _{t+1}-\,\bar{\kern-3pt \pi }\right)\end{equation}
Taking conditional expectations of the land-market clearing Equation (1) at
 $t+1$
, and using the constant-inflation PLM:
 \begin{equation*} {E_{t+1}}{\pi _{t+2}}\approx E_{t}\pi _{t+1} \end{equation*}
gives the following linearized actual law of motion around the non-stochastic steady state:
 \begin{equation}E_{t}q_{t+1}-\,\bar{\kern-3pt q}\approx \big[\psi \rho _{d}+\nu \left(1-\tau \right)\,\bar{\kern-1pt \Theta }'\chi _{d}\rho _{d}\big](d_{t}-\,\bar{\kern-3pt d})+\nu \left(1-\tau \right)\,\bar{\kern-1pt \Theta }'\chi _{\pi }\left(E_{t}\pi _{t+1}-\,\bar{\kern-3pt \pi }\right)\end{equation}
Matching coefficients between the centered PLM in (A.5 ′) and the linearized ALM in (A.8) yields:
 \begin{equation}\alpha _{d}=\psi \rho _{d}+\nu \left(1-\tau \right)\,\bar{\kern-1pt \Theta }'\chi _{d}\rho _{d}\end{equation}
 \begin{equation}\alpha _{\pi }=\nu \left(1-\tau \right)\,\bar{\kern-1pt \Theta }'\chi _{\pi }\end{equation}
These conditions determine
 $\alpha _{\pi }$
and
 $\alpha _{d}$
entirely from structural parameters
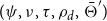 $(\psi ,\nu ,\tau ,\rho _{d},\,\bar{\kern-1pt \Theta }')$
and the sensitivity coefficients (
 $\chi _{\pi }$
,
 $\chi _{d}$
). No additional free parameters are introduced beyond the reference steady state at which the RPE is evaluated. The RPE is internally consistent under the constant-inflation PLM, and the parameters
 $\chi _{\pi }$
and
 $\chi _{d}$
in Equation (1) are properly interpreted as reduced-form composites of the deeper structural parameters appearing in (A.9).
Three remarks on the scope of this consistency argument are in order. First, conditions (A.9a) and (A.9b) jointly with the definitions
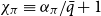 $\chi _{\pi }\equiv \alpha _{\pi }/\,\bar{\kern-3pt q}+1$
and
 $\chi _{d}\equiv \alpha _{d}/\,\bar{\kern-3pt q}$
define the RPE coefficients as the solution of a fixed-point problem evaluated at the reference steady state around which the PLM is anchored—throughout the paper, the low stable regime
 $\pi _{L}$
, since
 $\,\bar{\kern-1pt \Theta }'$
is steady-state specific. Solving the fixed point for the inflation coefficient yields
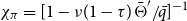 $\chi _{\pi }=[1-\nu (1-\tau )\,\bar{\kern-1pt \Theta }'/\,\bar{\kern-3pt q}]^{-1}$
, so existence and positivity of the RPE require the mild condition
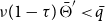 $\nu (1-\tau )\,\bar{\kern-1pt \Theta }'\lt \,\bar{\kern-3pt q}$
, which holds at the low regime under the baseline calibration. In the main text,
 $\chi _{\pi }$
and
 $\chi _{d}$
are accordingly treated as reduced-form composites held fixed at their baseline values; the numerical illustration should be read as a calibration of these composites, not of the deeper PLM coefficients.
Second, because
 $\alpha _{\pi }$
in (A.9b) is proportional to
 $(1-\tau )$
, the RPE introduces an additional channel through which the fiscal instrument operates: a higher
 $\tau$
lowers the consistent value of
 $\chi _{\pi }$
itself, over and above the direct effect through
 $C(\tau ,\eta _{q})$
analyzed in Proposition 4. This additional effect works in the same direction as the direct effect—it further compresses the open-loop gain
 $m$
and the local amplification coefficient
 $K_{\pi }$
—so holding
 $\chi _{\pi }$
fixed in the comparative statics of Propositions 2 and 4 is conservative: the full RPE-consistent response to
 $\tau$
is weakly stronger than the one reported.
Third, the log-linearization in (A.6) abstracts from the contemporaneous-price term
 $-\hat{q}_{t}$
that would appear in an unrestricted expansion of
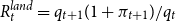 ${R}_{t}^{land}=q_{t+1}(1+\pi _{t+1})/q_{t}$
. This is a feature of the restricted PLM, not an omission: agents project expected land appreciation directly onto the observables
 $(d_{t},E_{t}\pi _{t+1})$
, as specified in (A.5), rather than forecasting the level
 $q_{t+1}$
and netting out the current price. Including the
 $-\hat{q}_{t}$
term would introduce contemporaneous self-dampening feedback from prices to participation, lowering the effective open-loop gain; the multiplicity region would then require a correspondingly larger
 $\nu \chi _{\pi }$
, but the fixed-point geometry of Propositions 1 and 3—an S-shaped map with at most three non-negative crossings—would be unchanged.
A.5 Land market clearing and Equation (1)
Decomposing the aggregate portfolio share into a fundamental component
 ${\gamma }_{t}^{\,f}$
(driven by
 $d_{t}$
alone) and the speculative component
 ${\gamma }_{t}^{s}$
derived above, and using the steady-state savings approximation
 $a_{t}\approx \,\bar{\kern-3pt a}$
(standard in reduced-form OLG land-market models; Iacoviello Reference Iacoviello2005; Bekiros et al. Reference Bekiros, Nilavongse and Uddin2020), market clearing
 $q_{t}=\gamma _{t}\,\bar{\kern-3pt a}$
gives:
 \begin{equation*} q_{t}=\psi d_{t}+\nu (1-\tau _{t})\Theta (\chi _{\pi }E_{t}\pi _{t+1}+\chi _{d}d_{t}-\xi ) (\rm {A}.10) \equiv (1)\end{equation*}
This completes the microfoundation of Equation (1). The speculative term
 ${\gamma }_{t}^{s}$
is not an unconstrained ad hoc portfolio share. It is the aggregate participation-adjusted speculative share implied by a household participation problem with idiosyncratic entry costs. The three structural elements—the logistic participation rule arising from the distribution of entry costs, the argument
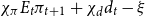 $\chi _{\pi }E_{t}\pi _{t+1}+\chi _{d}d_{t}-\xi$
arising from the log-linearized expected excess return under the restricted PLM, and the market-clearing condition under the steady-state savings approximation—each have an independent economic foundation. Together they yield Equation (1) as a derived rather than assumed relationship.
Appendix B
Microfoundation of the New Keynesian Phillips Curve with Land (Equation 2).
B.1 Production technology and real marginal cost
Each intermediate firm
 $j\in [0,1]$
produces a differentiated good using labor
 $N_{jt}$
and land services
 $L_{jt}$
according to the Cobb-Douglas technology
 \begin{equation}Y_{jt}=A{\,N_{jt}}^{1-{\alpha _{q}}}{L_{jt}}^{{\alpha _{q}}}\end{equation}
where
 $A$
is aggregate total factor productivity and
 $\alpha _{q}\in (0,1)$
is the cost share of land services. Land is supplied inelastically in aggregate, but individual firms rent land services in a competitive market and take the real rental price of land,
 $q_{t}$
, as given. The aggregate inelasticity of land supply is therefore reflected in the equilibrium price
 $q_{t}$
, not in a firm-level constraint that prevents land services from entering marginal cost.
Cost minimization subject to (B.1) yields nominal marginal cost:
 \begin{equation}MC_{jt}=\frac{1}{A}\left(\frac{W_{t}}{1-\alpha _{q}}\right)^{1-{\alpha _{q}}}\left(\frac{q_{t}P_{t}}{\alpha _{q}}\right)^{{\alpha _{q}}}\end{equation}
Note that
 $MC_{jt}$
is identical across firms because the real land price qt
is economy-wide and wages
 $W$
t are determined in a competitive labor market. Log-linearizing (B.2) around a zero-inflation steady state and defining real marginal cost as
 $mc_{t}\equiv MC_{t}/P_{t}$
:
 \begin{equation}mc_{t}=\omega x_{t}+\alpha _{q}q_{t}\end{equation}
where
 $\omega \gt 0$
absorbs the labor share and the output-gap elasticity of the real wage, and
 $x_{t}$
is the output gap. Equation (B.3) shows that real marginal cost rises with the output gap through the standard labor-market channel and with the real land price through the land-cost channel.
B.2 Calvo price setting and the Phillips curve
Intermediate firms set prices subject to Calvo (Reference Calvo1983) staggering: in each period a fraction
 $1-\theta$
of firms resets its price optimally, while the remaining fraction
 $\theta$
keeps its price unchanged. The standard Calvo log-linearization around a zero-inflation steady state (Clarida et al. Reference Clarida, Galí and Gertler1999) delivers:
 \begin{equation}\pi _{t}=\beta E_{t}\pi _{t+1}+\kappa mc_{t}\end{equation}
where
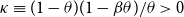 $\kappa \equiv (1-\theta )(1-\beta \theta )/\theta \gt 0$
is the Calvo slope, which depends solely on the price-adjustment frequency
 $1-\theta$
and the discount factor
 $\beta$
. Substituting (B.3) into (B.4):
 \begin{equation}\pi _{t}=\beta E_{t}\pi _{t+1}+\kappa \omega x_{t}+\kappa \alpha _{q}q_{t}\end{equation}
Redefining
 $\kappa \omega \equiv \kappa$
(the slope on the output gap, absorbing
 $\omega$
into the normalization of
 $x_{t}$
) and setting
 $\varphi _{q}\equiv \kappa \alpha _{q}$
yields Equation (2) of the paper:
 \begin{equation*} \pi _{t}=\beta E_{t}\pi _{t+1}+\kappa x_{t}+\varphi _{q}q_{t} (B.6) \equiv (2) \end{equation*}
B.3 Separability of
$\boldsymbol{\varphi }_{\boldsymbol{q}}$
from
$\boldsymbol{\kappa }$
: structural interpretation


The Cobb-Douglas derivation in B.1–B.2 establishes that land prices enter the Phillips curve through firms’ real marginal cost and delivers the structural restriction:
 \begin{equation*} \varphi _{q}\equiv \kappa \alpha _{q} \end{equation*}
This restriction links the pass-through coefficient
 $\varphi _{q}$
to the Calvo slope
 $\kappa$
through the land cost share
 $\alpha _{q}$
. It should not, however, be interpreted as implying that the land-cost channel and the standard output-gap channel are the same economic object. The relevant separability is economic rather than a claim of absolute parametric independence.
The reason is that the two components reflect structurally distinct margins. The coefficient
 $\kappa$
is determined by the frequency of price adjustment under Calvo pricing, while
 $\alpha _{q}$
reflects the cost share of land in production. Thus, even though the Cobb-Douglas benchmark implies
 $\varphi _{q}=\kappa \alpha _{q}$
, variation in
 $\varphi _{q}$
can arise from variation in the land-cost margin
 $\alpha _{q}$
, holding the price-adjustment margin fixed. This is the sense in which the main text treats
 $\varphi _{q}$
as a separate structural pass-through parameter.
This interpretation is consistent with the micro-level evidence of Gagliardone et al. (Reference Gagliardone, Gertler, Lenzu and Tielens2025), who show that cost-push channels and price-adjustment frequency operate through distinct margins. In the present model, the additive specification:
 \begin{equation*} \pi _{t}=\beta E_{t}\pi _{t+1}+\kappa x_{t}+\varphi _{q}q_{t} \end{equation*}
therefore, separates the standard output-gap channel from the land-cost channel, without requiring
 $\varphi _{q}$
to be absolutely independent of
 $\kappa$
. The analysis requires only
 $\varphi _{q}\gt 0$
and the maintained restriction
 $0\leq \kappa a_{q}\lt \varphi _{q}$
, where
 $a_{q}\equiv \frac{\eta _{q}}{\eta _{x}}$
is the output-gap sensitivity implied by the Taylor rule.
Here
 $\varphi _{q}$
denotes the structural land-price pass-through coefficient in the Phillips curve, while
 $\eta _{q}$
denotes the Taylor-rule response to land prices. The maintained restriction therefore holds whenever the monetary policy response to land prices,
 $\eta _{q}$
, is not too large relative to the structural pass-through coefficient,
 $\varphi _{q}$
. Hence, the additive specification in Equation (2) is internally consistent with the Calvo pricing model: Calvo pricing determines the adjustment-frequency margin, while the land cost share determines the strength of the land-price cost-push channel.
Appendix C
Consistency Between the Dynamic IS Equation and the Multiple-Asset OLG Block.
C.1 Household problem with two margins
Consider the two-period OLG structure of Section 2.2. A young household born in period
 $t$
receives wage income
 $w_{t}$
, consumes
 $c_{t}$
, and saves
 $a_{t}=w_{t}-c_{t}$
. Savings can be allocated between one-period nominal bonds, with gross nominal return
 ${R}_{t}^{n}$
, and urban land, with gross nominal return
 ${R}_{t}^{land}$
defined in Appendix A.
Let
 $\gamma _{t}\in [0,1]$
denote the share of savings allocated to land. Old-age consumption is
 \begin{equation*} c^{\left(t+1\right)old}=a_{t}\big[\gamma _{t}{R}_{t}^{land}+(1-\gamma _{t}{)R}_{t}^{n}\big] \end{equation*}
The household problem contains two conceptually distinct margins. The first is the intertemporal margin, which determines total saving
 $a_{t}$
. The second is the portfolio margin, which determines the allocation of savings between nominal bonds and land. The paper uses these two margins for different purposes: the intertemporal margin motivates the standard New Keynesian aggregate-demand closure, while the portfolio margin generates the speculative land-demand channel.
C.2 Intertemporal margin and the dynamic IS equation
Let
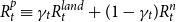 ${R}_{t}^{p}\equiv \gamma _{t}{R}_{t}^{land}+(1-\gamma _{t}{)R}_{t}^{n}$
denote the gross portfolio return. The intertemporal Euler condition can be written generically as
 \begin{equation}u'\left(c_{t}\right)=\beta E_{t}\big[u'\big(c^{\left(t+1\right)old}\big){R}_{t}^{p}\big]\end{equation}
In a fully integrated OLG-NK model, equation (C.1), together with market clearing and the policy rule, would determine aggregate demand. The present paper does not require that full integration. Instead, as stated in Section 2.3, Equation (3) is used as a reduced-form New Keynesian aggregate-demand closure:
 \begin{equation}x_{t}=E_{t}x_{t+1}-\sigma ^{-1}\left(i_{t}-E_{t}\pi _{t+1}-{r}_{t}^{n}\right)\end{equation}
This is the standard log-linear Euler-equation representation used in New Keynesian models. Its role in the present framework is to summarize the intertemporal aggregate-demand margin. The key restriction imposed by using Equation (3) is that, to first order, the bond return remains the marginal intertemporal price relevant for aggregate demand, while land-market frictions enter inflation dynamics through the separate cost-push and portfolio-demand channels.
In particular, this rules out a direct wealth effect of land-price changes on aggregate consumption demand—an effect that would arise in a fully integrated model but is not the mechanism the paper isolates. The multiplicity and hysteresis results do not depend on an additional nonlinear savings response. They are generated by the interaction between speculative land demand, land-price pass-through into marginal costs, and the Taylor rule. Endogenizing aggregate savings in the OLG block would add an additional dynamic margin, but it is not the source of the fixed-point geometry analyzed in the paper.
C.3 Portfolio margin and speculative land demand
The portfolio margin compares the expected payoff from holding land with the payoff from holding nominal bonds. Without participation frictions and for an interior portfolio choice, the usual first-order condition would equate risk-adjusted returns:
 \begin{equation}E_{t}\big[u'\big(c^{\left(t+1\right)old}\big)\big({R}_{t}^{land}-{R}_{t}^{n}\big)\big]=0\end{equation}
Appendix A departs from this frictionless benchmark by introducing idiosyncratic participation costs. With those costs, households do not all adjust land holdings at an interior margin. Instead, participation is governed by a threshold rule: a household enters the speculative land market only when the expected excess return from land exceeds its household-specific participation cost.
Aggregating this threshold decision across households yields the speculative participation share
 \begin{equation*} {\gamma }_{t}^{s}=\Theta (\chi _{\pi }E_{t}\pi _{t+1}+\chi _{d}d_{t}-\xi ) \end{equation*}
which is the speculative-demand component used in Equation (1). Thus, Equation (1) is not an additional Euler equation for aggregate consumption. It is the aggregate implication of the portfolio participation margin in the presence of heterogeneous entry costs.
C.4 Why the two blocks are internally consistent
The dynamic IS equation and the speculative land-demand equation operate on different margins. Equation (3) summarizes the intertemporal aggregate-demand margin through the standard New Keynesian Euler representation. Equation (1) summarizes the portfolio participation margin through which inflation expectations and demographic pressure affect speculative land demand and land prices.
The steady-state savings approximation
 $(a_{t}\approx \,\bar{\kern-3pt a})$
, used in Section 2.2 and Appendix A, is therefore applied only to the land-market clearing and portfolio-demand block. It does not assert that the aggregate-demand Euler equation is absent. Rather, the aggregate-demand Euler equation is summarized by the reduced-form IS curve in Equation (3).
In this sense, the model is modular but internally consistent. The NK block provides the standard intertemporal demand channel; the OLG asset-market block provides the land-specific portfolio channel. Combining them allows the paper to isolate the mechanism of interest: a feedback loop in which inflation expectations raise speculative land demand, land prices raise marginal costs, and marginal costs feed back into inflation.


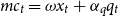

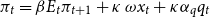


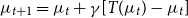


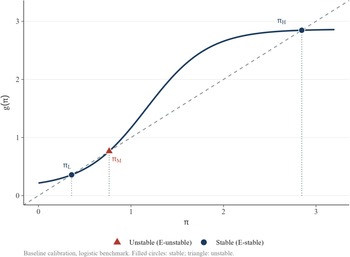


 η¯q(τ)


