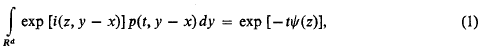
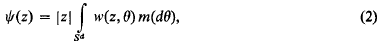
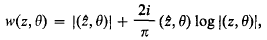
Hostname: page-component-7b7567c8c-mnklg Total loading time: 0 Render date: 2026-11-12T19:37:01.820Z Has data issue: false hasContentIssue false

Measure function properties of the asymmetric Cauchy process

Published online by Cambridge University Press:  26 February 2010

John Hawkes
Affiliation:
Department of Mathematics, University of Michigan, Ann Arbor, Michigan, U.S.A.
Get access

Extract

§1. Preliminaries. A Cauchy process in d-dimensional Euclidean space, Rd, is a stochastic process, Xt(ω), with stationary independent increments and with a continuous transition density, p(t, y − x) defined by

and

where m, the isotropic measure, is a probability measure on Sd, the unit sphere in Rd, such that when d > 1 the support of m is not contained in any d − 1 dimensional subspace. In (2) w is given by

where . It follows that for each t > 0 and y we have p(t, y) > 0 and that for each t > 0 p(t, y) is a bounded and continuous function of y. Xt(ω) can be considered as being a standard Markov process (for a full description of the definition of such a process see Chapter 1 of [1]) and in particular we can assume that the sample functions of Xt(ω) are right continuous and have left limits. We can also assume that Xt(ω) enjoys the strong Markov property. We write Px and Ex for probabilities and expectations conditional on X0(ω) = x, and we write P for P0.

Information

Type
Research Article
Copyright
Copyright © University College London 1970

Access options

Get access to the full version of this content by using one of the access options below. (Log in options will check for institutional or personal access. Content may require purchase if you do not have access.)

Article purchase

Temporarily unavailable
