




No CrossRef data available.
Article contents
Notes on energy for space-time processes over Lévy processes
Published online by Cambridge University Press: 22 January 2016
Extract
Core share and HTML view are not available for this content. However, as you have access to this content, a full PDF is available via the 'Save PDF' action button.
Let X = (Xt , 0 ≤ t < ∞) be a Lévy process on the Euclidean space Rd , that is, a process on Rd with stationary independent increments which has right continuous paths with left limits. We denote by Px the probability measure such that PX(X0 = x) = 1 and by Ex the expectation relative to Px . The process is characterized by the exponent Ψ through
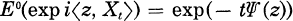 .
Information
- Type
- Research Article
- Information
- Copyright
- Copyright © Editorial Board of Nagoya Mathematical Journal 1991
References
[1]
Blumenthal, R. G. and Getoor, R. K., Markov Processes and Potential Theory, Academic Press, New York, 1968.Google Scholar
[2]
Bochner, S., Harmonic Analysis and Theory of Probability, Berkeley: Univ. of California Press
1955.CrossRefGoogle Scholar
[4]
Hawkes, J., Potential theory of Levy processes, Proc. London Math. Soc., (3) 38 (1979), 335–352.CrossRefGoogle Scholar
[5]
Kanda, M., Two theorems on capacity for Markov processes with stationary independent increments, Z. Wahrsch. Verw. Gebiete, 35 (1976), 159–165.CrossRefGoogle Scholar
[6]
Kanda, M., Characterizations of semipolar sets for processes with stationary independent increments, Z. Wahrsch. Verw. Gebiete, 42 (1978), 141–154.CrossRefGoogle Scholar
[7]
Kanda, M., Characterization of semipolar sets for Levy processes by Fourier transform of measures, Surikaiseki Kenkyusho Kokyuroku, 502 (1983), 161–170.Google Scholar
[8]
Kanda, M., A note on capacitary measures of semipolar sets, The Annals of Probability, (1) 17 (1989), 379–384.Google Scholar
[9]
Kanda, M., A note on a characterization of semipolar sets, Abstracts, Singapore Prob. Conference (1989).Google Scholar
[10]
Pop-Stojanovic, Z. R., Energy in Markov processes, Functional analysis, (II) (Dubrovnik
1985), Lecture Notes in Math., 1242 (1987), 374–395.Google Scholar
[11]
Rao, M., On polar sets for Lévy processes, J. London Math. Soc., (2) 35 (1987), 569–576.Google Scholar
[12]
Rao, M., Hunt’s hypothesis for Levy processes, Proc. Amer. Math. Soc., (2) 104 (1988), 621–624.Google Scholar
[14]
Zabczyk, J., A note on semipolar sets for processes with independent increments, Winter School on Probability, Karpacz, Poland, Lecture Notes in Math., 472 (1975) 277–283.Google Scholar
 You have
Access
- 1
- Cited by