




No CrossRef data available.
Article contents
On stochastic optimal control laws
Published online by Cambridge University Press: 22 January 2016
Extract
Core share and HTML view are not available for this content. However, as you have access to this content, a full PDF is available via the 'Save PDF' action button.
Let us begin by recalling the existence of optimal controls for a class of stochastic differential equations
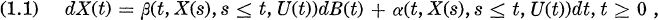
with given initial condition X(0) = x, where B is an n-dimensional Brownian motion and the control U is a stochastic process. As admissible controls, let us allow all non-anticipative process U(t) = (U1(t),…Um(t)) ∈ Γ where Γ is a compact subset of Rm . We call Γ a control region. Assume that the matrix valued functional β and the n-vector valued α satisfy a Lipscitz condition in X and some growth condition. Then we have a unique solution Xu for an admissible control U.
Information
- Type
- Research Article
- Information
- Copyright
- Copyright © Editorial Board of Nagoya Mathematical Journal 1973
References
[1]
Beneš, V. E., Existence of optimal strategies based on specified informations, for a class of stochastic decision problems, SIAM J. control, 8 (1970), 179–188.Google Scholar
[2]
Beneš, V. E., Existence of optimal stochastic control laws, SIAM J. control, 9 (1971), 446–472.Google Scholar
[3]
Fleming, W. H., Some Markovian optimization problems, J. Math. & Mech., 12 (1963), 131–140.Google Scholar
[4]
Fleming, W. H. & Nisio, M., On the existence of optimal stochastic controls, J. Math. & Mech., 15 (1966), 779–794.Google Scholar
[5]
Fujisaki, M., Kallianpur, G. & Kunita, H., Stochastic differential equations for the non-linear filtering problem, Osaka J. Math., 9 (1972), 19–40.Google Scholar
[6]
Itô, K., On a formula concerning stochastic differentials, Nagoya Math. J., 3 (1951), 55–65.CrossRefGoogle Scholar
[7]
Krylov, N. V., On the stochastic integral of Itô, Th. Prob. Appl., 14 (1969), 330–336.CrossRefGoogle Scholar
[8]
Krylov, N. V., On an inequality in the theory of stochastic integrals, T. V., 16 (1971), 446–457.Google Scholar
[9]
Krylov, N. V., On the control of diffusion type processes, 2nd Japan-USSR Symp. Proba. Th. (1972).Google Scholar
[10]
Kunita, H. & Watanabe, S., On square integrable martingales, Nagoya Math. J., 30 (1967), 209–245.CrossRefGoogle Scholar
 You have
Access
- 3
- Cited by