




No CrossRef data available.
Article contents
Optimal control of ultimately bounded stochastic processes
Published online by Cambridge University Press: 22 January 2016
Extract
Core share and HTML view are not available for this content. However, as you have access to this content, a full PDF is available via the 'Save PDF' action button.
We shall consider the optimal control for a system governed by a stochastic differential equation
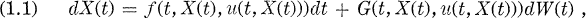
where u(t, x) is an admissible control and W(t) is a standard Wiener process. By an optimal control we mean a control which minimizes the cost and in addition makes the corresponding Markov process stable.
Information
- Type
- Research Article
- Information
- Copyright
- Copyright © Editorial Board of Nagoya Mathematical Journal 1974
References
[1]
Haussmann, U. G.; Optimal Stationary Control with State and Control Dependent Noise, SIAM J. Control, Vol. 9 No. 2 (1971) pp. 184–198.CrossRefGoogle Scholar
[2]
Miyahara, Y.; Ultimate Boundedness of the Systems Governed by Stochastic Differential Equations, Nagoya Math. J. Vol. 47 (1972), pp. 111–144.Google Scholar
[3]
Miyahara, Y.; Invariant Measures of Ultimately Bounded Stochastic Process, Nagoya Math. J. Vol. 49 (1973) pp. 149–153.CrossRefGoogle Scholar
[4]
Wonham, W. M.; Optimal Stationary Control of a Linear System with State-dependent Noise, SIAM J. Control, Vol. 5, No. 3 (1967).CrossRefGoogle Scholar
[5]
Wonham, W. M.; On Pole assignment in Multi-input Controllable linear systems, IEEE Trans. Automatic Control, AC-12 (1967), pp. 660–665.Google Scholar
 You have Access