
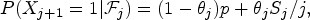
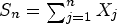
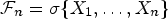

Hostname: page-component-7b7567c8c-tnkh4 Total loading time: 0 Render date: 2026-11-16T01:56:15.024Z Has data issue: false hasContentIssue false

ASYMPTOTIC BEHAVIORS FOR CORRELATED BERNOULLI MODEL

Published online by Cambridge University Press:  11 July 2019

Yu Miao
Affiliation:
College of Mathematics and Information Science, Henan Normal University, Henan Province 453007, China E-mail: yumiao728@gmail.com; huanhuanma16@126.com
Huanhuan Ma
Affiliation:
College of Mathematics and Information Science, Henan Normal University, Henan Province 453007, China E-mail: yumiao728@gmail.com; huanhuanma16@126.com
Qinglong Yang
Affiliation:
School of Statistics and Mathematics, Zhongnan University of Economics and Law, Hubei Province 430073, China E-mail: yangqinglong@zuel.edu.cn
Rights & Permissions [Opens in a new window]

Abstract

Core share and HTML view are not available for this content. However, as you have access to this content, a full PDF is available via the 'Save PDF' action button.

We consider a class of correlated Bernoulli variables, which have the following form: for some 0 < p < 1,

$$\begin{align}{P(X_{j+1}=1 \vert {\cal F}_{j})= (1-\theta_j)p+\theta_jS_j/j,}\end{align}$$
where 0 ≤ θj ≤ 1, $S_n=\sum _{j=1}^nX_j$ and ${\cal F}_n=\sigma \{X_1,\ldots , X_n\}$. The aim of this paper is to establish the strong law of large numbers which extend some known results, and prove the moderate deviation principle for the correlated Bernoulli model.

Information

Type
Research Article
Copyright
Copyright © Cambridge University Press 2019