
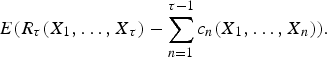

Hostname: page-component-7b7567c8c-fvjsw Total loading time: 0 Render date: 2026-11-16T09:41:00.335Z Has data issue: false hasContentIssue false

CHARACTERIZATIONS OF OPTIMAL POLICIES IN A GENERAL STOPPING PROBLEM AND STABILITY ESTIMATING

Published online by Cambridge University Press:  05 June 2014

Evgueni Gordienko
Affiliation:
Department of Mathematics, UAM-Iztapalapa, San Rafael Atlixco 186, col. Vicentina, C.P. 11320, Mexico City, Mexico E-mail: gord@xanum.uam.mx and an@xanum.uam.mx
Andrey Novikov
Affiliation:
Department of Mathematics, UAM-Iztapalapa, San Rafael Atlixco 186, col. Vicentina, C.P. 11320, Mexico City, Mexico E-mail: gord@xanum.uam.mx and an@xanum.uam.mx
Rights & Permissions [Opens in a new window]

Abstract

Core share and HTML view are not available for this content. However, as you have access to this content, a full PDF is available via the 'Save PDF' action button.

We consider an optimal stopping problem for a general discrete-time process X1, X2, …, Xn, … on a common measurable space. Stopping at time n (n = 1, 2, …) yields a reward Rn(X1, …, Xn) ≥ 0, while if we do not stop, we pay cn(X1, …, Xn) ≥ 0 and keep observing the process. The problem is to characterize all the optimal stopping times τ, i.e., such that maximize the mean net gain:

$$E(R_\tau(X_1,\dots,X_\tau)-\sum_{n=1}^{\tau-1}c_n(X_1,\dots,X_n)).$$
We propose a new simple approach to stopping problems which allows to obtain not only sufficient, but also necessary conditions of optimality in some natural classes of (randomized) stopping rules.

In the particular case of Markov sequence X1, X2, … we estimate the stability of the optimal stopping problem under perturbations of transition probabilities.

Information

Type
Research Article
Copyright
Copyright © Cambridge University Press 2014