




No CrossRef data available.
RATIO MONOTONICITY FOR TAIL PROBABILITIES IN THE RENEWAL RISK MODEL
Published online by Cambridge University Press: 31 March 2011
Abstract
Core share and HTML view are not available for this content. However, as you have access to this content, a full PDF is available via the 'Save PDF' action button.
A renewal model in risk theory is considered, where  is the tail of the distribution of the deficit at ruin with initial surplus u and
 is the tail of the ladder height distribution. Conditions are derived under which the ratio
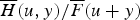 is nondecreasing in u for any y≥0. In particular, it is proven that if the ladder height distribution is stable and DFR or phase type, then the above ratio is nondecreasing in u. As a byproduct of this monotonicity, an upper bound and an asymptotic result for
 are derived. Examples are given to illustrate the monotonicity results.
Information
- Type
- Research Article
- Information
- Probability in the Engineering and Informational Sciences , Volume 25 , Issue 2 , April 2011, pp. 171 - 185
- Copyright
- Copyright © Cambridge University Press 2011
References
3.Berman, A. & Plemmons, B. (1994). Nonnegative matrices in the mathematical sciences. Philadelphia: SIAM.CrossRefGoogle Scholar
4.Bingham, N.H., Goldie, C.M. & Teugels, J.L. (1987). Regular variation. Cambridge: Cambridge University Press.CrossRefGoogle Scholar
5.Daley, D.J., Omey, E. & Vesilo, R. (2007). The tail behavior of a random sum of subexponential random variables and vectors. Extremes 10: 21–39.CrossRefGoogle Scholar
6.Dickson, D.C.M. (1998). On a class of renewal risk processes. North American Actuarial Journal 11(3): 128–137.Google Scholar
7.Dickson, D.C.M. & dos Reis, A.E. (1996). On the distribution of the duration of negative surplus. Scandinavian Actuarial Journal 1996: 148–164.CrossRefGoogle Scholar
8.Drekic, S., Dickson, D.C.M., Stanford, D.A. & Willmot, G.E. (2004). On the distribution of the deficit at ruin when claims are phase-type. Scandinavian Actuarial Journal 2004: 105–120.CrossRefGoogle Scholar
9.Embrechts, P. & Veraverbeke, N. (1982). Estimates for the probability of ruin with special emphasis on the possibility of large claims. Insurance: Mathematics and Economics 7: 55–72.Google Scholar
10.Fagiuoli, E. & Pellerey, F. (1994). Preservation of certain classes of life distributions under Poisson shock models. Journal of Applied Probability 31: 458–465.CrossRefGoogle Scholar
11.Gerber, H.U., Goovaerts, M.J. & Kaas, R. (1987). On the probability and severity of ruin. ASTIN Bulletin 17: 152–163.CrossRefGoogle Scholar
12.Horn, R.A. & Johnson, C.R. (1985). Matrix analysis. Cambridge: Cambridge University Press.CrossRefGoogle Scholar
13.Psarrakos, G. (2009). Asymptotic results for heavy-tailed distributions using defective renewal equations. Statistics and Probability Letters 79: 774–779.CrossRefGoogle Scholar
14.Psarrakos, G. & Politis, K. (2009). Monotonicity properties and the deficit at ruin in the Sparre Andersen model. Scandinavian Actuarial Journal 2009: 104–118.CrossRefGoogle Scholar
15.Rolski, T., Schmidli, H., Schmidt, V. & Teugels, J. (1999). Stochastic processes for insurance and finance. New York: Wiley.CrossRefGoogle Scholar
16.Samorodnitsky, G. & Taqqu, M. (1994). Stable non-Gaussian random processes. London: Chapman and Hall.Google Scholar
17.Shanthikumar, J.G. (1988). DFR properties of first-passage times and its preservation under geometric compounding. Annals of Probability 33: 397–406.Google Scholar
18.Willmot, G.E. (2002). Compound geometric residual lifetime distributions and the deficit at ruin. Insurance: Mathematics and Economics 30: 421–438.Google Scholar
19.Willmot, G.E., Dickson, D.C.M., Drekic, S. & Stanford, D.A. (2004). The deficit at ruin in the stationary renewal risk model. Scandinavian Actuarial Journal 2004: 241–255.CrossRefGoogle Scholar
20.Willmot, G.E. & Lin, X.S. (1998). Exact and approximate properties of the distribution of the surplus before and after ruin. Insurance: Mathematics and Economics 23: 91–110.Google Scholar
 You have Access