


1 Introduction
There is a long-standing debate among financial economists, pension actuaries, and other interested parties about the appropriate rate to use for discounting future pension liabilities. The Government Accounting Standards Board (GASB), which sets standards for US state and local government pension plans, has long used rules that relate the discount rate to the expected return on pension plan assets, a position that has been defended by numerous actuaries and plan sponsors.Footnote 1 In contrast, most financial economists argue that liabilities should be discounted using a rate that reflects the risk of the liabilities (Brown and Wilcox, Reference Brown and Wilcox2009; Lucas and Zeldes, Reference Lucas and Zeldes2009; Novy-Marx and Rauh, Reference Novy-Marx and Rauh2011a , Reference Novy-Marx and Rauh b ; Andonov et al., Reference Andonov, Bauer and Cremers2014; Novy-Marx, Reference Novy-Marx2015). In the special case where the public pension benefits are considered free of default risk, such as in the presence of strong constitutional protections, financial economists have argued that the appropriate rate to use is a default-free one (e.g., Brown and Wilcox, Reference Brown and Wilcox2009; Novy-Marx, Reference Novy-Marx2015).
In this paper, we make a simple but important conceptual point. We argue that there is an important difference between the appropriate measures of a plan's funding status and of its market value. Specifically, we argue that the correct discount rate for determining a plan's funding status is the default-free rate: in a departure from prior studies in financial economics, we argue that this is true regardless of whether the liabilities are default-free or not. In contrast, a default-risky discount rate is the appropriate rate to use for measuring the market value of the liabilities.
Measuring underfunding and placing a market value on liabilities are clearly two distinct concepts, and both are useful for answering different questions. For example, the use of a default-free discount rate is informative to participants who want to know how much money the plan would need to be assured that the plan will be able to pay promised benefits. This would also be a relevant measure if the plan wished to offload its liabilities to an insurance company that intends to make good on the future benefit payments. For example, a number of defined benefit (DB) plans, including General Motors, have recently transferred their currently accrued pension liabilities to an insurance company (Prudential, in the GM case) that will then provide retirement annuities to the sponsor's employees. The insurance company taking over the plan would rationally require the sponsor to pay the difference between the accrued plan liabilities discounted at the default-free rate and the plan's assets (plus any administrative costs). If the insurance company received this payment along with the plan's current assets, it would permit the insurance company to invest in exactly those default-free securities that guarantees its ability to meet future obligations to the sponsor's employees. Thus, for the purpose of determining how much it would cost the sponsor to sell off its pension liabilities, discounting the liabilities at the default-free rate is needed to determine the payment to the acquirer of the liabilities.
Yet, there are also cases where the market value of the liability is important. Current or potential plan participants might want to know the market value of pension liabilities (rather than their promised value) when they are making decisions about the value of pension benefits being offered by two different employers. Current employees may also want to know the market value of pension promises when they are deciding when to retire: if their employer is likely to default on pension promises, they may want to work longer to increase their savings from current salary. The market value of a DB plan's promises would also be informative to individuals faced with a choice between a DB and a defined contribution (DC) plan, a choice that a number of states provide to their public employees.
Prior research analyzing the financial condition of public pension funds often fails to distinguish between accounting for pension liabilities to compute a pension fund's level of (under-) funding, and determining the market value of the pension fund's liabilities. We demonstrate that these are distinct exercises, though previous work frequently treats them as being the same.Footnote 2 Specifically, it has been common in academic studies to justify the use of a pension discount rate based on the likelihood that a state or local government will default on its pension obligations: a higher probability of default would warrant a higher discount rate.
We apply the standard Merton (Reference Merton1974) structural credit risk model to the context of a DB pension fund. We show that discounting the liability with a default-free rate has the attractive property that the size of the total liability (funded plus unfunded) is not affected by the plan's funding status. We further show that it has the desirable property that the measure of fundedness declines to zero as plan assets fall to zero. For comparison, we show that the market value of the liability can have odd properties as a system of funding measurement: specifically, the size of the total (funded plus unfunded) liability can vary with the degree of funding, and that funding levels asymptotically approach 100% as assets approach zero.
Our argument, therefore, is that the appropriate measure of funding uses default-risk-free rates. This naturally leads to the practical question of how to measure default-free discount rates. There are at least three reasons that the most commonly used proxies – yields on debt securities issued by the federal government – can be criticized as biased measures of the economy's default-free rates. First, government bonds are not truly default-free. Although the risk of a US government default is not high, it is also not zero, as is evidenced by the very existence of a market for credit default swaps on government bonds. Second, there are state income tax advantages to US government bonds, suggesting that some investors in high marginal tax rate states might be willing to accept a lower yield compared with other securities with the same default risk. Third, government bond yields might be lowered by their high liquidity relative to other fixed income assets. Our paper discusses these factors and their quantitative importance as a way of bounding the measure of a default-free rate. In the end, we find that the effects are roughly offsetting and that Treasury yields are a reasonable approximation to a default-free rate.
Having established that the appropriate way to discount pension liabilities for purposes of measuring funding status is to use (a proxy for) the default-free rate, we then turn to the question of how to incorporate cost-of-living adjustments (COLAs) that are common in public sector plans. Were COLAs purely indexed to the Consumer Price Index (CPI) and were there a deep market for CPI-indexed default-free bonds available in the economy, one could simply use the term structure of default-free real yields on these indexed bonds, rather than the term structure of default-free nominal yields. But as we discuss below, most public pensions in the USA do not use straight CPI indexation for their COLAs. Rather, COLAs are contractually subject to upper and lower bounds (caps and floors) on inflation. Therefore, we discuss how one can use market prices of inflation derivatives to compute the default-free values of these promised state-contingent COLAs.
This paper proceeds as follows: in Section 2, we provide a brief discussion of issues that arise when choosing an appropriate discount rate for public pensions and the debate that surrounds this issue. In Section 3, we apply the Merton (Reference Merton1974) model to a discussion of DB pension liabilities and use it to illustrate the distinction between measuring funded status and valuing liabilities. In Section 4, we discuss how one should think about the choice of a default-free rate to use for discounting. We acknowledge three common criticisms of using the US Treasury yield curve, present relevant evidence, and ultimately conclude that Treasury yields are a reasonable proxy for default-free rates. In Section 5, we turn to the issue of how to account for the presence of COLAs commonly found in public pensions. We show that COLAs often have the same promised payments as particular combinations of inflation derivatives, so that the price of these derivatives represents the market cost of replicating the COLA payments. We provide examples of how this approach can be used to value several COLAs that are common in the public sector. Section 6 concludes.
2 Background on public pension funding measures
Unlike private pensions in the USA, which are required to meet funding standards imposed by the federal government, state and local plans are not subject to externally imposed funding rules. Despite this, most states have adopted policies for funding their public employee pensions based on standards issued by the GASB, an independent organization responsible for establishing accounting and financial reporting standards for state and local governments. GASB has no enforcement authority and its pronouncements only have any legally binding nature if the state or local government chooses to voluntarily adopt the standards as law or regulation.
Because states have no external legal requirement to fund their pensions, funding becomes a policy decision. Although ‘full funding’ is one natural benchmark, it is worth noting that economic theory does not dictate that full funding is optimal. If a populace wishes to engage in some form of intergenerational redistribution, then transferring resources across cohorts can be achieved through under- or overfunding pensions, adjusting the levels of other debt obligations or, using resources to spend on consumption versus investment. Indeed, the largest public pension in the USA – the Social Security system – has operated in a manner closer to a true pay-as-you-go system than as a funded system. Although states are less able to sustain pure unfunded systems than is the federal government, owing to the fact that it is much easier to move capital and labor out of a fiscally distressed state than out of the country, they nonetheless have some policy flexibility in choosing how much to fund.
It is important to acknowledge that a funding ratio is a policy choice rather than a requirement, since it allows one to separate the measurement of the level of funding from the choice of the level of funding. One can accept that the appropriate way to measure funding is to use a default-free rate, without it necessarily following that the optimal funding level for a state must always be 100% according to this measure. This paper is focused on the issue of how to measure the level of funding, without taking a view on what the optimal level of funding should be.Footnote 3
In contrast to GASB standards that rely upon expected asset returns, numerous financial economists have argued that the appropriate discount rate is one adjusted for the risk of the liabilities being discounted. Several authors have then made the argument that public pensions are ‘close to’ default-free. For example, Brown and Wilcox (Reference Brown and Wilcox2009) use several historical case studies to argue that public pension benefits have little default risk.
The discount rate assumptions matter for the measurement of funding status. For example, Munnell et al. (Reference Munnell, Aubry and Cafarelli2014) estimated that the actuarial value of assets for the 150 state and local plans in their database was $2.9 trillion at the end of 2013.Footnote 4 Using the prior GASB standards that allowed for discounting based on the expected return of plan assets, they calculated the present value of liabilities at $4.1 trillion. Yet, the implied 72% funded ratio clearly overstates the financial health of these plans, because it uses a high discount rate. Government bond yields were quite low in 2013: on December 21, 2013, the yield on a 30-year Treasury was only 3.96%, and the yield on shorter-term bonds was even lower. Assuming a flat 4% term structure, Munnell, Aubry, and Cafarelli calculate an alternative aggregate liability of $6.8 trillion, for an average funding ratio of approximately 43%.
In a departure from most existing papers in financial economics (including one co-authored by one of the current authors), it is our contention that the appropriate discount rate to use for measuring funding shortfalls is the default-free rate, even if the liabilities are not default-free. We discuss this more in the next section with the help of a simple model.
Before turning to this discussion, we note that we are focusing here on discounting the Accumulated Benefit Obligation (ABO) rather than the Projected Benefit Obligation (PBO). The general distinction is that the ABO represents the liability that the plan has accrued to date, measured at current earnings levels. The PBO, in contrast, accounts for the fact that many of today's participants have earned a benefit that will not be payable until some future date and will, at that time, be based on a higher earnings level. We focus on the ABO for the reasons outlined in Brown and Wilcox (Reference Brown and Wilcox2009) and Bulow (Reference Bulow1982), including the fact that the ABO measure has the effect of treating salary and pension accruals similarly. In other words, employers are not required to report a higher salary today just because employees are likely to receive a higher salary in the future. Similarly, we believe that it is appropriate to account for the effect of future salary increases on pension liabilities only after those salary increases have become effective. Because we are focused only on the ABO, we do not need to worry about adjusting discount rates to reflect the risk of liabilities that might arise from uncertain earnings growth. Lucas and Zeldes (Reference Lucas and Zeldes2006, Reference Lucas and Zeldes2009) discuss the implications of PBO hedging for both discount rate selection and portfolio allocation.
3 A simple model for measuring pension funding
To illustrate the distinction between measuring pension liabilities and placing a market valuation on them, we apply the standard Merton (Reference Merton1974) structural credit risk model to the context of a defined-benefit pension fund. To make our point transparent, we first consider a highly simplified case in which a pension plan promises a single lump-sum benefit payment at one future date. The model makes the following four simplifying assumptions:
-
(1) The pension fund invests in risky assets that have a current date t market value of A t and a rate of return volatility (annual standard deviation) of σ.
-
(2) The pension fund promises a single retirement benefit equal to X payable at date t + τ.
-
(3) The continuously compounded, default-free interest rate (yield) is constant, equal to y.
-
(4) The sponsor of the pension fund is expected to contribute to the fund's assets in amounts cA t per unit time until date t + τ.Footnote 5 If, at date t + τ, the pension fund has sufficient asset value, pension participants receive their promised payment of X. Instead, if A t+τ is worth less than X, the pension fund defaults and the participants receive only A t+τ .
Let us denote the date t market value of the pension fund's liabilities as L t . This is the current fair market value that investors would pay for the possibility of receiving the default-risky cash flow of min [X, A t+τ ] at the future date t + τ. Similar to Merton (Reference Merton1974), the market value of this default-risky pension liability equals
 $${L_t} = X{{\rm e}^{ - y\tau}} N({d_2}) + {A_t}{{\rm e}^{c\tau}} N( - {d_1}),$$
where
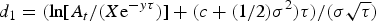 ${d_1} = (\ln [{A_t}/(X{{\rm e}^{ - y\tau}} )] + (c + (1/2){\sigma ^2})\tau )/(\sigma \sqrt \tau )$
,
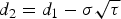 ${d_2} = {d_1} - \sigma \sqrt \tau $
, and N(·) is the standard normal cumulative distribution function. Note from equation (1) that L
t
is a function of five quantities: (1) the current market value of assets, A
t
; (2) the rate at which new assets are expected to be contributed to the fund, c; (3) the volatility of assets, σ; (4) the time until the pension's benefit is due to be paid, τ; and (5) the promised pension benefit discounted at the default-free interest rate,Xe−yτ
.
Equation (1) provides several immediate insights. One is that the market value of liabilities, L t , can never be worth more than the promised payment discounted at the default-free rate, Xe−yτ . Further, as the value of the pension fund's current assets grows, L t converges toXe−yτ :
 $$\mathop {\lim} \limits_{{A_t} \to \infty} {L_t} = X{{\rm e}^{ - y\tau}} $$
The quantity Xe−yτ plays a natural role in the concept of a fully funded pension plan for at least two reasons. First, if the current value of pension assets equals A t = Xe−yτ , then there exists an investment strategy that can guarantee to participants their full payment of X, without any need for the sponsor to make future asset contributions to the fund (c = 0). This strategy consists of investing all of the pension assets in the default-free security at rate y. Indeed, if this plan were to transfer its currently accrued liabilities to an insurance company, so that it would not need to make any new contributions after the transfer, it would need to top up its assets to equal A t = Xe−yτ in order for the insurance company to implement this riskless investment strategy.
Second, we argue that the ratio of the default-risky market value of liabilities to its default-free value is a good measure of the relative risk faced by a pension participant. This quantity
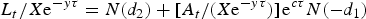 ${L_t}/X{{\rm e}^{ - y\tau}} = N({d_2}) + [{A_t}/(X{{\rm e}^{ - y\tau}} )]{\kern 1pt} {{\rm e}^{c\tau}} N( - {d_1})$
is a function of only four factors: c, σ, τ, and
 ${A_t}/(X{\kern 1pt} {{\rm e}^{ - y\tau}} )$
. Thus the pension funding ratio for which liabilities are discounted at the default-free rate, A
t
/(Xe−yτ
), emerges as the natural factor for measuring pension risk. Moreover, it is clear that this definition of a funding ratio delivers the sensible result that, as the value of pension assets declines, the funding ratio goes to zero:
 $$\displaystyle{\mathop {\lim} \limits_{{A_t} \to 0}} {{A_t} \over {X{{\rm e}^{ - y\tau}}}} = 0.$$
If, instead, pension liabilities were discounted at a risk-adjusted rate, say Y, that reflected their true default risk, then Xe−Yτ = L t . However, using this liability measure to account for the pension plan's funding ratio,A t /L t , is nonsensical because it leads to the following illogical result. Under this measure, it is straightforward to show that the pension plan becomes fully funded as the value of assets shrinks:
 $${\mathop {\lim} \limits_{{A_t} \to 0}} {{A_t} \over {L_t}} = 1.$$
A simple numerical example illustrates the importance of this distinction. Consider a plan that has a single nominal liability of X = $1,000 that is payable in 10 years. If the current continuously compounded yield on a 10-year default-free bond is y = 3.0%, then investing X e−y τ = $1,000 e−0.03×10 = $740.82 in this bond today, without any need for the sponsor to make future contributions (c = 0), would guarantee that the plan could make good on its liability.
Now suppose the plan was underfunded, having assets of only A t = $500 on hand today. Using the default-free rate, the plan would be X e−y τ − A t = $240.82 underfunded, or a funding ratio of A t /(X e−y τ ) = 67.5%. Contrary to how GASB discounts, this level of underfunding is the same regardless of how the $500 is invested. We argue that this 67.5% is the appropriate measure of a plan's funding status because it tells participants and other stakeholders how much money the plan would need today to pay full promised benefits in the future. This measure would also be helpful to determine the future contribution rate, c, that would be expected to close this funding gap over some future horizon.Footnote 6
Next, consider the consequence of incorporating default risk when discounting pension liabilities. Suppose that the rate of return on the plan's assets has an annual standard deviation of σ = 20%. If the sponsor is expected to make additional contributions to the fund at the rate of c = 2% per year, the current market value of liabilities calculated from equation (1) is L t = $476.64. This market value is equivalent to discounting the plan's promised liabilities by Y = 7.41%. That is, L t = $476.64 = X e−Y τ = 1,000 × e−0.0741×10. If one then discounted the plan's benefit promises by a rate that reflects the true likelihood of default and used the result to measure funding, then the plan would be overfunded by $500–476.64 = 23.36 and its funding ratio would be A t /(X e−Y τ ) = 104.9%.
While discounting benefit promises by a risk-adjusted rate leads to a distorted measure of funding, information on the L t = $477 current market value of liabilities would be quite valuable, for example, to an employee deciding between the DB plan and, say, a $600 immediate contribution to a DC plan. If the DB plan was fully funded and default-free, then the individual might rationally choose the $741 DB over a $600 DC.Footnote 7 But if the DB plan is underfunded, the rational choice might be the $600 DC rather than the $477 market value of the DB.
Thus, the market value of the DB liability does contain useful information. But it is not a particularly robust measure of funding levels, i.e., how much money the plan sponsor would need to set aside today to pay promised benefits. For example, if one is interested in measuring funding status, it makes little sense to effectively ‘reward’ the plan sponsor for underfunding the plan. As indicated in the model above, if a plan sponsor does not fund at all, and if this drives the probability of the plan sponsor making good on its promises toward zero, then the market value of the liability can disappear completely. That is useful information to those trying to value their future benefits, but it serves little purpose as a measure of the funding shortfall.
Novy-Marx and Rauh (Reference Novy-Marx and Rauh2011a , Reference Novy-Marx and Rauh b ) consider two candidate rates as being potentially appropriate for discounting state pension liabilities in practice. One is a tax-adjusted general obligation municipal bond rate. They argue that such a rate is appropriate if a state is just as likely to default on its pension obligations as it is to default on its general obligation bonds. Their second candidate discount rate is based on the logic of Brown and Wilcox (Reference Brown and Wilcox2009) who document that a majority of states' pension obligations are protected by state constitutional guarantees. It is argued that these states have a lower probability of defaulting on their pension obligations than of defaulting on their municipal bonds. Therefore, they argue that the appropriate discount rate for pension liabilities should be less than a municipal bond rate and closer to a nearly default-free zero-coupon US Treasury rate.Footnote 8 The main point of the present paper is that this discussion is relevant to computing the market value of public pension liabilities, but only the default-free rate is relevant for measuring the degree of underfunding. We argue that there is no need to justify the choice of the liability discount rate based on the municipality's likelihood of default, because finance theory supports the discounting of promised pension obligations by a default-free rate, whether the pension fund sponsor is the US government, the State of Illinois, or the City of Detroit.
As we discuss in the following sections, the insights obtained from equation (1) carry over to more realistic models where benefits are promised at many future dates. For the purpose of measuring a plan's funding status, each future promised benefit payment should be discounted using the yield on the default-free bond that matures at the benefit's payment date. Furthermore, when promised benefits are state contingent, as they are in the case of COLAs subject to limits on future inflation, these promises should be valued as if they were default-free. If there exists default-free securities that can replicate the plan's state-contingent benefit promises, then the cost of these securities should be used to value liabilities when calculating funding status. In other words, while valuation for the purpose of measuring funding status should account for the state-contingent risk of the plan's contracted benefits, it should not account for benefit default risk which would constitute a violation or breach of the benefit contract.
To further clarify our definition of a ‘benefit default,’ it is any deviation from a contractually pre-specified benefit payment. Notably, a benefit reduction due to a COLA in the benefit contract would not constitute default, even if the COLA is explicitly linked to the plan's funding status or the investment return on the plan's assets.Footnote 9 Though our focus is on public pension plans, a similar definition of default holds for corporate pension plans: default occurs when a bankrupt corporate sponsor of an underfunded plan terminates or fails to pay contractually pre-specified benefits, even if the plan's benefits are subsequently fully or partially insured by a third party.Footnote 10
4 How to measure default-free rates
To account for a pension plan's funding level, we argued in the previous section that liabilities should be valued as if future promised payments were default-free, unless explicit contractual provisions allow for changes in these payments. Our rationale is that full funding should imply that the plan has sufficient assets to implement an investment strategy that guarantees payment of the plan's promised retirement benefits. If the plan's promised benefits can be replicated by a particular portfolio of securities, then the minimum cost of this portfolio equals the plan's fully funded asset value. In turn, the difference between this portfolio's cost and the plan's current asset value equals the plan's underfunding. Equivalently, should the sponsor terminate the plan and transfer its accrued liabilities to an insurance company, the company's cost of implementing an investment strategy that guarantees payment of the benefits is the value of the replicating portfolio.
As we discuss below, there exist several nominal and inflation-related securities that can replicate many promised plan benefits.Footnote 11 In this section, we consider purely nominal liabilities and then cover inflation-related COLAs in the following section.
The simple model of the previous section assumed a single future promised payment, X, and a single default-free interest rate, y. The qualitative insights of that model extend to payments promised at multiple future dates. Suppose the current date is 0 and a plan promises payments each year for T future years, t = 1,…, T, with corresponding amounts X t , t = 1,…, T. Then the current date 0 default-free value of the plan's liabilities is
 $$\sum\limits_{t = 1}^T {{X_t}{{\rm e}^{ - {y_{0,t}}t}}}, $$
where y 0,t denotes the date 0 continuously compounded yield to maturity on a default-free zero-coupon bond that matures at date t. Consequently, if the plan had asset value sufficient to purchase T default-free bonds with maturity values X t , t = 1,…, T, it could guarantee payment of the benefits. Thus, expression (5) represents the plan's fully funded asset value. Equivalently, a portfolio of default-free bonds whose value and duration equals that of (5) is sufficient to pay future benefits and immunize the plan from interest rate risk.
Lewis and Pennacchi (Reference Lewis and Pennacchi1999) extend the model of the previous section to find the market value of a DB plan's liabilities or, equivalently, the fair cost of insuring its liabilities from default. Their model permits benefit payments and contributions from a plan sponsor at multiple future dates and assumes default occurs if the plan's sponsor (e.g., a corporation or a municipality) declares bankruptcy when the pension plan is underfunded. Consistent with (5), the model assumes that there exists a duration-matching bond portfolio that replicates the plan's promised benefits. The term structure of default-free yields changes randomly according to the Vasicek (Reference Vasicek1977) no-arbitrage model. The insight of the previous section carries over to this extended model, in that the critical measure of the plan's funding status is the ratio of the market value of the plan's assets to the value of the duration-matched, default-free bond portfolio that replicates the plan's promised future benefits.Footnote 12
The issue that we now address is how to determine the appropriate set of default-free yields. A natural starting point is yields on Treasury securities. The term structure of zero-coupon Treasury yields can be obtained from Treasury STRIPS or the zero-coupon yields implicit in the prices of Treasury coupon-paying notes and bonds.Footnote 13 However, several objections might be made for using unadjusted Treasury yields to discount pension promises. We briefly discuss these concerns and use the existing literature to place bounds on adjustments that might be made when using a Treasury yield curve to proxy default-free rates.
4.1 US government debt is not default-risk-free
One criticism of using Treasury securities as proxies for default-free assets is that they, like any sovereign debt, are not truly free from default risk. Evidence that at least some investors believe US Treasuries are default risky comes from the credit default swap (CDS) market.Footnote 14 CDS are insurance contracts against default. If an investor purchases a default-risky bond and also buys CDS protection against the bond's default, this combined investment approximates a default-free bond whose annual yield equals the default-risky bond's promised yield minus the annualized CDS spread.
Figure 1 shows US Treasury CDS spreads reported by Bloomberg over the period from December 2007 to December 2014.Footnote 15 The average CDS spreads over this sample period were 22.9, 34.6, and 46.0 basis points for contract maturities of 1, 5, and 10 years, respectively. CDS spreads increased sharply following the Lehman Brothers bankruptcy, peaking in February of 2009. There was also an especially large spike for spreads of the 1-year contract in July 2011, just before the resolution of the debt-ceiling crisis on July 31, 2011.Footnote 16 CDS spreads rose to a smaller extent prior to the culmination of a second debt ceiling crisis resolved on October 17, 2013.Footnote 17 In summary, based on evidence from CDS spreads, yields on Treasuries might contain roughly a 20–50 basis point default-risk premium, depending on maturity.
CDS spreads for US Treasury Securities. Source: Bloomberg.

4.2 US government debt provides state-tax advantages
States that tax investment income typically exempt interest from federal government bonds from the tax base. According to standard tax clientele theory, high-marginal-tax-rate investors would be willing to accept a lower pre-tax yield on US government debt than they are willing to accept on an otherwise identical, but taxable, asset. This would drive the yield on government bonds down and therefore require that one adjust the yields by 1/(1 − τ), where τ is the relevant state-tax rate on interest income.
Nevertheless, the tax clientele theory does not appear to be empirically relevant. Using data from the Federal Reserve Bank of St. Louis as of April 1, 2014, out of the $12,877 million of US federal debt outstanding (a figure that excludes government holdings of its own debt, such as in the Social Security trust funds), just over $6 billion (47% of total) was held by foreign investors, including foreign governments, for which tax considerations do not apply. Another 2.7 billion (21%) was held by Federal Reserve Banks, who also do not face a tax wedge between government and corporate bonds. This leaves less than one-third of all US government debt held by private US investors. These private investors, in turn, are dominated by pension funds, life insurance companies, and other institutional investors. As noted by Cochrane (Reference Cochrane2015), ‘the market for Treasury debt is heavily segmented, with few taxable investors holding any debt.’ Non-taxable investors experience no tax advantage to holding Treasuries relative to other assets, and thus there is little reason to think that US Treasury yields are significantly affected by the state-tax exemption. Thus, to a first approximation, we believe it is appropriate to make no adjustment to Treasury yields to account for their preferential state-tax status.
4.3 Liquidity premia for US government debt
Another objection to using unadjusted Treasury yields as default-free rates relates to Treasury securities' high liquidity which makes them especially attractive for investors that may have needs to trade. Treasuries can be quickly converted to cash or easily used as collateral for borrowing via repurchase agreements, features which raise their prices and lower their yields relative to a less-liquid default-free security. However, if a pension fund tends to buy and hold bonds until they mature, it may be able to form a replicating portfolio with default-free securities that are less liquid than US Treasuries. Doing so would allow it to purchase default-free securities at lower prices and higher yields.
Longstaff (Reference Longstaff2004) provides evidence of such a possibility. He examines yields on bonds issued by a US government agency, Refcorp.Footnote 18 Unlike other government agencies such as Fannie Mae or Freddie Mac, Refcorp bonds are fully collateralized by US Treasury securities and hence have the same credit risk as Treasuries. Over his April 1991 to March 2001 sample period, the average difference in Refcorp bond yields relative to equivalent maturity Treasury yields was 13.1 basis points at the 10-year maturity and 16.3 basis points at the 30-year maturity. Yet, these yield spreads tended to be higher during periods of financial market stress or ‘flights to liquidity.’ Other research finds that, even among different Treasury securities, liquidity premia affect yields. Recently auctioned ‘on-the-run’ Treasury notes and bonds tend to have yields that are 5–10 basis points lower than similar maturity but seasoned ‘off-the-run’ Treasury notes and bonds.Footnote 19 Thus, if a pension plan does not benefit from the greater liquidity of on-the-run Treasuries, it would be justified to discount nominal payments using yields of off-the-run securities or equivalent credit-risk agency securities, such as Refcorp bonds.
4.4 Net effect: Treasuries are a reasonable proxy
Starting with Treasury yields, the above evidence suggests that it may be appropriate to subtract 20–50 basis points to remove the effect of a small default-risk premium and then add 10–16 basis points to remove the average effect of the liquidity premium. While Figure 1 seems to indicate that Treasuries' credit risk spread rises during periods of financial distress, research also finds that their relative liquidity is highest during such periods, so time variation in these two effects might partially offset each other. We further argued that the marginal investor in Treasury securities is unlikely to be taxable, given the large share of government bonds held by foreign governments and tax-exempt institutional investors. The net effect of these adjustments is close to a wash: if anything, the previous evidence might suggest that a true default-free rate in the US economy is up to 35 basis points below the yields on government bonds.
Additional evidence on whether Treasury yields are a reasonable proxy for default-free rates might be to compare the effective yields on synthetic default-free bonds created from CDS-insured, high credit quality corporate bonds. We carried out a very rough, exploratory analysis by obtaining yields on all existing AAA-rated, non-callable corporate bonds.Footnote 20 Currently, the only two corporations with outstanding AAA-rated, non-callable bonds are Johnson & Johnson and Microsoft. To see how yields on their corporate bonds compare with similar Treasuries, we matched each corporate bond that currently has at least four years until maturity to a Treasury note or bond with the most similar maturity date and coupon rate. Data on yields for each corporate bond and matching Treasury bond were obtained from Bloomberg. Summary statistics from this exercise are reported in Table 1.
AAA corporate bond – Treasury spreads

Source: Bloomberg.
The sample period over which yield data was available for each corporate and matching Treasury bond is given in the first column of Table 1. Columns 2, 3, and 4 give each corporate bond's maturity date, coupon rate, and average yield over the sample period, respectively. The same data items for each bond's matching Treasury are given in columns 5, 6, and 7. In the last column 8 is the difference in the average yields of the corporate bond and its matching Treasury, which we refer to as the ‘average spread.’
Table 1 lists the bonds by corporation and maturity date. As is indicated in column 8, the corporate–Treasury spread tends to rise with the bonds' time until maturity.Footnote 21 Averaged over all corporate bonds, the average spread is about 60 basis points for each corporate issuer. However, if we limit the comparison to only bonds with a current time until maturity of 10 years or less, then the average spread is 29.8 basis points for the (six) Johnson & Johnson bonds and 48.7 basis points for the (four) Microsoft bonds. The reason that we focus on bonds of 10 years or less is that data on CDS spreads for these corporate bonds were available only for CDS contract maturities of 5 and 10 years.Footnote 22
The last four rows in Table 1 compare these corporations' spreads for 5- and 10-year CDS contracts to those of the US Treasury. Johnson & Johnson and Treasury CDS spreads are reported over the sample period beginning in December of 2007. However, since Microsoft issued its first corporate bond in 2009, its CDS is compared with that of Treasuries for a shorter sample period. As can be seen from the table, the differences are small, between 0 and 10 basis points.
By subtracting this difference in relatively higher corporate CDS spreads from their relatively higher yields, we can roughly estimate that the net yield from creating a synthetic default-free 10-year Johnson & Johnson bond is about 30 − 5 = 25 basis points greater than that for a default-free synthetic Treasury. Similarly, the net yield from creating a synthetic, default-free 10-year Microsoft bond is about 49 − 10 = 39 basis points greater than that for a default-free Treasury. Therefore, while our previous evidence suggested that using CDS to make Treasuries default-free would subtract up to 35 basis points from raw Treasury yields, this evidence from less-liquid corporate bonds suggests that the raw Treasury yield is approximately the correct return from creating a synthetic default-free bond from AAA corporates.Footnote 23 Thus a solid argument can be made that it is appropriate to use US Treasuries as the base case for measuring the degree of pension underfunding.
5 Accounting for COLAs
The discussion above indicates that using the US Treasury yield curve to discount nominal pension liabilities, and comparing this to the market value of plan assets, is an appropriate way to measure plan underfunding. But the exercise assumes that pension liabilities are fixed nominal liabilities, whereas many public pension plans have COLAs, an issue that can complicate the discounting process.
Figure 2 shows percentages of the 127 plans in NASRA's Public Fund Survey with various types of COLAS. Thirty-six plans (28%) use a post-retirement benefit adjustment that is not a true COLA but rather is a pre-determined rate of automatic increase in nominal benefits. Illinois is one such example: current retirees receive an annual 3% ‘automatic annual increase’ regardless of the actual rate of inflation. In such cases, one can apply the nominal Treasury yield curve directly to the growing nominal stream of benefits.
Types of COLAs in public plans. Source: National Association of State Retirement Administrators Survey of 127 Public Retirement Funds.

Forty-five plans (35%) use a COLA based on the CPI. If these plans were fully indexed, i.e., if benefits were real rather than nominal, then one could use a real yield curve rather than a nominal yield curve to discount benefits. However, very few of the plans are purely inflation-indexed. Thirty-eight of the 45 plans have some sort of ceiling on the inflation adjustment, ranging from a low of 1.5% in the Kentucky ERS to a high of 6% in the Connecticut SERS plan. The most common ceiling is 3%, with 15 plans capped at this level. Five plans report floors, although we suspect that more plans than this have an implicit floor of zero. It would therefore be misleading to use a real term structure to discount a stream of benefits that is subject to floors and ceilings on the inflation adjustment.
Unlike prior research that values COLAs by making ad hoc assumptions regarding future inflation, we show particular types of limited pension COLAs can be replicated and valued using the market prices of recently available inflation derivatives, such as inflation swaps, inflation caps, and inflation floors. Few, if any, assumptions regarding the process for inflation need to be made when taking this approach. In addition, because market data are available at high frequency, immediate updates on the cost of COLAs can be recognized.
This approach is useful for at least two purposes. First, it allows us to convert the COLA provisions into a fixed nominal price that can then be discounted back using the nominal default-free term structure. Second, it provides a tool for evaluating the cost savings associated with reforms that reduce COLAs. This latter point is highly relevant to the current policy environment: Munnell et al. (Reference Munnell, Aubry and Cafarelli2014) report that between 2010 and 2013, 30 plans across 17 states either reduced, suspended, or eliminated COLAs for existing employees. Of these, 13 also reduced COLAs for current retires. Although these changes were legally challenged in at least 12 of the states, the cuts were upheld in most cases.
5.1 Fixed rate COLAs
Valuing automatic fixed-rate COLAs, such as compounded or simple 3% annual increases is straightforward and can be done using the term structure of default-free nominal bond yields. To illustrate this calculation, we assume for simplicity that each future year's annuity payment is made in a lump sum at the end of each year, rather than paid monthly throughout the year. If the COLA is compounded at the rate r, then for each $1 of base year's annuity, the cashflow paid t years in the future is (1 + r) t − 1. If y 0,t is the initial, date 0 annually-compounded yield to maturity on a default-free zero-coupon bond maturing at date t, then the present value of this future year's promised COLA payment is simply [(1 + r) t − 1]/(1 + y 0,t ) t . Over a T-year retirement horizon, the present value of all future years' COLA payments are
 $$\sum\limits_{t = 1}^T \displaystyle{(1 + r)^t - 1 \over (1 + y_{0,t})^t}. $$
Expression (6) is the value of the COLA per $1 of base annuity value. Expressing it as a proportion of the present value of the total nominal annuity received over T years, i.e., the present value of a $1 per year benefit without a COLA, leads to:
 $${{\sum\nolimits_{t = 1}^T \left[{{{\big((1 + r)}^t} - 1\big) / {{(1 + {y_{0,t}})}^t}} \right]} \over {\sum\nolimits_{t = 1}^T \left[{1 / {{(1 + {y_{0,t}})}^t}} \right]}}.$$
Expression (7) is then the default-free value of a fixed rate, compounded COLA over a T-year period as a proportion of the value of the nominal annuity over that same period. The corresponding expression for a non-compounded (simple) COLA at the fixed rate r is
 $$\displaystyle{{ {\sum\nolimits_{t = 1}^T \left[{r \times t/{{(1 + {y_{0,t}})}^t}}\right]} } \over { {\sum\nolimits_{t = 1}^T \left[{1/{{(1 + {y_{0,t}})}^t}} \right]}}}.$$
We calculate (7) and (8) using Treasury security data compiled by Gürkaynak et al. (Reference Gürkaynak, Sack and Wright2007). They provide daily estimates of zero-coupon Treasury yields from daily prices of Treasury coupon notes and bonds. Because their estimates use data on ‘off-the-run’ Treasury securities, liquidity premia that are highest for ‘on-the-run’ Treasury securities are mitigated.Footnote 24 Hence, these yields reflect what a pension fund would earn on more illiquid, seasoned Treasury securities.
The single most common fixed rate that pension funds choose for automatic COLAs is 3%, both when this rate is compounded and when it is not. Therefore, we compare the value of 3% compounded and simple (non-compounded) COLAs for retirement horizons of 10, 20, and 30 years. In each case, the COLA values are expressed as a percentage of the value of the same-horizon retirement annuity that does not contain the COLA. We make these calculations for each day starting from the beginning of October 2004 until February 2015.
Over this sample period, the average compounded versus simple COLAs per nominal benefit at the 10, 20, and 30-year horizons are 17.0% versus 15.6%, 32.5 versus 27.1%, and 48.2 versus 36.8%, respectively. Therefore, as one would expect, compounded COLA are worth more than simple COLAs, and the difference grows as the retirement horizon lengthens. For both compounded and simple COLAs, their values relative to the value of the nominal benefit were highest during periods when the yield curve was generally lowest, such as during the depth of the financial crisis in late 2008 and early 2009, as well as the most recent period of Federal Reserve ‘quantitative easing.’Footnote 25
5.2 Fully inflation-indexed COLAs
Inflation-indexed COLAs provide future cashflows that are random in terms of nominal payments but fixed in terms of real purchasing power. Previous research such as Novy-Marx and Rauh (Reference Novy-Marx and Rauh2011a ) estimates COLAs tied to the CPI by making an assumption regarding future inflation and discounting the resulting expected nominal cashflows by nominal yields. Alternatively, one might discount a CPI-indexed annuity payment using the term structure of real yields, rather than nominal yields. Daily zero-coupon real yield curves estimated from US Treasury Inflation Protected Security (TIPS) coupon prices are available for maturities from 2 to 20 years and could be used.Footnote 26 However, TIPS are less liquid than nominal US Treasuries, and there is evidence that their yields became unrealistically high (and prices unreasonably low) during stress periods such as the 2008–2009 financial crisis.Footnote 27
An alternative to using TIPS to value CPI-indexed COLAs is to use an inflation derivative security known as a zero-coupon inflation swap. Zero-coupon inflation swaps are the most common and liquid type of inflation derivative. Also, traders in inflation swap contracts are subject to regulatory collateral requirements that are intended to minimize counterparty default risk.Footnote 28 A zero-coupon inflation swap is really a forward contract in which there is a single future exchange between two parties where one party pays a fixed payment and the other pays an inflation-linked payment. For a swap negotiated at date 0 and maturing at the end of year t, the net payment from the point of view of the fixed-rate payer is (1 + k 0,t ) t − CPI t /CPI 0, where k 0,t is the inflation swap rate negotiated at date 0 on this t-year inflation swap and CPI t is the CPI at date t.Footnote 29 k 0,t is the inflation swap rate agreed to by the parties at date 0 such that the present value of the future exchange is zero.
Let r 0,t be the annualized real yield on a zero-coupon inflation-indexed bond (e.g., TIPS) that promises one unit of current date 0 purchasing power at the future date t, which in nominal terms equals CPI t /CPI 0. Then the present value of the swap's inflation payment is 1/(1 + r 0,t ) t while the present value of the swap's fixed-rate payment equals (1 + k 0,t ) t /(1 + y 0,t ) t . Since the exchange has zero value, equating the value of these two payments implies k 0,t = (1 + y 0,t )/(1 + r 0,t ) − 1 ≈ y 0,t − r 0,t , which makes the inflation swap rate equal to what is known as the ‘breakeven inflation’ rate.Footnote 30 Hence, knowledge of the term structure of inflation swap rates, along with the term structure of nominal yields, implies a term structure of real interest rates.Footnote 31 Inflation swaps also have advantages because they are quoted daily in maturities from 1 to 30 years, and sometime as long as 50 years.
Like TIPS breakeven inflation rates, zero-coupon swap rates equal ‘risk-neutral’ or ‘certainty equivalent’ expectations of inflation. In other words, zero-coupon swap rates equal actual (physical) expectations of inflation plus an inflation-risk premium. Studies that attempt to estimate this inflation-risk premium typically find that it is positive.Footnote 32 Additional evidence is given in Figure 3 which graphs the 10-year mean forecasts of inflation from the Federal Reserve Bank of Philadelphia's Survey of Professional Forecasters.Footnote 33 For comparison, over the same 2004–2015 period is graphed times series data from Bloomberg on 10- and 30-year inflation swap rates.
Survey of Professional Forecasters mean 10-year inflation forecast versus 10- and 30-year inflation swap rates. Source: Federal Reserve Bank of Philadelphia Survey of Professional Forecasters and Bloomberg.

The figure shows that, over the 2004–2014 sample period, the average 10-year zero-coupon inflation swap rate of 2.65% exceeds the survey's average 10-year expected inflation rate of 2.44%, reflecting an average inflation-risk premium of 21 basis points for a 10-year horizon. The average 30-year zero-coupon inflation swap rate is even higher at 2.93%, consistent with theory predicting that inflation-risk premia increase with the time horizon. As we discuss next, inflation swap rates that include this inflation-risk premium are appropriate for valuing inflation-linked COLAs.
Inflation swaps imply that the value of the random accumulated inflation from the current date 0 to future date t, CPI t /CPI 0 − 1, equals a fixed payment of (1 + k 0,t ) t − 1 at date t. Thus, the present value of this accumulated inflation payment equals [(1 + k 0,t ) t − 1]/(1 + y 0,t ) t . Aggregated over a T-year retirement horizon, a fully CPI-indexed COLA per $1 of initial base year annuity payment equals
 $$\sum\limits_{t = 1}^T {\displaystyle{{{{(1 + {k_{0,t}})}^t} - 1} \over {{{(1 + {y_{0,t}})}^t}}}} $$
and the value of this COLA as a proportion of the total nominal annuity without the COLA is
 $$\displaystyle{{ {\sum\nolimits_{t = 1}^T \big[{{{\big((1 + {k_{0,t}})^t}} - 1\big)/{{(1 + {y_{0,t}})}^t}}} \big]} \over { {\sum\nolimits_{t = 1}^T \left[{1/{{(1 + {y_{0,t}})}^t}} \right]}}}$$
Note that these expressions are similar to those of the fixed-rate COLAs but the term structure of inflation swap rates, k 0,t t = 1,…, T, replaces the single fixed rate, r.
To compute the COLA values in (9) and (10), we obtained data from Bloomberg on daily zero-coupon swap rates at maturities from 1 to 10 years, and also for 12, 15, 20, 25, and 30 years. A swap rate yield curve for every annual horizon greater than 10 years was fitted by a cubic spline that passed through the observed 12, 15, 20, 25, and 30-year rates. Along with the daily nominal yield curve obtained from the Gürkaynak et al. (Reference Gürkaynak, Sack and Wright2007) database, expressions (9) and (10) were calculated for each day from November 2004 through January 2015. The monthly averages of these daily COLA values are plotted in Figure 4.
CPI-indexed COLA values as a multiple of initial year benefit and as a percent of initial year benefit. Source: Bloomberg and Gürkaynak et al. (Reference Gürkaynak, Sack and Wright2007).

Figure 4 plots COLA values for 10, 20, and 30-year horizons. The dotted lines measured by the left axis are the COLA values as a multiple of the initial year's annual benefit. Over the entire sample period COLA these values averaged 1.1, 3.9, and 7.5 times the initial year's annual benefit for horizons of 10, 20, and 30 years, respectively. The values declined dramatically at the depth of the financial crisis as deflation fears heightened. Values appear to have peaked early in 2013 when beliefs that quantitative easing could produce greater inflation were highest.
The solid lines in Figure 4, measured by the left axis, plot the same COLA values but as a percentage of the value of the nominal annuity over the same horizons. Over the sample period, COLA values for 10, 20, and 30-year horizons averaged 13.3%, 27.7%, and 42.5%, respectively, of the nominal annuity values. The declines in these relative values in late 2008 were even more dramatic, since deflation fears coincided with a dramatic decline in the nominal term structure which raised the value of the nominal annuity.
5.3 Inflation-indexed COLAs subject to zero-coupon floors and caps
As mentioned at the start of this section, few, if any, actual pension COLAs are linked purely to the CPI without any constraints. Rather, COLAs are typically constrained by a minimum inflation rate floor, say r f, and often limited to a maximum inflation rate cap, say r c. For example, r f is almost always 0 and r c is often 2% or 3%. If these minimum and maximum rates are compounded relative to the annuity's base year (date 0), then the COLA paid at the end of future year t can be written as
 $$\displaystyle{{CP{I_t}} \over {CP{I_0}}} - 1 + \max \left[ {{{(1 + {r_f})}^t} - \displaystyle{{CP{I_t}} \over {CP{I_0}}},\;0} \right] - \max \left[ {\displaystyle{{CP{I_t}} \over {CP{I_0}}} - {{(1 + {r_c})}^t},\;0} \right].$$
In expression (11), CPI t /CPI 0 − 1 is the unconstrained inflation payment made in year t. The next term max[(1 + r f ) t − CPI t /CPI 0, 0] is the payoff of a put option on inflation, also referred to as a zero-coupon inflation floor. If r f = 0, the floor pays the owner the amount of deflation since the start of the retirement annuity at the initial date 0.Footnote 34 This floor combined with the unconstrained inflation payment CPI t /CPI 0 − 1 implies that the future COLA adjustment is always nonnegative, so that the future annual benefit payment is never less than the base year annual payment. The last term, max[CPI t /CPI 0−(1 + r c) t ,0] is the payoff of a call option on inflation, also referred to as a zero-coupon inflation cap.
Over a T-year retirement horizon, the present value per $1 of base year annuity of the payoff in expression (11) is
 $$\sum\limits_{t = 1}^T {\displaystyle{{{{(1 + {k_{0,t}})}^t} - 1} \over {{{(1 + {y_{0,t}})}^t}}}} + \sum\limits_{t = 1}^T {\left[ {zc{\,f_0}({r_{\rm f}},t) - zc{c_0}({r_{\rm c}},t)} \right]}, $$
where zcf 0(r f, t) is the date 0 value of a zero-coupon floor with floor rate r f and time to maturity t and zcc 0(r c, t) is the date 0 value of a zero-coupon cap with cap rate r f. The combination of purchasing a floor and writing a cap is referred to as a ‘collar.’ Prices of zero-coupon floors and caps are quoted daily for a variety of floor and cap rates. We obtained from Bloomberg daily prices for floors with a floor rate of 0% and for caps with cap rates of 2% and 3%. Prices for 0% floors and 2% caps were available since October 2009, and prices for 3% caps were available starting in April of 2011. Similar to zero-coupon inflation swaps, these floor and cap prices are quoted for maturities of 1 to 10 years and 12, 15, 20, 25, and 30 years. Prices for every annual horizon between 10 and 30 years were obtained by fitting a cubic spline.
Figure 5 plots CPI COLAs with 0% floors as well as CPI COLAs with 0% and 3% collars, and also 0% and 2% collars. These COLAs are computed for horizons of 10 and 30 years as a percent of the present value of the total nominal annuity for the corresponding horizon. Comparing the values of CPI COLAs with a 0% floor to the pure CPI COLAs in Figure 4, one sees that the 0% zero-coupon floor adds relatively little value. On average over the sample period, the value of the floors adds 3.9%, 2.4%, and 1.9% at the 10, 20, and 30-year horizons, respectively, to the value of the pure CPI COLAs. These low floor values indicate that likelihood of deflation over horizons of many years is small. In contrast, the 3% cap at the 10, 20, and 30-year horizons subtracts 12.9%, 17.9%, and 20.5%, respectively, from the pure CPI COLAs. For the 2% cap at the 10, 20, and 30-year horizons, the deductions are 32.6%, 39.2%, and 43.9%, respectively. As expected, the lower the cap, the less valuable is the COLA.
Values of CPI COLAs with zero-coupon floors and caps as a percent of total nominal benefit. Source: Bloomberg and Gürkaynak et al. (Reference Gürkaynak, Sack and Wright2007).

5.4 ‘Simple’ inflation-indexed COLAs subject to year on year floors and caps
A few states offer non-compounded CPI-linked COLAs subject to a 0% floor and a cap. For illustrative purposes, we focus on this type of COLA provided by the State of Illinois.Footnote 35 The Illinois COLA applies to state employees hired after December 31, 2010. It is a non-compounded COLA where annual benefit increases are the lesser of ½ of CPI inflation and 3%, or zero when annual inflation is negative. Therefore, if annual CPI inflation exceeds 6%, the total annual benefit increase is limited to 3%. Because increases are non-compounded, each future year's increase is based on the initial year's annuity value, not that of the year prior to the increase. Since this non-compounded COLA is tied to half of annual CPI inflation subject to a 3% cap and 0% floor, the COLA is equivalent to a non-compounded COLA equal to the full CPI subject to a 6% cap and 0% floor but where the COLA applies to only one-half of the annuitant's initial-year pension payment.
As in our prior calculations, let us assume that each future year's annuity payment is made in a lump sum at the end of each year and includes the year's COLA with no indexation lag. In this case, the total non-compounded COLA cashflow received at the end of year T per $1 of base year annual benefit equals:
 $$\eqalign{&\sum\limits_{t = 1}^T {\min \left[ {\displaystyle{1 \over 2}\max \left[ {{r_{\rm f}},\left( {\displaystyle{{CP{I_t}} \over {CP{I_{t - 1}}}} - 1} \right)} \right],\displaystyle{1 \over 2}{r_{\rm c}}} \right]} \cr & \quad = \displaystyle{1 \over 2}\sum\limits_{t = 1}^T {\min \left[ {\max \left[ {{r_{\rm f}},\left( {\displaystyle{{CP{I_t}} \over {CP{I_{t - 1}}}} - 1} \right)} \right],{r_{\rm c}}} \right]},} $$
where in the case of the Illinois COLA, r f = 0 and r c = 6%.
Each year's annual future random inflation, CPI t /CPI t−1, can be valued using forward inflation rates implied by the term structure of zero-coupon inflation swaps.Footnote 36 Recall that for a swap maturing at the end of year t, the net payment from the point of view of the fixed-rate payer is (1 + k 0,t ) t − CPI t /CPI 0, where k 0,t is the inflation swap rate negotiated at date 0 on a t-year inflation swap. Similarly, for a swap maturing at the end of year t − 1, the net payment from the point of view of the fixed-rate payer is (1 + k 0,t−1) t−1 − CPI t−1/CPI 0, where k 0,t−1 is the inflation swap rate negotiated at date 0 on a (t − 1)-year inflation swap.
The inflation payment received on a t-year inflation swap, CPI t /CPI 0, can be replicated by entering into a t − 1 year inflation swap at date 0, and then at date t − 1 using the inflation proceeds to enter into a one-year inflation swap with the notional principal of CPI t−1/CPI 0. The accumulated inflation proceeds at date t is then (CPI t−1/CPI 0) × (CPI t /CPI t−1) = CPI t /CPI 0, the same as the t-year inflation swap. Thus, the implied forward inflation swap rate that equates the value of the replicating contract is (1 + k 0,t−1) t−1 × (1 + k t−1,t ) = (1 + k 0,t ) t , or:
 $${k_{t - 1,t}} = \displaystyle{{{{(1 + {k_{0,t}})}^t}} \over {{{(1 + {k_{0,t - 1}})}^{t - 1}}}} - 1.$$
Consequently, the random inflation payment of CPI t /CPI t−1 received at date t has the same date 0 value as receiving a fixed payment of a (1 + k t−1,t ) at time t. Equivalently, the payment of CPI t /CPI t−1 − 1 received at date t has the same date 0 value as receiving k t−1,t at time t.
Therefore, since the COLA payment received at date t includes all previous non-compounded annual inflation increases, the present value of the total non-compounded CPI-linked COLA with no floor or cap paid at the end of year t is:
 $$\displaystyle{{\sum\nolimits_{i = 1}^t {{k_{i - 1,i}}}} \over {{{(1 + {y_{0,t}})}^t}}},$$
where y 0,t is the date 0 annually compounded yield to maturity on a default-free zero-coupon bond maturing at date t. Thus, using the term structure of zero-coupon inflation swaps and zero-coupon Treasury securities, we can value future non-compounded annual inflation payments.
Importantly, floors and caps on non-compounding annual CPI inflation payments are traded. They are referred to as ‘year-on-year’ inflation options. For example, the purchase of a year-on-year CPI inflation cap with a maturity of t years and a cap rate of r c would pay max[(CPI i /CPI i−1 − 1) − r c, 0] at the end of each year i = 1,…, t.Footnote 37 Similarly, the purchase of a year-on-year CPI inflation floor with a maturity of t years and a strike price of X would pay max[r f − (CPI i /CPI i−1 − 1), 0] at the end of each year i = 1,…, t. Thus, for each $1 of initial base annuity, the Illinois COLA paid at the end of year t has a value equal to one-half of:
 $$\displaystyle{{\sum\nolimits_{i = 1}^t {{k_{i - 1,i}}}} \over {{{(1 + {y_{0,t}})}^t}}} + yy{\,f_0}({r_{\rm f}} = 0\%, \;t) - yy{c_0}({r_{\rm c}} = 6\%, \;t),$$
where yyf 0(r f = 0%, t) is the date 0 value of a 0% t-year, year on year inflation floor and where yyc 0(r c = 6%, t) is the date 0 value of a 6% t-year, year on year inflation cap. The expression (16) gives the present value of the floored and capped inflation payment made at the end of a single future year, t. Therefore, the present value of COLA payments for years t = 1,…, T has a value equal to one-half of:
 $$\eqalign{&\sum\limits_{t = 1}^T {\left( {\displaystyle{{\sum\nolimits_{i = 1}^t {{k_{i - 1,i}}}} \over {{{(1 + {y_{0,t}})}^t}}} + yy{\,f_0}({r_{\rm f}} = 0\%, \;t) - yy{c_0}({r_{\rm c}} = 6\%, \;t)} \right)} \cr & \quad = \sum\limits_{t = 1}^T {\left( {\displaystyle{{\sum\nolimits_{i = 1}^t {{k_{i - 1,i}}}} \over {{{(1 + {y_{0,t}})}^t}}}} \right)} + \sum\limits_{t = 1}^T {(yyf{c_0}({r_{\rm f}} = 0\%, \;{r_{\rm c}} = 6\%, \;t))},} $$
where yyfc 0(r f = 0%, r c = 6%, t) is a year on year inflation collar with a 0% floor and 6% cap.
Daily prices of year-on-year 0% floors and 6% caps were obtained from Bloomberg over the period from October 2009 through January 2015. As with the zero-coupon floors and caps, these year-on-year floor and cap prices are quoted for maturities of 1–10 years and 12, 15, 20, 25, and 30 years. As before, we fit a cubic spline to obtain prices for every annual horizon between 10 and 30 years.
Figure 6 plots the results of calculating one-half of the value of the expression (17), first including a pure simple (non-compounded) yearly change in the CPI, then adding the zero rate floor, and finally adding the 6% cap rate. COLA costs were computed for 10 and 30-year retirement horizons.
Values of the Illinois COLA as a percent of total nominal benefit. Source: Bloomberg and Gürkaynak et al. (Reference Gürkaynak, Sack and Wright2007).

Compared with the previous section's calculations that used zero-coupon floors and caps, year-on-year floors and caps have values that are larger versus their corresponding unconstrained simple interest COLAs. Over the sample period, the average value of the floors adds 17.0%, 21.2%, and 26.4% at the 10, 20, and 30-year horizons, respectively to the value of the simple CPI COLAs. The 6% cap (3% on ½ of the CPI) decreases the simple CPI COLA by 10.0%, 15.9%, and 21.5% at the 10, 20, and 30-year horizons, respectively. The intuition for the relatively large effects of these floors and caps is that they are based on each year's change in the CPI, rather than the CPI accumulated since the beginning of retirement. If inflation is believed to follow a process that mean-reverts to a target between the floor and cap constraints, the value on long-dated options may be less than that of short-dated ones.
This new Illinois ½ CPI simple COLA with the 0% and 6% collar is worth significantly less than the automatic 3% compounded fixed rate COLA that previously covered all Illinois state employees. Over the sample period, the average value of the new COLA for a 10-year retirement horizon is 5.8 % of the total nominal retirement benefit while the comparable value of the old 3% compounded COLA is 17.2%. At the 20 and 30-year retirement horizons, the new versus old COLA values are 9.4% versus 33.0% and 11.2% versus 49.1%, respectively.
5.5 Limited price index (LPI) COLAs
One of the more common types of COLA is an inflation-indexed, compounded COLA with year on year floors and caps. This COLA is similar to the previous section's non-compounded ‘simple’ COLA with year on year floors and caps. However, standard year on year floors and caps are not equivalent to this compounded COLA's limits because standard year on year floors and caps are based on the same, non-compounded notional principal throughout the lives of the options.
In contrast, compounded COLAs with annual limits on inflation payments can be linked to a LPI that derives from the CPI. Specifically, let LPI t be the LPI at the end of year t, and set LPI 0 = CPI 0 at the initial date 0. Let this LPI be subject to a year on year floor rate of r f and a year on year cap rate of r c. Then the annual change in the LPI is:
 $$LP{I_t} = LP{I_{t - 1}} \times \max \left[ {\min \left[ {\displaystyle{{CP{I_t}} \over {CP{I_{t - 1}}}},1 + {r_{\rm f}}} \right],\;(1 + {r_{\rm c}})} \right],$$
so that its process from date 0 to the end of year T satisfies:
 $$LP{I_T} = \prod\limits_{t = 1}^T {\max \left[ {\min \left[ {\displaystyle{{CP{I_t}} \over {CP{I_{t - 1}}}},\;1 + {r_{\rm f}}} \right],\;(1 + {r_{\rm c}})} \right]}. $$
Thus, LPIs have annual growth rates that are equal to the corresponding annual CPI growth rate, but with the annual growth floored at rate r f and capped at rate r c .
In the United Kingdom, the Pensions Act of 1995 required that pension plans increase their benefit payments with annual inflation up to a cap of at least 5%.Footnote 38 These plans' LPI COLAs were usually indexed to the Retail price index (RPI), which is similar to the US CPI. Perhaps due to a desire by UK pension managers to hedge this type of inflation-risk, zero-coupon inflation swaps trade on LPIs with specific floors and caps. As with a zero-coupon swap tied to the RPI or CPI, a zero-coupon swap tied to an LPI represents a single future exchange between two parties. For an LPI swap negotiated at date 0 and maturing at the end of year t, the net payment from the point of view of the fixed-rate payer is (1 + k 0,t ) t − LPI t /LPI 0, where k 0,t is the LPI swap rate negotiated at date 0 on this t-year swap. Two of the most popular swaps are based on LPIs with the sets of limits (r f = 0%, r c = 5%) and (r f = 0%, r c = 3%).
Given the existence of zero-coupon swaps on an LPI, the value of such an LPI-based COLA is easily valued using the same method for a zero-coupon swap based on the CPI (or RPI). That is by using the expressions in (9) or (10). From Bloomberg, we collected daily data on three different UK zero-coupon swaps: the first based on the RPI, the second on the LPI with (r f = 0%, r c = 5%), and the third on the LPI with (r f = 0%, r c = 3%). Daily zero-coupon bond yield curves based on UK gilts also were obtained from the Bank of England.Footnote 39
Figure 7 graphs COLA values for indexation based on the RPI (with no floor or cap), the LPI with r f = 0%, r c = 5% (denoted LPI05), and LPI with r f = 0%, r c = 3% (denoted LPI03). This is done for the period of July 2012 through December 2014 for retirement horizons of 10 and 30 years and expressed as a percent of total nominal annuity value.
RPI- and LPI-based COLA values as a percent of total nominal benefit. Source: Bloomberg and Bank of England.

For all horizons, the LPI05 COLA values are very similar to those based on the RPI. On average over the sample period, the LPI05 COLAs are worth 99.0%, 99.6%, and 100.8% of RPI COLAs for horizons of 10, 20, and 30 years, respectively. Consequently, the value of the 0% floor is approximately equal to the value of the 5% cap. In contrast, the LPI03 COLAs are worth 77.7%, 72.2%, and 68.4% of RPI COLAs for horizons of 10, 20, and 30 years, respectively. Thus, the tighter 3% cap significantly reduces the COLA value.
At this time, LPI swaps based on the US CPI are not traded. In the absence of these swaps, valuing LPI-based COLAs require additional assumptions regarding the random process followed by the CPI index.Footnote 40 Such valuation, while straightforward, is beyond the scope of our paper. However, given that the CPI inflation has been similar to RPI inflation in the last few years, we expect LPIs based on the US CPI might not be too different from those in Figure 7.
5.6 COLAs conditional on funding status or legislative discretion
The Wisconsin Retirement System and most pension plans in the Netherlands offer COLAs that are explicitly contingent on a plan's investment returns or funding status. Since funding status depends, at least partially, on the pension fund's asset returns, one way to account for these types of promised COLA payments is to value them as options on the pension fund's assets. Promised future COLA benefits would be higher (lower) when future asset values are greater (less) than the COLA-contingent exercise value. Bikker and Vlaar (Reference Bikker and Vlaar2006) take such an approach when valuing COLAs of Dutch pension funds which guarantee nominal pension benefits but where COLAs are contingent on a plan's funding ratio. Novy-Marx and Rauh (Reference Novy-Marx and Rauh2014) also use the option-pricing theory to value various types of retirement benefit adjustments linked to investment performance.
In practice, it may be difficult to accurately value options written on a pension fund's asset portfolio. An alternative might be to calculate two liability measures of a plan's funding status: one which values only promised nominal payments assuming no COLA will be paid; another which values both nominal and COLA payments assuming the COLA is paid with certainty. These two measures would represent lower and upper bounds on the default-free value of pension benefits.
This two-measure approach for valuing promised pension liabilities also would be reasonable when a plan's COLA is at the discretion of legislators or the plan's directors.Footnote 41 Moreover, providing two liability measures, one with and one without a COLA, makes the marginal COLA cost transparent and should lead to improved policy.
6 Conclusion
How pension plans should account for the value of their liabilities is a prominent policy issue, as evidenced by a recent US Senate-requested Government Accountability Office (2014) study of this topic. The GAO found that ‘experts sharply disagree on which approach should be taken to calculate these plans' estimated obligations for benefits promised to workers and retirees.’ Given this lack of consensus, it is not surprising that the GAO decided against making any recommendations as a result of its findings.
We anticipate that our paper clarifies the essential issues of pension discounting and, as a consequence, creates consensus on how discounting should be done. Our main point is that the appropriate rate for discounting depends on the purpose of the discounting exercise. In particular, if the objective is to account for pension under- or over- funding, a default-free discount rate should always be used.Footnote 42 Instead, if the objective is to determine the market value of an employee's pension benefits, then it is appropriate that discount rates incorporate the plan's default risk.
Another contribution of our work is to show how to account for different types of COLAs in pension plan benefits. In many instances, inflation-linked benefits can be valued by recognizing that they are replicated by inflation derivatives, such as inflation swaps, floors, and caps. Using the market prices of these derivative securities the cost of specific COLAs can be objectively determined. The ability to accurately value COLAs is particularly important for gauging the impact of recent and proposed public pension plan reforms.
Appendix
Data sources



