

Introduction
Famously, colonial commodity production was geared to metropolitan (or quasi-metropolitan) requirements for raw or semi-processed materials. Of course, there were plenty of exceptions. In southeast Asia, the world's foremost zone of colonial plantation and mining activities for more than half a century prior to the Second World War, the rubber and tin industries serviced not only metropolitan demand but also that of third parties, most notably the United States. Nonetheless, the situation of the erstwhile Netherlands Indies (present-day Indonesia) was quite exceptional in this respect.Footnote 1 The vast colony of a small European nation, its commodities, especially as they were developed for export c. 1880 onwards, could not possibly hope to find their main market in the ‘mother country.’ Instead, as perhaps befitted a trading nation with a relatively small industrial base and an equally small population of consumers, the bulk of Indies exports were destined for (eventual) sale elsewhere than the Netherlands or even its European commercial hinterland.
From the late nineteenth century onwards, this was spectacularly the case with sugar, the foremost export commodity of the Indies from the late 1870s through to the early 1930s. Beginning in the 1880s, the colony's industrialised sugar factories, all of them located on the key island of Java, lost virtually all connection with metropolitan markets and European consumers. Around the turn of the century, the bulk of the island's sugar exports went to the United States, where they made up for the (temporary) shortfall in imports from the Caribbean, consequent of the revolution in Cuba and subsequent Spanish–American war. Towards the end of the first decade of the twentieth century, however, these exports dropped away and (with a hiatus during the Great War, when it again exported huge quantities ‘west of Suez’), Java became the prime supplier of sugar to other Asian—rather than Western—markets, primarily in the Indian subcontinent, in China and in Japan.
In consequence, Java's colonial sugar producers, who were second only to Cuba in terms of the quantities that they exported, stood out in the international sugar economy of the early twentieth century as a uniquely exogenous industry. No other major producer of sugar for world markets had an ‘outsider’ status remotely comparable to that of the Java sugar factories of the late nineteenth and early twentieth centuries. Unlike their global counterparts elsewhere in the Asia-Pacific region and in the Caribbean, production in Java developed outside the endogenous context of ‘home’ markets and (quasi-)imperial connection that supplied a degree of assured sales to export-oriented industries elsewhere in Asia (the Philippines and Taiwan) and in much of the New World.
Likewise, the Java manufacturers lacked the exclusive marketing, financial and ownership ties with (overseas) refineries that typified internationally most of their cane sugar producing counterparts. East Asian refineries in both Hong Kong and Japan were major customers for Java's output of raw (brown) sugar, but the vertical integration that characterized refinery–producer relations in, for example, the United States and the ‘American’ Caribbean from the early twentieth century onwards was largely absent in the case of Java. It was an absence reflected, moreover, in the very high proportion of Java's output that consisted of factory white (aka ‘plantation white’ or ‘bianco’). Originating in the beet sugar factories of northern Europe c. 1870 onwards, this was a variety of the commodity created through chemical treatment of ‘raw’ cane juice during the course of processing it into sugar. It was a somewhat coarse but relatively cheap product (which improved over time) that could be sold to direct consumers without further refining.Footnote 2
Devoid of ‘metropolitan’ connections of these several kinds, the colony's sugar industry was one in which Dutch and Dutch colonial (and Indies Chinese) capital exploited Javanese land and labour to produce a commodity that found its markets outside the Netherlands’ domestic or imperial orbit.Footnote 3 The upshot was to leave the industry singularly exposed to the vagaries, vicissitudes and volatility of the international commerce in sugar, at a time when the notional ‘world market’ for the commodity was becoming increasingly residual— and was to become even more so when the interwar Depression of the 1930s exacerbated already existing tendencies toward autarchy.
Java Sugar and the Interwar Depression
Viewed from the standpoint of the early 1920s, the Java industry's development of mass markets in Asia for industrially manufactured sugar had proved an eminently successful strategy: it compensated for the almost complete loss of those sales in the West that had underpinned its mid-nineteenth-century expansion. The strategy was predicated on the price advantage enjoyed by Java factory sugar over the locally produced ‘indigenous’ form of the commodity and on the growing taste among the new middle classes of early twentieth-century Asia for sugar that was white, hygienic and ‘Western.’ As a result, for two decades the Java factories enjoyed a sales bonanza in east Asia (and, likewise, in the Indian subcontinent). For a decade or more, from the time of the outbreak of the First World War (which incapacitated rival beet sugar producers in Europe) through into the 1920s, the Java industry had Asia largely to itself. Its domination of markets from Bombay through to Shanghai was scarcely threatened either by local domestic factory production or by imports from rival producers elsewhere in the international sugar economy of cane or beet.
It was virtually inevitable, of course, that Java's position as Asia's prime purveyor of industrially manufactured sugar would not last forever. However, Java's colonial producers gambled on an almost limitless expansion of the Asian market and on their own superior expertise and efficiency to ensure their hold over it. This proved to be a miscalculation. During the interwar decades, the industry's late colonial trajectory began to unravel, eventually in fairly dramatic fashion. The industry's output peaked in 1930 at a little over 3 million tons. Five years later, only 30 of its nearly 180 factories remained in operation, and their production amounted to only one-sixth of the industry's 1930 total. Sales had plummeted, so that Java ran some danger of submerging under a mountain—as big as 3 millions tons—of unsold sugar, part at least of which had to be disposed of at fire-sale prices.
In short, the Java industry experienced a commercial crisis during the 1930s of a quite different order, quantitatively speaking, than that of Cuba, its erstwhile Occidental counterpart. Cuba's output peaked at (an exceptional) 5 million tons in 1929 and hit a low of under 2 million some four years later in 1933. After that, however, its production rapidly returned to over 50% or more of its pre-Depression peak. This was not least because it was able to maintain—from 1934 onwards—a level of exports to its main United States market that, in most years, amounted to nearly two-thirds of its average sales during the previous decade.Footnote 4
Java enjoyed no such advantage, and the depth of the crisis that its sugar industry experienced during the Depression decade singled it out from virtually all its major competitors in the international sugar economy. Moreover, though the industry experienced a degree of recovery towards the end of the decade, it was late in coming and predicated, not on steady—albeit reduced—access to its old markets, but on a fluctuating ability to sell its extremely cheap product on international ‘spot markets.’ By 1941, a year before the Japanese invasion of the island, 85 of Java's sugar factories were back in operation, and output amounted to 1.7 million tons or well over half the industry's production at its pre-Depression peak. Nonetheless, the revived industry's commercial future was uncertain. Asian markets that had formed the industry's key outlets prior to 1931 remained so precarious that in 1938, sheltered by newly granted preferences in the Dutch metropolitan market and sugar shortages in Europe, the Java product found greater sales in ‘the West’ than it did in Asia.Footnote 5
Simply to posit the Java sugar industry as a major casualty of the interwar world Depression, however, is to an extent misleading. A broader, more comprehensive history of Java sugar during the interwar decades relates to the causes of the Depression as well as its effects and to the evident complexity of the industry's ambiguous location across the notional divide between industrial and agricultural Depression.Footnote 6 On the one hand, in respect to production, Java sugar undoubtedly experienced problems common to manufacturing industries worldwide from the mid-1920s onwards, including overproduction and the downward spiral of the price of manufactured commodities. It was not simply blind commercial folly and over-sanguine expectations of ever-expanding Asian markets that brought the Java industry to its knees in the early 1930s. Specifically, the Java producers were caught up in a drive to increase the throughput of their factories and thereby bring down the unit costs of production. However, since similar developments were taking place throughout the international sugar economy during the 1920s (of which Cuba was perhaps the foremost instance),Footnote 7 the industry was caught up globally in a vortex that was almost guaranteed to bring about a major crisis of over-supply. These were developments by no means unique to sugar manufacturers, and the sudden closedown in the early 1930s of the big industrial plants that constituted the heart of Java sugar had numerous contemporary parallels throughout the industrialised world of western Europe and North America.
On the consumption side of the equation, however, the situation was different and posed unique difficulties for an industry as exposed to the vagaries of the international sugar economy as was that of Java. In respect to its sugar sales, c. 1930 onwards, Java was caught up in an agricultural Depression in those parts of Asia in which it found its major markets. In this context, the industry encountered responses, in the form of Depression era economic nationalism and consequent autarchy, over which, because of its exogenous character, it had virtually no influence and absolutely no control. This was, in short, a crisis of a different order to that postulated by reference to a worldwide turmoil of industrial capitalism, though far from unconnected with it.
Moreover, the crisis in consumption that stemmed from agricultural Depression is easily misread. It is indeed true that recorded world sales of sugar fell after 1930, following a decade of considerable growth, and that they remained in the doldrums for the better part of the subsequent decade.Footnote 8 Yet, the exact situation with respect to Java sugar's (erstwhile) major customers is far from clear. In Japan (where the relevant data might be assumed to be fairly reliable), the secular trend towards rising per capita consumption of sugar faltered briefly early in the 1930s and then resumed its upward trajectory.Footnote 9 In China which (together with the Indian subcontinent), prior to the Depression, constituted by far the largest market for Java sugar, largely impressionistic evidence is that per capita consumption indeed fell. A Dutch report of 1933, for example, sought to explain the disastrous decline in the sales of Java sugar in China in terms (in part at least) of the ‘constantly declining purchasing power of the population.’Footnote 10 Nonetheless, it is equally clear that Depression conditions affected the various strata of consumers differently; that industrially manufactured sugar generally found its markets among middle classes that experienced the Depression less harshly than workers and peasants; and that we need to be wary of an unquestioning application of the ‘Depression’ concept to developments during the course of the 1930s. Ramon Myers, for example, has argued that the Chinese economy experienced growth rather than regression for much of the decade.Footnote 11
In short, all-purpose, one-case-fits-all explanations of developments in the international sugar economy during the 1930s need to be treated with some scepticism and do not explain adequately or even substantially Java sugar's plummeting sales. With respect to its Asian markets, the industry's problems were caused less by an overall decline in consumption than by the fact that the sugar that was consumed no longer came pre-eminently from Java. In the case of India, this was because of the rapid expansion of the industrial manufacture of sugar within the subcontinent itself and the encouragement given to this development by a tariff regime that placed huge imposts on the imported commodity, including that from Java.Footnote 12 In east Asia, however, the situation in which the Java producers found themselves was somewhat different.
Java and the Japanese Sugar Empire
The great bulk of Java sugar exported to the Indian subcontinent was comprised of factory white, available for direct consumption without further refining. Prior to the late 1920s, however, Java's exports to east Asia consisted predominantly of ‘raw’ brown sugar, destined for refineries initially in Hong Kong, from where it was exported to China and Japan. Subsequently, and in increasing quantities, it was sold to refineries in Japan itself. This resulted in a radical change in the dynamic of Java's east Asian markets. What began in the 1880s as a relationship with two rival British refineries in Hong Kong—above all with Butterfield and Swire's Taikoo (established 1884)—had become by the 1920s a relationship in which Nippon, in the shape of a small handful of major Japanese business concerns, played the key role. Indeed, by the early 1920s, the Java sugar industry had become, in effect, an outpost of the Japanese sugar ‘empire’.
The origins of that empire—a term that usefully exploits the comparison with its larger, virtually contemporaneous American counterpart, whose Asian outlier was located in the Philippines – lay in the country's transformation into Asia's first modern state in the late nineteenth and early twentieth centuries. Worldwide, a taste for white sugar and sugar-sweetened drinks was one of the consumerist hallmarks of that modernity. Japan was no exception. There was a notable growth in imports of primitively manufactured, ‘pre-industrial’ sugar into Japan from around 1870 onwards, initially from southern China but subsequently from Formosa. Imported refined sugar, increasingly derived from industrially manufactured raw material from Java itself, started to penetrate this market c. 1880. Towards the end of the century Japanese imports of sugar peaked at around 18,000 tons. Much of it was supplied by Hong Kong refineries and bought by Japan's new urban middle classes, reflecting the fact that it was significantly more expensive than the crude, non-refined sugar imported from either Formosa or the Philippines.Footnote 13
During the 1880s and 1890s, Japan's average per capita consumption of sugar began to surge ahead of that of its east Asian neighboursFootnote 14 and quickly came to attract the attention of the big zaibatsu that were indelibly associated with the country's economic advance. As early as 1896, it was reported from Hong Kong that a Japanese syndicate had ‘already sent its emissaries to Europe to study the best methods for plant etc.’Footnote 15 A couple of refineries were quickly established, one of them at Osaka and the other in Tokyo, with more to follow.Footnote 16 The Osaka refinery had German-built equipment and was said to be capable of producing 100 tons of refined sugar per day.Footnote 17 These refineries quickly came to be designated as ‘a troublesome competitor' by their British counterparts in Hong Kong,Footnote 18 who had previously had the east Asian market for refined sugar very largely to themselves, and plans were mooted (though soon abandoned) to flood the Japanese market with cheap sugar in an effort to deter further investment in domestic refining.Footnote 19
Mitsui and Mitsubishi capital—the capital, that is to say, of the two commercial, financial and industrial conglomerates that lay at the heart of Japan's late-nineteenth-century transformation—was closely involved in the new ventures. Indeed, sugar was one of the most important items traded by Mitsui through to the outbreak of the Second World War.Footnote 20 During much of the 1910s and the first half of the 1920s, however, the biggest name in the country's sugar trade was not one of the established zaibatsu but the (relative) newcomer firm of Suzuki Shoten. Founded in Kobe in 1874 specifically as a sugar import business, by 1914 Suzuki had become a widely diversified conglomerate, with major interests in steel and shipping. It eventually embraced some 78 corporations and rivalled Mitsui itself in terms of paid-up capital and value of traded goods.Footnote 21 Nonetheless, sugar remained one of the key facets of its business. Indeed, an early twentieth-century head of the company apparently became known as Japan's ‘king of sugar refining’.Footnote 22
By the 1920s, the Japanese refineries, such as that with which Suzuki was associated, were supplying not only Japan's domestic market but also that of the adjacent Chinese and Manchurian mainland immediately to the west and south. Indeed, by the early 1930s the Japanese appear to have been operating three refineries in Manchuko and by the end of the decade were also running one in (occupied) Shanghai.Footnote 23 As did their counterparts worldwide, by the late 1920s, Japanese sugar interests formed a cartel, designed both to restrain production and to maintain the domestic price of the commodity.Footnote 24 Moreover, the fundamentally international character of the Japanese sugar empire, focused on the markets of its Asian neighbours as well as on those of metropolitan Japan, was already firmly established in the pre-Depression decade. In this respect, it differed significantly from its United States’ counterpart, based in Cuba, Hawaii, the Philippines and Puerto Rico, which had a vastly greater domestic market in North America than its Japanese counterpart and hence had no absolute need for export sales of its refined product. The Japanese refineries on the other hand (as we shall see) were heavily dependent for their viability on their ability to divert ‘excess’ capacity onto overseas markets, above all in China.
The empire drew its raw material from a variety of sources. Its eventual centrepiece was the island of Formosa (Taiwan), which Japan had acquired as a colony in 1895. Nonetheless, its suppliers were as far-flung as beet sugar producers in Korea (brought formally under Japanese control in 1910) and cane sugar factories in the mandated territory of the northern Marianas, in Micronesia, far to the south, which Japan gained in the wake of the German defeat in the First World War. By the mid-1930s, more than 11,000 hectares of cane and six or more large modern sugar factories existed there, worked by a mixture of Japanese, Korean and local labour.Footnote 25 The Empire also established a beachhead on Java. Around 1920, a handful of factories (five out of a total of nearly 180) were owned by Japanese interests, including the Dai Nihon refinery company, one of Japan's biggest.Footnote 26 The prime—and very substantial—connection between the Java industry and the Japanese sugar empire, however, was essentially a commercial one. Japanese interests had very little direct investment in the manufacture of Java sugar but had huge sums tied up in its purchase and shipment to Japan and elsewhere in east Asia.
The development of Japan's connections with the Java industry dated from the very beginning of the twentieth century, when, for example, the new Suzuki refinery at Kobe appears to have drawn most of its supplies of raw sugar direct from Java via the newly established (and Dutch run) Java–China–Japan Line's steamers.Footnote 27 A direct Java–Japan shipping route was established under Japanese auspices in 1912, and another followed in 1916.Footnote 28 The connection was greatly accelerated by the impact of the First World War and the consequent shifting of the Netherlands Indies out of the European and towards the Japanese and United States’ economic orbits.Footnote 29 Though the end of hostilities in 1918 brought some return to prewar conditions, the extent to which Japanese and associated commercial and financial interests had penetrated—and continued to penetrate—the Indies economy emerges quite clearly from analysis of Java sugar sales in the course of the 1920s.Footnote 30
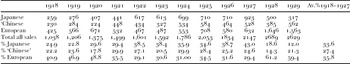
Throughout the decade, the great bulk of Java's sugar sales, representing about 90% of the colony's total production, were carried out through the VJSP (Vereenigde Javasuiker Producenten or United Java Sugar Producers Association), a cartel of manufacturers established in 1918.Footnote 31 On the basis of the VJSP's extensive surviving data, we can show that, on average, in the 10-year period prior to the sudden termination of large Japanese purchases of Java sugar in 1928 (see Table 1), around one-third of the cartel's sales were made direct to Japanese buyers, with Suzuki and Mitsui well to the fore.Footnote 32 During these years, on-average Japanese purchases of Java sugar fell only a little short of those made by the colony's long-established European ‘sugar’ firms, principally Fraser Eaton, Erdmann & Sielcken and Wellenstein Krause.Footnote 33 Indeed, in a few years—1922–2 and 1926–1927—Japanese firms bought substantially more sugar than did their colonial-based European counterparts. Moreover (as we shall see), in assessing the full extent of Japan's position in the trade in Java sugar, the large sugar purchases of Java's Indies-Chinese firms also have to be taken into account.Footnote 34
Japanese, Indies Chinese and European Sugar Purchases from VJSP 1918–1929 as % of total VJSP sales in those years (ooo metric tons)

Yet, the importance of Japan to the Java sugar industry was not simply that it bought large quantities of sugar. Japanese interests were also prominent in the financing of the sugar trade over and above the direct purchase of the commodity.Footnote 35 In 1921, for example, just over half of the sugar sold by the VJSP, to the value of nearly 178,600,000 guilders, was disposed of against guarantees (i.e. under arrangements ‘waarvoor zekerheid moest worden erlangd’) provided by banks and other financial institutions. In all, 10 such businesses were involved, but six of them led the field by a wide margin.
Ranked in order of importance measured in terms of guilder value of their investment, the foremost of these six key financiers was the Indies’ own premier financial provider, the Batavia-based De Javasche Bank (DJB), closely followed by the Bank voor Indie, established in Rotterdam only a year earlier.Footnote 36 Next, however, however, were two Japanese and Japanese colonial concerns. One was the Bank of Taiwan, the quasi-official central bank of the Japanese colony. Founded at the very end of the nineteenth century to facilitate the penetration of Japanese capital into mainland China and southeast Asia, by the early twentieth century it had several branches in the Netherlands Indies. The other was the Yokohama Specie Bank, the institution that in the early twentieth century financed the bulk of Japan's foreign trade.Footnote 37 The remaining European member of the ‘big six,’ the Batavia Branch Office (the Factorij) of the Amsterdam-based NHM (Nederlandsche Handelsmaatschappij), the biggest investment and banking concern operating in the Indies, ranked at number five, only a very little ahead of Mitsui Bussan Kaisha, the commercial and banking wing of the eponymous combine. Through the investments of these several firms, Japanese or Japanese colonial capital provided in 1921 around 46% of the financial backing for that part of the VJSP's sugar trade that was carried out on the basis of bank guarantees—and by 1925 (the only other year in the 1920s for which this information is available) it provided some 50%.
Along with the Japanese and colonial European firms engaged in the trade in Java sugar in the 1920s, Indies-Chinese business concerns also played a significant role, presaging their larger and later role as Asian ‘multinationals.’ From the point of view of the present analysis, however, the immediate point is the extent to which, in the 1920s and earlier, they drew on Japanese (or Japanese colonial) capital to underpin their ventures. Though there were a plethora of such firms, only two stood out as consistent and large-scale participants: Kwik Hoo Tong (KHT) and Kian Gwan, itself the commercial arm of the Oie Tjong Ham ‘Concern’ (OTHC), by far the largest ‘Chinese’ firm operating in late colonial Indonesia.Footnote 38 In total, Indonesian-Chinese purchasers of Java sugar accounted for a little less than one-third of all the sugar sold by the VJSP in 1921, and many small dealers were involved, most of whom appear to have been engaged in the speculative resale of sugar in Java itself. It was KHT and Kian Gwan, however, which bought the bulk of the sugar sold by the VJSP to Indies-Chinese buyers. Both firms were based in Semarang, midway along Java's north coast, and both had extensive connections not only in the Indies (and Singapore) but also in east Asia, where their networks of offices and investments extended from Kobe to Shanghai, Hong Kong and Formosa.
Both KHT and Kian Gwan had long-term links with Japanese capital. Kwik Djoen Eng, who masterminded KHT from the 1910s until its collapse in the 1930s, had major interests on Formosa, where he owned a tea export company, and had close links with the Bank of Taiwan that dated back to the period of its foundation in the very early years of the century. Indeed, it was in Formosa that he died in 1935. Kian Gwan's commercial profile showed some similar traits. Early in the twentieth century, Kian Gwan had opened a branch in Kobe, in addition to those in Hong Kong and Shanghai. Oei Tiong Ham, the head of the conglomerate of which Kian Gwan was a part, had close contacts with Japanese capital (and worked hard to promote collaboration between Chinese and Japanese traders and to mitigate the impact in the Netherlands Indies of anti-Japanese commercial boycotts). Close and early ties to the Bank of Taiwan were also part of his business profile, and like Kwik Djoen Eng, he had a Japanese passport (and hence dual citizenship in the Netherlands Indies), in consideration of his standing in east Asia in general and Formosa in particular. The extent to which KHT and Kian Gwan's operations were financed by Japanese capital is impossible to say, and other sources were also involved. It rather looks, for example, as if De Javasche Bank (DJB or The Java Bank), for example, was the major creditor of KHT.Footnote 39 Nonetheless, this hardly detracts from the conclusion that for the better part of a decade prior to 1927, Japanese capital, either directly or indirectly, through Japanese businesses and banks and through their links with the colony's Indies-Chinese ‘multinationals,’ accounted for the greater part of Java's export trade in sugar.
Java's Marginalisation in the Japanese Sugar Empire
During the late 1920s, in a rapid reversal of previous trends, the Java industry was effectively marginalised in relation to the Japanese sugar empire. There were three main factors at work here. One was crisis within the empire itself, precipitated by the collapse of the Suzuki zaibatsu in 1927 and by long-running, albeit intermittent, boycotts of Japanese products, sugar included, in Nationalist China. The second, and probably the critical factor, was the emergence of the colony of Formosa as a rival supplier to Japan's refineries. A third, rather more speculative, was the failure during the 1930s to resolve a trade war between the Netherlands Indies and Japan which could hardly fail to damage the interests of Java sugar, even though the commodity was only tangential to the main issues involved. The immediate impact of these three developments, however, was masked by a fourth: a temporary boom in sales of Java sugar—predominantly unrefined factory white—on the China market, in apparent response to the difficulties there of both the Japanese refineries and their British counterparts in Hong Kong.
The 1927 collapse of Suzuki threatened to take with it a sizeable swathe of key Japanese financial institutions, both in Japan itself (where the prime minister and cabinet also fell victim to the crisis) and in Formosa. With close financial ties to the failed zaibatsu, the Bank of Taiwan had to close its doors temporarily and to curtail its subsequent operations.Footnote 40 The crisis also took its toll on those Indies-Chinese multinationals that had come to play such a big part in the Java sugar trade to east Asia, and who were heavily dependent on Japanese or Formosan capital. In particular, it contributed to the gradual collapse at the end of the 1920s of KHT and may be presumed to have curbed the activities of the other major Indies-Chinese combine, Kian Gwan.Footnote 41
The situation was exacerbated by the military-political situation in China itself. Between 1926 and 1929, escalating civil war intermittently brought large-scale trade to a virtual standstill in the Yangzi Valley hinterland of Shanghai, the key centre for the sugar trade that provisioned central China.Footnote 42 From the late 1920s onward, moreover, well before they embarked on a full-scale war in China, Japanese military aggression (notably the Jinan Incident of May 1928), answering Chinese boycotts of Japanese goods and business, created considerable problems for the Japanese sugar trade on the China coast.Footnote 43 In Shanghai itself, the Japanese-owned refinery was forced to close.Footnote 44
It was in the Shanghai market, in particular, that the anti-Japanese boycott had its greatest impact: so much so indeed that, by the middle of 1929, Japanese sugar dealers were resorting to repacking their sugar into the gunny sacks typical of Netherlands Indies production and attempting to sell it as ‘crushed Java.’Footnote 45 Dutch commercial representatives in the city were prone to congratulate themselves on the discomfiture of their competitors—though the fact was that much of the Japanese refinery product that had reached China at this date was derived from Japanese imports of Java ‘raws.’Footnote 46 Roughly contemporaneously, the British refineries in Hong Kong—Taikoo and the China Sugar Refinery (CSR)—experienced difficulties of a similar but not identical kind. Beginning in 1925, boycotts, strikes and political turmoil in their south China hinterland made the second half of the 1920s a disastrous period for business. Taikoo survived after a temporary shutdown, but the CSR closed down for good. In these circumstances, large quantities of Java white—unrefined but ready for direct consumption—appear to have plugged the gap that was left by the disruption to the supply of refined sugar.
‘A Flood of Factory White’: Java and the China Market at the end of the 1920s
Early in 1929, the Taikoo refinery's British owners had prefaced an analysis of future prospects with the observation that China had become ‘with its deep and practically open market . . . the world's dumping ground for sugar: the Japanese are dumping unmercifully; Java [i.e. Java factory white] are flooding the market at rock bottom prices; Cuba is also turning its attention in this direction;[and] the Continental beet producers are also looking this way.’Footnote 47 Nonetheless, ‘China,’ as the owners aptly observed, was not one market but three. Northern China and Manchuria constituted one sector; a second was formed by central China and Shanghai; and a third was that of southern China (and adjacent Hong Kong). At the end of the 1920s, the first of these sectors, boycotts notwithstanding, was one ‘in which the pace . . . [was] set by Japanese sugars.’Footnote 48 In the second and third sectors, however, the circumstances just described combined towards the close of the decade to provide an unprecedented opening for Java's factory white, which more or less dominated the market in South China and vied for supremacy in Central China and Shanghai with Japanese imports.
Indeed, between 1927 and 1931, Java's exports of factory white to China, either directly to Shanghai or indirectly via Hong Kong, were sufficiently large to compensate for the drop in the industry's sales to east Asian refineries, be they Japanese or British.Footnote 49 Until 1927, the bulk of the Java industry's exports to east Asia took the form of raw sugar. Despite the very significant drop in refinery purchases—and especially in sales in Japan in the late 1920s—Java's exports to east Asia remained buoyant. In 1925–1926, total exports to all such destinations (Hong Kong, China and Japan) amounted to 880,877 tons, while five years later (1930–1931) they stood at 885,023 tons—despite a drop of nearly 50% in the amounts going to Japan.
This new phase in Java's exploitation of the China market was carried on primarily through the agency of Java's old-established European sugar trading firms, Fraser Eaton (part of the Maclaine Watson combine), Erdmann & Sielcken and Wellenstein Krause. It was they, rather than the big Indies-Chinese firms, who significantly increased their purchases of Java sugar in these years. Total ‘European’ purchases of Java sugar had amounted to no more than 30% of sales in 1926 and 1927. Over the following three years, however, they accounted on average for some 56% of such purchases.Footnote 50 Reportedly, the direct trade in sugar between Java and Shanghai was carried on by Chinese importers, who were said to prefer to deal with Java's European firms rather than with their “own countrymen” on the island.Footnote 51 In the absence of any surviving documentation from the companies concerned, it is impossible to say how profitable this trade was—but it can hardly have been a losing game: to all appearances, the Java industry was able to sidestep and take advantage of the late 1920s crisis in both the Japanese sugar empire and Hong Kong—and to achieve a considerable degree of success, selling factory white into the China market in quite unprecedented quantities.
Nonetheless, developments in the China market need to be placed in perspective. Although Java maintained the 1925–1926 level of exports to east Asia, it proved incapable of increasing its overall sales in the region during a period in which its output of sugar grew significantly. Production, which had stood at around 2.3 million tons in 1925, had risen to a little over 3 million tons by 1930. Much of this ‘excess’ production was absorbed by the south Asian market: developments there, however, were about to make Java's prospects in the subcontinent even less promising than those in China, where, by 1932, the boom in the import of factory white was coming to an end.
Tariffs, Nationalist Factories and Smokeless Sugar: Java and South China in the 1930s
Most immediately, the Java industry's prospects in east Asia were stymied by the imposition by the Chinese Nationalist authorities of a substantial tariff on imported sugar. This took place in the context of attempts not only to raise revenue but also to protect the development of a nascent industrial base for indigenous sugar manufacture, a development in which the state was itself directly involved. The actual production of industrially manufactured sugar in China during the 1930s was so small that it could have had little direct impact on existing overseas suppliers, though a parallel upsurge in peasant-made brown sugar may indeed have had some such effect. (There was a stark contrast here with contemporary developments in the Indian subcontinent, where industrialised sugar manufacture virtually replaced imports by the close of the decade.) On the other hand, the tariff regime that ran in tandem with attempts to establish industrialised manufacture had far-reaching implications for the Java industry. Notionally, at least, imported sugar was priced out of the range of many consumers, turning into what Dutch sources lamentably called a ‘luxury item.’Footnote 52 Even more to the point, however, it promoted large-scale smuggling, the chief beneficiaries of which were rival Japanese sugar interests, who drew increasing amounts of their raw material from sources other than the Netherlands Indies. In combination, these two developments had serious, and ultimately disastrous, consequences for the Java industry's hopes of retaining or regaining its hold over the east Asian market.
The production of industrially manufactured sugar began in south China in the mid-1930s, under the patronage of the Nationalist leader Chen Jitang, whose regime monopolized the production and sale of white sugar throughout Guangdong.Footnote 53 Half a dozen up-to-date sugar factories, with equipment of either Czechoslovak (Skoda) or United States (Honolulu Ironworks) origin, were established there, variously under military and civilian auspices, and presided over by Dr Feng Rui, an American-trained agricultural expert and chief architect of Chen's sugar production scheme.Footnote 54 Some of the technicians, including a number of Indonesian-Chinese sugar makers, were ex-employees of the Java industry.Footnote 55 In 1937 (after the ousting of Chen Jitang and the execution of Feng Rui on a charge of large-scale sugar smuggling), colonial Indonesia's ubiquitous Kian Gwan, a multinational avant la lettre, with what was said to be an ‘outstanding' business organization in China and ready access on a personal level to influential people in the Nanjing government, took over the running of several of the factories.Footnote 56 In a development likewise foreshadowing overseas Chinese investment later in the century, Straits Chinese capital was also tentatively involved. However, neither development came to fruition. The Straits interests withdrew,Footnote 57 and Kian Gwan severed its links within less than a year.Footnote 58
It cannot be said with any degree of certainty how much sugar was actually produced before the factories concerned were badly damaged by Japanese bombing raids in 1938.Footnote 59 A year previously, it had been reckoned that output had never been more than 20,000–30,000 tons annually: this amounted, at best, to only a little over 1% of broadly estimated Chinese annual consumption and to no more than 3% of the quantity of sugar imported into China at the height of the boom at the end of the 1920s.Footnote 60 Quality also left much to be desired. For the most part, it was said to be ‘by no means up to the standard of Java Whites,’Footnote 61 and when quantities started to arrive in Shanghai in 1935, it hardly competed against overseas sugar, even with the protection afforded by the high tariff then in force.Footnote 62 Part of the problem was that the majority of the Guangdong factories were equipped to produce raw (brown) sugar, meant for subsequent refining, but had been converted—without total success, it would seem—to the production of ‘Factory White’ that was suitable for direct consumption.Footnote 63 From the vantage point of their Hong Kong enclave, the British managers of Taikoo viewed the whole development with some scepticism. They did not doubt south China's potential for producing large amounts of industrially manufactured sugar, but, in their own words, ‘turning to actualities, corruption, mismanagement, lack of care and official interference have so far prevented any large-scale production, and with recent successive changes of officials, the industry is very near at a standstill.”Footnote 64
One of the problems that the nascent industrial manufacture of sugar in south China faced in the 1930s—and which concerned the Dutch because it also threatened to impact on the local sales of their sugar—was the extent to which the new tariff regime (amongst other factors) encouraged a surge in the output of ‘traditionally’ manufactured brown sugar among south China's peasantry. Since the end of the nineteenth century, China had been flooded with cheap industrially manufactured sugar, when, in the aftermath of the collapse of world sugar prices in the mid-1880s, imported sugar became cheap enough to compete effectively with local, peasant-produced ‘brown’ sugar on China's markets.Footnote 65 With China's recovery of tariff autonomy c. 1929 onwards, this situation changed. By 1937, there were said to be some 1,789 crude stone and wooden mills for producing this kind of sugar in the Guangdong area alone.Footnote 66 At the beginning of the decade, the NHM's agent in Shanghai reported that far greater quantities of ‘native,’ peasant-made sugar had been offered for sale than had been the case a year earlier. Most of it was from the vicinity of Shantou, the prime area of ‘peasant’ sugar production in southern China. The agent was evidently relieved that the high asking price kept sales low.Footnote 67
This changed, however, with the higher imposts on imports: two years later, in 1932, reports began to come in to Hong Kong of burgeoning peasant cultivation of cane, encouraged by the renewed access to the market for sugar contingent on the increased tariff. Similar reports were still being received later in the decade: in 1937, Dutch sources there reported on it as an altogether more worrisome development than the faltering emergence of industrialized manufacture.Footnote 68 By this date, moreover, peasant preference for brown sugar production was a significant factor in stopping south China's industrial sugar factories from obtaining access to sufficient raw material,Footnote 69 and continued to be so after the Japanese attempted to revive the industry at the close of the decade.Footnote 70
By the middle of the 1930s, however, the biggest problem confronting the Java producers in their bid to retain a hold on the China market was the impact of the large-scale smuggling of sugar which the new tariff perforce encouraged. In Guangdong, the Chen Jitang regime (1929–1936) was itself heavily engaged in the smuggling of sugar, in which activity the general's elder brother was the key figure. Illicit trade in ‘Smokeless Sugar’—sugar that purported to be of local manufacture but which, in reality, had never been anywhere near a Chinese factory (chimney)—was big business. The factories set up by his regime did not live up to expectations and produced (as we have just seen) only modest quantities of sugar. Smuggled sugar made up the deficit—and made a fortune for Chen and his family.Footnote 71 Nonetheless, Chen's operation in Guangdong was unlikely to have impacted adversely Java's sugar trade, because much of Chen's ‘Smokeless Sugar’ came from Hong Kong's Taikoo refinery, which drew most of its supplies from Java, or was raw (brown) sugar—or factory white—from the same source.Footnote 72 The implications of other sugar-smuggling operations were very different, however, and deeply threatening to Java's long term prospects in China.
By 1929, sugar from Japanese factories in Formosa (as described below) was already being smuggled in significant quantities into coastal China on Japanese motor vessels—and far more was to come during the course of the decade, despite attempts by the (British-run) Chinese Customs Service to prevent it.Footnote 73 Following Chen Jitang's fall and subsequent flight to Hong Kong, it was reported that the new Guangdong authorities had been largely successful in suppressing the illicit trade. To the northeast, however, it was a different story, and smuggled sugar continued finding its way into southern China via Xiamen (Amoy) and Shantou (Swatow).Footnote 74 As early as 1933, the NHM's agent in Shanghai referred to the ‘frightful increase' (schrikbarende toeneming) in smuggling there and speculated that around 40% of the sugar coming into China was smuggled.Footnote 75 In north China, in particular, smuggling of sugar (along with that of other goods) paralleled the growing degree of Japanese entrenchment, c. 1930 onward. By 1936, conditions there—described by one singularly well-placed contemporary in terms of ‘an orgy of officially protected smuggling unparalleled even in China’Footnote 76 —had created a situation in which the bona fide sugar trade through Shanghai was reduced to a state of ‘total disorganization.’Footnote 77
One year later, the outbreak of the Sino-Japanese war meant that in the wake of the Japanese advance, Shanghai itself and its Yangzi valley hinterland were flooded with cheap Japanese goods, sugar included.Footnote 78 Reportedly, the Japanese brought sugar into north China disguised as ‘military supplies’ and thereby avoided paying duty.Footnote 79 By 1939, Dutch business sources in Asia reckoned that ‘great quantities' of sugar were coming into China generally without paying the high duties demanded by the Chinese authorities.Footnote 80
Industrialised Sugar Manufacture in Formosa
The massive expansion of smuggling into China during the 1930s, and the pre-eminence of Japanese interests in promoting it, would have mattered less to the Java producers had the situation of a decade earlier still prevailed, when Japanese firms had bought huge quantities of the Dutch colony's output. From the late 1920s onward, however, this ceased to be the case, as Japanese refineries took an ever-increasing portion of their supplies from their own or associated factories on Formosa.
The Formosa sugar industry that the Japanese took over, after gaining control over the island in 1895, was an old one and as antiquated in its methods as that of southern China. Early in the twentieth century, however, Japanese colonialists made short shrift of the kind of ‘peasant’ production of brown sugar that proved one of the obstacles to the development of industrialised sugar manufacture in Guangdong in the 1930s. With strong government backing, Japanese companies began pouring in capital, and importing know-how, to create a network of state-of-the-art sugar factories that emulated those of Java and paralleled those that contemporary American and Filipino interests were building further south in Luzon and Negros. The new Japanese factories on Formosa produced both raw sugar for Japanese refineries and factory white for direct consumption throughout east Asia.Footnote 81
By the late 1920s, there were 48 such factories (eight of which were double installations, located alongside each other), producing some 571,718 tons of sugar from more than 117,000 hectares of cane. During the course of the 1930s—quite exceptionally amongst the world's major sugar industries during the ‘Depression’ decade—output doubled to more than a million tons, so that by 1940, with around the same number of factories in operation, Formosa had become the world's fourth largest producer-exporter of cane sugar, the bulk of which, as was also the case with Java, was factory white.Footnote 82
Initially, the growth of production impacted Java's prospects in Japan's domestic market, where sugar from Formosa benefited from a preferential tariff, but its ramifications quickly spread to China. The burgeoning Formosa industry created an important alternative source of supply for the Japanese refineries and contributed powerfully to undermining Java's hold over the east Asian market—and its position in the Japanese sugar empire. The increase in smuggling that has just been described went hand in hand with a steep decline in the exports of Java sugar to Shanghai and the central China region to which it was the gateway. At the end of the 1920s, these had peaked at over one-quarter of a million tons. In 1939–1940, by way of contrast, they amounted to only 22,500 tons, and although in the following year they appear to have increased substantially to 78, 400 tons, a year later the Java industry was itself engulfed in the World War.Footnote 83
Of at least equal seriousness, however, was the fall in sales to the Japanese refineries occasioned by the rise of Formosa as an alternative source of supply.
In the early years of the twentieth century, Java had been by far the largest supplier of raw sugar to Japan's refineries. At the beginning of the 1920s, it had already been reduced to providing about 50% of their requirements, with most of the balance coming from Formosa. By the end of the decade, the ratio had changed to 75:25 in Formosa's favour. Worse was to come. Indeed, at the very close of the 1930s, imports from Java accounted for a mere 15% or less of Japan's imports, and Formosa sugar dominated the market.
Nonetheless, although the rise of industrial sugar production in Formosa eventually served to marginalise Java in the Japanese sugar empire, at the beginning of the 1930s the demise of the Dutch colonial industry's east Asian markets was far from a foregone conclusion. For all that Formosa took over from Java as the main supplier to Japanese refineries during the course of the 1920s, sources appear to be agreed that the colony was not in a position to totally supplant Java in the Japanese sugar empire. Such calculations as are currently available suggest that although Formosa's output was sufficient to supply Japan's domestic market, its factories could not meet the demands of Japan's expanding sugar empire on the east Asian mainland.Footnote 84 Moreover, there seems to be no doubt that Java's sugar was cheaper to produce than that of its Formosa counterpart and was hence notionally more attractive to Japan's refineries than the output of their own colonial possessions.Footnote 85
Java Sugar and the Trade War between the Netherlands Indies and Japan
Attempts to (re-)integrate Java into the Japanese sugar empire ran up against a number of obstacles. Chief among them were the conflicted commercial relations between the Netherlands Indies and Japan that developed during the course of the 1930s, allied to the high degree of integration that characterized colonial producers and metropolitan refiners within the Japanese sugar empire during the interwar decades. Embedded in this history (as Sugiyama and Grove have noted in a broader context) are themes of collaboration, as well as of rivalry,Footnote 86 that can be no more than touched on here. Nonetheless, it might well appear that Java sugar became caught up in an emergent commercial confrontation between Japan and the Western powers in southeast Asia that was not of its making—and in which sugar was an issue of an order different than that posed by other commodities, notably textiles.Footnote 87 What is notable, in short, is that this expansion of sugar production in Formosa (as described above) did not take place in a vacuum, independent of other factors. Rather, it was the fallout from unresolved trade wars between Japan and Asia's Western colonial powers, in which the Netherlands Indies was well to the fore. To an extent, that is to say, it was rivalry on other fronts that doomed collaboration to failure and resulted in the marginalisation of Java sugar in Japan's sugar empire.
Within this context, confrontation centred on the contested penetration by Japanese manufactures of the Asian colonies of the Netherlands, Britain, France and the United States. Java's relations with the Japanese sugar ‘empire,’ on the other hand, hinged on the access of a (semi-)manufactured product of the Netherlands Indies to the Japanese market and—perhaps critically—to the markets of those parts of China that Japan came to dominate, politically and militarily, c. 1930 onwards.
Amongst the factors at work here was the relative strength of the Netherlands Indies currency. The Indies remained the gold standard until 1936, as did Holland itself. The consequent strong depreciation of the yen against the Netherlands Indies guilder drastically reduced the cost of Japanese imports but correspondingly increased the cost of Java sugar for the Japanese refineries. Nonetheless, this was hardly critical, since the weakened buying power of the yen could be set against a steep fall in the selling price of Java sugar. Indirectly, however, the currency question had an enormous impact on the fortunes of the Java sugar producers, because the flood of cheap Japanese imports into the Indies consequent on the devalued yen precipitated a trade war in which they were the ultimate losers.
One dimension of the ‘war’ was that the Dutch metropolitan textile interests, hurt by Japanese competition, pressed for quotas on Japanese cotton goods. Simultaneously, for senior Dutch officials in the Indies, ‘economic protection formed part of a much broader issue: that of colonial defence and safeguards.’Footnote 88 Moreover, as Anne Booth has argued, the Indies government embarked on what was, in effect, a degree of ‘import–substitution–industrialisation’ (ISI) with regard to textiles in particular—but by no means confined to that commodity—that was predicated on protection from cheap Japanese imports.Footnote 89 The upshot was to stymie any arrangement that would have enabled Java sugar to be (re-)incorporated in the Japanese sugar empire, since incorporation could only have taken place on terms that involved a trade-off for Japanese textiles. Metropolitan sugar refiners, intimately linked as they were to Formosa producers, were equally opposed to such a trade-off. Any such arrangement defied the logic of the tight vertical integration of producers and refiners that characterised the Japanese sugar empire. It appears, for example, that in mid-1934, inter-governmental discussions between Batavia and Tokyo presaged an arrangement whereby Japan would take Java sugar in return for textiles, but that the deal was strongly opposed by Japan-Formosa sugar interests.Footnote 90 As these interests included both the Mitsui and Mitsubishi zaibatsu, the chance for any arrangement might appear to have been bleak.Footnote 91
Nonetheless, the outcome was not totally unpromising for Java sugar. The inter-governmental negotiations just alluded to, whose object (inter alia) was to pressure Japan into buying large quantities of Java's massive sugar stockpile in return for concessions relating to the import into the Netherlands, extended over several months in the second half of 1934. On the Japanese side, there was initially preparedness to meet at least some of the Netherlands Indies’ demands, and there was talk of setting up a fund, to be financed (in part) by cotton interests, to indemnify the Japanese (and Japanese colonial) sugar producers for whatever losses they suffered from the deal. However, the Netherlands Indies’ demands—for an annual purchase of half a million tons of Java sugar (subsequently scaled back to 300,000 tons), for a reduction of Japanese output from Formosa and for tight limits to be imposed on Japan's export of sugar to China, proved a major obstacle.Footnote 92
When a separate sugar agreement was finally reached between Netherlands Indies and Japanese sugar interests, at the end of 1936, it contained provisions for minimizing competition in the China market, in return for which the Japanese refineries undertook to increase, as far as possible, their imports of raw Java sugar into Japan.Footnote 93 It appears, however, to have left the Japanese sugar refiners free to develop their interests in sugar production in Formosa, which increased by almost 100% during the course of the 1930s (a development entirely without parallel in the contemporary international sugar economy). In these circumstances, a great deal hinged on the potential for expansion in the China market, beset from 1937 onwards by the outbreak of full-scale war between the Nationalist government and Japanese invaders. The upshot was perhaps predictable. Though in 1936–1937 Japanese imports of raw Java sugar amounted to over 250,000 tons, a figure not reached since 1930–1931, by the end of the decade Java's sales to Japan had dwindled to a tickle—a mere 15,000 tons in 1939.Footnote 94
The Best of British: Java and Taikoo
These several developments left the Java industry to make the best it could of its long-standing connections with the British refineries in Hong Kong. The industry's relations with Hong Kong had begun in the 1880s, when the steep fall in the price of Java sugar made the output of the island's colonial factories more than competitive with the raw sugar produced by pre-industrial means in China itself. Initially, Java supplied not only Butterfield and Swire's massive Taikoo refinery, the largest such operation in Asia, but also the China Sugar Refinery owned by Jardine Matherson, the ubiquity of whose presence on the ‘China Coast’ rivaled that of Butterfield and Swire for the better part of a century prior to Second World War.Footnote 95 At the end of the 1920s, however, the China Sugar Refinery closed down and left the field to Taikoo, which remained (as we shall see) an artery for Java's sugar trade down to the outbreak of the Second World War—though no longer the major one that it had been in earlier decades.
In reviewing Java sugar's access to east Asia, there were some potential alternatives. Foremost among them were the extensive commercial networks of the Netherlands Indies’ ‘own’ Kian Gwan. Evidence is, however, that the big Dutch sugar companies, and their allies among the colony's old-established European sugar traders, were anxious to keep the remaining great Indonesian-Chinese combine (since KHT had slowly expired c. 1930–1935) at arm's length.Footnote 96
Hence Kian Gwan, despite having purportedly very good contacts in China, was refused entry into the inner councils of NIVAS,Footnote 97 while Java's East Asia sugar trade came to be dominated by ‘the combine’ (as it was known), comprised of Erdman & Sielcken, Wallenstein Krause and – above all– the London-based Maclaine Sugar Company and their close Java associates, Maclaine Watson, MacNeil & Co and Fraser Eaton.Footnote 98 Since these companies, the latter in particular, had long been closely associated with the Hong Kong refineries, the implication was that if the Java producers were to find salvation in the East, it was to be through the agency of Taikoo.Footnote 99
Yet, by the 1930s, the great Hong Kong refinery was itself in difficulties. In the middle of the previous decade, the sugar business in Hong Kong had been badly hit by boycotts, disturbed conditions in its Chinese hinterland and Japanese competition.Footnote 100 Taikoo survived, but had to suspend operations for a couple of years (1927–29), while Jardine Matheson's China Sugar Refinery closed its doors for good in 1928, and left the field to its erstwhile competitor.Footnote 101
In part, the key to Taikoo's survival was to be found in reforms to its up-country sales organization,Footnote 102 but a fundamental problem remained: “the Japanese have a home market for sugars not immediately required in China, and can adjust their sales and deliveries accordingly – we [Taikoo] have not”.Footnote 103 Hence, the refining business in Hong Kong was extremely speculative, dependent for its success on buying raw sugar wherever and whenever it was cheapest. Loyalty to suppliers was hardly at a premium. Indeed, it was fundamental to the refinery's success that it could buy raw sugar when and wherever it was cheapest.Footnote 104 In consequence, Taikoo's relations with the Java sugar producers was an ambivalent one: it fell far short of the kind of vertical integration that linked, for example, the big New York refineries to the Cuba industry and to other sectors of the American sugar empire,Footnote 105 and likewise (as we have seen) tied the Formosa industry to Japan. Unsurprisingly in these circumstances, the relations between Taikoo and NIVAS (Nederlandsch-Indisch Vereniging for Afzet van Suiker or Netherlands-Indies Association for the Sale of Sugar), from 1932 onwards the Java sugar industry's single seller organisation, were somewhat strained.Footnote 106
The underlying problem, however, was that without some agreement with the Japanese, Taikoo's own prospects in east Asia did not look good. Japanese competition was one of the factors that had caused the (temporary) closedown of the refinery in the late 1920s, and though it had reopened by the end of the decade, it did so with a significantly reduced output. What had once been the largest such operation in the whole of Asia was now a shadow of its former self. Indeed, by 1937, the refinery was being forced to operate at only 50% of its economically optimal capacity,Footnote 107 and the outbreak in the same year of the Sino-Japanese War reportedly threatened to totally disrupt Taikoo's business in China.Footnote 108 More than ever, Taikoo had to look to sales outside its Chinese hinterland.Footnote 109 Some months earlier, attempts had indeed been made to reach an accommodation with the Japanese, and negotiations had been opened with Mitsui about a sales agreement covering the China market,Footnote 110 a strategy which, though it ran the risk of ‘Chinese agitation being deflected onto [Taikoo],' was nonetheless considered worth taking ‘because the advantages of an agreement with [the Japanese were] . . . so great.’Footnote 111 Moreover, through Taikoo and Swire's long association with Maclaine Watson (in Java) and the Maclaine Sugar Company (in London), the agreement might also have involved the Java industry.Footnote 112 Any such prospect appears to have been sabotaged in advance, however, by inspired leaks to the Chinese press in Shanghai to the effect that Taikoo and the Japanese refineries were ‘conspiring to strangle China as far as sugar supplies . . . [were] concerned'—leaks that pointed to the factional nature of Japanese sugar interests and hence the profound unlikelihood of any agreement being possible.Footnote 113
The upshot was to leave the Java producers in a position where there seemed little likelihood of a substantial recovery of their east Asian markets. To be sure, on the eve of the outbreak of war in the Pacific (1940–1941) around one-quarter of Java's exports (244,703 tons) went to the China market, a very substantial increase from the previous year and largely attributable to the increased sales of Taikoo.Footnote 114 Nor was it a situation in which the Java factories adopted a totally passive stance. One ploy was to supply sectors of the China market with a product better than the all-purpose factory white—without recourse to the Hong Kong or Japan refineries. Hence at the very height of the Depression, in 1933–1934, one large East Java producer built a small refinery adjacent to their factory, with a view to supplying China direct with a grade of refined white sugar that was said to be fully the equal of the best overseas imports.Footnote 115 The first refinery to be built in Java, it began to make a modest profit well before the end of the decade. It was significant as an indication of the way in which, in sugar as in other industries, the Depression encouraged autonomous economic development in the Indies and might have proved the precursor of a large-scale shift to refining self-sufficiency. There was indeed speculation that other factories would follow suit,Footnote 116 but in the wake of the outbreak of the Sino-Japanese War and its subsequent escalation into Second World War, this small refinery appears to have found no imitators, and the large-scale refining of sugar in Java (by that date exclusively for the domestic market) did not begin until the 1970s.
In the meantime, towards the close of the 1930s, the general run of Java producers had to contend with steadily declining sales in what had once been their prime market. The complete domination of the sugar trade of occupied China by four big Japanese firms—Mitsui, Mitsubishi, Masuko and Fukawa—did not bode well for Java.Footnote 117 It was calculated in 1936, for example, that Java supplied only a little over a third of China's total sugar imports, the bulk of which were supplied by Japan. Unsurprisingly, the decline in sales in Shanghai was particularly pronounced. At the beginning of the 1930s, these had stood at well over one-quarter of a million tons, whereas by the end of the decade they amounted (at 22,600 tons) to less than one-tenth of that quantity.Footnote 118
Conclusion: The Depression and the Collapse of Java's East Asian Markets
The Depression's impact on Java sugar production needs to be located within a much broader framework of developments that began around 1920 and only concluded with the outbreak of war in the Pacific more than two decades later. The endogenous nature of Java's sugar industry, bereft of the (relatively) secure ‘home’ markets that characterized virtually all of its counterparts in the international sugar economy of the late colonial era, had always had the potential to spell trouble. The situation in which the industry found itself—one in which sugar was as ‘global’ a commodity as oil is today—was accentuated in the Depression of the 1930s. ‘This sending back and forth of huge quantities of sugar,' lamented NIVAS in 1934, ‘is indicative of the chaos in which the world finds itself.’Footnote 119
Yet, in east Asia during the interwar decades, the Java industry was caught up in a more historically specific situation than that implied by the palpably global character of the international sugar economy and its ostensibly paradoxical tendency towards autarchy. The critical development, played out over the better part of 20 years, was Java's relation to a Japanese ‘sugar empire’ whose origins dated back to the very end of the nineteenth century. In the Western Hemisphere, Cuba—Java's occidental counterpart and the world's largest exporter of cane sugar during the period concerned—remained (however uneasily) within the orbit of an American ‘sugar empire’ that embraced both the old Spanish Caribbean, Hawaii, the Philippines and the United States’ own domestic producers. In ‘the East’ Java clearly had the potential to be similarly located within the parallel, virtually contemporaneous, though smaller, Japanese imperium, whose production zones extended southwards from Korea by way of Formosa into the islands of the South Pacific.
This did not happen for a number of reasons. The resistance of the Netherlands Indies State to the forces drawing it into the Japanese orbit, combined with the crisis-ridden nature of the ‘empire’ itself (the collapse of one of its biggest enterprises in 1927 and a subsequent decade of conflicted sales in its main market on the Chinese mainland) to marginalise the Java producers and promote the expansion of their competitors in Formosa which, unlike Java, was quite unambiguously within the Japanese sphere. Although the British-owned Taikoo refinery in Hong Kong maintained its long-standing ties with the Java industry more or less throughout the 1930s, its own reduced markets in China (consequent in part at least of the expansion of Japanese power and influence) meant that it could not provide Java's salvation.