INTRODUCTION
This paper proposes a sunspot- and habits-based mechanism that quantitatively accounts for monetary facts. A cash-in-advance model (CIA) with habit persistence and local durability in consumption is considered. In this economy, the equilibrium is indeterminate provided habit formation is large enough. We then study the empirical relevance of the real indeterminacy phenomenon and investigate the quantitative performance of the model in reproducing monetary facts.
The empirical literature that has studied the short-run effects of a monetary shock (in particular the structural vector autoregressions (SVAR) literature) reports the following monetary facts. After an expansionary monetary policy, (i) there is a persistent and hump-shaped increase in real GDP, (ii) prices decrease in the very short run but then persistently increase, and (iii) the nominal interest rate declines in the short run. Points (i) and (iii) together define the liquidity effect. The short-run response of inflation is described as the Nprice puzzle in the literature. Indeed, when prices are almost nonresponsive in the very short run, points (i) and (ii) together define the monetary transmission mechanism, whereas the price puzzle is defined as a decrease of the price level after an expansionary monetary policy shock. These results seem to be robust against different identification schemes [see, e.g., Sims (1992), Leeper et al. (1996), and Christiano et al. (1999, 2005)]. Consequently, any structural model that could plausibly be used for monetary policy analysis should be able to account for these facts.
A large strand of the literature has developed dynamic stochastic general equilibrium (DSGE) models to account for these facts [see Rotemberg and Woodford (1997), Ireland (2001), Smets and Wouters (2003), Christiano et al. (2005), and Boivin and Giannoni (2006)]. These models include real frictions (habit formation, adjustments costs, etc.) as well as nominal rigidities (price stickiness, wages stickiness, price indexation, etc.). Due to their empirical success, these models are gaining credibility in policy-making institutions. However, it is worth noting that to empirically perform well, these large-scale models have to pay a high price in terms of sophistication and lose a lot in terms of understanding the economic mechanism. It is well known that the intertemporal elasticity of substitution needs to be weakened to match the result of theoretical models with data. For this reason, large-scale models consider habit persistence as a key ingredient in intertemporal complementarities in consumption decisions. Thus, it seems natural to investigate the role of this mechanism more deeply.
We assume that intertemporal substitution motives are weakened by including habit formation over preferences. We also depart from the monetary literature [see Rotemberg and Woodford (1997), Christiano et al. (2005), and Boivin and Giannoni (2006)] and stick to the financial one in assuming the existence of a local durability effect [see Heaton (1995), Hindy et al. (1997), and Giannikos and Shi (2004)]. Durability captures the notion that consumption is substitutable over time, whereas habit persistence implies intertemporal complementarities in consumption decisions. We consider a specification of the utility function that implies both long-run habit persistence and short-run durability effect.
The paper provides conditions on the elasticity of intertemporal substitution in consumption decisions for real indeterminacy to occur when the central bank follows an exogenous money growth rule. Real indeterminacy results from the interplay of habit formation and the cash-in-advance constraint when the parameter indexing habit persistence exceeds a particular threshold. When the equilibrium is indeterminate, we take into account sunspots. We investigate types of sunspots that are consistent with monetary facts. We follow a large part of the literature on real indeterminacy, which introduces a correlation structure between sunspots and fundamentals shocks to replicate observed business cycle facts.1
For example, Benhabib and Farmer (1996), Perli (1998), and Schmitt-Grohe (2000) calibrate the correlation between the sunspots and the technology shock to reproduce the co-movements of aggregate US data. See Farmer and Guo (1995) for an applied econometric study.
When the equilibrium is indeterminate and sunspots display a positive correlation structure with money injections, the model accounts for the hump-shaped response of output, the price puzzle and to a lesser extent the liquidity effect. The ability to match these facts is not a trivial consequence of the degrees of freedom that are provided by the property of real indeterminacy and the form of the sunspots function. First, the sunspots function is consistent with the rational expectations equilibrium. Second, we restrict attention to a time-invariant linear sunspot function. By assuming that the martingale difference sequence on aggregate variables is a linear and stable function of the money injection, the approach is kept parsimonious.
We quantitatively evaluate and test the ability of our model to match the data. The habit formation and monetary sunspot parameters are estimated using the empirical strategy proposed by Rotemberg and Woodford (1997), Boivin and Giannoni (2006), and Christiano et al. (2005). This approach consists in minimizing the distance between the impulse response functions generated by a SVAR model (i.e, “the monetary facts”) and the ones computed from our monetary model. It is worth noting that the number of moments to be matched greatly exceeds the number of estimated parameters. Consequently, the monetary model under indeterminacy can be tested on the basis of overidentifying restrictions.
We show that our model matches well the persistent and hump-shaped response of output; it is able to reproduce the puzzling behavior of prices as well as the monetary transmission mechanism. In our model, only three parameters matter to do the job: the habit persistence parameter must be large enough, a local durability effect must be significant, and the monetary sunspot must be positively correlated with money injections.2
Notice that with only three key parameters, the dynamics of the economy is rich enough for the model to be considered quantitatively relevant.
The paper is organized as follows. Section 2 presents the monetary facts. Section 3 presents the model and characterizes its local dynamic properties. More precisely, this section gives conditions for real indeterminacy and discusses the role of sunspots in generating the monetary facts. Section 4 presents a quantitative evaluation of our economy. A last section concludes.
MONETARY FACTS
This section presents the strategy used to identify the monetary policy shock in a SVAR model, the data, and the monetary facts.
The Monetary SVAR
We start our analysis by characterizing the actual economy's response to a monetary policy shock. As is now standard, this is done by estimating a monetary SVAR in line with Christiano et al. (1996, 1999) to identify monetary policy shocks.3
See also Christiano et al. (1997, 2005), and Rotemberg and Woodford (1997, 1999) for other examples of this identifying strategy.
(here the Federal Funds rate), according to the policy rule

where Ωt is the information set available at the time monetary authorities take their decisions, σi is a positive scalar, and εt is a white noise monetary shock orthogonal to the elements generating Ωt. Formally, let Zt denote the data vector of dimension m

The vector Z1,t is an n1 × 1 vector composed of variables whose current and past realizations are included in Ωt and that are assumed to be predetermined with respect to εt. Z2,t is an n2 × 1 vector containing variables that are allowed to respond contemporaneously to εt but whose value is unknown to monetary policy authorities at t. Thus only lagged values of Z2,t appear in Ωt. Accordingly, m=n1+n2+1.
In order to implement this identification strategy, we first estimate an unconstrained vector autoregression (VAR) of the form

where [ell ] is the maximal lag, which we determine by minimizing the Hannan–Quinn information criterion. In our empirical analysis, we found that [ell ]=4. Then, to recover the structural shock to monetary policy εt, we assume that the canonical innovations ut are linear combinations of the structural shocks ηt; that is,

for some nonsingular matrix S. As usual, we impose an orthogonality assumption on the structural shocks, which combined with a scale normalization implies
, where Im is the identity matrix and m is the number of variables in Zt.
With the above recursiveness assumptions, a monetary policy shock can be recovered as follows. Let S be the Cholesky factor of Σ, so that SS′=Σ. Then σi is the (n1+1, n1+1) element of S, and εt is the shock appearing in the (n1+1) equation of the system

where A0=S−1 and Ai=S−1Bi, i=1, …, [ell ].
Data and Findings
We apply the SVAR methodology to U.S. quarterly data4
The data are extracted from the Bureau of Labor Statistics Web site, except for the Fed Funds rate and M1, which are obtained from the FREDII database.
We also experimented with quadratically detrended or first-differenced output, without quantitatively altering our findings.
As in Christiano et al. (1999), the federal funds rate is taken to be the main instrument of monetary policy. We refer to a monetary shock as a shock on the nominal interest rate. Recursiveness assumes, among other things, that although the policymaker observes current production and prices when he sets the federal funds rate, private agents do not observe the current monetary shock. Another implication is that GDP and prices do not react to a monetary policy shock on impact.
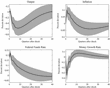
Figure 1 reports the estimated IRF for all the variables in the SVAR model after a contractionary shock to monetary policy—that is, a positive shock to the federal fund rate. The solid line reports the point estimates of the various dynamic response functions. The dashed lines correspond to the 95% confidence interval obtained through Monte Carlo simulations. The main consequences of a contractionary monetary policy shock are similar to those obtained by previous studies. Following a contractionary shock to monetary policy, Figure 1 indicates (i) a persistent decline in real GDP. Moreover, outputs exhibits a hump-shaped response with a trough effect after about 2.5 years. Furthermore, (ii) the aggregate price level exhibits a positive response in the very short run but then persistently increases. Finally, (iii) the federal fund rate rises and the money growth rate decreases. Points (i) and (iii) together define the so-called liquidity effect. The response of inflation is described as the price puzzle in the literature [see Sims (1992)]. Indeed, when prices are almost nonresponsive in the very short run but decrease, the points (i) and (ii) together define the monetary transmission mechanism, whereas the price puzzle is defined as an increase of the price level after a contractionary monetary policy shock. This is explained by bad times that bring a high price level as money demand falls. In this paper, we focus on the hump-shaped response of output, the prize puzzle, and the liquidity effect. Our SVAR results confirm a host of previous studies and show that the hump and persistent responses of output, the nominal interest rate, and the delayed and persistent response of inflation are key stylized monetary facts that any monetary DSGE model should be able to reproduce.

Impulse response functions from the monetary SVAR.
We compute the variance decomposition in order to briefly document the contribution of monetary policy shocks to the variability of the different economic aggregates under consideration. Table 1 shows that monetary policy shocks account for a small portion of the variance of output and inflation when the forecast horizons are short, and a substantially bigger portion at longer horizons, comprised between 13% and 41%. However, what turns out to be important when focusing on monetary effects is to obtain precisely estimated responses of aggregate variables, this is the case especially when it comes to the typical hump shape and persistent patterns previously emphasized.

THE MONETARY MODEL
In this section, we present a flexible price model with a cash-in-advance constraint and habit formation. We also describe the dynamic properties of the economy and discuss its qualitative implications.
The Economy
This section describes a cash-in-advance model with habit persistence and local substitution in consumption. Some assumptions on the functional forms of preferences and technology make it possible to determine analytically the approximate solution of the model.
Households
The setup is standard. The economy is composed of a unit mass continuum of identical infinitely lived agents. A representative household enters period t with nominal balances Mt brought from the previous period and nominal bonds Bt. The household supplies labor at the real wage Wt/Pt. During the period, the household also receives a lump-sum transfer from the monetary authorities in the form of cash equal to Nt, profit from the firm Πt, and real interest rate payments from bond holdings ((Rt−1−1)Bt/Pt). These revenues are used to buy a consumption good (Ct), money balances (Mt+1), and nominal bonds (Bt+1) for the next period. Therefore, the budget constraint takes the form

Money is held for transaction motives. The household must carry cash to purchase goods and faces the following cash-in-advance constraint:

We restrict our attention to equilibria with a strictly positive nominal interest rate, so that the cash constraint is binding. Following Abel (1990), Carroll et al. (2000), and Fuhrer (2000), consumers' utility at time t is affected by habits expressed as a ratio. Each household has preferences over consumption and leisure represented by the intertemporal utility function

where β ∈(0, 1) is the discount factor and ht denotes the number of hours supplied by the household. Following Hansen (1985) and Rogerson (1988), we assume that utility is linear in leisure.
denotes the expectation operator conditional on the information set Φt available in period t. Because, later on, we will seek to compare the model with the monetary SVAR model of Section 2.1, it is important to make sure that both models embed the same timing restrictions. To achieve this, we make assumptions about the timing of various decision variables. For instance, consumption is decided prior to observing the monetary shock, whereas bond holdings are decided after observing this shock. Zτ refers to the level of habit and the parameter φ rules the sensitivity of individual consumption to this level of habit. Notice that when φ=0, we retrieve the standard model. The stock of habits in the utility function is defined as

where
is aggregate consumption in period τ. The second parameter ς represents the potential existence of durability in consumption behavior. Our modeling choice allows us to represent different consumption behaviors in a parsimonious way. Indeed, depending on the values of φ and ς, the model may generate pure habit (φ > 0 and ς ≥ 0) or habit persistence with local durability (φ > 0 and ς < 0). As emphasized by Heaton (1993), one problem with the habit persistence specification [as in Constantinides (1990)] is that it ignores a local substitution effect in consumption decisions [see also Hindy and Huang (1992) and Hindy et al. (1993)]. Our modeling choice is simpler than the one used by these authors. However, it allows us to account for both the long-run persistence of consumption and for the durability effect in the short run.
We consider external habit specified in ratio form. Aggregate consumption
is unaffected by any one agent's decision, exhibiting the “catching up with the Joneses” form of habit formation [see Abel (1990)].6
External habit has been preferred to internal habit only for tractability purposes. However, the mechanism at work plays in the same direction for these two specifications of habit. Indeed, whatever the form of habit is, the model generates real indeterminacy because of the interplay between the CIA constraint and the habit formation assumption. In addition, the dynamic properties of the model are very similar.
The household determines its optimal consumption/saving choice, labor supply, and money and bond holdings plans by maximizing utility (3) subject to the budget (1) and cash-in-advance (2) constraints. The timing is of importance in this framework. Households decide on consumption and money holdings before observing the shock, whereas bonds holdings are decided afterward. Therefore, consumption behavior together with labor supply yields

whereas nominal return of bond holdings is given by

Equations (2) and (6) determine money demand, where the real balances are a decreasing function of the nominal interest rate for a given real wage.
Firms
The representative firm produces the homogenous consumption good by means of labor according to the constant-returns-to-scale technology

Profit maximization implies that, in equilibrium, the real wage will be constant and equal to 1.
The government budget constraint and the monetary policy
The government issues nominal bonds Bt to finance open market operations.7
These nominal bonds could be used to finance government consumption. Nevertheless, this issue is beyond the scope of the paper.

with M0 and B0 given. As in Christiano et al. (2005), money is exogenously supplied according to the money growth rule

where the gross rate of money growth γt follows a stationary stochastic process,

where εt is a white noise with variance σ2 and |ρ|<1.
Equilibrium conditions
An equilibrium is a sequence of prices and allocations, such that, given prices, allocations maximize profits (taking technology into account) and utility (subject to the budget constraint), and all markets clear. In a symmetric equilibrium, all households have the same consumption and
every period. Goods-market-clearing conditions require Ct=Yt for all t. The equilibrium conditions are approximated by log-linearization about the deterministic steady state,


where
,
,
, and
correspond to the percentage deviation from steady state of output, the inflation rate the gross nominal interest rate, and the money growth rate. Equations (7)–(10) describe the equilibrium conditions of the monetary model with a CIA constraint and habit formation. Note that the dynamics of output is only affected by the exogenous money supply. It can thus be solved independently from inflation and the nominal interest rate. At the same time, the dynamics of inflation and the interest rate depend on those of output.
Dynamic Properties
This section establishes the dynamic properties of our model economy. We characterize conditions on the level of habits and discuss the economic mechanisms that yield real indeterminacy.
Real indeterminacy
The local dynamic properties of output are strongly related to the perfect foresight version of the model. Importantly, the dynamic properties of the monetary model can be summarized by the behavior of output. Holding the rate of growth of the money supply constant, equation (7) reduces to the following linear second-order finite difference equation:

The model satisfies a saddle path property if and only if one root of the characteristic equation

has modulus greater than one; that is, the number of eigenvalues whose modulus exceeds one must be equal to the number of nonpredetermined variables. In the model, the next period consumption levels are free. Conversely, if the modulus of the eigenvalue is less than one, the equilibrium is locally indeterminate; that is, there exists a continuum of equilibrium paths that converge to the steady state. The following proposition establishes conditions for the existence of real indeterminacy.
PROPOSITION 1. If φ, ς, and η satisfy

then the equilibrium is locally indeterminate.
Proof 1. The roots of the characteristic polynomial have modulus lower than 1 when P(λ) satisfies P(1) > 0, P(−1) > 0, and |P(0)| < 1. The result follows immediately.
Proposition 1 shows that there exist values of the habit formation parameters (φ, ς) and η that yield real indeterminacy. Notice that the model can exhibit negative or positive real roots as well as complex roots. These conditions show that habit persistence must be strong enough to generate real indeterminacy. They also state that, to guarantee the stationarity of the solution, the habit effect cannot be too high. Further, one may notice that Proposition 1 nests previous conditions for real indeterminacy in CIA economies. For instance, when φ and ς are equal to 0, then η > 2 yields indeterminacy [see, e.g, Woodford (1994), Farmer (1999), or Carlstrom and Fuerst (2003)]. In addition, when η=2 and ς=0, the conditions can be rewritten as φ∈(0, 2) which is very similar to the results of Auray et al. (2005).
Discussion and robustness
This section attempts to shed light on the underlying forces that are at work in generating indeterminacy. Further, it proposes some extensions of the model to show that the indeterminacy results are robust.
First note that whatever happens in this economy, labor demand takes the simple form Wt/Pt=1. Therefore, the only way for an individual to increase his or her income is to supply more labor. The intuition for real indeterminacy is the following.8
The mechanisms at the core of the indeterminacy phenomenon are similar to those presented in Auray et al. (2005) in a cash-in-advance economy with pure internal habit persistence.
Let us now consider the case where intertemporal substitution is low (η>1 and φ[Gt ]0, for example) and all individuals again have the same expectations of future inflation. As in the previous case, individuals consume more today. But, contrary to the preceding case, the irreversibility in consumption decisions associated with habit persistence leads the agents to increase their future individual consumption too. Because they are all identical and have the same expectations, aggregate future consumption eventually increases. It follows that the aggregate inflation tax increases, therefore supporting the initial individual expectations. These expectations can now depart from fundamentals—even though they may be arbitrarily correlated with fundamentals.
The above discussion shows how the interplay between habit persistence and cash in advance, given a specific environment in the labor and asset markets, can give rise to real indeterminacy and persistence. One may then question the robustness of our results to modifications in the labor and asset markets arrangements.
First, rather than using linear utility in leisure, we assume that preferences are represented by the following expression:

With this specification of the utility function, the conditions of Proposition 1 can be rewritten as

These conditions show that the results on real indeterminacy are maintained when the elasticity of labor supply is finite. The main difference is that the conditions on the parameters φ and ς are more stringent. To see this, consider the case where ς=0 and η=2. The condition for indeterminacy reduces to χ<φ<2+χ. When the elasticity of labor supply decreases—that is, χ increases—the threshold value for φ that yields indeterminacy increases. In other words, the intertemporal complementarities in consumption decisions must be higher in order to obtain indeterminacy, since labor supply is less responsive. Indeed, if the labor supply does not respond sufficiently, the expectations-based willingness to consume more cannot be supported, and this may weaken the mechanism that creates indeterminacy.
We next consider a second departure from the original model, for which the production function displays decreasing returns to scale to labor. As aforementioned, the response of labor income is crucial in generating real indeterminacy. One of the implications of our previous technology is that the real wage is constant in equilibrium. Therefore, labor income can increase following an increase in the labor supply. One may question the robustness of our previous results to a nonconstant endogenous real wage. To address this issue, we investigate the case of a more general production function given by

where α∈(0, 1]. The conditions for indeterminacy become

Results on real indeterminacy are left qualitatively unaffected by the nonconstancy of the endogenous real wage, unless α is equal to zero. When α is close to 1, the real wage is not very responsive to increases in hours worked, and we retrieve the results of Proposition 1. Consider now a rather extreme experiment, where α is set close to 0. In this case, the real wage drops by a huge amount after an increase in hours worked, such that the labor income does not respond. This implies that φ has to be large to support inflation expectations. But real indeterminacy continues to occur.
This discussion illustrates the robustness of our results to relaxing the assumption of a constant real wage. We next check the robustness of our results to the introduction of a new good (an asset) as a mean to escape the inflation tax. In our simple framework, the household can only use leisure to avoid paying the tax. We consider, instead, an economy where the household can use physical capital to avoid it. We use a monetary optimal growth model à la Cooley and Hansen (1989) augmented with habit formation. Each household has preferences over consumption and leisure represented by the intertemporal utility function (3). We allow for capital accumulation and assume a constant depreciation rate [δ∈(0, 1)], so that the intertemporal budget constraint of the household can be rewritten as

where Qt is the real rental rate of capital. As in the previous model, money is held because the household faces a cash-in-advance constraint (2). The problem of the representative household is to choose its consumption–savings, labor, and real balances plans to maximize (3) subject to (2) and (11). Monetary arrangements are assumed to be the same as in our benchmark framework. The representative firm produces a homogeneous good that can be either invested or consumed using the constant-returns-to-scale technology, represented by the Cobb–Douglas production function

where A>0 is a scale parameter. The firm determines its production plans to maximize its profit. We keep the preceding assumption concerning the determination of the labor demand, implying that the real wage does not remain constant when hours vary. Finally, market clearing imposes yt=ct+it. The labor supply takes the form

where λt is the Lagrange multiplier associated with the budget constraint (11). Together with the production function, this implies that the output/capital ratio is a function of λt only:

The Euler equation associated with capital decisions [Qt=(1−α)yt/kt] can be written as

Plugging the labor market clearing condition into the Euler equation, we obtain

which can be solved for λt independent of the rest of the dynamic system. It follows that the model with capital accumulation generates the same conditions for real indeterminacy as the simple model. Hence all our previous results still apply. In other words, letting the agent escape the inflation tax using another asset does not eliminate the possibility of real indeterminacy of the equilibrium.
Qualitative results
When the equilibrium is indeterminate, the dynamics of the economy is described by the set of equations

where
is a martingale difference sequence that satisfies
. Let us consider the following sunspot function:

This linear time-invariant function is consistent with rational expectations equilibrium, because Et−2(b1εt+b2εt−1)=0.9
This function may introduce an additional variable (consistent with rational expectations equilibrium) that accounts for pure extrinsic sunspots that are unrelated to fundamentals, but this variable is meaningless in our quantitative analysis.
Due to our timing restrictions (i.e., consumption must be decided before the observation of the money shock), the output equation displays two types of sunspots (b1εt and b2εt−1). For compatibility with the timing of the SVAR model, we set b1=0. In this case, output is allowed to react to the monetary shock only one period later. In addition, the interplay of this timing restriction with the CIA constraint (2) leads inflation to respond with one lag. Conversely, the nominal interest rate (bond holdings are decided after observing the shock) and the money growth are free to react instantaneously to the shock.
We now investigate the ability of this model to match the stylized facts that emerged from the SVAR. For simplicity of exposition, we consider an i.i.d. process for the money growth rate. This leads to the following proposition:
PROPOSITION 2. When money growth is i.i.d., the model matches monetary facts through sunspots if
- (i) φ, ς and η satisfy Proposition 1,
- (ii) ,
- (iii) b2>1,
- (iv) .
The proof is straightforward and is implicitly given in the following discussion. The first condition (i) is related to real indeterminacy. In this case, the model may generate some persistence adjustment paths for output. We retrieve these persistent effects in the dynamics of inflation and the nominal interest rate given the assumption of the CIA constraint. The second requirement (ii) implies that the habit persistence parameter must be large enough to generate a hump pattern in output. It is important to notice that condition (ii) is consistent with Proposition 1. Consequently, getting persistent and hump-shaped responses is more than empirically plausible in our indeterminate economy. Condition (iii) is necessary to get the monetary transmission mechanism and the price puzzle. These three conditions highlight that this model is able to reproduce the persistent and hump-shaped responses of the variables that characterized the monetary SVAR.10
One may remark that money is neutral when b2=0.
Propositions 1 and 2 show that a high value for the habit persistence parameter φ is needed to match the monetary facts. Consequently, the marginal utility of consumption is very responsive to an unexpected shock, leading to a too high reactivity of the nominal interest rate. We end this section by arguing again that these results are not trivial. As previously explained, the sunspots function is fully consistent with the rational expectations equilibrium. Furthermore, we restrict attention to a time-invariant linear sunspot function. Therefore, our approach is kept parsimonious. More importantly, the model is formally taken to the data. Notice that, at this stage, there is no guarantee that our economy performs well quantitatively. This point is examined in the next section.
QUANTITATIVE ANALYSIS
In this section, we present our empirical strategy and the estimation results and then discuss the empirical performance of the model.
Econometric Methodology
As in most of the literature that follows the original work by Rotemberg and Woodford (1997), we estimate the model parameters ψ by minimizing a measure of the distance between the empirical responses of key aggregate variables obtained from the monetary SVAR (see Section 2) and their model counterparts.11
See also Giannoni and Woodford (2004), Altig et al. (2005), Christiano et al. (2005), and Boivin and Giannoni (2006).
More precisely, we focus our attention on the responses of the vector of actual variables Zt. We let θk be the vector of responses to a monetary shock at horizon k≥0, as implied by the above SVAR estimated on actual data; that is,

where εt is the monetary policy shock previously identified.
Given a selected horizon k, we seek to match θ=vec([θ0, θ1, …, θk])′, where we exclude from θ0 the responses corresponding to the elements in Zt that belong to Ωt. As previously mentioned the monetary DSGE model embeds the same exclusion restrictions as the SVAR model. Then let h(·) denote the mapping from the structural parameters ψ=(η, φ, ς, b2, ρ, σ)′ to the monetary model counterpart of θ. Our estimate of ψ is the solution to the problem

where
is an estimate of θ, T is the sample size, Ψ is the set of admissible values of ψ, and VT is a weighting matrix, which we assume to be the inverse of the diagonal matrix containing the variances of each element of θ. These variances are obtained from the SVAR parameters.
For further reference, let us define the objective function at convergence,

Under the null hypothesis, as shown in Hansen (1982),
. Given our choice of weighting matrix, we can further decompose
into components pertaining to each element of Zt, according to

The latter decomposition provides a simple diagnostic tool allowing us to locate the dimensions on which the model succeeds or fails to replicate the impulse response functions implied by the SVAR.
Results
The model parameters are partitioned into two subsets. A first subset contains the parameters that are calibrated prior to estimation, η and σ. A second subset contains the parameters that are estimated: the habit formation parameters, φ and ς, the sunspot parameter, b2, and the money growth parameter that defines the persistency of the process, ρ.
Due to numerical failures incurred when all parameters are jointly estimated, we set the value for the parameters η and σ.12
Most likely, those parameters are not identified.
For each value of η, the remaining model parameters are estimated to minimize the loss function.

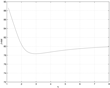
$\mathcal{J}$ statistics for different values of η and with Zt={yt, πt, γt}.
The estimation of {φ, ς, b2, ρ} is performed for different choices of Zt: (i) output and the money growth rate (Zt={yt, γt}), (ii) inflation and the money growth rate Zt={πt, γt}), and (iii) output, inflation, and the money growth rate (Zt={yt, πt, γt}). The first choice allows us to evaluate the ability of the model to mimic the persistency of the real effect of monetary policy shocks on output. The second choice aims at examining whether the model is able to replicate the price puzzle as well as the persistent and delayed response of the inflation rate. Finally, the last choice allows us to study the dynamics of output and inflation following a monetary policy shock.
As previously mentioned, the model has a hard time reproducing the dynamics of the nominal interest rate. Indeed, the excessive response of the nominal interest rate leads to the rejection of the model. Furthermore, in this case the estimates of {φ, ς, b2, ρ} take implausibly high values with very large standard errors. For these reasons, we discarded the nominal interest rate from our estimation. We will discuss this empirical issue later.
We present the estimation results in Table 2 for different Zt and different restrictions on habit parameters. In each case, we set the impulse response functions horizons k to 41.14
Notice that the results are left qualitatively unaffected by a modification of the horizon, provided that the impulse response functions contain the hump pattern of output and inflation.
at convergence and its associated decomposition. It also reports the eigenvalues of the polynomial that describes the dynamic properties of the model.

Let us first concentrate on the unconstrained estimation of {φ, ς, b2, ρ}. The model is in no case rejected by the data. Indeed, the P value of the
statistics is very large whatever the choice of Zt. Consequently, the model does a very good job reproducing both the monetary transmission mechanism and the price puzzle. In looking at the decomposition of the
statistics, it appears that the model performs well in terms of the persistent and hump-shaped responses of output and inflation after a monetary policy shock. In contrast, though not rejected by the data, the model matches the dynamics of money growth poorly. This is a direct consequence of our simple money-growth rule.
The estimates of the habit persistence parameter φ lie between 2.39 and 2.42 and are always significant in the different cases. As already mentioned, this parameter captures the sensitivity of individual consumption to the stock of habits. The higher is φ, the more the agent will take into account habits in his consumption decisions over time. We previously showed that a high value of this parameter is necessary to match the monetary stylized facts. This high value clearly helps us to obtain a quantitatively persistent response to the monetary shock.
The estimate of the parameter ς lies between −0.37 and −0.39 and is also significant. The negative estimated value of this parameter suggests a local durability effect in consumption behavior. It expresses a substitution (or saturation) effect that is associated with local substitution of consumption over time. The value obtained is similar to the ones obtained in many different empirical studies focusing on the moments of U.S. asset returns [see Heaton (1993, 1995), Hindy et al. (1997), Allais (2004), and Giannikos and Shi (2004)]. For instance, Heaton (1993, 1995) finds that both durability and habits help to improve the explanatory power of his model. The values we obtain express the existence both of a strong habit persistence effect and of a significant durability effect. High complementarity and substitutability of consumption, coupled with high sensitivity of consumption to habits, allow the model to reproduce persistent and hump-shaped responses to the monetary shock.
The estimate of the sunspot parameter b2 exceeds 2 and it is always significant. Note that the estimates of b2 lie in a very tiny range, whatever impulse response functions are used to estimate the parameters. As shown in Proposition 2, when b2 is greater than zero, the model replicates the monetary transmission mechanism, and when b2 is greater than one, the model reproduces the price puzzle. Our results suggest that, as long as people believe that sunspots may exist, sunspots may affect the economy. Although our estimates are not easily comparable, our findings are in line with previous studies that point out the quantitative relevance of the correlation structure between sunspots and fundamentals shocks to replicate observed business cycle facts [see Benhabib and Farmer (1996, 2000), Farmer and Guo (1995), Perli (1998), and Schmitt-Grohe (2000)].
Our estimate of the money growth parameter defining the persistence of the process is between 0.70 and 0.74. This value is high but not far from previous estimates [see for instance Christiano et al. (1997, 2005)]. Notice also that imposing lower values for this parameter in the estimation procedure does not affect our results.
Table 2 reports the modulus of eigenvalues associated with the characteristic polynomial P(λ) summarizing the dynamics of the economy. These eigenvalues are complex conjugates but the complex part remains very small compared to the real one. The large values obtained show that the persistency generated in this model may be, in accordance with the data, very high. Notice also that the ability of the model to reproduce the hump-shaped response is strongly related to these high eigenvalues.
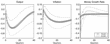
For illustrative purposes, we now present the impulse response functions of output, inflation, and money growth rate from our monetary model (solid line with bullet) and report the impulse response functions of the SVAR model (solid line) in Figure 3. The figure also includes a 95% confidence interval. The persistent and hump-shaped response of output is particularly well reproduced. Furthermore, as discussed at length in Woodford (2003), the delayed response of inflation is a key stylized fact that any monetary model should accurately mimic. The figure shows that on this dimension our model does a very good job, as it precisely accounts for the delayed and persistent response of inflation and for the price puzzle in the short run.

Impulse response functions from the monetary and the SVAR models. Note: These figures are drawn for η=3, σ=0.0007, and Zt={yt, πt, γt}.
Let us now consider the constrained estimate ς=0. The results are reported in the last three columns of Table 2. The
statistics, as well as the
statistics associated with output, inflation, and the money growth rate, lead unambiguously to a rejection of the model. This experiment is important because it shows that both complementarity and substitutability of consumption over time are necessary to match actual U.S. data. The estimates of φ are still significant, meaning that the consumption is sensitive to the habit persistence effect. However, the model will never be able to perform well in terms of persistence. Furthermore, the estimates of the money growth parameter indicate that this parameter may be negative. We therefore join Heaton (1995) (though focusing on different data), in arguing that habit persistence and durability help improve the ability of the model to match U.S. data. The relevance of this assumption is also highlighted by the plot of output, inflation, the nominal interest rate, and the money growth rate after a monetary policy shock when ς=0 (see Figure A.2 in the Appendix). In this case, the model dramatically fails to reproduce the hump-shaped and persistent responses of output and the inflation rate.
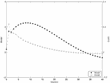
We next address the issue of how well our model can explain the liquidity effect. As discussed above, our model is able to qualitatively match the dynamics of the nominal interest rate but is rejected by the data when this variable is taken into account in the estimation. The failure occurs because its response is too strong compared to the data. This is a direct consequence of the large stock of habits, which implies a high volatility of the marginal utility of consumption and thus of the nominal interest rate. In order to better compare the two responses, we report in Figure 4 the nominal interest rate behavior extracted from the model on the left vertical axis and the Federal Funds Rate dynamics extracted from the SVAR on the right vertical axis. The responses from the model are obtained using the parameter estimates of Table 2 and Zt={yt, πt, γt}. Such comparison indicates that, although the model fails quantitatively on this dimension, it provides a similar shape to the data. Furthermore, it is of importance to notice that the model reproduces well the response of the nominal interest rate at the impact of the shock. The impact response implied by the model is 0.24 whereas the one implied by the SVAR is 0.19. In addition, the value of the nominal interest rate at the impact of the shock in the model is within the confidence interval of the Federal Funds Rate response provided by the SVAR.

IRF of the nominal interest rate from the monetary and the SVAR models. Note: This figure is drawn for η=3,σ=0.0007, and Zt={yt, πt, γt}.
CONCLUDING REMARKS
This paper considered a cash-in-advance economy with long-run complementarity and short-run substitutability in consumption decisions and aimed to match the monetary facts that emerge from a SVAR model. The hump-shaped and persistent responses of output and inflation are considered as key empirical features that the theoretical model should be able to reproduce. In addition, we focused on the puzzling behavior of the inflation rate after a monetary shock. We first studied the dynamic properties of our economy and determined under which conditions on habits real indeterminacy may occur. We did not try to avoid indeterminacy, but instead we took advantage of it to investigate whether our monetary economy with sunspot fluctuations can account for the monetary stylized facts. Using a minimum distance estimation method, we compared the model to the data. Our findings suggest that the model replicates the monetary transmission mechanism and the price puzzle identified in the data. However, the model overestimates the response of the nominal interest rate.
APPENDIX

Data used for estimation.

Impulse response functions from the monetary and the SVAR models. Note: These figures are drawn for η=3, σ=0.0007, ς=0, and Zt={yt,πt,γt}.
We would like to thank the editor, William Barnett, an associate editor, and two referees for insightful comments that lead to a substantial revision of the paper. We would also like to thank Paul Beaudry, Andreas Beyer, Fabrice Collard, Arianna Degan, Julien Matheron, and Franck Portier for helpful comments. This work has benefited from discussions during presentations at various conferences. The traditional disclaimer applies. The views expressed herein are those of the authors and not necessarily those of the Banque de France.