


1. Introduction
Risk exchange refers to the transfer or sharing of risks between different entities in a system, such as an economy. Various entities aggregate uncertain profits/losses into a common pool and aim to implement efficient distribution mechanisms to allocate profits/losses among all participants. The primary objective of the classical risk exchange model is to determine an effective method for distributing the uncertain overall profit, which is typically modeled as a random variable from the mathematical perspective. Extensive research has been conducted on risk exchange within static models since Borch (Reference Borch1960a, Reference Borch1960b, Reference Borch1960c, Reference Borch1962) introduces the concept. Gerber (Reference Gerber1978) extends Borch’s theorem to scenarios in which certain companies are unwilling to contribute more than a specified amount toward the losses incurred by other companies. Bühlmann and Jewell (Reference Bühlmann and Jewell1979) incorporate the actuarial concept of long-run fairness for each participant in the risk exchange framework. Aase (Reference Aase2002) provides a comprehensive overview of the standard risk-sharing model within the insurance context.
This paper extends the paradigm of risk exchange from a static model to a continuous-time economy. In static models, risk exchange is limited to a single-period economy, where entities enter formal agreements at the beginning of the period and exchange risks at the end. However, in reality, entities with cooperative relationships often engage in long-term risk exchange agreements, exchanging risks multiple times over an extended period. Although this can be seen as a series of multiple static models, it may not lead to a global optimum over the long-term horizon. By adopting a continuous-time framework, we can take account of the overall utility throughout the entire period for each entity, leading to more efficient and potentially optimal risk-exchanging arrangements. Moreover, the incorporation of optimal investment strategies alongside risk-sharing mechanisms provides additional advantages within the continuous-time context. Specifically, unlike static models, where the total income at a given time is fixed, continuous-time models enable agents to adjust both the timing and risk of endowment processes through devising optimal investment strategies. This allows for more efficient risk distribution across the whole time horizon and facilitates dynamic risk sharing with security markets. Iwaki (Reference Iwaki2002) introduces the concept of continuous-time risk exchange, and frames it as that all entities purchase insurance from each other. However, this situation does not appear to be common due to the limited number of qualified insurance companies, and Iwaki (Reference Iwaki2002)’s approach does not seem to be a natural extension of the classical static model since it does not involve the distribution of the aggregate endowment process. In this paper, we generalize the concept of uncertain aggregate profit from a random variable to a stochastic process, allowing the risk exchange strategies to be naturally modeled as stochastic processes.
Pareto optimality is a fundamental criterion for optimal risk exchange problems. It describes a profit allocation state where enhancing the position of one entity is impossible without negatively affecting at least one other entity. In other words, a Pareto-optimal allocation signifies the endpoint where no additional Pareto enhancements are possible. Borch (Reference Borch1960b,Reference Borch1960c, Reference Borch1960a, Reference Borch1962), Gerber (Reference Gerber1975, Reference Gerber1978), and Aase (Reference Aase2002) provide detailed explanations of Pareto optimality in risk exchange contexts. Gerber and Pafumi (Reference Gerber and Pafum1998) find explicit solutions for a wide range of utility functions. Under the continuous-time model setting, we assume that the agents not only participate in risk exchange but also make dynamic decisions on consumption and investment in risky assets over time. Distinct from the conventional approaches used in static models, we formulate the dynamic risk exchange problem as a stochastic control problem and derive the Pareto-optimal investment, consumption, and risk exchange strategies using martingale methods.
In this paper, we consider a scenario where n entities are classified into two types of agents based on their utilities. The first type of agents prioritizes the total utility of intertemporal consumption, while the second type focuses on the utility of terminal wealth. For example, the first type can be a fund that focuses on long-term dividends, while the second type can be a company that focuses on terminal opulence without a dividend plan. Each agent can allocate their wealth among multiple risky assets and a risk-free asset. Each agent experiences a stochastic endowment process before engaging in risk exchange and undergoes a new endowment process afterwards. By establishing a Pareto-optimal stochastic control problem within this model, we are able to determine the optimal investment, consumption, and risk exchange strategies using martingale methods (Karatzas and Shreve, Reference Karatzas and Shreve1998). We find that the optimal risk exchange strategies are not unique and can take various forms. For illustrative purposes, we present four distinct cases of Pareto-optimal risk exchange strategies tailored to different scenarios.
To highlight practical applications of our results, we apply them to discuss risk sharing in the context of a target benefit pension (TBP) plan. The TBP plan is an innovative pension system that combines aspects of both defined benefit (DB) and defined contribution (DC) pension funds (Wang et al., Reference Wang, Lu and Sanders2018, Reference Wang and Lu2019; Zhu et al., Reference Zhu, Hardy and Saunders2021; Chen et al., Reference Chen, Li, Wang and Zhu2022, Reference Chen, Yao, Yang and Zhu2023; Rong et al., Reference Rong, Tao and Zhao2023). This collective pension scheme features a predetermined target benefit annuity with dynamic adjustments. TBP plans have already been implemented in several countries such as Canada and Germany, offering the flexibility of risk sharing among different generations, rather than individuals shouldering risks alone (Canadian Institute of Actuaries, 2015; Chen and Rach, Reference Chen and Rach2021).
Managing a TBP plan entails addressing various sources of risks, including but not limited to financial, longevity, inflation, stochastic interest rate, and reputation risks. These risks are not solely borne by the agent but are shared among all members of the TBP plan through dynamic adjustments. By implementing a risk exchange mechanism, TBP plan members can effectively share risks with other entities, enabling the TBP plan to play a role similar as reinsurance companies. The TBP plan can accept risks from other companies and redistribute them through an adjustment term determining risk sharing among its members. Furthermore, the TBP plan has the flexibility to transfer a portion of its own risks to other companies, thereby contributing to its overall stability.
In this paper, we focus on an important source of risk affecting the original endowment process of the TBP, namely longevity risk. In general, we may consider the incorporation of the impacts of other sources of risks and their interactions. Longevity risk pertains to the possibility that retirees may live longer than anticipated, which can have a profound impact on the financial stability of pension funds. Rong et al. (Reference Rong, Tao and Zhao2023) and Tao et al. (Reference Tao, Rong and Zhao2025) have explored the optimal investment and benefit strategies for TBP plans in the presence of longevity risk. To alleviate the payment pressure faced by pension funds due to longevity risk, one natural approach is to share or exchange this risk with another company. Cox et al. (Reference Cox, Lin and Liu2021) have investigated optimal strategies for longevity risk transfer and investment in the context of defined benefit pensions. To further explore the risk transfer or exchange of longevity risk, our paper contributes to the literature by providing insights into the possibilities and implications of such risk management strategies within the TBP framework.
This paper makes three significant contributions to the literature. First, we propose a novel risk exchange mechanism that operates within a continuous-time model, facilitating the real-time transfer and sharing of risks among multiple entities. This framework advances our understanding of risk exchange in a dynamic environment. Second, we derive the Pareto-optimal investment, consumption, and risk exchange strategies. By employing martingale methods and dynamic stochastic control techniques, we provide explicit solutions for these strategies. Moreover, we identify and present various forms of risk exchange, tailored to different scenarios and objectives. Lastly, we apply this model to the TBP system. By integrating our risk exchange framework into the TBP, we enhance the plausibility of this pension scheme in effectively sharing risks among its members. This application underscores the practical relevance and implications of our research in advancing prudent risk management strategies within the TBP framework.
The rest of the paper is structured as follows. Section 2 introduces the basic model settings and establishes a Pareto-optimal stochastic control problem. Section 3 derives the optimal solutions. Section 4 presents the application of our results to the TBP. In Section 5, we analyze numerical examples to illustrate the results. Finally, Section 6 concludes the paper.
2. Model formulation
In this section, we formulate the Pareto-optimal risk exchange problem in a continuous-time economy through the following steps: First, we present the basic assumptions regarding the financial market. Then, we define the admissible risk exchange, portfolio process, and consumption process. Finally, we establish the Pareto-optimal risk exchange problem and derive its equivalent formulation.
2.1 Financial market
Our continuous-time financial market is defined as follows.
Definition 2.1. A complete financial market
 $\mathcal M$
consists of
-
1. a finite time horizon
 ${\mathcal T}\, :\! =[0, T]$
, where
$T \lt \infty$
is a positive constant, called the terminal time;
-
2. a probability space
$(\Omega,\mathcal{F},\mathbb{F},\mathbb{P})$
, where
$\mathbb{P}$
is the real-world probability measure on the measurable space
$(\Omega, {\mathcal F})$
,
${\mathcal F}$
is a
$\sigma$
-field on
$\Omega$
, and
$\mathbb{F} \, :\! = \{ {\mathcal F}_t \}_{t \in {\mathcal T}}$
is a filtration to be specified in Point 3 below; -
3. a D-dimensional standard Brownian motion
$\{ W(t)=(W_1 (t), W_2 (t), \ldots, W_D (t))^{\top} \}_{t \in {\mathcal T}}$
defined on
$(\Omega,\mathcal{F},\mathbb{F},\mathbb{P})$
, where the filtration
$\mathbb{F}$
is the
$\mathbb{P}$
-augmentation of the natural filtration generated by
$\{ W (t) \}_{t \in {\mathcal T}}$
. Here,
${\bf y}^{\top}$
is the transpose of a vector, or a matrix
$\mathbf{y}$
. -
4. an
$\mathbb{F}$
-progressively measurable continuously compounded risk-free interest rate process
$\{ r (t) \}_{t \in {\mathcal T}}$
such that
$\int_0^T|r(t)|\mathrm{d}t \lt \infty$
,
$\mathbb{P}$
-almost surely (a.s.); -
5. an
$\mathbb{F}$
-progressively measurable, D-dimensional mean rate of return process
$\{ \mu (t)=(\mu_1(t),\mu_2(t),\ldots,\mu_D(t))^{\top} \}_{t \in {\mathcal T}}$
such that
$\int_0^T||\mu(t)||\mathrm{d}t \lt \infty$
,
$\mathbb{P}$
-a.s.; -
6. an
$\mathbb{F}$
-progressively measurable,
$(D \times D)$
-matrix-valued nonsingular volatility process
$\{ \sigma (t)=(\sigma_{ij}(t))_{D\times D} \}_{t \in {\mathcal T}}$
such that
$\sum_{j=1}^D\sum_{k=1}^D \int_0^T\sigma_{jk}^2(t) \mathrm{d}t \lt \infty$
,
$\mathbb{P}$
-a.s.


The agents of the entities are allowed to invest their wealth in the financial market
 ${\mathcal M}$
consisting of a money market account and D correlated risky securities. By investing in a risk-free asset, agents can stabilize income timing, while investing in risky assets allows them to advance or postpone risk exposure. This flexibility enables a more efficient risk distribution across the entire time horizon, rather than merely optimizing risk at a terminal point or through iterative static exchanges. Incorporating investment strategies essentially facilitates dynamic risk sharing with financial markets, leading to a more integrated, consistent risk management approach.
We denote the time-t price of the money market account by
 $S_0(t)$
and the time-t price of the j-th risky security by
 $S_j(t)$
,
 $j=1,2,\ldots,D$
. The evolution of the money market account balance
 $\{ S_0 (t) \}_{t \in {\mathcal T}}$
is governed by the following equation:
 \begin{equation*} \left\{ \begin{aligned}&\mathrm{d}S_0(t)=r(t)S_0(t)\mathrm{d}t, \ \ \ \ \ t\in{\mathcal T},\\&S_0(0)=1, \end{aligned} \right.\end{equation*}
where
 $\{ r(t) \}_{t \in {\mathcal T}}$
is the risk-free rate process defined in Definition 2.1.
Suppose that the evolution of the price processes
 $\{ S_j (t) \}_{t \in {\mathcal T}}$
, for
 $j = 1, 2, \ldots, D$
, of the risky securities is governed by the following system of stochastic differential equations:
 \begin{equation*} \left\{ \begin{aligned}&\mathrm{d}S_j(t)=S_j(t)\left(\mu_j(t)\mathrm{d}t+\sum_{k=1}^D\sigma_{jk}(t) \mathrm{d}W_k(t)\right)=S_j(t)\left(\mu_j(t)\mathrm{d}t+\sigma_{j}(t)^{\top} \mathrm{d}W(t)\right),\qquad t\in{\mathcal T},\\&S_j(0)=1. \end{aligned} \right.\end{equation*}
Note that for each
 $t \in {\mathcal T}$
and
 $j = 1, 2, \ldots, D$
,
 $\sigma_j (t) \, :\! = (\sigma_{j1}(t), \sigma_{j2}(t), \ldots, \sigma_{jD}(t))^{\top} \in \Re^D$
, where
 $\mathbf{y}^{\top}$
is the transpose of a vector
 $\mathbf{y}$
and
 $\Re^D$
is the D dimension real Euclidean space. For each
 $k = 1, 2, \ldots, D$
, the
 $k\textrm{th}$
component of
 $\sigma_j (t)$
, namely
 $\sigma_{jk} (t)$
, is the instantaneous volatility coefficient at time t which describes the impact of the
 $k\textrm{th}$
random shock described by the
 $k\textrm{th}$
Brownian motion
 $\{ W_k (t) \}_{t \in {\mathcal T}}$
on the
 $j\textrm{th}$
risky asset.
To preclude arbitrage opportunities, we assume that
 $\mu_j(t)\gt r(t)$
for each
 $j=1,2,\ldots,D$
and
 $t\in{\mathcal T}$
.
For each
 $t \in {\mathcal T}$
, the market price of risk at time t, (i.e., the Sharpe ratio at time t), is given by:
 \begin{equation*} \theta(t)\, :\! =\sigma(t)^{-1}(\mu(t)-r(t)1_D),\end{equation*}
where
 $1_D$
is a D-dimensional vector with all elements being 1. We assume that the market price of risk process
 $\{ \theta (t) \}_{t \in {\mathcal T}}$
satisfies Novikov’s condition over the finite time horizon
 ${\mathcal T}$
. Thus, we can define an exponential martingale
 $\{ \phi (t) \}_{t \in {\mathcal T}}$
as follows:
 \begin{equation*} \phi(t)\, :\! =\exp\left\{-\int_0^t \theta(s)^{\top}\mathrm{d}W(s)-\frac{1}{2}\int_0^t \left \| \theta(s) \right \|^2\mathrm{d}s\right\}.\end{equation*}
The state price density process
 $\{ H (t) \}_{t \in {\mathcal T}}$
is then defined by putting:
 \begin{equation} H(t)\, :\! =\frac{\phi(t)}{S_0(t)}=\exp\left\{\int_0^t \left[-r(s)-\frac{1}{2}\left \| \theta(s) \right \|^2\right]\mathrm{d}s-\int_0^t \theta(s)^{\top}\mathrm{d}W(s)\right\}.\end{equation}
We impose the technical assumptions that
 $\mathrm{E}[\! \int_0^TH(u)\mathrm{d}u] \lt \infty$
and
 $\mathrm{E}[H(T)] \lt \infty$
.
2.2 Risk exchange
Consider n entities, whose stochastic endowment processes are
 $\{ Y_1 (t) \}_{t \in {\mathcal T}}$
,
 $\{ Y_2 (t) \}_{t \in {\mathcal T}}$
,
 $\dots$
,
 $\{ Y_n (t) \}_{t \in {\mathcal T}}$
. The initial wealth for the i-th entity is given by a nonnegative constant
 $x_i$
, for
 $i \in {\mathcal N} \, :\! = \{ 1, 2, \dots, n \}$
. Let x denote the sum of all
 $x_i$
, that is,
 $x\, :\! =\sum_{i\in {\mathcal N}} x_i$
. For each
 $t \in {\mathcal T}$
, let Y (t) denote the sum of the endowments of the n entities at time t, that is:
 \begin{equation*}Y(t)\, :\! =\sum_{i=1}^n Y_i(t).\end{equation*}
We call
 $\{Y(t)\}_{t\in \mathcal T}$
the aggregate endowment process. Technically, it should satisfy the following assumption:
Assumption (A1). The aggregate endowment process
 $Y\, : \, \Omega\times {\mathcal T}\to \Re$
is an
 $\mathbb{F}$
-progressively measurable process such that
 $\int_0^T Y(s)\mathrm{d}s \lt \infty$
,
 $\mathbb{P}$
-a.s. and
 $x+\mathrm{E}[\! \int_0^TH(t)Y(t)\mathrm{d}t]\gt 0$
.
The fundamental concept of risk exchange in continuous time involves redistributing the aggregate endowment process Y(t), at each time
 $t \in {\mathcal T}$
, among the n entities. The notion of admissible risk exchange is formally given in the following definition.
Definition 2.2. Under Assumption (A1), an admissible risk exchange is an n-dimensional vector-valued stochastic process
 $\{ (Z_1 (t), Z_2 (t), \dots, Z_n (t)) \}_{t \in {\mathcal T}}$
satisfying:
-
1.
$\sum_{i=1}^nZ_i(t)=Y(t)$
, for all
$t\in {\mathcal T}$
; -
2.
$x_i+\mathrm{E}[\! \int_0^TH(t)Z_i(t)\mathrm{d}t]\ge0$
; -
3.
$\{ Z_i (t) \}_{t \in {\mathcal T}}$
is
$\mathbb{F}$
-progressively measurable, for each
$i \in {\mathcal N}$
; -
4.
$\mathrm{E}[\! \int_0^TH(t)Z_i(t)\mathrm{d}t] \lt \infty$
, for each
$i \in {\mathcal N}$
; -
5.
$\int_0^T Z_i(s)\mathrm{d}s \lt \infty$
$\mathbb{P}$
-a.s. for each
$i \in {\mathcal N}$
.


The initial endowment process
 $\{ (Y_1 (t), Y_2 (t), \dots, Y_n (t)) \}_{t \in {\mathcal T}}$
can be also viewed as a risk exchange and should satisfy all the conditions in Definition 2.2. Condition (2) in Definition 2.2 requires that the total wealth of each entity, comprising the initial wealth and the expected present value of total endowments, where the present value is determined by the state price density process
 $H(\! \cdot \!)$
, must remain positive. This requirement ensures the long-term viability of each entity and prevents any entity from making excessive concessions through risk exchange.
2.3 Wealth processes
In this paper, the wealth process of an entity refers to the evolution of the total wealth of the entity over time, typically modeled as a stochastic process in continuous time. It captures the accumulated value of assets the entity holds, accounting for initial wealth, investment returns (from both risky and risk-free assets), endowments, and consumption.
Suppose that there are two types of entities sharing their risks in the pure risk exchange economy. The numbers of the two types of entities are
 $n_1$
and
 $n_2$
, respectively, where
 $n_1$
and
 $n_2$
are given nonnegative integers such that
 $n=n_1+n_2$
. Type 1 only focuses on its overall consumption, while Type 2 focuses on its terminal wealth. Denote by
 ${\mathcal N}_1=\{1,\ldots,n_1\}$
and
 ${\mathcal N}_2=\{n_1 +1,\ldots,n\}$
. We permit the cases where
 $n_1=0$
or
 $n_2=0$
. When
 $n_1=0$
, it follows that
 ${\mathcal N}_1=\emptyset$
; Similarly, when
 $n_2=0$
,
 ${\mathcal N}_2=\emptyset$
. The model remains valid even when there is only one type of agents.
We assign the label “agent i” to the i-th entity. The wealth processes of the agents depend on the returns on investments from the money market account and the risky securities, as well as the agents’ endowment processes, denoted as
 $Y_i$
, for
 $i=1,2,\ldots, n$
. Additionally, agent
 $i\in {\mathcal N}_1$
is required to make continuous consumption, while agent
 $i\in {\mathcal N}_2$
is not subject to this obligation. For example, if these n companies are all pension funds, then
 $n_1$
of them are required to make continuous annuity payments (viewed as a consumption process), while the remaining
 $n_2$
are only required to make a large amount of pension payments at the terminal time (retirement time), such as defined contribution (DC) pension plans.
For each
 $i \in {\mathcal N}$
, let
 $f_i (t)$
and
 $\pi_i(t)=(\pi_{i1}(t),\ldots,\pi_{iD}(t))$
denote the consumption rate and the vector of invested amounts, respectively, of the i-th agent at time t, where
 $\pi_{ij}(t)$
is the amount invested in the j-th risky security, for each
 $j = 1, 2, \ldots, D$
. Since the agents of Type 2 have no consumption process, it holds that
 $f_i(t)=0$
for each
 $i\in {\mathcal N}_2$
and
 $t\in{\mathcal T}$
. Throughout this paper, we make the following assumptions about the financial market
 ${\mathcal M}$
: (1) there are not transaction costs/taxes; (2) the agents can trade continuously over time; and (3) fractional units of assets can be traded; (4) short-selling is allowed. Then for each
 $i \in {\mathcal N}$
, the evolution of the wealth process
 $\{ X_i (t) \}_{i \in {\mathcal N}}$
of the i-th agent over time is governed by the following stochastic differential equation:
 \begin{equation} \left\{ \begin{aligned} &\mathrm{d}X_i(t)=\sum_{j=1}^D \pi_{ij}(t)\left(\mu_j(t)\mathrm{d}t+\sigma_j(t)^{\top}\mathrm{d}W(t)\right)+\left(X_i(t)-\sum_{j=1}^D \pi_{ij}(t)\right)r(t)\mathrm{d}t+(Z_i(t)-f_i(t))\mathrm{d}t,\\ &X_i(0)=x_i. \end{aligned} \right. \end{equation}
We now define
 $\nu\, :\! =\{(\pi_i(t),f_i(t),Z_i(t)), i\in {\mathcal N}, t\in{\mathcal T}\}$
as a strategy adopted by all agents over the time interval
 ${\mathcal T}$
. To emphasize its dependence on
 $\nu$
, we denote
 $X_i(\! \cdot \!)$
as
 $X_i^{\nu}(\! \cdot \!)$
unless otherwise stated.
2.4 Pareto-optimal problem
The utility function
 $U_i$
for agent
 $i\in {\mathcal N}_1$
and
 $V_i$
for agent
 $i\in {\mathcal N}_2$
should satisfy the following assumption.
Assumption (A2).
-
1.
$U_i\, : \, [0,+\infty)\to \Re$
is strictly increasing, strictly concave, and possesses twice continuously differentiable properties. -
2.
$U_i'(+\infty)\, :\! = \lim_{s\to +\infty}U_i'(s)=0$
and
$U_i'(0+\!)\, :\! =\lim_{s\downarrow 0}U_i'(s)=+\infty.$
-
3. Denote by
$I_i(\! \cdot \!)$
the inverse function of the derivative
$U_i'(s)$
in s, for each
$i\in{\mathcal N}_1$
. And there exist positive constants
$a_{i1}$
,
$a_{i2}$
and
$\tau_i$
, such that
$I_i(s)\le\tau_i s^{-a_{i1}}$
for
$0 \lt s \le 1$
and
$I_i(s)\le\tau_i s^{-a_{i2}}$
for
$1 \lt s \lt \infty$
. -
4. We denote by
$J_i(\! \cdot \!)$
the inverse function of the derivative
$V_i'(s)$
in s, for each
$i\in{\mathcal N}_2$
. The functions
$V_i$
and
$J_i$
for agent
$i\in {\mathcal N}_2$
satisfy the same set of conditions.


Assumption (A3). Suppose that the risk-free interest rate process
 $\{ r (t) \}_{t \in {\mathcal T}}$
and the market price of risk process
 $\{ \theta (t) \}_{t \in {\mathcal T}}$
satisfy the following integrability condition
 $\mathrm{E} [ \exp \{ a_{ij} \vee (2 a^2_{ij} ) \int_0^t [r(s)+\left \| \theta(s) \right \|^2]\mathrm{d}s \} ] \lt \infty$
, for any
 $i\in {\mathcal N}$
and
 $j = 1, 2$
, where
 $a_{ij} \vee (2 a^2_{ij} )$
represents the maximum of
 $a_{ij}$
and
 $2 a^2_{ij}$
.
Proposition 2.3. Under Assumptions (A2) and (A3), for any
 $u\gt0$
,
 $\mathrm{E}[\! \int_0^TU_i(I_i(uH(t)))\mathrm{d}t] \lt \infty$
, for
 $i\in {\mathcal N}_1$
, and
 $\mathrm{E}[V_i(J_i(uH(T)))] \lt \infty$
, for
 $i\in {\mathcal N}_2$
.
Proof. See Appendix A for details.
In fact, Proposition 2.3 establishes the admissibility of the strategy presented in Theorem 3.10, verifying that it satisfies condition 5 of Definition 2.4.
Under Assumption (A2), the inverse functions
 $I_i(s)$
and
 $J_i(s)$
are also continuous, differentiable, and strictly decreasing in s and map
 $(0,+\infty]$
onto themselves with the properties
 $I_i(0+)=U_i'(0+)= J_i(0+)=V_i'(0+)=+\infty$
and
 $I_i(+\infty)=U_i'(+\infty)=J_i(+\infty)=V_i'(+\infty)=0$
.
Definition 2.4. A strategy
 $\nu\, :\! =\{(\pi_i(t),f_i(t),Z_i(t)), i\in {\mathcal N}, t\in{\mathcal T}\}$
is admissible if
-
1. The corresponding wealth process
$\{ X_i (t) \}_{t \in {\mathcal T}}$
, for each
$i \in {\mathcal N}$
, satisfy where
\begin{equation*}H(t)X_i(t)+\mathrm{E}_t\left[\int_t^TH(s)Z_i(s)\mathrm{d}s\right]\ge 0,\qquad t\in {\mathcal T},i\in {\mathcal N},\end{equation*}
$\mathrm{E}_t[\! \cdot \!]\, :\! =\mathrm{E}[\cdot|\mathcal{F}_t]$
is the conditional expectation taken with respect to the probability measure
$\mathbb{P}$
given the information up to and including time t, that is,
${\mathcal F}_t$
.
-
2. Each
$\pi_{ij}:\Omega\times {\mathcal T}\to \Re$
is an
$\mathbb{F}$
-progressively measurable portfolio process satisfying
$\int_0^T\pi_{ij}^2(s)\mathrm{d}s \lt \infty$
,
$\mathbb{P}$
-a.s., for each
$i\in {\mathcal N}$
and
$j=1,\ldots,D$
. -
3. Each
$f_i:\Omega\times {\mathcal T}\to [0,+ \infty)$
is an
$\mathbb{F}$
-progressively measurable process satisfying
$\int_0^T f_i(s)\mathrm{d}s \lt \infty$
,
$\mathbb{P}$
-a.s., for each
$i\in {\mathcal N}_1$
, and
$f_i(t)=0$
for each
$i\in {\mathcal N}_2$
. -
4. The n-dimensional vector valued process
$\{ (Z_1 (t), Z_2 (t), \dots, Z_n (t)) \}_{t \in {\mathcal T}}$
is an admissible risk exchange satisfying Definition 2.2. -
5.
$\mathrm{E}[\! \int_0^T U_i(f_i(s))\mathrm{d}s] \lt \infty$
for
$i\in {\mathcal N}_1$
, and
$\mathrm{E}[V_i(X_i(T))] \lt \infty$
for
$i\in {\mathcal N}_2$
.


The set of admissible strategies is denoted as
 $\mathscr{A}$
. Note that the range of
 $\pi_{ij}$
contains negative real numbers, implying short-selling of the risky securities is allowed. However, in practice, there might be some institutional restrictions for agents such as pension funds to sell short.
We assume that the time preference (discounting) of agent i is modeled by a positive deterministic integrable function
 $\{ \eta_i (t) \}_{t \in {\mathcal T}}$
. Therefore, given an admissible strategy
 $\nu\in \mathscr{A}$
, the objective functional for agent
 $i\in {\mathcal N}_1$
is defined by
 \begin{equation*}F_i(\nu)=\mathrm{E}\left[\int_0^T \mathrm{e}^{-\int_0^s \eta_i(u)\mathrm{d}u}U_i(f_i(s))\mathrm{d}s\right],\qquad \nu\in\mathscr{A},\end{equation*}
and the objective functional for agent
 $i\in {\mathcal N}_2$
is defined by
 \begin{equation*}F_i(\nu)=\mathrm{E}\left[\mathrm{e}^{-\int_0^T \eta_i(u)\mathrm{d}u}V_i(X_i(T))\right],\qquad \nu\in\mathscr{A}.\end{equation*}
Assumption (A4). For any
 $0 \lt u \lt \infty$
,
 $\mathrm{E}[\! \int_0^TH(t)I_i(u\mathrm{e}^{\int_0^t\eta_i(u)\mathrm{d}u}H(t))\mathrm{d}t]\lt\infty$
,
 $i\in{\mathcal N}_1$
, and
 $\mathrm{E}[H(T)J_i (u\mathrm{e}^{\int_0^T\eta_i(u)\mathrm{d}u}H(T))]\lt\infty$
,
 $i\in{\mathcal N}_2$
.
Remark 2.5. Assumption (A4) ensures the validity of Assumptions 7.1 and 7.2 in Karatzas and Shreve (Reference Karatzas and Shreve1998). Specifically, for any
 $0 \lt u \lt \infty$
,
 \begin{align*}&\mathrm{E}\left[\int_0^TH(t)I(t,uH(t))\mathrm{d}t+H(T)J(uH(T))\right]\\&=\mathrm{E}\left[\int_0^TH(t)\sum_{i\in {\mathcal N}_1'} I_i\left(\rho_i^{-1}u\mathrm{e}^{\int_0^t\eta_i(u)\mathrm{d}u}H(t)\right)\mathrm{d}t+H(T)\sum_{i\in {\mathcal N}_2'} J_i\left(\rho_i^{-1}u\mathrm{e}^{\int_0^T\eta_i(u)\mathrm{d}u}H(T)\right)\right]\\&=\sum_{i\in {\mathcal N}_1'}\mathrm{E}\left[\int_0^TH(t) I_i\left(\rho_i^{-1}u\mathrm{e}^{\int_0^t\eta_i(u)\mathrm{d}u}uH(t)\right)\mathrm{d}t\right]+\sum_{i\in {\mathcal N}_2'}\mathrm{E}\left[H(T) J_i\left(\rho_i^{-1}u\mathrm{e}^{\int_0^T\eta_i(u)\mathrm{d}u}H(T)\right)\right]\lt\infty,\end{align*}
thereby satisfying Assumption 6.1 in Karatzas and Shreve (Reference Karatzas and Shreve1998).
Since
 $\mathrm{e}^{-\int_0^s \eta_i(u)\mathrm{d}u}\le 1$
for
 $0 \le s \le T$
, according to Condition 5 in Definition 2.4, we have
 $F_i(\nu)\lt\infty$
, for
 $i\in {\mathcal N}$
.
Our goal is to find an optimal strategy
 $\nu\in\mathscr{A}$
that maximizes all
 $F_i$
in a Pareto-optimal manner. In this context, we define Pareto optimality as follows:
Definition 2.6. A strategy
 $\nu_1$
is said to be strictly better than a strategy
 $\nu_2$
, if
 $F_i(\nu_1)\ge F_i(\nu_2)$
for all
 $i\in {\mathcal N}$
, and if at least one of these inequalities is strict. A strategy
 $\nu \in \mathscr{A}$
is said to be Pareto-optimal over a set of admissible strategies
 $\mathscr{A}$
, if there is no strategy in
 $\mathscr{A}$
that is strictly better than
 $\nu$
.
Inspired by Gerber (Reference Gerber1978), Cheung et al. (Reference Cheung, Rong and Yam2014) and Aase (Reference Aase2002), we obtain the necessary and sufficient conditions for the Pareto-optimal strategy in the continuous-time framework:
Theorem 2.7. Under Assumption (A2) for all
 $i\in {\mathcal N}$
. Then
 $\nu=\{(\pi_i(t),f_i(t),Z_i(t)), i\in {\mathcal N}, t\in{\mathcal T}\}$
is a Pareto-optimal strategy if and only if there exist n nonnegative constants
 $\rho_i$
, for
 $i \in {\mathcal N}$
that are not all zeroes, such that
 $\nu \in \mathscr{A}$
and
 $\nu$
is an optimal solution to the following maximization problem:
 \begin{align*}\mbox{Problem A:} \quad \max_{\nu\in \mathscr{A}}\sum_{i\in {\mathcal N}} \rho_i F_i(\nu).\end{align*}
Proof. See Appendix A for details.
Therefore, if there exists a strategy
 $\nu^*$
that solves Problem A, it is said to be a Pareto-optimal strategy. Here, the constant
 $\rho_i$
is interpreted as a weight coefficient describing the relative significance of the utility of agent i. If there exists an agent i such that the weight coefficient
 $\rho_i = 0$
, then agent i has no incentive to participate in the risk exchange. We denote
 ${\mathcal N}_0\, :\! =\{i\in{\mathcal N}:\rho_i=0\}$
,
 ${\mathcal N}'\, :\! =\{i\in{\mathcal N}:\rho_i\gt0\}$
,
 ${\mathcal N}_1'\, :\! =\{i\in{\mathcal N}_1:\rho_i\gt0\}$
, and
 ${\mathcal N}_2'\, :\! =\{i\in{\mathcal N}_2:\rho_i\gt0\}$
. Then Problem A becomes:
 \begin{align}\max_{\nu\in \mathscr{A}}\sum_{i\in {\mathcal N'}} \rho_i F_i(\nu).\end{align}
In the next section, we will find an optimal strategy
 $\nu^*\, :\! =\{(\pi_i^*,f_i^*,Z_i^*),i\in {\mathcal N}\}$
for Problem A. Then we can claim that
 $\nu^*$
is a Pareto-optimal strategy and thus
 $(Z_1^*,\ldots, Z_n^*)$
is a Pareto-optimal risk exchange.
3. Main results
In this section, to solve Problem A, we first introduce an auxiliary problem whose solution will be used to establish our required strategy
 $\nu^*$
. Then we show that
 $\nu^*$
is a Pareto-optimal strategy. Finally, we provide illustrations of different forms of Pareto-optimal risk exchange.
3.1 Properties of the aggregate utilities
In this subsection, we study the properties of two aggregate utility functions defined as follows:
 \begin{equation*}U(t,s)=\sup_{s_i\ge 0 : i \in {\mathcal N}_1} \left\{\sum_{i\in {\mathcal N}_1'} \rho_i\mathrm{e}^{-\int_0^t\eta_i(u)\mathrm{d}u} U_i(s_i)\Big|\sum_{i\in {\mathcal N}_1'} s_i=s\right\},\end{equation*}
and
 \begin{equation*}V(s)=\sup_{s_i\ge 0 : i \in {\mathcal N}_2' }\left\{\sum_{i\in {\mathcal N}_2'} \rho_i\mathrm{e}^{-\int_0^T\eta_i(u)\mathrm{d}u} V_i(s_i)\Big|\sum_{i\in {\mathcal N}_2'} s_i=s\right\} , \quad \mbox{for} \ s\ge 0 .\end{equation*}
Given that
 $\eta_i(\! \cdot \!)$
are positive integrable functions, for all
 $i\in \mathcal N$
, we give explicit expressions for U(t,s) and V(s) in Theorem 3.1 below.
Theorem 3.1. Under Assumption (A2), for
 $s\ge 0$
and
 $t\in \mathcal T$
, the explicit expressions for U(t,s) and V(s) are
 \begin{equation}U(t,s)=\sum_{i\in {\mathcal N}_1'} \rho_i\mathrm{e}^{-\int_0^t\eta_i(u)\mathrm{d}u} U_i\left(I_i\left(\rho_i^{-1}\mathrm{e}^{\int_0^t\eta_i(u)\mathrm{d}u}\kappa(t,s)\right)\right),\end{equation}
and
 \begin{equation}V(s)=\sum_{i\in {\mathcal N}_2'} \rho_i\mathrm{e}^{-\int_0^T\eta_i(u)\mathrm{d}u} V_i\left(J_i\left(\rho_i^{-1}\mathrm{e}^{\int_0^T\eta_i(u)\mathrm{d}u}\epsilon(s)\right)\right),\end{equation}
where
 $\kappa(t,s)$
and
 $\epsilon(s)$
are unique solutions to
 \begin{equation}\sum_{i\in {\mathcal N}_1'} I_i\left(\rho_i^{-1}\mathrm{e}^{\int_0^t\eta_i(u)\mathrm{d}u}\kappa(t,s)\right)-s=0\end{equation}
and
 \begin{equation}\sum_{i\in {\mathcal N}_2'} J_i\left(\rho_i^{-1}\mathrm{e}^{\int_0^T\eta_i(u)\mathrm{d}u}\epsilon(s)\right)-s=0,\end{equation}
respectively.
Specifically, given
 \begin{equation*}s_i= I_i\left(\rho_i^{-1}\mathrm{e}^{\int_0^t\eta_i(u)\mathrm{d}u}\kappa(t,s)\right),\qquad i\in {\mathcal N}_1',\end{equation*}
we have
 \begin{equation*}U(t,s)=\sum_{i\in {\mathcal N}_1'} \rho_i\mathrm{e}^{-\int_0^t\eta_i(u)\mathrm{d}u} U_i(s_i) \ \ \ and \ \ \ \sum_{i\in {\mathcal N}_1'} s_i=s,\end{equation*}
and given
 \begin{equation*}s_i= J_i\left(\rho_i^{-1}\mathrm{e}^{\int_0^T\eta_i(u)\mathrm{d}u}\epsilon(s)\right),\qquad i\in {\mathcal N}_2',\end{equation*}
we have
 \begin{equation*}V(s)=\sum_{i\in {\mathcal N}_2'} \rho_i\mathrm{e}^{-\int_0^T\eta_i(u)\mathrm{d}u} V_i(s_i) \ \ \ and \ \ \ \sum_{i\in {\mathcal N}_2'} s_i=s.\end{equation*}
Proof. See Appendix A.
We observe from Equations (3.3) and (3.4) that for a fixed
 $t \in {\mathcal T}$
,
 $\kappa(t,s)$
is the inverse function of
 \begin{equation}I(t,s)\, :\! =\sum_{i\in {\mathcal N}_1'} I_i\left(\rho_i^{-1}\mathrm{e}^{\int_0^t\eta_i(u)\mathrm{d}u}s\right),\end{equation}
and
 $\epsilon(s)$
is the inverse function of
 \begin{equation}J(s)\, :\! =\sum_{i\in {\mathcal N}_2'} J_i\left(\rho_i^{-1}\mathrm{e}^{\int_0^T\eta_i(u)\mathrm{d}u}s\right)\end{equation}
in s.
Since I(t,s) is differentiable with respect to s, its inverse function
 $\kappa(t,s)$
is differentiable with respect to s. Thus, U(t,s) is differentiable with respect to s according to Equation (3.1). Similarly, V(s) is differentiable with respect to s. The derivatives of U (t, s) and V(s) in s are given by the following proposition.
Proposition 3.2. Under Assumption (A2), if
 $\kappa(t,s)$
is the solution to Equation (3.3) and
 $\epsilon(s)$
is the solution to Equation (3.4), the following relations hold true:
 \begin{equation}\kappa(t,s)=U_s(t,s)\, :\! =\frac{\partial}{\partial s}U(t,s),\end{equation}
and
 \begin{equation}\epsilon(s)=V_s(s).\end{equation}
Proof. See Appendix A.
Remark 3.3. Following the above proportions, we have that for a fixed
 $t \in {\mathcal T}$
, I(t,s) is the inverse function of
 $U_s(t,s)$
and J(s) is the inverse function of
 $V_s(s)$
in s. It can be seen from Equations (3.5) and (3.6) that I(t,s) and J(s) are positive and strictly decreasing in s, and
 $I(t,0+)=J(0+)=+\infty$
and
 $I(t,+\infty)=J(+\infty)=0$
. Thus, we say that U(t,s) and V(s) are strictly increasing and strictly concave in s.
3.2 Auxiliary problems
In this subsection, we consider several auxiliary problems that are stochastic control problems intimately linked with Problem A. The solutions to these problems are well established in the literature (see, for example, Karatzas and Shreve, Reference Karatzas and Shreve1998).
3.2.1 Problem B
Given
 $\{Z_i, i\in {\mathcal N}_0\}$
satisfying
 $\sum_{i \in {\mathcal N}_0}(x_i+\mathrm{E}[\! \int_0^TH(t)Z_i(t)\mathrm{d}t]) \lt x+\mathrm{E}[\! \int_0^TH(t)Y(t)\mathrm{d}t]$
(which guarantees that the left-hand side of Equation (3.13) remains positive), Problem B introduces a fictitious agent whose wealth process represents the aggregate wealth of all agents in
 $\mathcal{N}'$
. Specifically, the fictitious agent’s wealth at time
 $t \in {\mathcal T}$
is denoted as
 $X(t)\, :\! = \sum_{i\in{\mathcal N}'}X_i(t)$
, with the initial wealth given by
 $\sum_{i\in {\mathcal N}'}x_i$
, and the fictitious agent’s portfolio choice and endowment at time
 $t \in {\mathcal T}$
are given by
 $\Pi(t)\, :\! =\sum_{i\in{\mathcal N}'}\pi_i(t)=\left(\sum_{i\in{\mathcal N}'}\pi_{i1}(t),\ldots,\sum_{i\in{\mathcal N}'}\pi_{iD}(t)\right)=(\Pi_1(t),\ldots,\Pi_D(t))$
, and the total consumption at time
 $t \in {\mathcal T}$
is given by
 $f(t)\, :\! =\sum_{i\in{\mathcal N}_1'}f_i(t)$
, respectively. Since the fictitious agent is concerned with the aggregate endowment
 $Y(t)-\sum_{i\in {\mathcal N}_0}Z_i(t)$
itself in this formulation, there is no need to consider the redistribution of
 $Y(t)-\sum_{i\in {\mathcal N}_0}Z_i(t)$
at each time
 $t \in {\mathcal T}$
.
The objective of the fictitious agent is to maximize the expected utility on the total consumption f(t) and the terminal wealth X(T) by choosing
 $\Pi$
and f. We state Problem B as follows:
 \begin{equation}\max_{(\Pi,f)\in\mathscr{A}_B}\mathrm{E}\left[\int_0^T U(s,f(s))\mathrm{d}s+V(X(T))\right]\end{equation}
subject to the aggregate wealth dynamics:
 \begin{equation} \left\{ \begin{aligned} &\mathrm{d}X(t)=\sum_{j=1}^D \Pi_j(t)(\mu_j(t)\mathrm{d}t+\sigma_j(t)^{\top}\mathrm{d}W(t))+\left(X(t)-\sum_{j=1}^D \Pi_j(t)\right)r(t)\mathrm{d}t+\left(Y(t)-\sum_{i\in {\mathcal N}_0}Z_i(t)-f(t)\right)\mathrm{d}t,\\ &X(0)=\sum_{i\in {\mathcal N}'}x_i. \end{aligned} \right. \end{equation}
Definition 3.4. Here
 $\mathscr{A}_B$
is the admissible set containing all admissible pairs
 $(\Pi,f)$
satisfying
-
1. The aggregate wealth process
$X(\! \cdot \!)$
satisfies
$H(t)X(t)+\mathrm{E}_t[\! \int_t^TH(s)(Y(s)-\sum_{i\in {\mathcal N}_0}Z_i(s))\mathrm{d}s]\ge0$
for all
$t\in {\mathcal T}$
; -
2. Each
$\Pi_{i}:\Omega\times {\mathcal T}\to \Re$
is an
$\mathbb{F}$
-progressively measurable portfolio process satisfying
$\int_0^T\Pi_{i}^2(s)\mathrm{d}s\lt\infty$
,
$\mathbb{P}$
-a.s., for each
$i=1,\ldots,D$
; -
3. The aggregate consumption process
$f:\Omega\times {\mathcal T}\to [0,+\infty)$
is an
$\mathbb{F}$
-progressively measurable process satisfying
$\int_0^T f(s)\mathrm{d}s\lt\infty$
,
$\mathbb{P}$
-a.s.; -
4. For any
$u\gt0$
,
$\mathrm{E}[\! \int_0^TU(I(t,uH(t)))\mathrm{d}t]\lt\infty$
and
$\mathrm{E}[V(J(uH(T)))]\lt\infty$
.


Recall that I(t,s) is the inverse function of
 $U_s(t,s)$
in s and J(s) is the inverse function of
 $V_s(s)$
in s. The optimal strategy for Problem B, denoted as
 $(\bar{\Pi}, \bar{f})$
, is provided in the following theorem without giving proof, which can be obtained using the standard martingale approach to stochastic optimal control. One can refer to Karatzas and Shreve (Reference Karatzas and Shreve1998) for more details.
Theorem 3.5. Let
 $\bar{\Pi}$
be the unique optimal portfolio process,
 $\bar{f}$
be the unique optimal consumption process, and
 $\bar{X}(t)$
be the corresponding aggregate wealth process whose terminal value is denoted by
 $\bar{\xi} \, :\! = \bar{X}(T)$
. Under Assumptions (A1)–(A4), the unique optimal consumption process and the corresponding terminal value of the aggregate wealth process to Problem B in the market
 $\mathcal M$
are as follows:
 \begin{equation}\bar{f}(t)=I(t,yH(t)),\end{equation}
and
 \begin{equation}\bar{\xi}=J(yH(T)),\end{equation}
where y is the unique constant that satisfies the following equation:
 \begin{equation} \sum_{i\in{\mathcal N}'}x_i+\mathrm{E}\left[\int_0^TH(t)\left(Y(t)-\sum_{i\in{\mathcal N}_0}Z_i(t)\right)\mathrm{d}t\right]=\mathrm{E}\left[\int_0^TH(t)I(t,yH(t))\mathrm{d}t+H(T)J(yH(T))\right].\end{equation}
The corresponding wealth process
 $\bar{X}(t)$
is determined as follows:
 \begin{equation*}\bar{X}(t)=\frac{1}{H(t)}\mathrm{E}\left[\int_t^T H(u)(\bar{f}(u)-Y(u))\mathrm{d}u+H(T)\bar{\xi}\Big|\mathcal{F}_t\right],\qquad t\in{\mathcal T},\end{equation*}
and the optimal portfolio
 ${\bar \Pi} (t)$
is given by
 \begin{equation*}\bar{\Pi}(t)=(\sigma(t)^{-1})^{\top}\left[\frac{\psi(t)}{H(t)}+\bar{X}(t)\theta(t)\right],\qquad t\in{\mathcal T},\end{equation*}
where
 $\psi (\! \cdot \!)$
is the unique integrand in the martingale representation
 $M(t)=x+\int_0^t \psi(u)^{\top}\mathrm{d}W(u)$
of the martingale
 \begin{equation*}M(t)\, :\! =\mathrm{E}\left[\int_0^TH(u)(\bar{f}(u)-Y(u))\mathrm{d}u+H(T)\bar{\xi}\Big|\mathcal{F}_t\right],\qquad t\in{\mathcal T}.\end{equation*}
To show the existence of the solution to Equation (3.13), let
 $\Gamma(y)$
denote the right-hand side of Equation (3.13). According to Equations (3.5) and (3.6), it holds that
 $I(t,0+)=J(0+)=\infty$
and
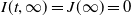 $I(t,\infty)=J(\infty)=0$
, thus
 $\Gamma(0+)=\infty$
and
 $\Gamma(\infty)=0$
. Since
 $\sum_{i\in{\mathcal N}_0}(x_i+\mathrm{E}[\! \int_0^TH(t)Z_i(t)\mathrm{d}t]) \lt x + \mathrm{ E}[\! \int_0^TH(t)Y(t)\mathrm{d}t]$
, the left-hand side of Equation (3.13) is positive. Consequently, the solution to Equation (3.13) exists. And since
 $I(t,\cdot)$
and
 $J(\! \cdot \!)$
are strictly decreasing, the solution of Equation (3.13) is unique.
From Equations (3.11) and (3.12), we observe that the expected utility
 $\mathrm{E}\left[\int_0^T U(s,\bar{f}(s))ds + V(\bar{\xi})\right]$
is monotonically decreasing in y. Therefore, to maximize this expected utility, we must minimize y. Furthermore, Equation (3.13) shows that minimizing y is equivalent to maximizing the left-hand side of Equation (3.13), that is,
 \begin{align*} \sum_{i\in{\mathcal N}'}x_i+\mathrm{E}\left[\int_0^T\! H(t)\left(Y(t)-\! \sum_{i\in{\mathcal N}_0}Z_i(t)\right)\mathrm{d}t\right]=x+\mathrm{ E}\left[\int_0^T\! H(t)Y(t)\mathrm{d}t\right]-\! \sum_{i\in{\mathcal N}_0}\left(x_i+\mathrm{E}\left[\int_0^T\! H(t)Z_i(t)\mathrm{d}t\right]\right).\end{align*}
From the second point of Definition 2.2, we have
 \begin{align*}x+\mathrm{E}\left[\int_0^TH(t)Y(t)\mathrm{d}t\right]-\sum_{i\in{\mathcal N}_0}\left(x_i+\mathrm{E}\left[\int_0^TH(t)Z_i(t)\mathrm{d}t\right]\right)\le x+\mathrm{E}\left[\int_0^TH(t)Y(t)\mathrm{d}t\right].\end{align*}
The equality condition holds if and only if
 $x_i+\mathrm{E}\left[\int_0^TH(t)Z_i(t)\mathrm{d}t\right]=0$
for each
 $i\in{\mathcal N}_0$
. Consequently, the minimization of y is achieved by setting
 $x_i+\mathrm{E}\left[\int_0^TH(t)Z_i(t)\mathrm{d}t\right]=0$
for all
 $i\in{\mathcal N}_0$
. This, together with Equation (3.13), implies that y is the unique solution to
 \begin{equation} x+\mathrm{E}\left[\int_0^TH(t)Y(t)\mathrm{d}t\right]=\mathrm{E}\left[\int_0^TH(t)I(t,yH(t))\mathrm{d}t+H(T)J(yH(T))\right].\end{equation}
3.2.2 Problem
$C_i$

In Problem
 $C_i$
,
 $i\in {\mathcal N}'$
, we assume an admissible risk exchange
 $\{Z_i,i\in {\mathcal N}\}$
is given and thus no longer a part of the control process in the model. We focus solely on the wealth process and objective of agent i,
 $i\in {\mathcal N}'$
. This allows us to determine and analyze an optimal strategy from the perspective of each agent
 $i\in {\mathcal N}'$
.
Definition 3.6. We define for each
 $i\in {\mathcal N}'$
the i-th admissible set
 $\mathscr{A}_i$
contains all pairs
 $(\pi_i,f_i)$
satisfying
-
1. The wealth process
$X_i(\! \cdot \!)$
satisfies
$H(t)X_i(t)+\mathrm{E}_t[\! \int_t^TH(s)Z_i(s)\mathrm{d}s]\ge0$
for all
$t\in {\mathcal T}$
; -
2. The portfolio process
$\pi_{i}:\Omega\times {\mathcal T}\to \Re^D$
is an
$\mathbb{F}$
-progressively measurable process satisfying
$\int_0^T\sum_{j=1}^D\pi_{ij}^2(s)\mathrm{d}s\lt\infty$
,
$\mathbb{P}$
-a.s., for each
$i \in {\mathcal N}$
; -
3. The consumption process
$f_i:\Omega\times {\mathcal T}\to [0,+\infty)$
is an
$\mathbb{F}$
-progressively measurable process satisfying
$\int_0^T f_i(s)\mathrm{d}s\lt\infty$
,
$\mathbb{P}$
-a.s., for each
$i\in {\mathcal N}_1'$
. If
$i\in {\mathcal N}_2'$
, set
$f_i(t)=0$
for all
$t\in {\mathcal T}$
; -
4. For any
$u\gt0$
,
$\mathrm{E}[\! \int_0^TU_i(I_i(uH(t)))\mathrm{d}t]\lt\infty$
and
$\mathrm{E}[V_i(J_i(uH(T)))]\lt\infty$
, for
$i\in {\mathcal N}'$
.


When the agent i’s wealth process follows Equation (2.2) and
 $Z_i$
is given (which means
 $Z_i$
is no longer a part of the strategy), agent i aims to maximize the objective
 $F_i$
, thus Problem
 $C_i$
,
 $i\in {\mathcal N}_1'$
, is given by
 \begin{equation}\max_{(\pi_i,f_i)\in\mathscr{A}_i}\mathrm{E}\left[ \int_0^T \mathrm{e}^{-\int_0^s \eta_i(u)\mathrm{d}u}U_i(f_i(s))\mathrm{d}s\right]\end{equation}
subject to Equation (2.2). Similarly, Problem
 $C_i$
,
 $i\in {\mathcal N}_2'$
, is given by
 \begin{equation}\max_{\pi_i\in\mathscr{A}_i}\mathrm{E}\left[\mathrm{e}^{-\int_0^T \eta_i(u)\mathrm{d}u}V_i(X_i(T))\right]\end{equation}
subject to Equation (2.2).
The optimal solutions to Problem
 $C_i$
are denoted by
 $(\hat{\pi}_i,\hat{f}_i,Z_i)$
,
 $i\in {\mathcal N}'$
, which can be found in Appendix B.
3.3 The optimal strategy
In this subsection, we find the optimal strategy through the following procedures. First, we determine an upper bound for the objective function in Equation (2.3). Second, we formulate a strategy and show that this strategy can attain the upper bound. Based on the attainment of the upper bound, it can be concluded that this strategy is the desired optimal strategy.
Lemma 3.7. Under Assumptions (A1)–(A4), for any given admissible risk exchange
 $\{Z_i,i\in {\mathcal N}\}$
and all
 $(\pi_i,f_i)\in\mathscr{A}_i$
,
 $i\in {\mathcal N}'$
, satisfying the wealth Equation (2.2), we have
 \begin{equation}\mathrm{E}\left[\sum_{i\in {\mathcal N}_1'} \left(\int_0^T \rho_i\mathrm{e}^{-\int_0^s \eta_i(u)\mathrm{d}u}U_i(f_i(s))\mathrm{d}s\right)+\sum_{i\in {\mathcal N}_2'} \rho_i\mathrm{e}^{-\int_0^T \eta_i(u)\mathrm{d}u}V_i(X_i(T))\right]\le \mathrm{E}\left[\int_0^T U\left(s,\bar{f}(s)\right)\mathrm{d}s+V(\bar{\xi})\right],\end{equation}
where
 $\bar{f}(t)=I(t,yH(t))$
,
 $\bar{\xi}=J(yH(T))$
, and y satisfies Equation (3.14).
Remark 3.8. Based on Lemma 3.7, we know that the maximum value of the objective functional in Problem B serves as an upper bound for that in Problem A. We conjecture that the objective functionals of Problems A and B have the same maximum value, and this conjecture will be validated in Theorem 3.10.
According to Karatzas and Shreve (Reference Karatzas and Shreve1998), given
 $f_i(t)$
,
 $\xi_i$
and
 $Z_i(t)$
, there exists a portfolio
 $\pi_i(\! \cdot \!)$
such that
 $(\pi_i, f_i)\in\mathscr{A}_i$
and
 $\xi_i=X_i(T)$
, which is given by the following lemma.
Lemma 3.9. Under Assumption (A1), suppose that
 $f_i:\Omega\times {\mathcal T}\to [0,+\infty)$
is an
 $\mathbb{F}$
-progressively measurable process satisfying
 $\mathrm{E}[\! \int_0^T f_i(s)\mathrm{d}s]\lt\infty$
,
 $\mathbb{P}$
-a.s., for each
 $i\in {\mathcal N}_1$
, and
 $f_i(t)=0$
, for each
 $i\in {\mathcal N}_2$
. Let
 $\{Z_i,i\in{\mathcal N}\}$
be an admissible risk exchange, and
 $\xi_i$
be a nonnegative
 $\mathcal{F}_T$
-measurable random variable, such that
 \begin{align}x_i+\mathrm{E}\left[\int_0^TH(u)Z_i(u)\mathrm{d}u\right]=\mathrm{E}\left[\int_0^TH(u)f_i(u)\mathrm{d}u\right],\qquad i\in {\mathcal N}_1',\end{align}
and
 \begin{align}x_i+\mathrm{E}\left[\int_0^TH(u)Z_i(u)\mathrm{d}u\right]=\mathrm{E}[H(T)\xi_i],\qquad i\in {\mathcal N}_2',\end{align}
and
 \begin{align}x_i+\mathrm{E}\left[\int_0^TH(u)Z_i(u)\mathrm{d}u\right]=0,\qquad i\in {\mathcal N}_0.\end{align}
Then there exists a portfolio process
 $\pi_i(\! \cdot \!)$
such that the pair
 $(\pi_i,f_i)\in {\mathscr A}_i$
, and
 $0 = X_i(T)$
for
 $i\in \mathcal{N}_1$
and
 $\xi_i = X_i(T)$
for
 $i\in \mathcal{N}_2$
.
In fact, Equation (3.18) ensures that the initial wealth and the new endowment together are sufficient to finance the consumption over
 ${\mathcal T}$
for each
 $i\in {\mathcal N}_1$
, and Equation (3.19) ensures that the initial wealth and the new endowment can make the terminal wealth reach
 $\xi_i$
for each
 $i\in {\mathcal N}_2$
.
We now establish
 $\nu^*=\{(\pi_i^*,\, f_i^*,Z_i^*),i\in {\mathcal N}\}$
by the following method.
Let
 \begin{equation} f_{i}^*(t) \, :\! =\left\{\begin{aligned} & I_{i}\left(\rho_{i}^{-1}{\textrm e}^{\int_{0}^t \eta_{i}(u){\textrm d}u}yH(t)\right),\quad i \in {\mathcal N}_{1}',\\ & 0,\qquad \qquad \qquad \qquad \quad \quad i\in {\mathcal N}_{1}/{\mathcal N}_{1}', \end{aligned} \right.\end{equation}
and
 \begin{equation} \xi_{i}^* \, :\! =\left\{\begin{aligned} & 0,\qquad & i\in{\mathcal N}/{\mathcal N}_{2}', \\ & J_{i}\left(\rho_{i}^{-1}{\textrm e}^{\int_{0}^T \eta_{i}(u){\textrm d}u}yH(T)\right),\qquad & i\in{\mathcal N}_{2} ,\end{aligned}\right.\end{equation}
where y satisfies Equation (3.14). Suppose that
 $\{Z_i^*,i\in {\mathcal N}\}$
is an admissible risk exchange satisfying
 \begin{align}\mathrm{E}\left[\int_0^TH(u)Z_i^*(u)\mathrm{d}u\right]=-x_i,\qquad i\in {\mathcal N}_0,\end{align}
 \begin{align}\mathrm{E}\left[\int_0^TH(u)Z_i^*(u)\mathrm{d}u\right]=\mathrm{E}\left[\int_0^TH(u)I_i\left(\rho_i^{-1}\mathrm{e}^{\int_0^u \eta_i(s)\mathrm{d}s}yH(u)\right)\mathrm{d}u\right]-x_i,\qquad i\in {\mathcal N}_1',\end{align}
and
 \begin{align}\mathrm{E}\left[\int_0^TH(u)Z_i^*(u)\mathrm{d}u\right]=\mathrm{E}\left[H(T)J_i\left(\rho_i^{-1}\mathrm{e}^{\int_0^T \eta_i(u)\mathrm{d}u}yH(T)\right)\right]-x_i,\qquad i\in {\mathcal N}_2',\end{align}
where y is the solution to Equation (3.14).
Theorem 3.10. Under Assumptions (A1)–(A4), let the constant y satisfy Equation (3.14). Define
 $f_i^*$
,
 $\xi_i^*$
according to Equations (3.21) and (3.22), respectively, and let
 $\{Z_i^*,i\in {\mathcal N}\}$
denote an admissible risk exchange satisfying Equations (3.23), (3.24), and (3.25). Suppose further that for each
 $i\in {\mathcal N}$
, the pair
 $(\pi_i^*,\, f_i^*)\in \mathscr{A}_i$
and
 $\xi_i^*=X_i^*(T)$
, where
 $X_i^*(\! \cdot \!)=X_i^{\nu^*}(\! \cdot \!)$
, with
 $\nu^*\, :\! =\{(\pi_i^*,f_i^*,Z_i^*),i\in {\mathcal N}\}$
. Then
 $\nu^*\in \mathscr{A}$
, and
 $\nu^*$
is optimal for Problem A.
Proof. See Appendix A.
Now we have found an optimal strategy for Problem A. We refer to the admissible risk exchange
 $\{Z_i^*,i\in {\mathcal N}\}$
satisfying Equations (3.23)–(3.25) as a Pareto-optimal risk exchange. In fact, Equations (3.23)–(3.25) are obtained from Equations (3.18)–(3.20), and they imply that the selection of a Pareto-optimal risk exchange is based on the optimal consumption and terminal wealth.
Remark 3.11. Note that we have not provided an explicit form for
 $Z_i^*(t)$
because any
 $Z_i^*(t)$
satisfying Equations (3.23)–(3.25) and Definition 2.2 can be a Pareto-optimal risk exchange. In Subsection 3.4, we will present several cases of
 $\{Z_i^*(t),i\in{\mathcal N}\}_{t\in{\mathcal T}}$
in explicit forms.
Remark 3.12. The analysis reveals that the optimal consumption processes
 $f_i^*(t)$
remain independent of the specific risk exchange structure, while the optimal portfolios
 $\pi^*_i(t)$
are notably influenced by the selected structure of risk exchange.
Proposition 3.13. For
 $\nu^*$
in Theorem 3.10, if
 $\{Z_i^*,i\in {\mathcal N}'\}$
is applied in Problem
 $C_i$
,
 $(\pi_i^*,f_i^*)$
is the optimal solution to each Problem
 $C_i$
,
 $i\in {\mathcal N}'$
.
Proof. See Appendix B.
Remark 3.14. Proposition 3.13 demonstrates that when the entire economy achieves Pareto optimality, each individual agent’s investment and consumption strategies also become optimal, given the new endowment process. This rules out the existence of any scenarios where certain agents must sacrifice their interests to facilitate the attainment of Pareto optimality for the whole economy.
Remark 3.15. For agents with positive weights, participation constraints are conditions under which agent
 $i\in{\mathcal N'}$
agrees to participate in risk exchange if and only if the utility derived from the risk exchange endowment process
 $Z^*_i$
is at least the utility associated with retaining their initial endowment process
 $Y_i$
. We consider the situation where the initial endowment processes
 $\{Y_i,i\in {\mathcal N'}\}$
are applied to Problem
 $C_i$
,
 $i\in {\mathcal N}'$
. The optimal solutions to Problem
 $C_i$
,
 $i \in {\mathcal N'}$
, are denoted by
 $(\hat{\pi}_i,\hat{f}_i,Y_i)$
,
 $i\in {\mathcal N}'$
. For each agent
 $i\in {\mathcal N}_0$
, given the initial endowment process
 $\{Y_i(t)\}_{t\in{\mathcal T}}$
, we may set
 $\hat{\pi}_i(t)=\hat{f}_i(t)=0$
for
 $t\in{\mathcal T}$
. Then we set
 $\hat{\nu}\, :\! =\{(\hat{\pi}_i,\hat{f}_i,Y_i),i\in {\mathcal N}\}$
. According to Appendix B, we have
 \begin{equation*} \left\{ \begin{aligned} &\hat{f}_i(t)=I_i\left(y_i\mathrm{e}^{\int_0^t\eta_i(u)\mathrm{d}u}H(t)\right),\qquad i\in {\mathcal N}_1',\\ &\hat{\xi}_i=J_i\left(y_i\mathrm{e}^{\int_0^t\eta(u)\mathrm{d}u}H(T)\right),\qquad i\in {\mathcal N}_2', \end{aligned} \right. \end{equation*}
where the constants
 $y_i, i\in {\mathcal N}'$
, are unique solutions to
 \begin{equation*} \left\{ \begin{aligned} &x_i+\mathrm{E}\left[\int_0^TH(t)Y_i(t)\mathrm{d}t\right]=\mathrm{E}\left[\int_0^TH(t)I_i\left(y_i\mathrm{e}^{\int_0^t\eta_i(u)\mathrm{d}u}H(t)\right)\mathrm{d}t\right],\qquad i\in {\mathcal N}_1', \\ &x_i+\mathrm{E}\left[\int_0^TH(t)Y_i(t)\mathrm{d}t\right]=\mathrm{E}\left[H(T)J_i\left(y_i\mathrm{e}^{\int_0^T\eta_i(u)\mathrm{d}u}H(T)\right)\right],\qquad i\in {\mathcal N}_2'. \end{aligned} \right. \end{equation*}
In comparison with Equations (3.21) and (3.22), it follows that
 $ f_i^*(t) \ge \hat{f}_i(t) $
for all
 $ i \in \mathcal{N}_1' $
and
 $ \xi_i^* \ge \hat{\xi}_i $
for all
 $ i \in \mathcal{N}_2' $
if and only if
 $ y \le \rho_i y_i $
for all
 $ i \in \mathcal{N}' $
, where y satisfies Equation (3.14). Consequently, the utility levels satisfy
 $ F_i(\nu^*) \ge F_i(\hat{\nu}) $
if and only if
 $ y \le \rho_i y_i $
for all
 $ i \in \mathcal{N}' $
. Therefore, the participation constraints for agents with positive weights can be expressed as
 $ y \le \rho_i y_i $
,
 $ \forall i \in \mathcal{N}' $
.
3.4 Cases of Pareto-optimal risk exchange
In this subsection, we present four distinct cases of Pareto-optimal risk exchange, each of which fulfills the conditions specified in Equations (3.23)–(3.25). However, the relaxation of these conditions implies that the proper risk exchange arrangement is not unique. Hence, agents have the flexibility to select different cases of risk exchange in accordance with their individual demands and preferences.
For simplicity, let
 $\zeta$
denote an n-dimensional vector whose i-th element is given by
 \begin{equation} \zeta_{i} \, :\! = \left\{\begin{aligned} & \mathrm{E}\left[\int_{0}^TH(u)f_{i}^*(u)\mathrm{d}u\right]-x_{i}, & i\in {\mathcal N}_{1}', \\ & \mathrm{E}[H(T)\xi_{i}^*]-x_{i},& i \in {\mathcal N}_{2}',\\ &-x_{i}, & i \in{\mathcal N}_{0}.\end{aligned}\right.\end{equation}
Then according to Equations (3.23)–(3.25), it holds for all
 $i\in {\mathcal N}$
,
 \begin{equation*}\mathrm{E}\left[\int_0^TH(u)Z_i^*(u)\mathrm{d}u\right]=\zeta_i.\end{equation*}
In the remaining part of this subsection, we present four general scenarios of specific risk exchange mechanisms to accommodate diverse requirements. In Case 1, agents have an option to distribute the aggregate endowment process in a fixed proportion, or one agent can shoulder all risks while keeping the endowment processes of all other agents constant. Case 2 ensures that the endowment processes of all agents, except one, remain above a certain threshold. Case 3 involves each agent receiving a fixed proportion from each of original endowment processes and merging them into a new endowment process. In Case 4, the new endowment processes allocated to the first type of agents are based on their optimal consumption processes, potentially enhancing the security of their consumption processes.
3.4.1 Case 1
In this case, we introduce a benchmark stochastic process, in which all agents, except one, are endowed with risk exchange endowment processes that are proportional to this benchmark. This framework encompasses two specific and practically relevant scenarios.
The first scenario describes the situation where all risk exchange endowment processes are proportional to the aggregate endowment process. This approach offers a natural and straightforward mechanism for distributing the aggregate endowment/resource in fixed proportions, maintaining consistency across agents.
The second scenario considers the case where all but one agent receive constant endowment processes. This structure is tailor-made for agents that prioritize exceptionally stable income streams. Those agents typically operate in capital-intensive industries with long-term operational horizons and high requirements for financial stability; examples include the utility sector, life insurance companies, and consumer staples firms known for maintaining stable dividend policies. These agents often operate under regulatory oversight or investor expectations that strongly favor minimal volatility.
Given
 $j\in {\mathcal N}$
, set
 ${\mathcal N}_{-j}=\{i\in {\mathcal N}:i\ne j\}$
and let
 $\{\varrho_i(t)\}_{t\in{\mathcal T}}, i\in {\mathcal N}_{-j}$
, denote an
 $\mathbb{F}$
-adapted benchmark process satisfying
 $\mathrm{E}[\! \int_0^TH(t)\varrho_i(t)\mathrm{d}t]\lt\infty$
and
 $\mathrm{E}[\! \int_0^TH(t)\varrho_i(t)\mathrm{d}t]\ne 0$
. We can take
 \begin{equation*}Z_i^*(t)=p_i \varrho_i(t),\qquad i\in {\mathcal N}_{-j},\end{equation*}
and
 \begin{equation*}Z_j^*(t)=Y(t)-\sum_{i\in {\mathcal N}_{-j}}Z_i^*(t),\end{equation*}
where
 $p_i$
is given by
 \begin{equation*}p_i=\frac{\zeta_i}{\mathrm{E}\left[\int_0^TH(u)\varrho_i(u)\mathrm{d}u\right]},\qquad i\in {\mathcal N}_{-j}.\end{equation*}
In fact,
 $\{\varrho_i(t)\}_{t\in{\mathcal T}}, i\in {\mathcal N}_{-j}$
, has a wide range of choices. For example,
 $\varrho_i(t)$
can be 1,
 $\frac{1}{H(t)}$
or Y(t). When
 $\varrho_i(t)$
is selected as Y(t) (assuming that
 $\mathrm{E}[\! \int_0^TH(t)Y(t)\mathrm{d}t]\ne 0$
), we do not need to rule out j, that is, for all
 $i\in {\mathcal N}$
,
 \begin{equation*}p_i=\frac{\zeta_i}{\mathrm{E}\left[\int_0^TH(u)Y(u)\mathrm{d}u\right]},\end{equation*}
and
 \begin{equation*}Z_i^*(t)=p_i Y(t).\end{equation*}
Here,
 $p_i,i\in {\mathcal N}$
, is called the allocation ratio for agent i. This situation is of particular interest since the new endowment process after risk exchange is proportional to the aggregate endowment process Y(t), which is natural in business practice. For example, revenue sharing agreements, which are common for firms in a supply chain, require retailers to share profits with suppliers in a fixed ratio (Cachon and Lariviere, Reference Cachon and Lariviere2005).
On the other hand, if
 $\varrho_i(t)=1, i\in {\mathcal N}_{-j}$
, then
 $Z_i(t)$
is a constant for each
 $i\in {\mathcal N}_{-j}$
and we have
 \begin{equation*}Z_i^*(t)=p_i,\qquad i\in {\mathcal N}_{-j},\end{equation*}
and
 \begin{equation*}Z_j^*(t)=Y(t)-\sum_{i\in {\mathcal N}_{-j}}Z_i^*(t),\end{equation*}
where
 \begin{equation*}p_i=\frac{\zeta_i}{\mathrm{E}\left[\int_0^TH(u)\mathrm{d}u\right]},\qquad i\in {\mathcal N}_{-j}.\end{equation*}
In this case, agent i (
 $i\ne j$
) has a constant endowment process
 $p_i$
, while agent j’s endowment process
 $Y(t)-\sum_{i\in {\mathcal N}_{-j}}p_i$
has the same variance as the total income process Y(t). Therefore, agent j assumes the role of an “insurer,” effectively accepting all risks from other agents with the objective of stabilizing the endowment processes of those other agents. Although agent j relatively bears great risks, regardless of the risk exchange strategy, its endowment process always satisfies Equations (3.23)–(3.25) and does not affect the value of its utility
 $F_i(\nu^*)$
. Thus, agent j may not necessarily suffer significant losses.
3.4.2 Case 2
In this case, we establish a constrained Pareto-optimal risk exchange, corresponding to that in the static model (see Bühlmann and Jewell, Reference Bühlmann and Jewell1979). Each agent, except one, is endowed with a risk exchange endowment process that includes a minimum guarantee. This guarantee is chosen individually by each agent, subject to an upper limit. Compared to the second scenario in Case 1, this setting is better suited for agents who seek to avoid excessively low endowment levels while being able to tolerate a certain degree of volatility. It describes a preference that balances income stability and flexibility in risk exposure.
Given
 $j\in {\mathcal N}$
, we aim to construct
 $\{Z_i^*(t), i\in {\mathcal N}_{-j}\}_{t\in{\mathcal T}}$
such that
 $Z_i^*(t)\ge A_i$
for each t, where
 $A_i$
is a constant. Then we discuss the range of
 $A_i$
and the structure of
 $\{Z_i^*(t),i\in {\mathcal N}_{-j}\}_{t\in{\mathcal T}}$
.
If
 $\varrho_i(t)$
is selected as 1 in Case 1,
 $i\in {\mathcal N}_{-j}$
, then
 \begin{equation*}Z_i^*(t)=p_i,\qquad i\in {\mathcal N}_{-j},\end{equation*}
where
 \begin{equation*}p_i=\frac{\zeta_i}{\mathrm{E}\left[\int_0^TH(u)\mathrm{d}u\right]},\qquad i\in {\mathcal N}_{-j}.\end{equation*}
In this situation, all agents except j have a constant new endowment process.
If
 $Z_i^*(t)\ge A_i$
for each t and
 $i\in {\mathcal N}_{-j}$
, then it holds that
 \begin{align*}\zeta_i=\mathrm{E}\left[\int_0^TH(u)Z_i^*(u)\mathrm{d}u\right]\ge \mathrm{E}\left[\int_0^TH(u)A_i\mathrm{d}u\right]=A_i\mathrm{E}\left[\int_0^TH(u)\mathrm{d}u\right],\qquad i\in {\mathcal N}_{-j}.\end{align*}
Then
 \begin{equation}A_i\le \frac{\zeta_i}{\mathrm{E}\left[\int_0^TH(u)\mathrm{d}u\right]}=p_i,\qquad i\in {\mathcal N}_{-j}.\end{equation}
We say that Equation (3.27) is the constraint for
 $A_i,i\in {\mathcal N}_{-j}$
.
Denote
 $Z_i^*(t)-A_i$
by
 $B_i(t)$
. Then we have
 $Z_i^*(t)=A_i+B_i(t)$
. It holds that
 \begin{equation}\mathrm{E}\left[\int_0^TH(u)B_i(u)\mathrm{d}u\right]=\zeta_i-A_i\mathrm{E}\left[\int_0^TH(u)\mathrm{d}u\right],\qquad i\in {\mathcal N}_{-j},\end{equation}
which is the condition that
 $B_i(t)$
should satisfy.
Let
 $\{\bar{D}_i(t)\}_{t\in{\mathcal T}}, i\in {\mathcal N}_{-j}$
, denote a positive
 $\mathbb{F}$
-adapted process satisfying
 $0 \lt \mathrm{E}[\! \int_0^TH(t)\bar{D}_i(t)\mathrm{d}t]\lt\infty$
. Then we assume that
 \begin{equation}B_i(t)=\bar{p}_i\bar{D}_i(t),\qquad i\in {\mathcal N}_{-j},\end{equation}
where
 $\bar{p}_i$
is a constant that can be calculated by substituting Equation (3.29) into Equation (3.28), resulting in
 \begin{equation*}\bar{p}_i=\frac{\zeta_i-A_i\mathrm{E}\left[\int_0^TH(u)\mathrm{d}u\right]}{\mathrm{E}\left[\int_0^TH(u)\bar{D}_i(u)\mathrm{d}u\right]},\qquad i\in {\mathcal N}_{-j}.\end{equation*}
It follows from the inequality in Equation (3.27) that
 ${\bar p}_i \ge 0$
, for all
 $i \in {\mathcal N}_{-j}$
. This, together with the definition of
 $B_i (t)$
in Equation (3.29), imply that
 $B_i(t)$
is nonnegative for each t,
 $i\in {\mathcal N}_{-j}$
. Therefore
 $Z_i^*(t)\ge A_i$
for each t,
 $i\in {\mathcal N}_{-j}$
.
It is worth noting that no constraints are imposed on agent j. This decision is attributed to the fact that for a fixed time t, the range of Y(t) spans the entire real number line
 $\Re$
. Introducing a constraint
 $A_j$
for agent j could potentially lead to situations where
 $Y(t)\le\sum_{i\in {\mathcal N}}A_i$
, thereby violating the established constraints. To avoid such issues, we refrain from imposing any constraints on agent j.
3.4.3 Case 3
In this case, each agent’s risk exchange endowment process is expressed as a linear combination of all initial endowment processes. The first scenario in Case 1 can be regarded as a special case of this setting, where the combination weights are identical across all initial endowments. Compared to the first scenario in Case 1, this case is less restrictive and offers greater flexibility in risk exchange.
Assume that there exists a constant matrix
 $p=(p_{ij})_{n\times n}$
, such that
 \begin{equation}Z_i^*(t)=\sum_{j\in {\mathcal N}}p_{ij}Y_j(t),\qquad i\in {\mathcal N}\end{equation}
and
 \begin{equation*}\sum_{i\in {\mathcal N}}p_{ij}=1,\end{equation*}
for each
 $j\in {\mathcal N}$
. In this case, agent i receives a proportion
 $p_{ij}$
of the original endowment process
 $Y_j(t)$
from the agent j.
Let
 $\bar{Y}$
be an n-dimensional vector whose i-th element is
 \begin{equation*}\bar{Y}_i=\mathrm{E}\left[\int_0^TH(t)Y_i(t)\mathrm{d}t\right].\end{equation*}
Then p satisfies
 \begin{equation}p\bar{Y}=\zeta,\end{equation}
representing n linear equations. In fact, the n-th equation of linear Equations (3.31) can be deduced according to Equations (3.23)–(3.25) and the other
 $n-1$
equations of the system (3.31), which means it does not provide new information. Therefore, the degree of freedom of p is at least
 $n^2-2n+1$
. For some special situations, Equation (3.31) may fail to hold, for example, if
 $\bar{Y}=0$
and
 $F\ne 0$
, then p does not exist.
3.4.4 Case 4
In this case, agents of the first type, those with a consumption process, receive risk exchange endowment processes that are tailored to align with their consumption needs. Specifically, the endowment processes are adjusted in accordance with the agents’ optimal consumption trajectories. This framework is particularly suitable for agents concerned with closely matching endowment inflows to consumption outflows, such as firms with limited capacity for wealth accumulation but significant pressure to maintain regular payouts. The setting requires that both
 $n_1\ge 1$
and
 $n_2\ge 1$
.
For agents of the first type, we set
 \begin{equation*}Z_i^*(t)=f_i^*(t)-\frac{x_i}{H(t)T},\qquad i\in {\mathcal N}_1.\end{equation*}
For agent
 $i\in {\mathcal N}_1$
,
 $Z_i^*(t)$
comprises two elements: the first part represents the optimal consumption, while the second part is linked to the initial wealth
 $x_i$
. Agent i consumes the quantity
 $f_i^*(t)$
, and the second part ensures that the wealth process reaches 0 at the terminal time T. In this case, agents are aware that the new endowment processes they receive can effectively offset the consumption processes, thereby easing potential consumption pressure.
For agents of the second type, given
 $j\in {\mathcal N}_2$
, set
 \begin{equation*}Z_i^*(t)=\frac{\zeta_i}{H(t)T},\qquad i\in {\mathcal N}_2\cap{\mathcal N}_{-j},\end{equation*}
and
 \begin{equation*}Z_j^*(t)=Y(t)-\sum_{i\in {\mathcal N}_{-j}}Z_i^*(t).\end{equation*}
Note that for
 $i\in {\mathcal N}_2$
and
 $i\ne j$
,
 $Z_i^*(t)$
is a fixed proportion of
 $\frac{1}{H(t)}$
. Agent j plays the role of balancing the system by ensuring that the aggregate endowment process remains equal to Y(t), given the endowment processes of all other agents.
4. Application to target benefit pension
In this section, we investigate a simple case with
 ${\mathcal N}_1=\{1\}$
and
 ${\mathcal N}_2=\{2\}$
. Here agents 1 and 2 represent a target benefit pension and a cooperative entity, respectively. Since each
 ${\mathcal N}_i, i\in\{1,2\}$
has only one element, the discounted aggregate utility functions are
 $U(t,s)=\rho_1\mathrm{e}^{\int_0^t\eta_1(u)\mathrm{d}u}U_1(s)$
and
 $V(s)=\rho_2\mathrm{e}^{\int_0^T\eta_2(u)\mathrm{d}u}V_2(s)$
with
 $\rho_1$
and
 $\rho_2$
being positive.
In what follows, we first establish the stochastic endowment processes for both the target benefit pension fund and the cooperative entity. Then we rewrite the control problem and its solution and give some particular examples of Pareto-optimal risk exchange. Finally, we illustrate a special situation with a constant relative risk aversion (CRRA) utility for numerical analysis.
4.1 Target benefit pension
In this subsection, we introduce a collective target benefit pension (TBP) plan over the interval
 ${\mathcal T}=[0,T]$
, where individuals join the plan over time. From a theoretical perspective, the initial endowment process of the TBP fund is determined by the total contributions from new members minus the total benefits paid to all retired members at each time point. The total benefits are affected by longevity risk, as reflected in fluctuating increases in life expectancy. Our analysis begins with examining the benefits associated with an individual member in the TBP plan, which allows us to determine the per-member profit. The initial endowment process of the TBP fund is then modeled as the product of this individual profit and the plan’s entry rate.
When a member of the TBP plan retires at time t, she contributes a lump sum amount c(t) (or the present value of her accumulated contributions) and, in return, begins receiving a stream of payments that continues until her death. At time
 $s\ge t$
, the actual benefit comprises a target benefit annuity denoted as
 $\bar{b}(t,s)$
that is determined at time t, and an individual adjustment w(s) that can be modified by the agent at time s. We denote the payment stream at time s for an individual who retires at time t as b(t,s):
 \begin{equation*}b(t,s)=\bar{b}(t,s)+w(s),\qquad s\ge t.\end{equation*}
Next, it is necessary to determine the values of b(t,s) and w(s). We assume that the target benefit annuity
 $\bar{b}(t,s)$
has an initial value
 $\bar{b}(t)$
and evolves over time according to a continuously compounded risk-free interest rate r (t) as follows:
 \begin{equation*}\bar{b}(t,s)=\bar{b}(t)\mathrm{e}^{\int_t^s r(u) \mathrm{d}u},\qquad s\ge t.\end{equation*}
The individual adjustment w(t) corresponds to an overall adjustment distributed equally across all retired members. In the following analysis, we explain f(t) as the overall adjustment process, rather than as the consumption process. Maximizing this overall adjustment process effectively enhances the actual benefits for all members, which is a key objective in the design of a TBP plan. From the perspective of the pension fund, the agent makes decisions regarding the overall adjustment f(t) at time t and allocates it equally among all retirees. The total number of members in the pension fund at time t is denoted as R(t), where
 $\{ R (t) \}_{t \in {\mathcal T}}$
could be a stochastic process adapted to an observable filtration. Then, all retired members, irrespective of their ages, receive the same individual adjustment amount at time t, that is,
 \begin{equation*}w(t)=\frac{f(t)}{R(t)}.\end{equation*}
We denote the average remaining lifetime of the member who retires at time t as G(t). The present value of the overall target benefit annuity over the remaining lifetime can then be calculated as follows:
 \begin{equation*}k(t)=\int_t^{t+G(t)}\bar{b}(t,s)\mathrm{e}^{-\int_t^s r(u) \mathrm{d}u}\mathrm{d}s=\bar{b}(t)G(t).\end{equation*}
Therefore, neglecting the adjustment term, the profit for the pension fund from one contract at time t is given by
 $c(t) - k(t)$
. Here,
 $\{ n (t) \}_{t \in {\mathcal T}}$
represents the entry rate of the pension fund, which could be a stochastic process adapted to an observable filtration. We can then approximate the profit rate (the profit per unit of time) of the pension fund at time t as follows:
 \begin{equation}Y_1(t)=n(t)(c(t)-\bar{b}(t)G(t)).\end{equation}
The longevity risk model adopted in this paper is based on the framework proposed by Tao et al. (Reference Tao, Rong and Zhao2025), which captures the trend of steadily increasing human life expectancy accompanied by stochastic fluctuations. We model longevity risk using an Ornstein–Uhlenbeck (O-U) process that can capture the mean-reverting behavior of the average remaining lifetime, following Tao et al. (Reference Tao, Rong and Zhao2025). Let Q(t) denote
 $G(t)-\bar{G}(t)$
, where
 $\bar{G}(t)$
is the fitted curve of G(t). Then we assume that Q(t) satisfies the following OU process:
 \begin{equation}\left\{\begin{aligned}&\mathrm{d}Q(t)=-aQ(t)\mathrm{d}t +\sigma_g\mathrm{d}W_g(t),\\&Q(0)=0,\end{aligned}\right.\end{equation}
where
 $a\gt0$
is the speed of mean-reversion,
 $\sigma_g\gt0$
is the volatility rate and
 $\{ W_g (t) \}_{t \in {\mathcal T}}$
is an
 $\mathbb{F}$
-adapted standard Browinan motion. While random factors may cause G(t) to deviate from
 $\bar{G}(t)$
, the mean-reverting property of the OU process attracts it towards
 $\bar{G}(t)$
. Suppose that
 $\bar{G}(t)=\beta t+\alpha$
, where
 $\alpha\gt0$
is the initial remaining lifetime and
 $\beta\gt0$
is the increasing speed of the remaining lifetime.
4.2 The cooperative entity
In this subsection, we establish a model for the cooperative entity that exchanges risks with the target benefit pension fund. We assume that the original endowment process of the entity is modeled by a geometric Brownian motion:
 \begin{equation}\left\{\begin{aligned}&\mathrm{d}Y_2(t)=Y_2(t)(m\mathrm{d}t+L\mathrm{d}W_c(t)),\\&Y_2(0)=N,\end{aligned}\right.\end{equation}
where
 $m\gt0$
is the earning rate,
 $N\gt0$
is the initial value of
 $Y_2(t)$
,
 $\{W_c(t)\}_{t\in \mathcal T}$
is an
 $\mathbb{F}$
-adapted standard Brownian motion, and
 $L\in \Re^+$
is the volatility of
 $Y_2(t)$
. Here, we assume that
 $\{ W_g (t) \}_{t \in {\mathcal T}}$
and
 $\{ W_c (t) \}_{t \in {\mathcal T}}$
are independent under the probability measure
 $\mathbb{P}$
.
The stochastic income of the cooperative entity, represented by the endowment process
 $Y_2(t)$
, can be influenced by various sources of fluctuations, such as economic conditions, market demand, climate change, competitive pressure, consumer preferences, and internal management issues. For simplicity, we interpret this as a source of “income risk”. This designation draws inspiration from He (Reference He2009), where firm size is modeled as a geometric Brownian motion. Within the framework of the risk exchange mechanism, both the pension fund and the cooperative entity mutually bear longevity risk and income risk.
It is also assumed that the cooperative belongs to Type 2, indicating it does not employ a consumption strategy and aims to maximize the expected terminal wealth utility. This characterization resembles an entity without a dividend plan, where agent 2 stands to benefit from terminal wealth. Hence, agent 2 is motivated to augment terminal wealth. For instance, certain funds prioritize terminal time-point assets over dividends, as exemplified by defined contribution pension funds. In such funds, members contribute a fixed portion of their salaries and receive substantial payments upon retirement. If the salary process follows a geometric Brownian motion, then the contribution process, which is a fixed proportion of the salary process, is also a geometric Brownian motion and can be characterized by
 $Y_2(\! \cdot \!)$
.
4.3 Control problem
In this subsection, we formulate the stochastic control problem with the objective of maximizing the utilities of both the pension fund and the cooperative entity in a Pareto-optimal manner. The strategies to be determined in this problem include the allocation of investments between the money market account and risky securities, the overall adjustment for TBP members, and the structure of risk exchange. This stochastic control problem can be conceptualized as a game between the pension fund and the cooperative entity, and our goal is to identify the Pareto-optimal strategy.
We assign the label “agent 1” to the pension fund and “agent 2” to the cooperative entity. The wealth processes of both agents are contingent on the returns from investments made in the money market and risky securities, as well as the two agents’ new endowment processes, denoted as
 $\{Z_1(t)\}_{t\in{\mathcal T}}$
and
 $\{Z_2(t)\}_{t\in{\mathcal T}}$
. Additionally, agent 1 is required to make continuous overall adjustment to the members, while agent 2 is not subject to this obligation.
Let
 $x_1$
and
 $x_2$
denote the initial wealth of agent 1 and agent 2, and
 $X_1(t)$
and
 $X_2(t)$
denote their wealth processes, respectively. Then the evolutions of
 $\{ X_1 (t) \}_{t \in {\mathcal T}}$
and
 $\{ X_2 (t) \}_{t \in {\mathcal T}}$
are governed by the following stochastic differential equations:
 \begin{equation} \left\{ \begin{aligned} &\mathrm{d}X_1(t)=\sum_{j=1}^D \pi_{1j}(t)(\mu_j(t)\mathrm{d}t+\sigma_j(t)^{\top}\mathrm{d}W(t))+\left(X_1(t)-\sum_{j=1}^D \pi_{1j}(t)\right)r(t)\mathrm{d}t+(Z_1(t)-f(t))\mathrm{d}t,\\ &X_1(0)=x_1. \end{aligned} \right. \end{equation}
and
 \begin{equation} \left\{ \begin{aligned} &\mathrm{d}X_2(t)=\sum_{j=1}^D \pi_{2j}(t)(\mu_j(t)\mathrm{d}t+\sigma_j(t)^{\top}\mathrm{d}W(t))+\left(X_2(t)-\sum_{j=1}^D \pi_{2j}(t)\right)r(t)\mathrm{d}t+Z_2(t)\mathrm{d}t,\\ &X_2(0)=x_2. \end{aligned} \right. \end{equation}
Especially, we say the strategy
 $\nu\, :\! =\{\pi_1(t),\pi_2(t),f(t),Z_1(t),Z_2(t)\}_{t\in{\mathcal T}}$
is admissible if it satisfies Definition 2.4.
The objectives of the pension fund and the cooperative entity diverge. The pension fund seeks to maximize the expected value of the discounted total adjustment, given by
 $\mathrm{E}[\! \int_0^T \mathrm{e}^{-\int_0^s \eta_1(u)\mathrm{d}u}U_1(f(s))\mathrm{d}s]$
. In doing so, it can optimize the overall benefits for the TBP members within the interval
 ${\mathcal T}$
, while simultaneously increasing the attractiveness of the TBP pension fund by elevating the value of
 $\mathrm{E}[\! \int_0^T \mathrm{e}^{-\int_0^s \eta_1(u)\mathrm{d}u}U_1(f(s))\mathrm{d}s]$
. Conversely, the cooperative entity aims to maximize the expected utility of the terminal wealth, denoted by
 $\mathrm{E}[V_2(X_2(T))]$
. This objective aligns with the cooperative entity’s absence of a dividend plan, where agent 2 stands to gain greater profits from increased terminal wealth. Then the problem can be written as
 \begin{align*}\max_{\nu\in \mathscr{A}} \mathrm{E}\left[\rho_1\int_0^T \mathrm{e}^{-\int_0^s \eta_1(u)\mathrm{d}u}U_1(f(s))\mathrm{d}s+\rho_2\mathrm{e}^{-\int_0^T \eta_2(u)\mathrm{d}u}V_2(X_2(T))\right].\end{align*}
Noting that
 $U(t,s)=\rho_1\mathrm{e}^{-\int_0^t\eta_1(u)\mathrm{d}u}U_1(s)$
and
 $V(s)=\rho_2\mathrm{e}^{-\int_0^T\eta_2(u)\mathrm{d}u}V_2(s)$
, this problem can also be written as
 \begin{align*}\max_{\nu\in \mathscr{A}} \mathrm{E}\left[\int_0^T U(s,f(s))\mathrm{d}s+V(X_2(T))\right].\end{align*}
By Theorem 3.10, we obtain the solution to the above problem. Specifically, the optimal overall adjustment process and the optimal terminal wealth are given by
 \begin{equation}f^*(t)=I(\mathrm{e}^{\int_0^t \eta_1(u)\mathrm{d}u}yH(t)),\end{equation}
and
 \begin{equation*}\xi^*=J(\mathrm{e}^{\int_0^T \eta_2(u)\mathrm{d}u}yH(T)),\end{equation*}
respectively, where y satisfies
 \begin{equation} x+\mathrm{E}\left[\int_0^TH(t)Y(t)\mathrm{d}t\right]=\mathrm{E}\left[\int_0^TH(t)I(t,yH(t))\mathrm{d}t+H(T)J(yH(T))\right].\end{equation}
The Pareto-optimal risk exchange processes
 $\{Z_1^*(t)\}_{t\in{\mathcal T}}$
and
 $\{Z_2^*(t)\}_{t\in{\mathcal T}}$
satisfy
 \begin{align}\mathrm{E}\left[\int_0^TH(u)Z_1^*(u)\mathrm{d}u\right]=\mathrm{E}\left[\int_0^TH(u)f^*(u)\mathrm{d}u\right]-x_1,\end{align}
and
 \begin{align}\mathrm{E}\left[\int_0^TH(u)Z_2^*(u)\mathrm{d}u\right]=\mathrm{E}[H(T)\xi^*]-x_2.\end{align}
As demonstrated in the previous section, the pair of Pareto-optimal risk exchange processes is not unique. In Subsection 4.4, we will provide several examples of the
 $\{Z_1^*(t)\}_{t\in{\mathcal T}}$
and
 $\{Z_2^*(t)\}_{t\in{\mathcal T}}$
that satisfy the above conditions.
The optimal wealth process
 $X^*_1(t)$
is
 \begin{equation*}X^*_1(t)=\frac{1}{H(t)}\mathrm{E}\left[\int_t^T H(u)(f^*(u)-Z_1^*(u))\mathrm{d}u\Big|\mathcal{F}_t\right],\qquad t\in{\mathcal T}.\end{equation*}
The optimal portfolio
 $\pi^*_1$
is given by
 \begin{equation}\pi^*_1(t)=\left(\sigma(t)^{-1}\right)^{\top}\left[\frac{\hat{\psi}_1(t)}{H(t)}+X^*_1(t)\theta(t)\right],\end{equation}
where we recall that
 $\theta (t)$
is the market price of risk at time t, and
 $\hat{\psi}_1(\! \cdot \!)$
is the integrand in the stochastic integral representation
 $\hat{M}_1(t)=x_1+\int_0^t \hat{\psi}_1(u)^{\top}\mathrm{d}W(u)$
of the martingale
 \begin{equation*}\hat{M}_1(t)\, :\! =\mathrm{E}\left[\int_0^TH(u)\left(f^*(u)-Z_1^*(u)\right)\mathrm{d}u\Big|\mathcal{F}_t\right],\qquad t\in{\mathcal T}.\end{equation*}
The optimal wealth process
 $X^*_2(t)$
is
 \begin{equation*}X^*_2(t)=\frac{1}{H(t)}\mathrm{E}\left[H(T)\xi^*-\int_t^T H(u)Z_2^*(u)\mathrm{d}u\Big|\mathcal{F}_t\right],\qquad t\in{\mathcal T}.\end{equation*}
The optimal portfolio
 $\pi^*_2$
is given by
 \begin{equation}\pi^*_2(t)=\left(\sigma(t)^{-1}\right)^{\top}\left[\frac{\hat{\psi}_2(t)}{H(t)}+X^*_2(t)\theta(t)\right],\end{equation}
where
 $\hat{\psi}_2(\! \cdot \!)$
is the integrand in the stochastic integral representation
 $\hat{M}_2(t)=x_2+\int_0^t \hat{\psi}_2(u)^{\top}\mathrm{d}W(u),$
of the martingale
 \begin{equation*}\hat{M}_2(t)\, :\! =\mathrm{E}\left[H(T)\xi^*-\int_0^TH(u)Z_2^*(u)\mathrm{d}u\Big|\mathcal{F}_t\right],\qquad t\in{\mathcal T}.\end{equation*}
4.4 Examples of
$Z_1^*$
and
$Z_2^*$


In this subsection, we present three examples to illustrate the risk exchange between the TBP fund and the cooperative entity. Given that the TBP fund is responsible for providing continuous benefit payments to its members, thereby requiring a stable endowment process, we consider the two scenarios in Case 1, along with Case 4 as representative examples.
Recall that the aggregate endowment process
 $\{Y(t)= Y_1(t) + Y_2(t)\}_{t\in{\mathcal T}}$
incorporates both longevity risk and income risk. The risk exchange endowment processes
 $\{Z_1^*(t)\}_{t\in{\mathcal T}}$
and
 $\{Z_2^*(t)\}_{t\in{\mathcal T}}$
may reflect various risks, including financial risk, longevity risk, and income risk. The specific structure of the risk exchange determines how these risks are allocated between
 $\{Z_1^*(t)\}_{t\in{\mathcal T}}$
and
 $\{Z_2^*(t)\}_{t\in{\mathcal T}}$
.
4.4.1 Example 1
In Example 1, the pension fund and the cooperative entity allocate Y(t) in a fixed proportion, which corresponds to the first scenario in Case 1. The case is intuitively appealing.
According to the first scenario in Case 1, we have
 \begin{equation}Z_1^*(t)=p Y(t),\end{equation}
and
 \begin{equation*}Z_2^*(t)=(1-p) Y(t),\end{equation*}
where p is a constant given by
 \begin{equation}p=\frac{\mathrm{E}\left[\int_0^TH(u)f^*(u)\mathrm{d}u\right]-x_1}{\mathrm{E}\left[\int_0^TH(u)Y(u)\mathrm{d}u\right]}.\end{equation}
Here, the value of p is calculated by substituting Equation (4.12) into Equation (4.8), which determines the allocation of the aggregate endowment process Y(t) between the pension fund and the cooperative entity.
By allocating Y(t) according to the predetermined ratio p, the pension fund and the cooperative entity share both longevity risk and income risk. This establishes a risk exchange mechanism that is natural and easy to execute.
It is possible for
 $p\lt0$
or
 $1-p\lt0$
. In the case of
 $p\lt0$
, two scenarios can occur. First, if
 $\mathrm{E}[\! \int_0^TH(u)f^*(u)\mathrm{d}u]-x_1\lt0$
and
 $\mathrm{E}[\! \int_0^TH(u)Y(u)\mathrm{d}u]\gt0$
, agent 1’s initial wealth exceeds its requirements, necessitating the transfer of funds to agent 2. Second, if
 $\mathrm{E}[\! \int_0^TH(u)f^*(u)\mathrm{d}u]-x_1\gt0$
and
 $\mathrm{E}[\! \int_0^TH(u)Y(u)\mathrm{d}u]\lt0$
, Y(t) is more likely to be negative, prompting a negative p value to ensure
 $Z_1^*(t)$
remains positive. The case of
 $1-p\lt0$
can be analyzed similarly to the case of
 $p\lt0$
.
4.4.2 Example 2
Example 2 corresponds to the second scenario in Case 1 with
 $j=2$
and
 $\varrho_1(t)=1$
. Then the TBP’s risk exchange endowment process becomes a constant, rendering it fully predictable. This predictability can enhance the confidence of TBP members.
We have
 $Z_1^*(t)=p$
and
 $Z_2^*(t)=Y(t)-p$
, where
 \begin{equation}p=\frac{\mathrm{E}\left[\int_0^TH(u)f^*(u)\mathrm{d}u\right]-x_1}{\mathrm{E}\left[\int_0^TH(u)\mathrm{d}u\right]}.\end{equation}
Example 2 presents a scenario in which the TBP fund’s risk exchange endowment process is fixed at a constant, indicating that the fund bears no risk from the endowment process itself. However, it remains exposed to financial risk through its risky investments. In contrast, the cooperative entity assumes financial risk from its own investments, as well as longevity and income risks transferred through the endowment process. This structure mirrors a typical insurance arrangement, where agent 1, functioning as the “policyholder,” transfers endowment-related risks to agent 2, the “insurer,” in order to stabilize its endowment process.
4.4.3 Example 3
Example 3 corresponds to Case 4, in which the risk exchange endowment process of the TBP fund closely aligns with its optimal adjustment process. As a result, this setup ensures the execution of the optimal adjustment process, thus protecting the benefits of the TBP members.
The structure of the Pareto-optimal risk exchange is
 \begin{equation*}Z_1^*(t)=f^*(t)-\frac{x_1}{T(H(t))},\end{equation*}
 \begin{equation*}Z_2^*(t)=Y(t)-Z_1^*(t).\end{equation*}
Since the pension fund has a nonnegative initial wealth of
 $x_1$
,
 $Z_1^*(t)$
can be less than
 $f^*(t)$
. If
 $x_1=0$
, then
 $Z_1^*(t)$
is simply equal to
 $f^*(t)$
, indicating that the pension fund takes the optimal overall adjustment from Y(t) as the new endowment
 $Z_1^*(t)$
and pays out the entire
 $Z_1^*(t)$
to its members.
Notably, since
 $f^*(t)=I(y\mathrm{e}^{\int_0^t\eta_1(u)\mathrm{d}u}H(t))$
, we can express
 $Z_1^*(t)$
as
 $Z_1^*(t)=I(y\mathrm{e}^{\int_0^t\eta_1(u)\mathrm{d}u}H(t))-\frac{x_1}{T(H(t))}$
. Note that H(t) is the state price density process depending solely on financial risk. This implies that
 $Z_1^*(t)$
is only influenced by financial risk. Consequently,
 $Z_2^*(t)$
is affected by financial risk, longevity risk, and income risk. In this case, the pension fund transfers its longevity risk to the cooperative entity.
4.5 Special case
In this subsection, we provide more explicit expressions for the solutions obtained in Subsections 4.3 and 4.4, in order to better illustrate our results in special cases. For that purpose, we assume that the utility functions U and V have CRRA form, that is,
 \begin{equation}U_1(s)=\frac{s^{\gamma_1}}{\gamma_1},\end{equation}
and
 \begin{equation}V_2(s)=\frac{s^{\gamma_2}}{\gamma_2},\end{equation}
where
 $\gamma_1$
and
 $\gamma_2$
are parameters taking values in
 $(\! -\infty, 0) \cup(0,1)$
. The weight coefficients are set to
 $\rho_1=1$
and
 $\rho_2=\rho$
. Therefore, the inverse functions of
 $U_1'$
and
 $V_2'$
are
 \begin{equation}I_1(s)=s^{\frac{1}{\gamma_1-1}},\end{equation}
and
 \begin{equation*}J_2(s)=s^{\frac{1}{\gamma_2-1}}.\end{equation*}
For simplicity, we set
 $D=3$
, that is, there are three risky securities in the financial market. We assume that
 $W_g(t)=W_2(t)$
and
 $W_c(t)=W_3(t)$
. To simplify the analysis, it is assumed that
 $\eta_1(t)=\eta_2(t)=\eta$
,
 $\mu_1(t)=\mu_1, \mu_2(t)=\mu_2, \mu_3(t)=\mu_3$
,
 $(\sigma_{ij}(t))_{D\times D}=(\sigma_{ij})_{D\times D}$
,
 $r(t)=r$
and
 $\theta(t)=(\theta_1,\theta_2,\theta_3)^{\top}$
are constant functions. Then we have
 \begin{equation*}H(t)=\exp\left(-\left(\frac{1}{2}\theta^{\top}\theta+r\right)t-(\theta_1 W_1(t)+\theta_2 W_2(t)+\theta_3 W_3(t))\right),\end{equation*}
and
 \begin{equation*}Y_2(t)=N\exp\left(\left(m-\frac{1}{2}L^2\right)t+LW_3(t)\right).\end{equation*}
Thus,
 \begin{equation*}H(t)Y_2(t)=N\exp\left(\left(m-r-\frac{1}{2}\theta^{\top}\theta-\frac{1}{2}L^2\right)t-\theta_1 W_1(t)-\theta_2 W_2(t)+(L-\theta_3) W_3(t))\right).\end{equation*}
Let h denote
 $\sqrt{\theta^{\top}\theta}$
. Then
 $\bar{W}(t)=\frac{1}{h}(\theta_1 W_1(t)+\theta_2 W_2(t)+\theta_3 W_3(t))$
is a standard Brownian motion. It holds that
 \begin{equation*}H(t)=\exp\left(-\left(\frac{1}{2}h^2+r\right)t-h\bar{W}(t)\right),\end{equation*}
and thus
 \begin{equation*}\mathrm{d}H(t)=-r H(t)\mathrm{d}t-h H(t)\mathrm{d}\bar{W}(t).\end{equation*}
Next we simplify Equation (4.7) to obtain y:
 \begin{align*}&x+\mathrm{E}\left[\int_0^T H(t)Y(t)\mathrm{d}t\right]=\mathrm{E}\left[\int_0^T H(t)(y \mathrm{e}^{\eta t}H(t))^{\frac{1}{\gamma_1-1}}\mathrm{d}t+H(T)\left(\frac{y}{\rho}\mathrm{e}^{\eta T} H(T)\right)^{\frac{1}{\gamma_2-1}}\right]\\&=\mathrm{E}\left[\int_0^T(y\mathrm{e}^{\eta t})^{\frac{1}{\gamma_1-1}}H(t)^{\frac{\gamma_1}{\gamma_1-1}}\mathrm{d}t+\left(\frac{y}{\rho}\mathrm{e}^{\eta T}\right)^{\frac{1}{\gamma_2-1}}H(T)^{\frac{\gamma_2}{\gamma_2-1}}\right]\\&=y^{\frac{1}{\gamma_1-1}}\mathrm{E}\left[\int_0^T\mathrm{e}^{\left(\frac{\eta}{\gamma_1-1}-\frac{\gamma_1}{\gamma_1-1}\left(\frac{1}{2}\theta^2+r\right)\right)t-\frac{h\gamma_1}{\gamma_1-1} W(t)}\mathrm{d}t\right]+\left(\frac{y}{\rho}\right)^{\frac{1}{\gamma_2-1}}\mathrm{E}\left[\mathrm{e}^{\left(\frac{\eta}{\gamma_2-1}-\frac{\gamma_2}{\gamma_2-1}(\frac{1}{2}\theta^2+r)\right)T-\frac{h\gamma_2}{\gamma_2-1} W(T)}\right]\\&=y^{\frac{1}{\gamma_1-1}}\frac{2(\gamma_1-1)^2}{-2r\gamma_1^2+(2r+h^2+2\eta)\gamma_1-2\eta}\left[\mathrm{e}^{\left(\frac{-2r\gamma_1^2+(2r+h^2+2\eta)\gamma_1-2\eta}{2(\gamma_1-1)^2}\right)T}-1\right]+\left(\frac{y}{\rho}\right)^{\frac{1}{\gamma_2-1}}\mathrm{e}^{\left(\frac{-2r\gamma_2^2+(2r+h^2+2\eta)\gamma_2-2\eta}{2(\gamma_2-1)^2}\right)T}.\end{align*}
If
 $\gamma_1=\gamma_2\, :\! =\gamma$
and
 $\eta_1=\eta_2\, :\! =\eta$
, then we can get a semi-analytical expression of y:
 \begin{equation}y=\left(\frac{x+\mathrm{E}\left[\int_0^T H(t)Y(t)\mathrm{d}t\right]}{(\frac{1}{K_1}+\rho^{\frac{1}{1-\gamma}})\mathrm{e}^{K_1T}-\frac{1}{K_1}}\right)^{\gamma-1},\end{equation}
where
 $K_1=\frac{-2r\gamma^2+(2r+\theta^2+2\eta)\gamma-2\eta}{2(\gamma-1)^2}$
. Furthermore, we note
 \begin{equation*}\mathrm{E}\left[\int_0^TH(t)Y_2(t)\mathrm{d}t\right]=\frac{N}{K_2}\exp(K_2T-1),\end{equation*}
where
 $K_2 = m-r-L\theta_3$
. Thus, Equation (4.18) can be written in a more explicit form as
 \begin{equation*}y=\left(\frac{x+\frac{N}{K_2}\exp(K_2T-1)+\mathrm{E}\left[\int_0^T H(t)Y_1(t)\mathrm{d}t\right]}{(\frac{1}{K_1}+\rho^{\frac{1}{1-\gamma}})\mathrm{e}^{K_1T}-\frac{1}{K_1}}\right)^{\gamma-1}.\end{equation*}
According to Equations (4.6) and (4.17), the optimal overall adjustment process
 $f^*(t)$
is given by
 \begin{equation}f^*(t)=(y\mathrm{e}^{\eta t}H(t))^{\frac{1}{\gamma-1}}.\end{equation}
Since we are particularly interested in Example 1, which appears to be a natural structure for the risk exchange, the constant p in Equation (4.13) can be calculated more explicitly as follows:
 \begin{equation}p=\frac{1}{1+\frac{K\rho^{\frac{1}{1-\gamma}}}{1-\mathrm{e}^{-KT}}}-\frac{x_1}{x+\mathrm{E}[\! \int_0^T H(t)Y(t)\mathrm{d}t]}.\end{equation}
Remark 4.1. From Equation (4.20), we can observe that when the weight coefficient
 $\rho$
increases, the value of p decreases. This can be explained by the fact that as the significance of agent 2 increases, the proportion of agent 1 in the combined endowment process Y(t) decreases. Therefore, a higher value of
 $\rho$
leads to a smaller allocation of the combined endowment to agent 1. Besides, we can rewrite Equation (4.20) as follows:
 \begin{equation*}p=\frac{1}{1+\frac{K\rho^{\frac{1}{1-\gamma_1}}}{1-\mathrm{e}^{-KT}}}-\frac{1}{1+\frac{x_2+\mathrm{E}[\! \int_0^T H(t)Y(t)\mathrm{d}t]}{x_1}}.\end{equation*}
This implies that an increase in agent 1’s initial wealth
 $x_1$
will result in a decrease in the value of p. This may be explained as follows: when agent 1 has a higher initial wealth, it already possesses a larger portion of the total resources. As a result, there is less demand for agent 1 to receive a significant share of the aggregate endowment process Y(t) through the risk exchange. Consequently, the value of p decreases as agent 1’s initial wealth increases.
Remark 4.2. Due to the complexity involved in obtaining explicit expressions for
 $\hat{M}_1(t)$
and
 $\hat{M}_2(t)$
, the explicit forms of
 $\pi^*_1(t)$
and
 $\pi^*_2(t)$
remain unknown. Consequently, in Section 5, we resort to numerical methods for analyzing the investment portfolios of agents 1 and 2. The analysis will be based on the semi-explicit solutions provided in Equations (4.10) and (4.11).
5. Numerical analysis
In this section, we provide numerical examples based on the explicit solutions derived in Subsections 4.3 and 4.4, aiming to provide a concrete illustration of our results in specific scenarios. To achieve this, we make assumptions on parameters to facilitate the analysis and subsequently investigate the effects of varying parameters on the solutions. Figures can be found in Appendix C.
5.1 Assumptions
Unless specified otherwise, we use the following configuration of parameter values for our numerical illustrations.
-
• The retirement age is 66, which is the full retirement age in the United States.Footnote 1
-
• The terminal time T is 15, which is hypothetical.
-
• Through the least squares estimation of the average remaining life expectancy of the 66-year-old population in the United States from 1933 to 2021,Footnote 2 we obtain that
$\bar{G}(t)=0.08124t+11.71$
, giving the
$R^2$
0.9818, which may indicate a good fit. Recall that a is the regression coefficient and
$\sigma_g$
is the volatility rate of the O-U process Q(t) in Equation (4.2), which are 1.0381 and 0.2922, Tao et al. (Reference Tao, Rong and Zhao2025) give that
$a=1.0381$
and
$\sigma_g=0.2922$
through the maximum likelihood estimation method. -
• The interest rate of the risk-free asset r is 0.0076, which is the average interest rate of the U.S. Treasury bonds with a 3-month maturity from 2009 to 2020.Footnote 3
-
• Using the maximum likelihood estimation method on Dow Jones Index (1993–2022), the rate of return (per annum) of the first risky asset
$\mu_1$
is estimated to be
$0.0882$
, and the volatility (per annum)
$\sigma_{11}$
is estimated to be
$0.1485$
. To enrich the choices, we assume that the second risky asset has lower returns and volatility (
$\mu_2=0.07$
,
$\sqrt{\sigma_{21}^2+\sigma_{22}^2+\sigma_{23}^2}=0.12$
), while the third risky asset has higher returns and volatility (
$\mu_3=0.1$
,
$\sqrt{\sigma_{31}^2+\sigma_{32}^2+\sigma_{33}^2}=0.16$
). In this case, we set
$\sigma_{12}=\sigma_{13}=\sigma_{32}=\sigma_{23}=0$
,
$\sigma_{21}=0.12g_1$
,
$\sigma_{22}=0.12\sqrt{1-g_1^2}$
,
$\sigma_{31}=0.16g_2$
and
$\sigma_{33}=0.16\sqrt{1-g_2^2}$
, where
$g_1=0.8$
and
$g_2=0.7$
. -
• For the ease of illustration, we denote $3,310 as 1 unit, which is the initial price of
$S_1(0)$
. Therefore, we can normalize
$S_i, i=1,2,3$
such that
$S_1(0)=S_2(0)=S_3(0)=1$
. -
• The entry rate n(t) is the number of people aged 66 years of each year in the United States.Footnote 4
-
• The utility parameters in Equations (4.15) and (4.16) are set as follows:
$\gamma=\gamma_1 = \gamma_2=-4$
, which is a ‘plausible level of risk-aversion’ considered by Parker (Reference Parker2003). -
• The initial target benefit for members who retire at time t is
$\bar{b}(t)=\bar{b}(0)\mathrm{e}^{rt}$
. Since a monthly retirement benefit of $1000 is suggested by the U.S. Social Security Administration,Footnote 5 the annual benefit is $12,000, and we set
$\bar{b}(0)=3.6$
. -
• According to data from the U.S. Bureau of Labor Statistics,Footnote 6 the average annual salary for people aged 65 years and over is $50,016, and it is 15.1 units. If the individual works for 40 years, and the ratio of pension contribution is assumed to be 0.1, then the initial contribution of a contract is
$c=40\times0.1\times15.1=60.4$
. -
• The earning rate m of agent 2 is
$0.1$
and the volatility L of
$Y_2(t)$
is 0.2. In fact, the selection of m and L depends on the specific situation of the cooperating entity. We adopt hypothetical values here, and then we change the value of L in numerical analysis to examine different situations. -
• The initial wealth of the target benefit pension
$x_1$
is $500,000, which is the same as the initial wealth of the cooperative entity
$x_2$
. -
• The discount rate of utility functions
$\eta_1(t)=\eta_2(t)=\eta=0.035$
, which is suggested by Moore et al. (Reference Moore, Boardman and Vining2013).


5.2 Effects of parameters on the overall adjustment
We proceed to examine the behavior of the optimal overall adjustment
 $f^*(t)$
using Monte Carlo methods with the time interval between adjacent time points set at
 $\frac{1}{12}$
. Figure C.1 illustrates the 50th percentile of
 $f^*(t)$
generated by Equation (4.19) from 100,000 simulations. Figure C.1 depicts how the overall adjustment
 $f^*(t)$
is influenced by various parameters, namely
 $\beta$
, c, m, L,
 $\rho$
, and
 $\eta$
. Observations reveal that each path of
 $f^*(t)$
exhibits an increasing trend over time. Additionally, for a fixed t,
 $f^*(t)$
tends to increase with the parameters c, m, and
 $\eta$
, while it decreases with
 $\beta$
, L, and
 $\rho$
. This behavior may be explained by various factors. An acceleration of remaining lifetime
 $\beta$
intensifies the burden of the pension fund, and a higher contribution from members leads to greater abundance in the pension fund. Similarly, a higher earning rate m and lower volatility L enhance agent 2’s endowment process, which in turn boosts the aggregate endowment process Y(t), resulting in an increase of
 $f^*(t)$
. Furthermore, decreasing the weight
 $\rho$
of agent 2, which indicates attaching greater importance to the utility of agent 1, leads to an increase in the overall adjustment
 $f^*(t)$
. Moreover, a higher discount rate
 $\eta$
reflects a greater value placed on immediate utility over future utility, leading to an increase in the value of
 $f^*(t)$
. Notably, the paths of
 $f^*(t)$
with different
 $\eta$
gradually converge, as future utility gradually loses significance when “future” diminishes.
5.3 Effects of parameters on the allocation ratio
The risk exchange structure employed in this subsection aligns with that in Example 1, wherein
 $Y_1(t)=pY(t)$
and
 $Y_2(t)=(1-p)Y(t)$
, with p determined by Equation (4.20). Figure C.2 depicts the impact of the six parameters on the allocation ratio p for agent 1. Notably, p is observed to increase with c, m, and
 $\eta$
, while it decreases with
 $\beta$
, L, and
 $\rho$
. Furthermore, the effects of
 $\rho$
and
 $\eta$
on p are notably more significant compared to those of
 $\beta$
, c, m, and L.
The observed trends can be explained by Equation (4.20). An increase in
 $\mathrm{E}[\! \int_0^T H(t)Y(t)\mathrm{d}t]$
leads to an increase in p, accounting for the increasing trend of p with the rise of c and m and the decrease of
 $\beta$
and L. Additionally, in line with remark 4.1, higher values of
 $\rho$
correspond to smaller values of p, as the importance of agent 1’s utility diminishes. Moreover, based on Figure C.1(f), an increase in
 $\eta$
results in an increase in
 $f^*(t)$
, leading to an increase in the allocation ratio p with a view to meeting the pension payment requirements.
5.4 Effects of parameters on the investment portfolio
Figure C.3 illustrates the influence of six parameters on the initial portfolio
 $\pi^*_1(0)=(\pi^*_{11}(0), \pi^*_{12}(0), \pi^*_{13}(0))^{\top}$
of agent 1 and
 $\pi^*_2(0)=(\pi^*_{21}(0), \pi^*_{22}(0), \pi^*_{23}(0))^{\top}$
of agent 2. Each subfigure has two vertical axes on the left and right, representing
 $\pi^*_1(0)$
and
 $\pi^*_2(0)$
, respectively. Overall, both agents 1 and 2 invest the most in the third risky asset, followed by the second risky asset, and finally the first risky asset. The paths of
 $\pi_2^*(0)$
and
 $\pi_1^*(0)$
exhibit similar trends with respect to parameters
 $\beta$
, m,
 $\rho$
, and
 $\eta$
, while they have opposite trends with respect to c and L. In general,
 $\pi^*_{12}(0)$
,
 $\pi^*_{13}(0)$
,
 $\pi^*_{22}(0)$
, and
 $\pi^*_{23}(0)$
have opposite trends compared to
 $\pi^*_{11}(0)$
and
 $\pi^*_{21}(0)$
.
An increase in
 $\beta$
signifies greater pressure on pension benefits, which leads to a decrease in risky investments. In contrast, an increase in c results in an enhancement of the funds available for agent 1 to invest in risky assets, as well as an increase in the proportion of agent 1 and a decrease in the proportion of agent 2 (see Figure C.2(b)). This transition leads to a reduction in the amounts of
 $\pi^*_{22}(0)$
and
 $\pi^*_{23}(0)$
allocated by agent 2 for risk hedging.
Moreover, an increase in m provides the system with more abundant funds, thereby heightening the agents’ motivation for risky investments. Conversely, an increase in L results in a decrease in the proportion of agent 1, which reduces its risk investments; however, this change simultaneously increases the proportion of agent 2, leading to an increase in its risk investments.
Furthermore, a decrease in
 $\rho$
implies a diminished significance of agent 1 and a corresponding reduction in support from agent 2, prompting agent 1 to increase its risky investments with the objective of boosting investment returns. Lastly, an increase in
 $\eta$
results in a decrease in the discounted value of future wealth, motivating both agents 1 and 2 to enhance their risky investments in order to maximize current profits.
6. Conclusion
This paper considers the risk exchange model under a continuous-time framework and obtains Pareto-optimal solutions for the associated stochastic control problem. We have proposed the conditions that need to be satisfied for risk exchange and established various risk exchange structures based on these conditions to meet the flexible requirements of different scenarios. Moreover, the application of our model to the target benefit pension (TBP) plan illustrates the optimal adjustment and investment strategies for agents, along with the structure of certain risk exchanges. This study contributes to a deeper understanding of risk operating and resource allocation in dynamic systems, while providing practical insights into risk-sharing mechanisms in collective pension schemes such as TBP.
Supplementary material
The supplementary material for this article can be found at https://doi.org/10.1017/asb.2025.10060
Acknowledgment
The authors thank the handling editor and two referees for helpful comments and suggestions. Cheng Tao was partially supported by the Fundamental Research Funds for the Central Universities (63252036) and the National Natural Science Foundation of China (12371475). Yang Shen was partially supported by the Australian Research Council (DP210101195 and DE200101266).
Competing interests
We declare that there is no competing interest.



