




No CrossRef data available.
SEMI-NONPARAMETRIC ESTIMATES OF THE DEMAND FOR MONEY IN THE UNITED STATES
Published online by Cambridge University Press: 25 October 2005
Abstract
This paper focuses on the demand for money in the United States in the context of two globally flexible functional forms—the Fourier and the asymptotically ideal model (AIM)—estimated subject to full regularity, using methods suggested over 20 years ago. We provide a comparison in terms of violations of the regularity conditions for consumer maximization and in terms of output in the form of a full set of elasticities. We also provide a policy perspective, using (for the first time) parameter estimates that are consistent with global regularity, in that a very strong case can be made for abandoning the simple-sum approach to monetary aggregation, on the basis of the low elasticities of substitution among the components of the popular M2 aggregate of money.
Information
- Type
- ARTICLES
- Information
- Copyright
- © 2005 Cambridge University Press
INTRODUCTION
For many years the literature on monetary asset demand systems employed globally regular generating functions such as the Cobb-Douglas or the constant elasticity of substitution (CES) utility functions [see, e.g., Chetty (1969)]. These forms had the advantage of conforming to the neoclassical conditions for constrained consumer maximization. However, when Uzawa (1962) proved that one cannot simultaneously obtain arbitrary estimates of elasticities of substitution and have a CES specification, the approach ran into a dead end.
To overcome that problem, flexible functional forms that provide local approximations to the demand functions were then used. Specifically, a popular local approximation to the indirect utility function was achieved by a translog specification. In this way, duality theory would provide access to all the implications of aggregate integrability at least at a point. On the demand for money, Offenbacher (1979) was the first to employ a flexible functional form (the translog) in this manner. As noted, these models can attain arbitrary elasticities at a single point and, according to Barnett et al. (1991), do so at a high degree; as a consequence, they have revolutionized microeconometrics by providing access to all of neoclassical microeconomic theory in econometric applications.
However, although locally flexible functional forms provide arbitrary elasticity estimates at the point of approximation, they gain this precision at the expense of giving up global regularity. There is also evidence that these models fail to meet the regularity conditions for consumer maximization in large regions. Barnett (1983, 1985), Barnett and Lee (1985), and Barnett et al. (1985, 1987) provided a partial solution to this problem by proposing the minflex Laurent model that is locally flexible and regular over a large region but is still not globally regular. However, the problem persisted that the flexibility was achieved only at a single point. An innovation in this respect are the semi-nonparametric flexible functional forms that possess global flexibility and in which asymptotic inferences are, potentially, free from any specification error.
Semi-nonparametric functions can provide an asymptotically global approximation to complex economic relationships. These functions provide global approximations to the true data generating process and its partial derivatives. By global approximation, we mean that the flexible functional form is capable, in the limit, of approximating the unknown underlying generating function at all points and thus of producing arbitrarily accurate elasticities at all data points. Two such semi-nonparametric functions are the Fourier flexible functional form, introduced by Gallant (1981), and the asymptotically ideal model (AIM), introduced by Barnett and Jonas (1983) and employed and explained by Barnett and Yue (1988); see also Fleissig and Swofford (1996, 1997), Fisher and Fleissig (1997), Fisher, Fleissig, and Serletis (2001), Fleissig and Serletis (2002), and Drake et al. (2003) for some interesting applications.
This paper focuses on the demand for money in the United States in the context of these two globally flexible functional forms—the Fourier and the asymptotically ideal model. We compare these two models in terms of violations of the regularity conditions for consumer maximization and also provide a policy perspective, using (for the first time) parameter estimates that are consistent with global regularity, in that a very strong case can be made for abandoning the simple-sum approach to monetary aggregation, on the basis of the low elasticities of substitution among the components of the popular M2 aggregate of money. We believe that much of the older literature that investigates the substitutability/complementarity relation between monetary assets in the context of demand systems does not impose full regularity (as we do in this paper) and hence has to be disregarded.
The paper is organized as follows: Section 2 briefly sketches out the neoclassical monetary problem while Section 3 discusses monetary aggregation and measurement matters and uses the Divisia index to aggregate monetary assets. In Sections 5–9, we estimate the models, assess the results in terms of their consistency with optimizing behavior, and explore the economic significance of the results. The final section concludes the paper.
DEMAND FOR MONETARY SERVICES
We assume a weakly separable monetary utility function, so that the representative money holder faces the following problem:
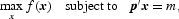
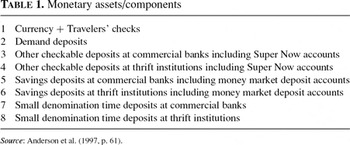
where x = (x1, x2, …, x8) is the vector of monetary asset quantities described in Table 1; p = (p1,p2,…, p8) is the corresponding vector of monetary asset user costs; and m is the expenditure on the services of monetary assets.

Because the economic agent involved in this study is the household, it is important to work with data that reflect this composite agent's selection of monetary services. In practice, the assets in the official M2 definition of money are appropriate, but we have excluded the rapidly growing retail money market mutual funds, as does much of the empirical literature, mainly because satisfactory monetary aggregates cannot be obtained using this asset most probably because the household employs this particular asset for its savings properties and not for its monetary services.
Moreover, because the flexible functional forms are parameter intensive we rationalize the estimation to a small set of monetary asset demand equations by imposing the following separable structure of preferences:
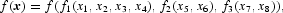
where the subaggregator functions fi(i = 1, 2, 3) provide subaggregate measures of monetary services. Here the subaggregates will be thought of as Divisia quantity indexes that can allow for less than perfect substitutability among the relevant monetary components.
As already noted, the main reason for employing subaggregates, rather than studying all eight items, is that our models are very parameter intensive. We have separated the group of assets into three collections based on empirical pretesting. The pretesting, for which there is a large literature [see Barnett et al. (1992)] is based on the NONPAR GARP procedure of Varian (1982, 1983). The specific collection used here is very much like that reported in the literature.
THE DATA
The Federal Reserve Bank of St. Louis, in its Monetary Services Index project, provides monetary quantities as well as user costs, for the eight items listed in Table 1 (and many others, up through the L definition of money in the Federal Reserve's lexicon). For our empirical work, we require per capita real data, and to that end, we have divided each measure of monetary services by the U.S. CPI (for all items) and total U.S. population. Those data are quarterly from 1970:1 to 2003:2 (a total of 134 observations). The calculation of the user costs, which are the appropriate prices for monetary services, is explained in several online publications of the Federal Reserve Bank of St. Louis or in Barnett et al. (1992), Barnett and Serletis (2000), and Serletis (2001).
To provide the three subaggregates shown in Table 1, we employ a Divisia quantity index, defined (in discrete time) as
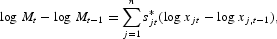
according to which the growth rate of the subaggregate is the weighted average of the growth rates of the component quantities, with the Divisia weights being defined as the expenditure shares averaged over the two periods of the change, s*jt = (1/2)(sjt + sj,t−1) for j = 1, …, n, where sjt = πjtxjt/[sum ]πktxkt is the expenditure share of asset j during period t, and πjt is the user cost of asset j. What this does, up to a third-order remainder term, is preserve the microeconomic characteristics of the underlying monetary assets.
The collection of assets, then, are as follows: Subaggregate A is composed of currency, travelers' checks, and other checkable deposits including Super NOW accounts issued by commercial banks and thrifts (series 1 to 4 in Table 1). Subaggregate B is composed of savings deposits issued by commercial banks and thrifts (series 5 and 6), and subaggregate C is composed of small time deposits issued by commercial banks and thrifts (series 7 and 8). Finally, Divisia user cost indexes are calculated by applying Fisher's (1922) weak factor reversal test.
FOURIER AND AIM MODELS
Our objective is to estimate a system of demand equations derived from an indirect utility function. The most important advantage of using the indirect utility approach is that prices enter as exogenous variables in the estimation process and the demand system is easily derived by applying Roy's identity.
In this section, we briefly present the basic properties of two models that we plan to use in our empirical work. As we have already indicated, the models are the Fourier and the AIM. Although there is some comparison implied in our presentation in this section, our purpose is basically to make clear the properties of the models with which we will work.
The Fourier
We follow the procedure explained by Gallant (1981) for expanding the indirect utility function using the Fourier series
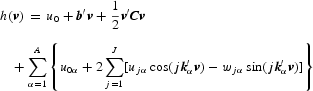
in which
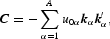
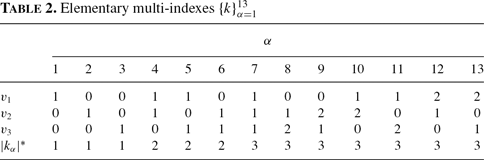
where v denotes income-normalized prices (=p/m), kα is a multi-index—an n-vector with integer components—and u0, {b}, {u}, and {w} are parameters to be estimated. As Gallant (1981) shows, the length of a multi-index, denoted as |kα|* = [sum ]ni=1|kiα|, reduces the complexity of the notation required to denote high-order partial differentiation and multivariate Fourier series expansions.1
For example, with n = 3 in (1), the multi-index λ′ = (5, 2, 7), generates the 14th-order partial derivative, as follows:
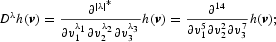
see Gallant (1981) for more details.
The Fourier flexible functional form has the ability to achieve close approximation in Sobolev norm, which confers nonparametric properties on the functional form. This is the reason the Fourier flexible form is considered to be a semi-nonparametric functional form.
By applying Roy's modified identity,
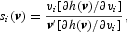
to (1), we obtain the Fourier demand system
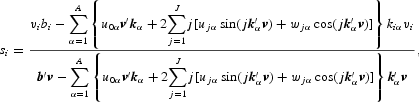
for i = 1, 2, 3 monetary assets; the time subscript t has been suppressed.
Eastwood and Gallant (1991) show that Fourier functions produce consistent and asymptotically normal parameter estimates when the number of parameters to be estimated equals the number of effective observations raised to the power of 2/3. This result follows from Huber (1981) and is similar to optimal bandwidth results in many nonparametric models. In our case, with n = 3 and T = 134, the number of effective observations is 268 (=2 ×134)—since we estimate (n − 1) share equations—and we should therefore estimate (approximately) 41 (=2682/3) parameters. As we impose the normalization bn = [sum ]n−1i=1bi, the Fourier demand system has (n − 1) b, Au0α, AJujα, and AJwjα parameters to be estimated, for a total of (n − 1) + A(1 + 2J) free parameters. By setting (n − 1) + A(1 + 2J) equal to 41, in this application we choose the values of A and J to be 13 and 1, respectively. This also determines the elementary multi-indexes used in this paper, as shown in Table 2.
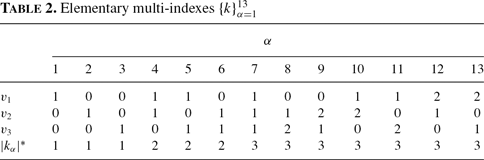
Because a Fourier series is a periodic function in its arguments but the indirect utility function is not, the scaling of the data is also important. In empirical applications, to avoid having the approximation diverge from the true indirect utility function, the data should be rescaled so that the income-normalized prices lie on 0 ≤ vi ≤ 2π. The income-normalized prices vi(i = 1, …, n) typically are rescaled as follows: vi × [(2π − ε)/max{vi:i = 1, …, n}], with (2π − ε) set equal to 6, as in Gallant (1982). In our case, however, the income-normalized prices vi(i = 1, …, n) are already between 0 and 2π, so we performed no such rescaling.
The AIM
Following Barnett and Yue (1988), the reciprocal indirect utility function for the asymptotically ideal model of first-order approximation for n = 3 (our problem in hand) is
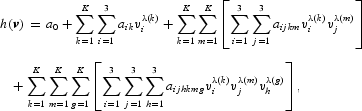
where λ(z) = 2−z for z = {k, m, g} is the exponent set and aik, aijkm, and aijhkmg, for all i, j, h = 1, 2, 3, are the parameters to be estimated. The number of parameters is reduced by deleting the diagonal elements of the parameter arrays so that i ≠ j, j ≠ h, and i ≠ h. This does not alter the span of the model's approximation.
To avoid the extensive multiple subscripting in the coefficients aijhkmg, we follow Barnett and Yue (1988), and reparameterize by stacking the coefficients as they appear in (4) into a single vector of parameters, b = (b0, …, b26)′ containing the 27 coefficients in (4), as follows:
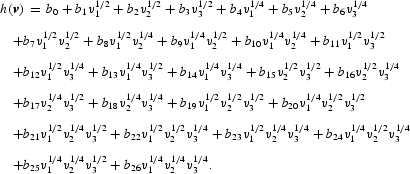
Applying the modified version of Roy's identity, (2), to (5), we obtain the AIM demand system


where D is the sum of the numerators in equations (6), (7), and (8).
COMPUTATIONAL CONSIDERATIONS
Demand systems (3) and (6)–(8) can be written as
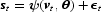
with an error term appended. In (9), s = (s1, …, sn)′, ψ(v,θ) = [ψ1(v,θ),…, ψn(v, θ)]′, and ψi(v,θ) is given by the right-hand side of each of (3) and (6)–(8).
As Gallant and Golub (1984, p. 298) put it,
all statistical estimation procedures that are commonly used in econometric research can be formulated as an optimization problem of the following type [Burguete et al. (1982)]:
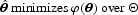
with φ(θ) twice continuously differentiable in θ.
In this paper, we follow Gallant and Golub (1984) and use Zellner's (1962) seemingly unrelated regression method to estimate θ. Hence, φ(θ) has the form
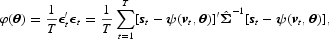
where T is the number of observations and
is an estimate of the variance-covariance matrix of (9). In minimizing (10), we use the TOMLAB/NPSOL tool box with MATLAB see http://tomlab.biz/products/npsol. NPSOL uses a sequential quadratic programming algorithm and is suitable for both unconstrained and constrained optimization of smooth (i.e., at least twice continuously differentiable) nonlinear functions.
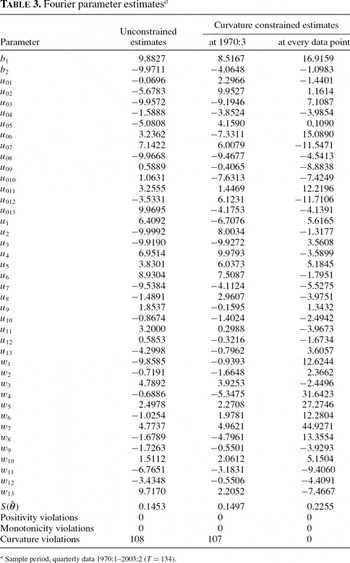
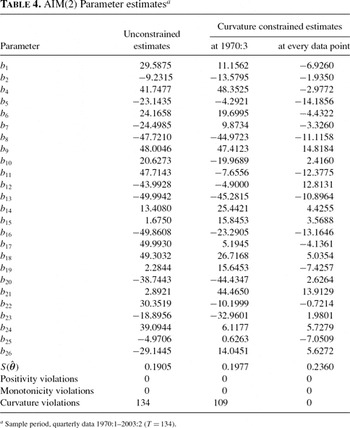
Because results in nonlinear optimization are sensitive to the initial parameter values, to achieve global convergence, we randomly generated 500 sets of initial parameter values and chose the starting θ that led to the lowest value of the objective function. The parameter estimates that minimize the objective function are reported in the first column of Tables 3 and 4 for the Fourier and AIM, respectively. As in Gallant (1981) and Barnett and Yue (1988) we do not have access to asymptotic standard errors that can be supported by statistical theory. We also report the number of positivity, monotonicity, and curvature violations, since the usefulness of flexible functional forms depends on whether they satisfy these theoretical regularity conditions. The regularity conditions are checked as follows:
- Positivity is checked by direct computation of the values of the estimated budget shares, . It is satisfied if , for all t.
- Monotonicity is checked by choosing a normalization on the indirect utility function so as to make h(p, m) decreasing in its arguments and by direct computation of the values of the first gradient vector of the estimated indirect utility function. It is satisfied if and or, equivalently, if , where .
- Curvature requires that the Slutsky matrix be negative semidefinite and is checked by performing a Cholesky factorization of that matrix and checking whether the Cholesky values are nonpositive [since a matrix is negative semidefinite if its Cholesky factors are nonpositive—see Lau (1978, Theorem 3.2)]. Curvature can also be checked by examining the Allen elasticities of substitution matrix, provided that the monotonicity condition holds. It requires that this matrix be negative semidefinite.


The results of the regularity tests for each model are presented in the last three rows of each of Tables 3 and 4. The numbers in the tables represent the number of times the regularity conditions are violated. For both models, the positivity and monotonicity conditions are satisfied at every data point, whereas the curvature condition is violated at 108 data points with the Fourier and at every data point with the AIM. As Barnett (2002, p. 199) put it in his Journal of Econometrics Fellow's opinion article, without satisfaction of all three theoretical regularity conditions
the second-order conditions for optimizing behavior fail, and duality theory fails. The resulting first-order conditions, demand functions, and supply functions become invalid.
IMPOSING CURVATURE RESTRICTIONS
The indirect utility function should be a quasi-convex function in income-normalized prices, vi(i = 1, …, n)—as already noted, this is the curvature condition. Gallant and Golub (1984), following Diewert et al. (1977), argue that a necessary and sufficient condition for quasi-convexity of h(v, θ) is
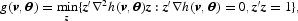
where ∇h(v,θ)=(∂/∂ v) h(v,θ) and ∇2h(v,θ)=(∂2/∂ v∂ v′)h(v,θ), and g(v, θ) is nonnegative (i.e., zero or positive) when the quasi-convexity (curvature) constraint is satisfied and negative when it is violated; g(v, θ) is referred to as the “constraint indicator.” Hence, as in Gallant and Golub (1984), we impose quasi convexity by modifying the optimization problem as follows:
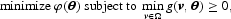
where Ω is a finite set with the finite number of elements vi (i = 1, …, n). Curvature can be imposed at some representative point in the data (i.e., locally), over a region of data points, or at every data point in the sample (i.e., globally).
Let us briefly describe in more detail the Gallant and Golub (1984) method for imposing curvature restrictions on flexible functional forms. Define a real symmetric n × n matrix A = ∇2h(v, θ) [note that this is the Hessian matrix of the indirect utility function, h(v, θ)] and an n × 1 vector α = ∇h(v, θ) as the gradient vector of h(v, θ). The curvature condition (11) can be written as
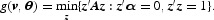
The next step is to partition α as α=(α1, α(2)′)′, where α1 is the first element of α and α(2) is an (n − 1) × 1 vector of the remaining elements of α, and construct an n × 1 vector u,
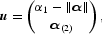
where ‖α‖ is the norm of α, defined as ‖α‖ = ([sum ]ni=1α2i)1/2. With this notation, we define the following:
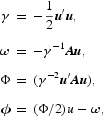
where γ is a scalar, Φ is an n × n matrix, and ω and ϕ are n × 1 vectors. The next and final step is to form an n × n matrix K as follows:
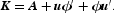
Let's delete the first row and column of K and rename the (n − 1) × (n − 1) thereby obtained matrix as K22. A necessary and sufficient condition for curvature [or, equivalently, for the indicator function (11) to be nonnegative] is that K22 should be a positive semidefinite matrix. In this paper, we use the ‘chol’ command in MATLAB to perform a Cholesky factorization of the K22 matrix and construct an indicator of whether K22 is positive semidefinite (this indicator is zero when K22 is positive semidefinite and a positive integer otherwise). Hence, we run a constrained optimization subject to the constraint that K22 is positive semidefinite (in which case curvature is satisfied). As already noted, we can evaluate K22 at a single data point, over a region of data points, or at every data point in the sample.
Using NPSOL, we performed the computations and report the results in the second and third columns of Tables 3 and 4, where the second column shows the results when the quasi-convexity constraint is imposed locally (in 1970:3) and the third column shows the results when the constraint is imposed at every data point in the sample. Clearly, the effect of imposing the quasi-convexity constraint locally is negligible, as the number of curvature violations drops from 108 to 107 with the Fourier and from 134 to 109 with the AIM. Note also that the imposition of local curvature does not induce violations of monotonicity for both the Fourier and AIM that satisfy monotonicity (at all observations) when the local curvature condition is not imposed.
However, imposing the constraint at every data point (again using NPSOL), we obtain the results reported in the last column of each of Tables 3 and 4. Imposition of the quasi-convexity constraint globally has a significant impact on both models, as we obtain parameter estimates that are consistent with all three theoretical regularity restrictions (positivity, monotonicity, and curvature) at every data point in the sample. In this regard, Barnett and Pasupathy (2003, p. 151) argue that
imposing curvature without monotonicity, while perhaps to be preferred to the prior common practice of imposing neither, is not adequate without at least reporting data points at which violations of monotonicity occur. Monotonicity is too important to be ignored.
In our case, the imposition of curvature globally does not produce spurious violations of monotonicity, thereby assuring true theoretical regularity. Hence, in what follows we discuss the income and price elasticities as well as the elasticities of substitution based on the Fourier and AIM models that (with our data set) satisfy both the neoclassical monotonicity and curvature conditions. We believe that much of the older literature in this area does not impose full regularity—that is, both monotonicity and curvature—and hence has to be disregarded.
INCOME AND PRICE ELASTICITIES
In the demand systems approach to estimation of economic relationships, the primary interest, especially in policy analysis, is in how the arguments of the underlying functions affect the quantities demanded. This is conventionally and completely expressed in terms of income and price elasticities and in elasticities of substitution. These elasticities can be calculated directly from the estimated budget share equations by writing the left-hand side as
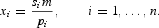
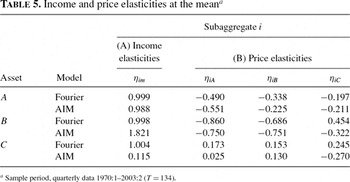
In particular, the income elasticities, ηim, can be calculated as
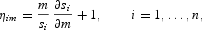
and the uncompensated (Cournot) price elasticities, ηij, as
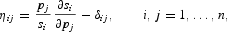
where δij = 0 for i ≠ j and 1 otherwise. If ηij>0, the assets are gross substitutes; if ηij < 0, they are gross complements; and if ηij = 0, they are independent.
We begin by presenting the income elasticities in Part A of Table 5, evaluated at the mean of the data, for the three subaggregates and the two models.3
All elasticities in this paper have been acquired using numerical differentiation to produce the values of ∂si/∂m and ∂si/∂pj for i, j = 1, 2, 3.

ELASTICITIES OF SUBSTITUTION
From the point of view of monetary policy, the measurement of the elasticities of substitution among the three monetary assets is of prime importance. As we have already pointed out, the currently popular simple-sum approach to monetary aggregation requires, in effect, that the elasticities of substitution be very high especially among the components of the aggregate M2. By “very high” we mean infinite, of course, but since the policy literature has not addressed the question of how high such an estimate should be to warrant a simple-sum calculation from a practical standpoint, all we can do is report our results.
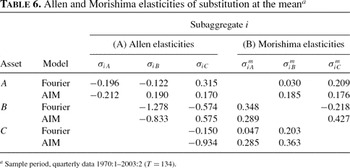
There are currently two methods employed for calculating the partial elasticity of substitution between two variables, the Allen and the Morishima. Following Serletis (2001), the Allen partial elasticity of substitution between two liquid assets i and j, σaij, can be calculated as

The Allen elasticity of substitution is the traditional measure and has been employed to measure substitution behavior and structural instability in a variety of contexts. However, when there are more than two goods, the Allen elasticity may be uninformative. For two assets the relationship is unambiguous: The assets must be substitutes. When there are more than two assets, the relationship becomes complex and depends on things such as the direction taken toward the point of approximation. In that case the Morishima elasticity of substitution is the correct measure of substitution elasticity:
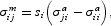
where si is the share of asset i in the consumer's budget. Notice that the Morishima elasticity looks at the impact on the ratio of two goods (xi/xj). Assets will be Morishima complements (substitutes) if an increase in the price of j causes xi/xj to decrease (increase).
Table 6 shows estimates of both the Allen and Morishima elasticities, evaluated at the means of the data. For Part A, we expect the three diagonal terms, representing the Allen own-elasticities of substitution for the three assets to be negative. This expectation is clearly achieved. However, because the Allen elasticity of substitution produces ambiguous results off-diagonal, we use the Morishima elasticity of substitution to investigate the substitutability/complementarity relation between assets. Based on the asymmetrical Morishima elasticities of substitution—the correct measures of substitution—as documented in Part B of Table 6, the assets are Morishima substitutes with only one of these elasticities being negative. Moreover, all Morishima elasticities of substitution are less than unity, irrespective of the model used.

This clearly indicates difficulties for a simple-sum-based monetary policy and helps explain why recent attempts to target and control the money supply (simple sum M2) have been abandoned in favor of interest-rate procedures.
CONFIDENCE INTERVALS FOR THE ELASTICITY ESTIMATORS
The elasticities are parametric functions, σ(θ), and a parametric bootstrap could be used, as in Gallant and Golub (1984), to compute standard errors or confidence intervals for the estimates reported in Tables 5 and 6. This involves the use of Monte Carlo methods to obtain a reliable estimate of the sampling distribution of σ(θ) by generating a large enough sample from the distribution of the constrained estimator; see also Anderson and Thursby (1986) for similar Monte Carlo experiments in the case of translog demand models. At each Monte Carlo trial, however, we need to search over a wide range of starting values of θ, using TOMLAB/NPSOL (as discussed in Section 5), to achieve global convergence.
In particular, as already mentioned in Section 5, for each Monte Carlo trial we need to randomly generate 500 sets of initial parameter values and choose the starting θ that leads to the lowest value of the objective function. In terms of cost, with 134 observations and the models used in this paper, it takes on average 2.5 minutes of CPU time on a Pentium-4 PC per random draw of initial parameter values. This amounts to over 20 hours of CPU time for each Monte Carlo trial. If we were to use 250 Monte Carlo trials, as in Gallant and Golub (1984), it will take over 5,000 hours of CPU time to obtain bootstrap standard errors! This is not affordable at present, unless we use a smaller number of sets of initial parameter values at each Monte Carlo trial. We are against such an approach, however, because it will likely lead to the non-optimization of the objective function in some (if not all) of the Monte Carlo trials and consequently to extremely wide confidence intervals.
CONCLUSIONS
We have investigated the demand for money in the United States in the context of two semi-nonparametric flexible functional forms—the Fourier and the AIM. We have argued that inferences based on flexible functional forms are virtually worthless unless all three theoretical regularity conditions (of positivity, monotonicity, and curvature) are satisfied, since violations of regularity violate the maintained hypothesis and invalidate the duality theory that produces the estimated model. We have also argued that unless regularity is attained by luck, flexible functional forms should always be estimated subject to regularity.
As Barnett and Pasupathy (2003, p. 136) put it
an earlier practice with “flexible functional forms” was to impose neither monotonicity nor curvature, but check those conditions at each data point ex post. Experience in that tradition has suggested that when violations of regularity occur, they are much more likely to occur through violations of curvature conditions than through violations of monotonicity conditions. Based on those results, the more recent approach of imposing curvature alone seems constructive and reasonable. But once curvature is imposed without the imposition of monotonicity, the earlier observation may no longer apply.
We have shown that (with our data set) imposition of global curvature in the Fourier and AIM models, using methods suggested over 20 years ago by Gallant and Golub (1984), does not produce spurious violations of monotonicity, thereby assuring true regularity, that is, both monotonicity and curvature.
We have also indicated throughout this paper that a primary concern was to show how our results affect the formulation of monetary policy. As we have noted, considerable research has indicated that the simple-sum approach to monetary aggregation, in the face of cyclically fluctuating incomes and interest rates (and hence user costs), cannot be the best that can be achieved. Our study corroborates the existence of these phenomena and hence concurs with the general preference for the use of chain-linked monetary aggregates based on, for example, the Divisia index. A second consideration that favors such an approach, again corroborated in our study, is that the elasticities of substitution among the monetary assets (in the popular M2 aggregate) are consistently and believably below unity. The simple-sum approach is invalid in such a case, because the method requires that the monetary components of the aggregates be perfect substitutes. The Divisia method of aggregation again solves this problem.
We would like to thank two referees, William Barnett, Douglas Fisher, and Ricardo Rangel-Ruiz for their sharing and helpful comments, and Kenneth Holmstrom for his help with the NPSOL toolbox. Serletis gratefully acknowledges financial support from the Social Sciences and Humanities Research Council of Canada (SSHRCC).
References
Anderson Richard G. &
Jerry G. Thursby
1986
Confidence intervals for elasticity estimators in translog models.
Review of Economics and Statistics
68,
647–
656.Google Scholar
Anderson Richard G.,
Barry E. Jones &
Travis D. Nesmith
1997
Building new monetary services indexes: Concepts, data, and methods.
Federal Reserve Bank of St. Louis Review
79,
53–
82.Google Scholar
Barnett William A.
1983
New indices of money supply and the flexible Laurent demand system.
Journal of Business and Economic Statistics
1,
7–
23.Google Scholar
Barnett William A.
1985
The minflex Laurent translog functional form.
Journal of Econometrics
30,
33–
44.Google Scholar
Barnett William A.
2002
Tastes and technology: Curvature is not sufficient for regularity.
Journal of Econometrics
108,
199–
202.Google Scholar
Barnett William A. &
A. Jonas
1983
The Muntz-Szatz demand system: an application of a globally well-behaved series expansion.
Economics Letters
11,
337–
342.Google Scholar
Barnett William A. &
Y.W. Lee
1985
The global properties of the minflex Laurent, generalized Leontief, and translog flexible functional forms.
Econometrica
53,
1421–
1437.Google Scholar
Barnett William A. &
Meenakshi Pasupathy
2003
Regularity of the generalized quadratic production model: a Counterexample.
Econometric Reviews
22,
135–
154.Google Scholar
Barnett William A. &
Apostolos Serletis
2000
The Theory of Monetary Aggregation. Contributions to Economic Analysis 245.
Amsterdam:
North-Holland.
Barnett William A.,
Y.W. Lee &
M.D. Wolfe
1985
The three-dimensional global properties of the minflex Laurent, generalized Leontief, and translog flexible functional forms.
Journal of Econometrics
30,
3–
31.Google Scholar
Barnett William A.,
Y.W. Lee &
M.D. Wolfe
1987
The global properties of the two minflex Laurent flexible functional forms.
Journal of Econometrics
36,
281–
298.Google Scholar
Barnett William A. &
P. Yue
1988
Semi-nonparametric estimation of the asymptotically ideal model: the AIM demand system.
In G. Rhodes and
T.B. Fomby (eds.),
Advances in Econometrics, vol VII,
Greenwich, CT:
JAI Press.
Barnett William A.,
J. Geweke &
M. Wolfe
1991
Semi-nonparametric Bayesian estimation of the asymptotically ideal production model.
Journal of Econometrics
49,
5–
50.Google Scholar
Barnett William A.,
Douglas Fisher &
Apostolos Serletis
1992
Consumer theory and the demand for money.
Journal of Economic Literature
30,
2086–
2119.Google Scholar
Burguete Jose F.,
A. Ronald Gallant &
Geraldo Souza
1982
On unification of the asymptotic theory of nonlinear econometric models.
Econometric Reviews
1,
151–
190.Google Scholar
Chetty V. Karuppan
1969
On measuring the nearness of near-moneys.
American Economic Review
59,
270–
281.Google Scholar
Diewert W. Erwin,
M. Avriel &
I. Zang
1977
Nine kinds of quasiconcavity and concavity.
Journal of Economic Theory
25,
397–
420.Google Scholar
Drake Leigh M.,
Adrian R. Fleissig &
James L. Swofford
2003
A semi-nonparametric approach to the demand for U.K. monetary assets.
Economica
70,
99–
120.Google Scholar
Eastwood Brian J. &
A. Ronald Gallant
1991
Adaptive rules for semi-nonparametric estimators that achieve asymptotic normality.
Econometric Theory
7,
307–
340.Google Scholar
Fisher I.
1922
The Making of Index Numbers: A Study of Their Varieties, Tests, and Reliability.
Boston:
Houghton Mifflin.
Fisher Douglas &
Adrian R. Fleissig
1997
Monetary aggregation and the demand for assets.
Journal of Money, Credit and Banking
29,
458–
475.Google Scholar
Fleissig Adrian R. &
Apostolos Serletis
2002
Semi-nonparametric estimates of substitution for Canadian monetary assets.
Canadian Journal of Economics
35,
78–
91.Google Scholar
Fleissig Adrian R. &
James L. Swofford
1996
A dynamic asymptotically ideal model of money demand.
Journal of Monetary Economics
37,
371–
380.Google Scholar
Fleissig Adrian R. &
James L. Swofford
1997
Dynamic asymptotically ideal models and finite approximation.
Journal of Business and Economic Statistics
15,
482–
492.Google Scholar
Fisher Douglas,
Adrian R. Fleissig &
Apostolos Serletis
2001
An empirical comparison of flexible demand system functional forms.
Journal of Applied Econometrics
16,
59–
80.Google Scholar
Gallant A. Ronald
1981
On the bias in flexible functcional forms and an essentially unbiased form: The Fourier flexible form.
Journal of Econometrics
15,
211–
245.Google Scholar
Gallant A. Ronald
1982
Unbiased determination of production technologies.
Journal of Econometrics
20,
285–
323.Google Scholar
Gallant A. Ronald &
Gene H. Golub
1984
Imposing curvature restrictions on flexible functional forms.
Journal of Econometrics
26,
295–
321.Google Scholar
Huber Peter J.
1981
Robust Statistics.
New York:
Wiley.
Lau L.J.
1978
Testing and imposing monotonicity, convexity, and quasi-convexity constraints.
In M. Fuss and
D. McFadden (eds.),
Production Economics: A Dual Approach to Theory and Applications, vol. 1,
Amsterdam:
North-Holland
(1978),
pp. 409–
453.
Offenbacher E.K.
1979
The Substitution of Monetary Assets.
Ph.D. Dissertation,
University of Chicago.
Serletis Apostolos
2001
The Demand for Money: Theoretical and Empirical Approaches.
Amsterdam:
Kluwer Academic.
Uzawa H.
1962
Production functions with constant elasticities of substitution.
Review of Economic Studies
29,
291–
299.Google Scholar
Varian Hal R.
1982
The nonparametric approach to demand analysis.
Econometrica
50,
945–
973.Google Scholar
Varian Hal R.
1983
Nonparametric tests of consumer behaviour.
Review of Economic Studies
50,
99–
110.Google Scholar
Zellner A.
1962
An efficient method of estimating seemingly unrelated regressions and tests for aggregation bias.
Journal of the American Statistical Association
57,
348–
368.Google Scholar
Monetary assets/components
Elementary multi-indexes {k}13α=1
Fourier parameter estimatesa
AIM(2) Parameter estimatesa
Income and price elasticities at the meana
Allen and Morishima elasticities of substitution at the meana
 You have
Access
- 40
- Cited by