


1. Introduction
Normative decision theory, and in particular statistical decision theory, is generally based on minimizing a quantitative loss function or maximizing a quantitative utility function, which is itself a unit-less representation of values for outcomes. Such representations result from the familiar axiomatic derivations of subjective expected utility theory (see, e.g., Savage Reference Savage1954; Anscombe and Aumann Reference Anscombe and Aumann1963). There is also minimax theory (Wald Reference Wald1950), wherein the decision maker chooses an option so as minimize, over all feasible options, the maximum, over states, of the loss. Minimax theory and others assume the existence of a loss function without addressing the issue of in what, if any, units the loss is measured.
What are the effects of not being careful about the units in which losses and gains are realized when outcomes are in terms of one set of prizes rather than another? Example 1 is a toy example that will be extended to illustrate a problem that arises whenever one is not careful about how a loss function is actually paid. The example and its extensions will raise serious issues that need to be addressed about whether the loss function is measured in pure numbers or in units with intrinsic values.
Although we focus primarily on statistical decision theory in this article, the issues raised by example 1 and its extensions have wide-ranging consequences in philosophy whenever uncertainty is connected with decision making. For instance, the issues affect how the criterion of coherence (avoiding sure loss when betting) regulates rational degrees of belief (Shimony Reference Shimony1955). The same issues affect how bargaining theory (e.g., the Nash bargaining solution) may regulate ethical standards of fairness (Braithwaite Reference Braithwaite1955; Harsanyi Reference Harsanyi1977).
Example 1. Let  be a partition into two complementary events, E and not-E (denoted E C), sufficient for formulating the following decision problems. Let
 be the set of feasible options with a loss function given by the following table:
| E | E C | |
|---|---|---|
| d 1 | .5 | 2.0 |
| d 2 | 1.0 | 1.0 |
The minimax decision in this problem would appear to be to choose d 2 since the maximum loss is 1, whereas the maximum loss for choosing d 1 is 2. Also, a naive Bayesian who uses a prior distribution with  will make the same decision since the expected loss for choosing d 1 is 1.25, while the expected loss for choosing d 2 is 1.
In this article, we take seriously the question, “In what units will the agent in example 1 (and every other decision problem with a loss function) be charged the stated loss?” There are two natural answers to this question, both of which will be illustrated in versions of example 1, and neither of which is handled in a satisfactory fashion by the popular methods used in statistical decision theory.
Two natural assumptions about the units in which an agent pays a loss function are:
i) The agent must pay an amount of some commodity or currency of value equal to the numerical value of the loss function.
ii) For each combination of decision and state of nature, the agent must pay a specified amount of some commodity or currency. The agent has a cardinal utility function over amounts of said commodity or currency, and the numerical values of the loss function encode the agent’s loss of utility from losing the specified amount of commodity/currency in each of the combinations of decision/state of nature.
There is a third assumption that we will not pursue in this article, namely, that no loss is paid by the agent, and the loss function is just a mathematical construct with no operational meaning.
Assumption ii is a generalization of i, in the sense that the two are essentially the same if the agent’s utility is linear in the units of the commodity/currency. The problems that arise for both interpretations are easily illustrated by extensions of example 1. First, consider assumption i.
Example 2. In example 1, suppose that the loss is paid in a currency C 1, while there is an alternative currency C 2 whose exchange rate with C 1 is given as follows:
• On event E, one unit of C 1 is worth two units of C 2.
• On event E C, one unit of C 1 is worth 0.5 units of C 2.
Suppose that the minimax decision maker prefers to think in units of C 2. The loss function from example 1, converted to units of C 2, is
| E | E C | |
|---|---|---|
| d 1 | 1.0 | 1.0 |
| d 2 | 2.0 | .5 |
The minimax decision is now d 1, even though the two loss functions charge equivalent values under all circumstances. Application of the minimax rule regardless of the units in which losses occur results in inconsistent decision making. If the naive Bayesian in example 1 calculates expected loss independent of the currency, he or she will make the same choices as the minimax decision maker. With currency C 2, the expected losses for decisions d 1 and d 2 are 1.0 and 1.25, respectively.
The seemingly inconsistent decisions in examples 1 and 2 arise from a failure to account for the varying values of one unit of loss from state to state. The minimax theory explicitly treats one unit of loss as being equally important in every state. But the state-dependent exchange rate makes it clear that one unit of loss cannot be equally valuable in both states for both currencies. The minimax decision maker either needs to guarantee that one unit of loss means the same thing in every state or needs explicitly to take into account the varying value of one unit of loss.
Axiomatic derivations of decision theory (e.g., Savage Reference Savage1954; Anscombe and Aumann Reference Anscombe and Aumann1963) make assumption ii explicit by encoding the decision maker’s values through a unit-less, real-valued utility function. These derivations derive the utility by giving privileged status to a particular set of constant acts. These constant acts purport to serve as utility theory’s “rigid rods” (or numeraires, in the language of mathematical finance) for measuring both preference and uncertainty across states of uncertainty. The problem with applying either the theory of Anscombe and Aumann (Reference Anscombe and Aumann1963) or the theory of Savage (Reference Savage1954) in examples 1 and 2 is the choice of numeraire. Either currency C 1 or C 2 can play the role of numeraire, but the mere presence of the other currency violates an assumption of each of the subjective expected utility theories. This violation prevents the identification of a unique representation of an agent’s preference in terms of a single probability and a single utility. The same problem arises when applying bargaining theory in the service of ethics, as in the works of Braithwaite (Reference Braithwaite1955) and Harsanyi (Reference Harsanyi1977). As we explain in section 2, a more general expected utility theory is needed to allow for relative values that change from event to event. Unfortunately, the more general theory makes it clear why it is not possible to compare numerical utility values from one event to the next. For example, regardless of which of the two loss functions (in examples 1 and 2, respectively) corresponds to an agent’s cardinal utility, d 2 costs the agent twice as much as d 1 costs when E occurs. Similarly, d 1 costs twice as much as d 2 costs when E C occurs in both examples. What we cannot say is whether d 1 costs more or less when E occurs than when E C occurs. Such comparisons are not available because they are confounded with the probabilities of the events E and E C. Another extension of example 1 will illustrate this.
Example 3. Suppose that the agent in examples 1 and 2 faces a collection of decision problems, including the one described in those examples. The payments that the agent will be charged will be either one unit of currency C 1 or one unit of currency C 2. Using assumption i to explain what the loss function measures, the decision problem in examples 1 and 2 corresponds to the agent paying one unit of currency C 2 if decision d 1 is made (regardless of whether E or E C occurs) and one unit of currency C 1 if decision d 2 is made (regardless of whether E or E C occurs). The different versions of the loss function in those two examples correspond to different choices of the numeraire. In example 1, the number 1 stands for one unit of C 1 in both events, while in example 2, the number 1 stands for one unit of C 2 in both events. Suppose that the naive Bayesian who used probability  in example 1 were to change the probability to
 and
 in example 2. The expected losses in example 2 would now be 1 for d 1 and 0.8 for d 2. Not only would the agent choose d 2 in both examples, but the ratio of the two expected losses is 0.8 in both examples.
It should come as no surprise that changing the probability used to compute expected loss might change the chosen decision. What happens in example 3 is actually characteristic of every statistical decision problem. When one changes the numeraire (i.e., what counts as one unit of loss), then there is a corresponding change to the probability over the states of nature that will preserve all statistical decisions. We extend example 1 again to illustrate this.
Example 4. There are a total of 16 decision problems involving two decisions, the two events (E and E C), and the two prizes (one unit of either currency) that can be distinguished by what the agent must pay. For this example, we make assumption ii, to explain what the loss function measures, in order to show that the phenomenon of example 3 does not depend on assumption i. Denote the loss from paying one unit of currency i ( ) by L(i, E) or L(i, E C), depending on which event occurs. The loss function for each of the 16 decision problems corresponds to a table similar to those in examples 1 and 2. For decision d j (
 ), let i j(F) denote the currency that the agent must pay (one unit) if he or she makes decision d j and event F (either E or E C) occurs. Then the 16 loss functions all have the form:
| E | E C | |
|---|---|---|
| d 1 | L(i 1(E), E) | L(i 1(E C), E C) |
| d 2 | L(i 2(E), E) | L(i 2(E C), E C) |
Suppose that the agent combines the above loss function with a probability  and
 . Then, the agent chooses d 1 if

He or she chooses d 2 if the opposite inequality holds, and either decision is optimal if the inequality becomes equality.
What we show next is that, no matter how the agent specifies  and p (so long as p is neither 0 nor 1), there are infinitely many alternative choices that lead to identical decisions in all 16 decision problems simultaneously. That is, (1) holds for one choice of L and p if and only if it holds for all of the other choices. Each choice of L and p corresponds to a different choice of numeraire. Let c E and
 be two strictly positive finite numbers. Replace L by
 for
 and
 . Let
 . Replace p by
 so that
 . It is simple to see that (1) holds if and only if

Indeed, the two sides of (2) are merely  times the corresponding sides of (1). Example 3 corresponds to using
 ,
 , and
 to transform the loss table in example 1.
The important point to learn from example 4 is that the relative values of losses on disjoint events are hopelessly confounded with the probabilities of those events. It is meaningless to compare the numerical values of the losses that arise on different events without reference to the probabilities. We can rescale the loss function to make the ratio of losses (even for the same payment) on different events to be any positive finite value we want, without affecting what decisions an agent will make, so long as we modify the probabilities accordingly. Similarly, we can modify the probabilities of any event E (except one whose probability is either 0 or 1) so that  is anything we want. None of this invalidates subjective expected utility theory, as we show in section 2. However, it is difficult to justify treating probability values (other than 0 and 1) as if they had meanings independently of the utility (or loss) function. Similarly, the utility function values do not have meaning independently of the probabilities of events. Rubin (Reference Rubin1987) raised this issue, but exploration of its implications has been limited in the years since. This interaction between the state-dependent value of prizes and a rational agent’s degrees of belief also affects the traditional Dutch Book betting arguments that equate a decision maker’s coherent fair-betting rates with the decision maker’s confirmation function (Shimony Reference Shimony1955).
The examples in this section are simplified decision problems in which some subtle issues have been avoided:
1. How shall we formalize a global utility function that applies simultaneously across different numeraires?
2. What may serve as a numeraire for formulating gambles, and how is the exchange rate between numeraires related to the decision maker’s uncertainty over states?
3. Can preferences be elicited by special loss functions, for example, using scoring rules, in order to identify the decision maker’s quantitative degrees of belief—where degrees of belief are epistemic states that are not indexed by the units in which prizes are given?
In this article, we provide a general theory to answer these questions and others that we identify later on. However, our positive approach does not salvage the inconsistent decisions generated by the minimax theory or by the naive Bayesian’s analysis, where the decision maker’s uncertainty is represented by a probability that ignores the units associated with prizes.
In sections 2 and 3, we address the first two questions in considerable generality. We show how a general theory of maximizing expected utility takes explicit account of the conversion from currencies and commodities of value into pure utility values. We focus on the state-dependent relative values between various currencies and commodities to which attention must be paid in order to avoid inconsistencies like those displayed in examples 1 and 2. Also, in many applications, utility functions are not linear in every currency. We address this in section 4.
Under the theory developed here, in general there is no unique subjective probability that the Bayesian can use in all decision problems without regard to how losses are paid. However, as considered in section 5, we give conditions under which the same decision will be made, regardless of which of several currencies is used for paying the loss. In this connection, in section 6 we investigate elicitation and question 3 (above). We consider special decision problems in which a decision maker is asked to provide a subjective expected value for some random variable. For instance, the decision maker’s degree of belief about an event E is his or her expected value of the indicator function for E. This is the area in which the state-dependent theory has its most striking consequences. The idea common in the work of De Finetti (Reference De Finetti1974) on Brier score and the more general analysis of proper and consistent scoring rules of Savage (Reference Savage1971) and Gneiting (Reference Gneiting2011a, Reference Gneiting2011b) is that one may elicit a decision maker’s degrees of belief about specific random quantities (i.e., the indicator function for E) by providing the decision maker with incentive-compatible losses for the elicitation. However, as we show, this approach needs to be tempered by the realization that the elicited probability is just one of many that form part of a state-dependent expected utility representation of the same preference ordering. We show how the choice of unit for applying the scoring rule affects the elicitation. That is, we show where state-dependent utilities create strategic aspects for elicitation, even with proper/consistent scoring rules.
2. State-Dependent Utility
Let  be a set of states of nature, that is, any partition of the sure event. In a typical mathematical presentation,
 would have a σ-field
 of subsets. Measurable real-valued functions defined on
 are called random variables. Elements of
 are called events, and we allow ourselves the convention of denoting the indicator function of an event
 by the name of the event itself. If P is a probability on (
 ) and X is a random variable, we will allow ourselves the convention of letting
 stand for the expected value of X under
 .
Let  be a set of fortunes for a decision maker with σ-field
 of subsets. A Von Neumann–Morgenstern lottery (NM lottery) L is a stipulated probability distribution (auxiliary randomization) over the set
 . Let
 be a set of functions from
 to the NM lotteries. (See Von Neumann and Morgenstern [Reference Von Neumann and Morgenstern1947] for a discussion of how NM lotteries figure in the axiomatic derivation of decision theory.) An element H of
 is called a horse lottery, following Anscombe and Aumann (Reference Anscombe and Aumann1963). There is one special element of
 that we will call status quo. It stands for the current fortune of a decision maker at the point when he or she is being asked to make the next decision. We assume that, in every state
 there is some fortune better than status quo and some fortune worse than status quo.
Anscombe and Aumann (Reference Anscombe and Aumann1963) prove that an agent’s preferences among simple horse lotteries satisfy some seemingly innocuous conditions, if and only if they can be represented by a unique probability/utility pair. That is, the conditions hold if and only if there is a unique probability P and a unique utility, a bounded function  , with the following property. The agent prefers H 2 to H 1 if and only if

When L is an NM lottery, the meaning of  is
 . Savage (Reference Savage1954) gives an alternative derivation of an expected-utility representation of preference. See Fisburn (Reference Fisburn1970) for an overview of several derivations of expected utility theory.
One of the seemingly innocuous conditions of Anscombe and Aumann (Reference Anscombe and Aumann1963) implies that, almost surely, the relative values of fortunes remain the same as the state of nature changes (state independence). This condition is violated when the fortunes involve different currencies whose values can vary from state to state with positive probability. Without that state-independence condition, the uniqueness of the probability/utility representation is lost, and the utility function must be a more general object of the form to be defined in definition 1 below.
Example 5. Let  . Suppose that $1 can be exchanged cost-free for €0.7 in state 1 and that $1 can be exchanged cost-free for €0.6 in state 2. Suppose also that utility is continuous and increasing in both currencies but is not necessarily linear in either currency. Finally, suppose that a state-independent utility representation for preference, as in (3), gives each state probability 0.5. Let
 ,
 , and
 . Then
 , and
 . Let x be the number of euros that has value c; that is,
 . Then
 . The state-independent utility representation would assign expected utility c to the horse lottery H that gives $1 in state 1 and €x in state 2. But this is unsatisfactory since H is the same as $1 in state 1 and H is strictly more valuable than $1 in state 2, which has positive probability.
State-independent utility representations such as (3) are not capable of representing preferences when the relative values of fortunes vary from state to state. Hence, we introduce the usual generalization to handle such cases. (See Rubin [Reference Rubin1987] for one derivation.)
Definition 1 (State-Dependent Utility). Let  be a collection of mutually absolutely continuous probabilities on
 . Suppose that, for each
 , there is a utility function
 with the following properties.
• For all P,

• For every
,almost surely, where is a scalar that can depend on P 1 and P 2 but nothing else, is some P 2-integrable function of , and is the Radon-Nikodym derivative of P 1 with respect to P 2.

 ,

 is a scalar that can depend on P 1 and P 2 but nothing else,
 is some P 2-integrable function of
 , and
 is the Radon-Nikodym derivative of P 1 with respect to P 2.
The collection  is called a state-dependent expected utility representation of preference over
 . We say that a horse lottery H has state-independent values under
 if
 is constant as a function of
 .
Example 6. Every state-independent expected utility representation of preference extends in a simple fashion to a state-dependent utility. Let P be a probability and let U be a bounded function such that the agent prefers H 2 to H 1 if and only if (3). Let  consist of all probabilities that are mutually absolutely continuous with respect to P. For each
 , define

It is straightforward to see that  satisfies definition 1 with
 and
 .
Throughout this article, we assume that  is as large as possible in the following sense. If
 and P 2 is mutually absolutely continuous with P 1, then
 . This causes no loss of generality because
 is easily constructed from (5). We will also suppress the “almost surely” qualification in equations and formulas that involve Radon-Nikodym derivatives since all probabilities in
 have the same zero-probability sets.
Condition (4) in definition 1 is the state-dependent analog of the requirement that a utility is a bounded function. Even if some  are bounded, the conversion equation (5) allows other
 to be unbounded. Because each utility can be multiplied by a positive constant without changing the representation of preference, (4) means that all expected utilities can be bounded by a common bound. Technically, the condition that utilities are bounded arises as a consequence of such derivations as Savage (Reference Savage1954). If one skips the derivation of expected utility and simply adopts a probability/utility pair (P, U) as in example 6, one need not assume that U is bounded, so long as one can guarantee that the expected utilities of all horse lotteries are finite. This would require restrictions on the set
 of horse lotteries.
Example 7. In example 6, assume that the utility U is unbounded above. For each n, let  be a fortune such that
 . If L 0 is the NM lottery that assigns fortune
 with probability
 , then
 . If
 , then
 will be either infinite or undefined. Clearly, we cannot allow elements of
 to assume NM lotteries like L 0. For infinite spaces, we need further restrictions on
 . Assume that there are disjoint subsets
 of
 such that
 for all n. For each n, let
 be a fortune such that
 . Let
 . That is, for each n and each
 ,
 . Then
 for every natural number m. Hence,
 . In order for
 for all
 , we must prevent H 0 and all similar horse lotteries from being in
 . One way to do that would be to restrict
 to contain only simple horse lotteries, namely, those that assume only finitely many NM lotteries, each of which has finite utility, as in Anscombe and Aumann (Reference Anscombe and Aumann1963).
Rather than impose the types of restrictions discussed in example 7, we assume (4). Seidenfeld, Schervish, and Kadane (Reference Seidenfeld, Schervish and Kadane2009) discuss other problems that arise when utilities are unbounded.
One important consequence of (5) is as follows. Let H 1, H 2 be elements of  . Then, for every
 ,

That is, every probability/utility pair ( ) ranks all horse lotteries the same as every other such pair.
It is easy to see that one can add an arbitrary integrable function of  to a utility or multiply a utility by a positive constant without changing how the utility ranks horse lotteries. We will make a standardization of all utility functions so that
 , for all
 and all P. Hence, status quo has the state-independent value 0 under all utilities. In (5), this makes t 1,2 identically 0 for all P 1 and P 2.
The scalar factor c 1,2 in (5) is an inconvenience that we can do without if we scale all utilities in a standard way. There are uncountably many ways that we could scale. The most convenient way is to pick a single P 0 and force  for all other
 . No matter which P 0 we choose for this purpose, we get
 in (5) for all P 1 and P 2. Also, we still have
 for all P.
With the standardizations above, we see that, for all  , (5) gives

for all P 1 and P 2. In particular for each  and
 , the sign of
 is the same for all P. Also, for every horse lottery H and all
 ,

This is a more convenient (and seemingly stronger) form of (6).
We make heavy use of a special kind of horse lottery in the rest of this article.
Definition 2 (Numeraire). A numeraire is any horse lottery H such that  has the same sign (not 0) for all P and all
 . If that sign is positive, the numeraire is called positive, and if the sign is negative, the numeraire is called negative. The marginal value of a numeraire H is the number

which is the same for all P according to (8).
The name “numeraire” is commonly used in finance to refer to a currency that counts as a unit for various calculations. In section 3.2, numeraires will provide a convenient stand-in for currency values when utilities are nonlinear.
Lemma 1. Let H be a numeraire. Then there is a unique probability/utility pair ( ) such that H has state-independent value
 under
 .
Proof. Let ( ) be a probability/utility pair. Let Q be the probability with
 . It follows from (7) that
 for all
 , and H has state-independent values under U Q. If
 is another probability/utility pair for which H has state-independent values, then
 is constant by (7), and that constant must be 1. So
 and
 . QED
Definition 3. For each numeraire H, we refer to the pair ( ) such that H has state-independent values under U Q as the probability and utility corresponding to H.
Although each numeraire has state-independent values under one and only one utility, each utility may have several numeraires that all have state-independent values. For example, if $1 has state-independent values under a utility, and if that utility is linear in dollar values, then $2 will have state-independent values as well. With a general utility, if H has state-independent values and  , then the numeraire that gives, in each state
 ,
 with probability
 and status quo with probability
 also has state-independent values.
Lemma 1 gives some insight into how to fix the decision making in examples 1 and 2.
Example 8. Reconsider example 1. One unit of currency C 1 is a numeraire as is one unit of C 2. They do not have the same corresponding probability/utility pairs, however. A Bayesian who uses  with one of the two currencies cannot use that same probability with the other currency. The theory does not allow it. Once we introduce general currencies and exchange rates, we can be more specific about the probabilities that correspond to the two currencies in this example.
The minimax decision maker in examples 1 and 2 behaves as if both numeraires have state-independent values, but that is impossible. If one of the numeraires has state-independent values, the other does not. A minimax decision maker needs some way to figure out which numeraire, if either, has state-independent values. Next, we turn to the general concept of currency and how it is related to utility in a state-dependent utility representation of preference.
3. Currency
We give a general definition of currencies, so that we can make precise the dependence of statistical decisions on currency.
Definition 4. A currency is a set C of horse lotteries in one-to-one correspondence with a subset R C of the reals ( ) that satisfies the following conditions.
• R C contains 0.
•
if and only if, for every and every utility U and every , .•
is status quo.
 if and only if, for every
 and every utility U and every
 ,
 .
 is status quo.
Currencies are defined as changes relative to the status quo and in such a way that more is always better. The reason for allowing R C to be a subset of the reals (rather than requiring it to be the whole set of reals) is primarily as follows. In order for utility to be bounded when utility is also linear in currency, we need the set of currency values to be bounded. Definition 5 makes precise what we mean to say, that utility is linear in a currency.
Definition 5. We say that utility is linear in currency C if, for each P, there exists  such that

for all  and all
 . Let
 stand for the class of all currencies C such that utility is linear in C.
Lemma 2, below, shows that (10) holds for a single  if and only if it holds for all P with

3.1. General Results
The first result merely says that currency values are numeraires, and its proof is straightforward.
Proposition 1. If C is a currency, then every element H of C except status quo is a numeraire with sign equal to the sign of  .
The next result is useful when we try to define exchange rates. It says that the state-dependent relative values of two numeraires do not depend on the particular probability/utility pair used to represent preference.
Lemma 2. Let H 1 and H 2 be two numeraires. Then,  is the same for all
 .
 . It follows from

 . Hence, the ratio on the left side of
 ,


3.2. Utility Linear in Currency
The next result exhibits a useful relationship between values of a currency that has linear utility values.
Lemma 3. Let  , and for each
 , let
 , that is, x units of currency C. Then, the probability/utility pair
 corresponding to
 is the same for all
 , and the state-independent value of x units of currency C is
 .
Proof. Let  . Because
 has state-independent values under
 ,
 is constant. Let
 . From (10) and (11), we see that P x must satisfy

which is the same for all  . From (9), we get that the state-independent value of
 is
 . QED
Suppose that the loss function L in a statistical decision problem will be paid as  units of currency C when the agent chooses action q and
 is the state of nature. The agent wants to choose q to maximize

for some  (hence, for all
 ). If
 is not linear in its second argument, maximizing expected utility will bear no relationship to minimizing expected loss. For this reason, we would like to deal only with currencies in
 . Fortunately, there are many currencies in
 . Lemma 4 shows how to construct an element of
 from each pair of positive and negative numeraires.
Lemma 4. Suppose that there exist both a positive numeraire and a negative numeraire. Then there exist (possibly) other positive and negative numeraires H + and H − and a currency C such that utility is linear in the values of C, both H + and H − have the same corresponding probability/utility pairs, and that common probability/utility pair corresponds to every element of C.
Proof. Let  be a negative numeraire, and let
 be a positive numeraire. For each probability
 , let

which is strictly positive for all  . For each
 , let
 . It follows from (7) that
 is the same for all P and that
 . Define
 to be
 with probability
 and status quo with probability
 . Similarly, let
 , which is also the same for all P and
 . Define
 to be
 with probability
 and status quo with probability
 . By construction, we have

hence, H + and H − share a common corresponding probability/utility pair as seen from the proof of lemma 1.
For each  , let
 assign
 with probability
 and status quo with probability
 . For
 , let
 assign
 with probability x and status quo with probability
 . Define
 . First, note that
 and
 satisfy definition 4, so that C is a currency. Also, for
 ,

for all P and all  . Since
 for all P and all
 ,
 in definition 5. The final two claims follow from lemma 3 and the facts that
 and
 . QED
The construction in the proof of lemma 4 was first introduced by Smith (Reference Smith1961), who calls it an adaptation from Savage (Reference Savage1954). Intuitively, the method of Smith (Reference Smith1961) is to replace x units of a currency C′ with an NM lottery that has probability proportional to  of receiving (or paying) a fixed amount and stays in status quo otherwise. The utility of such an NM lottery is proportional to x, regardless of whether
 . In this way, we need only evaluate the utility at a single positive currency value and at a single negative currency value in C′. Next, we show how to make use of this idea in decision problems.
3.3. Paying Loss in a Currency
Consider a statistical decision problem with a set  of available actions and a bounded loss function
 . That is, the decision maker’s fortune will change to
 (in some yet to be named currency) if the chosen action is q and the state of nature is
 . Here, q can be a very general action. For example, q can be a function of random variables whose values will not be observed until some later time, presumably before the loss gets paid. All that is required is that
 is known in time for paying the loss and that there is enough measurability to be able to compute expected values.
Suppose that we want the loss to be paid using a currency C′. Rather than paying directly in units of C′, let  and
 be negative and positive numeraires in C′, respectively, and construct the currency C in lemma 4. Define
 , where M is an upper bound on the loss function. If the agent chooses action q, change the agent’s fortune to
 units of currency C. The agent’s expected utility (15) becomes

We are now in position to state the following key result.
Theorem 1. Suppose either that we construct a currency C as in lemma 4 or that utility is already linear in an existing currency C. Suppose also that a decision problem has a loss function  that is bounded by 1. This means that the agent’s fortune moves to
 units of currency C if the agent chooses action q and the state of nature is
 . Then the agent maximizes expected utility by minimizing expected loss using the probability Q that corresponds to C.
Proof. If the currency C is constructed as in lemma 4, let Q be the probability corresponding to H −. Then for each  ,
 is a positive constant times
 , and (17) is a positive constant times

which is maximized by minimizing expected loss under Q. If utility was already linear in some currency C, then (15) is

which is a positive constant multiple of (18). Hence, maximizing expected utility is the same as minimizing expected loss under Q. QED
If we contemplate different choices for the currency in which the loss is paid, the question arises as to whether some currencies are better for a decision problem than others. We turn to that question in section 6.3. In order to choose between different currencies, we need a scale on which to compare them. The natural comparison between currencies is their exchange rate, which we consider in section 4.
4. Exchange Rates
An obvious problem with exchange rates, in the presence of nonlinear utility, is as follows. Let C 1 and C 2 be currencies. Even if one unit of C 2 is worth x units of C 1, it does not necessarily follow that two units of C 2 are worth  units of C 1. Hence, the exchange rate is difficult to define in a manner that matches how it is used in the foreign exchange market, unless utility is linear in both currencies. We begin the discussion of exchange rates by comparing two numeraires and then extend to currencies in which utility is linear.
Definition 6 (Exchange Rates). Let H 1 and H 2 be numeraires. The conditional exchange rate from H 1 to H 2 is the function  equal to the ratio of their state-dependent values, namely,

which is the same for all P according to lemma 2. The marginal exchange rate from H 1 to H 2 is the ratio of their marginal values  .
One can think of the marginal exchange rate between two numeraires as their relative values at the present time. In general, when the loss function in a decision problem will be paid at some future time, the relative values of various numeraires might change between now and when the loss is paid. In our discussion of decision problems, we think of the conditional exchange rates between numeraires as their future exchange rates at the time when the loss will be paid.
Notice that  and
 . If H 3 is a third numeraire, then
 and
 , as one would expect of exchange rates. Next, we present some natural relationships between conditional and marginal exchange rates.
Lemma 5. Let H 1 and H 2 be numeraires with corresponding probability/utility pairs  and
 . Then

Proof. Let ( ) be a probability/utility pair. From the construction in the proof of lemma 1, we see that
 for
 . It follows that

hence, (21) holds. QED
Lemma 6. Under the conditions of lemma 5,  .
Proof. From lemma 5,

QED
In words, lemma 6 says that the marginal exchange rate from H 1 to H 2 is the mean of the conditional exchange rate with respect to the probability corresponding to the utility that gives H 1 state-independent values.
The remaining results in this section concern the collection  of currencies such that utility is linear in each of the currencies. In the notation of lemma 3, the conditional exchange rate between x units of two different currencies C 1 and C 2 in
 is

for all  . That is, as long as we compare numeraires consisting of the same numerical amounts x of currency, the conditional exchange rate does not depend on the common amount x. Lemma 2 shows that
 does not depend on P, which fact also follows quickly from (11). Use the symbol
 to denote the conditional exchange rate in (23). Let
 stand for the marginal exchange rate from C 1 to C 2.
In the linear case, exchange rates have interpretations much like what we see in foreign exchange. The marginal exchange rate  is the number of units of C 1 that has the same value as one unit of C 2 at the present time. The conditional exchange rate has the same interpretation state by state.
We are now in a position to see how the Bayesian in examples 1 and 2 can clear up the inconsistent choices that were made.
Example 9. Reconsider examples 1 and 2. We have not yet given enough information to determine the probabilities that correspond to each of the two currencies. But we know that they are not the same. First suppose that  is the probability that corresponds to C 1. Let P 2 be the probability that corresponds to C 2. According to lemma 5,

In example 2, we specified  and
 . This makes
 , and

So  and
 .
Using currency C 1, the expected losses for actions a and b are as given in example 1, namely, 1.25 and 1 respectively, and the agent chooses b. Using currency C 2, the expected loss for action a is again 1, while the expected loss for action b is  , and the agent still chooses b, as expected.
For completeness, suppose next that the probability corresponding to C 2 is  , which happens to be the same as P 1 above. Let Q 1 be the probability corresponding to C 1. The conditional exchange rate that we need now is
 ; that is,
 ,
 . The marginal exchange rate is now
 , and

So,  and
 . Using currency C 1, the expected losses for actions a and b are
 and 1, respectively. The agent chooses a. Using currency C 2, the expected losses are 1 and 1.25 (as in example 2), and the agent chooses a again, as expected. We do not know how the minimax decision maker can resolve the inconsistent choices in examples 1 and 2, and we leave it as an open question.
5. When Currency Does Not Matter
There are cases in which the currency used for charging a loss does not affect the decision.
Lemma 7. Assume the conditions of theorem 1. Let  and
 be two currencies in
 with corresponding probability/utility pairs
 and
 and with a marginal exchange rate equal to 1. Then, the following statements are equivalent:
• for each q, the two expected utilities from paying the loss in units of C 1 and C 2 are equal,
•
is uncorrelated with under P 1 for all q,•
is uncorrelated with under P 2 for all q.
 is uncorrelated with
 under P 1 for all q,
 is uncorrelated with
 under P 2 for all q.
Proof. First, we show that the second bullet implies the first and third bullets. Suppose that  is uncorrelated with
 under P 1 for all q. According to lemma 5,
 , so
 is uncorrelated with
 under P 1. Then, for each q,

where the third equality follows from  and
 being uncorrelated under P 1. This establishes the first bullet.
Next, we show that  is uncorrelated with
 under P 2, which is equivalent to showing that
 is uncorrelated with
 under P 2. We have

which is the third bullet. That the third bullet implies the first two follows by repeating the above argument with subscripts 1 and 2 switched.
To complete the proof, it suffices to show that the first bullet implies the second bullet. Suppose that  for all q. Since
 is a constant times
 , we need to show that

The left side of (24) is  , and the right side is
 , which are equal. QED
The ability to apply lemma 7 depends on how complicated the loss function is and how complicated the decision rules  are. If all of the random variables that go into determining the loss (and q) are independent of
 under P 1, then
 is uncorrelated with
 under P 1 for all q, and the lemma says that all actions will be ranked the same, regardless of which currency (C 1 or C 2) is used to pay the loss. Put less technically, if the decision problem is independent of the exchange rate, then it does not matter what currency is used for charging the loss.
6. Elicitation via Proper Scoring Rules
6.1. Elicitation as a Decision Problem
Proper scoring rules were designed to give experts the proper incentives for providing their subjective probabilities and expected values when being elicited. Being scored by a proper scoring rule is a special case of a statistical decision problem.
Definition 7 (Proper Scoring Rule). Let R be a set of real numbers and let  be a measurable space. Let
 be a function such that g(x, q) is measurable in x for all q. For each probability Q over
 and each bounded random variable X, let
 denote the mean of X. Suppose that, for every Q and every X,
 is minimized as a function of q at
 . Then g is a proper scoring rule. If, for every Q,
 is the unique minimizer, then g is strictly proper.
Definition 7 could be extended to allow unbounded random variables, but then one has to deal with the possibility of infinite or undefined means. Although the definition of proper scoring rule above is widely accepted, there is some controversy about what should be called strictly proper. Some authors reserve the qualification “strictly proper” for scoring rules such that are designed to elicit an entire distribution. That is, R in definition 7 is a set of probability measures, and g is strictly proper if and only if  is the unique minimizer of
 for every
 . Gneiting (Reference Gneiting2011a) calls a scoring rule strictly consistent if it satisfies the final clause of definition 7. For the remainder of this article, we will continue to follow definition 7, which matches the usage in Gneiting (Reference Gneiting2011b). The two definitions agree when R is a set of Bernoulli distributions.
Suppose that we wish to learn a particular agent’s subjective expectation for a random variable X (possibly the indicator of an event). Let g be a strictly proper scoring rule. We can create a statistical decision problem with loss function  . If we were able to convince the agent to provide us with the value q that minimizes
 , where P is the agent’s subjective probability distribution, we would learn
 , according to the definition of proper scoring rule. But theorem 1 says that the solution to a statistical decision problem depends on which currency is used for charging the loss (score). If the agent is being given the proper incentive for providing his or her subjective probability of an event, then how can the elicited probability depend on which currency is being used for scoring?
The answer is straightforward. Minimizing expected score is the same as maximizing expected utility, only when the probability/utility pair corresponds to the currency used for scoring. Using different currencies creates different decision problems for the agent. These different decision problems can have different solutions. The confusion arises from mistakenly treating the scores as pure (unit-less) numbers, regardless of how their values change from state to state.
Chapter 6 of Degroot (Reference Degroot1970) constructs a unique subjective probability P without reference to changes in an agent’s fortunes. Then chapter 7 of Degroot (Reference Degroot1970) goes on to construct a state-independent utility. A more complicated theory of Karni, Schmeidler, and Vind (Reference Karni, Schmeidler and Vind1983) and Schervish, Kadane, and Seidenfeld (Reference Schervish, Kadane and Seidenfeld1991) allows the construction of a unique probability and state-dependent utility  . Suppose that an agent believes that he or she has constructed a unique probability and utility
 by one of these methods or by some other method. If we attempt to elicit
 from this agent using a strictly proper scoring rule, we will not be successful, unless we already know enough about
 to choose a currency with state-independent values.
Lemma 7 has a simpler form when restricted to elicitation via proper scoring rules.
Proposition 2. Let  and
 be two currencies with corresponding probability/utility pairs
 and
 . Then the following items are equivalent:
•
,• X is uncorrelated with
under P 1,• X is uncorrelated with
under P 2.
 ,
 under P 1,
 under P 2.
The proof of proposition 2 is similar to that of lemma 7 and will not be given.
One can elicit other aspects of a probability distribution, such as quantiles, using other loss functions. For example, if  , then
 is minimized over q by setting q equal to any median of the distribution of X under P. For more general quantiles, one can use loss functions of the form

where  . In this case,
 is minimized by setting q equal to any
 quantile of the distribution of X under P. In such a decision problem, if the loss is settled in a currency, the quantile elicited will be from the probability corresponding to the currency.
6.2. Strategic Choices in Elicitation
De Finetti (Reference De Finetti1974, 93) noticed a shortcoming of the use of gambles for elicitation and preferred to use a proper scoring rule. When an agent is gambling, there is an opponent who gets to choose which side of the gamble to take. Suppose that the agent has reason to believe that the opponent has a higher mean for the random variable of interest than does the agent. Then the agent will have an incentive to specify a slightly higher value than his or her true mean. Here is an example.
Example 10. In the gambling formulation of elicitation, the agent is asked to specify the mean  of a random variable X, with the understanding that the agent then feels that it is fair to receive
 in state
 , where the real scalar
 is chosen by an opponent. For example, suppose that the agent thinks that
 meets the above condition, but the agent is certain that the opponent would choose
 if it were up to the opponent. So, the agent feels that
 would be advantageous to receive, as it is 0.1 higher than the fair value of
 . Also, the opponent (in the opinion of the agent) would think it is advantageous to receive
 , as it is 0.1 higher than the fair
 . In this case, the agent has an incentive to specify a value of
 that is higher than his or her mean of X; hence, the gambling formulation would fail to provide a proper elicitation in this case.
Strategic considerations of the sort in example 10 can undermine the value of gambling as an elicitation method. Scoring rules do not involve an opponent who has any decisions that should influence the agent. For this reason, de Finetti believed that scoring rules should be preferred to gambles as a means of elicitation. Using gambles to elicit probabilities in finite spaces also leads to the same dependence on currency that we noticed above, as shown by Schervish, Seidenfeld, and Kadane (Reference Schervish, Seidenfeld and Kadane1990). In this article, we have extended the results of Schervish et al. (Reference Schervish, Seidenfeld and Kadane1990) to proper scoring rules as well as to all statistical decision problems, even in general spaces. Next, we show that a different set of strategic considerations arises when using scoring rules to elicit probabilities.
6.3. Strategic Choice of Currency
Suppose that we wish to elicit the mean of a random variable from an agent who is given the choice of currency in which to be scored before announcing the mean. Are some currency choices better than others? Without further conditions, the answer is an obvious yes. Surely it is better to pay a score of x units in pennies than to pay x units in dollars. To avoid such trivial answers, we need to standardize currencies somehow and compare only those currencies that are of the same size according to the standardization. But even that appears not to be enough to prevent strategic choice of currency.
Example 11. Let  . Suppose that we are trying to elicit the probability of the event
 . That is,
 is the indicator of F. Suppose that we are using Brier score,
 . Suppose also that we assume that utility is linear in all of the currencies that we use in this example. Let P 1 be the probability corresponding to a currency C 1 having state-independent values, and let
 . Suppose that P 1 is the uniform distribution on (0, 1). If the agent chooses to be scored in currency C 1, then
 , and the expected Brier score is
 .
Each alternative currency C 2 corresponds to a conditional exchange rate  that is integrable with respect to P 1. The corresponding probability P 2 that gives currency C 2 state-independent values has
 , where
 is the marginal exchange rate. If the agent chooses to be scored in currency C 2, the probability is

For example, suppose that we consider a currency C 2 with  so that
 . Then
 , and the expected Brier score under P 2 is
 . Since the marginal exchange rate is 1, paying 3/16 units of C 2 is preferred to paying 1/2 unit of C 1.
Taking the above comparison between C 1 and C 2 further, let C n be a currency with  . Then
 ,
 , and
 . The differences between the expected scores in currencies C 1 and C n cannot be explained by the marginal exchange rate between the two currencies since the marginal exchange rates are all 1. What is happening is that C n is essentially worthless (when measured in units of C 1) if F occurs. The agent announces a very small probability of F and agrees to pay a large score in currency C n if F occurs. But such a large score is not worth much in other currencies. If F C occurs, making C n more valuable relative to other currencies, the agent does not have to pay very much in units of C n because
 is close to 1.
The same strategic consideration, that is, choice of currency, does not arise when using gambles for elicitation. In that formulation, the gambles to which an agent commits are all fair, regardless of in what currency they are settled. Without a secondary criterion with which to distinguish fair gambles, there is no way to choose among them.
6.4. Choice of Scoring Rule
Another strategic consideration arises if the agent is given the choice of which scoring rule will be used to score the elicitation. Clearly, scaling a scoring rule down is advantageous to the agent being scored. In order to compare scoring rules that are comparable in terms of the payout, we need an appropriate standardization. One naive standardization is to scale by  .
For simplicity, consider the case in which X is the indicator of some event. According to theorem 4.2 of Schervish (Reference Schervish1989), every bounded left-continuous strictly proper scoring rule with  for
 has the form

for some measure  on [0, 1] that assigns a positive measure to every nondegenerate interval. In order for
 , we need
 to be two times a probability that has mean of 1/2. By choosing
 to put as much of its mass as possible near the two extreme values of 0 and 1, the expected score can be made as close as one likes to 0, no matter what q happens to be. Hence, the agent would like to be scored by a rule corresponding to such a
 , regardless of the currency.
An alternative normalization of scoring rules is to use the maximin expected score. That is, normalize by  . In this case, the expected score will lie on a strictly concave curve m on [0, 1], with a maximum value of 1 and satisfying
 . If
 , then the curve m lies strictly above the piecewise linear function
 (except for
 , where
 ). We can make
 arbitrarily close to
 , by making
 concentrate its mass arbitrarily close to
 . In such a case, if the agent’s subjective probability of the event being forecast is q, then the best expected score will be approximately
 , which will be minimized by choosing
 so that
 if
 and
 if
 . If
 , either
 or
 will do equally well. If the agent also gets to choose the currency along with the scoring rule, he or she would choose a currency such that q is as close to 0 or 1 as is feasible and match it with a scoring rule that made the optimal expected score as close as possible to 0 near that q. In the gambling framework, there is no obvious strategic counterpart to the choice of the scoring rule on the part of the agent being scored.
6.5. Converting between Currencies
Our results show that a mean elicited by a scoring rule comes from the probability P associated with the utility  that gives state-independent values to the currency used for eliciting. In general, it is not possible to infer
 from
 , even if we know the conditional exchange rate between the two currencies
 and
 that have state-independent values under P and Q, respectively. Even when X is the indicator of an event F, we have

It is true that

but we still need to know P for all subsets of the event F, not just  (unless
 is constant over F or F C). In general,

which can also be written as  .
6.6. Finite State Spaces
In finite state spaces, we can make a bit more progress. Let  . Schervish et al. (Reference Schervish, Seidenfeld and Kadane1990) dealt with this case, and the events whose probabilities were being elicited (via gambles) were singletons
 . In such cases,
 is constant on singletons; hence, we can convert probabilities of singletons from one currency to the next if both the conditional exchange rate and the marginal exchange rate are known. If the probabilities of all singletons are elicited in the same currency, then the marginal exchange rate can be computed from the conditional exchange rate. If the probability of each singleton is elicited in a (possibly) different currency, one can set up a system of equations whose solution will give the necessary marginal exchange rates.
To be specific, suppose that the probability of  is elicited in currency C i for
 with corresponding probabilities
 . Let C 0 be a currency with corresponding probability P 0. We assume that we know
 for all i, even if we do not know
 . So, we elicit
 for
 . As in (27),

For each i, we can set up an equation giving the value of  . According to (22) and then (29),

For  , (30) gives us n linear equations in (at most) n unknowns
 for
 . The equations are linearly dependent, and every scalar multiple of each solution is also a solution. The appropriate scaling can be determined from the fact that
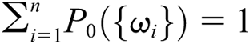 . If two or more events were elicited in the same currency, there will be further linear dependence, which could be removed by using only one equation for each unique currency.
7. Discussion
This article explores implications of the fact that preferences between Anscombe and Aumann (Reference Anscombe and Aumann1963) style horse lotteries cannot reveal a unique probability and state-independent utility in the presence of numeraires with state-dependent values. The most that one can determine is a state-dependent expected utility representation in the form of definition 1. Even an agent who believes that they have a unique probability and state-dependent utility  cannot ignore the units in which losses are paid in a statistical decision problem. The formal solution to a decision problem as if the losses were unit-less pure numbers will not match the agent’s solution, unless the loss is paid in a currency that has state-independent values under
 .
Schervish et al. (Reference Schervish, Seidenfeld and Kadane1990) considered elicitation via gambles, but the current article shows that general statistical decision problems suffer from possible state dependence of the currency used for charging the loss. When one pays the loss in a particular currency C, then a Bayesian will solve the decision problem using the probability Q, where  is the particular state-dependent utility representation of the agent’s preferences such that currency C has state-independent values under
 . If one changes the currency to C′ and
 is an equivalent state-dependent utility for which C′ has state-independent values under
 , then the agent will solve the decision problem using probability Q′. Lemma 7 and proposition 2 give conditions under which the solutions to various decision problems will not depend on the currency in which the loss is paid.
We examine elicitation of subjective probability in detail because the implications of state-dependent utility are so striking for elicitation. Under some restrictive conditions, one can convert means elicited in one currency to means that would have been elicited in another currency. But, one cannot elicit an agent’s “true subjective probability” (whatever that means) unless that probability happens to correspond to the state-dependent utility that gives state-independent values to the currency in which one does the elicitation. If the random variable whose prevision is being elicited is uncorrelated with the conditional exchange rate between two currencies, then the same prevision will be elicited using either currency. If one is to take seriously the idea that elicited probabilities stand for something that can be used for statistical inference, one needs to be confident that those probabilities were derived in a manner consistent with their intended use. If it is possible to constrain the effects of the decisions so that they do not involve fortunes whose relative values vary from state to state, then one can feel safe that probabilities elicited using such fortunes as currency values will be meaningful. The challenge is making sure that the decision problem is so constrained.
Additional work is needed in order to identify the implications of state dependence on decision problems with multiple decision points. For example, an agent may get the opportunity to revise a decision after learning additional information. The agent may be asked to make several decisions at different times. It is well known that exchange rates change over time, and it makes sense to model exchange rates as stochastic processes. In this article, we have considered only two times, namely, when the decision is made and when the loss is paid. We also believe that state dependence has implications for financial product pricing, especially in the foreign exchange market.
Finally, we have presented some results concerning strategic choices that an agent might make when being scored, but we have not yet studied strategic choices that are available to the elicitor who is requesting the elicited prevision. Such a study could proceed if we specified how the elicited prevision was going to affect the elicitor as well as his or her state-dependent utility representation and his or her opinion of the agent. This problem is left for future study.


