


1. Introduction
Researchers in applied fields often face the task of evaluating how common (macro) factors influence various disaggregated or individual economic results. Examples include understanding the impact of global liquidity changes on international capital movements (Avdjiev et al. (Reference Avdjiev, Gambacorta, Goldberg and Schiaffi2020)), assessing how changes in macroeconomic conditions alter the behaviors of banks and firms (Jiménez et al. (Reference Jiménez, Ongena, Peydró and Saurina2012); Gulen and Ion (Reference Gulen and Ion2016)), and examining how US financial uncertainty affects global economic growth (Carrière-Swallow and Céspedes (Reference Carrière-Swallow and Céspedes2013); Choi (Reference Choi2018); Berg and Vu (Reference Berg and Vu2019); Bhattarai et al. (Reference Bhattarai, Chatterjee and Park2020)). Analyzing these common factors is crucial for empirical studies and can have significant policy implications.
Traditional empirical approaches estimate the effect of common regressors using conditional mean regression models. This implicitly assumes that other conditional moments of the dependent variable, besides the mean, remain unchanged in response to variations in the common regressors. However, limiting the analysis to the mean can obscure the impact of these common regressors on the entire conditional distribution. Indeed, recent studies have found that much economic data is left-skewed, indicating that downturns tend to be rapid and severe. For instance, Adrian et al. (Reference Adrian, Grinberg, Liang, Malik and Yu2022) demonstrate that financial conditions significantly affect the lower fifth percentile of conditional growth more than the median. Although rare, extreme events can incur substantial economic costs. Therefore, it is important to broaden empirical analyses to investigate the potential effects of common regressors on higher moments, which characterize tail regions of the distribution of economic outcomes.
Moreover, common regressors may exhibit non-constant effects on the conditional distribution. For instance, financial instability in the US tends to have global repercussions, with its effects potentially fluctuating over different periods. One possible reason is that a surge in domestic financial uncertainty can lead to tighter domestic or foreign credit conditions, which crucially depends on market participants’ expectations, as we show in the empirical application. Since nonlinearity can occur in all conditional moments under consideration, the common regressor can have different effects on various parts of the conditional distribution.
In this paper, we introduce a semiparametric panel model, designed to investigate potential time-varying effects of common regressors on the conditional distribution of economic outcomes. Our model has three notable features. First, it allows common regressors to influence the conditional distribution of the dependent variable through its mean, variance, and skewness functions. This feature shares a similar spirit to a recent study by Badunenko and Henderson (Reference Badunenko and Henderson2024), who model heterogeneous variance and skewness in the noise distribution of production or cost functions. Second, the impact of common regressors within each conditional moment function is time-varying, driven by contextual variables we call effect modifiers. This specification enables the coefficients of common regressors to be functions of the effect modifiers, facilitating empirical investigation of the underlying drivers of time-varying effects. Third, our model addresses possible serial correlation by incorporating a dynamic structure, wherein the lagged dependent variable enters the conditional mean function linearly along with other control variables. Additionally, our model includes fixed effects to account for unobserved heterogeneity across individuals, thereby mitigating potential issues related to omitted time-invariant variables.
Estimating our proposed model presents three econometric challenges. First, incorporating the effect of common regressors on the conditional distribution requires introducing a skewed error component. The conditional moment functions (i.e., mean, variance, skewness) of the skewed error are determined by the common regressors and their associated effect modifiers. Since a skewed random variable lacks a zero conditional mean, conventional estimators cannot be directly applied because the model does not conform to a standard regression framework. Second, the coefficient functions of common regressors are typically unknown in practice. Conventionally, parameterized coefficient functions (e.g., linear functions of effect modifiers) of common regressors are popular structures in applied studies. Though parsimonious, the linear coefficient functions are pre-specified by empirical practitioners rather than guided by economic theories. Misspecified parametric coefficient functions lead to inconsistent estimates and misleading conclusions. To address this issue, we increase the flexibility of our model by incorporating nonparametric coefficient functions of common regressors in the conditional mean. The nonparametrization allows for any nonlinear functional form of the time-varying effect to be revealed by the data rather than being predetermined by arbitrary choices. We also employ flexible polynomial functions in conditional variance and skewness to achieve model identification, given the complex nature of higher-moment functions. Third, the presence of dynamic variables and individual fixed effects in a semiparametric model introduces a non-negligible bias in our estimator, requiring careful handling to achieve consistent estimation.
To address these methodological challenges, we introduce an innovative two-step procedure for model estimation. In the first step, we estimate the unknown parameters governing the conditional moment functions using a pseudo-maximum likelihood estimator (pseudo-MLE). Our pseudo-MLE construction is based on a within-transformation that eliminates all common components in the mean function, rendering it robust to potential misspecification of coefficient functions. In the second step, we estimate nonparametrically the effect of common regressors in the mean function using a profile local linear estimator. This two-step approach mitigates the risk of misspecifying unknown model structures, thereby ensuring consistent estimates of interest.
We apply our model to investigate the effect of US financial uncertainty on the conditional distribution of global future output growth. In our application, the effect modifier of US financial uncertainty reflects market participants’ economic expectations. Inspired by Huang and Luo (Reference Huang and Luo2020b), we construct the effect modifier as the ratio of good to bad volatility in the US stock market, based on the maximum and minimum monthly stock returns.Footnote 1 Employing a panel dataset of 30 developed and developing countries over nearly three decades, our findings reveal that US financial uncertainty has notable time-varying and nonlinear effects on various aspects of the conditional distribution of global future output growth. During periods of pessimism, US financial uncertainty shifts the entire conditional distribution downward, with a greater impact on the lower percentiles, particularly the fifth percentile, compared to the ninety-fifth percentile. This results in a left-skewed distribution, suggesting a higher likelihood of negative economic outcomes. Conversely, during periods of optimism, heightened US financial uncertainty causes the conditional distribution to stretch out while only slightly shifting to the left. In this scenario, an increase in US financial uncertainty significantly decreases the fifth percentile but increases the ninety-fifth percentile, indicating a rise in overall global economic uncertainty.
From an empirical perspective, our findings contribute to the literature by demonstrating that heightened US financial uncertainty significantly affects global economic activities, influencing not only the conditional mean but also the conditional variance and skewness of the global output growth distribution. Our findings complement two key aspects of the recent empirical literature. First, the link between macroeconomic and financial uncertainty has been identified in a domestic context (Ludvigson et al. (Reference Ludvigson, Ma and Ng2021); Caggiano et al. (Reference Caggiano, Castelnuovo, Delrio and Kima2021)), and we find that this correlation extends beyond the border. Our results indicate that global macro uncertainty, proxied by the second moment of the conditional distribution of world output growth, also rises, therefore providing empirical evidence for a global macro-financial uncertainty linkage. Second, financial conditions have been found to affect tail risks for predicted GDP growth (Adrian et al. (Reference Adrian, Boyarchenko and Giannone2019); Adrian et al. (Reference Adrian, Grinberg, Liang, Malik and Yu2022)). In particular, Adrian et al. (Reference Adrian, Grinberg, Liang, Malik and Yu2022) find that financial conditions have a larger effect on the lower fifth percentile of conditional growth, called growth-at-risk (GaR), than the median. We take financial conditions as the channel through which US financial uncertainty spills over to the rest of the world, finding GaR to be more responsive compared to the median. Consistent with existing empirical findings, our results highlight significant variations in both the lower and upper percentiles due to the flexibility of our semiparametric model.
From a methodology viewpoint, we contribute to the literature by introducing a semiparametric dynamic skewed panel model. Our model accommodates the effects of common regressors on the conditional distribution, allowing these effects to be nonlinear and time-varying, and incorporates both a dynamic structure and country-specific unobserved heterogeneity. Using the properties of common regressors, we propose a consistent two-step estimator for parametric and nonparametric components while properly handling the bias introduced by the dynamic variables and fixed effects. To broaden the appeal of the model, we characterize the asymptotic properties of the two-step estimator and demonstrate its promising numerical properties through simulation studies.
Our proposed empirical methodology provides a useful framework for understanding the complexities of macroeconomic issues using microeconomic datasets. In our application, the extent to which US financial uncertainty affects the global economy is likely shaped by different expectations among market participants, proxied using S&P 500 Index. Similarly, our model can be utilized to investigate the impact of global liquidity drivers on international capital flows, analyzing how these drivers work through financial markets worldwide (Avdjiev et al. (Reference Avdjiev, Gambacorta, Goldberg and Schiaffi2020)). The use of more granular data can facilitate deeper insights. For example, Jiménez et al. (Reference Jiménez, Ongena, Peydró and Saurina2012) analyze the impact of monetary policy by employing loan-level data; Gulen and Ion (Reference Gulen and Ion2016) investigate how economic policy uncertainty affects investment using firm-specific data; and Tarkom and Ujah (Reference Tarkom and Ujah2023) examine how macroeconomic policy uncertainty influences firm efficiency, which is intimately linked to firm productivity. In each case, our model extends beyond the scope of existing studies by accommodating nonlinear changes in distribution–specifically regarding mean, dispersion, and skewness–driven by common regressors, meanwhile exploring how these changes interact with effect modifiers through micro-channels. Thus, our empirical modeling approach can be helpful for analyses involving tail risk and may shed some new light on various traditional issues.
The remainder of the paper is organized as follows. Section 2 introduces our proposed empirical model and outlines the estimation procedure. Section 3 characterizes the asymptotic properties of the proposed estimators. Section 4 details the data and constructions of key variables in our empirical application and presents empirical results evidence for the nonlinear effects of US financial uncertainty. Finally, Section 5 concludes the paper. All proofs and simulation results associated with the model estimator are relegated to the Online Appendix.
2. A semiparametric dynamic skewed panel model
This section presents an empirical approach to analyze the impact of typical macroeconomic variables on the distribution of key economic outcomes. The model is detailed in Section 2.1, with the estimators illustrated in Section 2.2.
2.1. Model
Our empirical methodology is based on the following semiparametric dynamic skewed panel model:
 \begin{align} y_{i,t}=\beta _0+x_t\beta (z_t)+\omega _{i,t}^{\top }\delta _{0}+\alpha _{0i}+e_{i,t}, \end{align}
where  $i=1,\ldots, n$ and
 $t=1,\ldots, T$ index a total of
 $ n$ individuals and
 $ T$ time units, respectively. The dependent variable
 $y_{i,t}$ is the aggregate or disaggregate economic outcome variable. The common regressor,
 $ x_t$, represents a certain macroeconomic condition that affects all agents in the economy. We generalize the effect of
 $ x_t$ beyond a constant and let it vary with an effect modifier
 $z_t$ through an unknown coefficient function
 $ \beta ({\cdot})$.Footnote 2 While a common approach in applied studies assumes a parametric specification, i.e.,
 $ \beta (z_t)=z_t\beta _1$ known up to a constant coefficient
 $ \beta _1$, such linearity assumptions are made a priori and may be difficult to justify given an unknown data generation process. To address potential model misspecification, we specify the functional form of
 $ \beta ({\cdot})$ nonparametrically, allowing an arbitrary nonlinear structure and nesting the linear structure as a special case. Additionally, we include a global constant
 $ \beta _0$, a random vector of control variables
 $ \omega _{i,t}\in \Re ^{d_w}$ that includes lagged dependent variable
 $ y_{i,t-1}$, and fixed effects
 $ \alpha _{0i}$ capturing unobserved country heterogeneity. Here, we adopt a fixed effect model assuming
 $ E(\alpha _{0i}|x_t,z_t,\omega _{i,t})\neq 0$, thus capturing arbitrary correlation between the fixed effects and all other variables in the model.
It is clear that both  $x_t$ and
 $z_t$ in (1) influence the conditional mean of
 $y_{i,t}$. Building on our earlier discussion, we extend the roles of both
 $x_t$ and
 $z_t$ to include their effects on conditional variance and skewness, which are essential for capturing their joint influence on the entire conditional distribution of
 $y_{i,t}$. To achieve this, we specify a skew normal (SN) distribution for the error term in (1), i.e.,
 \begin{equation} \quad e_{i,t}\sim SN\!\left(\xi _t,\sigma (x_t, z_t),\lambda (x_t, z_t)\right), \end{equation}
where  $SN(\xi _t, \sigma _t, \lambda _t)$ denotes a SN distribution characterized by three time-varying functions: the location function
 $\xi _t$ indicates the central point around which
 $e_{i,t}$ is distributed either symmetrically or asymmetrically; the scale function
 $\sigma _t \equiv \sigma (x_t, z_t) \gt 0$ measures the degree of dispersion in a usual sense under a normal distribution; and the shape function
 $\lambda _t \equiv \lambda (x_t, z_t)$ controls for the degree of skewness, where
 $\lambda _t \gt 0$ (
 $\lambda _t \lt 0$) introduces right (left) skew in the density of
 $e_{i,t}$. If
 $\lambda _t = 0$ for a given
 $t$, the SN distribution degenerates into a normal distribution
 $N(\xi _t, \sigma _t)$. Thus, we set
 $\xi _t = 0$ in our study to “anchor” the location of the SN, ensuring that when there is no skewness,
 $e_{i,t} \sim N(0, \sigma _t)$ satisfies a conventional normality assumption in MLE regression models. In this way, a zero location point facilitates a straightforward comparison of tail differences between the SN and conventional normal distributions.
Compared to alternative skewed distributions, we adopt the SN distribution for four main reasons. First, it has well-established theoretical properties (Azzalini and Capitanio (Reference Capitanio and Azzalini2003)), allowing its higher moments to be easily specified and estimated as parametric functions of variables of interest. Second, its favorable characteristics have motivated numerous recent studies aimed at characterizing asymmetric distributions in various contexts (e.g., Wang and Ho (Reference Wang and Ho2010); Huang and Luo (Reference Huang and Luo2020b); Badunenko and Henderson (Reference Badunenko and Henderson2024)). Third, for given parameters  $\xi _t$ and
 $\sigma _t$, a nonzero
 $\lambda _t$ smoothly transitions the distribution of
 $e_{i,t}$ from normal (with symmetric tails) to skew normal (with asymmetric tails), effectively highlighting the roles of
 $x$ and
 $z$ in the tail regions compared to a normal distribution as a benchmark. Finally, it can be skewed in either the right or left direction, accommodating the unknown effects of variables on tails. This feature provides greater flexibility than other asymmetric distributions, such as exponential, Gamma, chi-squared, log-normal, Weibull, and logistic distributions, which have a fixed tail direction.
In general, both conditional variance and skewness in (2) are unknown functions of  $x_t$ and
 $z_t$. To increase the flexibility of functional form, it would be appealing to allow
 $\sigma ({\cdot})$ and
 $\lambda ({\cdot})$ to take a smooth coefficient structure as in the conditional mean of (1) (see, e.g., Henderson, Reference Henderson2007) for nonparametric estimation of higher conditional moments of inefficiency in the production function). However, modeling both
 $\sigma ({\cdot})$ and
 $\lambda ({\cdot})$ nonparametrically leads to individual identification problems.Footnote 3 In our study,
 $x_t$ and
 $z_t$ are likely to influence both variance and skewness of the distribution, so the separation of which is important for our empirical investigation. Following the conventions in the literature, we consider the parametric structures in
 $\sigma ({\cdot})$ and
 $\lambda ({\cdot})$ in (2) as
 \begin{align} \sigma (x_t,z_t;\,\gamma _{0\sigma })=\exp (c_{0\sigma }+x_t\gamma _\sigma (z_t)),\quad \lambda (x_t,z_t;\,\gamma _{0\lambda })=c_{0\lambda }+x_t\gamma _\lambda (z_t), \end{align}
where for  $j\in \{\sigma, \lambda \}$,
 $\gamma _j(z_t)=\sum _{k=0}^{K_j}z^k_t\gamma _{0j,k}$ measures the marginal effect of
 $ x_t$ through a
 $K_j$-th degree polynomial function of
 $ z_t$ known up to a finite vector
 $ \gamma _{0j}=(c_{0j},\gamma _{0j,0},\gamma _{0j,1},\ldots, \gamma _{0j,K_j})$. Compared to the nonparametric smooth coefficient
 $\beta (z_t)$ in the conditional mean function, the coefficient of
 $ x_t$ in the conditional variance and skewness functions is modified through parametric coefficient functions
 $\gamma _j(z_t)$. The structure in (3) allows all parameters
 $ \gamma _{0j}$ to be uniquely identified while imposing the non-negativity constraint in
 $\sigma ({\cdot})$ through an exponential structure.
Our models (1)–(2) are appropriate for meeting our empirical goal. Through smooth coefficient structures (either nonparametric in (1) or parametric in (2)), we allow  $x_t$ to affect the conditional mean, variance, and skewness function of the distribution of
 $ y_{i,t}$ in a nonlinear fashion. The SN distribution of (2) deviates from the conventional normality assumption, facilitating our investigation of skewness change driven by
 $ x_t$ and
 $ z_t$ through modeling their higher conditional moments. Furthermore, the parametric structure of all moment functions provides a convenient approach for connecting the higher moments of
 $e_{i,t}$ to variables of interest, and offer a viable parametric alternative to distribution-free quantile regression (Mikkel and Thomas (Reference Plagborg-Moller and Thomas2020)).
2.2. A two-step estimator
Our model structure in (1) does not follow its conventional form in the literature (see, for instance, Li et al. (Reference Li, Huang, Li and Fu2002)), since the nonlinear component only takes common variables  $ (x_t,z_t)$, and the linear component takes both time and individual variant variables (
 $w_{i,t}$) including a lagged dependent variable. Furthermore, as
 $ n$ gets large, the fixed effect
 $ \alpha _i$ needs to be properly handled to avoid the incidental parameter problem. We propose estimating
 $ \alpha _i$ using dummy variables, which is consistent provided that
 $ T\rightarrow \infty$ is faster than
 $n$ to offer sufficient information in time dimension for each fixed effect (Wooldridge (Reference Wooldridge2010)).
Let  $ \alpha _0=[\alpha _{01},\ldots, \alpha _{0n}]^{\top }$. For identification purposes, we impose the normalization condition
 $\sum _{i=1}^{n}\alpha _i=0$ (Su and Ullah (Reference Su and Ullah2006); Sun et al. (Reference Sun, Carroll and Li2009)). This forms a
 $(n-1)\times 1$ dummy vector
 $ d_{i,-1}$, which takes a value of
 $-1$ for
 $i=1$, and
 $1$ in the
 $i^{th}$ element and zero otherwise for
 $i=2,\ldots, n$. Consequently, we replace
 $ \alpha _0$ with
 $ \alpha _{0,-1}$ removing the first element of
 $ \alpha$, so the first fixed effect can be recovered through
 $a_{01}=-\sum _{i=2}^{n}\alpha _{0i}$. As in (3), we define
 $ \gamma _0=(\gamma _{0\lambda }^{\top },\gamma _{0\sigma }^{\top })$ of dimension
 $K_\lambda +K_\sigma +4$ as the true coefficients that govern the distribution of
 $e_{i,t}$. Let
 $\theta _0=(\delta _{0}^{\top },\gamma _0^{\top })$ of dimension
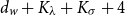 $d_w+K_\lambda +K_\sigma +4$ combines all the parameters except fixed effects and
 $\beta _0$, and define
 $\vartheta _0=(\theta _0^{\top },\alpha _{0,-1}^{\top })$. In the following, we propose a two-step estimator of
 $\vartheta _0$ and
 $(\beta _0,\beta ({\cdot}))$.
2.2.1. Step 1: estimating  $\vartheta _0$ through pseudo-MLE

In the first step, we estimate  $ \vartheta _0$ using a pseudo-MLE. As mentioned above, the unknown coefficient function
 $\beta ({\cdot})$ in (1) impedes direct implementation of conventional MLE for
 $ \vartheta _0$. To proceed, we perform a within-transformation with respect to individuals to wipe out common components
 $ \beta _0$ and
 $ x_t\beta (z_t)$ as
 \begin{equation} y_{i,t}-\frac{1}{n}\overset{n}{\underset{i=1}{\sum }} y_{i,t}=\left(\omega _{i,t}-\frac{1}{n}\overset{n}{\underset{i=1}{\sum }} \omega _{i,t}\right)^{\top }\delta +d_{i,-1}^{\top }\alpha _{0,-1}+e_{i,t}-\frac{1}{n}\overset{n}{\underset{i=1}{\sum }} e_{i,t}, \end{equation}
where the term  $n^{-1}\sum _{i=1}^{n}d_{i,-1}$ is a zero vector by our construction above.Footnote 4 Given our specifications in (3),
 \begin{equation} E(e_{i,t})\equiv \mu (x_t,z_t;\,\gamma _0)=\sqrt{\frac{2}{\pi }}\sigma (x_t,z_t;\,\gamma _0)\lambda (x_t,z_t;\,\gamma _0)/\sqrt{1+\lambda (x_t,z_t;\,\gamma _0)^{2}}, \end{equation}
which is known up to  $ \gamma _0$. Let
 $ \tilde{\zeta }_{i,t}=\zeta _{i,t}-\bar{\zeta }_t$ be a shorthand notation for within-transformed variable
 $ \zeta _{i,t}$ with
 $ \bar{\zeta }_t=\frac{1}{n}\sum _{i=1}^{n}\zeta _{i,t}$. Since
 $ \bar{e}_{i,t}$ in (4) is unobserved, we assume identical and independent distribution (i.i.d,) over individuals, and replace
 $ \bar{e}_{i,t}$ with its probability limit
 $\mu (x_t,z_t;\,\gamma _0)$ in (5) by the weak law of large number. This implies that the SN distribution of
 $e_{i,t}$ is governed by
 $\vartheta _0$. Define
 $ \Theta$ as a compact parameter space whose interior points contain the true coefficient vector
 $ \vartheta _0$. For any
 $ \vartheta \in \Theta$, we define pseudo residual
 $ e_{i,t}^{*}(\vartheta )=\tilde{y}_{i,t}-\tilde{\omega }_{i,t}^{\top }\delta -d_{i,-1}^{\top }\alpha _{-1}+\mu (x_t,z_t;\,\gamma )$ and construct the following conditional pseudo-likelihood functionFootnote 5
 \begin{align*} l(e^{*}_{i,t}(\vartheta );\,x_t,z_t)=\frac{2}{\sigma (x_t,z_t;\,\gamma _\sigma )}\varphi \left (\frac{e^{*}_{i,t}(\vartheta )}{\sigma (x_t,z_t;\,\gamma _\sigma )}\right )\Phi \left (\frac{\lambda (x_t,z_t;\,\gamma _\lambda )\, e^{*}_{i,t}(\vartheta )}{\sigma (x_t,z_t;\,\gamma _\sigma )}\right ). \end{align*}
Notice that we capture the possible serial correlation in  $ e_{i,t}$ by incorporating the lagged dependent variable in linear component
 $ \omega _{i,t}$. Assuming
 $e_{i,t}$ is i.i.d. conditioning on
 $(\omega _{i,t}^{\top },x_t,z_t,\alpha _i)$, we estimate
 $ \vartheta _0$ by a pseudo-MLE
 $ \hat{\vartheta }$ from
 \begin{equation} \hat{\vartheta }=\underset{\vartheta \in \Theta }{\text{argmax }} \frac{1}{nT}\sum _{i=1}^{n}\sum _{t=1}^{T}\ln l(e_{i,t}^{*}(\vartheta )|x_t,z_t). \end{equation}
Remark 1. Estimation of  $ \vartheta _0$ in our skewed model crucially depends on the correct specification of
 $ \beta ({\cdot})$, which is typically unknown in practice. We circumvent this issue by removing
 $ \beta ({\cdot})$ through within-transformation in (4), thus making our pseudo-MLE estimator
 $ \hat \vartheta$ in (7) invariant to unknown functional form of
 $\beta ({\cdot})$. This improves the likelihood estimator in conventional models placing restrictive structure assumptions, such as linearity, on
 $ \beta ({\cdot})$, potentially subject to inconsistent estimation upon model misspecification. Instead of applying the transformation in (4), one may alternatively construct our pseudo-response
 $ e_{i,t}^{*}(\vartheta )$ by Taylor expanding
 $ \beta ({\cdot})$ and apply local MLE (Kumbhakar et al. (Reference Kumbhakar, Park, Simar and Tsionas2007)); however, such expansion introduces additional local parameters with slower nonparametric convergence rate, generating non-negligible impact on the asymptotic distribution of
 $ \hat{\vartheta }$. In contrast, the approximation error in our first step is minimum because
 $ \bar{e}_{t}$ converges to
 $ \mu (x_t,z_t;\,\gamma _0)$ at a faster parametric rate of
 $ 1/\sqrt{n}$.
Remark 2. The consistency of our proposed estimator  $\hat{\vartheta }$ relies on the correct assumption that
 $e$ follows a SN distribution. If the true distribution is asymmetric but differs from the SN distribution in tail thickness, such as skew t (ST) or asymmetric Laplace (AL) distribution, then
 $\hat{\vartheta }$ becomes inconsistent as the conditional likelihood function
 $l(e_{i,t}^{*}(\theta );\, x_t, z_t)$ is misspecified. Footnote 6 Consequently,
 $\mu _t \equiv \mu (x_t, z_t;\, \gamma _0)$ in (5) changes to
 $\tilde{\mu }_t$, the expectation under ST or AL distribution. Let
 $D_t = \tilde{\mu }_t - \mu _t$ be the difference of the two mean functions. In Appendix 2.2, we show that the smaller
 $D_t$ approaches zero, the closer the skewness between the SN and ST (AL) distribution, leading to consistent (improved) estimation for
 $\hat{\vartheta }$. If the distribution of
 $e$ exhibits heavier tails than the SN, we may capture unconditional large kurtosis through a conditional time-varying scale function, following similar arguments in Bai et al. (Reference Bai, Russell and Tiao2003) and Carnero et al. (Reference Carnero, Peña and Ruiz2004). Alternatively, we can implement
 $\hat{\vartheta }$ under an ST or AL, as outlined in Appendix 2.2. Inspired by Henderson (Reference Henderson2007), it would also be desirable to avoid distributional assumptions by exploring nonparametric conditional moment functions in a semiparametric dynamic panel model. We leave this topic for future research.
2.2.2. Step 2: estimating $(\beta _0,\beta (z))$ through profile local linear estimator

In the second step, with the preceding estimates  $ \hat{\vartheta }=(\hat{\theta }^{\top },\hat{\alpha }_{-1}^{\top })$, we estimate
 $ \beta _0$ and
 $ \beta ({\cdot})$ using a profile local linear estimator. From (1), suppose that we knew
 $ \mathcal{Y}_{i,t}(\vartheta _0)=y_{i,t}-\omega _{i,t}^{\top }\delta _0-\alpha _{0i}-\mu (x_t,z_t;\,\gamma _0)$. Averaging both sides of the equation yields the following regression model
 \begin{equation} \bar{\mathcal{Y}}_{t}(\theta _0)=\beta _0+x_t\beta (z_t)+\bar{\epsilon }_{t}, \end{equation}
where 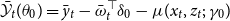 $ \bar{\mathcal{Y}}_{t}(\theta _{0})=\bar{y}_{t}-\bar{\omega }_{t}^{\top }\delta _0-\mu (x_t,z_t;\,\gamma _0)$ depends only on
 $ \theta _0=(\delta _0^{\top },\gamma _0^{\top })$ due to our identification condition
 $ \sum _{i=1}^{n}\alpha _{0i}=0$, and
 $ \bar{\epsilon }_{t}=\bar{e}_{t}-\mu (x_t,z_t;\,\gamma _0)$ satisfies
 $ E(\bar{\epsilon }_{t}|x_t,z_t)=0$. Assuming
 $ \beta ({\cdot})$ in (8) is sufficiently smooth with its compact support
 $ \mathcal{Z}\subset \Re$. For any
 $ z\in \mathcal{Z}$, a first-order Taylor expansion on
 $ \beta (z_t)$ around
 $ z$ yields
 $x_{t}\beta (z_{t})\approx \mathcal{X}_t(z)^{\top } B(z),$ where
 $ \mathcal{X}_t(z)=[x_t,x_t(z_t-z)]^{\top }$ and
 $ B(z)=[\beta (z),\beta ^{(1)}(z)]^{\top }$ with
 $ \beta ^{(1)}(z)\equiv \partial \beta (z_t)/\partial z_t|_{z_t=z}$. Given that
 $ \beta _0$ is a global constant while
 $ \beta ({\cdot})$ is locally approximated,
 $ \beta _0$ and
 $ \beta ({\cdot})$ converge at different rates and thus need to be estimated separately. If
 $ \beta _0$ was known, we apply a local linear estimator
 $ \hat{B}(z)\equiv \hat{B}(z;\,\theta _0,\beta _0)$ from
 \begin{equation} \hat{B}(z;\,\theta _0,\beta _0)=\underset{B(z)\in \Re ^{2}}{\text{argmin }} \overset{T}{\underset{t=1}{\sum }} \left [\bar{\mathcal{Y}}_{t}(\theta _0)-\beta _0-\mathcal{X}_t(z)^{\top } B(z)\right ]^{2}k\left (\frac{z_t-z}{b}\right ), \end{equation}
where  $ k(v)$ is a symmetric kernel weighting function with bounded moments, and
 $ b\rightarrow 0$ as
 $ T\rightarrow \infty$ is a selected bandwidth controlling the distance between
 $ z_t$ and
 $ z$ (see Remark (Reference Arellano and Hahn3) below). Define
 $ T\times 1$ vectors
 $ \bar{\mathcal{Y}}(\theta )=[\bar{\mathcal{Y}}_{1}(\theta ),\ldots, \bar{\mathcal{Y}}_{T}(\theta )]^{\top }$ and
 $ \bar{\epsilon }=[\bar{\epsilon _{1}},\ldots, \bar{\epsilon }_T]^{\top }$, and a
 $ T\times 2$ matrix
 $ \mathcal{X}(z)=[\mathcal{X}_{1}(z),\ldots, \mathcal{X}_{T}(z)]^{\top }$ whose
 $ t$-th row is given by
 $ \mathcal{X}_t(z)^{\top }$. The analytical solution for
 $ B(z)$ in (9) is
 \begin{equation} \hat{B}(z;\,\theta _0,\beta _0)=\left [\mathcal{X}(z)^{\top } K(z)\mathcal{X}(z) \right ]^{-1}\mathcal{X}(z)^{\top } K(z)\left (\bar{\mathcal{Y}}(\theta _0)-\beta _0 \right ), \end{equation}
where  $ K(z)=diag \!\left\{k\left (\frac{z_t-z}{b}\right )\right\}_{t=1}^{T}$ is a
 $ T\times T$ diagonal matrix.
In practice,  $ B(z;\,\theta _0,\beta _0)$ in (10) is infeasible because both
 $ \theta _0$ and
 $ \beta _0$ are unknown. To estimate
 $ \beta _0$, observe first that (8) can be expressed in vector form as
 $ \bar{\mathcal{Y}}(\theta _0)=\iota _T\beta _0+\beta _T(x,z)+\bar{\epsilon }$, where
 $ \iota _T$ is a
 $ T\times 1$ vector of ones and
 $ \beta _T(x,z)=[x_1\beta (z_1),\ldots, x_T\beta (z_T)]^{\top }$. Using estimates in (7), we replace
 $ \theta _0$ in
 $ \bar{\mathcal{Y}}(\theta _0)$ with
 $ \hat{\theta }$ to construct
 $ \bar{\mathcal{Y}}_{t}(\hat{\theta })=\bar{y}_{t}-\bar{\omega }_{t}^{\top }\hat{\delta }-\mu (x_t,z_t;\,\hat{\gamma })$.Footnote 7 We implement (10) with
 $ z\in \{z_1,\ldots, z_T\}$ to approximate
 $ \beta _T(x,z)$ by
 $ S_T(\bar{\mathcal{Y}}(\hat{\theta })-\iota _T\beta _0)$, where
 $ S_T$ is a
 $ T\times T$ smoothing matrix from
 \begin{equation*}S_T= \begin {pmatrix} [x_1,0]^{\top }\left ( \mathcal {X}(z_1)^{\top } K(z_1)\mathcal {X}(z_1) \right )^{-1} \mathcal {X}(z_1)^{\top } K(z_1)\\[3pt] \vdots \\[3pt] [x_T,0]^{\top }\left ( \mathcal {X}(z_T)^{\top } K(z_T)\mathcal {X}(z_T) \right )^{-1} \mathcal {X}(z_T)^{\top } K(z_T)\\[3pt] \end {pmatrix}. \end{equation*}
By re-arranging terms, we obtain the profile estimator for  $ \beta _0$ as
 \begin{equation} \hat{\beta }_0=\left [\iota _T^{\top } (I_T-S_T)^{\top } (I_T-S_T)\iota _T \right ]^{-1}\iota _T^{\top } (I_T-S_T)^{\top } (I_T-S_T)\bar{\mathcal{Y}}(\hat{\theta }). \end{equation}
Finally, we obtain coefficient function estimates by updating (10) as  $ \hat{\beta }(z)=[1,0]^{\top }\hat{B}(z;\,\hat{\theta },\hat{\beta }_0)$.
Remark 3. The intuition behind our second step estimator  $ \hat{\beta }({\cdot})$ through (9) is as follows.
 $\hat{\beta }({\cdot})$ is designated as a “local linear” estimator due to the methodology of “locally” fitting a “linear” line through neighboring observations around each evaluation point
 $z \in \mathcal{Z}$. The nearness is controlled by the bandwidth
 $b$ in the kernel function
 $ k\left (\frac{z_t-z}{b}\right )$, which assigns higher (lower) weight for points closer to (further away from)
 $ z$. Consequently, an increased (decreased) bandwidth
 $ b$ results in a more (less) uniform weight. As
 $ T\rightarrow \infty$, we require
 $ b\rightarrow 0$ at a proper rate to ensure the local linear estimator converges in mean square error.
3. Asymptotic characterization
Under mild conditions given in Appendix 1.1, Theorem1 shows the consistency and asymptotic normality of our first-step pseudo-MLE estimator  $\hat \theta$.
(a) Under assumptions A1–A3, as
$n,T\rightarrow \infty$ and $n/T\rightarrow 0$,
\begin{equation*}\hat {\theta }\stackrel {p}{\rightarrow } \theta _0. \end{equation*}
(b) Under assumptions A1–A4, as
$n,T\rightarrow \infty$ and $n/T\rightarrow 0$,
where
\begin{equation*}\sqrt {nT}\left (\hat {\theta }-\theta _0\right )\stackrel {d}{\rightarrow } \mathcal {N}\left (0, \mathcal {H}_{\theta _0}^{-1}\Sigma _{\theta _0}\mathcal {H}_{\theta _0}^{-1} \right ), \end{equation*}
$\mathcal{H}_{\theta _0}$ is a nonsingular negative definite matrix, and $\Sigma _{\theta _0}$ is a positive definite matrix, both defined in A4(4).


Remark 4. Theorem 1(a) indicates that using  $\mu (x_t,z_t;\,\gamma )$ to approximate
 $\bar{e}_{t}$ results in an error that is asymptotically negligible for the distribution of
 $\hat{\vartheta }$. Theorem1(b) shows that, as
 $n\rightarrow \infty$, the incidental parameter problem due to
 $\hat{\alpha }_{i}$ does not generate an impact on the asymptotic distribution of
 $\hat{\theta }$. This result holds under the condition
 $n/T\rightarrow 0$, implying a faster growth rate of
 $T$ compared to
 $n$. In Appendix 1.2, we show that
 $\hat{\alpha }_i$ converges at a slower rate of
 $ 1/\sqrt{T}$ compared to
 $ \hat{\theta }$ at a faster rate of
 $ 1/\sqrt{nT}$. Furthermore,
 $\hat{\alpha }_{i}$ induces a nonzero bias of order
 $1/T$ in
 $\hat \theta$ due to noncentered skew error
 $ e_{i,t}$ and lagged dependent variable in
 $ \omega _{i,t}$.Footnote 8 In line with Arellano et al. (Reference Arellano and Hahn2007), this induced bias does not vanish when
 $ T$ is either fixed or grows at the same rate with
 $ n$, i.e.,
 $n/T\rightarrow \rho \neq 0$. To eliminate the bias, we set
 $\rho =0$ by letting
 $ T$ grows faster than
 $ n$, which is satisfied by our empirical dataset in which
 $T$ is larger than
 $n$ by more than threefold. See numerical evidence through simulation studies in Appendix 2.1. Footnote 9
Given the results in Theorem1(b) and the additional conditions in Appendix 1.1, Theorem2 demonstrates the asymptotic normality of  $\hat{\beta }_0$ and
 $\hat{\beta }(z)$.
Theorem 2. Under assumptions A1, A2, B1–B3, as  $ T\rightarrow \infty$ and
 $ b\rightarrow 0$,
(a) For finite constants  $ \Sigma _{\beta _0}\gt 0$ and
 $ \Omega _{\beta _0}\gt 0$ defined in B2(5),
 \begin{equation*}\sqrt {T}\!\left(\hat {\beta }_0-\beta _0\right)\stackrel {d}{\rightarrow } \mathcal {N}\left (0,\Sigma _{\beta _0}^{-2}\Omega _{\beta _0}\right ).\end{equation*}
(b) For finite constant  $ \mathcal{B}(z)=\frac{1}{2}\beta ^{(2)}(z)\int k(v)v^{2}dv$ with
 $ \beta ^{(2)}(z)\equiv \partial ^{2} \beta (z_t)/\partial z_t^{2}|z_t=z$,
 \begin{equation*} \sqrt {Tb}\!\left(\hat {\beta }(z)-\beta (z)-b^{2}\mathcal {B}(z)(1+o_p(1)\right)\stackrel {d}{\rightarrow } \mathcal {N}\left (0, \Omega _{\beta }\right ),\end{equation*}
where  $ \Omega _{\beta }=\sigma ^{2}_{\bar{\epsilon }}(z)\int k^{2}(v)dv/E(x_t^{2}|z)f_z(z)\gt 0$ is a finite constant with
 $ \sigma ^{2}_{\bar{\epsilon }}(z)\equiv E(\bar{\epsilon }^{2}_t|z_t)$ and
 $ f_z(z)$ is the marginal density of
 $ z$.
Remark 5. Given a finite sample, a well-known trade-off in nonparametric estimation literature is that a larger (smaller) bandwidth  $ b$ reduces (increases) variance but increases (reduces) bias of the function estimator
 $\hat{\beta }(z)$. Thus, a proper selection of
 $ b$ is crucial for the performance of
 $ \hat{\beta }(z)$ in application studies. Our assumption B3(1) regulates the rate at which
 $ b\rightarrow 0$, allowing us to implement a data-driven cross-validation (CV) bandwidth
 $ b_{cv}$ optimal for minimization of finite sample mean squared error (MSE), i.e.,
 \begin{equation} b_{cv}=\underset{b\gt 0}{\text{argmin }} \frac{1}{T}\overset{T}{\underset{t=1}{\sum }} \left [\bar{\mathcal{Y}}_{t}(\hat \theta )-\hat{\beta }_0-x_t\hat \beta _{-t}(z_t) \right ]^{2}, \end{equation}
where  $ \hat{\beta }_{-t}(z_t)=[1,0]^{\top } \hat{B}_{-t}(z_t)$ is the leave-one-out estimator in (9), with
 $ \hat{B}_{-t}(z_t)\equiv \hat{B}_t$ the minimizer (with respect to
 $ B_t$) of
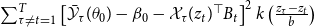 $ \sum _{\tau \neq t=1}^{T}\left [\bar{\mathcal{Y}}_{\tau }(\theta _0)-\beta _0-\mathcal{X}_\tau (z_t)^{\top } B_t\right ]^{2}k\left (\frac{z_\tau -z_t}{b}\right )$ using all sample points except at
 $ t$. Notably, the local linear estimator nests the linear (OLS) estimator as a special case, since if
 $ \beta (z_t)$ is truly linear,
 $ \hat{\beta }(z)$ fits a global linear line by treating the whole sample as neighbor points of
 $ z$. In this case,
 $ b_{cv}$ in (12) is sufficiently large (Li and Racine (Reference Li and Racine2007)). If one is further interested in the derivative of
 $\beta (z)$ (i.e.,
 $\beta ^{(1)}(z)$), the optimal bandwidth for derivative estimation should be upward adjusted by minimizing the MSE of
 $\hat{\beta }^{(1)}(z)$ based on lower and higher order of local polynomial estimators (Henderson et al., Reference Henderson, Li, Parmeter and Yao2015). See the appealing finite sample performance of
 $ \hat{\beta }_0$ and
 $ \hat{\beta }(z)$ in Appendix 2.
4. Empirical application: nonlinear spillover effect of US financial uncertainty
Credit conditions have been documented to vary with financial uncertainty (Caldara et al. (Reference Caldara, Fuentes-Albero, Gilchrist and Zakrajšek2016); Caggiano et al. (Reference Caggiano, Castelnuovo, Delrio and Kima2021)). The intuition is that following a surge of domestic financial uncertainty, domestic credit conditions tighten due to investors’ risk aversion (Bloom (Reference Bloom2014); Gilchrist et al. (Reference Gilchrist, Sim and Zakrajšek2014)) or banks’ monitoring costs (Christiano et al. (Reference Christiano, Motto and Rostagno2014); Lhuissier and Tripier (Reference Lhuissier and Tripier2021)). As a result, financial uncertainty in the US can extend beyond its borders, causing credit conditions to become more stringent both within the country and abroad. Cesa-Bianchi and Sokol (Reference Cesa-Bianchi and Sokol2022) find that tightening US credit conditions can be rapidly transmitted internationally, leading to tightening credit conditions and slowed economic activity in foreign economies. This indicates the existence of an “international credit channel.”
Because financial investment decisions are usually made in a forward-looking manner, investors’ requested compensation and banks’ requested premium for heightened uncertainty may depend on associated economic expectations. For example, facing heightened financial uncertainty, pessimistic investors tend to seek safe assets and avoid risky investment projects more than optimistic investors, asking for higher compensation, which can lead to an additional domestic tightening of credit conditions and then worldwide through international credit channels. In other words, the degree to which domestic and international credit conditions tighten may depend on how financial uncertainty is perceived, from pessimistic or optimistic perspectives.
In this study, we investigate the nonlinear effects of US financial uncertainty on the distribution of global output growth, focusing not only on changes in the mean but also in dispersion and skewness. Additionally, we explore whether these effects are altered by different perspectives among investors regarding US financial uncertainty.
4.1. Measuring US financial uncertainty
We proxy US financial uncertainty using US stock volatility based on monthly S&P 500 Index. The conventional monthly return on stock price ( $p_t$) is usually defined as the log difference between the closing prices in two consecutive months, i.e.,
 \begin{align} r^{mkt}_t=\ln p_t -\ln p_{t-1}, \end{align}
where  $t=1,\ldots, 12$ is a monthly index. In addition, we follow Huang and Luo (Reference Huang and Luo2020b) and look at two alternative measures of returns:
 \begin{align} r^{max}_t=\ln \left (\max _{n=1,\ldots, N_t}\{p_{n,t}\}\right )-\ln p_{t-1}, \end{align}
 \begin{align} r^{min}_t=\ln \left (\min _{n=1,\ldots, N_t}\{p_{n,t}\}\right )-\ln p_{t-1}, \end{align}
where  $p_{n,t}$ is the stock price in
 $n^{th}$ of the total
 $N_t$ trading days in month
 $t$, and
 $p_{t-1}$ is the closing price from the previous month. Huang and Luo (Reference Huang and Luo2020b) interpret the maximal (minimum) return as the return that the luckiest (unluckiest) investor earns in this month among those who hold a market portfolio at the end of last month. Due to the forward-looking nature of the stock market, investors’ assessments should reflect their outlooks of the economy, so the maximum (minimum) price within the month may represent the market’s most optimistic (pessimistic) assessment of the stock values within this month. As a result, different perspectives on future economic conditions may be extracted from these two returns.
We model the three return series in equations (13)–(15) with a simple time-varying parameter model that deviates from the symmetric distributional assumption, i.e.,
 \begin{align} r_{j,t}&=\mu ^j_{t}+\sigma ^j_{t}\eta _{j,t},\quad \eta _{j,t}\sim SN\!\left(0,1,\alpha ^j\right), \end{align}
where  $j\in \{mkt, max, min\}$. It can be seen that
 $r_{j,t}$ in (16) follows an SN distribution with a location parameter
 $\mu ^j_{t}$, a scale parameter
 $\sigma ^j_{t}$, and a shape parameter
 $\alpha ^j$. We do not adopt the conventional normality assumption because maximum- and minimum-return series are not symmetrically distributed: the sample skewness of the maximum (minimum) return is 1.48 (−2.78), and the null hypothesis of skewness being zero is strongly rejected. It should be noted that a SN distribution exhibits thin tails (Azzalini and Capitanio (Reference Capitanio and Azzalini2003)), which may seem counter-intuitive because financial return series
 $r_{t}^{j}$ are typically characterized by heavy tails. However, model (16) is a stochastic volatility model, specifying a conditional scale function
 $\sigma _t^{j}$ varying over time. A conditional scale function, as shown in Bai et al. (Reference Bai, Russell and Tiao2003) and Carnero et al. (Reference Carnero, Peña and Ruiz2004), would effectively capture a large unconditional kurtosis of the overall distribution.Footnote 10
We assume that the mean return,  $\mu ^j_{t}$, and the log-volatility,
 $\ln (\sigma _t^{j})^2$, follow driftless random walk processes. Estimation is conducted using the Bayesian MCMC approach proposed by Huang and Luo (Reference Huang and Luo2020b) with minor adjustments.Footnote 11
Figure 1 shows the market volatility (Market Vol., solid line), good volatility (Good Vol., line with o), and bad volatility (Bad Vol., line with  $ +$) from 1995Q1 to 2019Q4. Huang and Luo (Reference Huang and Luo2020b) find that
 $\sigma _t^{max}$ (
 $\sigma _t^{min}$) signals acceleration (deceleration) in economic activity, motivating the moniker “good (bad) volatility.” Although the three measures substantially comove, there exist apparent unsynchronized movements across the three measures.
 $\sigma _t^{min}$ rises sharply in almost every recession, but this is not the case for
 $\sigma _t^{max}$. It is also notable that the marked elevation in
 $\sigma _t^{max}$ in the mid-1990s coincides with the late-1990s expansion, arguably driven by technical progress in the information technology sector.
The estimates of stock volatility from 1995Q1 to 2019Q4.
Note: This figure displays time series plots for three measures of stock return volatility  $ \sigma _{t}^{mkt}$ (solid line),
 $ \sigma _{t}^{max}$ (line with o), and
 $ \sigma _{t}^{min}$ (line with
 $ +$) during 1995Q1 and 2019Q4.

We use  $\sigma ^{mkt}_t$ as a measure of US stock volatility and an empirical proxy for US financial uncertainty, i.e.,
 $ x_{t}\equiv \sigma ^{mkt}_t$. As noted previously, if
 $\alpha ^{mkt}=0$,
 $\sigma ^{mkt}_t$ is exactly the standard deviation (volatility) of the market return from a model with symmetric normal error. In an asymmetric case where
 $ \alpha ^{mkt} \neq 0$,
 $\sigma ^{mkt}_t$ is proportional to the volatility of the market return, which depends on skewness
 $\alpha ^{mkt}$.
4.2. Effect modifier of US financial uncertainty
Based on the estimated good volatility  $\hat{\sigma }_t^{max}$ and bad volatility
 $\hat{\sigma }_{t}^{min}$, we define the effect modifier of US financial uncertainty as
 \begin{align} z_t=\frac{\hat{\sigma }_t^{max}}{\hat{\sigma }_t^{max}+\hat{\sigma }_t^{min}}. \end{align}
To empirically test the linkage between  $ z_t$ and investor’s economic expectations, we consider the following regression
 \begin{align} f_{t}^{(h)}=a+z_{t-1}b_1+\textbf{F}_{t-1}b_2+e_t, \end{align}
where  $f_{t}^{(h)}$ is the survey expectation made at time
 $t$ about the future value of a variable at time
 $ t+h$, for
 $h\geq 1$.
 $\textbf{F}_{t}$ includes information on the fundamentals of the economy upon which individuals’ expectations are based. We use the Chicago Fed’s National Activity Index and the National Financial Conditions Index to represent economic fundamentals.Footnote 12 We use two different surveys that ask about expectations for future economic conditions: the Survey of Professional Forecasters (SPF) and the University of Michigan Survey of Consumers (MSC).Footnote 13
Table 1 reports the ordinary least squares (OLS) estimation results, indicating that  $ z$ is clearly associated with nonfundamental optimism/pessimism conditioning on economic fundamentals. Using SPF data, the
 $ z$ has a significant and positive relationship with professional forecasters’ predictions of real GDP and corporate profit in two and four quarters. Notably, in the four-quarter forecast horizon, the economic fundamentals do not seem to be a significant factor in professional forecasters’ predictions, but
 $ z$ still has a significant coefficient. A similar pattern is revealed using the MSC data. Regardless of the fundamentals, consumers expect better business conditions with a higher
 $ z$.
Survey forecasts and good/Bad volatility

Note: Results are obtained from the model  $f_{t}^{(h)}=a+b_1 z_{t-1}+b_2 \textbf{F}_{t-1}+e_t$, where
 $f_{t}^{(h)}$ is the survey data of interest with
 $h\geq 1$ the number of quarters ahead. For SPF data, RGDP is the growth of the real gross domestic product, and CRPOF is the growth of nominal corporate profits after tax. For MFC data, BUSS
 $^{(h)}$ is an index from business conditions expected during the next
 $h$ quarters; CBUSS
 $^{(h)}$ is an index from expected change in business conditions in the next
 $h$ quarters. Standards errors are in the parentheses and Newey-West adjusted. The sample period of SPF data is 1971Q1 to 2019Q1. The sample period of MSC data is 1978m1 to 2019m4.
4.3. Empirical evidence for nonlinear spillover effects of US financial uncertainty
4.3.1. Data
We collect quarterly panel data consisting of 30 countries from 1995Q1 to 2019Q4. Our dependent variable is denoted as  $y_{i,t+1}$, which is the annualized average growth rate of the real GDP of country
 $i$ between quarters
 $t$ and
 $t+1$. Our country-specific regressors
 $ \omega _{i,t}$ include the growth rate of real GDP, consumer price indexes (CPI), and credit-to-GDP ratio. Quarterly data for real GDP growth and CPI to measure inflation (quarter-to-quarter percent change) are available from OECD Statistics. Nonfinancial credit-to-GDP ratios are from the BIS, where nonfinancial credit is the sum of household and business credit.
4.3.2. Model specification tests
The flexibility of our model in (1) leads to hypothesis testing for two components. The first component involves examining the potentially nonlinear relationship between US financial uncertainty and the SN error distribution. The degree of nonlinearity is determined by the order  $K_j$ of polynomial functions in (3). When
 $K_j$ is larger, the scale and shape functions exhibit greater nonlinearity. However, this increased flexibility comes at the cost of over-parametrization, which can result in imprecise estimates. This trade-off is important because estimating higher moments, particularly skewness, is notoriously challenging. The second component pertains to assessing the extent to which the nonparametric coefficient function
 $\beta ({\cdot})$ in (1) deviates from a simple linear function. If the deviation is insignificant, employing a parsimonious parametric form, such as
 $\beta (z_t) = z_t\beta _1$, can improve estimation efficiency.
Regarding the first component, we rely on the likelihood ratio (LR) test to determine the appropriate degree of polynomial in (3). Table 2 reports the first-step estimates with different degrees of polynomial, from which we set  $K_{\sigma }=K_{\lambda }=2$. The first column shows the estimates of a model with
 $\gamma _j(z_t)$ as a quadratic function for
 $j\in \{\sigma, \lambda \}$. The parameter estimates in the shape function
 $\lambda ({\cdot})$ are insignificant at the 5% level, indicating that the full model may be over-parameterized. In the second column, we estimate a restricted model in which
 $x$ appears only in scale function
 $\sigma ({\cdot})$. However, the LR test suggests that excluding
 $x$ entirely from
 $\lambda ({\cdot})$ is also not supported by the data. Note that the estimates reported in column (1) indicate that
 $\gamma _{\lambda, 0}$ is significant at the 5% level, suggesting that
 $x$ might enters
 $\lambda ({\cdot})$ linearly. Column (3) presents the estimates of the model with
 $z_t$ being excluded in
 $\lambda ({\cdot})$. Comparing columns (1) and (3) suggests that the null hypothesis
 $H_0\,:\, \gamma _{\lambda, 1}=\gamma _{\lambda, 2}=0$ cannot be rejected. Column (4) reports the estimates of the model in which
 $x$ enters the scale and shape functions linearly. Comparing columns (3) and (4) suggests that
 $H_0$:
 $ \gamma _{\sigma, 1}=\gamma _{\sigma, 2}=0$ can be rejected at the 1% level. In summary, our LR tests indicate that the error distribution does change with
 $x$, and
 $z_t$ is an important effect modifier in
 $\sigma ({\cdot})$ rather than
 $\lambda ({\cdot})$. Thus, we use the model specified in column (3) (i.e.,
 $K_\sigma =2$ and
 $K_\lambda =0$) in subsequent analysis.
The first step pseudo-maximum likelihood estimates

Note: Each column shows the MLE estimates of model (1) with different number of  $K_j$ in
 $ \sigma (x_t,z_t;\,\gamma _{0\sigma })=\exp (c_{0\sigma }+x_t\gamma _\sigma (z_t))$,
 $\lambda (x_t,z_t;\,\gamma _{0\lambda })=c_{0\lambda }+x_t\gamma _\lambda (z_t)$, where
 $\gamma _j(z_t)=\sum _{k=0}^{K_j}z^k\gamma _{0j,k}$ for
 $ j\in \{\sigma, \lambda \}$ Standard errors are in parentheses. The last row reports the likelihood ratio statistic compared with the full model (1).
Regarding the second component, we follow Li et al. (Reference Li, Huang, Li and Fu2002) to base a null hypothesis on a correct parametric coefficient function, i.e.,  $ H_{0}\,:\, \Pr (\beta (z)=z\beta _1)=1$ for some
 $ \beta _1$ against the alternative
 $ H_{1}\,:\, \Pr (\beta (z)=z\beta _1)\lt 1$ for any
 $ \beta _1$. We test the null through a nonparametric test statistic
 $ T=\int [\hat{\beta }(z)-z\hat{\beta }_1]^{2}dz$, where
 $ \hat{\beta }_1$ is the OLS estimate under
 $ H_0$ (
 $ \hat{\beta }({\cdot})$. Following our LR test results above, we set
 $(K_\sigma, K_\lambda )=(2,0)$ to specify moment functions in (2). Using a bootstrapped version of
 $ T$ with 399 repetitions, we reject the null based on an empirical p-value of 0.0000. Thus, the parametric structure
 $ \beta (z)=z\beta _1$ is insufficient to capture the underlying channels through which
 $ x$ and
 $ z$ impact the location of future output growth distribution. In the following, we focus on the estimation results in (1) with nonparametric coefficient function
 $ \beta (z)$.
4.3.3. Conditional distribution of future output growth
Taking into account all estimates of parameters, model (1) can be used to characterize the conditional distribution of future production for each country. We are particularly interested in the comovements of output growth in these countries; thus, we deliberately exclude the constant and country-specific factors to highlight the role of US financial uncertainty. To be exact, we examine the conditional distribution of  $\tilde{y}_{i,t+1}=y_{i,t+1}-\beta _0-\alpha _{0i}-\omega _{i,t}^{\top }\delta _{0}$, denoted as
 $f(\tilde{y}_{i,t+1}|x_t,z_t)$, which follows the following SN distribution
 \begin{equation} \tilde{y}_{i,t+1}\sim SN(x_t\beta (z_t),\sigma (x_t, z_t;\,\gamma _{0\sigma }),\lambda (x_t, z_t;\,\gamma _{0\lambda })). \end{equation}
We focus on the lower  $5^{th}$ percentile, middle
 $50^{th}$ percentile, and upper
 $90^{th}$ percentile to effectively depict the conditional distribution. Since these percentiles do not have an analytical form, we approximate them numerically.
Percentiles of the conditional distribution of future output growth.
Note: This figure plots the estimated 5 $^{th}$ (line with o), 50
 $^{th}$ (line), and 95
 $^{th}$ (line with
 $ +$) percentile of the conditional distribution of one-quarter-ahead real GDP growth.

Figure 2 indicates that all three representative percentiles vary substantially with US financial uncertainty, and the upper percentile is less volatile than the lower one.Footnote 14 The most notable change in the conditional distribution occurred during the global financial crisis, revealing that both the upper and lower percentiles shift to the left in 2008Q4, making double-digit output loss very possible. The upper percentile turned negative, suggesting that a deteriorating economic outcome is very likely approaching.
To better understand how US financial uncertainty affects  $f(\tilde{y}_{i,t+1}|x_t,z_t)$, we illustrate the relationship between US financial uncertainty and three estimated conditional moment functions from (19) in Figure 3. As shown in the upper panel, we observe that the estimated location function
 $ x_t\hat{\beta }(z_t)$ plays a dominant role in the conditional distribution of future output growth. Furthermore, the US financial uncertainty has significantly effects on higher moments of the distribution: an increase in the uncertainty is associated with a rise in estimated scale function
 $ \sigma (x_t,z_t;\,\hat{\gamma }_\sigma )$ (middle panel) but with a decline in the estimated shape function
 $ \lambda (x_t,z_t;\,\hat{\gamma }_\lambda )$ (lower panel). The comovement of the estimated scale and shape functions implies that, following a rise in US financial uncertainty, the left tail of the error distribution will shift more to the left, while the right tail could either widen or narrow, leading to greater volatility in the left tail compared to the right.
The evolution of estimated location, scale, and shape function during 1995Q1 to 2019Q4.
Note: This figure plots quarterly time index against the estimated conditional mean (location) function  $ x_t\hat{\beta }(z_t)$ in the top panel; conditional scale function
 $ \sigma (x_t,z_t;\,\hat{\gamma }_{\sigma })$ in the middle panel; and conditional shape function
 $ \lambda (x_t,z_t;\,\hat{\gamma }_{\lambda })$ in the bottom panel. Each estimated function is displayed along with its corresponding 95% confidence interval (dash line).

However, an intriguing aspect of Figure 2 is that the increasing financial uncertainty in the US does not always lead to worse economic outcomes. In the late 1990s, the US stock market experienced an episode of prolonged turbulence as market volatility gradually rose from 2.8 in 1996Q2 to 5.8 in 1998Q4. Similarly, before the global financial crisis, the US financial uncertainty increased from 4.8 in 2008Q1 to 7.6 in 2008Q4. In both episodes, US financial uncertainty rise by about three units; however, in the late 1990s, the conditional distribution of future output growth does not shift as it does in 2008 when the US economy was severely impaired, as witnessed in the global financial crisis. This finding implies that the association between US financial uncertainty and the conditional distribution of future output growth varies over time.
4.3.4. Nonlinear spillover effect
The estimated marginal effect of US financial uncertainty on the location, scale, and shape function.
Note: This figure plots estimated marginal effect (i.e., coefficient functions) of US financial uncertainty on conditional mean function  $ \hat{\beta }(z_t)$ in the left panel; conditional scale function
 $ \hat{\gamma }_\sigma (z_t)=\hat{\gamma }_{\sigma, 0}+z_{t}\hat{\gamma }_{\sigma, 1}+z_{t}^{2}\hat{\gamma }_{\sigma, 2}$ in the middle panel; and conditional shape function
 $ \hat{\gamma }_\lambda (z_t)=\hat{\gamma }_{\lambda, 0}$ in the right panel. Each estimated function is displayed along with its corresponding 95% confidence interval (dash line).

Figure 4 plots the estimated marginal effect of US financial uncertainty on location function  $ \hat{\beta }(z_t)$, scale function
 $ \hat{\gamma }_\sigma (z_t)=\hat{\gamma }_{\sigma, 0}+z_{t}\hat{\gamma }_{\sigma, 1}+z_{t}^{2}\hat{\gamma }_{\sigma, 2}$, and shape function
 $ \hat{\gamma }_\lambda (z_t)=\hat{\gamma }_{\lambda, 0}$ against
 $z_t$. When
 $z_t$ is below approximately 0.31 so that the bad volatility is much greater than the good volatility, an increase in US financial uncertainty lowers the location function (i.e.,
 $\hat{\beta }(z_t)\lt 0$), rises the scale function (i.e.,
 $\hat{\gamma }_\sigma (z_t)\gt 0$), and decreases the shape function (i.e.,
 $\hat{\gamma }_\lambda (z_t)\lt 0$). Therefore, the conditional distribution of future output growth would shift and skew to the left, accompanied by greater dispersion. In contrast, when
 $z_t$ is high so that the bad volatility is smaller than the good volatility, the location of the distribution moves rightward with increased US financial uncertainty, the scale function inflates more than when
 $z_t$ is low, and the shape function continues to decline.
We proceed by investigating the marginal effects of US financial uncertainty on the conditional distribution of future output growth, which takes a complicated structure, viz.,
 \begin{align} \frac{\partial Q_j(\mu _t,\sigma _t,\lambda _t)}{\partial x_t}= \frac{\partial Q_j}{\partial \mu _t}\frac{\partial \mu _t}{\partial x_t}+\frac{\partial Q_j}{\partial \sigma _t}\frac{\partial \sigma _t}{\partial x_t}+\frac{\partial Q_j}{\partial \lambda _t}\frac{\partial \lambda _t}{\partial x_t}, \end{align}
where  $Q_j$ is the
 $j^{th}$ percentile of
 $f(\tilde{y}_{i,t+1}|x_{t},z_{t})$ in (19) with short-hand notations
 $ \mu _t\equiv x_t\beta (z_t)$,
 $ \sigma _t\equiv \sigma (x_t,z_t;\,\gamma _{0\sigma })$, and
 $ \lambda _t\equiv \lambda (x_t,z_t;\,\gamma _{0\lambda })$. Since
 $x_t$ enters all moment functions with its coefficient changing with
 $z_t$, its marginal impact on
 $ Q_j$ is nonlinear. We can easily derive
 \begin{align} \frac{\partial \mu _t}{\partial x_t}=\beta (z_t),\quad \frac{\partial \sigma _t}{\partial x_t}=\exp [c_\sigma +x_t\gamma _\sigma (z_t)]\gamma _\sigma (z_t),\quad \frac{\partial \lambda _t}{\partial x_t}=\gamma _\lambda . \end{align}
However, partial effects of each moment function on  $Q_j$ (e.g.,
 $ \partial Q_j/\partial \mu _t$) cannot be computed analytically. We overcome this problem by numerically approximating these partial derivatives, and using estimates for (21) to compute the marginal effects of
 $x_t$ according to (20).
The marginal effect of US financial uncertainty on the percentiles of the conditional distribution.
Note: This figure plots the estimated nonlinear marginal effect of US financial uncertainty on the  $5^{th}$ (black solid line),
 $50^{th}$ (dark gray line), and
 $95^{th}$ (light gray line) percentile of the conditional distribution of one-quarter-ahead annual real GDP growth. Each estimated marginal effect is plotted against the effect modifier
 $ z$ along with a (shaded) 95% confidence interval.

Historical conditional distribution of the future output growth.
Note: This figure plots the distribution of estimated one-quarter-ahead real GDP growth (Y) in 1996Q2 and 1998Q1 (left panel), and 2008Q1 and 2008Q4 (right panel).

Figure 5 presents the estimated  $ \partial Q_j/\partial x_t$ on three representative percentiles for
 $j=5$,
 $50$, and
 $95$ given different levels of
 $z_t$.Footnote 15 When
 $z_t$ is equal to its mean level (about 0.47), a rise in US financial uncertainty only stretches the tails slightly and does not affect significantly the median of the conditional distribution. Therefore, the influence of US financial uncertainty is minor, as small changes in the unlikely outcomes are negligible.
However, US financial uncertainty has significant and strikingly different effects when  $z_t$ approaches its extremes. When
 $ z_t$ reaches its minimum (i.e., when bad volatility is at its highest), a unit increase in US financial uncertainty pulls all percentiles downward and significantly reduces the
 $ 5^{th}$,
 $ 50^{th}$, and
 $ 95^{th}$ percentiles of the distribution by 2.03%, 1.34%, and 0.97%, respectively. Consequently, bad economic outcomes are more likely to occur. When
 $ z_t$ reaches its maximum (i.e., with the greatest good volatility), one unit increase in US financial uncertainty significantly reduces the
 $ 5^{th}$ percentile by 3.20% but increases the
 $ 95^{th}$ percentile by 1.47%, implying a significant rise in the dispersion of the conditional distribution. The median decreases only by 0.5%. In this circumstance, future economic outcomes are even more uncertain and unpredictable.
Finally, we compare the two periods of increased US financial uncertainty in our sample period, which includes the late 1990s (left panel) and the 2008–2009 global financial crisis (right panel). In both episodes, US financial uncertainty rises by about three units, but good and bad volatility respond very differently. In the late 1990s, both good and bad volatility are alike (i.e.,  $z_t\approx 0.5$). In contrast, the great financial crisis features the highest bad volatility and
 $ z_t$ reaches its lowest value of 0.26. Figure 6 shows that as US financial uncertainty rises in the late 1990s, the dispersion of
 $f(\tilde{y}_{i,t+1}|x_t,z_t)$ increases without a noticeable change in mode. However, at the height of the global financial crisis, the conditional distribution shifts to the left and becomes more dispersed, leading to only a minimal chance of positive growth.Footnote 16
5. Conclusion
In this paper, we propose a semiparametric dynamic skewed panel model to examine the effects of common macroeconomic regressors on the conditional distribution of an interested dependent variable. The model allows the conditional mean, variance, and skewness of the distribution to be functions of the common regressors. Within each conditional moment function, there are potential effect modifiers that alter the effect of common regressors in a nonlinear and time-varying manner. We model the time-varying effect through either nonparametric or flexible parametric coefficient functions, effectively alleviating the risk of model misspecification. Additionally, our model incorporates a dynamic structure and unobserved individual fixed effects. We propose a consistent two-step estimator, characterize its asymptotic properties, and demonstrate its finite sample performance through simulation studies.
Employing a panel dataset of 30 countries over nearly three decades, we examine whether US financial uncertainty affects the distribution of future global output growth. Our findings indicate that the effect is significant, time-varying, and dependent on an effect modifier reflecting market participants’ expectations. During periods of pessimism, heightened financial uncertainty originating from the United States causes a leftward shift and skew in the distribution, increases dispersion, and likely leads to a contraction in global output. In contrast, during times of optimism, it stretches the distribution, resulting in greater uncertainty about future global output growth.
Supplementary material
The supplementary material for this article can be found at https://doi.org/10.1017/S1365100524000762.
Acknowledgement
We thank the Guest editor, Apostolos Serletis, and two anonymous reviewers for their constructive and thoughtful comments, which helped improved the paper substantially. Any remaining errors are the authors’ responsibility. Yu-Fan Huang acknowledges financial support from the National Natural Science Foundation of China (No. 72373104). Taining Wang acknowledges financial support from the National Natural Science Foundation of China (No. 72403177) and The Project of Construction and Support for High-Level Innovative Teams of Beijing Municipal Institutions (No. BPHR20220199).
Competing interests
The authors declare none.



