


1. Introduction
The guarantees traditionally provided by life annuities, protecting an individual from the financial cost of living longer than expected, have become expensive in the latest decades, due to the dynamics of financial markets and the decreasing trend in mortality rates. The possibility of unanticipated reductions in mortality rates, in particular, charges the annuity provider with the so-called aggregate longevity risk, which motivates this paper.
As is well known, despite being an insurance risk, the aggregate longevity risk is not subject to risk pooling; as such, it cannot be diversified inside the traditional insurance–reinsurance process. Innovative risk management solutions are rather required.
In principle, we can figure out a number of ways to cope with the aggregate longevity risk, including premium loadings, capital allocation, hedging through longevity-linked reinsurance or through longevity-linked securities, or setting some form of risk sharing between the provider and the individual. In practice, each of these solutions has some drawbacks. Indeed, charging higher loadings can make life annuities even less attractive than how currently perceived by potential customers. Allocating more capital (if not matched by higher loadings) reduces shareholders’ value, making the business less appealing to potential investors. Hedging the aggregate longevity risk is not yet possible at a convenient price or in an efficient way. Indeed, while longevity-linked reinsurance is usually expensive, the market for longevity-linked securities is still underdeveloped; further, hedging transactions can involve counterparty and basis risk, partially offsetting the benefits from the risk transfer. Finally, sharing the risk with the individual involves a possible adjustment, even downward, of the benefit amount, and this could have an adverse impact on the demand.
Despite the drawbacks, longevity-linked reinsurance, longevity-linked securities, and longevity risk-sharing arrangements currently represent the most innovative risk management solutions in respect of the aggregate longevity risk, and the ones that is worth investigating. In this paper, we focus on risk-sharing solutions.
Longevity risk-sharing effects can be achieved either indirectly or directly. An indirect effect, namely a natural hedging across time, can be obtained by including a rider death benefit to the annuity. The exposure of the provider to longevity risk is reduced because, thanks to the death benefit, the mortality credits are reduced. As a result, however, the annuity becomes more expensive, as the annuity rate decreases; nevertheless, the reduction of the annuity rate is limited, as death benefits included as riders to annuities are usually restricted to a range of ages (say, up to age 75) in which the mortality level is not high. For the same reason, the risk reduction gained this way by the annuity provider is not significant.
A direct sharing of the longevity risk can be attained by linking the annuity benefit to the mortality/longevity experienced in a chosen population: unanticipated mortality improvements should result in a reduction of the benefit amount, thus offsetting (at least partially) the possible loss suffered by the provider. Conversely, higher mortality rates could support an increase of the benefit amount, and then the profit possibly gained by the provider would be shared with annuitants. The main drawback for annuitants is clear: in the future, the benefit amount may decrease. However, this risk could be balanced by an immediate advantage, namely, a higher annuity rate. For the provider, a trade-off between the default probability and the business value is involved, which must be examined.
Annuity designs in which the benefit amount is subject to updating based on the mortality/longevity experience have been named in different ways in the literature: adaptive algorithmic annuities by Lüthy et al. (Reference Lüthy, Keller, Bingswanger and Gmür2001), longevity-indexed life annuities by Denuit et al. (Reference Denuit, Haberman and Renshaw2011), longevity-contingent life annuities by Denuit et al. (Reference Denuit, Haberman and Renshaw2015), mortality-indexed annuities by Richter & Weber (Reference Richter and Weber2011), and longevity-linked life annuities by Bravo & de Freitas (Reference Bravo and de Freitas2018). Also, different adjustment coefficients of the benefit amount have been considered. Lüthy et al. (Reference Lüthy, Keller, Bingswanger and Gmür2001) consider the ratio between the actuarial values of the annuity based on the initial and the latest mortality forecast. A similar choice is made by Denuit et al. (Reference Denuit, Haberman and Renshaw2015), who consider the expected lifetime, that is to say the actuarial value of the annuity at a 0% discount rate. Denuit et al. (Reference Denuit, Haberman and Renshaw2011) and Bravo & de Freitas (Reference Bravo and de Freitas2018) adopt the ratio between the expected survival probability and the proportion of survivors observed in a reference population. Richter & Weber (Reference Richter and Weber2011) consider the ratio between the available reserve and the actuarial value of the annuity updated to observed mortality. An adjustment based on the ratio between reserves is discussed also by Maurer et al. (Reference Maurer, Mitchell, Rogalla and Kartashov2013), dealing with variable investment-linked deferred annuities. Deferred living benefits are also considered by Hanbali et al. (Reference Hanbali, Denuit, Dhaene and Trufin2019), who investigate longevity risk-sharing arrangements, based on the number of survivors, under which the provider is allowed to revise not only the benefit amount, but also the pricing basis, by charging additional premiums. To this purpose, they focus on a pure endowment.
Forms of participation to the longevity experience were already present in tontine annuities. These arrangements, dating back to the 17th century, were designed as financial annuities in which the annual or final amount was increased thanks to the funds released by the deceased. Originally developed for speculative purposes, tontine annuities have recently been revised as a form of longevity risk management. See, for example, McKeever (Reference McKeever2009), Baker & Siegelman (Reference Baker and Siegelman2010), Sabin (Reference Sabin2010), Milevsky (Reference Milevsky2014), Milevsky & Salisbury (Reference Milevsky and Salisbury2015), Milevsky & Salisbury (Reference Milevsky and Salisbury2016), Weinert & Gründl (Reference Weinert and Gründl2016), and Chen et al. (Reference Chen, Hieber and Klein2019).
Examples of non-insurance arrangements in which the longevity risk is shared among the individuals are provided by group self-annuitisation pools (see, e.g. Piggot et al. Reference Piggott, Valdez and Detzel2005; Valdez et al. Reference Valdez, Piggott and Wanga2006; Qiao & Sherris Reference Qiao and Sherris2012), pooled annuity funds (see Stamos Reference Stamos2008; Donnelly et al. Reference Donnelly, Guillén and Nielsen2013), and annuity overlay funds (see Donnelly et al. Reference Donnelly, Guillén and Nielsen2014; Donnelly Reference Donnelly2015). The common idea here is that liabilities must always be funded; this target is reached by letting the benefit amount decrease, if required by the available asset amount. Such arrangements rely on pooling arguments; they do not provide explicit longevity guarantees, and they are unable to absorb systematic losses caused by unanticipated mortality improvements.
We see that the literature review suggests a number of alternatives to define a longevity-linking arrangement, but others could be designed. It is therefore useful to have a common framework, under which the various solutions can represent specific cases. A common framework could facilitate the interpretation of the various alternatives in view of the possible targets of the provider and the individual, as well as of the features of the guarantees that may be offered. Understanding the trade-off between risk and cost of the guarantees is important, from both the point of view of individuals and providers.
Developing a general structure describing longevity-linked post-retirement benefits is the main contribution of this paper. Allowing for aggregate longevity risk, we then examine suitable solutions for insurance products, that we will name longevity-linked annuities. To this purpose, we analyse their features and value from both the point of view of the insurer and the individual, considering different levels of the longevity guarantee.
The paper is organised as follows. In Section 2, we make some preliminary remarks on a longevity-linked arrangement, while in Section 3, we describe a general structure for longevity-linked post-retirement benefits and discuss some particular cases of interest in insurance applications. The valuation in the insurer’s and individual’s perspective is examined in Section 4. A numerical experiment is developed in Section 5. Finally, in Section 6, we conclude with some final comments.
2. Designing a Longevity-Linked Arrangement: Preliminary Remarks
2.1 The alternative targets of the provider and individuals
In a linking arrangement, insurers share profits or losses with policyholders, with the aim of reducing some risks, and ultimately the default probability, while trying to reach a satisfactory business value. The variables involved in a linking arrangement impact differently on the default probability and business value, which indeed move quite often in opposite directions. On the other hand, policyholders usually have conflicting objectives with those of insurers. When designing a linking arrangement, it is therefore appropriate to examine preliminarily what could be the resultant risk-return trade-off, for the provider and for the individual as well.
A very well-known example of a linking arrangement, which can serve as a reference guide, is provided by participating policies: at policy issue, the technical interest rate is set low (or even zero); the realised return above the technical interest rate (or possibly above an additional guaranteed return) is then assigned periodically to the policy account value, resulting in an increase of the benefit amount. This way, the insurer waves part of the profits (and this affects negatively the business value) but offers the policyholders a return in line with the market, leaving a significant part of the financial risk to them (with a positive impact on the default probability). In turn, the policyholder is charged a higher premium rate (because of the size of the technical interest rate), still receives a financial guarantee, but may also have a reasonable expectation of adequate returns. The success of participating policies witnesses that a good balance between the alternative targets of the insurer and the policyholder has been achieved.
A similar arrangement can be developed for longevity risk. We first make clear that we only refer to the aggregate longevity risk, that is, the risk of unanticipated mortality improvements. This is because the idiosyncratic longevity risk, which is subject to pooling effects, should be managed by the insurer with traditional tools, namely, traditional reinsurance arrangements. Conversely, the systematic nature of the aggregate longevity risk requires innovative management solutions, as we mention in Section 1.
While a financial linking arrangement is designed primarily to distribute profits, a longevity-linking arrangement responds mostly to the need to share possible losses. This can have at first a negative impact on the demand, as it is psychologically easier to agree to share a profit than a loss. On the other hand, the possibility of sharing losses should be offset by a more favourable rating to the policyholder. Maurer et al. (Reference Maurer, Mitchell, Rogalla and Kartashov2013) suggest that individuals should be willing to accept such a deal. Furthermore, a longevity-linking arrangement can be designed so to also share (at least partially) profits.
Intuitively, under a longevity-linking arrangement, the default probability of the provider should decrease. Conversely, the impact on the business value is not so clear, due to the different rating conditions, and the possible distribution of profits. This is an aspect that requires further investigation.
A lower default probability and a higher business value are multi-period targets for the insurer. Annual targets may relate to the annual payout, annual profit, or the comparison between the portfolio reserve and the available assets. From the point of view of the individual, the premium loading and, therefore, the annuity rate are significant components in the choice whether or not to underwrite the contract. Leaving apart bequest preferences (we assume that the individual has already decided to underwrite an annuity), further components can be the features of the longevity guarantee, in particular with regard to the possible duration of the annuity (which should be lifelong, in an insurance contract) and the possible sequence of benefit amounts (which should not present too large fluctuations). In Section 4, appropriate quantities are introduced so to assess the alternative longevity-linked annuity designs considering the main targets for providers and individuals.
2.2 The basic items of a longevity-linking rule
A linking of annuity benefits to the longevity experience requires to choose on one side a mortality data set (or mortality/longevity index) in which to measure the longevity experience, on the other side the type of adjustment coefficient of the benefit amount.
The longevity experience can be measured: (i) in a portfolio, (ii) in a reference population, and (iii) with a (projected) life table. Solution (i) is usually referred to as indemnity-based, as it depends on the mortality reported in the portfolio of the provider and then on the loss/profit realised by the provider itself. An indemnity-based solution avoids basis risk for the provider, as the benefits are adjusted in line with the mortality experienced by the provider itself, but it is subject to random fluctuations, due to the (presumably not large) portfolio size. Furthermore, individuals could suspect possible data manipulations, with a consequent lack of trust. Solution (ii) is usually referred to as index-based, as it depends on an external experience for the provider, namely, an index. The reference population is typically a representative sample of the population of a country (e.g. Italy), or a region (e.g. England and Wales). When the purpose is to measure longevity, a specific cohort can be addressed (e.g. people born in 1948). An index-based solution involves basis risk for the provider, as the mortality experienced by the provider is not necessarily in line with that referred to for the benefit adjustment, but it is less exposed to random fluctuations, due to the larger size of the population with respect to a portfolio. The confidence of individuals in the quality of data should be higher, as data are usually collected and processed by an independent institution. Also solution (iii) is index-based; in this case, the longevity experience is measured in terms of updated mortality projections. Being a life table, the risk that data are affected by random fluctuations is low. The confidence of individuals should be high, as life tables are usually developed by independent institutions; however, a prediction of future mortality trends is involved, which is exposed to uncertainty risk.
When defining the adjustment coefficient of the benefit amount, the longevity experience can be expressed in terms of numbers of survivors (or, equivalently, survival probabilities), or in terms of actuarial quantities (such as the actuarial value of the annuity, the portfolio reserve, and the portfolio assets). Table 1 provides an overview of the main alternatives, distinguishing between indemnity- and index-based solutions. A more detailed description is provided in Section 3.
Quantities used to define the adjustment coefficient.

3. Benefit Structure: From a General Expression to Particular Solutions
3.1 Basic assumptions and notation
In this section, we develop a general structure describing longevity-linked benefits. Specific solutions are obtained with appropriate choices of the parameters involved. We mainly refer to insurance arrangements; this justifies some terminology (e.g. we refer to annuities, policy conditions, policyholders, the insurer, and so on). However, the structure is suitable to represent also cases in which no guarantee is provided, that can be adopted in self-insured arrangements, as we mention in some examples.
What follows refer to a discrete-time annuity immediate in arrears, that is, with payments at the end of the year. For simplicity, one cohort only is addressed, aged x at entry time 0. We denote with S the initial amount paid by each policyholder.
As far as notation is concerned, the best estimate assumption at time h is denoted as i(h) for the interest rate,  $q_{x+t}(h)$ for the mortality rate (at age
 $x+t$), and
 $p_{x+t}(h)$ for the survival probability (at age
 $x+t$). The actuarial value at time t, age
 $x+t$, of a unitary discrete-time annuity in arrears, conditional on the best estimate assumptions at time h,
 $0\leq h\leq t$, is denoted as
 $a_{x+t}(h)$ and computed as follows:
 \begin{equation}a_{x+t}(h)=\sum_{s=1}^{\omega-(x+t)}(1+i(h))^{-s}\cdot {_sp_{x+t}}(h)\end{equation}
where  $\omega$ is the maximum attainable age (note that, for simplicity, in writing the expression for
 $a_{x+t}(h)$ in (1), we have assumed a flat term structure). Since it is based on best estimate assumptions, we mean that no loading is included in
 $a_{x+t}(h)$. Variables that, depending on the assumption, can be either deterministic or stochastic, are denoted with a tilde on the top when assumed to be stochastic; for example,
 $\widetilde{p}_{x+t}$ is the survival probability at age
 $x+t$ observed in a given population, while
 $\widetilde{\imath}_t$ is the return on investments realised in year
 ${(t-1,t)}$. Further quantities and the relevant notation will be introduced in the following, step by step.
3.2 A general expression for the updated benefit amount
We assume that the initial benefit amount is assessed as follows:
 \begin{equation}b_0=S\cdot\frac{1}{a_{x}(0)\cdot(1+\pi)}\end{equation}
where  $\pi$ represents the premium loading, whose size is assumed to be defined at time 0, depending on the risk retained by the provider, as we discuss in detail in Section 4.
If the annuity is fixed amount, the benefit amount at time t,  $t=1,2,\dots$ is simply
 $b_t=b_0$.
Let  $\text{adj}_{(t',t'')}$,
 $t'<t''$, denote the adjustment coefficient based on the longevity experience in the time interval (tʹ,tʹʹ).
If the benefit is subject to annual adjustments, the benefit amount at time t is assumed to be assessed alternatively as follows:
 \begin{equation}b_t=b_{t-1}\cdot \text{adj}_{(t-1,t)}\ ;\ \ \ t=1,2,\dots\end{equation}
 \begin{equation}b_t=b_0\cdot \text{adj}_{(0,t)} \ ; \ \ \ t=1,2,\dots\end{equation}
Considering that the longevity trend can be captured better over a period of several years, rather than year by year, it is reasonable to consider the case of adjustments every k years (say,  $k=3$ or 5), instead of every year. In this case, alternative definitions of the benefit amount at time t are as follows:
 \begin{equation}\begin{cases}b_t=b_{t-k}\cdot \text{adj}_{(t-k,t)}\ ; & t=k,2k,\dots \\b_t=b_{t-1} \ ; & t\not=k,2k,\dots\end{cases}\end{equation}
 \begin{equation}\begin{cases}b_t=b_{0}\cdot \text{adj}_{(0,t)}\ ; & t=k,2k,\dots \\b_t=b_{t-1} \ ; & t\not=k,2k,\dots\end{cases}\end{equation}
In order to work out possible expressions of the adjustment coefficients, we now assume that the update occurs annually. The case of multi-period adjustments is discussed in Section 3.6.
Refer to a policy in-force at time  $t-1$. According to policy conditions, the following actuarial balance must be fulfilled for year
 ${(t-1,t)}$:
 \begin{equation}b_{t-1}\cdot a_{x+t-1}(\tau)\cdot(1+g_t) = b_t\cdot (1+a_{x+t}(\tau'))\cdot\widetilde{p}_{x+t-1}\end{equation}
where
–
 $\tau$, $0\leq \tau\leq t-1$, and $\tau'$, $\tau\leq\tau'\leq t$, are the times when the technical basis for the assessment at times $t-1$ and t of the insurer’s liabilities is respectively set;
–
$g_t$ represents the financial return credited to the policy account value for year ${(t-1,t)}$, which is based on the return realised on investments, possibly including minimum guarantees (some examples are provided below and, in more detail, in Section 3.3);–
$\widetilde{p}_{x+t-1}$ represents the survival probability measuring the mortality credit assigned to the policy account value for year ${(t-1,t)}$. The probability $\tilde{p}_{x+t-1}$ is set depending on the mortality observed in a chosen population, with possible guarantees. Some examples are discussed below and, in more detail, in Section 3.4.


We point out that whenever  $g_t$ and
 $\tilde{p}_{x+t-1}$ are not fixed but depend (respectively) on the realised investment return and the observed mortality, the parameters of equation (7) are random and the balance between the right- and left-hand sides of (7) is ensured by the benefit
 $b_t$, which will be adjusted accordingly. Indeed, as a result of the linking arrangement, the annuity benefit amount is random, and (part of) the risk is kept by the annuitant.
Under a fixed-benefit (FB) arrangement, equation (7) becomes the well known
 \begin{equation}b_0\cdot a_{x+t-1}(0)\cdot(1+i(0))= b_0\cdot (1+a_{x+t}(0))\cdot p_{x+t-1}(0)\end{equation}
where the interest rate i(0) and the survival probability  $p_{x+t-1}(0)$ are set at time 0 and guaranteed over the whole life of the annuity. Under a linking arrangement, the financial return
 $g_t$ or the survival probability
 $\widetilde{p}_{x+t-1}$ can depend, respectively, on the return realised on investments or the survival probability observed in a given population. Similarly, the actuarial value of the annuity at time t could be based on an updated best estimate assumption compared to that adopted at time
 $t-1$. If
 $g_t=i(\tau)$,
 $\widetilde{p}_{x+t-1}=p_{x+t-1}(\tau)$, and
 $\tau'=\tau$, the actuarial balance (7) is preserved with
 $b_t=b_{t-1}$. Otherwise, an adjustment of the benefit amount
 $b_t$ compared to
 $b_{t-1}$ is required. Alternative choices of the parameters of equation (7) are discussed in Sections 3.3–3.6.
Starting from equation (7), it is useful to obtain an explicit expression for the adjustment coefficient. We can easily write:
 \begin{equation}b_t=b_{t-1}\cdot \frac{a_{x+t-1}(\tau)\cdot(1+g_t)}{(1+a_{x+t}(\tau'))\cdot\widetilde{p}_{x+t-1}}\end{equation}
where the adjustment coefficient can be interpreted as a ratio between the unitary value of the assets assigned to the policy, namely,  $a_{x+t-1}(\tau)\cdot(1+g_t)$, and the unitary value of the liability in its respect at the end of the year, namely,
 $(1+a_{x+t}(\tau'))\cdot\widetilde{p}_{x+t-1}$. This recalls how benefits are adjusted in self-insured arrangements, such as group self-annuitisation plans, where no guarantee is provided. In this case,
 $\tau=t-1$,
 $\tau'=t$,
 $g_t=\widetilde{\imath}_t$, and
 $\widetilde{p}_{x+t-1}=\widetilde{p}_{x+t-1}^{[\text{pool}]}$, where
 $\widetilde{p}_{x+t-1}^{[\text{pool}]}$ denotes the survival probability observed in the pool, that is, the proportion at time t of survivors in the pool aged
 $x+t-1$ at the beginning of the year. In this regard, it is important to note that equation (9), as well as the following (11), resembles what discussed for group self-annuitisation (GSA) arrangements by Piggot et al., (Reference Piggott, Valdez and Detzel2005).
For arrangements providing some guarantees, it is convenient to further develop (9). First, consider that
 \begin{equation}a_{x+t-1}(\tau)=(1+a_{x+t}(\tau))\cdot (1+i(\tau))^{-1}\cdot p_{x+t-1}(\tau)\end{equation}
We can then rearrange equation (7) as follows:
 \begin{equation}b_t = b_{t-1}\cdot\frac{1+g_t}{1+i(\tau)}\cdot\frac{p_{x+t-1}(\tau)}{\widetilde{p}_{x+t-1}}\cdot \frac{1+a_{x+t}(\tau)}{1+a_{x+t}(\tau')}\end{equation}
which suggests specific alternative solutions for the adjustment coefficient  $\text{adj}_{(t',t'')}$, that we are now going to discuss.
3.3 Financial linking
As we mention in Section 1, in this paper we deal with the longevity risk only, while we disregard financial risk. However, equation (11) also provides the case of participating policies, which is therefore interesting to discuss briefly, also to get a first insight into the choice of some parameters.
Assume that only a financial linking is realised, with a guaranteed technical basis at time 0. Then
–
$\tau=\tau'=0$, $a_{x+t}(\tau)=a_{x+t}(\tau')=a_{x+t}(0)$ and $p_{x+t-1}(\tau)=p_{x+t-1}(0)$, due to the guaranteed technical basis;–
$\widetilde{p}_{x+t-1}=p_{x+t-1}(0)$, as there is no longevity linking.


Equation (11) reduces to
 \begin{equation}b_t = b_{t-1}\cdot\frac{1+g_t}{1+i(0)}\end{equation}
If  $g_t=i(0)$, the arrangement is with fixed return and FB. If
 $g_t=\widetilde{\imath}_t$, no guarantee is provided, and the benefit amount can either increase or decrease (or keep unchanged), depending on whether
 $\widetilde{\imath}_t\gtreqless i(0)$. Usually, a financial guarantee is provided. For example,
 $g_t\geq i_{\min}$ in the traditional participating arrangements that offer an annual minimum guaranteed rate. More recently, the annual rate is guaranteed just on average, every k years (
 $k=3$ or 5, typically). Then,
 $g_t=\widetilde{\imath}_t$ for
 $t\not=k,2k,\dots$, while
 $\prod_{h=t-k}^{t}(1+g_{h})\geq (1+i_{\min})^k$ for
 $t=k,2k,\dots$.
In what follows, we no longer consider a possible financial participation, as we focus on the longevity linking only. Then, in the following, we assume that the interest rate is fixed, at the initial level i(0) and that  $g_t=i(\tau)=i(0)$. We point out that this choice for the financial parameters implies that no financial profit is realised by the provider; on the other hand, in a deterministic financial setting, no profit should emerge from interest rates. Conversely, an asset management fee is admissible, but we omit it, as it would not affect significantly the results that we discuss in Section 5.
3.4 Longevity linking by means of the survival probability
As we mentioned above, we exclude financial participation. Furthermore, we assume that the technical basis for the assessment of the policy account value is guaranteed at time 0; then  $a_{x+t}(\tau)=a_{x+t}(\tau')=a_{x+t}(0)$. In this case, equation (11) reduces to
 \begin{equation}b_t = b_{t-1}\cdot\frac{p_{x+t-1}(\tau)}{\widetilde{p}_{x+t-1}}\end{equation}
Let  $\widetilde{p}_{x+t-1}^{[\text{pop}]}$ and
 $\widetilde{p}_{x+t-1}^{[\text{ptf}]}$ denote, respectively, the survival probability observed in a reference population or in the portfolio, that is, the proportion at time t of survivors aged
 $x+t-1$ at the beginning of the year, respectively, in a chosen reference population or in the portfolio of the insurer.
If  $\widetilde{p}_{x+t-1}=p_{x+t-1}(\tau)=p_{x+t-1}(0)$, there is no longevity linking, and the benefit is guaranteed. If
 $\widetilde{p}_{x+t-1}=\widetilde{p}_{x+t-1}^{[\text{pop}]}$, there is an index-based longevity linking, without guarantees, whereas if
 $\widetilde{p}_{x+t-1}=\widetilde{p}_{x+t-1}^{[\text{ptf}]}$, the linking is indemnity-based (still without guarantees). Whatever is the choice, whether it is index-based or indemnity-based, if
 $\widetilde{p}_{x+t-1}>p_{x+t-1}(\tau)$, the benefit amount is reduced, while if
 $\widetilde{p}_{x+t-1}<p_{x+t-1}(\tau)$ the benefit amount is increased. The probability
 $p_{x+t-1}(\tau)$ represents the benchmark survival probability, which is set at time
 $\tau$,
 $0\leq\tau\leq t-1$. If
 $\tau=0$, the benchmark survival probability is never changed; otherwise, it is updated to more recent mortality projections. In any case,
 $p_{x+t-1}(\tau)$ is known at the latest at the beginning of the year, that is, at time
 $t-1$.
Linking by means of the survival probability: A path of the benefit amount for alternative choices of the parameters. Index-based: the mortality is observed in a large population. Indemnity-based: the mortality is observed in a small population. Experienced mortality is on average higher than expected, with major random fluctuations in the small population.  $\tau$ is the time at which the benchmark probability is set.

To get an initial idea of what the different choices of parameters may imply, Figures 1 and 2 show a sample of paths of the benefit amount, for an initial unitary benefit amount,  $b_0=1$. We have considered both index-based solutions (where the realised survival probability is observed in a large population) and indemnity-based solutions (where the realised survival probability is observed in a small population). With reference to the large population, a purely deterministic path has been assumed for mortality rates. In particular, Figure 1 refers to the case of a mortality moderately higher than expected (implying increasing benefit), while a mortality moderately lower than expected is considered in Figure 2 (where benefits tend to decrease). In both cases, the best estimate life table at each time is updated (deterministically) according to the emerging trend (simply applying to future mortality rates the ratio between the observed and the expected mortality rate realized in the current year). The small population share the same longevity trend as the large population, apart from random fluctuations (whose effect has been included, once again choosing a deterministic path). When comparing indemnity to index-based solutions, the impact of random fluctuations clearly emerges. Both in Figures 1 and 2, the benchmark survival probability to be compared to the observed one is set alternatively at the time 0 (
 $\tau=0$) or at the beginning of each year (
 $\tau=t-1$). Some comments concerning the choice of
 $\tau$ are provided below.
Linking by means of the survival probability: A path of the benefit amount for alternative choices of the parameters. Index-based: the mortality is observed in a large population. Indemnity-based: the mortality is observed in a small population. Experienced mortality is on average lower than expected, with major random fluctuations in the small population.  $\tau$ is the time at which the benchmark probability is set.

Appropriate bounds to the survival probability  $\widetilde{p}_{x+t-1}$ can be used to introduce partial guarantees, to avoid excessive changes or to avoid the transfer of random fluctuations (indeed, when
 $\widetilde{p}_{x+t-1}\not=p_{x+t-1}(\tau)$, it is not immediately clear whether this is due to random fluctuations or systematic deviations; in any case, the insurer must be able to cover small fluctuations on its own). Thus, we can require
 \begin{equation}p_{x+t-1,\min}\leq \widetilde{p}_{x+t-1}\leq p_{x+t-1,\max}\end{equation}
or
 \begin{equation}\begin{cases}\widetilde{p}_{x+t-1}=p_{x+t-1}(\tau) & \text{if }p'_{x+t-1,\min}\leq \widetilde{p}^{[\cdot]}_{x+t-1}\leq p'_{x+t-1,\max} \\[8pt] \widetilde{p}_{x+t-1}=\widetilde{p}^{[\cdot]}_{x+t-1} & \text{otherwise}\end{cases}\end{equation}
where, for example,  $p_{x+t-1,\min}=0.8\cdot p_{x+t-1}(\tau)$,
 $p_{x+t-1,\max}=1.2\cdot p_{x+t-1}(\tau)$,
 $p'_{x+t-1,\min}=0.95\cdot p_{x+t-1}(\tau)\ ;\ p'_{x+t-1,\max}=1.05\cdot p_{x+t-1}(\tau)$.
In respect of the choice  $\tau=0$ or
 $\tau>0$, we can make the following remarks. The choice
 $\tau=0$ is simpler to explain to the policyholder, as the benchmark survival probability is never changed. However, in the case of a mortality trend different from that predicted at time 0, major and iterated adjustments would be necessary. Conversely, when
 $\tau>0$, the benchmark survival probability is based on a more recent best estimate assumption, such as the latest projected life table, the processing of which should account for the information gained in the meantime on the mortality trend. Then, we should expect values for the ratio
 $\frac{p_{x+t-1}(\tau)}{\widetilde{p}_{x+t-1}}$ farther from 1 when
 $\tau=0$ than when
 $\tau>0$. Thus, setting
 $\tau>0$ can respond to the aim of containing the change of the benefit amount. However, such a choice can be harder to explain to the policyholder, as both the numerator and the denominator of the adjustment coefficient are subject to update after the issue of the contract.
Concerning the choice  $\tau=0$, we point out the following result:
 \begin{eqnarray}b_t &=& b_{t-1}\cdot \frac{p_{x+t-1}(0)}{\widetilde{p}_{x+t-1}} \end{eqnarray}
 \begin{eqnarray}= b_0\cdot \frac{_tp_{x}(0)}{_t\widetilde{p}_{x}}\end{eqnarray}
where  $_tp_{x}(0)$ is the probability for an individual age x to be alive after t years, based on the best estimate assumptions at time 0, while
 $_t\widetilde{p}_{x}$ is the proportion of survivors at age
 $x+t$ out of a cohort initially aged x, in a given population. Note that (17) provides an example of benefit structure (4). Model (17) has been investigated by Denuit et al. (Reference Denuit, Haberman and Renshaw2011) and Bravo & de Freitas (Reference Bravo and de Freitas2018), who also consider bounds like (14).
Concerning the choice of the population, we note that index-based solutions are more suitable for insurance arrangements. A basis risk may follow for the provider, but the adjustment coefficient should be less subject to random fluctuations.
In the above discussion, we explicitly refer to one cohort, and the survival probabilities  $\widetilde{p}^{[\cdot]}$ are meant to be observed on a specific cohort. As an alternative, the survival probabilities
 $\widetilde{p}^{[\cdot]}$ could be obtained from cross-sectional observations; for example, the general survival probability of (a subgroup of) a population could be considered, summarising the longevity experience over several age classes (instead of only one). This is to compensate possible fluctuations originated by the size or the specific features of a particular cohort. Clearly, the basis risk for the insurer can worsen, to the benefit of a greater stability of the linking parameters. This solution will not be further addressed in this paper.
3.5 Longevity linking by means of the actuarial value of the annuity
Assume now that  $\frac{1+g_t}{1+i(\tau)}=1$,
 $\frac{p_{x+t-1}(\tau)}{\widetilde{p}_{x+t-1}}=1$, while the actuarial value of the annuity is subject to update. Then, equation (11) reduces to
 \begin{equation}b_t = b_{t-1}\cdot \frac{1+a_{x+t}(\tau)}{1+a_{x+t}(\tau')}\end{equation}
If  $\tau'\not=\tau$, the actuarial values
 $a_{x+t}(\tau)$ and
 $a_{x+t}(\tau')$ could be based on different best estimate assumptions (clearly, if such assumptions have changed in the time interval
 ${(\tau,\tau')}$). We note that the best estimate assumptions adopted for the assessment of actuarial values involve both a discount rate and survival (or death) probabilities; as we mentioned, we disregard financial issues. Thus, we discuss only possible changes of the survival probabilities.
If, because of a higher expected lifetime, we find  $a_{x+t}(\tau')>a_{x+t}(\tau)$, according to (18), the benefit amount is reduced. Vice versa, the benefit amount is increased if
 $a_{x+t}(\tau')<a_{x+t}(\tau)$. The quantity
 $a_{x+t}(\tau)$ represents the benchmark actuarial value, set at time
 $t-1$ at the latest, that is,
 $0\leq \tau\leq t-1$. The quantity
 $a_{x+t}(\tau')$ is the value updated at time
 $\tau'$, with
 $0\leq\tau'\leq t$.
To get an initial idea of what the different choices of parameters may imply, Figures 3 and 4 show a sample of paths of the benefit amount, for an initial unitary benefit amount,  $b_0=1$. The mortality trajectories are the same as for Figures 1 and 2. For comparison, the scale of the y-axis is the same as Figures 1 and 2. In the denominator of (18), reference is to the latest lifetable (
 ${\tau'=t}$). The benchmark life table to be compared to this one is set alternatively at time 0 (
 $\tau=0$) or at the beginning of each year (
 $\tau=t-1$). The life table is based on data obtained from a large population, so the solution is by construction index-based (that is why here we do not provide an indemnity-based example).
Linking by means of the actuarial value of the annuity: A path of the benefit amount for alternative choices of the parameters. Updated life tables predict on average a lower expected lifetime.  $\tau'=t$ is the time at which the latest life table is set.
 $\tau$ is the time at which the benchmark life table is set.

Linking by means of the actuarial value of the annuity: A path of the benefit amount for alternative choices of the parameters. Updated life tables predict on average a higher expected lifetime.  $\tau'=t$ is the time at which the latest life table is set.
 $\tau$ is the time at which the benchmark life table is set.

As we noted in Section 3.4, the choice  $\tau=0$ is easier to explain to the policyholder. On the other hand, we could expect more changes in the benefit amounts than in the case
 $\tau>0$, for similar reasons to those commented in Section 3.4.
Variants of (18) have been addressed by Richter & Weber (Reference Richter and Weber2011), Maurer et al. (Reference Maurer, Mitchell, Rogalla and Kartashov2013), Lüthy et al. (Reference Lüthy, Keller, Bingswanger and Gmür2001) (they actually make a comparison between the required and the available reserve, which can be interpreted in terms of (18)). Denuit et al. (Reference Denuit, Haberman and Renshaw2015) also adopt a variant of (18); they refer to the expected lifetime, which is an actuarial value assessed with a 0% discount rate.
3.6 Mixed solutions and additional conditions
In Sections 3.4 and 3.5, we discuss longevity-linking solutions in which the adjustment coefficients depend only on the survival probability or only on the actuarial value of the annuity. Clearly, an adjustment coefficient depending on both quantities can be defined, namely, as follows:
 \begin{equation}b_t = b_{t-1}\cdot\frac{p_{x+t-1}(\tau)}{\widetilde{p}_{x+t-1}}\cdot \frac{1+a_{x+t}(\tau)}{1+a_{x+t}(\tau')}\end{equation}
Solution (19) is perhaps preferred by the insurer, whose profits are exposed to changes in both the survival probabilities and the actuarial value of the annuity. However, within an insurance arrangement, choice (19) is critical, since the items subject to change are several, making it perhaps difficult to understand the policy conditions by the potential policyholders.
Variants of model (19) can be found in arrangements in which all the risks are borne by the individuals, such as GSA funds. In these arrangements, as we have briefly recalled in Section 3.2, also the financial risk is retained by the participants, and then the benefit adjustment can be obtained from (11) (or equivalently from (7)), with no guarantee embedded; see, e.g. Piggot et al., (Reference Piggott, Valdez and Detzel2005) or Qiao & Sherris (Reference Qiao and Sherris2012).
Conversely, in an insurance arrangement, it is appropriate to include policy conditions safeguarding the policyholder. For example
– bounds to the benefit amount:
(20)for example,
\begin{equation} b_{\min}\leq b_t\leq b_{\max} \end{equation}
$b_{\min}=0.75\cdot b_0$, $b_{\max}=1.25\cdot b_0$. This provides a guaranteed minimum benefit ($b_{\min}$); on the other hand, $b_{\max}$ avoids too large increases, which are not strictly required by the policyholder and could impact negatively on the premium loading.– A maximum age
$x_{\max}$ to apply the benefit adjustment:
(21)for example,
\begin{equation} b_t=b_{x_{\max}-x} \ \ \ \text{for}\ \ \ t>x_{\max}-x \end{equation}
$x_{\max}=95$. This prevents the individual from having to worry about downward fluctuations of the benefit amount at a stage in life where it can be difficult to obtain additional income.– Partial participation:
(22)where
\begin{equation} b_t=(1-\psi)\cdot b_0+\psi\cdot b_{t-1}\cdot \text{adj}_{(t-1,t)} \end{equation}
$\psi$ represents a participation proportion, $0\leq \psi\leq 1$, which must be chosen at policy issue. This solution clearly provides a minimum guaranteed benefit, while offering a premium loading reduction and the possibility to gain a higher benefit amount in case of lower longevity than expected.


Some policy conditions overlap: for example, (14), (20), and (22). Clearly, one or the other must be chosen, as suggested by the features of the longevity index referred to, hedging opportunities or market practice.
Finally, we mention an expression of the adjustment coefficient alternative to (11). Instead of (10), we can consider the following relation:
 \begin{equation}a_{x+t-1}(\tau')=(1+a_{x+t}(\tau'))\cdot (1+i(\tau'))^{-1}\cdot p_{x+t-1}(\tau')\end{equation}
The structure of relation (23) is obviously the same of (10). The difference stands in the best estimate assumption, which in (23) is chosen at time  $\tau'$, with
 $0\leq\tau'\leq t$, instead of time
 $\tau$, which can be set at time
 $t-1$ at the latest (since
 $0\leq\tau\leq t-1$). Replacing (23) into (7), we obtain the following expression for the adjusted benefit amount:
 \begin{equation}b_t=b_{t-1}\cdot \frac{1+g_t}{1+i(\tau')}\cdot \frac{p_{x+t-1}(\tau')}{\widetilde{p}_{x+t-1}} \cdot \frac{a_{x+t-1}(\tau)}{a_{x+t-1}(\tau')}\end{equation}
which is alternative to (11). Note that in case of a longevity linking by means of the survival probability, equation (24) admits that the benchmark survival probability is set at time t. This could introduce too much uncertainty from the point of view of the policyholder. That is why we prefer to discuss model (11). We also note that model (11) can be generalised to the case of adjustments on a k-years basis, as we describe in Section 3.7.
3.7 Multi-period adjustments
Let us now examine the case of adjustments every k years. Refer to a policy in-force at time  ${t-k}$; the benefit amount is kept unchanged over the next k years, while it is subject to an update at time t. Following the discussion in Section 3.2, we can write the following actuarial balance relating to period
 ${(t-k,t)}$ and based on policy conditions:
 \begin{equation}{b_{t - k}}\cdot{a_{x + t - k}}(\tau ) = {b_{t - k}}\cdot{\tilde a_{\left. {\overline {\, {x + t - k:k - 1} \,}}\! \right| }} + {b_t}\cdot\left( {1 + {a_{x + t}}(\tau ')} \right){\cdot_k}{\tilde p_{x + t - k}}\cdot\prod\limits_{h = t - k + 1}^t {{{(1 + {g_h})}^{ - 1}}}\end{equation}
where ${\tilde a_{\left. {\overline {\,
{x + t - k:k - 1} \,}}\! \right| }}$ represents the actuarial value at time
 $t-k$ of a unitary annuity in arrears temporary
 $k-1$ years, assessed with the survival probabilities
 $\widetilde{p}$ and the financial returns g (the expression of
 ${{\tilde a}_{\left. {\overline {\,
{x + t - k:k - 1} \,}}\! \right| }}$ is similar to (1), with a duration limited to
 $k-1$ terms, and the discount rate and the survival probabilities set as mentioned above). For a policy in-force at time
 $t-k$, on the left-hand side of equation (25), we have the value of the annuity at age
 $x+t-k$, when the benefit amount is
 $b_{t-k}$, assessed according to the parameters set at time
 $t-k$. The benefit amount is kept at the level
 $b_{t-k}$ for the next k years, that is, until time t, when an update can occur. The quantity
 ${b_{t - k}}\cdot{{\tilde a}_{\left. {\overline {\, {x + t - k:k - 1} \,}}\! \right| }}$ expresses the value at time
 $t-k$ of the payments made during the time interval
 ${(t-k,t)}$, which is assessed according to the interest rate and survival probabilities credited to the policy account value during this time. The quantity
 $b_t\cdot a_{x+t}(\tau')$ is the value at time t of the future payments, based on updated parameters, which is then discounted (joint to the benefit currently due) back to time
 $t-k$. The benefit at time t is adjusted so to reach the balance described by (25).
Now we note that
 \begin{equation}{a_{x + t - k}}(\tau ) = {a_{\left. {\overline {\, {x + t - k:k - 1} \,}}\! \right| }}(\tau ) + (1 + {a_{x + t}}(\tau )){\cdot_k}{p_{x + t - k}}(\tau )\cdot{(1 + i(\tau ))^{ - k}}\end{equation}
(where  ${a_{\left. {\overline {\, {x + t - k:k - 1} \,}}\! \right| }}(\tau )$ represents the actuarial value of a temporary annuity, based on best estimate assumptions at time
 $\tau$), and we can rewrite
 \begin{align}\eqalign{
& {b_{t - k}}\cdot\left( {{a_{\left. {\overline {\,
{x + t - k:k - 1} \,}}\! \right| }}(\tau ) - {{\tilde a}_{\left. {\overline {\,
{x + t - k:k - 1} \,}}\! \right| }}} \right) \cr
& + {b_{t - k}}\cdot(1 + {a_{x + t}}(\tau )){\cdot_k}{p_{x + t - k}}(\tau )\cdot{(1 + i(\tau ))^{ - k}} \cr
& = {b_t}\cdot(1 + {a_{x + t}}(\tau ')){\cdot_k}{{\tilde p}_{x + t - k}}\cdot\prod\nolimits_{h = t - k + 1}^t {{{(1 + {g_h})}^{ - 1}}} \cr} \end{align}
Within an insurance arrangement, it is difficult to justify a value  ${\tilde a_{\left. {\overline {\, {x + t - k:k - 1} \,}}\! \right| }}\not = {a_{\left. {\overline {\ {x + t - k:k - 1} \,}}\! \right| }}(\tau )$, in particular given that such a quantity concerns past benefits; thus, we assume that policy conditions state that
 ${\tilde a_{\left. {\overline {\, {x + t - k:k - 1} \,}}\! \right| }} = {a_{\left. {\overline {\, {x + t - k:k - 1} \,}}\! \right| }}(\tau )$. Therefore, equation (27) can be rewritten as
 \begin{equation}b_t = b_{t-k}\cdot \frac{\prod_{h=t-k+1}^{t}(1+g_h)}{(1+i(\tau))^{k}} \cdot \frac{{_kp_{x+t-k}(\tau)}}{{_k\widetilde{p}_{x+t-k}}} \cdot \frac{1+a_{x+t}(\tau)}{1+a_{x+t}(\tau')}\end{equation}
which is a clear generalisation of equation (11). It is now redundant to discuss the choice of the parameters. We only note that if the adjustment is based only on the survival probabilities and  $\tau=0$, we find model (17) again.
4. Valuation
4.1 Quantities of interest to both the insurer and the individual
A basic assessment of a longevity-linked annuity, which is of interest both to the insurer and the individual, consists in the present value of future benefits. We assess it at time t, per individual, as follows:
 \begin{equation}\text{PVFB}^{[\cdot]}_t=\sum_{h=1}^{\infty} b_{t+h}\cdot {_h\widetilde{p}^{[\cdot]}_{x+t}}\cdot v(t,t+h)\end{equation}
where  $v(t,t+h)$ is an appropriate discount factor, while
 $_h\widetilde{p}^{[\cdot]}_{x+t}$ is measured either in the portfolio or in a reference population, depending on the purpose of the assessment. In particular, while the probabilities
 $_h\widetilde{p}^{[\text{ptf}]}_{x+t}$ lead to an indemnity-based or entity-specific assessment, the probabilities
 $_h\widetilde{p}^{[\text{pop}]}_{x+t}$ lead to an index-based valuation. Entity-specific valuations are useful, for example, to perform a realistic assessment of the insurer’s liabilities. Conversely, an index-based valuation avoids accounting for risks which are specific to the insurer (e.g. because of a small portfolio size or a portfolio composition negatively affected by adverse selection).
As we mentioned several times, we do not address financial issues; therefore, we assume a deterministic value for  $v(t,t+h)$, and we do not allow for any financial margin to the insurer.
A quantity expressing the risk-return trade-off of the linking arrangement is the premium loading  $\pi$. We follow a VaR-like approach, and we refer to the possible loss suffered by the insurer. Parameters are index-based, so that possible insurer’s inefficiencies are not charged to the policyholders.
Setting to S the initial amount paid by each policyholder, we assume that the premium loading  $\pi$ must satisfy the following requirement:
 \begin{equation}\Pr[S<\text{PVFB}^{[\text{pop}]}_0]=\lambda\end{equation}
where  $\lambda$ (say,
 $\lambda=0.1$) is the accepted loss probability. Given S, the size of
 $\lambda$ will impact on the initial benefit amount
 $b_0$.
It is important to stress that the pricing rule (30) only focusses on losses; then, consistently, the longevity-linking parameters must be set so to imply a possible participation to losses only (while possible profits are retained by the insurer). The definition of pricing rules in the presence of a participation to both profits and losses deserves a specific research.
4.2 Valuation in the insurer’s perspective
As we mentioned in Section 2, the main targets for the insurer are the business value and the default probability. The business value is given by the present value of future profits net of the cost of capital (see, e.g. Blackburn et al. Reference Blackburn, Hanewald, Olivieri and Sherris2017). In this paper, we do not address capital allocation, so we are unable to assess the cost of capital; however, we can assess the present value of future profits.
For the sake of brevity, we omit the expression of the annual profits, and we define directly the present value of future profits at time t (per policy in-force), as follows:
 \begin{equation}\text{PVFP}_t=V_{t}-\text{PVFB}_t^{[\text{ptf}]}\end{equation}
where  $V_t$ is the individual reserve at time t. We assume that the insurer is required by the supervisor to assess the technical provision adopting the latest best estimate assumption, and including a proportional risk margin, in the proportion defined by the premium loading
 $\pi$. Thus, we assume that the individual reserve at time t is defined as follows:
 \begin{equation}V_t=b_t\cdot a_{x+t}(t)\cdot (1+\pi)\end{equation}
In particular,  $V_0=b_0\cdot a_{x}(0)\cdot (1+\pi)=S$, and then
 $\text{PVFP}_0=S-\text{PVFB}_0^{[\text{ptf}]}$.
We note that  $\text{PVFP}_t$ is affected by basis risk, due to the mortality assumption adopted for the assessment of the premium loading (see (30)) and to the indexing rule as well.
Since we do not consider capital allocation, we are unable to perform the assessment of the default probability, while we can assess the loss probability, namely,  $\Pr[\text{PVFP}_t<0]$. Given the pricing rule (30), such a probability (even if affected by basis risk) will have a magnitude in line with the probability
 $\lambda$, so its investigation is not very significant.
4.3 Valuation in the individual’s perspective
We assume that the individual is mainly concerned with the premium loading, and with the amount that he/she will cash in total from the life annuity. Clearly, a basic valuation of the sequence of benefit amounts is provided by  $\text{PVFB}_0^{\text{[pop]}}$, but perhaps this is a value of not immediate understanding by the individual, being based on an actuarial assessment. We then prefer to address a more pragmatical quantity, namely, the cumulative cash balance (to the individual), defined as follows:
 \begin{equation}\text{CB}_t=\sum_{h=1}^t b_h-S\end{equation}
We stress that  $\text{CB}_t$ is a naive measure, as discounting is disregarded. However, not all individuals are familiar with discounting, as suggested by empirical evidence about financial literacy; see, for example, Lusardi (Reference Lusardi2019). For such individuals, a basic comparison concerns how much they pay in respect of how much they cash, independent of when cashflows are due. This is why, in the individual’s perspective, we address this kind of assessment.
In the case of an FB,  $\text{CB}_t$ follows a deterministic trajectory, while the path of
 $\text{CB}_t$ is random in the case of longevity-linked annuities. We note that negative values for
 $\text{CB}_t$ mean that so far (i.e. up to time t) the individual has cashed less money than the initial amount, vice versa if
 $\text{CB}_t>0$. It is interesting to examine the value of
 $\text{CB}_t$ at a time t, which represents a significant duration, such as the expected lifetime according to the best estimate life table (at issue) or around the Lexis point (i.e. the modal value – at adult ages – of the curve of deaths; see, e.g. Pitacco et al. Reference Pitacco, Denuit, Haberman and Olivieri2009), when most of the aggregate longevity risk is expected to arise.
We are aware that a traditional theoretical measure expressing the value of the annuity to the individual is the expected utility (which, in the framework of longevity-linked structures, has been considered, e.g. by Valdez et al. Reference Valdez, Piggott and Wanga2006; Stamos Reference Stamos2008; Donnelly et al. Reference Donnelly, Guillén and Nielsen2013; Maurer et al. Reference Maurer, Mitchell, Rogalla and Kartashov2013; Milevsky & Salisbury Reference Milevsky and Salisbury2015; Bravo & de Freitas Reference Bravo and de Freitas2018; Chen et al. Reference Chen, Hieber and Klein2019). We do not perform an assessment in this respect because we prefer to address quantities which are easier to understand by the individual. On the other hand, we do not deal with an optimisation problem, which is usually convenient to solve by maximising the utility of the individual.
5. Numerical Implementation
5.1 Mortality model
In order to perform a thorough comparison of alternative longevity-linking solutions, we clearly need a stochastic mortality model. The model must be suitable to project mortality at every time (i.e. not just at time 0), to simulate the numbers of survivors, to update the mortality projection, as well as the simulated numbers of survivors, according to the gained experience. As is well known, several stochastic mortality models are discussed in the literature. After the seminal paper by Lee & Carter (Reference Lee and Carter1992), several models have been described, either suggesting variants and extensions of the Lee–Carter model (among the earlier contributions, we recall Brouhns et al. Reference Brouhns, Denuit and Vermunt2002; Renshaw & Haberman Reference Renshaw and Haberman2003; Renshaw & Haberman Reference Renshaw and Haberman2006; Cairns et al. Reference Cairns, Blake and Dowd2006), as well as alternative approaches; particularly interesting are the applications of affine stochastic models, first suggested by Biffis (Reference Biffis2005) and Schrager (Reference Schrager2006), and further developed by many others, as for example Blackburn & Sherris (Reference Blackburn and Sherris2013). The more sophisticated models ensure higher accuracy, but they can present computational complexity. Thus, they are mainly used to perform projections at the initial time only. In view of computational tractability, we prefer to use a simpler model, which quickly updates future forecasts according to the emerging experience.
The model is described in Olivieri & Pitacco (Reference Olivieri and Pitacco2009). With reference to a given cohort consisting of  $n_{x}$ individuals at time 0, we assume that the random mortality rate at age
 $x+t$,
 $t=0,1,\dots$, can be expressed as follows:
 \begin{equation}\skew2\widetilde{q}_{x+t}=q_{x+t}(0)\cdot Z_{x+t}\end{equation}
where  $q_{x+t}(0)$ is the best estimate mortality rate at time 0, while
 $Z_{x+t}$ is a (positive) random coefficient (such that
 $0\leq \skew2\widetilde{q}_{x+t}\leq 1$), expressing a deviation of the mortality rate in respect of the best estimate one, i.e. a deviation in aggregate mortality. We assume
 \begin{equation}Z_{x+t}\sim \text{Gamma}(\alpha_{x+t},\beta_{x+t})\end{equation}
from which it follows
 \begin{equation}\skew2\widetilde{q}_{x+t}\sim \text{Gamma}\left(\alpha_{x+t},\frac{\beta_{x+t}}{q_{x+t}(0)}\right)\end{equation}
Let  $n_{x+t}$ denote the observed number of survivors at age
 $x+t$. For the (random) number of deaths at age
 $x+t$,
 $D_{x+t}$, we accept the Poisson approximation, given
 $n_{x+t}$ and conditional on a given value for the mortality rate
 $q_{x+t}$:
 \begin{equation}[D_{x+t}\vert q_{x+t};\, n_{x+t}]\sim\text{Poi}(n_{x+t}\cdot q_{x+t})\end{equation}
Using (34) and (35), we obtain a negative binomial unconditional distribution for the number of deaths:
 \begin{equation}[D_{x+t}\vert n_{x+t}]\sim \text{NBin}\left(\alpha_{x+t},\frac{\theta_{x+t}}{\theta_{x+t}+1}\right)\end{equation}
where  $\theta_{x+t}=\frac{\beta_{x+t}}{n_{x+t}\cdot q_{x+t}(0)}$.
As far as the parameters in (35) are concerned, which drive the aggregate deviations in mortality, we adopt the following inferential procedure. At time 0, when no experience on the cohort is available, we assume
 \begin{equation}Z_{x+t}\sim\text{Gamma}(\alpha_0,\beta_0)\end{equation}
for all ages  $x+t$,
 $t=0,1,\dots$. At time 1, a specific information on the mortality of the cohort is gained, namely, the observed number of deaths
 $d_{x}$. Then, we can assess the posterior distribution of
 $\skew2\widetilde{q}_{x}$ conditional on the information
 $D_{x}=d_{x}$ as follows:
 \begin{equation}[\skew2\widetilde{q}_{x}\vert d_{x}]\sim\text{Gamma}\left(\alpha_0+d_{x},\frac{\beta_0}{q_{x}(0)}+n_{x}\right)\end{equation}
Thanks to (34), it then follows:
 \begin{equation}[Z_{x+t}\vert d_{x}]\sim\text{Gamma}(\alpha_1,\beta_1)\end{equation}
where  $\alpha_1=\alpha_0+d_{x},\beta_1=\beta_0+n_{x}\cdot q_{x}(0)$. These steps can be repeated recursively in time, so that at time h, once the numbers of deaths
 $d_{x},d_{x+1},\dots,d_{x+h-1}$ and the numbers of survivors
 $n_{x},n_{x+1}=n_{x}-d_{x},\dots,n_{x+h-1}=n_{x+h-2}-d_{x+h-2}$ have been observed, the parameters of the probability distribution of
 $Z_{x+t}$ are updated as follows:
 \begin{align}\alpha_h & = \alpha_0+d_{x}+d_{x+1}+\dots+d_{x+h-1}\nonumber\\[6pt] \beta_h & = \beta_0+n_{x}\cdot q_{x}(0)+n_{x+1}\cdot q_{x+1}(0)+\dots +n_{x+h-1}\cdot q_{x+h-1}(0)\end{align}
Note that this way a correlation is (naturally) introduced among the coefficients  $Z_{x+t}$’s. Obviously, at any time h, the parameters of the distribution of the number of deaths are also updated. For further details, we refer to Olivieri & Pitacco (Reference Olivieri and Pitacco2009).
In this paper, we consider a cohort initial age  $x=65$. We set
 $\alpha_0=\beta_0$, so that at time 0 we have the following expected values for the aggregate deviation in mortality and for the mortality rates:
 $\mathbb{E}_0[Z_{x+t}]=1$ and
 $\mathbb{E}_0[\skew2\widetilde{q}_{x+t}]=q_{x+t}(0)$. We assume that the best estimate mortality rates at time h are given by
 $\mathbb{E}_h[\skew2\widetilde{q}_{x+t}]=\frac{\alpha_h}{\beta_h}\cdot q_{x+t}(0)$, where the parameters
 $\alpha_h,\beta_h$ are updated to the mortality observed (i.e. simulated) in a reference (large) population. The best estimate mortality rates
 $q_{x+t}(0)$ are obtained from a Gompertz law with parameters as in Bacinello et al. (Reference Bacinello, Millossovich and Chen2018). The expected lifetime at age 65 is almost 20 years; to avoid the impact of major random fluctuations at the highest ages, the maximum age is set at 100. Two alternative values for
 $\alpha_0$ are considered:
 $\alpha_0=100$,
 $\alpha_0=1000$, expressing (respectively) a major and a moderate aggregate longevity risk (as at time 0 the coefficient of variation of
 $Z_{x+t}$ is 0.1 in the former case, 0.0316 in the latter).
Basis risk is included by addressing a portfolio with a much reduced size in respect of the reference population; otherwise, the portfolio follows the same trend as the reference population (which means that basis risk is only attributable to random fluctuations).
5.2 Benefit structures examined
We compare the following benefit structures:
1. FB:
$b_t=b_0$.2. GSA-like benefit (GSA):
$b_t=b_{t-1}\cdot \frac{a_{x+t-1}(t-1)\cdot(1+\widetilde{\imath}_t)}{(1+a_{x+t}(t))\cdot \widetilde{p}_{x+t-1}^{\text{[pool]}}}$.3. Linking by means of the survival probability, with benchmark probability set at time 0 (
$\text{L-SP}(0)$): $b_t=b_0\cdot\frac{_tp_{x}(0)}{_t\widetilde{p}_x^{[\text{pop}]}}$.4. Linking by means of the survival probability, with benchmark probability set at time at time
$t-k$ ($\text{L-SP}(t-k)$): $b_t=b_{t-k}\cdot\frac{_kp_{x+t-k}(t-k)}{_k\widetilde{p}_{x+t-k}^{[\text{pop}]}}$.5. Linking by means of the actuarial value of the annuity, with benchmark life table set at time 0, to be compared to the latest life table (
$\text{L-AV}(0,t)$): $b_t=b_{0}\cdot \frac{1+a_{x+t}(0)}{1+a_{x+t}(t)}$.6. Linking by means of the actuarial value of the annuity, with benchmark life table set at time
$t-k$, to be compared to the latest life table ($\text{L-AV}(t-k,t)$): $b_t=b_{t-k}\cdot \frac{1+a_{x+t}(t-k)}{1+a_{x+t}(t)}$.


Arrangement 2 (GSA), which can be adopted in self-insured schemes, is implemented every year, with no guaranteed minimum benefit amount. Arrangements 1 and 2 represent two opposite cases, and they are used as references to interpret the results of the other linking solutions. For arrangements 3–6, some guarantees are introduced: a minimum benefit amount, namely,  $0.75\cdot b_0\leq b_t\leq b_0$, and a maximum age for the benefit adjustment,
 $x_{\max}=95$. Furthermore, annual or multi-period adjustments are considered, assuming alternatively
 $k=3$ or
 $k=5$ in the latter case. We think that this way we have a fairly significant comparison of a number of possible linking solutions that could be adopted in insurance products.
As we have already mentioned, we disregard financial risk and adopt a deterministic financial setting. Given that at present risk-free rates are very low, we set a 0 interest rate at any time. Obviously, present values are affected by this choice, but only in a deterministic way. Taking a positive (but still deterministic) interest rate would not affect significantly the main conclusions of the numerical assessment.
5.3 Numerical assessments and discussion
We perform an assessment of the quantities described in Section 4, namely, the safety loading, the present value of future profits at time 0 (including basis risk or not), and the cumulative cash balance. The latter is examined at time 20, which almost corresponds to the expected lifetime at issue. We note that from the present value of future profits we obtain information also about the present value of future benefits, as  $\text{PVFP}_0=S-\text{PVFB}_0^{\text{[ptf]}}$ (see (31)). All assessments are performed simulating the numbers of survivors in a reference (large) population and in an annuity portfolio. The mortality experience in the reference population is also used to update the best estimate life table at all times.
Table 2 quotes the premium loadings, assessed adopting an accepted loss probability  $\lambda=0.1$. We recall that the case of moderate longevity risk is represented by setting
 $\alpha_0=1000$ in the probability distribution describing the possible deviations in mortality rates, while we set
 $\alpha_0=100$ to represent the case of major longevity risk.
Premium loading  $\pi=\frac{b_0\cdot a_{x}(0)}{S}-1$, ensuring an accepted 0.1 loss probability to the provider.

Considering Table 2, we first see that, as it is reasonable, higher loadings are required when major aggregate deviations in mortality are expected. Second, the size of the premium loading is affected by the extent of the possible benefit adjustment. Indeed, the premium loading is lower when the benefit is more reactive to an adverse experience. The highest loading is required for FBs, where the risk is fully retained by the insurer. On the contrary, no loading is required for a GSA-like linking, where all the risks are borne by the individuals.
The magnitude of the loading required for the arrangement  $\text{L-SP}(t-k)$,
 $k=1$, which is similar to the case of FBs, is justified by the fact that we do not have to expect values far from 1 in the adjustment coefficient
 $\frac{p_{x+t-1}(t-1)}{\widetilde{p}_{x+t-1}^{\text{[pop]}}}$, given that both the numerator and the denominator reflect the same experience. This is undeniably a consequence of the mortality model; however, in general (whatever the model), it is reasonable to assume that numerator and denominator take similar values, given that both the latest best estimate assumptions and the current number of deaths reflect the latest mortality trend. There is a trade-off between the frequency of benefit adjustment and the time at which the benchmark probability is updated, in respect of the current time. In particular, under arrangement
 $\text{L-SP}(t-k)$, the loading reduces when
 $k>1$; this can be explained considering that the numerator of the adjustment coefficient, namely
 $_kp_{x+t-k}(t-k)$, is updated to the experience k years ago (
 $k>1$), while the denominator, namely
 $_k\widetilde{p}_{x+t-k}^{[\text{pop}]}$, is the result of the experience until the current time. Thus, with respect to the case
 $k=1$, it is easier that the ratio between the two probabilities is farther from 1.
When the benchmark best estimate assumption is set at time 0, that is, in the arrangements L-SP(0) and  $\text{L-AV}(0,t)$, it is more probable (in respect of the cases in which the benchmark is chosen at time
 $t-k$) that the adjustment coefficient takes value far from 1. As a result, lower loadings are required for such arrangements. The lowest loadings (even negative) are required for the arrangement
 $\text{L-AV}(0,t)$; this is due to the fact that actuarial values are aggregate values and, contrarily to survival probabilities, they incorporate already the effect of an expected change in the future mortality trend, based on the recent experience. When the benchmark best estimate is set at time 0, the premium loading is lower if
 $k>1$, because of the reduced adjustment frequency. Conversely, as we have commented for
 $\text{L-SP}(t-k)$, when the benchmark best estimate is updated, namely, under the arrangements
 $\text{L-SP}(t-k)$ and
 $\text{L-AV}(t-k,t)$, there is a trade-off between the frequency of adjustment and the distance between the reference information in the numerator and the denominator. While, as noted above, under
 $\text{L-SP}(t-k)$, the trade-off is dominated by the latter aspect, under arrangement
 $\text{L-AV}(t-k,t)$ prevails the former.
The higher loading for the arrangement  $\text{L-AV}(t-k,t)$ in respect of
 $\text{L-AV}(0,t)$ can be justified because of the different distance between the reference information in the numerator and the denominator. Conversely, the lower magnitude of the loading for arrangement
 $\text{L-AV}(t-k,t)$ in respect of
 $\text{L-SP}(t-k)$ can be explained by the fact that actuarial values are aggregate values, and (as already commented) they incorporate the effect of an expected change in the future mortality trend as suggested by the recent experience.
Table 3 quotes the present value of future profits at time 0 (per policy issued and for an initial amount  $S=100$ monetary units). In the assessment of
 $\text{PVFP}_0$, we include no basis risk, by assuming that the mortality in the portfolio is exactly the same as in the reference population, so that
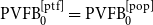 $\text{PVFB}_0^{\text{[ptf]}}=\text{PVFB}_0^{\text{[pop]}}$. In general, the magnitude of the expected present value of future profits is highly affected by the size of the premium loadings (which are those of Table 2). In effect, in Table 3, we find results in line with those of Table 2. It is interesting to note the possible range of values of
 $\text{PVFP}_0$, in terms of the 99% confidence interval, which is much reduced (in particular downwards) when the linking arrangement implies a significant possible adjustment of the benefit amount. Clearly, no profit emerges under a GSA-like arrangement, as the risk is retained by individuals.
Expected value and 99% confidence interval of the present value of future profits at time 0,  $\text{PVFP}_0$. Values per policy issued and for an initial amount
 $S=100$. No basis risk.

Table 4 quotes similar values, but we have included basis risk, by assuming that because of a lower portfolio size, the mortality in the portfolio is not exactly the same as in the reference population. Basis risk is therefore simply attributable to random fluctuations. Results in Table 4 are in line with those of Table 3, with a lower expected profit and a higher variability, due to basis risk.
Expected value and 99% confidence interval of the present value of future profits at time 0,  $\text{PVFP}_0$. Values per policy issued and for an initial amount
 $S=100$. Basis risk included.

Expected value and 99% confidence interval of the cumulative cash balance at time 20,  $\text{CB}_{20}$. Values for an initial amount
 $S=100$.

Table 5 quotes the cumulative cash balance at time 20. Such a time is chosen as it roughly corresponds to the expected lifetime at age 65, according to the best estimate life table at time 0. The larger magnitude of  $\text{CB}_{20}$ under the assumption of moderate longevity risk is a consequence of the lower premium loading (see Table 2), while the different size of the 99% confidence interval is a consequence of the linking rule. Under a given longevity scenario, the different expected values for the various arrangements are in particular due to the premium loading (and then to the initial value of the benefit amount). Leaving aside arrangement
 $\text{L-SP}(t-k)$, which does not seem very competitive compared to an FB (neither for the insurer nor for the individual), arrangement L-SP(0) seems to be preferable to
 $\text{L-AV}(t-k,t)$ and
 $\text{L-AV}(0,t)$ because, while the expected cumulative cash balances are similar, the range of variation is narrower for L-SP(0). On the other hand, Tables 3 and 4 suggest that this solution could be convenient also for the insurer.
6. Concluding Remarks
This paper addresses annuity designs in which the benefit amount is updated to the mortality experience. We develop a general structure that allows us to interpret the different features of a number of particular solutions in comparative terms. Linking the annuity benefit amount to the mortality experience implies a new definition of the longevity guarantee, which can be convenient both to the individual and the provider. Individuals, in particular, can benefit from a reduction in premium loadings. Providers, conversely, do not need to underwrite a fixed guarantee in respect of a long-term risk, which is difficult to predict. Understanding the risk-return trade-off of a new design of the longevity guarantees is important, from both the point of view of individuals and providers.
In this respect, we perform an assessment of longevity-linked arrangements in the perspective both of the individual and the provider. We identify a solution which seems more satisfactory for both parties, namely, a linking involving a comparison between the survival probability based on best estimate assumption at time 0 and the observed proportion of survivors. But certainly this is just a first insight, which suggests further research.
The investigation can be carried out further following several lines of study. From the point of view of the individual, the comparison of the several solutions could be developed modelling individual’s preferences. From the point of view of the provider, the assessment of the business value can be analysed more in-depth, addressing the cost of capital and the default probability. While, in this paper, we have considered an aggregate value of the business performance, namely, the present value of future profits at time 0, annual targets could also be analysed. The case of multiple cohorts should also be examined.
A topic that deserves further research is the pricing of the guarantees. It is worth developing pricing models of the options embedded in the arrangements, admitting a participation also to possible profits. The possibility to introduce flexibility by charging annual fees for the guarantees is also a solution that could be explored. Finally, the joint presence of financial and longevity linking is a problem of theoretical and practical importance.
Acknowledgements
The authors wish to thank the anonymous referees for their constructive comments.



