


1. INTRODUCTION AND MOTIVATION
Banks and financial institutions need to assess the risks within their credit portfolios both for regulatory requirements and for internal risk management. Default risk is related to the inability of a borrower to reimburse a loan or a bond. The definition of a default hinges on the relevant bankruptcy rules that themselves depend on geographical regions, quality of the borrower, and seniority of the loan.
In case of default, the lender only gets a fraction of the promised payments. In the most severe cases, no further cash flows are being paid by the borrower. The loss given default is equal to the difference between the face value of the loan or the bond and the recovered value. Specifically, in credit risk models, the loss for the lender due to obligor i in a certain period of time is usually represented as
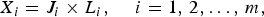
where J i = 1 if obligor i defaults and zero otherwise and L i is the loss given default (describing the fraction of the loan's exposure expected to be lost in case of default, and the exposure at default subject to be lost in the considered time period).
The default indicators might not generally be considered as being mutually independent. Dependence between the defaults of different obligors can be caused by direct links between them (e.g., one obligor is the other's largest customer) or by more indirect links. In the latter category, we find industrial firms using the same input factors (and are thus exposed to the same price shocks) or selling on the same markets (and are thus tributary of the same demand). A number of macroeconomic factors thus influence the default indicators. Common macroeconomic factors include business cycles, level of unemployment, or shifts in monetary policy, for instance. Macroeconomic shocks usually lead to positive dependence.
In credit risk modeling, the random variables J 1, …, J m are often correlated via common mixture models. The idea is that there exists a (small) number of systematic factors Θ1, … , Θp such that the J i's are independent conditionally to Θ. Unconditionally, however, the J i's depend on each other because they are subject to the same unobservable macroeconomic factors Θj. These factor models are among the few models that can replicate a realistic correlated default behavior while dramatically reducing the numerical complexity when computing the distribution of ∑i=1mX i. Many models that are used in practice are based on this approach.
Let p i = Pr[J i = 1] be the default probability for obligor i. Given the environmental risk factor vector Θ = θ, the conditional default probability is p i(θ) = Pr[J i = 1 | Θ = θ] so that p i = 𝔼[p i(Θ)]. In general, conditional default probabilities are functions of linear combinations of the Θj's, that is, p i(θ) is a function of ∑j=1pw ijθj, where w ij ≥ 0 is the relative selectivity of obligor i to risk factor j. In the CreditRisk+ model, for instance, Θ is a vector of p independent Gamma-distributed random variables Θ1, … , Θp and
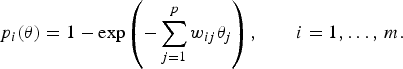
See http://www.riskmetrics.com for more details. In this case, the heterogeneity of the portfolio is represented by the different vectors w 1, … , w m. These weights give the sensitivity of each obligor to the risk factors in Θ.
In this article, we aim to investigate the consequences of increasing the strength of dependence among the macroeconomic factors Θ1, … , Θp. Intuitively, we expect that more positively correlated Θj's yield more positively dependent J i's. If p = 1, we will see that the variability of Θ1 drives the intensity of the dependence between the default indicators: The more Θ1 is variable, the more the default indicators are positively dependent. To examine the impact of the dependence among the risk factors on the default events, we resort to stochastic orderings. Univariate stochastic order relations aim to mathematically express intuitive ideas such as “being larger than” or “being less variable than” for random variables. Multivariate stochastic order relations for random vectors translate the fact that the components of one of these vectors are more positively dependent than those of the other random vector. These relations are based on supermodular functions that play an important role in the theory of stochastic orderings and positive dependence.
The article is organized as follows. Section 2 briefly recalls some useful definitions. The next sections are devoted to the application in credit risk models. Section 3 examines the effect on the J i's of an increase in the dependence among the Θj's. Section 4 considers the special case p = 1 (so that there is only one systematic factor). Section 5 discusses credit risk models built from the Poisson distribution. Section 6 extends the results to the X i's given in (1.1). All of the proofs are gathered in the appendixes.
2. SOME USEFUL PROBABILISTIC TOOLS
This section aims to recall the definitions of some univariate and multivariate stochastic orderings that will be extensively used in the subsequent sections. For more details, we refer the interested reader to Denuit, Dhaene, Goovaerts, and Kaas [Reference Denuit, Dhaene, Goovaerts and Kaas1].
2.1. Univariate Stochastic Orders
Let ⪯cx denote the standard convex ordering between two variables X and Y. Specifically, one writes X ⪯cx Y if and only if
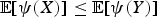
for every convex function ψ : ℝ → ℝ, making these expectations finite. Since both functions ψ(x) = x and ψ(x) = −x are convex, X ⪯cxY implies that 𝔼[X] = 𝔼[Y], so that only random variables with equal means can be compared through ⪯cx. Intuitively speaking, by X ⪯cxY we mean that X is “less variable” than Y (since, in particular, Var[X] ≤ Var[Y], but, on average, X and Y are equal).
2.2. Multivariate Stochastic Orders
Definition (2.1) is easily extended to the n-dimensional case by considering appropriate classes of functions defined on ℝn by means of a difference operator. Let Δiε be the ith difference operator defined for a function Ψ : ℝn → ℝ as
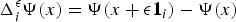
in terms of the ith canonical unit vector 1i. The function Ψ:ℝn → ℝ is said to be supermodular if Δiε Δjδ Ψ (x) ≥ 0 holds for all 1 ≤ i < j ≤ n and ε, δ > 0. It is said to be ultramodular if the aforementioned inequalities also hold in the special case i = j; that is, Ψ : ℝn →ℝ is ultramodular if ΔiεΔjδΨ(x) ≥ 0 for all 1 ≤ i ≤ j ≤ n and ε, δ > 0. Ultramodular functions are precisely those functions that are supermodular and convex in each of their coordinates. We refer to Marinacci and Montrucchio [Reference Marinacci and Montrucchio6] for a detailed account of the properties of ultramodular functions. These functions are also called directionally convex in applied probability.
Note that if Ψ : ℝn → ℝ is twice differentiable, then it is supermodular if and only if 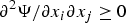 for every 1≤ i < j ≤ n, and it is ultramodular if and only if,
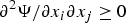 for every 1 ≤ i ≤ j ≤ n.
Let X and Y be two n-dimensional random vectors. Suppose that X and Y are such that
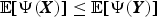
for all the supermodular functions Ψ, provided the expectations exist. Then X is said to be smaller than Y in the supermodular order (denoted as X ⪯smY). Similarly, if (2.2) holds for all of the nondecreasing supermodular functions Ψ, then X is said to be smaller than Y in the increasing supermodular order (denoted as X ⪯ismY); if (2.2) holds for all of the nonincreasing supermodular functions Ψ, then X is said to be smaller than Y in the decreasing supermodular order (denoted as X ⪯dsmY); if (2.2) holds for all of the ultramodular functions Ψ, then X is said to be smaller than Y in the ultramodular order (denoted as X ⪯umY); if (2.2) holds for all of the nondecreasing ultramodular functions Ψ, then X is said to be smaller than Y in the increasing ultramodular order (denoted as X ⪯iumY); and if (2.2) holds for all of the nonincreasing ultramodular functions Ψ, then X is said to be smaller than Y in the decreasing ultramodular order (denoted as X ⪯dumY).
Supermodular ordering is a useful tool for comparing dependence structures of random vectors. Only distributions with the same marginals can be compared in the supermodular sense. Moreover, if X ⪯smY, then Pearson's, Kendall's, and Spearman's correlation coefficients are smaller for (X i, X j) than for (Y i, Y j) for any i ≠ j. By writing X ⪯smY we intuitively mean that the components of X and Y have the same marginal behavior but that the components of Y are more positively dependent that those of X. Formally, the following statements are equivalent: (Reference Denuit, Dhaene, Goovaerts and Kaas1) X ⪯smY; (Reference Denuit and Müller2) X and Y have the same marginals and X ⪯ismY; and (Reference Frey and McNeil3) X and Y have the same expectation and X ⪯ismY. The main difference between the ultramodular order and the supermodular order is that supermodular order compares only dependence structures of random vectors with fixed marginals, whereas the ultramodular order additionally takes into account the variability of the marginals, which might then be different.
3. APPLICATION TO CREDIT RISK MODELS
Let us now compare two credit risk portfolios. The underlying macroeconomic variables are Θ and Γ (with the same dimension p, usually much smaller than the number of credit risks m), and the associated default indicators are J and K, respectively. Here,
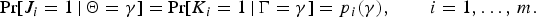
We are now ready to state our first result that allows one to compare J and K when the Γj's are more positively dependent than the Θj's. The key assumptions are about the behavior of θ ↦ p i(θ).
Proposition 3.1
(i) If θ ↦ p i(θ) is monotone (either nondecreasing for all i or nonincreasing for all i) and supermodular for each i, … , m, then Θ ⪯smΓ ⇒ J ⪯ismK.
(ii) If θ ↦ p i(θ) is monotone (either nondecreasing for all i or nonincreasing for all i) and −p i(θ) is supermodular for each i, … , m, then Θ ⪯sm Γ ⇒ J ⪯dsmK.
(iii) If θ ↦ p i(θ) is linear in θand monotone (either nondecreasing for all i or nonincreasing for all i), then Θ ⪯smΓ ⇒ J ⪯sm K.
The proof is given in Appendix A. This result complements Denuit and Müller [Reference Denuit and Müller2], where only the special case p = m is considered. Coming back to the credit risk setting, let us assume that
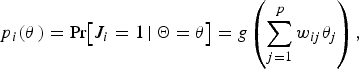
where the w ij's are nonnegative constant. Then, as a direct application of Proposition 3.1, we find that if g is monotone and convex, then Θ ⪯smΓ ⇒ J ⪯ismK, whereas if g is monotone and concave, then Θ ⪯smΓ ⇒ J ⪯dsmK. Thus, in such credit risk models, dependence among the risk factors implies a similar dependence structure among obligors.
Example 3.2
As proposed by Gordy [Reference Gordy4], let us assume that the state of obligor i depends on an unobserved latent variable
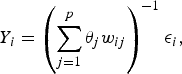
where the εi's are independent and conform to the negative exponential distribution with unit mean. The obligor defaults if Y i falls below a given threshold c i so that
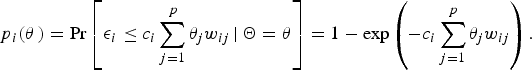
In this case, Proposition 3.1 (ii) ensures that Θ ⪯smΓ ⇒ J ⪯dsmK.
Remark 3.3
Note that in the original Moody's KMV model, Y i is of the form
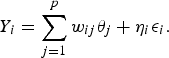
with independent εi, i = 1, … , p, that conform to the standard Normal distribution. For more details, see http://www.moodyskmv.com. In this case, we cannot say much about the impact of the dependence relations among the risk factor on the dependence relations among the obligors in the portfolio, since the Normal density function is not monotone.
Example 3.4
Assume that Pr[J i = 1] = Pr[Y i > 0] for some underlying random variable Y i. Given Θ = θ, the Y i's are independent Poisson random variable with respective parameter λi(θ). Thus, Pr[J i = 1] = 1 − exp(−λi(θ)). This model is applied in the CreditRisk+ model. See McNeil, Frey, and Embrechts [5, p. 356] for more details. Assume that the λi(θ)'s are monotone and that the −λi(θ)'s are supermodular in θ. Then item (ii) of Proposition 3.1 implies that Θ ⪯smΓ ⇒ J ⪯dsmK.
4. MIXTURE MODELS WITH ONE RISK FACTOR
Frey and McNeil [Reference Frey and McNeil3] considered models where the default probabilities depended on a single risk factor Θ (i.e., p = 1). The single-factor approach is also the idea behind the regulatory Basel II framework. When the default indicators are exchangeable, one can think of using de Finetti's theorem, which states the existence of a univariate factor such that the default indicators are conditionally independent given that factor. In other words, for homogeneous portfolios, the assumption of a one-dimensional factor is not restrictive. The only assumption to be made is upon the distribution of conditional default probabilities. As earlier, we consider that given Θ = θ, the default events are independent. Next, we analyze some of these model with respect to their dependence structure.
As in Proposition 3.1, let us consider two credit risk portfolios, with respective univariate risk factors Θ and Γ and the corresponding default indicators are J and K.
Here,
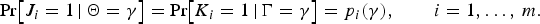
The next result shows that the variability of the risk factor drives the intensity of the dependence between the default indicators. The key assumptions are about the behavior of θ ↦ p i(θ).
Proposition 4.1
(i) If θ ↦ p i(θ) is monotone (either nondecreasing for all i or nonincreasing for all i) and convex for each i, … , m, then Θ ⪯cx Γ
 J ⪯ismK.
(ii) If θ ↦ p i(θ) is monotone (either nondecreasing for all i or nonincreasing for all i) and concave for each i, … , m, then Θ ⪯cx Γ
J ⪯dsmK.(iii) If θ ↦ p i(θ) is monotone (either nondecreasing for all i or nonincreasing for all i) and linear for each i, … , m, then Θ ⪯cx Γ
J ⪯smK.

The proof is similar to the one of Proposition 3.1 and is thus omitted.
Example 4.2
Let Θ be Normally distributed with mean μ1 and variance σ21. Given Θ = θ, the default indicators J 1, … , J m are independent, all with the same default probability p(θ) = 1/(1 + exp(θ)). Such a model is referred to as the logit-Normal model. Similarly, let Γ be Normally distributed with mean μ2 and variance σ22. Given Γ = γ, the default indicators K 1, … , K m are independent, all with the same default probability p(γ) = 1/(1 + exp(γ)). Then
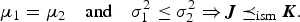
Example 4.3
(Bernoulli regression models): Given Θ = θ, the default indicators J 1, … , J m are independent with default probabilities that depend on ℓ-dimensional vectors, z i, of deterministic covariates. For example, Frey and McNeil [Reference McNeil, Frey and Embrechts5] considered
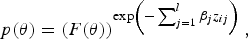
where β is an ℓ-dimensional vector with real components. Assume that ∑j=1lβjz ij > 0 and that F is concave. For instance, F corresponds to the negative exponential distribution, to the Weibull distribution with shape parameter less than 1, or to the Pareto distribution. Then Proposition 4.1(ii) ensures that Θ ⪯cx Γ ⇒ I ⪯dsmJ.
5. POISSON MODELS
In this section, we extend the results derived in Proposition 3.1 from dependent (default) indicators to dependent Poisson counting random variables. If, instead of considering the default occurrences on each obligor, we work at an aggregate level, we are then naturally lead to Poisson approximations. This section aims to examine the effect of increasing the strength of dependence between the macroeconomic factors on the Poisson variables.
Let N = (N 1, … , N m) be a random vector with discrete components. Given Θ = θ, the N i's are independent and have a Poisson distribution with parameter λi(θ). Similarly, consider a random vector Q = (Q 1, … , Q m) such that given Γ = γ, the Q i's are independent and have a Poisson distribution with parameter λi(γ). We then have the following result.
Proposition 5.1
Consider two portfolios N = (N 1, … , N m) and Q = (Q 1, … , Q m), with risk factor vectors Θ and Γ, respectively. Then, we have the following:
(i) If θ ↦ λi(θ) is monotone (either nondecreasing for all i or nonincreasing for all i) and supermodular for each i, … , m, then Θ ⪯sm Γ ⇒ N ⪯iumQ.
(ii) If θ ↦ λi(θ) is monotone (either nondecreasing for all i or nonincreasing for all i) and ultramodular for each i, … , m, then Θ ⪯sm Γ ⇒ N ⪯iumQ.
6. LOSSES GIVEN DEFAULT
Let L = (L 1, … , L m) be a vector of exchangeable nonnegative random variables independent of J and K. The L i's represent the losses given default as in (1.1). The results obtained for the comparison of J and K extend to the credit risks as follows.
Proposition 6.1
Let X = JL = (J 1L 1, … , J mL m) and Y = KL = (K 1L 1, … , K mL m) be two vectors of credit risks of the form (1.1). Then the following hold:
(i) Under the conditions of Proposition 3.1(i) we have that Θ ⪯sm Γ ⇒ X ⪯ismY.
(ii) Under the conditions of Proposition 3.1(ii) we have that Θ ⪯sm Γ ⇒ X ⪯dsmY.
(iii) Under the conditions of Proposition 3.1(iii) we have that Θ ⪯sm Γ ⇒ X ⪯smY.
(iv) Under the conditions of Proposition 4.1(i) we have that if Θ ⪯cx Γ in the one-dimensional case, then X ⪯ismY.
(v) Under the conditions of Proposition 4.1(ii) we have that if Θ ⪯cx Γ in the one-dimensional case, then X ⪯dsmY.
(vi) Under the conditions of Proposition 4.1(iii) we have that if Θ ⪯cx Γ in the one-dimensional case, then X ⪯smY.
These multivariate stochastic inequalities between X and Y then allow one to compare ∑i=1mX i and ∑i=1mY i.
Acknowledgments
Michel Denuit acknowledges the financial support of the Communauté française de Belgique under contract “Projet d'Actions de Recherche Concertées” ARC 04/09-320, as well as the financial support of the Banque Nationale de Belgique under grant “Risk measures and Economic capital.”
Esther Frostig thanks the Zimerman Foundation for the study of Banking and Finance for its financial support.
APPENDIX A
Proof of Proposition 3.1
It is easily seen that for any function g:{0, 1}m→ ℝ, we can write

For i = 1, … , m, let us define the subset D i = {δ : δi = 0} of {0, 1}m. Let us denote as p h(k)(θ) the first partial derivative of p h(θ) with respect to θk; that is, p h(k)(θ) = ∂p h(θ)/∂θk, k = 1, … , p. Thus,
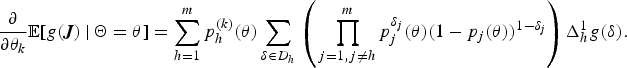
Let us denote as p h(k,i)(θ) the second partial derivative of p h(θ) with respect to θk and θi; that is, p h(k,i)(θ) = ∂2p h(θ)/∂θk∂θi for k, i ∈ {1, … , p}. We can then write, for k≠ i,
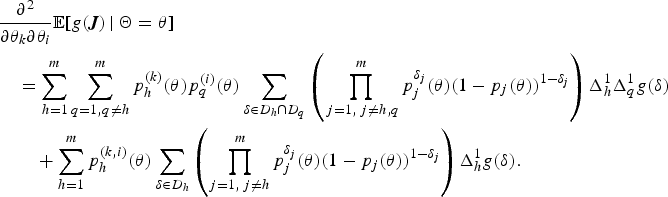
From (A.1) and (A.2), we see that the following hold:
(i) If g is nondecreasing and supermodular (so that Δh1g(δ) ≥ 0 and Δh1Δq1g(δ) ≥ 0) and if p i(θ) is monotone and supermodular (so that p h(k)(θ)p q(i)(θ) ≥ 0 and p h(k,i)(θ) ≥ 0), then (A.2) is nonnegative, so that θ ↦ 𝔼[g(J)|Θ = θ] is supermodular.
(ii) If g is nonincreasing and supermodular (so that Δh1g(δ) ≤ 0 and Δh1Δq1g(δ) ≥ 0) and if −p i(θ) is monotone and supermodular (so that p h(k)(θ)p q(i)(θ) ≥ 0 and p h(k,i)(θ) ≤ 0), then (A.2) is nonnegative, so that θ ↦ 𝔼[g(J)|Θ = θ] is supermodular.
(iii) If p i(θ) is linear in θ, then the second term on the right-hand side of (A.2) vanishes, and if p i(θ) is monotone and g is supermodular, then θ ↦ 𝔼[g(J)|Θ = θ] is supermodular.
We are now able to conclude since 𝔼[g(J)] = 𝔼[Ψ(Θ)], where Ψ is defined as Ψ(θ) = 𝔼[g(J)|Θ = θ]. Hence, under conditions (i)–(iii),
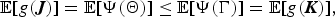
provided Θ ⪯smΓ and g possesses the appropriate properties.
APPENDIX B
Proof of Proposition 5.1
Let g:ℕm → ℝ be nondecreasing, where ℕ is the set of nonnegative integers. Let us denote as λh(ℓ)(θ) the partial derivative of λh(θ) with respect to θℓ; that is, λh(ℓ)(θ) = ∂λh(θ)/∂θℓ for ℓ = 1, … , p. Let us λh(ℓ,κ)(θ) the second partial derivative of λh(θ) with respect to θℓ and θκ; that is, λh(ℓ,κ)(θ) = ∂2λh(θ)/∂θℓ ∂θκ for ℓ, κ ∈ {1, … , p}. Then it is easily seen that

where 𝒩 h(n h) is the set of all the vectors with the hth component equal to n h. Furthermore,

where 𝒩 h,r(n h, n r) is the set of all the vectors with the hth and rth component, respectively, equal to n h and n r. To prove (i), let us consider a nondecreasing and ultramodular function g. Hence, Δh1g(n), Δr1Δh1g(n), and Δh2g(n) are all nonnegative. If for i = 1, … , m, λi(θ) is supermodular in θ and λi(θ), i = 1, … , m, are monotone in the same direction, then 𝔼[g(𝒩)|Θ = θ] is supermodular in θ.
Item (ii) is obtained in a similar way, considering again a nondecreasing and ultramodular function g. If, in addition to being supermodular, θ ↦ λi(θ) is convex in each argument, then it can be proven that θ ↦ 𝔼[g(N)|Θ = θ] is nondecreasing and ultramodular.


