1. Introduction
Let X be a non-negative loss or risk random variable with a cumulative distribution function (cdf) F
X
(x)=P(X≤x) and a survival or decumulative function S
X
(x)=1–F
X
(x). A risk measure is a mapping from a loss random variable to a value in the real line. It can be used to determine an appropriate premium or a required capital for a given risk portfolio based on its loss potential. Basic risk measures include quantile-based risk measures such as value at risk (VaR) and conditional tail expectation (CTE). VaR at level q summarises the loss distribution with its quantile defined to be
 ${\rm }VaR{\rm }_{q} (X){\rm }{\equals}{\rm inf }\{ x\,\mid\,F_{X} \left( x \right)\geq q\} {\rm }{\equals}{\rm }F_{X}^{{{\minus}1}} (q)$
for 0≤q≤1. Two loss random variables may have the same VaR value as VaR involves the confidence level q ignoring the magnitude of potential losses. The CTE=E[X|X≥VaR
q
(X)] is the average value of losses that incurred beyond a VaR cutoff value. It is by definition greater than the VaR.
A risk measure ρ(X):X→ℝ is said to be coherent if it satisfies that following four coherency axioms; see Artzner et al. (Reference Artzner, Delbaen, Eber and Heath1999):
∙ Monotonicity: if Y≤X⇒ρ(X)≥ρ(Y)
∙ Subadditivity: ρ(X+Y)≤ρ(X)+ρ(Y)
∙ Positive homogeneity: for any c>0, ρ(cX)=cρ(X)
∙ Translation invariance: for any c>0, ρ(X+c)=ρ(X)+c
Subadditivity axiom reflects the notion that the premium for the sum of two risks is not greater than the one for individual risk and that pooling risks helps to diversify a portfolio. It is well known that VaR does not satisfy the subadditivity axiom, but CTE does.
A distortion function ψ: [0, 1] → [0, 1] is a non-decreasing function such that ψ(0)=0 and ψ(1)=1. Wang (Reference Wang2000) has examined classes of premium/distortion functionals that transform the survival function S X (x) of the loss variable. The risk-adjusted or distortion risk measure denoted by ρ(X) is then given by
 $$\rho (X){\equals}{\int}_0^\infty {\psi (S(x))dx} $$
Furthermore, by substitutions and integration by parts:
 $$\eqalignno{ \rho (X){\equals} & {\int}_0^\infty {x\psi {\rm '}\left( {S(x)} \right)} f(x)dx{\equals}{\int}_0^\infty {xd} \left[ {1{\minus}\psi \left( {S(x)} \right)} \right] \cr {\rm }{\equals}{\rm } & {\minus}{\int}_0^1 {S^{{{\minus}1}} (t)\psi {\rm '}(t)dt{\rm }} {\equals}{\int}_0^1 {F^{{{\minus}1}} (t)\psi {\rm '}(1{\minus}t)dt} $$
where f(x)=dF(x)/dx and ψ′(·) is the first derivative of ψ(·). Based on (1), the risk measure ρ(X) can be interpreted as the mean of the utility function xψ′(S(x)) with respect to the loss distribution or as the mean of a random variable Y with cdf 1−ψ(S(x)) (see Pflug, Reference Pflug2009). Distortion risk measures form an important class of risk measures. Both VaR and CTE can be rewritten as the integration of a distortion function. See also Sereda et al. (Reference Sereda, Bronshtein, Rachev, Fabozzi, Sun and Stoyanov2010) for more analyses of distortion risk measures.
Wang (Reference Wang1995) proposes the proportional hazard (PH) premium principle such that ψ
PH
(u)=u
a
, where 0 < a < 1 and shows that if a distortion/transform function ψ(·) is concave then ρ(X) is coherent. Wang (Reference Wang2000) introduces another class of distortion operators ψ
θ
(u)=Φ[Φ−1(u) + θ], where Φ is the standard normal cumulative distribution. If ψ(·) is concave with ψ(0)=0 and ψ(1)=1, then u=uψ(1) + (1–u)ψ(0) ≤ ψ(u) for u ∈ [0, 1]. That is, S(x) ≤ ψ(S(x)) for 0 ≤ S(x) ≤ 1. Integrating both sides,
 $E(X){\equals}{\int}_0^\infty {S(x)dx\leq \rho (X)} $
A concave distortion operator ψ(·) therefore adjusts the premiums so that the risk-adjusted premium is not less than the expected loss value.
Wirch and Hardy (Reference Wirch and Hardy1999) consider the beta distribution distortion given by
 $$\psi _{b} (u){\equals}{\int}_0^u {{1 \over {B(a,b)}}t^{{a{\minus}1}} } (1{\minus}t)^{{b{\minus}1}} dt$$
where parameters a and b are non-negative and the beta function
 $B(a,b){\equals}{\int}_0^1 {t^{{a{\minus}1}} (1{\minus}t)^{{b{\minus}1}} dt} {\rm }.$
It is shown that when a≤1 and b≥1, the second derivative
 $\psi _{b}^{{{\rm ''}}} (u)\leq 0$
for all u ∈ [0, 1]. Hence ψ
b
(u) is concave and results in a coherent distorted risk measure for a≤1 and b≥1. Setting a=1, it yields the dual-power transform ψ
b
(u)=1–(1–u)
b
. The PH transform ψ
PH
(u) is a special case of the beta distortion with b=1. When calculating risk measures, unlike VaR and CTE, the beta distortion not only takes the entire loss distribution into consideration but also can better accommodate the desired degree of risk aversion by adjusting the values of parameters a and b.
In this paper, we study new classes of distortions and the corresponding distortion risk measures. The methods are based on distribution transforms, e.g., the beta distribution as seen in (2). The literatures that inspire the proposed methods are included in section 2. In section 3, we present new distribution distortions by replacing the beta distribution in (2) with other distributions having a support of [0, 1], such as truncated normal and Kumaraswamy distributions. In section 3, we develop composite distribution distortions in which the distribution distortion is applied to a function of the survival function. Specifically, we replace the upper limit of the integral in (2) by −ln(1−u), which allows us to use distributions with support [0, ∞). The parameter spaces ensuring the coherency of the resulting risk measures are derived for the proposed distortions. In section 4, closed-form expressions for distortion risk measures are derived for exponential and Pareto loss distributions. Numerical and graphical comparisons are presented. We apply the proposed distortion functions to derive risk measures for segregated fund guarantees in section 5, followed by concluding remarks.
2. Motivation
We next describe key works that motivate the proposed new families of distortion transforms in this paper. We report only a few pertinent studies. Nadarajah and Rocha (Reference Nadarajah and Rocha2016) have compiled an extensive list of references and explained how to use an R statistical package for statistical computations.
Eugene et al. (Reference Eugene, Lee and Famoye2002) launch a class of beta generalised distributions given by
 $$H(y){\equals}{\int}_0^{R(y)} {{1 \over {B(\alpha ,\beta )}}} t^{{\alpha {\minus}1}} (1{\minus}t)^{{\beta {\minus}1}} dt,y\in({\minus}\infty,\infty)$$
where R(⋅) is an arbitrary baseline cdf. Since then a myriad of multi-parameter distributions have been generated from similar frameworks by distorting various R(⋅) utilising appropriate non-beta generating distributions. For example, Cordeiro and de Castro (Reference Cordeiro and de Castro2011) employ the Kumaraswamy distribution instead of the beta distribution as the generating distribution.
Alzaatreh et al. (Reference Alzaatreh, Lee and Famoye2013, Reference Alzaatreh, Lee and Famoye2014) advance another new method for generating so-called T-X families of distributions by replacing R(⋅) with a differentiable and monotonically non-decreasing function w°R:ℝ→[a,b] in (3):
 $$H(y){\equals}{\int}_0^{w\left( {R(y)} \right)} {g(t)dt{\equals}G(w\left( {R(y)} \right))} $$
where g(⋅) is an appropriate probability density function (pdf) with support on [a, b] and G(⋅) denotes the corresponding cdf. The introduction of the function w(R(⋅)) as the upper limit in the integral allows one to employ a pdf g(⋅) with support other than [0, 1]. Alzaatreh et al. (Reference Alzaatreh, Lee and Famoye2015) suggest several w(⋅) functions, e.g., w(u)=−ln(u/(1−u)) and −ln(1−u a ) where a>0, and focus on the case when w(u)=−ln(1−u) and g(⋅) is the gamma pdf. The fact that H(y)=G(w(R(y))) provides a relationship for simulations of random numbers and calculations of quantiles of the resulting distribution.
In the context of this paper, instead of a cdf R(⋅), the distortion is applied to a survival function. With R(⋅) in (3) being standard uniform cdf, it gives the beta distortion in (2). Utilising the framework of the T-X family, we obtain new distortions, specifically focussing on the case w(u)=−ln(1−u) in (4), and name it as composite distribution distortion.
3. Distribution Distortions
In this section, we introduce new families of distortion functions of the form
 $$\psi (u){\equals}{\int}_0^u {g(t)dt,u \in\element [0,1]} $$
where the generating pdf
 $g\in{\rm }{\cal G}_{{[0,{\rm }1]}} $
and
 ${\cal G}_{{[p,q]}} {\rm }{\equals}{\rm }\{g \,|\, g{\rm \,\,is \,\,a \,\,non{\minus}increasing \,\,pdf \,\,with \,\,support }\,\,[p,q]\} .$
From (1), we obtain the following relationships:
 $$\rho (X){\equals}{\int}_0^\infty {xg\left( {S(x)} \right)f(x)dx{\rm }} {\equals}{\int}_0^1 {S^{{{\minus}1}} (t)g(t)dt{\rm }{\equals}} {\minus}{\int}_0^1 {F^{{{\minus}1}} (t)g(1{\minus}t)dt} $$
The risk measure in (6) is the weighted average of the losses with a weight function of g(S(x))f(x). The function g(S(x)) can be seen as a weighting risk aversion function defined over the loss; see Cotter and Dowd (Reference Cotter and Dowd2006). That the slope of the tangent line to the distortion curve, defined to be g(u)=dψ(u)/du, is non-increasing means that the weights associated with lower survival values and hence with higher losses should be no less than the weights associated with lower losses. If a uniform g(t)=1 for t∈[0, 1], i.e., the identity ψ(u)=u for u∈[0, 1] is chosen, then ρ(X)=E(X) and the decision-maker is said to be risk neutral.
There are several candidates for g(⋅) in
 ${\cal G}_{{[0,1]}} $
; see Johnson et al. (Reference Johnson, Kotz and Balakrishnan1995) and Kotz and Van Dorp (Reference Kotz and Van Dorp2004). For example, the reciprocal distribution with a pdf of (1 + t)−1/ln(2) for t∈[0,1]. However, it is not flexible as it involves no parameters. The beta distribution has been investigated in Wirch and Hardy(Reference Wirch and Hardy1999). We choose to study the case when g is the Kumaraswamy pdf. Technically, one may also use any concave truncated distribution, and here the commonly used truncated normal with support [0, 1] is explored for demonstration. Both the Kumaraswamy and truncated normal distributions have two parameters.
The appropriate parameter spaces where the distortion functions satisfy the concavity condition required for coherency will be derived by inspecting the second derivative of the proposed distortion functions. Note that the first derivative dψ(u)/du=g(u) is non-negative. The concavity requires that ψ''(u)=g'(u)≤0 for all u∈(0,1). That is, g(⋅) is non-increasing and mainly has a reverse J shape for the appropriate parameter spaces.
In the following subsections, we derive the parameter spaces in which the proposed distortion is concave. While the selection of parameter values of the distortions may be political or depend on the degree of risk aversion of the users, we construct plots of the distortion functions to see the effects of parameters on the distortion functions and risk attitudes.
3.1. Kumaraswamy distortion
The pdf of the Kumaraswamy distribution with support [0, 1] is
 $$g_{K} (t){\rm }{\equals}{\rm }abt^{{a{\minus}1}} (1{\minus}t^{a} )^{{b{\minus}1}} ,{\rm }t{\rm \,\in\,}[0,{\rm }1]$$
where a and b are non-negative parameters. When a=1, the Kumaraswamy distribution gives the beta distribution. The Kumaraswamy distribution distortion is given by
 $$\psi _{K} (u){\equals}{\int}_0^u {abt^{{a{\minus}1}} (1{\minus}t^{a} )^{{b{\minus}1}} dt{\equals}1{\minus}(1{\minus}u^{a} )^{b} } {\equals}\mathop \sum\limits_{k{\rm }{\equals}{\rm }1}^\infty \left( {\matrix{ b \hfill \cr k \hfill \cr } } \right)({\minus}1)^{k} u^{{ak}} $$
since
 $$(1{\minus}x)^{r} {\equals}\mathop{\sum}\limits_{k{\rm }{\equals}{\rm }0}^\infty {\left( {\matrix{ r \hfill \cr k \hfill \cr } } \right)} {\rm \ztbnd(\minus1) }^{k} x^{k} $$
for |x| < 1. The series expression can give rise to a possible closed-form expression for the Kumaraswamy distortion risk measure. The dual-power transform is a special case with a=1. When b=1, it gives the PH transform.The corresponding risk measure is then given by
 $$\rho _{K} (X){\equals}{\int}_0^\infty {1{\minus}\{ (1{\minus}[S(x)]^{a} \} ^{b} dx} {\equals}\mathop{\sum}\limits_{k{\equals}1}^\infty {{\int}_0^\infty {\left( {\matrix{ b \cr k \cr } } \right)({\minus}1)^{k} [S(x)]^{{ak}} } } $$
It may have a closed form depending on the loss distribution, e.g., Pareto loss in section 5.2.
Lemma 1: The Kumaraswamy distortion ψ K (u)=1−(1−u a ) b in (7) is concave if a≤1 and b≥1.
Proof: The second derivative of ψ k (u) is given by
 $$\psi _{K}^{{{\rm ''}}} (u){\rm }{\equals}{\rm }abu^{{a{\minus}2}} (1{\minus}u^{a} )^{{b{\minus}2}} \left[ {a{\minus}1{\plus}(1{\minus}ab)u^{a} } \right]$$
For u∈(0,1), a−1 < a−1 + (1−ab)u
a
< a(1−b) when (1−ab) < 0, and a(1−b)<a−1+(1−ab)u
a
<a−1 when (1−ab)<0. Therefore, the concavity requirement of
 $\psi _{K}^{{{\rm ''}}} (u)\leq 0$
for u∈(0,1) is satisfied when a≤1 and b ≥ 1, which, notably, is the same requirement for the parameters in the beta distortion.
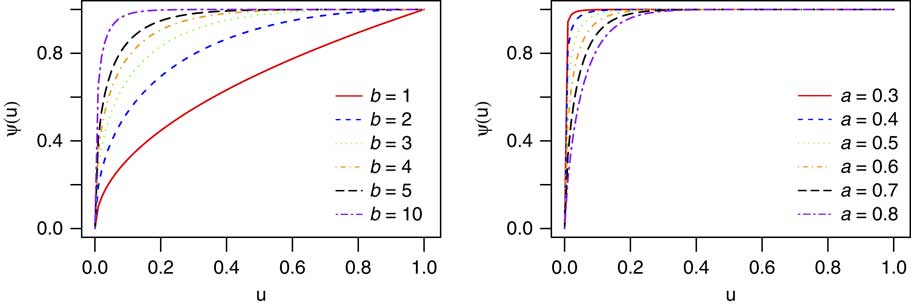
Figure 1 displays the concave curves of the Kumaraswamy distortion for various parameter values. Belles-Sampera et al. (Reference Belles-Sampera, Guillen and Santolino2016) use the area under the distortion function as a measure of global risk attitude. Note that the area under a concave curve on [0, 1] is always greater than half, and a larger area indicates a higher level of global risk tolerant attitude. It appears that the choice of a larger b value or a smaller a value reflects a higher level of global risk tolerant attitude.
Kumaraswamy transform. Left panel: a=0.5. Right panel: b=10.

Fixing a=0.5, at a small extreme survival value u, the slopes of the tangent lines to the curves increases as b increases. That is, a greater weight is assigned to a large extreme loss as b increases, indicating a higher level of risk aversion. The parameter b controls the right tail risk aversion. The graph on the right, fixing b=10, indicates that the parameter a controls the rate of convergence.
As one might expect, the parameters in the Kumaraswamy and beta distortions have similar effects on the risk measures and risk attitudes. Bear in mind that the Kumaraswamy distortion has a closed functional form that appears more attractive and can be readily applied. In section 5, we examine the effects of parameters on the risk measure for some selected loss distributions.
3.2. Truncated normal distortion
The pdf of a truncated normal distribution that has a support of [0, 1] and an original normal distribution with mean μ and standard deviation σ, is given by
 $$g_{{tn}} (t){\equals}\phi \left( {{{t{\minus}\mu } \over \sigma }} \right)\,/\,(c\sigma )\,{\rm where}\,c{\equals}{\rm \Phi }\left( {{{1{\minus}\mu } \over \sigma }} \right){\minus}{\rm \Phi }\left( {{{{\minus}\mu } \over \sigma }} \right)$$
for t ∈ [0, 1]. The functions ϕ(·) and Φ(·) are the standard normal pdf and cdf, respectively. The truncated normal transform is defined to be
 $$\psi _{{tn}} (u{\hbox{;}}\,\mu ,\sigma ){\equals}{\int}_0^u {g_{{tn}} (t)d} t{\equals}{1 \over c}\left[ {{\rm \Phi }\left( {{{u{\minus}\mu } \over \sigma }} \right){\minus}{\rm \Phi }\left( {{{{\minus}\mu } \over \sigma }} \right)} \right]$$
The corresponding risk measure is then given by
 $$\rho _{{tn}} (X){\equals}{\int}_0^\infty {{1 \over c}\left[ {{\rm \Phi }\left( {{{S(x){\minus}\mu } \over \sigma }} \right){\minus}{\rm \Phi }\left( {{{{\minus}\mu } \over \sigma }} \right)} \right]} dx$$
The following lemma specifies the parameter spaces for the truncated normal distortion to maintain the coherency of the resulting risk measures.
Lemma 2: The truncated normal transform ψ tn in (9) with parameters μ and σ>0 is concave if μ≤0.
Proof The second derivative of truncated normal transform is
 $$\psi _{{tn}}^{\prime\prime} (u){\equals}{\minus}g_{{tn}} (u){{u{\minus}\mu } \over {c\sigma ^{2} }}$$
For all u ∈ [0, 1],
 $\psi _{{tn}}^{\prime\prime} (u)\leq 0$
when μ ≤ 0. That is, with the original mean μ ≤ 0 and truncated to [0, 1], a segment of the right half of the normal pdf curve is used to generate a concave distortion function.
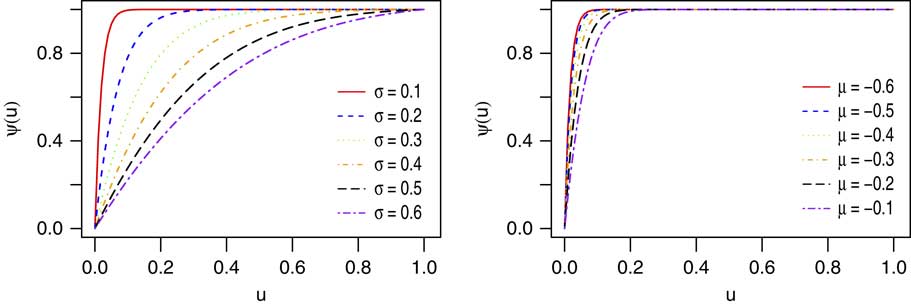
In Figure 2, the effects of varying μ<0 and σ are shown. When μ=−0.5, a lower level of global risk tolerant attitude and risk aversion is associated with the distortion function resulting from a higher value of σ. Setting σ=1, a smaller μ value corresponds to a higher level of global risk tolerant attitude. From the spreadness in the plotted curves, it appears that the calibration of the parameter σ would allow one to make a larger extent of risk attitude adjustments.
Truncated normal transform. Left panel: μ=−0.5. Right panel: σ=0.1.

4. Composite Distribution Distortions
In section 3, we introduce two concave distortions using distribution functions with finite support [0, 1]. In this section, we present new distortion functions by adopting the proposal in Alzaatreh et al. (Reference Alzaatreh, Lee and Famoye2015). In particular, the composite distribution distortions of the form:
 $$\psi (u){\equals}G(w(u)){\equals}{\int}_0^{w(u)} {g(t)dt} $$
where w(u)=−ln(1–u) and g(·) is a pdf with a support of [0,∞) and with a corresponding cdf G(·). Note that for u ∈ [0, 1], 0≤w(u)≤∞, ψ(0)=0 and lim u→1 ψ(u)=1. The resulting risk measure is given by
 $$\eqalignno{ \rho (X){\equals} & {\int}_0^\infty {xg\left( {{\minus}{\rm ln}(1{\minus}S(x))} \right)[1{\minus}S(x)]^{{{\minus}1}} f(x)dx} \cr {\equals} & {\int}_0^\infty {\left. {xd\left[ {1{\minus}\psi \left( {w(S(x)} \right)} \right]} \right)} {\equals}{\int}_0^1 {t^{{{\minus}1}} S^{{{\minus}1}} (1{\minus}t)g({\minus}{\rm ln}(t))dt} $$
This integration is relatively easy to program using a computer software. To see the proposed distortion function and the corresponding risk measure from a different angle, let V be a random variable with pdf g(·) and define Y=S −1 (1–e −V ). The cdf of Y is then 1−ψ(S(·)). The mean of Y is equal to the risk measure based on the distortion function defined in (10).
The first derivative ψ′(u)=g(w(u))/(1–u) is non-negative for u ∈ [0, 1]. The second derivative ψ″ is given by
 $$\psi \prime\prime(u){\equals}{1 \over {(1{\minus}u^{2} )}}\left[ {g\prime(w(u)){\plus}g(w(u))} \right]$$
Since 1/(1−u)2>0 for u ∈ (0, 1), to induce a coherent risk measure, a proper candidate g(⋅) in (10) must satisfy the condition that g'(w(u)) + g(w(u)) ≤ 0 for u ∈ (0, 1). The condition also implies that g(⋅) is strictly decreasing since g(⋅) is positive.
Note that not all continuous, strictly decreasing pdf’s can meet the concavity requirement in (12). For example, the Pareto pdf given by g(t)=ba b /(t + a) b+1, where a > 0 and b > 0. In this case, g'(w(u))=−b(b+1)a b [w(u)+a]−(b+2) < 0 for all a > 0 and b > 0, but there does not exist any (a, b) value such that g′(w(u)) + g(w(u))=ba[w(u) + a −(b+2)[w(u) + a−b−1] < 0 for all u ∈ (0, 1).
There is a long list of potentially suitable distribution choices for g(⋅) with support [0,∞). In the following subsections, we examine only the two parameters cases when g(⋅) are the exponentiated exponential (EE) and gamma pdf’s. Both distributions are a generalisation of exponential distribution but in different ways. One major advantage of the EE distribution is that its cdf has a closed-form expression.
4.1. Composite EE distortion
Let g ee (t) be the EE pdf, for t > 0:
 $$g_{{ee}} (t){\equals}abe^{{{\minus}bt}} \left( {1{\minus}e^{{{\minus}bt}} } \right)^{{a{\minus}1}} $$
where the shape parameter a > 0 and the scale parameter b > 0. Applying the series expansion
 $(1{\minus}x^{b} )^{a} {\equals}\mathop{\sum}\limits_{k{\equals}0}^\infty {\left( {\matrix{ a \cr k \cr } } \right)({\minus}1)^{k} t^{{bk}} } $
for |x|
b
< 1, the composite EE distortion is given by
 $$\eqalignno{ \psi _{{ee}} (u){\equals} & {\int}_0^{{\minus}{\rm ln}(1{\minus}u)} {abe^{{{\minus}bt}} \left( {1{\minus}e^{{{\minus}bt}} } \right)^{{a{\minus}1}} dt} \cr {\equals} & \left[ {1{\minus}(1{\minus}u)^{b} } \right]^{a} {\equals}\mathop{\sum}\limits_{k{\equals}0}^\infty {\left( {\matrix{ a \cr k \cr } } \right)({\minus}1)^{k} } \:\mathop{\sum}\limits_{i{\equals}0}^\infty {\left( {\matrix{ {bk} \cr i \cr } } \right)({\minus}1)^{i} u^{i} } $$
One can see from the closed functional form that ϕ ee (u)=u when a=1 and b=1. Just as in the beta and Kumaraswamy distortions, the PH is its special case with b=1. When a=1, it gives the dual-power transform.
The distortion risk measure is given by
 $$\rho _{{ee}} (X){\equals}{\int}_0^\infty {\{ 1{\minus}[1{\minus}S(x)]^{b} \} ^{a} \:dx} $$
This integral, seemingly similar to the one in the Kumaraswamy risk measure, can also be easily obtained by a built-in R integration function.
Lemma 3: The EE distortion ψ ee (u)=[1−(1−u) b ] a in (13) is concave if b ≥ 1 and a ≤ b.
Proof:
Since e
bln(1−u)=(1 − u)
b
, the first derivative
 $\psi _{{ee}}^{\prime} (u){\equals}ab(1{\minus}u)^{{b{\minus}1}} \left[ {1{\minus}(1{\minus}u)^{b} } \right]^{{a{\minus}1}} $
. The second derivative
 $\psi _{{ee}}^{\prime\prime} (u)$
of ψ(u) with respect to u is given by
 $$\eqalignno{ \psi _{{ee}}^{\prime\prime} (u){\equals} & ab\left[ {1{\minus}(1{\minus}u)^{b} } \right]^{{a{\minus}2}} (1{\minus}u)^{{b{\minus}2}} \left\{ {(a{\minus}1)b(1{\minus}u)^{b} {\minus}(b{\minus}1)\left[ {1{\minus}(1{\minus}u)^{b} } \right]} \right\} \cr {\equals} & ab\left[ {1{\minus}(1{\minus}u)^{b} } \right]^{{a{\minus}2}} (1{\minus}u)^{{b{\minus}2}} \left\{ {(a{\minus}1)(1{\minus}u)^{b} {\minus}(b{\minus}1)} \right\} $$
If b ≥ 1 (a − 1)(1 − u)
b
≤ (b − 1) for all u ∈ [0, 1] when a ≤ b. When b < 1, there does not exist a positive a value such that
 $\psi _{{ee}}^{\prime\prime} (u)\leq 0$
for u ∈ (0, 1).
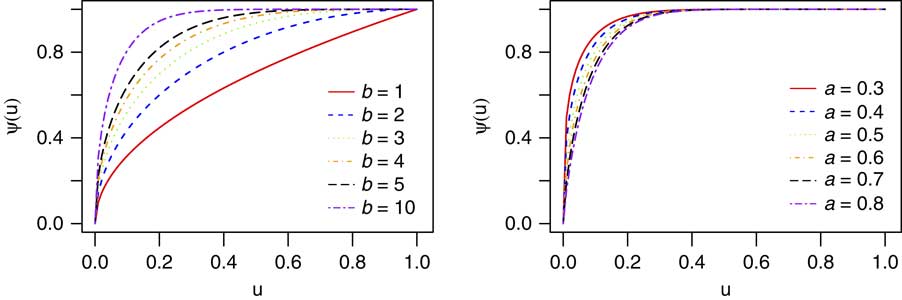
Note that the figures below are very similar to Figure 1. Therefore, the conclusions about the effects of the parameters a and b on the distortion functions, risk measures and risk attitudes based on Figure 1 also hold and are not repeated here (Figure 3).
Exponentiated exponential transform. Left panel: a=0.5. Right panel: b=10.

4.2. Composite gamma distortion
Let g(t) be the gamma probability density function with parameters a > 0 and b > 0, then
 $$\psi _{G} (u){\equals}{\int}_0^{{\minus}{\rm ln}(1{\minus}u)} {{{b^{a} } \over {{\rm \Gamma }(a)}}t^{{a{\minus}1}} e^{{{\minus}bt}} dt} {\equals}{1 \over {{\rm \Gamma }(a)}}\gamma \left( {a,{\minus}b\:{\rm ln}(1{\minus}u)} \right)$$
where
 $\gamma (s,x){\equals}{\int}_0^x {t^{{s{\minus}1}} e^{{{\minus}t}} dt} $
is the lower incomplete gamma. The composite gamma distortion is the cdf of a gamma random variable with parameters a and b=1 evaluated at −bln(1 − u). When a=1 and b=1, ψ
G
(u)=1. When a=1, g(t) is exponential and leads to the dual-power transform 1 − (1 − u)
b
, which is concave for b ≥ 1. Applying the series expansion
 $e^{{{\minus}bt}} {\equals}\:\mathop{\sum}\limits_{i{\equals}1}^\infty {(bt)^{i} \,/\,i\,!\,} $
an alternative form of the proposed composite gamma distortion function is given by
 $$\psi _{G} (u){\equals}{{b^{a} } \over {{\rm \Gamma }(a)}}\mathop{\sum}\limits_{i{\equals}0}^\infty {{{b^{i} [{\minus}{\rm ln}(1{\minus}u)]^{{a{\plus}i}} } \over {i\,!\,(a{\plus}i)}}} $$
The distortion risk measure is, using (11):
 $$\eqalignno{ \rho _{G} (X){\equals} & {{b^{a} } \over {{\rm \Gamma }(a)}}{\int}_0^\infty {x\left[ {{\minus}{\rm ln}(1{\minus}S(x))} \right]^{{a{\minus}1}} e^{{b\,\,{\rm ln}(1{\minus}S(x))}} \left[ {1{\minus}S(x)} \right]^{{{\minus}1}} f(x)dx} \cr {\equals} & {{b^{a} } \over {{\rm \Gamma }(a)}}{\int}_0^1 {S^{{{\minus}1}} (1{\minus}t)t^{{b{\minus}1}} [{\minus}{\rm ln}(t)]^{{a{\minus}1}} dt} $$
Lemma 4: The composite gamma distortion ψ G (u) in (14) is concave if 0 < a ≤ 1 and b ≥ 1.
Proof: The second derivative of ψ G (u) is given by
 $$\psi _{G}^{\prime\prime} (u){\equals}{{b^{a} \left[ {{\minus}\left( {{\rm ln}(1{\minus}u)} \right)} \right]^{{a{\minus}2}} (1{\minus}u)^{{b{\minus}2}} } \over {{\rm \Gamma }(a)}}\left[ {(a{\minus}1){\plus}{\rm ln}(1{\minus}u)(b{\minus}1)} \right]$$
Consequently, when 0 < a ≤ 1 and b ≥ 1,
 $\psi _{G}^{\prime\prime} (u)\leq 0$
for all u ∈ (0, 1).
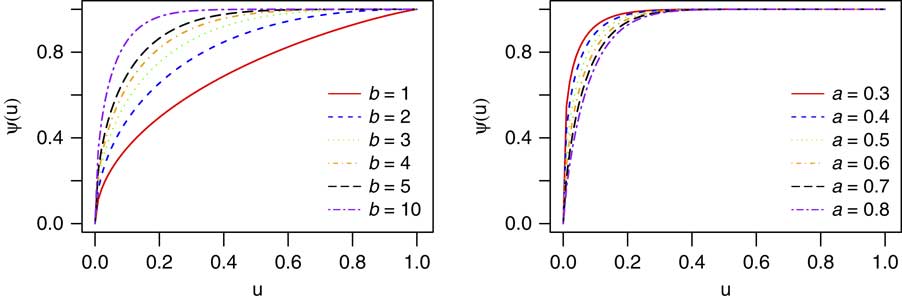
Figure 4 shows the same patterns as in Figure 1 for various a and b values.
Gamma transform. Left panel: a=0.5. Right panel: b=10.

5. Examples
In this section, we apply the distortions defined in section 3 and 4 to exponential, Pareto and log-normal losses. Closed-form expressions of distortion risk measures for the exponential and Pareto losses, including the ones resulting from the beta distortion, are derived. Numerical and graphical comparisons are then performed in the last subsection.
5.1. Exponential loss
An exponential loss random variable has a pdf f(x)=θe −αx , θ > 0. It has a mean of 1/θ, a variance of 1/θ 2, a survival function S(x)=e −θx for x ≥ 0 and S −1(t)=−ln(t)/θ, t ∈ [0, 1].
Using (6) and using the fact that du t /dt=u t ln(t), beta distortion risk measure is
 $$\rho _{b} (X){\equals}{\minus}{1 \over {\theta B(a,b)}}{\int}_0^1 {{\rm ln}(t)t^{{a{\minus}1}} (1{\minus}t)^{{b{\minus}1}} dt} {\equals}{1 \over \theta }\left[ {{\rm \Psi }(a{\plus}b){\minus}{\rm \Psi }(a)} \right]$$
where the digamma function Ψ(a)=dΓ(a)/da is the digamma function. When b=1, ρ b (X)=(aθ)−1 since Ψ(a + 1)=Ψ(a) + 1/a.
Similar to the derivation of (16), Kumaraswamy distortion risk measure is
 $$\eqalignno{ \rho _{K} (X){\equals} & {\int}_0^\infty {abt[e^{{{\minus}\theta t}} ]^{{a{\minus}1}} [1{\minus}e^{{{\minus}a\theta t}} ]^{{b{\minus}1}} \theta e^{{{\minus}\theta t}} dt} \cr {\equals} & {b \over {a\theta }}{\int}_0^1 {{\rm ln}(u)(1{\minus}u)^{{b{\minus}1}} du} {\equals}{1 \over {a\theta }}\left[ {{\rm \Psi }(b{\plus}1){\minus}{\rm \Psi }(1)} \right]. $$
For a fixed b value, the risk measure is inversely proportional to a, 0 ≤ a ≤ 1. A very small a value can greatly inflate the risk measure, which is consistent with the observation based on Figure 1. Alternatively, based on the infinite sum expression in (7):
 $$\rho _{K} (X){\equals}{1 \over {a\theta }}\mathop{\sum}\limits_{k{\equals}1}^\infty {\left( {\matrix{ b \cr k \cr } } \right){{({\minus}1)^{k} } \over k}} $$
another closed form can be derived, via integration by parts similar to the derivation of (16) and the fact that du t /dt=u t ln(t), The EE distortion risk measure, based on (13), is given by
 $$\rho _{{ee}} (X){\equals}\mathop{\sum}\limits_{k{\equals}0}^\infty {\left( {\matrix{ a \cr k \cr } } \right)({\minus}1)^{k} } \left[ {1{\plus}\mathop{\sum}\limits_{i{\equals}1}^\infty {\left( {\matrix{ {bk} \cr i \cr } } \right){{({\minus}1)^{i} } \over {i\theta }}} } \right]$$
Using series expansion
 ${\rm ln}(1{\minus}t){\equals}{\minus}\mathop{\sum}\limits_{k{\equals}1}^\infty {t^{k} \,/\,k} $
for |t| < 1 and S
−1(1−t)=−ln(1−t)/θ, the gamma distortion risk measure in (15) is
 $$\eqalignno{ \rho _{{ga}} (X){\equals} & {\int}_0^1 \,{{{b^{a} } \over {\theta {\rm \Gamma }(a)}}{\rm ln}(1{\minus}t)\left[ {{\minus}{\rm ln}(t)} \right]^{{a{\minus}1}} t^{{b{\minus}1}} dt} \cr {\equals} & {\int}_0^1 \,{{{b^{a} } \over {\theta {\rm \Gamma }(a)}}\left[ {{\minus}{\rm ln}(t)} \right]^{{a{\minus}1}} } \mathop{\sum}\limits_{k{\equals}1}^\infty {{{t^{{k{\plus}b{\minus}1}} } \over k}dt} \cr {\equals} & {\int}_0^\infty {{{b^{a} } \over {\theta {\rm \Gamma }(a)}}s^{{a{\minus}1}} } \mathop{\sum}\limits_{k{\equals}1}^\infty {{{e^{{{\minus}s(k{\plus}b)}} } \over k}ds} {\equals}{{b^{a} } \over \theta }\mathop{\sum}\limits_{k{\equals}1}^\infty {{k \over {(k{\plus}b)^{a} }}} $$
for 0 ≤ a ≤ 1 and b ≥ 1.
5.2. Pareto loss
Consider a Pareto loss random variable with pdf f(x)=βα β /(x + α) β+1, x > 0. It has mean α/(β − 1) for β > 1, variance α 2 β/[(β − 1)2(β − 2)] for β > 2, survival function S(x)=[α/(x + α)] β , and S −1(t)=α(1 − t 1/β )t −1/β , t ∈ [0, 1].
The beta distortion risk measure is
 $$\eqalignno{ \rho _{{bt}} (X){\equals} & {\alpha \over {B(a,b)}}{\int}_0^1 {(t^{{{\minus}1\,/\,\beta }} {\minus}1)t^{{a{\minus}1}} (1{\minus}t)^{{b{\minus}1}} dt} \cr {\equals} & {\alpha \over {B(a,b)}}\left[ {B(a{\minus}1\,/\,\beta ,b){\minus}B(a,b)} \right] $$
When a − 1/β ≤ 0, the B(a − 1/β, b) is not well defined.
The Kumaraswamy distortion risk measure defined in (8), with a substitution of s=[α/(x + α)] aβ , is given by
 $$\eqalignno{ \rho _{K} (X){\equals} & {\int}_0^\infty {abx\left[ {\left( {{\alpha \over {x{\plus}\alpha }}} \right)^{\beta } } \right]^{{a{\minus}1}} \left[ {1{\minus}\left( {{\alpha \over {x{\plus}\alpha }}} \right)^{{a\beta }} } \right]^{{b{\minus}1}} {{\beta \alpha ^{\beta } } \over {(x{\plus}\alpha )^{{\beta {\plus}1}} }}dx} \cr {\equals} & \alpha b{\int}_0^1 {(s^{{{\minus}1\,/\,(a\beta )}} {\minus}1)(1{\minus}s)^{{b{\minus}1}} ds} \cr {\equals} & \alpha b\left[ {B(1{\minus}1\,/\,(a\beta ),b){\minus}B(1,b)} \right] $$
Similar to the beta distortion risk measure, when aβ ≤ 1 or equivalently a − 1/β ≤ 0, the beta function and consequently the risk measure are not well defined. When a=1 and b=1, the risk measure is α/(β − 1) for β > 1, which is the mean of the Pareto loss random variable. Alternatively, the distortion risk measure is
 $$\rho _{K} (X){\equals}\alpha \mathop{\sum}\limits_{k{\equals}1}^\infty {\left( {\matrix{ b \cr k \cr } } \right){{({\minus}1)^{k} } \over {a\beta k{\minus}1}}} $$
Note that
 $${\int}_0^\infty {S(x)^{k} dx} $$
is not well defined if aβk ≤ 1. That is, again, aβ > 1 is required for a finite risk measure.
The EE distortion risk measure is
 $$\rho _{{ee}} (X){\equals}\mathop{\sum}\limits_{k{\equals}0}^\infty {\left( {\matrix{ a \cr k \cr } } \right)({\minus}1)^{k} } \left[ {1{\plus}\mathop{\sum}\limits_{i{\equals}1}^\infty {\left( {\matrix{ {bk} \cr i \cr } } \right){{({\minus}1)^{i} \alpha } \over {i\beta {\minus}1}}} } \right]$$
Notice that, for u ∈ [0, 1] and b ≥ 1,(1 − u) > (1 − u) b and [1 − (1 − u) b ] a ≥ u a . Therefore,
 $${\int}_0^\infty {\left\{ {1{\minus}\left[ {1{\minus}\left( {{\alpha \over {x{\plus}\alpha }}} \right)^{\beta } } \right]^{b} } \right\}} ^{a} dx\geq \mathop{\int}\limits_0^\infty {\left( {{\alpha \over {x{\plus}\alpha }}} \right)^{{a\beta }} dx} $$
The integral on the right hand side is not finite when aβ ≤ 1. This places a constraint on the choice of a value at which the EE distortion risk measure on the left-hand side is finite.
The composite gamma distortion risk measure is
 $$\rho _{{ga}} (X){\equals}{\int}_0^1 {{\alpha \over {b^{a} {\rm \Gamma }(a)}}\left[ {(1{\minus}t)^{{{\minus}1\,/\,\beta }} {\minus}1} \right]\left[ {{\minus}{\rm ln}(t)} \right]^{{a{\minus}1}} t^{{1\,/\,b{\minus}1}} dt} $$
for 0 ≤ a ≤ 1 and 0 ≤ b ≤ 1.
5.3. Numerical results
We consider three loss distributions. They are the exponential loss distribution with θ=1, the Pareto distribution with (α, β)=(2, 3) and the log-normal distribution with mean of −0.5 and s.d. of 1. For the purpose of easier comparisons, the parameter values are chosen such that all have a mean loss of 1. They have a variance of 1, 3 and 1, respectively. The proposed distortion risk measures for a log-normal loss random variable are computed numerically using the software R in our numerical results below.
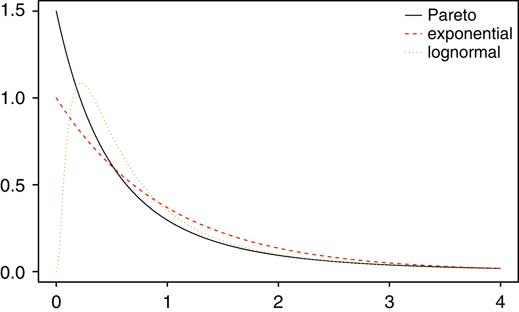
In addition to the distortion risk measures proposed in this paper, VaR and CTE were also computed. Figure 5, we plotted the pdf’s of the three widely used loss random variables. Exponential distribution is a special case of gamma and has a light tail. Pareto has the heaviest tail and therefore one would expect the highest risk measure when the same distortion function is applied. The tail of the log-normal distribution is heavier than exponential and used in financial application such as stock return modelling.
Density functions of exponential, Pareto and log-normal losses.

Note that
 $CTE{\equals}{\int}_q^1 {F^{{{\minus}1}} (t)dt\,/\,(1{\minus}q)} $
. The formulas for the VaR and CTE risk measures at level q for the three loss random variables are shown below.
∙ Exponential loss with a cdf of 1 − e −θx for x ≥ 0
 $${\rm VaR}{\equals}{\minus}{\rm ln}(1{\minus}q)\,/\,\theta \,{\rm and}\,{\rm CTE}{\equals}{\minus}[{\rm ln}(1{\minus}q){\minus}1]\,/\,\theta $$
∙ Pareto loss with a cdf of 1 − [α/(x + α)] β for x ≥ 0
$${\rm VaR}{\equals}\alpha [1{\minus}(1{\minus}q)^{{1\,/\,\beta }} ](1{\minus}q)^{{{\minus}1\,/\,\beta }} \,{\rm and}\,{\rm CTE}{\equals}{{\alpha \beta (1{\minus}q)^{{{\minus}1\,/\,\beta }} } \over {(\beta {\minus}1)}}{\minus}\alpha $$
∙ Log-normal loss random variable with a cdf of
${\rm \Phi }\left( {{{{\rm ln}(x){\minus}\mu _{x} } \over {\sigma _{x} }}} \right)$
for x ≥ 0


 $${\rm VaR}{\equals}{\rm exp}\{ {\rm \Phi }^{{{\minus}1}} (q)\sigma _{x} {\plus}\mu _{x} \} \,{\rm and}\,{\rm CTE}{\equals}{{e^{{\mu _{x} {\plus}\sigma _{x}^{2} \,/\,2}} } \over {1{\minus}q}}\left[ {1{\minus}{\rm \Phi }\left( {{{{\rm ln}({\rm VaR}{\minus}\mu _{x} {\minus}\sigma _{x}^{2} )} \over {\sigma _{x} }}} \right)} \right]$$
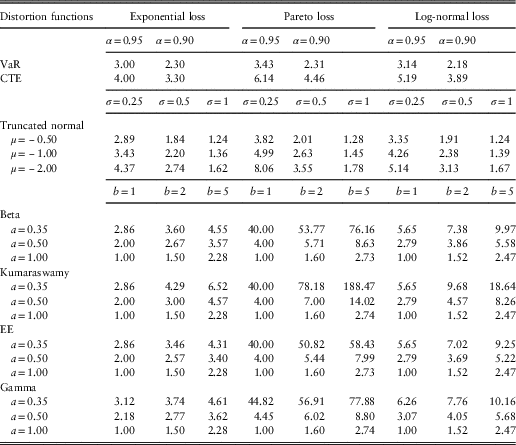
In Table 1, distortion risk measures are calculated for various combinations of parameter values to investigate the magnitudes of their effects.
Risk measures.

Note: VaR, value at risk; CTE, conditional tail expectation.
For the truncated normal distortion with a support of [0, 1], the risk measure increases as the mean of the original normal distribution decreases and as the standard deviation decreases. While they are all expectedly larger than the mean loss of 1, most of the results reported here are not greater than CTE. As shown in the previous section, setting b=1, the beta, Kumaraswamy and EE distortions all yield the PH transform with parameter a, and hence output the same risk measure. For all distortion functions, the risk measure increases as a decreases and as b increases. The parameter a appears to have a more dramatic effect on the risk measure than b for the Pareto loss, which has the highest variance and skewness among the three loss distributions.
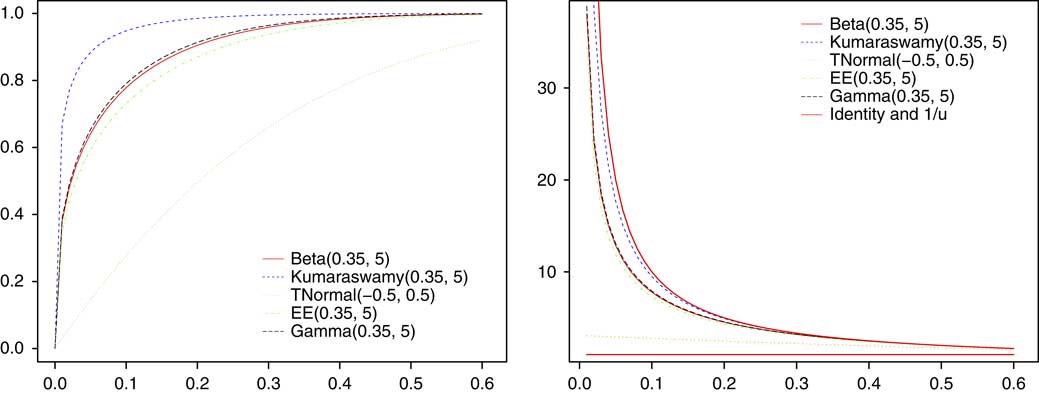
Belles-Sampera et al. (Reference Belles-Sampera, Guillen and Santolino2016) also suggest graphing the quotient between the distortion function ψ(u) and the identity function u for analysis of the risk attitude locally at each u value, with quotients greater than 1, equal to 1 and less than 1 representing risk tolerant, neutral and intolerant, respectively. Figure 6 exhibits the distortion curves and the corresponding quotient curves with parameter values (a, b)=(0.35, 5) and (μ, σ)=(−0.5, 0.5) for the truncated normal distortion.
The distortion and quotient functions of truncated normal transform with μ=−0.5 and σ=0.5 and other transforms with parameters a=0.35 and b=5. EE, exponentiated exponential.

Note that although the same parameter values are employed, the global and local risk behaviours reflected by the beta, Kumaraswamy, EE and gamma distortions are not the same. The curve of the truncated normal transform with parameters μ=−0.5 and σ=0.5 lies below all other transforms with parameters a=0.35 and b=5. Hence, among the plotted distortions, it produces the smallest risk measure, consistent with the conclusion by inspecting the areas under the curve. At a=0.35 and b=5, the Kumaraswamy distortion represents more risk tolerant attitude than other distortions, and its quotient reflects a local risk attitude near the maximum possible quotient value of 1/u. Furthermore, the beta and gamma distortions behave in a similar manner. The EE distortion appears to be relatively less risk tolerant locally at u ≤ 0.5. The truncated normal transform with μ=−0.5 and σ=0.5 reflects a risk attitude closer to the risk neutral behaviour than all other transforms considered in Figure 6.
6. Application
In this section, we discuss a practical application of the proposed distortion risk measures. Investigations of the reserve requirements for variable annuities and segregated fund guarantee have received a fair share of attention from actuaries. Here, we revisit the segregated fund guarantees example in Wirch and Hardy (Reference Wirch and Hardy1999), and study the reserve requirement using the proposed risk measures and compare them to some existing coherent risk measure approaches such as VaR, CTE and beta distortion risk measures.
As in Wirch and Hardy (Reference Wirch and Hardy1999), we consider a 10-year single premium segregated fund contract with a guarantee, v, of $75, $85 or $100 at maturity for a $100 premium paid upfront. It is assumed that the company invests the premium in stocks offering log-normal returns with annual parameters μ=0.07 and σ=0.18. The distribution of the losses, L, depends on the guarantee v and the stock return, S
10, at maturity. In other words, L=max (0, v − S
10), where S
10 follows log-norm
 $\left( {0.7,0.18{\times}\sqrt {10} } \right)$
.
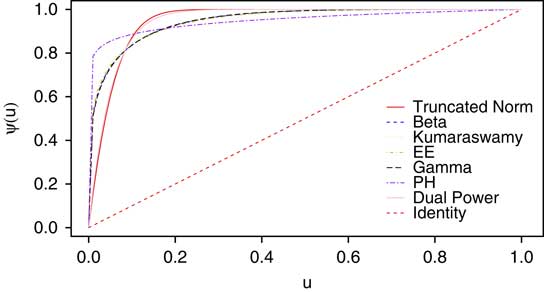
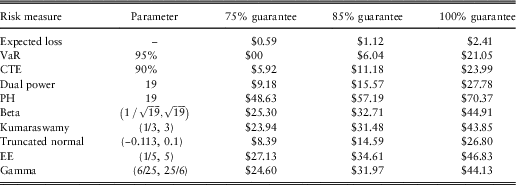
We are interested in comparing the risk measures using existing and proposed approaches so the results in Wirch and Hardy (Reference Wirch and Hardy1999) were reproduced and reported in Table 2. The parameters of the distortion functions were selected such that they give the same risk measure of 0.95 for a uniform loss distribution on [0, 1]. When there are two parameters in the distortion function, one parameter is set to be the reciprocal of the other. Figure 7 is a plot of the distortion functions chosen based on the above criteria.
The distortion functions of uniform loss distributions with a risk measure of 0.95. EE, exponentiated exponential; PH, proportional hazard.

When the initial gradients of the distortion functions are large, that corresponds to loading more weight towards the far right tail of the loss distribution. In addition, the distortion functions that converge faster than others assign more weight to moderate as well as extremely large losses. Therefore, focussing on the shape of distortion functions based on the changes in the parameters of the distortion function is crucial in risk management.
Based on Table 2, a larger guarantee level carries more risk to the insurer, hence the risk measure increases as the guarantee level increases. The coherent risk measures such as beta, Kumaraswamy, EE and gamma have only slight differences for each guarantee level. They are relatively moderate compared to PH distortion risk measure. For the selected parameters, the truncated normal and dual-power transforms generate smaller risk measures than other distortions.
Risk measures for segregated fund guarantees.

Note: VaR, value at risk; CTE, conditional tail expectation; PH, proportional hazard; EE, exponentiated exponential.
7. Concluding Remarks
This paper uses the framework in (4) that has been employed to generate various distributions to develop new families of distortion functionals. Instead of a beta generating pdf as in (2), we first propose to use a Kumaraswamy or a truncated normal pdf. We then study the case when w (u)=−ln(1 − u) with an EE or a gamma pdf as the generating pdf. Both Kumaraswamy and composite EE distortions have closed forms that can be readily employed, and include PH and dual-power transforms as their special cases. To ensure coherent risk measures, we derive the domains of parameter spaces in which the distortion functions are concave. The effects of parameter values on distortion risk measures and risk attitudes are examined through graphs and closed-form expressions for the risk measures or numerical calculations via computer programming.
Note again that the proposed distortion risk measures can be interpreted as the mean of a random variable Y=S −1(V), where V has a beta or Kumaraswamy distribution, or the mean of Y=S −1(1 − e −V ), where V has an EE distribution or a gamma distribution. Though not reported, simulations of random numbers for Y were run to check if the formulas and numerical integrations for computing risk measures are correctly derived. The inverse transformation method was used to generate Y. It is also possible to follow the tedious methods in Castellares et al. (Reference Castellares, Montenegro and Cordeiro2013), involving multiple sums of infinite series, to work out closed-form expressions for the mean of Y.
If the loss distribution is unknown, the risk measure can be estimated via L-statistics. In particular, the empirical estimator of the risk measure is given by
 $\hat{\rho }_{X} {\equals}\mathop{\sum}\limits_{m{\equals}1}^n {c_{{mn}} X_{{m\,\colon\,n}} } $
where X
m:n
is the mth order statistics of a random sample of size n and
 $c_{{mn}} {\equals}{\int}_{(m{\minus}1)\,/\,n}^{m\,/\,n} {\psi \prime(1{\minus}t) dt} {\equals}\psi (1{\minus}(m{\minus}1)\,/\,n){\minus}\psi (1{\minus}m\,/\,n)$
; see Tsukahara (Reference Tsukahara2014) for more details. Kaiser and Brazauskas (Reference Kaiser and Brazauskas2006) also investigate methodologies for the constructions of confidence intervals for various risk measures. They consider risk measures with one parameter: VaR, CTE, PH and Wang. The estimation of the proposed distortion risk measures with two parameters in this paper needs to be further studied.
A natural question that arises is the choice of an adequate distortion or a risk measure. The answer to this question is not obvious since there is no clear way to compare the proposed distortions partly due to the flexibility induced by the parameters, although it is possible to calibrate the parameter values in a distortion function to reflect a decision-maker’s risk attitude. Goovaerts et al. (Reference Goovaerts, Kaas, Dhaene and Tang2004) suggest that insurance premium principles or risk measures should be selected so that they satisfy certain properties or axioms such as monotonicity, subadditivity, positive homogeneity and translation invariance to reflect the realities of practices. Belles-Sampera et al. (Reference Belles-Sampera, Guillen and Santolino2016) use the area under the distortion function to quantify the global risk attitude, with decision-makers classifies as risk tolerant, risk neutral or risk intolerant if the corresponding areas are more than half, half and less than half, respectively. The proposed coherent distortions lead to risk measures satisfying the four coherency axioms. They are concave on [0, 1] and therefore, reflect a risk tolerant attitude.
In addition to the choice of g(⋅), one may also use different w(⋅) functions. For example, let g(t) be the density function of a normal distribution with a mean of θ and a s.d. of 1 and w(u)=Φ−1(u), then (4) is
 $${\rm \Phi }\left( {{\rm \Phi }^{{{\minus}1}} (u){\minus}\theta } \right){\equals}{\int}_{{\minus}\infty}^{{\rm \Phi }^{{{\minus}1}} (u)} {g(t)dt} $$
which gives Wang’s transform. To generalise this idea, w(⋅) can be well-defined quantile functions. We will further investigate this, in a way, a different kind of quantile-based class of distortion functions, in a future paper.
Finally, we would like to mention that the multi-parameter classes of distributions generated by the framework (4) are of great flexibility. One may employ them to fit loss data. Commonly used loss distributions such as Pareto and Gumbel distributions are special cases of the rich classes of distributions. They can be applied to fit unimodal, multi-modal or heavy-tailed data with the help of extra parameters. While there are often no simple or attractive closed-form expressions for means, standard deviations and maximum likelihood estimates, Nadarajah and Rocha (Reference Nadarajah and Rocha2016) explain how one can use an R Package for estimations of the parameters for these rich families of distributions.
Acknowledgements
The authors thank two anonymous referees for careful reading and the useful comments and suggestions, which are all valuable for revising and improving the paper.