Introduction
According to the bounded rationality hypothesis (Simon, Reference Simon1955), evolutionary economics emphasizes that firms, when making decisions, do not know every possible outcome because of future uncertainty (Nelson & Winter, Reference Nelson and Winter1982). Firms pursue profits but cannot establish perfect rules and processes because of uncertainties in the economic environment. They can make decisions only by following simple preformed routines that are not necessarily perfectly appropriate for present or future situations and changes. Hence, in uncertain environments, firms seek satisfactory solutions instead of optimal solutions derived through continual trial and error.
Adopting the notion of evolution from biology, evolutionary economists consider routines to be the ‘genes’ of firms (Nelson & Winter, Reference Nelson and Winter1982). They have proposed the concept of ‘organizational routines,’ attributing the durable differences between firms to the various genetic combinations among individual firms. Nelson and Winter (Reference Nelson and Winter1982) asserted that organizational routines are analogous to personal habits: Similar to how genes guide people without the need for conscious decisions, the execution of routines is automatic, programmed to instruct firms on how to react when encountering similar contingencies. Because personal habits are formed from experience and learning, Argote (Reference Argote2013) stated that organizational routines result from organizational learning. Forming and changes in organizational routines reflect the history of organizational learning (Nelson & Winter, Reference Nelson and Winter1982; Levitt & March, Reference Levitt and March1988). Current organizational routines are thus the result of identifying previous mistakes and improving efficiency and will endure for a long time.
Previous studies have applied this evolutionary concept only to explain how distinct routines among firms result in distinct outcomes (Nelson & Winter, Reference Nelson and Winter1982; Levitt & March, Reference Levitt and March1988; Argote, Reference Argote2013; Frigotto & Zamarian, Reference Frigotto and Zamarian2015). However, because the routines of firms are undefined, explaining the types of routines that firms possess is difficult. Moreover, whether routines are inherited and whether firms establish the routines of affiliates according to routines inherited from parent firms remains unclear. On the basis of the biological concept of genetic characteristics, we attempted to apply accounting information to evolutionary economics.
In biology, physical characteristics originate from the protein expressed by genes, which influence the structure and function of organisms, producing visible characteristics related to an organism’s appearance and physical abilities. Regarding firms, number of documented organizational information is relevant to business operations. The information is eventually transferred to the accounting office, which in turn, presents the information to managers, investors, or creditors in the form of financial statements. Based on this information, management makes business decisions, and investors or creditors make decisions regarding investments or credit extensions. The accounting information of a firm exhibits characteristics resulting from the execution of routines; therefore, such information is similar to the characteristics of organisms that are affected by genes. For example, a long-term high-liability ratio within a financial structure indicates that a company possesses routines for high financial-leverage operations. Similarly, a high inventory turnover indicates that a company possesses routines that are advantageous to inventory processing. Hence, the accounting information contains biological information that influences decisions and results from organizational routines.
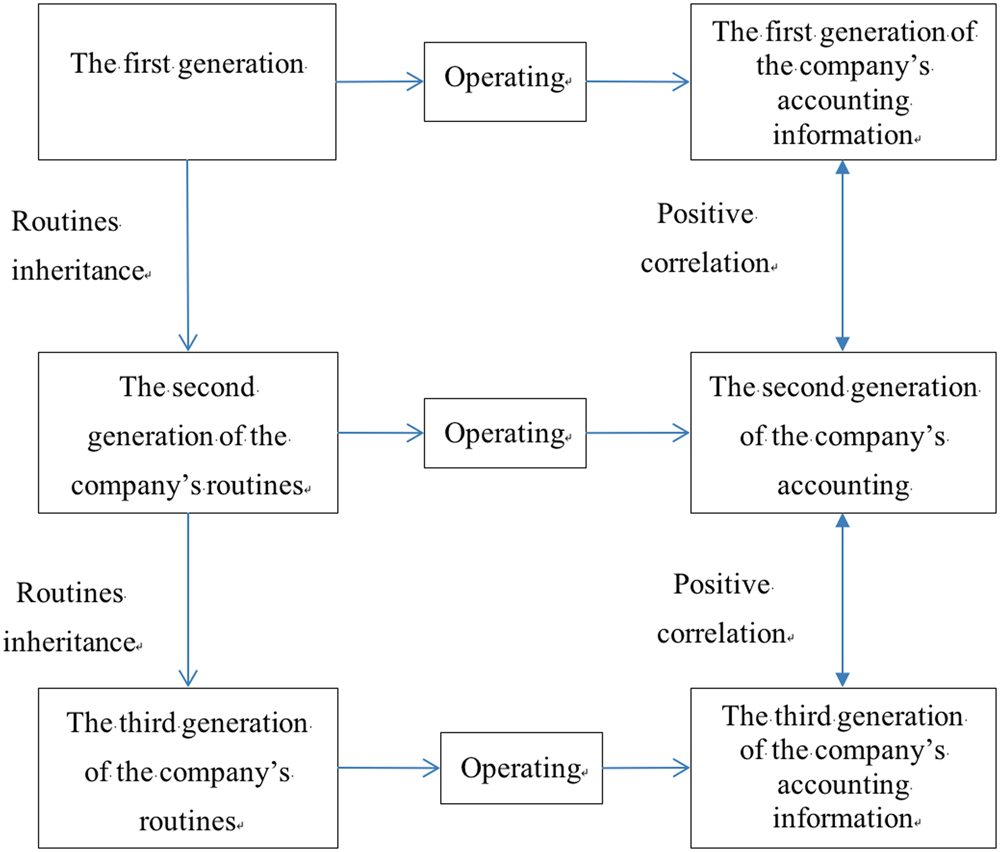
Although previous studies on accounting have focused on how to predict the future performance of a company by examining the accounting information (Beaver, Reference Beaver1966; Altman, Reference Altman1968; Ohlson, Reference Ohlson1980; Taffler, Reference Taffler1982; Wilson & Sharda, Reference Wilson and Sharda1994; Holsapple & Wu, Reference Holsapple and Wu2011; Olson, Delen, & Meng, Reference Olson, Delen and Meng2012; Nguyen & Nguyen, Reference Nguyen and Nguyen2015), few studies have investigated the routines that guide the decisions behind accounting information. Accounting information does not lead to company success or failure, but is the result of executing organizational routines and strategies. Thus, on the basis of the biological characteristics of accounting information, this study explored whether the routines (decisions) adopted by the current generation of firms are influenced by those of preceding generations (Figure 1). In other words, we explored whether a current generation of a firm’s routines is inherited from its preceding generation.
Conceptual framework.

The study results revealed that the financial structure, debt-paying ability, earnings power, and cash flow control of parent companies have significant impacts on the ratios of their subsidiaries. According to the analysis, the subsidiaries inherited routines from the parent companies related to financing tendency, risk preference, earnings power, and level of cash flow, so we suggest that people should judge the adequacy of a firm’s financial situation by not only referring to the standard of its industry but also to its parent company.
Group businesses play crucial roles in the Chinese societies economies that include China, Hong Kong, and Taiwan. According to the research of China Credit Information Inc. (2014), the total sales of the top 100 Taiwan group businesses in 2013 were ~100 billion dollars. The situations in other Chinese societies are similar to those in Taiwan. The value of group businesses accounted for 60% of the total value of the entire Chinese industry (Editorial Committee of China Economic Yearbook, 2000). Many of the richest Hong Kong people listed in the 2015 Forbes magazine are leaders of group businesses, which includes the Cheung Kong (Holdings) Limited, Henderson Land Development Company, New World Development Limited, and Li and Fung Limited, etc. So, the results of this study may have important implication for most of the Chinese societies.
Literature review
We organized the related literature in four parts. In Part 1, we will introduce the definition and function of the organizational routines. Part 2 will focus on the discussion about the forming, transferring, and inheritance of the organizational routines. We collate some research about the accounting information and financial ratio analysis in Part 3. Inferring from the discussions in the above three parts, we propose some hypothesis about the impact of routines inheritance on the subsidiaries financial ratio.
Routines in evolutionary economics
A routine is a ‘prescribed, detailed course of action to be followed regularly.’ Routines are core characteristics of firms, and each firm operates by applying unique routines in decision-making.
In the past decades, numerous studies have focused on the importance of routines (March & Simon, Reference March and Simon1958; Nelson & Winter, Reference Nelson and Winter1982; Levitt & March, Reference Levitt and March1988; Gersick & Hackman, Reference Gersick and Hackman1990; Teece, Pisano, & Shuen, Reference Teece, Pisano and Shuen1997); however, progress has been limited. Cohen and Bacdayan (Reference Cohen and Bacdayan1994) asserted that the difficulties in studying organizational routines are caused by their multifactor, emergent quality, and inarticulate components.
Organizational routines are regular behaviors restricted by rules and habits, observed repeatedly in an organization, that are characteristic of typical organizational activities (Nelson & Winter, Reference Nelson and Winter1982; Edmondson, Bohmer, & Pisano, Reference Edmondson, Bohmer and Pisano2001). Gersick and Hackman (Reference Gersick and Hackman1990) defined organizational routines as behavioral regularities with similar functions, causing custom behavioral regularities for particular circumstances that do not require selecting an appropriate behavioral model from other possibilities. Cohen et al. defined a routine as ‘an executable capability for repeated performance in some context that has been learned by an organization in response to selective pressures’ (Reference Cohen, Burkhart, Dosi, Egidi, Marengo, Warglien and Winter1996: 683). Feldman and Pentland defined an organizational routine as ‘a repetitive, recognizable pattern of interdependent actions carried out by multiple actors’ (Reference Feldman and Pentland2003: 105). According to these definitions, an organizational routine contains the following four characteristics: (a) repetition, (b) recognizable patterns of action, (c) multiple participants, and (d) interdependent actions. Because organizational routines are regular and repetitive, routinization affects the financial performance of firms through daily decision-making regarding necessary tasks and how to perform them. Individual employees can manage daily tasks by referring to the routines of the firm without thinking thoroughly before acting. Firms with routines can subtly integrate each professionalized department that resulted from a division of labor into a whole to promote efficiency.
Organizational routines, similar to other social phenomena, constitute a multidimensional concept: an agent that has specific participants performing actions at a specific time and place, and its structure, which combines all of the organizational routines. Feldman and Pentland (Reference Feldman and Pentland2003) divided routines into ostensive and performative routines. Ostensive aspects refer to the constructs and principles related to organizational routines, such as policies, rules, standard operational procedures, consensuses, and established norms, that can involve codified or tacit components. Ostensive aspects are only in principle; thus, they cannot involve all contingencies and details of each operation. Although rules are established to guide action, they cannot guide all actions. Performative aspects refer to specific actions performed at specific times and places by certain people engaged in an organizational routine. In certain circumstances, improvisational performances occur inevitably when routines are combined with various interrelated situations. For example, in a musical performance (the performative aspect), even though music scores (i.e., musical notation, the ostensive aspect) are used, the style and atmosphere vary according to the situation and performers.
Organizational routines can act as positive functions for organizations. March and Simon (Reference March and Simon1958) proposed that positive functions include reducing organizational complexity and organizational uncertainty, and increasing organizational efficiency. Hannan and Freeman (Reference Hannan and Freeman1984) asserted that organizational routines increase the legitimacy of organizations. Some scholars have maintained that organizational routines enable accumulating organizational knowledge and skills (Nelson & Winter, Reference Nelson and Winter1982; Levitt & March, Reference Levitt and March1988; Argote, Reference Argote2013; Frigotto & Zamarian, Reference Frigotto and Zamarian2015).
However, routinization involves numerous problems because it inevitably causes rigidity within firms. Hannan and Freeman (Reference Hannan and Freeman1984) purported that organizational routines are the primary source of organizational inertia, causing organizational rigidity. Ashforth and Fried (Reference Ashforth and Fried1988) argued that organizational routines cause mindlessness among organizational members. Leidner (Reference Leidner1993) claimed that organizational routines lead to deskilling and demotivation for organizational members. March (Reference March1991) concluded that organizational routines cause organizations to become complacent. When inappropriate routines continue, the damage to firms increases. Routines executed in the wrong place and at the wrong time may negate performance.
Because the routines have both the advantageous and disadvantageous to the organization, the ability to improve routines rapidly, alter them appropriately, and select the most appropriate among existing routines might be considered the primary source of competitive advantage. Moreover, this ability reflects the characteristics of successful firms (Teece, Pisano, & Shuen, Reference Teece, Pisano and Shuen1997).
Argote (Reference Argote2013) stated that organizational routines result from organizational learning. Changes in organizational regulatory systems, such as establishing new rules or revising old rules, reflect the history of organizational learning (Nelson & Winter, Reference Nelson and Winter1982; Levitt & March, Reference Levitt and March1988). Current organizational routines are thus the result of identifying previous mistakes and improving efficiency.
Inheriting organizational routines
Organizational learning: Forming routines
Levitt and March (Reference Levitt and March1988) stated that organizational learning is viewed as routine-based, history-dependent, and target-oriented. Organizations are seen as learning by encoding inferences from history into routines that guide behavior. According to this definition, routines constitute forms, rules, conventions, strategies, and technologies, as well as belief structures, frameworks, paradigms, codes, cultures, and knowledge related to routines. However, this definition excludes the performative aspect, which they considered independent of the individual actors who execute them and capable of surviving considerable turnover in individual actors. Therefore, the performative aspect involves a characteristically static perspective. In contrast, Feldman and Pentland (Reference Feldman and Pentland2003) analyzed organizational routines from a long-term dynamic perspective and included behavior as a dimension of routines. Hence, the present study adopted the position of Feldman and Pentland (Reference Feldman and Pentland2003) regarding continuity, defining organizational learning as a formative and evolutionary process of organizational routines.
Fiol and Lyles (Reference Fiol and Lyles1985) argued that organizational learning is not the sum of individual learning. The paradox of organizational learning is that organizational members are required to learn; however, the knowledge possessed by an organization is not the total sum of the knowledge of all organizational members (Lipshitz & Popper, Reference Lipshitz and Popper2000). Argyris and Schon (Reference Argyris and Schon1996) stated that when organizational members perform their tasks (according to the roles assigned by the organization) and learn that the results differ from their expectations, they correct their understanding and behaviors through inquiry, thereby aligning the results with their expectations. Thus, this imprints the changes resulting from personal inquiry by means of mind maps, memories, and plans, forming organizational learning and routines.
Organizational routines have been likened to memories of organizational knowledge (Nelson & Winter, Reference Nelson and Winter1982; Olivera, Reference Olivera2000; Argote, Reference Argote2013). Accumulated knowledge from all organizational routines (i.e., the so-called stock of knowledge that exists in an organization) is known as intellectual capital. The difference between the stock of knowledge at two specific points of time, either increasing or decreasing, represents the flow of knowledge that is referred to as organizational learning (Bontis, Crossan, & Hulland, Reference Bontis, Crossan and Hulland2002). >From the perspective of certain organizational routines, the process of forming and altering an organizational routine between two points of time, changing the knowledge accumulated by that routine, is called organizational learning. This definition clearly distinguishes intellectual capital from organizational learning.
Crossan, Lane, and White (Reference Crossan, Lane and White1999) explained the process of forming new organizational strategies by referring to intuition, interpretation, integration, and systemization. From the perspective of forming an organizational routine (particularly the ostensive aspects of organizational routines), establishing a consensus of job division and coordination must involve a feed-forward process that includes intuition, interpretation, integration, and systemization. After establishing the ostensive aspect of organizational routines, the process of executing organizational routine is realized through feedback, which guides performers on how to follow rules. When the results match the expectations, stabilization is achieved and organizational routines are formed. Hence, establishing and changing the ostensive aspect of organizational routines involves creating new organizational knowledge. Executing the ostensive aspect of organizational routines refers to disseminating new organizational knowledge, and forming new organizational routines is the process of memory-saving for new organizational knowledge. Therefore, this study emphasized that the process of forming organizational routines is the process of organizational learning.
Organizational knowledge transfer: Routines inheritance
Organizations establish routines through learning. Whether these routines can be inherited similarly to biological genes, or specifically, whether organizational knowledge can be transferred to a newly established organization, remains unclear. Singley and Anderson (Reference Singley and Anderson1989) defined knowledge transfer as the application of knowledge acquired from one situation to another. Knowledge transfer can occur between people within organizations, between people and groups, between groups, and between organizations. The present study proposes that through inherited routines, knowledge can be transferred between established and new organizations.
Badaracco (Reference Badaracco1991) asserted that alliance management is a process of learning, creating, sharing, and controlling knowledge. Organizations combine migratory knowledge (learned from outside) and embedded knowledge (generated from the mixed combined of the other knowledge already rooted in an organization). To understand how to manage alliances, factors for encouraging and stopping acquiring, transferring, and creating embedded knowledge must be determined. Case studies on alliances such as General Electric and International Business Machines have shown that nine factors, including trust, openness, and leadership, can accelerate knowledge trade inside an alliance. Simonin (Reference Simonin1999) indicated that the causal ambiguity of knowledge influences knowledge transfer in strategic alliances, and that tacit and complex knowledge, previous experience, cultural difference, and organizational difference exert a positive effect on causal ambiguity, but a negative influence at the technological knowledge transfer level.
Gupta and Govindarajan (Reference Gupta and Govindarajan2003) proposed a theoretical framework for knowledge transfer between foreign subsidiaries of multinational corporations, determining that the volume of knowledge stock and transfer methods of subsidiary companies positively influences knowledge outflows. Furthermore, the number of transfer methods, motivational predisposition in the acquired knowledge, and capability of absorbing foreign knowledge all exert a positive influence on the knowledge inflow of subsidiary companies. Martin and Salomon (Reference Martin and Salomon2003) also found that knowledge transfer capability influences the transfer cost of tacit knowledge. Castro-Casal, Neira-Fontela, and Álvarez-Pérez (Reference Castro-Casal, Neira-Fontela and Álvarez-Pérez2013) indicated that the more the embedded knowledge is, the greater the impact of the acquired firm’s high-value human resources retention on the knowledge transfer.
Williamson (Reference Williamson1981) contended that most markets for knowledge have failed or do not exist because of measuring and leaking problems that incur high transaction costs. A measuring problem occurs when the buyer’s insufficient knowledge renders him or her unable to determine whether the value of the involved knowledge is reasonable. However, a leaking problem occurs when the seller attempts to convince the buyer that the value of the knowledge is reasonable by disclosing all the detailed information about it; being thus informed, the buyer no longer needs to buy the knowledge. Moreover, asymmetric information, opportunistic behavior, and uncertainty render an even higher transaction cost when market price mechanisms are used to trade knowledge.
To apply acquired knowledge efficiently, internal and external details must be continually refined, and learning-by-doing may be the most effective approach for knowledge transfer. Technicians, regardless of their proficiency, might not be able to accurately describe the skills required in an operational environment; thus, a mentor and apprentice system is an effective approach when teaching others how to apply complex production technologies. Moreover, daily contact between members within the organization is an optimal approach for acquiring complex knowledge that cannot be learned through document reading. Because of these requirements for efficient knowledge transfer, in addition to the high transaction cost in using the market, the hierarchy might be the most appropriate mechanism for knowledge transfer.
According to the literature discussion, we conclude that organizational knowledge is embodied in a system of routines, and learning from an associated company is an efficient approach through which a new venture can establish routines. Accordingly, we propose that subsidiary companies inherit routines from their parent and associate companies, as detailed in the following.
Accounting information and firm performance
The American Accounting Association defined accounting as the process of identifying, measuring, and communicating economic information to enable informed judgments and decisions by people who use such information. The American Institute of Certified Public Accountants defined accounting as the art of recording, classifying, and summarizing in a notable manner and in terms of money, transactions, and events that are, in part at least, of financial character, and interpreting the results thereof.
Ball and Brown (Reference Ball and Brown1968) indicated that changes in a firm’s accounting earnings are highly related to its stock value. Subsequent studies on accounting have also revealed that accounting numbers or financial ratios contain information related to business execution (Beaver, Reference Beaver1966; Altman, Reference Altman1968; Ohlson, Reference Ohlson1980; Taffler, Reference Taffler1982; Wilson & Sharda, Reference Wilson and Sharda1994; Holsapple & Wu, Reference Holsapple and Wu2011; Olson, Delen, & Meng, Reference Olson, Delen and Meng2012; Nguyen & Nguyen, Reference Nguyen and Nguyen2015), which can serve as a reference for investors. Among various types of accounting information, financial ratios are typically used to assist the management in understanding the current financial and operating status of an organization (Trotman, Tan, & Ang, Reference Trotman, Tan and Ang2011). Beaver (Reference Beaver1966) was the first to show that financial ratios have explanatory power for signaling financial warnings. Through empirical studies on the 5 years preceding the bankruptcy of companies, he found six specific financial ratios that exhibit significant explanatory power for predicting bankruptcy, verifying that accounting information can predict the final outcomes of company management practices.
Lin, Liang, and Chen (Reference Lin, Liang and Chen2011) used financial ratios to construct a model to forecast business crisis of the Taiwan public listed companies. They found that they must add two financial features, tax rate and four-quarterly earnings per share (EPS), into the models proposed by previous research (Beaver, Reference Beaver1966; Altman, Reference Altman1968; Ohlson, Reference Ohlson1980) to improve the model accuracy. This study thinks there are two problems in Lin’s model. First, the tax rate is an exogenous variable that could not be influenced by the firm’s decision. Second, there will be a tautological fallacy when applying outcome (EPS) to predict outcome (crisis). This study proposes that the reason why the low predicting power of the previous models in forecasting Taiwan business crisis might be that there are too many parent–subsidiary relationships between Taiwan public listed companies.
Accounting information embodying organizational routines
Evolution in organisms occurs through changes in hereditary traits, which are the particular characteristics of an organism. In humans, for example, eye color is an inherited characteristic (Sturm & Frudakis, Reference Sturm and Frudakis2004). In organizations, accounting information also contains biological characteristics.
As required by the Financial Supervisory Commission, listed companies and public companies must declare their financial ratios regarding financial structure, debt-paying ability, operating ability, earnings power, and cash flow.
Financial structure involves debt ratio and long-term capital ratio. Debt ratio indicates the ratio of external capital to the total capital of an organization. Long-term capital ratio is the ratio of the amount of fixed assets to the total assets of an organization. These two ratios reflect the financial health of organizations and the preference of the organizational decision-makers on financial leverage. A high ratio of external capital implies that the management prefers to use less equity money to operate a large business. Although a low fixed assets ratio partly reflects industry characteristics, partly because of the management’s risk-averse tendency will not be highly committed to operating the business. Both of these ratios reflect routines that guide financial decision-makers when applying for financing. Hence, for financing-related preferences or routines of subsidiary companies that are inherited from parent companies, we propose the following hypothesis:
Hypothesis 1: The financial structure ratios of a parent company have positive impacts on those of its subsidiary companies.
Among the various financial ratios, the current ratio, quick ratio, and interest protection multiples are crucial for organizational solvency. These ratios reflect the short-term debt-paying ability of organizations and represent the safety degree of short-term creditor rights, as well as the routines affecting how organizations use working capital. The higher these ratios, the safer it is for creditors. However, from an operational perspective, when these ratios are higher, the firm asset turnover and financial leverage will be lower, and the idle fund will be higher. Therefore, these ratios reflect the attitude or tendency of the management in tradeoffs between fully using capital and protecting creditors. This attitude or tendency is embodied in the routines of the organization. Hence, we propose the following hypothesis:
Hypothesis 2: The debt-paying ability of a parent company has a positive impact on those of its subsidiary companies.
Organizational operating ability reflects management performance in using resources (i.e., assets) to achieve objectives. Indicators of whether the management uses current and fixed assets effectively include the turnover ratios of the account receivables, fixed assets, inventory, and total assets. The higher these ratios are, the more efficient the asset usage is. For example, the account receivables turnover ratio represents an organization’s receivables policies, managerial decisions regarding terms and conditions, and receivable control. Adequate receivable control can minimize default risk. Inventory turnover represents an organization’s decisions regarding inventory control, such as the just in time strategy employed by Toyota, which represents the zero inventories policy of the company. Although the relative bargaining power of the suppliers may dictate the degree of achievement of the zero-inventory policy, the willingness to exert this power is influenced by the attitude of the management. Both fixed assets and the total asset turnover ratio represent organizational policies related to asset usage. Hence, regarding these policies or attitudes (routines) in a subsidiary company inherited from a parent company, we propose the following hypothesis:
Hypothesis 3: The operating ability of a parent company has a positive impact on those of its subsidiary companies.
A company’s earnings power depends on whether it can create sufficient profit to attract more capital from investors. When analyzing earnings power, investors can observe a company’s return on assets, return on equity, net profit margin, and earnings per share. A company with substantial earnings power is evaluated highly. Return on assets is applied to analyze the return ratio of a company’s ability to produce profit by using assets. The net profit ratio indicates a company’s ability to produce net profit (or net loss) from its revenue and reflects the earnings power and cost control effectiveness of the company. A company with a high net profit ratio has substantial earnings power and cost control. However, no absolute appropriate value exists for these indicators. In practice, these indicators must be compared with those of similar companies to evaluate the earnings power of a company. However, when a company belongs to a group company, these ratios should conform to the management expectation of the parent company. Hence, for the decisions regarding earnings power of subsidiary companies influenced by the parent company, we propose the following hypothesis:
Hypothesis 4: The earnings power of a parent company has a positive impact on that of its subsidiary companies.
A cash flow statement is one of four major financial statements and provides cash flow information regarding operating, investment, and cash management of a company within a specific period. This statement can be used to calculate the cash flow ratio, cash flow adequacy ratio, and cash reinvestment ratio. The cash flow ratio reflects a company’s ability to pay debts in cash, and the cash flow adequacy ratio indicates the ability to pay punctually. Both of these ratios are influenced by the management’s risk tendency. The cash reinvestment ratio reflects a company’s ability to satisfy the requirement for assets replacement and business growth. Typically, this ratio reflects company policies regarding assets usage and earnings ability. As previously mentioned, both subsidiary management tendencies and asset management policies are influenced by the parent company. Hence, we propose the following hypothesis:
Hypothesis 5: The cash flow situation of a parent company has a positive impact on those of its subsidiary companies.
Methodology
Research sample
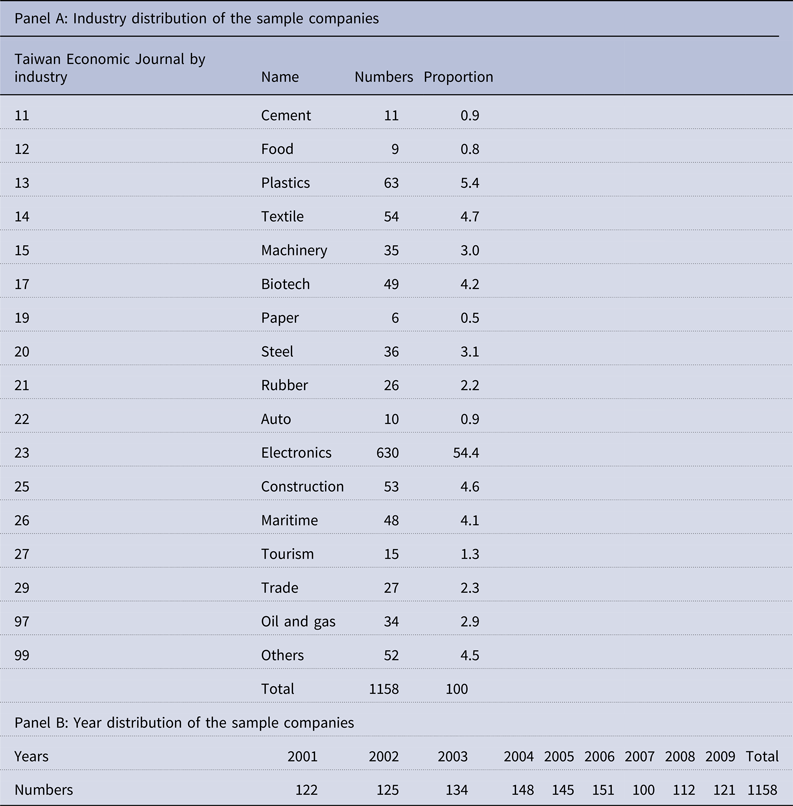
This study focused on the group businesses in Taiwan. Companies listed in the Taiwan Securities Market belonging to a group company were selected as our research subjects and from 2001 to 2009 Taiwan Economic Journal. All these companies are registered and located in Taiwan. The birth order of the subsidiary companies was determined according to the chronological order in which the companies were listed. The first-born firms were considered first-generation companies, the second-born firms were considered second-generation companies, and so forth.
This study was conducted to identify the routines inheritance of firms by analyzing whether the financial variables of the previous generation affected subsequent generations. The first-listed company was designated the parent company and the second-listed company was designated its subsidiary. Similarly, the second-listed company was considered the parent company of the third-listed company, its subsidiary. All subsidiary companies were selected as the research sample. Although some companies appeared multiple times in the sample, all sampled companies were pooled for analysis. All the sampled companies are treated as independent legal units by banks and financial institutions, because their lines of credit are independent of each other; hence, there is no serious contagion effect in our sample. The financial variables of the sample companies were collected from the Taiwan Economic Journal archives. Banking and insurance firms were excluded from this study because of their unique characteristics. A total of 1,158 listed and over-the-counter companies were identified. Table 1 shows the date the sampled companies were established. The industry distribution of the sampled companies is approximated to the distribution of the population companies listed in the Taiwan Securities Market.
The sample’s year of establishment

Empirical models and variable measures
The following multiple regression model was used:
 $$\eqalignno{ {\rm ID1}_{{{\rm it}}} {=}{\rm \beta }_{{\rm 0}} {+}{\rm \beta }_{{\rm 1}} {\rm ID2}_{{{\rm it}}} {+}{\rm \beta }_{{\rm 2}} {\rm CEOFAMILY}_{{{\rm it}}} {+}{\rm \beta }_{{\rm 3}} {\rm OWN}_{{{\rm it}}} {+}{\rm \beta }_{{\rm 4}} {\rm DEV}_{{{\rm it}}} {+}{\rm \beta }_{{\rm 5}} {\rm NOB}_{{{\rm it}}} \cr \unicode{x0026} \hskip -260pt {+}{\rm \beta }_{{\rm 6}} {\rm NCH}_{{{\rm it}}} {+}{\rm \beta }_{{\rm 7}} {\rm CPA}_{{{\rm it}}} {+}{\rm \beta }_{{\rm 8}} {\rm IND}_{{{\rm it}}} {+}{\rm {\epsilon}}_{{{\rm it}}} , $$
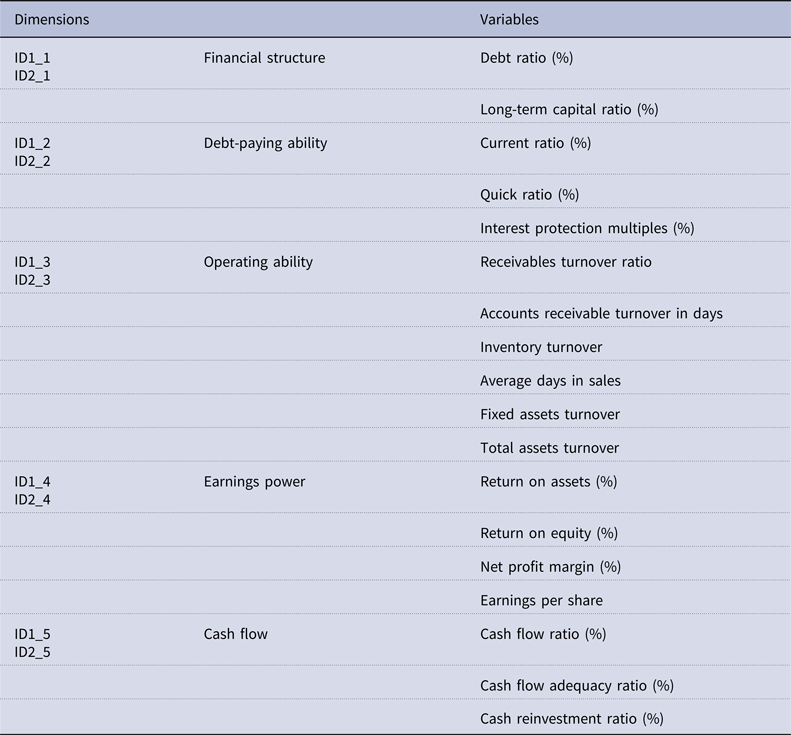
where ID1 is the financial variable of the subsidiary company, and ID2 the financial variable of the parent company. If a routine effect exists in a group firm, the financial variable of the subsidiary company is influenced by the financial variable of the parent company, and β1 is expected to be positive. The following five financial variables were adopted (the indicators for these variables are shown in parentheses): (a) financial structure (debt ratio and long-term capital ratio); (b) debt-paying ability (current ratio, quick ratio, and interest protection multiples); (c) operating ability (receivables turnover ratio, accounts receivable turnover in days, inventory turnover, average days in sales, fixed assets turnover, and total assets turnover); (d) earnings power (return on assets, return on equity, net profit margin, and earnings per share); and (e) cash flow (cash flow ratio, cash flow adequacy ratio, and cash reinvestment ratio).
Table 2 shows how these financial ratios are calculated. Through a factor analysis approach, the financial ratios of the same category were deduced to the same factor. A regression analysis was subsequently performed using the factor scores generated from the factor analysis as new variables. The financial variable of the subsidiary companies was denoted as ID1. The five categories of the financial variables (financial structure, debt-paying ability, operating ability, earnings power, and cash flow) were represented as ID1_1, ID1_2, ID1_3, ID1_4, and ID1_5, respectively. Similarly, the financial variable of the parent companies was denoted as ID2, and the five categories were represented as ID2_1, ID2_2, ID2_3, ID2_4, and ID2_5, respectively.
Financial variables

To control subsidiary companies, parent companies typically appoint staff from parent companies to key positions in subsidiary companies (e.g., president, chief executive officer, or senior manager). These appointments influence the management decisions of subsidiary companies (La Porta, Florencio, & Shleifer, Reference La Porta, Florencio and Shleifer1999).
This study used CEOFAMILY, a dummy variable, to indicate whether the chief executive officer of a subsidiary was appointed by its parent firm. The value was set to 1 when the chief executive officer was appointed by the parent firm; otherwise, it was set to 0. Furthermore, the shareholding proportion (ownership), right of control, and cash flow rights of subsidiary companies that parent companies have influences the effect of the parent company on the subsidiary companies (Baysinger & Hoskisson, Reference Baysinger and Hoskisson1990). The OWN variable represents the ownership proportion of the parent company. This variable was measured according to the parent company’s shareholding proportion of the subsidiary company. By referring to Claessens, Djankov, and Lang (Reference Claessens, Djankov and Lang2000), the present study used the DEV to measure the degree of the agency problem. The DEV variable represents the deviation of the control right and cash flow right of the controlling shareholders, and was measured by subtracting the cash flow right from the parent company’s control right. For example, when Company A holds 60% of the shareholding of Company B, and Company B holds 40% of the shareholding of Company C, the control right of Company A in C is 40% (the minimum percentage in this holding chain), but the cash flow right of A in C is 24% (60%×40%); thus, the DEV is 16%. To prevent bias generated from industry effect on the accounting information, industry type, which was considered a critical factor influencing the financial variables, was also controlled for. Hence, the IND variable was used to indicate whether the parent company and subsidiary company operated in the same industry. The value was set to 1 when they operated in the same industry; otherwise, it was set to 0. Because the composition of board members may have an impact on the company’s major decisions, we control the possible influence by adding two percentages of the outside member (NOB) and the member assigned by the controlling shareholder (NCH) to our model. Furthermore, subsidiaries’ hiring the CPA independent of their parent companies might alleviate the problem of the parents’ manipulating accounting information (Jones, Reference Jones1991). The control variable CPA was set to 1 when the subsidiary had an independent CPA; otherwise, it was set to 0.
Results
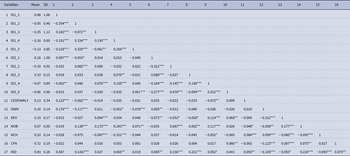
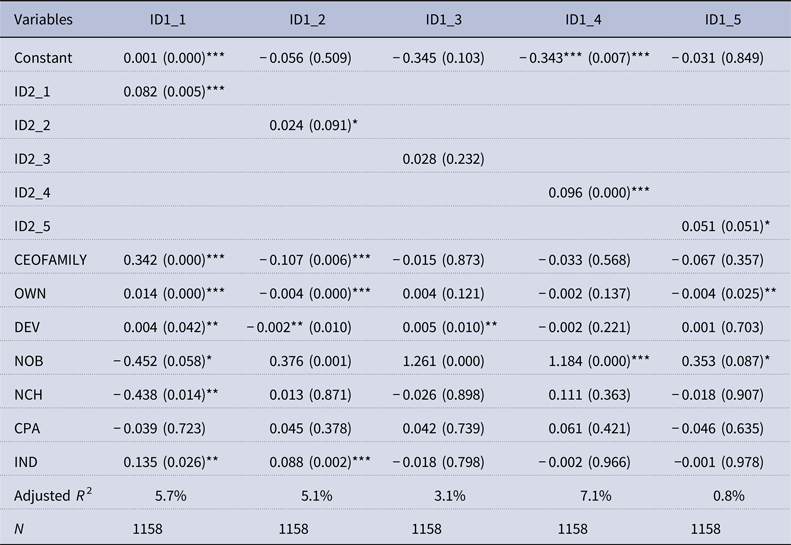
The descriptive statistics and correlations of this study were showed in Table 3. Table 4 presents the results of the regression analysis performed on the five financial variables categories for both the parent and subsidiary companies. The first regression shows that the coefficient of the parent company financial structure (ID2_1) was positively significant, implying that the subsidiary’s operating decisions (routines) regarding the financial structure were influenced by the parent company; thus, Hypothesis 1 was supported. The second regression revealed that the coefficient of the parent company debt-paying ability (ID2_2) was positively significant, indicating that the subsidiary’s operating decisions regarding debt-paying ability were also influenced by the parent company; thus, Hypothesis 2 was supported. The third regression revealed that the coefficient of the parent company operating ability (ID2_3) was positive but nonsignificant, implying that the subsidiary operating decisions regarding operating ability were not influenced by the parent company; thus, Hypothesis 3 was not supported. The fourth regression revealed that the coefficient of the parent company earnings power (ID2_4) was significantly positive, implying that the subsidiary’s operating decisions regarding earnings power were influenced by the parent company; thus, Hypothesis 4 was supported. All control variables were nonsignificant. The fifth regression revealed that the coefficient of the parent company cash flow (ID2_5) was positively significant, indicating that the subsidiary’s operating decisions regarding cash flow were influenced by the parent company; thus, Hypothesis 5 was supported.
Descriptive statistics and correlations

Note. ***p<0.01; **p<0.05; *p<0.1.
Results of regression analysis

Note. ***p<0.01; **p<0.05; *p<0.1.
The results of the regression analysis revealed a significantly positive relationship between the subsidiaries and parent companies in financial structure, debt-paying ability, earnings power, and cash flow control. According to the analysis, the subsidiaries inherited parent company routines related to financing tendencies, risk preference, earnings power, and the level of cash flow. However, we observed a nonsignificant relationship in the financial ratios of operating ability. Thus, the subsidiaries did not inherit routines related to operating efficiency.
Conclusion and recommendations for future studies
Conclusion
This study considered accounting information (financial structure, debt-paying ability, operating ability, earnings power, and cash flow) as a visible characteristic originating from organizational routines. If routines inheritance in a group company exists (in other words, if a new generation firm follows the same decision rules as the previous generation), the differences between their financial ratios must be nonsignificant.
The ostensive aspect of routines described by Feldman and Pentland (Reference Feldman and Pentland2003) refers to the principle of organizational routines and the standard operational procedures related to documentation. Thus, when a group company creates a new firm, the current relevant systems are transferred to the firm. These systems, however, cannot determine all behaviors; the ostensive aspect cannot account for all situations and details. Under various circumstances, members of the new subsidiary inevitably make decisions that differ from those of the parent company on the basis of their own knowledge. Among the five financial ratios, decisions regarding subsidiaries’ financial structure, debt-paying abilities, earnings power, and levels of cash flow are primarily decided by senior managers who are appointed by parent companies; thus, the routines from the parent companies are inherited. Regarding operating ability, the subsidiary’s collection policy typically accounts for customers more than does that of the parent company. Furthermore, the decisions regarding inventory and asset management are made by mid- and low-level managers. According to the consideration of transfer costs proposed by Martin and Salomon (Reference Martin and Salomon2003), a parent company seldom appoints personnel as mid- and low-level managers, creating a gap between the ostensive and performative aspects. The business routines pertaining to this aspect are thus difficult to inherit.
This study has three major contributions. First, it links accounting and organization research by applying accounting information as the characteristics of organization to explore the inheritance phenomenon between different generations of organization. Second, the result of this study suggests that in determining the adequacy of a company’s financial situation, people should refer not only to the industry standard as traditional accounting textbooks suggest but also to its parent company. Third, the empirical results evidence that routine inheritance occurs between generations of organizations. The last two contributions also can answer why lower predicting power occurred in some previous financial ratio/firm performance models (Beaver, Reference Beaver1966; Altman, Reference Altman1968; Ohlson, Reference Ohlson1980) when they applied in Taiwan (Lin, Liang, & Chen, Reference Lin, Liang and Chen2011).
Recommendations for future studies
We applied the accounting information of group companies to examine whether parent companies’ existing routines influence subsidiary decisions. Although the results verify that routines inheritance exists among firms in a group company, the characteristics of firm routines should not be limited to financial information. There is considerable amount of additional financial and nonfinancial information that are related to organizational operations. Future studies might confirm the existence of firm routines through broader investigations.
Acknowledgements
This work was supported by the National Natural Science Foundation of China (71774120) and the Fundamental Research Funds for The Central Universities of China (410500262).