


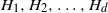
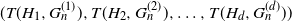
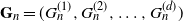

1. Introduction
Let
 $G_n = (V(G_n), E(G_n))$
be a sequence of graphs with vertex set
 $V(G_n)= [n]\;:\!=\; \{1,2,\ldots, n\}$
and edge set
 $E(G_n)$
. Suppose the vertices of
 $G_n$
are colored uniformly at random with
 $c \geq 2$
colors, that is,
 \begin{equation*} \mathrm{P}(v \in [n] \text{ is assigned color } a \in \{1, 2, \ldots, c\} ) = \frac{1}{c},\end{equation*}
independently of the other vertices. Given such a coloring, an edge
 $(u, v) \in E(G_n)$
is said to be monochromatic if both u and v are assigned the same color. Formally, if
 $X_v$
denotes the color of the vertex
 $v \in [n]$
then
 $(u, v) \in E(G_n)$
is monochromatic if and only if
 $X_u = X_v$
. Denote by
 $T(K_2,G_n)$
the number of monochromatic edges in
 $G_n$
, that is,
 \begin{equation} T(K_2,G_n) \;:\!=\;\frac{1}{2}\sum_{1\leq u\neq v\leq n}a_{uv}(G_n)\textbf{1}\{X_u=X_v\} ,\end{equation}
where
 $A(G_n)= (a_{uv}(G_n))_{1 \leq u, v \leq n}$
is the adjacency matrix of
 $G_n$
. More generally, for a fixed graph
 $H = (V(H), E(H))$
with
 $V(H)=\{1,\ldots, |V(H)| \}$
, denote by
 $T(H, G_n)$
the number of monochromatic copies of H in
 $G_n$
, that is,
 \begin{equation} T(H, G_n)\;:\!=\; \frac{1}{|{\textrm{Aut}}(H)|}\sum_{\mathbf{s}\in [n]_{|V(H)|}}\prod_{(a,b)\in E(H)}a_{s_as_b}(G_n)\textbf{1}\{X_{=\mathbf{s}}\} ,\end{equation}
where:
-
•
 $[n]_{|V(H)|}$
is the set of all
$|V(H)|$
-tuples
$\mathbf{s}=(s_1,\ldots, s_{|V(H)|})\in [n]^{|V(H)|}$
with distinct indices (here,
$S^N$
denotes the N-fold cartesian product
$S\times S\times \cdots \times S$
of a set S); thus, the cardinality of
$[n]_{|V(H)|}$
is
$\frac{n!}{(n-|V(H)|)!}$
;
-
• for any
$\mathbf{s}=(s_1,\ldots, s_{|V(H)|})\in [n]_{|V(H)|}$
,
\begin{equation*} \textbf{1}\{X_{=\mathbf{s}}\}\;:\!=\;\textbf{1}\{X_{s_1}=\cdots = X_{s_{|V(H)|}}\}; \end{equation*}
-
•
${\textrm{Aut}}(H)$
is the automorphism group of H, that is, the set of permutations
$\sigma$
of the vertex set V(H) such that
$(x,y)\in E(H)$
if and only if
$(\sigma(x),\sigma(y))\in E(H)$
.Note that
where
\begin{equation*} \mathrm{E} T(H, G_n) = \frac{N(H, G_n)}{c^{|V(H)| - 1}},\end{equation*}
$N(H, G_n)$
is the number of copies of H in
$G_n$
.


Various problems in combinatorial probability, nonparametric statistics, and theoretical computer science involve the study of (1) and (2). The following are some examples.
Example 1. (Birthday problem.) Suppose
 $G_n$
is a friendship graph (two people are connected by an edge in the graph if they are friends) which is colored uniformly randomly with
 $c=365$
colors (where the colors correspond to birthdays and the birthdays are assumed to be uniformly distributed across the year). In this case a monochromatic edge in
 $G_n$
corresponds to two friends with the same birthday. The birthday problem asks for the probability that there are two friends with the same birthday, that is,
 $\mathrm{P}(T(K_2, G_n)>0)$
. This is a celebrated problem in elementary probability (see [Reference DasGupta28, Reference Diaconis and Holmes30, Reference Mitzenmacher and Upfal62] and references therein), which appears in many different contexts, such as the study of coincidences [Reference Diaconis and Mosteller31], graph coloring problems [Reference Barbour, Holst and Janson4, Reference Bhattacharya, Diaconis and Mukherjee13, Reference Cerquetti and Fortini22], testing discrete distributions [Reference Batu, Fortnow, Rubinfeld, Smith and White6, Reference Diakonikolas, Gouleakis, Peebles and Price32, Reference Paninski74], security of hash functions [Reference Bellare and Kohno7, Reference Stinson83], and the discrete logarithm problem [Reference Bhattacharya9, Reference Galbraith and Holmes34, Reference Kim, Montenegro, Peres and Tetali46]. A natural generalization of the birthday problem is to consider higher-order birthday matches (often referred to as multicollisions), that is, the number of r-tuples of friends sharing the same birthday [Reference Diaconis and Mosteller31, Reference Mckinney61, Reference Nandi and Stinson64, Reference Suzuki, Tonien, Kurosawa and Toyota84]. This corresponds to studying the asymptotics of
 $T(K_r, G_n)$
, the number of monochromatic r-cliques
 $K_r$
in the friendship graph
 $G_n$
[Reference Bhattacharya and Mukherjee16, Reference Bhattacharya, Mukherjee and Mukherjee17].
Example 2. (Graph-based nonparametric two-sample tests.) One of the fundamental problems in statistical inference is to decide whether or not two data sets are generated from the same statistical model. This is the classical two-sample problem which can be formally stated as follows. Given independent and identically distributed (i.i.d.) samples
 $\mathscr{X}_{n} = \{X_1, X_2, \ldots, X_n\}$
and
 $\mathscr{Y}_{n} = \{Y_1, Y_2, \ldots, Y_n\}$
from two multivariate distributions F and G, respectively, the two-sample problem is to test the hypothesis
 \begin{equation} H_0 \;:\; F = G \quad \text{versus} \quad H_1 \;:\; F \ne G. \end{equation}
A theme that has emerged repeatedly in the development of nonparametric two-sample tests is the use of random geometric graphs. This includes the celebrated Friedman-Rafsky test based on the minimum spanning tree [Reference Friedman and Rafsky33], tests based on nearest-neighbor graphs [Reference Henze39, Reference Schilling81], and optimal matchings [Reference Rosenbaum78]. Here, the idea is to construct a random geometric graph
 $\mathscr{G}_n$
of the pooled sample
 $\mathscr{X}_{n}\cup \mathscr{Y}_{n}$
, and reject the null hypothesis
 $H_0$
in (3) if the number of edges in
 $\mathscr{G}_n$
with one end-point in sample 1 and another in sample 2 is ‘small’. In other words,
 $H_0$
is rejected when the number of nonmonochromatic edges in
 $\mathscr{G}_n$
is ‘small’ (where the sample labels correspond to the colors), which is equivalent to rejecting
 $H_0$
when the number of monochromatic edges is ‘large’. Hence, understanding the null distribution of such a test statistic entails studying the asymptotic properties of
 $T(K_2, \mathscr{G}_n)$
with
 $c=2$
colors.
Example 3. (Quadratic Rademacher chaos.) When
 $c=2$
,
 $T(K_2, G_n)$
centered by its mean can be expressed as a quadratic form in Rademacher variables as follows:
 \begin{align} T(K_2,G_n) - \mathrm{E} T(K_2, G_n) & =\frac{1}{2}\sum_{1\leq u\neq v\leq n}a_{uv}(G_n) \bigg( \textbf{1}\{X_u=X_v\} - \frac{1}{2} \bigg) \nonumber \\[5pt] & = \frac{1}{4}\sum_{1\leq u\neq v\leq n}a_{uv}(G_n) (2\textbf{1}\{X_u=1\} -1)(2\textbf{1}\{X_v=1\} -1) \nonumber \\[5pt] & = \frac{1}{4} \sum_{1\leq u\neq v\leq n} a_{uv}(G_n) Y_u Y_v , \end{align}
where
 $Y_u = 2\textbf{1}\{X_u=1\} -1$
, for
 $1 \leq u \leq n$
, are i.i.d. Rademacher random variables. Hence, when
 $c=2$
,
 $T(K_2, G_n) - \mathrm{E} T(K_2, G_n)$
is the quadratic Rademacher chaos [Reference Blei and Janson19, Reference Nourdin, Peccati and Reinert67], which appears in various contexts, for example, in the Hamiltonian of the Ising model [Reference Basak and Mukherjee5, Reference Bhattacharya and Mukherjee15], testing independence in autoregressive models [Reference Beran8], and Ramsey theory [Reference Kwan, Sah, Sauermann and Sawhney50]. A characterization of all distributional limits of (4) has been obtained recently in [Reference Bhattacharya, Das, Mukherjee and Mukherjee12].
A number of recent papers have studied the limiting distribution of
 $T(H, G_n)$
(appropriately centered and scaled), beginning with [Reference Bhattacharya, Diaconis and Mukherjee13] which considered the case
 $H=K_2$
. Specifically, [Reference Bhattacharya, Diaconis and Mukherjee13, Theorem 1.3] shows that
 $T(K_2, G_n)$
is asymptotically normal whenever the fourth moment of a suitably normalized version of
 $T(K_2, G_n)$
converges to 3 (the fourth moment of the standard normal distribution). This is an instance of the celebrated fourth-moment phenomenon, which was originally discovered in the seminal papers [Reference Nourdin and Peccati65, Reference Nualart and Peccati70] and has, since then, emerged as a unifying principle governing the asymptotic normality of random multilinear forms (see the book [Reference Nourdin and Peccati66] for further details). Going beyond monochromatic edges, it was subsequently shown that the fourth-moment phenomenon continues to hold for the asymptotic normality of
 $T(K_3, G_n)$
(the number of monochromatic triangles) when
 $c \geq 5$
[Reference Bhattacharya, Fang and Yan14] and for
 $T(H, G_n)$
, for any fixed graph H, when
 $c \geq 30$
[Reference Das, Himwich and Mani27]. For
 $c=2$
a more refined result on the asymptotic normality of
 $T(H, G_n)$
has been recently obtained by Mani and Mikulincer [Reference Mani and Mikulincer58] in terms of local influence-based conditions. While the aforementioned results provide sufficient conditions (some of which are also necessary) for the asymptotic normality of
 $T(H, G_n)$
, there are many instances where
 $T(H, G_n)$
has a non-Gaussian limit. This, in particular, is often the case when
 $G_n$
is a sequence of dense graphs, that is,
 $|E(G_n)| = \Theta(n^2)$
. In this case, to describe the limiting distribution of
 $T(H, G_n)$
it is convenient to adopt the framework of graph limit theory [Reference Lovász52] and assume
 $G_n$
converges (in the cut-distance) to a graphon W. The limiting distribution of
 $T(H, G_n)$
(suitably standardized) has both Gaussian and non-Gaussian components, where the non-Gaussian component is a (possibly) infinite weighted sum of independent centered chi-squared random variables with the weights determined by the eigenvalues of a graphon derived from W (see [Reference Bhattacharya, Diaconis and Mukherjee13, Theorem 1.4] and [Reference Bhattacharya and Mukherjee16, Theorem 1.3]).
Given the above results, a natural next step is to study the joint distribution of a finite collection of monochromatic subgraphs. Specifically, given a collection of
 $d \geq 1$
graphs
 $\mathcal{H} = $
 $(H_1, H_2, \ldots, H_d)$
, what is the limiting joint distribution of
 $(T(H_1, G_n),T(H_2, G_n),\ldots,$
 $T(H_d, G_n))$
(suitably standardized)? More generally, we can consider the joint distribution of
 \begin{equation*} \mathbf{T}(\mathcal{H}, \mathbf{G}_n) \;:\!=\; \big(T\big(H_1, G_n^{(1)}\big), T\big(H_2, G_n^{(2)}\big), \ldots, T\big(H_d, G_n^{(d)}\big)\big),\end{equation*}
where
 $\mathbf{G}_n = (G_n^{(1)}, G_n^{(2)}, \ldots, G_n^{(d)})$
is a collection of
 $d\geq 1$
graphs having the same vertex set [n]. Multiple graphs sharing a common vertex set are known as multilayer networks (or multiplexes). The ubiquitous presence of complex relational data with many interdependencies has propelled the rapidly developing literature on multiplex networks (see [Reference Arroyo, Athreya, Cape, Chen, Priebe and Vogelstein2, Reference Bhattacharya, Bhowal, Das, Eslava and Karmakar10, Reference Bianconi18, Reference Chandna, Janson and Olhede24, Reference De Domenico, Solé-Ribalta, Cozzo, Kivelä, Moreno, Porter, Gómez and Arenas29, Reference Kiani, Gomez-Cabrero and Bianconi45, Reference Kivelä, Arenas, Barthelemy, Gleeson, Moreno and Porter47, Reference Lei, Chen and Lynch51, Reference Lunagómez, Olhede and Wolfe54, Reference MacDonald, Levina and Zhu57, Reference Skeja and Olhede82] and the references therein). In this paper we derive the asymptotic distribution of
 $T(\mathcal{H}, \mathbf{G}_n)$
for a sequence of dense multiplexes
 $\mathbf{G}_n$
. To describe the limiting distribution, we define a natural notion of convergence of multiplexes (in the multiplex cut-distance) and also invoke the framework of multiple stochastic integrals (for capturing the non-Gaussian dependencies between the different marginals). Under the assumption that the multiplex
 $\mathbf{G}_n$
converges in the multiplex cut-metric, we show that the limiting distribution of
 $T(\mathcal{H}, \mathbf{G}_n)$
has two independent components, one of which is a multivariate Gaussian and the other is a sum of independent bivariate stochastic integrals (see Theorem 1). The stochastic integrals are with respect to the same underlying Brownian motion on [0, 1], which captures the dependence between the different marginals. A key ingredient of the proof is an invariance principle which allows us to replace the coloring variables with appropriately chosen Gaussian variables, which might be of independent interest (see Section 2). As a corollary of our general result, by considering
 $G_n^{(1)} = G_n^{(2)} = \cdots = G_n^{(d)} = G_n$
, we obtain the joint distribution of
 $(T(H_1, G_n), T(H_2, G_n), \ldots, T(H_d, G_n))$
whenever
 $G_n$
converges to a graphon. This extends the result in [Reference Bhattacharya and Mukherjee16] from the marginal distribution of the number of monochromatic copies of a particular graph H to the joint distribution of the number of monochromatic copies of a collection of graphs (see Corollary 2). Another important special case is when
 $H_1= H_2, \ldots = H_d = K_2$
is the edge (see Corollary 1), which establishes the joint distribution of a finite collection of random quadratic forms in Rademacher variables (recall Example 3). In Section 4 we discuss various examples, including, in particular, the correlated Erdős–Rényi multiplex that commonly appears in the study of graph matching problems (see Example 4).
1.1. Convergence of graphs and multiplexes
The theory of graph limits [Reference Borgs, Chayes, Lovász, Sós and Vesztergombi20, Reference Borgs, Chayes, Lovász, Sós and Vesztergombi21, Reference Lovász52] has received phenomenal attention in recent years. Here, we will recall the basic notions about the convergence of graph sequences. For a detailed exposition of the theory of graph limits refer to Lovász [Reference Lovász52].
For two graphs F and G, define the homomorphism density of F into G by
 \begin{equation*} t(F,G) \;:\!=\;\frac{|\hom(F,G)|}{|V (G)|^{|V (F)|}} ,\end{equation*}
where
 $|\hom(F,G)|$
denotes the number of homomorphisms from F to G. In fact, t(F, G) is the proportion of maps
 $\phi\;:\; V (F) \rightarrow V (G)$
which define a graph homomorphism. To define the continuous analog of graphs, consider
 $\mathscr{W}$
to be the space of all measurable functions from
 $[0, 1]^2$
into [0, 1] which are symmetric, that is,
 $W(x, y) = W(y,x)$
, for all
 $x, y \in [0, 1]$
. An element of
 $\mathscr{W}$
is called a graphon. For a simple graph F with
 $V (F)= \{1, 2, \ldots, |V(F)|\}$
and a graphon
 $W \in \mathscr{W}$
, define the homomorphism density of F in W by
 \begin{equation*} t(F,W) =\int_{[0,1]^{|V(F)|}}\prod_{(i,j)\in E(F)}W(x_i,x_j) \,\mathrm{d}x_1\, \mathrm{d}x_2\cdots \mathrm{d}x_{|V(F)|} = \mathrm{E}\left(\prod_{(i, j)\in E(F)}W(U_i, U_j)\right)\!,\end{equation*}
where
 $U_1, U_2, \ldots$
are i.i.d.
 $\mathrm{Unif}[0, 1]$
. It is easy to verify that
 $t(F, G) = t(F, W^{G})$
, where
 $W^{G}$
is the empirical graphon associated with the graph G which is defined as
 \begin{equation} W^G(x, y) \;:\!=\; \textbf{1}\{(\lceil |V(G)|x \rceil, \lceil |V(G)|y \rceil)\in E(G)\}.\end{equation}
(In other words, to obtain the empirical graphon
 $W^G$
from the graph G, partition
 $[0, 1]^2$
into
 $|V(G)|^2$
squares of side length
 $1/|V(G)|$
, and let
 $W^G(x, y)=1$
in the (i, j)th square if
 $(i, j)\in E(G)$
, and 0 otherwise.)
The basic definition of graph limit theory is in terms of the convergence of the homomorphism densities [Reference Borgs, Chayes, Lovász, Sós and Vesztergombi20, Reference Borgs, Chayes, Lovász, Sós and Vesztergombi21, Reference Lovász52]. Specifically, a sequence of graphs
 $G_n$
converges to a graphon W if for every finite simple graph F,
 \begin{equation} \lim_{n\rightarrow \infty}t(F, G_n) = t(F, W). \end{equation}
This convergence can be captured through the cut-distance, which is defined as follows.
Definition 1. [Reference Lovász52] The cut-distance between two graphons
 $W_1, W_2 \in \mathcal{W}$
is defined as
 \begin{equation} \|W_1-W_2\|_{\square}\;:\!=\;\sup_{A, B \in [0, 1]}\left|\int_{A \times B} W_1(x, y)-W_2(x, y)\, \mathrm{d}x \, \mathrm{d}y \right| , \end{equation}
for
 $W_1, W_2 \in \mathscr{W}$
.
Using the cut-distance, we define an equivalence relation on
 $\mathscr{W}$
as follows:
 $W_1 \sim W_2$
when
 $\inf_{\phi} \|W_1 - W_2^\phi\|_{\square} = 0$
, where the infimum taken over all measure-preserving bijections
 $\phi\;:\; [0, 1] \rightarrow [0, 1]$
and
 $W_2^\phi(x, y)\;:\!=\; W_2(\phi(x), \phi(y))$
, for
 $x, y \in [0, 1]$
. The orbit of
 $W \in \mathscr{W}$
is the set of all functions
 $W^{\phi}$
, as
 $\phi$
varies over all measure-preserving bijections from
 $[0, 1] \rightarrow [0, 1]$
. Denote by
 $\tilde{W}$
the closure of the orbit of W in
 $(\mathscr{W}, \|\cdot\|_\square)$
. The quotient space
 $\tilde{\mathscr{W}} = \{\tilde{W} \colon W \in \mathscr{W}\}$
of closed equivalence classes is associated with the cut-metric:
 \begin{equation*} \delta_\square(\tilde{W}_1, \tilde{W}_2 )\;:\!=\;\inf_{\phi} \big\| W_1 - W_2^{\phi}\big\|_{\square} .\end{equation*}
The central result in graph limit theory is that a sequence of graphs
 $G_n$
converges to W in the sense of (6) if and only if
 $\tilde{W}^{G_n}$
is a Cauchy sequence in the
 $\delta_{\square}$
metric. Moreover, a sequence of graphs
 $G_n$
converges to a graphon W if and only if
 $\delta_{\square}(\tilde{W}^{G_n}, \tilde{W} ) \rightarrow 0$
(see [Reference Borgs, Chayes, Lovász, Sós and Vesztergombi20, Theorem 3.8]).
In this paper we deal with sequences of multilayer networks (multiplexes), where multiple graphs share the same set vertices. A multiplex with d layers will be referred to as a d-multiplex. To define convergence of a sequence of d-multiplexes
 $\mathbf{G}_n$
with a common vertex set
 $V(\mathbf{G}_n) = [n]$
, we need the notion of the multiplex cut-metric. Towards this, denote by
 $\mathscr{W}^d$
the d-fold Cartesian product of
 $\mathscr{W}$
. An element of
 $\mathscr{W}^d$
will be referred to as a d-graphon. We can define an equivalence relation on
 $\mathscr{W}^d$
as follows. Given
 $\mathbf{W}=(W_1, W_2, \ldots, W_d) \in \mathscr{W}^d$
and
 $\mathbf{W}'=(W_1', W_2', \ldots, W_d') \in \mathscr{W}^d$
, we say
 $\mathbf{W} \sim \mathbf{W}'$
if
 $\inf_{\phi} \sum_{j=1}^d \| W_j^\phi - W_j'\|_{\square} = 0$
, where, as before, the infimum is taken over all measure-preserving bijections
 $\phi\;:\; [0, 1] \rightarrow [0, 1]$
. Denote by
 $\tilde{\mathbf{W}}$
the closure of the orbit of
 $\mathbf{W}$
and the quotient space of closed equivalence classes as
 $\tilde{\mathscr{W}}^d = \{\tilde{\mathbf{W}} \colon \mathbf{W} \in \mathscr{W}^d\}$
. For
 $\tilde{\mathbf{W}}, \tilde{\mathbf{W}}' \in \tilde{\mathscr{W}}^d$
, define the multiplex cut-metric as
 \begin{equation} \delta_\square(\tilde{\mathbf{W}}, \tilde{\mathbf{W}}' )\;:\!=\;\inf_{\phi} \sum_{j=1}^d \big\| W_j^{\phi} - W_j'\big\|_{\square} .\end{equation}
Remark 1. It is important to note that in the definition of the multiplex cut-metric, the same measure-preserving transformation is applied to all the layers. This is because the different layers of a multiplex network have the same set of nodes, hence we need to apply a single measure-preserving transformation to all the coordinates to preserve the invariance of certain multiplex features. If we were allowed different measure-preserving transformations, we would obtain the metric for marginal convergence of the layers in the cut-metric.
We will say that a sequence of d-multiplexes
 $\mathbf{G}_n = (G_n^{(1)}, G_n^{(2)}, \ldots, G_n^{d})$
converges to the d-graphon
 $\mathbf{W} = (W_1, W_2, \ldots, W_d) \in \mathscr{W}^d$
if
 \begin{equation} \delta_\square\left( \tilde{\mathbf{W}}^{\mathbf{G}_n}, \tilde{\mathbf{W}} \right) \rightarrow 0,\end{equation}
where
 $\mathbf{W}^{\mathbf{G}_n} = (W^{G_n^{(1)}}, \ldots, W^{G_n^{(d)}})$
is the empirical d-graphon associated with the d-multiplex
 $\mathbf{G}_n$
.
Remark 2. The objects that we refer to as d-graphons have appeared in the literature (in more general settings) under different names, such as decorated graphons [Reference Kunszenti-Kovács, Lovász and Szegedy49, Reference Lovász and Szegedy53] and probability graphons or P-graphons [Reference Abraham, Delmas and Weibel1, Reference Zucal88, Reference Zucal89] (see the recent survey [Reference Ganguly and Bhattacharya35] for a discussion on the various connections). In particular, the joint cut-metric defined in (8) is a special case of the cut-metric for probability graphons, when the probability measure is supported on a finite set (see, for example, [Reference Abraham, Delmas and Weibel1, Definition 3.15] and [Reference Ganguly and Bhattacharya35, Section 10]).
1.2. Statement of the results
With the above preparations, we are now ready to state our main results. To this end, fix an integer
 $d \geq 1$
and a finite collection of graphs
 $\mathcal{H}= (H_1, H_2, \ldots, H_d)$
. Then for a sequence of d-multiplexes
 $\mathbf{G}_n = (G_n^{(1)}, G_n^{(2)}, \ldots, G_n^{(d)})$
, define the vector of standardized monochromatic copies as
 \begin{align} \boldsymbol{\Gamma}(\mathcal{H}, \mathbf{G}_n) = \begin{pmatrix} \Gamma\big(H^{(1)},G_n^{(1)}\big) \\[5pt] \vdots \\[5pt] \Gamma\big(H^{(d)},G_n^{(d)}\big) \end{pmatrix},\end{align}
where
 \begin{equation} \Gamma(H,G_n) \;:\!=\; |{\textrm{Aut}}(H)| c^{|V(H)|-\frac{3}{2}} \left\{ \frac{ T(H,G_n) - \mathrm{E}(T(H,G_n)) }{n^{|V(H)|-1} } \right\},\end{equation}
for any graph
 $H=(V(H), E(H))$
and any graph sequence
 $G_n$
with
 $G_n=([n], E(G_n))$
. Our aim is to derive the limiting distribution of
 $\boldsymbol{\Gamma}(\mathcal{H}, \mathbf{G}_n)$
when
 $\mathbf{G}_n$
converges to a d-multiplex
 $\boldsymbol{W}$
. We begin by introducing the notion of the two-point conditional kernel.
Definition 2. (Two-point conditional kernel.) Given a finite graph
 $H = (V(H), E(H))$
and a graphon W, define the two-point conditional kernel of H with respect to W as follows:
 \begin{equation} W_H(x,y)\;:\!=\;\sum_{1\leq a \neq b \leq |V(H)|}\mathrm{E}\left( \prod_{(i, j)\in E(H)} W(U_i, U_j) \;\middle|\; U_{a}=x, U_{b}=y\right)\!. \end{equation}
(Note that
 $W_H$
can take values greater than 1; hence, technically,
 $W_H$
is not a graphon. However,
 $W_H \leq |V(H)|(|V(H)|-1)$
, hence
 $W_H \in \mathscr{W}_1$
, where
 $\mathscr{W}_1$
is the space of bounded, symmetric, measurable functions from
 $[0, 1]^2$
to
 $[0, \infty)$
.)
To describe the asymptotic variance of
 $\boldsymbol{\Gamma}(\mathcal{H}, \mathbf{G}_n)$
it is convenient to define the following graph operation.
Definition 3. Suppose
 $H_1 = (V(H_1), E(H_1))$
and
 $H_2 = (V(H_2), E(H_2))$
are two graphs with vertex sets
 $V(H_1) = \{1, 2, \ldots, |V(H_1)|\}$
and
 $V(H_2) = \{1, 2, \ldots, |V(H_2)|\}$
and edge sets
 $E(H_1)$
and
 $E(H_2)$
, respectively. Then for
 $1 \leq a \ne b \leq |V(H_1)|$
and
 $1 \leq a' \ne b' \leq |V(H_2)|$
, the (a, b), (a′, b′)-join of
 $H_1$
and
 $H_2$
is the simple graph obtained by identifying the vertices a and b in
 $H_1$
with the vertices a′ and b′ in
 $H_2$
, respectively. The resulting graph will be denoted by
 \begin{equation*} H_1 \bigotimes_{(a, b), (a', b')} H_2. \end{equation*}
An example is shown in Figure 1. (Note that the (a, b),(a′, b′)-join between two graphs can be different from the (b, a),(a′, b′)-join.)
Furthermore, denote the
 $L^2$
inner product between graphons W and W′ by
 \begin{equation*} \langle W,W'\rangle \;:\!=\; \int_{[0,1]^2} W(x,y) W'(x,y)\,\mathrm{d}x \,\mathrm{d}y.\end{equation*}
With the above notation we can now state our result on the asymptotic distribution of
 $\boldsymbol{\Gamma}(\mathcal{H}, \mathbf{G}_n)$
. Throughout, the stochastic integrals are considered in the Wiener–Itô sense [Reference Itô42] (see also [Reference Janson43, Chapter 7]).
The (a, b), (a′, b′)-join of the graphs
 $H_1$
and
 $H_2$
.

Theorem 1. Suppose
 $\mathbf{G}_n$
is a sequence of d-multiplexes converging to a d-graphon
 $\mathbf{W}$
. Let
 $\mathcal{H}= (H_1, H_2, \ldots, H_d)$
be a collection of fixed graphs and
 $\boldsymbol{\Gamma}(\mathcal{H}, \mathbf{G}_n)$
be as defined in (10). Assume, for
 $1 \leq i \ne j \leq d$
, there exists
 $\rho_{ij} \geq 0$
such that
 \begin{equation} \lim_{n \rightarrow \infty} \Big\langle W_{H_i}^{G_n^{(i)}}, W_{H_j}^{G_n^{(j)}} \Big\rangle = \rho_{ij} , \end{equation}
where
 $W_{H_i}^{G_n^{(i)}}$
is the two-point conditional kernel of the empirical graphon
 $W^{G_n^{(i)}}$
with respect to
 $H_i$
, for
 $1 \leq i \leq d$
. Then, as
 $n \rightarrow \infty$
,
 \begin{equation} \boldsymbol{\Gamma}(\mathcal{H}, \mathbf{G}_n) \xrightarrow{D} \sqrt{\frac{c-1}{2c}} \mathbf{Z} +\frac{1}{2\sqrt{c}\,}\sum_{a=1}^{c-1}\begin{pmatrix}\displaystyle\int_{[0,1]^2} (W_1)_{H_1} (x, y) \,\mathrm{d}B_x^{(a)}\,\mathrm{d}B_y^{(a)} \\[5pt] \vdots \\[5pt] \displaystyle\int_{[0,1]^2} (W_d)_{H_d}(x, y) \,\mathrm{d}B_x^{(a)}\,\mathrm{d}B_y^{(a)} \end{pmatrix} , \end{equation}
where:
-
•
$(W_i)_{H_i}$
is the two-point conditional kernel of the graphon
$W_i$
with respect to
$H_i$
, for
$1 \leq i \leq d$
; -
•
$\mathbf{Z} \sim N_d(0, \Sigma)$
, with
$\Sigma = (\sigma_{ij})_{1 \leq i, j \leq d}$
defined as:
\begin{equation*} \sigma_{ij} \;:\!=\; \left\{ \begin{array}{c@{\quad}c} \sum\limits_{\substack{1\leq a \neq b\leq |V(H_i)| \\ 1\leq a' \ne b'\leq |V(H_i)|}}t\left( H_i\bigotimes\limits_{(a, b), (a', b')}H_i, W_i \right) - \|(W_i)_{H_i}\|^2 & \textit{ for } i = j , \\[5pt] \rho_{ij} - \langle (W_i)_{H_i}, (W_j)_{H_j}\rangle & \textit{ for } i \ne j ; \end{array} \right. \end{equation*}
-
•
$\{B^{(1)}_{t}, \ldots, B^{(c-1)}_{t} \}_{t \in [0, 1]}$
are i.i.d. Brownian motions on [0, 1] which are independent of
$\mathbf{Z}$
.


The proof of Theorem 1 is given in Section 3. A key ingredient of the proof is a general invariance principle, which shows the following: random multilinear forms indexed by the variables which encode the vertex coloring are asymptotically close in moments to multilinear forms indexed by appropriately chosen Gaussian variables (see Section 2). To apply this result, we first express
 $T(H, G_n) - \mathrm{E} T(H, G_n)$
, for any graph H, as a weighted sum of multilinear forms with degrees ranging from 2 to
 $|V(H)|$
(see Lemma 4). Next, we show all terms in the expansion with degree greater than 2 are asymptotically negligible (see Lemma 5). In other words, only the quadratic terms in the expansion of
 $T(H, G_n) - \mathrm{E} T(H, G_n)$
contribute to the limiting distribution. Then, using the invariance principle, the problem of deriving the joint distribution of
 $\boldsymbol{\Gamma}(\mathcal{H}, \mathbf{G}_n)$
reduces to finding the joint distribution of certain Gaussian quadratic forms, which is analyzed using the Cramér–Wold device and spectral methods.
Remark 3. The two terms that appear in the right-hand side of (14) can be interpreted as follows. The component with the bivariate stochastic integral arises from the randomness of the coloring. In particular, for each
 $1 \leq u \leq n$
, the collection
 $\{B^{(a)}(\frac{u+1}{n})-B^{(a)}(\frac{u}{n})\}_{a\in[c]}$
can be thought of as an asymptotic surrogate for the collection
 $(\textbf{1}\{X_{u}=a\}-\frac{1}{c})_{a\in [c]}$
. (Note that the vector
 $(\textbf{1}\{X_{u}=a\}-\frac{1}{c})_{a\in [c]}$
adds to zero, hence the total degrees of freedom gets reduced from c to
 $c-1$
.) The reason for the appearance of the normal component in (14) is more subtle. It reflects the discrepancy between the total variance and the variance captured by the stochastic integrals, a phenomenon that is well known in the study of incomplete degenerate U-statistics. Alternatively, in our context this discrepancy can be intuitively explained using ‘pseudorandomness’ properties of the graph sequence
 $\mathbf{G}_n$
, which emerge from the convergence of
 $\mathbf{G}_n$
to the limiting d-graphon
 $\mathbf{W}$
and the convergence of the pairwise overlaps (13). The pseudorandomness from this approximation gets translated into the randomness in the Gaussian part. Supporting this interpretation is the observation that the ith marginal of the Gaussian component becomes degenerate, for
 $1 \leq i \leq d$
, whenever the corresponding graphon
 $W_i$
takes values only in
 $\{0, 1\}$
(see also the discussion in Remark 6). Such graphons are known as random-free [Reference Janson44, Section 10], as there is no edge-level randomness in graphs sampled from them.
Remark 4. Note that Theorem 1 assumes that the layers of the multiplex
 $\mathbf{G}_n$
collectively converge in the multiplex cut-distance and the pairwise overlaps of the two-point conditional kernels have a limit. In Section 4 we provide examples which illustrate that both these assumptions are necessary for the limiting distribution of
 $\boldsymbol{\Gamma}(\mathcal{H}, \mathbf{G}_n)$
to exist.
One useful special case of Theorem 1 is when
 $H_1= H_2 = \cdots = H_d = K_2$
is the edge. In this case, the 2-conditional kernel
 $W_{K_2}(x, y) = 2 W(x, y)$
(recall (12)) and, for
 $1 \leq i \ne j \leq d$
,
 \begin{equation*} \Big\langle W^{G_n^{(i)}}, W^{G_n^{(j)}} \Big\rangle = \frac{1}{4}\bigg\langle W_{K_2}^{G_n^{(i)}}, W_{K_2}^{G_n^{(j)}} \bigg\rangle = \frac{ 2 |E\big(G_n^{(i)}\big) \cap E\big(G_n^{(j)}\big)|}{n^2} ,\end{equation*}
where
 $\langle W,W'\rangle=\int_{[0,1]^2}W(x,y)W'(x,y)\,\mathrm{d}x \,\mathrm{d}y$
, and
 $E(G_n^{(i)}) $
is the edge set of the graph
 $G_n^{(i)}$
, for
 $1 \leq i \leq d$
. Hence, Theorem 1 implies the following result.
Corollary 1. Suppose
 $\mathbf{G}_n$
is a sequence of d-multiplexes converging to a d-graphon
 $\mathbf{W}$
. In addition, assume that there exists
 $\tilde{\rho}_{ij} \geq 0$
such that
 \begin{equation} \frac{2 |E\big(G_n^{(i)}\big) \cap E\big(G_n^{(j)}\big)|}{n^2} \rightarrow \tilde{\rho}_{ij} , \end{equation}
for
 $1 \leq i \ne j \leq d$
. Then, as
 $n \rightarrow \infty$
,
 \begin{equation*} \frac{1}{n}\left[ \begin{pmatrix} T\big(K_2,G_{n}^{(1)}\big)\\[5pt] \vdots \\[5pt] T\big(K_2,G_{n}^{(d)}\big) \end{pmatrix} - \frac{1}{c}\begin{pmatrix} |E\big(G_{n}^{(1)}\big)|\\[5pt] \vdots\\[5pt] |E\big(G_{n}^{(d)}\big)| \end{pmatrix} \right] \xrightarrow{D} \frac{\sqrt{c-1}}{\sqrt{2}c} \mathbf{Z} +\frac{1}{2c}\sum_{a=1}^{c-1}\begin{pmatrix}\displaystyle\int_{[0,1]^2}W_1\,\mathrm{d}B_x^{(a)}\,\mathrm{d}B_y^{(a)} \\[5pt] \vdots \\[5pt] \displaystyle\int_{[0,1]^2}W_d \,\mathrm{d}B_x^{(a)}\,\mathrm{d}B_y^{(a)} \end{pmatrix} , \end{equation*}
where:
-
•
$\mathbf{Z} \sim N_d(0, \Sigma)$
, with
$\Sigma = (\sigma_{ij})_{1 \leq i, j \leq d}$
defined as:
\begin{equation*}\sigma_{ij} \;:\!=\; \left\{ \begin{array}{c@{\quad}c} \int_{[0,1]^2} W_{i}(x, y)(1-W_{i}(x, y) ) \,\mathrm{d}x\,\mathrm{d}y & \textit{ for } i = j , \\[5pt] \tilde{\rho}_{ij} - \int_{[0,1]^2} W_i(x, y) W_j(x, y) \,\mathrm{d}x \, \mathrm{d}y & \textit{ for } i \ne j ; \end{array} \right. \end{equation*}
$\{B^{(1)}_{t}, \ldots, B^{(c-1)}_{t} \}_{t \in [0, 1]}$
are i.i.d. Brownian motions on [0, 1] which are independent of
$\mathbf{Z}$
.


Note that the parameter
 $\tilde\rho_{ij}$
in the above result is related to the parameter
 $\rho_{ij}$
defined in (13) via
 $\tilde{\rho}_{ij}=\frac{1}{4}\rho_{ij}$
. If all the d layers of
 $\mathbf{G}_n$
are the same, that is,
 $G_n^{(1)}= G_n^{(2)} = \cdots = G_n^{(d)} = G_n$
, then Theorem 1 gives the joint distribution of
 $(\Gamma(H_1, G_n), \ldots, \Gamma(H_d, G_n))$
for any collection of fixed graphs
 $\mathcal{H}= (H_1, H_2, \ldots, H_d)$
. In this case, the limit of
 $\langle W^{G_n}_{H_i}, W^{G_n}_{H_j} \rangle$
, for
 $1 \leq i \ne j \leq d$
, can be derived from the convergence of
 $G_n$
to a graphon W. Specifically, we have (see Lemma 8 for the proof)
 \begin{equation*} \lim_{n \rightarrow \infty} \Big\langle W^{G_n}_{H_1}, W^{G_n}_{H_2} \Big\rangle = \sum_{\substack{1\leq u\neq v\leq |V(H_1)|\\ 1\leq u'\neq v'\leq |V(H_2)|}} t\left( H_1 \bigotimes_{(u,v),(u',v')} H_2, W \right)\!.\end{equation*}
The above identity combined with Theorem 1 gives the following result.
Corollary 2. Suppose
 $G_n$
is a sequence of graphs converging to a graphon W and let
 $\mathcal{H}= (H_1, H_2, \ldots, H_d)$
be a collection of fixed graphs. Then, as
 $n \rightarrow \infty$
,
 \begin{equation*} \begin{pmatrix} \Gamma(H_1, G_n) \\[5pt] \vdots \\[5pt] \Gamma(H_d, G_n) \end{pmatrix} \xrightarrow{D} \sqrt{\frac{c-1}{2c}} \mathbf{Z} +\frac{1}{2\sqrt{c}\, }\sum_{a=1}^{c-1}\begin{pmatrix}\displaystyle\int_{[0,1]^2} W_{H_1} (x, y) \,\mathrm{d}B_x^{(a)}\,\mathrm{d}B_y^{(a)} \\[5pt] \vdots \\[5pt] \displaystyle\int_{[0,1]^2} W_{H_d}(x, y) \,\mathrm{d}B_x^{(a)}\,\mathrm{d}B_y^{(a)} \end{pmatrix} , \end{equation*}
where:
-
•
$\mathbf{Z} \sim N_d(0, \Sigma)$
, with
$\Sigma = (\sigma_{ij})_{1 \leq i, j \leq d}$
defined as:
\begin{equation*}\sigma_{ij} \;:\!=\; \left\{ \begin{array}{c@{\quad}c} \sum_{\substack{1\leq a \neq b\leq |V(H_i)| \\ 1\leq a' \ne b'\leq |V(H_i)|}}t\big( H_i\bigotimes_{(a, b), (a', b')}H_i, W \big) - \|W_{H_i}\|^2 & \textit{ for } i = j , \\[5pt] \ \sum_{\substack{1\leq a \neq b\leq |V(H_i)| \\ 1\leq a' \ne b'\leq |V(H_j)|}}t\big( H_i\bigotimes_{(a, b), (a', b')}H_j, W \big) - \langle W_{H_i}, W_{H_j}\rangle & \textit{ for } i \ne j ; \end{array} \right. \end{equation*}
-
•
$\{B^{(1)}_{t}, \ldots, B^{(c-1)}_{t} \}_{t \in [0, 1]}$
are i.i.d. Brownian motions on [0, 1] which are independent of
$\mathbf{Z}$
.


Note that when
 $\mathcal{H}= (H)$
is a singleton we recover from Corollary 2 the marginal distribution of
 $T(H, G_n)$
, which was proved in [Reference Bhattacharya and Mukherjee16, Theorem 3.1]. In this case the limiting distribution can alternatively be expressed in terms of the eigenvalues of the two-point conditional kernel (recall (12)) as discussed in the following remark.
Remark 5. Note that by the spectral theorem, for any graph H, the two-point conditional kernel
 $W_H$
can be expressed as (see [Reference Lovász52, Section 7.5])
 \begin{align} W_H (x, y) = \sum_{s=1}^\infty \lambda_s \phi_s(x) \phi_s(y), \end{align}
where
 $\{\lambda_s\}_{s \geq 1}$
are the eigenvalues and
 $\{\phi_s\}_{s \geq 1}$
are an orthonormal collection of eigenvectors of the operator
 $\mathcal T_{W_H}$
defined by
 $\mathcal T_{W_H}(f)(x) = \int_0^1 W_H(x, y) f(y) \mathrm{d}y$
. Hence, by the linearity of stochastic integrals and the product formula (see [Reference Janson43, p. 100]), we have, for each
 $a \in [c]$
,
 \begin{align*} \;\; \int_{[0, 1]^2} W_H(x, y) \,\mathrm{d} B_x^{(a)} \,\mathrm{d} B_y^{(a)} & = \sum_{s=1}^\infty \lambda_s \int_{[0, 1]^2} \phi_s(x) \phi_s(y) \,\mathrm{d} B_x^{(a)}\, \mathrm{d} B_y^{(a)}\nonumber \\[5pt] & = \sum_{s=1}^\infty \lambda_s \left( \left( \int_0^1 \phi_s(x) \,\mathrm{d} B_x^{(a)} \right)^2 - \int_0^1 \phi_s(x)^2\, \mathrm{d} x \right) \nonumber \\[5pt] & = \sum_{s=1}^\infty \lambda_s \left( \left( \int_0^1 \phi_s(x) \,\mathrm{d} B_x^{(a)} \right)^2 - 1 \right) \quad\qquad \textrm{ (by orthonormality) } \nonumber \\[5pt] & \stackrel{D} = \sum_{s=1}^\infty \lambda_s \big( Z_{s, a}^2 - 1 \big) , \end{align*}
where
 $Z_{s, a} \stackrel{D} = \int_0^1 \phi_s(x) \,\mathrm{d} B_x$
. Note that by orthonormality
 $\{Z_{s, a}\}_{s \geq 1, a \in [c]}$
is a collection of i.i.d. N(0, 1) random variables. Hence, from Corollary 2 we obtain the following alternative expression of the limiting distribution of
 $\Gamma(H, G_n)$
:
 \begin{align} \Gamma(H, G_n) \stackrel{D}{\to} & \, \sqrt{\frac{c-1}{2c}} Z +\frac{1}{ 2 \sqrt{c}\, }\sum_{a=1}^{c-1} \sum_{s=1}^\infty \lambda_s \big( Z_{s, a}^2 - 1 \big) \nonumber \\[5pt] \stackrel{D} = & \, \sqrt{\frac{c-1}{2c}} Z +\frac{1}{ 2 \sqrt{c}\, } \sum_{s=1}^\infty \lambda_s \xi_s , \end{align}
where
 $\{\xi_s\}_{ s \geq 1}$
is a collection of i.i.d.
 $\chi^2_{c-1} - (c-1)$
random variables that are independent of
 $Z \sim N(0, \sigma^2)$
, with
 \begin{equation*} \sigma^2 = \sum_{\substack{1\leq a \neq b\leq |V(H)|\\ 1\leq a' \ne b'\leq |V(H)|}}t\left( H\bigotimes_{(a, b), (a', b')}H, W \right) - \|W_{H}\|^2 . \end{equation*}
This recovers the result in [Reference Bhattacharya and Mukherjee16, Theorem 1.3]. Interestingly, although the problem settings are different, distributions similar to (17) also appear as limits of subgraph counts and the largest eigenvalue in random graphs sampled from graphon models [Reference Bhattacharya, Chatterjee and Janson11, Reference Chatterjee and Huang25, Reference Hladký, Pelekis and Šileikis40]. Functional versions of these results for the dynamic Erdős–Rényi random graph have recently been obtained in [Reference Hazra, Kriukov and Mandjes37, Reference Hazra, Kriukov and Mandjes38].
Remark 6. It is also worth noting that the limiting distribution in (17) is always nondegenerate under our standing assumption
 $t(H, W) > 0$
. Specifically, the non-normal component of the limiting distribution (the second term in the right-hand side of (17)) is always nondegenerate when
 $t(H, W) > 0$
. This is because
 \begin{equation*} \mathrm{Var}\left(\sum_{s=1}^\infty \lambda_s \xi_s\right) = 2 (c-1) \sum_{s=1}^\infty \lambda_s^2 = 2 (c-1) \| W_H\|_2^2 = 0 \Longleftrightarrow W_H = 0 \quad \text{ almost everywhere}. \end{equation*}
Then averaging over
 $x, y \in [0, 1]$
in (12) gives
 $t(H, W) = 0$
, which is a contradiction. In particular, this shows that the limiting distribution of
 $\Gamma (H, G_n)$
always has a non-normal component. On the other hand, recalling the definition of the join from Definition 3, it is easy to see that the normal component vanishes (that is,
 $\sigma^2= 0$
) whenever the W is
 $\{0, 1\}$
-valued, that is, when the graphon is random-free [Reference Janson44, Section 10]. For example, this can be seen in the Erdős–Rényi model (Example 5 when
 $p \in \{0, 1\}$
), or, more generally, in the correlated stochastic block model (SBM), as in Example 7 when
 $p_{ab} \in \{0, 1\}$
.
Remark 7. In this paper we considered the case where the number of colors
 $c \geq 2$
is fixed. Another interesting regime is where
 $c=c_n \rightarrow \infty$
such that the expectation of
 $T(H, G_n)$
is O(1). In this case we get Poisson-type limiting distributions for
 $T(H, G_n)$
(see [Reference Barbour, Holst and Janson4, Theorem 5.G] and [Reference Bhattacharya, Diaconis and Mukherjee13, Theorem 1.1] for
 $H=K_2$
and [Reference Bhattacharya, Mukherjee and Mukherjee17] for general graphs H). A version of this result for multiplex hypergraphs has been obtained in the recent paper [Reference Xie and Bhattacharya86], where the limiting law is described by jointly dependent Poisson distributions.
1.3. Asymptotic notation
Throughout the paper we will use the following asymptotic notation. For two sequences
 $a_n$
and
 $b_n$
we say
 $a_n \lesssim b_n$
if for all n large enough
 $a_n \leq C b_n$
, for some constant
 $C > 0$
. Similarly,
 $a_n \gtrsim b_n$
means
 $a_n \geq C b_n$
, for n large enough and some constant
 $C > 0$
. Subscripts in the above notation, for example
 $\lesssim_{\square}$
and
 $\gtrsim_{\square}$
, denote that the hidden constants may depend on the subscripted parameters.
2. A general invariance principle
For each
 $v \in [n]$
and
 $a\in [c]$
, let
 \begin{align} \tilde{X}_{v ,a} = \sqrt{c}\bigg( \textbf{1}\{X_v=a\}-\frac{1}{c}\bigg).\end{align}
Let
 $\{Z_{v, a}\}_{v\in [n],a\in [c]}$
be a collection of i.i.d. N(0,1) and define
 \begin{align} \tilde{Z}_{v,a}\;:\!=\; Z_{v,a} - \frac{1}{c}\sum_{a=1}^c Z_{v,a} .\end{align}
We collect some easy facts about the random variables
 $\{\tilde{X}_{v, a}\}_{v\in [n],a\in [c]}$
and
 $\{\tilde{Z}_{v, a}\}_{v\in [n],a\in [c]}$
in the following observation.
Observation 1. Let
 $\{\tilde{X}_{v, a}\}_{v\in [n],a\in [c]}$
and
 $\{\tilde{Z}_{v, a}\}_{v\in [n],a\in [c]}$
be as defined above. Then the following statements hold:
-
(a)
$\mathrm{E} \tilde{X}_{v,a} = \mathrm{E} \tilde{Z}_{v,a} = 0$
, for
$v\in [n],a\in [c]$
; -
(b)
$\textrm{Var}(\tilde{X}_{v,a}) = \textrm{Var}(\tilde{Z}_{v,a}) = 1-\frac{1}{c}$
, for
$v\in [n],a\in [c]$
; -
(c)
$\mathrm{Cov}(\tilde{X}_{v,a},\tilde{X}_{v,b}) = \mathrm{Cov}(\tilde{Z}_{v,a},\tilde{Z}_{v,b}) = -\frac{1}{c}$
, for
$v\in [n]$
and
$a \ne b \in [c]$
; -
(d)
$\{\tilde{X}_{u,a}\}_{a\in [c]} \perp \{\tilde{X}_{v,a}\}_{a\in [c]}$
and
$\{\tilde{Z}_{u,a}\}_{a\in [c]} \perp \{\tilde{Z}_{v,a}\}_{a\in [c]}$
, for
$u \ne v \in [n]$
.


Hereafter, denote
 \begin{align*} \mathbf{X}&=(X_{v,a})_{v\in [n],a\in [c]},\\[5pt] \tilde{\mathbf{X}}&=(\tilde{X}_{v,a})_{v\in [n],a\in [c]},\\[5pt] \mathbf{Z}&=(Z_{v,a})_{v\in [n],a\in [c]},\\[5pt] \tilde{\mathbf{Z}}&=(\tilde{Z}_{v,a})_{v\in [n],a\in [c]}.\end{align*}
Fix an integer
 $r\geq 0$
. Then for a function
 $f\;:\;[n]_r \rightarrow \mathbb{R}$
, define
 \begin{align} \mathcal{T}(f;\; \tilde{\mathbf{X}}) \;:\!=\; \frac{1}{n^{\frac{r}{2}}\sqrt{c}\,}\sum_{a=1}^{c}\sum_{\mathbf{s}\in [n]_{r}}f(\mathbf{s})\prod_{j=1}^{r} \tilde{X}_{s_j, a} .\end{align}
Define
 $\mathcal{T}(f;\; \mathbf{X})$
and
 $\mathcal{T}(f;\; \tilde{\mathbf{Z}})$
similarly. Let
 $\mathcal{S}_r$
denote the set of all permutations of the set [r]. Then define the symmetrization of f as follows:
 \begin{align*} \tilde{f} (s_1,\ldots s_r)=\frac{1}{r!}\sum_{\sigma \in \mathcal{S}_r} f(s_{\sigma(1)},\ldots, s_{\sigma(r)}) .\end{align*}
For functions
 $f,f'\;:\;[n]_{r}\rightarrow \mathbb{R}$
, their inner product is defined as
 \begin{align*} \langle f,f'\rangle \;:\!=\; \frac{1}{n^r}\sum_{\mathbf{s}\in [n]_{r}}f(\mathbf{s})f'(\mathbf{s}) .\end{align*}
and let
 $\|f\|\;:\!=\;\sqrt{\langle f,f\rangle}$
be the associated norm. For
 $\mathbf{s} \in [n]_{r}$
, let
 $\underline{\mathbf{s}}$
denote the (unordered) set formed by the entries of
 $\mathbf{s}$
. (For example, if
 $\mathbf{s} = (4, 2, 5)$
then
 $\underline{\mathbf{s}} = \{2, 4, 5\}$
.) Note that
 \begin{align} \langle\tilde{f},\tilde{f}'\rangle = & \langle\tilde{f},f'\rangle = \langle f,\tilde{f}'\rangle = \frac{1}{n^r}\frac{1}{r!}\sum_{\substack{\mathbf{s}, \mathbf{s}' \in [n]_{r} \\ \underline{\mathbf{s}}=\underline{\mathbf{s}}'}} f(\mathbf{s})f'(\mathbf{s}') .\end{align}
We can then define the following bilinear operation:
 \begin{align*} \langle f,f'\rangle_{\bullet} \;:\!=\; \langle f,\tilde{f}'\rangle .\end{align*}
Lemma 1. Fix integers
 $r, r' \geq 1$
. Then for functions
 $f\;:\;[n]_{r}\rightarrow \mathbb{R}$
and
 $f'\;:\;[n]_{r'}\rightarrow \mathbb{R}$
, the following statements hold.
-
• If
$r\neq r'$
then (22)
\begin{align} \mathrm{Cov}( \mathcal{T}(f,\tilde{\mathbf{X}}),\mathcal{T}(f',\tilde{\mathbf{X}}) ) =0 . \end{align}
-
• If
$r=r'$
then where
\begin{align*} \mathrm{Cov}( \mathcal{T}(f,\tilde{\mathbf{X}}),\mathcal{T}(f',\tilde{\mathbf{X}}) ) = \mathrm{E} ( \mathcal{T}(f,\tilde{\mathbf{X}}) \mathcal{T}(f',\tilde{\mathbf{X}}) ) =\eta \cdot r!\,\langle f,f'\rangle_{\bullet} , \end{align*}
$\eta\;:\!=\; \left(1-\frac{1}{c}\right)^r+(c-1)\left(-\frac{1}{c}\right)^r$
.


The same holds for
 $\mathrm{Cov} ( \mathcal{T}(f,\tilde{\mathbf{Z}}),\mathcal{T}(f',\tilde{\mathbf{Z}}) )$
.
Proof. Note that for any
 $\mathbf{s} \in [n]_{r}$
and
 $a \in [c]$
,
 $\mathrm{E}(\prod_{j = 1}^r \tilde{X}_{s_j, a}) = 0$
. This implies
 $\mathrm{E}(\mathcal{T}(f,\tilde{\mathbf{X}})) = 0$
(recall (20)). Hence,
 \begin{align} \mathrm{Cov}( \mathcal{T}(f,\tilde{\mathbf{X}}),\mathcal{T}(f',\tilde{\mathbf{X}}) ) & = \mathrm{E} ( \mathcal{T}(f,\tilde{\mathbf{X}}) \mathcal{T}(f',\tilde{\mathbf{X}}) ) \nonumber \\[5pt] & =\frac{1}{n^{\frac{r+r'}{2}}c}\sum_{a,a'\in [c]} \sum_{\substack{\mathbf{s} \in [n]_{r} \mathbf{s}'\in [n]_{r'}}}f(\mathbf{s})f'(\mathbf{s}')\mathrm{E}\left(\prod_{j\in \underline{\mathbf{s}}}\tilde{X}_{s_j,a}\prod_{j\in \underline{\mathbf{s}}'}\tilde{X}_{s_j' ,a'} \right)\!, \end{align}
where
 $\mathbf{s} = (s_1, s_2, \ldots, s_r)$
and
 $\mathbf{s}' = (s_1', s_2', \ldots, s_{r'}')$
, for
 $\mathbf{s} \in [n]_{r}$
and
 $\mathbf{s}'\in [n]_{r'}$
. Observe that if
 $\mathbf{s} \ne \mathbf{s'}$
(that is, either
 $\underline{\mathbf{s}} \backslash \underline{\mathbf{s}}'$
or
 $\underline{\mathbf{s}}' \backslash \underline{\mathbf{s}}$
is nonempty), then
 \begin{equation*} \mathrm{E}\left(\prod_{j\in \underline{\mathbf{s}}}\tilde{X}_{s_j,a}\prod_{j\in \underline{\mathbf{s}}'}\tilde{X}_{s_j' ,a'} \right) = 0. \end{equation*}
To begin with, suppose
 $r\neq r'$
. Then
 $\mathbf{s} \ne \mathbf{s}$
′, for any
 $\mathbf{s} \in [n]_{r}$
and
 $\mathbf{s}'\in [n]_{r'}$
. Hence, in this case all the terms in (23) are zero, and the result in (22) follows.
Now suppose
 $r=r'$
and
 $\mathbf{s}, \mathbf{s}' \in [n]_{r}$
is such that
 $\underline{\mathbf{s}}=\underline{\mathbf{s}}'$
. Then
 \begin{align*} \frac{1}{c}\sum_{a,a'\in [c]}\mathrm{E}\left(\prod_{j\in \underline{\mathbf{s}}}\tilde{X}_{s_j, a}\prod_{j\in \underline{\mathbf{s}}'}\tilde{X}_{s_j, a'}\right) & =\frac{1}{c}\sum_{a,a'\in [c]}\mathrm{E}\left(\prod_{j\in \underline{\mathbf{s}}}\tilde{X}_{s_j, a}\tilde{X}_{s_j, a'}\right) \\[5pt] & =\frac{1}{c}\sum_{a\in [c]}\mathrm{E}\left(\prod_{j\in \underline{\mathbf{s}}}\tilde{X}_{s_j, a}^2\right) + \frac{1}{c}\sum_{ a \ne a'\in [c] }\mathrm{E}\left(\prod_{j\in \underline{\mathbf{s}}}\tilde{X}_{s_j, a}\tilde{X}_{s_j, a'}\right) \\[5pt] & =\bigg( 1-\frac{1}{c}\bigg)^r +(c-1)\bigg( -\frac{1}{c}\bigg)^r = \eta . \end{align*}
Hence, from (23),
 \begin{align*} \mathrm{Cov}( \mathcal{T}(f,\tilde{\mathbf{X}}),\mathcal{T}(f',\tilde{\mathbf{X}}) ) & =\frac{1}{n^r c}\sum_{a,a'\in [c]} \sum_{\substack{ \mathbf{s} \in [n]_{r}, \mathbf{s}'\in [n]_{r} \\ \underline{\mathbf{s}}=\underline{\mathbf{s}}'}}f(\mathbf{s})f'(\mathbf{s}')\mathrm{E}\left(\prod_{j\in \underline{\mathbf{s}}}\tilde{X}_{s_j, a}\prod_{j\in \underline{\mathbf{s}}'}\tilde{X}_{s_j, a'} \right)\\[5pt] & =\eta \cdot \frac{1}{n^r}\sum_{\substack{ \mathbf{s} \in [n]_{r}, \mathbf{s}' \in [n]_{r'} \\ \underline{\mathbf{s}}=\underline{\mathbf{s}}'}}f( \mathbf{s} ) f'( \mathbf{s}') \\[5pt] & =\eta \cdot r!\,\langle f,f'\rangle_{\bullet} , \end{align*}
where the last step uses (21).
Next, we show that
 $\mathcal{T}(\cdot;\; \tilde{\mathbf{X}}) $
satisfies an invariance principle. Specifically, we show that the moments of
 $\mathcal{T}(\cdot;\; \tilde{\mathbf{X}}) $
and
 $\mathcal{T}(\cdot;\; \tilde{\mathbf{Z}}) $
are asymptotically close, for any finite collection of bounded functions. This result falls within the purview of universality/invariance principles for random multilinear forms (see, for example, [Reference Chatterjee26, Reference Mossel, O’Donnell and Oleszkiewicz63, Reference Nourdin, Peccati and Reinert68, Reference Rotar80]).
Proposition 1. Fix
 $K \geq 1$
and
 $r \geq 0$
. Let
 $\{f_{n}\}_{n \geq 1}$
be sequence of functions such that
 $f_{n}\;:\;[n]_{r}\rightarrow [\!-M, M]$
, for some
 $M > 0$
. Then
 \begin{align} \lim_{n\rightarrow\infty}\big| \mathrm{E} \big( \mathcal{T} ( f_{n} ;\; \tilde{\mathbf{X}} )^K \big)- \mathrm{E} \big(\mathcal{T} ( f_{n};\; \tilde{\mathbf{Z}} )^K \big) \big| = 0 . \end{align}
Proof. For notational convenience, denote
 $$\Delta_{n, K}\;:\!=\; \big| \mathrm{E} \big( \mathcal{T} ( f_{n} ;\; \tilde{\mathbf{X}} )^K \big)- \mathrm{E} \big(\mathcal{T} ( f_{n};\; \tilde{\mathbf{Z}} )^K \big) \big|.$$
Note that
 \begin{align*} \Delta_{n, K} & =\frac{1}{n^{\frac{K r}{2}} c^{\frac{K}{2}}}\left| \sum_{\mathbf{a}\in [c]^K}\sum_{\substack{ \mathbf{s}^{(1)}, \ldots, \mathbf{s}^{(K)} \\ \mathbf{s}^{(k)}\in [n]_{r} }} \prod_{k = 1}^{K}f_{n}(\mathbf{s}^{(k)}) \left\{ \mathrm{E} \left(\prod_{k = 1}^{K}\prod_{j\in [n]_{r}}\tilde{X}_{s^{(k)}_j,a_k}\right) - \mathrm{E}\left( \prod_{k = 1}^{K}\prod_{j\in [n]_{r}}\tilde{Z}_{s^{(k)}_j,a_k}\right) \right\} \right| , \end{align*}
where
 $\mathbf{a} = (a_1, a_2, \ldots, a_K) \in [c]^K$
and
 $\mathbf{s}^{(k)} = (s_1^{(k)}, s_2^{(k)}, \ldots, s_{r}^{(k)}) \in [n]_{r}$
, for
 $1 \leq k \leq K$
. Using the fact that
 $|f_n| \leq M$
gives
 \begin{align} \Delta_{n, K} & \leq \frac{M^K}{n^{\frac{K r}{2}}c^{\frac{K}{2}}} \sum_{\mathbf{a}\in [c]^K} \sum_{\substack{ \mathbf{s}^{(1)}, \ldots, \mathbf{s}^{(K)} \\ \mathbf{s}^{(k)}\in [n]_{r} }} \left|\mathrm{E} \left(\prod_{k = 1}^{K}\prod_{j\in [n]_{r}}\tilde{X}_{s^{(k)}_j,a_k}\right) - \mathrm{E}\left( \prod_{k = 1}^{K}\prod_{j\in [n]_{r}}\tilde{Z}_{s^{(k)}_j,a_k}\right) \right| . \end{align}
Given
 $\mathbf{a} \in [c]^K$
and
 $\mathbf{S} \;:\!=\; (\mathbf{s}^{(1)},\ldots, \mathbf{s}^{(K)})$
, such that
 $\mathbf{s}^{(k)} \in [n]_{r}$
, for
 $1 \leq k \leq K$
, define the edge-colored multihypergraph
 $F_{\mathbf{S}, \mathbf{a}} = (V(F_{\mathbf{S}, \mathbf{a}}), E(F_{\mathbf{S}, \mathbf{a}}))$
as follows:
 \begin{equation*} V(F_{\mathbf{S}, \mathbf{a}}) \;:\!=\; \bigcup_{k=1}^K \underline{\mathbf{s}}^{(k)} \quad \text{and} \quad E(F_{\mathbf{S}, \mathbf{a}} ) \;:\!=\; \big\{\underline{\mathbf{s}}^{(1)}, \ldots, \underline{\mathbf{s}}^{(K)}\big\}, \end{equation*}
and the color of the hyperedge
 $\underline{\mathbf{s}}^{(k)}$
is
 $a_k$
, for
 $1 \leq k \leq K$
. Note that the hyperedges in
 $\mathbf{s}^{(1)},\ldots, \mathbf{s}^{(K)}$
can be repeated, so
 $E(F_{\mathbf{S}_K, \mathbf{a}} )$
is a multiset and
 $F_{\mathbf{S}, \mathbf{a}}$
is a multihypergraph. In addition, define
 \begin{equation*} \tilde{\mathbf{X}}_{F_{\mathbf{S}, \mathbf{a}}} \;:\!=\; \prod_{k = 1}^{K}\prod_{j\in [n]_{r}}\tilde{X}_{s^{(k)}_j,a_k} \quad \text{and} \quad \tilde{\mathbf{Z}}_{F_{\mathbf{S}, \mathbf{a}}} \;:\!=\; \prod_{k = 1}^{K}\prod_{j\in [n]_{r}}\tilde{Z}_{s^{(k)}_j,a_k} . \end{equation*}
The following lemma records two crucial properties of
 $\mathrm{E} \tilde{\mathbf{X}}_{F_{\mathbf{S}, \mathbf{a}}}$
and
 $\mathrm{E} \tilde{\mathbf{Z}}_{F_{\mathbf{S}, \mathbf{a}}}$
.
Lemma 2. Denote by
 $d_j$
the degree of vertex
 $j \in V(F_{\mathbf{S}, \mathbf{a}})$
. Then the following statements hold.
-
• If there exists
$j \in V(F_{\mathbf{S}, \mathbf{a}})$
such that
$d_j = 1$
then
$$\mathrm{E} \tilde{\mathbf{X}}_{F_{\mathbf{S}, \mathbf{a}}} = \mathrm{E} \tilde{\mathbf{Z}}_{F_{\mathbf{S}, \mathbf{a}}} = 0.$$
-
• If
$d_j = 2$
, for all
$j \in V(F_{\mathbf{S}, \mathbf{a}})$
then
$$\mathrm{E} \tilde{\mathbf{X}}_{F_{\mathbf{S}, \mathbf{a}}} = \mathrm{E} \tilde{\mathbf{Z}}_{F_{\mathbf{S}, \mathbf{a}}} .$$


Proof. Note that
 \begin{align} \mathrm{E} \tilde{\mathbf{X}}_{F_{\mathbf{S}, \mathbf{a}}} = \mathrm{E}\left( \prod_{j\in V(F_{\mathbf{S}, \mathbf{a}})}\prod_{a=1}^c \tilde{X}_{j,a}^{\ell_{j,a}} \right)= \prod_{j\in V(F_{\mathbf{S}, \mathbf{a}})} \mathrm{E}\left( \prod_{a=1}^c \tilde{X}_{j,a}^{\ell_{j,a}} \right)\!, \end{align}
where
 $\ell_{j,a}$
be the number of hyperedges with color
 $a \in [c]$
containing the vertex
 $j \in V(F_{\mathbf{S}, \mathbf{a}})$
.
Now, if
 $j \in V(F_{\mathbf{S}, \mathbf{a}})$
is such that
 $d_j = 1$
then there exists
 $b \in [c]$
such that
 $\ell_{j,b} =1$
and
 $\ell_{j,a} =0 $
, for all
 $a \in [c]\backslash{b}$
. This means that
 \begin{equation*} \mathrm{E}\left(\prod_{a=1}^c \tilde{X}_{j,a}^{\ell_{j,a}} \right) = \mathrm{E} \tilde{X}_{j,b} = 0 \end{equation*}
and, consequently,
 $\mathrm{E} \tilde{\mathbf{X}}_{F_{\mathbf{S}, \mathbf{a}}} = 0$
. By the same argument, we also have
 $\mathrm{E} \tilde{\mathbf{Z}}_{F_{\mathbf{S}, \mathbf{a}}} = 0$
.
Next, suppose
 $d_j = 2$
for all
 $j \in V(F_{\mathbf{S}, \mathbf{a}})$
. Then there are two possibilities.
-
• There exists
$b \in [c]$
such that
$\ell_{j,b} =2$
and
$\ell_{j,a} =0 $
, for all
$a \in [c]\backslash\{b\}$
. This means that by Observation 1. By the same argument,
\begin{equation*} \mathrm{E}\left(\prod_{a=1}^c \tilde{X}_{j,a}^{\ell_{j,a}} \right) = \mathrm{E} \tilde{X}_{j,b}^2 = 1-\frac{1}{c} , \end{equation*}
\begin{equation*} \mathrm{E}\left(\prod_{a=1}^c \tilde{Z}_{j,a}^{\ell_{j,a}} \right) = \mathrm{E} \tilde{Z}_{j,b}^2 = 1-\frac{1}{c}. \end{equation*}
-
• There exists
$b \ne b' \in [c]$
such that
$\ell_{j,b} = \ell_{j,b'} = 1$
and
$\ell_{j,a} =0 $
, for all
$a \in [c]\backslash\{ b, b' \}$
. This means that by Observation 1. By the same argument,
\begin{equation*} \mathrm{E}\left(\prod_{a=1}^c \tilde{X}_{j,a}^{\ell_{j,a}} \right) = \mathrm{E} \tilde{X}_{j,b} \tilde{X}_{j,b'} = -\frac{1}{c}, \end{equation*}
\begin{equation*} \mathrm{E}\left(\prod_{a=1}^c \tilde{Z}_{j,a}^{\ell_{j,a}} \right) = \mathrm{E} \tilde{Z}_{j,b} \tilde{Z}_{j,b'} = -\frac{1}{c}. \end{equation*}


Hence, if
 $d_j = 2$
then
 \begin{align*} \mathrm{E}\left(\prod_{a=1}^c \tilde{X}_{j,a}^{\ell_{j,a}} \right) = \mathrm{E}\left(\prod_{a=1}^c \tilde{Z}_{j,a}^{\ell_{j,a}} \right)\!. \end{align*}
Hence, taking product over
 $j \in V(F_{\mathbf{S}, \mathbf{a}})$
(recall (26)) gives
 $\mathrm{E} \tilde{\mathbf{X}}_{F_{\mathbf{S}, \mathbf{a}}} = \mathrm{E} \tilde{\mathbf{Z}}_{F_{\mathbf{S}, \mathbf{a}}} $
.
The next lemma gives bounds on
 $\mathrm{E} \tilde{\mathbf{X}}_{F_{\mathbf{S}, \mathbf{a}}}$
and
 $\mathrm{E} \tilde{\mathbf{Z}}_{F_{\mathbf{S}, \mathbf{a}}}$
.
Lemma 3. For any
 $\mathbf{a} = (a_1, a_2, \ldots, a_K) \in [c]^K$
and
 $\mathbf{S} = (\mathbf{s}^{(1)},\ldots, \mathbf{s}^{(K)})$
, with
 $\mathbf{s}^{(k)} \in [n]_{r}$
, for
 $1 \leq k \leq K$
, we have
 \begin{align} \mathrm{E} \tilde{\mathbf{X}}_{F_{\mathbf{S}, \mathbf{a}}} & \lesssim_{K, c, r} 1 . \end{align}
Moreover,
 $ \mathrm{E} \tilde{\mathbf{Z}}_{F_{\mathbf{S}, \mathbf{a}}} \lesssim_{K, c, r} 1$
.
Proof. Note that for each
 $j \in V(F_{\mathbf{S}, \mathbf{a}})$
,
 \begin{align} \left|\mathrm{E}\left( \prod_{a=1}^c \tilde{X}_{j,a}^{\ell_{j,a}} \right)\right| & = c^{\frac{1}{2} \sum_{a =1}^{c} \ell_{j, a}} \left| \mathrm{E} \prod_{a =1}^c \left( \textbf{1} \{X_{j}=a\}-\frac{1}{c}\right)^{\ell_{j, a}} \right| \lesssim_{K, c, r} 1 . \end{align}
Hence, from (26),
 $|\mathrm{E} \tilde{\mathbf{X}}_{F_{\mathbf{S}, \mathbf{a}}} | \lesssim_{K, c, r} 1$
. This proves (27).
Next, we bound
 $\mathrm{E} \tilde{\mathbf{Z}}_{F_{\mathbf{S}, \mathbf{a}}}$
. First, observe that for each
 $j \in V(F_{\mathbf{S}, \mathbf{a}})$
,
 \begin{align} \left|\mathrm{E}\left( \prod_{a=1}^c \tilde{Z}_{j,a}^{\ell_{j,a}} \right)\right| & \leq \mathrm{E} \prod_{a =1}^{c} \left| Z_{j, a} - \frac{1}{c} \sum_{b=1}^c Z_{j, b} \right| ^{\ell_{j, a}} \lesssim_{K, c, r} 1. \end{align}
This implies that
 \begin{align*} | \mathrm{E} \tilde{\mathbf{Z}}_{F_{\mathbf{S}, \mathbf{a}}} | = \left| \mathrm{E}\left( \prod_{j\in V(F_{\mathbf{S}, \mathbf{a}})}\prod_{a=1}^c \tilde{Z}_{j,a}^{\ell_{j,a}} \right) \right| = \prod_{j\in V(F_{\mathbf{S}, \mathbf{a}})} \left| \mathrm{E}\left( \prod_{a=1}^c \tilde{Z}_{j,a}^{\ell_{j,a}} \right) \right| \lesssim_{K, c, r} 1 , \end{align*}
since
 $|V(F_{\mathbf{S}, \mathbf{a}})| \leq K r$
. This completes the proof of Lemma 3.
Now let
 $\mathcal{F}$
be the set of colored hypergraphs with the following properties:
-
•
$F \in \mathcal{F}$
is a hypergraph with vertex set contained in [Kr] and K hyperedges, and every hyperedge of F is assigned a color from [K]; -
• all vertices of F have degree at least 2; and
-
• some vertex of F has degree at least 3.

Note that for
 $F \in \mathcal{F}$
there are
 $O(n^{|V(F)|})$
terms in the joint sum (25) such that
 $F_{\mathbf{S}, \mathbf{a}}$
is isomorphic (as a colored hypergraph) to F. In such case,
 $\mathrm{E}\tilde{\mathbf{X}}_{F}=\mathrm{E}\tilde{\mathbf{X}}_{F_{\mathbf{S}, \mathbf{a}}}$
and
 $\mathrm{E}\tilde{\mathbf{Z}}_{F}=\mathrm{E}\tilde{\mathbf{Z}}_{F_{\mathbf{S}, \mathbf{a}}}$
. This implies, from (25) and Lemma 2, that
 \begin{align} \Delta_{n, K} & \lesssim_{M, K, c} \frac{1}{n^{\frac{Kr}{2}}} \sum_{F \in \mathcal{F}} n^{|V(F)|} | \mathrm{E} \tilde{\mathbf{X}}_{F} - \mathrm{E} \tilde{\mathbf{Z}}_{F} |\nonumber \\[5pt] & \lesssim_{M, K, c} \sum_{F \in \mathcal{F}}n^{ |V(F)| -\frac{Kr}{2}} . \end{align}
Note that
 $Kr=\sum_{e\in E(F)}|e|$
. In addition, for
 $F \in \mathcal{F}$
, we have that
 $d_j \geq 2$
for all
 $j\in V(F)$
with strict inequality for some j. Therefore,
 \begin{align*} \frac{Kr }{2} = \frac{1}{2}\sum_{e\in E(F)}|e|=\frac{1}{2}\sum_{j\in V(F)} d_j > |V(F)|. \end{align*}
Hence, each term in (30) is o(1). Since
 $|\mathcal{F}| \lesssim_{K, c, r} 1$
, the result in Proposition 1 now follows.
3. Proof of Theorem 1
Recall the definition of
 $T(H,G_n)$
from (2), which is the number of monochromatic copies of H in
 $G_n$
:
 \begin{align} T(H,G_n)= \frac{1}{|{\textrm{Aut}}(H)|}\sum_{\mathbf{s}\in [n]_{|V(H)|}}\prod_{(a,b)\in E(H)}a_{s_as_b}(G_n)\textbf{1}\{X_{=\mathbf{s}}\} .\end{align}
We begin by rewriting
 $T(H,G_n)$
in terms of
 $\mathcal{T}(\cdot,\tilde{\mathbf{X}})$
. To this end, we set
 $V(H) = [|V(H)|]\;:\!=\; \{1, 2, \ldots, |V(H)|\}$
. In addition, for
 $J=\{i_1<\cdots < i_{|J|}\}\subseteq [|V(H)|]$
and
 $\mathbf{s} \in [n]_{|V(H)|}$
, denote
 $\mathbf{s}_J = (s_{i_1},\ldots, s_{i_{|J|}})$
.
Lemma 4. For
 $J=\{i_1<\cdots < i_{|J|}\}\subseteq [|V(H)|]$
, define
 $f_{H, J}^{G_n}\;:\;[n]_{|J|}\rightarrow [0,1]$
as follows:
 \begin{align} f_{H, J}^{G_n}(\mathbf{t})\;:\!=\;\frac{1}{n^{|V(H)|-|J|}}\sum_{\substack{\mathbf{s}\in [n]_{|V(H)|} \\ \mathbf{s}_J=\mathbf{t}}}\prod_{(a,b)\in E(H)}a_{\mathbf{s}_a \mathbf{s}_b}(G_n) . \end{align}
Then
 \begin{align} T(H,G_n)-\mathrm{E}(T(H,G_n))= \frac{1}{|{\mathrm{Aut}}(H)|}\sum_{\substack{J\subseteq V(H)\\ |J|\geq 2}}\mathcal{T}\Big( f_{H, J}^{G_n};\; \tilde{\mathbf{X}} \Big) \frac{n^{|V(H)|-\frac{|J|}{2}}}{c^{|V(H)|-\frac{|J|}{2}-\frac{1}{2}}} . \end{align}
Proof. Note that
 \begin{align} \textbf{1}\{X_{=\mathbf{s}}\} & = \sum_{a=1}^c \prod_{j=1}^{|V(H)|} \textbf{1}\{X_{s_j}=a\} \nonumber \\[3pt] & = \sum_{a=1}^c \prod_{j=1}^{|V(H)|}\bigg( \textbf{1}\{X_{s_j}=a\} -\frac{1}{c}+\frac{1}{c}\bigg) \nonumber \\[3pt] & = \sum_{a=1}^c \sum_{J\subseteq V(H)}\prod_{j\in J}\bigg( \textbf{1}\{X_{s_j}=a\} -\frac{1}{c}\bigg) \frac{1}{c^{|V(H)|-|J|}} \nonumber \\[3pt] & = \sum_{a=1}^c \sum_{J\subseteq V(H)}\prod_{j\in J} \tilde{X}_{s_j, a}\frac{1}{c^{|V(H)|-\frac{|J|}{2}}} . \end{align}
Then, recalling (20), we have
 \begin{align} \mathcal{T}\Big(f_{H, J}^{G_n};\; \tilde{\mathbf{X}}\Big) & = \frac{1}{n^{|V(H)| - \frac{|J|}{2}}\sqrt{c}\,}\sum_{a=1}^{c}\sum_{\mathbf{t}\in [n]_{|J|}} \sum_{\substack{\mathbf{s}\in [n]_{|V(H)|} \\ \mathbf{s}_J=\mathbf{t}}}\prod_{(a,b)\in E(H)}a_{\mathbf{s}_a \mathbf{s}_b}(G_n) \prod_{j \in J} \tilde{X}_{t_j, a} \nonumber \\[3pt] & = \frac{1}{n^{|V(H)| - \frac{|J|}{2}}\sqrt{c}\,}\sum_{a=1}^{c} \sum_{\mathbf{s}\in [n]_{|V(H)|} } \prod_{(a,b)\in E(H)}a_{\mathbf{s}_a \mathbf{s}_b}(G_n) \prod_{j \in J} \tilde{X}_{s_j, a} . \end{align}
Hence,
 \begin{align} & \frac{1}{|{\textrm{Aut}}(H)|}\sum_{J\subseteq V(H)} \mathcal{T}\left( f_{H, J}^{G_n};\; \tilde{\mathbf{X}} \right) \frac{n^{|V(H)|-\frac{|J|}{2}}}{c^{|V(H)|-\frac{|J|}{2}-\frac{1}{2}}} \nonumber \\[3pt] & = \frac{1}{|{\textrm{Aut}}(H)|}\sum_{J\subseteq V(H)} \sum_{a=1}^{c} \sum_{\mathbf{s}\in [n]_{|V(H)|} } \prod_{(a,b)\in E(H)}a_{\mathbf{s}_a \mathbf{s}_b}(G_n) \prod_{j \in J} \tilde{X}_{s_j, a} \frac{1}{c^{|V(H)|-\frac{|J|}{2}}} \nonumber \\[3pt] & = \frac{1}{|{\textrm{Aut}}(H)|} \sum_{\mathbf{s}\in [n]_{|V(H)|} } \prod_{(a,b)\in E(H)}a_{\mathbf{s}_a \mathbf{s}_b}(G_n) \textbf{1}\{X_{=\mathbf{s}}\} , \end{align}
where the last step uses (34).
Now observe that, if
 $J=\{j_0\}$
, for some
 $j_0 \in V(H)$
,
 \begin{align*} \sum_{a=1}^c\prod_{j\in J}\left( \textbf{1}\{X_{s_j}=a\} -\frac{1}{c}\right)=\sum_{a=1}^c\left( \textbf{1}\{X_{s_{j_0}}=a\} -\frac{1}{c}\right)=0. \end{align*}
This means (recall (35)) that
 \begin{equation} \sum_{\substack{J\subseteq V(H)\\ |J|= 1}}\mathcal{T}\left( f_{H, J}^{G_n};\; \tilde{\mathbf{X}} \right) = 0. \end{equation}
In addition, note that when
 $J = \emptyset$
,
 \begin{equation} \frac{1}{|{\textrm{Aut}}(H)|} \mathcal{T}\left( f_{H,\emptyset}^{G_n};\; \tilde{\mathbf{X}} \right) \frac{n^{|V(H)|}}{c^{|V(H)|-\frac{1}{2}}} = \mathrm{E}(T(H,G_n)) . \end{equation}
Combining (36), (37), and (38) and rearranging the sums, the result in Lemma 4 follows.
Now let
 $\{U_r\}_{r\in V(H)}$
be a collection of i.i.d. uniform random variables on [0,Reference Abraham, Delmas and Weibel1]. Define the counterpart of
 $W_H$
for finite n as follows:
 \begin{equation} \tilde{W}^{G_n}_{H}(x,y) \;:\!=\; \sum_{1\leq u\neq v\leq |V(H)|} \mathrm{E}\left(\textbf{1}\{A_n\}\prod_{(i, j)\in E(H)}W^{G_n}(U_i, U_j)\, \middle|\, U_u = x, U_v = y\right)\!,\end{equation}
where
 $A_n$
is the event that the variables
 $\{U_r\}_{r\in V(H)}$
fall in distinct intervals when [0, 1] is partitioned in a grid of size
 $\frac{1}{n}$
, that is,
 $A_n=\{(\lceil nU_r \rceil)_{r\in V(H)}\in [n]_{|V(H)|}\}$
. (We show in Lemma 5 that
 $\tilde{W}^{G_n}_{H}$
is directly related to
 $f_{H,J}^{G_n}$
, which is a sum over distinct indices; see (32). This set of distinct indices gets translated to the event
 $A_n$
in (39).) Then we define
 \begin{align} Q(H, G_n) & \;:\!=\; \frac{1}{ 2 n\sqrt{c}\,}\sum_{a=1}^c \sum_{1 \leq u \ne v \leq n} \tilde{W}^{G_n}_{H}\left(\frac{u}{n},\frac{v}{n}\right) \tilde{Z}_{u, a} \tilde{Z}_{v, a} , \end{align}
where
 $\{\tilde{Z}_{v, a}\}_{v \in [n], a \in [c]}$
is defined in (19).
Lemma 5. Let
 $\Gamma(H,G_n)$
and
 $Q(H, G_n)$
be as defined in (11) and (40), respectively. Then
 \begin{align} Q(H, G_n) = \mathcal{T}\left( \sum_{\substack{J\subseteq V(H) \\ |J|= 2}} f_{H, J}^{G_n};\; \tilde{\mathbf{Z}} \right)\!. \end{align}
In addition, as
 $n \rightarrow \infty$
,
 \begin{align} \Gamma(H,G_n) & = \mathcal{T}\left( \sum_{\substack{J\subseteq V(H) \\ |J|= 2}} f_{H, J}^{G_n};\; \tilde{\mathbf{X}} \right) + o_{L_2}(1) . \end{align}
Proof. Recalling (32) and (39), we obtain, for
 $1 \leq i \ne j \leq n$
,
 \begin{align*} \sum_{\substack{J\subseteq V(H) \\ |J|= 2}} f_{H, J}^{G_n}(i, j) =\frac{1}{n^{|V(H)|-2}}\sum_{1 \leq u < v\leq |V(H)|}\sum_{\substack{\mathbf{s}\in [n]_{|V(H)|}\\ s_u=i,\ s_v=j } }\prod_{(a,b)\in E(H)}a_{\mathbf{s}_a \mathbf{s}_b}(G_n) & = \frac{1}{2}\tilde{W}^{G_n}_{H}\left( x,y \right)\!, \end{align*}
for
 $x\in [\frac{i}{n},\frac{i+1}{n}]$
and
 $y\in [\frac{j}{n},\frac{j+1}{n}]$
. Therefore,
 \begin{align*} \mathcal{T}\left( \sum_{\substack{J\subseteq V(H) \\[5pt] |J|= 2}} f_{H, J}^{G_n} ; \tilde{\mathbf{Z}} \right) & = \frac{1}{ 2 n\sqrt{c}\,}\sum_{a=1}^c \sum_{1 \leq u \ne v \leq n} \tilde{W}^{G_n}_{H}\left(\frac{u}{n},\frac{v}{n}\right) \tilde{Z}_{u, a} \tilde{Z}_{v, a} = Q(H, G_n) . \end{align*}
This proves (41).
Next, recalling (11) and from (33), we have
 \begin{align} \Gamma(H, G_n) & = \frac{c^{|V(H)|-\frac{3}{2}}}{n^{|V(H)|-1}} \left\{ T(H,G_n)-\mathrm{E}(T(H,G_n)) \right\} \nonumber \\[5pt] & = \frac{1}{|{\textrm{Aut}}(H)|}\sum_{\substack{J\subseteq V(H) \\ |J|\geq 2}}\mathcal{T}\left( f_{H, J}^{G_n};\; \tilde{\mathbf{X}} \right) \frac{c^{\frac{|J|}{2}-\frac{1}{2}} }{n^{\frac{|J|}{2}-1}} . \end{align}
Note that, for any
 $J \subseteq V(H)$
, with
 $|J| \geq 3$
,
 $\mathrm{E} \mathcal{T}(f_{H, J}^{G_n};\; \tilde{\mathbf{X}}) = 0$
and, from Lemma 1,
 \begin{align*} \frac{1}{n^{|J| -2}} \mathrm{Var} \left(\mathcal{T}\left(f_{H, J}^{G_n};\; \tilde{\mathbf{X}}\right)\right ) & = \frac{\eta |J|!}{n^{|J| -2}} \|\tilde{f}_{H, J}^{G_n} \|_2^2 = o(1) , \end{align*}
since
 $0\leq \tilde{f}_{H, J}^{G_n} \leq 1$
. Hence,
 $\mathcal{T}(f_{H, J}^{G_n}) = o_{L_2}(1)$
, for all
 $J \subseteq V(H)$
such that
 $|J| \geq 3$
. This implies, from (43), that
 \begin{align*} \Gamma(H,G_n) & = \frac{c^{|V(H)|-\frac{3}{2}}}{n^{|V(H)|-1}} \sum_{\substack{J\subseteq V(H) \\ |J|= 2}}\mathcal{T}\left( f_{H, J}^{G_n};\; \tilde{\mathbf{X}} \right) \frac{n^{|V(H)|-\frac{|J|}{2}}}{c^{|V(H)|-\frac{|J|}{2}-\frac{1}{2}}} + o_{L_2}(1)\\[5pt] & = \mathcal{T}\left( \sum_{\substack{J\subseteq V(H) \\ |J|= 2}} f_{H, J}^{G_n};\; \tilde{\mathbf{X}} \right) + o_{L_2}(1). \end{align*}
The following lemma represents
 $Q(H,G_n)$
as a sum of independent bivariate stochastic integrals.
Lemma 6. Let
 $\big\{B^{(1)}(t), B^{(2)}(t), \ldots, B^{(c-1)}(t)\big\}_{t \in [0, 1]}$
be a collection of independent Brownian motions on [0, 1] and
 $Q(H,G_n)$
be as defined in (40). Then
 \begin{align*} Q(H,G_n) \stackrel{D} = \frac{1}{2\sqrt{c}\,}\sum_{a=1}^{c-1}\int_{[0, 1]^2} \tilde{W}^{G_n}_{H}(x,y)\,\mathrm{d}B^{(a)}_x\,\mathrm{d}B^{(a)}_y . \end{align*}
Proof. Let
 $\{Z_{v, a}\}_{v\in [n],a\in [c]}$
be a collection of i.i.d. N(0,1) random variables. For
 $1 \leq v \leq n$
, let
 $\mathbf{Z}_v = (Z_{v, 1}, Z_{v, 2}, \ldots, Z_{v, c})^\top$
. Then, for
 $1 \leq v \leq n$
,
 $\mathbf{M} \mathbf{Z}_v = \tilde{\mathbf{Z}}_v$
, where
 $\tilde{\mathbf{Z}}_v = (\tilde{Z}_{v, 1}, \tilde{Z}_{v, 2}, \ldots, \tilde{Z}_{v, c})^\top$
,
 $\mathbf{M}= \mathbf{I}-\frac{1}{c}\textbf{1}^{\top}\textbf{1}$
, and
 $\textbf{1}$
is the vector of ones of length c. Note that
 $\mathbf{M}^\top \mathbf{M} = \mathbf{M}$
and
 $\mathbf{M}$
has
 $c-1$
nonzero eigenvalues all of which are 1. Hence, we can write
 \begin{align*} Q(H,G_n) & =\frac{1}{ 2 n\sqrt{c}\,}\sum_{a=1}^c\sum_{1\leq u \neq v \leq n}\tilde{W}^{G_n}_{H}\left( \frac{u}{n},\frac{v}{n}\right)\tilde{Z}_{u,a}\tilde{Z}_{v,a} \\[5pt] & = \frac{1}{ 2 n\sqrt{c}\,}\sum_{1\leq u \neq v \leq n}\tilde{W}^{G_n}_{H}\left(\frac{u}{n},\frac{v}{n}\right) \mathbf{Z}_u^\top \mathbf{M}^\top \mathbf{M} \mathbf{Z}_v \end{align*}
 \begin{align*} & = \frac{1}{ 2 n\sqrt{c}\,}\sum_{1\leq u \neq v \leq n}\tilde{W}^{G_n}_{H}\left(\frac{u}{n},\frac{v}{n}\right) \mathbf{Z}_u^\top \mathbf{M} \mathbf{Z}_v \nonumber \\[5pt] & \stackrel{D}= \frac{1}{ 2 n\sqrt{c}\,}\sum_{1\leq u \neq v \leq n}\tilde{W}^{G_n}_{H}\left( \frac{u}{n},\frac{v}{n}\right)\sum_{a=1}^{c-1} Y_{u,a} Y_{v,a}\\& \qquad\qquad\qquad \textrm{(where $\{Y_{v, a}\}_{v\in [n],a\in [c-1]}$ are i.i.d.}\,{N}(0, 1)) \nonumber \\[5pt] & \stackrel{D}{=} \frac{1}{ 2 \sqrt{c}\,}\sum_{a=1}^{c-1}\int_{[0, 1]^2} \tilde{W}^{G_n}_{H}(x,y)\,\mathrm{d}B^{(a)}_x\,\mathrm{d}B^{(a)}_y, \end{align*}
where the last inequality follows after noting that
 $$\frac{1}{n}Y_{u,a}Y_{v,a}\stackrel{D}{=}\int_{[0,1]^2}\textbf{1}\bigg\{\bigg[\frac{u-1}{n},\frac{u}{n}\bigg)\times \bigg[\frac{v-1}{n},\frac{v}{n}\bigg)\bigg\} \mathrm{d}B_x \mathrm{d}B_y$$
and that
 $\tilde{W}^{G_n}_{H}$
is a constant on
 $\big[\frac{u-1}{n},\frac{u}{n}\big)\times \big[\frac{v-1}{n},\frac{v}{n}\big)$
, for all
 $1\leq u\neq v\leq n$
.
With the above preparations, we proceed with the proof of Theorem 1. For this, suppose
 $\mathcal{H}= (H_1, H_2, \ldots, H_d)$
is a finite collection of graphs and
 $\mathbf{G}_n = (G_n^{(1)}, G_n^{(2)}, \ldots, G_n^{(d)})$
is a sequence of d-multiplexes converging in multiplex cut-norm to
 $\mathbf{W} = (W_1, W_2, \ldots, W_d)$
. Recall the definition of
 $\boldsymbol{\Gamma}(\mathcal{H}, \mathbf{G}_n)$
from (10) and define
 \begin{equation*} \mathbf{Q}(\mathcal{H}, \mathbf{G}_n) = \big(Q\big(H_1, G_n^{(1)}\big), Q\big(H_2,G_n^{(2)}\big), \ldots, Q\big(H_d, G_n^{(d)}\big)\big)^\top.\end{equation*}
Then, for any vector
 $\boldsymbol \alpha = (\alpha_1, \alpha_2, \ldots, \alpha_d) \in \mathbb{R}^d$
, recalling (41), we have
 \begin{align*} \boldsymbol \alpha^\top Q(\mathcal{H}, \mathbf{G}_n) = \mathcal{T}\left( \sum_{i=1}^d \sum_{\substack{J\subseteq V(H_i) \\ |J|= 2}} \alpha_i\, f_{H_i, J}^{G_n^{(i)}};\; \tilde{\mathbf{Z}} \right)\!.\end{align*}
In addition, from (42) we have, as
 $n \rightarrow \infty$
,
 \begin{align*} \boldsymbol \alpha^\top \boldsymbol \Gamma(\mathcal{H}, \mathbf{G}_n) & = \mathcal{T}\left( \sum_{i=1}^d \sum_{\substack{J\subseteq V(H_i) \\ |J|= 2}} \alpha_i\, f_{H_i, J}^{G_n^{(i)}};\; \tilde{\mathbf{X}} \right) + o_{L_2}(1) .\end{align*}
From Proposition 1 and the above we have, for all integers
 $K \geq 1$
,
 \begin{align*} \lim_{n \rightarrow \infty} \left| \mathrm{E} \left(\big(\boldsymbol \alpha^ \top \boldsymbol{\Gamma}(\mathcal{H}, \mathbf{G}_n)\big)^K\right) - \mathrm{E} \left(\big(\boldsymbol \alpha^ \top \mathbf{Q}(\mathcal{H}, \mathbf{G}_n)\big)^K \right) \right| = 0.\end{align*}
Therefore, by the Cramér–Wold device, to prove Theorem 1 it suffices to derive the limiting distribution of
 $\boldsymbol \alpha^ \top \mathbf{Q}(\mathcal{H}, \mathbf{G}_n)$
. For this, note that
 \begin{align} \boldsymbol{\alpha}^{\top} \mathbf{Q}(\mathcal{H}, \mathbf{G}_n) = \sum_{i=1}^d \alpha_i Q\big(H_i, G_n^{(i)}\big) = \frac{1}{ 2 \sqrt{c}\,}\sum_{a=1}^{c-1}I^{(a)}_2\left( \sum_{i=1}^d \alpha_i \tilde{W}^{G_n^{(i)}}_{H_i} \right)\!,\end{align}
where
 $I^{(a)}_2(F)\;:\!=\;\int_{[0,1]^2}F(x,y)\,\mathrm{d}B^{(a)}_x\,\mathrm{d}B^{(a)}_y$
, for any bounded symmetric kernel
 $F \in \mathscr{W}_1$
. Observe that for any
 $1 \leq i \leq d$
,
 $$\Big\|\tilde{W}^{G_n^{(i)}}_{H_i}-W^{G_n^{(i)}}_{H_i}\Big\|_2^2 \leq |V(H_i)|^2\mathrm{P}\big(A_n^c\big) . $$
Since
 $(\lceil nU_i \rceil)_{i \in V(H)}$
is a uniform random vector over
 $[n]^{V(H)}$
,
 $$\mathrm{P}(A_n)=\frac{n(n-1)\cdots (n-|V(H)| +1 )}{n^{|V(H)|}}\rightarrow 1.$$
Hence, (44) has the same limiting distribution as
 \begin{align} \frac{1}{ 2 \sqrt{c}\,} \sum_{a=1}^{c-1} I^{(a)}_2\left( \sum_{i=1}^d \alpha_i W^{G_n^{(i)}}_{H_i} \right)\!.\end{align}
Now let
 \begin{align} W_{\boldsymbol{\alpha}, n} \;:\!=\; \sum_{i=1}^d \alpha_i W^{G_n^{(i)}}_{H_i} \quad\text{and}\quad W_{\boldsymbol \alpha} \;:\!=\; \sum_{i=1}^d \alpha_i (W_i)_{H_i} .\end{align}
Since
 $\mathbf{G}_n$
converges to
 $\mathbf{W}$
in the multiplex cut-metric, there is a sequence of invertible measure-preserving maps
 $\phi_n\;:\;[0,1]\rightarrow [0,1]$
such that
 \begin{equation*} \sum_{i=1}^d \Big\|\Big(W^{G_n^{(i)}}\Big)^{\phi_n}-W_i \Big\|_{\square} \rightarrow 0.\end{equation*}
Let
 $\mathscr{W}_1$
be the space of bounded, symmetric, measurable functions from
 $[0, 1]^2$
to
 $[0, \infty)$
. Define the map
 $\eta_{H_i} \;:\; \mathscr{W}_1 \rightarrow \mathscr{W}_1$
, for
 $1 \leq i \leq d$
, given by
 $\eta_{H_i}(W) = W_{H_i}$
. Note that
 $\eta_{H_i}((W^{G_n^{(i)}})^{\phi_n}) = \eta_{H_i}(W^{G_n^{(i)}})^{\phi_n}$
. Then by Lemma 9, as
 $n \rightarrow \infty$
,
 \begin{align} \| W_{\boldsymbol{\alpha}, n}^{\phi_n} - W_{\boldsymbol{\alpha}}\|_\square \rightarrow 0 .\end{align}
Using (46), we can rewrite (45) as
 \begin{align} \frac{1}{ 2 \sqrt{c}\,} \sum_{a=1}^{c-1} I^{(a)}_2\left( \sum_{i=1}^d \alpha_i W^{G_n^{(i)}}_{H_i} \right) & = \frac{1}{ 2 \sqrt{c}\,} \sum_{a=1}^{c-1} I^{(a)}_2\big( W_{\boldsymbol{\alpha}, n} \big) \nonumber\\[5pt] & \stackrel{D} = \frac{1}{ 2 \sqrt{c}\,} \sum_{a=1}^{c-1} I^{(a)}_2( W_{\boldsymbol{\alpha}, n}^{\phi_n} ) \nonumber\\[5pt] & = \frac{1}{ 2 \sqrt{c}\,}\sum_{a=1}^{c-1}I_2^{(a)}\big(W_{\boldsymbol \alpha, n}^{\phi_n}-W_{\boldsymbol{\alpha}}\big)+\frac{1}{ 2 \sqrt{c}\,}\sum_{a=1}^{c-1}I_2^{(a)}(W_{\boldsymbol{\alpha}}) .\end{align}
By Lemma 10 the two terms in the right-hand side above are asymptotically independent, hence it suffices to derive the limiting distribution of the first term.
Lemma 7. As
 $n \rightarrow \infty$
,
 \begin{align} \frac{1}{2 \sqrt{c}\,}\sum_{a=1}^{c-1}I_2^{(a)}\big(W_{\boldsymbol \alpha, n}^{\phi_n}-W_{\boldsymbol{\alpha}}\big) \stackrel{D}{\to} \sqrt{\frac{c-1}{2c}} N(0, \boldsymbol \alpha^\top \Sigma \boldsymbol \alpha ) , \end{align}
where
 $\Sigma$
is defined in Theorem 1.
Proof. By the spectral theorem for bounded symmetric kernels (see [Reference Lovász52, Section 7.5]),
 $$\Delta_{\alpha, n}(x, y)\;:\!=\; W_{\boldsymbol \alpha,n}^{\phi_n}(x,y)-W_{\boldsymbol{\alpha}}(x,y)=\sum_{s=1}^\infty \lambda^{(n)}_s \phi_s^{(n)}(x) \phi_s^{(n)}(y), $$
where
 $\{\lambda^{(n)}_s\}_{s \geq 1}$
are the eigenvalues and
 $\{ \phi_s^{(n)}\}_{s \geq 1}$
are a set of orthonormal eigenvectors for the operator
 $$T_{\Delta_{\boldsymbol{\alpha}, n}} f (x) = \int_0^1 \Delta_{\boldsymbol{\alpha}, n}(x, y) f(y) \mathrm{d}y.$$
Define, for
 $s \geq 1$
,
 \begin{align*} \xi_s=\sum_{a=1}^{c-1} \left(\int_0^1 \phi_s^{(n)}(x)\mathrm{d}B^{(a)}_x \right)^2-(c-1). \end{align*}
By orthonormality, the variables
 $\{\xi_s\}_{s \geq 1}$
have independent
 $\chi^2_{c-1}-(c-1)$
distributions. Hence,
 \begin{align*} \frac{1}{2\sqrt{c}\,}\sum_{a=1}^{c-1}I_2^{(a)}\big(W_{\boldsymbol \alpha,n}^{\phi_n}-W_{\boldsymbol{\alpha}}\big) \stackrel{D} = \frac{1}{2 \sqrt{c}\,}\sum_{s=1}^{\infty}\lambda^{(n)}_s \xi_s. \end{align*}
The result in (49) then follows from Lemma 11 if we show the following:
 \begin{align} \lim_{n \rightarrow \infty} \max_{s \geq 1}\big|\lambda_s^{(n)}\big| = 0 \quad\text{and}\quad\lim_{n \rightarrow \infty} \sum_{s \geq 1}|\lambda_s^{(n)}|_2^2 = \boldsymbol{\alpha}^\top \Sigma \boldsymbol{\alpha}. \end{align}
To show the first condition in (50), we will use the identity
 $\sum_{s \geq 1}(\lambda^{(n)}_s )^4=t(C_4, \Delta_{n, \boldsymbol{\alpha}})$
(see [Reference Lovász52, Section 7.5]), where
 $C_4$
denotes the cycle of size 4. This implies that
 \begin{align*} \max_{s \geq 1}|\lambda_s^{(n)}|^4 \leq \sum_{s=1}^\infty \big(\lambda^{(n)}_s \big)^4=t(C_4, \Delta_{n, \boldsymbol{\alpha}}) & = \|\Delta_{n, \boldsymbol{\alpha}}\|_{\infty}^4t\left( C_4, \frac{\Delta_{n, \boldsymbol{\alpha}}}{\|\Delta_{n, \boldsymbol{\alpha}}\|_{\infty}}\right) \nonumber \\[5pt] & \leq 16\|\Delta_{n, \boldsymbol{\alpha}}\|_{\infty}^3\|\Delta_{n, \boldsymbol{\alpha}} \|_\square \rightarrow 0, \end{align*}
by (47), the counting lemma [Reference Lovász52, Lemma 10.24], and the fact that
 \begin{equation*} \|\Delta_{n, \boldsymbol{\alpha}}\|_{\infty}\leq \sum_{i=1}^d|\alpha_i|\Big\|W^{G_n^{(i)}}_{H_i}\Big\|_{\infty} \leq \sum_{i=1}^d|\alpha_i|(|V(H_i)|-1)|V(H_i)|. \end{equation*}
We now prove the second condition in (50). For this, observe that
 \begin{align*} \lim_{n\rightarrow\infty}\|\Delta_{n, \boldsymbol{\alpha}}\|_2^2 & = \lim_{n\rightarrow\infty}\big\|W_{\boldsymbol \alpha,n}^{\phi_n}-W_{\boldsymbol{\alpha}}\big\|_2^2 \\[5pt] & = \lim_{n\rightarrow\infty}\big\|W_{\boldsymbol \alpha, n}^{\phi_n} \big\|_2^2 - 2 \lim_{n\rightarrow\infty} \big\langle W_{\boldsymbol \alpha,n}^{\phi_n}, W_{\boldsymbol{\alpha}} \big\rangle +\|W_{\boldsymbol{\alpha}}\|_2^2 \\[5pt] & = \lim_{n\rightarrow\infty}\|W_{\boldsymbol \alpha, n} \|_2^2-\|W_{\boldsymbol{\alpha}}\|_2^2, \end{align*}
using the fact that
 $\lim_{n\rightarrow\infty} \langle W_{\boldsymbol \alpha,n}^{\phi_n}, W_{\boldsymbol{\alpha}} \rangle = \|W_{\boldsymbol{\alpha}}\|_2^2$
, which follows from (47) and by invoking [Reference Lovász52, Lemma 8.22]. In addition,
 \begin{align*} \lim_{n\rightarrow\infty}\|W_{\boldsymbol \alpha, n} \|_2^2 & = \lim_{n\rightarrow\infty}\left\| \sum_{i=1}^d \alpha_i W^{G_n^{(i)}}_{H_i} \right\|_2^2 \\[5pt] & = \lim_{n\rightarrow\infty} \left\{ \sum_{i=1}^d \alpha_i^2 \| W^{G_n^{(i)}}_{H_i} \|_2^2 + \sum_{1 \leq i \ne j \leq d} \alpha_i \alpha_j \Big\langle W^{G_n^{(i)}}_{H_i} , W^{G_n^{(j)}}_{H^{(j)}} \Big\rangle \right\} \\[5pt] & = \sum_{i=1}^d \alpha_i^2 \tau(H_i, W_i) + \sum_{1 \leq i \ne j \leq d} \alpha_i \alpha_j \rho_{ij} , \end{align*}
where
 $\tau(H_i, W_i)$
is as defined in Lemma 8 and
 $\rho_{ij}$
is as in (13). Combining the above and observing that
 \begin{equation*} \|W_{\boldsymbol{\alpha}}\|_2^2 = \sum_{i=1}^d \alpha_i^2 \|(W_i)_{H_i}\|_2^2 + \sum_{1 \leq i \ne j \leq d} \alpha_i \alpha_j \big\langle (W_i)_{H_i}, (W_j)_{H_j} \big\rangle, \end{equation*}
the second condition in (50) follows. This completes the proof of Lemma 7.
The proof of Lemma 7 uses the following result about the limiting value of
 $\|W^{G_n}_{H}\|_2^2$
.
Lemma 8. For any fixed graph
 $H = (V(H), E(H))$
and a sequence of graphs
 $G_n$
converging to a graphon W,
 $$\lim_{n \rightarrow \infty} \big\|W^{G_n}_{H}\big\|_2^2 = \sum_{\substack{1\leq u\neq v\leq |V(H)|\\ 1\leq u'\neq v'\leq |V(H)|}} t\left( H\bigotimes_{(a, b),(a', b')} H, W \right) \;:\!=\; \tau(H, W).$$
Moreover, for any two fixed graphs
 $H_1 = (V(H_1), E(H_1))$
and
 $H_2 = (V(H_2), E(H_2))$
and a sequence of graphs
 $G_n$
converging to a graphon W,
 \begin{align} \lim_{n \rightarrow \infty} \Big\langle W^{G_n}_{H_1}, W^{G_n}_{H_2} \Big\rangle = \sum_{\substack{1\leq u\neq v\leq |V(H_1)| \\ 1\leq u'\neq v'\leq |V(H_2)|}} t\left( H_1 \bigotimes_{(a, b),(a', b')} H_2, W \right)\!. \end{align}
Proof. Let H′ be an isomorphic copy of H. Then
 \begin{align*} \Big\|W^{G_n}_{H}\Big\|_2^2 & = \int_{[0,1]^2}\left[ \sum_{1\leq a \neq b \leq |V(H)|} \mathrm{E}\left( \prod_{(i, j)\in E(H)} W^{G_n}(U_i,U_j) \;\middle|\; U_a=x,U_b=y \right) \right]^2\,\mathrm{d}x \,\mathrm{d}y \\[5pt] & = \int_{[0,1]^2}\sum_{\substack{(a, b)\in V(H)_2 \\ (a',b')\in V(H')_2}}\mathrm{E}\left( \prod_{(i, j) \in E(H)\cup E(H')} W^{G_n}(U_i,U_j) \;\middle|\; \begin{pmatrix} U_a \\[5pt] U_b\end{pmatrix} = \begin{pmatrix} U_{a'} \\[5pt] U_{b'}\end{pmatrix} = \begin{pmatrix} x \\[5pt] y\end{pmatrix} \right) \,\mathrm{d}x \,\mathrm{d}y\\[5pt] & = \sum_{\substack{1\leq a \neq b \leq |V(H)| \\ 1\leq a' \neq b' \leq |V(H)|}} t\left( H\bigotimes_{(a,b),(a',b')} H, W^{G_n} \right) \rightarrow \tau(H, W) , \end{align*}
since
 $G_n$
converges to W. The result in (51) can be proved similarly.
To complete the proof of Theorem 1, recall the representation in (48). Then applying Lemmas 7 and 10 shows that
 \begin{align*} \frac{1}{2 \sqrt{c}\,} \sum_{a=1}^{c-1} I^{(a)}_2\left( \sum_{i=1}^d \alpha_i W^{G_n^{(i)}}_{H_i} \right) \stackrel{D} \rightarrow \sqrt{\frac{c-1}{2c}} \boldsymbol{\alpha}^\top \mathbf{Z} + \frac{1}{2 \sqrt{c}\,}\sum_{a=1}^{c-1}I_2^{(a)}(W_{\boldsymbol{\alpha}}) ,\end{align*}
where
 $\mathbf{Z}$
is as defined Theorem 1 and the two terms in the right-hand side above are independent. Finally, recall (from (44) and (45)) that the left-hand side above has the same limiting distribution as
 $\boldsymbol{\alpha}^\top \mathbf{Q}(\mathcal{H}, \mathbf{G}_n)$
. Hence, by the Cramér–Wold device the result in Theorem 1 follows.
4. Examples
In this section we illustrate our results in various examples. A few of the examples will involve random multiplexes. To this end, it is worth noting that Theorem 1 can be easily extended to random multiplexes, when the limits in (9) and (13) hold in probability, under the assumption that the multiplex and its coloring are jointly independent (see, for example, [Reference Bhattacharya, Diaconis and Mukherjee13, Lemma C.1]).
Example 4. A natural example of a random multiplex is the correlated Erdős–Rényi model, which is a 2-multiplex where the edges are dependent across the different layers. This model emerged from the study of network privacy [Reference Pedarsani and Grossglauser75] and is the basic underlying model in graph matching problems (see [Reference Mao, Wu, Xu and Yu59, Reference Mao, Wu, Xu and Yu60] and the references therein). Specifically, the correlated Erdős–Rényi model
 $\mathbf{G}(n, p, q, \rho) = (G_n^{(1)}, G_n^{(2)})$
is a 2-multiplex with a common vertex set [n], where independently for every
 $1 \leq i < j \leq n$
, we have
 \begin{align*} \mathrm{P}\big( (i, j) \in E\big(G_n^{(1)}\big)\big) = p, \quad \mathrm{P}\big( (i, j) \in E\big(G_n^{(2)}\big)\big) = q, \end{align*}
and
 \begin{align*} \mathrm{P}\big( (i, j) \in E\big(G_n^{(1)}\big) \cap E\big(G_n^{(2)}\big)\big) = \rho + p q \;:\!=\; p_{1, 2}, \end{align*}
for
 $p, q \in (0, 1)$
and
 $p_{1,2} \in [\max\{p+q-1,0\}, \min\{p,q\}]$
. In this case,
 $(G_n^{(1)}, G_n^{(2)})$
converges in the multiplex cut-metric to
 $(W_1, W_2)$
, where
 $W_1 \equiv p$
and
 $W_2 \equiv q$
. Therefore, for any two graphs
 $H_1$
and
 $H_2$
,
 \begin{align} ((W_1)_{H_1}, (W_2)_{H_2})=\left( |V(H_1)| (|V(H_1)| -1) p^{|E(H_1)|},|V(H_2)| (|V(H_2)| -1 ) q^{|E(H_2)|}\right)\!. \end{align}
To apply Theorem 1, it remains to find the limit
 \begin{align*} \lim_{n \rightarrow \infty} \Big\langle W_{H_1}^{G_n^{(1)}}, W_{H_2}^{G_n^{(2)}} \Big\rangle \end{align*}
(recall (14)) and to compute
 $\Sigma$
.
Note that, given
 $\mathbf{G}_n = (G_n^{(1)}, G_n^{(2)})$
,
 \begin{align*} \Big\langle W_{H_1}^{G_n^{(1)}}, W_{H_2}^{G_n^{(2)}} \Big\rangle & = \int_{[0, 1]^2} W_{H_1}^{G_n^{(1)}} (x, y) W_{H_2}^{G_n^{(2)}} (x, y) \,\mathrm{d} x \,\mathrm{d} y \nonumber \\[5pt] & = \sum_{\substack{(a, b)\in V(H_1)_2 \\ (a',b')\in V(H_2)_2}} B_{H_1, H_2}^{G_n^{(1)} G_n^{(2)}} ((a, b), (a', b')) , \end{align*}
where
 \begin{align*} & B_{H_1, H_2}^{G_n^{(1)} G_n^{(2)}} ((a, b), (a', b')) \nonumber \\[5pt] & \;:\!=\; \int_{[0, 1]^2} \Bigg\{ \mathrm{E}\left( \prod_{(i, j)\in E(H_1)} W^{G_n^{(1)}}(U_i, U_j) \;\middle|\; \begin{pmatrix} U_a \\ U_b\end{pmatrix} = \begin{pmatrix} x \\ y\end{pmatrix} \right) \nonumber \\[5pt] & \hspace{1.5in} \mathrm{E}\left( \prod_{(i, j)\in E(H_2)} W^{G_n^{(2)}}(U_i,U_j) \;\middle|\; \begin{pmatrix} U_{a'} \\ U_{b'}\end{pmatrix} = \begin{pmatrix} x \\ y\end{pmatrix} \right) \Bigg\} \mathrm{d}x \mathrm{d}y \nonumber \\[5pt] & \stackrel{L^2} \rightarrow \begin{cases} p_{1,2} \cdot p^{|E(H_1)|-1}q^{|E(H_2)|-1} & \textit{if } (a,b)\in E(H_1) \textit{ and } (a',b')\in E(H_2) , \\[5pt] p^{|E(H_1)|}q^{|E(H_2)|} & \textit{otherwise}. \end{cases} \end{align*}
Therefore, from (52),
 \begin{align} \Big\langle W_{H_1}^{G_n^{(1)}}, W_{H_2}^{G_n^{(2)}} \Big\rangle - \langle(W_1)_{H_1},(W_2)_{H_2}\rangle \stackrel{L^2} \rightarrow |E(H_1)||E(H_2)| \rho \cdot p^{|E(H_1)|-1}q^{|E(H_2)|-1} . \end{align}
This implies that
 \begin{align} \hspace{-0.125in} \Sigma = \begin{pmatrix} |E(H_1)||E(H_2)| p^{|E(H_1)|+ E(H_2)|-1}(1-p)\;\;\;\;\; & |E(H_1)||E(H_2)| \rho \cdot p^{|E(H_1)|-1}q^{|E(H_2)|-1} \\[5pt] |E(H_1)||E(H_2)| \rho \cdot p^{|E(H_1)|-1}q^{|E(H_2)|-1}\;\;\;\; & |E(H_1)||E(H_2)| q^{|E(H_1)|+E(H_2)|-1} (1-q)\end{pmatrix} . \end{align}
Combining (53) and (54) and applying Theorem 1 gives
 \begin{align*} \begin{pmatrix} \Gamma(H_1,G_n^{(1)}) \\[5pt] \Gamma(H_2,G_n^{(2)}) \end{pmatrix} \xrightarrow{D} \sqrt{\frac{c-1}{2c}} \begin{pmatrix} Z_1 \\[5pt] Z_2 \end{pmatrix} +\frac{1}{ 2 \sqrt{c}\,} \begin{pmatrix} |V(H_1)| (|V(H_1)| -1) p^{|E(H_1)|} \\[5pt] |V(H_2)| (|V(H_2)| -1) q^{|E(H_1)|} \end{pmatrix} \xi , \end{align*}
with
 $\xi \sim \chi^2_{c-1}-(c-1)$
which is independent of
 $(Z_1,Z_2) \sim N_2(\mathbf 0, \Sigma)$
.
Next, we construct an example where the Gaussian component of the limiting distribution in (14) has a degenerate covariance matrix.
Example 5. Suppose
 $G_n^{(1)} \sim G(n, p)$
, where
 $p \in (0, 1)$
, and consider the multiplex
 $\mathbf{G}_n = (G_n^{(1)}, G_n^{(2)})$
, where
 $G_n^{(2)}$
is the complement graph of
 $G_n^{(1)}$
. Then, by plugging in
 $H_1=H_2=K_3$
,
 $c=2$
,
 $q=1-p$
, and
 $p_{1,2}=0$
into Example 4 gives
 \begin{align*} \begin{pmatrix} \Gamma(K_3,G_n^{(1)}) \\[5pt] \Gamma(K_3, G_n^{(2)}) \end{pmatrix} \xrightarrow{D} 3\sqrt{p(1-p)}\begin{pmatrix} p^2Z \\[5pt] -(1-p)^2Z \end{pmatrix} +3\sqrt{2}\begin{pmatrix} \displaystyle p^3 \\[5pt] \displaystyle (1-p)^3 \end{pmatrix} \xi , \end{align*}
with
 $\xi\sim \chi^2_1-1$
which is independent of
 $Z \sim N(0,1)$
.
The next example shows that marginal convergence (in the cut-metric) of the graphs in the different layers of a multiplex
 $\mathbf{G}_n$
and the convergence of the pairwise overlaps (13) are not enough for the convergence of the joint distribution of
 $\Gamma(\mathcal{H}, \mathbf{G}_n)$
. This illustrates the need to assume that the graphs in the different layers converge in the multiplex cut-metric (as in (9)) for the limiting distribution of
 $\Gamma(\mathcal{H}, \mathbf{G}_n)$
to exist. To this end, for two graphs
 $G_1 = (V(G_1), E(G_1))$
and
 $G_2 = (V(G_2), E(G_2))$
, denote
 $G_1 \bigcup G_2 = (V(G_1) \bigcup V(G_2), E(G_1) \bigcup E(G_2))$
.
The graphs
 $G_n^{(1)}$
,
 $G_n^{(2)}$
, and
 $G_n^{(3)}$
in Example 6.

Example 6. Let
 $A_1, A_2, A_3, A_4$
be four disjoint sets of size n. Denote by
 $B_{n}^{(s, s+1)}$
the complete bipartite graph between the sets
 $A_s$
and
 $A_{s+1}$
, for
 $1 \leq s \leq 3$
(see Figure 2). Define
 \begin{equation*} G_n^{(1)} = \bigcup_{s=1}^3 B_n^{(s, s+1)}, \quad G_n^{(2)} = B_n^{(1, 2)}, \quad \text{and} \quad G_n^{(3)} = B_n^{(2, 3)}. \end{equation*}
(Note that, in other words,
 $G_n$
is the n-blow-up of a path with four vertices; see [Reference Lovász52, Section 3.3].) Now consider the following two sequences of multiplexes:
 \begin{equation*} \mathbf{G}_n = \big(G_n^{(1)}, G_n^{(2)}\big) \quad \text{and} \quad \tilde{\mathbf{G}}_n = \big(G_n^{(1)}, G_n^{(3)}\big). \end{equation*}
Note that the graph
 $G_n^{(1)}$
converges to the graphon
 $W_{1234}$
in Figure 3(a) and the graphs
 $G_n^{(2)}$
and
 $G_n^{(3)}$
converge to the graphon
 $W_{23}$
in Figure 3(b). Hence, marginally the graphs in the two layers of
 $\mathbf{G}_n$
and the graphs in the two layers of
 $\tilde{\mathbf{G}}_n$
converge to the same limits. Moreover,
 \begin{align*} \lim_{n \rightarrow \infty} \frac{2 |E\big(G_n^{(1)}\big) \cap E\big(G_n^{(2)}\big)|}{n^2} = \lim_{n \rightarrow \infty} \frac{2 |E\big(G_n^{(1)}\big) \cap E\big(G_n^{(3)}\big)|}{n^2} = \frac{1}{8}, \end{align*}
that is, (15) converges to the same limit for both
 $\mathbf{G}_n$
and
 $\tilde{\mathbf{G}}_n$
. Hence, the premises of Corollary 1 hold for both
 $\mathbf{G}_n$
and
 $\tilde{\mathbf{G}}_n$
. In particular, with
 $c=2$
, we get
 \begin{align} \begin{pmatrix} \Gamma\left(K_2,G_n^{(1)}\right) \\[5pt] \Gamma\left(K_2,G_n^{(2)}\right) \end{pmatrix} \xrightarrow{D} \begin{pmatrix}\displaystyle\int_{[0,1]^2}W_{1234}(x, y)\,\mathrm{d}B_x\,\mathrm{d}B_y \\[5pt] \displaystyle\int_{[0,1]^2}W_{23}(x, y)\,\mathrm{d}B_x\,\mathrm{d}B_y\end{pmatrix} & \stackrel{D}{=} \frac{1}{4}\begin{pmatrix}\displaystyle Z_1Z_2+Z_2Z_3+Z_3Z_4 \\[5pt] Z_1Z_2 \end{pmatrix} \nonumber \\[5pt] & \;=\!:\; \begin{pmatrix} Y \\[5pt] Y'\end{pmatrix} \end{align}
and
 \begin{align} \begin{pmatrix} \Gamma\big(K_2,G_n^{(1)}\big) \\[5pt] \Gamma\big(K_2,G_n^{(3)}\big) \end{pmatrix} \xrightarrow{D} \begin{pmatrix}\displaystyle\int_{[0,1]^2}W_{1234}(x, y)\,\mathrm{d}B_x\,\mathrm{d}B_y \\[5pt] \displaystyle\int_{[0,1]^2}W_{23}(x, y)\,\mathrm{d}B_x\,\mathrm{d}B_y\end{pmatrix} & \stackrel{D}{=} \frac{1}{4}\begin{pmatrix}\displaystyle Z_1Z_2+Z_2Z_3+Z_3Z_4 \\[5pt] Z_2Z_3 \end{pmatrix} \nonumber \\[5pt] & \;=\!:\; \begin{pmatrix} Y \\[5pt] Y'' \end{pmatrix} , \end{align}
where
 $Z_1, Z_2, Z_3, Z_4$
are i.i.d. N(0,1) and
 $\{B_t\}_{t \in [0, 1]}$
is the standard Brownian motion on [0, 1]. Note that the limiting distributions in (55) and (56) are different. In particular,
 $\mathrm{E}(Y-Y')^4=\frac{36}{4^4}$
which is different from
 $\mathrm{E}(Y-Y'')^4=\frac{24}{4^4}$
. The reason for this is that in this case
 $\lim_{n\rightarrow\infty}\delta_{\square}(\mathbf{W}^{\mathbf{G}_n},\mathbf{W}^{\tilde{\mathbf{G}}_n})\neq 0$
.
The graphons
 $W_{1234}$
and
 $W_{23}$
in Example 6.

Finally, we consider the correlated stochastic block model, which generalizes both Examples 5 and 6.
Example 7. The SBM is one of the most widely studied models in network analysis [Reference Holland, Laskey and Leinhardt41, Reference Kolaczyk and Csárdi48, Reference Olhede and Wolfe71]. This is a random graph
 $G_n=([n],E(G_n))$
, where the vertex set [n] is partitioned into
 $K\geq 1$
blocks
 $C_1, C_2, \ldots, C_K$
(which are referred to as communities) and the edges are obtained as follows: independently for
 $1 \leq u < v \leq n$
,
 \begin{equation*} \mathrm{P}((u, v)\in E(G_n)) = p_{ab} , \quad \text{if } u \in C_a \text{ and } v \in C_b , \end{equation*}
for
 $a, b \in [K]$
. Here,
 $((p_{ab}))_{1\leq a, b \leq K}$
is a
 $K \times K$
is a matrix of parameters encoding the within/between block connection probabilities. The correlated SBM (on 2 layers) is a random multiplex
 $(G_n^{(1)},G_n^{(2)})$
where the common vertex set [n] is partitioned into
 $K\geq 1$
blocks
 $C_1, C_2, \ldots, C_K$
as before and the edges are obtained as follows: independently for
 $1 \leq u < v \leq n$
,
 \begin{equation*} \mathrm{P}\big((u, v)\in E\big(G_n^{(1)}\big)\big) = p_{ab}^{(1)} , \quad \mathrm{P}\big((u, v)\in E\big(G_n^{(2)}\big)\big) = p_{ab}^{(2)} , \end{equation*}
and
 \begin{equation*} \mathrm{P}\big((u, v)\in E\big(G_n^{(1)}\big) \cap E\big(G_n^{(2)}\big)\big) = p_{ab}^{(12)}, \end{equation*}
if
 $u \in C_a \text{ and } v \in C_b$
, for
 $a, b \in [K]$
. Here,
 $((p_{ab}^{(1)}))_{1\leq a, b \leq K}$
,
 $((p_{ab}^{(2)}))_{1\leq a, b \leq K}$
, and
 $((p_{ab}^{(12)}))_{1\leq a, b \leq K}$
are
 $K \times K$
matrices of parameters encoding the connection probabilities within/between blocks in layer 1, layer 2, and in both the layers, respectively. The correlated SBM has recently emerged as an important prototype for modeling multilayer social network data and in graph matching problems (see [Reference Barbillon, Donnet, Lazega and Bar-Hen3, Reference Chai and Rácz23, Reference Chandna, Janson and Olhede24, Reference Gaudio, Racz and Sridhar36, Reference Lyzinski55, Reference Lyzinski, Sussman, Fishkind, Pao, Chen, Vogelstein, Park and Priebe56, Reference Onaran, Garg and Erkip72, Reference Pamfil, Howison and Porter73, Reference Racz and Sridhar76, Reference Rácz and Sridhar77, Reference Zhang, Wang and Wang87] and references therein). Suppose that
 $\frac{|V_a|}{n} \rightarrow \lambda_a \in [0, 1]$
, for
 $a \in [K]$
, and
 $\{I_1, I_2, \ldots, I_K\}$
is a partition of [0, 1] into intervals of length
 $\lambda_1, \lambda_2, \ldots, \lambda_K$
, respectively. Then the multiplex
 $(G_n^{(1)}, G_n^{(2)}, G_n^{(1)}\cap G_n^{(2)})$
converges, in the appropriate multiplex cut-distance, to the 3-graphon
 $(W_{1},W_{2},W_{12}),$
where
 $$W_{1}(x,y)= p_{ab}^{(1)}, \quad W_{2}(x,y)= p_{ab}^{(2)}, \quad W_{12}(x,y)= p_{ab}^{(12)},$$
for all
 $x\in I_a$
and
 $y\in I_b$
, and
 $a, b \in [K]$
. Hence, fixing
 $c=2$
, Corollary 1 implies that
 \begin{equation*} \frac{1}{n}\left[ \begin{pmatrix} T\big(K_2,G_{n}^{(1)}\big) \\[5pt] T\big(K_2,G_{n}^{(2)}\big) \end{pmatrix} - \frac{1}{c}\begin{pmatrix} |E\big(G_{n}^{(1)}\big)| \\[5pt] |E\big(G_{n}^{(2)}\big)| \end{pmatrix} \right] \xrightarrow{D} \frac{1}{2\sqrt{2}\,}\mathbf{L} + \frac{1}{4}\mathbf{Q} , \end{equation*}
where
 $\mathbf{L}=(L^{(1)},L^{(2)})$
and
 $\mathbf{Q}=(Q^{(1)},Q^{(2)})$
are independent. Here,
 \begin{align*} Q^{(1)} &= \sum_{{a, b \in [K]}}p_{ab}\sqrt{\lambda_a \lambda_b}\big( Z_a^{(1)}Z_b^{(1)} - \mathrm{E} Z_a^{(1)}Z_b^{(1)}\big),\\[5pt] Q^{(2)} &= \sum_{{a, b \in [K]}}p_{ab}\sqrt{\lambda_a \lambda_b}\big( Z_a^{(2)}Z_b^{(2)} - \mathrm{E} Z_a^{(2)}Z_b^{(2)}\big) , \end{align*}
where
 $\{Z_a^{(1)}\}_{a \in [K]}$
and
 $\{Z_a^{(2)}\}_{a \in [K]}$
are independent collections of i.i.d. N(0, 1) random variables; and
 \begin{align*} L^{(1)} = \sum_{{a, b \in [K]}}\lambda_a \lambda_b\eta_{ab}^{(1)}, \quad L^{(2)} = \sum_{{a, b \in [K]}}\lambda_a \lambda_b\eta_{ab}^{(2)} , \end{align*}
where
 $\{(\eta_{ab}^{(1)},\eta_{ab}^{(2)})\}_{a, b \in [K]}$
is a collection of independent
 $N_2(0,\Sigma_{ab})$
variables with
 \begin{equation*} \Sigma_{ab} = \begin{pmatrix} p_{ab}^{(1)}\big(1-p_{ab}^{(1)}\big) & p_{ab}^{(12)} - p_{ab}^{(1)}p_{ab}^{(2)} \\[5pt] p_{ab}^{(12)} - p_{ab}^{(1)}p_{ab}^{(2)} & p_{ab}^{(2)}\big(1-p_{ab}^{(2)}\big) \end{pmatrix}, \end{equation*}
for all
 ${a, b \in [K]}$
.
5. Future directions
In this paper we have derived the joint distribution of monochromatic subgraphs in multiplex networks (converging in the cut-metric) colored uniformly at random with c colors. A possible future direction would be to consider nonuniform colorings. The authors expect the techniques developed in this paper to be still relevant in the nonuniform setting, although the nature of the limiting distribution may differ. Additionally, it may be relevant to study settings in which the coloring in each layer differs, yet exhibits some correlation structure across layers. Another question is to derive convergence rates for the asymptotic results presented in this paper. A key challenge is that the limiting distribution involves both Gaussian and non-Gaussian components. While techniques for Gaussian convergence are well developed, results for non-Gaussian distributions are limited to specific cases. Understanding how convergence rates depend on the structure of the multiplex, particularly inter-layer interactions, is an interesting future direction.
Appendix A. Continuity of the two-point conditional kernel
Recall the definition of the two-point conditional kernel from (12). Note that
 $W_H$
is symmetric and bounded, but can take values greater 1, hence
 $W_H \in \mathscr{W}_1$
, where
 $\mathscr{W}_1$
is the space of bounded, symmetric, measurable functions from
 $[0, 1]^2$
to
 $[0, \infty)$
. The topology generated by the cut-distance (7) (extended naturally to the space
 $\mathscr{W}_1$
) is the same as the topology generated by the following norm (see [Reference Lovász52, Lemma 8.11]):
 \begin{align*} \|W_1-W_2\|_{1 \rightarrow \infty}\;:\!=\;\sup_{f, g: [0, 1] \rightarrow [-1, 1]}\left|\int_{[0, 1]^2} \left(W_1(x, y)-W_2(x, y)\right) f(x) g(y) \mathrm{d}x \mathrm{d}y \right|\!,\end{align*}
for
 $W_1, W_2 \in \mathscr{W}_1$
. The next lemma shows that the map
 $W \rightarrow W_H$
is Lipschitz in the
 $\| \cdot \|_{1 \rightarrow \infty}$
norm and, hence the cut-distance
 $\| \cdot \|_{\square}$
. This, in particular, means that if
 $G_n$
converges to a graphon W then
 $W^{G_n}_{H}$
converges in cut-norm to
 $W_H$
.
Lemma 9. The mapping
 $\eta_H\;:\;W\mapsto W_H$
defined on
 $\mathscr{W}_1$
is Lipschitz under
 $\|\cdot\|_{\infty\rightarrow 1}$
and, hence, under
 $\|\cdot\|_{\square}$
.
Proof. Let
 $\{U_r\}_{r\in V(H)}$
be a collection i.i.d.
 $\mathrm{Unif}[0,1]$
random variables. To show the map
 $\eta_H$
is Lipschitz, it suffices to prove
 \begin{align} \| (W+R)_H- R_H \|_{\infty \rightarrow 1} \lesssim_H \| R \|_{\infty \rightarrow 1}, \end{align}
for
 $W, R \in \mathscr{W}_1$
. To this end, fix
 $1 \leq a \ne b \leq |V(H)|$
and note that
 \begin{align*} \Delta_{a, b}(x, y) & \;:\!=\; \mathrm{E}\left( \prod_{(i, j)\in E(H)}\left(W(U_i, U_j)+ R(U_i, U_j)\right)-\prod_{(i, j)\in E(H)}W(U_i, U_j) \Bigg| U_a=x, U_b=y \right) \\[5pt] & =\mathrm{E}\left(\left. \sum_{\substack{\mathcal{A}\subseteq E(H) \\ |\mathcal{A}|\geq 1}} \prod_{(i, j) \in \mathcal{A}^c}W(U_i, U_j)\prod_{(i, j) \in \mathcal{A}}R(U_i, U_j)\,\right\rvert\, U_a=x, U_b=y \right)\!. \end{align*}
Recalling (12), note that
 \begin{align} \| (W+R)_H- R_H \|_{\infty \rightarrow 1} = \left\| \sum_{1 \leq a \ne b \leq |V(H)|} \Delta_{a, b} \right\|_{\infty \rightarrow 1} & \leq \sum_{1 \leq a \ne b \leq |V(H)|} \left\| \Delta_{a, b} \right\|_{\infty \rightarrow 1}\!, \end{align}
by the triangle inequality. Hence, to prove (A1) it suffices to consider each term in the above sum separately. Towards this,
 \begin{align} & \left\| \Delta_{a, b} \right\|_{\infty \rightarrow 1} \nonumber\\[5pt] & = \sup_{\substack{\|f\|_{\infty}\leq 1 \\ \|g\|_{\infty}\leq 1}}\left\lvert \mathrm{E}\left(\mathrm{E}\left(\left. \sum_{\substack{\mathcal{A}\subseteq E(H)\\ |\mathcal{A}|\geq 1}} \prod_{(i, j) \in \mathcal{A}^c}W(U_i, U_j)\prod_{(i, j) \in \mathcal{A}}R(U_i, U_j)\,\right\rvert\, U_a, U_b\right)f(U_a)g(U_b)\right)\right\rvert\nonumber\\[5pt] & =\sup_{\substack{\|f\|_{\infty}\leq 1 \\ \|g\|_{\infty}\leq 1}}\left\lvert \mathrm{E}\left(\sum_{\substack{\mathcal{A}\subseteq E(H)\\ |\mathcal{A}|\geq 1}} f(U_a)g(U_b)\prod_{(i, j) \in \mathcal{A}^c}W(U_i, U_j)\prod_{(i, j) \in \mathcal{A}}R(U_i, U_j)\right)\right\rvert\nonumber\\[5pt] & \leq \sum_{\substack{\mathcal{A}\subseteq E(H) \\ |\mathcal{A}|\geq 1}} \sup_{\substack{\|f\|_{\infty}\leq 1\\ \|g\|_{\infty}\leq 1}}\left\lvert \mathrm{E}\left( f(U_a)g(U_b)\prod_{(i, j) \in \mathcal{A}^c}W(U_i, U_j)\prod_{(i, j) \in \mathcal{A}}R(U_i, U_j)\right)\right\rvert , \end{align}
by the triangle inequality. Now, by a telescoping argument similar to the proof of the counting lemma (see [Reference Borgs, Chayes, Lovász, Sós and Vesztergombi20, Theorem 3.7] and [Reference Lovász52, Lemma 10.24]), we can show that
 \begin{align} \sup_{\substack{\|f\|_{\infty}\leq 1 \\ \|g\|_{\infty}\leq 1}}\left\lvert \mathrm{E}\left( f(U_a)g(U_b)\prod_{(i, j) \in \mathcal{A}^c}W(U_i, U_j)\prod_{(i, j) \in \mathcal{A}}R(U_i, U_j)\right)\right\rvert \lesssim_H \| R \|_{\infty \rightarrow 1}.\end{align}
Appendix B. Independence of bivariate stochastic integrals
Fix
 $d \geq 1$
. Given a bounded function
 $f\;:\; [0, 1]^d \rightarrow \mathbb{R}$
, denote by
 $I_d(f)$
the d-dimensional Wiener–Itô stochastic integral of f with respect to a Brownian motion on [0, 1]. Conditions under which two multiple stochastic integrals are independent are well known. Üstünel and Zakai [Reference Üstünel and Zakai85] provided a useful necessary and sufficient for the independence of multiple stochastic integrals, and Rosiński and Samorodnitsky [Reference Rosiński and Samorodnitsky79] showed that multiple stochastic integrals are independent if and only if their squares are uncorrelated. An asymptotic version of these results was established by Nourdin and Rosiński [Reference Nourdin and Rosiński69]. Using this asymptotic result, we prove the following lemma.
Lemma 10. Fix
 $W \in \mathscr{W}_1$
and consider a sequence of bounded kernels
 $\{R_n\}_{n \geq 1}$
, with
 $R_n \in \mathscr{W}_1$
, such that
 $\|R_n\|_{\square} \rightarrow 0$
. Then
 $\mathbf{Q}_n \;:\!=\; (I_2(R_n), I_2(W))$
are asymptotically independent along any subsequence for which
 $\mathbf{Q}_n$
has a limit in distribution.
Proof. By [Reference Nourdin and Rosiński69, Theorem 3.1], to show the asymptotic independence it suffices to check the following two conditions:
 \begin{align} \int_{[0,1]^2} R_n(x, y) W(x, y) \mathrm{d} x \mathrm{d} y \rightarrow 0 \quad\text{and}\quad \int_{[0, 1]^2} \left(\int_0^1 R_n(x, z) W(z, y) \mathrm{d}z \right)^2 \mathrm{d} x \mathrm{d} y \rightarrow 0. \end{align}
The first condition in (B1) follows from [Reference Lovász52, Lemma 8.22]. For the second condition note that
 \begin{align*} & \int_{[0, 1]^2} \left(\int_0^1 R_n(x, z) W(z, y) \mathrm{d}z \right)^2 \mathrm{d} x \mathrm{d} y \nonumber \\[5pt] & = \int_{[0, 1]^4} R_n(x, z) W(z, y) R_n(x, z') W(z', y) \mathrm{d}z \mathrm{d} z' \mathrm{d} x \mathrm{d} y \nonumber \\[5pt] & = \int_{[0, 1]^2} \left(\int_{[0, 1]^2} g_n(x, y) R_n(x, z) W(z, y) \mathrm{d} x\mathrm{d}z\right) \mathrm{d} y\\ &\qquad\qquad\qquad\qquad\qquad \text{(where $g_n(x, y) \;:\!=\; \int_{[0, 1]} R_n(x, z') W(z', y) \mathrm{d} z'$)} \nonumber \\[5pt] & \leq \|R_n\|_{\square} \rightarrow 0. \nonumber \end{align*}
This establishes the second condition in (B1) and completes the proof of Lemma 10.
Appendix C. A central limit theorem for weighted sum of centered chi-squared random variables
In this section we establish a central limit theorem for an infinite weighted sum of independent centered
 $\chi^2$
random variables.
Lemma 11. Consider a sequence of infinite sequences
 $\{(a_s^{(n)}\;:\; s\geq 1)\}_{n \geq 1}$
satisfying the following conditions:
 \begin{align} \lim_{n \rightarrow \infty} \max_{s \geq 1} \big| a_s^{(n)} \big| = 0 \quad \textit{and} \quad \lim_{n \rightarrow \infty} \sum_{s \geq 1} \big(a_s^{(n)}\big)^2 = \tau^2 , \end{align}
for some constant
 $\tau \geq 0$
. Let
 $\{\xi_s\}_{s \ge 1}$
be an i.i.d. sequence of
 $\chi^2_k-k$
random variables. Then the infinite sum
 $\sum_{s \geq 1} a_s^{(n)} \xi_s$
is well defined, for n large enough, and, as
 $n \rightarrow \infty$
,
 \begin{align} \sum_{s \geq 1} a_s^{(n)} \xi_s \stackrel{D} \rightarrow N\big(0,2k \tau^2 \big) . \end{align}
Proof. Fix
 $M \geq 1$
and let
 $\mathcal{F}_M \;:\!=\; \sigma(\{\xi_s\}_{s=1}^M)$
be the sigma-algebra generated by
 $\{\xi_s\}_{s=1}^M$
and
 $S_M^{(n)} \;:\!=\; \sum_{s=1}^M a_s^{(n)} \xi_s$
. Then
 $(S_M, \mathcal{F}_M)$
is a martingale with
 $$\sup_{M \geq 1}\mathrm{E} \big(S_M^{(n)}\big)^2 \leq \sum_{s \geq 1} \big(a_s^{(n)}\big)^2 < \infty,$$
for all n large enough. Hence, the sum
 $\sum_{s \geq 1} a_s^{(n)} \xi_s$
is well defined, for n large enough.
We will show (C2) by establishing the convergence of the moment generating function (MGF). By [Reference Bhattacharya, Diaconis and Mukherjee13, Proposition 7.1] we know that the MGF of
 $\sum_{s \geq 1} a_s^{(n)}\xi_i$
is well defined in a neighborhood of zero. In particular, for
 $|\lambda| < \frac{1}{8}$
, we have
 \begin{align*} \mathcal{E}_n(\lambda) \;:\!=\; \mathrm{E}\left( \mathrm{e}^{\lambda \sum_{s \geq 1} a_s^{(n)}\xi_i } \right) = \prod_{s \geq 1} \frac{\mathrm{e}^{- \lambda k a_s^{(n)}}}{\left(1-2 \lambda a_s^{(n)}\right)^{\frac{k}{2}}} . \end{align*}
Taking logarithms on both sides,
 \begin{align} \log \mathcal{E}_n(\lambda) = -\frac{k}{2} \sum_{s \geq 1} \log\big(1-2 \lambda a_s^{(n)}\big)- \lambda k \sum_{s \geq 1} a_s^{(n)} & = \frac{k}{2}\sum_{s \geq 1} \sum_{t=1}^\infty\frac{\big(2 \lambda a_s^{(n)}\big)^t}{t} - \lambda k \sum_{s \geq 1} a_s^{(n)} \nonumber\\[5pt] & = \frac{k}{2}\sum_{s \geq 1} \sum_{t=2}^\infty\frac{ \big(2t a_s^{(n)}\big)^t}{t} \nonumber\\[5pt] & = \frac{k}{2}\sum_{s \geq 1} \sum_{t=3}^\infty\frac{\big(2 \lambda a_s^{(n)}\big)^t}{t} +k \lambda^2 \sum_{s \geq 1} \big(a_s^{(n)}\big)^2 . \end{align}
Denote by
 $a^{(n)}_{(s)}$
the sth largest among
 $\{a_s^{(n)}\}_{s \geq 1}$
. Then, for any
 $L \geq 1$
, we have
 \begin{align*} 4 \tau^2 \geq \sum_{s\geq 1} \big(a_s^{(n)}\big)^2 \geq\sum_{s=1}^L\big(a^{(n)}_{(s)}\big)^2\geq L \big(a^{(n)}_{(L)}\big)^2 , \end{align*}
for all n large enough. (Note that the first inequality in the display above holds for all n large enough by the second condition in (C1).) This implies that
 $a^{(n)}_{(L)}\leq \frac{2\tau}{\sqrt{L}\,}$
, for n large enough and
 $L \geq 1$
. Hence, for
 $|\lambda| < \frac{1}{8 \tau}$
,
 \begin{align} \sum_{s \geq 1} \sum_{t=3}^\infty\frac{|\lambda a_s^{(n)}|^t}{t} \leq \sum_{s \geq 1} \sum_{t=3}^\infty | \lambda a^{(n)}_{(s)}|^t \leq \sum_{s \geq 1} \sum_{t=3}^\infty\left\lvert\frac{4 \lambda \tau}{\sqrt{s}\,}\right\rvert^t & \leq \sum_{t=3}^\infty\sum_{s \geq 1} \left\lvert\frac{1}{2\sqrt{s}\,}\right\rvert^t < \infty . \end{align}
This shows that the double sum in (C3) is absolutely convergent. In addition, for
 $t \geq 3$
,
 \begin{align*} \lim_{n \rightarrow \infty} \left|\sum_{s \geq 1} (a_s^{(n)})^t\right| \leq \lim_{n \rightarrow \infty} \Big(\max_{s\geq 1} \big| a_s^{(n)}\big|\Big)^{t-2} \sum_{s \geq 1} \big(a_s^{(n)}\big)^2 = 0 , \end{align*}
from (C1). Hence, by the dominated convergence theorem on the sequence of functions
 $f_n(t) = \sum_{s\geq 1}|a^{(n)}_{(s)}|^{t}$
(observe that the bound in (C4) is uniform over n),
 $$ \lim_{n \rightarrow \infty} \sum_{s \geq 1} \sum_{t=3}^\infty\frac{\big|\lambda a_s^{(n)}\big|^t}{t} = 0.$$
Hence, taking limits as
 $n \rightarrow \infty$
on both sides of (C3) gives, for
 $|\lambda| < \frac{1}{8 \tau}$
,
 \begin{align*} \lim_{n\rightarrow\infty}\mathcal{E}_n(\lambda)= \mathrm{e}^{k \tau^2 \lambda^2 } , \end{align*}
which is the MGF of
 $N(0, 2k \tau^2)$
. This completes the proof of Lemma 11.
Funding Information
B. B. Bhattacharya was supported by NSF CAREER grant DMS 2046393, NSF grant DMS 2113771, and a Sloan Research Fellowship. M. Daros was supported by NSF grant 1953848.
Competing Interests
There were no competing interests to declare which arose during the preparation or publication process of this article.
Acknowledgements
The authors thank Giulio Zucal for pointing them to the references on decorated and probability graphons. The authors also thank the anonymous referees for their thoughtful comments, which greatly improved the quality and the presentation of the paper.



