Research on international productivity comparisons has highlighted the difficulties in reconciling benchmark comparisons across countries with backward extrapolations from other benchmarks. Whether such productivity puzzles are genuine or just the result of incomplete data exploration has been controversial.Footnote 1 Recently, Stephen Broadberry and Carsten Burhop [henceforth B & B] looked into benchmark comparisons of Anglo-German industrial productivity to evaluate two rivaling indices of German industrial production against each other.Footnote 2 They found that a recent revision to the German index of industrial production by Ritschl would induce an Anglo-German productivity puzzle for the pre–World War I years, while the traditional industrial output data for Germany by Walther Hoffmann does not.Footnote 3
This observation led B & B to discard the revised industrial production index for Germany in favor of the traditional one. Specifically, they argued that the revised German output series yields an implausibly high German productivity lead over Britain on the eve of World War I, which is not borne out by their comparative productivity estimate for 1907. Once the older, disputed industrial output index was employed instead, the fit with the 1907 productivity benchmark was good.
A trade-off therefore seems to exist between the quality of the fit and the quality of the series employed. Hoffmann's index of industrial production has been criticized for the implausibly high levels of industrial recovery in the late 1920s, and again in the 1930s.Footnote 4 Among other things, it implies that output in metal-making and metal processing was 70 percent above the prewar level in 1929, and no less than 180 percent higher than the prewar levels in 1938. Building on a large German literature on failed economic reconstruction after World War I, Ritschl argued that Hoffmann's index was heavily upward biased, and was grossly inconsistent with existing evidence on iron and steel consumption, as well as with output data from the relevant subsectors.Footnote 5 If it takes this index to reconcile productivity benchmark comparisons between Germany and Britain, there is an Anglo-German productivity puzzle that has to be resolved.
This article revisits the Anglo-German industrial productivity puzzle. To resolve it, it revises the time series evidence one more time and also recalculates the 1907 productivity benchmark. Three clear tendencies emerge from this exercise. First, the revisions to the German industrial production index by Ritschl can be further substantiated for the 1920s.Footnote 6 Second, new evidence by Rainer Fremdling and Reiner Staeglin on armament industries hidden in Germany's 1936 industry census suggest a slight upward revision of levels in that year.Footnote 7 Third, careful revision of the 1907 benchmark leads to significantly higher estimates of German productivity. This is largely, but not entirely due to removing upward bias in B & B's estimates of German employment. If similar lower cutoff levels in firm size are assumed as in Britain (and as in the 1935 benchmark), the German productivity lead becomes much more pronounced. And there is no contradiction between the corrected time series evidence and the corrected benchmark for 1907—in short, no Anglo-German productivity puzzle.
The findings of this article relate to a long debate about the productivity of German industry relative to Britain's before and between the World Wars. An older literature, by scholars such as Alexander Gerschenkron or David Landes, took it for granted that German industry had enjoyed a substantial productivity lead over Britain prior to World War I.Footnote 8 Evidence also suggested that the comparative productivity performance of German industry was not similarly strong in the 1930s.Footnote 9 All this pointed to a relative decline of German industry in the interwar period, which seemed consistent with contemporary indices of industrial production worked out by Rolf Wagenführ.Footnote 10 Pessimistic assessments of the state of German industry given by contemporary economic experts after World War II further bolstered this view. Adam Tooze has gone as far as to argue for an industrial failure of Germany in the 1930s.Footnote 11
Revisions to the conventional wisdom about Anglo-German comparative productivity trends were prompted by Fremdling's work for 1907 and by Broadberry and Fremdling's or 1935/36.Footnote 12 These studies found productivity in German manufacturing to be roughly at par with Britain's before World War I, and slightly ahead of Britain's before World War II. Broadberry related Germany's poor industrial showing before World War I to its large peasant agriculture and its backwardness in services.Footnote 13
Recently, new studies have emerged, which recalculated the old results with refined methodologies and from a broader database. Broadberry and Burhop recalculated Fremdling's productivity benchmark comparison for 1907 and arrived at broadly the same results.Footnote 14 And Herman de Jong, Fremdling, and Marcel Timmer reworked the 1935 productivity benchmark.Footnote 15 Yet in spite of an improved methodology and access to vastly better data, they again arrive at broadly the same aggregate results, important sectoral differences notwithstanding. They also found that proper adjustments of employment levels are crucial: the British industry census methodology used in Germany in 1935/36 entailed a significantly narrower employment concept than the German workplace censuses of 1907, 1933, and 1939, because it excluded employment in small establishments, as well as seasonal and part-time industrial employment in largely agricultural areas. My revisions to the industrial productivity benchmark of 1907 follow the same logic: I suggest adjustments that make the coverage of German industrial employment comparable to the British census in 1907 as well.
RESTATING THE PRODUCTIVITY PUZZLE
The first step toward resolving the Anglo-German productivity puzzle is to restate it. B & B employed two different indices of German industrial output in the 1935 and 1907 benchmark comparisons with Britain. The first was the traditional Hoffmann series, which Broadberry has also used.Footnote 16 With this index, B & B find no inconsistency between the backward extrapolation from 1935 and the productivity benchmark comparison for 1907. The alternative index relies on Ritschl's corrections to Hoffmann's series.Footnote 17 When B & B extrapolate backward from 1935 with this index, the discrepancies with the 1907 benchmark are substantial.
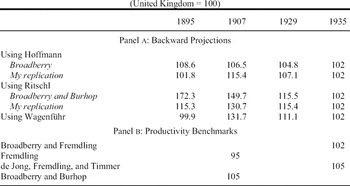
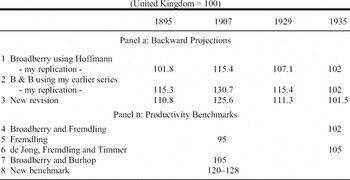
In addition to replicating their exercise, this section also includes the industrial production series of Wagenführ, which was used semi-officially in the interwar period.Footnote 18 The upper panel of Table 1 shows three different time series estimates of German labor productivity relative to the United Kingdom, calculated from the three indices of German manufacturing output. All data shown in the upper panel of Table 1 are backward extrapolations from the comparative industrial productivity level of 102 (United Kingdom = 100), found by Broadberry and Fremdling for 1935, and for comparable sectors of industry.Footnote 19 Employment as well as U.K. output is the same as in B & B.
ESTIMATES OF COMPARATIVE PRODUCTIVITY IN GERMAN MANUFACTURING

Notes:
All data refer to changing territory. Data exclude mining, utilities, and construction. Data for Britain are from Feinstein, National Income.
Sources:
Hoffmann, Das Wachstum; Broadberry, Productivity Race; Ritschl, “Spurious Growth”; Broadberry and Burhop, “Comparative Productivity”; Wagenfuehr, “Die Industriewirtschaft”; Broadberry and Fremdling, “Comparative Productivity”; Fremdling, “Productivity Comparison”; and de Jong, Fremdling, and Timmer, “British and German Manufacturing.”
The backward projections in the upper panel of Table 1 all suggest a German productivity lead over Britain on the eve of World War I. Using Hoffmann's industrial production series, Broadberry obtained a mere 6.5 percent German lead for 1907.Footnote 20 My attempted replication of this estimate in Table 1 points to a 15 percent German productivity lead that year. When B & B use Ritschl's correction of Hoffmann's index, they obtain a 1907 productivity lead of almost 50 percent, a puzzling result that they discard as implausible.Footnote 21 My replication of their estimate using the same data and methods finds a lower—yet still substantial—30 percent productivity lead for 1907.Footnote 22 If I use the Wagenführ index instead, the German productivity lead in 1907 is again around 30 percent.Footnote 23 Overall, use of the Wagenführ series and Ritschl's revision of Hoffmann's index lead to similar results.
The lower panel of Table 1 provides an overview of the existing benchmark productivity comparisons. With a mere 95 percent of British productivity in 1907, the Fremdling benchmark is probably on the low side.Footnote 24 The B & B benchmark for the same year suggests a modest German productivity lead of 5 percent and fits Broadberry's time series projection for 1907 almost perfectly.Footnote 25 The fit would still look acceptable for my reconstruction of Broadberry's time series extrapolation with Hoffmann's index.Footnote 26 For the revised series of Ritschl, as well as the Wagenführ estimate, the discrepancy between their 30 percent productivity lead and the 5 percent suggested by the benchmark is considerable—although it is still far below the 50 percent productivity lead suggested by B & B for the Ritschl series.Footnote 27 Yet even the remaining discrepancies are puzzling: it seems that improving the time series worsens the fit with the 1907 productivity benchmark. This discrepancy is the Anglo-German productivity puzzle.
REVISITING THE TIME SERIES EVIDENCE
To resolve the productivity puzzle in Table 1, one strategy is to pick the series that produces the best fit, and to discard the rest. This is the option chosen by B & B, and it leaves the researcher with Hoffmann's index for Germany.Footnote 28 The price to be paid for this is committing to a time series that is likely to exhibit spurious growth across World War I. Ritschl examined Hoffmann's index in the light of disaggregate industrial output data for 1913 and the late 1920s.Footnote 29 His finding was that Hoffmann's series for capital-goods industries did not match with existing contemporary data on machine building and related industries. To construct alternative estimates of output in the metal processing industries, he used series from the respective industry associations, as well as a detailed commodity-flow estimate of equipment investment in the German economy by Gerhard Gehrig.Footnote 30 The resulting series were consistent with the official statistics on gross investment as well as with domestic steel consumption and machinery exports.Footnote 31 They also fit the components in Wagenführ's index of industrial production.Footnote 32 But they differed sharply from Hoffmann's estimate for the same industries.Footnote 33
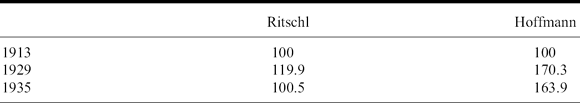
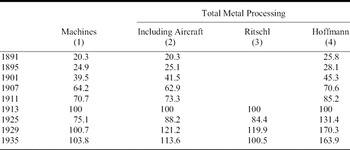
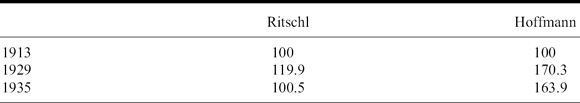
Ritschl's estimate (Table 2) suggests that between 1913 and 1929, output in Germany's metal-processing sector grew by roughly 20 percent (or 30 percent if one adjusts for the loss of territory after World War I), which is roughly consistent with British data for the same period in Charles Feinstein's study.Footnote 34 In contrast, Hoffmann's index of production for the same industry yields an output increase of 70 percent between 1913 and 1929.Footnote 35 One reason is that Hoffmann calculated his estimate for this sector from the income side, using wage bills and assuming constant wage shares in value added. This approach towards estimating output ignores the substantial increase in labor's bargaining power in Germany after 1918. Ritschl showed that all available estimates of German industrial output and national product except for Hoffmann's output series imply a strong increase in wage shares between 1913 and 1929.Footnote 36 Using the Wagenführ industrial production index, Broadberry and Ritschl found that the implied increase in industrial wage shares across World War I was similar to that implied by the British data.Footnote 37 The resulting profit squeeze in German industry between 1913 and 1929 is a classical theme in German historiography that has generated a large literature, yet Hoffmann's index merely assumes it away.Footnote 38 As Ritschl shows, if in Hoffmann's index of industrial production, the income estimate for metal processing is revised using contemporary data, the resulting aggregate index tracks Wagenführ's index closely.Footnote 39 The productivity discrepancies in extrapolated German productivity shown in Table 1 thus seem to rest largely on the assumptions about the metal processing industry.
TIME SERIES ESTIMATES OF OUTPUT IN GERMAN METAL PROCESSING
Notes:
All data are indices (1913 = 100) and refer to changing territory. Total metal processing also includes shipbuilding and cars. The Hoffmann index is estimated from wage bills.
Sources:
Ritschl, “Spurious Growth”; and Hoffmann, Das Wachstum.
Ritschl's revisions were partly an attempt to find evidence that is independent of both the Hoffmann and the Wagenführ indices.Footnote 40 The key element was constructing a new index of machine production for the period between 1913 and 1928. This new series could then be aggregated with series from other industries in the metal working sector to provide a new output estimate of the sector as a whole. Recent archival findings by Fremdling make it possible to refine this calculation further, and to substantiate its central assumptions.Footnote 41
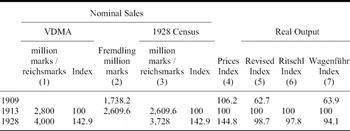
The German machine industry association, the Verein Deutscher Maschinenbau-Anstalten (VDMA), published sales figures for 1913 and from 1925 to 1928.Footnote 42 In 1928 an official industry census for machine building yielded slightly lower numbers than the VDMA for the same year. Extrapolating backwards from the 1928 census using the deflated sales data and companion data from the VDMA, Ritschl arrived at slightly higher output growth in machinery than Wagenführ.Footnote 43
Archival data from the VDMA reported by Fremdling pin down the growth rate of machinery output between 1913 and 1928, as well as the 1913 level (see Table 3).Footnote 44 For the industries covered by his source, Fremdling finds sales in 1913 to be 2609.6 mill. M (see Table 3, column 2), as opposed to the VDMA's 2800 mill. M (see Table 3, column 1).Footnote 45 The percentage discrepancy between both 1913 benchmarks exactly matches the percentage discrepancy between the VDMA's own sales data for 1928 and the official census for that year (Table 3, column 3).Footnote 46 This suggests that the 1928 machine industry census was conducted for the same reporting group of machine producers for which Fremdling worked out the 1913 benchmark.Footnote 47
RECALCULATING OUTPUT IN GERMAN MACHINE BUILDING

Notes:
Ritschl's and Wagenführ's real output figures are shown for comparison to the revised estimate.
Sources:
Calculated from Ritschl, “Spurious Growth”; and Fremdling, “Machine Building.” VDMA, Statistisches Handbuch. Wagenführ, “Die Industriewirtschaft.”
If so, the VDMA figures in Table 3 (column 1) describe growth between these benchmarks correctly, while overstating levels in both 1913 and 1928. The 1913 output within the reporting group of the 1928 machine census (Table 3, column 3) must then equal Fremdling's benchmark value of 2609.6 mill. M (Table 3, column 2).Footnote 48 If we deflate Table 3 (column 3) by machinery prices (column 4), real output of machinery (column 5) is seen to decline slightly between 1913 and 1928. The decline is very close to Ritschl's data.Footnote 49 By contrast, Wagenführ's estimates suggest a larger decline between 1913 and 1928.Footnote 50
Fremdling's archival data thus confirm the existing revisions of Hoffmann's estimates for metal working during the 1913 to 1928 period.Footnote 51 In other words, if “Hoffmann's tales” are replaced with actual data, the traditional picture reappears: profits in metal processing were much larger before the war than afterwards, and the output of this industry increased only moderately between 1913 to 1928, instead of shooting up.Footnote 52 In any case, reverting to the original Hoffmann data no longer seems to be an option. There is solid evidence on output in the industries in question across World War I, and it tells a different story. Any time series projection of comparative productivity simply has to deal with this evidence.
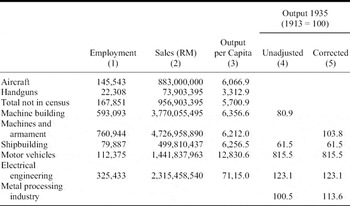
Further revisions suggest themselves for the 1930s from a reassessment of Germany's 1936 industry census by Fremdling and Staeglin.Footnote 53 According to their results, the production of military aircraft, along with some minor armament industries, is missing from the industry aggregates of this census, and is instead included in the construction sector. The industries in question employed about 168 thousand people in 1936 and generated sales of about 956 mill. RM. For aircraft industry with 145 thousand people at work, gross output was 883 mill. RM or 6,067 RM per capita.Footnote 54
As Table 4 reveals, in 1936 the aircraft and small firearms industries together were slightly smaller than the auto industry in terms of output, but somewhat larger in terms of employment.Footnote 55 Employment in these armament industries was about 28.3 percent of employment in machine building, with slightly lower productivity. There is good reason to assume that these industries are missing from the traditional Wagenführ index and its continuation in the IfK publications—which would, after all, explain why Hoffmann chose such a roundabout way of estimating output in the metal-processing industries.Footnote 56
GERMAN AIRCRAFT AND ARMAMENT INDUSTRY IN 1936

With the information now at hand, Hoffmann's income-side estimate for the metal-processing industries can be replaced by an output estimate based on the 1935/6 benchmark.Footnote 57 To add aircraft and armament industry to the index of industrial production for 1936, machine building seems to be the proper choice. Also, it seems plausible to assume that in the mid-1930s, machinery and aircraft production grew roughly at the same rates. If so, the index (with 1913 = 100) for machine building for 1935 increases by 28.3 percent, that is, from 80.9 to 103.8 (see Table 4).Footnote 58 This neglects aircraft production in 1913, which however was still small.Footnote 59
We can combine the evidence from Table 4 and the resulting new machinery series (Table 5, column 1) to recalculate output in metal-processing industry for key years from 1881 to 1935. Calculation of this series follows the same methods as in Table 2, column (5) until 1929, and includes the revised 1935 entry from Table 4, column (5). This series is then aggregated with data on electrical industry, cars, and shipbuilding to yield a production index for metal-processing industry, using a procedure described by Ritschl.Footnote 60 This revised series (in Table 5, column 2) is one index point higher than Ritschl's index (in Table 5, column 3) for 1929, and 13 index points higher for 1935.Footnote 61 It implies cumulative growth of German metal-processing industry from 1913 to 1935 of 13 percent, compared to 64 percent in the Hoffmann data (in Table 5, column 4).Footnote 62
RECALCULATING OUTPUT IN GERMAN METAL PROCESSING

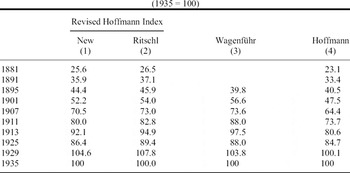
The new series can then be substituted into the Hoffmann index of industrial production.Footnote 63Table 6 shows the new revision alongside Ritschl's previous estimate as well as those of Hoffmann and Wagenführ's original indices.Footnote 64
INDUSTRIAL PRODUCTION INDICES FOR GERMANY

Sources and Methods:
All series for categories comparable to Feinstein, National Income. See the text for calculation of the revised Hoffmann series. All data refer to changing territory.
Both the new revision and Ritschl's previous version track Wagenführ's figures closely between 1913 and 1929.Footnote 65 The new revision and Wagenführ's seem to agree on the relative levels of 1929 and 1935, that is, before and after the depression, while Hoffmann's estimate overstates the speed of recovery, and Ritschl's previous series understates it.Footnote 66 The net effect continues to be a drastic downward revision of Hoffmann's growth estimate between the benchmarks of 1907 and 1935. Cumulative growth in this period according to the new revision is 41.8 percent. This is up from 36 percent in the series of Wagenführ and 37 percent in the earlier revision of Hoffmann's series by Ritschl.Footnote 67 By contrast, Hoffmann's series implies a higher figure of 55.2 percent.Footnote 68
As a result of these revisions, the backward extrapolations of output and productivity from 1935 to 1907 will be slightly lower than the Wagenführ index or Ritschl's earlier data would imply.Footnote 69 However, it is still much higher than the backward extrapolation using Hoffmann's figures.Footnote 70 Before the backward extrapolations are discussed in more detail, the next section will revise the 1907 benchmark.
REVISITING THE 1907 PRODUCTIVITY BENCHMARK
The existing Anglo-German productivity benchmarks of Fremdling and B & B are partly based on censuses undertaken in both countries in 1907.Footnote 71 Yet as I will argue, there is a serious mismatch in employment coverage between these two censuses, which leads to an overestimate of German employment and an underestimate of productivity. The British industry census of 1907 provides rich details on physical production, gross output, and value added, but is considerably less detailed on employment.Footnote 72 In terms of coverage, the British census omits one-person establishments, small firms employing only men, as well as helping family members, and an unknown percentage of outworkers in cottage industries.Footnote 73 In contrast, the German workplace census of 1907 provided a full count of all employment. For comparable categories, the shortfall of the British census is between 25 and 30 percent.Footnote 74
Not all German data used in the B & B productivity benchmark are from the workplace census. B & B rely also on annual industry surveys, as well as statistics on the output of taxable goods.Footnote 75 For a rather limited range of industries, the annual surveys provide revenues, sometimes physical output, several cost items, and in some cases, employment.Footnote 76 The tax statistics provide output figures for industries like beer, sugar, tobacco, and salt. For all industries, employment data by firm size are available from the 1907 workplace census.
The gaps of the German data cause problems of mutual compatibility. Participation in the industry surveys was limited to firms included in the national disability insurance scheme. This excluded Germany's large crafts sector, as well as most small-scale establishments. Comparison with the firm size data in the 1907 census reveals that the surveys were often limited to firms with 50 employees or more. In contrast, the German 1907 workplace census is a full count of employment in the private sector, and provides a fairly detailed breakup of employment by establishments and lines of production.
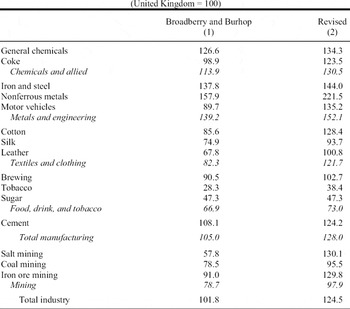
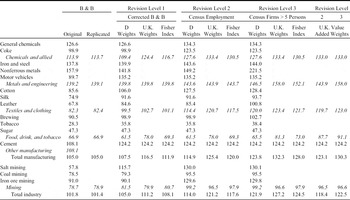
In their productivity benchmark for 1907, B & B adhere to the industry surveys for Germany whenever possible, otherwise drawing on the tax statistics for additional output data and on the 1907 workplace census for employment. Their preferred option is to compare physical output per capita, or alternatively real output as deflated by unit value ratios. The first column of Table 7 reproduces the results of their comparison. It shows a substantial German productivity lead in chemical industry and metal making, while the United Kingdom is seen to lead in textiles as well as in food, drink, and tobacco. On the whole, B & B find a 5 percent productivity lead in German manufacturing over Britain. Aggregating over manufacturing and mining, B & B find German industrial productivity around 1907 to have been a mere 2 percent higher than in Britain.Footnote 77
ANGLO-GERMAN BENCHMARK COMPARISON OF INDUSTRIAL PRODUCTIVITY, 1907

Sources and Methods:
See Broadberry and Burhop, “Comparative Productivity.” See also Appendix Table 1 and Appendix Table 2.
Table 7 also reports two new productivity benchmarks for 1907, with substantial upward revisions over the B & B estimate. Averaging over these revisions, German manufacturing productivity was about 25 percent ahead of Britain. For industry including mining, Germany's productivity lead was probably a few percentage points lower.
Corrections and revisions to the B & B productivity benchmark seem advisable for three reasons. First, some of the choices made by B & B in calculating their data for Germany would seem problematic, and a number of apparent errors need to be dealt with (see the Appendix for a more detailed discussion). To highlight but a few points, one issue is that not all German data in the B & B benchmark are from 1907, but rather from industry surveys for 1908 or 1910. Weighed by employment, these later data dominate their estimate, with a 68 percent share for data from 1908 and another 4 percentage points for the 1910 data, respectively. Since the chemical industry and iron and steel went into recession after 1907, their productivity in 1908 and 1910 as reported in B & B is likely to understate the 1907 levels. Yet the German surveys do provide data on many of the same industries for the benchmark year of 1907. Inserting the 1907 data whenever possible, I find that the productivity estimates increase across the board. For the auto industry, I use the 1907 data in the German source used by B & B, and find productivity to be higher than in Britain.Footnote 78
For the textile industries, B & B aggregate over employment in spinning and weaving on the basis of output data in spinning alone, as comparable output data for weaving are absent. This would probably be innocuous in the absence of foreign trade in yarn. However, given that Britain was a heavy exporter and Germany both an importer and exporter of yarn (albeit of different qualities), this procedure is likely to be misleading, as domestic yarn output is no longer a good input measure of output in weaving. Thus I rely on spinning alone.Footnote 79 Moreover, the B & B employment data for Germany appear to include substantial employment in trade rather than in production, which inflates the denominator of their German productivity estimate. My reconstruction arrives at distinctly lower levels of employment in the spinning industry.
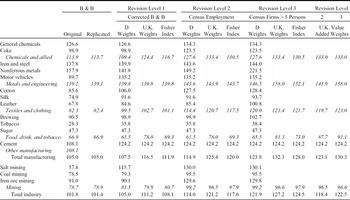
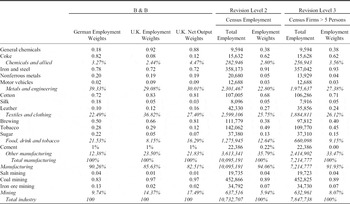
Major corrections apply to tobacco, where B & B capture only 30 percent of domestic tobacco supply in Germany, and to salt mining, where B & B report salt works instead of mines for Germany. Appendix Table 2 (Revision Level 1) reports my version of the B & B employment and productivity benchmark. As a result of these corrections, German comparative productivity around the benchmark rises to 112 percent of the British level in manufacturing, or 108 percent in total industry including mining.Footnote 80
A second source of revisions comes in through differences in employment coverage between the German industry surveys and the 1907 census. B & B adhere to the survey data of employment in chemical industry, the metal and engineering trades, leather, and mining. However, these employment data can be misleading when it comes to productivity measurement, because of employment in multi-product firms. The surveys follow a firm-oriented concept and take a shortcut by allocating employment to the major product line in the main establishment of a firm. This implied counting all employment in these establishments towards the main product. As a consequence, steel workers would be included in the employment of coal producers and vice versa, depending on the respective firm's major product. This resulted in over-reporting of employment in some of these industries.
By contrast, the 1907 workplace census followed a product-oriented concept. In order to provide a clean breakdown of employment in multi-product firms, employees were asked individually to report their employment by the relevant product category on the census date. On balance, census employment levels are therefore lower than in the industry survey data. To the same extent, the industry survey data understate productivity, not at a firm level but per unit of specific products.Footnote 81 In essence, they reflect the high degree of vertical integration between German coal and steel, and of horizontal integration in chemical industry.
Related difficulties exist in the British census data. To deal with these problems, B & B break down employment by the relevant product's percentage in value added.Footnote 82 The German census employment data provide this breakdown directly (while a breakdown by value added is often not possible).
This discrepancy gives rise to a revision of the B & B benchmark that goes beyond mere adjustments. Revision Level 2 in Appendix Tables 1 and 2 shows the results of using census employment whenever possible. Replacing the (firm-specific) survey data on employment with the (product-specific) workplace census data on employment leads to upward revisions of productivity in the chemical and metals industries, as well as in mining. As a result of this revision, comparative productivity in German manufacturing rises to 120 percent of British levels. For industry including mining, the estimate is around 118 percent.Footnote 83
A third source of revisions derives from the different treatment of very small enterprises in the British and German data. The British industry census of 1907 excluded one-person establishments, family helpers and some outworkers, and small establishments of less than 10 employees where only men were working. The census estimates the resulting employment pitfall at roughly 25 percent.Footnote 84 In contrast, the German workplace census of 1907 aimed at the total working population. The difference leads to a mismatch between the censoring points of the firm size distributions in the German workplace census and the British industry census. This mismatch is insignificant in chemical and most of metal industry as well as in mining, where large firms prevailed. It is more of a problem in the food, drink and tobacco industries in the index, where small-scale establishments were quantitatively important.
Evidently, the employment figures cannot simply be adjusted without taking care of the output figures as well. For the German output data from the industry survey, this is not a problem. In the surveys, only the larger firms were included. Hence the output estimate does not need to be adjusted when removing the smaller firms from the employment data.Footnote 85 By contrast, the statistics for these taxable goods include all legally produced output, and hence also the output of small establishments. I follow the British 1907 census, as well as de Jong, Fremdling, and Timmer for the German 1936 census, in assuming that small establishments were 20 percent less productive than larger firms.Footnote 86
Textiles present some special problems. The only product categories comparable to Britain in 1907 seem to be cotton and silk spinning. The German surveys for cotton spinning cover only 398 out of 1062 firms counted in the 1907 census.Footnote 87 In that census, 379 firms were reported to have 50 or more employees. This implies that neither the smaller firms nor their output were counted in the surveys. The surveys did, however, include the output of outworkers and cottage industries working for the firms surveyed.Footnote 88 I have therefore adjusted employment in cotton spinning by excluding only small firms. Outworkers in cottage industries, who accounted for roughly 8 percent of employment in cotton spinning, are left in the sample. Very similar adjustments apply to the smaller silk spinning industry.
Appendix Tables 1 and 2 report the results from adjusting for firm size in the German employment and output data. Revision Level 3 subtracts employment in establishments of five persons or less (again, except for outworkers in textiles) from the German employment data. The resulting coverage is probably slightly narrower than its British counterpart. The resulting estimate “Revision Level 3” in Appendix Tables 1 and 2 then provides an upper bound for productivity. For manufacturing, this upper-bound estimate suggests a 28 percent productivity lead for Germany in 1907. With mining, German industry was up to 25 percent ahead of the United Kingdom.
In sum then, the revised productivity benchmark for 1907 yields substantially higher German productivity. About 30 percent of the increase can be attributed to minor corrections and improvements to the B & B benchmark. The other 70 percent stem from adjustments made because of mismatches in employment coverage between the British industry census, the German employment census, and the German industry surveys. Once employment coverage in the two countries is put on the same footing, the traditional picture of a substantial German productivity lead reappears. However, Germany's sectoral productivity performance in 1907 continues to look very uneven. While Germany clearly led in the chemical and metal trades, German productivity in the food industries was very low. To this extent, the basic findings of Broadberry's earlier work on Germany's comparative advantage are preserved.Footnote 89
PUTTING THE PIECES TOGETHER: RESOLUTION OF THE PRODUCTIVITY PUZZLE
Both the revised time series evidence and the revised 1907 benchmark can now be fed back into the productivity comparisons of Table 1.
Table 8 recalculates the productivity comparisons of Table 1, both along the time series dimension, shown in the upper panel, and for the benchmarks, shown in the lower panel. The new extrapolation (row 3) is based on the revision of Hoffmann's German industrial production index from Table 6, which incorporates the evidence on the aircraft industry by de Jong, Fremdling, and Timmer, and the conclusions of the previous section for 1907.Footnote 90 The revisions to the benchmarks have a double effect. Including the hidden armament industries for 1935 lowers German productivity slightly. Adjusting the German employment statistics for 1907 (Table 8, row 8) boosts German productivity substantially.
REVISED ESTIMATES OF COMPARATIVE PRODUCTIVITY IN GERMAN MANUFACTURING

Notes: All data refer to changing territory. Data exclude mining, utilities, and construction. See Tables 1 and 6 for details on the backward projections. See Table 7 and Appendix Table 2 for revised 1907 benchmark.
As for the revision to the time series evidence discussed previously, it has two effects. First, it reduces the decline of industrial output between 1929 and 1935: once one accounts for the Heinkel bomber, Germany's industrial recovery from the Great Depression is more complete than suggested in my earlier revision.Footnote 91 Second, the revision to the time series also implies somewhat lower productivity levels relative to Britain before 1929. As a net effect, the revised time-series estimate of Germany's productivity lead over Britain in 1907 (Table 8, row 3) is 26 percent, down from 31 percent in the unadjusted estimates of Table 1 above, and from 50 percent in B & B.
If we combine the revised time series extrapolation and the revised productivity benchmark for 1907, there is no longer any discrepancy left: the time series evidence suggests a 26 percent productivity lead, while the benchmark suggests that German manufacturing was between 20 percent (Revision Level 2) and 28 percent (Revision Level 3) ahead. In other words, the Anglo-German productivity puzzle disappears.
All the evidence examined here indicates that Germany enjoyed a growing productivity lead in manufacturing over Britain prior to World War I. Given the paucity of comparable data for 1907 and the inevitable pitfalls in the historical time series, it is hard to know whether the lead was closer to 20 or 30 percent. However, it seems safe to rule out extreme scenarios such as Germany trailing Britain in manufacturing around 1907 or instead forging ahead at 50 percent, as one of the calculations in B & B suggested.
CONCLUSIONS AND AVENUES FOR FUTURE RESEARCH
The Anglo-German industrial productivity puzzle of the early 1900s has a resolution. Careful reexamination of the evidence on Germany suggests revisions to both the time projections and the productivity benchmarks. Application of both methods suggest that in manufacturing, Germany had a substantial productivity lead over Britain on the eve of World War I, albeit with an uneven sectoral distribution.
Previous benchmark estimates, last proposed by Broadberry and Burhop, suggested a very small German productivity lead over Britain in 1907, or none at all.Footnote 92 At the same time, backward extrapolations from a 1935 benchmark implied an implausibly large productivity lead of 50 percent for 1907. This was the Anglo-German industrial productivity puzzle. This article has resolved the puzzle. It does so by undertaking further revisions to the German time series evidence, based on Fremdling and Staeglin's discovery of armament industry data hidden in Germany's industrial census in 1936.Footnote 93 This article also reworks the 1907 benchmark to take into account differences in employment coverage between the British and German data.
With these revisions in place, the Anglo-German productivity puzzle all but disappears. German manufacturing in 1907 turns out to have been 20 to 28 percent ahead of Britain if measured by the benchmark comparison method, or 26 percent ahead if measured by backward extrapolation. This puts traditional interpretations of German industrial dynamics prior to World War I firmly back on the map.Footnote 94 At the same time, however, the picture that emerges is very much that of a dual economy, as is already implicit in Broadberry's earlier work: while chemical industry, metals, and engineering appear to have been quite far ahead, the light industries in sectors closer to agriculture were not.Footnote 95 Yet the overall picture I obtain of these industries is less unfavorable to Germany than the data of Broadberry and Burhop would suggest.Footnote 96 This article also confirms that Germany underwent a remarkable slowdown in growth and productivity across World War I, as described by Knut Borchardt.Footnote 97 The implication is that Hoffmann's series (which has been employed by Angus Maddison and others), substantially overstates Germany's industrial and aggregate output growth after World War I.Footnote 98
Further research should concentrate on a full recalculation of a German industrial production index, combining the various existing revisions with the available archival data. Still, the Anglo-German industrial productivity puzzle appears to be resolved, given the information currently available.
Appendix: Data Sources and Methods Underlying the Revised 1907 Benchmark
GENERAL REMARKS
Appendix Table 1 and Appendix Table 2 report the Broadberry and Burhop benchmark productivity comparison for 1907, along with three revisions.Footnote 99 Appendix Table 1 provides employment levels and index weights, Appendix Table 2 shows comparative productivity. The British data are from the 1907 U.K. production census.Footnote 100 The German data are from industry surveys of production in Kaiserliches Statistisches Amt, from the workplace census of 1907, and from output data on taxable goods.Footnote 101 Coverage of employment differs considerably between the German and the U.K. data, as well as between the various different German data. This gives rise to a series of revisions.
Revision Level 1 is a corrected version of the B & B estimate, without adjustment of employment coverage.
Revision Level 2 is based on 1907 German workplace census employment. Entries show all employment including outworkers in cottage industries. As most of the German output data were sampled only from medium- to large-size firms, Revision Level 2 underreports German productivity in most sectors. Due to wider employment coverage than in the British data, it also underreports German comparative productivity.
Revision Level 3 excludes firms with five persons or fewer (but not any workers in cottage industry) from the German employment data. This aims to establish comparable levels of coverage with the U.K. data, which exclude one-person firms, all-male establishments with up to ten employees, and an unknown percentage of outworkers in cottage industries. For those German industries (mostly taxable goods) where all output was reported, output in Appendix Table 2 is adjusted accordingly, assuming the excluded employment categories were 20 percent less productive than the rest. No output adjustment is made to the production survey data, thus some underreporting of productivity in the respective sectors is still likely.
General Chemicals
Broadberry and Burhop (hereafter B & B) report German data for 1908, which they take from an industry survey.Footnote 102 For sulphuric acid, data are also available for the census year of 1907.Footnote 103 These data are consistent with the survey for 1908. Product-specific employment data in Appendix Table 1 are from the 1907 workplace census.Footnote 104 The U.K. data are from the Board of Trade.Footnote 105
Coke
The employment figures differ considerably across sources. The production surveys in Kaiserliches Statistisches Amt show 24,535 employed in 1908, and the 1907 census has only 15,632 in the same category.Footnote 106 However, the (firm-specific) survey categories include significant output of joint and related products such as tar and several varieties of gas. Hence their employment category is also wider and includes these lines of production as well. In contrast, the workplace census provides narrower (product-specific) employment concepts, which are to be preferred. Revision Levels 2 and 3 in Appendix Table 1 and Appendix Table 2 are based on the census employment data. Labor productivity growth according to the industry surveys averaged 5 percent per year from 1908 to 1911. To obtain productivity for 1907, I calculate output in 1908 into employment in 1907 and adjust for 5 percent productivity growth per annum. The resulting figure is 1384.4 metric tonnes of coke per capita of census employment in 1907, or 123.5 percent of British productivity levels. U.K. data (which exclude tar and gas) are from Board of Trade.Footnote 107
Iron and Steel
B & B's productivity comparison rests on unit value comparisons for major subgroups of this industry. As historical distinctions between the various groups of iron and steel are highly arbitrary, the preferred method of comparison is physical output and productivity, subtracting the inputs of pig iron. German data for 1907 from Kaiserliches Statistisches Amt (1909, p. 98) provide output along with employment following the survey concept.Footnote 108 Results are very close to the B & B estimate. U.K. data are from the Board of Trade.Footnote 109
Nonferrous Metals
B & B's productivity comparison rests on only two products, unwrought copper and unrefined zinc. The same industries produced a much wider range of products. However, the British sources do not provide employment estimates for the various product categories separately.Footnote 110 German 1907 data on output and employment for the relevant product categories are available from Kaiserliches Statistisches Amt.Footnote 111 The data in Appendix Table 2, Revision Level 1, report a conservative comparison of physical productivity. Here, copper, zinc, and lead output from various different industries in the 1907 U.K. census are added up, without being able to add up the relevant employment categories as well.Footnote 112 The resulting comparative productivity estimate is slightly lower than the one by B & B. The much higher productivity level in Appendix Table 2, Revision Level 3, results from subtracting employment in small establishments of five persons or fewer, and would be consistent with a physical productivity comparison for lead, zinc, and copper sampled from the industries included by B & B. For these three metals together, German productivity according to the surveys in Kaiserliches Statistisches Amt was 235 percent of U.K. levels.Footnote 113
Motor Vehicles
The German data underlying the comparison in B&B are for 1909, not 1907 as claimed in the text. Overall employment (12,688) and value of output (29.3 mill. M) for 1907 are available from the same source.Footnote 114 My estimate employs information about relative unit values from 1909, and combines it with the 1907 employment and physical output data in the different categories. The U.K. data are from the Board of Trade.Footnote 115
Cotton
Output data for cotton spinning are available for both the United Kingdom and Germany. For weaving, the British census only has a surface measure of output, while the German data are in tonnes. The British sources provide employment only for spinning and weaving combined.Footnote 116 B & B adjust their U.K. employment data to spinning by the ratio of gross value in cotton spinning to that in the whole industry. We adopt this adjusted estimate. Output data for Germany for 1907 are from the industry surveys of Kaiserliches Statistisches Amt.Footnote 117 B & B's employment data, taken from the 1907 census in Kaiserliches Statistisches Amt, include an apparent typo (“Bigognespinnerei” in the German source, whose employment they record as 9,493, instead of 6,493 as in the published sources).Footnote 118 Inserting the correct employment level, the corrected productivity estimate (“Revision Level 1”) for cotton spinning in Appendix Table 2 is 106 percent instead of 85 percent of British levels. Moreover, B & B count an additional 21,515 employed (most likely in retailing) that I could not allocate to any category of cotton spinning. Subtracting these from employment, I arrive at the census employment estimate of productivity (“Revision Level 2”) in Appendix Table 2, which includes outworkers and cottage industries in spinning. Productivity according to this employment concept is 129 percent of British levels. To arrive at categories comparable to the U.K. data, Revision Level 3 results from subtracting employment in very small establishments (but not in cottage industries) from the German employment data.
Silk
For silk, B & B again aggregate over spinning and weaving on the basis of silk yarn output. Given the absence of comparable output data for weaving, our estimate rests on spinning alone. Following B & B's procedure for cotton, we adjust British employment by the share of spinning in reported industry value. German output data for 1907 are from the industry surveys.Footnote 119 As in B & B, German employment in the industry is from the 1907 census.Footnote 120 Again, my reconstruction of the German employment data leads to substantially lower levels than in B & B. Inserting these data yields the corrected productivity estimate (Revision Level 1) in silk spinning in Appendix Table 2. Further adjustments (Revision Level 3) result from eliminating employment in establishments with 5 persons or less (but not in the cottage industries)
Leather
British data in the B & B estimate refer to tanning only, while their German data cover a wider category. Our estimate compares only tanning, and adjusts British employment by the relation between gross output in tanning and the surveyed industry total. German output data for 1907 are from the industry surveys.Footnote 121 The surveys also provide employment data, which enter our corrected version (Revision Level 1) of the B & B productivity estimate in Appendix Table 2. Census employment is again slightly lower and forms the basis for the census estimate of productivity (Revision Level 2) in Appendix Table 2.Footnote 122 The further correction of employment in Revision Level 3 concerns employment in establishments with five persons or fewer, following the methodology described above.
Brewing
The British data include several activities of the brewing industry, including bottling and bottle transport. The B & B estimate considers only brewing itself, and adjusts industry employment by the ratio of gross sales in brewing to gross value in industry. Our estimate adds this activity back to brewing sales to provide a coverage that matches the wider coverage of the German data. This results in a slightly higher employment figure. As in B & B, German output figures for 1907 are from Kaiserliches Statistisches Amt, while employment comes from the 1907 census.Footnote 123 Again, the German employment figures are distorted upwards relative to the British census by the inclusion of very small establishments. However, beer being a taxable good, all legal brewing was presumably included in the output data. Hence, correction for employment in small operations cannot be made in isolation, and some adjustment for the output of these establishments is needed as well. I assume that the small firms to be excluded had 80 percent of the productivity of the remaining ones. This is the estimate applied by de Jong, Fremdling and Timmer for similar industries in the German 1936 census.Footnote 124
Tobacco
B & B approximate the output of tobacco products by the input of tobacco to the industry. However, for Germany they report only domestic tobacco production, which was quite small compared to imports. Our estimate instead rests on the domestic supply of tobacco, converted into manufactured tobacco.Footnote 125 Employment data from the same source is reported net of employment in tobacco production, which is essentially an agricultural activity.Footnote 126 Adjustment for employment and output in very small establishments follows the same procedures as in the brewing industry.
Sugar
No adjustments were made to the estimate for sugar. 1907 was a bad harvest, and was about 30 percent lower than that of 1906. The German figures appear to include substantial seasonal labor in sugar beet harvesting, an industry that was insignificant in Britain. No employment figures for sugar refineries were available that would allow proper comparison between similar industries.
Cement
B & B use output and employment data for cement factories from the U.K. census, and output and employment in both factories and quarries for Germany from 1910. The German survey also reports employment in cement factories separately.Footnote 127 The adjusted productivity comparison is based on factory employment in both countries and omits quarries, for which the British census reports no data.
Other Industries
B & B apply their productivity estimate for cement to all other industries. We refrain from this in order not to inflate German comparative productivity, and instead assume productivity in “Other Industries” to be equal to the aggregate.
Salt Mining
For Germany, B & B provide data on salt extraction rather than salt mining. The revised estimate for 1907 is based on output and employment in salt mining.Footnote 128
Coal Mining
The revised estimate is based on census employment from Kaiserliches Statistisches Amt.Footnote 129 Census employment counts individual occupations in multiproduct firms more precisely.Footnote 130 Hence, the census data are to be preferred.
Iron Ore Mining
B & B take their data from the Board of Trade for coal and ironstone, and record the output of ironstone together with total employment in all coal mines.Footnote 131 However, the British census also provides output, value, and employment in iron mines under a different industry classification.Footnote 132 The German data are from Kaiserliches Statistisches Amt.Footnote 133 Census employment in this source is markedly lower than employment according to the industry concept. In Appendix Table 2 the latter enters the corrected version of the B & B estimate, while the former appears in Revisions Level 1–3.
GERMAN EMPLOYMENT LEVELS AND INDEX WEIGHTS FOR 1907

GERMAN COMPARATIVE PRODUCTIVITY IN 1907 (United Kingdom = 100)