



1. Introduction
This article is concerned with the optimal long-term exponential growth rate of expected utility of an investor’s wealth under drawdown constraints, in which the investor takes her decisions at discrete times. The model proposed for the random evolution of the asset’s prices has a Markovian structure (see [Reference Bielecki, Hernández-Hernández and Pliska5]) and is a discrete-time version of the continuous-time stochastic volatility model presented by Bielecki and Pliska in [Reference Bielecki and Pliska6]; the main characteristic of that model is that Gaussian processes represent both macroeconomics and financial factors, and they affect the mean returns of the risky assets. In the discrete-time model, the evolution of the asset’s prices depends on the state of a Markov chain with stationary transition probabilities, replicating the same effect observed in continuous time. These models are also known in the literature as regime-switching or Markov-modulated, where the determining financial parameters, such as the volatility rate, depend on the market regime of the economic environment.
In the prototype model used in this paper, at each period an investor divides his wealth between the set of risky assets and a riskless asset, with the restriction that its wealth process should satisfy a drawdown constraint written in terms of the last recorded maximum. Thanks to the introduction of an extra state variable satisfying a Markovian structure, the method of dynamic programming can be used, together with risk-sensitive stochastic control tools, in order to maximize the long-term exponential growth rate of the expected utility of terminal wealth with drawdown constraints.
The main results of this paper can be described as follows:
-
(i) For a constant relative risk aversion (CRRA) utility function, the value function and the optimal allocation strategy are characterized by a dynamic programming—or optimality—inequality, and
-
(ii) for a regular utility function with an asymptotic risk-sensitive coefficient in the nonnegative unit interval, the value function and the optimal investment strategy coincide with those obtained for a CRRA utility function with the same asymptotic risk-sensitive coefficient.
In the first part of this paper we use the discounted method to establish a solution of the optimality inequality and the existence of an optimal strategy, defining a set of contractive operators; see [Reference Sladký33]. To the best of our knowledge, a version of this result for either continuous- or discrete-time stochastic volatility models does not exist, and the techniques developed here might be helpful for extending them to more general frameworks. We obtain the second conclusion via the Arrow–Pratt function and technical properties of utility functions. These results extend the existing ones significantly for continuous-time models [Reference Grossman and Zhou15, Reference Bielecki, Hernández-Hernández and Pliska5], clarifying the role of the optimality inequality in solving the optimal allocation problem, as well as the difficulties in solving it.
In order to provide a historical review of this problem, including a literature review, it is important to highlight the fact that the optimal allocation problem under drawdown constraints with long-term growth rate of the expected utility of wealth is well developed and is still a good source of interesting problems. This problem was faced initially by Grossman and Zhou [Reference Grossman and Zhou15] for the classical log-normal model with a single risky asset with constant coefficients. In contrast, Cvitanic and Karatzas [Reference Cvitanić and Karatzas12] considered a similar model with multiple risky assets and deterministic coefficients for the diffusion process. Also, Sekine [Reference Sekine31, Reference Sekine32] and Cherny and Oblój [Reference Cherny and Oblój11], for diffusion and semimartingale models with a generalized drawdown constraint, respectively, have made significant contributions to the analysis of this problem, while in discrete-time models it has been studied by Chekhlov, Uryasev and Zabarankin [Reference Chekhlov, Uryasev and Zabarankin10]. In [Reference Bielecki, Hernández-Hernández and Pliska5], Bielecki, Hernández and Pliska applied risk-sensitive optimal control techniques in order to characterize the value function and the optimal strategy in terms of a dynamic programming equation for the optimal growth problem with a non-bankruptcy constraint. For other market models in discrete time we refer to Bauerle and Rieder [Reference Bauerle and Rieder3].
The main result of Grossman and Zhou [Reference Grossman and Zhou15] states that, for CRRA utility functions, the optimal allocation strategy consists of a fraction of wealth in the risky asset, depending on the difference between the value of the portfolio and the drawdown constraint. Grossman and Zhou obtained their solution using the dynamic programming method, showing that the corresponding Hamilton–Jacobi–Bellman equation has a solution, and proved that the allocation strategy obtained from the solution of the Merton problem with non-bankruptcy constraint [Reference Merton26] violates the drawdown constraint with probability one. Cvitanic and Karatzas [Reference Cvitanić and Karatzas12] extended the result of Grossman and Zhou to the case of several risky assets with a simplified approach, which was based on an auxiliary finite-horizon stochastic control problem with an explicit solution that is independent of the time and solves the drawdown constraint problem (see Karatzas et al. [Reference Karatzas, Lehoczky and Shreve22]). Sekine [Reference Sekine31] extended the above results for a semimartingale model with linear drawdown constraint, showing that the value function and the optimal strategy for the drawdown constraint problem coincide with the solution of another standard risk-sensitive-type portfolio optimization problem without constraints; his proof follows some ideas from [Reference Cvitanić and Karatzas12]. He also established a dual optimization problem, which results in a large deviation problem, represented as the maximization of the drawdown probability (see [Reference Pham27] and [Reference Pham28]). Cherny and Oblój [Reference Cherny and Oblój11] showed that, for an abstract semimartingale financial model, endowing an investor with a drawdown constraint is equivalent to encoding his preferences. They solved the functional drawdown constraint problem for a general utility function, showing that the value function is equal to the value function for an unconstrained portfolio optimization problem with a modified utility function. Moreover, they obtained the optimal wealth process for the functional drawdown constraint problem as a transformation of the optimal wealth process for the unconstrained problem; their work relies on the so-called Azéma–Yor processes, which allow them to provide a bijection between constrained and unconstrained problems. In relation to this paper, the above authors also use risk-sensitive stochastic control tools to determine the value function and the optimal strategy.
On the other hand, drawdown constraints have been considered in different settings. For instance, for a stochastic volatility market model, Agarwal and Sircar [Reference Agarwal and Sircar1] maximize the utility of the ratio of the wealth and the maximum of wealth at the end of a fixed investment horizon; Roche [Reference Roche29] maximized the expected utility of consumption over an infinite time horizon for a power utility function; Elie and Touzi [Reference Sekine32] generalized the above results to a general class of utility functions; and finally, Guasoni and Oblój [Reference Guasoni and Obloj16] proved that when the manager maximizes utility from performance fees, the optimal portfolio coincides with the optimal portfolio of a hypothetical investor intending to maximize the expected utility from the fund management, with no fees, facing the classical drawdown constraint.
The organization of this paper is as follows. In Section 2 the mathematical model and the drawdown constraint are introduced. The main results are established in Section 3, where a family of contractive operators are defined in order to get a solution for the corresponding optimality inequality, and we characterize the value function as its solution. Finally, in Section 4 it is shown that, for a regular utility function, the value function coincides with the value function for a power utility function.
2. Set-up and model description
In this section we present the mathematical model describing an investor interested in maximizing the average long-term certainty equivalent, subject to a drawdown constraint that restricts the possible losses of her portfolio in terms of a percentage of its historical maximum.
2.1. Mathematical model
The discrete-time model consists of m risky assets and a bank account paying a constant interest rate r. For convenience, the evolution of the deposit of one dollar after t periods in the bank account is described in terms of
 $e^{tr}$
instead of
 $(1+r)^t$
. The evolution of the risky assets is modeled through a stochastic kernel
 $v(dz|x,y)$
, taking into account the influence of an endogenous factor process
 $\{X_t\}$
, which determines the performance of the market and evolves as a finite-state Markov chain in S, according to the given one-step transition probabilities
 $Q_{xy}$
. In continuous-time models, this endogenous process describes a stochastic volatility environment; in [Reference Fouque, Papanicolaou and Sircar14] the authors present interesting technical arguments to introduce this type of environment of uncertainty. In our case we are introducing an extra uncertainty through the process
 $\{X_t\}$
, incorporating possible variations in the economical environment. Hence, the m-dimensional random vector
 $Z_{t+1}$
describing the relative prices of the risky assets between t and
 $t+1$
has conditional distribution
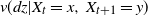 $v(dz|X_t=x,\;X_{t+1}=y)$
. More precisely, if we denote the price at time t of the ith asset by
 $P^{i}_t$
,
 $Z_t$
is interpreted as being the m-dimensional vector with ith component
 $P^i_{t+1}/P_t^i$
.
Let
 $A\subset \mathbb{R}^m$
be the constraint set for the investor. The vector
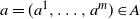 $a=(a^1,\ldots,a^m)\in A$
denotes an investment action, with
 $a^i$
representing the proportion of wealth invested in the ith risky asset, while the sum
 $1-\sum_{i=1}^{m}a^i$
is the proportion of wealth invested in the bank account. Thus, if the vector
 $a_t\in A$
represents the trading strategy at time t and
 $V_t$
denotes the value of the portfolio at that period of time, then
 \begin{equation}V_{t+1}=V_t[e^r+a_t\cdot(Z_{t+1}-e^r \textbf{1})]\end{equation}
represents its evolution at the next period of time
 $t+1.$
Here
 $\cdot $
denotes the inner product in
 $\mathbb{R}^m,$
and
 $ \textbf{1}$
stands for the m-dimensional vector of 1s. For simplicity of notation, we define for
 $a\in A$
and
 $z\in \mathbb{R}^m$
 \begin{equation*}F(a,z)\;:\!=\;[e^r+a\cdot(z-e^r \textbf{1})],\end{equation*}
and abbreviate
 $F(a_t,Z_{t+1})$
by
 $F_{t+1}$
when the context is clear.
The drawdown constraint has two components:
-
1. The fixed growth rate
 $\lambda \in \, ]0,r]$
represents an estimate of the inflation rate obtained by the supervisor, who imposes the restriction that any trading strategy followed by the fund manager should outperform inflation.
-
2. Let
$M_0$
be a fixed constant larger than the initial wealth
$V_0,$
and let
$\alpha \in \, ]0,1[$
be such that
$\frac{V_0}{M_0}\geq \alpha e^{-\lambda}$
. Then the last recorded maximum process associated with
$\lambda$
up to time t is defined as it is not difficult to see that
\begin{align*}M_t\;:\!=\;\max\{M_0e^{\lambda t}; V_se^{\lambda(t-s)}, s \leq t \};\end{align*}
$M_t=\max\{e^{\lambda}M_{t-1},V_t\}$
for all
$t \in \mathbb{N}.$
We say that a trading strategy
$\{a_t\}$
satisfies the drawdown constraint if the value process cannot drop below a fraction
$\alpha$
of the last recorded maximum, i.e. (2.2)
\begin{align}V_t \geq \alpha M_{t-1}, \ \ \ \ \forall\; t \in \mathbb{N}, \ \ \text{almost surely.}\end{align}


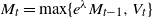


Remark 2.1. The value of the drawdown parameter
 $\alpha$
depends on the financial industry. The drawdown constraint imposed on the fund manager by his supervisor commits to other users a proportion
 $\alpha$
of the profits made by the manager, when the last recorded maximum is reached. This constraint also reflects the fact that the supervisor is reluctant to let the wealth fund fall below a fraction of its maximum to date (see [Reference Guasoni and Obloj16], [Reference Grossman and Zhou15]); in the investment management industry
 $\alpha$
ranges from 75% to 90%.
In order to describe precisely the set of admissible trading strategies, it is convenient to define the quotient process as
 \begin{align}W_0\;:\!=\;\frac{V_0}{M_0} \ \ \ \textrm{and} \ \ \ W_t\;:\!=\;\frac{V_t}{M_t}, \ \ \ \forall \ t \in \mathbb{N}.\end{align}
When the value process
 $\{V_t\}$
is driven by a trading strategy satisfying the drawdown constraint (2.2), we get the following two possibilities for each
 $t \in \mathbb{N}$
:
Case 1:
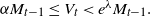 $\alpha M_{t-1} \leq V_t < e^{\lambda}M_{t-1}.$
In this situation, the quotient process
 $\{W_t\}$
takes values in the interval
 $[\alpha e^{-\lambda},1[.$
Case 2: If
 $V_t \geq e^{\lambda}M_{t-1},$
then
 $V_t = M_t$
; that is,
 $W_t=1.$
Therefore, the quotient process
 $\{W_t\}$
takes values in the interval
 $[\alpha e^{-\lambda},1].$
We define the function
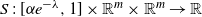 $S\; :\; [\alpha e^{-\lambda},1] \times \mathbb{R}^{m}\times \mathbb{R}^{m} \rightarrow \mathbb{R}$
by
 \begin{align}S(w,a,z)\;:\!=\;wF(a,z).\end{align}
Let us denote
 $S(W_t,a_t,Z_{t+1})$
by
 $S_{t+1}$
, with
 $\{a_t\}$
a trading strategy. Then the dynamics of the quotient process
 $\{W_t\}$
is the following:
 \begin{align*}W_{t+1}&=W_{t+1}\mathbb{I}_{[V_{t+1}<e^{\lambda}M_{t}]}+W_{t+1}\mathbb{I}_{[V_{t+1} \geq e^{\lambda}M_{t}]}\\[5pt] &=\frac{V_{t+1}e^{-\lambda}}{M_t}\mathbb{I}_{[S_{t+1}<e^{\lambda}]}+\frac{V_{t+1}}{V_{t+1}}\mathbb{I}_{[S_{t+1} \geq e^{\lambda}]}\\[5pt] &=\frac{V_{t}e^{-\lambda}F_{t+1}}{M_t}\mathbb{I}_{[S_{t+1}<e^{\lambda}]}+\mathbb{I}_{[S_{t+1} \geq e^{\lambda}]}.\end{align*}
Hence, defining
 \begin{equation}G(w,a,z)\;:\!=\;wF(a,z)e^{-\lambda}\mathbb{I}_{[S(w,a,z)<e^{\lambda}]}+ \mathbb{I}_{[S(w,a,z)\geq e^{\lambda}]},\end{equation}
the dynamics of
 $W_t$
are described by
 \begin{align} W_{t+1}= G(W_t,a_t,Z_{t+1}),\;\;\;\text{for all}\;\; t \in \mathbb{N}, \end{align}
and following a backward induction argument, we conclude that
 \begin{align*} W_{t+1}=W_0e^{-(t+1)\lambda}\prod_{k=1}^{t+1}F_{k}\mathbb{I}_{[S_{k} < e^{\lambda}]} + \sum_{k=1}^{t}\mathbb{I}_{[S_{k} \geq e^{\lambda}]}e^{(k-(t+1))\lambda}\prod_{i=k+1}^{t+1}F_i\mathbb{I}_{[S_{i} < e^{\lambda}]} + \mathbb{I}_{[S_{t+1} \geq e^{\lambda}]}.\end{align*}
We use this auxiliary process to define the investor’s long-term growth rate for the certainty equivalence, to control the value drop by a fixed fraction of the last recorded maximum, and maximize this rate in the long run.
Utility functions and the Arrow–Pratt function
In the remainder, it is assumed that risk preferences of the investor are determined by a utility function U, belonging to the family
 $\mathcal{U}$
defined below.
Definition 1. Let
 $\mathcal{U}$
be the family of functions
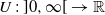 $U\;:\; ]0,\infty[ \rightarrow \mathbb{R}$
satisfying the following requirements:
-
(i) U has continuous derivatives up to second order in
$]0, \infty[$
. -
(ii)
$U^\prime (x) > 0$
for all
$x \in \, ]0,\infty[$
. -
(iii)
$U^{\prime \prime}(x) < 0 $
for all
$x \in \, ]0,\infty[.$


The optimization of the long-term growth rate of the certainty equivalence involves the analysis of the Arrow–Pratt function associated with a utility function U, as a measure of risk from the investor’s perspective; see Theorem 2.
Definition 2. (The Arrow–Pratt function.) For a utility function
 $U \in \mathcal{U},$
and
 $x \in (0,\infty),$
the corresponding Arrow–Pratt function
 $\Delta_U(x)$
is defined by
 \begin{equation*}\Delta_U(x)\;:\!=\;-x\frac{U''(x)}{U'(x)}.\end{equation*}
Definition 3. A utility function
 $U \in \mathcal{U}$
is regular if
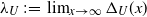 $\lambda_{U}\;:\!=\;\lim_{x \rightarrow \infty}\Delta_U(x)$
exists in
 $\mathbb{R}.$
This limit is called the asymptotic risk-sensitive coefficient of U.
Given a random variable X, its certainty equivalent is defined as
 \begin{equation*}\Psi_{U}(X)\;:\!=\;U^{-1}(\mathbb{E}[U(X)]).\end{equation*}
Let us suppose that the investor has initial capital x and that a utility function
 $U \in \mathcal{U}$
is used to measure her risk preferences. If she must choose between a loss without uncertainty of size C and a random loss
 $\theta Y,$
with
 $\theta \in \mathbb{R}$
and
 $\mathbb{E}[U(Y)] < \infty,$
the investor prefers the loss C when
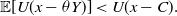 $\mathbb{E}[U(x-\theta Y)]<U(x-C).$
However, she is indifferent choosing C and
 $\theta Y$
if
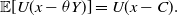 $\mathbb{E}[U(x-\theta Y)]=U(x-C).$
It is clear that the amount
 $x-C$
for which the last equality holds will be, by definition, the certainty equivalent of
 $x-\theta Y$
, and applying the Taylor expansion around
 $\theta = 0,$
we deduce that
 \begin{align}\Psi_{U}(x+\theta Y) \approx x + \theta \mathbb{E}[Y]- \frac{1}{2}\theta^{2}x^{-1}\Delta_U(x)\text{Var} (Y).\end{align}
Example 1. Fix
 $\gamma \in \, ]0,1[$
and define the constant relative risk aversion (CRRA) utility function
 $U_{\gamma}(x)\;:\!=\;x^{\gamma}$
. For a random variable Z, the corresponding certainty equivalent
 $\Psi_{U_{\gamma}}(Z)$
will be denoted by
 $\Psi_{\gamma}(Z).$
Also, it is easy to check that the corresponding Arrow–Pratt function is the constant
 $1-\gamma,$
and hence its asymptotic risk-sensitive coefficient is
 $\lambda_{U_{\gamma}}=1-\gamma.$
The function
 $\Delta_{U_{\gamma}}(x)$
and the coefficient
 $\lambda_{U_{\gamma}}$
will be denoted by
 $\Delta_{\gamma}(x)$
and
 $\lambda_{\gamma}$
, respectively.
Performance index
Let us fix the initial conditions for the factor and quotient processes
 $X_0=x$
and
 $W_0=w$
. For a utility function
 $U\in \mathcal{U}$
and a trading strategy
 $\pi=\{a_t\}$
, we define the long-term exponential growth rate of the expected utility (or objective function) of the final wealth as
 \begin{equation}\widehat{J}_{U}(x,w,\pi)\;:\!=\;\liminf_{t \rightarrow \infty} \frac{1}{t}\ln \Psi_{U}^{\pi,x,w}(V_t).\end{equation}
The function
 $\widehat{J}_{U}(x,w,\pi)$
quantifies the exponential growth of the certainty equivalence associated with the strategy
 $\pi$
. When the utility function
 $U_{\gamma}(x)$
is used, we denote the objective function by
 $\widehat{J}_{\gamma};$
applying Taylor expansion around
 $\gamma = 0$
, we get the approximation
 \begin{align}\widehat{J}_{\gamma}(x,w,\pi) \approx \liminf_{t \rightarrow \infty}\frac{1}{t}\left(\mathbb{E}_{x,w}^{\pi}[\ln V_t]+\frac{\gamma}{2}\text{Var}_{x,w}^{\pi}(\ln V_t)\right).\end{align}
Hence,
 $\widehat{J}_{\gamma}$
can be interpreted as the long-term expected growth rate per unit time plus a penalty proportional to the variance of the portfolio’s value and the risk coefficient
 $\gamma.$
Note the similarities between the expressions (2.9) and (2.7).
The investor aims to maximize, within the set of admissible trading strategies
 $\Gamma_{\alpha}$
, the long-term exponential growth rate of the certainty equivalent value
 $\widehat{J}_{U}(x,w,\pi)$
, and to find a trading strategy
 $\pi^*$
where the maximum of the objective function is achieved. That is, we are interested in the analysis of the value function
 \begin{equation}\widehat{J}_{U}(x,w,\pi^*)=\sup_{\pi \in \Gamma_{\alpha}}\widehat{J}_{U}(x,w,\pi)\;=\!:\;\,\widehat{J}_{{U}}^{*}( x,w ).\end{equation}
The set
 $ \Gamma_{\alpha}$
describing the admissible trading strategies
 $\pi$
is defined precisely below. When U is a CRRA utility function with parameter
 $\gamma\in \, ]0,1[$
, the corresponding value function is denoted by
 $\widehat{J}_{\gamma}^*(x,w).$
The main results presented in this paper can be summarized as follows. Let
 $U\in \mathcal{U}$
be a regular utility function with asymptotic risk-sensitive coefficient
 $\lambda_{U} =1-\gamma.$
-
We characterize
$\widehat{J}_{{U}}^{*}( x,w )$
and provide conditions under which an optimal trading strategy
$\pi^*$
can be proposed. -
For a CRRA utility function
$U_{\gamma}$
, with
$\gamma\in \, ]0,1[$
, it is proved that
$\widehat{J}_{{U}}^{*}( x,w )=\widehat{J}_{\gamma}^*(x,w)$
, and that the optimal strategy
$\pi^*$
, obtained from the previous step, is also optimal for
$\widehat{J}_{\gamma}^*(x,w)$
.


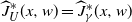


Admissible strategies. In order to complete the description of the mathematical model, we proceed to define precisely the set of admissible strategies
 $ \Gamma_{\alpha}$
for the investor and the probability space where the stochastic processes involved in the description of the problem are defined. Let us introduce first the positive cone
 $\mathbb{R}^{m^+}$
in Euclidean space, defined by
 \begin{equation*} \mathbb{R}^{m^+}\;:\!=\;\{ \textbf{x} \in \mathbb{R}^m \ : \ x_1>0,x_2>0, \dotsb, x_m >0\};\end{equation*}
the zero vector in
 $\mathbb{R}^{m}$
will be denoted by
 $ \textbf{0}$
.
Throughout the remainder the next hypotheses are assumed to hold even without explicit reference.
Assumption 1.
-
(i) There exists a compact set
$B\subset \mathbb{R}^{m^+} \cup \{ \textbf{0}\}$
such that
$ \textbf{0} \in B$
and
$e^r \textbf{1} \in \textrm{int}(B),$
and for each x and y in S—the state space of the Markov chain
$\{X_t\}$
—the stochastic kernel
$v( \cdot |x,y)$
is concentrated on B, i.e.
$v(B|x,y)=1.$
-
(ii) The action set
$A\subset \mathbb{R}^m$
is compact,
$ \textbf{0} \in \textrm{int}A$
, and for each
$(a,z) \in A\times B$
,
$0 < F(a,z)$
. -
(iii) For each
$w \in [\alpha e^{-\lambda},1]$
there exists a nonempty compact set
$A_w \subset A$
such that
$a \in A_w$
if and only if
$\frac{\alpha}{w} \leq F(a,z)$
for all
$z\in B$
; that is, (2.11)Moreover, the set-valued function
\begin{align}A_w\;:\!=\;\{ a \in A \; :\; \frac{\alpha}{w} \leq F(a,z),\;\forall\;z\in B \}.\end{align}
$w \mapsto A_w$
is continuous on
$[\alpha e^{-\lambda},1]$
; the definition of continuity for this class of maps is recalled below. The set
$A_w$
describes the admissible actions when the quotient process is equal to w.


Let X and Y be Borel spaces and denote by
 $\mathcal{C}(Y)$
the family of nonempty compact subsets of Y. A compact-set-valued function
 $\psi\;:\; X \rightarrow \mathcal{C}(Y)$
is upper semi-continuous (respectively, lower semi-continuous) if and only if, for each open subset G (respectively, closed subset F) of Y, the set
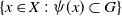 $\{x \in X \ : \ \psi(x) \subset G\}$
(respectively,
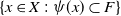 $\{x \in X \ : \ \psi(x) \subset F \}$
) is open (respectively, closed) in X. The function
 $\psi$
is continuous if it is both upper and lower semi-continuous.
Remark 1. Denoting by
 $\overline{K}$
the maximum of F on
 $A \times B,$
in view of the above hypotheses it follows that
 $\overline{K} > F( \textbf{0},e^r \textbf{1} ),$
that is,
 $\ln \overline{K} > r,$
since F is a hyperbolic paraboloid with saddle point at
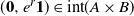 $( \textbf{0},e^r \textbf{1} ) \in \textrm{int} (A \times B)$
. This relation will be useful in the proof of some results in the next section.
Next, a concrete example describing set
 $A_w$
is presented, in order to illustrate possible ways to verify Assumption 1(iii).
Example 2. Fix
 $\alpha \in \, ]0,1[,$
 $r>0,$
 $\lambda \in \, ]0,r]$
and take
 $m=1.$
Define
 $B^*=[0,b],$
with
 $b>e^r$
, and
 $A^*=[-1,1].$
Consider now the functions
 \begin{equation*}\widehat{\zeta}(w)\;:\!=\;\frac{\alpha w^{-1}-e^r}{b-e^r}, \qquad \zeta(w)\;:\!=\;\max\{-1,\widehat{\zeta}(w)\}, \qquad \xi(w)\;:\!=\;1-\frac{\alpha}{w}e^{-r},\end{equation*}
with
 $w\in [\alpha e^{-\lambda},1]$
, and define
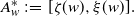 $A^*_w\;:\!=\;[\zeta(w),\xi(w)].$
We claim that the action set
 $A^*_w$
can be characterized as
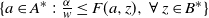 $\{a \in A^* \ : \ \frac{\alpha}{w} \leq F(a,z), \; \forall \; z \in B^*\}$
and, moreover, that the set-valued function
 $w\longmapsto A^*_w$
is continuous on
 $[\alpha e^{-\lambda},1]$
, as required in (2.11). The verification of these claims is postponed to the appendix.
The control model. The set of possible market regimes affecting the asset prices is denoted by
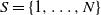 $S=\{1,\ldots,N\}$
, endowed with the discrete topology, and
 $Q_{xy}$
is the homogeneous transition probability on this set. Define the space
 $\overline{\mathbb{H}}_t$
of regime-quotient histories up to time t by
 \begin{align*}\overline{\mathbb{H}}_t\;:\!=\;\bigg(\prod_{k=0}^{t-1}(S \times [\alpha e^{-\lambda},1] \times A)_k \bigg) \times (S\times [\alpha e^{-\lambda}, 1]),\;\;\text{for}\;\;t=1,2,\ldots,\end{align*}
with
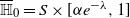 $\overline{\mathbb{H}}_0=S\times [\alpha e^{-\lambda}, 1]$
. A generic vector of
 $\overline{\mathbb{H}}_t$
is denoted by
 \begin{equation*}\overline{h}_t=(x,w,a_0,x_1,w_1, \ldots , x_{t-1},w_{t-1},a_{t-1},x_t,w_t).\end{equation*}
Given
 $\alpha \in \, ]0,1[$
fixed, an admissible trading strategy
 $\pi$
is a sequence
 $\pi\;:\!=\;\{\pi_t\}_{t=0}^{\infty}$
of stochastic kernels
 $\pi_t$
on A given
 $\overline{\mathbb{H}}_t,$
such that for
 $ t=0,1\ldots,$
 \begin{equation*}\pi_t(A_{w_t}|\overline{h}_t)=1, \ \ \textrm{with} \ \overline{h}_t \in \overline{\mathbb{H}}_t.\end{equation*}
The set of admissible strategies is denoted by
 $\Gamma_{\alpha}$
. Observe that this set is nonempty, and the value process
 $\{V_t\}$
driven by
 $\pi \in \Gamma_{\alpha}$
satisfies the drawdown constraint (2.2). Indeed, the trading strategy
 $\pi_0$
with the property that the total amount of wealth is invested in the riskless asset (that is,
 $a_t= \textbf{0}$
for all t) satisfies
 \begin{align*}M_{t-1}^{\pi_0} &= \max \{ M_0e^{\lambda(t-1)}, V_0e^{\lambda(t-1)}, V_0e^{\lambda(t-1)+(r-\lambda)},\cdots, V_0e^{\lambda(t-1)+(t-2)(r-\lambda)}, V_0e^{r(t-1)}\}\\[5pt]&=\max \{ M_0e^{\lambda(t-1)},V_0e^{r(t-1)}\},\end{align*}
and
 $V_t^{\pi_0}=V_0e^{rt}.$
Moreover,
 $V_t^{\pi_0} \geq \alpha M_{t-1}^{\pi_0}$
if, and only if, either
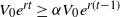 $V_0e^{rt} \geq \alpha V_0e^{r(t-1)} $
or
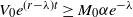 $V_0 e^{(r-\lambda)t} \geq M_0 \alpha e^{-\lambda}$
holds, and recalling that
 $V_0$
and
 $M_0$
were chosen in such a way that
 $V_0 \geq M_0 \alpha e^{-\lambda},$
it follows that
 $\pi_0 \in \Gamma_{\alpha}.$
Throughout, the family of stationary strategies
 $\overline{\mathbb{F}}_{\alpha} \subset \Gamma_{\alpha}$
is identified with the family of measurable functions
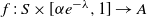 $f\;:\; S \times [\alpha e^{-\lambda},1] \rightarrow A$
such that
 $f(x,w) \in A_w$
for all
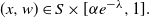 $(x,w) \in S \times [\alpha e^{-\lambda},1].$
Let
 $(\Omega,\mathcal{F})$
be the measurable space defined as
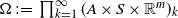 $\Omega\;:\!=\;\prod_{k=1}^{\infty}(A \times S \times \mathbb{R}^m)_k$
and
 $\mathcal{F}$
the corresponding product
 $\sigma$
-algebra. By the Ionescu–Tulcea theorem (see [Reference Ash2, Teorema: 2.7.2]), given the initial states
 $x_0=x \in S$
and
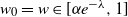 $w_0=w \in [\alpha e^{-\lambda},1]$
and
 $\pi \in \Gamma_{\alpha},$
there exists a unique probability measure
 $\mathbb{P}_{x,w}^{\pi}$
on
 $(\Omega,\mathcal{F})$
given by
 \begin{align*}\mathbb{P}_{x,w}^{\pi} &(da_0,x_1,dz_1,da_1,x_2\cdots) \\[5pt] & \, =\, \pi_0(da_0|x,w)Q_{xx_1}v(dz_1|x,x_1)\pi_1(da_1|x,w,a_0,x_1,w_1(w,a_o,z_1))Q_{x_1x_2}\cdots.\end{align*}
The expectation operator with respect to the probability measure
 $\mathbb{P}_{x,w}^{\pi}$
is denoted by
 $\mathbb{E}_{x,w}^{\pi}$
, and we define
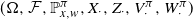 $ (\Omega,\mathcal{F}, \mathbb{P}_{x,w}^{\pi}, X_{\cdot}, Z_{\cdot}, V_{\cdot}^{\pi}, W_{\cdot}^{\pi})$
as an admissible control system, for
 $\pi\in \Gamma_{\alpha}$
. Observe that once the trading strategy
 $\pi$
is chosen, together with the initial wealth
 $V_0$
, the evolution in time of the value of the portfolio
 $\{V_t^\pi\}$
and the quotient process
 $\{W_t^\pi\}$
are given, respectively, by (2.1) and (2.6); here we make explicit the dependence of these processes on
 $\pi$
, but we omit it when the context is clear. The description of the control model is completed by specifying the payoff function to be optimized (cf. (2.8) and (2.10)), defined as
 \begin{equation*}\widehat{J}_{U}(x,w,\pi)=\liminf_{t \rightarrow \infty} \frac{1}{t}\ln \Psi_{U}^{\pi,x,w}(V_t^\pi),\end{equation*}
and the value function is given by
 \begin{equation}\widehat{J}_{{U}}^{*}( x,w )=\sup_{\pi \in \Gamma_{\alpha}}\widehat{J}_{U}(x,w,\pi).\end{equation}
3. Main results: CRRA preferences
In the sequel, we focus our analysis on solving the long-term optimal exponential growth rate problem for the CRRA case,
 $U_{\gamma}$
, with
 $\gamma\in \, ]0,1[$
fixed. The following result ensures the existence of a solution to the optimality inequality linked to the optimization problem
 \begin{equation*} \widehat{J}_{\gamma}^*(x,w)=\sup_{\pi \in \Gamma_{\alpha}} \widehat{J}_{\gamma}(x,w,\pi). \end{equation*}
Theorem 1. Let
 $\gamma,$
 $\alpha$
in ]0, 1[ be fixed. Then there exist a constant
 $g^{*} \in \mathbb{R}$
and an upper semi-continuous function
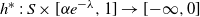 $h^{*}\;:\;S \times [\alpha e^{-\lambda},1] \rightarrow [ - \infty,0]$
such that
 \begin{align}e^{g^*+h^*(x,w)} \leq \sup_{a \in A_w}\big\{\sum_{y \in S}\int_{B} e^{h^*(y,G(w,a,z))}F^{\gamma}(a,z)v(dz|x,y)Q_{xy}\big\},\;\;(x,w) \in S\times [\alpha e^{-\lambda},1].\end{align}
Moreover, there exists a function
 $f^* \in \overline{\mathbb{F}}_{\alpha}$
such that
 \begin{align}\sup_{a \in A_w}\big\{\sum_{y \in S}\int_{B} e^{h^*(y,G(w,a,z))}F^{\gamma}(a,z)v(dz|x,y)Q_{xy}\big\}&= \end{align}
 \begin{align} \sum_{y \in S}\int_{B} e^{h^*(y,G(w,f^*(x,w),z))}F^{\gamma}(f^*(x,w),z)v(dz|x,y)Q_{xy} \end{align}
and, for
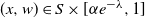 $(x,w) \in S \times [\alpha e^{-\lambda},1]$
with
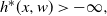 $ h^{*}(x,w)>-\infty,$
it follows that
 \begin{equation*}\widehat{J}_{\gamma}^{*}( x,w )=\widehat{J}_{\gamma}(f^{*},x,w)= \frac{g^*}{\gamma}.\end{equation*}
Remark 2. (i) Ideally, it would be desirable to find a solution
 $(g^*,h^*)$
to (3.1), with equality, and
 $h^*$
continuous. However, under the weak assumptions imposed on the model, such results were not expected to be obtained, and it remains an open problem under study by the authors. Instead, the set
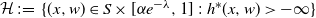 $\mathcal{H}\;:\!=\;\{(x,w) \in S \times [\alpha e^{-\lambda},1] \ : \ h^{*}(x,w)>-\infty\}$
is defined in terms of the semi-continuous function
 $h^*$
, which describes assertive initial conditions for which an optimal strategy can be implemented.
(ii) Regarding the existence of analogous versions of this result in continuous time, to the best of our knowledge, the results presented in [Reference Agarwal and Sircar1] are the closest versions we could find in the literature, for a stochastic volatility model, with a fixed finite horizon. However, for the finite-horizon case, the main results of that paper were obtained under the assumption that there exists a smooth solution to the Hamilton–Jacobi–Bellman equation, which corresponds to the optimality equation (3.1). Indeed, the extension of the above theorem to the framework studied by Agarwal and Sircar [Reference Agarwal and Sircar1] remains also an open problem.
The proof of Theorem 1 is somewhat technical, and we first present some preliminary results, divided into three steps. The first one, in Lemma 2, introduces a family of contractive operators, together with their main properties. Next, we propose a solution to the optimality inequality and an optimal strategy; see Proposition 1. Finally, we show that the value function
 $\widehat{J}_{\gamma}^{*}( x,w )$
in (2.12) is constant and equal to
 $g^*/\gamma$
within the set
 $\mathcal{H}$
, where the function
 $h^*$
is finite.
3.1. Contractive operators
First of all, recall that the function G involved in the dynamics of the quotient process
 $\{W_t\}$
was defined in (2.5) as
 \begin{equation*}G(w,a,z)=wF(a,z)e^{-\lambda}\mathbb{I}_{\{S(w,a,z)<e^{\lambda}\}}+ \mathbb{I}_{\{S(w,a,z)\geq e^{\lambda}\}}=\min\{S(w,a,z) e^{-\lambda},1\}.\end{equation*}
Throughout, we keep
 $\alpha\in \, ]0,1[$
fixed. The proof of the following result is straightforward.
Lemma 1. Let
 $z \in B$
be fixed. Then the function
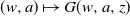 $(w,a) \mapsto G(w,a,z)$
is continuous on
 $[\alpha e ^{-\lambda},1]\times A.$
Let
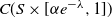 $C(S\times [\alpha e^{-\lambda},1])$
be the space of real-valued continuous functions V defined on
 $ S\times [\alpha e^{-\lambda},1]$
, endowed with the supremum norm
 $\|\cdot\|$
. For
 $\gamma,$
 $\beta \in \, ]0,1],$
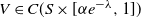 $V \in C(S\times [\alpha e^{-\lambda},1])$
, define the functions
 $l_V^{\beta}$
and
 $\tilde{l}_V^{\beta}$
by
 \begin{align}l_V^{\beta}(x,w,a)\;:\!=\;\sum_{y \in S} \int &e^{\beta V(y,G(w,a,z))}F^{\gamma}(a,z)v(dz|x,y)Q_{xy}, \nonumber\\[5pt]& \quad \text{for}\ (x,w,a) \in S\times [\alpha e^{-\lambda},1]\times A,\end{align}
and
 \begin{align} \tilde{l}_V^{\beta}(x,w)\;:\!=\;\sup_{a \in A_w}l_V^{\beta}(x,w,a),\;\;(x,w) \in S \times [\alpha e^{-\lambda},1],\end{align}
respectively. The following lemma allows us to ensure the existence of a mapping that maximizes the function
 $l_V^{\beta}$
, and will be helpful in appropriately defining the family of contractive operators in which we are interested.
Lemma 2. Let
 $\beta\in \, ]0,1[$
and
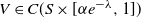 $V \in C(S\times [\alpha e^{-\lambda},1])$
. Then there exists a function
 $f_V^{\beta} \in \overline{\mathbb{F}}_{\alpha}$
such that
 \begin{equation*}\tilde{l}_V^{\beta}(x,w)=l_V^{\beta}(x,w,f_V^{\beta}(x,w)),\;\;(x,w)\in S \times [\alpha e^{-\lambda},1].\end{equation*}
Moreover,
 $\tilde{l}_V^{\beta}(x,w)$
is continuous in
 $S\times [\alpha e^{-\lambda},1].$
Proof. This result is a consequence of the measurable selection theorem; see the results by Himmelberg et al. in [Reference Himmelberg, Partasarathy and Van Vleck19, Theorem 2]. In order to apply that theorem to our case, we need to prove that the function
 $l_V^{\beta}(x,w,a)$
is continuous. Since the state space S is endowed with the discrete topology, we only need to verify the continuity of
 $l_V^{\beta}$
in the variables (w, a). Note that, from Assumption 1, it follows that
 \begin{align}\alpha^{\gamma} e^{-\beta||V||} \leq e^{\beta V(y,G(w,a,z))}F^{\gamma}(a,z)\leq e^{\beta ||V||}\overline{K}^{\gamma}.\end{align}
Now, for any sequence
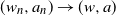 $(w_n,a_n)\to(w,a)$
, the dominated convergence theorem and Lemma 1 yield
 \begin{align*}\lim_{n\to\infty} l_V^{\beta}(x,w_n,a_n)&=\sum_{y \in S}\int e^{\beta \lim_{n\to \infty}V(y,G(w_n,a_n,z))}F^{\gamma}(a,z)v(dz|x,y)Q_{xy}\\[5pt]&=\sum_{y \in S}\int e^{\beta V(y,\lim_{n\to \infty}G(w_n,a_n,z))}F^{\gamma}(a,z)v(dz|x,y)Q_{xy}\\[5pt]&=\sum_{y \in S}\int e^{\beta V(y,G(w,a,z))}F^{\gamma}(a,z)v(dz|x,y)Q_{xy}\\[5pt]&=l_V^{\beta}(x,w,a);\end{align*}
therefore
 $l_V^{\beta}(x,w,a)$
is a continuous function. Since
 $A_w$
is a continuous set-valued function by Assumption 1(iii), the measurable selection theorem [Reference Himmelberg, Partasarathy and Van Vleck19] yields the result.

Definition 4. For
 $\gamma,$
 $\beta \in \, ]0,1[$
fixed, we define the operator
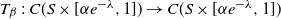 $T_{\beta}\;:\;C(S \times [\alpha e^{-\lambda},1 ])\rightarrow C(S \times [\alpha e^{-\lambda},1])$
by
 \begin{align*}T_{\beta}[V](x,w)\;:\!=\; \ln \tilde{l}_V^{\beta}(x,w),\end{align*}
with
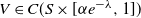 $V \in C(S\times [\alpha e^{-\lambda},1])$
.
The operator
 $T_{\beta}$
is well-defined in view of Lemma 2, and by the identity
 \begin{align}e^{T_{\beta}[V](x,w)}=\tilde{l}_V^{\beta}(x,w),\end{align}
the following two properties are satisfied:
-
1. Monotonicity: For each
$V, \ W \in C(S \times [\alpha e^{-\lambda},1])$
with
$V \leq W,$
$T_{\beta}[V] \leq T_{\beta}[W].$
-
2.
$\beta$
-homogeneity: For
$V \in C(S \times [\alpha e^{-\lambda},1])$
and
$r \in \mathbb{R}$
,
$T_{\beta}[V+r]=T_{\beta}[V]+\beta r.$
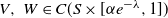

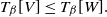

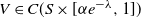

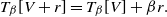
Lemma 3. For
 $\gamma $
and
 $\beta \in \, ]0,1[$
the operator
 $T_{\beta}$
defined on
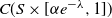 $ C(S\times [\alpha e^{-\lambda},1])$
is contractive, and there exists a unique
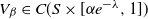 $V_{\beta} \in C(S \times [\alpha e^{-\lambda},1])$
such that
-
(i)
$T_{\beta}[V_{\beta}]=V_{\beta}$
, and -
(ii) furthermore,
(3.8)
\begin{align} (1-\beta)||V_{\beta}|| \leq \ln \overline{K}^{\gamma}.\end{align}


The constant
 $\overline{K}$
was introduced in Remark 1. Notice that if we write the identity
 $T_{\beta}[V_{\beta}]=V_{\beta}$
equivalently as
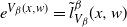 $e^{V_{\beta}(x,w)}=\tilde{l}_{V_{\beta}}^{\beta}(x,w)$
and use Lemma 2, it follows that there exists a measurable function
 $f_{\beta}(x,w)$
such that
 \begin{align}e^{V_{\beta}(x,w)}=l_{V_{\beta}}^{\beta}(x,w,f_{\beta}(x,w)), \ \ \forall (x,w).\end{align}
Proof. Fix
 $\beta \in \, ]0,1[,$
and let V and W be arbitrary functions in
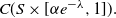 $C(S \times [\alpha e^{-\lambda},1]).$
Then, for each
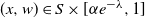 $(x,w)\in S \times [\alpha e^{-\lambda},1]$
,
 \begin{equation*}W(x,w)-||V-W|| \leq V(x,w) \leq W(x,w) + ||V-W||,\end{equation*}
or, in terms of the absolute value
 $|\cdot|$
,
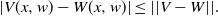 $|V(x,w)-W(x,w)| \leq || V-W ||.$
The properties of monotonicity and
 $\beta$
-homogeneity, together with the above display, imply
 \begin{equation*} T_{\beta}[W]- \beta||V-W|| \leq T_{\beta}[V] \leq T_{\beta}[W] + \beta ||V-W||,\end{equation*}
that is
 \begin{equation*}||T_{\beta}[V]-T_{\beta}[W]|| \leq \beta ||V-W||.\end{equation*}
So, from Banach’s fixed point theorem (see [Reference Kirk23, Theorem 2.2]), there exists a unique function
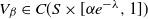 $V_{\beta} \in C(S \times [\alpha e^{-\lambda},1])$
such that
 $T_{\beta}[V_{\beta}]=V_{\beta}.$
Moreover, an easy computation shows that
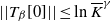 $|| T_{\beta}[0]|| \leq \ln \overline{K}^{\gamma}$
, and hence
 \begin{align*}||V_{\beta}||-||T_{\beta}[0]|| &\leq ||V_{\beta}-T_{\beta}[0] ||\\[5pt]&=||T_{\beta}[V_{\beta}]-T_{\beta}[0] ||\\[5pt]& \leq \beta || V_{\beta}||,\end{align*}
from which we conclude that
 \begin{align*}(1-\beta)||V_{\beta}|| &\leq || T_{\beta}[0] ||\\[5pt] &\leq \ln \overline{K}^{\gamma}.\end{align*}
3.2. Existence of a solution to the optimality inequality
Now, the discounted approach technique (see [Reference Cavazos-Cadena and Hernández-Hernández8] and [Reference Cavazos-Cadena and Salem-Silva9]) will be used to build a solution to the optimality inequality (3.1). The construction adopted in this paper is inspired by the one introduced by Cavazos-Cadena and Salem [Reference Cavazos-Cadena and Salem-Silva9] within the context of risk-sensitive optimal control. We begin by introducing the generalized superior limit of a sequence of functions.
Definition 5. For a sequence of functions
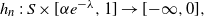 $h_n\;:\; S \times [\alpha e^{-\lambda},1] \rightarrow [ - \infty,0],$
the generalized superior limit is defined as
 \begin{align*}\tilde{h}(x,w)\;:\!=\;\sup\{r \;:\; r=\limsup_{n\to \infty} h_n(x,w_n), \ for \ some \ sequence \ w_n\ such \ that \ w_n \rightarrow w \},\end{align*}
and it is denoted by
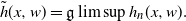 $\tilde{h}(x,w)=\mathfrak{g}\limsup h_n(x,w).$
The following property of
 $\tilde{h}$
will be needed in the proof of Proposition 1. Its proof can be obtained by adapting the arguments given in [Reference Jaśkiewicz and Nowak21, Lemma 3.1]; see also [Reference Cavazos-Cadena and Salem-Silva9, Lemma 4.2].
Lemma 4. The function
 $\tilde{h}$
is upper semi-continuous.
The family of fixed points obtained in Lemma 3, namely
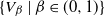 $\{V_{\beta}\;|\;\beta \in (0,1)\}$
, will be used to generate a real number
 $\widehat{g}$
and an upper semi-continuous function
 $\widehat{h},$
which together are natural candidates to be a solution to the optimality inequality (3.1).
Definition 6. For each
 $\beta \in (0,1),$
let
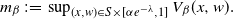 $m_{\beta}\;:\!=\;\sup_{(x,w) \in S\times [\alpha e ^{-\lambda},1] }V_{\beta}(x,w).$
The relative rate
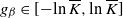 $g_{\beta} \in [ - \ln \overline{K}, \ln \overline{K}]$
and the relative function
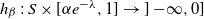 $h_{\beta}\;:\; S\times [\alpha e ^{-\lambda},1] \rightarrow ]- \infty,0]$
are specified by
 \begin{align}g_{\beta}\;:\!=\;(1-\beta)m_{\beta} \ \ \textrm{and} \ \ h_{\beta}(x,w)\;:\!=\;V_{\beta}(x,w)-m_{\beta}, \ \text{for}\;\; (x,w).\end{align}
Note that from (3.10), Equation (3.9) can be written as
 \begin{align} e^{g_{\beta}+h_{\beta}(x,w)}=l_{h_{\beta}}^{\beta}(x,w,f_{\beta}(x,w)), \ \ \forall (x,w) \in S\times [\alpha e^{-\lambda},1].\end{align}
Now, select a sequence
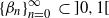 $\{\beta_n\}_{n=0}^{\infty} \,\subset ]0,1[$
such that the following two conditions are satisfied:
 \begin{align} \lim_{n\rightarrow \infty}\beta_{n}=1,\end{align}
and the corresponding sequence of relative rates
 $\{g_{\beta_{n}}\}_{n \in \mathbb{N}}$
converges, that is,
 \begin{align} \lim_{n \rightarrow \infty}g_{\beta_n}=\widehat{g}. \end{align}
The sequence
 $\{\beta_n\}_{n=0}^{\infty}$
satisfying (3.12) and (3.13) will be kept fixed unless otherwise stated. Thus, for the sequence
 $\{h_{\beta_n}\}_{n=1}^{\infty},$
its corresponding generalized superior limit is denoted by
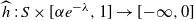 $\widehat{h}\;:\;S\times [\alpha e^{-\lambda},1] \rightarrow [ - \infty,0]$
; that is,
 \begin{align}\widehat{h}(x,w)\;:\!=\;\mathfrak{g}\limsup h_{\beta_{n}}(x,w).\end{align}
In order to simplify the notation, we write
 $(g_{n}, h_n)$
instead of
 $(g_{\beta_n},h_{\beta_n})$
, and if
 $f_{\beta_n}$
satisfies (3.11), we use
 $f_n$
to denote
 $f_{\beta_n}.$
The following proposition states the existence of a solution to the optimality inequality and the existence of a measurable selector such that (3.2) holds. Hence, the first part of Theorem 1 is obtained from this result. For similar results for Markov decision processes, see [Reference Cavazos-Cadena and Salem-Silva9, Lemma 4.3], [Reference Schal30, Theorem 3.8], and [Reference Jaśkiewicz20, Theorem 1].
Proposition 1. Let
 $\{\beta_n\}$
be the sequence fixed in (3.12)–(3.14). Then the pair
 $(\widehat{g},\widehat{h})$
is a solution of the optimality inequality (3.1). Moreover, there exists a function
 $\widehat{f} \in \overline{\mathbb{F}}_{\alpha}$
satisfying (3.2).
Proof. First, let us fix a point
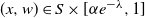 $(x,w) \in S \times [\alpha e^{-\lambda},1]$
. Following Definition 5, an arbitrary sequence
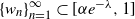 $\{w_n\}_{n=1}^{\infty} \subset [\alpha e^{-\lambda},1]$
such that
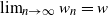 $\lim_{n \rightarrow \infty}w_n=w$
is chosen. From Equation (3.11), we can see that for each
 $n \in \mathbb{N},$
 \begin{align}e^{g_n+h_n(x,w_n)}=l_{h_n}^{\beta_n}(x,w_n,f_n(x,w_n)).\end{align}
Now we define the following compact set:
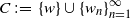 $C\;:\!=\; \{w\} \cup \{w_n\}_{n=1}^{\infty}$
in
 $[\alpha e^{-\lambda},1].$
From continuity (or upper semi-continuity) of the function
 $w \mapsto A_{w},$
compactness of every
 $A_{w}$
, and Berge’s theorem (see [Reference Berge4] or [Reference Klein and Thomson24]), it follows that
 $\bigcup_{w \in C} A_{w}$
is a compact set in A. Then the sequence
 $\{f_n(x,w_n)\}_{n=1}^{\infty},$
has a sub-sequence which converges to
 $a^* \in A,$
and since the set-valued function
 $A_{w}$
is continuous (or upper semi-continuous), we have
 $a^* \in A_w.$
Without loss of generality, it can be assumed that
 \begin{align} \lim_{n\rightarrow \infty}f_n(x,w_n)=a^*.\end{align}
Using the estimate in (3.6), Fatou’s lemma and Lemma 1, together with (3.14) and (3.16), yield
 \begin{align*} \limsup_{n\to\infty} l_{h_n}^{\beta_n}(x,w_n,f_n(x,w_n))&\leq \sum_{y \in S}\int_{B} e^{\limsup_{n\to \infty} h_n(y,G(w_n,f_n(x,w_n),z))}F^{\gamma}(a^*,z)v(dz|x,y)Q_{xy}\\[5pt]&\leq \sum_{y \in S}\int_{B} e^{\widehat{ h}(y,G(w,a^*,z))}F^{\gamma}(a^*,z)v(dz|x,y)Q_{xy}\\[5pt]&= l_{\widehat{h}}^1(x,w,a^*),\end{align*}
and hence
 \begin{align}\limsup_{n\to \infty} l_{h_n}^{\beta_n}(x,w_n,f_n(x,w_n)) \leq \tilde{l}_{\widehat{h}}^1(x,w).\end{align}
On the other hand, from (3.15) we see that
 \begin{equation*}\limsup_{n\to \infty} l_{h_n}^{\beta_n}(x,w_n,f_n(x,w_n))=e^{\widehat{g}+\limsup_{n\to \infty} h_n(x,w_n)}.\end{equation*}
Moreover, by replacing this identity in (3.17), we can rewrite it as
 \begin{equation*} e^{\widehat{g}+\limsup_{n\to \infty} h_n(x,w_n)} \leq \tilde{l}_{\widehat{h}}^1(x,w).\end{equation*}
Since the above display holds for any sequence
 $\{(x,w_n)\}_{n=1}^{\infty}$
converging to (x, w) for each
 $x\in S$
, by definition of
 $\widehat{h}$
in (3.14), and recalling Definition 5, it follows that there exists a pair
 $(\widehat{g},\widehat{h})$
such that
 \begin{equation*}e^{\widehat{g}+\widehat{h}(x,w)} \leq \tilde{l}_{\widehat{h}}^1(x,w).\end{equation*}
Also, since
 $\widehat{h}$
is upper semi-continuous, by Lemma 4, and the set-valued function
 $A_w$
is continuous, the measurable selection theorem [Reference Himmelberg, Partasarathy and Van Vleck19, Theorem 2] implies that there exists a function
 $\widehat{f} \in \overline{\mathbb{F}}_{\alpha}$
such that
 \begin{align*} \tilde{l}_{\widehat{h}}^1(x,w)=l_{\widehat{h}}^1(x,w,\widehat{f}(x,w)),\end{align*}
for
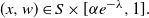 $(x,w) \in S\times [\alpha e^{-\lambda},1].$
3.3. Verification results
The following two results complement the preliminaries needed to complete the proof of Theorem 1. Recall that one of the conclusions of that result shows that the optimal value function is constant on
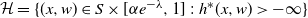 $\mathcal{H}=\{(x,w) \in S \times [\alpha e^{-\lambda},1] \ : \ h^{*}(x,w)>-\infty\}$
.
Lemma 5. Let
 $g^*,$
 $h^*$
, and
 $f^*$
be as in (3.1)–(3.2). Given
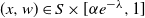 $(x,w)\in S \times [\alpha e^{-\lambda},1]$
, for each
 $t \in \mathbb{N},$
 \begin{align} V_0^{\gamma}e^{t g^*+h^*(x,w)}&\leq E_{x,w}^{f^*}[V_t^{\gamma}e^{h^*(X_t,W_t)}], \end{align}
where
 $\{V_{t}\}$
and
 $\{W_{t}\}$
are the processes associated to the stationary strategy
 $f^*\in \overline{\mathbb{F}}_{\alpha} $
.
As a consequence, if
 $(x,w) \in \mathcal{H},$
it follows that
 \begin{equation*} \frac{g^*}{\gamma} \leq \widehat{J}_{\gamma}(x,w,f^{*}) \leq \widehat{J}_{\gamma}^{*}( x,w ).\end{equation*}
Proof. Given
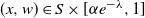 $(x,w) \in S \times [\alpha e^{-\lambda},1]$
arbitrary, from (3.2) we get that
 \begin{align*}V_0^{\gamma}e^{g^*+h^*(x,w)}&\leq \sum_{y \in S}\int_{B}e^{h^*(y,G(w,f^*(x,w),z))}V_0^{\gamma}F^{\gamma}(f^*(x,w),z)v(dz|x,y)Q_{xy}\\[5pt]&= E_{x,w}^{f^*}[V_1^{\gamma}e^{h^*(X_1,W_1)}],\end{align*}
and therefore (3.18) holds for
 $t=1.$
Assuming that (3.18) holds for a positive integer t, again applying (3.2), it follows that
 \begin{align*}V_0^{\gamma}e^{(t+1)g^*+h^*(x,w)} &\leq e^{g^*}E_{x,w}^{f^*}[V_t^{\gamma}e^{h^*(X_t,W_t)}]\\[5pt]&=\sum_{r_1 \in S} \int_{B}\cdots\sum_{r_{t}\in S}\int_{B}e^{g^*+h^*(r_{t},G(W_{t-1},f^*(r_{t-1},W_{t-1}),z_t))}V_0^{\gamma}\\[5pt]& \ \ \ \ \ \ \ \ \ \ \ \ \ \ \ \ \ \ \ \ \ \ \ \ \ \ \ \ \ F^{\gamma}(f^*(r_{t-1},W_{t-1}),z_t)\cdots F^{\gamma}(f^*(x,w),z_1)\\[5pt]& \ \ \ \ \ \ \ \ \ \ \ \ \ \ \ \ \ \ \ \ \ \ \ \ \ \ \ \ \ \ \ \ \ \ \ v(dz_t|r_{t-1},r_{t})Q_{r_{t-1}r_{t}}\cdots v(dz|x,r_1)Q_{xr_1}\\[5pt]&\leq \sum_{r_1 \in S} \int_{B}\cdots \sum_{r_t \in S}\int_{B}\sum_{r_{t+1} \in S}\int_{B}e^{h^*(r_{t+1},G(W_t,f^*(r_t,W_t),z_{t+1}))}V_0^{\gamma} \\[5pt]& \ \ \ \ \ \ \ \ \ \ \ \ \ \ \ \ \ \ \ \ \ \ \ \ \ \ \ \ \ F^{\gamma}(f^*(r_t,W_t),z_{t+1}) \cdots F^{\gamma}(f^*(x,w),z_1)\\[5pt]& \ \ \ \ \ \ \ \ \ \ \ \ \ \ \ \ \ \ \ \ \ \ \ \ \ \ \ \ \ \ \ \ v(dz_{t+1}|r_t,r_{t+1})Q_{r_tr_{t+1}}\cdots v(dz|x,r_1)Q_{xr_1}\\[5pt]&=E_{x,w}^{f^*}[V_{t+1}^{\gamma}e^{h^*(X_{t+1},W_{t+1})}].\end{align*}
The inequality (3.18) implies that
 \begin{align*} V_0^{\gamma}e^{tg^*+h^*(x,w)}&\leq E_{x,w}^{f^*}[V_t^{\gamma}],\end{align*}
and hence, when
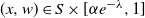 $(x,w) \in S \times [\alpha e^{-\lambda},1]$
is such that
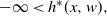 $-\infty < h^*(x,w),$
 \begin{align*} \frac{\ln V_0}{t} + \frac{g^*}{\gamma}+ \frac{h^*(x,w)}{\gamma t}&\leq\frac{1}{\gamma t} \ln E_{x,w}^{f^*}[V_t^{\gamma}].\end{align*}
By taking liminf as
 $t\to \infty$
in both sides of the above inequality, we get
 \begin{align*}\frac{g^*}{\gamma} \leq \widehat{J}_{\gamma}(x,w,f^{*}) \leq \widehat{J}_{\gamma}^{*}( x,w ).\end{align*}
Lemma 6. Let
 $\beta \in \, ]0,1[,$
 $\pi \in \Gamma_{\alpha}$
and
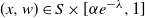 $(x,w) \in S \times [\alpha e^{-\lambda},1]$
be arbitrary but fixed. Then, for each
 $t \in \mathbb{N},$
 \begin{align}e^{tg_{\beta}+\beta h_{\beta}(x,w)} &\geq E_{x,w}^{\pi}[V_t^{\gamma}e^{\beta h_{\beta}(X_t,W_t)}].\end{align}
Proof. The proof is by induction in the time variable t. First, note that Lemma 3(i) yields
 \begin{align} e^{g_{\beta}+\beta h_{\beta}(x,w)} \geq e^{g_{\beta}+h_{\beta}(x,w)} \end{align}
 \begin{align} =\tilde{l}_{h_{\beta}}^{\beta}(x,w),\end{align}
and hence (3.19) holds for
 $t=1.$
Assume now that (3.19) is satisfied for t, so we can proceed to verifying it for
 $t+1.$
Let
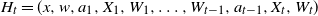 $H_t=(x,w,a_1,X_1,W_1, \dots , W_{t-1},a_{t-1},X_t,W_t)$
be the regime-quotient history vector, for
 $\pi \in \Gamma_{\alpha}$
and
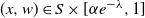 $(x,w) \in S \times [\alpha e^{-\lambda},1]$
. Then, from (3.20), it follows that
 \begin{align*}E_{x,w}^{\pi}[V_{t+1}^{\gamma}e^{\beta h_{\beta}(X_{t+1},W_{t+1})}|H_t,a_t]&=V_t^{\gamma}\sum_y\int_Be^{\beta h_{\beta}(y,G(W_t,a_t,z))}F(a_t,z)v(dz|X_t,y)Q_{X_ty}\\[5pt]&\leq V_t^{\gamma}e^{g_{\beta}+\beta h_{\beta}(X_t,W_t)}.\end{align*}
By the induction hypothesis, integrating both sides gives
 \begin{align*}E_{x,w}^{\pi}[V_{t+1}^{\gamma}e^{\beta h_{\beta}(X_{t+1},W_{t+1})}]&=E_{x,w}^{\pi}[E_{x,w}^{\pi}[V_{t+1}^{\gamma}e^{\beta h_{\beta}(X_{t+1},W_{t+1})}|H_t,a_t]]\\[5pt]&\leq E_{x,w}^{\pi}[V_t^{\gamma}e^{g_{\beta}+\beta h_{\beta}(X_t,W_t)}]\\[5pt]&\leq e^{g_{\beta}}e^{tg_{\beta}+\beta h_{\beta}(x,w)}\\[5pt]&=e^{(t+1)g_{\beta}+\beta h_{\beta}(x,w)}.\end{align*}
We conclude this section by putting together the previous results to complete the proof of our main result.
Proof of Theorem
1. First, notice that Proposition 1 yields that the inequality (3.1) and the equality (3.2) hold if we take
 $\widehat{h}=h^*,$
 $\widehat{g}=g^*$
, and
 $\widehat{f}=f^*.$
On the other hand, Lemma 6 implies that for each
 $\pi \in \Gamma_{\alpha}$
and
 $\beta \in \, ]0,1[$
,
 \begin{align*}\frac{g_{\beta}}{\gamma} + \frac{\beta (h_{\beta}(x,w)+||h_{\beta}||)}{t \gamma} \geq \frac{1}{t \gamma}\ln E_{xw}^{\pi}[V_t^{\gamma}],\end{align*}
and then, taking liminf as
 $t\to \infty$
in both sides, it follows that
 \begin{align*} \frac{g_{\beta}}{\gamma} \geq \widehat{J}_{\gamma}^{*}( x,w )\end{align*}
for all
 $\beta \in \, ]0,1[$
. Recalling the definition of
 $\widehat{g}$
in (3.13), we conclude that the above inequality is valid when
 $g_{\beta}$
is replaced by
 $\widehat{g}$
. Now, when
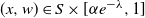 $(x,w) \in S \times [\alpha e^{-\lambda},1]$
is such that
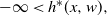 $-\infty < h^*(x,w),$
Lemma 5 and the above display imply
 \begin{align*} \frac{g^*}{\gamma} \leq \widehat{J}_{\gamma}(x,w,f^{*}) \leq \widehat{J}_{\gamma}^{*}( x,w ) \leq \frac{g^*}{\gamma},\end{align*}
which completes the proof.
Remark 3. There is an important question related to the conditions required to ensure that
 $\widehat{h}(x,w)>-\infty$
. In some works this has been assumed; see, for instance, [Reference Cavazos-Cadena and Salem-Silva9, Assumption 4.1] and [Reference Jaśkiewicz20, Condition B]. At least for the risk-neutral case, it could be verified by using some communication structure in the underlying processes, and we conjecture that a similar conclusion might be valid for this case; this is the subject of ongoing research by the authors.
4. Asymptotic results via the Arrow–Pratt function
This section aims to extend Theorem 1 to a more general class of utility functions. This class consists of the regular utility functions U with asymptotic risk-sensitive coefficient
 $\lambda_U \in \, ]0,1[$
; see Definition 3. This is done by proving that, if we choose the CRRA utility
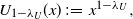 $U_{1-\lambda_U}(x)\;:\!=\;x^{1-\lambda_U},$
their asymptotic optimal values are the same, and moreover, they share the same set of optimal strategies. Recall that Theorem 1 ensures that the set of optimal strategies is not empty.
Theorem 2. For a regular utility function
 $U \in \mathcal{U}$
with asymptotic risk-sensitive coefficient
 $\lambda_{U} \in \, ]0,1[,$
it follows that
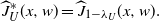 $\widehat{J}_{{U}}^{*}( x,w )=\widehat{J}_{1-\lambda_U}(x,w).$
Furthermore, if
 $\pi^{*} \in \Gamma_{\alpha}$
is such that
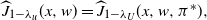 $\widehat{J}_{1-\lambda_u}(x,w)=\widehat{J}_{1-\lambda_U}(x,w,\pi^{*}),$
then
 $\pi^{*}$
is an optimal strategy for U, and vice versa.
4.1. Optimal strategies for regular utility functions
The following proposition provides an inverse order relation on the family of certainty equivalent values; its proof can be found in [Reference Cavazos-Cadena and Hernández-Hernández7]. This property, together with Lemma 7 and Corollary 1, allows us to relate the optimal value functions
 $\widehat{J}_U^*$
and
 $\widehat{J}^*_{1-\lambda_{U}}$
; the last one corresponds to the value function for the CRRA utility with parameter
 $\gamma\;:\!=\;1-\lambda_{U}$
studied in Section 3.
Proposition 2. Let
 $I=(a,b)$
be a nonempty interval contained in
 $(0,\infty),$
and let
 $U, V \in \mathcal{U}$
be arbitrary utility functions such that their corresponding Arrow–Pratt functions satisfy the relation
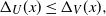 $\Delta_U(x)\leq \Delta_V(x),$
for
 $x \in I.$
Further, consider a random variable Y taking values in I almost surely, such that U(Y) and V(Y) have finite expectations. Then
 \begin{equation*} \Psi_{V}(Y) \leq \Psi_{U}(Y).\end{equation*}
Notice that for each
 $\pi \in \Gamma_{\alpha}$
and
 $\gamma \in \, ]0,1[$
, Assumption 1 implies that
 \begin{align}(\alpha M_0e^{\lambda (t-1)})^{\gamma} \leq (V_t^{\pi})^{\gamma}\leq (V_0 \overline{K}^t)^{\gamma},\end{align}
and hence, for
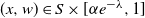 $(x,w) \in S \times [\alpha e^{-\lambda},1]$
, it follows that
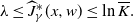 $\lambda \leq \widehat{J}_{\gamma}^{*}( x,w ) \leq \ln \overline{K}.$
Lemma 7. Let
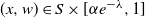 $(x,w) \in S \times [\alpha e^{-\lambda},1]$
be fixed. The function
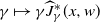 $\gamma \mapsto \gamma \widehat{J}_{\gamma}^{*}( x,w )$
satisfies the following properties on ]0, 1[:
-
(i) it is increasing;
-
(ii) for
$\gamma>\beta$
in ]0, 1[ it satisfies (4.2)and consequently,
\begin{align} \gamma\widehat{J}_{\gamma}^{*}( x,w ) \leq \beta\widehat{J}_{\beta }^{*}( x,w ) + (\gamma - \beta) \ln \overline{K}, \end{align}
-
(iii) it is continuous on ]0, 1[.


Proof. Given
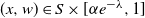 $(x,w) \in S \times [\alpha e^{-\lambda},1]$
and
 $\pi \in \Gamma_{\alpha},$
we choose
 $\gamma, \beta \in \, ]0,1[$
such that
 $\beta < \gamma$
. Then, using (4.1), we have that
 \begin{align}\mathbb{E}_{xw}^{\pi}[V_t^{\beta}](\alpha M_0e^{\lambda (t-1)})^{\gamma-\beta} \leq \mathbb{E}_{xw}^{\pi}[V_t^{\gamma}] \leq \mathbb{E}_{xw}^{\pi}[V_t^{\beta}](V_0\overline{K}^{ t})^{\gamma -\beta}.\end{align}
The left-hand side of the above display implies that
 \begin{align}(\gamma-\beta)\lambda + \beta \liminf_{t \rightarrow \infty} \frac{1}{t \beta } \ln \mathbb{E}_{xw}^{\pi}[V_t^{\beta }] & \leq \gamma \liminf_{t \rightarrow \infty} \frac{1}{t \gamma }\ln \mathbb{E}_{xw}^{\pi}[V_t^{\gamma}],\end{align}
and since
 $(\gamma-\beta)\lambda $
is positive, we have that
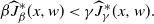 $\beta\widehat{J}_{\beta }^{*}( x,w ) < \gamma \widehat{J}_{\gamma}^{*}( x,w ).$
In the same manner, from (4.3) we conclude that
 \begin{align} \gamma \liminf_{t \rightarrow \infty} \frac{1}{t \gamma } \ln \mathbb{E}_{xw}^{\pi}[V_t^{\gamma}] & \leq \beta \liminf_{t \rightarrow \infty} \frac{1}{t \beta }\ln \mathbb{E}_{xw}^{\pi}[V_t^{\beta}] + (\gamma-\beta)\ln \overline{K}.\end{align}
Hence (4.2) is obtained from (4.5), and finally from (4.2) it follows that
 \begin{equation*}|\gamma\widehat{J}_{\gamma}^{*}( x,w ) - \beta\widehat{J}_{\beta }^{*}( x,w )| \leq |\gamma - \beta| \ln K.\end{equation*}
Notice that it is straightforward to verify the following claim, from (4.4) and (4.5).
Corollary 1. For any
 $\pi \in \Gamma_{\alpha}$
and
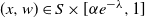 $(x,w) \in S \times [\alpha e^{-\lambda},1]$
, the function
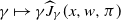 $\gamma \mapsto \gamma \widehat{J}_{\gamma}(x,w,\pi)$
is continuous in
 $]0,1[.$
Now we are ready to present the proof of the main result of this section.
Proof of Theorem
2. First, we take
 $\gamma\;:\!=\;1-\lambda_{U} .$
Hence, given
 $\varepsilon > 0$
small enough, from the definition of
 $\lambda_{U}$
, there exists
 $z>0$
such that
 \begin{align*}1-(\gamma+\varepsilon) \leq \Delta_U(y)\leq 1-(\gamma - \varepsilon) \ \ \ \forall y > z,\end{align*}
which yields
 \begin{align*}\Delta_{U_{\gamma +\varepsilon}}(y) \leq \Delta_U(y)\leq \Delta_{U_{\gamma - \varepsilon}}(y), \ \ \ \forall y > z.\end{align*}
Now, given
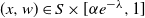 $(x,w) \in S \times [\alpha e^{-\lambda},1]$
and
 $\pi \in \Gamma_{\alpha},$
we choose a positive integer
 $t^*$
such that
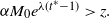 $\alpha M_0e^{\lambda (t^*-1)} > z.$
Thus, from the drawdown constraint (2.2), it follows that
 $V_t^{\pi} > z$
for
 $t \geq t^*$
almost surely, and hence
 \begin{align*}\Delta_{U_{\gamma+\varepsilon}}(V_t^{\pi}) \leq \Delta_U(V_t^{\pi})\leq \Delta_{U_{\gamma -\varepsilon}}(V_t^{\pi}).\end{align*}
Using Proposition 2, we get
 \begin{align}\frac{1}{t}\Psi^{\pi,x,w}_{U_{\gamma-\varepsilon}}(V_t^\pi) \leq \frac{1}{t}\Psi^{\pi,x,w}_U(V_t^\pi)\leq \frac{1}{t}\Psi^{\pi,x,w}_{U_{\gamma + \varepsilon}}(V_t^\pi),\end{align}
and therefore
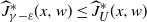 $\widehat{J}_{\gamma - \varepsilon}^{*}( x,w ) \leq \widehat{J}_{{U}}^{*}( x,w )$
and
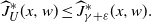 $\widehat{J}_{{U}}^{*}( x,w ) \leq \widehat{J}_{\gamma + \varepsilon}^{*}( x,w ).$
Letting
 $\varepsilon\to 0$
in the above inequality, Corollary 1 implies that
 \begin{align}\widehat{J}_{{U}}^{*}( x,w )=\widehat{J}_{\gamma}^{*}( x,w ).\end{align}
On the other hand, let
 $\pi^* \in \Gamma_{\alpha}$
be a strategy such that
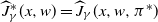 $\widehat{J}_{\gamma}^{*}( x,w )=\widehat{J}_{\gamma}(x,w,\pi^{*})$
. Replacing
 $\pi$
by
 $\pi^*$
in (4.6) and letting
 $\varepsilon\to0,$
from Corollary 1 and (4.7) we have that
 \begin{align*}\widehat{J}_{U}(x,w,\pi^{*}) &= \widehat{J}_{\gamma}(x,w,\pi^{*})\\[5pt] &= \widehat{J}_{\gamma}^{*}( x,w ) \\[5pt] &= \widehat{J}_{{U}}^{*}( x,w ).\end{align*}
Now, if
 $\pi^{\star} \in \Gamma_{\alpha}$
is a strategy such that
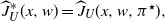 $\widehat{J}_{{U}}^{*}( x,w )=\widehat{J}_{U}(x,w,\pi^{\star}),$
following the same arguments given above, we conclude the proof.
Conclusion
In a discrete-time financial market setting, the construction of efficient dynamic portfolios satisfying a benchmark is desirable within the theory of portfolio management. For the regime-switching model, we have studied the optimal long-term exponential growth rate of the expected utility of portfolios satisfying a drawdown constraint, which plays the benchmark role. The main result, Theorem 3.1, provides conditions to obtain the optimal growth rate
 $g^*$
of portfolios satisfying such a restriction and establishes the existence of an optimal strategy using the decision rule described in that result. A dynamic programming approach is followed to deal with an expanded state variable and the optimality inequality. Interestingly, the drawdown constraint is encoded in the evolution of the quotient process, with a role similar to the Lagrange multiplier rule, transforming the original optimization problem with restrictions into a new one without constraints. Several interesting problems have arisen, and some remain open, which deserve further analysis. In particular, it would be interesting to analyze in future works the applicability of the policy iteration algorithm in order to approximate the optimal investment strategy, as well as the value iteration, in order to obtain results similar to those described in [Reference Bielecki, Hernández-Hernández and Pliska5].
Appendix A. Sketch of claims associated with Example 2
In Example 2, the action set was defined as
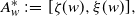 $A^*_w\;:\!=\;[\zeta(w),\xi(w)],$
and we made two claims:
-
C1: The set
$A^*_w$
can be characterized as
$\{a \in A^* \ : \ \frac{\alpha}{w} \leq F(a,z), \; \forall \; z \in B^*\}$
. -
C2: The set-value function
$w\longmapsto A^*_w$
is continuous on
$[\alpha e^{-\lambda},1]$
.

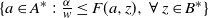


Recall that
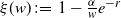 $\xi(w)\;:\!=\;1-\frac{\alpha}{w}e^{-r}$
, and clearly it is continuous and increasing on
 $[\alpha e^{-\lambda},1].$
Now, let
 $\mu=\xi(\alpha e^{-\lambda}),$
 $\rho=\xi(1)$
, and define
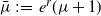 $\bar{\mu}\;:\!=\;e^r(\mu+1)$
and
 $\bar{\rho}\;:\!=\;e^r(\rho+1)$
. Then straightforward calculations yield the following:
-
(i) if
$b \geq \bar{\rho},$
then
$\zeta(w)=\widehat{\zeta}(w)$
for all
$w \in [\alpha e^{-r},1]$
; -
(ii) if
$b \leq \bar{\mu},$
then
$\zeta(w)=-1$
for all
$w \in [\alpha e^{-\lambda},1]$
; -
(iii) if
$b \in \, ]\bar{\mu},\bar{\rho}[,$
then there exists
$w^* \in [\alpha e^{-\lambda},1]$
such that
\begin{equation*} \zeta(x)= \left\{ \begin{array}{l@{\quad}c@{\quad}c} \widehat{\zeta}(w) & \text{if} & w < w^*; \\[5pt] -1 & \text{if} & w \geq w^*. \\[5pt] \end{array} \right.\end{equation*}


Consequently,
 $\zeta(w)$
is continuous and decreasing on
 $[\alpha e^{-\lambda},1].$
Also, using first-order conditions and the fact that the function F is a hyperbolic paraboloid with saddle point at
 $( \textbf{0},e^r \textbf{1}),$
it can be verified that the minimum of F(a, z) on
 $A_w^* \times B^*$
is equal to
 $\frac{\alpha}{w}.$
These facts are used in the proof of the above claims.
For C1: We know that there exists a family
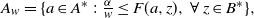 $A_w=\{a \in A^* \ : \ \frac{\alpha}{w} \leq F(a,z), \; \forall \; z \in B^*\},$
with
 $w \in [\alpha e^{-\lambda},1].$
Since
 $0 \in A^*$
and
 $F(0,z)=e^r$
for all
 $z \in B^*,$
we conclude that
 $A_w \neq \emptyset$
for all
 $w \in [\alpha e^{-\lambda},1].$
Given
 $a \in A_w,$
we have that
 \begin{align*} F(a,0)=e^r(1-a)\geq \frac{\alpha}{w},\end{align*}
and hence
 $a \leq \xi(w);$
since
 $A=[ - 1,1]$
and
 \begin{equation*} F(a,b) = e^r+a(b-e^r)\geq \frac{\alpha}{w},\end{equation*}
it follows that
 $\zeta(w) \leq a,$
and therefore
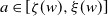 $a \in [\zeta(w),\xi(w)]$
. We conclude that
 $A_w \subseteq A_w^*.$
Given
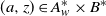 $(a,z) \in A_w^* \times B^*$
,
 $F(a,z) \geq \frac{\alpha}{w}$
, and hence
 $A_w^* \subseteq A_w$
.
For C2: This can be proved in two steps, by first showing that the set-valued mapping
 $w \mapsto A_w$
is upper semi-continuous, and then proving the lower semi-continuity of this map. The main arguments to prove the first step are below, while those for the second step are analogous and are omitted.
Let
 $G\subset A^*$
be an open set and define
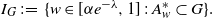 $I_G\;:\!=\;\{w \in [\alpha e^{-\lambda},1] \; : \; A_w^* \subset G \}.$
In the easy cases, when
 $G=\emptyset$
or
 $A_1^* \subset G,$
we get that
 $I_G=\emptyset$
or
 $I_G=[\alpha e^{-\lambda},1]$
; here we use the fact that the family
 $A_w^*$
is increasing. When
 $I_G \neq \emptyset $
and
 $I_G \neq [\alpha e^{-\lambda},1]$
, using that
 $A_w^*$
is an increasing family, it can be proved that G must contain at least an open interval containing
 $A_{\alpha e^{-\lambda}}^*$
. In fact, defining
 $\bar{I}_G\;:\!=\;\sup I_G,$
we conclude that
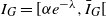 $I_G=[\alpha e^{- \lambda},\bar{I}_G[$
. This explicit form of
 $I_G$
yields the upper semi-continuity of the map.
Acknowledgements
The authors are grateful to the referees for several useful remarks and constructive criticisms which significantly improved the paper. The first author also wishes to thank the Centro de Investigación en Matemáticas, A. C., where this paper was written.
Competing interests
There were no competing interests to declare which arose during the preparation or publication process for this article.


