

“RUMORS SPREAD LIKE WILDFIRE”
A mob of hostile depositors gathered in the rain outside of the Guardian Bank in the Five Points and the Bowling Green Bank near Wall Street. Crowds of Irish and German immigrants were clamoring at the shuttered iron gates to withdraw their meager savings. When it became clear the banks would not open for daily business, according to the New York Herald, a commotion erupted in the streets. Wet and angry, the locked-out depositors cursed the names of prominent bank officials, including the Guardian's president, William M. Tweed, who was concurrently the local state senator, New York City commissioner of public works, chairman of the county Democratic Party, and Grand Sachem of Tammany Hall. Despite the hopeless situation, many people lingered outside the gates for news. Reporters described a weeping elderly man, peddlers anxious about paying debts, and parents worried about their children's savings accounts. More ominous was a bulwark of police on standby to combat public disorder. After all, Henry “Hank” Smith, chairman of the police commission, was also vice president of the Guardian and president at the Bowling Green. It was Monday morning, November 20, 1871.
The bank run was sparked by a slow-moving change in municipal government. Richard Connolly, the Tammany-backed comptroller and Tweed ally, had abruptly resigned in disgrace one month earlier and named a reformer, Andrew Green, acting deputy with full powers over the Department of Finance. Mayor Oakey Hall, another Tweed confidant, initially refused to accept Green's legitimacy and to ratify the appointment of a political opponent. Yet, faced with an escalating crisis over allegations of pervasive official misconduct, on Saturday, November 18, Mayor Hall at last conceded to the reform movement.Footnote 1 In one of his first official acts, deputy comptroller Green ordered the transfer of $56,000 of public money away from the Guardian Bank.Footnote 2 When the Guardian was unable to honor the bank draft, “rumors spread life wildfire” about the solvency of financial institutions affiliated with Tammany Hall, the dominant faction of New York City's Democratic Party. In the panic, even old-line savings banks faced questions.
To calm depositors and avert a run, on Sunday the 19th, officials at the National Savings Institution placed a sign on its door assuring clients that all claims would be faithfully met when open for business the following day. The bold gesture failed to delay a swift downfall; the bank could not meet the draft of $847 by a depositor named Charles Hoff. When a Herald reporter sought comment from Guardian Bank officials, several of whom sat on both boards, he found its “doors bespattered with Five Points filth, and with the appearance of not having been opened in a century.”
Hank Smith drawn by Thomas Nast.

No fewer than four savings banks with Tammany political connections failed: the Guardian, Bowling Green, National Savings, and Yorkville. For weeks, rumors of insolvency shook a series of commercial banks: the Tenth National, Ocean, Broadway, Central National, Eighth National, and Union-Square.Footnote 3 Members of the “Tweed Ring” were already under investigation for their role overseeing city finances. These very same officials, along with many of their contractors and business associates, now faced multiplying lawsuits from depositors targeting banks placed in receivership by the courts.Footnote 4
THE TAMMANY BANKS
Political capitalism flourished during the Gilded Age as party entrepreneurs experimented with techniques to both win office and accumulate capital. In this vein, the rapid growth and sudden disappearance of Tammany Hall's financial sector is one of the most intriguing yet unexplored facets of the “Tweed Ring.” The Ring was a small circle of officeholders who governed New York City between 1866 and 1871; they were caught embezzling millions of dollars from state and local government through the Tammany political machine.Footnote 5 Control over a network of banks, savings and commercial, was integral to William Tweed's sweeping ambition to reshape the postbellum political landscape by bringing to power a coalition that included laborers, immigrants, and Catholics. Holding many positions that crosscut elected and appointed positions, party factions, and social clubs, a number of influential Tammany figures transformed themselves into bank officers. Crucially, these banks opened access to new sources of capital—lines of credit conjured from electoral conquest—that went into financing ventures large and small, local and national. These banking institutions were the linchpin of Ring members’ vast but fleeting personal fortunes.Footnote 6
Although Tammany banks existed only a few years, officeholders from both parties used them to route cash and checks through “special” accounts; finance personal loans and mortgages; purchase municipal debt; and speculate in real estate, stocks, and bonds. Banks were not afterthoughts of the Tweed Ring's program, as previous scholars have treated them. Nor were they designed as swindles. Working-class immigrants were invited to embrace bourgeois values of thrift by opening savings accounts. Tammany bankers marketed their services to credit-hungry neighborhoods, changed small bills for the poor, and provided an ostensibly safe place to store hard-earned wages while reaping interest. Most strikingly, Tammany leadership and their families held significant personal accounts in these institutions, including the entire Ring—William “Boss” Tweed himself, Oakey Hall, Richard Connolly, and Peter Sweeny—as well as the wider clique of building contractors, business associates, and patronage appointees.Footnote 7 “The petty politicians of the Sixth, Seventh, Fourteenth, and Fourth Wards are howling with indignation,” remarked the New York World, as the November 20th bank run left them high and dry along with common depositors.Footnote 8
To say Tammany political figures were flush with cash during their heyday under Tweed would be an understatement—between $6 and $30 million was pilfered from taxpayers. Popular mythology offers a number of tantalizing hypotheses about where New York's money disappeared, from Spanish banks after Tweed's failed 1875 escape to tales of buried treasure.Footnote 9 The more plausible—albeit less sensational—explanation is the money circulated through New York's own banks, including those controlled by Tammany Hall. Established banking houses doing business with the city did not ask embarrassing questions about the origin of deposits, something that rapacious aldermen and county board officials discovered in the 1850s. Yet the Ring needed more than the tacit support of venerable bankers with impeccable credentials. William Tweed, Oakey Hall, Richard Connolly, and Peter Sweeny needed allies they could trust completely with active knowledge about the political sources of their newfound wealth. To fill this niche arose a stratum of politician-bankers who oversaw the Ring's schemes and also participated in them.
The Tammany bank run of 1871 dramatizes the scholarly lacuna about the transformation of political power into economic capital in American political development. Aside from early struggles over the national bank and the federal government's role paying for wars, there are few nineteenth-century studies in which political authority so starkly deployed public coffers to deliberately call into being a professional class of partisan financiers.Footnote 10 Certainly no scholarship exists outside of national political institutions, where Congress and the Treasury Department set monetary policy or financed armed conflicts such as the Civil War. Tammany banks, by contrast, took root locally within a specific historical conjuncture: the development of mass parties and New York's privileged place within the national and world economy. Universal white manhood suffrage prompted a bureaucratization of party organization that fueled electoral competition and the quest for spoils. Concurrently at midcentury, merchant capital in New York migrated into the financial sector. Debt-financed Union victory further consolidated Wall Street's position as the “capital of capital” and fostered a Republican-leaning group of financiers.Footnote 11 The Tweed Ring's brief foray into financial services demonstrated that a parallel process was underway on a smaller scale: Tammany officeholders transformed into bankers by leveraging their position as intermediaries between working-class voters and public treasuries in New York.
Close examination of the Tammany banks, including those who ran them and how they worked, reveals that members of the Tweed Ring were ascendant political capitalists who appropriated democratic capital—that is to say, capital mobilized through the political system—and put it to work in diverse investments.Footnote 12 Whereas capitalism is the process by which money begets money, the formula of political capitalism is when politics begets money. In this particular case study, the institutional medium for private wealth accumulation was a network of partisan banks. To foreclose this burgeoning trajectory, anti-Tweed forces led by the Committee of Seventy, composed entirely of established merchants and bankers, vigorously attacked the Ring with every tool at its disposal: taxpayer strikes, capital flight, social pressure, party fusion, and civil as well as criminal suits. The origins of Tammany banks in the mass party system and their ultimate extinction are thus exemplary of tensions that erupted over sources of wealth and power in postwar American society.
Why have the Tammany banks escaped scrutiny, despite all the attention the Tweed Ring has received over the years? Historiography has focused on how bribery, fraud, and embezzlement allowed the Ring to coordinate political authority across New York City's fragmented Gilded Age social divisions and political institutions. Thus, analysis of the Ring has always begun and ended with the same explanation: corruption.Footnote 13 The corruption charge was originally advanced by the middle-class press, which celebrated wealth while condemning the chaos of industrial society in terms of moral failure.Footnote 14 This framing of events also served the aims of anti-Tweed vigilance committees formed by the upper classes that longed to reverse the gains made by the poor under universal white manhood suffrage.Footnote 15 And while Samuel Tilden's grand jury and subsequent investigations aggressively pursued the beneficiaries of stolen money, they were careful to avoid shining unwanted attention upon the complicity of powerful financial institutions. To this day, no muckraker, historian, or social scientist has scrutinized the central role of banks in making Tweed's activities possible.
Tammany's nascent financial sector, chartered in the state legislature and buffeted with politically acquired deposits, allowed Tweed to finance party and business activities on a grand scale. The nineteenth-century spoils system had fueled mass parties in the United States since the Jacksonian Era. By the Gilded Age, spoils evolved beyond control over patronage in parks departments and customhouses—the traditional focus of historians and political scientists. Midcentury party brokers had been content to collect assessments on appointees, acting essentially as tax farmers on behalf of the mass party system.Footnote 16 More risky operators might risk scandal to extract a share from public contracts. In the heady days of economic expansion between 1865 and the Depression of 1873, activist pro-growth government agendas catalyzed a breed of conspicuously political businesses. “The golden years of the age of capital,” as Sven Beckert has called them, were a period when enterprising officeholders innovated new techniques to acquire greater resources.Footnote 17 They did so by offering businessmen access to pools of publicly backed capital by chartering corporations with special rights and privileges.Footnote 18 The price of influence peddling was no longer just the one-time lobbying fee, but partnership in management and profits. In New York, Tammany Hall was at the forefront of this chartering mania as corporations shed their status from long-term investments in the public interest into objects of private speculation.Footnote 19 Between 1867 and 1871, banks with new or amended charters became the nerve center of the Tweed Ring, converting popular support, electoral victory, and public office into finance capital.
Tammany banks are also an opportunity to explore the colorful cast of secondary characters who participated in the Tweed Ring: Hank Smith, Walter Roche, Reeves Selmes, and Henry Genet. These figures have remained virtually anonymous to historians who have focused attention upon peak political actors. Although he was the central organizer, Tweed depended upon banking allies to perform vital services. Ring leaders were hardly dictators who commanded unthinking allegiances, despite being vilified as such by the popular press. They were instead party operators, entrepreneurs voluntarily cooperating across multiple institutions—including financial ones—for mutual benefit at the polls and on balance sheets. The handful of political allies who ran Tammany banks became newly minted property owners by extending credit; pooling resources; and coordinating investments in real estate, railroads, and newspapers. Banks and the ventures they financed placed propertied elites on corporate boards alongside Ring members, bringing Tweed together with scions like the Astors, newer robber barons such as the Vanderbilts, and staunch Republicans like Levi Morton and George Opdyke.Footnote 20 Tammany politicians from lower wards and the uptown elite rarely caucused within the same party factions.Footnote 21 But they were tied together as corporate managers on business deals that cemented mutual interest over the accumulation of wealth.
The Tammany bank run of November 1871 shattered this precarious network that wove together political allegiances with debt, credit, and speculation. The panic generated by Andrew Green's “checkmate moves” against Tweed's financial infrastructure exposed that its solvency was not based upon the typical cash reserves, deposits, or securities. Tammany banks were bolstered by the flimsiest of political confidence won in the rough-and-tumble of mass politics but lost just as easily when turned out of office. Bankruptcy deprived the Tweed Ring of crucial resources at the very moment when they faced unprecedented attacks. Without access to banks, the circulation of the Ring's political capital came crashing to a halt.Footnote 22
THE BOSS'S BANKERS
Investigations into the Tweed Ring continued for years after their removal from office. Court battles persisted long after the city's credit was restored because of the great difficulty proving allegations of fraud and embezzlement. The main reason was the sheer magnitude and complexity of the Ring's banking practices. The principal point where public funds were diverted was clear enough: “Tweed's Charter” of 1870 and a new tax levy bill created a Board of Audit that empowered Tweed, Hall, Sweeny, and Connolly to co-authorize new spending. Yet, it was virtually impossible to fully reconstruct where money went and exactly who pocketed it along the way. One of Samuel Tilden's investigators, Henry Fox Taintor, devoted four and one-half years of his life to this project. Tellingly, in 1877 he conceded to the city council in testimony that it would be “impossible for me to recite the various tedious, complicated, and laborious operations which have been conducted.” In fact, he explained, “the necessity of the minuteness of the inquiry” demanded that he sometimes visit between thirty and fifty separate banks on a single day to review accounts.Footnote 23 Amid confusion tracking money, a fundamental reality was lost. New York banks had widely varying relationships to the Ring.
On a conceptual level, Tammany's financial sector had three mutually dependent layers. What distinguished each layer were the level of Tammany influence and the way it functioned within larger Ring operations. The inner layer consisted of savings banks the Ring founded and controlled: the Guardian, Bowling Green, National Savings, and Yorkville. The second layer was composed of the Tenth National, a commercial bank where Tammany placed large city deposits and comanaged affairs. Finally, there were more established commercial banks that serviced individual Tammany leaders by allowing them to circulate checks and notes drawn from less reputable Tammany-backed institutions. Individual members of the Tweed Ring might sit as directors on banks within this tertiary layer, but as outsiders with the status of glorified clients.
Tweed and his allies in the state legislature chartered four savings banks between 1867 and 1869 and propped them up with money from city deposits, Catholic charities, and the earnings of common laborers. The number of savings banks in New York had been strictly limited for most of the nineteenth century. This was due in part to the high degree of faith required of trustees to handle client savings. In theory, state charters were supposed to mandate conservative banking principles and enforce countermeasures between bank officers and trustees to prevent theft, collusion, and self-dealing. This was particularly important for an institution's solvency because, unlike commercial banks, the only capital reserves lay in people's deposits. Of course, this feature was the central attraction for capital-poor Tammanyites. However, if deposits were mismanaged—or worse, stolen—then solvency fell upon whatever securities or collateral the bank officers might be able to produce at a moment's notice. Integrity in bank officers was therefore paramount. In the aftermath of bankruptcy, committees of depositors suing Tammany banks found this trait in short supply.Footnote 24
Another reason for the paucity of savings banks was that the legislature acted as a legal bulwark defending the privilege of a handful of wealthy individuals to speculate on deposits. It was not until the decade after the Civil War that the exclusive hold over savings banks was blown wide open: 133 were newly incorporated, the vast majority at the peak of Tweed's influence, whereas only 18 were previously in operation.Footnote 25 A major factor in the savings bank expansion was the political exigencies of Tammany's governing coalition, hungry for lucrative sources of patronage. Beyond politics, however, demand for services was riding high. Manhattan's population grew by leaps and bounds while wage labor was proliferating, generating new potential clients. The lower classes benefited from a tight postwar labor market, fostered by Tweed's debt-financed public works. The four years that Tammany savings banks were in operation, the number of depositors rose by 108,988 in New York City; impressive considering the population was roughly one million.Footnote 26 The ability to harness the savings of laborers offered a tantalizing source of “working” capital for whoever could get their hands on it.
Savings bank officials were all Tammany officeholders in the National Savings Institution (chartered 1867), the Guardian Savings Bank (1868), the Bowling Green Savings Bank (1868), and the Yorkville Savings Bank (1869). William Tweed was titular head at the Guardian, and Hank Smith at the Bowling Green. Several officers overlapped across multiple banks, in particular, Hank Smith and Walter Roche. In practice, the two comanaged the Guardian, Bowling Green, and National Savings Institution, which were all mutually dependent upon resources acquired by the Tweed Ring. Tweed's favored building contractor, James Ingersoll, was director at the Guardian and the National Savings. John McBride Davidson, the city's supplier of safes, was president at the latter, where Tweed's brother Richard was also director.Footnote 27 Five Pointers held a majority at the Bowling Green. Along with Roche sat Owen and Timothy Brennan, whose brother Matthew was sheriff. The Yorkville Savings, located uptown in East Harlem, a working-class immigrant neighborhood, was essentially a private bank for Henry Genet, the local state senator. He ran the bank with political allies John McQuade, police justice; and Frank Twomey, city clerk. On the Yorkville's board of directors sat John McKeon, a popular Irish attorney, wartime Copperhead, and leader of the McKeon Democrats.Footnote 28
Bowling Green Savings bank check.

Hank Smith and Walter Roche ran daily affairs at the Tammany savings banks, with the exception of the Yorkville.Footnote 29 Smith was a prominent “Tammany Republican,” a faction that exchanged patronage with local Democrats in return for political support. He first met Tweed and Roche on the New York County Board of Supervisors where they served on the Committee on Banks and Insurance Companies. Together, they evaluated claims for fees and directed public money for deposit.Footnote 30 Born into a Mohawk Valley farm family in 1821, Smith worked his way through Erie Canal boats becoming a driver, captain, and then company agent in New York City for the Swift-sure Steamboat and Albany Day-lines. A staunch Whig, he was elected alderman in the First Ward from 1854 until it was reorganized into the County Board of Supervisors, when he was elected as a Republican. His organization, the Henry Smith Club, made him a powerful Republican district leader. The New York Tribune once noted that he was “extremely popular with the working classes in the lower part of the city.”Footnote 31
On Tweed's recommendation, Hank Smith was appointed by the state legislature in 1868 to the Metropolitan Police Commission and was subsequently elected treasurer. In 1870 he became president, despite the fact that Democrats controlled a majority. Control over police authority was the third rail of municipal politics. Native-born propertied elites fiercely resisted local control over the coercive apparatus; invariably that would mean Tammany police, which reverberated into issues of temperance, gambling, crime, and patronage. Most notably, the Republican-designed commission system from the Charter of 1857 stripped Mayor Fernando Wood of power in this arena and precipitated the bloody Police Riots.Footnote 32 Tweed's solution was to appoint a Republican with which he could do business, quite literally. Smith was never a Democrat or member of Tammany Hall. However, he was vice president of Tweed's Americus Club, located in Greenwich, Connecticut, and also a member of his Blossom Club on Fifth Avenue.Footnote 33 The very same year Smith was appointed police commissioner he became president of the Bowling Green Savings Bank and vice president of the Guardian. He was also director at the National Savings Institution and two commercial banks, the Tenth National and Eight National.
Hank Smith's business partner was Walter Roche, an Irish famine refugee from County Carlowe. On Election Day, his “low rum shop” at 19 Mulberry Street served as a Five Points polling place. Much like Tweed and others of his generation, Roche cut his teeth as foreman of volunteer firemen. The Roche Guards emerged in the 1850s as a force of “shoulder-hitters,” or street fighters, allied with the Brennan brothers in neighborhood politics.Footnote 34 Matthew Brennan was one of the first Catholics to secure a place of influence within the Tammany hierarchy, and in a major achievement, the first Five Pointer elected citywide. Roche himself was elected County Supervisor for its inaugural session, from which the Tweed Ring crystalized. Politics served Roche well, although he began to describe himself as a “strict business man.”Footnote 35 The same year that Roche became vice president of two banks and director of a third he was also Commissioner of Street Openings and a noted “speculator ‘on the make’ generally.”Footnote 36 It was through Roche and the Brennans that Catholic charities were recruited to place large deposits with Tammany savings banks.Footnote 37
The second layer of Tammany's financial sector was organized around the Tenth National, a commercial bank. Its connection to Tammany Hall dated from October 1868. Wall Street speculators Jay Gould and Jim Fisk brought William Tweed and Peter Sweeny, his lieutenant, onto the Erie Railroad board of directors to build a political firewall against the legal advances of rival industrialist Cornelius Vanderbilt. Gould and Fisk also recruited the Tweed Ring's support for an audacious plan to corner the market in gold. The adventurers collectively purchased a majority stake in the Tenth National Bank, with the Ring's share of the investment at $500,000.Footnote 38 As part of Gould's and Fisk's financial speculation, Sweeny, the city chamberlain, moved millions of dollars of taxpayer money away from the Broadway Bank.Footnote 39
To make the gold corner possible, by the culmination of Black Friday, September 24, 1869, the Tenth National had certified $25 million in checks with mostly nonexistent collateral.Footnote 40 The bank survived the Friday crash that it helped trigger, and an investigation by the Treasury Department. When the Tenth National's officer elections were held in January 1870, the entire Tweed Ring was elevated to directors—Tweed, Sweeny, Connolly, and Hall. Tweed's father-in-law, Joseph Skaden, joined them, as did Peter Sweeny's brother in law, John Bradley, a Tammany state senator from the 7th District. Hank Smith, Tweed's connection with the police and Tammany savings banks, was also placed on the board, thereby forging a key management link between the Ring's commercial and savings banks.Footnote 41 Tellingly, the bank became the repository of over $1.2 million of city money.Footnote 42
The Tenth National, through Gould and Fisk, offered something of great value to Tammany that was otherwise beyond its reach: a bank with a national charter. With the United States off the gold standard to finance war debt, Congress empowered the Treasury Department to grant national banks exclusive rights to hold reserves in the form of U.S. banknotes. The national banks issued these notes, deemed legal tender, based upon federal government bonds purchased as security. Along with greenbacks, they represented a new uniform currency backed not by promise of payment in specie but rather, as Stephen Mihm explains, an abstract belief in “the credit of the nation.”Footnote 43 With a capitalization of $1 million, the Tenth National partnership with Gould and Fisk thus greatly magnified the Tweed Ring's reach.Footnote 44 The politicos could now use the “broker's bank” as a reliable intermediary between public money and Wall Street.
Finally, the outermost layer of the Tammany network was composed of a patchwork of personal accounts in established commercial banks. To the greatest extent possible, Ring members preferred to work with cash. However, under the Tweed Ring's regime of profligate spending, government departments paid contractors in vouchers and warrants.Footnote 45 What this meant in practice was that New York issued promises to pay bills with its own form of scrip. Payment in city paper facilitated embezzlement, but also made the grossly inflated cost of goods and services traceable for later investigators. This paper was circulated through dozens of banks and funded by a trebling of bonded debt purchased by New York banks, including Tammany institutions, and European investors. A veritable army of plasterers, plumbers, carpenters, furnishers, and printers were overflowing with vouchers and thus required banking services. Once a bank accepted the local government paper, essentially converting it, Tammany contractors would transfer the Ring's cut—which ranged from 16 percent to 66 percent into the personal accounts of their patrons through payment in checks, banknotes, and greenbacks.Footnote 46
New York Pay's Boss Tweed's brother, Richard.

In this way, Tammany officeholders brought long-standing financial institutions a large volume of business. Each member of the Tweed Ring had their preferred banks through which they circulated money dispossessed from taxpayers. In return, the banks gave them special treatment. Frequently this meant loans without security or collateral. But their checks would often be mislabeled as cash deposits in accounting books while they were allowed to withdraw cash, essentially trading questionable paper from Tammany banks for greenbacks. Tweed himself patronized the Ocean Bank, among others, where his New York Printing Company secured loans and he later became director.Footnote 47 Comptroller Richard Connolly kept his largest account at the Central National Bank. Andrew Garvey, whose firm plastered the walls of the New York County Courthouse, sent his money through the Broadway Bank.Footnote 48 Not surprisingly, the Ocean, Central National, and Broadway banks were all custodians of city deposits.Footnote 49 Peter Sweeny and his brother James frequented the Nassau, Broadway, and Fourth National banks.Footnote 50 The principal contractor for the construction of the Harlem District Courthouse, John Scallon, made deposits at several different banks, including directly into the Yorkville Savings Bank. As Yorkville's president and also counsel to the courthouse commission awarding contracts, Henry Genet was less discrete than most.Footnote 51 More typical was the strategy of James Ingersoll. He later testified that several million dollars worth of warrants passed through his hands into a half dozen New York banks, of which he only retained $100,000 for personal use.Footnote 52 When extrapolated to the Ring's main contractors John Keyser, John McBride Davidson, Andrew Garvey, J. O. Seymour and others, the sheer breadth of circulation is staggering.
Investigators for Samuel Tilden's grand jury found that peripheral accounts in commercial banks invariably routed checks to and from the Tenth National, which acted as Tammany's clearinghouse. Essentially, the Tweed Ring laundered public funds through well-regarded institutions into one whose reputation was tainted by association with Jay Gould's corporate empire. With their position at the Tenth National, the Tweed Ring then supplied its savings banks and political projects with an ample flow of credit. The Ring therefore had its own savings banks, a comanaged commercial bank, and a web of accounts scattered across the city. “[N]early every bank in the city is implicated in frauds upon the public treasury,” argued Henry Genet as the state senate debated his expulsion from the chamber.Footnote 53 Genet meant to rally this fact in defense of his actions. Whether or not the entire banking community shared culpability, in the end, only members of the Tweed Ring were punished.
Henry Genet of Tammany Hall and the Yorkville Savings Bank.

POLITICAL FINANCE
How exactly did the Tammany banks function? Official investigations and court records show they mixed spoils-style patronage with profit-minded business calculations. They provided access to a pot of money devoted to lobbying activities in Albany. At the same time, bank officers financed a diverse array of personal and corporate loans and investments; a surprising number were spread across the country. Bolstered by public deposits and securities of real estate acquired cheaply through political channels, Tammany banks participated in some of the period's most notorious financial practices—sweetheart loans, risky speculation, loose bookkeeping, and straight-up theft. Voracious demand for credit ultimately outstripped Tammany's ability to provide sufficient collateral. This gap left its banking network vulnerable to the panic catalyzed by Andrew Green's transfer away of a small amount of city money on November 18, 1871.
Some loans hewed conspicuously to the political side of the equation. A major obstacle of Tammany Democrats in the state legislature was cultivating alliances with upstate Republicans. Yet, the 1870 and 1871 state legislative sessions experienced a burst of productivity that included two of Tweed's top priorities: a revised state charter and decentralization of tax revenue. To advance his Albany agenda, William Tweed used his banks to make personal loans to legislators. A prime example of how this worked were the loans that he oversaw to General James Wood, a Republican state senator from the 30th District in Livingston County.
Senator James Wood was elected in 1869 by defeating an incumbent Democrat closely allied with Jay Gould's Erie Railroad. Once in office, Wood seized an opportunity to raise capital for a new business venture. His local reputation was damaged by a failed law partnership and insolvency; thus, Wood turned to political avenues to finance his investment in a whiskey distillery. He approached Jay Gould, president of Erie Railroad, who offered him $10,000 in cash; and then Tweed, who wrote the senator a check for $15,000 from the Tenth National Bank. Both were ostensibly loans, and they were based on Wood's paper—a promissory note to repay the sum three months later with interest. Neither lender sought collateral or securities, or undertook the normal inquiries about Wood's creditworthiness. The loans were granted based on their new relationship as “friends” and Wood's reception to pending legislation.
With these funds, Senator Wood was in need of banking services. He did not deposit the money locally, at least not at first. Instead, he turned to Tammany banks, where he sought to push his new credit further. Hugh Hastings, a Republican assemblyman, newspaper editor, and Tweed lobbyist, later explained in testimony how the rural senator came to open accounts in downtown Manhattan with the Bowling Green Savings Bank. Wood informed Hastings in conversation that he was traveling from Albany to New York City for business, and requested advice where to place his money. According to Hastings, “Mr. Smith was standing close by us at the time, and I said, ‘there is the President of the Bowling Green Savings Bank.’” In fact, Hank Smith and James Wood were already acquainted from the Republican state convention in Syracuse that nominated him for senate, and from Smith's frequent lobbying trips to Albany on Tweed's behalf. When the senator opened an account with the Bowling Green Bank, Smith was present at the meeting, along with Walter Roche, the bank's vice president; and its secretary, Reeves Selmes, who was also deputy county clerk. Wood's new account was granted “special” status, meaning he received interest daily, as opposed to the monthly interest accrued by common depositors.Footnote 54 That same meeting Wood withdrew $1,000 for later deposit at the Livingston County Savings Bank located within his electoral district.
The Tammany leader also made another loan to Senator Wood's business partner, Henry Chamberlain. Tweed discounted a note from the Tenth National Bank for $15,000 at 3.4 percent interest due in three months. To accompany the note, Tweed wrote an introductory letter for Chamberlain to William Bliss, president of the Tenth National. Chamberlain subsequently opened a corporate account for the New York Whiskey Company at the bank. The Tenth National accepted Tweed's note, and on his word, the whiskey company's credit. By the time of Tweed's first arrest in the fall of 1871, the whiskey company had yet to generate one dollar of profit. Wood never repaid Tweed the principal on loans totaling $30,000, the maturity of which was extended six times in two years.Footnote 55
During investigations, Tweed acknowledged making substantial loans to state senators, and noted in 1872, “I have many [outstanding] claims against the lower House.” Attorney General Charles Fairchild's reconstruction of Tweed's finances found $1,596,725.14 worth of these “Loans and Donations.”Footnote 56 It is doubtful that he expected to make any money from them or that he even expected to be paid back. Rather, Tweed cultivated the image within legislative chambers that he was a banker with capital at his disposal and could be approached for favors. Extension of credit to upstate politicians was meant to foster cycles of dependence: loans could be perennially renewed as long as help on votes and committee work continued. Importantly, such benevolence was in contrast to money loaned to Tammany subordinates who were required to repay in full.Footnote 57 But Tweed's Albany loans also reveal another facet of banking operations. By working through the Bowling Green and Tenth National banks, Tweed sought to keep the circulation of capital firmly within the orbit of Tammany-controlled institutions.Footnote 58 Tweed's political debtors patronized his banks.
In contrast to explicitly political loans, a separate category of Tammany investments was meant to generate profit. Bank officers used their privileged positions to finance personal mortgages on choice real estate.Footnote 59 Most strikingly, the savings banks had an overwhelming amount of their capital invested in risky “call loans.” Savings institutions typically invested in low-yielding government or corporate bonds that were unlikely to place depositors’ savings in peril. On the other hand, call loans were speculative investments. In theory, they could be recalled upon demand should the need arise, as opposed to a fixed date in the future. Commercial banks did a brisk business in these types of loans. The Ocean Bank, where Tweed was director, had $500,000 worth of outstanding call loans in 1871; but it was also capitalized at $1 million.Footnote 60 Savings banks had no such working capital beyond deposits. Worse, there was virtually no oversight of investments. The boards of directors of Tammany banks were figureheads who rarely met, and Reeves Selmes, treasurer, happily cosigned checks without question.
At the time of its bankruptcy, the Bowling Green Savings Bank had nearly 40 percent of its total deposits invested in call loans, with interest running as high as 15 percent to 20 percent on principal. Most of these loans were extended to political associates without security or consultation beyond one or two individuals with clear conflicts of interest. As might be expected, this practice had a destabilizing effect. Smith and Roche used the Guardian Bank, where they were also officers, to pump tens of thousands of dollars into the Bowling Green to temporarily cover up heavy losses.Footnote 61 Following the November 20 run, Smith, Roche, and Selmes utterly failed to collect at a pace fast enough to keep the Bowling Green Bank solvent.Footnote 62
For example, the bank loaned $65,000 to the Avenue C Railroad. Alfred Darling, a Republican and founder of the prestigious Union League Club, was lead incorporator. Upon the loan's negotiation, Smith and Roche were elevated onto the railroad's board of directors. The company had been organized in December 1868 with the mandate to place track across a circuitous route through Lower East Side. The legislature later amended the charter to further expand the scope of its terrain uptown.Footnote 63 However, most of the Avenue C line remained unfinished when the Bowling Green Bank called in its loan in late November 1871. The railroad balked and filed suit on the grounds that Roche had illegally appropriated bonds for personal use. Even in receivership, the bank never recouped the money.Footnote 64 The Avenue C was a classic example of how Tammany politicians leveraged political institutions for private accumulation. They supported the passage of a railroad charter whose mandate fell within the confines of their electoral constituency, even going so far as to partially finance it through private banks with money appropriated from taxpayers.
Another class of investments were geographically far from Tammany's parochial domain. During an impromptu April 1870 meeting that took place in Hank Smith's office at police headquarters, the Bowling Green Bank decided to purchase shares of the Hannibal and St. Joseph, a Missouri railroad. Unfortunately, the railroad's stock prices fell precipitously. The bank eventually lost $123,000 on the gamble, despite Smith's initial assurances to Roche and Selmes that “plenty of money was to be made in it.”Footnote 65 Counted among the losses were police funds: pensions, disability, and compensation for family of officers killed in the line of duty. In addition, the bank had illegally invested and subsequently lost $18,000 raised by police for victims of the Great Chicago Fire.Footnote 66
The Bowling Green was not the only Tammany bank to look across the country for speculative opportunities. The Yorkville Savings Bank held $10,000 worth of Alabama and Chattanooga Railroad bonds.Footnote 67 When the Ocean Bank failed in December 1871, the court-appointed receiver found that, along with uptown lots on 7th Avenue, the bank owned 2,357 acres of land in Cherokee County, Iowa; and 14,000 acres in Illinois. The Ocean also owed $40,000 to an unnamed “western” bank.Footnote 68 Tammany's own newspaper confessed, “the failure of the Ocean Bank has involved many persons in a sea of troubles.”Footnote 69
In their hurry to get rich quick, the Tweed Ring also patronized Wall Street brokerage firms. It may be of little surprise that Tweed had a “speculative” account in Smith, Gould, Martin & Co., where Jay Gould was a named partner.Footnote 70 More startling was the healthy amount of business given to the brokerage firm of George Opdyke, the wartime mayor of New York and a leading figure in Radical Republican circles. After the Ring scandals broke, Opdyke wrote a letter, expressing his embarrassment, to Tilden's investigators. Apparently, Tweed and other Tammany officeholders had purchased $76,000 worth of convertible bonds through his firm for the New York & Oswego Midland Railroad; Opdyke claimed to have no prior knowledge about these sales before the grand jury's inquiry.Footnote 71 Still, it was widely known that investigators were seeking to claw back public money. Opdyke, the sitting vice president of the New York Chamber of Commerce, did not volunteer to return his commission. There is no record he ever did.
REVENGE OF THE BANKERS
Historiography has largely cast the elite reaction against the Tweed Ring as a revolt of wealthy taxpayers led by an old guard of gentlemen-politicians. Yet many of the individuals who actively led the reform effort had material stakes involved beyond abstract goals of restoring the city's credit and public confidence in government. Reformers’ heavy interests in banking and finance meant that many of them were in direct competition with the Ring's upstart banks. Anti-Tweed forces used their skills as ruthless business operators to bring swift closure to Tammany's experiment in political capitalism.
Rival savings institutions led the revolt against the Boss's banks. For a coterie of the immigrant bourgeoisie who made their fortunes prior to the Tweed Ring, or independently of it, becoming bank officers at the Emigrant Savings Bank (founded in 1850) and German Savings Bank (1859) was already a recognized path to elite status. Furthermore, these savings banks sought the same immigrant working-class constituency as Tammany voters and would-be depositors. When credible accusations of speculation arose in the press, Charles O'Conor from Emigrant Savings and Philip Bissinger of the German Savings placed their resources behind reformers. The 67 year-old O'Conor took the lead in early suits against Tweed.Footnote 72 The law firm of John Develin, who was counsel for the Emigrant Bank and vice president of the anti-Tweed Committee of Seventy, represented depositor suits against the Guardian that precipitated its involuntary bankruptcy. Develin in particular was hardly coy in making business competition a motivating factor. He once closed legal arguments by reading from the “glowing prospectus issued by the [Guardian] bank and circulated among citizens and smaller dealers” in order to highlight Tammany's lack of credibility in banking affairs.Footnote 73 The activism of wealthier and more established financial institutions was thus felt in court actions. To oversee the Bowling Green's cannibalization, Shepherd Knapp was appointed receiver. At the time, Knapp was trustee at Greenwich Savings, an old-line rival, president of Mechanics’ National Bank, and former president of the Clearing House.Footnote 74 Richard Schell posted bond for his brother Edward's receivership of the National Savings Institution; Edward was treasurer at the rival Manhattan Savings Institution, located one block north on Broadway. When the bank run had occurred, Richard also happened to be vice president of the Union Trust Company.Footnote 75 This was the same bank where the newly empowered deputy comptroller, Andrew Green, was moving public deposits away from the Guardian Bank at the explicit request of mayor-in-waiting William Havemeyer and Samuel Tilden.Footnote 76 Notably, the million dollars clawed back from Ring members through civil suits was placed with Union Trust.Footnote 77 The redirection of public deposits to this bank was a deliberate allocation of patronage by reformers to their own allies.
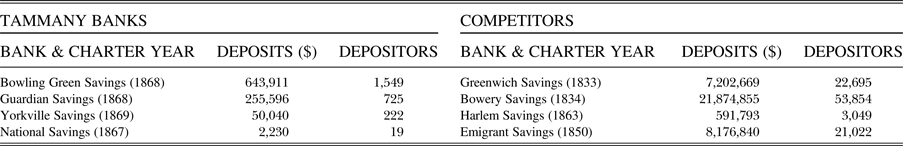
One nineteenth-century chronicler, Emerson Keyes, attributed the failure of Tammany savings banks to “struggling for existence in the effort to compete with old established organizations.”Footnote 78 Table 1 confirms the established banks had both the greater number of depositors and the larger quantity of deposits. The threat of economic competition, however, was quite real. Established rivals found the congruence between voters and depositors at the Tammany banks alarming. Also worrying, the terms of Tammany banks were generous to the poor, forcing more established banks to raise interest dividends on savings accounts to compete.Footnote 79 Indeed, through political connections, Tammany enjoyed a major competitive advantage. With ready access to public funds, Tammany banks enjoyed a plentiful source of capital for future growth.Footnote 80 Keyes was correct to cite competition between savings banks as one cause of Tammany bank failures. But the struggle was as much political as economic.
Comparison of Tammany Savings Banks and Competitors

Source: The Bankers' Magazine and Statistical Register, July 1871, 124
Did the Tammany banks have a future? In one respect, they were expanding along with Tweed's political reach. The summer of 1871, Tweed amended the charter of the National Savings Institution to cover a wider geographic area that included all the territory south of 14th Street.Footnote 81 These ambitions for growth met with fierce resistance. One measure is the invective that erupted from redoubts of established banking. The Tammany banks were “fraudulent all through,” charged The Financier. “Their rapacity which had such an adaptability that, like the elephant's trunk, it could pick up with equal ease small things and great, created savings banks because it wanted even small hoards.”Footnote 82 The New York Times chided the banks for accumulating “capital thus wrongly acquired.”Footnote 83 Another Republican paper mocked Tammany politicians for “playing bank.”Footnote 84
Public attention generated by the bankruptcies in November 1871 provided a fresh wave of embarrassment for Tammany Hall, already weakened by The New York Times’ revelation of embezzlement over the summer. Henry Genet of the Yorkville Savings Bank failed to satisfy fraud investigators, claiming strangely for a banker, “he was not in the habit of keeping accounts.” Senator Genet subsequently fled to Canada with $17,000 of bank deposits.Footnote 85 Acrimonious legal battles between the Guardian and Bowling Green, formerly allied banks placed in receivership, elicited court testimony that exposed off-the-books activity. In several cases, Tweed apparently withdrew tens of thousands of dollars without leaving any record.Footnote 86 Roche, for his part, was found guilty of improperly lifting $77,408 of bank money.Footnote 87 As the hammer fell, former associates turned against each other in quixotic attempts to escape liability, thereby fraying a once powerful alliance.
By the run of November 1871, Tammany banks were effectively ostracized from the business community. This was symbolized by expulsion from the New York Clearing House and the refusal of other banks to honor checks, notes, and other forms of paper. Reeves Selmes of the Guardian and Bowling Green banks frankly acknowledged to the press that “the odium heaped upon us” crippled long-term viability.Footnote 88 Soiled reputations left the banks with only local government available as the lender of last resort; yet, political conditions made rescue impossible. The power of reformers over the flow of credit was made clear when deputy comptroller Green secured a half-million-dollar loan without security from the New York Clearing House to meet the bankrupt city's payroll obligations.Footnote 89 The November Tammany run had forced many established banks into questionable financial status, but these institutions had no trouble finding rescuers to stabilize them. In triumph, reformers crowed that no bank chartered before 1850 was swept away in the fallout.Footnote 90
CONCLUSION
Tammany Hall's banks were an innovative development in the late spoils system, but their central role in the Tweed Ring elicited a fierce reaction from capital-owning New Yorkers. In the following decades, Tammany became synonymous with democratic regulars in the city. However, the composition of leadership and political practices were transformed by the Ring's defeat, including the end of a foray into finance.Footnote 91 It is impossible, of course, to speculate about historical trajectories in which the banks might have survived Tweed intact. Would Tammany-grown capitalists have developed distinctive policy interests in tension with its immigrant and working-class electoral base? After all, an important contingent of Republican financiers weaned on selling U.S. government debt bolted their party in 1872, demonstrating independence from machine politics. Or would the development of Tammany's banking sector have made the faction even more influential in state and national politics by providing access to greater resources? We only know the actual historical outcome. In a loss that Walter Roche told the press he felt “very deeply,” the bank run of November 18 to 20, 1871, aborted the emergence of Tammany's politician-bankers.Footnote 92 Reformers imposed a division of labor between political professionalism, the domain of ward heelers, and control over the private allocation of capital investment—the sphere of capitalists.