



1. Introduction
Random-length sequences and distribution tails of their sums and maxima have attracted the interest of many researchers due to numerous applications including queues, branching processes [Reference Asmussen and Foss4], actuarial risk theory [Reference Robert and Segers29, Reference Tillier and Wintenberger32], random networks [Reference Lebedev19, Reference Litvak, Scheinhardt and Volkovich21, Reference Markovich24, Reference Volkovich and Litvak33], and general theory [Reference Gissibl and Klüppelberg11, Reference Goldaeva and Lebedev13, Reference Jelenkovic and Olvera-Cravioto15–Reference Jessen and Mikosch17, Reference Lebedev20, Reference Markovich and Rodionov26, Reference Olvera-Cravioto28].
We aim to extend the results for weighted sums and maxima obtained in [Reference Markovich and Rodionov26]. As in the latter paper, we deal with a doubly indexed array
 $\{Y_{n,i}\colon n,i\ge 1\}$
of non-negative random variables (RVs) in which the ‘row index’ n corresponds to the time, and the ‘column index’ i enumerates the series. On the same probability space, the existence of a sequence of non-negative integer-valued RVs
 $\{N_n\colon n\ge 1\}$
is assumed. Let
 $\{Y_{n,i}\colon n\ge 1\}$
be a strict-sense stationary sequence with the extremal index
 $\theta_i$
having a regularly varying tail
 \begin{equation} \mathbb{P}\{Y_{n,i}>x\} = \ell_i(x)x^{-k_i} \end{equation}
with tail index
 $k_i>0$
and a slowly varying function
 $\ell_i(x)$
for any
 $i\ge 1$
. There are no assumptions on the dependence structure in i.
Definition 1. A strictly stationary sequence
 $\{Y_n\}_{n\ge 1}$
with distribution function F(x) and
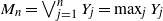 $M_n=\bigvee_{j=1}^{n}Y_j=\max_j Y_j$
is said to have the extremal index
 $\theta\in[0,1]$
if, for each
 $0 < \tau < \infty$
there exists a sequence of real numbers
 $u_n=u_n(\tau)$
such that [Reference Leadbetter, Lindgren and Rootzén18, p. 63]
 \begin{align} \lim_{n\to\infty}n(1-F(u_n)) & = \tau, \nonumber \\ \lim_{n\to\infty}\mathbb{P}\{M_n\le u_n\} & = {\mathrm{e}}^{-\tau\theta}. \end{align}
Independent and identically distributed (i.i.d.) RVs
 $\{Y_n\}$
give
 $\theta=1$
. The converse may be incorrect. An extremal index that is close to zero implies a kind of a strong local dependence.
In [Reference Markovich and Rodionov26], the weighted sums and maxima
 \begin{equation} \begin{aligned} Y_{n}^{*}(z, N_n) & = \max\!(z_1Y_{n,1},\ldots,z_{N_n}Y_{n,N_n}), \\ Y_{n}(z, N_n) & = z_1Y_{n,1} + \cdots + z_{N_n}Y_{n,N_n} \end{aligned}\end{equation}
for positive constants
 $z_1, z_2,\ldots$
and regularly varying
 $\{Y_{n,i}\colon n\ge 1\}$
were considered. A similar result was obtained in [Reference Goldaeva12] for the same weights and for random sequences of a fixed length
 $l\ge 1$
and when the
 $\{Y_{n,i}\colon n\ge 1\}$
have a power-type tail, i.e.
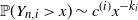 $\mathbb{P}(Y_{n,i}>x) \sim c^{(i)} x^{-k_i}$
as
 $x\to\infty$
, where
 $c^{(i)}$
is a positive constant for each fixed i. The symbol
 $\sim$
means asymptotically equal to, or
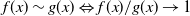 $f(x)\sim g(x) \Leftrightarrow f(x)/g(x)\rightarrow 1$
as
 $x\rightarrow a$
,
 $x\in M$
, where the functions f(x) and g(x) are defined on some set M and a is a limit point of M.
We recall [Reference Markovich and Rodionov26, Theorem 4], related to the sums and maxima (3), in Theorem 2. Everywhere it is assumed that the ‘column’ sequences
 $\{Y_{n,i}\colon i\ge 1\}$
have stationary distribution tails (1) in n with positive tail indices
 $k_i$
and extremal indices
 $\theta_i$
for each fixed i. Here, the
 $\{\ell_i(x)\}$
are restricted by the uniform condition in i: for all constants
 $A>1$
and
 $\delta>0$
there exists
 $x_0(A,\delta)$
such that, for all
 $i\geq 1$
,
 \begin{equation} \ell_i(x) \leq A x^\delta, \quad x>x_0(A, \delta) .\end{equation}
The result for fixed i follows by Potter’s theorem [Reference Bingham, Goldie and Teugels6, Theorem 1.5.6]. The condition in (4) is not valid for any slowly varying function, for instance, for
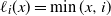 $\ell_i(x)=\min(x,i)$
. (4) is required to neglect the impact of terms
 $Y_{n,i}$
distributed with non-minimum tail indices on the tail functions of
 $Y_{n}(z, N_n)$
and
 $Y_{n}^*(z, N_n)$
by means of the polynomial multiplier.
 $\{N_n\colon n\ge 1\}$
is assumed to be a sequence of non-negative integer-valued RVs. It is noted in [Reference Jessen and Mikosch17, Reference Robert and Segers29, Reference Volkovich and Litvak33] that
 $N_n$
can be modeled by a regularly varying distribution with the tail index
 $\alpha>0$
, that is,
 \begin{equation} \mathbb{P}(N_n>x) = x^{-\alpha}\tilde{\ell}_n(x).\end{equation}
This model is realistic and has applications in random networks [Reference Markovich24, Reference Volkovich and Litvak33], teletraffic, and finance [Reference Robert and Segers29]. There is a minimum tail index
 $k_1$
and
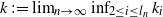 $k \,:\!= \lim_{n\to\infty} \inf_{2\leq i\leq l_n} k_i$
,
 \begin{equation} l_n=[n^\chi],\end{equation}
where
 $\chi$
satisfies
 \begin{equation} 0<\chi<\chi_0, \qquad\chi_0 = \frac{k-k_1}{k_1(k+1)}.\end{equation}
Such k,
 $l_n$
, and
 $\chi_0$
were taken in Theorems 1 and 2 by [Reference Markovich and Rodionov26] for the basic case with a unique ‘column’ sequence with a minimum tail index. An arbitrary dependence structure between
 $\{Y_{n,i}\}$
and
 $\{N_n\}$
is allowed. The tail of
 $N_n$
does not dominate the tail of the most heavy-tailed term
 $Y_{n,1}$
. Let
 $\ell(x)$
be such that
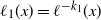 $\ell_1(x) = \ell^{-k_1}(x)$
, and
 $\ell^{\sharp}(x)$
be the de Brujin conjugate of
 $\ell(x)$
[Reference Bingham, Goldie and Teugels6]. Let
 \begin{equation} u_n = yn^{1/k_1}\ell_1^{\sharp}(n), \quad y>0,\end{equation}
where we write
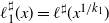 $\ell_1^{\sharp}(x) = \ell^{\sharp}(x^{1/k_1})$
, and the positive weights
 $\{z_i\}$
are bounded. Theorem 2 follows from Theorem 1.
Theorem 1. ([Reference Markovich and Rodionov26].) Let
 $k_1<k$
, (4), (6), and (7) hold. Then the sequences
 $Y_n^*(z,l_n)$
and
 $Y_n(z,l_n)$
have the same tail index
 $k_1$
and the same extremal index
 $\theta_1$
.
Theorem 2. ([Reference Markovich and Rodionov26].) Let the sets of slowly varying functions
 $\{\tilde{\ell}_n(x)\}_{n\geq 1}$
in (5) and
 $\{\ell_i(x)\}_{i\geq 1}$
in (1) satisfy the condition (4). Suppose that
 $k_1<k$
and
 \begin{equation} \mathbb{P}\{N_n>l_n\} = o(\mathbb{P}\{Y_{n,1}>u_n\}), \quad n\to\infty, \end{equation}
where the sequence
 $l_n$
satisfies (6) and (7). Then the sequences
 $Y_{n}^*(z,N_n)$
and
 $Y_{n}(z,N_n)$
have the same tail index
 $k_1$
and the same extremal index
 $\theta_1$
.
Remark 1. From these theorems it follows that if the ‘column’ series with a minimum tail index
 $k_1$
is unique, then the tail distributions of the sequences
 $Y_{n}^*(z,N_n)$
and
 $Y_{n}(z,N_n)$
are asymptotically equivalent to its distribution tail. The stationarity of the ‘column’ series with a minimum tail index
 $k_1$
is enough for
 $Y_{n}^*(z,N_n)$
and
 $Y_{n}(z,N_n)$
to have an extremal index
 $\theta_1$
for an arbitrary dependence between the ‘column’ sequences.
Our objective is to extend Theorem 2 for the case when a random number of ‘column’ series in (3) may have the minimum tail index. Additional dependency conditions on the latter ‘columns’ are then required. The extension is motivated by applications in distributed computation, random networks, and telecommunication systems as described in Section 3.
Moreover, we observe how the results may change under the opposite assumption,
 \begin{equation} \mathbb{P}\{Y_{n,1}>u_n\} = o(\mathbb{P}\{N_n>l_n\}), \quad n\to\infty,\end{equation}
instead of (9). This setting is relevant as mentioned in [Reference Robert and Segers29], particularly for earthquake insurance featuring a potentially large number of bounded claims, and in teletraffic arrivals. The condition in (10) is allowed in [Reference Volkovich and Litvak33] to build a recursive procedure for PageRank for a randomly chosen web page (a node of a web graph). The procedure starts with an initial distribution of PageRank (e.g.
 $R^{(0)}\equiv 1$
) that has a lighter tail than the node in-degree N in [Reference Volkovich and Litvak33, Theorem 3.2].
We use the following notation:
 \begin{align*} M_n^{(i)} & = \max\{Y_{1,i}, Y_{2,i},\ldots,Y_{n,i}\}, \quad i\in\{1,\ldots,l_n\}, \\ M_n(z,l_n) & = \max\{Y_1(z,l_n),Y_2(z,l_n),\ldots,Y_n(z,l_n)\}, \\ M_n^*(z,l_n) & = \max\{Y_1^*(z,l_n),\ldots,Y_n^*(z,l_n)\} = \max\{z_1M_n^{(1)},\ldots,z_{l_n}M_n^{(l_n)}\}, \quad n\ge 1.\end{align*}
Here,
 $l_n$
serves as an upper bound regarding the number of series both with a minimum tail index and the non-minimum tail indices. k defines the minimum tail index among the other columns that have higher tail indices than the minimum
 $k_1$
. The choice of the value
 $\chi_0$
is used to determine the upper bound of
 $l_n$
in such a way as to suppress the influence of columns with tail indices exceeding
 $k_1$
.
The paper is organized as follows. The extension of Theorems 1 and 2 by Theorems 3 and 4 for fixed and random numbers of the most heavy-tailed ‘column’ series in (3) is given in Section 2.1. Examples of stochastic sequences that satisfy the conditions of Theorems 3 and 4 are provided in Section 2.2. The extension of Theorems 2 and 4 for a heavy-tailed number
 $N_n$
of light-tailed terms is stated in Section 2.3. The motivation for and application of the topic are given in Section 3. We finalize with conclusions in Section 4. The proofs are given in the Appendix.
2. Main results
2.1. Extension of Theorem 2
We extend Theorem 2 by Theorem 4, allowing a random bounded number
 $d\ge 1$
of series to have a minimum tail index. To this end, we extend Theorem 1 by Theorem 3. Theorem 1 covers the case
 $d=1$
. We assume in Theorem 3 that
 $d>1$
is fixed and
 $k_i=k_1$
,
 $i\in\{1,\ldots, d\}$
,
 $1\le d\le l_n-1$
,
 $k_1<k=k_{d+1}$
, where k provides the minimal tail index among the rest of columns, i.e.
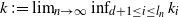 $k \,:\!= \lim_{n\to\infty}\inf_{d+1\leq i\leq l_n}k_i$
. We introduce the following conditions:
-
(C1) The stationary sequences
 $\{Y_{n,i}\}_{n\ge 1}$
,
$i\in\{1,\ldots,d\}$
are mutually independent, and independent of the sequences
$\{Y_{n,i}\}_{n\ge 1}$
,
$i\in\{d+1,\ldots,l_n\}$
.
-
(C2) Assume
$\{Y_{n,i}\}_{n\ge 1}$
,
$i\in\{1,2,\ldots,d\}$
satisfy the following conditions as
$x\to\infty$
: (11)for some non-negative numbers
\begin{equation} \frac{\mathbb{P}\{Y_{n,i}>x\}}{x^{-k_1}\ell_1(x)} \rightarrow c_i, \quad i\in\{1,2,\ldots,d\},\end{equation}
$c_i$
; (12)
\begin{equation} \frac{\mathbb{P}\{Y_{n,i}>x, Y_{n,j}>x\}}{x^{-k_1}\ell_1(x)} \rightarrow 0, \quad i\neq j,\ i,j\in\{1,2,\ldots,d\}. \end{equation}
By [Reference Davis and Resnick9, Lemma 2.1], in condition (C2),
(13)for any
\begin{equation} \frac{\mathbb{P}\big\{\sum_{i=1}^dY_{n,i}>x\big\}}{x^{-k_1}\ell_1(x)} \rightarrow \sum_{i=1}^dc_i, \quad x\to\infty,\end{equation}
$n\ge 1$
.
-
(C3) Assume that there exists
$i\in\{1,\ldots,d\}$
such that (14)
\begin{equation} \mathbb{P}\Big\{\max_{1\le j\le d, j\neq i}(z_{j}M_n^{(j)})>u_n, z_{i}M_n^{(i)}\le u_n\Big\} =o(1), \quad n\to\infty. \end{equation}


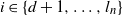

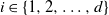


Remark 2. Condition (C1) means that the mutual dependence between the rest of the ‘column’ sequences
 $\{Y_{n,i}\}_{n\ge 1}$
,
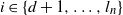 $i\in\{d+1,\ldots,l_n\}$
, does not matter. This case appears particularly in random networks where communities of nodes with their influence indices can be considered as the ‘columns’ and communities with the minimum tail index may be thought to be the most influential ones, see Section 3. (11) appears to be a tail equivalence condition between the
 $\{Y_{n,i}\}$
,
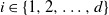 $i\in\{1,2,\ldots,d\}$
. (12) can be considered as asymptotic independence between the d ‘column’ sequences with the minimum tail index. It is important for our proof that (13) is valid for not necessarily independent or identically distributed RVs
 $Y_{n,1},\ldots,Y_{n,d}$
. (12) is a sufficient but not necessary condition for (13). Condition (C3) is required to provide a distribution asymptotic equivalence of maxima over d dependent ‘columns’
 $M_n^*(z,d)$
and a maximum over one of the d ‘columns’
 $M_n^{(i)}$
,
 $i\in\{1,\ldots,d\}$
.
Remark 3. Not all the conditions (C1)–(C3) are simultaneously required for the results to hold. The results will be shown under different subsets of these conditions.
Let
 $u_n$
in Theorems 3 and 4 be as in (8).
Theorem 3. Let (4) hold for all
 $d+1\leq i\leq l_n$
, and let (6) and (7) be satisfied. If, in addition, condition (C1) or (C2) holds, then
 $Y_n^*(z,l_n)$
and
 $Y_n(z,l_n)$
have tail index
 $k_1$
.
-
(i) If condition (C1) holds, then
$Y_n^*(z,l_n)$
and
$Y_n(z,l_n)$
have the same extremal index (15)
\begin{equation} \theta(z) = \frac{\sum_{j=1}^d\theta_jz_j^{k_1}}{\sum_{j=1}^dz_j^{k_1}}. \end{equation}
-
(ii) If condition (C3) holds, then
$Y_n^*(z,l_n)$
has the extremal index
$\theta_i$
. If, in addition to (C3), (C2) holds, then
$Y_n(z,l_n)$
has the same extremal index as
$Y_n^*(z,l_n)$
.


Remark 4. Condition (C3) determines the dependence between maxima of d ‘columns’ with the minimum tail index. The extremal index of
 $Y_n^*(z,l_n)$
exists in case of (14) due to the asymptotic equivalence of the distributions of the maximum over d columns,
 $M_n^*(z,d)$
, and the maximum over the ith column,
 $M_n^{(i)}$
. Roughly speaking, (C3) allows us to return to the case of a unique column with the minimum tail index and to use the corresponding extremal index
 $\theta_i$
of the ith column in (C3) for
 $Y_n^*(z,l_n)$
. The same extremal index for the sums
 $Y_n(z,l_n)$
requires both (C2) and (C3).
Now we reformulate Theorem 2.
Theorem 4. Let the sets of slowly varying functions
 $\{\ell_i(x)\}_{i\ge 1}$
in (1) and
 $\{\tilde{\ell}_n(x)\}_{n\geq 1}$
in (5) satisfy the condition in (4), and let (6), (7), and (9) hold. Assume that d and
 $\{Y_{n,i}\}$
are independent.
-
(i) Let d be a bounded discrete RV such that
$1 < d < d_n = \min(C, l_n)$
,
$C>1$
.-
(a) If (C1) or (C2) hold for any
$d\in\{2,3,\ldots,\lfloor d_n-1\rfloor\}$
, and
$N_n$
and
$\{Y_{n,i}\}$
are independent, then
$Y_{n}(z,N_n)$
and
$Y^*_{n}(z,N_n)$
have the tail index
$k_1$
. -
(b) If (C3) holds with d in (14) replaced by
$\lfloor d_n-1\rfloor$
, then
$Y_n^*(z,N_n)$
has the extremal index
$\theta_i$
,
$i\in\{1,2,\ldots,\lfloor d_n-1\rfloor\}$
. If, in addition, (C2) holds for any
$d\in\{2,3,\ldots,\lfloor d_n-1\rfloor\}$
, then
$Y_n(z,N_n)$
has the same extremal index.
-
-
(ii) Suppose that
$d>1$
is a bounded discrete RV equal to a positive integer almost surely (a.s.). Then all the statements of (i) are fulfilled under the same assumptions.
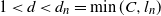

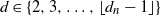


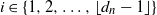
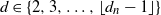


The hypothesis that the random number d is bounded is plausible in applications like distributed computing, random networks, or peer-to-peer overlay networks (see Section 3), where the random number of processors, node communities, or links at the overlay paths between source and destination nodes are bounded.
2.2. Examples
Let us consider some examples where some of the conditions (C1)–(C3) may be valid.
Example 1. Assumption (C3) is valid for the following d ‘column’ sequences, which are regularly varying distributed with the minimum tail index
 $k_1$
. The weights are taken such that
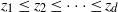 $z_1\le z_2\le \cdots \le z_d$
. Let elements of each ‘column’ sequence be sums of the corresponding elements of all previous ‘columns’, i.e.
 \begin{equation} Y_{n,i}=\sum_{j=1}^{i-1}Y_{n,j}, \quad i>1. \end{equation}
Assuming the first ‘column’ sequence has the tail index
 $k_1$
, each of the d ‘column’ sequences has the same tail index. Then (13) is valid with the constant
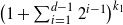 $\big(1+\sum_{i=1}^{d-1}2^{i-1}\big)^{k_1}$
instead of
 $\sum_{i=1}^dc_i$
since
 $Y_{n,1}$
satisfies (1). Note that (12) is not required to fulfill (13) in this case. As
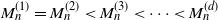 $M_n^{(1)}=M_n^{(2)}< M_n^{(3)}< \cdots <M_n^{(d)}$
, then
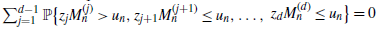 $\sum_{j=1}^{d-1}\mathbb{P}\big\{z_{j}M_n^{(j)}>u_n,z_{j+1}M_n^{(j+1)}\le u_n,\ldots, z_{d}M_n^{(d)}\le u_n\big\}=0$
, or equivalently (14) for
 $i=d$
follows. In the same way, (14) is valid for all d ‘column’ sequences such that
 \begin{equation} M_n^{(1)} \le M_n^{(2)} \le M_n^{(3)} \le \cdots \le M_n^{(d)}. \end{equation}
The sequence
 \begin{equation} \{Y_{n,1}, Y_{n,i}=c^{i-1}Y_{n,1}, \quad c>0,\ i\in\{2,\ldots,d\}\}, \end{equation}
provides a similar example. (13) is fulfilled with the right-hand side
 \begin{align*}\Bigg(\sum_{i=1}^dc^{i-1}\Bigg)^{k_1}=\bigg(\frac{1-c^d}{1-c}\bigg)^{k_1},\end{align*}
and (14) is valid in this case. (18) can be generalized by taking constants
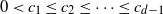 $0 < c_1\le c_2\le \cdots \le c_{d-1}$
instead of
 $\{c^{i-1}\}$
.
Conditions (16) and (18) seem to be quite restrictive. However, they appear in end-to-end peer-to-peer overlay networks where the transmission delay of a packet between nodes is regulated by the capacity of links at the overlay path, or in distributed computing where the capacity of servers determines the runtime of a job that is sent to the servers; see Section 3.
If the extremal indices
 $\{\theta_j\}$
,
 $j=1,\ldots,d$
of the d ‘column’ series are all equal to zero, then (C3) holds since
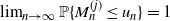 $\lim_{n\to\infty}\mathbb{P}\{M_n^{(j)}\le u_n\}=1$
,
 $j\in\{1,\ldots,d\}$
. A Lindley process with subexponential heavy-tailed noise that has a negative mean provides an example of such a series [Reference Asmussen2]. (1) with
 $k_1>1$
is an example of the tail of such noise. [Reference Asmussen3, Theorems 9.1, 9.4] state that the waiting time in a GI/G/1 queue that is modelled by a Lindley process has subexponential distribution. Metropolis chains with long-tail stationary distributions provide another example of sequences with extremal index zero [Reference Roberts, Rosenthal, Segers and Sousa30].
Example 2. Let us assume that each of the d ‘column’ sequences is modeled by an ARMAX process [Reference Beirlant, Goegebeur, Teugels and Segers5]. The ARMAX process of the ith ‘column’ sequence (
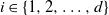 $i\in\{1,2,\ldots,d\}$
) is defined as
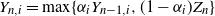 $Y_{n,i}=\max\{\alpha_i Y_{n-1,i},(1-\alpha_i)Z_n\}$
,
 $n\in \textrm{Z}$
, where
 $0\le \alpha_i < 1$
and the
 $\{Z_n\}$
are i.i.d. standard Fréchet-distributed RVs with the distribution function
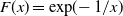 $F(x)=\exp\!(\!-1/x)$
,
 $x>0$
. The stationary solution of the recursion is
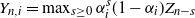 $Y_{n,i}=\max_{s\ge 0} \alpha_i^s(1-\alpha_i)Z_{n-s}$
, and
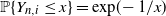 $\mathbb{P}\{Y_{n,i}\le x\}=\exp\!(\!-1/x)$
assuming
 $Y_{0,i}=Z_0$
[Reference Beirlant, Goegebeur, Teugels and Segers5]. The extremal index of the process is
 $\theta_i=1-\alpha_i$
[Reference Ancona-Navarrete and Tawn1]. In fact, (11) holds but (12) generally does not since
 \begin{align*} \mathbb{P}\{Y_{n,i}>x, Y_{n,j}>x\} & = \mathbb{P}\{Y_{n,i}>x\} + \mathbb{P}\{Y_{n,j}>x\} - 1 + \mathbb{P}\{Y_{n,i}\le x, Y_{n,j}\le x\}, \\ \mathbb{P}\{Y_{n,i}\le x, Y_{n,j}\le x\} & = \mathbb{P}\{\max_{s\ge 0} \max\{\alpha_i^s(1-\alpha_i),\alpha_j^s(1-\alpha_j)\}Z_{n-s}\le x\} \\ & = \exp\Bigg(-\frac{\sum_{s=0}^{\infty}\max\{\alpha_i^s(1-\alpha_i),\alpha_j^s(1-\alpha_j)\}}{x}\Bigg). \end{align*}
(C1) is not valid since
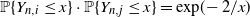 $\mathbb{P}\{Y_{n,i}\le x\}\cdot\mathbb{P}\{Y_{n,j}\le x\}=\exp\!(\!-2/x)$
. We impose conditions on
 $\{z_i\}$
,
 $\{\alpha_i\}$
, for the d ‘columns’ to prove (C3) by induction.
 $u_n=yn\ell_1^{\sharp}(n)$
is taken as in (8) with
 $k_1=1$
as required for our theorems. We have
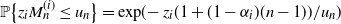 $\mathbb{P}\big\{z_{i}M_n^{(i)}\le u_n\big\} = \exp\!(\!-z_i(1+(1-\alpha_i)(n-1))/u_n)$
for any
 $i\in\{1,\ldots,d\}$
[Reference Beirlant, Goegebeur, Teugels and Segers5]. For the base case
 $d=2$
we prove (C3) assuming
 $z_1$
,
 $z_2$
,
 $\alpha_1$
, and
 $\alpha_2$
are such that
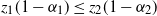 $z_1(1-\alpha_1)\le z_2(1-\alpha_2)$
and
 $z_1\alpha_1\le z_2\alpha_2$
. It follows that
 \begin{align*} \mathbb{P}\{z_{1}M_n^{(1)}>u_n, z_{2}M_n^{(2)}\le u_n\} & = \mathbb{P}\{z_{2}M_n^{(2)}\le u_n\}-\mathbb{P}\{z_{1}M_n^{(1)}\le u_n, z_{2}M_n^{(2)}\le u_n\} \\ & = \exp\left(-z_2(1+(1-\alpha_2)(n-1))/u_n\right) \\ & \quad - \exp\left(-(z_2\alpha_2+ nz_2(1-\alpha_2))/u_n\right) = 0, \end{align*}
since
 \begin{multline*} \mathbb{P}\{z_{1}M_n^{(1)}\le u_n, z_{2}M_n^{(2)}\le u_n\} \\ = \mathbb{P}\{\max\{z_1\alpha_1, z_2\alpha_2\}Z_0\le u_n, z_2(1-\alpha_2)Z_1\le u_n, \ldots, z_2(1-\alpha_2)Z_n\le u_n\} \end{multline*}
and
 $z_1\alpha_1\le z_2\alpha_2$
.
Let us prove (C3) for
 $d>2$
assuming
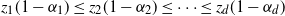 $z_1(1-\alpha_1)\le z_2(1-\alpha_2)\le\cdots\le z_d(1-\alpha_d)$
and
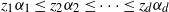 $z_1\alpha_1\le z_2\alpha_2\le\cdots\le z_d\alpha_d$
. Suppose (C3) holds for
 $d=D$
, i.e.
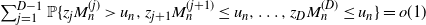 $\sum_{j=1}^{D-1} \mathbb{P}\{z_{j}M_n^{(j)}>u_n,z_{j+1}M_n^{(j+1)}\le u_n,\ldots,z_{D}M_n^{(D)}\le u_n\}=o(1)$
. We can prove (C3) for
 $d=D+1$
by induction since
 \begin{align*} & \sum_{j=1}^{D}\mathbb{P}\{z_{j}M_n^{(j)}>u_n,z_{j+1}M_n^{(j+1)}\le u_n,\ldots,z_{D+1}M_n^{(D+1)}\le u_n\} \\ & \qquad\le \sum_{j=1}^{D-1}\mathbb{P}\{z_{j}M_n^{(j)}>u_n,z_{j+1}M_n^{(j+1)}\le u_n,\ldots,z_{D}M_n^{(D)}\le u_n\} \\ & \qquad\quad + \mathbb{P}\{z_{D}M_n^{(D)}>u_n,z_{D+1}M_n^{(D+1)}\le u_n\}=o(1), \quad n\to\infty. \end{align*}
Taking the ARMAX process as
 $\{Y_{n,1}\}$
and assuming (16) or (18), each of the d ‘column’ sequences is stationary Fréchet distributed with tail index
 $k_1$
. Then (17) and (C3) are fulfilled and (13) is valid.
Example 3. Let us assume that each of the d ‘column’ sequences is modelled by the process given by [Reference Davis and Resnick9, (2.5)] where the RVs satisfy condition (C2). In our notation and without loss of meaning we represent the ith ‘column’ sequence (
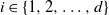 $i\in\{1,2,\ldots,d\}$
) as
 \begin{equation} Y_{1,i} = Z_{n,i}, \qquad Y_{j,i} = \Bigg(\prod_{s=1}^{j-2}Z_{n-s,i}\Bigg)Z_{n-j+1,i}^2, \quad j=2,\ldots,n. \end{equation}
We use the convention that
 $\prod_{s=1}^0=1$
. For each
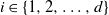 $i\in\{1,2,\ldots,d\}$
,
 $\{Z_{n,i}\colon n\ge 1\}$
are i.i.d. non-negative RVs with a common distribution function whose tail satisfies
 \begin{equation} 1-F_i(x) = x^{-\alpha}\ell_i(x), \quad \alpha>0,\, x>0, \end{equation}
where
 $\ell_i(x)$
is a slowly varying function. Condition (C1) is valid due to the independence of
 $\{Z_{n,i}\}$
by i. Following [Reference Davis and Resnick9], it is assumed that there are positive constants
 $\{c_i\}$
such that
 $c_i^{\alpha/2}\mathbb{E}Z_{1,i}^{\alpha/2}<1$
,
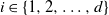 $i\in\{1,2,\ldots,d\}$
. By Breiman’s result, if
 $\xi$
is a non-negative RV satisfying (20) and if
 $\eta$
is another non-negative RV independent of
 $\xi$
satisfying
 $\mathbb{E}\eta^{\gamma}<\infty$
for some
 $\gamma>\alpha$
then
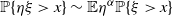 $\mathbb{P}\{\eta\xi>x\}\sim\mathbb{E}\eta^{\alpha}\mathbb{P}\{\xi>x\}$
as
 $x\to\infty$
[Reference Breiman7]. From the proof of [Reference Davis and Resnick9, Lemma 2.2], due to Breiman’s result and since the tail index of
 $\prod_{s=1}^{j-2}Z_{n-s,i}$
is equal to
 $\alpha$
by [Reference Jessen and Mikosch17, Lemma 4.1], for
 $j\ge 2$
,
 \begin{equation*} \mathbb{P}\{Y_{j,i}>x\} \sim \mathbb{E}\Bigg(\prod_{s=1}^{j-2}Z_{n-s,i}\Bigg)^{\alpha/2}\mathbb{P}\big\{Z_{n-j+1,i}^2>x\big\} = \big(\mathbb{E}Z_{n-1,i}^{\alpha/2}\big)^{j-2}x^{-\alpha/2}\ell_i(\sqrt x) \end{equation*}
as
 $x\to\infty$
for each
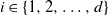 $i\in\{1,2,\ldots,d\}$
. Then the first d of our ‘column’ series have the tail index
 $k_1=\alpha/2$
. The ‘columns’ with numbers larger than d are assumed to have distribution tails with higher values of the tail index. The extremal index of the ‘columns’ does not exist by Definition 1 due to their non-stationarity by j.
If the first ‘column’
 $\{Y_{n,1}\colon n\ge 1\}$
is modeled by (19), and (16) or (18) is fulfilled as mutual dependence between the d ‘column’ series, then (13) is valid.
Let us model the ith ‘row’ sequence for
 $i\ge 1$
by the same process [Reference Davis and Resnick9, (2.5)]:
 \begin{equation} Y_{i,1} = Z_{i,n}, \qquad Y_{i,j} = \Bigg(\prod_{s=1}^{j-2}Z_{i,n-s}\Bigg)Z_{i,n-j+1}^2, \quad j=2,\ldots,d, \,n\ge 1. \end{equation}
Then the first ‘column’ has the tail index
 $\alpha$
. It is independent of the rest of the ‘columns’
 $\{Y_{n,j}\}_{n\ge 1}$
,
 $j\in\{2,\ldots,d\}$
, which have the tail index
 $\alpha/2$
and fulfill (11). The
 $\{Y_{i,j}\}$
with
 $j>d$
can be modelled the same way but with larger tail indices. The extremal index of the ‘columns’
 $\{Y_{i,j}\}$
does not exist due to their non-stationarity by i.
The proof of [Reference Davis and Resnick9, Lemma 2.2(2)] contains a query. We provide a correction to prove (12) and thus (C2). Writing
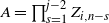 $A=\prod_{s=1}^{j-2}Z_{i,n-s}$
,
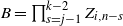 $B=\prod_{s=j-1}^{k-2}Z_{i,n-s}$
, we have, for
 $\epsilon>0$
, by Breiman’s result,
 \begin{align*} \mathbb{P}\{Y_{i,j}>x, Y_{i,k}>x\} & = \mathbb{P}\big\{AZ_{i,n-j+1}^2>x, ABZ_{i,n-k+1}^2>x\big\} \\ & \le \mathbb{P}\big\{A\le\epsilon,AZ_{i,n-j+1}^2>x\big\} + \mathbb{P}\big\{A>\epsilon, AZ_{i,n-j+1}^2>x, ABZ_{i,n-k+1}^2>x\big\} \\ & \le \mathbb{P}\big\{Z_{i,n-j+1}^2>x/\epsilon\big\} + \mathbb{P}\big\{A{\mathbf{1}}\{A>\epsilon\}Z_{i,n-j+1}^2>x\big\} \\ & = x^{-\alpha/2}\ell(\sqrt x)\big(\epsilon^{\alpha/2}+\mathbb{E}(A{\mathbf{1}}\{A>\epsilon\})^{\alpha/2}\big)(1+o(1)) \end{align*}
as
 $x\to\infty$
. Let
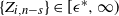 $\{Z_{i,n-s}\}\in[\epsilon^*,\infty)$
,
 $\epsilon^*>0$
, and
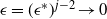 $\epsilon=(\epsilon^*)^{j-2}\to 0$
. Using (4) with constants
 $(\epsilon^*)^{\alpha}$
and
 $0 < \delta < \alpha/2$
for the slowly varying function in (20) we get
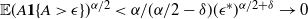 $\mathbb{E}(A{\mathbf{1}}\{A>\epsilon\})^{\alpha/2}<\alpha/(\alpha/2 -\delta)(\epsilon^*)^{\alpha/2+\delta} \to 0$
as
 $\epsilon^*\to 0$
. Hence, (12) is valid for the process (21) for
 $j\neq k$
,
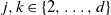 $j,k\in\{2,\ldots,d\}$
:
 \begin{equation*} \lim\sup_{x\to\infty}\frac{\mathbb{P}\{Y_{i,j}>x, Y_{i,k}>x\}}{x^{-\alpha/2}\ell(\sqrt x)} = \epsilon^{\alpha/2} + \mathbb{E}(A{\mathbf{1}}\{A>\epsilon\})^{\alpha/2} \to 0, \quad \epsilon\to 0. \end{equation*}
2.3. Extension of Theorems 2 and 4 for a heavy-tailed number of light-tailed terms
The assumption in (9) is crucial for the proof of Theorem 2. We replace this assumption with an opposite one and derive new statements for a unique column sequence and a random number of column sequences with a minimum tail index for positive weights.
First, consider a unique ‘column’ series with a minimum tail index.
Theorem 5. Let the conditions of Theorem 2 be fulfilled apart from (9), and the sequence
 $l_n$
satisfy (6) and (7). Let
 $N_n$
satisfy (5) with the tail index
 $\alpha$
.
-
(i) Assume (10) and
(22)for
\begin{equation} \alpha\chi_0 > 1+\frac{\alpha}{k_1}\delta^* \end{equation}
$\delta^*>0$
. Then the sequences
$Y_{n}^*(z,N_n)$
and
$Y_{n}(z,N_n)$
have the same tail index
$k_1$
, and if (23)then they also have the same extremal index
\begin{equation} \alpha\chi_0 > 1+\frac{1}{2}(1-\alpha\chi), \end{equation}
$\theta_1$
.
-
(ii) Assume
(24)Then
\begin{equation} \mathbb{P}\{N_n>l_n\} = \mathbb{P}\{z_1Y_{n,1}>u_n\}(1+o(1)). \end{equation}
$Y_{n}^*(z,N_n)$
and
$Y_{n}(z,N_n)$
have the same tail index
$k_1$
and the extremal index
$\theta_1$
.


Next, consider a random number of ‘column’ series with a minimum tail index.
3. Applications
3.1. Distributed computing
The doubly indexed array
 $\{Y_{n,i}\colon n,i\ge 1\}$
described in the introduction can be interpreted in terms of distributed computing or the desktop grid project with servers and work units (see [Reference Lukashenko, Morozov and Pagano22] for details of computational grid systems). In [Reference Feitelson10] a model of parallel jobs considers them as rectangles in a
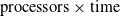 $\mathrm{processors} \times \mathrm{time}$
space: each job needs a certain number of processors for a certain interval of time. Then the ‘column’ in
 $\{Y_{n,i}\}$
corresponds to a server (processor) that is loaded with a new job once the previous one is fulfilled.
 $Y_{n,i}$
may be determined as the runtime of the job which is loaded on server i. The runtime may be reformulated as energy consumption. A weight
 $z_i$
may be interpreted as the capacity of a server (or computer). The number of busy servers is random since the job divided into tasks is sent to a random number of computers for calculation.
The distribution of process runtimes is heavy-tailed [Reference Feitelson10]. As an example, empirical observations about the workload on a network of Unix workstations were investigated in [Reference Harchol-Balter and Downey14] and it was found that the distribution of lifetimes of Unix process is Pareto. Stationary workloads are realistic for those that are generated by a uniform process, e.g. the behavior of a single application is often stationary [Reference Feitelson10]. One task can be sent to several servers for security reasons. Then the runtimes
 $Y_{n,1},\ldots, Y_{n,d}$
for some
 $d\ge 1$
can be dependent. The runtime of the same task calculated by more powerful servers is smaller. Then condition (14) will be fulfilled due to (17). The sum and maxima over the ‘row’ may imply the total and maximum runtime or the energy consumption of servers for one task, respectively.
3.2. Random networks
The sums and maxima over ‘rows’ of
 $\{Y_{n,i}\colon n,i\ge 1\}$
are applied to evolving random networks to find the tail and extremal indices of PageRanks (PRs) and max-linear models (MLMs) in [Reference Markovich24]. The PRs and MLMs are used as influence measures of web pages randomly chosen in a web graph. New nodes are appended to the network by some attachment tool provided that the distribution tails of the PRs are regularly varying, e.g. by preferential attachment.
In [Reference Jelenkovic and Olvera-Cravioto15, Reference Volkovich and Litvak33] the PR R of a node in the web graph is considered as the solution to the fixed-point problem
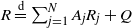 $R \overset{{\mathrm{d}}}{=}\sum_{j=1}^{N}A_{j}R_{j}+Q$
, where
 $\overset{{\mathrm{d}}}{=}$
denotes equality in distribution, and
 $\{A_j\}$
are independent non-negative RVs distributed as some RV A with
 $E(A)<1$
, N is the node in-degree, Q is a personalization value of the node,
 $E(Q)<1$
. The MLM is considered as the ‘minimal/endogeneous’ solution of the equation
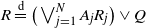 $R\overset{{\mathrm{d}}}{=}\big(\bigvee_{j=1}^{N}A_{j}R_j\big)\vee Q$
in [Reference Jelenkovic and Olvera-Cravioto16]. The
 $\{R_j\}$
,
 $j=1,2,\ldots$
, are assumed to be regularly varying i.i.d. copies of R apart from other independence conditions. Theorem 4 allows us to reconsider the right-hand sides of the latter equations in a more realistic way for real-world network conditions, where the PRs
 $\{R_j\}$
of followers of a node can be non-stationary distributed with regularly varying tails and dependent due to possible links between followers. [Reference Markovich24, Theorem 1] is based on Theorem 4.
The application is easier to explain for citation networks. Each node in a random network is considered as a root of some directed graph of its followers. In terms of citations, a row series
 $\{Y_{n,i}\colon i\ge 1\}$
corresponds to a set of papers citing a book. The communities are sets of highly connected nodes which have a few links with other communities. Node PRs within network communities are taken as the ‘column’ series in the array
 $\{Y_{n,i}\colon n,i\ge 1\}$
. A zero value in a row sequence implies that the book is not cited by a paper from the corresponding community.
Considering the PRs and MLMs of a set of root nodes as sequences of sums and maxima of PRs of their nearest neighbors with in-coming links to the roots, we can determine the tail and extremal indices of the PRs and MLMs of the roots. These indices are determined by those of PRs in the most heavy-tailed (‘dominating’) community within the graph. The ‘dominating’ community contains nodes whose PRs are stationary distributed with a regularly varying tail and a minimum tail index. The number of ‘dominating’ communities may be random. Some ‘dominating’ community may contain papers of especially distinguished authors and their PRs may satisfy (17), and thus condition (C3).
Some methods that can be used to test the dependence of node influence indices of two communities and the stationarity of node influence indices of the community can be found in [Reference Markovich and Vaičiulis27]. The disconnected communities are independent.
3.3. End-to-end delays
Information is transmitted by packets in telecommunication systems. In peer-to-peer (P2P) overlay networks packets are sent from the source node S to the destination node D by paths of a random length L [Reference Markovich23, Reference Markovich and Krieger25]. The packet transfer time over a path, the end-to-end (E2E) delay, is equal to the sum of L per-hop (p-h) delays. The p-h delay is the time required to transmit the packet between two neighboring nodes. We can also consider a maximum p-h delay over an overlay path. The p-h delays are assumed to be i.i.d. RVs with a light or heavy tail depending on the P2P overlay structure [Reference Dán and Fodor8, Reference Shih and Hero31]. The overlay path can be considered as a random-length row in
 $\{Y_{n,i}\colon n,i\ge 1\}$
. The ith column
 $\{Y_{n,i}\colon n\ge 1\}$
can be interpreted as the p-h delays at the ith link enumerated from S. The first and last columns corresponding to the first links from S and the last links before D contain non-zero p-h delays. A zero p-h delay
 $Y_{n,i}$
implies that there is no link between the ith and
 $(i-1)$
th nodes (
 $i>1$
) for the nth path.
The column elements (p-h delays) can be dependent since the paths may overlap [Reference Markovich and Krieger25]. It is remarkable that the first links from the source node have larger capacities and the last links have the smallest ones [Reference Dán and Fodor8]. This leads to a heavier tail of the p-h delays on the last links before the destination, i.e. the last column series may have the minimum tail index. The sum and maximum over a path mean the total E2E delay and maximal p-h delay of a packet between the source and destination. By Theorem 4 their tail and extremal indices are determined by the p-h delays at the last links before the destination for which condition (C3) is fulfilled. The condition in (10) is also plausible here, if the path length has a heavier tail than the p-h delays.
4. Conclusion
The tail and extremal indices of maxima and sums of weighted non-stationary random-length sequences of regularly varying RVs are obtained. To this end, the array
 $\{Y_{n,i}\colon n,i\ge 1\}$
is considered. We extend [Reference Markovich and Rodionov26, Theorems 3 and 4], where a unique column series in
 $\{Y_{n,i}\}$
is assumed to have a minimum tail index, by allowing a bounded random number of column series to have the minimum tail index (Theorems 3 and 4 here). These theorems work under the assumption that the number of terms in both the sums and maxima has a lighter tail than the terms, and that the weights are positive. In Theorems 5 and 6 the case of a heavy-tailed number of lighter-tail terms is considered. Theorem 5 deals with a unique ‘column’ series with a minimum tail index whereas Theorem 6 considers a random number of such series. We discuss adopting the results in different application areas in Section 3.
Appendix A. Proofs
A.1. Proof of Theorem 3
The proof extends that of [Reference Markovich and Rodionov26, Theorem 3]; we just indicate the modifications. The numbering of [Reference Markovich and Rodionov26, Theorem 3] is preserved throughout the proof. For brevity, in this section we use
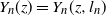 $Y_n(z)=Y_n(z,l_n)$
,
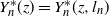 $Y_n^*(z)=Y_n^*(z,l_n)$
,
 $M_n(z)=M_n(z,l_n)$
, and
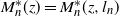 $M_n^*(z)=M_n^*(z,l_n)$
. We have
 \begin{equation} \mathbb{P}\{Y_n(z)>u_n\} \le \mathbb{P}\Bigg\{\sum_{i=1}^{d}z_iY_{n,i}>u_n(1-\varepsilon)\Bigg\} + \sum_{i=d+1}^{l_n}\mathbb{P}\{z_iY_{n,i}>u_n\varepsilon_i\},\end{equation}
where
 $\sum_{i=1}^{l_n}\varepsilon_i=1$
and
 $\{\varepsilon_i\}$
is a sequence of positive elements. We write
 $\varepsilon=\sum_{i=d+1}^{l_n}\varepsilon_i$
. We can take
 $\varepsilon_i$
,
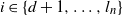 $i\in\{d+1,\ldots,l_n\}$
, in such a way that
 $\varepsilon_i\to 0$
and
 $\varepsilon\to 0$
as
 $n\to\infty$
. [Reference Markovich and Rodionov26, Lemma 1] states that if the conditions of Theorem 1 are fulfilled, then the sequence
 $\{\varepsilon_i\}_{i=2}^{l_n}$
can be chosen such that
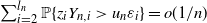 $\sum_{i=2}^{l_n}\mathbb{P}\{z_iY_{n,i}>u_n\varepsilon_i\}=o(1/n)$
. Choosing
 $\big\{\varepsilon_i=1/l_n^{\eta+1}\big\}$
,
 $\eta>0$
, we can derive that
 \begin{equation} \sum_{i=d+1}^{l_n}\mathbb{P}\{z_iY_{n,i}>u_n\varepsilon_i\}=o(1/n), \quad n\to\infty,\end{equation}
in the same way as in [Reference Markovich and Rodionov26, Lemma 1], substituting 2 in the sum there with
 $d+1$
. To prove the latter equation, we need to assume (4) for
 $d+1\leq i\leq l_n$
. For the selected
 $u_n$
we have
 \begin{equation} \mathbb{P}\{z_1 Y_{n,1} > u_n\} = (z_1/y)^{k_1} n^{-1} (1+o(1)), \quad n\to\infty.\end{equation}
We obtain
 \begin{align} \mathbb{P}\Bigg\{\sum_{i=1}^{d}z_iY_{n,i}>u_n(1-\varepsilon)\Bigg\} & \le \sum_{i=1}^{d}\mathbb{P}\{z_iY_{n,i}>u_n(1-\varepsilon)\varepsilon_i^*\} \nonumber \\ & = \frac{n^{-1}}{(y(1-\varepsilon))^{k_1}}\sum_{i=1}^d\bigg(\frac{z_i}{\varepsilon_i^*}\bigg)^{k_1}(1+o(1)) \nonumber \\ & = \bigg(\frac{z^*}{y(1-\varepsilon)}\bigg)^{k_1}n^{-1}(1+o(1)), \end{align}
where
 $\sum_{i=1}^d \varepsilon_i^*=1$
and
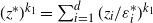 $(z^*)^{k_1}= \sum_{i=1}^d(z_i/\varepsilon_i^*)^{k_1}$
. By (25)–(28),
 \begin{align*} (z_1/y)^{k_1}n^{-1}(1+o(1)) & = \mathbb{P}\{z_1Y_{n,1}>u_n\} \nonumber \\ & \le \mathbb{P}\{Y_n^*(z)>u_n\} \nonumber \\ & \le \mathbb{P}\{Y_n(z)>u_n\} \le (z^*/y(1-\varepsilon))^{k_1}n^{-1}(1+o(1)) + o(1/n).\end{align*}
If condition (C2) holds, and replacing x in (13) by
 $u_n$
, we get, for any
 $m\ge 1$
,
 \begin{equation*} \mathbb{P}\Bigg\{\sum_{i=1}^dz_iY_{m,i}>u_n\Bigg\} = n^{-1}\sum_{i=1}^d\bigg(\frac{z_i}{y}\bigg)^{k_1}c_i(1+o(1))\end{equation*}
 \begin{equation*} \frac{\mathbb{P}\{z_iY_{n,i}>u_n\}}{\mathbb{P}\{z_1Y_{n,1}>u_n\}} = \bigg(\frac{z_i}{z_1}\bigg)^{k_1}c_i(1+o(1)), \quad n\to\infty,\,i=1,2,\ldots,d.\end{equation*}
By (25) and (26), this implies that
 \begin{equation} \lim_{n\to\infty}n\mathbb{P}\{Y_n(z)>u_n\} = \lim_{n\to\infty}n\mathbb{P}\{Y_n^*(z)>u_n\}=\sum_{i=1}^d\bigg(\frac{z_i}{y}\bigg)^{k_1}c_i.\end{equation}
This is valid for
 $Y_m^*(z)$
by (11) and (12), because
 \begin{align*} \mathbb{P}\{\max\!(z_1Y_{m,1},z_2Y_{m,2})>u_n\} &= \mathbb{P}\{z_1Y_{m,1}>u_n\}+\mathbb{P}\{z_2Y_{m,2}>u_n\}\\&\quad-\mathbb{P}\{z_1Y_{m,1}>u_n,z_2Y_{m,2}>u_n\} \end{align*}
(the case for general d follows by induction), and since
 \begin{equation*} \mathbb{P}\{Y_n^*(z,d)>u_n\}\le \mathbb{P}\{Y_n^*(z)>u_n\}\le \mathbb{P}\{Y_n(z,d)>u_n\}.\end{equation*}
A.1.1. Tail index.
Let us find the tail index of
 $Y_m(z)$
and
 $Y_m^*(z)$
for all
 $m\ge 1$
. Notice that the relation (25) remains true when replacing
 $u_n$
by
 $x>0$
. Similarly to (28),
 \begin{align*} \mathbb{P}\Bigg\{\sum_{i=1}^{d}z_iY_{m,i}>x(1-\varepsilon)\Bigg\} & \le \frac{1}{(x(1-\varepsilon))^{k_1}}\sum_{i=1}^d\bigg(\frac{z_i}{\varepsilon_i^*}\bigg)^{k_1}\ell_i(x)(1+o(1)) \\ & = \frac{\ell^*(x)}{x^{k_1}}(1+o(1)), \quad x\to\infty, \end{align*}
where
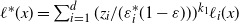 $\ell^*(x)=\sum_{i=1}^d(z_i/(\varepsilon_i^*(1-\varepsilon)))^{k_1}\ell_i(x)$
is a slowly varying function. [Reference Markovich and Rodionov26, (16)], i.e.
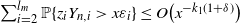 $\sum_{i=2}^{l_m}\mathbb{P}\{z_i Y_{n,i}>x\varepsilon_i\} \le O\big(x^{-k_1(1+\delta)}\big)$
as
 $x\to\infty$
, is fulfilled by replacing 2 by
 $d+1$
in the sum, namely,
 \begin{equation} \sum_{i=d+1}^{l_m}\mathbb{P}\{z_i Y_{n,i}>x\varepsilon_i\} \le O\big(x^{-k_1(1+\delta)}\big), \quad x\to\infty,\end{equation}
where
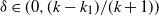 $\delta\in(0,(k-k_1)/(k+1))$
. Then it follows that
 \begin{align} (z_1/x)^{k_1}\ell_1(x)(1+o(1)) & = \mathbb{P}\{Y_{m,1}(z)>x/z_1\} \nonumber \\ & \le \mathbb{P}\{Y^*_m(z)>x\} \nonumber \\ & \le \mathbb{P}\{Y_m(z)>x\} \nonumber \\ & \le \mathbb{P}\Bigg\{\sum_{i=1}^{d}z_iY_{m,i}>x(1-\varepsilon)\Bigg\} + \sum_{i=d+1}^{l_m}\mathbb{P}\{z_iY_{n,i}>x\varepsilon_i\} \nonumber \\ & \le \ell^*(x)x^{-k_1}(1+o(1)).\end{align}
By (31) it does not follow that
 $Y_m(z)$
and
 $Y_m^*(z)$
are regularly varying.
A.1.2. Condition (C1).
The tail index of
 $Y_n(z)$
and
 $Y_n^*(z)$
is equal to
 $k_1$
if condition (C1) holds. In fact,
 \begin{equation} \mathbb{P}\{Y_n^*(z)>x\} = \sum_{i=1}^{d}\bigg(\frac{z_i}{x}\bigg)^{k_1}\ell_i(x)(1+o(1)), \quad x\to\infty\end{equation}
by (36), replacing
 $u_n$
by
 $x>0$
, and
 \begin{equation} \mathbb{P}\{Y_n(z)>x\} = \sum_{i=1}^{d}\mathbb{P}\{z_iY_i> x\}(1+o(1)) = \sum_{i=1}^{d}\bigg(\frac{z_i}{x}\bigg)^{k_1}\ell_i(x)(1+o(1))\end{equation}
as
 $x\to\infty$
by [17, Lemma 3.1] due to independence of the first d ‘column’ sequences.
A.1.3. Condition (C2).
In Condition (C2) and due to (13), (30), and (31) we get
 \begin{equation} \mathbb{P}\{Y_m(z)>x\} = x^{-k_1}\ell_1(x)\sum_{i=1}^dz_i^{k_1}c_i(1+o(1))\end{equation}
since
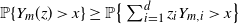 $\mathbb{P}\{Y_m(z)>x\} \ge \mathbb{P}\big\{\sum_{i=1}^{d}z_iY_{m,i}>x\big\}$
. The same is valid for
 $Y_m^*(z)$
by (11) and (12) in the same way as before. Hence,
 $Y_m(z)$
and
 $Y_m^*(z)$
have the same tail index
 $k_1$
for arbitrary (fixed)
 $m\ge 1$
.
A.1.4. The extremal index for d independent ‘column’ sequences.
Let us assume that condition (C1) holds. Due to independence, we have
 \begin{equation*} \mathbb{P}\big\{M_n^*(z)\le u_n\big\} = \prod_{j=1}^{d}\mathbb{P}\big\{z_j M_n^{(j)}\le u_n\big\} \mathbb{P}\big\{z_{d+1}M_n^{(d+1)}\le u_n,\ldots,z_{l_n}M_n^{(l_n)}\le u_n\big\}.\end{equation*}
Since the extremal index of the sequence
 $\{Y_{n,j}\}_{n \geq 1}$
,
 $1\le j\le d$
, is assumed to be equal to
 $\theta_j$
, by (2) and (27) we get
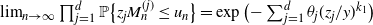 $\lim_{n\to\infty}\prod_{j=1}^{d}\mathbb{P}\big\{z_jM_n^{(j)}\le u_n\big\} =\exp\big({-}\sum_{j=1}^{d}\theta_j(z_j/y)^{k_1}\big)$
. By a Bonferroni-type inequality, we get
 \begin{align*} \mathbb{P}\big\{z_{d+1} M_n^{(d+1)}\le u_n\big\} - \sum_{i=d+2}^{l_n}\mathbb{P}\big\{z_iM_n^{(i)}> u_n\big\} & \leq \mathbb{P}\big\{z_{d+1}M_n^{(d+1)}\le u_n,\ldots,z_{l_n}M_n^{(l_n)}\le u_n\big\} \\ & \leq \mathbb{P}\big\{z_{d+1} M_n^{(d+1)}\le u_n\big\}.\end{align*}
In the same way as [Reference Markovich and Rodionov26, (21)], i.e.
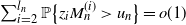 $\sum_{i=2}^{l_n}\mathbb{P}\big\{z_iM_n^{(i)}> u_n\big\}=o(1)$
, we get
 \begin{align*}\sum_{i=d+2}^{l_n}\mathbb{P}\big\{z_iM_n^{(i)}> u_n\big\}=o(1).\end{align*}
Then, by (2),
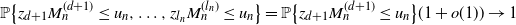 $\mathbb{P}\big\{z_{d+1}M_n^{(d+1)}\le u_n,\ldots,z_{l_n}M_n^{(l_n)}\le u_n\big\}= \mathbb{P}\big\{z_{d+1} M_n^{(d+1)} \leq u_n\big\} (1+o(1)) \to 1$
, assuming
 $k=k_{d+1}$
, since
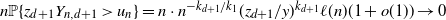 $n\mathbb{P}\{z_{d+1}Y_{n,d+1}>u_n\}= n\cdot n^{-k_{d+1}/k_1}(z_{d+1}/y)^{k_{d+1}}\ell(n)(1+o(1))\to 0$
as
 $n\to\infty$
due to
 $k_{d+1} > k_1$
. We obtain
 \begin{equation} \lim_{n\to\infty}n\mathbb{P} \{Y_n^*(z) > u_n\} = \sum_{j=1}^d\bigg(\frac{z_{j}}{y}\bigg)^{k_1}\end{equation}
since
 \begin{align*} \mathbb{P}\{Y_n^*(z)> u_n\} & = \mathbb{P}\{\max\!(z_1Y_{n,1},\ldots,z_{d}Y_{n,d},z_{d+1}Y_{n,d+1},\ldots,z_{l_n}Y_{n,l_n})> u_n\} \\ & = 1-\prod_{i=1}^d\big(1-\mathbb{P}\{z_iY_{n,i}> u_n\}\big) \big(1-\mathbb{P}\{\max\!(z_{d+1}Y_{n,d+1},\ldots,z_{l_n}Y_{n,l_n})> u_n\}\big).\end{align*}
Since
 \begin{align*} \prod_{i=1}^d(1-\mathbb{P}\{z_iY_{n,i}> u_n\}) & = 1-\sum_{i=1}^d\mathbb{P}\{z_iY_{n,i}> u_n\} + \sum_{i < j}\mathbb{P}\{z_iY_{n,i}> u_n\}\mathbb{P}\{z_jY_{n,j}> u_n\} \\ & \quad - \cdots - (-1)^{d-1}\prod_{i=1}^d\mathbb{P}\{z_iY_{n,i}> u_n\} \\ & = \Bigg(1-\sum_{i=1}^d\mathbb{P}\{z_iY_{n,i}> u_n\}\Bigg)(1+o(1)), \quad n\to\infty\end{align*}
and by (27) it follows that
 \begin{align} \mathbb{P}\{Y_n^*(z)> u_n\} & = \Bigg(\sum_{i=1}^d\mathbb{P}\{z_iY_{n,i}>u_n\} + \mathbb{P}\{\max\!(z_{d+1}Y_{n,d+1},\ldots,z_{l_n}Y_{n,l_n})>u_n\}\Bigg)\cdot(1+o(1)) \nonumber \\ & = \sum_{i=1}^d\bigg(\frac{z_{i}}{y}\bigg)^{k_1}\cdot n^{-1}(1+o(1))+o(1/n) \end{align}
due to [Reference Markovich and Rodionov26, (9), (12), (13), and Lemma 1] and
 $k=k_{d+1}$
. By [17, Lemma 3.1], it follows that
 \begin{equation} \lim_{n\to\infty}n\mathbb{P}\{Y_n(z)> u_n\}=\sum_{i=1}^d\bigg(\frac{z_{i}}{y}\bigg)^{k_1}.\end{equation}
By (35) and
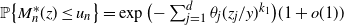 $\mathbb{P}\big\{M_n^*(z)\le u_n\big\} =\exp\big({-}\sum_{j=1}^{d}\theta_j(z_j/y)^{k_1}\big) (1+o(1))$
, the extremal index of
 $Y_n^*(z)$
is equal to (15). We can show that
 $Y_n(z)$
has the same extremal index. We obtain
 \begin{align} 0 & \le \mathbb{P}\big\{M_n^*(z)\le u_n\big\}-\mathbb{P}\{M_n(z)\le u_n\} \nonumber \\ & = \sum_{j=1}^{n-1}\mathbb{P}\big\{M_n^*(z)\le u_n, Y_j(z)>u_n, Y_{j+1}(z)\le u_n,\ldots,Y_n(z)\le u_n\big\} \nonumber \\ & \quad + \mathbb{P}\big\{M_n^*(z)\le u_n, Y_n(z)> u_n\big\} \nonumber \\ & \le \sum_{j=1}^{n}\mathbb{P}\big\{Y_j^*(z)\le u_n, Y_j(z)>u_n\big\}. \end{align}
It follows that
 \begin{equation} \mathbb{P}\big\{Y_j^*(z)\le u_n, Y_j(z)>u_n\big\} = \mathbb{P}\{Y_j(z)>u_n\} - \mathbb{P}\big\{Y_j^*(z)> u_n\big\} = o(n^{-1})\end{equation}

A.1.5. The extremal index for d dependent ‘column’ sequences
We find the extremal index of the sequences
 $Y_n^*(z)$
and
 $Y_n(z)$
if there is a dependence of
 $\{Y_{n,i}\}_{n\ge 1}$
in i. Applying a Bonferroni-type inequality, we get
 \begin{align} \mathbb{P}\big\{M_n^*(z,d) \le u_n\big\} - \sum_{i=d+1}^{l_n}\mathbb{P}\big\{z_i M_n^{(i)}> u_n\big\} & \leq \mathbb{P}\big\{z_1M_n^{(1)}\le u_n,\ldots,z_{l_n}M_n^{(l_n)}\le u_n\big\} \nonumber \\ & = \mathbb{P}\big\{M_n^*(z)\le u_n\big\} \nonumber \\ & \leq \mathbb{P}\big\{M_n^*(z,d) \le u_n\big\} \leq \mathbb{P}\big\{z_dM_n^{(d)}\le u_n\big\}.\end{align}
The tail indices
 $\{k_i\}$
,
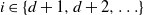 $i\in\{d+1,d+2,\ldots\}$
, of the corresponding ‘column’ series are larger than
 $k_1$
. Then, assuming (4), we can prove that
 \begin{equation} \sum_{i=d+1}^{l_n}\mathbb{P}\big\{z_i M_n^{(i)}> u_n\big\} = o(1), \quad n\to\infty,\end{equation}
in a similar fashion to [Reference Markovich and Rodionov26, (21)]. Then
 \begin{align*} \mathbb{P}\big\{M_n^*(z,d) \le u_n\big\} & = 1 - \mathbb{P}\big\{M_n^*(z,d) > u_n\big\} \\ & = 1 - \mathbb{P}\big\{z_dM_n^{(d)}> u_n\big\} - \sum_{j=1}^{d-1} \mathbb{P}\Big\{z_{j}M_n^{(j)}>u_n, \max_{j+1\le i\le d}\big(z_{i}M_n^{(i)}\big)\le u_n\Big\}.\end{align*}
Note that
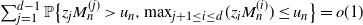 $\sum_{j=1}^{d-1}\mathbb{P}\big\{z_{j}M_n^{(j)}>u_n,\max_{j+1\le i\le d}(z_{i}M_n^{(i)})\le u_n\big\}=o(1)$
is equivalent to (14) for
 $i=d$
. If (14) holds, then
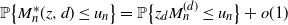 $\mathbb{P}\big\{M_n^*(z,d) \le u_n\big\} = \mathbb{P}\big\{z_{d}M_n^{(d)}\le u_n\big\}+o(1)$
,
 $n\to\infty$
. Then, by (40) and (41), the expression
 \begin{equation*} \mathbb{P}\big\{M_n^*(z) \leq u_n\big\} = \mathbb{P}\big\{z_d M_n^{(d)} \leq u_n\big\}(1+o(1))=\exp\!(\!-\theta_d (z_d/y)^{k_1})(1+o(1))\end{equation*}
that is required to obtain the extremal index
 $\theta_d$
for
 $Y_n^*(z)$
follows by (2) and (27). For some
 $i\in\{1,\ldots,d\}$
such that (14) holds,
 $Y_n^*(z)$
has the extremal index
 $\theta_i$
for reasons of symmetry. The same result holds for
 $Y_n(z)$
due to (29), (38), and (39) if condition (C2) is additionally fulfilled.
A.2. Proof of Theorem 4
We concentrate on case (i). If we then let
 $d=d_0$
a.s. then the same statements follow for case (ii). It is sufficient to replace s in the formulas of case (i) by
 $d_0$
with probability 1.
A.2.1. Tail index.
Similarly to the proof of [Reference Markovich and Rodionov26, Theorem 4] we have, for all
 $m\ge 1$
,
 \begin{align*} (z_1/x)^{k_1}\ell_1(x)(1+o(1)) & \le \mathbb{P}\{z_{1}Y_{n,1}>x\} \\ & \le \mathbb{P}\big\{Y_{m}^*(z,N_m)>x\big\} \\ & \leq \mathbb{P}\{Y_{m}(z,N_m)>x\} \leq \mathbb{P}\{Y_{m}(z,l(x))>x\} + \mathbb{P}\{N_m>l(x)\},\end{align*}
where l(x) is selected in such a way as to neglect the term
 $\mathbb{P}\{N_m>l(x)\}$
taking into account (5). Namely,
 $l_m$
is replaced by an arbitrary natural number
 $l=l(x)$
and for all sufficiently large x we set
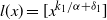 $l(x) = [x^{k_1/\alpha + \delta_1}]$
with
 $\delta_1>0$
. We get
 \begin{equation} \mathbb{P}\big\{Y_m^*(z,l(x))>x\big\} = \mathbb{P}\{z_{1}Y_{n,1}>x\} + \sum_{i=2}^{l}\mathbb{P}\Big\{z_{i}Y_{n,i}>x,\max_{1\le j\le i-1}z_{j}Y_{n,j}\le x\Big\}. \end{equation}
If, in addition to condition (C1) or (C2),
 $N_m$
and
 $\{Y_{m,i}\}$
are assumed to be independent, then
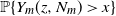 $\mathbb{P}\{Y_m(z,N_m)>x\}$
and
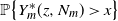 $\mathbb{P}\big\{Y^*_m(z,N_m)>x\big\}$
have the same tail index
 $k_1$
. By (30), (32), and (33) (or (34)) we get, for
 $m\ge 1$
,
 \begin{equation} \mathbb{P}\{Y_m(z,N_m)>x\} = \sum_{i=1}^{\infty}\mathbb{P}\{Y_m(z,i)>x\}\mathbb{P}\{N_m=i\} = x^{-k_1}\Omega(d_m,k_1)(1+o(1)), \end{equation}
where
 \begin{equation*} \Omega(d_m,k_1) = \sum_{i=1}^{\infty}\sum_{s=2}^{\lfloor d_m-1\rfloor}\Bigg(\sum_{j=1}^sz_j^{k_1}\ell_j(x){\mathbf{1}}\{i>s\} + \sum_{j=1}^iz_j^{k_1}\ell_j(x){\mathbf{1}}\{i\le s\}\Bigg)\mathbb{P}\{d=s\}\mathbb{P}\{N_m=i\}.\end{equation*}
The same is valid for
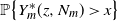 $\mathbb{P}\big\{Y^*_m(z,N_m)>x\big\}$
for the same reasons.
A.2.2. Extremal index.
Let us find the extremal index of
 $Y_n^*(z,N_n)$
and
 $Y_n(z,N_n)$
. We recall [Reference Markovich and Rodionov26, (31)],
 \begin{align} \mathbb{P}\big\{z_1M_n^{(1)}>u_n\big\} & \le \mathbb{P}\big\{M_{n}^*(z,N_n)>u_n\big\} \nonumber \\ & \le \mathbb{P}\big\{M_{n}^*(z,\tilde{l}_n)>u_n\big\} + \mathbb{P}\{N>\tilde{l}_n\} \nonumber \\ & \le \mathbb{P}\big\{M_{n}^*(z,\tilde{l}_n)>u_n\big\} + \sum_{i=1}^n \mathbb{P}\{N_i>\tilde{l}_n\}, \end{align}
where
 $\tilde{l}_n>l_n$
is selected such that the term
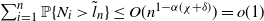 $\sum_{i=1}^n \mathbb{P}\{N_i>\tilde{l}_n\}\le O(n^{1-\alpha(\chi+\delta)})=o(1)$
is neglected as
 $n\to\infty$
, i.e.
 \begin{equation} \tilde{l}_n=n^{\chi+2\delta}, \qquad \delta=(\chi_0-\chi)/3.\end{equation}
Similarly to (42), we get
 \begin{equation*} \mathbb{P}\big\{M_n^*(z,\tilde{l}_n)> u_n\big\} = \mathbb{P}\{z_{1}M_n^{(1)}>u_n\} + \sum_{i=2}^{\tilde{l}_n}\mathbb{P}\Big\{z_{i}M_n^{(i)}>u_n,\max_{1\le j\le i-1}z_{j}M_n^{(j)}\le u_n\Big\}.\end{equation*}
Denoting
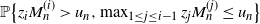 $\mathbb{P}\big\{z_{i}M_n^{(i)}>u_n,\max_{1\le j\le i-1}z_{j}M_n^{(j)}\le u_n\big\}$
by
 $\zeta_i$
and splitting the sum
 $\sum_{i=2}^{\tilde{l}_n}$
into
 \begin{equation*} \sum_{i=2}^{\tilde{l}_n}\zeta_i = \sum_{s=2}^{\lfloor d_n-1\rfloor}\Bigg(\sum_{i=2}^{s}\zeta_i+\sum_{i=s+1}^{\tilde{l}_n}\zeta_i\Bigg)\mathbb{P}\{d=s\}\end{equation*}
since d and
 $\{Y_{n,i}\}$
are assumed to be independent and
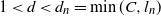 $1 < d < d_n=\min(C,l_n)$
, we obtain
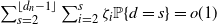 $\sum_{s=2}^{\lfloor d_n-1\rfloor}\sum_{i=2}^{s}\zeta_i\mathbb{P}\{d=s\}=o(1)$
by (14) and
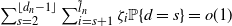 $\sum_{s=2}^{\lfloor d_n-1\rfloor}\sum_{i=s+1}^{\tilde{l}_n}\zeta_i\mathbb{P}\{d=s\}=o(1)$
by (41) as
 $n\to\infty$
. (41) is valid for
 $\tilde{l}_n$
since
 $\chi+2\delta<\chi_0$
. Hence,
 \begin{equation} \mathbb{P}\big\{M_n^*(z,\tilde{l}_n)> u_n\big\} = \mathbb{P}\big\{z_1M_n^{(1)}>u_n\big\}(1+o(1)).\end{equation}
Then, by (44),
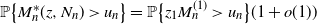 $\mathbb{P}\big\{M_{n}^*(z,N_n)>u_n\big\} =\mathbb{P}\big\{z_1M_n^{(1)}>u_n\big\}(1+o(1))$
follows and the extremal index of
 $Y_n^*(z,N_n)$
is equal to
 $\theta_1$
(or, for reasons of symmetry, to
 $\theta_i$
for some
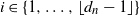 $i\in\{1,\ldots,\lfloor d_n-1\rfloor\}$
such that (14) holds).
 $Y_n(z,N_n)$
has the same extremal index since
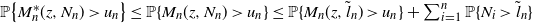 $\mathbb{P}\big\{M_n^*(z,N_n)>u_n\big\}\le \mathbb{P}\{M_n(z,N_n)>u_n\}\le \mathbb{P}\{M_{n}(z,\tilde{l}_n)>u_n\}+ \sum_{i=1}^n \mathbb{P}\{N_i>\tilde{l}_n\}$
by (44), and since, in addition, condition (C2) is assumed due to (29), (35), (37), (38), and (39).
A.3. Proof of Theorem 5
The proof is similar to that of Theorem 2. We only indicate the modifications.
A.3.1. Case (i).
Under the conditions of Theorem 2,
 \begin{align} \mathbb{P}\{Y_{n}(z,l_n)> u_n\} & = \mathbb{P}\big\{Y_{n}^*(z,l_n)> u_n\big\}(1+o(1)) \nonumber \\ & = \mathbb{P}\{z_1Y_{n,1}> u_n\}(1+o(1)) = (z_1/y)^{k_1} n^{-1}(1+o(1)) \end{align}
as
 $\ n\to\infty$
(see also [Reference Markovich and Rodionov26, (8), (10)]). Hence, (10) implies
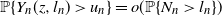 $\mathbb{P}\{Y_{n}(z,l_n)> u_n\} = o(\mathbb{P}\{N_n>l_n\})$
. Indeed,
 $\alpha\chi<1$
follows by (10).
Tail index
Let us find the tail index of
 $Y^*_{n}(z,N_n)$
and
 $Y_{n}(z,N_n)$
. The claim
 $\alpha\chi_0>1$
is required in Theorem 2 for the following result derived in [Reference Markovich and Rodionov26, (15)], namely,
 \begin{align*} \mathbb{P}\{Y_{m}(z,l_m)>x\} & = \mathbb{P}\big\{Y_{m}^*(z,l_m)>x\big\}(1+o(1)) \\ & = \mathbb{P}\{Y_{m,1}>x/z_1\}(1+o(1))=(z_1/x)^{k_1}\ell_1(x)(1+o(1))\end{align*}
for any fixed
 $m\ge 1$
and as
 $x\to\infty$
. To this end, we use
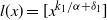 $l(x)=[x^{k_1/\alpha+\delta_1}]$
with
 $\delta_1>0$
to replace
 $l_m$
in [Reference Markovich and Rodionov26, (16)] (i.e.
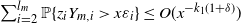 $\sum_{i=2}^{l_m}\mathbb{P}\{z_iY_{m,i}>x\varepsilon_i\}\leq O(x^{-k_1(1+\delta)})$
) for sufficiently large x such that
 $l(x)<x^{k_1\chi_0-\delta_2}$
with arbitrary
 $\delta_2\in(0, k_1\chi_0)$
, where
 $\delta_1+\delta_2=\delta^*$
,
 $\delta^*$
being determined by (22). Thus, by (22),
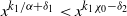 $x^{k_1/\alpha+\delta_1} < x^{k_1\chi_0-\delta_2}$
holds for
 $x>1$
. In the same way as in (31) for
 $d=1$
and by (1) we have
 \begin{align} \mathbb{P}\big\{Y_{m}^*(z,N_m)>x\big\} & \le \mathbb{P}\{Y_{m}(z,N_m)>x\} \nonumber \\ & \le \mathbb{P}\{Y_{m}(z,l(x))>x\} + \mathbb{P}\{N_m>l(x)\} \nonumber \\ & = (z_1/x)^{k_1}\ell_1(x)(1+o(1)) + x^{-k_1-\alpha \delta_1}\tilde{\ell}_m(x^{k_1/\alpha +\delta_1}) \nonumber \\ & = (z_1/x)^{k_1}\ell_1(x)(1+o(1)),\end{align}
 \begin{align} \mathbb{P}\big\{Y_{m}^*(z,N_m)>x\big\} & \ge \mathbb{P}\{Y_{m,1}>x/z_1\}(1+o(1)) =(z_1/x)^{k_1}\ell_1(x)(1+o(1)) \end{align}
as
 $x\to\infty$
. Then the first statement of Theorem 5(i) follows.
A.3.2. Extremal index.
Let us find the extremal index of
 $Y_{m}(z,N_m)$
and
 $Y_{m}^*(z,N_m)$
. We use
 $\widetilde{l}_n$
as in (45). By (6),
 $\widetilde{l}_n>l_n$
follows and (47) holds for
 $\widetilde{l}_n$
since
 $\chi+2\delta<\chi_0$
. By (5), (6), (10), (27), and (47) we have
 \begin{align*} (z_1/y)^{k_1} n^{-1}(1+o(1)) = \mathbb{P}\{z_1Y_{n,1}>u_n\} & \le \mathbb{P}\big\{Y^*_n(z,N_n)>u_n\big\} \\ & \le \mathbb{P}\{Y_n(z,N_n)>u_n\} \\ & \le \mathbb{P}\{Y_n(z,\widetilde{l}_n)>u_n\} + \mathbb{P}\{N_n>\widetilde{l}_n\} \\ & \le (z_1/y)^{k_1} n^{-1}(1+o(1))+n^{-\alpha(\chi+2\delta)} \tilde{\ell}_n(n^{\chi+2\delta}) \\ & = (z_1/y)^{k_1} n^{-1}(1+o(1)), \quad n\to\infty\end{align*}
since
 \begin{equation} \alpha(\chi+2\delta)>1\end{equation}
is valid by (23) and
 $\alpha\chi<1$
. Let us write
 $\tilde{l}_n^*=n^{\chi+2.5\delta}$
and recall [Reference Markovich and Rodionov26, (31)]:
 \begin{align} \mathbb{P}\big\{z_1M_n^{(1)}>u_n\big\} & \le \mathbb{P}\big\{M_{n}^*(z,N_n)>u_n\big\} \nonumber \\ & \le \mathbb{P}\big\{M_{n}^*(z,\tilde{l}_n^*)>u_n\big\} + \mathbb{P}\{N>\tilde{l}_n^*\} \nonumber \\ & \le \mathbb{P}\big\{M_{n}^*(z,\tilde{l}_n^*)>u_n\big\} + \sum_{i=1}^n \mathbb{P}\{N_i>\tilde{l}_n^*\}. \end{align}
We get
 \begin{equation} \sum_{i=1}^n \mathbb{P}\{N_i>\tilde{l}_n^*\} = \sum_{i=1}^nn^{-\alpha(\chi+2\delta)}n^{-0.5\alpha\delta}\tilde{\ell}_i(n^{\chi+2.5\delta}) \le O(n^{1-\alpha(\chi+2\delta)})=o(1)\end{equation}
since
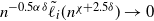 $n^{-0.5\alpha\delta}\tilde{\ell}_i(n^{\chi+2.5\delta})\to 0$
uniformly for all
 $i\in\{1,\ldots,n\}$
as
 $n\to\infty$
and (50) holds. By [Reference Markovich and Rodionov26, (22)], that is,
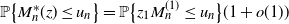 $\mathbb{P}\big\{M_{n}^*(z)\le u_n\big\}=\mathbb{P}\big\{z_1M_{n}^{(1)}\le u_n\big\}(1+o(1))$
, (51), and (52) it follows that
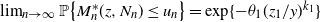 $\lim_{n\to\infty}\mathbb{P}\big\{M_{n}^*(z,N_n)\le u_n\big\} = \exp\{-\theta_1(z_1/y)^{k_1}\}$
and the extremal index of
 $Y^*_n(z,N_n)$
is equal to
 $\theta_1$
by (47). It remains to show the same for
 $Y_n(z,N_n)$
. To this end, we can find that
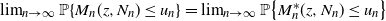 $\lim_{n\to\infty}\mathbb{P}\{M_{n}(z,N_n)\le u_n\}=\lim_{n\to\infty}\mathbb{P}\big\{M_{n}^*(z,N_n)\le u_n\big\}$
by (51), (52), and using
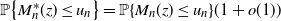 $\mathbb{P}\big\{M_n^*(z)\le u_n\big\} = \mathbb{P}\{M_n(z)\le u_n\} (1+o(1))$
([Reference Markovich and Rodionov26, (23)]).


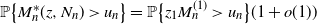
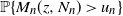
Acknowledgements
The author would like to thank Igor Rodionov for some useful comments and both anonymous referees for their constructive feedback.
Funding information
The author was supported by the Russian Science Foundation (grant no. 24-21-00183).
Competing interests
There were no competing interests to declare which arose during the preparation or publication process of this article.


