1. Executive Summary
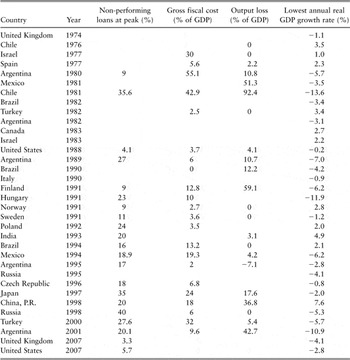
1.1 We provide an overview of previous banking and financial crises, drawing on a number of historical comparative studies. Banking and financial crises have occurred on many occasions in many countries since the early 1970s (Table 1). There were also many earlier banking and financial crises before the Second World War (Appendix A). The current global crisis is unusual mainly because of the number of financial institutions and countries involved.
Post-1945 Large-Scale Banking Crises.

Source: Reinhart & Rogoff (Reference Reinhart and Rogoff2008b), Laeven & Valencia (Reference Laeven and Valencia2008), calculation of the authors. Appendix A contains more detailed descriptions of these crises. The lowest annual GDP growth rate is the lowest year-on-year decline of GDP recorded in the years immediately following the crisis. Thus, for example, the rows for the UK and USA refer to the falls of GDP in 2008–2009.
1.2 Financial deregulation has played a facilitating role in these crises. Without deregulated financial markets, there are no financial crises. But this does not mean that financial deregulation is a cause of crises; rather, financial deregulation exposes weaknesses of governance and control for inappropriate government intervention that then undermine the disciplines on individual financial institutions. Problems are especially likely to arise immediately after deregulation, when institutions have not yet learned to understand properly the new environment. Financial innovation can have a similar impact, because institutions do not always understand novel financial instruments as well as they should.
1.3 Many financial crises have been associated with misguided attempts to maintain unsustainable fixed exchange rates. It is relatively easy, in a country committed to fixed exchange rates and deregulated capital markets, for banks to attract short-term foreign deposits to finance domestic lending. Overseas investors are often attracted by relatively high domestic rates of interest used to defend the exchange rate peg. As long as the confidence in the peg is maintained then there can be rapid expansion of domestic demand. But if confidence is then lost the result is a painful combination of banking losses and a sharp rise of domestic interest rates, to counteract rapidly depreciating exchange rates. The policy challenge is especially difficult for small countries. Larger countries, whose currencies are well established for trading in foreign exchange markets, find it relatively easier to negotiate the fall out of such ‘twin’ crises.
1.4 A common factor found in almost all banking and financial crises has been a pronounced credit cycle, with banks employing increased leverage and maturity mismatch to finance a lending boom, accompanied by unsustainable increases in the pricing of housing and other real estate. The sources of these credit booms are much debated. One school of thought, associated with the US economist, the late Hyman Minsky, argues that freely operating banking and credit markets are inherently unstable, and that stability can only be restored by using regulation to limit the extent of credit growth and prevent large-scale credit expansions. An opposing view is that these unsustainable credit expansions are a consequence of weaknesses of governance and control, and also of inappropriate government and regulatory intervention that protects bank lenders when there are substantial losses, so that by addressing these problems it is possible to have the advantages of freely operating capital markets without necessarily enduring financial crises.
1.5 Weaknesses of governance and control have certainly played a major role in previous crises. A large share of losses is often incurred by a relatively small number of institutions. 100% deposit insurance can further weaken the discipline on failing firms, allowing them to continue to attract the funding that allows them to stay in business and thus allows their losses to mount. Accounting rules and risk management systems also play a central role in the control of exposures. But these can create damaging ‘feedback loops’ that undermine rather than protect bank stability.
1.6 It is notable and rather surprising that there are no widely used definitions of systemic risk. Many commentators assume, without further thought, that a systemic risk means any disturbance which threatens the insolvency of a large number of banks or other financial institutions. But this is too crude an approach. Equating ‘systemic’ with ‘very large’ makes it difficult to distinguish systemic risks from other risks and to analyse the policy responses that can help mitigate systemic risk.
1.7 We therefore put forward the following definition:
A systemic risk materialises when an initial disturbance is transmitted through the networks of interconnections that link firms, households and financial institutions with each other, leading, as a result, to either the breakdown or degradation of these networks.
For brevity we do not include government bodies in this definition, although they could be added. An implication of this definition is that an event can be systemic without affecting every network, for example the recent credit crisis affected credit availability and money markets, but did not lead to the breakdown of payment and settlement systems.
1.8 By ‘networks’ of interconnections we mean the markets and other institutional arrangements that firms, households and financial institutions use for conducting economic transactions with each other. The simplest economic transactions, for example a small farmer or artisan bartering his or her wares directly to households, do not require such networks. But all, more sophisticated economic activity, including financial and monetary transactions, rely on such networks. In our analysis, systemic risk arises when these networks no longer operate or become much more difficult to use.
1.9 Any aggregate shock – if sufficiently large – will be systemic under this definition. Were there to be a sufficiently large enough common shock – for example one arising from a global environmental or epidemiological catastrophe – then the consequence would be widespread insolvency and a breakdown of markets and other institutional arrangements that support economic activity. But our definition is more helpful than simply equating ‘systemic crisis’ with large-scale insolvency. By distinguishing the different risks that can trigger the breakdown of the various networks in banking and financial services, we can then identify specific actions that can be taken to mitigate particular risks. This is more helpful than a ‘one–size-fits-all’ approach to analysing and responding to potential systemic risk.
1.10 We identify four groups of networks of interconnections in banking that can be subject to such systemic risk. These are:
(1) payments systems and other financial infrastructure such as systems of clearing and settlement;
(2) short-term funding markets;
(3) common exposures in collateral, securities and derivatives markets; and
(4) counterparty exposure to other financial market participants, especially in over-the-counter markets.
1.11 Two of these networks of interconnections, namely (2) and (3), have played a major role in most of the banking and financial crises listed in Table 1. These are the use of short-term funding and common exposure to real estate collateral; easy access to short-term funding and rising real estate prices have both encouraged unsustainable credit expansion and then, when the booms have ended, these mechanisms have gone into reverse creating severe liquidity and solvency problems for many banks.
1.12 Similar interactions, between the availability of external funding and the value of investments undermining net worth, could affect other investment vehicles relying on short-term funding, not just banks. We think of the impact of the financial crisis, and in particular of the losses of the Madoff investment fraud, on hedge funds. A loss of confidence could trigger large-scale redemptions and this might turn into a systemic risk, with withdrawal of funds triggering declines in asset values and further withdrawals. In practice, such erosions of confidence in hedge funds seem to have occurred in the current financial crisis only for those funds exploiting similar investment strategies to banks, using short-term funding to invest in illiquid structured credit securities. Responses such as temporary suspensions of redemptions appear to have been enough to prevent problems becoming more widespread in the hedge fund industry. But this is not to say that more serious systemic problems could not arise in the future.
1.13 On occasion there have been disturbances to banking networks without triggering a financial crisis. Problems in payment systems and with counterparty risk have arisen in the past without creating widespread financial disturbance. Withdrawal of short-term funding or falling collateral values has weakened bank balance sheets without always creating a crisis. This implies that a full understanding of systemic risk requires study not just of the banking and financial crises listed in Table 1 but also of these more benign episodes where the consequences have not been so serious.
1.14 A sufficiently large common shock – for example a sudden global environmental catastrophe or dramatic demographic change – could result in widespread insolvency amongst insurance and pension funds and so lead to a breakdown of insurance and pension arrangements. Under our definition this would be a systemic event, but originating outside of the insurance and pensions sectors.
1.15 We find that there is only very limited scope for systemic problems arising from these four networks of interconnection within the insurance and pension sectors. Of the four networks of interconnections which we identify in banking, two do not affect the insurance and pension sectors at all. The third – common exposures to collateral, securities and derivatives markets – affects life insurance and pension funds but to a much more limited degree than in banking. Only the fourth – exposure to a common counterparty – affects general insurance companies and this has only very rarely had a widespread impact. There is an obvious reason why networks of interconnections do not usually transmit systemic risk to the insurance and pension sectors. Because insurance companies and pension funds cannot directly create money and credit, they do not play the same role of supporting unsustainable balance sheet growth as does the banking system. However the willingness of pension and insurance companies to acquire bank bonds, structured securities, and other long-term and short-term bank paper contributes to credit growth; and withdrawal of pension funds and insurance companies from these markets can potentially be part of a systemic crisis.
1.16 There is also some potential for systemic risks originating from within the pension and insurance systems. Weaknesses of governance and control leading to excessive counterparty risk, or inappropriate governance and regulation forcing pension funds or insurance companies to sell assets into illiquid and underpriced markets, can sometimes create potentially systemic problems. We provide some examples (the Lloyd's reinsurance spirals and the United Kingdom life insurance difficulties of 1998) where such problems have emerged in the past. Similar systemic problems could potentially affect life insurance companies and pension funds in the future, but this risk can be averted by ensuring regulation and governance does not force sales of assets into illiquid markets. Pension funds and insurance companies are major buy-and-hold investors in fixed income markets and are thus natural providers of liquidity (long-term funding) to banks and regulation should not make it difficult for them to carry out this role.
1.17 Accounting and valuation practice can also contribute to the build up and eventual materialisation of systemic risk, both within the banking system and in the pension and insurance systems. Arguably, optimistic valuations of credit securitisations contributed to the rapid expansion of structured credit prior to the crisis. Valuation conventions, e.g. the discount rate applied to insurance and pension liabilities or the different treatments of hold to maturity portfolio and trading assets, can greatly affect balance sheet volatility.
1.18 Our four case studies further support these conclusions. The banking and financial crisis of the 1930s, and their contribution to the international Great Depression, was a complex event, in which banking instability played a major role. It was also exacerbated by weak institutional structures and a failure of governments worldwide to respond with expansionary monetary and fiscal policies to the mounting economic difficulties.
1.19 The Asian crisis of 1997 was one of the clearest examples of the interaction of short-term funding and unsustainable and uncontrolled credit growth, triggering a banking and financial crisis.
1.20 The equity market crash of 2000–2002 had a major impact on the pension system but this was not a systemic problem. Despite the major deterioration in net worth and the emergence of substantial defined-benefit pension deficits, the pension system continued to function. There was no widespread systemic crisis.
1.21 The current financial crisis has many of the features of earlier crises, with both excessive credit growth and short-term funding playing a major role. It has caused systemic problems in banking, with a sharp contraction of credit availability.
1.22 Our paper is completed with a number of recommendations as to how systemic risk in financial services can be mitigated. Four of these concern regulation and governance.
Recommendation 1. The operation of regulatory capital requirements, for both banks and insurance companies, needs to reflect the potential for damaging systemic interactions. Specifically, regulatory capital requirements should never be applied in such a way that they force asset sales or limit portfolio growth during periods of widespread financial distress.
Recommendation 2. In order to minimise the moral hazard created by support for the banking system, banks must either hold, or have in place ex-ante arrangements for raising additional (or ‘contingent’) capital, such that their capitalisation in a financial crisis is substantially greater than minimum regulatory capital requirements.
Note that current Basel II regulations for bank capital adequacy do not address concerns over forced asset sales or the need to raise additional capital in a systemic crisis (although there has been a degree of flexibility in some jurisdictions including the UK by imposing a higher ‘target’ level of capital that banks are expected to attain over time). There is currently active discussion by banking regulators and supervisors about how such additional precommitment to provision of capital would work. A prominent suggestion is that banks should issue ‘hybrid’ bonds that convert to equity in stated conditions, e.g. when the market value of banking sector equity falls below a trigger level. There might also be a pre-funded system for recapitalisations, funded by levies on banks.
Recommendation 3. Supervision should ensure that a firm's management takes into account long-term and systemic risks, i.e. the possibility of degradation or collapse of the networks of interconnections between the firm and other financial institutions and its customers. This might be facilitated through the supervisory appointment of non-executive directors for larger banks, a mechanism that was recently introduced in Ireland in the wake of their banking crisis.
While making some additional suggestions (see section 7), we say relatively little about the practicalities of how these recommendations are to be put into effect. Rather, we are pointing out where, in principle, action can be taken to improve regulation and governance in ways that minimise the kind of damaging systemic interactions identified in our report.
1.23 We make two further recommendations to improve redundancy and flexibility in the networks of interconnections between households, firms and financial institutions, and to allow regulators and financial market participants to assess system-wide risk in these markets.
Recommendation 4. The industry should move to establish sufficient ‘redundancy’ and flexibility in over-the-counter (‘OTC’) markets for securities, derivatives and insurance trading, so that counterparty risk from dealers or other participants is effectively controlled.
Recommendation 5. The financial authorities should require financial institutions to reveal all necessary information to allow regulators and other market participants to assess risks at the wider systemic level.
Thus, for example, recommendation 4 might be achieved by establishing central counterparty (CCP) arrangements, with the CCP taking on all counterparty risk exposure, and imposing strict procedures for collateralisation and capital adequacy on members. But it may be enough to ensure that there is full disclosure of counterparty exposure, through a central registry, and all institutions then ensure that they have sufficient capital and collateral protection to survive a severe shock. Having more, but smaller, participants might also reduce counterparty risk, but not when there is a very large shock that triggers widespread failure.
Again, we are careful to put forward these recommendations in a general form, without specifying precisely how they will be put into practice. There has been much recent discussion about the desirability of having in place a central counterparty for OTC markets, or even for moving much OTC trading, for example credit derivatives, onto an exchange. Such arrangements may well be a cost effective way of achieving the required redundancy and flexibility, but we believe this is a matter for detailed discussion between the financial authorities and market participants.
1.24 Finally, we discuss the role of traditional macroeconomic policy in limiting systemic risk. Avoiding future systemic crises requires also that traditional macroeconomic policy instruments – both monetary and fiscal policy – are used appropriately. It is necessary to maintain both fiscal and monetary discipline and not encourage unsustainable credit growth.
1.25 But we should not expect that these traditional instruments, or any new macro-prudential policy tools, can be easily used to restrain credit growth (leaning against the wind). When there is strong growth of spending, high and stable employment, and rising asset prices then credit risks will appear low. It is then difficult to agree on using policy instruments to restrain credit and expenditure, especially if there is a perceived danger that doing so will trigger repayment problems. This reinforces our earlier recommendations. We cannot rely on macro-policy alone to avoid systemic risk. There is a need also for ensuring that financial institutions are governed and regulated in ways that help reduce their exposure to aggregate system-wide shocks and that there is sufficient redundancy and flexibility in the networks of interconnections to prevent damaging systemic interactions.
2. Introduction
2.1 The current banking crisis has made us all too aware of how risks materialising in one part of the financial system can have a widespread impact, affecting other financial markets and institutions and the broader economy. But what leads to such events having an impact on the entire financial system? Can such disturbance arise in the insurance and pension sectors as well as in banking? And what can be done to reduce the likelihood of such ‘systemic’ events occurring and lower their impact when they do occur?
2.2 This is an independent report, prepared at the request of the Actuarial Profession, which seeks to answer these questions. This report is not primary research using new data. There is a very large literature on banking crises and also on foreign exchange and stock market crises. Our contributions are:
(1) to provide an overview of a number of banking and other financial crises that have occurred in the past (we provide a general overview and four case studies);
(2) to discuss what constitutes a systemic event and what distinguishes it from a large aggregate system wide shock;
(3) to assess the extent to which systemic problems can emerge in the insurance and pension sectors as well as in banking; and
(4) to discuss how policy-makers can respond to the risk of such systemic financial events.
2.3 The paper is organised as follows:
– Section 3, drawing on several comparative studies, is an historical review of system wide banking and financial crises. The discussion focuses on the period since 1970, but provides some additional comments on earlier crises in periods back to 1800 (an annotated tabulation of earlier crises is provided in Appendix A). This section also provides a brief review of the causes of such crises, focusing on what supported the credit booms and busts that triggered most of these crises. A more detailed literature review is provided in Appendix B.
– Section 4 then discusses the nature of a systemic event. It offers a definition of a ‘systemic event’, as an initial disturbance, transmitted through the networks of interconnections that link firms, households and financial institutions with each other, causing damage to, or breakdown of, these networks. The most important of these networks of interconnections, for the financial system, are money, securities, collateral, and debt markets. If a large number of financial institutions fail then that too is likely to be systemic, because this makes it difficult or impossible for firms, households and financial institutions to conduct transactions. We note that there is a recent but rapidly growing academic literature, using analytical tools previously applied in the physical and biological sciences for the study of complex adaptive systems, to examine the potential for instability in financial networks. But this is a new area of research and while very promising has not so far yielded many practical insights into the nature of systemic risk. We take a relatively simple approach, examining the specific networks that have been associated with systemic financial crises and discussing the factors which can either increase or reduce the transmission of shocks through these networks.
– Section 5 considers the extent to which similar linkages are present in the insurance and pension sectors. Systemic interactions are much less likely to occur in pensions and insurance than in banking. At the same time, a wider systemic crisis can cause considerable problems for the insurance and pension sectors.
– Section 6 of the report presents four more detailed case studies. These are on the international banking crisis of the 1930s, the Asian crisis of 1997, the stock market crash of 2000–2002 and its impact on the pension funds, and finally on the current financial crisis.
– Section 7 then analyses the policy responses that can help avert or deal with systemic financial disturbances, emphasising the need to ensure an appropriate ‘redundancy’ or spare capacity in the various networks of interconnections linking financial institutions and their customers, and also the importance of having appropriate governance, accounting and regulation. There is a difficult balance to be struck between long-term discipline (encouraging firms to protect themselves from systemic interactions) and short-term support (to limit these interactions when they actually arise). This section provides specific discussion of three major aspects of policy: regulation and governance; redundancy and flexibility in the networks of interconnections; and fiscal and monetary discipline.
– A final section summarises and concludes.
– The report is supported by two appendices. Appendix A provides some additional historical perspective with a tabulation and discussion of financial crises prior to 1970. Appendix B is a selective survey of recent literature on financial crises and systemic instability in financial networks.
3. The Frequent Recurrence of Banking and Financial Crises
3.1 An Overview of Past Banking and Financial Crises
3.1.1 It is useful, as a starting point, to take an historical perspective. For this purpose we refer readers to the recent National Bureau of Economic Research Working Paper of Carmen Reinhart and Kenneth Rogoff (Reinhart & Rogoff, Reference Reinhart and Rogoff2008b) and their subsequently published book (Reinhart & Rogoff, Reference Reinhart and Rogoff2009b). Their paper is an extensive historical examination of banking and financial crises investigating episodes as far back as the Danish financial panic at the time of the Napoleonic wars (they extend a data set of Michael Bordo (Bordo & Eichengreen, Reference Bordo and Eichengreen1999 and Bordo et al., Reference Bordo, Eichengreen, Klingebiel and Martinez-Peria2001) back from 1880 to 1800). Their paper documents many recurring features of different banking crises, across both emerging and developed markets in both recent and distant episodes. They find that these crises are typically preceded by high levels of foreign borrowing, by credit booms and by substantial increases in real estate and stock prices. They also find that these crises have a substantial economic impact. They are typically followed by a recession, sometimes very deep; public sector debt increases on average by 86% of GDP following a major banking crisis; and there are house price falls lasting for, on average, between four and six years. Their book is even more comprehensive, not only covering banking crises but also offering a similar review of episodes of default on sovereign and domestic debt and of hyperinflation. It is noteworthy that their extensive historical investigation finds no examples of systemic financial crises originating in the insurance or pension sectors.
3.1.2 Figure 1 on page 9 of the paper Reinhart & Rogoff (Reference Reinhart and Rogoff2008b) is particularly informative (a similar figure appears in their book Reinhart & Rogoff (Reference Reinhart and Rogoff2009b), see Figure 16.1, page 252). Using a sample of 66 countries, this presents the proportion of countries affected by a crisis in any given year (this proportion is an average weighted by nominal GDP). This figure highlights two points. First, crises have occurred regularly on a global scale. Their index – the proportion of countries affected – rises sharply on several occasions, climbing above 10% in 1907, 1914, 1922–24, and in 1930–1933 (where it reaches its historical peak of around 40%). It also stays at very high levels, in the range 20–25% between 1987 and 1999, and, although it then falls back, it rises sharply once again to well over 20% in 2007–2008.

3.1.3 A second point that emerges from their chart is that there was a striking period of quiescence, from 1940–1975, with scarcely any crises. The index is close to 0% in most years, with a small rise to 5% in the immediate post-war years 1946–1950, before falling back to 0%. This quiet period can be explained by the imposition of tight regulations of both financial activities and international capital flows. We will return to the role of domestic and international capital market liberalisation in systemic financial crises.
3.1.4 Reinhart & Rogoff (Reference Reinhart and Rogoff2008b) provides the longest historical perspective, but there are a number of other similar comparative studies (see Appendix B for a more detailed review of these studies). Laeven & Valencia (Reference Laeven and Valencia2008) present an IMF database covering the period 1970 onwards. This includes banking, financial and stock market crises and provides a considerable amount of supplementary detail such as the fiscal costs of bail-out and the peak-to-trough decline of GDP associated with the crisis. Bordo et al. (Reference Bordo, Eichengreen, Klingebiel and Martinez-Peria2001) is a further comparative study also employing a long historical perspective.
3.1.5 A challenge to all such studies is distinguishing ‘systemic’ crises. Perhaps surprisingly, there is no standard accepted definition of what makes a crisis systemic. Most judgements are based on it having a substantial macro-economic impact or affecting a large proportion of the financial services industry. The problem with this approach is that it treats all these crises alike. It does not distinguish the different possible sources of a systemic crisis, and hence tends to lead to a ‘one-size-fits-all’ recommendation for policy-makers. It leads almost inevitably to the conclusion that the way to avoid systemic problems is to limit credit and asset price growth; but such constraints on credit have costs. A more detailed investigation of the sources of systemic problems, such as we provide in this paper, makes clear that there are other policy measures available that may be a more cost effective way of responding to particular aspects of systemic risk. This approach also fails to address one of the main questions with which we are concerned: whether or not the insurance and pension sectors are as vulnerable as the banking sector to systemic risk.
3.1.6 A central argument made in this report is that systemic financial problems, far from all being the same, can take many different forms. While systemic risks often arise in banking, they can also, in some circumstances, originate in the pension and insurance sectors. Systemic risk is not just the consequence of rapid credit expansion, but also of weaknesses in either the regulation or governance of financial institutions and of unanticipated market interactions that magnify the impact of disturbances on markets and firms. As a result, a number of other policy measures can appropriately be used, alongside or instead of restrictions on credit availability, to reduce the threat of systemic financial crises.
3.1.7 In order to develop this argument, we propose, in section 4, a definition of a systemic crisis based on the damage or degradation of the networks of interconnections between firms, households and financial institutions. Such a definition is useful because it draws attention to specific policies that can be used to limit systemic interactions. These policies will not entirely eliminate systemic risk. There is still the possibility of a sufficiently large common shock that pushes many financial institutions into insolvency and hence causes systemic damage to these networks.
3.1.8 Still, it is the largest scale crises that are of particular interest. Using various studies of previous crises, we have prepared our own tabulation (See Table 1, Table 2 and Appendix A), of some 116 major banking crises in larger countries, 40 in the years 1974–2008 shown in Table 1 and Table 2, with 21 between 1921 and 1934 and 55 dating back to the 1800s shown in the tabulation provided in Appendix A.

3.1.9 Our criteria for inclusion in this tabulation was: (i) that the banking crisis should be large-scale, (ii) that the country concerned should have ranked in the top 50 countries of the world by 2007 GDP and, finally, (iii) that it should also rank in the top 40 percent of countries of the world, according to the average of 1996 and 1998 World Bank Index of Rule of Law (published in www.govindicators.org).
3.1.10 In Table 1, the determination of whether a crisis is ‘large-scale’ is taken from Laeven & Valencia (Reference Laeven and Valencia2008). (What we call ‘large-scale’ is what they call ‘systemic’, as discussed in the next section. This is because we avoid the assumption that any large-scale disturbance is necessarily systemic, and so distinguish systemic risk from large common shocks.) Their criterion is that the crisis should have either a substantial macro-economic impact, or a large effect on the country's financial sector, with a major increase of non-performing loans and doubts about the solvency of financial institutions. For crises before 1945 tabulated in Appendix A, we use a simpler criteria for deciding if a crisis is ‘large-scale’: we include it if three or more banks are threatened with insolvency.
3.1.11 We use the Rule of Law Index because we wish to exclude crises resulting from weaknesses of legal institutions that have allowed large-scale fraud or corruption to undermine the financial system. We also however, judgementally, added back crises observed in Argentina, Brazil, Mexico, China, Russia and Turkey, all of which are below the rank of the top 40 percent of countries in the world, according to Rule of Law measures, because of the particular interest in studying financial crises in Latin America and in Asia.
3.1.12 We highlight some further features of this tabulation. We note that some countries have been subject to serial crises, especially in the pre-1914 period (see Appendix A). Turning to recent years, Table 1 includes the most widely known crises of the post-war years, in Latin America and in the US in the 1980s, and in Finland, Sweden and Norway and Japan in the 1990s, but it also includes a number of less well known large-scale banking crises.
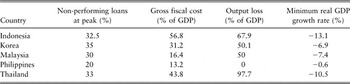
3.1.13 The criteria used to create this tabulation means we exclude the Asian banking crisis of 1997, which impacted on Thailand, Indonesia, Malaysia, South Korea, and the Philippines as well as, to a more limited extent, on Hong Kong and Singapore. We, however, discuss the 1997 Asian crisis as one of our case studies and present there a similar tabulation for these countries (Table 2).
3.1.14 What lies behind these large numbers of banking and associated exchange rate crises? Some can be attributed to structural or institutional features not to be found elsewhere. Thus, for example, the banking problems in Hungary and China arose after the abandonment of a centrally planned economic system, in India they arose after much bank lending had been politically directed rather than decided on commercial criteria and in Spain where the Franco dictatorship had only recently ended.
3.1.15 As previously mentioned, many crises, in both emerging and developed economies, share a number of common characteristics identified by Reinhart & Rogoff (Reference Reinhart and Rogoff2008b): large-scale private sector borrowing (often but not always from overseas); rapid increase in domestic demand associated with expansionary monetary and fiscal policy; and substantial increases in real estate and asset prices.
3.1.16 Finally, we note that there have been many credit booms and subsequent busts that have not had a sufficiently large impact to be included in our tabulations.
3.1.17 Amongst prominent examples are the real estate boom in the north-eastern United States culminating in the failure in early 1991 of the Bank of New England and the Connecticut Bank and Trust Company, and the lending boom in the UK in the late 1980s, which preceded the deep recession of 1991–1992 and the near failure of Barclays Bank. There are several other cases where a large-scale banking crisis has been threatened but not taken place. However, such ‘near misses’ are as important to understanding systemic risk as are the large-scale banking crises that have actually taken place. So, our subsequent analysis is not restricted to the cases listed in Table 1. We also note that the current global crisis has produced many individual episodes (Iceland, Ireland, Latvia, Ukraine) of countries with their own financial crisis triggered by the global turbulence. Many of these cases fit with the ‘twin’ or ‘triple’ crises discussed below because they involved doubts about exchange rates and fiscal credibility, as well as banking problems.
3.1.18 The remainder of this section discusses the various contributing factors that support unsustainable booms. We will shortly discuss the role of the ‘credit cycle’ in these financial crises but first we discuss the part played by financial deregulation and then (in the next subsection) of unsustainable fixed exchange rates.
3.2 Financial Deregulation: a Facilitator but not a Cause of Crisis
3.2.1 Financial deregulation occurs when rules and regulations applied to financial institutions are removed or no longer enforced. The 1970s and 1980s saw widespread financial deregulation, partly in response to technological change that allowed banks and other institutions to get around the existing rules (for example the telex machine played a critical role in the shift of US banking in the 1960s ‘offshore’ to London). Financial deregulation plays a facilitating role allowing the unsustainable build up of credit and asset prices that is later exposed in the ensuing financial crisis. As already remarked above, it has only been since the dismantling of capital controls and the parallel deregulation of domestic financial markets in the late 1960s and early 1970s that we have had any episodes of financial crisis in the post-World War II era. Earlier crises are associated with earlier periods of free flows of global capital: in the 19th century at the time of the establishment of the classical gold standard and with the abortive restoration of the gold standard in the 1920s and early 1930s.
3.2.2 But the link between financial deregulation and financial crisis is indirect. As we argue at greater length below, free flows of capital need not necessarily result in financial crisis. As long as risks and risk exposures are well understood, and there are effective disciplines on financial firms, then they need not be tempted to take on the excessive leverage and maturity mismatch and risky exposures that later result in a financial crisis. This suggests that an underlying cause of financial crisis is not deregulation per se, but rather weaknesses of governance and control or inappropriate government intervention which undermine the disciplines on individual firms.
3.2.3 Even if deregulation itself is not directly responsible for financial crises, the initial impact of financial deregulation is to change markets substantially, with the result that participants fail to keep up with these changes, and do not recognise the true extent of their risk exposure. The problems of the ‘secondary banks’ in the UK, that emerged in 1974 are an example. Deregulation at the beginning of the decade had allowed a number of new institutions to compete with the established clearing banks, especially in areas of business such as property finance. These new secondary banks relied on the established clearing banks for funding. But the clearing banks were still exposed to risk of loss on the underlying loans should these secondary banks fail. The clearing banks did not monitor this off-balance sheet risk as closely as their own on-balance sheet lending, and were eventually forced to provide a considerable amount of money to support their weaker competitors.
3.2.4 The process of deregulation also played a role in the US Savings and Loans crisis of the 1980s, in the Scandinavian banking crises of the early 1990s and in the Asian crisis of 1997. The US Savings and Loans crisis was triggered by a combination of deregulation (liberalisation of deposit markets allowing deposit interest rates to increase in line with market rates of interest, and so exposing the Savings and Loans who predominantly made loans at fixed 30 year rates of interest to massive interest rate risk, something of which they had little previous experience). Again, it was the failure to adjust to the initial impact of deregulation rather than deregulation per se that caused the problem. Most US Savings and Loans had not realised the great extent to which this deregulation had increased their exposure to interest rate risk. As a result, they did not hedge against this risk, and when tight monetary policy in the early 1980s raised short-term interest rates and their costs of funding, their net worth was undermined. These losses in turn eroded normal commercial disciplines. A combination of access to 100% guaranteed retail deposits and lax supervision then allowed a great deal of fraud and risky investment. It eventually cost the US taxpayer about 2.5% of national income to clear up the mess. Across Scandinavia, bank deregulation encouraged much greater competition in residential and commercial property lending but again the real problem was that many banks failed to understand the extent of their risk exposure.
3.2.5 Financial innovation has also played a role in financial crises, rather similar to the process of financial deregulation, leading to some firms misunderstanding the extent of their risk exposure, especially in newer instruments which they do not understand as well as they should. The problems of many US Savings and Loans in the 1980s was made worse first by competition for deposits from ‘money market’ mutual funds and also by losses on investments in the newly expanding market for relatively risky speculative grade corporate securities (so called ‘junk bonds’). New, poorly understood instruments have also played a prominent part in the current global financial crisis.
3.2.6 Another problem is that deregulation, especially the abolition of capital controls, also releases banks from the constraints of relying on retail funding. They can instead compete for wholesale funding, often provided from international markets. This, in turn, makes it easier for banks to engage in rapid credit expansion, in turn fuelling the asset price rises and current account deficits that are observed in the build up to most of these crises. Again, the problem is the absence of appropriate discipline and control. Banks need to be aware of the risks associated with relying on wholesale funding that increases leverage and maturity mismatch. If they are not aware of these risks, then there can be a sudden loss of net worth and reversal of funding that undermines their business (and as we discuss in our case study at section 6.5 this has played a major role in the current global financial crisis).
3.3 ‘Twin’ Crises
3.3.1 A feature of many of the crises listed in these tabulations, although by no means all, is that they are so-called ‘twin’ crises, where a crisis in the domestic banking system is accompanied by a collapse of confidence in the domestic currency and a major exchange rate depreciation. These two developments have often occurred in countries operating a currency peg and enjoying a temporary credit boom, financing the resulting current account deficit through short-term borrowing from overseas, either by government or through domestic banks attracting short-term international deposits.
3.3.2 Such a currency peg can directly encourage short-term capital inflows. As long as the fixed currency peg is credible, then domestic banks and firms are encouraged to borrow in foreign currency at relatively low interest rates, while international investors are attracted to the relatively high interest rates on offer for lending in domestic currency. Such interest rate differentials can be maintained for a considerable time by what economists have come to call the ‘peso problem’: even with a strong commitment to a fixed exchange rate, short-term there is some small probability of financial problems and a devaluation. So domestic interest rates must exceed global interest rates to compensate for this risk. In this situation, the impact of the unwinding of the credit boom is then magnified by the loss of confidence of international investors in the domestic exchange rate and the possibility of a large capital loss for domestic borrowers who have borrowed in foreign currency.
3.3.3 Not all banking crises are ‘twin’ crises. Two prominent examples of domestic (single not twin) banking crises are the US Savings and Loans crisis of the 1980s and the Japanese banking crisis of the 1990s. The current global banking crisis, while having a substantial exchange rate impact, is a twin crisis only to the extent that it was rooted in unsustainably low exchange rates of major export economies (see the case study in section 6). The majority of the other crises listed in Table 1, together with the Asian banking crises of 1997, were ‘twin crises’ of this kind. There have also been several previous examples of ‘twin crises’ before World War II (our 1930s case study discusses some examples). Finally, some of these crises can be labelled as ‘triple crises’ with a combination of banking, exchange rate and government debt problems.
3.3.4 The aftermath of a twin crisis poses an especially difficult challenge to policy-makers because it reveals a conflict in monetary policy: a conflict between the desire on the one hand to minimise bank losses and on the other to prevent external capital outflows. A reduction of interest rates is needed to support domestic asset prices and the cash-flow burden on bank borrowers. An increase of interest rates is needed to prevent capital outflows. This conflict also contributes to the crisis itself. The absence of a credible political commitment to enduring the pain of high interest rates and maintaining a fixed exchange rate peg creates self-fulfilling expectations of exchange rate depreciation, which then often leads to the dramatic collapse of the exchange rate peg broken by a flood of speculative capital outflows.
3.3.5 For small countries with relatively illiquid foreign exchange markets, the likely consequence is then a precipitous depreciation of the exchange rate. This in turn results either in rapidly increasing inflation or high levels of nominal interest rates to maintain domestic price stability. The only other policy option, the one chosen by many countries in the 1930s and which remained in place until the late 1960s, is the introduction of capital and exchange controls. Provided that a country does not run large current account deficits, that need to be financed from overseas, then having such controls make fixed exchange rates credible and avoids the possibility of a ‘twin crisis’. But such controls come with considerable costs. They limit competition in domestic securities and banking markets and, in any case, capital controls can only be introduced as an emergency measure. If international investors fear the introduction of capital controls, they will be even more reluctant to lend money.
3.3.6 Twin crises pose somewhat less difficult problems in countries whose currencies are regarded as sensible choices for short-term investment and so are actively traded in foreign exchange markets. It is then somewhat easier to establish a floor for the currency without imposing high levels of domestic interest rates. Examples are the Scandinavian countries of Norway, Finland and Sweden during their financial crises of the early 1990s, when their exchange rate pegs against the ECU basket of European currencies were broken. Far from worsening their financial problems, the resulting exchange rate depreciation made their export industries more competitive and made a substantial contribution to their economic recovery, while at the same time they were able to lower nominal interest rates sharply to reduce the burden on domestic borrowers.
3.3.7 Even if a country's exchange rate is actively traded in global foreign exchange markets, and so there is no severe constraint imposed by the need to attract international capital, there is still a conflict in the operation of monetary policy between short and long-term policy goals. In the short-term, policy-makers will want to provide cheap money in order to limit the impact of a banking crisis, but in the long-term this can help undermine the discipline on banks and also encourage a renewed growth of credit and asset prices and so make a future crisis more likely. This point is discussed further in the next section on the ‘credit cycle’ in section 3.4.
3.4 The Credit Cycle, Leverage and Maturity Mismatch
3.4.1 So far we have discussed the roles of financial deregulation as a facilitator of credit expansions and of fixed exchange rate policies that have contributed to unsustainable inflows of external capital. But all these factors, while important, are only a contributory, not a direct, cause of banking and financial crises. Their role is to exaggerate the underlying credit cycle, the rapid and unsustainable increase of bank lending and asset prices during the boom and the subsequent contraction of lending, fall of asset prices and high level of credit losses during the following bust.
3.4.2 Many have argued that credit cycles of this kind are endemic in a free market economy with a deregulated financial system. Perhaps the best known exponent of this view point is Hyman Minsky, the US economist who devoted his career to arguing that the US money and credit markets were fundamentally unstable (see the recently republished Minsky (Reference Minsky1986) and various articles cited therein). There are several strands to Minsky's arguments. One is a rejection of the notion of rationality in bank lending decisions, stressing instead the increasing speculative element of lending as a credit boom develops, with lending shifting from a sound financial basis first to a speculative basis (loan repayment relying on increases of asset values) and then to ponzi finance (loan repayments relying on the further extension of lending). His name is now indelibly associated with the phrase ‘Minsky moment’, the point at which financial market participants and banks realise that the loans they have been making are unsound.
3.4.3 In common with many mainstream economists, Minsky also argues that bank lending plays a major role in business cycle fluctuations, so that the ending of each credit boom is accompanied by a severe contraction in the supply of credit and in turn triggering economic recessions. Minsky also argues that Federal Reserve actions create moral hazard, encouraging banks to take even greater risks when expanding credit. He views the relaxation of monetary policy and the granting of Federal Reserve credit to banks at times of distress as inevitable responses to a reversal of the credit cycle, necessary to prevent widespread borrower distress and bank failures, but argues that the expectation of such an accommodation itself encourages an even greater degree of speculation in each succeeding credit cycle. Minsky's arguments point to the need for tight regulation and control of financial markets.
3.4.4 Much of Minsky's analysis is widely accepted. The controversial part of his argument is his view that excessive credit creation is an inherent part of the cycle of boom and bust, an instability that can only be restrained by tight regulation. Certainly he is right that standards of credit assessment can weaken alarmingly during major credit expansions. There are a number of reasons for this, including: overconfidence on the part of borrowers who assume that current growth of incomes will continue into the indefinite future; failure to recognise the possibility that property and other collateral values might reverse after a credit boom; reliance on recent default and recovery rates during the credit boom as a measure of prospective default and recovery when the boom is over; a low level of losses during the boom boosting bank capital and profits and encouraging greater risk taking and also aggressive entry into loan markets; and remuneration and bonus arrangements that reward staff for volumes of lending or short-term returns, with insufficient regard to risk exposure or long-term performance. Minsky also points out the fairly general practice followed by central banks following the ending of a credit boom of lowering interest rates to revive borrowing and spending and so setting the seeds for a subsequent possibly even larger boom to follow. These and other factors create a cycle with bank loans and other forms of credit widely available during credit booms but in very short supply when there is a subsequent bust.
3.4.5 What is not so clear is that tighter regulation is the best response to the credit cycle. Not every boom and bust results in a financial crisis. A major contribution to the credit cycle is inappropriate fiscal and monetary policy. Major credit booms are not difficult to spot. There is very rapid credit creation and major increases of asset prices, especially those of residential and commercial property. If fiscal and monetary policy were used to control asset prices and credit growth as well as consumer price inflation then any remaining credit cycle should be relatively modest.
3.4.6 Bank exposure to credit boom and bust should also be controlled by ensuring that there are adequate commercial disciplines on their lending decisions. When banks or other lenders become overexposed and suffer substantial losses at the end of a credit boom, a large part of these losses can be attributed to failures of governance and control. The right policy response to the credit cycle is not to restrict bank lending directly but to ensure that banks act in the interests of their own shareholders. As Minsky himself points out, banks may take excessive risks during a credit expansion because they expect to be supported by the central bank or by government if they get into difficulties; but this distortion of incentives is better dealt with if possible through arrangements that impose costs on bank shareholders and bond-holders rather than through tight regulation.
3.4.7 What about stock market booms and crashes? Do they also play a role in the credit cycle and in financial crises? Stock markets are less important to the credit cycle than property markets. Unlike commercial or residential property there is relatively little direct lending against equity prices (although there are exceptions – bank lending collateralised against equity investments was commonplace in Japan in the 1990s and also ‘margin lending’ for stock purchase played a role in the US in the late 1920s before the 1929 economic and stock market downturn). Especially outside of the United States, households hold relatively small direct portfolios of equities and so equity prices have a relatively small impact on household wealth. Stock markets are also relatively volatile and crashes can quickly reverse. Unlike property markets, when stock markets have crashed they have typically recovered much or all of their losses within a few months (this is true both of the 1929 and the 1987 crash, although in the 1930s there was then a renewed decline in US stock prices as the US economy fell into depression).
3.4.8 For these reasons, it is not surprising that movements in stock prices do not seem to have much direct impact on consumer spending or corporate investment. The direction of causation runs mostly from the real economy and expectations about future earnings and growth into stock prices, not from stock prices into the real economy and into future earnings and growth, and for this reason stock price crashes have played a relatively minor role in the financial crises listed in Table 1 and Appendix A. There is also the possibility of a major fall of stock prices, substantially reducing the net worth of life insurance and pension funds and, depending on the regulatory regime and how the funds themselves respond, this could then lead to large portfolio re-allocations and further impact on prices and net worth. As we discuss below, this is a potential systemic risk but one that can be largely averted through appropriate regulation, allowing funds flexibility and time to respond to market developments.
3.4.9 A further aspect of the credit cycle, mentioned by Minsky but given particular emphasis by the current credit crisis (see our case study in section 6.5), comes from excessive leverage and from maturity mismatch. Leverage and maturity mismatch are, of course, an inherent part of the banking business model. Deposit taking, especially in transactions accounts or relatively short maturity savings and time deposits, is a core banking function. So when compared with other companies, banks automatically have a relatively high share of debt finance on their balance sheet, and most of this is at short maturity.
3.4.10 Problems arise when banks are over-leveraged or engage in excessive maturity transformation, leading to bank failures and bank runs in a financial crisis. Leverage is determined by bank capitalisation. Banks that operate with comparatively low levels of shareholder capital earn relatively high returns for shareholders during expansionary periods. But their earnings are much riskier and, if it suffers from substantial credit losses or write downs of investments, a highly leveraged bank can quickly find that its capital falls down to, or below, the minimum levels required by regulators. In this situation, if it is unable to recapitalise, it must expect to be closed or acquired.
3.4.11 Even if a highly leveraged bank has enough capital to meet regulatory requirements, it may still face funding problems if it relies heavily on short-term wholesale funding of maturity of, say, three months or less. Doubts about the levels of bank capital, and the possibility of further credit losses or investment write downs, can lead to wholesale depositors refusing to renew their deposits. If the bank cannot replace these funds, say using interbank lending, then it will quickly run out of funds and have to turn to the central bank for support.
3.4.12 Leverage and maturity mismatch have played a role in all the banking crises listed in Table 1 and Appendix A. After the event, it is easy to see that many banks had insufficient capital and relied too much on short-term funding. This is why the initial financial problems pushed them close to failure. But, on many other occasions, financial problems in the aftermath of a credit cycle have not proved severe enough to lead to widespread bank failure. The difficult challenge is determining an appropriate degree of leverage and maturity mismatch and the extent to which this decision should be subject to regulation and not simply a commercial decision of banks, or other financial institutions. We review further the role of leverage and maturity mismatch in creating systemic financial disturbance in section 4.3 and we discuss the regulation of leverage and maturity mismatch in section 7.2.
3.5 Governance, Accounting and Control
3.5.1 The preceding discussions of financial regulation and innovation and of the credit cycle, all point to a central role for weak governance and control in many banking crises. If banks were all well run, and avoided taking on highly risky exposures, then banking crises would be rare events.
3.5.2 But not all banks are well run. It is striking that in almost every bank credit boom and bust, a large share of losses is incurred by a relatively small number of aggressive lenders. These are typically banks that have sought to take advantage of the large-scale of demand for credit from corporate or household borrowers during the preceding credit boom to expand their market share. Such a strategy creates a high level of both credit risk (lending to relatively risky borrowers) and liquidity risk (from reliance on unstable short-term wholesale funding to finance rapid balance sheet expansion). The position of more aggressive banks is also sometimes further undermined by acquisition of competitors at high ‘boom’ prices. The high level of future potential losses from such aggressive strategies can also be masked by backward looking accounting rules for loan loss provisions, focussed on past rather than prospective performance.
3.5.3 It is not easy to exert effective governance and control on banks and limit this kind of risk-taking. Unlike other firms, banks create credit. This means that, at least in good times when short-term funding is easily available, there is relatively little external commercial discipline on aggressive balance sheet expansion. Cultural and political pressures can further encourage credit growth. In theory, shareholders should want to reign in headstrong senior executives following such aggressive expansionary policies. In practice, shareholders find it difficult to interfere directly in bank management decisions and the non-executive directors whose job it is to question bank strategy are often in a relatively weak position and unable to exert a restraining influence. Bank supervisors also have had relatively little power to intervene. There is little they can do as long as a bank is complying with the various prudential and other regulations.
3.5.4 Governance and control is also a concern in the aftermath of a crisis. One of the biggest concerns, for example in the US Savings and Loans crisis and in Japan in the 1990s, is inadequate disclosure. Banks can hide the true extent of loan problems by lending more money to borrowers to enable them to service their loans, and so mask the true extent of loan arrears. Both US Savings and Loans in the 1980s and Japanese banks in the 1990s were for some years able to use retail deposit inflows to refinance many struggling borrowers in this way, thus throwing ‘good money after bad’ and substantially increasing the eventual scale of loan losses. They became what are sometimes referred to as ‘zombie banks’: banks that were no longer controlling their lending according to commercial criteria but simply handing out money as necessary to keep both borrowers and themselves afloat.
3.5.5 The access to deposits necessary for such ‘zombie banking’ is only possible because of the deposit safety net, the presence of either explicit deposit insurance or an implicit promise by government to make depositors whole. In such a situation, regulators need to step in, to force banks to stop lending further money to borrowers with little prospect of repayment, and where necessary close down or restructure banks that cannot repay their own liabilities. But regulators themselves can be reluctant to intervene, they may prefer ‘forbearance’, giving banks more time in the hope that the problems will recede.
3.5.6 Both accounting rules and risk management systems play a central role in governance and control. It can be argued that fair value accounting rules – marking positions to market values wherever possible – impose better discipline on banks, ensuring that there is relatively early recognition of loan problems and making ‘zombie banking’ (lending without regard to the prospects of obtaining a commercial return) and regulatory forbearance much more difficult.
3.5.7 But mark-to-market accounting cannot be easily applied to all bank exposures, and, where it is applied, it can create problems of instability of its own. When, as is often the case, bank assets are illiquid then there can be a damaging feedback loop with falling prices undermining balance sheets; in certain regulatory contexts, this can lead to ‘fire sales’ of assets which further weaken market prices. Our case study on the current financial crisis at section 6.5 looks at the role of fair value accounting in the current crisis. There is still controversy. Some in the industry believe accounting standards have been a major source of instability. Others resist proposed departures from fair value accounting, concerned that this will weaken reporting disciplines. This same criticism can be levelled in the context of applying fair value methods to insurers, which are long on liquidity (i.e. rarely need to enter forced disposals to satisfy obligations). However, banks are short on liquidity and so need to have sufficient liquid assets that can be disposed of to pay back short-term funding should the need arise. The providers of short-term funds, e.g. in repo markets, are really only interested in mark-to-market valuations, what assets would realise if they were sold in the near future.
3.5.8 There is also debate on whether better risk management might have prevented or limited the crisis. Certainly it appears that risk reporting was not taken seriously enough by senior management in many of the firms that have experienced the greatest losses. There was too much emphasis on running risk systems as a goal in itself, with an excessive focus on quantitative risk modelling, and insufficient attention paid to using risk systems to develop a better understanding of exposures at a firm-wide level and communicating this understanding at senior management and board level. It is also arguable that risk models were too similar across the industry, resulting in correlation of exposures and so exposing banks to large collective risks. There was gross underestimation of tail VaR for many asset classes, both because of flaws in model design and because of incentive problems – management wanted the model to produce a certain answer that reinforced their chosen business strategy. These two factors probably reinforced each other.
4. What is Systemic Risk and How Does It Arise in Banking?
4.1 Definition
4.1.1 We now discuss the causes of systemic problems in banking. To do this, we first offer a definition of ‘systemic’ risk, and then use this definition to discuss how such systemic risk arises in banking. The following section of this paper (section 5) then considers the extent to which similar mechanisms are a feature of the insurance and pension sectors.
4.1.2 ‘Systemic’ risk is not the same thing as a large-scale disturbance affecting all financial institutions. There can be large common shocks affecting many financial institutions, banks or non-banks. These are not necessarily systemic. For example, there may be a major decline in aggregate spending (all too common in smaller economies subject to terms of trade or export shocks). Such an outturn could increase loan losses and reduce earnings for a large number of banks. But provided it does not undermine bank solvency, cut banks off from access to liquid funds, result in a breakdown of bank lending markets or otherwise prevent the normal functioning of the economic and financial system then it is still only a (possibly large) common shock.
4.1.3 At the same time, it is possible for systemic problems to occur, but to have a substantially smaller economic impact than in the major crises listed in Table 1. We give a number of examples of such smaller systemic problems at section 4.3. Defining a systemic risk as a large-scale banking or financial crisis means failing to pay attention to many, somewhat smaller scale systemic problems, from which much can be learned. This is a further reason for avoiding the assumption that a systemic crisis is the same thing as a very large common shock affecting all financial institutions.
4.1.4 Some further confusion arises because of the use of the term ‘systematic risk’ in finance to describe such common shocks and their impact on investment returns. One of the main contributions of modern finance theory has been to show that investors should require a premium return to compensate them for the risk of common shocks (because such systematic risk cannot be diversified through altering investment portfolios) but, in the absence of capital market frictions, should not require a premium return for other ‘idiosyncratic’ or, as they are sometimes called, ‘specific’ risks (because these can be fully diversified by adjustment of an investor's portfolio).
4.1.5 What then makes a systematic risk or common shock systemic? We propose the following definition of systemic risk.
A systemic risk materialises when an initial disturbance is transmitted through the networks of interconnections that link firms, households and financial institutions with each other, leading, as a result, to either the breakdown or degradation of these networks.
It would be possible to vary this definition in various ways, without altering its basic thrust. We could exclude financial institutions from this list altogether, viewing them instead as simply another of the networks that link households and firms. We could also lengthen the list of institutions to include government as well as financial institutions, so drawing attention to other possibly systemic problems, such as government default. This specific definition is preferred as being most relevant to the issue addressed in this paper, the emergence of systemic risk in financial services.
4.1.6 By ‘networks’ of interconnections we mean here the markets and other institutional arrangements that firms, households and financial institutions use for conducting economic transactions with each other. The simplest economic transactions, for example a small farmer or artisan bartering his or her wares directly to households, do not require such networks. But more sophisticated economic activities, including financial and monetary transactions, rely on many such networks, including for example arrangements for making payments or storing value in financial assets. In our analysis, systemic risk arises when these networks no longer operate or become much more difficult to use.
4.1.7 Applying this definition makes it clear how systematic risk differs from systemic risk. Systematic risk does not imply damage or breakdown of interconnections between firms, households and financial institutions. But if there is such damage or breakdown, then the systematic risk becomes systemic.
4.1.8 This definition of systemic risk does not just apply to financial networks, but also to other networks, for example telecommunications or electrical power. To use an example from a few years ago, in the days when a large proportion of the UK population watched the FA Cup Final on television, there was always a major surge in electricity consumption at half-time, when millions plugged in their electric kettles simultaneously. This created a systemic risk which, if not averted, might have led to a failure of the national electricity grid.
4.1.9 A similar notable systemic failure happened in the New York blackout of 1965, as vividly described in Wikipedia:
“The cause of the failure was human error that happened days before the blackout, when maintenance personnel incorrectly set a protective relay on one of the transmission lines between the Niagara generating station Sir Adam Beck Station No. 2 in Queenston, Ontario and Southern Ontario. The safety relay, which is set to trip if the current exceeds the capacity of the transmission line, was set too low.”
“As was common on a cold November evening, power for heating, lighting and cooking was pushing the electrical system to near its peak capacity, and the transmission lines heading into Southern Ontario were heavily loaded. At 5:16 p.m. Eastern Time a small surge of power coming from Lewiston, New York's Robert Moses generating plant caused the misset relay to trip at far below the line's rated capacity, disabling a main power line heading into Southern Ontario. Instantly, the power that was flowing on the tripped line transferred to the other lines, causing them to become overloaded. Their protective relays, which are designed to protect the line if it became overloaded, tripped, isolating Adam Beck from all of Southern Ontario.”
“With no place else to go, the excess power from Beck then switched direction and headed east over the interconnected lines into New York State, overloading them as well and isolating the power generated in the Niagara region from the rest of the interconnected grid. The Beck and Moses generators, with no outlet for their power, were automatically shut down to prevent damage. Within five minutes the power distribution system in the northeast was in chaos as the effects of overloads and loss of generating capacity cascaded through the network, breaking it up into “islands”. Plant after plant experienced load imbalances and automatically shut down. The affected power areas were the Ontario Hydro System, St Lawrence-Oswego, Western New York and Eastern New York-New England. Maine, with only limited electrical connection southwards, was not affected. The only part of the Ontario Hydro System not affected was the Fort Erie area next to Buffalo which was still powered by the old 25 Hz generators.”
4.1.10 What our definition does is to draw attention to the networks of connections and how they can breakdown or be damaged in a systemic event. The most important of the financial networks are the various markets where firms, households and financial institutions participate, both for assets and for funding. As we discuss shortly, both bank asset and funding markets can be exposed to potential systemic breakdown. This is why the banking industry has so often transmitted systemic risk.
4.1.11 A classic example of the materialisation of financial systemic risk is the Herstatt or payments risk which hit the New York money markets in 1974, when the failure, due to fraud, of the relatively small Hamburg-based Herstatt bank led to the near collapse of the New York CHIPS interbank system. The key feature of this failure was the large gross exposure of many CHIPS participants to Herstatt because of the absence of delivery against payment in the money markets of that time. In many cases, they had made large foreign currency (German Deutschmark) payments to Herstatt earlier in the day and were due to receive dollar payments back later that afternoon New York time – payments which could not be made because of the bankruptcy of Herstatt. As a result, payments activity in the interbank market froze (no-one wanted to pay first and thus expose themselves to counterparty risk), with a consequent knock-on impact on securities and other transaction settlements. The soundness of the entire US financial system was threatened.
4.1.12 We make three further comments about this definition of systemic risk. First, we repeat again that our definition distinguishes systemic risk from a major economic shock. It is possible for there to be a contained systemic event which has only a relatively small wider economic impact. The New York blackout and the failure of Herstatt are two examples. Another is the 1987 stock market crash, during which it became impossible to execute transactions on the US stock markets or stock future markets, but which in the end and despite fears at the time had only a relatively muted effect on the wider economy.
4.1.13 Equally, there can be a major economic shock, reducing the net worth and earnings of a large number of financial institutions, but such a shock is only systemic if it results in network damage, preventing the proper functioning of the markets and other networks that link households, firms and financial institutions. Of course, if a shock is large enough, then it can be systemic. For example, suppose there was a twenty five per cent decline in economic activity, impairing a large proportion of bank loans and so making the greater part of the banking system insolvent and interrupting the access of firms and households to credit and transaction facilities. This would be a systemic shock, not because it is large or because many banks failed, but because of the damage it causes to networks for the allocation of credit and transmission of payments.
4.1.14 Second, we note that this definition also covers economic crises which originate from broader macroeconomic and monetary developments, rooted ultimately in failures of government policy. A government debt default, a collapse of monetary discipline (the extreme case is hyperinflation) or a disorderly collapse of the foreign exchange rate can all lead to damage or breakdown of economic relationships.
4.1.15 Equally, a large impact on the financial system could arise from demographic shocks (e.g. a major extension of life expectancy undermining pension fund solvency), from climate change or other events from outside the economic and financial system. Such major events can threaten the widespread insolvency of financial institutions and hence pose a systemic risk. However, such major shocks cannot be anticipated or easily prevented in advance. The best which can be done would seem to be to have in place arrangements for dealing with widespread insolvencies in an orderly manner and ensuring the burden of costs is distributed fairly. Whether these types of major external shocks are a systemic risk in terms of our definition is a moot point; one could argue that they are covered. But whether or not they are systemic, policies to cope with such shocks are not discussed in detail in this paper.
4.1.16 Third (as we shall illustrate further in our case studies in section 6), the institutional environment greatly affects the networks of interconnections linking households, firms and financial institutions. Law and its enforcement, macroeconomic policy, prudential regulation, accounting standards and firm governance all influence the response of individual firms and financial institutions, and this can in turn have a major impact on whether an initial disturbance has a systemic impact. Thus, a proper assessment of systemic risk must take account of regulation, and of the responses of public officials, of financial authorities and of shareholders and their representatives in asset management companies and on the boards of financial institutions.
4.1.17 Our definition of systemic risk is more precise than that used in most of the research on previous financial crises reviewed in section 3 and Appendix B. The usual assumption is that any economic shock that results in widespread financial distress or insolvency of financial institutions is a systemic financial crisis. Such an outcome would also be systemic under our definition. For example, were there to be a sufficiently large enough common shock – such as one arising from a global environmental or epidemiological catastrophe – then the consequence would be widespread insolvency of financial firms and a breakdown of markets and other institutional arrangements which support economic activity.
4.1.18 But we believe our definition is more useful than the usual practice of equating ‘systemic crisis’ with such large-scale financial sector distress and insolvency. By distinguishing the different risks which can trigger the breakdown of the various networks in banking and financial services, we can then identify specific actions which can be taken to mitigate particular risks. This is more helpful than a ‘one-size-fits-all’ approach to analysing and responding to potential systemic risk.
4.1.19 There is now a considerable and growing interest in analysing financial networks, especially in applying techniques for the analysis of complex adaptive systems more commonly used in the biological and natural sciences. There is some hope that these new approaches may yield insights into the potential for instability in financial systems, which cannot be obtained from more conventional models of rational agents and market equilibrium. Appendix B includes a short review of some of this work.
4.1.20 However, while this type of analysis is promising, it is far too early for any consensus to have emerged about the use of such novel modelling techniques and what they can inform us about systemic risk. We instead use a relatively simple and practical approach, seeking to identify those network interconnections in banking that have in the past triggered episodes of systemic risk.
4.2 Network Interconnections in Banking
4.2.1 We now identify four distinct networks of interconnections in which systemic interactions can originate. This list makes no strict demarcation between commercial and investment banking, since nowadays these two activities are very closely intertwined.
1) Payment systems and other financial infrastructure. The systemic risk is that a failure of a participant in a core financial infrastructure, such as the interbank payment system, leaves other banks with large gross exposures both to and from the failed participant and undermines the payment system itself.
– This is the risk that emerged in the Herstatt crisis.
– Investment banks are exposed to each other in a similar way through the infrastructure used to settle trades in securities markets. A systemic problem could, in theory, emerge from securities settlement infrastructure.
2) Short-term funding and deposit markets. Banks obtain short-term funding from wholesale deposits, interbank borrowing and using a variety of other money market instruments. The systemic risk is of losses at one or more institutions triggering a shortening of tenor or a complete withdrawal of funding for an entire group of institutions, because investors suspect that others are affected by similar problems.
– A loss of funding of this kind affecting a single institution is not systemic.
– Such loss of short-term withdrawable funding occurs in the ‘twin’ banking and exchange rate crises discussed in the previous section, when banks have relied on short-term deposits from international investors.
– Historically, in the 19th century, such systemic risk resulted in the withdrawal of deposits from branches of several banks. In the very different institutional environment of today such a systemic risk emerges in the wholesale money markets. Such systemic problems in wholesale money markets have been a prominent feature of the current global credit crisis.
3) Collateral, securities, and derivatives markets. The systemic risk arises when many banks are taking similar positions, lending on the same type of collateral or conducting the same trades in securities or derivatives markets. Many banks taking the same positions can result in prices being pushed up above sustainable levels; and subsequently, if positions are unwound rapidly, prices can then also be pushed well below fundamentals.
– There are several examples of bank lending contributing to asset price bubbles. For example, in many residential and commercial property price booms an excess of bank credit has pushed prices well above sustainable levels and often subsequently, as a result of sales and glut of remarketed property, well below levels that would result from the normal interaction of supply and demand. On some occasions, bank lending has also driven up equity prices to a peak that, with the benefit of hindsight, appears well above sustainable levels (the US in 1929, Japan in 1989).
– Similar interactions are also a common occurrence in the securities and derivatives markets. The difficulties of the large hedge fund Long-term Capital Management (LTCM) in 1998 triggered just such a potentially systemic event. The reason that it was a systemic concern was that many other institutions held similar positions to LTCM. Had it failed, and been forced to close these positions, then many other institutions could have been pushed to failure as well. Such interactions have occurred on other occasions on a much smaller scale, for example in world fixed income markets in 1994 at the time of the failure of Orange County and in 2005 when many banks held similar positions in traded credit derivative indices and were caught out by the downgrading of Ford and General Motors. We comment on all these examples further at section 4.3 below.
– A particularly fierce variation on this type of interaction is the so-called ‘short’ squeeze, when many market participants are contractually obliged to deliver the securities or commodities to close out either repo or futures contracts. If there is insufficient supply of these securities or commodities in the spot market to close out on these contracts, then prices will soar, triggering major losses. Such a squeeze can be deliberately (and illegally) engineered. The most renowned case of this kind (which, in the event, was stopped before the squeeze itself occurred) was the attempt by the Bunker-Hunt brothers to corner the world silver market in 1980.
– This systemic interaction can also arise when many banks are ‘long’ rather than short in the same asset, but only when banks hold relatively little equity capital. If banks hold a substantial reserve of capital they can absorb short-term losses and hold these positions or close them only gradually over time, instead of becoming forced sellers and losing money because of the collapse of prices.
4) Exposure to a common counterparty. This systemic risk arises when many banks hold positions against the same counterparty. The failure of this counterparty can then create a system-wide risk, if banks are unaware of either their total exposure (direct and indirect) to the counterparty or of the total exposure of the counterparty to banking returns.
– An example of a potential risk of this kind would arise with the failure of a single, large over-the-counter (OTC) dealer; say, for example, JP Morgan-Chase which is the world's largest dealer of OTC derivative contracts such as interest rate and credit derivative swaps. Such a failure, while unlikely, would pose a systemic risk because all the contracts with JP Morgan-Chase would then have to be replaced and the price at which this could be done is very uncertain (see Bliss & Kauffman (2007) for a discussion of this risk).
– Similar systemic concerns can potentially arise when insuring or hedging risks. If Bank A, Bank B and Bank C all lay off the same risk with a dealer or insurance company, D; then looking at their own individual bilateral relationships, insurance company D (in 2008 this was ‘AIG’), appears to have sufficient capital to cope; but it can then turn out to be severely undercapitalised against the total risk. This, in turn, can undermine the insurance or hedging arrangements.
– Such risks can be mitigated through having a single central counterparty, which becomes the buyer to every seller and the seller to every buyer (see Krozner (Reference Krozner1999) for a discussion of the emergence of such central counterparty arrangements in the Chicago futures exchanges and an argument favouring the view that the private sector can generally provide effective control over its own risks). Such a central counterparty is nowadays present in all the major derivatives exchanges, but as yet still covers only a small part of global OTC derivative trading exposures.
– Note that this exposure to a common counterparty is distinct from the problems of counterparty risk which have emerged in short-term money markets, especially since the failure of Lehman Brothers in September 2008. Counterparty concerns in money markets arise mainly because of reliance on short-term funding. If there is a loss of confidence in the ability of a bank to refinance itself then wholesale depositors become reluctant to renew their deposits and this in turn makes it very difficult for the bank to refinance its maturing liabilities. This is also a major systemic risk, but it arises because of the reliance on short-term funding, not because counterparties have underestimated their exposure or the default risk of the counterparty.
4.2.2 This list of networks which have transmitted systemic risk amongst banks does not mention ‘domino’ type interactions through direct holding of bank liabilities by other banks, in which the failure of one bank then leads to the failure of a second and third, which in turn leads to the collapse of a large part of the banking system. Nor does it consider intra-group connections, the possibility that problems in one part of a larger company could bring down the institution as a whole. In theory, these are also a material systemic risk. In practice, they are risks that rarely materialise. A considerable amount of research has been devoted to the question of whether or not the interbank exposures can trigger a systemic collapse, for a number of different banking systems (for a survey of this kind of work see Upper (Reference Upper2007), further references are provided at section B4.1.2). It turns out that, outside of derivatives and payments markets, this is not a concern, and that tracing through the direct exposures of one bank to another, in almost all cases when one bank – even the largest in any single country, fails – the further impact peters out rapidly. Interbank linkages have the potential to generate such multiple failures only in the very smallest countries where banking activity is dominated by one or two large institutions and then only if the authorities do not intervene to prevent the further knock-on effects.
4.2.3 This finding, that direct exposures between banks do not threaten system wide bank failure, should not be a surprise. The principal exposure between banks is interbank lending, when banks with excess funding lend for a relatively short period of time to banks that are short of funding. But typically these excess funds are only a small part of total bank assets; and they also run predominantly in one direction only, with one group of banks (those with excess funds) exposed to another group of banks (those with insufficient funds). Moreover, when there is a threat to solvency, then these funds are typically withdrawn and placed somewhere else before the failure occurs. They only play a role in the transmission of systemic risk as part of our second network of interconnections, namely short-term funding and deposit markets.
4.2.4 Another omission from this list of networks that have transmitted systemic risk in banking is foreign exchange markets. These play only a secondary role, in relation to ‘twin crises’. The reason for giving such a brief reference to these markets is that direct bank exposure to these markets arises through the second group in our list of networks of interconnections (short-term funding and deposit markets).
4.2.5 This is not to say that foreign exchange arrangements cannot sometimes be the source of major systemic disturbance. The collapse of the restored gold standard in 1931, and of the Bretton Woods exchange rates in the early 1970s, and the collapse of the European fixed exchange rate arrangements in 1991 are three prominent examples of disruption of exchange rates which led to at least a temporary degradation to the networks of interconnections between firms, households and financial institutions. As such they count as systemic events, in our definition. But these are problems of macro-monetary policy and did not originate in the banking industry, so they are not included in this list.
4.2.6 The collapse of these fixed exchange rate arrangements were all a result of fundamental institutional weaknesses, including lack of political commitment to the necessary sharing of responsibility for maintaining fixed exchange rate arrangements. They illustrate well how systemic disturbance can arise from the wider institutional and political environment.
4.3 Sources of Systemic Risk in Banking
4.3.1 What then can lead to systemic events that damage one of these four networks of interconnections between banks and between banks and their customers? Of these four networks of interconnection, the possibility of systemic breakdown of interbank payments or other infrastructure is well understood and nowadays well controlled. There has been a shift from netting of payments to gross real time settlement, a development which limits systemic risk because the failure of a payment system participant no longer creates a problem of how to unwind previous netted payments. A failure will leave payments due to other participants, but this is a bilateral not a system wide concern. The authorities are also now more aware than they were at the time of the Herstatt failure of the need to manage a bank closure to minimise the payments system impact, avoiding the closure of a firm late in the working day that has received many payments in and made relatively few payments out. While there is always a possibility of a systemic breakdown in payments and settlement systems, this can only directly affect banks, not other financial institutions, such as pension funds or insurance companies.
4.3.2 Our discussion of banking and financial crises since the 1970s also illustrates the role of short-term funding and maturity mismatch as a cause of banking instability. This is a major systemic risk for banks, because of the large proportion of short-term liabilities on their balance sheets. As a consequence, there has been, on several occasions, a breakdown of short-term funding markets, especially when banks borrow short-term from international investors. This is a systemic breakdown which has played a role in almost all banking crises (the only cases where it does not arise are situations such as the US Savings and Loans, where the affected banks funded themselves using 100% government backed deposit insurance). The financial authorities have responded to these crises through the central bank acting as ‘lender of last resort’, providing short-term collateralised loans to banks that could not fund themselves in interbank markets and often also through the announcement of government guarantees on bank liabilities. Such maturity mismatch is a major source of systemic risk, but it usually affects only commercial banks. It can also affect investment banks and hedge funds, when they adopt trading strategies that rely excessively on short-term funding. But it does not affect funds, such as pension and life insurance funds, with long-term liabilities.
4.3.3 Another major source of systemic risk is unsustainable increases in bank commercial and residential mortgage lending. This has occurred on many occasions not only in the large-scale banking crises, listed in Table 1, but also in many other smaller credit booms and busts. Such credit booms are characterised by rapid increases in real estate prices, strong demand for mortgage credit and very low default rates in an environment of freely available credit. This shared common exposure, with many banks engaged in the same type of lending, encourages substantial credit expansion and so masks the extent of risks during the upswing. The same shared common exposure can then magnify the reduction of credit and decline of real estate prices, once the credit expansion goes into reverse. This correction can be especially severe when bank capital is eroded and they struggle to absorb the resulting losses on their balance sheets. The current global credit crisis provides a clear illustration of this damaging feedback loop (see Figure 4 and the accompanying discussion of the credit cycle, presented as part of our case study of the recent crisis).
4.3.4 Disruption due to common exposures is something which has also occurred on a number of other occasions, both in securities and in derivatives markets, without necessarily resulting in a major impact on the wider economy. One well known example is the correction of US dollar interest rates in 1994. An unexpected rise in the Federal Reserve policy rate led to a disorderly unwinding of short-term trading positions, with many banks and hedge funds who had been borrowing short-term to hold longer term higher yielding Treasury bonds forced to close down their positions. The consequence was some very sharp yield curve movements across the maturity spectrum, with a sharp decline in bond prices. The most widely publicised loser from these extreme market movements was the investment fund of Orange County in California. The Treasurer who controlled this fund, Bob Citron, had been earning relatively high returns through aggressively leveraged investments of this kind.Footnote 1 Orange County were forced to close out their positions at a substantial loss and this had a major impact on the price of short-term money. Still, after some weeks, prices recovered. Less leveraged funds were able to ride out this period. In the end there was little systemic impact. Within a few weeks these markets had returned to normal functioning and, aside from a few well publicised trading losses, there was little economic impact.
4.3.5 This interest rate example had a widespread impact because of the reliance on short-term funding (it was not the common exposure alone that created problems). Similar systemic trading shocks have occurred on other occasions, in traded commodity and derivative markets. There was a very similar temporary distortion of market prices at the time of the failure of LTCM in 1998. LTCM's principal trading strategy, which it pursued on a huge scale, was ‘convergence trading’, holding long positions in relatively illiquid securities with corresponding short positions in more liquid securities offering very similar future pay offs. Over time they anticipated that the prices of these securities would converge and thus earn them large profits. Their successful trading strategies were copied by many other market participants. But the Russian government bond default of 1998 triggered a ‘flight to liquidity’, pushing apart the prices of otherwise similar liquid and illiquid bonds, and creating huge paper losses on the positions held by LTCM and others copying their trading strategy. The resulting failure of LTCM threatened to result in a large volume of illiquid assets being thrown onto the market and short-term traders, anticipating such a ‘fire sale’, pushed market prices further apart. The situation was stabilised through the acquisition of LTCM's positions by a consortium of banks organised by the New York Federal Reserve.
4.3.6 A credit market example is the large-scale losses on so called ‘correlation trades’ on traded credit indices in May of 2005, when many hedge funds and investment banks held similar trading positions which generated large-scale losses following the downgrading of Ford and General Motors to speculative grade credit ratings. This arose because a number of hedge funds and other speculative traders were holding what they thought to be fully hedged positions in the tranched CDX credit indices, indexes based on 125 investment grade corporate names including Ford and General Motors. The hedging of risk in these trades was all based on simple and widely used model of default correlation (the David Li Gaussian Copula model) amongst all 125 names in the index. The downgrading of Ford and General Motors was an idiosyncratic event, due to their loss of market share to Japanese rivals and the heavy burden of pension and insurance liabilities for their retired workforce. The correlation was much lower than assumed in the model parameterisations and so the market prices of the different tranches of the index behaved in unexpectedly divergent ways. Many traders found themselves ‘short squeezed’, as mounting losses forced them to close down their positions at a substantial loss. After some weeks of volatility the market then stabilised.
4.3.7 A feature of these examples of systemic interactions in traded credit, security and derivative markets, not associated with excessive bank credit expansion and resulting common exposure of banks to similar collateral assets, is the role of mark-to-market valuation of securities and derivative trading positions and the consequent demands for margin payments when trading positions experience losses. In all these cases – fixed income markets in 1994, LTCM in 1998 and credit correlation trades in 2005 – margin payments forced the closure of trading positions and the resulting adverse movement of prices had magnified the losses for those unable to hold their positions. But it would be a mistake to argue that mark-to-market valuation and margin payments are a major cause of systemic risk.
4.3.8 Providers of short-term funding for trading in security and derivative markets will not lend without the protection against counterparty risk provided by mark-to-market valuations and margin payments. But this in turn means that there is always a risk in short-term financial trading of margin payments resulting in large-scale cash outflows. What resulted in large-scale losses on these occasions was flawed risk management, with participants having inadequate capital to absorb losses and margin payments, and failing to apply risk mitigation strategies that ensured that their positions are closed down in a gradual and orderly way to limit losses. In fact all of these cases have been ‘one-offs’ with market participants learning from these episodes how better to manage their risks in the future.
4.3.9 The mark-to-market valuation of illiquid structured credit exposures has been especially controversial in the current global financial crisis, leading as it has done to widespread writedowns on many traded credit portfolios, write downs that many believe overstate the potential for future credit impairments (see our case study at section 6.5 for further discussion). But it is far from clear that it is these mark-to-market valuations themselves that have been a cause of systemic risk. What is more obvious is a mechanism operating in the other direction. There has been a systemic breakdown in previously liquid traded credit markets, and this has been reflected, because of mark-to-market valuations, in large-scale losses on these markets.
4.3.10 Following the crisis, there has been at least a temporary shift away from a mark-to-market valuation of these assets, under both US GAAP and IFRS accounting standards, so limiting the impact on bank balance sheets. IFRS has allowed institutions to transition assets from ‘available for sale’ or ‘trading assets’ to ‘hold to maturity’, with the result that they need no longer be marked-to-market valuations, as long as there is no prospect of impairment. US GAAP allowed a different temporary relaxation. Where underlying markets are clearly illiquid, US GAAP allowed fair value accounting measures to be based on models of prospective future cashflows. Such changes can be justified as a means of limiting the impact on bank balance sheets; but there is no reason to anticipate that this shift will restore liquidity to the underlying credit markets.
4.3.11 Finally, we turn to the failure to monitor and manage counterparty risk at an aggregate ‘system wide’ level. It has been a concern in only a few systemic banking crises but did play a role in 2007–2008. As already discussed, it is hardly ever the case, even in major banking crises, that the failure of one bank imposes such direct large losses on other banks that there is a chain of subsequent failures. Mismanagement of counterparty risk has most often arisen when banks have turned to insurance companies or derivative markets to hedge risks. Two examples are the role of ‘mortgage indemnity insurance’ in the UK credit boom of the late 1980s and of the emergence of large-scale counterparty risks against AIG and monoline insurance companies in the current global financial crisis. These cases were not, however, systemic on their own, but a contribution to a wider systemic disruption based on common exposure shared by many banks. In each case, the provision of insurance first contributed to the preceding mortgage lending boom; and then the subsequent materialisation of counterparty risk exacerbated the subsequent credit bust.
4.3.12 Finally, it is worth emphasising that, while we distinguish four different network interactions that create systemic risk in banking, these different sources of systemic risk do not operate independently. Many of the crises shown in Table 1 have been triggered by a combination of increased maturity mismatch, based on increased reliance on wholesale short-term funding, and an unsustainable expansion of mortgage and other credit. We are unable, within the scope of this present study, to carry out the necessary statistical analysis; but we hypothesise, from the crises in Table 1, that there is a powerful interaction between excessive maturity mismatch and unsustainable credit expansion and that the probability of a major banking crisis is very much increased when both risks are present.
4.3.13 Can similar systemic interactions affect other financial institutions? The following section discusses the extent to which systemic interactions can affect the insurance and pension sectors. We find that generally these possibilities are limited, mainly because insurance companies and pension funds do not rely on short-term funding. What about the possibility that similar interactions, between the availability of external funding and the value of investments undermining net worth, could affect the variety of investment vehicles, other than banks, that rely on short-term funding. We think, in particular, of the impact of the financial crisis, and of the losses of the Madoff investment fraud, on hedge funds. A loss of confidence could trigger large-scale redemptions and this might turn into a systemic risk, with withdrawal of funds triggering declines in asset valuations and further withdrawals. In practice, such erosion of confidence in hedge funds does seem to have occurred in the current financial crisis but only for those funds exploiting very similar investment strategies to banks, using short-term funding to invest in illiquid structured credit securities. Responses such as temporary suspension of redemptions appear to have been enough to prevent problems becoming more widespread in the hedge fund industry. But this is not to say that more serious systemic problems could not arise in the future.
4.3.14 This discussion reveals that systemic interactions in banking can arise in a number of different ways and result in, at least temporary, damage or breakdown in the various networks of interconnection between banks. But does such a systemic disturbance always have a major economic impact? Often it does not. Provided that the participants in the network survive, then the networks of interconnections can be restored to normal functioning after a relatively short period of time, perhaps days or weeks. Some participants may have suffered fairly large losses but there are often other participants who have made substantial gains. Relatively soon there can be a return to ‘business as usual’.
4.3.15 A major economic impact arises only when the disruption is prolonged and there is no rapid return to normal operation. This is a likely outcome if the systemic disturbance results in the failure of major participants in the networks. This in turn points to the critical importance of adequate capitalisation. Provided financial institutions have sufficient equity or other capital to absorb the losses resulting from a systemic disturbance, then the wider economic impact should be contained. This is an illustration of a more general lesson, that systems of interconnection should have sufficient redundancy so that they can cope with extreme disturbances. By this we mean that there should be sufficient margin for error, for example by holding substantial free reserves of liquidity or capital, so that firms and networks can absorb shocks without amplifying them and transmitting them.
5. Systemic Risk in the Insurance Industry and the Pension System
5.1 This section discusses the involvement of the insurance and pension sectors in systemic financial events. Systemic problems originating in the life insurance industry and in the pension system have occurred only rarely and have arisen only because of common exposures, to asset markets or to hedging counterparties. Insurance companies and pension plans are not involved in the same network linkages and to the same extent as banks. Although they have many fixed contractual liabilities, such as those to life insurance policyholders and pensioners, they are not directly linked to financial infrastructures (for this they rely on banks), and they also do not rely on short-term withdrawable funding and are not involved in the provision of unsustainable credit expansions. This is not to say that banking problems will not affect insurers and pension plans – they still need to access banks for example to make customer payments, to hold cash deposits, or to hedge exposures using financial derivatives. But in this respect they are just like other customers; this is not something that amplifies shocks.
5.2 Thus, of the four networks of interconnections which we identify in banking, two do not affect the insurance industry or the pension system. Only the third – common exposures to collateral, securities and derivatives markets – often affects life insurance and pension funds and then to a much more limited degree than in banking. Only the fourth – exposure to a common counterparty – can affect general insurance companies and this has never been a major source of systemic risk on its own. This is why these networks of interconnections do not usually transmit systemic risk to insurance companies and pension plans.
5.3 Insurance companies and pension funds are typically less leveraged than banks. Also, at least until the relatively recent solvency tests, insurance companies, like pension funds, did not become forced sellers in adverse circumstances. Instead, and unlike banks, they could hold positions, even when suffering from large declines of net worth. But, as we shall discuss in section 5.8 and 7.3, the introduction of regulatory solvency requirements has made systemic risk more possible now than in previous years for insurance companies. Counterparty risk has occasionally caused systemic problems in general insurance, but this is a consequence of an evident failure to properly monitor and control exposures and does not appear to be a major source of systemic risk interactions.
5.4 This is not to say that the insurance industry and the pension system cannot be sometimes affected by large common shocks, both those originating in financial markets (for example substantial declines of share prices) or major environmental, epidemiological or demographic events. There have been major episodes – for example, the losses on Hurricane Katrina which was the largest single insurance episode to date. These have not been, on our definition, systemic events. Yes, Katrina had a major impact on the net worth of insurance and reinsurance companies. Yes, it led to an increase in claims. But it did not lead to the breakdown of insurance markets or the disruption of financial flows.
5.5 An even larger catastrophe might have a systemic impact, but such an event would have to be on a quite exceptional scale, far exceeding previous loss experiences. For example, one can envisage a medical breakthrough leading to a sudden major increase in life expectancy, say from 75 to 150 years, which in turn undermines the solvency of pension funds and their sponsors. Or there could be a major geographical or environmental catastrophe which leads to the insolvency of the major global reinsurance groups. Such events might lead to breakdowns of networks of interconnections amongst households, firms and financial institutions and would therefore also be, even under our definition, systemic. But, as we argue, the policy required to deal with such extreme but highly unlikely large common shocks is not the same as that needed for mitigating the systemic risks arising from within the financial system.
5.6 Overall, we conclude that the insurance industry and the pension system are not vulnerable to systemic risk to anything like the same extent as the banking system. However, weaknesses of governance and control that lead to excessive risk exposure or inappropriate asset and liability mismatch have the potential to create system wide problems. And these problems can be exacerbated by crude regulations that force companies to transact in illiquid markets.
5.7 Insurance Underwriting and Counterparty Risk
5.7.1 This sub-section discusses the extent to which systemic problems can arise in insurance underwriting and in life and pension investment. There are a few examples where insurance companies have taken on banking sector risks, leading to banks themselves failing to recognise the extent of their exposure to a system-wide shock. The example of mortgage indemnity insurance in the late 1980s in the UK has already been referred to. The years 1985–1989 saw a rapid rise of UK mortgage lending and of UK house prices, with intense competition in newly liberalised mortgage markets and the extension of credit to a number of relatively risky borrowers, first-time buyers with little or no cash and relatively low income.
5.7.2 In order to minimise loss-given-default, it became the usual practice in the UK, when lending mortgages at high loan-to-value ratios, to require the borrower to take out a mortgage indemnity policy, paying an additional regular monthly premium for a policy which would pay the lender any shortfall in the event that mortgage payments were not maintained and the mortgaged property was sold for less than the outstanding loan. The problem in the late 1980s was that the specialised companies selling this mortgage indemnity insurance grossly underestimated the risk of a nationwide fall of house prices and, as a result, substantially underpriced this insurance. This contributed to the credit expansion, making loans available at low cost to relatively high risk borrowers.
5.7.3 When the housing and mortgage lending boom reversed, in 1990–1992, house prices fell sharply in most regions of the UK, especially in the South-East, and several of the leading providers of mortgage indemnity insurance failed. Mortgage lenders had not taken into account the possibility of counterparty risk, and this in turn encouraged a more pronounced credit boom and bust than if they had been accepting these risks themselves. This was a potential systemic risk exacerbating the exposure to credit risks in the UK in the late 1980s and early 1990s; but in the event there was little systemic damage to bank lending or other networks and it did not lead to a sufficiently large-scale banking crisis to be included in our Table 1.
5.7.4 A remarkably similar failure to recognise aggregate system-wide counterparty risk has occurred in the current global financial crisis, where AIG and also a number of the leading monoline insurance companies have written insurance on senior US sub-prime mortgage-backed securities and on senior collateralised debt obligations.Footnote 2 This case is slightly different from that of mortgage indemnity insurance in the UK, because the contracts used were not traditional insurance contracts but the widely traded credit derivatives known as ‘credit default swaps’ or CDS. These contracts stipulated that if the protection sellers, in this case AIG and various ‘monoline’ insurance companies, lost their privileged AAA credit ratings then they were required to make cash payments to compensate the protection buyer, in this case mostly banks holding the underlying senior structured credit assets, for declines in the market value of these bonds. This commitment placed an unsupportable negative cashflow burden on AIG and the monoline insurers writing these contracts, and in turn undermined the market for senior structured credit assets. It is worth noting that both these two examples involved the insurance of credit risk and the potentially systemic aspect arose as a result of the relationship between the insurance companies and the banking sector. The systemic problems were not within the insurance sector itself. The event imposed unexpectedly large loan losses or write downs on banks.
5.7.5 We have found only one example of a counterparty risk which is specific to the insurance industry. This is the extended crisis in Lloyd's at the end of the 1980s. The nature of the reinsurance arrangements led to a wider systemic impact after the impact of an initial common shock. Syndicates had taken out reinsurance to close out their liabilities at the end of their three-year reporting period, as was standard practice. As the potential losses were very uncertain, liability was passed through to other parts of the market. However, a complex network or ‘spiral’ of reinsurance often led to those who thought they had offloaded risks on to others being liable for these risks again (or liable to very similar risks) from underwriting insurance or reinsurance related to risks similar to those that they had ‘offloaded’. The reinsurance mechanism did not disperse risk in the way that had been hoped and led to serious disruptions within Lloyd's with the impact of risks coming back through reinsurers to the syndicates that had tried to offload it.
5.8 Life Insurance Common Exposure to Long-term Asset Markets and the Impact of Solvency Requirements
5.8.1 A different potential cause of systemic problems in the insurance and pension sectors arises when there is exposure to shocks to the price of assets which institutions hold in common. This can have a particularly marked impact when regulation encourages institutions to respond in a similar way to price changes. This can lead to what might be relatively minor problems within individual institutions developing into more major problems that can disrupt the market as a whole.
5.8.2 One such example occurred in the life insurance sector at the end of 1998. There was a period of falling gilt yields combined with falling equity prices (this combination was extremely rare in the 20th century and does not appear to have occurred on any previous occasion since World War II). Given the very long-term liabilities of life insurance companies (including guaranteed annuity liabilities) and their high levels of equity investment at that time, this led some life insurance companies to have solvency difficulties. These were exacerbated by a ‘resilience’ test that the companies had to follow to show that their financial position was robust in the face of further declines in equity values and gilt yields.
5.8.3 In order to match their liabilities better, many insurance companies sold equities and bought long-dated gilts. This further drove down gilts yields and equity prices and thus drew more companies into a position of having potential difficulties with their solvency position.
5.8.4 The actions of individual companies therefore caused problems for other companies. The initial difficulty was caused by a mismatching of assets and liabilities with relatively low levels of investment in long-term bonds. These companies then acted, thus making the problem worse for others and themselves.
5.8.5 Such an interaction was especially pronounced because of conditions in the gilt market (low government borrowing) which meant that it was difficult to increase long-gilt issuance significantly to satisfy the demands of life insurance companies. These interactions had a systemic impact, damaging a key investment market for the affected companies, because there were no close substitutes to the longest available gilt and the market was particularly illiquid. Efforts to purchase this gilt thus led to price spikes.
5.8.6 A particular form of regulation (which was arbitrary and very narrowly conceived), made this systemic impact worse. The market impact, arising because of the shortage of the longest-dated gilt, was exacerbated by regulatory rules. UK insurance regulators applied a mechanical ‘resilience test’ with a particular focus on year-end valuations which put particular pressure on the limited supply of long-term gilts at that time. This forced institutions to purchase these bonds even when, on purely commercial grounds, they would not have willingly done so.
5.8.7 This problem was largely resolved by changing the rules for the resilience test, thus making the solvency requirements for insurance companies with particular asset and liability structures less onerous.
5.9 Systemic Risk and the Pension System
5.9.1 What would constitute systemic failure for the pension system? According to our definition, a systemic risk materialises when an initial disturbance is transmitted through the networks of interconnections that link firms, households and financial institutions with each other; leading, as a result, to either the breakdown or degradation of these networks. This can and has happened, quite frequently, in banking; but, as we will now argue, it is much less likely to occur in the pension system.
5.9.2 Take funded defined benefit (‘DB’) pensions, for example, for which the securities market is a key network. The stock market might crash and remain illiquid for months. But, as long as pension plan sponsors remain solvent, pensions should continue to be paid. Pension plans have one particular distinguishing feature – their long-term orientation – which enables them to act as a stabilising influence. The long duration of their obligations gives pension funds time to ‘ride-out’ economic and financial shocks – you don't get ‘runs’ on pension funds. Pension funds have small liquidity needs compared to their assets. So, they do not have to sell assets when markets crash; they can rely on the regular flow of contributions and investment income to pay pensions. And, if they are prepared to invest through the business cycle, pension funds can help the economy recover from a shock by supporting cash-calls from corporates and governments. There is still some systemic risk. The application of fair value accounting rules which require pension assets to be marked-to-market can weaken the balance sheets of plan sponsors and this could create systemic problems if these sponsors responded by selling assets at distressed prices. But regulation does not require such sales and this potentially damaging systemic interaction is much less likely to affect DB pensions than the banking or even the insurance industry.
5.9.3 What about unfunded DB pensions, as in the UK public sector? Here, the important link is that between the plan sponsor and the pension beneficiary – the promise and subsequent payment of pensions. Here there is really no network of interconnections at all. But a public sector funding crisis, or a big longevity shock, could still spell disaster for the operation of such pensions. Here the danger of the system collapsing arises from the possibility of a large common shock, rather than from systemic interactions such as have arisen all too frequently for banks in their various networks of asset and funding markets.
5.9.4 And, thirdly, consider defined contribution pensions. Here, substantial declines in stock market prices (perhaps resulting from network failure, e.g. as in the 1987 crash) might devastate the value of pension pots but the system – the purchase of annuities and the payment of pensions – could continue, albeit offering much reduced levels of benefits for those unfortunate enough to retire in the midst of such a crisis. Once again systemic interactions do not undermine the network of connections between defined contribution pension schemes and their owners.
5.9.5 What this discussion indicates is that the pension system is much less vulnerable to systemic risk than the banking system. This is not to say that it cannot still fail or be severely damaged as the result of a large common shock. But major systemic problems are much less likely to originate in the pension system than in banking.
6. Case Studies
6.1 We now turn to four detailed case studies. These are: the international banking and exchange rate crises of the 1930s which accompanied the Great Depression; the Asian banking and exchange rate crisis of 1997; the impact of the equity market crash of 2000–2002; and the current global banking crisis of 2007–2009. We present each case study and discuss the extent to which they were systemic events.
6.1.1 We find that the three banking crises were systemic, with a breakdown of networks of bank financing and of investment assets. The systemic impact of the banking crisis of the 1930s, aggravated as it was by some very inappropriate policy responses, was especially large with a major and long lasting impact on the activity and employment of firms and households worldwide.
6.1.2 Both the Asian banking crisis and the most recent global banking crisis also had major impacts. The large impact of both these crises can be attributed to a combination of structural economic problems and unstable bank financing relationships, including reliance on short-term borrowing. The structural economic problems in both cases were rapid and unsustainable credit expansion with a great deal of lending to uncreditworthy borrowers and with land and property prices rising well above reasonable fundamental levels. But the impact of the reversal of asset prices and credit growth was greatly amplified by loss of confidence in banks and withdrawal of short-term funding. In the case of the Asian crisis this emerged as a collapse of fixed exchange rate arrangement. In the most recent crisis this emerged as a collapse in the pricing and trading of new structured credit products. These events, combined with growing credit losses and economic downturn, undermined bank balance sheets.
6.1.3 In contrast the equity market crash of 2000–2002 did not have a systemic impact. There was a marked slowdown in global investment and growth, with many corporate defaults, but this did not have a further impact on either banks or (despite a major deterioration of net worth) the pension system, which continued to function and carry out obligations to members.
6.2 The Banking and Financial Crises of the 1930s and their Contribution to the International Great Depression
6.2.1 Some of the deepest systemic financial and banking crises and the most severe global economic contraction ever experienced all occurred in the early 1930s. Between March and September 1931 there were both widespread bank failures across much of Europe and in the United States, and a breakdown of the restored international gold standard. This same year also marked an intensification of the ‘Great Depression’ of the 1930s, in which output and employment of many countries, including the United States, Germany, France and Italy fell by far more than in any business cycle before or since. According to Friedman & Schwartz (Reference Friedman and Schwartz1963: 299–300), 1840–1843 is the only earlier US economic contraction of anywhere near a comparable magnitude and this was not so global. No examination of systemic risk would be complete without some discussion of what led to these financial crises (there were several related problems, not just one) and their contribution to the decline of economic activity of that time.
6.2.2 This summary presented here draws on a considerable academic literature investigating these events, to which the current Chairman of the Federal Reserve, Ben Bernanke, has made several substantial contributions. He is also a clear and lucid writer, and his collection of essays on this topic (Bernanke, Reference Bernanke2000), remains one of the best single references on the Great Depression. Chapter 7 of Friedman & Schwartz (Reference Friedman and Schwartz1963) is not just the classic statement of the monetarist interpretation of the Great Depression; it is also an informed and insightful review of financial and economic developments. Finally the economic historian Barry Eichengreen has also made major and readable contributions, especially Eichengreen (Reference Eichengreen1992).
6.2.3 Let us begin with a statement of what happened in the Great Depression. This is a complex story, difficult to set out in only a few paragraphs. It is probably best to begin with the developments in the real economy. During the years 1925–1929, global manufacturing output grew fairly strongly, by around 4% per year. An exception is the UK, where there was little growth after the adoption of the gold standard in 1925 and the General Strike of 1926. Then from 1929 to 1932, global manufacturing output fell by a massive 40% in the course of only three years. The global economic contraction appeared to be stabilising towards the end of 1930. But then in 1931, the decline resumed and gathered pace. The United States and Germany were both hit especially hard, with total industrial production falling to around one half of 1929 levels.
6.2.4 There were substantial differences in individual country experience.Footnote 3 The UK was amongst the least affected by the Great Depression. Although output of traditional manufacturing industries, such as steel and shipbuilding fell sharply, this was compensated by growth of house construction and consumer durables. Overall industrial production in the UK fell only just over 18 per cent. Other countries also experiencing relatively small declines of industrial output (although still steep recessions) include Sweden, Denmark, Japan, Spain and Australia. Industrial output in Italy and France was relatively unaffected in 1930, but then fell sharply by more than 30 per cent in 1931 and 1932. Many other countries, including Canada, New Zealand and Austria suffered to nearly as great an extent as the US and Germany.
6.2.5 What about financial and monetary developments? The popular mind associates the Great Depression with the Wall Street crash of October 1929, and especially with the calamitous trading on ‘Black Monday’ and ‘Black Tuesday’ the 28th and 29th of October. In these two days the Dow Jones Industrial Average declined by more than 30 per cent. In reality, there is only a tenuous link between these two chaotic days of trading and the contraction of the real economy. US industrial output had already peaked in August of 1929 and in fact share prices subsequently recovered, by April 1930, to reach roughly their level prior to Black Monday. The severe and sustained decline in share prices occurred only later and more gradually, after April 1931, as a reaction to the US and international banking and exchange rate problems and the deepening fall in US output and employment. The Dow Jones Industrial Average eventually bottomed out in July 1932, some 89% below the level of April 1930 (and nine months ahead of the trough of US industrial production). Much as in the later stock market crash of 1987, there was rather little direct transmission from stock prices to output and employment. There was probably some impact on confidence, consumer spending and business investment but on its own this would never have created a contraction anything like the Great Depression.
6.2.6 The important financial developments, in terms of their impact on the real economy, were not in stock markets, but in banking and foreign exchange markets. A second indelible image of the Great Depression is of queues of small depositors clamoring on the doors of closed US banks, hoping to retrieve some of their life savings. Banking failures did indeed play a major role in the Great Depression, but it is important to distinguish the experience of the United States from that of most other countries and also to recognise that, while some banks were brought down by depositor runs, many failures were the direct result of other problems, for example large losses on loans and investments.
6.2.7 The most detailed study of US bank failures at that time is Wicker (Reference Wicker1996). His Table 1.1 reports the Federal Reserve data on bank failures (Chart 30 of Friedman & Schwartz (Reference Friedman and Schwartz1963: 309) presents the same data in graphical form). When discussing US bank failures, it must be remembered that the US banking system was then extremely fragmented, in large part because of regulatory restrictions preventing banks operating with more than one branch or in different states. There were some 24,000 banks operating in 1929, most of them extremely small. Small banks are always vulnerable. Bank failures had been common throughout the 1920s, with an average of around 650 banks failing each year, accounting each year for about 0.4% of total US bank deposits.
6.2.8 Then, as the depression took hold, the rate of bank failures increased sharply, averaging 2,750 per year from January 1930 until March 1933, and affecting altogether more than 13% of total bank deposits. Rates of failure were especially high in two panic episodes: in November 1930-January 1931 and in the much more extended panic of April – October 1931. Finally, an even larger number of bank closures took place in February-March of 1933 (these latter closures mostly came about as a result of the governors of various states restricting deposit withdrawals, before banks actually ran out of funds to pay depositors, a restriction which was eventually extended nationwide in the March 1933 ‘bank holiday’ imposed by the newly installed President Roosevelt).
6.2.9 As Wicker points out, the banking problems of the 1930s were very different from those that affected US banking on several occasions before the First World War, during the 19th century ‘national banking era’ and the major panic of 1907. Those earlier panics mainly affected banks in New York, and although they did result in bank runs and failures elsewhere in the country, these generally occurred later and on a smaller scale. During the 1930s, in contrast, banks in New York were largely unaffected by runs and panics; the banking problems of this time affected mostly small local institutions. There were very many failures but all specific to particular localities or regions. For example, during the early months of the second period of panic, from April – August 1931, when the national rate of bank failures was unusually high, more than sixty per cent of these failures took place in Chicago and Cleveland, banks undermined primarily by the severe collapses of real estate prices in these two cities.
6.2.10 The earlier ‘national banking era’ panics of the 19th century were contained through several devices (for example, suspension of deposits and the issue of ‘clearing house certificates’ as claims on liquidity which could be transferred between banks) and resulted in comparatively few failures. In most cases, the economic contractions which accompanied these 19th century US banking crises, while often deep, were relatively short lived and output and employment recovered relatively quickly. In contrast, the banking problems of the 1930s did result in a high level of bank closures and with losses for very many depositors. According to Friedman & Schwartz, this was partly because the creation of the Federal Reserve (Fed) in 1914 had eroded the responsibility of banks and clearing houses for containing panic. The expectation was that the Fed would take steps to prevent bank runs; but when the runs of the 1930s occurred, the Fed failed to take decisive action to prevent the panic. Whatever the reason for the high level of failures, economic activity in the 1930s continued to contract after the various banking crises, rather than recovering quickly.
6.2.11 The banking difficulties in much of Europe, especially Austria, Germany and Hungary, were of a very different character to those of the US and closely linked to international financial arrangements of the interwar years (Eichengreen (Reference Eichengreen1992) provides a detailed account, see especially chapter 9 which describes the banking and exchange rate crises of 1931). In modern jargon, these were ‘twin’ crises caused by a combination of weak banks and unsustainable fixed exchange rates. So, we need first to look at exchange rate arrangements before describing the banking problems and the ensuing financial crises.
6.2.12 Between 1924 and 1927, an international fixed exchange system was restored with most currencies once again pegged to gold, as they had been prior to the First World War. This is documented in Table 7.1 of Eichengreen. The US never left gold, Germany rejoined in 1924, the UK in 1925, France in 1926 and Italy in 1927. By this time, some 30 countries were on gold. Japan and Spain were the only major trading nations not yet to do so and Japan too eventually pegged to gold in 1930.
6.2.13 But while the gold standard had been restored, it did not have the stability of the earlier ‘classical’ gold standard which had operated from the closing years of the 19th century until the outbreak of the First World War in 1914. There were major strains on the restored system. The UK's decision to return to gold at the pre-World War I exchange rate made no allowance for the relatively large post-war inflation in the UK. This meant that sterling was substantially overvalued against other currencies, notably the French Franc and the US dollar, and as a result the UK ran substantial current account deficits in the late 1920s and was the world's largest international borrower, with some £2 billion of short-term deposits held by international depositors in London (this was not all lending to UK borrowers; these deposits also financed loans to international borrowers who came to the London markets to raise finance, but much of this short-term money financed UK borrowing).
6.2.14 Germany continued to carry a heavy burden of reparations from the post-World War I Versailles settlement. It needed to maintain an export surplus, both to pay reparations, and as a condition for qualifying for access to international borrowing and for concessions on remaining reparations. Other countries in Europe and around the world were also major international borrowers. Banks in Germany, Austria and Hungary all relied heavily on short-term deposits from international investors. The major creditor under the restored gold standard was the United States. For example, during the 1920s US investors bought more than $6bn dollars of bonds from European, Canadian, Latin American and Asian issuers (Eichengreen, Reference Eichengreen1992: 151, Table 5.4).
6.2.15 The restored gold standard was in difficulties as early as 1929, especially for commodity exporters who faced the combined difficulties of a slowing world economy, declining prices for industrial and agricultural commodities and a sharp reduction in US lending abroad. Australia, Brazil, Canada and New Zealand all left gold in 1929, and of these only Canada, with the benefit of better access to credit from US investors, was able to restore its fixed exchange rate against gold credibly. Germany too increasingly struggled to maintain its access to international borrowing.
6.2.16 The major breakdown of the restored gold standard came two years later in 1931. The early months saw default on foreign borrowing by many Latin American countries. Then in May, both international and domestic investors lost confidence in Credit-Anstalt, Austria's largest bank, triggering a classic ‘twin’ banking and foreign exchange crisis. Investors had good reason to be concerned. The bank itself was unsound with huge and largely hidden loan losses. But the further reason for the loss of confidence was growing doubts about the ability of the Austrian government to support Credit-Anstalt and, at the same time, maintain the Austrian Schilling against gold.
6.2.17 The crisis played out over many weeks. The substantial withdrawal of international depositors meant that, by the early summer, Austria was running out of reserves of gold and foreign exchange; a considerable turn around since before the crisis these reserves had been regarded as ample. Other major countries – France, Italy and the UK – failed to agree on an international loan to support Austria. Interest rates might have been raised further, to try and attract back international investors, but doing so would have put a considerable further strain on banks and domestic borrowers. The only options were open exchange rate devaluation, or a covert abandonment of gold through the imposition of exchange controls. Eventually, in September, Austria opted for exchange controls, preventing the exchange of domestic deposits for foreign currency.
6.2.18 The Credit-Anstalt crisis immediately triggered similar problems in neighbouring Hungary, whose banks also relied heavily on short-term international deposits. International investors withdrew deposits and there were runs on several Budapest banks. One reason for this contagion was that Credit-Anstalt held a majority stake in the largest bank in Budapest. It was also apparent that, if the major international countries would not lend to Austria, then they would certainly not lend to Hungary, whose position was fundamentally weaker. Hungary had less reserves of gold and international currency and as an agricultural exporter was already financing a large external trade deficit. As early as July, ahead of Austria, Hungary had opted for exchange controls.
6.2.19 The Austrian crisis also spread to Germany and then to the UK. Germany suffered another ‘twin’ crisis with major problems in several major banks combined with a loss of international investor confidence in its commitment to maintain its gold exchange rate. An international loan to Germany of $100m. was arranged in June from the Bank of England, the Federal Reserve and the Bank for International Settlements. But further banking problems emerged the following month – with the failure of two major banks Nordwalle and the Danat Bank – triggering further international outflows, exhausting the international loan, and so preventing the Reichsbank from providing the short-term credit to Danat bank which might at least have prevented its failure. Major concessions on German reparations could still have restored stability, and were indeed proposed by US president Herbert Hoover. But these concessions had to be agreed internationally and were not politically acceptable in France. By the time international agreement was reached in September, Germany too had been forced to introduce exchange controls.
6.2.20 The UK, unlike Austria, Hungary and Germany, had a very sound banking system. Its banks were large and profitable and took few risks, providing few long-term loans to industry and focusing on short-term credit for trade and working capital. They also benefited from their access to the highly liquid London money markets, which helped insulate them from potential deposit withdrawals. But although UK banks were safe and liquid, international investors were concerned about the ability of the UK to finance its large government budget and current account deficits, while also maintaining its exchange rate against gold. This challenge was made worse by political disagreements over how to respond to the crisis, culminating in the fall of Ramsay McDonald's Labour government on August 23rd 1931 and its replacement by an all-party National government, also led by Ramsay McDonald. There was no longer a clear hand in charge and this ruled out the expenditure cuts or tax increases which would have been necessary to close the government budget deficit and establish credibility for UK public finances. The next month, widely reported unrest at a Scottish naval base, Invergordon, became a symbol for the weakness of the UK Government, and this was followed by a resumption of international capital flight on an even greater scale than before. This forced Sterling's abandonment of gold on September 19th 1931, accompanied by many other ‘Sterling block’ countries such as India.
6.2.21 These, in brief summary, are the economic and financial developments which took place during the 1930s. But the bigger questions are the lessons these events have for today. For this we must understand not just what happened but how and why. What led to such a long and deep global slump? To what extent did banking and exchange rate problems contribute to the global economic depression? How far was this a ‘systemic’ crisis as we define such events, in which network interactions played a major role?
6.2.22 Friedman & Schwartz (Reference Friedman and Schwartz1963) is the classic statement of the ‘monetarist’ view of the Great Depression in the US, attributing the crisis in large part to the failure of the Federal Reserve to prevent a collapse in money holdings. Friedman & Schwartz emphasise the collapse in broad money (total bank deposits plus currency in circulation) resulting from the rapid increase in the US ‘currency to deposit ratio’ and the substantial increase of bank holdings of reserves with the Federal Reserve relative to loans (for changes in currency and deposits see Chart 27, of Friedman & Schwartz (Reference Friedman and Schwartz1963), chapter 9). Bank failures affected only a minority of bank deposits but they undermined confidence in banks more broadly and led to substantial withdrawal of customer deposits. Banks also shifted to holding very high levels of reserves to guard against illiquidity and failure. Money multiplier analysis implies that both these developments would lead to a reduction in the total stock of broad money.
6.2.23 According to Friedman & Schwartz, the initial shock of 1929 might have been simply another large, but short lived business cycle recession, if it had not been for the failure of the Federal Reserve to respond to these monetary developments, leading in turn to further falls of expenditure, declining prices and further cumulating reductions in output and employment. Rather than flooding banks with reserves and moving quickly to reduce the Federal Reserve discount rate to as low a rate as possible, the Federal Reserve responded slowly and inadequately. In the autumn of 1931 when the UK left the gold standard, the Federal Reserve even reversed a large part of its earlier discount rate reductions to defend the US dollar against gold.
6.2.24 There has been a huge body of later work on the US Great Depression and the response of policy-makers. One point of controversy has been the extent to which the initial economic downturn in 1929 was monetary, or due to autonomous shifts in consumption and investment. Friedman & Schwartz emphasise the impact of the 1928 increase of the Federal Reserve discount rate, a response to growing concerns about over inflated stock prices and the widespread practice of bank margin lending to finance stock speculation. Others, such as Temin (Reference Temin1976) put more emphasis on increased saving and reduced investment which would have happened regardless of the tightening of monetary policy.
6.2.25 The dominance of ‘Keynesian’ thinking in the economics profession during the post-war years has led many to argue that the Great Depression could have been averted through expansionary fiscal policy rather than expansionary monetary policy. Certainly US fiscal policy remained conservative, with a strong emphasis on maintaining balanced budgets at both state and Federal level and this contributed to the deflationary stance of monetary policy. Some characterise the policies of the Roosevelt administration, from 1933–1939, as Keynesian. This is mistaken. Roosevelt had no consistent approach to economic policy making. He tried a wide variety of different, often conflicting measures. The key decisions which accompanied the beginning of recovery in late 1933 were not programmes of public works, but the decision to end the convertibility of the US dollar against gold, and subsequent steps to raise the US dollar price of gold, together with the accompanying abrogation of gold clauses which pegged many US bond repayments to the dollar gold price. The other main economic policy of the Roosevelt era, which probably dampened rather than encouraged economic activity, was widespread price regulation. Keynesian policies of large-scale government expenditure might have helped increase output and employment, but such policy was not pursued in any consistent way, at least not before the global re-armament of 1938 and 1939.
6.2.26 The past twenty five years has seen a resurgence of scholarship on the economics of the Great Depression. This has led to a new understanding of the major role of international economic relations and of the restored gold standard in the Great Depression. There was not just inappropriate domestic monetary policy making in the US but a much more widespread failure in the co-ordination of international policy, creating a bias towards deflation and contraction.
6.2.27 As Eichengreen (Reference Eichengreen1992) argues, the restored gold standard of the 1920s had instability built into its foundations, both because of substantial exchange misalignment and, equally importantly, highly asymmetric responses to financial difficulties. The responsibility of responding to payments imbalances fell on countries such as Germany and the UK, experiencing structural outflows of gold, rather than on surplus countries such as the US and France experiencing inflows. These deficit countries had to contract their money supplies and domestic expenditure instead of surplus countries expanding their money supply and domestic expenditure. This asymmetry played a major role in the international spread of the Great Depression, prior to the 1931 crisis, when international gold flooded into France, but the Banque de France sterilised these gold inflows, selling government bonds to finance its acquisition of gold and so preventing any expansionary monetary policy response. In contrast in the 19th century, there was a political consensus on the need for surplus countries to accept responsibility for allowing gold inflows to translate into monetary expansion and allow the classic ‘gold specie flow’ mechanism to restore international equilibrium. This built in a bias towards contractionary policies which in the 1930s was further exacerbated by increasing tariff barriers discouraging international trade and investment and highly conservative fiscal policy.
6.2.28 These problems of international financial co-ordination persisted even after 1931, when many major countries left gold. As the work of Eichengreen & Sachs (Reference Eichengreen and Sachs1985) and Bernanke & James (Reference Bernanke and James1991) has documented, the countries which left gold relatively early such as the UK, Japan and Sweden experienced a shallower downturn and a relatively rapid recovery, compared to countries such as the US and France which maintained their gold parity through the Great Depression.
6.2.29 Another key issue (see Bernanke & James, Reference Bernanke and James1991 and Bernanke, Reference Bernanke1995) was the failure of nominal wage adjustments to lead to increased employment and output. According to standard economic thinking, widespread unemployment should have led wages to fall relative to prices, and this decline in the real wage should, eventually, have led employers to expand their employment. So the puzzle is not just the depth of the Great Depression (this can be explained by contractionary monetary policy at a global level), but its persistence. After the global economy stabilised in 1933, why was recovery so shallow in so many countries? This problem has not yet been resolved satisfactorily. There are two main explanations. The first is the damaging impact of fixed nominal debt in an environment of falling prices (deflation). The consequence was a major increase in the real burden of debt making it very difficult for firms to obtain finance for expansion, despite lower real wages. The second explanation is that the wage adjustment was itself inadequate. It has been noted that the fall in real product wages (wages compared with the price of industrial output) did not fall anything like as much as real consumption wages.
6.2.30 Another factor may have been that the combination of unfavourable circumstances may have shifted the economic outcome towards a new and undesirable low output equilibrium. There were several individual circumstances which lowered demand and output, including the aggregate impact of the international financial arrangements which introduced a bias towards contractionary monetary policy at a global level, rising debt burdens, pessimistic expectations and uncertainty (Romer, Reference Romer1990) and inadequate wage adjustments. The combination of all these circumstances may have ‘trapped’ the US and other economies in a low output depressed state.
6.2.31 Were the financial and economic crises of the 1930s systemic, in the sense that we have defined such events, with a breakdown or degradation of the networks of interconnections between firms, households and financial institutions? The answer is yes, in several respects. Our earlier discussion has identified four networks of interconnections linking banks to firms, to households, and to each other: payment systems; reliance on short-term funding and deposits; common exposures to assets; and counterparty exposures leading to ‘contagion’ effects. Major breakdown or degradation occurred in at least two of these networks and in many countries.
6.2.32 There was a collapse of the short-term deposit markets, both internationally and at least within the US for domestic retail deposits. Common exposure, notably to commercial and residential real estate and to corporate bonds, also played a major role in undermining banks, again an interaction which was especially marked in the US. As a result in some countries (but not all – the UK is an obvious exception) there was a major negative decline of property and other asset markets, substantially curtailing access to bank credit.
6.2.33 A further feature of the systemic and financial crises of the 1930s was the exceptionally unfavourable institutional and political environment. Lack of political commitment and the consequent failure of international policy co-ordination under the restored gold standard, provided a major deflationary bias to the international monetary system (Eichengreen, Reference Eichengreen1992). Policy-makers in the United States and elsewhere were wedded to strict monetary and fiscal discipline, at a time when the situation demanded at least a temporary relaxation of policy. While there is no clear evidence, uncertainty and lack of commitment by policy-makers may also have contributed to the system wide weakness of both labour markets and financial markets.
6.2.34 As a final question, it is worth briefly asking what was the position of the life insurance and pension sectors in the 1930s? We are not aware of detailed research on this topic. It appears that there were no systemic financial problems of that time to any large degree. Indeed, the failure of life insurance companies in the UK was virtually unknown between 1870 and 1945. A limited impact on the insurance and pension sectors would not be surprising. The pension system was immature. Pension funds were smaller then than today and had not yet built up large liabilities for payment to members. Insurance funds were primarily invested in government bonds and so not so much exposed to the decline of real economic activity. But we have not made a concerted effort to trace the experience of the insurance and pension sectors in the inter-war years. Problems may have arisen in some countries of which we are unaware.
6.3 The Asian Crisis of 1997
6.3.1 We now move on to a much more recent crisis (this section draws on Milne, (Reference Milne2009) chapter 3, which also discusses and compares some other banking crises, those from Latin American lending in the 1980s and in Scandinavia and Japan in the 1990s). In July 1997, a dramatic and almost entirely unanticipated banking and financial crisis struck Thailand, Indonesia, Malaysia, the Philippines and South Korea, forcing them into substantial exchange-rate devaluations, imposing major currency losses on many of their domestic banks and exposing large amounts of non-performing loans. Thailand, Indonesia and then South Korea turned to the IMF for financial support, accepting tough conditions on their monetary and fiscal policies until this lending was repaid. The Philippines expanded an IMF programme already in place before the crisis. Only Malaysia managed without IMF money, but could not avoid a painful economic slowdown. In all these countries, investment collapsed and growth fell well below trend for the next two years. The crisis also affected other Asian economies, such as those of Hong Kong, Singapore, China, and Taiwan, and weakened investor confidence in all emerging markets.
6.3.2 As Table 2 indicates, these events had a very large domestic impact, both on the banking sector and on the wider economy. Both the loan difficulties and the fall in output were very large, compared with the crises in other larger countries listed in Table 1.
6.3.3 The Asian crisis was produced by a combination of fundamental problems – in this case the use of bank borrowing for too many uneconomic and unproductive investments – with unstable short-term financing arrangements. Banks and investors, placing a somewhat naive faith in the continuation of business as usual, were unaware of their exposure to a disturbance of the entire system. The speed of subsequent developments took them entirely by surprise. A relatively small initial shock – the emergence of losses in the smaller, lightly regulated Thai finance houses – cumulated in a major global financial disruption. There was contagion, the initial shock undermining investor confidence, not just in Thailand but in all the countries that had absorbed large sums of short-term portfolio investment, exposing the fragility of banks and exchange-rate arrangements across the region. But the withdrawal of investor funds and crisis of confidence was greatly overdone; within a couple of years strong growth resumed in all these countries, exchange rates appreciated and the capital flight that undermined them was reversed.
6.3.4 The countries directly affected by the Asian crisis are very diverse. At one extreme is Indonesia, with a vast population of 221 million people and exceptionally rich natural resources, but with poor communications and transport and great ethnic and linguistic divisions. The Philippines is somewhat smaller, with 83 million people, and lacking natural resources, but with similar problems of transport and communications and frequently battered by tropical storms. The Philippines also has a large number of citizens working as migrants in other countries and remitting their earnings back home. Both Indonesia and the Philippines have average per capita annual incomes of less than $1,000. At the other extreme is South Korea, a rich manufacturing country and a member of the club of industrial nations, the Organization for Economic Co-operation and Development (OECD), with its population of 48 million enjoying an average per capita annual income of close to $20,000. Thailand and Malaysia are middle income countries, with populations of 64 million and 25 million and average per capita annual incomes of around $2,000 and nearly $4,000 respectively, based on successful exports of light manufacturing, clothing, textiles, electronic assembly, agriculture and tourism.
6.3.5 What these five countries had in common was rapid economic growth (especially in Thailand, Malaysia and South Korea), high savings ratios of around 30 per cent of GNP (but a lot lower in the Philippines, at 18 per cent) and fixed investment close to 40 per cent of GNP (the Philippines again a lot lower, at just over 20 per cent). The increase in output and incomes has been mostly based on the exploitation of low labour costs through high levels of savings and physical capital investment. A productivity improvement was not the main source of growth, with much of the fixed capital investment yielding rather low rates of return.
6.3.6 In all these countries the financial sector had been relatively underdeveloped, with low levels of share ownership and equity trading. Most companies remained family-owned or, as in South Korea, part of the large family-controlled industrial conglomerates known as chaebol, and relying on bank debt rather than equity for external financing. Standards of bank credit assessment were weak, with little tradition of analysing business plans or using credit analysis to assess the ability of borrowers to repay. Lending decisions were instead usually based on personal connections, and credit protection relied largely on collateral, such as land or property.
6.3.7 The reliance on bank lending for financing these high rates of fixed capital investment resulted in a very large increase in the stock of bank loans, mainly to companies rather than to households. Between 1990 and 1997, bank loans to the private sector increased from 65 per cent to 116 per cent of GDP in Thailand, from 100 per cent to 145 per cent of GDP in South Korea and from 71 per cent to 108 per cent of GDP in Malaysia. The Philippines and Indonesia had more modest levels of bank lending, but there, too, total lending had expanded rapidly and problems of inadequate credit controls were especially severe in Indonesia, where much bank lending was politically directed to cronies of the Suharto regime.
6.3.8 The sustainability of bank lending and the quality of bank credit assessment did not seem to be an immediate concern in the highly successful export-orientated economies of Thailand, Malaysia and South Korea. They were all enjoying rapid and sustained economic growth with real incomes rising at between 6 and 8 per cent per annum – no need to worry too much about the business plans of customers when revenues and asset values were so buoyant. Current account deficits, especially in Thailand and Malaysia, were uncomfortably large, and some of the South Korean chaebol had become unprofitable because of their rising labour costs. At some point, with prospects for growth slowing, bank lending would have to be allocated more efficiently. But there seemed to be no urgent need to starve customers of funds in the name of maintaining high standards of credit assessment, because the fundamentals supporting economic growth still appeared to be very strong.
6.3.9 Fundamentals alone do not explain the Asian crisis. The dramatic reversal of investment and growth would not have occurred without excessive reliance on short-term foreign currency borrowing exacerbated by mistakes in macroeconomic management. The macroeconomic mistake was the policy of capital account liberalisation combined with the maintenance of a fixed exchange-rate peg against the US dollar (which was maintained despite an incompatible monetary policy) and the subsequent misguided efforts to maintain these pegs against an overwhelming outflow of capital. The removal of capital controls in the 1980s was beneficial. It encouraged capital inflows and thus bridged the gap between high domestic savings rates and even higher rates of fixed capital investment. Since the countries of south-east Asia had an impressive record of growth, high domestic savings rates and generally modest fiscal deficits, there was little reason to believe that they could not maintain fixed exchange rates for a long time to come. The stability and apparent sustainability of their exchange rates encouraged large-scale inward portfolio investments from international investors looking for exposure to emerging markets. Fixed exchange rates also had another, much less desirable, effect. They encouraged local banks to use short-term foreign currency borrowing for financing their long-term domestic lending.
6.3.10 Domestic interest rates remained as much as 5 per cent above dollar rates of interest on global financial markets. Better to pay 5 per cent for foreign currency borrowing than 10 per cent for domestic currency deposits. If the money was lent out to domestic borrowers at, say, 14 per cent, then the interest margin – the profit on the lending provided that there is no default – would be 9 per cent rather than 4 per cent. This additional lucrative interest margin was an irresistible temptation.
6.3.11 How could domestic interest rates remain so much higher than dollar interest rates when the exchange rate was pegged and capital controls had been removed? The proximate reason was relatively high domestic inflation, with economic growth outrunning domestic productive capacity and consumer prices rising at around 5 per cent per annum compared with less than 3 per cent in the United States. This meant that domestic interest rates had to be kept relatively high to restrain domestic borrowing and help keep a lid on inflation. The more fundamental reason was a largely unappreciated devaluation ‘risk premium’, the ‘peso problem’ described at section 3.3.2.
6.3.12 The temptation to use foreign-currency funding for domestic lending was irresistible and was carried to an extreme in Thailand and South Korea. The foreign-currency borrowing of the Thai banking sector reached some 25 per cent of GNP. Much of this was financed through the Bangkok International Banking Facility, which allowed foreign-currency borrowing and lending by Thai-based institutions. The thinking behind this facility was to make it possible for Bangkok to compete with Hong Kong and Singapore as a regional centre for international banking, but in practice it was primarily used by local banks to fund their domestic lending. South Korea was even more exposed, with short foreign-currency bank exposures of over $100 billion, close to one third of GNP.
6.3.13 This highly unstable arrangement, using substantial amounts of short-term foreign-currency borrowing to finance long-term domestic lending, set the stage for the extreme financial crisis that followed. The trigger was the emergence in the first half of 1997 of problems among the relatively small Thai finance houses. These lightly regulated banks had financed a booming Thai real-estate market and were heavily involved in securities finance and other relatively risky exposures. The cooling of the Thai real-estate market in early 1997, resulted in the failure of the largest of these finance houses, Finance One, whose assets of $4 billion ranked it in about twelfth place among all Thai banks. Finance One was merged with a larger Thai bank, but the problems of the finance houses were not fully resolved, and increasing doubts emerged about the sustainability of the peg of the Thai baht against the US dollar.
6.3.14 At first it appeared that the Thai authorities could contain these problems and maintain the currency peg. The Bank of Thailand reported large foreign-currency reserves which could be deployed to maintain the fixed exchange rate. They successfully fended off an initial speculative attack on the currency on 14 and 15 May 1997. But the published statistics did not reveal the very large hidden commitments by the Bank of Thailand for purchase of the Thai baht using the currency forward market – in effect the large majority of foreign-currency reserves had already been deployed in defence of the currency. While the scale of these forward positions was not in the public domain, domestic and international investors were well aware that the currency was vulnerable and capital flight out of the baht into dollars continued. Then, on 2 July 1997, in the face of a renewed speculative attack, the Bank of Thailand ran out of ammunition, and the currency peg was abandoned.
6.3.15 What then followed was a financial whirlwind. Within days the currency pegs of Malaysia, Indonesia and the Philippines also collapsed. The Thai baht, the Malaysian ringgit and the Filipino peso all depreciated, falling by around 40 per cent against the dollar over the subsequent six months, and the Thai government arranged a large loan facility of $17 billion from the IMF. The Indonesian rupiah fell alongside the other currencies and Indonesia borrowed an even larger $40 billion from the IMF. But the Suharto regime's legacy of corruption, mismanagement and political uncertainty made it much more difficult to control the situation, and there followed a rapid monetary expansion, rising inflation and continued currency depreciation, with the rupiah eventually falling by an astonishing 80 per cent. South Korea held out for longer; its external deficits were clearly manageable and this allowed it to maintain the won peg for some months, but growing financial problems among many of the chaebol and the large amount of short-term foreign borrowing by South Korean banks led to a sharp depreciation in November 1997 of the South Korean won, which eventually also fell by around 40 per cent, and South Korea also turned to the IMF, receiving a huge loan package worth $57 billion.
6.3.16 Somewhat controversially, as a condition of its lending, the IMF imposed the conventional remedies of higher interest rates and tight limits on government borrowing. In the first months of the crisis, Thailand and South Korea raised their domestic interest rates to over 20 per cent and Indonesian rates, in the face of very high inflation, went much higher still. Government expenditure was redirected to dealing with the problems of bank balance sheets, offering banks funding (both loans to compensate for the withdrawal of foreign funds and guarantees of bank liabilities), closing a number of weaker institutions, acquiring and recapitalising others, and setting up holding companies the Indonesia Bank Restructuring Agency (IBRA), the Malaysian Danaharta, the Korean Asset Management Company (KAMCO), and the Thai Asset Management Company (TAMC) to manage non-performing loans transferred off bank balance sheets. The direct government expenditures on bank recapitalisation were relatively small, working out at around 2 per cent of GNP. The much bigger budget item were the loans and guarantees to banks, reaching 25 per cent of Indonesian GNP, 15 per cent of South Korean GNP and, astonishingly, nearly 40 per cent of Thai GNP.
6.3.17 The loss of investor confidence and the withdrawal of capital by both domestic and foreign investors resulted in substantial falls in investment, output, expenditure and employment. In 1998 fixed capital investment fell by more than one third in Indonesia, by one quarter in Thailand and by a fifth in South Korea. Economic output was down 17 per cent in Indonesia, 8 per cent in Thailand, 7 per cent in Malaysia and 16 per cent in South Korea. Domestic expenditure fell even more, by as much as 21 per cent in Thailand and 22 per cent in South Korea, as economic activity was reoriented towards export markets. Recorded unemployment rates rose sharply across the region, from less than 2 per cent to over 6 per cent. The contraction was severe but the trough was reached after about a year and sustained growth then resumed; for example, South Korean output rose by 9 per cent in 1999, boosted by the exchange-rate depreciation and by strong global demand and growing regional trade.
6.3.18 These are the bare statistics. They do not communicate the panic and confusion of global investors during 1997 and 1998 and the huge uncertainties about the financial systems of the Asian economies. What was behind these astonishing exchange rate movements? These were driven both by the absence of reliable information and by an exceptionally powerful feedback loop. The collapse of the exchange-rate pegs and subsequent currency depreciation undermined bank balance sheets. This in turn led to increasing doubts about the viability of local financial institutions and withdrawal of funds, provoking a capital flight that in turn exacerbated the exchange rate depreciations.
6.3.19 Dealing with this situation required large-scale government restructuring and support for the banking sector. Malaysia, Indonesia and South Korea moved quickly to deal with bank balance sheets. They provided large-scale guarantees to prevent rapid withdrawal of funds. They introduced improved bank accounting procedures to prevent banks hiding the extent of their difficulties and strengthened the legal arrangements for dealing with corporate bankruptcies.
6.3.20 Once loans had been written down to realistic values, the Indonesian and South Korean governments took a large proportion of non-performing loans off balance sheets, in exchange for government bonds, and transferred them to state-owned resolution companies. Banks were recapitalised, mostly using state funds. Malaysia had a relatively small stock of non-performing loans, but these were also transferred into a state-owned asset management company.
6.3.21 Thailand also provided guarantees to stabilise its banking sector, and closed down almost all its finance houses. Bankruptcy laws in Thailand remained weak, however, and the Thai government was relatively slow in dealing with non-performing loans and the recapitalisation of its banks, delaying until 2001 before establishing its own asset management company to transfer loans off bank balance sheets. But in all five affected countries, a combination of government support for their financial systems, substantial exchange-rate depreciation and strong growth in the world economy led to relatively rapid economic recovery.
6.3.22 As we define it, the Asian crisis was, clearly, also a systemic event with a breakdown of the network of interconnections which linked financial institutions with international depositors and with domestic customers. Both deposit and lending markets effectively broke down, for a period of months. There was a considerable overreaction, a withdrawal of funds and a consequent fall in investment and output far greater than was required to correct the growing imbalances of the south-east Asian economies. But this overreaction was unavoidable because of the underlying weaknesses of financial arrangements. Both banks and industrial companies were used to relying on leverage and short-term funding for growth, paying little attention to governance and avoiding external disciplines which might have restrained them during the rapid economic expansion. In addition, the resulting absence of transparency for both banks and industrial companies made it next to impossible to identify investment opportunities in the midst of the crisis or to work out which were solvent and viable and which were not. Good and bad alike paid the penalty when capital withdrew.
6.4 The Equity Market Crash of 2000–2002 and its Impact on the Pension System
6.4.1 We have looked in our case studies, so far, at two systemic banking crises. What about other segments of the financial system? Is the pension system, for example, vulnerable to systemic risk, as we define it? It has, after all, suffered some severe shocks in recent years.
6.4.2 Between 2000 and 2002, the pension system suffered a triple whammy – a ‘perfect storm’ of falling stock markets, increased life expectancy projections and low interest rates. As a consequence, the value of pension assets fell, and the present value of pension liabilities increased. Defined benefit (DB) pension deficits soared, resulting in large cash calls on many plan sponsors just when cash was in short supply, and defined contribution (DC) pension pots were much reduced.
6.4.3 The effects of this triple shock on the market capitalisation of DB plan sponsors increased because of the gearing effect of pension deficits on company balance sheets (DB pension deficits are debt; increased debt increases financial gearing; and financial gearing increases the sensitivity of a company's equity to financial and economic shocks). Furthermore, because DB pension funds have cross-holdings in one another's sponsors, a positive feedback loop was triggered in which the shock to company valuations lowered DB plan asset values which further reduced company valuations; and so on in a downward spiral.
6.4.4 Figure 1 illustrates the estimated effects of this shock on the aggregate funding status of the FTSE 100 Company DB pension schemes, based on their financial statements’ disclosures.
6.4.5 Many DB plan sponsors reacted to this shock by amending the terms of their pension plans – raising retirement age, reducing future benefits or increasing contributions. Some switched from DB to DC plans. But DB pension plans continued to deliver. And, as stock markets recovered, so did the funding status of most pension plans. By mid-2007, with the help of additional contributions, there was, as Figure 2 reveals, an aggregate FTSE 100 Company DB pension surplus.
Aggregate FTSE 100 Company DB pension surplus (deficit).
Source: Watson Wyatt Pension Deficit Index

6.4.6 The 2000–2 stock market crash was a shock to the pension system. But was it a systemic event? According to our definition, it was not a systemic event because there was no breakdown or degradation of the networks which link firms (plan sponsors), financial institutions (pension funds) and households (pension beneficiaries). This is not surprising. The defined benefit pension system is exposed to only one of the four networks of interconnections which we identified earlier, in section 4.2 – common exposure to securities and derivatives markets. And in 2000–2, these markets remained liquid, despite heavy price falls.
6.4.7 In 2007/8, as Figure 3 shows, pension funds were again hit by financial market turbulence. The decline in equity returns in 2008 was similar to that in 2000–2, but much faster. Between January and December 2008, there was an 18% ($5.4 trillion) fall in the value of global pension assets (IFSL, 2009).

6.4.8 In 2008, DB plan sponsors and their pension funds had common exposure not just to falling stock markets but also to an economic recession. There was degradation of some of the markets – those for mortgage backed securities and private equity funds – in which some assets held by pension funds are traded.
6.4.9 Despite this network damage, the pension system continues to function. Eventually, it will recover although, because of a widespread switch from DB to DC pensions, it will, arguably, settle at a lower level of operational efficiency – a new equilibrium. There are obvious concerns about how adequate the pensions it delivers will be and there could be further erosion of DB arrangements, with closure to existing members as well as to new employees. But households and employers will continue to make pension contributions and pensions will be paid at some level.
6.5 The Current Financial Crisis
6.5.1 This sub-section, drawing especially on Brunnermeier (Reference Brunnermeier2009) and Milne (Reference Milne2009), provides a brief review of the current financial crisis, emphasising how it has been intensified through the various feedback loops running through both asset and funding markets. These accounts, relative to many others, emphasise the role of unstable wholesale funding and the withdrawal of short-term ‘hot money’, leading to illiquidity of mortgage backed securities and the degradation and eventual collapse of wholesale money market intermediation. These were major systemic events – as we define systemic – and they greatly amplified the impact of the initial losses incurred on US sub-prime mortgage lending.
6.5.2 We are still rather close to these events. A distance of time and fuller research will allow a much better understanding of what has taken place. Still it is worth emphasising these systemic aspects of the current crisis. Most accounts have stressed the weaknesses of loan underwriting, especially to US sub-prime mortgage borrowers; and the willingness of market participants to accept relatively risky exposures, perhaps driven by high levels of bonus for short-term performance. But without the systemic interactions highlighted here, this excessive risk taking would not have led to the major global financial disturbance which has in fact occurred.
6.5.3 Brunnermeier (Reference Brunnermeier2009) traces how the initial increase in delinquencies in subprime mortgages led to a liquidity crisis, primarily because of a mismatch in the maturity structure of banks’ off-balance-sheet vehicles and of hedge funds. The new aspect of this crisis was the extent of securitisation. Financial products were more opaque; the exposure of banks to such products were more difficult to value. This created uncertainty which led to spillover effects in markets not directly linked to subprime mortgages. He highlights three important amplification mechanisms which explain why the mortgage crisis has caused such large dislocations and turmoil in the financial markets. The first mechanism involves liquidity spirals which arise from deterioration in borrowers’ balance sheets. When banks lose money from a decline in the market values of assets on their balance sheet, then typically this leads them to reduce their exposure to these assets. If there are no other banks or other institutions ready to purchase at a small price discount, this can then trigger a spiral of falling prices and reduced asset holdings. A second amplification mechanism works through the lending channel. Uncertainty about future funding needs, combined with potentially limited access to the interbank market, can lead to the hoarding of cash and to interest rate surges in the interbank market. A third mechanism which became especially powerful in the autumn of 2008 was runs on financial institutions.
6.5.4 These developments should be seen in the context of the shift by banks in many countries from retail to wholesale funding (see Milne, Reference Milne2009). Banking statistics give some idea of the magnitude of the shift from retail to short-term wholesale funding. In the United Kingdom the ratio of retail bank deposits to total bank lending fell from just over 100 per cent in 1970 to only 50 per cent by the middle of 2007 – nowadays for every £1 of lending, UK banks ‘rent’ 50p of funding from wholesale financial markets. A similar shift has taken place in most large developed countries. Retail deposits, as a percentage of total bank lending, fell over the same period from 102% to 76% in France, from 110% to 61% in Italy and from 136% to 77% in Australia. Canada also experienced a large decline, from 177% to 112%, but as this figure for 2007 reveals, their banks still have a relatively large retail deposit base relative to their total lending.
6.5.5 The increasing reliance of banks on wholesale funding has a macroeconomic dimension. It is the flip side of what are known as the global current-account imbalances, with large amounts of saving in some surplus countries, such as China, Japan and Germany, matching the borrowing in deficit countries such as the United States, the United Kingdom and Spain (Wolf (Reference Wolf2009) also emphasises the role of international capital flows in the current and previous financial crises). Wholesale borrowing by banks plays a key role in channeling this international flow of savings to borrowing households in deficit countries.
6.5.6 Among banks in the largest G8 developed economies, only banks in Japan and in Germany have not experienced a major shift in funding from retail to wholesale sources. The ratios of retail bank deposits to total bank lending in Germany rose from 87% in 1970 to 94% in 2007, and in Japan from 126% to 143% over the same period. It is no coincidence that the three G8 countries whose banks rely least on wholesale funding, Germany, Japan and Canada, are major exporters of manufactured goods or (in the case of Canada) of natural resources. Unlike the other five G8 countries, all three have enjoyed current-account surpluses.
6.5.7 Wholesale funding is more expensive than retail and increases the risk of banking instability. Wholesale investors lend large sums of money and so will only lend when the interest rate is attractive. Moreover, and for good reason, wholesale funders are sceptical about the ability of bank managements to manage their business and avoid major problems. Because of this opaqueness, investors ask for a considerably higher return for lending money to banks long-term (through purchasing bonds or holding capital instruments) than for short-term deposits. It is also arguable (see Farhi & Tirole (Reference Farhim and Tirole2009) for a theoretical analysis) that short-term wholesale deposits are relatively inexpensive because investors anticipate the support of the financial authorities in the event that the bank is in difficulties. Whatever the reasons, short-term deposits are a considerably cheaper form of banking funding than long-term bond issues.
6.5.8 Short-term funding is cheaper still if it is collateralised funding, with a claim on a government, corporate or structured security. This is why banks turned to the new structured credit instruments – that is, loans packaged into securities. They could use these securities, created out of their own loans, as collateral for short-term funding. This was rather like a high street shop pledging its own shelf inventory in order to obtain credit.
6.5.9 The analogy is not exact. The banks created pools of loans and bundled them up inside tradable mortgage- or asset-backed securities. The owner of these securities could not seize the bank loans if there was no repayment. What they had instead was a legal claim to the interest and principal payments due on the underlying loan pool. But this still gave the investors some confidence that they would be repaid. And as long as there was a liquid market for these structured securities they knew that they could obtain their money almost immediately. This meant that banks could attract and keep wholesale funds by selling or lending these loan-backed securities.
6.5.10 Some mortgage banks, such as Countrywide in the United States and Northern Rock in the United Kingdom, financed a very high proportion of their lending by selling these loan-backed securities. These are extreme examples, but most banks in countries with high levels of household borrowing also relied on loan-backed securities to obtain the funds for their lending.
6.5.11 The demand for borrowing was encouraged in the US by the policy of the US Federal Reserve, under its then chairman Alan Greenspan, during the years 2002–7, when interest rates were kept at very low levels following the puncturing of the ‘dot-com’ stock market boom in 2000, the emergence of the accounting scandals at Enron, WorldCom and other giant firms and the 9/11 terrorist attacks on the United States in 2001. With the benefit of hindsight we can see that this policy helped fuel the expansion of credit and another unsustainable asset price bubble, this time in US housing markets, but there was no obvious reason to expect as sharp a credit contraction as we have now experienced. The reason for the very sharp contraction has been the reliance on wholesale funding for financing the credit boom, especially at short maturity wholesale finance.
6.5.12 As Brunnermeier emphasises, another response to the shortage of bank retail funding has been to bypass altogether the role of banks in holding and funding loans, again using structured credit securities (so called ‘shadow’ or ‘parallel’ banking). A pool of loans, bought from banks or brokers, is bundled within a tradable security which can then be sold to banks or investors. The difference is that the originating bank or broker, that made the initial loan, no longer has any involvement in the securitisation. It has gone entirely ‘off balance sheet’. Not all securitisations happened this way. This bypassing of banks has happened to only a small extent with retail loans (US sub-prime mortgage lending has been the main exception, in other cases originating banks retained a major share of the issued securities, especially the more junior higher risk tranches). But such parallel banking has become a very important tool for the funding of corporate credit. Again, most of these securities were purchased by banks and were mostly funded using short-term ‘hot money’.
6.5.13 Other banks used these securities in a quite different way, as buyers rather than sellers, acquiring large investment portfolios of mortgage-backed and other structured securities. Very often they took a ‘hedge fund’ approach to these investments, financing them using short-term wholesale funds, most often using so-called ‘sale and repurchase agreements’ or repo. Many of the securities purchased by many banks have actually been rather remote from risk of default. Provided that they were at the ‘top of the pile’ in terms of seniority, then losses on underlying loan portfolios would have to rise to extraordinarily high levels to trigger defaults on these senior AAA-rated securities. Milne (Reference Milne2009) estimates that global bank holding of these senior AAA-securities, financed using repo or other short-term sources of funds, amounted to at least $3trillion dollars, or over 20% of US gross national income.
6.5.14 A repo works as follows. The bank which owns a mortgage-backed or other security agrees to sell it on a temporary basis to a ‘hot money’ investor, with an ironclad legal agreement to buy it back at a slightly higher price, say two weeks or one month later. This is, of course, equivalent to borrowing the money for two weeks or one month on a short-term secured basis. Such repo borrowing is now by far and away the most important form of short-term finance in modern financial markets. Banks, erroneously, assumed that repo finance collateralised against mortgage-backed securities would always be available. That proved not to be the case when investors lost confidence in these securities.
6.5.15 This practice, borrowing short-term wholesale funds on a very large-scale to finance portfolios of mortgage-backed and other structured securities, created substantial maturity mismatch. Banks were pursuing a very old banking stratagem, using relatively low-cost but unstable short-term borrowing to hold what turned out to be illiquid long-term securities. They thought they were safe. There appeared to be liquid markets in which these instruments could be bought and sold. As long as the long-term assets were liquid, short-term repo borrowing would always be available to finance them.
6.5.16 Banks and regulators alike failed to recognise the fallacy of composition on which this funding strategy rested. What was safe for an individual bank – borrowing short to hold long-term safe senior marketable structured credit securities – was far from safe for the banking sector as a whole. Such short-term wholesale funds are still ‘hot money’ that can be withdrawn at the slightest provocation. The ability of one bank to sell always depends on the presence of other banks willing to buy.
6.5.17 This then set in train the crisis that followed, a crisis characterised by what engineers call a ‘positive feedback loop’, when an initial disturbance has an effect which then feeds back, reinforcing the initial disturbance (see Mishkin (Reference Mishkin2009) for a similar analysis of the current financial crisis in terms of feedback loops).
6.5.18 Figure 4 (this is Figure 1 from Milne, Reference Milne2009, chapter 1) illustrates the damaging positive feedback which has undermined the world's banking system, since the summer of 2007. In this figure there are in fact two positive feedback loops, each reinforcing the other. The first positive feedback loop, on the left-hand side of the figure, is between the volume of lending and the levels of consumer expenditure and corporate investment. Lower lending leads to less consumer expenditure and corporate investment – that is, a recession. The recession increases credit impairment (the banker shorthand for arrears on payments of loan interest and principal). Rising credit impairment makes bankers more concerned about the risk of default and so less willing to make loans. So bankers reduce lending further, deepening the recession.
Positive feedback loops in bank funding and loan markets.

6.5.19 The second positive feedback loop is within wholesale funding markets. Rising credit impairment leads to write-downs of the values of mortgage and other loan-backed securities. This write-down of value leads to a withdrawal of short-term repo funding. The withdrawal of repo funding leads to a collapse of trading, with no buyers and no sellers. The collapse of trading volumes leads to further write-downs in the values of the securities and further withdrawal of repo funding. The withdrawal of repo funding leads to a reduction of bank lending. The presence of this second feedback loop is what has made this banking crisis so different from previous crises.
6.5.20 The presence of this second positive feedback loop in bank wholesale funding markets has substantially increased bank write-downs. The initial disturbance was increasing credit impairment (arrears) on US sub-prime mortgage lending. Because of the positive feedback loop in wholesale funding markets and the consequent withdrawal of short-term funding, the value of mortgage-backed securities fell by much more than could be justified by the credit impairment. The increasing illiquidity of the markets for mortgage-backed and other structured securities meant that no one had much idea what the market value of these securities was, and accountancy procedures for ‘marking to market’ turned instead to using extremely conservative hypothetical valuations (‘if you were to observe a trade of this security today, then what price might it trade at?’). Valuations fell markedly and investors suffered very large ‘liquidity losses’. Eventually these losses will be recovered, since the valuations of most of these securities have fallen far below even the most pessimistic assessment of eventual repayment from the underlying loan pools. But banks will have to wait a long time for recovery, and in the meantime they have suffered much larger ‘mark to market’ write-downs on US sub-prime mortgage and other loan-backed securities than they ever thought possible.
6.5.21 This wholesale funding loop explains the global nature of the crisis, and why the financial crisis and economic downturn is affecting banks in virtually all countries around the world at the same time. Many banks, notably in Germany, invested surplus retail funds in the high-yielding US mortgage-backed securities and the other structured credit products whose value has collapsed because of the withdrawal of wholesale funding. Many other banks around the world relied on the issue of mortgage-backed and other loan-backed securities in order to expand their lending and make up for a shortage of retail funding. Once the markets for these new issues closed, these banks with insufficient retail funds could no longer finance their lending.
6.5.22 This in turn created the global ‘credit crunch’, with banks unable to raise sufficient funding reducing lending, even to many good-quality borrowers who would normally face no difficulty in obtaining bank loans. These problems continued to mount in 2007 and 2008, causing ‘runs’ on banks as doubts about their ability to raise funding increased. At first this was limited to a few institutions. Then, in September and October 2008, as the macroeconomic situation deteriorated, investors began to worry about the possibility that many banks would become insolvent and the run spread to the entire global banking system. By late 2008, the only place from which many banks could borrow wholesale funds was their central bank.
6.5.23 Figure 4, deliberately for the sake of clarity, oversimplifies. There are several other important feedback loops in bank lending, feedbacks familiar from previous ‘credit cycles’ which have been especially pronounced in the current financial crisis:
1) Lenders interpret low levels of loan default as an indication that their lending is low-risk, when in fact low defaults are due to the economic expansion and the general availability of credit, making it easier for borrowers to pay interest and also to refinance their lending and so stay current on their loans. As credit expansion and income growth slow, defaults rise, and lenders suddenly realise that their lending is much riskier than they had believed. They thus begin to withdraw credit, refusing or limiting the amount of lending they provide to risky borrowers. This withdrawal of credit then amplifies the initial economic downturn. This is the first positive feedback loop, on the left of Figure 4.
2) This basic credit cycle was magnified by a weakening of controls and bank governance during the credit boom. Unscrupulous credit practices – for example offering loans to some US sub-prime mortgage borrowers who were clearly only able to repay this borrowing from capital gains on house price appreciation – became common. The credit cycle was also exaggerated by weaknesses of governance in some institutions, with senior management pursuing growth of earnings and stock valuations without proper regard for risk exposure.
3) A severe shortage of bank capital has amplified the credit cycle downswing. Capital is the difference between the value of bank assets and liabilities. It is the main protection against the threat of insolvency. In the downturn losses mount, reducing bank capital, and a substantial decline in bank capital can force banks to reduce their lending further. This is partly because of bank regulations. Banks are required to have certain minimum levels of capital to support their lending. It is also because banks with low capital are at greater risk of insolvency and struggle to raise funds. This aspect of the credit cycle has been further exaggerated this time by the ‘pro-cyclicality’ of regulatory capital requirements, with the new Basel II measures of required regulatory capital increasing sharply as asset quality deteriorates during the credit downturn, and by the excess leverage of many banks in the upswing, especially investment banks that had come to supply a great deal of the new credit.
4) Yet further amplification of the credit cycle has come from the rise and then subsequent fall in prices of land and housing and financial assets. During the boom, high-risk borrowers obtained credit against the expectation that prices would continue to rise further. As prices fall this supply of credit vanishes. Furthermore, asset price falls reduce the value of collateral that borrowers can pledge against their lending, so further reducing the supply and increasing the cost of credit.
5) Similarly, household incomes and corporate revenues rose during the economic upswing, making it easier for them to borrow money, but are now falling during the economic downturn, restricting their access to credit (a mechanism that economists refer to as the ‘financial accelerator’).
6) There is another, more technical, aspect of the credit cycle. Banks, regulators and rating agencies have increasingly been relying on quantitative models to assess their exposure to credit risk. These models are still in their infancy, and, compared with the risks of foreign exchange, government bonds, and equities, there are relatively short runs of data on which these models can be tested. Regrettably, most of these models shared a common weakness. In the data they have used there are relatively few loan defaults and low levels of loan losses, leading the modellers to assume mistakenly that it was very unlikely that many borrowers would default at the same time. The models failed to recognise that in a deep recession such as we are now experiencing, the rate of loan defaults and loan losses can rise sharply, resulting in much bigger losses than these models predict.
6.5.24 These factors have all played a role in the current crisis. The purpose of Figure 4 is to highlight a distinguishing feature of the current crisis: the effect of the much increased reliance of banks on wholesale funding. This has magnified the other feedbacks and resulted in a much more amplified credit cycle than usual. Banks face funding difficulties in every credit downturn, but the funding difficulties in this credit downturn have been much more severe than in the past.
6.5.25 We can complete this case study with a very brief assessment of policy. The strength of these feedback loops, illustrated in Figure 4, have led to a quite extraordinary public policy response, with governments and central banks providing in excess of $10 trillion dollars in the form of recapitalisation, asset and liability guarantees, and short-term central bank loans and asset swaps (See Milne, Reference Milne2009, chapter 2). Policy-makers have been very aware of the lessons of the 1930s and the danger of failing to respond sufficiently to a systemic crisis affecting the entire global financial system. As a result they have gone a very long way in their efforts to support market participants and prevent or reverse these damaging feedback loops.
6.5.26 There is understandable concern that these responses have been too supportive, that they are overgenerous ‘bail-outs’ which have undermined incentives on financial institutions to manage their own risks and avoid another future systemic crisis. But given the scale of the crisis and the difficulties of an orderly restructuring of institutions’ assets and liabilities in a midst of a major crisis, it would have been very difficult for the authorities not to provide such support. The practical question is not whether the authorities should have intervened or not, but whether there can now be changes in regulation and supervision, in firm governance and control, and in arrangements for the resolution of financially distressed banks, that will help prevent such a similar crisis occurring again and allow the authorities to respond better if they do.
6.5.27 There has been considerable controversy about the role of ‘fair value’ accounting in the crisis and especially about the eventual relaxation of these standards in late 2008 and early 2009. It can certainly be misleading to base accounting statements on ‘mark to market’ valuations when there is no liquid market for bank assets. Milne (Reference Milne2009) estimates that approximately half of global bank losses reported up to the end of 2009 are temporary write downs due to market illiquidity, losses which will be recovered in future years, provided banks do not sell assets at the prices used for accounting valuations.
6.5.28 This concern about the impact of mark-to-market valuation has led to the introduction of much greater flexibility in accounting standards, both in US GAAP (with options for valuation based on prospective future cashflows rather than through marking to market) and in global IFSR accounting standards (with much more generous transition rules, allowing transition to ‘hold to maturity’ classification. Provided there is no impairment, i.e. future payments in interest and principal seem likely to be forthcoming, they can be recorded at the value at which they are transferred so limiting balance sheet volatility).
6.5.29 These changes will allow firms to make a more favourable presentation of their balance sheets and income statements. But it is doubtful that such flexibility would have done much to prevent the crisis in the first place. The acceptability of structured credit products as collateral for short-term borrowing depends on their market pricing, not on their accounting valuation. The erosion of liquidity in credit and money markets would still have taken place even had these new more flexible rules applied from 2007 onwards.
6.5.30 There is also concern that such flexibility of accounting rules creates its own problems. Backward looking accounting rules fail to alert management or investors to emerging problems and allowing banks to choose from a range of different accounting treatments can facilitate the hiding of loan losses and write downs.
6.5.31 Another concern has been about the failure of risk-management to restrain aggressive trading and credit creation. This despite the very substantial resources applied to the development of more sophisticated risk-management systems, something encouraged by the new Basel II capital accord and, amongst insurance companies in Europe, by Solvency II. Despite this substantial effort the new risk management tools failed to prevent many banks from pursuing aggressive risk-taking strategies in the new credit markets.
6.5.32 Risk management did not fail across the board. Close to one third of global banking and insurance losses and writedowns emerged in only six institutions (See Milne (Reference Milne2009), Table 8.1). These six were: AIG; Citigroup; Merrill Lynch; UBS; Fannie Mae; and Freddie Mac. Two of these institutions were unconventional companies which had strong implicit state guarantees. Many other institutions (See Milne (Reference Milne2009), chapter 8 for discussion) were still conservatively run and suffered comparatively lower losses and write downs or faced less funding problems than their competitors.
6.5.33 There were two obvious failures of risk management. The first was that the quantitative risk modelling for many of the credit exposures assumed that there would always be market liquidity. Bank ‘credit value at risk models’ were based on the assumption that, if losses emerged, banks could always close down their positions. But these risk models failed to capture the system-wide interactions that undermined market liquidity. Indeed they contributed to system-wide risk. Because all banks were using similar risk models in an uncritical fashion, which assumed that the underlying securities would always be liquid, they all felt confident about building up large levels of exposure to structured credit securities, hence increasing the risk of illiquidity.
6.5.34 The second and even more fundamental failure was that in some banks – although by no means all – risk management was not taken sufficiently seriously at senior management and board level. All firms paid lip-service to risk management. They had chief risk officers with responsibility for monitoring and reporting firm level risks. But too often this became a shallow and unquestioning confirmation of existing strategies. Risk functions were not encouraged to challenge strategic and business decisions and in many cases senior management and board members simply did not understand the risks and risk reports presented to them. It is possible that the widespread use of apparently sophisticated risk models gave boards a false sense of security that they did not need to understand risks at an intuitive level – the risk could all be encapsulated in a few numbers or quantiles of probability distributions.
6.5.35 Another issue is whether an inappropriate approach to regulation was to blame for the crisis. There is a widespread view that the current crisis has been a regulatory failure. Certainly regulators did not take sufficient notice of the system-wide risks. As discussed in the March, 2009, Turner review (Turner, Reference Turner2009) the regulators were focusing too much on individual institutions and failed to pay attention to how risks might emerge at the level of the system as a whole.
6.5.36 There has also been a widespread political agreement on the need to introduce much more intrusive regulation of individual institutions as a means of preventing such a deep financial crisis happening again. Certainly some individual institutions – Fannie Mae and Freddie Mac, AIG, Citigroup, UBS, Merrill Lynch, Royal Bank of Scotland, Northern Rock, Halifax Bank of Scotland – were poorly governed and very inadequately capitalised for the risks which they were taking. But it is not clear that tighter regulation of individual institutions would have prevented the crisis, at least not without extreme restrictions on risk-taking applied to all institutions, well run and poorly run alike, that would have quite large economic costs. It is easy, in retrospect, to understand what type of tight regulation would have stopped banks making the mistakes that they have made. But it is also easy, in retrospect, for shareholders to know what action might have prevented the problems that have beset them! It is less clear that discretionary power given to regulators will be effective, when used ex ante, in preventing the combination of errors and accidents that leads to any particular financial crash. Regulators can be captured by the industry they are regulating and at least as affected by the problem of imperfect knowledge which affects banks owners and managers. There is a great deal of economic theory and empirical evidence which can justify this perspective. It is notable that Fannie Mae and Freddie Mac were closely related to the Federal government and had over 200 regulators (that is staff numbers equal to about 10% of the staff of the FSA working across all financial sectors before the crash) just regulating their activities.
6.5.37 A central question is the appropriateness of Basel II type capital regulation, with detailed ‘risk based’ modelling of exposures incorporated into regulatory capital requirements. Clearly Basel II failed to do anything to prevent the current crisis. Is it possible that Basel II actually made things worse? The global regulatory community has been quick to admit one failing of both Basel II and its predecessor Basel I. While the Basel committee has spent more than two decades of work on these two accords on capital standards for internationally active banks, it has failed to give anything like the same degree of attention to liquidity standards. Since the onset of the crisis, both the Basel committee and the major regulators represented on the committee have been seeking to remedy this shortcoming. A number of consultation documents have been issued on bank liquidity risk and the FSA and other regulators have rapidly introduced a range of new requirements for banks on the holding of liquid assets and the running of liquidity stress tests.
6.5.38 Basel II has also, rightly, been criticised for encouraging ‘procyclicality’, with reductions of capital that encourage more lending in credit booms and sharp increases of capital requirements at exactly the wrong time, during credit downturns. For this reason there is now considerable discussion and attention paid to the possibility of introducing countercyclical capital requirements that will behave in the opposite way, rising in credit booms and then falling in credit downturns (for one set of proposals of this kind see Brunnermeier et al., Reference Brunnermeier, Crickett, Goodhart, Persaud and Shin2009).
6.5.39 Still, there are more fundamental criticisms of Basel II, criticisms which go beyond the failure to say much about liquidity (that was not the purpose of the accord), or the problem of pro-cyclicality of regulatory capital requirements (something which is relatively easily corrected by making the capital requirements ‘through the cycle’ i.e. not altering probabilities of default (or ‘PD’) a critical input to Basel II calculations) over time. The fundamental criticisms are twofold:
1) First, that it has been a basic mistake for regulators to focus on the risks of individual institutions, at the expense of neglecting risks for the system as a whole. Basel II encouraged an entirely wrong mind-set, with both supervisors spending undue effort on understanding and modeling individual firm risks and (mistakenly) encouraging firms to use regulatory capital requirements as a basis for running their business. Instead, the focus should have been on ensuring that banks have sufficient capital to cope with a major system wide crisis.
2) Second, that the focus on individual firm risks encouraged much too great a reliance on quantitative models for regulatory purposes; with neither risk managers nor supervisors asking tough questions about how these models might fail in extreme circumstances. This overreliance on untested models and absence of criticism encouraged firms to take on very similar and very large positions in traded credit and other exposures, positions which greatly increased the systemic risk. Moreover the way these models were applied by Basel encouraged far too low a level of capitalisation for some exposures, especially for example residential and commercial mortgage lending where losses can rise sharply in a deep downturn.
6.5.40 So, it remains an open question whether the main change which is needed is not tighter regulation, but rather a shift in the approach to prudential regulation, with much greater emphasis on monitoring and limiting system-wide risks rather than the risks of individual firms, and on improving governance and control within individual firms rather than on quantitative modelling of regulatory capital. Part of this package may include ensuring that banks and their creditors have greater responsibility for the losses made by banks and action has been taken in the UK to provide a more credible bankruptcy regime which was certainly missing at the beginning of the crisis.
7. Policy Analysis
7.1 Overview
7.1.1 This section discusses the public policy measures which may help mitigate systemic financial risk. This policy discussion builds on the analytical framework developed in the preceding sections of the paper. We have proposed our definition of ‘systemic risk’, in section 4 above, in order to distinguish a large-scale common shock from systemic interactions that lead to the breakdown of networks of interconnections between households, firms and financial institutions. A large-scale common shock may well have a systemic impact, damaging these networks of interconnections, as a result of the widespread failure of financial institutions. But we have gone to some lengths, investigating many different examples, in order to distinguish a large-scale common shock from disturbance that is amplified through the damages or degrades of the networks of relationships amongst firms and households.
7.1.2 Most importantly for this policy discussion, it is useful to distinguish the two because different public policy responses are appropriate for limiting systemic interactions, and hence helping to prevent systemic network damage arising within the financial services sector, and for coping with the effects of a large common shock which triggers widespread insolvency of financial firms. Limiting systemic interactions can be achieved using a variety of approaches. We emphasise three:
1) First, it requires that regulation and governance do not exacerbate systemic disturbances, either encouraging too great a build up of potential systemic problems or exaggerating the impact on networks of interconnections when they eventually materialise.
2) Second, it means ensuring that there is sufficient ‘redundancy’ and flexibility in the networks of interconnections between households, firms and financial institutions to absorb shocks.
3) Third, it requires that traditional macroeconomic policy (both monetary and fiscal policy) is supportive, striking an appropriate balance between long-term stability and short-term support against unanticipated disturbances.
7.1.3 Additional policy responses will be needed to deal with widespread failure of firms and financial institutions, such as would occur following an extreme external shock. That situation requires an orderly distribution of the burden of costs on investors and customers, allowing firms to return as far as possible to the normal conduct of their business and new firms to enter the market, with as little disruption as possible. This requires different policy tools: notably effective arrangements for bankruptcy and settlement of financial and other claims, than does the limiting of systemic risk interactions.
7.1.4 In this section, we deal with each of these areas of policy. We first discuss governance and regulation; we then discuss the need for flexibility and ‘redundancy’ in networks of interconnections; and then we briefly review the need for supportive macroeconomic policy to limit the build up of systemic risks.
7.1.5 While most of our analysis and discussion is about banking, we have also sought to pay careful attention in this policy discussion to the pension and insurance sectors, where there has been relatively little previous attention paid to potential for systemic risk. But we emphasise our findings at section 5 that the insurance and pension sectors are much less vulnerable to systemic interactions. For insurance companies, the major concern is ensuring appropriate regulations, accounting and other external disciplines. There is relatively little else that policy-makers can seek to do to limit systemic interactions in the insurance industry and the pension system.
7.1.6 Finally, we discuss the response to a major external common shock. With appropriate external disciplines, from regulators and from shareholders and other investors; with adequate redundancy in networks of interconnections; and with supportive stable macroeconomic policy then the risks of a systemic crisis are greatly reduced. But even with these safeguards a systemic crisis could still occur. Suppose there were a sufficiently large common shock, perhaps arising for environmental or epidemiological reasons, resulting in widespread failure of non-financial and financial firms. This would be a different kind of systemic crisis. In this situation, minimising the impact of the crisis would require arrangements for the orderly closure of firms and financial institutions and determining the extent to which contractual obligations such as pension payments and insurance payouts are made.
7.1.7 There may be an expectation of blanket protection with government making good all pension, insurance and banking obligations. But in a very large-scale financial crisis such protection would be very costly and could lead in turn to government insolvency. Therefore, while there is a case for such protection, such obligations should not be unconditional.
7.2 Regulation and Governance
7.2.1 When systemic problems materialise then (provided that their own solvency is not called into question) government and financial authorities almost always provide substantial financial support for banks and sometimes also for other financial institutions (for example the support given to AIG in the current crisis). Rightly or wrongly, they do this in order to avoid possible disruption of payments and the supply of credit, to limit falls in the prices of financial assets and real estate and to stabilise short-term funding.
7.2.2 Such support is often criticised (as it has been quite fiercely during the current financial crisis) on the grounds of moral hazard. It protects investors from the consequences of their own mistakes and so encourages both risk taking and lax business controls. But the political and economic costs of not providing support to failing banks in a system wide crisis are so great that such support is rarely, if ever, withheld. In cases when major financial institutions have been allowed to fail (for example, Lehman Brothers in September of 2008), the grounds for doing so have not been a desire to reduce moral hazard but rather the more practical consideration that the government or central bank lacked the legal authority to provide such support (see Swagel (Reference Swagel2009), for documentation of this point that the US authorities did not have the legal authority to save Lehman Brothers without the passage of legislation through Congress, something that was not feasible in the short time available to prevent its failure).
7.2.3 The expectation of such support for banks in the event of a crisis creates in turn considerable challenges for financial regulation and governance of financial institutions. The financial authorities are seeking to achieve a difficult balance – providing support in times of crisis to limit systemic interactions but also ensuring that there are appropriate disciplines on financial institutions, either directly preventing them from taking excessive risks or providing them with incentives to manage their risks prudently on their own accord.
7.2.4 As one means of providing appropriate incentives, a number of countries have created special resolution regimes for distressed banks, allowing regulators to intervene in banks and limit losses at an early stage before they have mounted to the point where they are likely to impose substantial costs on government backed deposit insurance schemes and ensuring that the costs of risk-taking fall on shareholders. The losses which arose in the US Savings and Loan crises highlighted the potentially high costs of not acting quickly (‘regulatory forbearance’). This experience led to the Federal Deposit Insurance Corporation Improvement Act (FDICIA) of 1993 that created the US regime of ‘prompt corrective action’, requiring regulators to intervene increasingly aggressively as measures of bank capitalisation fall towards minimum required levels. Other countries, for example Canada, have well developed arrangements for closing down undercapitalised banks, with relatively little disruption to depositors or other customers.
7.2.5 The conventional measures of balance sheet capitalisation on which these intervention regimes are based are effective at identifying problems of poor loan quality in banks adopting unusual lending strategies. As a result, prompt corrective action does provide some useful discipline on small banks operating in traditional banking activities. But it is much less effective at disciplining either large banks or smaller banks engaged in much the same kind of lending as their competitors. As we have discussed earlier in the context of the ‘credit cycle’, an industry wide but unsustainable expansion of credit does not show up as a decline in conventional balance sheet measures of capitalisation until the credit boom has reversed. There can then be a very sharp decline in net worth. As a result, banks participating in the boom can appear safe until it is too late to prevent large-scale losses. Marking these exposures to market does not help either. For most bank lending, even today, there are no market prices and for the minority of loans which can be securitised or traded, market prices have proved to be a lagging not a leading indicator of underlying loan valuations and arguably, due to market illiquidity, have over-responded to the deterioration of underlying loan performance. Quantifying exposures for individual banks is always a necessary discipline, and will sometimes reveal exposures to extreme tail events or systemic risks, but often this will miss the potential for rapid changes in market conditions and market prices, and so not reveal the full exposure to systemic events.
7.2.6 How then are appropriate disciplines to be imposed on banks? There are really only two practical choices – this requires either a detailed and intrusive regulatory regime which keeps a very tight rein on bank lending or other bank exposures or arrangements must be in place to ensure that, in the event of major losses, bank shareholders and other long-term investors face the financial consequences of risky investments and inadequate controls.
7.2.7 Similar debates about regulation and governance arise in the wake of every episode of financial problems, at least back to the nineteenth century and not just in banking. For example, there is a well-documented debate relating to the regulation of life insurance companies which continued from 1850 to 1880 after the failure of a number of life insurance companies (see Booth, Reference Booth2007). Some participants in that debate wanted to have detailed regulation of insurance companies just as some wish to see much more detailed regulation of banks today. Others wanted to see a clear but simple and unobtrusive legal system which would ensure that life insurance companies were called to account financially for their own mistakes.
7.2.8 Since the late nineteenth century to roughly 1970, (the precise date is arguable – see Booth, Reference Booth2007), the approach to insurance regulation was to require detailed disclosure, a deposit for entry into the market and, crucially, an effective and credible bankruptcy regime for life insurance companies that did fail. This bankruptcy regime was only used twice in 60 years because the disclosure requirements led to companies competing on the basis of how conservative they were.
7.2.9 There are of course major differences between banking and insurance. The relative absence of systemic risks within the insurance industry means that there is no strong economic argument for providing financial support to failing insurance companies. Unlike in the case of banks, allowing insurance companies to fail should not create systemic instabilities. It will not provoke withdrawal of short-term funding and provided failure does not force the sale of assets in illiquid markets then there should be no impact on other institutions. But, rightly or wrongly, there is a convergence of insurance and banking regulation. Insurance regulation is increasingly taking the approach of setting regulatory capital using sophisticated models to provide a low probability of failure (as in banking).
7.2.10 This basic choice between approaches still exists. Financial institutions can be regulated in a detailed way to try to prevent failure, or a regime can exist where there is disclosure, but with arrangements for the reorganisation of failing institutions ensuring that shareholders and other long-term investors bear the cost of failure if it does occur. If the latter approach is taken, there is more tolerance of the failure of individual institutions – and ideally it should be possible to impose costs on shareholders and long-term debt holders even in a systemic crisis, while at the same time providing the financial support which prevents damaging systemic interactions taking place. We believe that there is a strong case for taking this latter approach.
7.2.11 This is not the approach which has been taken in the development of current solvency and capital standards. As we have remarked already, in our case study of the current global credit crisis, there are strong grounds for believing that the emphasis of Basel II on quantitative modelling of individual firm risks at the expense of qualitative assessments of system wide risks has contributed substantially to the scale of the current crisis. Basel II focussed bank risk management on relatively short-term – one year ahead – risks, risks that were always very low even in mid-2006 at the height of the global credit boom. There was little or no attention paid to potential systemic losses and banks were allowed to get away with the presumption – ultimately proved correct – that in the event of a major crisis, they would get sufficient support from the authorities to prevent widespread failure and at little direct cost to shareholders. Basel II has also imposed excessive and quite inappropriately rigid requirements on banks once the crisis itself materialised, with minimum required capital rising sharply because of increased risk at the same time as write-downs and other losses sharply reduced bank net worth. This has played a major role in the crisis during 2008 and early 2009, exacerbating what would in any case have been a sharp reduction in global availability of credit.
7.2.12 This raises the concern that Solvency II, which was largely framed before the crisis and has now acquired its own momentum, will make exactly the same mistakes in the prudential regulation of insurance, leading to insurance firms operating with too little capital to survive major systemic problems; and worse still imposing inappropriately rigid requirements on firms that fall close to regulatory minimum solvency requirements and so creating systemic interactions which could undermine insurance company solvency.
7.2.13 Even now, there is a failure to appreciate the potential impact of systemic problems. This is apparent in the continuing efforts by individual firms to obtain reductions in regulatory capital, both under Basel II and now, more recently, under Solvency II, on the basis of quantitative modelling of their own individual risks. But we now realise that quantitative modelling of individual firm risk will never ensure that firms have sufficient capital to survive a major systemic event.
7.2.14 Indeed, the possibility of major systemic losses makes clear that it is a fundamental mistake to think of prudential capital as something which must be measured and allocated against business risks. The whole agenda of ‘economic capital allocation’ – the notion that capital must be ‘efficiently’ allocated to individual business risks – which has come to be a major influence on business decision making across the financial services industries, is itself a major source of systemic risk because banks especially, but also other financial services companies, should have sufficient capital to survive a major systemic shock; capital that will never need to be used provided the system as a whole is well capitalised and so need not be allocated against business risks (for related criticism of ‘economic capital allocation’, see Milne & Onorato, Reference Milne and Onorato2009).
7.2.15 This leads to a specific recommendation.
Recommendation 1. The operation of regulatory capital requirements, for both banks and insurance companies, needs to reflect the potential for damaging systemic interactions. Specifically, regulatory capital requirements should never be applied in such a way that they force asset sales or limit portfolio growth during periods of widespread financial distress.
7.2.16 While the principle is important, there is considerable room for discussion as how best to ensure in practice that regulatory capital requirements do not force asset sales or portfolio reductions during a period of widespread financial distress. One practical step which will help achieve this goal will be to remove any elements of pro-cyclicality by calculating capital requirements on a ‘through the cycle’ basis. It may also be helpful to require two levels of capital, distinguishing an absolute minimum level of capital, at which firms must recapitalise or face closure, from a much higher desired minimum level of capital, which firms can re-establish over a reasonable period of time.
7.2.17 This first recommendation applies both to banks and to insurance companies. But additional considerations apply to banks. As we have pointed out, in major financial crises, the authorities have always been obliged to support banks, providing them with both short-term funding and enough capital to avoid a distressed sale of assets. This creates a major moral hazard and it can only be mitigated by:
Recommendation 2. In order to minimise the moral hazard created by support for the banking system, banks must either hold, or have in place ex-ante arrangements for raising, additional (or ‘contingent’) capital such that their capitalisation in a financial crisis is substantially greater than minimum regulatory capital requirements.
7.2.18 We do not make firm recommendations on how much greater available capital should be than the minimum regulatory capital requirements or on how, in practice, this is to be achieved. This is a matter for further discussion. But the principle is critically important. The financial authorities cannot avoid supporting banks during a financial crisis. In this circumstance, if shareholders or other investors are not obliged to provide additional capital, then bank risks fall unavoidably onto the taxpayer. There is then no incentive for banks to take any account of their exposure to the large-scale losses which arise in a financial crisis. If on the other hand shareholders know that they will have to finance a large part of any bank ‘bail-out’, then they will take more seriously the possibility of systemic problems and of ensuring that they are adequately protected against them. But shareholders may not provide sufficient discipline so, at the same time, it may also be necessary to have greater sanctions imposed on management if they fail in their ‘duty of care’ to shareholders.
7.2.19 There are a number of different possibilities for how this could be achieved in practice, and this decision could be left to individual banks. Banks could simply hold a large buffer of free capital over and above regulatory minima on their balance sheets. Shareholders could accept double or triple liability, with a legal requirement to subscribe additional capital in the event of bank failure or a systemic crisis (something that was common in many in the 19th century and often adopted voluntarily as a signalling device). There could be arrangements for conversion of long-term debt into equity. For a more general discussion of these issues, see Booth (Reference Booth2009).
7.2.20 This same consideration, the need to incentivise banks to manage their own risks better, also supports our third recommendation.
Recommendation 3. Supervision should ensure that a bank's management takes into account systemic risks, i.e. the possibility of degradation or collapse of the networks of interconnections between the bank and other financial institutions and its customers.
7.2.21 One way of achieving this is through the supervisory appointment of non-executive directors for larger banks, a mechanism which has been recently introduced in Ireland in the wake of their banking crisis. A further way of achieving this objective, especially for complex banks, may be to require that different forms of business are conducted in separately capitalised subsidiaries, funds and accounts to narrow those parts of the business that are directly exposed to systemic risk – especially for banking business linked to the payments system.
7.2.22 Our recommendations do not go as far as some other widely discussed suggestions for restructuring the banking system. We mention here four. Kay (Reference Kay2009) develops a proposal for ‘narrow banking’, requiring any institution that takes retail or corporate deposits to invest only in assets of undoubted quality, for example government securities. While not entirely new (similar narrow banking proposals have a long history going back at least to the work of the US economist Irving Fisher in the 1930s), his is a carefully developed analysis of the rationale for bank regulation drawing many lessons from the regulation of other regulated industries such as telecommunications and electricity, where regulatory intervention (unlike in banking) is kept as simple as possible. The principal argument against his proposal is that this will push the provision of credit outside of the banking system, and could either raise the cost of credit by too great an amount, or lead to a replication of unstable short-term financing of long-term lending, but outside of the regulated banking sector.
7.2.23 A second suggestion that has attracted support in many quarters, is for the creation of a new ‘Glass-Steagall’ act, forbidding any firm from combining investment bank and commercial bank activities within the same organisation, but implemented this time on a global rather than just a US basis. The appeal of this idea is that it appears to offer a way to separate highly risky ‘casino’ banking from what should be dull and safe ‘utility’ banking. This differs from the narrow banking proposal because commercial banks would still be allowed to grant loans to retail and corporate customers, but they could not issue securities or engage in speculative trading. The idea is attractive, but it is unclear that it would have prevented the present crisis. Many of the banks that got into greatest difficulties in the current crisis had no investment banking activities (in the UK we can think of the failed Bradford & Bingley and Northern Rock and the Halifax Bank of Scotland absorbed by Lloyds-TSB). A new Glass-Steagall act would not have affected them at all. At the same time there were also pure investment banks that failed or nearly failed (Merrill Lynch, Bear Stearns, Lehman Brothers). While some conglomerate institutions (Citygroup, UBS) got into great difficulties and were threatened by failure until they obtained government support, others were in much less danger (HSBC, BNP Paribas) and did not have to turn to government to obtain help.
7.2.24 Another suggestion, which has again attracted considerable interest, is intervening to split up the banks that are regarded as ‘too big to fail’, forcing them to sell off divisions or split themselves by business line or geography. Yet another closely related idea is for banks to develop so called ‘living wills’, working out arrangements for splitting up and winding down the business, should their solvency come into doubt. From a practical perspective these two ideas are quite similar, the only difference is whether the splitting of the bank, in order that it can be subsequently failed, is instituted ex-ante, well before any crisis; or whether the splitting and closure takes place once a crisis is pushing a bank under. Such arrangements would certainly reduce the ‘moral hazard’ caused by the protection offered in a systemic crisis; but the challenges to making these ideas work are considerable. It would take a huge amount of both time and of management effort to work out in practical detail how to separate out the different activities of a major financial institution, especially where its activities cross national borders. Some progress may be possible, for example by ensuring that all cross-border banking is carried out using subsidiaries (that can separately fail) rather than branches (which cannot separately fail). But it will take some fundamental changes in the way banks structure and operate their businesses and there will be fierce resistance from the industry, not just because they like being ‘too big too fail’, but also because ending this situation will impose substantial costs on both them and their shareholders.
7.2.25 The more likely outcome is that regulators will put such strong capital and liquidity requirements on either investment banks or commercial banks that engage in relatively risky activities such as proprietary trading, that most of this risky activity will be pushed outside of the banking system and into non-bank intermediaries such as hedge funds. There will then be concerns about risky activities moving into a relatively lightly regulated sector. But this should not matter as long as none of the four major sources of systemic risk identified at section 4 apply to hedge funds. Hedge funds do not participate directly in the payments system and are not exposed to a risk of deposit withdrawals in the same way as banks (unlike a bank, a hedge fund can always declare a halt on redemptions so dealing with any emerging liquidity problems). They could be exposed to counterparty risk or to large common exposures, in much the same way as banks, but unlike the case of commercial or indeed investment banks there are rarely any concerns about wider financial sector disruption following a hedge fund failure (there are several examples of hedge fund failures over the years, the only case that proved to be systemic was the failure of LTCM).
7.3 Redundancy and Flexibility in the Networks of Interconnections between Households, Firms and Financial Institutions
7.3.1 We mentioned earlier, that the Turner Review (Turner, Reference Turner2009) has recognised the importance of focusing not just on individual institutions’ risks but also on how risks might emerge at a system wide level. Our definition of systemic risk, with its focus on networks of interconnections which link firms, households and financial institutions, highlights the importance of an analytical framework in which the strengths and weaknesses of connecting networks are understood. We would also stress the need to understand the ways in which shocks can be transmitted through these networks, the positive feedback and other amplification mechanisms which can transform large common shocks into systemic events and the behaviours and actions that can help stabilise the networks in times of crisis.
7.3.2 In general, financial authorities have been aware of the need to maintain sufficient redundancy and flexibility in these networks. Over the past couple of decades appropriate standards have been established (primarily through the other ‘Basel committee’ on payments and settlement systems) to ensure that payments and settlements infrastructure has minimum exposure to the risk of systemic damage.
7.3.3 But, as we have observed above, the same high standards have not been applied in other areas, especially for counterparty risk in over-the-counter markets. This then leads to our fourth recommendation:
Recommendation 4. The industry should move to establish sufficient ‘redundancy’ and flexibility in over-the-counter markets, for securities, derivatives and insurance trading; so that counterparty risk from dealers or other participants is effectively controlled.
7.3.4 Our Recommendations 1–3 on regulatory capital and on governance will create additional redundancy and flexibility in many potentially systemic financial networks. Having access to sufficient, flexible capital helps to avoid situations where banks and insurance companies are forced to sell assets at distressed prices; and capital is also especially important to banks that face difficulties with access to short-term funding. But there are still further steps which can be taken to reduce the potential for systemic interactions arising from counterparty risk, especially in OTC markets.
7.3.5 This can be achieved through a combination of some or all of many different measures, including more conservative margining, the introduction of central counterparty clearing, higher standards on capitalisation and liquidity for major OTC dealers, the movement of OTC trading onto more formal exchanges, and ‘living wills’ for major market participants with clearly established arrangements for the reallocation of contracts in the event that a participant is forced to withdraw from the market, due to a rating downgrade or other event.
7.3.6 We are careful here not to specify exactly what combination of these or other measures should be used to achieve the required redundancy and flexibility in OTC markets. This is something for careful assessment by the major market participants. In general we believe that counterparty risk can be reduced using voluntary measures, but there is one exception: firms are very reluctant to reveal their exposures to other institutions, especially if they perceive some commercial advantage from keeping these exposures hidden. This suggests a final recommendation:
Recommendation 5. The financial authorities should require financial institutions to disclose all information necessary to allow regulators and market participants to assess risks at the wider systemic level.
7.3.7 This is required because firms will not generally provide such information voluntarily on an individual basis. To give a specific example, it is difficult to assess the risks of maturity mismatch associated with particular trading instruments, without being aware of the funding of positions across the market and how close market participants are to financing their positions using maximum available haircuts. If almost all investors are financing their positions short-term and at close to the maximum available haircuts, then there is a substantial risk of a withdrawal of funding and a price collapse. If on the other hand, there is substantial redundancy, with many firms able to absorb considerable price falls before they have to use their own capital to finance their positions, then the risks of such a price collapse are much less.
7.3.8 Again, we say little about the practical implementation of this recommendation. It requires a decision about what information should be revealed for the assessment of risks at the wider systemic level. We would hope that this can be agreed amongst industry participants themselves, with arrangements similar to those established for formal exchanges, for example the publication of statistics such as open interest in traded derivative contracts. But if industry participants do not make the decision themselves to publish sufficient information for the assessment of systemic risk, then financial regulators can be expected to take the lead by imposing their own requirements. Industry participants should not then complain if the compliance costs are relatively high.
7.3.9 So detailed discussion will be needed, between regulators and market participants, to determine what information is useful for assessing risks at the wider systemic level and how this can be provided at low cost. Some period of delay before such aggregated exposures become public knowledge may also be appropriate, to protect commercial interests.
7.4 Traditional Tools of Macroeconomic Policy
7.4.1 The final area where we identify policy concerns is with the traditional macroeconomic tools of fiscal and monetary policy. The motivation for this emerges clearly from the various studies of past banking crises which we have used for our Table 1 and Appendix A. Almost all major banking problems have followed periods of unsustainable credit creation. The result is an exposure to systemic damage to bank lending markets, resulting in a restriction of the supply of credit and, in extreme cases, to widespread bank failure.
7.4.2 There is now an ongoing debate about the development of a macroprudential response to such episodes of unsustainable credit creation. However this debate is resolved, it is clear that there needs to be more effective action to contain unsustainable credit creation. We do not make specific policy recommendations. But we draw attention to the essential role of macro-economic stability in ensuring systemic financial stability.
7.4.3 The established macroeconomic tool of monetary policy can continue to be directed towards maintaining price stability (as is currently pursued through the Bank of England's inflation target) but, at the same time, there is a need also to achieve credit stability in which the aggregate growth and outstanding levels of private sector credit are limited to sustainable levels, and this need should not be ignored. There are various ways in which credit stability could be taken into account. Some argue that there needs to be additional macro-prudential policy instruments such as quantitative controls on credit expansion. Others argue that it would be sufficient to have an inflation target (or price level target) that was not so focused on consumer prices and to take greater account of the developments of monetary aggregates and of asset prices, such as real-estate prices, when setting monetary policy.
7.4.4 There is as yet no consensus on the need for an additional macro-prudential policy instrument to restrain aggregate credit growth. In any case, it should be remembered that there are likely to be considerable limitations on the use of either monetary policy and/or regulatory instruments, such as capital requirements to restrain credit growth, when there is a general perception that risks are low and that the credit extended will mostly be repaid. There is no obvious way of working out what level of credit growth is acceptable.
7.4.5 There are also implications for the conduct of fiscal policy. Fiscal policy should not be employed in such a way that it amplifies cycles in private sector credit. Also, especially when as at present public sector finances are under strain, it is necessary to conduct fiscal policy in a way that ensures that there is no possibility of a loss of credibility in the repayment of public sector debt. Public sector debts are assets of undoubted safety, and as such provide a foundation for short-term bank lending and are a core form of investment for pension funds and insurance companies. A failure, for example, to bring the currently high fiscal deficits in the US, the UK and in other countries under control, would eventually create a new and serious problem across the financial system.
7.4.6 These limitations on the use of monetary, fiscal, or other macro-prudential tools to limit credit expansion suggest that these macro-tools are not enough, on their own, to avert the risk of systemic financial problems. Rather, as we have already argued, the macroeconomics must support and be supported by improved governance and regulation of financial institutions and by greater redundancy in the networks of interconnections between firms, households and financial institutions. Governance and regulation should limit exposure to systemic events but also give financial institutions sufficient flexibility to respond to large shocks without undermining their balance sheets. Greater redundancy in these networks – especially in OTC and short-term funding markets – will help prevent damaging systemic interactions.
7.5 The Response to Large-scale Common Shocks
7.5.1 To complete our discussion of the policy response to systemic risk, we finally discuss the policy response to large-scale common shocks. We have provided a number of examples of possible such shocks in our paper, for example, a sudden major increase in life expectancy which undermines the solvency of pension funds and their sponsors; an epidemiological catastrophe which leads to huge claims on life insurance policies on an unanticipated scale; a major climate event which leads to the insolvency of the leading global reinsurers; or a major external shock which undermines business activity and leads to widespread bankruptcies of companies and financial institutions.
7.5.2 We have relatively little to say about such unlikely, but extreme events. Should any of these occur, they would certainly be systemic because they would lead to a substantial breakdown of the networks of interconnection between firms, households and financial institutions.
7.5.3 Such huge common shocks may require additional policy measures to those we recommend, in order to limit the network interactions that generate systemic risk within financial services. Even if such systemic interactions are limited, such large-scale external disturbances would still lead to widespread disruption. There are various possible responses to such disruption. Extensive government intervention, both to ensure that critical services to companies and households are maintained and to protect the most vulnerable citizens is one approach. This could take the form of the government taking over the functions of bankrupt financial institutions, or assisting in the recapitalisation of insolvent firms. Alternatively, the government may simply be involved in a process of ensuring that any losses are appropriately distributed between contracting parties where the legal system does not deal with such things effectively.
7.5.4 Government intervention in this case may not create any obvious problem of moral hazard. The probability of such events taking place is sufficiently remote that they do not lead to excessive risk taking or undermine the adequacy of controls. In this, they are very different from the support that financial authorities are obliged to provide to banks in a systemic banking crisis and there is no need to intervene in the regulation of governance of financial institutions, in order to reduce the impact of this kind of large-scale common shock.
7.5.5 Still there is a need for the authorities to do some forward planning, to have in place contingency plans to ensure that such major common shocks do not lead to unnecessary disruption. In particular we think it will be necessary ahead of time to have in place orderly arrangements for the re-organisation of both firms and financial institutions, with an appropriate allocation of the costs of the common shock to customers, investors and taxpayers. So, for example, in the case of such a large-scale increase in longevity, it should be possible either to increase retirement age or to impose reductions in pension benefits so that a share of costs is imposed on pension members. While in the case of a large-scale common shock undermining bank solvency, there might be a reduction in the claims of bank depositors (something that might in practice be achieved through a period of negative real interest rates). It may well be the case that the industry as a whole is able to organise the process of dealing with such problems as, for example, in the Lloyd's crisis in the late 1980s, but some forward thinking by government could still prove extremely helpful.
Acknowledgements
This is an independent report prepared at the request of The Actuarial Profession in the UK. We would like to acknowledge comments received at a preliminary presentation, at the half day conference on systemic risk, held by The Actuarial Profession at Staple Inn, and from David Blake and three anonymous scrutineers. The opinions expressed here are our own personal views and not those of The Actuarial Profession or of Cass Business School.
Appendix A: Historical Banking and Financial Crises
Pre-World War II Banking and Financial Crises

Note: Most of the descriptions in the table are reproduced from Reinhart & Rogoff (2008).
Post-World War II Banking and Financial Crises

Note: Most of the descriptions in the table are reproduced from Laeven & Valencia (Reference Laeven and Valencia2008).
Appendix B: Literature Review
B.1. Introduction
B.1.1 This Appendix reviews some of the large literature on previous banking and financial crises. We do not claim that this in any way a complete review. What we have done is to look mainly at the most recent contributions and taken them into account in our main analysis. This Appendix provides a listing of these and other prominent papers with a very brief discussion of their content. But there is a very large amount written on financial crises and much will have escaped our net. Also we spend relatively little space discussing the relationship between the different contributions. This is a list of papers with comments. We do not provide an analytical framework within which different contributions can be compared and contrasted.
B.1.2 The Appendix is organised as follows. Section B.2 presents comparative studies that review a large number of banking and other financial crises. Section B.3 presents theoretical literature on financial crises. Section B.4 presents some of the more recent literature on financial networks and the possibility of instability and contagion. Section B.5 presents work on banking crisis resolution. Section B.6 presents insurance crises. Section B.7 reviews case studies on individual crises with sub-section on the pre-1930s, on the 1930s, on the Latin American debt crisis of 1980s, on the Savings & Loans (S&Ls) in the 1980s, on Japan in the 1980s, on the Scandinavian crisis and the Asian crisis of 1997–98 and the current financial crisis. Section B.8 presents policy orientated papers on how to improve regulation and avoid future crises.
B.2. Comparative Studies of Past Banking and other Financial Crises
B.2.1 Caprio & Klingebiel (2003) tabulate the information on banking crises in different countries since the 1970s. Their main contribution is to provide a considerable amount of information about banking crises over the last 40 years. The authors separate the crises into two categories: 117 systemic crises (in 93 countries) and 51 non-systemic banking crises (in 45 countries).
B.2.2 Reinhart & Rogoff (Reference Reinhart and Rogoff2008a) point out that the US sub-prime crisis may not be very different compared with some of the previous post-war financial crises. The discussion focuses on the patterns of the time series of five macroeconomic variables – housing prices, equity prices, GDP, GDP per capita, and public debt. The authors select a number of post-war financial crises considered to be relevant to the present US sub-prime crisis. They find that all crises are similar in the run-up of asset prices, in debt accumulation, in growth patterns and in current account deficits.
B.2.3 Laeven & Valencia (Reference Laeven and Valencia2008) presents a new database on the timing of systemic banking crises and policy responses. They find that banking crises were most frequent during the early 1990s with a peak of 13 systemic banking crises starting in 1995. In total, they count 124 banking crises, 208 currency crises, and 63 sovereign debt crises over the period 1970 to 2007. Of the 124 banking crises, 42 are considered twin crises and 10 can be classified as triple crises (banking, currency and sovereign debt). They also find that emergency liquidity support and blanket guarantees have frequently been used to contain crises and restore confidence, though not always with success.
B.2.4 Demirgüç-Kunt et al. (Reference Demirgüç-Kunt, Karacaovali and Laeven2008) present a new deposit insurance (DI) database that updates an earlier one constructed in 1999 by Demirgüç-Kunt & Sobaci (Reference Demirgüç-Kunt and Sobaci2001) and extends it in several important dimensions. First, the database includes 14 new countries that have adopted deposit insurance schemes (DISs) since 1999 and identifies 12 other countries with deposit insurance schemes as of 1999 that were not covered before. Second, the database uses various country sources and surveys of deposit insurance agencies and officials around the world, and hence completes and further details the other collected data. Third, this dataset adds historical time series data, and covers the values of deposit insurance coverage amounts, co-insurance and coverage ratios since the inception of the first nationwide scheme by the United States in 1934. Fourth, other new variables are incorporated that include the level of co-insurance requirements, percentage of the value of deposits covered and whether the payments are per depositor or per depositor per account.
B.2.5 Reinhart & Rogoff (Reference Reinhart and Rogoff2008b) study all the financial crises that are recorded since the 1800s. The authors note that there are striking similarities among all the financial crises and that these similarities are common for the advanced economies and the emerging markets. They find that banking crises almost invariably lead to sharp declines in tax revenues as well as significant increases in government spending (a share of which is presumably dissipative). On average, government debt rises by 86 percent during the three years following a banking crisis. These indirect fiscal consequences are thus of an order of magnitude larger than the usual bank bailout costs that are the centerpiece of most previous studies. The fact that the magnitudes are comparable in advanced and emerging market economies is noteworthy. Obviously, both the bailout costs and the fiscal costs depend on a host of political and economic factors, including especially the policy responses as well as the severity of the shocks which, typically, trigger crises.
B.2.6 Reinhart & Rogoff (Reference Reinhart and Rogoff2009a) discuss the aftermath of financial crises, noticing the major impact on economic activity, asset prices, and on government deficits and debt.
B.2.7 Reinhart & Rogoff (Reference Reinhart and Rogoff2009b) extends the analysis of Reinhart and Rogoff (Reference Reinhart and Rogoff2008b, Reference Reinhart and Rogoff2009a) into several new areas of analysis, notably sovereign debt crises, domestic debt crises (on which they appear to give the first systematic analysis) and episodes of uncontrolled inflation. They also provide a more extended discussion of the global crisis of 2007–2008.
B.2.8 Milne (Reference Milne2009) argues that the key challenge now facing economic policymakers is the collapse of confidence in bank assets and bank funding instruments and the consequent reductions of money and credit. The collapse of confidence and liquidity in traded credit instruments created a ‘feedback loop’ – what was initially a small shock became a large cumulative destabilising effect (systemic crisis). He also argues that liquidity losses are not external shocks but rather are reactions of market participants to a potential deterioration of economic fundamentals. The book then compares the current financial crisis with some previous historical episodes. One of the purposes of this book is to show that in past episodes of financial boom and bust both excessive optimism and excessive pessimism have played a role. In some cases – for example the grossly excessive extension of bank credit in Japan in the 1980s – the subsequent bust has been mainly due to the excesses and over-optimism of the preceding boom. In other cases – such as the US banking panic of 1907 or the Long-Term Capital Management (LTCM) liquidity crisis of 1998 – the crisis is more attributable to overreaction and panic, with a pronounced collapse in liquidity and market values prompted by a relatively small deterioration in fundamentals. Most crises result from a mixture of both of these causes, both over-optimism in the boom and excessive pessimism in the subsequent bust.
B.2.9 Hoggarth et al., (Reference Hoggarth, Reis and Sapporta2001) focus on cross-country estimates of the direct fiscal costs of crisis resolution and the broader welfare costs, approximated by output losses, associated with banking crises. They find that banking crises (but not currency crises) significantly affect output in developed countries, while the opposite is true in emerging-market countries. These results also seem to hold up after allowing for other factors that may have caused output to fall. However, there remains the possibility of reverse causation, with larger recessions causing banking (or currency) crises rather than financial crises causing bigger recessions. In conclusion, it seems to be the case that regardless of whether banking crises cause or are produced by recession, they exacerbate subsequent output losses (and are often costly to resolve).
B.2.10 Wolf (Reference Wolf2009) examines the relationship between international financial crises and global imbalances, and the role of global imbalances in the current crisis (his text was completed in the summer, before the crisis intensified in the autumn of 2008). He reports only some 38 financial crises between 1945 and 1971 none of which were banking crises, when finance was closely regulated; whereas between 1973 and 1997, there were 139 including many banking crises. He draws attention to the earlier crisis that affected Latin America, Russia and Asia in the years 1997 and 1998, the first example since the 1930s of a global crisis affecting many countries. He shows how the subprime loan crisis in the United States was supported by the fact that the United States was, in Wolf's phrase ‘the borrower and spender of last resort’, i.e. the global demand for goods and services depended on the willingness of the United States to borrow from other countries in order to buy their goods. Moreover, he concludes that we need to create a financial and global macroeconomic regime that allows reasonably well-run countries to import at least some capital with a degree of safety and so ends reliance on the United States as the borrower and spender of last resort.
B.2.11 Glick & Hutchison (Reference Glick and Hutchison2001) investigate the causal linkages between bank and currency crises using a broad country and time-series data set. The authors define the twin crises as instances in which a bank crisis is accompanied by a currency crisis in either the previous, current or following year. It can be concluded from the signal-to-noise ratios and the profit regressions that emerging markets that are financially liberalised suffered from the twin crises more than the industrial countries. And a strong causal, joint feedback link between banking and currency crises appears only for this group of emerging markets. They use data from 90 countries and find some evidence that the banking crisis is a good leading indicator of a currency crisis for the emerging market groups; yet the converse does not hold true.
B.3. Theoretical Explanations of Financial Crises
B.3.1 Allen & Gale (Reference Allen and Gale2000a) suggest that bubbles will occur when there is considerable uncertainty about real asset payoffs or about credit expansion. They have argued that in particular there is great scope for uncertainty about credit expansion. Financial liberalisation is often a major factor leading to such uncertainty. In designing policies, governments and central banks need to take into account the possible impacts of their actions on asset prices if a bubble is to be avoided. It is not simply the level of credit that is important but also the uncertainty of future levels. The paper provides a model of bubbles which is consistent with the type of crises observed in Japan, Scandinavia, South East Asia, Mexico and other emerging countries. It shows how an intermediated financial system could lead to risk shifting and bubbles in asset prices. A model of the relationship between the amount of credit provided by the banking system and the level of asset prices is developed. A fragile regime is identified in which the central bank must increase the amount of credit by a critical amount in order to avoid a financial crisis, it may not be sufficient simply to increase it.
B.3.2 Allen & Gale (Reference Allen and Gale2000b) seek to answer the question about the optimal policy toward crises. They address the question of how to model crises. Their empirical evidence suggests that banking panics are related to business cycles and are not simply the result of ‘sunspots’. Panics occur when depositors perceive that the returns on bank assets are going to be unusually low. They develop a simple model of this. In this setting, bank runs can be first-best efficient: they allow efficient risk sharing between early and late withdrawing depositors and they allow banks to hold efficient portfolios. However, if costly runs or markets for risky assets are introduced, central bank intervention of the right kind can lead to a Pareto improvement in welfare.
B.3.3 La Porta & De-Silanes (Reference LaPorta and De-Silanes2002) assemble data on government ownership of banks around the world. The data show that such ownership is large and pervasive, and higher in countries with low levels of per capita income, backward financial systems, interventionist and inefficient governments and poor protection of property rights. Higher government ownership of banks in 1970 is associated with slower subsequent financial development and lower growth of per capita income and productivity. This evidence supports ‘political’ theories of the effects of government ownership of firms.
B.3.4 Morris & Shin (Reference Morris and Shin2003) argue that traders with short horizons and privately known trading limits interact in markets for risky assets. Risk-averse, long-horizon traders supply a downward sloping residual demand curve that faces the short-horizon traders. When the price falls close to the trading limits of the short-horizon traders, selling of the risky asset by any trader increases the incentives for others to sell. Sales become mutually reinforcing in the short-term. By using global game techniques, they identify the unique trigger point at which the liquidity black hole comes into existence. When a liquidity black hole comes into existence, a large degree of illiquidity is associated with a sharper decline in prices and a commensurate bounce back in prices in the final period. Another implication of their model is that trading volumes at the time of a liquidity black hole and its aftermath will be considerable. When the market strikes a liquidity black hole, the whole of the asset holding in the risky asset changes hands from the risk-neutral short horizon traders to the risk-averse market making sector. Although they do not model the dynamics, they could envisage that once the loss limits have been adjusted down given the new price, there will be an immediate reversal of the trades in which the risky asset ends up back in the hands of the risk neutral traders. Moreover, the equilibrium strategies of the traders also take account of the degree of illiquidity of the market. Just as in the outcome in a bank run game, the traders in the illiquid market bail out more aggressively when they fear the bailing out of other traders.
B.3.5 Valencia (Reference Valencia2008) argues that periods of banking distress are often followed by sizable and long-lasting contractions in bank credit. This phenomenon may be explained by declined demand by financially impaired borrowers or by lower supply by capital-constrained banks, a ‘credit crunch’. He develops a bank model to study credit crunches and their real effects. From a policy perspective, the model justifies the use of public funds to recapitalise banks following a significant deterioration in their capital position. His results suggest that the financial health of the banking system may be a significant contributor to the propagation of economic shocks, especially negative ones. Banks’ precautionary motives insulate lending from shocks up to some size, but for larger shocks the economic consequences of the ensuing credit crunch may be significant. In this context, the results suggest that government bailouts of distressed banks – in the form of recapitalisation policies – may be a reasonable response during episodes of systemic financial pressure.
B.3.6 Acharya (Reference Acharya2009) explains that, with negative externality and limited liability, banks will choose highly correlated assets which may lead to collective failure. The authorities should therefore regulate a bank as a function of both its joint risk with other banks as well as its individual risk. The author follows the work of Allen & Gale (2000). It uses a two-period model (Time 0, Time 1 and Time 2) and assumes that there are two kinds of agents (banks and depositors) and two kinds of assets (safe assets and risky assets). The bank owners are assumed to have no wealth of their own, and all the wealth of the society belongs to the depositors, who can only choose to lend to the banks or keep the wealth themselves. Moreover, the model also assumes that there are two industries in the economy, and each bank can only invest in the firms that belong to the same industry; the risk levels of the firms are different, and each bank can choose the risk level that it wishes to accept. Each bank needs to make a number of choices:
(1) the amount of safe investment;
(2) the amount of risky investment;
(3) the level of risk of the risky asset; and
(4) the industry in which the risky assets belong.
Depending on the choices which the banks have made, there are different possible states:
(a) If no bank fails, the depositors keep on lending.
(b) If some banks fail, part of the depositors of these failed banks will migrate to the surviving banks, while the rest will keep their deposits. The total investment of the economy decreases (recessionary spillover) but the surviving banks may gain a strategic benefit from acquisition of the failed banks’ deposits. But the negative externality effect (recessionary spillover) exceeds the positive externality effect (strategic benefit).
(c) If all banks fail, there will be no investment in the economy. Depositors will hoard their savings. At each different state, the bank owners and the depositors receive their payoffs according the realised returns. The model shows that the choice of industry by different banks determines the correlation of their portfolio returns. Systemic risk arises as an endogenous consequence when in equilibrium, banks prefer to lend to similar industries. The model demonstrates that, due to the existence of limited liabilities, banks collectively increase their aggregate risk by investing in similar industries. The reason for this phenomenon is that bank owners have no preference between failing individually or failing collectively, but they have a preference of surviving together or failing together because they don't want to see their profits subsidise the failure of the others. Therefore the role of a central bank should be designed jointly with the incentive schemes of different banks to mitigate behaviour so that the welfare of bank owners and depositors are maximised.
B.3.7 Diamond & Rajan (Reference Diamond and Rajan2009) examine the causes of credit freezes and the interventions which can get lending going again. The authors suggest that bank managements are not willing to sacrifice future earnings by selling illiquid assets today, even if this helps avoid bank failures. The authors use a two-period model (Time 0, Time 1 and Time 2). The model assumes that a bank, which owned some financial assets, is supported by deposits which are callable at any time. A liquidity shock is defined by a large portion of deposits being drawn and happens with probability q at Time 1. Then, the model further assumes that there also exist some liquid buyers (with limited cash) who can purchase the bank's financial assets at either date. At Time 0, the bank has two choices:
(1) it can sell some of its assets for cash in order to avoid being illiquid at Time 1; or
(2) it can choose to keep all the assets. If there is no liquidity shock at Time 1, the second choice will produce larger earnings for the bank. However, if a liquidity shock does happen and the bank does not have enough cash to repay the depositors, it will be forced to sell some of its assets at ‘fire sale price’ which may be so low that the bank can become insolvent. The model shows that with limited liability, a bank will prefer not to sell its assets at Time 0 at a discounted price offered by the market (the ask price), because keeping all the assets maximises the payoff at Time 2 conditional on survival. In other words, a bank is not willing to sell its assets when the ask price is lower than its bid price. On the other hand, the liquid buyers would expect the ‘fire sale price’ to be low, so they are not willing to buy the financial assets at Time 0 unless the bank accepts their ask price. This also creates the gap between the bid and ask price. For these reasons, there is no trade at Time 0 and the market freezes up.
B.3.8 Bolton et al. (Reference Bolton, Santos and Scheinkman2009) presents a liquidity model which discusses the relationship between short run investors (SRs) who face liquidity problems and long run investors (LRs) who provide liquidity when they purchase assets at fire sales. The paper uses a multi-period model (Time 0, Time 1, Time 2 and Time 3). It assumes that two kinds of agents – the SRs who can invest in cash (inside liquidity) and risky assets only, and the LRs who can invest in cash (outside liquidity) and the long assets. Each of them will decide how much they are going to invest in the assets and the cash at Time 0. The SRs can liquidate the risky assets at Time 1 and Time 2 depending on the prices and the private and public information. The LRs have to hold the long asset until Time 4, and they also have to use all of their remaining cash to buy the risky assets from SRs at Time 1 and Time 2. At Time 1, an aggregate shock may happen with probability (1-lamda); at Time 2 and Time 3, some of the loans will fail and the proportion of failure is (1-theta) and (1-eta) respectively. The SRs will only sell the risky assets when shocks happen. It is assumed that the SRs have no idea whether the risky assets are going to succeed (no default) at Time 1, no matter whether the aggregate shock happens or not; the aggregate shocks only decrease the chance of the risky assets succeeding. Since no one has information about the risky assets at Time 1, there is no adverse selection. At Time 2, it is assumed that the SRs will keep the succeeded assets and sell the failed assets to the LRs. Therefore, there is adverse selection. At Time 3, everything is certain. The SRs and LRs know their payoffs respectively. The liquidation and acquisition strategies are made such that the agents maximise the payoffs and the markets are clear. The model shows that the immediate trading equilibrium (the trading occurs at Time 1 where there is no adverse selection) and the delayed trading equilibrium (the trading occurs at Time 2 where there exists adverse selection) generate very different results. In immediate trading equilibrium, the SRs will sell some of the risky assets which may succeed or fail to LRs. The liquidity of SRs increases. The prices are close to the expected payoffs. And the LRs will need to retain more cash at Time 0 in order to buy the risky assets. In delayed trading equilibrium, the LRs will keep less cash, and the prices are low because only the failed assets are sold by the SRs. The delayed equilibrium is more efficient. And the delayed equilibrium may not exist in some occasions.
B.4. Financial Networks and Systemic Stability
B.4.1 Recent Work on Financial Networks and Systemic Stability
B.4.1.1 Overview
B.4.1.1.1 A recent and quite rapidly growing literature has begun to apply tools and techniques for the study of complex adaptive systems, taken from the biological and natural sciences, to economic and financial networks. This part of our literature review looks briefly at these new contributions to the literature. While this work is very promising it is, as yet, at a relatively early stage and has not yet produced a consensus on the sources of systemic risk in financial networks.
B.4.1.1.2 One issue addressed is the nature of financial networks. Connections in the financial world take different forms and linkages. The complex structure of linkages between financial institutions can be captured by using a network representation of financial systems. The general concept of a network is quite intuitive: a network describes a collection of nodes and the links between them (Newman, Reference Newman2003). The notion of nodes could be individuals or firms or countries, or even collections of such entities. A link between two nodes represents a direct relationship between them. In the context of financial systems, the nodes of the network represent financial institutions, while the links are created through mutual exposures between banks, acquired on the interbank market by holding similar portfolio exposures or by sharing the same mass of depositors.
B.4.1.1.3 Economic research on networks offers insights into how network analysis might be applied to financial systems. While there would appear to be many applications of network analysis to financial systems, the literature on financial networks is still at an early stage (Allen & Babus, Reference Allen and Babus2008). Most of the existing research using network theory concentrates on issues such as financial stability and contagion. Moreover, most of the research done in financial networks studies network effects rather than network formation. The literature primarily investigates how different financial network structures respond to the breakdown of a single bank to identify which structures are more fragile.
B.4.1.1.4 Allen & Babus (Reference Allen and Babus2008) argue that the use of network theories can enrich understanding of complex and interdependent financial systems. They review the recent developments in financial networks, highlighting the synergies created from applying network theory to answer financial questions. Further, they propose several directions of research: (i) the issue of systemic risk; (ii) how network theory can be used to explain freezes in the interbank market of the type they have observed in August 2007 and subsequently; (iii) how social networks can improve investment decisions and corporate governance; (iv) networks in distributing primary issues of securities as, for example, in initial public offerings, or seasoned debt and equity issues; (v) networks as a form of mutual monitoring as in microfinance.
B.4.1.2 Studies of Payment Systems and Interbank Counterparty Risk
B.4.1.2.1 There are a number of earlier contributions on financial networks linking banks, written prior to the current global banking crisis. This work has focussed on payment system linkages and counterparty risk in interbank markets. Generally, these analyses concluded that the risks of a systemic breakdown were relatively small.
B.4.1.2.2 Upper (Reference Upper2007) is a valuable survey of much of this work. He summarises the findings of counterfactual simulations to estimate the danger of contagion owing to exposures in the interbank loan market, provides a critical assessment of the modelling assumptions, and discusses their use in financial stability analysis. However, on the whole, such simulations suggest that contagious defaults are unlikely, but cannot be fully ruled out, at least in some countries. If contagion does take place, then it could lead to the breakdown of a substantial fraction of the banking system, thus imposing high costs to society.
B.4.1.2.3 Upper (Reference Upper2007) also reviews some related technical issues. Much of this work uses a statistical estimation technique known as the “entropy maximising method” in order to overcome gaps in the statistics about interbank exposures. This technique is subject to important caveats. There is no account on any remedial action of banks when other banks are in difficulties or fail. Nor is there any allowance made for exposures in net terms. In addition, most of analyses are unable to make a distinction between uncollateralised and collateralised lending.
B.4.1.2.4 There are also at least three reasons why maximising the entropy might not be a particularly good way of capturing underlying relationships. First, fixed costs for screening of potential borrowers and monitoring loans may render small exposures unviable. Secondly, relationship lending may limit the number of counterparties of any one bank and thus lead to a higher degree of market concentration than suggested by the maximum entropy method. Thirdly, maximum entropy results in the same portfolio structure for estimated counterparties. Maximum entropy biases the estimated matrix and raises the threshold for a shock leading to contagion.
B.4.1.2.5 This relatively practically focused work on interbank and payments networks yields findings that are quite consistent with the theoretical analysis of Allen & Gale (2000). They study how the banking system responds to contagion when banks are connected under different network structures. The authors show that incomplete networks are more prone to contagion than complete structures. Specifically, they take the case of an incomplete network where the failure of a bank may trigger the failure of the entire banking system. They prove that, for the same set of parameters, if banks are connected in a complete structure, then the system is resilient to contagious effects. Their models and related work of Freixas et al. (Reference Freixas, Parigi and Rochet2000) show that the scope for contagion depends on the size of interbank exposures relative to capital as well as on the precise pattern of such linkages. Contagion is less likely to occur in what Allen & Gale term a complete structure of claims, in which every bank has symmetric exposures to all other banks. Incomplete structures, where banks are exposed only to a few neighbouring institutions, are shown to be more fragile. Finally, the scope for contagion in a system with money-centre banks, where the institutions on the periphery are linked to banks at the centre but not to each other, crucially depends on the precise values of the model's parameters.
B.4.1.2.6 We can mention some eight individual country studies, all of which fit well with Upper's (2007) view that there is a potential for contagion which, while small, has a major impact when it occurs:
1) Pröpper et al. (Reference Pröpper, Van Lelyveld and Heijmans2008) apply network theory to the Dutch payment system with specific attention to systemic stability. The network nodes comprise domestic banks, large international banks and TARGET countries, the links are established by payments between the nodes. Traditional measures (transactions, values) first show payments are relatively well behaved through time and that the system does not contain a group of significant structural net receivers or payers among the participant institutions. Structural circular flows do, however, exist in the system, most prominently a large circular net flow between TARGET countries. Analysis of the properties of prominent network measures over time shows that fast network development takes place in the early phase of network formation of about one hour and slower development afterwards. The payment network is small (in actual nodes and links), compact (in path length and eccentricity) and sparse (in connectivity) for all time periods. In the long run, a mere 12% of the possible number of interbank connections is ever used and banks are on average only 2 steps apart. Relations in the network tend to be reciprocal. Their results also indicate that the network is susceptible to directed attacks. In a final section they show that the recent ‘sub prime’ turmoil in credit markets has not materially affected the network structure.
2) Elsinger et al. (Reference Elsinger, Lehar and Summer2003) use standard risk management techniques in combination with a network model of interbank exposures to analyse the consequences of macroeconomic shocks for bank insolvency risk. They consider interest rate shocks, exchange rate and stock market movements as well as shocks related to the business cycle. They apply the model to a unique dataset of all Austrian banks. They find that correlation in banks’ asset portfolios dominates contagion as the main source of systemic risk. Contagion occurs rarely but can wipe out a major part of the banking system. Low bankruptcy costs and an efficient crisis resolution policy are crucial to limit the system wide impact of contagious default events. They compute the ‘value at risk’ for a lender of last resort and find the necessary funds to prevent contagion to be surprisingly small. More diversification in the inter-bank market does not necessarily reduce the risk of contagion.
3) Toivanen (Reference Toivanen2009) also applies the maximum entropy method for estimating the danger of contagion in the Finnish interbank market in 2005–2007 as well as the existence of contagion during a Finnish banking crisis. The contagion analysis of the early 1990s is able to predict the most troublesome and defaulting banks in the banking sector. The simulation results for 2005–2007 suggest that five of ten deposit banks are possible starting points for contagious effects. The magnitude of contagion is conditional on the first failing bank. In addition to large commercial banks, middle-sized banks also cause damaging domino effects. Over the last few years, the negative effects of contagion on the Finnish banking sector have been, on average, more limited than those of the early 1990s. The contagion is currently a low probability event in the Finnish interbank market.
4) Furfine (Reference Furfine2003) studies the inter linkages between the US banks; this paper examines the degree to which the failure of one bank would cause the subsequent collapse of other banks. Using unique data on interbank payment flows, the magnitude of bilateral federal funds exposures is quantified. These exposures are used to simulate the impact of various failure scenarios, and the risk of contagion is found to be economically small. They find that multiple rounds of failures are unlikely, and that aggregate assets at subsequently failing banks would never be expected to exceed 1% of total commercial banking assets when loss rates are kept to historically observed levels. However, although the system-wide impact of certain failures may be small when measured by total assets of failing banks, additional failures will generally occur. Simulations of the sudden illiquidity of a major institution suggest that the potential for illiquidity contagion is greater than failure contagion. Overall, the results suggest that contagion resulting from direct interbank linkages does not necessarily present a system-wide threat to the U.S. banking system.
5) Wells (Reference Wells2004) analyses the UK interbank market. He finds that a well-functioning interbank market is essential for efficient financial intermediation. But, in exceptional circumstances, inter linkages between banks may provide a channel through which financial difficulties in an individual bank can be propagated to other banks. In the event of the failure of a large bank, there does appear to be the potential for a substantial weakening in the capital position of a number of other banks. This is important since large banks rely on high credit ratings in order to participate in certain markets. There could therefore be significant spill-over effects by this route, even in the absence of outright failure. However such a shock to the system is very unlikely since large UK-owned banks generally have high credit ratings, i.e. their probability of default is generally low.
6) Upper & Worms (Reference Upper and Worms2004) analyse interbank exposures in the German banking system. Credit risk associated with interbank lending may lead to domino effects, where the failure of one bank results in the failure of other banks not directly affected by the initial shock. Recent work in economic theory shows that this risk of contagion depends on the precise pattern of interbank linkages. They use balance sheet information to estimate the matrix of bilateral credit relationships for the German banking system and test whether the breakdown of a single bank can lead to contagion. They find that the financial safety net (institutional guarantees for saving banks and cooperative banks) considerably reduces – but does not eliminate – the danger of contagion. Even so, the failure of a single bank could lead to the breakdown of up to 15% of the banking system in terms of assets.
7) Boss et al. (Reference Boss, Elsinger, Thurner and Summer2004) provide an empirical analysis of the network structure of the Austrian interbank market based on Austrian Central Bank (OeNB) data. The interbank market is interpreted as a network where banks are nodes and the claims and liabilities between banks define the links. They apply methods from general network theory. They find that the degree distributions of the interbank network follow power laws. Given this result they discuss how the network structure affects the stability of the banking system with respect to the elimination of a node in the network, i.e. the default of a single bank. Further, the interbank liability network shows a community structure that exactly mirrors the regional and sectoral organisation of the current Austrian banking system. The banking network has the typical structural features found in numerous other complex real-world networks: a low clustering coefficient and a short average path length. These empirical findings are in marked contrast to the network structures that have been assumed thus far in the theoretical economic and econo-physics literature.
8) Degryse & Nguyen (Reference Degryse and Nguyen2006) agree with Wells (Reference Wells2004) that interbank markets are important for the well functioning of modern financial systems. Yet, a network of interbank exposures may lead to domino effects following the event of an initial bank failure. They investigate the evolution and determinants of contagion risk for the Belgian banking system over the period 1993–2002. They find that a change from a complete structure towards a ‘multiple money centre’ structure (where money centres are symmetrically linked to otherwise disconnected banks) has decreased the risk and impact of contagion. In addition, an increase in the relative importance of cross-border interbank exposures has lowered local contagion risk. Yet, this reduction may have been compensated by an increase in contagion risk stemming from foreign banks.
B.4.1.3 Newer Approaches Emphasising Complexity of Modern Financial Networks
B.4.1.3.1 More recently, given the evident instability of banking networks revealed by the current global financial crisis, there have been a variety of new approaches to studying banking networks, much of which has been carried out at the Bank of England. Haldane (Reference Haldane2009) is a useful overview of these new approaches. He discusses the importance of network relationships and considers the financial system as a complex adaptive system that applies lessons from other network disciplines such as ecology, epidemiology, biology and engineering. He uses the network theory and evidence to explain the complexity and homogeneity of the financial network. He finds that in the present financial crisis the flight is of capital not humans (as in the SARS epidemic). Yet the scale and contagious consequences may be no less damaging. This financial epidemic may endure in the memories long after SARS has been forgotten. But in halting the spread of future financial epidemics, it is important that the lessons from SARS and from other non-financial networks are not forgotten.
B.4.1.3.2 Nier et al. (Reference Nier, Yang, Yorulmazer and Alentorn2008) is an application of this new approach, presenting a framework for analysing risk in the UK financial system. They argue that systemic risk is a key concern for central banks charged with safeguarding overall financial stability. In this paper they investigate how systemic risk is affected by the structure of the financial system. They construct banking systems which are composed of a number of banks that are connected by interbank linkages. They then vary the key parameters that define the structure of the financial system – including its level of capitalisation, the degree to which banks are connected, the size of interbank exposures and the degree of concentration of the system – and analyse the influence of these parameters on the likelihood of contagious (knock-on) defaults. First, they find that the better capitalised banks are the more resilient is the banking system against contagious defaults and this effect is non-linear. Second, the effect of the degree of connectivity is non-monotonic, that is, initially a small increase in connectivity increases the contagion effect; but after a certain threshold value, connectivity improves the ability of a banking system to absorb shocks. Third, the size of interbank liabilities tends to increase the risk of knock-on default, even if banks hold capital against such exposures. Fourth, more concentrated banking systems are shown to be prone to larger systemic risk, all else equal. In an extension to the main analysis they study how liquidity effects interact with banking structure to produce a greater chance of systemic breakdown. They finally consider how the risk of contagion might depend on the degree of asymmetry (tiering) inherent in the structure of the banking system.
B.4.1.3.3 Aikman et al., (Reference Aikman, Alessandri, Eklund, Gai, Kapadia, Martin, Mora, Sterne and Willison2009) further develop this line of analysis. Their work is influenced by a framework developed by the Oesterreichische Nationalbank for the Austrian banking system (OeNB, 2006; Elsinger et al., Reference Elsinger, Lehar and Summer2006; and Wells, Reference Wells2004; but also takes greater account of the potential network instabilities of the kind discussed by Haldane, Reference Haldane2009). In particular they demonstrate how the introduction of liability-side feedbacks i.e. withdrawal of short-term funding, affects the properties of a quantitative model of systemic risk incorporating interbank exposures. The resulting model is known as Risk Assessment Model for Systemic Institutions (RAMSI) and is still in its development phase. It is based on detailed balance sheets for ten UK banks at the end of 2007 and encompasses macro-credit risk, interest and non-interest income risk, network interactions, and feedback effects. They use maximum entropy techniques on total interbank asset and liability positions to fill in missing gaps in the network. This procedure is to ensure that none of the estimated entries exceed the reporting threshold for large exposures. If any interbank assets or liabilities are unallocated following this procedure, they assume that the assets or liabilities are associated with a residual sector which cannot default. Funding liquidity risk is introduced by allowing for rating downgrades and incorporating a simple framework in which concerns over solvency, funding profiles and confidence may trigger the outright closure of funding markets to particular institutions. They focus on aggregate distributions and analysis of a scenario in which large losses at some banks can be exacerbated by liability-side feedbacks, leading to system-wide instability. They also demonstrate how defaulting financial institutions may cause contagion by triggering default cascades through the interbank market; selling assets at fire sale prices; and through undermining confidence in other banks.
B.5. Banking Crisis Resolution
B.5.1 Hoggarth et al., (Reference Hoggarth, Reidhill and Sinclair2003) review the merits of the various techniques used by authorities when resolving individual or widespread bank failures in developed and emerging market economies. In particular, the various banking crisis resolution techniques available to the authorities are classified and then compared with the techniques that have been used in practice, drawing on both the available evidence and their own analysis. With individual bank failures the authorities usually first seek a private sector solution. Any losses are passed on to existing shareholders, managers and sometimes uninsured creditors, and not to taxpayers. But policy options are more limited in system wide crises. In most recent system wide crises, early on, central banks have provided liquidity to failing banks and governments have given blanket guarantees to depositors. In nearly all cases, investor panics have been quelled but at a cost to the budget and increasing the risk of future moral hazard. Open-ended central bank liquidity support seems to have prolonged crises, thus increasing rather than reducing the output costs to the economy.
B.5.2 Bank restructuring has usually occurred through mergers, often government assisted, and some government capital injection or increase in control. Bank liquidations have been rare and creditors – including uninsured ones – have rarely made losses. In system wide crises, resolution measures have been more successful in financial restructuring than in restoring banks’ ongoing profitability or credit to the private sector.
B.5.3 Honohan & Klingebiel (Reference Honohan and Klingebiel2000) try to quantify the extent to which fiscal outlays incurred in resolving banking distress can be attributed to crisis management measures of a particular kind adopted by the government in the early years of the crisis. They find evidence that certain crisis management strategies appear to add greatly to fiscal costs: unlimited deposit guarantees, open ended liquidity support, repeated recapitalisation, debtors bail-outs, and regulatory forbearance. Their findings clearly tilt the balance in favour of a strict rather than an accommodating approach to crisis resolution. At the very least, regulatory authorities who choose an accommodating or gradualist approach to an emerging crisis must be sure they have some other way to control risk taking.
B.5.4 Klingebiel (Reference Klingebiel2000) argues that Asset Management Company's (AMC) are rarely good tools to accelerate corporate restructuring. Only the Swedish AMC successfully managed its portfolio, acting in some instances as lead agent in the restructuring process. It was helped by some special circumstances – the assets acquired were mostly real estate related, not manufacturing that are harder to restructure, and were a small fraction of the banking system which made it easier for the AMC to maintain its independence from political pressures and to sell assets back to the private sector. Rapid asset disposition vehicles fared somewhat better with two out of four agencies, namely Spain and the US, achieving their objectives. The successful experiences suggest that AMCs can be effectively used, but only for the purpose of asset disposition including resolving insolvent and unviable financial institutions. But even achieving these objectives required many ingredients: a type of asset that is easily liquifiable – real estate, mostly professional management, political independence, a skilled resource base, appropriate funding, adequate bankruptcy and foreclosure laws, good information and management systems and transparency in operations and processes.
B.5.5 Claessens et al. (Reference Clæssens, Klingebiel and Laeven2004) have examined the impact of accommodative policy instruments and the quality of the institutional frameworks on the effectiveness of crisis resolutions as measured by the size of the fiscal costs associated with the resolution of systemic crises, economic output losses, and differential value added growth rates. They find more accommodative policy measures to be fiscally costly, as already documented by Honohan & Klingebiel (Reference Honohan and Klingebiel2003) and several aspects:
(1) output losses are not reduced by any of these accommodative policy measures;
(2) more evidence that applying accommodative policies, such as liquidity support, slows down the economic recovery; and
(3) better institutional development-less corruption, better law and order, higher quality of the bureaucracy, and a more efficient judicial system is uniformly positively associated with lower fiscal costs, lower output loss and faster recovery.
The degree of institutional development does not, however, displace the importance of policy as a determinant of fiscal costs and speed of recovery. Overall, the results suggest that accommodative policy measures to support the financial sector – such as extensive liquidity support, unlimited guarantees and regulatory forbearance – are not only fiscally costly but also do not speed up recovery and often even slow down the economic recovery. At the same time, the results suggest that sound legal and other institutions are important components for a crisis resolution that is not only cost-effective but also speedy. The best approach for a country to resolve a systemic crisis appears to be to implement strict resolution policies and improve its institutional framework.
B.5.6 Laeven & Valencia (Reference Laeven and Valencia2008) find that in episodes of significant banking distress or perceived systemic risk to the financial system, policymakers have often opted for issuing blanket guarantees on bank liabilities to stop or avoid widespread bank runs. In theory, blanket guarantees can prevent bank runs if they are credible. However, such guarantees add substantial fiscal costs to bank restructuring programs and may increase moral hazard going forward. They find that blanket guarantees are successful in reducing liquidity pressures on banks arising from deposit withdrawals. However, banks’ foreign liabilities appear virtually irresponsive to blanket guarantees. Furthermore, guarantees tend to be fiscally costly, though this positive association arises in large part because guarantees tend to be employed in conjunction with extensive liquidity support and when crises are severe.
B.5.7 Kane (Reference Kane2008) argues that systemic crises occur when governmental strategies for preventing and resolving financial-institution insolvencies fail massively. He employs market-mimicking strategies for preventing and managing financial crises. He suggests that credible strategies include:
(1) efficient prevention, focusing on enforcing adequate levels of bank capital and being prepared to resolve institutional insolvencies expeditiously when they arise; and
(2) efficient crisis management, which requires officials to develop, staff, rehearse, update, promulgate and commit themselves irrevocably to a market-mimicking plan for managing systemic banking disasters.
B.6 Insurance Crises
We have identified a number of papers on insurance problems. However it is important to state that none of these papers are on systemic problems. We include them here only to demonstrate that, while there is some work on large aggregate shocks, none of this concerns systemic risk.
2003
B.6.1 Insurance Related Literature
B6.1.1 Miranda & Glauber (Reference Miranda and Glauber1997) study systematic risk in agriculture. They find that the US private crop insurance markets are very likely to fail without the reinsurance provided by the government. The authors suggest that systematic risk destroys a crop insurer's ability to diversify risks across farms, crops, or even regions, and prevents it from performing the essential function of an insurance intermediary. Systematic risk of agriculture comes from the impact of geographically extensive unfavorable weather events, which is highly correlated among individual farm-level yields. These systematic risks causes crop insurers to bear a higher risk than other property liability and business insurers. The authors suggest that area-yield reinsurance and area-yield options contracts offer a potential solution to the systematic risk problems.
B.6.1.2 Allen & Jagtiani (Reference Allen and Jagtiani2000) examine the impact on total risk and systemic risk of combining commercial banking, securities, and insurance activities in the absence of any synergistic gains. They use US monthly data from January 1986 to December 1994 for bank holding companies, insurance companies and securities firms interest rate index from Citibase. They find that the overall risk of the ‘synthetic universal bank’ will likely reduce, but the systematic risk will rise. They argue that the systematic risk may be considered a proxy for the systemic risk faced by the US banking system; i.e., if the systematic risk increases, it would be more likely that a common shock could lead to massive bank failures across the entire banking system. The results from the regression show that the universal bank will have a smaller overall risk; however, it is also shown that the ability of the universal bank to diversify will be lowered with the intensity of the securities underwriting activities. Unlike securities underwriting, insurance activities have no significant impact on the universal bank's exposure to market risk.
B.6.1.3 Jaffee & Russell (Reference Jaffee and Russell2002) discuss terrorist insurance. They point out that terrorist insurance is just a specific type of casualty risk, and is therefore not a special kind of extreme event. However, the terrorist insurance may be of a significantly different degree (the premium loading and the number of investors necessary to induce insurers to hold a terrorist insurance portfolio is likely to be larger than the traditional portfolios). The authors answer the first question (Why did the terrorist market collapse so abruptly?) by describing the post event behavior, which has two aspects:
(1) There are difficulties in accessing capital markets ex post because an insurance firm is unlikely to issue new securities following a high-loss event, because:
(a) potential investors in the new securities will suspect that their funds will be used to pay off past losses, not to support future investments;
(b) potential investors evaluate future risks at a higher level and therefore require a lower price for the new securities than the firm is willing to accept.
(2) Irrational abhorrence which is a psychological behavior after the extreme event.
To the second question (What is the best public policy response to the failure of insurance markets following the occurrence of an extreme event?) the authors suggest three approaches:
(1) a limited liability pool;
(2) the government as the insurer last resort; and
(3) using CAT bond as the insurer last resort.
B.7 Case Studies on Individual Crises
B.7.1 Pre-1930s Crisis
B.7.1.1 Andrew (Reference Andrew1908a) argues that the 1907 crisis was probably the most extensive and prolonged breakdown of the US's credit mechanism to have occurred since the establishment of the US's banking system. The banks of so many cities in the US resorted to clearing house loan certificates for the settlement of their mutual obligations. These certificates were extensively issued in small denominations to meet ordinary bank obligations in lieu of cash. During the panic of 1893 eight cities were reported to have employed them; but during the disturbance of 1907 they were used by no less than 42. In 1893 their issue was confined mainly to the North-east, New Orleans being the only southern city, and Detroit the most western example, but in 1907 their use knew no geographic limitations. They were issued in several cities of California, Washington and Oregon, in cities of Texas, Alabama, Louisiana, and Arkansas and in most every sizable city of the Middle West. He concludes that during the period of apprehension, when banks were being run upon and legal money had disappeared in hoards, in default of any legal means of relief, the certificates worked effectively and doubtless prevented multitudes of bankruptcies which otherwise would have occurred.
B.7.1.2 Andrew (Reference Andrew1908b) finds that the 1907 crisis was surprisingly resemblant in several of its features to the crises of 1837, 1857, 1873, and 1893. It was marked by an outburst of fright as wide-spread and unreasoning as before, by the suspension of cash payments on the part of a very large proportion of US's sixteen thousand banks, by the issue of private and unauthorised currency in multitudes of towns and cities, and by the appearance and continuance during two months of a considerable premium upon legal money. They indicate the scale of the hoarding by highlighting the fact that the net loss of cash by all of the national banks of the country reached a total of US$41 million whereas the government had to injected deposits of cash by about US$72 million and the increase of safe deposit boxes by six times to 789 safes and this occurred in many safe deposits companies in the US.
B.7.1.3 Collins (Reference Collins1989) seeks to answers some questions of the 1878's crisis, whether it was still vulnerable to ‘unsafe’ banking practices and still susceptible to liquidity panics? Or had the process of consolidation, of professionalisation, carried the bankers beyond the more volatile decades of the early and mid-nineteenth century to a sounder business environment? To answer the questions, he uses Schwartz's (Reference Schwartz1986) distinction between ‘real’ and ‘pseudo’ crises. In a real crisis there is a general fear that commercial bank money may lose its convertibility to legal tender as banks close down. He finds that in general the conclusion is that the 1878 crisis was much more important than has been allowed for by many historians. The 1878 crisis occurred in the whole of Britain. The sharp contraction of bank liabilities, the jump in bank reserves, and the increase in the public's holdings of high powered money, all meet Schwartz's criteria for a ‘real’ crisis. The fact that the commercial viability of most banks remained intact – that there was no extensive list of bank failures – does not detract from this conclusion; this was also characteristic of other mid nineteenth-century crises.
B.7.2 1930s Banking Crises
B.7.2.1 White (Reference White1981) highlights the failure of state deposit guarantee systems to stem the US bank failures of the 1920s and the weakness of the banking industry during the crises of the 1930s. Before the creation of the Federal Deposit Insurance Corporation in 1933, several states established deposit guarantee funds. The key factor influencing the adoption of deposit insurance by a state was the structure of its banking industry. The problem engendered a weak solution in the form of state deposit insurance. The inherent weaknesses of the state guarantee funds in turn contributed to the problems of the banking industry. It was appropriate that the federal government should finally assume the job of insuring banks. With a well designed system, an individual state could insure banks only as long as a deflation or other general financial disturbance did not bring about widespread bank failures. The Federal Deposit Insurance Corporation's successful operation was not threatened by this problem because the risk to which the entire banking system was exposed could be controlled by the Federal Reserve System's open market operations or discounting.
B.7.2.2 Bernanke (Reference Bernanke1983) finds the financial collapse of the early 1930's had real effects on the macroeconomy. However, standard economic analysis has difficulties with the reconciliation of the obvious sub-optimality of this period with the postulate of reasonably rational, market-constrained agents. The solution to this paradox lies in recognising that economic institutions, rather than being a ‘veil,’ can affect costs of transactions and thus market opportunities and allocations. Institutions which evolve and perform well in normal times may become counterproductive during periods when exogenous shocks or policy mistakes drive the economy off course. The malfunctioning of financial institutions during the early 1930's exemplifies this point.
B.7.2.3 Bernanke (Reference Bernanke1995) argues that banking panics in a country significantly reduce the Ml money stock and significantly lower the money multiplier. This effect on the money supply is actually inconsistent with a simple Mundell-Fleming model of a small open economy on the gold standard. Possible reconciliations of the empirical result with the model are that banking panics lowered domestic M1 money demand or raised the probability of exchange-rate devaluation; the finding that panics raised the real interest rate fits with the latter possibility. They also find a consistency with the Mundell-Fleming model, once gold-standard membership is controlled for, that banking panics had no effect on wholesale prices. This suggests that the observed effects of panics on output and other real variables are operating largely through non-monetary channels, for example, the disruption of credit flows.
B.7.2.4 Calomiris & Mason (Reference Calomiris and Mason2003) seek to:
(1) gauge the extent to which the attributes of specific banks, in concert with local or national shocks that buffeted those banks, can explain the timing and incidence of bank failures;
(2) evaluate the importance of panic or contagion – nationally or locally – as a cause of bank failure during the Depression; and
(3) identify the extent to which particular banking crises were national or regional events. They find that fundamentals explain bank failure risk well.
They focus on four crises that feature in the Friedman-Shwartz Monetary History of the United States. The first two Friedman-Schwartz crises are well explained by bank specific and aggregate factors. There is little unexplained residual failure risk that suggests a contagion or panic. The third Friedman-Schwartz crisis is more ambiguous, but residual failure risk is small in the aggregate. The final crisis (early 1933) saw a large unexplained increase in bank failure risk. They conclude that local contagion and illiquidity may have played a role in pre-1933 bank failures, even though those effects were not large in their aggregate impact.
B.7.3 Latin American Debt Crisis
B.7.3.1 Theberge (Reference Theberge1999) concludes that several trends emerge from the history of the Latin American debt crisis. The problem started following a shift from government borrowing to commercial borrowing from 1820. This leads to most of Latin America's debt in 1980. The use of debt to finance military expenditure, while persisting since 1820 has generally decreased as a proportion of total Latin American debt. Argentina, Brazil, Chile and Peru continued to borrow in the 1970s to establish a more sophisticated army, but the loans were small relative to the private sector. Similarities between the 1980s crisis and its predecessors are mainly to be found in the general causes of the crisis. Most of Latin America's crises followed a long period of economic expansion. All the Latin American debt crises, excepting the Great Depression, have been preceded by fervent borrowing, peaking during the three years preceding default (1822–1825, 1870–1873, 1977–1980). A debt crisis consistently follows three inter-related exogenous shocks: a steep fall in commodities’ prices, instability in the financial markets of the first world and recessions abroad. In all four major Latin American debt crises, commercial bankers in the United States and Europe were main sources of capital. The differences between the debt crisis of the 1980s and its precursors are equally striking and more numerous. The 1980s crisis, while sparked by the official default of the Mexican government, was generally a crisis of the private sector. The majority of the debt was held in non-guaranteed private sector loans which were eventually nationalised to meet obligations.
B.7.4 S&L Crisis in 1980s
B.7.4.1 White (Reference White1991) shows that, rather than the result of widespread fraud, the crisis was rooted in the highly unusual economic conditions of the early 1980s, poorly thought-out deregulatory policies and flawed accounting practices. The S&L Debacle reveals that the banking system of the late 1970s was anachronistic. Tightly regulated thrifts were locked into portfolios of long-term mortgages and limited in the interest rates that they could pay to depositors. When interest rates soared, the thrifts experienced heavy losses. Clearly, adjustment in the industry was necessary, and the economic deregulatory policies implemented in the early 1980s were long overdue. But White points out that these policies should have been accompanied by strengthened safety-and-soundness regulations. Instead, safety-and-soundness rules were also deregulated, bringing a deadly combination of opportunities, capabilities and incentives for risk-taking that spelled disaster for hundreds of thrifts – and ultimately for the FSLIC insurance fund and the US taxpayer. White offers far-reaching recommendations for reform, such as better methods of gathering information about thrifts before they become insolvent, risk-related net worth requirements, risk-based insurance premiums – so that deposit insurance is treated more like other forms of insurance – and stronger powers of early intervention by regulators.
B.7.5 Japanese Banking Crisis
B.7.5.1 Ueda (Reference Ueda1998) argues that the major cause of the bad loans problem in Japan in the 1990s has been the speculative real estate related lending of the 1980s, and the volatile asset price movements that were mainly the result of monetary policy. In addition, the unfortunate combination of financial liberalisation and the segmentation approach to the banking sector has aggravated the extent of speculation. The increasing absence of monitors of bank behaviour under the Japanese safety net system may have played a role. Given that the mistake made by the BOJ in the late 1980s seems to have been due to outside intervention, the current discussion on the desirability of the BOJ's increased independence or improved coordination between monetary policy and other policies is timely and important. The traditional lines of segmentation between various branches of the banking industry are now obsolete. However, financial liberalisation must be accompanied by necessary skills to operate in a deregulated environment. The lesson they can learn from the current banking crisis is that the way, speed and order of liberalisation are difficult choice variables. Finally, in any event, they would have to move to a system with safety nets in which the force of market mechanism plays a more important role. Unfortunately, the public money necessary to close the already insolvent financial institutions has been hard to come by. Instead, healthier banks have been taxed. Thus, the resolution of the troubled banks and of Jusen carried out in the last year and a half seems to be slowing down the pace of transition.
B.7.5.2 Hoshi (Reference Hoshi2001) employs cross-sectional variation of growth in real estate lending and nonperforming loans. He argues that even if land prices in Japan recover, the fundamental problem of the Japanese banking sector will not go away. The solution is found in the completion of financial deregulation, which will allow depositors to migrate out of bank deposits and allow traditional banking business to shrink to fit the demand for bank loans by corporations. The incomplete deregulation in the 1980s created ‘over-banking’ which eventually led to the crisis in Japanese banking. The Big Bang deregulation completes the long process of deregulation in the Japanese financial system. When the effects of the Big Bang are all played out, the Japanese banking sector will be smaller. The banks that survive the transition will be much healthier and profitable than they really were in the ‘golden decade’ of the 1980s.
B.7.5.3 Nakaso (Reference Nakaso2001) addresses several issues:
(1) the chronology of events and the policy responses by the authorities and describes the evolutionary way in which the safety net in Japan was reinforced;
(2) identification of factors that explain why it has taken so long to bring the crisis under control;
(3) the central bank's lender of last resort function as the key policy tool in addressing the crisis. By categorising various types of emergency fund provision by the central bank, the paper explores whether the responsibility of the central bank might have been overstretched during the earlier part of the crisis;
(4) different aspects of Japan's experience that stand out relative to other countries that have undergone banking crises;
(5) information or indices that could effectively warn the authorities of build-up of risks in the financial system;
(6) the new safety net that became effective in April 2001 and the key features incorporated in the new framework following lessons learned in the crisis management during the 1990s; and finally,
(7) the future challenges for the central bank and the Japanese banking industry.
B.7.5.4 Cowling & Tomlinson (Reference Cowling and Tomlinson2000) argue that Japan's economic stagnation primarily reflects a structural change that has occurred because of the activities of Japan's large transnationals. They would not, of course, suggest that monetary and financial factors, and related exchange rate movements, have not played a part in the stagnation of the Japanese economy. There are many features of Japanese institutions and policy-making, which have undoubtedly played a significant role in both precipitating and extending the crisis. Yet, underpinning these explanations, they see a more fundamental one of the changing structure of production created by Japan's large transnationals. In particular, the growth in outsourcing has had serious implications for Japan's trade balance, domestic production and employment, whilst Japan's keiretsu firms have become increasingly isolated. This has also had important repercussions for macro economic policy, industrial development and future economic growth.
B.7.6 Nordic Banking Crisis
B.7.6.1 Drees & Pazarbasioglu (Reference Drees and Pazarbasioglu1995) examine the banking crises in Finland, Norway and Sweden in an attempt to draw some policy conclusion. They find that in all three countries, the timing of deregulation coincided with a strongly expansionary macroeconomic momentum. Delayed policy responses, as well as structural characteristics of the financial systems and banks’ inadequate internal risk management controls were important determinants of the consequences of the transition from tightly regulated to more or less competitive financial systems. In the absence of strengthened prudential banking supervision, these incentives coupled with expectations of government intervention in the event of a crisis prompted many Nordic banks to increase their lending excessively.
B.7.7 Indonesian Banking Crisis
B.7.7.1 Enoch et al. (Reference Enoch, Baldwin, Frecaut and Kovanen2001) look at the first two years of the banking crisis that erupted in Indonesia in late 1997. They find that the banking sector was weak at the outset and that governance problems intensified the crisis and seriously delayed its resolution. Although a strategy was put in place over the initial months, protracted delays in implementation led to an explosion in the costs of resolution. By end-1999, the critical elements to reconstruct the banking system were in place, and the political transition seemed completed; but, in a continuing unsettled environment, the new authorities still faced daunting challenges.
B.7.8 Chilean Banking Crisis
B.7.8.1 Sanhueza (Reference Sanhueza2001) reviews the solutions to the Chilean banking crisis of the 1980s and analyzes their effects on banks, deriving policy lessons from this analysis. He also estimates the cost of the rescue of each institution. The three main solutions to the crisis were:
(1) foreclosure of insolvent institutions or transfer of their assets and liabilities to the solvent institutions;
(2) acquisition of high-risk portfolio (bad loans) under condition of repurchase without provision of fresh funds; and
(3) acquisition of high-risk portfolios under condition of repurchase through future profits with provision of fresh funds.
He finds that the third alternative was the most efficient for the recovery of a significant number of financial institutions with solvency problems. Supporting bank re-capitalisation and creating incentives for recovering bad loans helped to accelerate the recovery of the banking industry. The total cost was significant. The cost of foreclosure of insolvent institutions was 10.6% of the GDP and the cost of portfolio purchase under conditions of repurchase reached 6.7% of the GDP.
B.7.9 Ecuadorian Banking Crisis
B.7.9.1 Jacome (Reference Jacome2004) stresses three factors which amplified the 1990s financial crisis in Ecuador, namely institutional weaknesses, rigidities in public finances and high financial dollarisation. He finds that institutional factors restricted the government's ability to respond in a timely manner and efficiently enough to prevent the escalation of the banking crisis and spurred the adoption of suboptimal policy decisions. Public finance rigidities limited the government's capacity to correct existing imbalances and the deteriorating fiscal stance associated with the costs of the financial crisis. Financial dollarisation increasingly reduced the effectiveness of financial safety nets, fostered foreign currency demand and accelerated a currency crisis, thereby further worsening the solvency of banks. These three factors reinforced each other, exacerbating costs as the economy went through a triple banking, currency, and fiscal crisis.
B.7.9.2 Hildebrand (Reference Hildebrand2008) argues that a local problem became a global crisis because of poor risk management, lack of transparency and excessive leverage. Not only does the capital base need re-building but also incentive schemes need reconsideration. The crisis is not yet over; the housing market continues to deteriorate and there is spill-over into other markets. Growth is declining, with potentially self re-enforcing mechanisms between financial markets and the real economy coming into play.
B.8. Policy Orientated Papers
B.8.1 Kashyap et al. (Reference Kashyap, Rajan and Stein2008) seek the answer as to why were banks so vulnerable to problems in the mortgage market? What does this vulnerability say about the effectiveness of current regulation? How should regulatory objectives and actual regulation change to minimise the risks of future crises? Their brief answers are as follows. The proximate cause of the credit crisis (as distinct from the housing crisis) was the interplay between two choices made by banks. First, substantial amounts of mortgage-backed securities with exposure to subprime risk were kept on bank balance sheets even though the ‘originate and distribute’ model of securitisation that many banks ostensibly followed was supposed to transfer risk to those institutions better able to bear it, such as unleveraged pension funds. Second, across the board, banks financed these and other risky assets with short-term market borrowing. This combination proved problematic for the system. As the housing market deteriorated, the perceived risk of mortgage-backed securities increased, and it became difficult to roll over short-term loans against these securities. Banks were thus forced to sell the assets they could no longer finance, and the value of these assets plummeted, perhaps even below their fundamental values – i.e., funding problems led to fire sales and depressed prices. And as valuation losses eroded bank capital, banks found it even harder to obtain the necessary short-term financing – i.e., fire sales created further funding problems, a feedback loop that spawned a downward spiral. Bank funding difficulties spilled over to bank borrowers, as banks cut back on loans to conserve liquidity, thereby slowing the whole economy. In their view, a better approach is to recognise up front that there will be a need for recapitalisation during certain crisis states and to ‘pre-wire’ things so that the private sector – rather than the government – is forced to do the recapitalisation. In other words, if the fundamental market failure is insufficiently aggressive recapitalisation during crises then regulation should seek to speed up the process of private-sector recapitalisation.
B.8.2 Brunnermeier et al. (Reference Brunnermeier, Crickett, Goodhart, Persaud and Shin2009) suggest that financial regulation should be focused, primarily rule-based (because discretion will be hard to use during periods of boom/euphoria), and time and state-varying (light during normal periods, increasing as systemic threats build up). Their key points and recommendations include:
(1) the main cause of externalities arises because the social cost of systemic financial collapse exceeds the private cost to the individual financial institutions (and markets);
(2) a collapse of a financial institution causes risk spillovers;
(3) effective regulation should provide incentives for financial institutions to internalise these externalities (risk spillovers);
(4) the main cause of systemic collapse is endogenous risk, the likelihood of self-amplifying spirals like the loss and margin spiral; and
(5) they propose a ‘mark to funding’ approach to provide incentives for more long-term funding.
The approach (5) is, in effect, closely akin to the maturity mis-match ladder previously considered by the Basel Committee on Banking Supervision (BCBS) and by some Central Banks.