




No CrossRef data available.
COMPOUND RANDOM VARIABLES
Published online by Cambridge University Press: 01 October 2004
Abstract
We give a probabilistic proof of an identity concerning the expectation of an arbitrary function of a compound random variable and then use this identity to obtain recursive formulas for the probability mass function of compound random variables when the compounding distribution is Poisson, binomial, negative binomial random, hypergeometric, logarithmic, or negative hypergeometric. We then show how to use simulation to efficiently estimate both the probability that a positive compound random variable is greater than a specified constant and the expected amount by which it exceeds that constant.
Information
- Type
- Research Article
- Information
- Probability in the Engineering and Informational Sciences , Volume 18 , Issue 4 , October 2004 , pp. 473 - 484
- Copyright
- © 2004 Cambridge University Press
1. INTRODUCTION AND SUMMARY
Let X1,X2,… be a sequence of independent and identically distributed (i.i.d.) positive random variables that are independent of the nonnegative integer-valued random variable N. The random variable
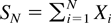
is called a compound random variable. In Section 2, we give a simple probabilistic proof of an identity concerning the expected value of a function of a compound random variable; when the Xi are positive integer-valued, an identity concerning the probability mass function of SN is obtained as a corollary. In Section 3, we use the latter identity to provide new derivations of the recursive formulas for the probability mass function of SN when X1 is a positive integer-valued random variable, and N has a variety of possible distributions. For other derivations of the applications of Section 3, the reader should see the references.
Sections 4 and 5 are concerned with finding efficient simulation techniques to estimate
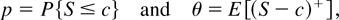
where c is a specified constant and the Xi need not be discrete. Because
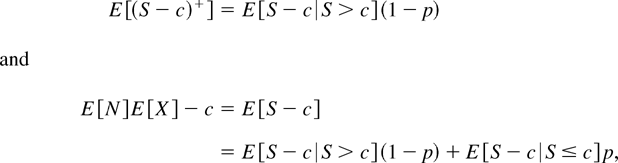
it follows that estimating p and θ will also give us estimates of E [S − c|S > c] and E [c − S|S ≤ c]. Although our major interest is when the Xi are positive, in Section 5 we show how an effective simulation can be performed when this restriction is removed.
2. THE COMPOUND IDENTITY
Consider the compound random variable
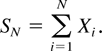
Let M be independent of X1,X2,… and such that
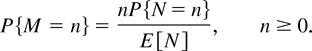
The random variable M is called the sized bias version of N. (If the interarrival times of a renewal process were distributed according to N, then the average length of a renewal interval containing a fixed point would be distributed according to M.)
Theorem 2.1 (The Compound Identity): For any function h,
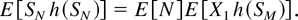
Proof:
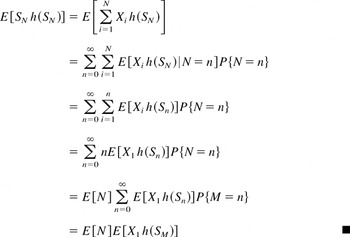
Corollary 2.1: If X1 is a positive integer-valued random variable with αi = P{X1 = i}, then
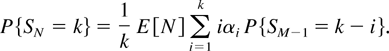
Proof: For an event A, let I(A) equal one if A occurs and let it equal zero otherwise. Then, with h(x) = I(x = k), the compound identity yields that

3. SPECIAL CASES
Suppose that X1 is a positive integer-valued random variable with αi = P{X1 = i}.
3.1. Poisson Case
If
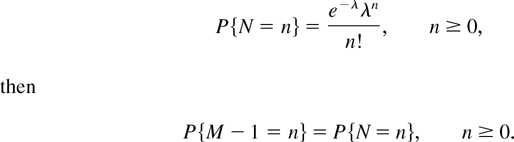
Therefore, the corollary yields the well-known recursion
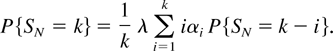
3.2. Negative Binomial Case
For a fixed value of p, we say that N is an NB(r) random variable if
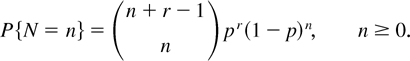
Such a random variable can be thought of as being the number of failures that occur before a total of r successes have been amassed when each trial is independently a success with probability p.
If M is the size-biased version of an NB(r) random variable N, then
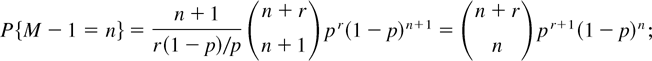
that is, M − 1 is an NB(r + 1) random variable.
Now, for N an NB(r) random variable, let
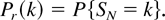
The corollary now yields the recursion
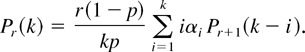
For instance, starting with

the recursion yields
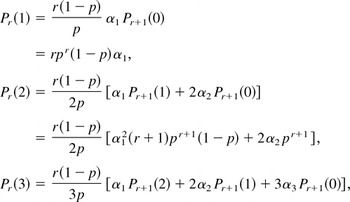
and so on.
3.3. Binomial Case
If N is a binomial random variable with parameters r and p, then
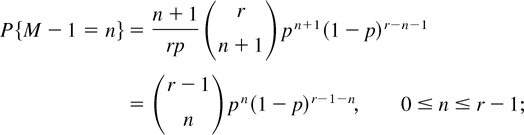
that is, M − 1 is a binomial random variable with parameters r − 1 and p.
For a fixed p, let
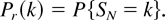
The corollary then yields the recursion
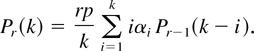
3.4. Hypergeometric Case
Let N = N(w,r) be a hypergeometric random variable having the distribution of the number of white balls chosen when a random sample of r is chosen from a set of w white and b blue balls; that is,
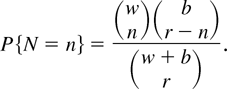
Then, it is straightforward to check that
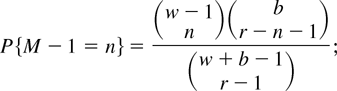
that is, M − 1 has the same distribution as N with the modification that w becomes w − 1 and r becomes r − 1. Letting
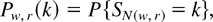
then
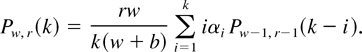
This yields
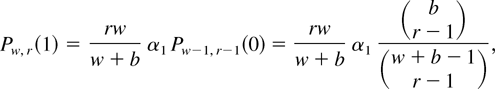
and so on. (We are using the convention that

if either k < 0 or k > n.)
3.5. The Logarithmic Count Distribution
Suppose that for 0 < β < 1,
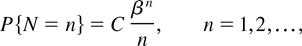
where C = −1/ln(1 − β). Then,

that is, M − 1 has the negative binomial distribution of Subsection 3.2 with r = 1 and p = 1 − β. Thus, the recursion of Subsection 3.2 and the corollary yield the probabilities P{SN = k}.
3.6. The Negative Hypergeometric Distribution
Suppose that N has the distribution of the number of blue balls chosen before a total of r white balls have been amassed when balls are randomly removed from an urn containing w white and b blue balls; that is,
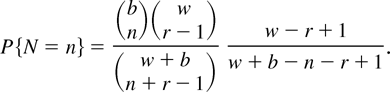
Using E [N] = rb/(w + 1), we obtain
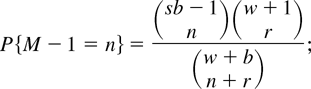
that is, M − 1 has a hypergeometric distribution, implying that the probabilities P{SM−1 = j} can be obtained from the recursion of Subsection 3.4. Applying the corollary then gives the probabilities P{SN = k}.
4. ESTIMATING P{S ≤ c}
The raw simulation approach to estimate p = P{S ≤ c} would first generate the value of N, say N = n, then generate the values of X1,…,Xn and use them to determine the value of the raw simulation estimator:
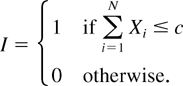
The average value of I over many such runs would then be the estimator of p.
We can improve upon the preceding by a conditional expectation approach that starts by generating the values of the Xi in sequence, stopping when the sum of the generated values exceeds c. Let M denote the number that are needed; that is,
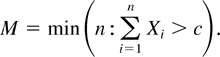
If the generated value of M is m, then we use P{N < m} as the estimate of p from this run. To see that this results in an estimator having a smaller variance than does the raw simulation estimator I, note that because the Xi are positive,
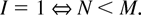
Hence,
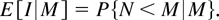
Now,
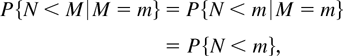
where the final equality used the independence of N and M. Consequently, if the value of M obtained from the simulation is M = m, then the value of E [I|M] obtained is P{N < m}.
The preceding conditional expectation estimator can be further improved by using a control variable. Let μ = E [Xi], and define the zero mean random variable
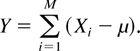
Because Y and the conditional expectation estimator P{N < M|M} are (strongly) negatively correlated, Y should make an effective control variable.
4.1. Improving the Conditional Expectation Estimator
Let M be defined as earlier and write
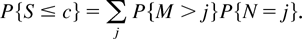
The conditional expectation estimator is obtained from the preceding by generating M and using I {M > j} as the estimator of P{M > j}.
We now show how to obtain a more efficient simulation estimator of P{M > j}. Let F denote the distribution function of Xi and write

If we now simulate X1 conditional on the event that it is less than or equal to c, then for this value of X1, the estimator
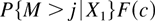
is an unbiased estimator of P{M > j} having a smaller variance than I {M > j}. Let x1 ≤ c be the generated value. For j > 1, we have
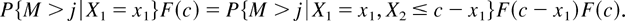
Hence, generating X2 conditional on the event that X2 ≤ c − x1 gives, when this generated value is x2, the estimate
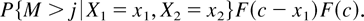
By continuing in this manner it follows that we can obtain, for any desired value n, estimates of P{M > j}, j = 1,…,n. We can then obtain estimators of the probabilities P{M > j}, j > n, by switching to an ordinary simulation. With ej denoting the estimator of P{M > j}, we obtain their values as follows.
1. e0 = 1, s = 0.
2. I = 1.
3. eI = F(c − s)eI−1.
4. Generate X conditional on X ≤ c − s. Let its value be X = x.
5. s → s + x, I → I + 1.
6. If I ≤ n, go to 3.
7. Generate X1,… until their sum exceeds c − s. Let R denote the number needed; that is,

8. en+k = en I {R > k}, k ≥ 1.
The estimator of P{S ≤ c} from this run is
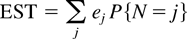
and its average over many runs is the overall estimate.
4.2. A Simulation Experiment
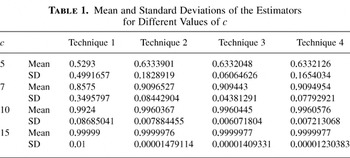
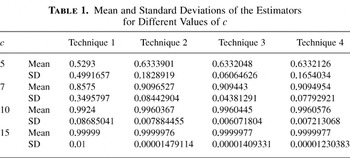
In this subsection, we give the numerical results of a simulation study done to evaluate the performance of the techniques 1–4. We let Xi be independent and identically distributed (i.i.d.) uniform (0,1) random variables and let N be Poisson, having mean 10. Table 1 summarizes the standard deviations of the estimators for different values of c. Ten thousand replications were done for each value of c to estimate
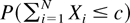
. Technique 1 is the raw simulation method; technique 2 is the conditional expectation method; technique 3 is the conditional expectation method along with the control variable (3); technique 4 uses the estimator (4). The raw estimator (technique 1), as expected, performs poorly and the other estimators perform much better.
Mean and Standard Deviations of the Estimators for Different Values of c
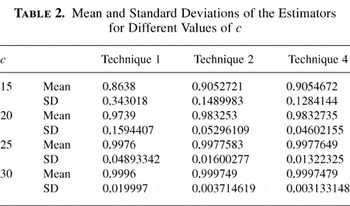
Next, we let Xi be i.i.d. exponential random variables with mean 1, and, again, let N be Poisson, having mean 10. Table 2 summarizes the standard deviations of the estimators for different values of c. Ten thousand replications were done for each value of c to estimate
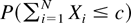
.
Mean and Standard Deviations of the Estimators for Different Values of c
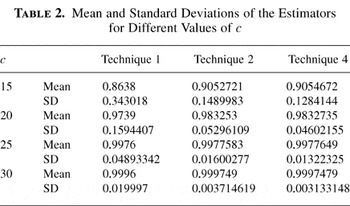
Thus, based on this small experiment, it appears that the reduction in variance effected by technique 4 over technique 2 is not worth the additional time that it takes to do a simulation run. Moreover technique 3, which does not require much more additional time than either technique 1 or technique 2, usually gives an even smaller variance than technique 4.
5. ESTIMATING θ = E [(S − c)+]
Start by letting
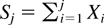
and note that
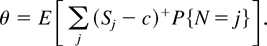
To estimate θ, follow the procedure of (2) and generate the sequence X1,…, stopping at
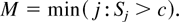
Let
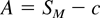
and use the estimator

that is, if the generated values of M and A are m and a, then the estimate of θ from that run is
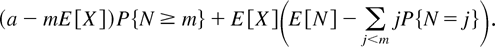
6. WHEN THE Xi ARE UNCONSTRAINED IN SIGN
When the Xi are not required to be positive, our previous methods no longer apply. We now present an approach in the general case. To estimate p, note that for a specified integer r,
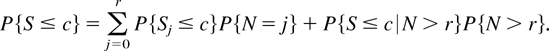
Our approach is to choose a value r and generate the value of N conditional on it exceeding r; if this generated value is g, then simulate the values of S1,…,Sr and Sg. The estimate of p from this run is
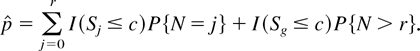
The larger the value of r chosen, the smaller the variance of this estimator. (When r = 0, it reduces to the raw simulation estimator.)
Similarly, we can estimate θ by using
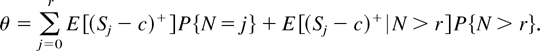
Hence, using the same data generated to estimate p, the estimate of θ is
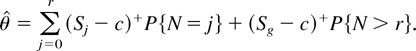
Acknowledgment
This research was supported by the National Science Foundation grant ECS-0224779 with the University of California.
References
REFERENCES
Chan, B.
(1982).
Recursive formulas for discrete distributions.
Insurance: Mathematics and Economics
1(4):
241–243.Google Scholar
Panjer, H.H.
(1981).
Recursive evaluation of a family of compound distributions.
ASTIN Bulletin
12:
22–26.Google Scholar
Panjer, H.H. &
Willmot, G.E.
(1982).
Recursions for compound distributions.
ASTIN Bulletin
13:
1–11.Google Scholar
Ross, S.
(2002).
SIMULATION,
3rd ed.,
San Diego, CA:
Academic Press.
Schroter, K.J.
(1990).
On a family of counting distributions and recursions for related
compound distributions.
Scandinavian Actuarial Journal
3/4:
161–175.Google Scholar
Sundt, B.
(1992).
On some extensions of Panjer's class of counting
distributions.
ASTIN Bulletin
22:
61–80.Google Scholar
Sundt, B. &
Jewell, W.S.
(1981).
Further results on a recursive evaluation of compound
distributions.
ASTIN Bulletin
12:
27–39.Google Scholar
Willmot, G.E.
(1993).
On recursive evaluation of mixed Poisson probabilities and related
quantities.
Scandinavian Actuarial Journal
2:
114–133.Google Scholar
Willmot, G.E. &
Panjer, H.H.
(1987).
Difference equation approaches in evaluation of compound
distributions.
Insurance: Mathematics and Economics
6:
43–56.Google Scholar
Mean and Standard Deviations of the Estimators for Different Values of c
Mean and Standard Deviations of the Estimators for Different Values of c
 You have
Access
- 7
- Cited by