



1. Introduction
The main purpose of this paper is to examine the impact of immigration on the behaviour of both single- and multitype continuous-time Markov branching processes, focusing on immigration types that differ from the Poisson model. Although classical Poisson processes are the most commonly used to model the immigration component, they have certain limitations in practical applications. These include the assumption of equidispersion, which may not always hold, and time homogeneity, which is addressed by introducing time-non-homogeneous intensity rates. Recently, such branching models with immigration at the jump times of a non-homogeneous Poisson process were considered in depth in [Reference Hyrien, Mitov and Yanev17] in the critical case, and later in [Reference Slavtchova-Bojkova, Hyrien and Yanev44, Reference Slavtchova-Bojkova, Hyrien and Yanev45] in the non-critical case. In these studies, efforts were concentrated mainly on analysing the asymptotic behaviour of the processes for various rates of the Poisson measure, under the assumption that these rates are asymptotically equivalent to either exponential or regularly varying functions. Consequently, results similar to the strong law of large numbers and central limit theorems were established.
Multitype Markov branching processes were first introduced in [Reference Kolmogorov and Dmitriev21], marking the term branching process as one of the earliest concepts in the literature. The notion of branching processes with immigration was later formalised in [Reference Sevastyanov39], which explored a single-type Markov process with immigration driven by a time-homogeneous Poisson process, and derived limiting distributions for subcritical, supercritical, and critical cases.
Since then, numerous extensions of branching processes with immigration have been developed and thoroughly explored. The seminal reviews [Reference Sevastyanov40, Reference Vatutin and Zubkov47, Reference Vatutin and Zubkov48] have highlighted many key results. More recent advances have been made in [Reference Barczy, Nedényi and Pap5, Reference Barczy, Palau and Pap6, Reference González, Kersting, Minuesa and del Puerto13, Reference Li, Vatutin and Zhang25], among others, which have expanded the theory of these processes.
Branching processes with time-non-homogeneous immigration were first introduced in [Reference Durham10, Reference Foster and Williamson12]. Comprehensive reviews of these models can be found in [Reference Badalbaev and Rahimov4, Reference Rahimov37, Reference Rahimov38]. In recent work [Reference Rabehasaina and Woo36] the model described in [Reference Hyrien, Mitov and Yanev17, Reference Slavtchova-Bojkova, Hyrien and Yanev44, Reference Slavtchova-Bojkova, Hyrien and Yanev45] was considered, and the established limit results were obtained by means of characteristic functions.
In this work, we aim to introduce the general framework of Laplace functionals of random point processes within the context of branching processes. We believe that this approach will be valuable for researchers looking to extend their work beyond the Poisson process. For example, our method simplifies the derivation of the generating function for a branching process with immigration, which often serves as the foundation for many studies. Traditionally, this derivation was based on the exact distribution of points over a given interval, which is tractable in the case of a Poisson process, as demonstrated in [Reference Hyrien, Mitov and Yanev17, Theorem 1], [Reference Rabehasaina and Woo36, Lemma 3.1], and [Reference Butkovsky7, Theorem 1]. Our framework provides a more unified and often simpler approach to addressing problems involving immigration, as can be seen from the proof of Theorem 5(iii) and similar results for Poisson immigration, such as [Reference Hyrien, Mitov and Yanev17, Theorem 8] and [Reference Rabehasaina and Woo36, Theorem 3]. Due to the tractability of the framework, we correct minor errors from the last two referenced results– see Remark 1.
The paper is structured as follows. In Section 2 we define the framework of point processes and give a few examples of such objects, and in Section 3 we introduce single- and multitype branching processes with immigration. Section 4 contains results for the probability-generating functions of the branching process with immigration spanned by a general point process, and asymptotic results in the case where the immigration is generated by a determinantal point process (DPP). More precisely, in Theorem 1 the generating functions of branching processes with immigration spanned by DPPs, Cox processes, and fractional Poisson processes (FPPs) are derived in the single-type case, while Theorem 2 presents the multivariate analogue. In Subsection 5.1, for the case of DPP immigration we establish equations for the mean and covariances of the process. Furthermore, in Theorem 4 we prove limit results analogous to those in the case without immigration, covering sub-, super-, and critical cases, respectively. Section 6 contains the proofs of the new results.
2. Point processes on the real line
As we will be interested in point processes (PPs) describing the times of immigrants joining a branching process, we define the basic notions for PPs on
 $\mathbb{R}_+\;:\!=\;[0,\infty)$
(or just PPs from now on), although the formalism for defining them on an arbitrary Polish space is similar.
Informally, we can consider the point process as a random collection of points; however, to formalise this idea, the basic construction is via the so-called random measures. We follow the presentation of [Reference Last and Penrose23, Chapter 2.1]; however, another suitable reference is the excellent monograph [Reference Baccelli, Blaszczyszyn and Karray3].
Let
 $(\Omega, \mathcal{F}, \mathbb{P})$
be a probability space,
 $\mathcal{B}(\mathbb{R})$
be the usual Borel
 $\sigma$
-algebra on
 $\mathbb{R}$
, and
 $\mathbf{N}_{<\infty}$
be the set of measures
 $\widetilde{\Phi}$
on
 $\mathbb{R}_+$
such that, for each
 $B\in \mathcal{B}(\mathbb{R}_+)$
,
 $\widetilde{\Phi}(B) \in \mathbb{N}_0\;:\!=\;\mathbb{N}\cup \{0\}$
. Further, denote by
 $\mathbf{N}$
the set of measures that can be represented as a countable sum of elements of
 $\mathbf{N}_{<\infty}$
, and let
 $\mathcal{N}$
be the
 $\sigma$
-algebra generated by the sets
 \[\{\Phi \in \mathbf{N}\colon\Phi(B) = k\text{ for some }B \in \mathcal{B}(\mathbb{R}_+)\text{ and } k \in \mathbb{N}_0\}.\]
We call
 $\Phi$
a random measure or a PP if it is a random element of
 $(\mathbf{N}, \mathcal{N})$
, i.e. a measurable mapping
 $\Phi\colon\Omega \to \mathbf{N}$
. In this work we will consider PPs that are proper, i.e. such that there exist random variables
 $\kappa,X_1, X_2, \dots$
such that
 $\Phi = \sum_{i \leq \kappa} \delta_{X_i}$
, where
 $\delta_x$
is the Dirac mass at x, so
 $\Phi$
places unit mass at the random locations
 $X_1, X_2,\dots,X_\kappa$
. For a deeper and more general presentation, see [Reference Last and Penrose23, Chapter 2.1], [Reference Baccelli, Blaszczyszyn and Karray3, Chapter 1], or [Reference Kallenberg18, Chapter 2].
Some of the characteristics that help to describe a PP include:
-
• its intensity measure
 $\Lambda$
, defined by
$\Lambda(B) = \mathbb{E}[\Phi(B)]$
, where
$B \in \mathcal{B}(\mathbb{R}_+)$
;
-
• its Laplace functional, which characterises the process completely – for all test functions f,
(1)The set of test functions can be all positive measurable ones, as in the case of a Poisson process, or functions with compact support, as in the case of determinantal point processes;
\begin{equation} \mathcal{L}_\Phi(f) \;:\!=\; \mathbb{E}\bigg[\exp\bigg\{{-}\int f\,\textrm{d}\Phi\bigg\}\bigg] = \mathbb{E}\Bigg[\exp\Bigg\{{-}\sum_{i\leq\kappa}f(X_i)\Bigg\}\Bigg]. \end{equation}
-
• its joint intensities
$\rho_k$
, if they exist, defined as
$\rho_k\colon\mathbb{R}_+^k\to\mathbb{R}_+$
such that, for each disjoint
$B_1, \dots, B_k \in \mathcal{B}(\mathbb{R}_+)$
,
\[ \mathbb{E}\Bigg[\prod_{i=1}^k\Phi(B_i)\Bigg] = \int_{B_1\times\dots\times B_k}\rho_k(x_1,\dots,x_k)\, \Lambda(\textrm{d}x_1)\cdots\Lambda(\textrm{d}x_k). \]


2.1. Poisson processes
Probably the most used point process, due to its mathematical tractability, is the Poisson process, which is characterised by the property that its intensity measure
 $\Lambda$
is such that:
-
(i) for every
$B \in \mathcal{B}(\mathbb{R}_+)$
,
$\Phi(B)\sim \textrm{Poi}(\Lambda(B))$
; and -
(ii) for every disjoint
$B_1,\dots,B_m \in \mathcal{B}(\mathbb{R}_+)$
,
$\Phi(B_1),\dots,\Phi(B_m)$
are independent.


It is a consequence that the Laplace functional of this PP is then
 \begin{equation} \mathcal{L}_\Phi(f) = \exp\bigg({-}\int_{\mathbb{R}_+}\big(1 - \textrm{e}^{-f(x)}\big)\,\Lambda(\textrm{d}x)\bigg).\end{equation}
If
 $\Lambda(\textrm{d}x) = {\lambda}\,\textrm{d}x$
, then we say that the Poisson process is homogeneous of rate
 ${\lambda}$
.
In the following three subsections, we list some PPs that are often used and cover, respectively, repulsive, clustering, and heavy-tailed behaviour of the interarrival times.
2.2. Determinantal point processes
DPPs were introduced in [Reference Macchi26] under the name fermion process, due to their repulsive behaviour. Since then they have arisen in various contexts, including random matrix theory, zeros of random analytic functions, statistical mechanics, and even machine learning [Reference Kulesza and Taskar22]. We refer the reader to [Reference Baccelli, Blaszczyszyn and Karray3, Chapter 5] for an introduction to their formalism, and to [Reference Decreusefond, Flint, Privault and Torrisi8] for an overview.
We call a point process
 $\Phi $
on
 $\mathbb R_+$
 $(\Lambda ,K)$
-determinantal if
 $\Lambda$
is a locally finite measure on
 $\mathbb{R}_+$
, and its joint intensities satisfy, for
 ${\boldsymbol{x}} = (x_1, \dots,x_n)$
,
 \[\rho_{n}(x_{1},\dots,x_{n})=\det(K(x_{i},x_{j}))_{1\le i,j\le n}\;=\!:\;D({\boldsymbol{x}}),\]
where
 $K\;:\;{\mathbb R}_ + ^2 \to {{\mathbb R}_ + }$
is symmetric; for
 $\Lambda^n$
-almost all
 ${\boldsymbol{x}}$
,
 $(K(x_{i},x_{j}))_{1\le i,j\le n}$
is non-negative definite, and for each bounded
 $D \in \mathcal{B}(\mathbb{R}_+)$
,
 $\int_D K(x,x)\,\Lambda(\textrm{d}x)$
is finite. These properties ensure that
 $\Lambda$
and K determine
 $\Phi$
uniquely, see [Reference Baccelli, Blaszczyszyn and Karray3, Corollary 5.1.14]. However, they may look too implicit, as they do not describe how to build admissible kernels. One recipe is to look at regular kernels of the type
 $K(x,y) = \sum_{n\in\mathbb{N}}{\lambda}_n\phi_n(x)\phi_n(y)$
for
 $\phi_i $
orthonormal in
 $L^2(\Lambda, \mathbb{R}_+)$
and
 ${\lambda}_i\in[0,1]$
; see [Reference Baccelli, Blaszczyszyn and Karray3, Theorem 5.2.5].
Further, the Laplace functional of
 $\Phi $
is given, for any non-negative
 $f$
of compact support,
 $\varphi_n({\boldsymbol{x}}) \;:\!=\; \prod_{i=1}^n \big(1 - {\textrm{e}}^{-f(x_i)}\big)$
, and
 $\Lambda(\textrm{d} {\boldsymbol{x}}) \;:\!=\; \Lambda(\textrm{d}x_1)\cdots\Lambda(\textrm{d}x_n)$
, by
 \begin{align} \mathcal{L}_\Phi(f) & = 1 + \sum_{n \geq 1}\frac{(\!-\!1)^n}{n!}\int_{\mathbb{R}_+^n}\rho_n(x_1, \dots , x_n) \varphi_n(x_1, \dots, x_n)\,\Lambda(\textrm{d}x_1)\cdots\Lambda(\textrm{d}x_n) \nonumber \\ & = 1 + \sum_{n \geq 1}\frac{(\!-\!1)^n}{n!}\int_{\mathbb{R}_+^n}D({\boldsymbol{x}})\varphi_n({\boldsymbol{x}})\, \Lambda(\textrm{d}{\boldsymbol{x}}); \end{align}
see, for example, [Reference Baccelli, Blaszczyszyn and Karray3, Proposition 5.1.18 and Corollary 5.1.19] or [Reference Shirai and Takahashi42, Theorem 3.6 with
 $\alpha = -1$
]. In particular, note that if
 $\Lambda(\textrm{d}x)$
is diffuse and we choose the kernel
 $K(x,y)=\textbf{1}_{\{x=y\}}$
, then for all n,
 $\rho_n$
is equal to 1
 $\Lambda(\textrm{d}{\boldsymbol{x}})$
-almost everywhere, so we obtain the usual
 $\Lambda$
-Poisson process; see [Reference Baccelli, Blaszczyszyn and Karray3, Example 5.1.6] for a rigorous derivation.
2.3. Cox processes
Cox processes, also known as doubly stochastic Poisson processes, extend the ordinary Poisson process by randomising its intensity measure. They are usually used for modelling phenomena where event occurrence is influenced by underlying random factors, as demonstrated in [Reference Møller32, Reference Møller, Syversveen and Waagepetersen33, Reference Yannaros50] and more recently in [Reference Diggle, Moraga, Rowlingson and Taylor9], which discuss their applications in spatial and spatio-temporal data analysis.
Formally, let
 $\eta$
be a random
 $\sigma$
-finite measure on
 $\mathbb{R}_+$
. Then we call a point process
 $\Phi$
a Cox process with directing measure
 $\eta$
if, conditional on
 $\eta$
,
 $\Phi \mid \eta \sim \eta\text{-Poisson process}$
. Therefore, its Laplace functional is obtained by averaging over
 $\eta$
in (2):
 \begin{equation} \mathcal{L}_\Phi(f) = \mathbb{E}\bigg[\exp\bigg({-}\int_{\mathbb{R}_+}\big(1-\textrm{e}^{-f(x)}\big)\, \eta(\textrm{d}x)\bigg)\bigg] \end{equation}
for every non-negative measurable f. The first two moment measures follow by conditioning on
 $\eta$
and using the Poisson moment formula, as in [Reference Last and Penrose23, Proposition 13.6]:
 \[ \mathbb{E}[\Phi(B)] = \mathbb{E}[\eta(B)], \qquad \textrm{Var}(\Phi(B)) = \textrm{Var}(\eta(B)) + \mathbb{E}[\eta(B)] \]
for all
 $B\in\mathcal{B}(\mathbb{R}_+)$
. For proofs and more properties, see, e.g., [Reference Last and Penrose23, Chapter 13].
2.4. Fractional Poisson processes
The FPP introduced in [Reference Mainardi, Gorenflo and Scalas27] is a non-Markovian generalisation of the standard homogeneous Poisson process, which has heavy-tailed interarrival times; see also [Reference Meerschaert and Sikorskii29]. It depends on parameters
 $\beta \in(0,1]$
and
 ${\lambda}>0$
, and is of renewal type, i.e. the atoms of the associated random measure
 $\Phi_{\beta, {\lambda}}$
are situated at
 $X_n = T_1 + \dots + T_n$
with independent and identically distributed (i.i.d.)
 $T_i$
such that
 \[\mathbb{P}(T_i>t) = E_\beta(\!-\! {\lambda} t^\beta),\quad\text{where}\ E_\beta(z) \;:\!=\; \sum_{k=0}^\infty\frac{z^k}{\Gamma(1+\beta k)}\]
is the Mittag–Leffler function. Define the counting process by
 $N_{\beta,{\lambda}}(t) \;:\!=\; \Phi_{\beta,{\lambda}}((0,t])$
. For
 $\beta=1$
, we get
 $T_i \sim \textrm{Exp}({\lambda})$
, so the FPP is in fact a homogeneous Poisson process of rate
 ${\lambda}$
. However, for
 $\beta\in(0,1)$
,
 $\mathbb{P}(T_i>t)$
is of order
 $1/t^\beta$
and a fortiori the expectation
 $\mathbb{E}[T_i]$
is infinite. [Reference Meerschaert, Nane and Vellaisamy28] extends the link to Poisson processes beyond
 $\beta=1$
by showing that
 $N_{\beta,{\lambda}}(t) = \mathcal{N}_{{\lambda}}(Y_\beta(t))$
, where
 $\mathcal{N}_{{\lambda}}$
is a homogenous Poisson process of rate
 ${\lambda} > 0$
, and
 $Y_\beta$
is the inverse of an independent
 $\beta$
-stable subordinator. Thus understanding the asymptotic properties of inverse subordinators
 ${Y_\beta }$
, for example as in [Reference Ascione, Savov and Toaldo1], is key to deriving limit theorems and other results for the FPP. Consequently, the Laplace functional of
 $\Phi_{\beta, {\lambda}}$
can be written as
 \begin{equation} \mathcal{L}_{\Phi_{\beta,{\lambda}}}(f) = \mathbb{E}\bigg[\exp\bigg({-}{\lambda}\int_{\mathbb{R}_+}\big(1-\textrm{e}^{-f(t)}\big)\,\textrm{d}Y_\beta(t)\bigg)\bigg].\end{equation}
3. Branching processes with immigration
In this section we present the branching process with immigration and fix the relevant notation.
3.1. Single-type processes
We denote by Z(t) the number of particles at time t, and outline that we use
 $G_X$
for the generating function of a random variable X.
The underlying branching process without immigration
 $Z_\times$
is a Markov branching process in continuous time with starting state
 $Z_{\times}(0)= I$
, where I will be the law of the size of a single immigrant group. Therefore, we can construct the process with immigration Z as follows:
-
• At times
$T_1 < T_2< \cdots$
, new particles (immigrants)
$I_1, I_2, \dots$
arrive with i.i.d.
$I_k\sim I$
. We assume that
$\mathbb{E}[I]$
is finite. -
• Each particle evolves independently of the others and at
$\textrm{Exp}(1/\mu)$
time dies and produces
$\nu$
new particles. It is then known [Reference Athreya and Ney2, (5), p. 106] that
$({\partial}/{\partial t})G_{Z_\times}(t, s) = f_\nu(G_{Z_\times}(t,s))$
, where
$G_{Z_\times}(t,s)\;:\!=\;G_{Z_\times(t)}(s)$
and
$f_\nu(s) = (G_\nu(s)-s)/\mu$
. Also,
$M_\times(t) \;:\!=\; \mathbb{E}[Z_\times(t)] = \textrm{e}^{\rho t}$
with
$\rho \;:\!=\; f_\nu'(1) = (\mathbb{E}[\nu]-1)/\mu$
. The process is called subcritical, critical, or supercritical according to whether
$\mathbb{E}[\nu]$
is, respectively, less than, equal to, or greater than 1.


Therefore, the process with immigration can be represented as
 $Z(t) = \sum_{i:T_i\leq t} {Z}^{(i)}_{\times}(t-T_i)$
, where
 ${Z}^{(i)}_{\times}$
are i.i.d. copies of the process without immigration
 $Z_\times$
started with
 ${Z}^{(i)}_{\times}(0) = I_i$
.
3.2. Multitype processes
Consider now a generalisation of the single-type process that is composed of d types of particles. We will use bold symbols
 $\boldsymbol{\nu}$
for a vector, and, unless explicitly stated otherwise,
 $\nu_{i}$
will denote the value of its ith coordinate. We define the generating function in this case as
 \[ G_{\boldsymbol{\nu}}({\boldsymbol{s}}) \;:\!=\; \sum_{{\boldsymbol{n}}\in \mathbb{N}_0^d}\mathbb{P}(\boldsymbol{\nu}={\boldsymbol{n}}) \prod_{i=1}^{d}s_i^{n_{i}} \quad \text{for}\ {\boldsymbol{s}}=(s_1, \dots, s_d).\]
The multitype branching process
 ${\boldsymbol{Z}}$
with
 ${\boldsymbol{Z}}(0)={\boldsymbol{I}}^{(0)}\sim{\boldsymbol{I}}$
is described as follows:
-
• At times
$0 = T_0<T_1<T_2<\cdots$
, i.i.d. immigrants
${\boldsymbol{I}}^{(0)},{\boldsymbol{I}}^{(1)},{\boldsymbol{I}}^{(2)},\ldots\sim{\boldsymbol{I}}$
join the population described by the branching process
${\boldsymbol{Z}}$
. -
• Each particle of type i lives
$\textrm{Exp}(1/\mu_i)$
time, after which it dies and produces new ones with distribution
$\boldsymbol{\nu}_i$
of their counts, i.e.
$({\nu}_i)_{j}$
of type j.


In this work we make the following assumptions.
Assumption 1. The immigrants and progeny,
 $I_i$
and
 $(\nu_i)_j$
, have finite expectation, and the latter is not almost surely (a.s.) constant. For some of the results we impose the following stronger restriction:
 \begin{equation} I_i \text{ and } (\nu_i)_j \text{ have finite second moments.} \end{equation}
Assumption 2. The mean offspring matrix
 $M \;:\!=\; \big(\mathbb{E}[(\nu_i)_j]\big)_{1\le i,j\le d}$
is assumed primitive, i.e. there exists an integer
 $p\ge1$
such that
 $M^p$
has strictly positive entries. We briefly discuss the more general decomposable (or also reducible) case in Subsection 3.3.
Similarly to the single-type case,
 ${\boldsymbol{Z}}(t) = \sum_{i:T_i\leq t}{\boldsymbol{Z}}^{(i)}_{\times}(t-T_i)$
, where
 ${\boldsymbol{Z}}^{(i)}_{\times}$
are i.i.d. processes with law
 ${\boldsymbol{Z}}_{\boldsymbol\times}$
, i.e. without immigration and started with
 ${\boldsymbol{I}}^{(\boldsymbol{i})}$
. This gives the generating function of the process, with
 $G_{{\boldsymbol{Z}}}(t,{\boldsymbol{s}})\;:\!=\;G_{{\boldsymbol{Z}}(t)}({\boldsymbol{s}})$
and
 $G_{{\boldsymbol{Z}}_{\times}}(t,{\boldsymbol{s}})\;:\!=\; G_{{\boldsymbol{Z}}_{\times}(t)}({\boldsymbol{s}})$
, as
 \begin{equation} G_{{\boldsymbol{Z}}}(t,{\boldsymbol{s}}) = \mathbb{E}\Bigg[ \prod_{i:T_i\leq t}G_{{\boldsymbol{Z}}^{(i)}_{\times}}(t-T_i,{\boldsymbol{s}})\Bigg] = \mathbb{E}\Bigg[\exp\Bigg(\sum_{i:T_i\leq t}\ln(G_{{\boldsymbol{Z}}_{\times}}(t-T_i,{\boldsymbol{s}}))\Bigg)\Bigg].\end{equation}
Translating this into the language of the Laplace functional of the random measure
 $\Phi$
governing the process
 $T_i$
, substituting in (1), we get that
 \begin{equation} G_{{\boldsymbol{Z}}}(t,{\boldsymbol{s}}) = \mathcal{L}_\Phi(f_t), \quad \text{with} \ f_t(x) \;:\!=\; -\ln(G_{{\boldsymbol{Z}}_{\times}}(t-x,{\boldsymbol{s}}))\textbf{1}_{\{x\leq t\}}.\end{equation}
If we want to work instead with the Laplace transform,
 $\mathcal{L}_{{\boldsymbol{Z}}}(t,{\boldsymbol{s}})\;:\!=\;\mathbb{E}[\exp(\!-\!\langle{\boldsymbol{Z}}(t),{\boldsymbol{s}}\rangle)]$
, where
 $\langle\cdot,\cdot\rangle$
is the usual scalar product on
 $\mathbb{R}^d$
, we would have
 \begin{equation} \mathcal{L}_{{\boldsymbol{Z}}}(t,{\boldsymbol{s}}) = \mathcal{L}_\Phi(g_t), \quad \text{with} \ g_t(x) \;:\!=\; -\ln(\mathcal{L}_{{\boldsymbol{Z}}_{\times}}(t-x,{\boldsymbol{s}}))\textbf{1}_{\{x\leq t\}}.\end{equation}
3.3. Decomposable (reducible) case
In the more general decomposable (or reducible) setting, the mean offspring matrix M can be permuted into a block-triangular form,
 \[ P M P^{-1} = \begin{pmatrix} M_{11}\;\;\;\; & M_{12}\;\;\;\; & \cdots\;\;\;\; & M_{1k} \\ 0\;\;\;\; & M_{22}\;\;\;\; & \cdots\;\;\;\; & M_{2k} \\ \vdots\;\;\;\; & \vdots\;\;\;\; & \ddots\;\;\;\; & \vdots \\ 0\;\;\;\; & 0\;\;\;\; & \cdots\;\;\;\; & M_{kk} \end{pmatrix},\]
where each diagonal block
 $M_{ii}$
is irreducible (primitive). We then study the multitype branching process in stages:
-
• Block 1 (leading class): behaves as an irreducible system with its own growth rate; immigration into this class follows the point process mechanism as before.
-
• Block r (subsequent class): receives external immigration from class
$1,\dots,r-1$
via their off-diagonal connections
$M_{jr}$
, in addition to the original point-process arrivals. We treat the output of earlier blocks as an inhomogeneous immigration input and apply the irreducible theory to each block in turn.


Asymptotic results for each class can then be obtained by iterating the single-block analysis, noting that the effective immigration intensity into block r is a superposition of point-process-driven arrivals plus the evolving contribution from blocks 1 through
 $r-1$
.
4. Asymptotic behaviour at infinity of the branching process with immigration
4.1. Single-type processes
The continuous-time Markov branching process without immigration is presented in [Reference Athreya and Ney2, Chapter III]. We refer again to [Reference Rahimov38] for an extensive recent review of branching processes with immigration, and to [Reference Vatutin and Zubkov47] for a review of the classical results up to 1983.
A standard argument using martingale theory, e.g. [Reference Athreya and Ney2, Theorem 1, p. 111], shows that, for the process without immigration
 $Z_{\times}$
, there exists a real-valued random variable
 $W_\times$
such that
 \begin{equation} \frac{Z_\times(t)}{\textrm{e}^{\rho t}} \xrightarrow[t \to \infty]{\textrm{a.s.}} W_\times.\end{equation}
In the supercritical case, it is natural to characterise some of the properties of
 $W_\times$
, e.g. the existence of a density. In the sub-critical and critical cases, this
 $W_\times$
is a.s. equal to 0 and a common question is to analyse the so-called Yaglom limit as
 $t\to\infty$
of quantities such as
 $\mathbb{P}(Z_\times(t)>f(t)\mid Z_\times(t)>0)$
for some f; see [Reference Athreya and Ney2, Chapter III, Theorems 2--4]. Similar results are also available for the case of age-dependent processes [Reference Athreya and Ney2, Chapter IV].
When an immigration component is added, it is often possible to extract asymptotic results for Z using the information for the underlying process
 $Z_\times$
through the representation in (6). The case of Poisson immigration is considered when the underlying process is subcritical in [Reference Hyrien, Mitov and Yanev16], critical in [Reference Mitov and Yanev30, Reference Mitov and Yanev31, Reference Slavtchova-Bojkova and Yanev46], and supercritical in [Reference Hyrien, Mitov and Yanev15].
We provide the generating functions in the cases of DPPs, Cox, and FPPs. After choosing an exact model, this can provide the limit of a scaled Z through the results for
 $Z_\times$
. We also note that it is possible to work with the generating function of the process starting with exactly one particle
 $Z_\times^{(1)}$
, i.e.
 $Z_\times^{(1)}(0) = 1$
, via the relation
 \begin{equation} G_{Z_{\times}}(s) = G_I\big( G_{Z_\times^{(1)}}(s)\big).\end{equation}
Theorem 1.
-
(i) In the case of immigration spanned by a
$(\Lambda, K)$
-DPP process, the expectation
$\mathbb{E}[s^{Z(t)}]$
is equal to (11)
\begin{equation} 1 + \sum_{n\geq 1}\frac{(\!-\!1)^{n}}{n!}\int_{(0,t]^n}D({\boldsymbol{x}})\prod_{i=1}^n(1 - G_{Z_{\times}}(t-x_i,s))\, \Lambda(\textrm{d}{\boldsymbol{x}}). \end{equation}
-
(ii) In the case of immigration spanned by a Cox process with a directing measure
$\eta$
,
\[ \mathbb{E}\big[s^{Z(t)}\big] = \mathbb{E}\bigg[\exp\bigg({-}\int_{(0,t]}(1-G_{Z_{\times}}(t-x,s))\, \eta(\textrm{d}x)\bigg)\bigg]. \]
-
(iii) In the case of immigration spanned by a
$(\beta,{\lambda})$
-FPP, where
\[ \mathbb{E}\big[s^{Z(t)}\big] = \mathbb{E}\bigg[\exp\bigg({-}{\lambda}\int_{(0, t]}(1-G_{Z_{\times}}(t-x,s))\, \textrm{d}Y_\beta(x)\bigg)\bigg], \]
$Y_\beta$
is the inverse of an independent
$\beta$
-stable subordinator.
To obtain the respective Laplace transforms, replace
$G_{Z_\times}$
with
$\mathcal{L}_{Z_\times}$
.


Proof. The generating functions are directly obtained by substituting (7) into the relevant Laplace functional: (4) for Cox processes, (5) for FPPs, and (3) for DPPs. For the Laplace transform, instead of (7) we should substitute (8).
To make a connection with the previously presented classes of point processes, Theorem 1(ii) was proved in [Reference Butkovsky7] and applied in the context of branching processes.
As for the fractional point process, since it is a renewal process we can apply the results of [Reference Kaplan and Pakes19, Reference Pakes and Kaplan34] for the sub- and supercritical cases; see also [Reference Pakes and Parthasarathy35]. The only specificity we need to take care of is that the interarrival times have infinite expectation, however the techniques are often the same [Reference Kaplan and Pakes19, Remarks on pp. 379, 385, and 389].
4.2. Multitype processes
The results for multitype processes have a similar nature, but generalising the one-dimensional results is not always direct and requires careful treatment. To extend (9), let us define an analogue of
 $\mathbb{E}[\nu]$
, i.e.
 $\textrm{e}^A$
, where the generator
 $d \times d$
matrix A is defined by
 \begin{equation} A_{i,j} \;:\!=\; \mu_i^{-1}\big(\mathbb{E}[(\nu_i)_j] - \textbf{1}_{\{i=j\}}\big).\end{equation}
We will suppose that A is irreducible and let
 $\rho$
be its largest eigenvalue (also known as the Perron–Frobenius root). The process is called sub-, super-, or just critical according to
 $\rho$
being, respectively, less than, greater than, or equal to 0. Let
 ${\boldsymbol{u}}$
and
 ${\boldsymbol{v}}$
be row vectors such that
 $A{\boldsymbol{u}}^t = \rho {\boldsymbol{u}}^t$
,
 ${\boldsymbol{v}}A = \rho {\boldsymbol{v}}$
,
 $\sum_i u_iv_i = 1$
, and
 $\sum_i u_i = 1$
, with t denoting the transpose. Moreover, it is known [Reference Athreya and Ney2, p. 203] that the coordinates of
 ${\boldsymbol{u}}$
and
 ${\boldsymbol{v}}$
are strictly positive. Then, from [Reference Athreya and Ney2, Theorem 2, p. 206], rewritten in the form [Reference Rabehasaina and Woo36, Lemma 2.1], there exists a real-valued random variable
 $W_\times$
such that
 \begin{equation} \frac{{\boldsymbol{Z}}_{\times}(t)}{\textrm{e}^{\rho t}} \xrightarrow[t\to\infty]{\textrm{a.s.}}{\boldsymbol{v}}\cdot W_\times,\end{equation}
with
 $\cdot$
the usual multiplication, spelled out for better readability. We recall that
 ${\boldsymbol{Z}}_{\times}(t)$
is the process without immigration started with a random number of particles according to the law
 ${\boldsymbol{I}}$
. For completeness, we also note that the equivalent of the functional equation (10) is
 $G_{{\boldsymbol{Z}}_{\times}}({\boldsymbol{s}}) = G_{{\boldsymbol{I}}}\big(G_{{\boldsymbol{Z}}^{(1)}_{\times}}({\boldsymbol{s}}), \dots,G_{{\boldsymbol{Z}}^{(d)}_{\times}}({\boldsymbol{s}})\big)$
, with
 ${{\boldsymbol{Z}}^{(k)}_{\times}}$
a process without immigration started with exactly one particle of type k.
Furthermore, a convenient fact is that Theorem 1 holds when changing everything to its multidimensional equivalent (which we write in bold).
Theorem 2. The statements of Theorem 1 extend to the vector case by
 $s\to{\boldsymbol{s}}$
,
 $Z\to{\boldsymbol{Z}}$
, in all regimes (subcritical, critical, supercritical). The same holds if we replace generating functions by Laplace transforms:
 $G_{{\boldsymbol{Z}}}\to\mathcal L_{{\boldsymbol{Z}}}$
and
 $G_{{\boldsymbol{Z}}_\times}\to\mathcal L_{{\boldsymbol{Z}}_\times}$
.
Therefore, in theory, we can use results for the process without immigration
 ${\boldsymbol{Z}}_\times$
to obtain information about
 ${\boldsymbol{Z}}$
.
As noted previously, the case of immigration generated by a Poisson random measure is analysed in [Reference Hyrien, Mitov and Yanev17, Reference Slavtchova-Bojkova, Hyrien and Yanev44, Reference Slavtchova-Bojkova, Hyrien and Yanev45], and independently in [Reference Rabehasaina and Woo36]. For immigration times that form a renewal process, see [Reference Slavtchova-Bojkova43]. The latter may be applied in the case of an immigration spanned by an FPP after checking that the arguments used can be modified to include the case of an infinite expectation of the inter-arrival times.
As an illustrative example of how ideas from the case of Poisson immigration can be modified to encompass the case of immigration spanned by a DPP, we generalise [Reference Rabehasaina and Woo36, Theorems 3--5] (since the Poisson point process is a DPP), which are also available in [Reference Hyrien, Mitov and Yanev17, Reference Slavtchova-Bojkova, Hyrien and Yanev44, Reference Slavtchova-Bojkova, Hyrien and Yanev45].
5. Multitype branching processes with DPP immigration
5.1. Moments of the process
Let us recall that, for a vector
 ${\boldsymbol{Z}}$
, we denote by
 $Z_i$
its ith coordinate. Then we have the following.
Theorem 3. In the case of immigration spanned by a
 $(\Lambda, K)$
-DPP:
-
(i)
$\mathbb{E}[{Z}_i(t)] = \int_{(0,t]}K(x,x)\mathbb{E}[Z_{\times,i}(t-x)]\,\Lambda(\textrm{d}x)$
. -
(ii) If we assume (H),
\begin{align*} \textrm{Cov}(Z_i(t),Z_j(t)) & = \int_{(0,t]}K(x,x)\mathbb{E}[Z_{\times,i}(t-x)Z_{\times,j}(t-x)]\,\Lambda(\textrm{d}x) \\ & \quad - \int_{(0,t]^2}K^2(x,y)\mathbb{E}[Z_{\times,i}(t-x)]\mathbb{E}[Z_{\times,j}(t-y)]\, \Lambda(\textrm{d}x)\,\Lambda(\textrm{d}y). \end{align*}


5.2. Asymptotics
Theorem 4. Let
 $\rho$
be the Perron–Frobenius root of the matrix A. In the case of immigration spanned by a
 $(\Lambda,K)$
-DPP
 $\Phi$
with kernel K such that
 $\int_{(0,\infty)}\textrm{e}^{-\rho x}K(x,x)\,\Lambda(\textrm{d}x)$
is finite, there exists an
 $\mathbb{R}^d$
-valued random variable
 ${\boldsymbol{W}}$
such that
 \begin{equation*} \frac{{\boldsymbol{Z}}(t)}{\textrm{e}^{\rho t}} \xrightarrow[t \to \infty]{\textrm{d}} {\boldsymbol{W}}. \end{equation*}
Moreover,
 ${\boldsymbol{W}} \stackrel{\textrm{d}}{=} \sum_i{\boldsymbol{v}}\cdot W^{(i)}_{\times}\textrm{e}^{-\rho T_i}$
and
 $\mathbb{E}[\exp(\!-\!\langle{\boldsymbol{W}},{\boldsymbol{s}}\rangle)] = \mathcal{L}_{\Phi}(\!-\!\ln(\mathcal{L}_{{\boldsymbol{v}}W_\times}({\boldsymbol{s}}\textrm{e}^{-\rho x})))$
, where
 $W^{(i)}_{\times}$
are i.i.d. copies of
 $W_{\times}$
and
 $T_i$
are the atoms of
 $\Phi$
.
For the next results, to introduce some regularity of the DPP we assume it is stationary, meaning that for any
 $t \in {\mathbb R}$
and
 ${\boldsymbol{x}} \in {{\mathbb R}^n}$
,
 \begin{equation} D({\boldsymbol{x}}+t) = D({\boldsymbol{x}}),\end{equation}
where
 ${\boldsymbol{x}} + t\;:\!=\; ({x_1} + t, \ldots ,{x_n} + t)$
; see [Reference Baccelli, Blaszczyszyn and Karray3, Section 5.6]. This property holds, for example, if the kernel is shift-invariant,
 $K(x,y) = K(x + t,y + t) \;=\!:\; C(x - y)$
, as in the case of the Poisson kernel,
 $K(x,y) = {{\bf{1}}_{\{ x = y\} }}$
, or the Ginibre (Gaussian) kernel,
 $K(x,y) = \exp ( - {(x - y)^2}/2)/\pi $
. A result in [Reference Lavancier, Møller and Rubak24, Theorem 1] states that
 $C$
can be any continuous correlation function with eigenvalues in its spectral representation bounded by 1, with examples provided in [Reference Lavancier, Møller and Rubak24].
Before stating our next result, we introduce the asymptotic equivalence notation: provided g(t) is non-zero for sufficiently large t,
 \[ f(t)\stackrel{\infty}{\sim} g(t) \quad \text{if} \ \lim_{t\to\infty}\frac{f(t)}{g(t)} = 1.\]
Theorem 5. Assume that immigration is spanned by a stationary
 $(\Lambda,K)$
-DPP with
 $\Lambda(\textrm{d}x) = {\lambda}(x)\,\textrm{d}x$
, and that
 ${\lambda}(x)\stackrel{\infty}{\sim}{\lambda}_\infty\textrm{e}^{\delta x}$
for some
 ${\lambda}_\infty > 0$
and
 $\delta \in \mathbb{R}$
.
-
(i) Under (H), if
$\delta>\max\{\rho,0\}$
then where
\[ \frac{{Z_i}(t)}{\textrm{e}^{\delta t}} \xrightarrow[t\to\infty]{L^2} A_i \;:\!=\; K_\ast{\lambda}_\infty\int_0^\infty{\textrm{e}}^{-\delta x}\mathbb{E}[Z_{\times,i}(x)]\,\textrm{d}x, \]
$K_\ast\;:\!=\;K(0,0)$
.
-
(ii) Under (H), if the process is supercritical, i.e.
$\rho>0$
, and
$\delta = \rho$
, then
\[ \frac{{Z_i}(t)}{t{\textrm{e}}^{\delta t}} \xrightarrow[t\to\infty]{L^2} A_i' \;:\!=\; K_\ast{\lambda}_\infty \langle{\boldsymbol{u}}, \mathbb{E}[{\boldsymbol{I}}]\rangle v_i. \]
-
(iii) If the process is critical, i.e.
$\rho=0$
,
$\mathbb{E}[||\boldsymbol{\nu}||^2]$
is finite,
${\lambda}$
is bounded,
$\delta = \rho$
, and the covariance function K(x,0) of the DPP tends to 0 as
$x\to \infty$
, then where
\[ \frac{{\boldsymbol{Z}}(t)}{t} \xrightarrow[t\to\infty]{\textrm{d}} Y{\boldsymbol{v}}, \]
$Y\sim\Gamma(K(0,0){\lambda}_\infty\beta,1/Q)$
with and
\[ Q \;:\!=\; \frac{1}{2}\sum_{i,j,k=1}^d\frac{\partial^2G_{\nu_i}}{\partial x_j\partial x_k}\bigg|_{{\boldsymbol{x}}=\textbf{1}} \mu_i^{-1}v_i u_j u_k, \qquad \beta \;:\!=\; \frac{\langle{\boldsymbol{u}},\mathbb{E}[{\boldsymbol{I}}]\rangle}{Q}, \]
$\Gamma(\alpha,\beta)$
is the Gamma law with shape
$\alpha$
and rate
$\beta$
, i.e. its density is, for
$x >0$
,
\[ f_{\alpha,\beta}(x) = \frac{\beta^\alpha}{\Gamma(\alpha)}x^{\alpha-1}{\textrm{e}}^{-\beta x}. \]
-
(iv) If the process is subcritical, i.e.
$\rho<0$
, and
$\delta = 0$
, then where
\[ {\boldsymbol{Z}}(t) \xrightarrow[t\to\infty]{\textrm{d}} {\boldsymbol{X}}, \]
${\boldsymbol{X}}$
is a random variable whose Laplace transform is available in (29).


Remark 1. The result of Theorem 5(iii) in the case of Poisson immigration is established in [Reference Hyrien, Mitov and Yanev17, Theorem 8] and, under the stronger assumption that all moments of
 $I_i$
exist, in [Reference Rabehasaina and Woo36, Theorem 3]. After a close inspection, we have observed that the two in fact do not match. This is due to two errata: in the proof of [Reference Hyrien, Mitov and Yanev17, Theorem 8], there is a missed
 $r^\ast$
on the second line of page 221. The error in [Reference Rabehasaina and Woo36, Theorem 3] is due to an incorrect application of the result of [Reference Weiner49], where the eigenvectors
 ${\boldsymbol{u}}_W$
and
 ${\boldsymbol{v}}_W$
are respectively defined as the right and left eigenvectors of the matrix composed of
 $\mathbb{E}[(\nu_{i})_j]-\textbf{1}_{\{i=j\}}$
, and not as the eigenvectors of the generator matrix A, see (12). The normalisation is
 $\langle {\boldsymbol{u}}_W, \textbf{1}\rangle = 1$
and
 $\langle {\boldsymbol{u}}_W, {\boldsymbol{v}}_W\rangle = 1$
. It is then direct that
 \begin{equation*} u_{W,i}\;:\!=\;(u_{W})_i = u_i, \qquad v_{W,i} = \frac{1}{\sum_j (u_j v_j/ \mu_j)}\frac{v_i}{\mu_i}, \qquad \sum_i\mu_i u_{W,i} v_{W,i} = \frac{1}{\sum_i (u_i v_i/\mu_i)}. \end{equation*}
The definitions of
 ${\boldsymbol{u}}$
and
 ${\boldsymbol{v}}$
in this work align with those in [Reference Athreya and Ney2, Reference Sevastyanov41].
Theorem 5 is proved in Section 6.3. To prove the first two items, we will need the following estimates.
Lemma 1. Under the assumptions of Theorem 5 and (H),
-
(i) if
$\delta>\rho$
then, for some
$A_i \in \mathbb{R}_+$
,
\[ \mathbb{E}[Z_i(t)] \stackrel{\infty}{\sim} A_i{\textrm{e}}^{\delta t}, \qquad \textrm{Var}(Z_{i}(t)) = \begin{cases} \textrm{O}({\textrm{e}}^{\max\{2\rho,\delta\}t}) & \text{if $\rho > 0$ and $\delta\neq2\rho$}, \\ \textrm{O}(t{\textrm{e}}^{\delta t}) & \text{if $2\rho=\delta > 0$}; \end{cases} \]
-
(ii) if
$\delta=\rho>0$
then, for some
$A_i'\in \mathbb{R}_+$
,
$\mathbb{E}[Z_i(t)] \stackrel{\infty}{\sim} A'_it{\textrm{e}}^{\delta t}$
and
$\textrm{Var}(Z_{i}(t)) = \textrm{O}({\textrm{e}}^{2\delta t})$
.


6. Proofs
6.1. Proof of Theorem 3
Proof. We start with the generating function of the process. Similarly to (11), the generating function of the multitype process
 $G_{{\boldsymbol{Z}}}(t,{\boldsymbol{s}}) \;:\!=\; \sum_{{\boldsymbol{n}}\in\mathbb{N}_0^d}\mathbb{P}({\boldsymbol{Z}}(t)={\boldsymbol{n}})\prod_{i=1}^{d}s_i^{n_{i}}$
is equal to
 \begin{equation} 1 + \sum_{n\geq 1}\frac{(\!-\!1)^{n}}{n!}\int_{(0,t]^n}D({\boldsymbol{x}}) \prod_{i=1}^n(1 - G_{{\boldsymbol{Z}}_{\times}}(t-x_i,{\boldsymbol{s}}))\,\Lambda(\textrm{d}{\boldsymbol{x}}). \end{equation}
To obtain the moments, we differentiate with respect to
 $s_i$
and evaluate at
 ${\boldsymbol{s}} = \textbf{1}$
. Note that we can interchange
 $\partial/\partial s_i$
with the integral because
 $G_{Z_{\times}}(t,{\boldsymbol{s}})\in[0,1]$
for each t and
 $||{\boldsymbol{s}}||\leq 1$
, and the assumption that the expectation of the progeny is finite gives that
 $\mathbb{E}[Z_{\times,i}(t)]$
is finite for each t; see, e.g., [Reference Athreya and Ney2, (5), p. 202]. Therefore,
 \[ \Bigg|\frac{\partial}{\partial s_i}\prod_{j=1}^n(1-G_{{\boldsymbol{Z}}_{\times}}(t-x_j,{\boldsymbol{s}}))\Bigg| \leq \sum_{i=1}^n\mathbb{E}[Z_{\times,i}(t-x_j)] \leq C_t \]
for some universal
 $C_t \in \mathbb{R}$
as t is fixed. Moreover, as K and
 $\Lambda$
are locally bounded, we can apply a variation of the dominated convergence theorem, e.g. [Reference Klenke20, Theorem 6.28]. To further exchange the summation and
 $\partial/\partial s_i$
, by Hadamard’s inequality (see, e.g., [Reference Baccelli, Blaszczyszyn and Karray3, (15.A.1)]),
 \begin{equation} D({\boldsymbol{x}}) = \det(K(x_i,x_j))_{1\leq i,j \leq n} \leq \prod_{i=1}^n K(x_i,x_i), \end{equation}
so
 \[ \Bigg|\int_{(0,t]^n}D({\boldsymbol{x}})\frac{\partial}{\partial s_i} \prod_{i=1}^n(1-G_{{\boldsymbol{Z}}_{\times}}(t-x_i,{\boldsymbol{s}}))\,\Lambda(\textrm{d}{\boldsymbol{x}})\Bigg| \leq \bigg(C_t\int_{(0,t]}K(x,x)\,\Lambda(\textrm{d}x)\bigg)^n \;=\!:\; D_t^n, \]
with
 $D_t \in \mathbb{R}_+$
, and again by dominated convergence we can interchange
 $\partial/\partial s_i$
and
 $\sum_{n\geq1}$
(considering the latter as an integral with respect to to a Dirac-type measure).
Observe that
 $1-G_{{\boldsymbol{Z}}_\times}(t-x_i,\textbf{1})=0$
, so
 \begin{align*} \mathbb{E}[Z_i(t)] = \frac{\partial}{\partial s_i} G_{{\boldsymbol{Z}}}(t,{\boldsymbol{s}})\bigg|_{{\boldsymbol{s}} = \textbf{1}} & = -\int_{(0,t]}K(x,x)\frac{\partial}{\partial s_i} (1-G_{{\boldsymbol{Z}}_\times}(t-x,{\boldsymbol{s}}))\bigg|_{{\boldsymbol{s}}=\textbf{1}}\,\Lambda(\textrm{d}x) \\ & = \int_{(0,t]}K(x,x)\mathbb{E}[Z_{\times,i}(t-x)]\,\Lambda(\textrm{d}x), \end{align*}
as the derivatives of the terms in (15) for
 $n>1$
would have multiple
 $1-G_{{\boldsymbol{Z}}_\times}(t-x_i, \textbf{1})$
for some i, which is zero when evaluated at
 ${\boldsymbol{s}} = \textbf{1}$
.
Similarly, for the second moments we can exchange the derivative and sum because we assume that the respective second moments exist, see (H). We are thus interested in
 \begin{equation} 1 + \sum_{n\geq 1}\frac{(\!-\!1)^{n}}{n!}\int_{(0,t]^n}D({\boldsymbol{x}})\Bigg( \frac{\partial^2}{\partial s_i\partial s_j} \prod_{i=1}^n(1-G_{{\boldsymbol{Z}}_{\times}}(t-x_i,{\boldsymbol{s}}))\bigg|_{{\boldsymbol{s}}=\textbf{1}}\Bigg)\, \Lambda(\textrm{d}{\boldsymbol{x}}), \end{equation}
but again since
 $1-G_{{\boldsymbol{Z}}_\times}(t-x_i, \textbf{1})= 0$
, the non-zero terms at
 ${\boldsymbol{s}}=1$
are obtained for
 $n=1$
and
 $n=2$
. For
 $n=1$
, we have
 \[ \frac{\partial^2}{\partial s_i\partial s_j}(1-G_{{\boldsymbol{Z}}_\times}(t-x,{\boldsymbol{s}})) \bigg|_{{\boldsymbol{s}} = \textbf{1}} = -\mathbb{E}[Z_{\times,i}(t-x)Z_{\times,j}(t-x)], \]
and for
 $n=2$
,
 \begin{multline*} {\frac{\partial}{\partial s_i}}(1-G_{{\boldsymbol{Z}}_{\times}}(t-x_1,{\boldsymbol{s}})) {\frac{\partial}{\partial s_j}}(1-G_{{\boldsymbol{Z}}_{\times}}(t-x_2,{\boldsymbol{s}})) \\ + {\frac{\partial}{\partial s_j}}(1-G_{{\boldsymbol{Z}}_{\times}}(t-x_1,{\boldsymbol{s}})) {\frac{\partial}{\partial s_i}}(1-G_{{\boldsymbol{Z}}_{\times}}(t-x_2,{\boldsymbol{s}})), \end{multline*}
which evaluated at
 ${\boldsymbol{s}}= \textbf{1}$
is exactly
 \[ F^\ast(i,j,x_1,x_2) \;:\!=\; \mathbb{E}[Z_{\times, i}(t-x_1)]\mathbb{E}[Z_{\times,j}(t-x_2)] + \mathbb{E}[Z_{\times,j}(t-x_1)]\mathbb{E}[Z_{\times,i}(t-x_2)]. \]
Writing
 $F(i,x_k)\;:\!=\;\mathbb{E}[Z_{\times,i}(t-x_k)]$
and using
 $\mathbb{E}[{Z}_i(t)] = \int_{(0,t]}K(x,x)\mathbb{E}[Z_{\times,i}(t-x)]\,\Lambda(\textrm{d}x)$
, we have
 \begin{align*} & \int_{(0,t]^2}K(x_1,x_1)K(x_2,x_2)F^\ast(i,j,x_1,x_2)\,\Lambda(\textrm{d}x_1)\,\Lambda(\textrm{d}x_2) \\ & \qquad = \int_{(0,t]}K(x_1,x_1)F(i,x_1)\,\Lambda(\textrm{d}x_1)\int_{(0,t]}K(x_2,x_2)F(j,x_2)\, \Lambda(\textrm{d}x_2) \\ & \qquad\quad + \int_{(0,t]}K(x_1,x_1)F(j,x_1)\,\Lambda(\textrm{d}x_1)\int_{(0,t]}K(x_2,x_2)F(i,x_2)\,\Lambda(\textrm{d}x_2) \\ & \qquad = 2\mathbb{E}[Z_i(t)]\mathbb{E}[Z_j(t)]. \end{align*}
Similarly, because by definition
 $K(x,y) = K(y,x)$
, we can also check that
 \begin{multline*} \int_{(0,t]^2} K^2(x_1,x_2)F^\ast(i,j,x_1,x_2)\,\Lambda(\textrm{d}x_1)\,\Lambda(\textrm{d}x_2) \\ = 2\int_{(0,t]^2}K^2(x_1,x_2)\mathbb{E}[Z_{\times,i}(t-x_1)]\mathbb{E}[Z_{\times,i}(t-x_2)]\, \Lambda(\textrm{d}x_1)\,\Lambda(\textrm{d}x_2). \end{multline*}
Therefore, substituting in (17), we get
 \begin{align*} & \mathbb{E}[Z_i(t)Z_j(t)] \\ & \quad = \frac{\partial^2}{\partial s_i\partial s_j}G_{{\boldsymbol{Z}}}(t,{\boldsymbol{s}}) \bigg|_{{\boldsymbol{s}}=\textbf{1}} \\ & \quad = -\int_{(0,t]}K(x,x)\frac{\partial^2}{\partial s_i\partial s_j}(1-G_{{\boldsymbol{Z}}_\times}(t-x,{\boldsymbol{s}})) \bigg|_{{\boldsymbol{s}}=\textbf{1}}\,\Lambda(\textrm{d}x) \\ & \qquad + \frac{1}{2!}\int_{(0,t]^2}\det(K(x_i,x_j))_{1\leq i,j \leq 2}\frac{\partial^2}{\partial s_i\partial s_j} \Bigg(\prod_{i=1}^2(1-G_{{\boldsymbol{Z}}_{\times}}(t-x_i,{\boldsymbol{s}}))\Bigg)\Bigg|_{{\boldsymbol{s}}=\textbf{1}}\, \Lambda(\textrm{d}x_1)\,\Lambda(\textrm{d}x_2) \\ & \quad = \int_{(0,t]}K(x,x)\mathbb{E}[Z_{\times,i}(t-x)Z_{\times,j}(t-x)]\,\Lambda(\textrm{d}x) \\ & \qquad + \frac{1}{2}\int_{(0,t]^2}(K(x_1,x_1)K(x_2,x_2)-K^2(x_1, x_2))F^\ast(i,j,x_1,x_2)\, \Lambda(\textrm{d}x_1)\,\Lambda(\textrm{d}x_2) \\ & \quad = \int_{(0,t]}K(x,x)\mathbb{E}[Z_{\times,i}(t-x)Z_{\times,j}(t-x)]\,\Lambda(\textrm{d}x) \\ & \qquad + \mathbb{E}[Z_i(t)]\mathbb{E}[Z_j(t)] - \int_{(0,t]^2}K^2(x_1,x_2)\mathbb{E}[Z_{\times,i}(t-x_1)]\mathbb{E}[Z_{\times,i}(t-x_2)]\, \Lambda(\textrm{d}x_1)\,\Lambda(\textrm{d}x_2). \end{align*}
Using the covariance formula gives exactly Theorem 3(ii), which concludes the proof.
6.2. Proof of Theorem 4
Proof. We will work with the Laplace transform of
 ${\boldsymbol{Z}}$
,
 $\mathcal{L}_{{\boldsymbol{Z}}}(t,{\boldsymbol{s}})\;:\!=\;\mathbb{E}[\exp(\!-\!\langle{\boldsymbol{Z}}(t),{\boldsymbol{s}}\rangle)]$
, and use a similar technique to [Reference Rabehasaina and Woo36, Theorem 3]. To facilitate the formalism, define
 ${\boldsymbol{Z}}(t)=0$
for
 $t <0$
. Using (13), we have, for positive x,
 \[ \frac{{\boldsymbol{Z}}_{\times}(t-x)}{{\textrm{e}}^{\rho t}} \xrightarrow[t\to\infty]{\textrm{a.s.}} {\boldsymbol{v}}\cdot{\textrm{e}}^{-\rho x}W_\times, \]
which gives the pointwise convergence of the Laplace transforms, for each
 $x>0$
,
 \begin{equation} \mathcal{L}_{{\boldsymbol{Z}}_{\times}}((t-x),{\boldsymbol{s}}{\textrm{e}}^{-\rho t}) \;:\!=\; \mathbb{E}[\exp(\!-\!\langle{\boldsymbol{Z}}_\times(t-x),{\boldsymbol{s}}{\textrm{e}}^{-\rho t}\rangle)] \xrightarrow[t\to\infty]{}\mathcal{L}_{{\boldsymbol{v}}{W}_{\times}}({\boldsymbol{s}}{\textrm{e}}^{-\rho x}). \end{equation}
 \begin{equation} \mathcal{L}_{{\boldsymbol{Z}}}(t,{\textrm{e}}^{-\rho t}{\boldsymbol{s}}) = 1 + \sum_{n \geq 1}\frac{(\!-\!1)^n}{n!}\int_{(0,t]^n}D({\boldsymbol{x}}) \prod_{i=1}^n(1-\mathcal{L}_{{\boldsymbol{Z}}_{\times}}(t-x_i,{\boldsymbol{s}}{\textrm{e}}^{-\rho t}))\, \Lambda(\textrm{d}{\boldsymbol{x}}). \end{equation}
From (18), for each
 ${\boldsymbol{x}}\in\mathbb{R}^n$
,
 \begin{equation} \textbf{1}_{\{{\boldsymbol{x}}\in(0,t]^n\}}D({\boldsymbol{x}}) \prod_{i=1}^n(1-\mathcal{L}_{{\boldsymbol{Z}}_{\times}}(t-x_i,{\boldsymbol{s}}{\textrm{e}}^{-\rho t})) \xrightarrow[t\to\infty]{} D({\boldsymbol{x}})\prod_{i=1}^n(1-\mathcal{L}_{{\boldsymbol{v}}W_{\times}}({\boldsymbol{s}}{\textrm{e}}^{-\rho x_i})). \end{equation}
To use the last result under the integral sign in (19), we need to provide a bound with an integrable function. First, by Hadamard’s inequality (16),
 $D({\boldsymbol{x}}) \leq \prod_{i=1}^n K(x_i,x_i)$
. Second, note that as we are working with Laplace transforms of positive random variables, we can assume that the vector
 ${\boldsymbol{s}}$
has positive entries. Let
 $C_{{\boldsymbol{s}}}^\ast \;:\!=\; \max_j s_j/\min_j v_j$
, so that, for all j,
 $0 \leq s_j \leq C_{{\boldsymbol{s}}}^\ast v_j$
. We next bound as in [Reference Rabehasaina and Woo36, Section 3.1]:
 \begin{align} {\textrm{e}}^{-\rho t}\mathbb{E}[\langle{\boldsymbol{Z}}_{\times}(t-x),{\boldsymbol{s}}\rangle] & = {\textrm{e}}^{-\rho x}\mathbb{E}[\langle{\textrm{e}}^{-\rho(t-x)}{\boldsymbol{Z}}_{\times}(t-x),{\boldsymbol{s}}\rangle] \nonumber \\ & \leq C_{{\boldsymbol{s}}}^\ast{\textrm{e}}^{-\rho x} \mathbb{E}[\langle{\textrm{e}}^{-\rho(t-x)}{\boldsymbol{Z}}_{\times}(t-x),{\boldsymbol{v}}\rangle] \nonumber \\ & = C_{{\boldsymbol{s}}}^\ast{\textrm{e}}^{-\rho x} \mathbb{E}[\langle{\textrm{e}}^{-\rho\cdot0}{\boldsymbol{Z}}_{\times}(0),{\boldsymbol{v}}\rangle] \nonumber \\ & = C_{{\boldsymbol{s}}}^\ast{\textrm{e}}^{-\rho x}\mathbb{E}[\langle{\boldsymbol{I}}_{0},{\boldsymbol{v}}\rangle] \;=\!:\; C_{{\boldsymbol{s}}}{\textrm{e}}^{-\rho x}, \end{align}
where we used the fact that
 $(\langle{\textrm{e}}^{-\rho t}{\boldsymbol{Z}}_{\times}(t),{\boldsymbol{v}}\rangle)_{t\geq0}$
is a martingale [Reference Athreya and Ney2, p. 209]. Therefore,
 \begin{align*} |1-\mathcal{L}_{{\boldsymbol{Z}}_{\times}}(t-x,{\boldsymbol{s}}{\textrm{e}}^{-\rho t})| & = \mathbb{E}[1-\exp(\!-\!{\textrm{e}}^{-\rho t}\langle{\boldsymbol{Z}}_{\times}(t-x),{\boldsymbol{s}}\rangle)] \\ & \leq \mathbb{E}[{\textrm{e}}^{-\rho t}\langle{\boldsymbol{Z}}_{\times}(t-x),{\boldsymbol{s}}\rangle] \leq C_{{\boldsymbol{s}}}{\textrm{e}}^{-\rho x}, \end{align*}
where in the first inequality we used that
 $1-{\textrm{e}}^{-x}\leq x$
for positive x. Thus, we get
 \begin{equation*} \Bigg|\textbf{1}_{\{{\boldsymbol{x}}\in(0,t]^n\}}D({\boldsymbol{x}}) \prod_{i=1}^n(1-\mathcal{L}_{{\boldsymbol{Z}}_{\times}}(t-x_i,{\boldsymbol{s}}{\textrm{e}}^{-\rho t}))\Bigg| \leq C_{{\boldsymbol{s}}}^n\prod_{i=1}^n K(x_i,x_i){\textrm{e}}^{-\rho x_i}. \end{equation*}
This is indeed a
 $\Lambda(\textrm{d}{\boldsymbol{x}})$
-integrable function because
 $\int_{(0,\infty)}{\textrm{e}}^{-\rho x}K(x,x)\,\Lambda(\textrm{d}x)$
is finite by assumption, so
 \begin{equation} C_{{\boldsymbol{s}}}^n\int_{(0,\infty)^n}\prod_{i=1}^n\det(K(x_i,x_i)){\textrm{e}}^{-\rho x_i}\,\Lambda(\textrm{d}{\boldsymbol{x}}) = \bigg(C_{{\boldsymbol{s}}}\int_{(0,\infty)}{\textrm{e}}^{-\rho x}K(x,x)\,\Lambda(\textrm{d}x)\bigg)^n < \infty. \end{equation}
Therefore, we can apply the dominated convergence theorem in (20), which gives, for each n,
 \begin{multline*} \int_{(0,t]^n}D({\boldsymbol{x}})\prod_{i=1}^n(1-\mathcal{L}_{{\boldsymbol{Z}}_{\times}}(t-x_i,{\boldsymbol{s}}{\textrm{e}}^{-\rho t}))\, \Lambda(\textrm{d}{\boldsymbol{x}}) \\ \xrightarrow[t\to\infty]{} \int_{(0,\infty)^n}D({\boldsymbol{x}})\prod_{i=1}^n(1-\mathcal{L}_{{\boldsymbol{v}}W_{\times}}({\boldsymbol{s}}{\textrm{e}}^{-\rho x_i}))\, \Lambda(\textrm{d}{\boldsymbol{x}}). \end{multline*}
Substituting in (19), again by dominated convergence and the bound in (22), we obtain that
 \[ \mathcal{L}_{{\boldsymbol{Z}}}(t,{\textrm{e}}^{-\rho t}{\boldsymbol{s}}) \xrightarrow[t\to\infty]{} 1 + \sum_{n \geq 1}\frac{(\!-\!1)^n}{n!}\int_{(0,\infty)^n}D({\boldsymbol{x}}) \prod_{i=1}^n(1-\mathcal{L}_{{\boldsymbol{v}}W_{\times}}({\boldsymbol{s}}{\textrm{e}}^{-\rho x_i}))\, \Lambda(\textrm{d}\,{\boldsymbol{x}}). \]
We note that the sum in the last limit is absolutely convergent by (22). Letting
 $\Phi$
be the underlying DPP, we can rewrite this as
 \[ \mathcal{L}_{{\boldsymbol{Z}}}(t,{\textrm{e}}^{-\rho t}{\boldsymbol{s}}) \xrightarrow[t\to\infty]{} \mathcal{L}_{\Phi}(\!-\!\ln(\mathcal{L}_{{\boldsymbol{v}}W_\times}({\boldsymbol{s}}{\textrm{e}}^{-\rho x}))), \]
which is exactly the Laplace transform of
 $\int_{(0,\infty)}{\textrm{e}}^{-\rho x}\,\Phi^\ast(\textrm{d}x)$
, where
 $\Phi^\ast(\textrm{d}x)$
is the random measure
 $\sum_k\beta_k\delta_{T_i}$
, where
 $\beta_k$
are i.i.d.
 $\mathbb{R}^d$
random variables with distribution
 ${\boldsymbol{v}}W_\times$
, and
 $T_i$
are the atoms of the determinantal point process
 $\Phi$
, see [Reference Baccelli, Blaszczyszyn and Karray3, Example 2.2.30]. This concludes the proof of Theorem 4.
6.3. Proof of Theorem 5
We will use the following result.
Lemma 2. ([Reference Slavtchova-Bojkova, Hyrien and Yanev44, Lemmas 2 and 3]). Let
 $\alpha_\infty$
and
 $\beta_\infty$
be positive real constants. Then:
-
(i) If
$\alpha (t)\mathop \sim \limits^\infty {\alpha _\infty }{{\textrm{e}}^{\delta t}}$
with
$\delta \in {\mathbb R}$
and
$\int_{0}^{\infty}{\textrm{e}}^{-\delta x}\beta(x)\,\textrm{d}x$
is finite, then
\[ \int_0^t\beta(t-x)\alpha(x)\,\textrm{d}x \stackrel{\infty}{\sim} \alpha(t)\int_{0}^{\infty}{\textrm{e}}^{-\delta x}\beta(x)\,\textrm{d}x. \]
-
(ii) If
$\alpha (t)\mathop \sim \limits^\infty {\alpha _\infty }$
and
$\beta(t) \stackrel{\infty}{\sim} \beta_\infty$
, then
$\int_0^t\beta(t-x)\alpha(x)\,\textrm{d}x \stackrel{\infty}{\sim} \alpha_\infty\beta_\infty t$
.


Proof of Lemma
1. Let us start with the observation that the stationarity assumption (14), applied for
 $n=1$
, implies that K(x, x) is constant over x. Denote its value by
 $K_\ast$
. By the classical result (see, e.g., [Reference Athreya and Ney2, p. 203] or [Reference Sevastyanov41, p. 151]), we have
 \begin{equation} \mathbb{E}[Z_{\times,i}(t)] \stackrel{\infty}{\sim} {\textrm{e}}^{\rho t}a_i \;:\!=\; {\textrm{e}}^{\rho t}\langle{\boldsymbol{u}},\mathbb{E}[{\boldsymbol{I}}]\rangle v_i. \end{equation}
Next, by Theorem 3,
 $\mathbb{E}[Z_i(t)] = K_\ast\int_0^t\mathbb{E}[Z_{\times,i}(t-x)] {\lambda}(x)\,\textrm{d}x$
, so:
-
• If
$\delta>\rho$
, by (23) the integral
$\int_0^\infty{\textrm{e}}^{-\delta x}\mathbb{E}[Z_{\times,i}(x)]\,\textrm{d}x$
is finite, and from Lemma 2(i) with
$\alpha(t) = {\lambda}(t)$
and
$\beta(t) = \mathbb{E}[Z_{\times,i}(t)]$
, we obtain
\[ \mathbb{E}[Z_i(t)] \stackrel{\infty}{\sim} {\textrm{e}}^{\delta t}A_i\;:\!=\; {\textrm{e}}^{\delta t}K_\ast{\lambda}_\infty\int_0^\infty{\textrm{e}}^{-\delta x}\mathbb{E}[Z_{\times,i}(x)]\,\textrm{d}x; \]
-
• if
$\delta = \rho$
, we apply Lemma 2(ii) with
$\beta(t) = {\textrm{e}}^{-\delta t}\mathbb{E}[Z_{\times,i}(t)] \stackrel{\infty}{\sim} a_i$
and
$\alpha(t) = {\textrm{e}}^{-\delta t}{\lambda}(t) \stackrel{\infty}{\sim} {\lambda}_\infty$
, so
\[ \mathbb{E}[Z_i(t)] = K_\ast{\textrm{e}}^{\delta t}\int_{0}^t\beta(t-x)\alpha(x)\,\textrm{d}x \stackrel{\infty}{\sim} K_\ast{\textrm{e}}^{\delta t}ta_i{\lambda}_\infty \;=\!:\; A_i't{\textrm{e}}^{\delta t}. \]


We continue with a similar strategy for the variance: the asymptotics of the second moment of
 $Z_{\times,i}(t)$
are available in [Reference Sevastyanov41, p. 152] or [Reference Athreya and Ney2, p. 204], giving, for some positive constants
 $B_{j,i}$
,
 \[ \mathbb{E}[(Z_{\times,i}(t))^2] \stackrel{\infty}{\sim} \begin{cases} {\textrm{e}}^{\rho t}B_{1,i} & \text{if $\rho<0$}, \\ tB_{2,i} & \text{if $\rho = 0$}, \\ {\textrm{e}}^{2\rho t}B_{3,i} & \text{if $\rho > 0$}. \end{cases} \]
Further, by Theorem 3(ii),
 $\textrm{Var}(Z_i(t)) \leq K_\ast\int_0^t\mathbb{E}[(Z_{\times,i}(t-x))^2]{\lambda}(x)\,\textrm{d}x$
. We consider the relevant cases:
-
• Fix
$\delta>\rho$
. We apply Lemma 2 with
$\alpha(t) = \mathbb{E}[(Z_{\times,i}(t))^2]$
and
$\beta(t) = {\lambda}(t) \stackrel{\infty}{\sim} {\textrm{e}}^{\delta t}{\lambda}_\infty$
. Note that if
$\rho<0$
then
$\alpha(t) \stackrel{\infty}{\sim} {\textrm{e}}^{\rho t}B_{1,i}$
, and if
$\rho = 0$
then
$\alpha(t) \stackrel{\infty}{\sim} tB_{2,i}$
, so in both cases
$\int_0^\infty{\textrm{e}}^{-\delta x}\alpha(x)\,\textrm{d}x$
is finite, and we thus obtain
\[ K_\ast\int_0^t\mathbb{E}[(Z_{\times,i}(t-x))^2]{\lambda}(x)\,\textrm{d}x \stackrel{\infty}{\sim} K_\ast{\textrm{e}}^{\delta t}{\lambda}_{\infty}\int_0^\infty{\textrm{e}}^{-\delta x}\beta(x)\,\textrm{d}x = \textrm{O}({\textrm{e}}^{\delta t}). \]
-
• Fix
$\rho > 0$
and
$\delta = 2\rho$
. We apply Lemma 2(ii) with
$\alpha(t) = {\textrm{e}}^{-2\rho t}\mathbb{E}[(Z_{\times,i}(t))^2] \stackrel{\infty}{\sim} B_{3,i}$
and
$\beta(t) = {\textrm{e}}^{-\delta t}{\lambda}(t) \stackrel{\infty}{\sim} {\lambda}_\infty$
, so
\[ K_\ast\int_0^t\mathbb{E}[(Z_{\times,i}(t-x))^2]{\lambda}(x)\,\textrm{d}x = K_\ast{\textrm{e}}^{2\rho t}\int_0^t\alpha(t-x)\beta(t)\,\textrm{d}t = \textrm{O}(t{\textrm{e}}^{2 \rho t}) = \textrm{O}(t{\textrm{e}}^{\delta t}). \]
-
• With similar arguments, if
$\delta>2\rho>0$
we have
$\mathbb{E}[(Z_{\times,i}(t))^2] \stackrel{\infty}{\sim} {\textrm{e}}^{2\rho t}B_{3,i}$
, so we apply Lemma 2 with
$\alpha(t) \;:\!=\; \mathbb{E}[(Z_{\times,i}(t))^2]$
and
$\beta(t) = {\lambda}(t)$
. If
$\delta < 2\rho$
, we should reverse the roles of
$\alpha$
and
$\beta$
. -
• If
$\delta=\rho>0$
, we use Lemma 1 with
$\alpha(t) = {\lambda}(t) \stackrel{\infty}{\sim} {\lambda}_\infty{\textrm{e}}^{\delta x}$
and
$\beta(t) = \mathbb{E}[(Z_{\times,i}(t))^2] \stackrel{\infty}{\sim} {\textrm{e}}^{2\rho t}B_{3,i}$
.


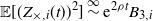


Proof of Theorem 5. For items (iii) and (iv) we follow an approach similar to the one chosen in [Reference Rabehasaina and Woo36], and for (i) and (ii) we use techniques from [Reference Hyrien, Mitov and Yanev15, Reference Hyrien, Mitov and Yanev16, Reference Slavtchova-Bojkova, Hyrien and Yanev44, Reference Slavtchova-Bojkova and Yanev46]; the core of the argument lies in Lemma 1.
Indeed, substituting its estimates, we see that if
 $\delta > \max\{\rho,0\}$
or
 $\delta=\rho>0$
,
 \begin{equation*} \mathbb{E}\bigg[\bigg(\frac{Z_i(t)}{\mathbb{E}[Z_i(t)]} - 1\bigg)^2\bigg] = \frac{\textrm{Var}(Z_i(t))}{\mathbb{E}[Z_i(t)]^2} \xrightarrow[t\to\infty]{} 0, \end{equation*}
which gives exactly items (i) and (ii) of the theorem.
For item (iv), we assume that the process is subcritical (
 $\rho<0$
) and that
 ${\lambda}(x) \stackrel{\infty}{\sim} {\lambda}_\infty$
. As we assume that the immigration is spanned by a DPP, by Theorem 2 we have
 \begin{equation} \mathcal{L}_{{\boldsymbol{Z}}}(t,{\boldsymbol{s}}) = 1 + \sum_{n \geq 1} \frac{(\!-\!1)^n}{n!} \int_{(0,t]^n}D({\boldsymbol{x}})\prod_{i=1}^n(1-\mathcal{L}_{{\boldsymbol{Z}}_{\times}}(t-x_i,{\boldsymbol{s}}))\, \Lambda(\textrm{d}{\boldsymbol{x}}). \end{equation}
To exploit the convergence of
 ${\lambda}(t)$
as
 $t\to\infty$
, we change variables
 $x_i \to t-x_i$
in the last integral. Note that
 \begin{equation} \det(K(t-x_i,t-x_j))_{1\leq i,j \leq n} = \det(K(x_i,x_j))_{1\leq i,j \leq n} \leq \prod_{i=1}^n K(x_i,x_i) = K_\ast^n, \end{equation}
where the first follows from our assumption that the DPP is stationary, and also using inequality (16). Next, for
 ${\boldsymbol{x}} = (x_1, \dots, x_n)$
, writing
 ${\lambda}(t-{\boldsymbol{x}}) \;:\!=\; {\lambda}(t-x_1)\cdots{\lambda}(t-x_n)$
and
 $\textrm{d}{\boldsymbol{x}} \;:\!=\; \textrm{d}x_1\cdots\textrm{d}x_n$
, we get
 \begin{equation} \mathcal{L}_{{\boldsymbol{Z}}}(t,{\boldsymbol{s}}) = 1 + \sum_{n \geq 1}\frac{(\!-\!1)^n}{n!} \int_{(0,t]^n}D({\boldsymbol{x}})\prod_{i=1}^n(1-\mathcal{L}_{{\boldsymbol{Z}}_{\times}}(x_i,{\boldsymbol{s}})) {\lambda}(t-{\boldsymbol{x}})\,\textrm{d}{\boldsymbol{x}}. \end{equation}
To apply the dominated convergence theorem, we first bound as in (21) and, with the same
 $C_{{\boldsymbol{s}}}$
as there,
 \begin{equation} |1-\mathcal{L}_{{\boldsymbol{Z}}_{\times}}(x,{\boldsymbol{s}})| = \mathbb{E}[1-\exp(\!-\!\langle{\boldsymbol{Z}}_{\times}(x),{\boldsymbol{s}}\rangle)] \leq \mathbb{E}[\langle{\boldsymbol{Z}}_{\times}(x),{\boldsymbol{s}}\rangle] \leq {\textrm{e}}^{\rho x}C_{{\boldsymbol{s}}}. \end{equation}
Next, pick C such that
 $\sup_{t \geq C}{\lambda}(t) < \infty$
, which exists as
 ${\lambda}$
has a finite limit at infinity. Therefore, for each
 ${\boldsymbol{x}}\in\mathbb{R}^n$
,
 \begin{align*} & \Bigg|\textbf{1}_{\{{\boldsymbol{x}}\in(0,t]^n\}}D({\boldsymbol{x}}) \prod_{i=1}^n(1-\mathcal{L}_{{\boldsymbol{Z}}_{\times}}(x_i,{\boldsymbol{s}})){\lambda}(t-{\boldsymbol{x}})\Bigg| \\ & \qquad \leq \prod_{i=1}^n\textbf{1}_{\{x_i\in(0,t)\}}K_\ast C_{{\boldsymbol{s}}}{\textrm{e}}^{\rho x_i}{\lambda}(t-x_i) \\ & \qquad = K_\ast^n C_{{\boldsymbol{s}}}^n \prod_{i=1}^n(\textbf{1}_{\{x_i\in(0,t-C)\}}{\textrm{e}}^{\rho x_i}{\lambda}(t-x_i) + \textbf{1}_{\{x_i\in(t-C,t)\}}{\textrm{e}}^{\rho x_i}{\lambda}(t-x_i)) \\ & \qquad \leq K_\ast^n C_{{\boldsymbol{s}}}^n\prod_{i=1}^n({\textrm{e}}^{\rho x_i}\sup_{x\geq C}{\lambda}(x) + \textbf{1}_{\{x_i\in(0,C)\}}{\lambda}(x_i)). \end{align*}
The last is a
 $\textrm{d}{\boldsymbol{x}}$
-integrable function with
 \begin{multline} \int_{(0,\infty)^n}K_\ast^n C_{{\boldsymbol{s}}}^n\prod_{i=1}^n({\textrm{e}}^{\rho x_i}\sup_{x\geq C}{\lambda}(x) + \textbf{1}_{\{x_i\in(0,C)\}}{\lambda}(x_i))\,\textrm{d}{\boldsymbol{x}} \\ = \bigg(K_\ast C_{{\boldsymbol{s}}}\int_0^\infty({\textrm{e}}^{\rho x_i}\sup_{x\geq C}{\lambda}(x) + \textbf{1}_{\{x_i\in(0,C)\}}{\lambda}(x))\,\textrm{d}x\bigg)^n < \infty, \end{multline}
because by assumption the directing measure
 $\Lambda$
of a DPP is always
 $\sigma$
-finite, and because in this case
 $\rho<0$
. Therefore, by dominated convergence,
 \begin{multline*} \int_{(0,t)^n}D({\boldsymbol{x}})\prod_{i=1}^n(1-\mathcal{L}_{{\boldsymbol{Z}}_{\times}}(x_i,{\boldsymbol{s}})) {\lambda}(t-{\boldsymbol{x}})\,\textrm{d}{\boldsymbol{x}} \\ \xrightarrow[t\to\infty]{} {\lambda}_\infty^n\int_{(0,\infty)^n}D({\boldsymbol{x}}) \prod_{i=1}^n(1-\mathcal{L}_{{\boldsymbol{Z}}_{\times}}(x_i,{\boldsymbol{s}}))\,\textrm{d}{\boldsymbol{x}}, \end{multline*}
and, again by dominated convergence, which we can apply thanks to the geometric bound in (28), for the sum in (26) we get
 \begin{equation} \mathcal{L}_{{\boldsymbol{Z}}}(t,{\boldsymbol{s}}) \xrightarrow[t\to\infty]{} 1 + \sum_{n \geq 1}\frac{(\!-\!1)^n{\lambda}^n_{\infty}}{n!}\int_{(0,\infty)^n}D({\boldsymbol{x}}) \prod_{i=1}^n(1-\mathcal{L}_{{\boldsymbol{Z}}_{\times}}(x_i,{\boldsymbol{s}}))\,\textrm{d}{\boldsymbol{x}}. \end{equation}
To conclude that this is the Laplace transform of a positive random variable, it remains to verify that it tends to 1 as
 ${\boldsymbol{s}}\to \textbf{0}$
; see, e.g., [Reference Feller11, p. 431, Chapter XIII.1, Theorem 2]. This is indeed true by the bound in (27) and the choice
 $C_{{\boldsymbol{s}}} = \max_j{s_j}/\min_j{v_j}$
.
Considering item (iv), for critical processes without immigration [Reference Holte14] obtains the limit distribution under optimal assumptions and for a more general class of branching mechanisms. Note, however, that Holte’s
 ${\boldsymbol{v}}$
is an eigenvector of the matrix with entries
 $\mathbb{E}[(\nu_i)_j]$
, whereas in this work we define
 ${\boldsymbol{v}}$
via (12) (see also Remark 1). Denoting with a subscript H the corresponding quantities from [Reference Holte14], and taking into account the normalization there of
 $\langle{\boldsymbol{u}}_\textrm{H},{\boldsymbol{v}}_\textrm{H}\rangle = 1$
,
 $\langle{\boldsymbol{v}}_\textrm{H},\textbf{1}\rangle = 1$
, we have, for
 $D_1\;:\!=\;{\sum _j(v_j/\mu_j)}$
and
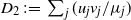 $D_2\;:\!=\;\sum_j(u_j v_j/\mu_j)$
,
 \begin{equation} u_{\textrm{H},i} = \frac{D_1}{D_2}u_i, \qquad v_{\textrm{H},i} = \frac{1}{D_1}\frac{v_i}{\mu_i}, \qquad \sum_j\mu_j u_{\textrm{H},j}v_{\textrm{H},j} = \frac{1}{D_2}. \end{equation}
We show how the results of [Reference Holte14] translate to our setting. Let
 $(e_i)$
be the standard basis in
 $\mathbb{R}^d$
. Therefore, from [Reference Holte14, Lemma on p. 493], and using subscript H for constants from [Reference Holte14], we have
 \begin{align*} H_i\bigg(\frac{{\boldsymbol{s}}}{t},t\bigg) & \;:\!=\; \mathbb{E}\bigg[1-\exp\bigg({-}\bigg\langle Z_\times(t),\frac{{\boldsymbol{s}}}{t}\bigg\rangle\bigg) \mid Z_{\times}(0)=e_i\bigg] \\ &\ = \frac{1}{t}\frac{||{\boldsymbol{s}}||_\textrm{H}}{1+\langle{\boldsymbol{c}}_\textrm{H},{{\boldsymbol{s}}}\rangle} {\boldsymbol{u}}_{\textrm{H},i} + \textrm{o}\bigg(\frac1t\bigg) \;=\!:\; \frac{C_i}{t} + \textrm{o}\bigg(\frac1t\bigg). \end{align*}
Our process starts with a random number of particles of law
 ${\boldsymbol{I}}$
, so a first-order expansion gives us
 \begin{align} 1-\mathcal{L}_{{\boldsymbol{Z}}_{\times}}\bigg(t,\frac{{\boldsymbol{s}}}{t}\bigg) & = \mathbb{E}\bigg[1-\exp\bigg({-}\bigg\langle{\boldsymbol{Z}}_\times(t), \frac{{\boldsymbol{s}}}{t}\bigg\rangle\bigg)\bigg] \nonumber \\ & = \sum_{{\boldsymbol{x}}=(x_1,\dots,x_d)}\mathbb{P}({\boldsymbol{I}}={\boldsymbol{x}}) \Bigg(1-\prod_i{\bigg(1-H_i\bigg(\frac{{\boldsymbol{s}}}{t},t\bigg)\bigg)}^{x_i}\Bigg) \nonumber \\ & = \sum_{{\boldsymbol{x}}=(x_1,\dots,x_d)}\mathbb{P}({\boldsymbol{I}}={\boldsymbol{x}}) \Bigg(1-\prod_i\bigg(1-x_i\frac{C_i}{t} + \textrm{o}\bigg(\frac1t\bigg)\bigg)\Bigg) \nonumber \\ & = \sum_{{\boldsymbol{x}}=(x_1,\dots,x_d)}\mathbb{P}({\boldsymbol{I}}={\boldsymbol{x}}) \Bigg(\sum_i\bigg(x_i\frac{C_i}{t} + \textrm{o}\bigg(\frac1t\bigg)\bigg)\Bigg) \nonumber \\ & = \frac{1}{t}\mathbb{E}[\langle{\boldsymbol{I}},{{\boldsymbol{C}}}\rangle] + \textrm{o}\bigg(\frac1t\bigg), \quad \text{with } {\boldsymbol{C}}\;:\!=\;(C_1,\dots,C_d). \end{align}
Setting our parameters as
 \[ \beta \;:\!=\; \frac{\mathbb{E}[\langle{\boldsymbol{I}},{\boldsymbol{u}}\rangle]}{Q} \quad \text{with} \ Q\;:\!=\;\frac{1}{2}\sum_{i,j,k=1}^d\frac{\partial^2 G_{{\nu_i}}}{\partial x_j\partial x_k} \bigg|_{{\boldsymbol{x}}=\textbf{1}}\mu_i^{-1}{v}_i{u}_j{u}_k, \]
using (30), we calculate the constants from [Reference Holte14]:
 \[ \beta_\textrm{H} = \frac{1}{D_2}, \qquad \frac{1}{2}\langle{\boldsymbol{v}}_\textrm{H},{\boldsymbol{q}}[{\boldsymbol{u}}]\rangle = \frac{D_1}{D_2^2}Q, \qquad ||{\boldsymbol{s}}||_\textrm{H} = \frac{D_2}{D_1}\langle{\boldsymbol{s}},{\boldsymbol{v}}\rangle, \qquad {\boldsymbol{c}}_\textrm{H} = Q{\boldsymbol{v}}. \]
Substituting the definition of
 $C_i$
in (31), we obtain
 \[ t\bigg(1-\mathcal{L}_{{\boldsymbol{Z}}_{\times}}\bigg(t,\frac{{\boldsymbol{s}}}{t}\bigg)\bigg) \xrightarrow[t\to\infty]{} {\beta}\frac{\langle{\boldsymbol{s}},{\boldsymbol{v}}\rangle}{1/Q+\boldsymbol{\langle s,{\boldsymbol{v}}\rangle}}. \]
We note that
 $Q\neq0$
: as earlier (see [Reference Athreya and Ney2, p. 203]),
 $u_i$
and
 $v_i$
are strictly positive, and because the derivatives represent factorial moments of
 $\mathbb{N}$
-valued random variables, if
 $Q=0$
then
 $\mathbb{E}[\nu_i(\nu_i-1)]=0$
for all i, so
 $\nu_i$
can only take values 0 and 1. However, by the criticality assumption,
 $\mathbb{E}[Z_\times(t)]=\mathbb{E}[Z_\times(0)]$
, so we must have
 $\mathbb{P}(\nu_i =1)=1$
, so
 $\textrm{Var}(||\boldsymbol{\nu}||)=0$
, which is not possible by our non-degeneracy assumption.
We will use the last limit in a form that is obtained by substituting t with
 $t(1-x)$
and
 ${\boldsymbol{s}}$
with
 ${\boldsymbol{s}}(1-x)$
for
 $x \in (0,1)$
, which gives
 \[ t(1-x)\bigg(1-\mathcal{L}_{{\boldsymbol{Z}}_{\times}}\bigg(t(1-x),\frac{{\boldsymbol{s}}}{t}\bigg)\bigg) \xrightarrow[t\to\infty]{} \beta\frac{(1-x)\langle{\boldsymbol{s}},{\boldsymbol{v}}\rangle} {1/Q+(1-x)\langle{\boldsymbol{s}},{\boldsymbol{v}}\rangle}. \]
Dividing by
 $(1-x)$
, then substituting in (24) and changing variables
 $x_i \to tx_i$
, we get
 \[ \mathcal{L}_{{\boldsymbol{Z}}}\bigg(t,\frac{{\boldsymbol{s}}}{t}\bigg) = 1 + \sum_{n \geq 1}\frac{(\!-\!1)^n}{n!}\int_{(0,1)^n}D(t{\boldsymbol{x}}) \prod_{i=1}^nt\bigg(1-\mathcal{L}_{{\boldsymbol{Z}}_{\times}}\bigg(t(1-x_i),\frac{{\boldsymbol{s}}}{t}\bigg)\bigg) {\lambda}(t{\boldsymbol{x}})\,\textrm{d}{\boldsymbol{x}}. \]
Next, (25) and (27) give constant bounds for
 $D(t{\boldsymbol{x}})$
and the product. Moreover, as
 ${\lambda}$
is integrable, it is bounded on
 $|x|>\epsilon$
. We also have that
 $D(t{\boldsymbol{x}})$
tends to 1
 $\textrm{d}{\boldsymbol{x}}$
-almost everywhere, because for
 ${\boldsymbol{x}}$
with different entries,
 $K(tx_i,tx_j) = K(t|x_i-x_j|,0)$
tends to 0 if
 $x_i \neq x_j$
for
 $t \to \infty$
by assumption. Therefore, by dominated convergence,
 \begin{align*} \mathcal{L}_{{\boldsymbol{Z}}}\bigg(t,\frac{{\boldsymbol{s}}}{t}\bigg) \xrightarrow[t\to\infty]{} & 1 + \sum_{n \geq 1}\frac{(\!-\!1)^n}{n!}\bigg(K^\ast\int_0^1{\lambda}_\infty\beta \frac{\langle{\boldsymbol{s}},{\boldsymbol{v}}\rangle}{1/Q+(1-x)\langle {\boldsymbol{s}},{\boldsymbol{v}}\rangle}\, \textrm{d}x\bigg)^n \\ & = \bigg(\frac{1/Q}{1/Q+\langle{\boldsymbol{s}},{\boldsymbol{v}}\rangle}\bigg)^{K^\ast{\lambda}_\infty\beta}. \end{align*}
This is indeed the Laplace transform of
 $Y{\boldsymbol{v}}$
with
 $Y\sim\Gamma(K ^\ast{\lambda}_\infty\beta,1/Q)$
as claimed, which concludes the proof.
Acknowledgements
We gratefully thank the anonymous referees for their careful review of our manuscript and for their valuable comments and suggestions.
Funding information
This study is financed by the European Union’s NextGenerationEU, through the National Recovery and Resilience Plan of the Republic of Bulgaria, project no. BG-RRP-2.004-0008.
Competing interests
There were no competing interests to declare which arose during the preparation or publication process of this article.


