




No CrossRef data available.
NONLINEAR FUNCTIONS AND CONVERGENCE TO BROWNIAN MOTION: BEYOND THE CONTINUOUS MAPPING THEOREM
Published online by Cambridge University Press: 05 March 2004
Abstract
Weak convergence results for sample averages of nonlinear functions of (discrete-time) stochastic processes satisfying a functional central limit theorem (e.g., integrated processes) are given. These results substantially extend recent work by Park and Phillips (1999, Econometric Theory 15, 269–298) and de Jong (2002, working paper), in that a much wider class of functions is covered. For example, some of the results hold for the class of all locally integrable functions, thus avoiding any of the various regularity conditions imposed on the functions in Park and Phillips (1999) or de Jong (2002).I thank Robert de Jong for drawing my attention to this problem and Hannes Leeb for helpful comments. This paper was presented at the Econometric Society European Meeting 2002 in Venice.
Information
- Type
- Research Article
- Information
- Copyright
- © 2004 Cambridge University Press
1. INTRODUCTION
A standard tool in the asymptotic theory of integrated processes and elsewhere is a functional central limit theorem. Typically, a real-valued stochastic process

is considered such that n−1/2x[rn], 0 ≤ r ≤ 1, converges weakly to σW(r) (in the space D[0,1] of cadlag functions), where W(.) represents Brownian motion and [x] denotes the integer part of x. Frequently, then the asymptotic behavior of a functional of the form
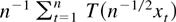
is of interest. Such functionals arise in the construction of test statistics or in the theory of nonlinear estimation with integrated processes (Park and Phillips, 2001). For continuous real-valued functions T on

an argument based on the continuous mapping theorem shows that
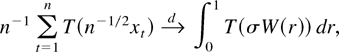
where

signifies convergence in distribution; for convenience we include a formal statement and a proof in Appendix A; cf. Lemma A.1 and its proof. For an important subclass (cf. Park and Phillips, 1999, Assumption 2.1) of the class of all processes satisfying a functional central limit theorem, Theorem 3.2 in Park and Phillips (1999) shows that property (1.1) actually holds for a class of functions T wider than the class of continuous functions. Functions in that class are dubbed “regular” in Park and Phillips (1999). Apart from continuous functions, this class contains, e.g., locally bounded monotone functions and piecewise continuous functions.
1The last claim is true if one adopts a definition of piecewise continuity such that the l.h.s. and r.h.s. limits exist and are finite at each point of discontinuity.
A function T can be constructed that satisfies all the conditions of Theorem 3.4 in Park and Phillips (1999) but does not satisfy cnT(cn) → 0 as claimed in the proof of that theorem. It seems that to salvage that theorem a condition such as T(x) = o(|x|−1) for x → 0, x ≠ 0, needs to be added.
For T to be defined as a real-valued function on all of

, de Jong (2002) assigns the value zero to T at the pole locations. The results in the present paper do not rely on this (arbitrary) assignment and also work for functions that assume the values ∞ or −∞; cf. Remarks 2.1 and 2.5. (The arguments in these remarks also show that an assignment such as the one in de Jong, 2002, is in fact inconsequential under the assumptions on the process made in that paper.)
In the present paper we establish the result (1.1) under the minimal condition that T is locally integrable (in the Lebesgue sense). In contrast to Park and Phillips (1999) and de Jong (2002) we thus are able to avoid any regularity condition on T save the unavoidable local integrability condition. Note that any “regular” function in the sense of Park and Phillips (1999) is locally bounded and thus is a fortiori locally integrable (cf. also Park and Phillips, 1999, Remark 3.3(a)). Thus, apart from covering a wider class of functions T than in Park and Phillips (1999) or de Jong (2002), our results also have the advantage of relieving one from the nontrivial burden of verifying regularity conditions as is necessary when using the results of Park and Phillips or de Jong. We first prove result (1.1) under high-level assumptions on the process xt in Section 2. In Section 3 we provide sufficient conditions on the process xt that imply these high-level assumptions, and we obtain corresponding corollaries. It turns out that one of these corollaries (Corollary 3.3) contains the result in de Jong (2002) as a special case in that it covers a much wider class of functions T (e.g., functions with infinitely many “poles,” or functions that are neither piecewise monotone nor piecewise continuous) and at the same time imposes weaker conditions on xt. Corollary 3.3, in fact, applies to any locally integrable function T that satisfies a certain growth condition at the origin. Corollary 3.2 moreover shows that this growth condition can be dispensed with if a rather mild condition on xt, namely, that the innovations driving xt have a bounded density, is added. Corollary 3.2 thus only imposes the minimal condition of local integrability on T. Both of these corollaries cover classes of functions much wider than the class of “regular” functions considered in Theorem 3.2 of Park and Phillips (1999). Although the conditions on xt maintained by these corollaries are somewhat stronger than the corresponding conditions in Theorem 3.2 of Park and Phillips (1999), we believe that the extra conditions on xt in these corollaries are a small price to pay for the ability to cover much larger function classes. It should furthermore be noted that the assumptions on xt in Corollary 3.3 are strictly weaker than the assumptions on xt employed in Theorem 3.4 of Park and Phillips (1999), thus showing that the “clipping” device of that theorem can be avoided altogether. Section 4 concludes the main body of the paper and discusses some generalizations of the results in Sections 2 and 3. All proofs are relegated to the Appendixes.
After this paper had been written, the book by Borodin and Ibragimov (1995) came to my attention. In this important work results of the form (1.1) and also many other related results are established for the case when the process xt is a random walk with increments that are independent and identically distributed (i.i.d.) and belong to the domain of attraction of a stable law. Their results always assume more in terms of the function T than we do in the present paper. (For example, one of the results in Borodin and Ibragimov, 1995, is for locally Riemann integrable functions, which constitute a much smaller class than the class of locally Lebesgue integrable functions. In particular, locally Riemann integrable functions are necessarily locally bounded, thus ruling out functions with poles.) Contrary to Park and Phillips (1999), de Jong (2002), and the present paper, Borodin and Ibragimov (1995) do not provide results for the case where the increments of xt are dependent (e.g., follow a linear process). However, it should be noted that the results in Borodin and Ibragimov (1995) are more general along another dimension, namely, that the limiting behavior of xt need not be given by Brownian motion but may be given by some stable process. A recent paper by Jeganathan (2002) takes up this issue and extends it to the case of dependent increments.
2. WEAK CONVERGENCE OF NONLINEAR FUNCTIONALS
Let

be a stochastic process with values in

. We shall make use of the following assumptions.
Assumption 2.1. The process n−1/2x[rn], 0 ≤ r ≤ 1, converges weakly to σW(r), where W(.) is Brownian motion on [0,1] and
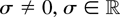
, holds. (As a convention, x[rn] is set equal to zero for r < n−1.)
4If, instead, x[rn] is set equal to an arbitrary random variable x* for r < n−1, which is defined on the probability space supporting (xt), an equivalent assumption is obtained. More generally, Assumption 2.1 is unaffected by any modification made to finitely many elements of (xt).
As usual, it is understood that W(0) = 0 a.s. and that W(.) has continuous sample paths a.s. Furthermore, weak convergence in the preceding assumption is understood w.r.t. the Skorohod topology on the space D[0,1].
Assumption 2.2. For every

the distribution of t−1/2xt possesses a density, ht, say, w.r.t. Lebesgue measure on

. The densities ht are uniformly bounded, i.e.,
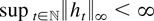
holds, where ∥.∥∞ denotes the sup-norm.
In light of the fact that the distribution of t−1/2xt converges to a normal distribution under Assumption 2.1, the conditions imposed by Assumption 2.2 have some intuitive appeal; in particular, if a local central limit theorem holds (cf. Ibragimov and Linnik, 1971, Theorem 4.3.1), then ∥ht∥∞ is automatically uniformly bounded (at least from some index onward). Sufficient conditions for Assumptions 2.1 and 2.2 will be discussed in the next section.
Let T be a real-valued Borel-measurable function on

. We say that T is locally integrable if and only if
5The integral in expression (2.2) is to be understood in the sense of Lebesgue.
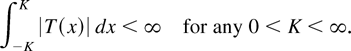
Condition (2.2) is certainly satisfied if T is locally bounded (i.e., sup|x|≤K|T(x)| < ∞ for any 0 < K < ∞) but is much less restrictive because it allows also for many locally unbounded functions such as, e.g., T(x) = log|x| and T(x) = |x|α, −1 < α < 0.
6Condition (2.2) is of course also satisfied if T is only essentially locally bounded (i.e., if ess-sup|x|≤K|T(x)| < ∞ for any 0 < K < ∞, where ess-sup denotes the essential supremum w.r.t. Lebesgue measure).

, a real number has to be specified as the value of T at x = 0; if one desires to set T(0) = −∞ or T(0) = ∞, respectively, T becomes a function with values in the extended real line; cf. Remarks 2.1 and 2.5, which follow.)
The following theorem establishes the main weak convergence result for locally integrable functions. It is remarkable in that it does not impose any regularity conditions on T beyond (2.2). Its generalization to the case of functions with values in the extended real line is given in Remark 2.1, which follows.
THEOREM 2.1. Suppose Assumptions 2.1 and 2.2 hold and

is locally integrable. Then
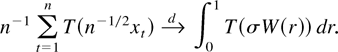
We note that the integral in (2.3) exists a.s. and is finite a.s. if and only if T is locally integrable (see Karatzas and Shreve, 1991, Ch. 3, Proposition 6.27 and Problem 6.29; cf. also Park and Phillips, 1999, Remark 3.3 (a)).7
The integral over the positive part T+(σW(r)) and also the integral over the negative part T−(σW(r)) exist a.s. for every Borel-measurable T, because almost every sample path of W(.) is continuous. The argument in the proof of Theorem 2.1 then also establishes a.s. finiteness of both these integrals under local integrability.
We note for later use that the integral in (2.3) can equivalently be expressed in terms of local time. That is,
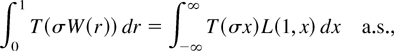
where L(t, x) denotes Brownian local time (cf. Chung and Williams, 1990, Corollary 7.4).
Remark 2.1. (Extended Real Functions)
(a) Theorem 2.1 also holds if T is a Borel-measurable function from

to the extended real line
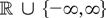
that is locally integrable (e.g., if T(x) = log|x| for x ≠ 0 and =−∞ for x = 0 or if T(x) = |x|α for x ≠ 0 and = ∞ for x = 0, −1 < α < 0). To see this, first note that we may change T into a locally integrable real-valued function T* by modifying T only on a set of Lebesgue measure zero. Because the distribution of xt is absolutely continuous by Assumption 2.2,

coincides with
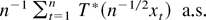
and, in particular, is a.s. well defined. It hence suffices to show that the integral
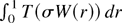
is well defined a.s. and coincides a.s. with
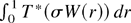
. For this it is enough to show that for almost every path of Brownian motion the set D = {r ∈ [0,1]: T (σW(r)) ≠ T*(σW(r))} is a Lebesgue null set: Let A denote the Lebesgue null set
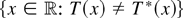
. Then 1D(r) = 1A(σW(r)) and hence
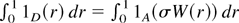
. Corollary 7.4 in Chung and Williams (1990) gives
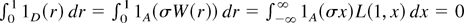
where L(t, x) denotes local time and where the last equality follows because A is a Lebesgue null set and σ ≠ 0. This establishes the claim.
(b) Similar reasoning as in (a) shows that equation (2.4) also holds for locally integrable functions
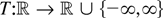
.
Remark 2.2. If T is a function from

(or to (
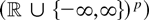
) with each component being locally integrable, then Theorem 2.1 continues to hold (where the r.h.s. of (2.3) is defined componentwise). This follows from Theorem 2.1 (and Remark 2.1) combined with the Cramér–Wold device.
Remark 2.3.
(a) If xt satisfies the convergence condition in Assumption 2.1 and if Assumption 2.2 holds, then necessarily σ ≠ 0 holds as is easily seen.
(b) If xt satisfies the convergence condition in Assumption 2.1, but with σ = 0, and if T is continuous, then (2.3) continues to hold by Lemma A.1. However, this is not necessarily true for arbitrary locally integrable (even “regular”) T as the following example shows.
8Of course, it is trivially true for any real-valued T if, e.g., xt = 0 with probability one for all

.
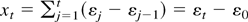
where the random variables εt are i.i.d. standard normal. Then the convergence condition in Assumption 2.1 is satisfied with σ = 0. Let T(x) = 1(−∞,0)(x) and note that T is locally integrable and is even “regular” in the sense of Park and Phillips (1999). The l.h.s. of (2.3) is now equal to
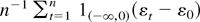
, which converges a.s. to E(1(−∞,0)(εt − ε0)|ε0) = Φ(ε0), which is positive (Φ denoting the standard normal cumulative distribution function [c.d.f.]). The r.h.s. of (2.3), however, is equal to T(0) = 0, because σ = 0.
Theorem 2.1 is in fact a special case of a more general result that makes use of a weaker version of Assumption 2.2.
Assumption 2.2*. There exists

such that for every t ≥ a the distribution of t−1/2xt possesses a density, ht, say, w.r.t. Lebesgue measure on

. Furthermore, supt≥a∥ht∥∞ < ∞ holds.
Assumption 2.2* does not restrict the distribution of xt,1 ≤ t < a, at all. Of course, under any assumption implying existence and boundedness of ht for 1 ≤ t < a, Assumption 2.2* becomes equivalent to Assumption 2.2. As with Theorem 2.1, Theorem 2.2 is formulated for real-valued functions. Its generalization to the case of extended real functions is given in Remark 2.5, which follows.
THEOREM 2.2. Suppose Assumptions 2.1 and 2.2* hold and

is locally integrable. Then
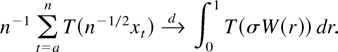
If, additionally,
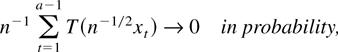
then (2.3) also holds. (In case a = 1 we use the convention that the sum in (2.6) is zero.)
Of course, Theorem 2.1 is a special case of Theorem 2.2 (with a = 1). It is not difficult to see that existence and boundedness of ht for 1 ≤ t < a is a sufficient condition for (2.6) when T is locally integrable.9
To see this note that for every t, 1 ≤ t < a, (and M > 0) we have

by local integrability of T.
Although (2.6) is true for such functions T, we stress that (2.6) is in general not true without further conditions even for locally integrable T.
PROPOSITION 2.3. For Borel-measurable

consider the following conditions:
(i) T(x) = o(|x|−2) for x → 0, x ≠ 0.
(ii) T is Lebesgue-integrable in a neighborhood of x = 0, |T(x)| is increasing on (−ε,0) and decreasing on (0, ε) for some ε > 0.
(iii) T is Lebesgue-integrable in a neighborhood of x = 0, |T(x)| is increasing on (−ε,0) and bounded on (0, ε) for some ε > 0.
(iv) T is Lebesgue-integrable in a neighborhood of x = 0, |T(x)| is bounded on (−ε,0) and decreasing on (0, ε) for some ε > 0.
(v) T is bounded on (−ε,0) and also on (0, ε) for some ε > 0.
Then each of conditions (ii)–(v) implies (i), which in turn implies (2.6).11
In fact, each one of (ii)–(v) even implies T(x) = o(|x|−1) for x → 0, x ≠ 0.
Simple corollaries to Theorem 2.2 that immediately follow from the preceding discussion are given next. In the important case where xt has an absolutely continuous distribution for all t, the conditions in these corollaries can be weakened somewhat; see Remark 2.4, which follows.
COROLLARY 2.4. Suppose Assumptions 2.1 and 2.2* hold and

is locally integrable. If T satisfies T(x) = o(|x|−2) for x → 0, x ≠ 0, then the weak convergence result (2.3) holds.
COROLLARY 2.5. Suppose Assumptions 2.1 and 2.2* hold and

is locally bounded (and Borel-measurable). Then the weak convergence result (2.3) holds.
As already noted, the “regularity” conditions on T in Park and Phillips (1999) and de Jong (2002), respectively, imply local integrability. Furthermore, their respective “regularity” conditions imply condition (i) in Proposition 2.3.12
Observe that any function “regular” in the sense of Park and Phillips (1999) is locally bounded and thus satisfies (v) of Proposition 2.3. Furthermore, any function “regular” in the sense of de Jong (2002) satisfies at least one of (ii)–(v) in Proposition 2.3 as is easily seen.
Remark 2.4. Suppose

is Borel-measurable and suppose that each xt, 1 ≤ t < a, has a (possibly unbounded) density. Then (2.6) already follows if condition (i) in Proposition 2.3 holds only outside of a set of Lebesgue measure zero.
13To see this, note that after suitably modifying T on a set of Lebesgue measure zero, condition (i) in Proposition 2.3 is satisfied for the modified function and that this modification changes the sum in (2.6) at most on a set of probability zero as a result of the assumption on xt, 1 ≤ t < a.
More generally, if modifying T on a set of Lebesgue measure zero results in a function that satisfies one of conditions (ii)–(v) of Proposition 2.3, then condition (i) holds outside a set of Lebesgue measure zero.
Remark 2.5. (Extended Real Functions).
(a) Similarly as in Remark 2.1, the first claim in Theorem 2.2 also holds for locally integrable functions T from
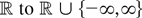
the second claim also holds provided that the expression in (2.6) is well defined (at least on a sequence of sets Ωn with P(Ωn) → 1 as n → ∞).
15That is, there exists a sequence of sets Ωn with P(Ωn) → 1 as n → ∞ such that T(n−1/2xt(ω)) = ∞ and T(n−1/2xs(ω)) = −∞ do not hold simultaneously for ω ∈ Ωn and some 1 ≤ s < a, 1 ≤ t < a.

(or in

).
(b) Suppose the function T in Proposition 2.3 takes now values in
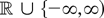
).
16As a point of interest we note that for real-valued T condition (v) is in fact equivalent to boundedness of T on (−ε, ε), but this is not necessarily so if T takes its values in

.

if additionally T(0) is finite or if none of the distributions of xt, 1 ≤ t < a, has positive point mass at x = 0.
(c) Remark 2.4 continues to hold for functions T :
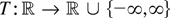
. In particular, Corollary 2.4 also holds for

already under the weaker form of condition (i), provided each xt, 1 ≤ t < a, has a (possibly unbounded) density. Similarly, Corollary 2.5 already holds for essentially locally bounded
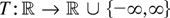
under the same provision for xt, 1 ≤ t < a. (If
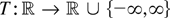
is locally bounded, we are back to the case of real-valued T, and hence Corollary 2.5 directly applies without any further provision on xt, 1 ≤ t < a.)
Remark 2.6. Suppose
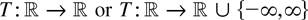
is essentially locally bounded and suppose that Assumptions 2.1 and 2.2* hold. Then certainly (2.5) holds (even T locally integrable would suffice). We stress, however, that (2.3) need not follow in general without further assumptions. Remarks 2.4 and 2.5(c) provide such additional conditions. Alternatively, it follows from the preceding discussion that (2.3) also holds if we additionally assume that condition (i) in Proposition 2.3 holds, and that T(0) is finite or none of the distributions of xt, 1 ≤ t < a, has positive point mass at x = 0.
Remark 2.7. Similarly as in Remark 2.2, Theorem 2.2 continues to hold for functions T with values in

. For functions T with values in (
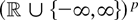
the same is also true for the first claim in Theorem 2.2, and it is true for the second claim provided (2.6) is well defined for any linear combination α′T. A corresponding remark applies to Corollaries 2.4 and 2.5, Remark 2.4, and their extensions discussed in Remark 2.5.
3. SUFFICIENT CONDITIONS AND COROLLARIES
In this section we discuss the important special case when xt is an integrated process, which is the case exclusively considered in Park and Phillips (1999) and de Jong (2002). Assume that for n ≥ 1 the process xn takes the form
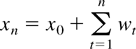
with x0 being independent of the process (wt)t≥1 and with wt given by
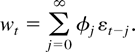
Here (εj) are i.i.d., E(εj) = 0, Eεj2 < ∞,
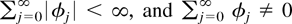
. Without loss of generality we shall set the variance of εj equal to one. Furthermore, it is assumed that εj has a density, say, q. The preceding assumptions will be kept throughout Section 3 and will be referred to as the maintained assumptions of Section 3.
3.1. Sufficient Conditions for Assumptions 2.2 and 2.2*
To begin with, note that xn can be represented as
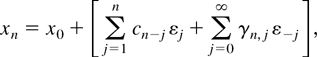
where
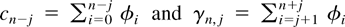
. It immediately follows that n−1/2xn has a density for every n ≥ 1 (cf. Lukacs, 1970, Theorem 3.3.2, and observe that the term in brackets in (3.3) cannot be identically zero because
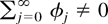
).
To motivate the sufficient conditions for Assumptions 2.2 and 2.2* given in Lemma 3.1, which follows, we start with a preparatory and informal discussion. It is easy to see that any distribution given by a convolution has a bounded density if at least one factor in the convolution has a bounded density. Consequently, the density hn of n−1/2xn is guaranteed to be bounded (for every fixed n ≥ 1) if the (common) density q of εj is bounded. We note that a sufficient condition for boundedness of q is that ψ, the characteristic function of εj, is absolutely integrable (Lukacs, 1970, Theorem 3.2.2). However, the density hn can be bounded even if the density q is unbounded. To see how this can happen, consider for the moment the special case where xn is a random walk, i.e., where wt = εt and where x0 = 0 (for simplicity). Because n−1/2xn is then the sum of n i.i.d. random variables, its density hn is the (scaled) n-fold convolution of q itself. Now, for example, if q has a pole, it can happen that this pole is “smoothed” out by the convolution operation, resulting in a bounded density hn. Related to this observation is the fact that in cases where the characteristic function ψ(s) of εj is not absolutely integrable, the characteristic function of n−1/2xn can be integrable (implying that hn is bounded) from some n onward, because it is the nth power of ψ (evaluated at n−1/2s) and because |ψ| ≤ 1 holds. It follows that absolute integrability of a power of ψ will imply (individual) boundedness of hn, at least from a certain n onward, and thus will be a central condition in the following. As it turns out, this central condition implies not only individual boundedness of hn (from a certain n onward) but also uniform boundedness (from a certain n onward). Returning to the case of general xn as in (3.1), we note that (depending on the behavior of the coefficients φj) often hn is in fact a convolution of much more than n factors of the form q (sometimes even of infinitely many factors). Not too surprisingly, in this case the previously mentioned central condition on ψ will automatically deliver individual boundedness of hn for every n ≥ 1.
With ψ denoting the characteristic function of εj, we shall therefore consider the following integrability condition:
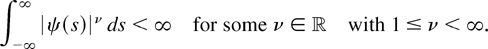
Recall that (3.4) with ν = 1 implies boundedness of q and that (3.4) becomes less stringent as ν increases. In particular, characteristic functions corresponding to unbounded densities can satisfy (3.4) with ν > 1; cf. Remark 3.1(b), which follows. We mention here that a simple sufficient condition for (3.4) is |ψ(s)| = O(s−η) as s → ∞ for some η > ν−1. In particular, if |ψ(s)| = O(s−η) for some η > 0, then (3.4) holds for some ν ≥ 1. The latter condition with “O” strengthened to “o” is used in Park and Phillips (1999) and de Jong (2002); see Section 3.3 for more discussion.
The following lemma provides sufficient conditions for Assumptions 2.2 and 2.2* and is inspired by Section 4.3 of Ibragimov and Linnik (1971). Part (i) of the lemma improves upon Lemma 1 in de Jong (2002). Recall that hn denotes the density of n−1/2xn.
LEMMA 3.1. Suppose condition (3.4) holds. Then the following statements are true.
(i) There exist

and a real number C such that for n ≥ n0

holds; i.e., Assumption 2.2* is satisfied.
(ii) If, for every n ≥ 1, at least ν coefficients of the innovations εj, −∞ < j ≤ n, in (3.3) are nonzero, then (3.5) holds for n ≥ n0 = 1.17
Lemma B.2 in fact shows that if at least ν coefficients of εj, −∞ < j ≤ n, in (3.3) are nonzero for a given n, then ∥hn∥∞ is finite for this n.
(iii) If ν = 1, then (3.5) holds for n ≥ n0 = 1. That is, Assumption 2.2 is satisfied.
(The constants C in (i)–(iii) and also the index n0 depend only on ψ and the coefficients φj.)
The more difficult part in the proof of the preceding lemma is to establish Assumption 2.2*, i.e., the uniform boundedness of the densities hn from a certain index n0 onward. Once Assumption 2.2* is known to hold, Assumption 2.2 then follows under any condition that implies (individual) boundedness of hn for every n (in fact for every n, 1 ≤ n < a, suffices). Parts (ii) and (iii) provide such conditions. The basic observation here is that whenever (3.4) holds and the distribution of xn is the convolution of not less than ν terms of the form q (not counting the factor corresponding to x0), then ∥hn∥∞ is finite (cf. Lemma B.2 in Appendix B). The additional assumptions in parts (ii) and (iii) precisely imply this for the distribution of xn. As already mentioned, boundedness of q, i.e.,

implies that ∥hn∥∞ is finite for every n ≥ 1. Thus (3.6) is an alternative condition under which Assumptions 2.2 and 2.2* are equivalent. (We note that (3.4) with ν = 1 implies (3.6); cf. Lukacs, 1970, Theorem 3.2.2.)18
Together with Lemma 3.1(i) this provides an alternative proof of part (iii) of Lemma 3.1.
Note that the conditions in Lemma 3.1(i) and (ii) allow the density q of εj to be unbounded, whereas the conditions for part (iii) imply boundedness of q.
Remark 3.1.
(a) The assumption in part (ii) is certainly satisfied if the coefficients φj are all positive (negative).
(b) The additional assumption in part (ii) cannot be removed. Consider the example where wt = εt − εt−1 + εt−2 and α1/2εt + α is gamma-distributed with shape parameter α satisfying 1/3 < α < ½ and scale parameter 1 and where x0 = 0 (for simplicity). Then x2 = ε2 + ε−1 whereas xn for n ≠ 2 is always the sum of at least three εj's. Consequently, the density of x2 (being a shifted and scaled version of a gamma(2α,1)-distribution) has a pole, whereas the density of xn, n ≠ 2 (being a shifted and scaled version of a gamma(β,1)-distribution with β ≥ 3α > 1) is bounded. Note that the characteristic function ψ(s) of εj satisfies |ψ(s)| = (1 + α−1s2)−α/2 and thus ψ satisfies (3.4) for ν > 1/α > 2 but not for ν ≤ 1/α.
3.2. Sufficient Conditions for Assumption 2.1
Sufficient conditions for Assumption 2.1 abound in the literature. For the sake of comparability with Park and Phillips (1999) and de Jong (2002) we shall use the condition
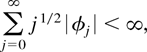
which is also used in Park and Phillips (1999) (cf. their Assumption 2.1). A stronger summability condition is used in Assumption 2.2 of Park and Phillips (1999) and also in de Jong (2002). It is well known that—under the maintained assumptions of Section 3—condition (3.7) implies our Assumption 2.1 with
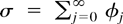
(cf., e.g., Phillips and Solo, 1992, Theorem 3.4 and Remarks 2.2(ii) and 3.5(i)).
3.3. Corollaries and Comparison with Park and Phillips (1999) and de Jong (2002)
The following corollary collects some of the results that can be obtained by combining Theorem 2.1 with the sufficient conditions discussed in Sections 3.1 and 3.2.
COROLLARY 3.2. Suppose the process xt satisfies the maintained assumptions of Section 3 and (3.4) and (3.7) hold. Let
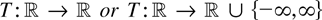
be locally integrable. Then
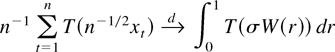
holds with
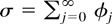
, provided the densities ht are (individually) bounded for every t ≥ 1.
19In fact, boundedness of ht for 1 ≤ t < n0 suffices, where n0 is as in Lemma 3.1(i).
(i) The density of q of εj is bounded; i.e., (3.6) holds.
(ii) The characteristic function ψ of εj is integrable; i.e., (3.4) holds with ν = 1.
(iii) φj > 0 for all j ≥ 0 or φj < 0 for all j ≥ 0.
The preceding corollary gives conditions that imply the desired convergence result for all locally integrable functions. The next corollary operates under weaker conditions on the process xt at the expense of imposing a mild growth condition on the function T.
COROLLARY 3.3. Suppose the process xt satisfies the maintained assumptions of Section 3 and (3.4) and (3.7) hold. Let
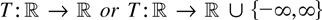
be locally integrable. Then
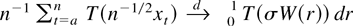
with
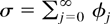
holds for some a ≥ 1.
20Namely, for a ≥ n0; cf. Lemma 3.1(i).
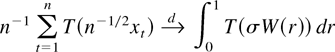
holds, provided T(x) = o(|x|−2) for x → 0, x ≠ 0, except possibly on a set of Lebesgue measure zero. This latter condition is satisfied if any of the conditions (ii)–(v) of Proposition 2.3 hold.21
For a minor generalization of this implication see Remark 2.4 and note 14.
A simple special case of Corollary 3.3 is the following result.
COROLLARY 3.4. Suppose the process xt satisfies the maintained assumptions of Section 3 and (3.4) and (3.7) hold. Let
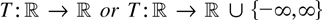
be essentially locally bounded (and Borel-measurable). Then
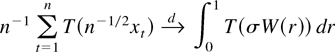
holds with

.
Corollary 3.2 is based on Theorem 2.1 and hence on Assumption 2.2, whereas Corollary 3.3 derives from Theorem 2.2 and Assumption 2.2*. As already noted, Assumption 2.2 differs from Assumption 2.2* only in that it additionally requires the first few densities ht to be (individually) bounded. As a consequence, the requirements on the process xt in Corollary 3.2 are only marginally stronger than in Corollary 3.3; e.g., adding condition (3.6), i.e., that the density q of εj is bounded, suffices. The advantage of Corollary 3.2 thus is that it does not impose any regularity condition on the function T but delivers the desired convergence result for any locally integrable function T (at a small cost in terms of additional conditions on xt).
It is easy to see that Corollary 3.3 contains the convergence result in de Jong (2002) as a special case: First, de Jong uses stronger assumptions on the process xt (namely, the stronger summability condition
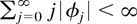
existence of moments of εj of order higher than 2, and the stronger condition |ψ(s)| = o(s−η) for some η > 0 on the characteristic function ψ). Second, the class of functions considered in Corollary 3.3 is much wider than the class considered in de Jong (2002) as the discussion subsequent to Corollary 2.5 has shown.
Comparing Corollary 3.3 with Theorem 3.2 in Park and Phillips (1999), we observe that Corollary 3.3 (and a fortiori Corollary 3.2) allows for a much wider class of functions than Theorem 3.2 in Park and Phillips (1999). In particular, Corollary 3.3 not only covers any (essentially) locally bounded function (cf. Corollary 3.4) but also allows for locally unbounded functions and extended real-valued functions. (Recall that any function that is “regular” in the sense of Park and Phillips, 1999, is locally bounded.) With respect to the conditions imposed on the process xt, note that Corollary 3.3 makes use of the same assumptions as used in Theorem 3.2 in Park and Phillips (1999) plus the additional condition (3.4) and the assumption that the innovations εj possess an absolutely continuous distribution. (Comparing Corollary 3.2 with Theorem 3.2 in Park and Phillips (1999) we see that a further mild condition such as, e.g., boundedness of the density of εj has been added.) This seems to be a modest price to pay for the ability to cover much larger classes of functions. Finally, we also point out that the conditions on xt in Corollary 3.3 are strictly weaker than the assumptions underlying Theorem 3.4 in Park and Phillips (1999) (cf. Park and Phillips, 1999, Assumption 2.2), which provides a weak convergence result for “clipped” versions of certain locally unbounded functions T. This shows that the “clipping” device of that theorem can be avoided altogether. (Recall from Section 1 that the proof of this theorem seems to be in error; cf. also note 2.)
We illustrate the corollaries with some examples.
Example 3.1
Suppose the process xt satisfies the assumptions of Corollary 3.3. Let T1(x) = log|x| and T2(x) = |x|α with −1 < α < 0, where T1(0) and T2(0) are set to an arbitrary element of
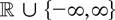
. It is easy to see that both functions are locally integrable and satisfy T1(x) = o(|x|−2) and T2(x) = o(|x|−2) for x → 0, x ≠ 0. Corollary 3.3 then implies
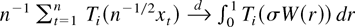
for i = 1,2 with

.
The functions in the preceding example do not satisfy the “regularity” conditions for Theorem 3.2 in Park and Phillips (1999) but do satisfy the “regularity” conditions of de Jong (2002). The following example is covered neither by the results in Park and Phillips (1999) (because the functions are not locally bounded) nor by the results in de Jong (2002) (because the functions are not piecewise monotone).
Example 3.2
Suppose the process xt satisfies the assumptions of Corollary 3.3. Let T3(x) = (log|x|)sin(x−1) and T4(x) = |x|αsin(x−1) with −1 < α < 0, where T3(0) and T4(0) are set to an arbitrary element of
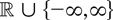
. Again both functions are locally integrable and satisfy T3(x) = o(|x|−2) and T4(x) = o(|x|−2) for x → 0, x ≠ 0. Corollary 3.3 then implies
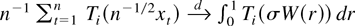
for i = 3,4 with
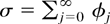
. In fact, Corollary 3.3 applies as well to the functions T5(x) = (log|x|)S(x) and T6(x) = |x|αS(x) with −1 < α < 0, where T5(0) and T6(0) are set to an arbitrary element of
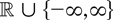
and where S is an arbitrary (essentially) local bounded Borel-measurable function.
4. EXTENSIONS
The results in Section 3 allow for dependence in the increments of the process xt as they are modeled as a linear process. It is quite natural to ask to what extent the results in Section 3 can be generalized to other dependence structures such as mixing, near epoch dependence, and so on. Observe that the results in Section 2 are of a generic nature in that they rely only on Assumptions 2.1 and 2.2 (or 2.2*), which do not specify a particular dependence structure. Because functional central limit theorems as expressed in Assumption 2.1 are widely available for various dependence structures, including those mentioned previously, the question reduces to whether or not Assumption 2.2 (or 2.2*) holds for such dependence structures. In particular, the validity of a local central limit theorem would imply Assumption 2.2*. Not much seems to be available in the literature in that regard.
A key feature of the results in this paper is that the random variables t−1/2xt have to have uniformly bounded densities (at least from some index onward). In view of local central limit theorems this appears to be a quite natural condition. Whether or not this condition can be relaxed while retaining the validity of the convergence result for all locally integrable functions, I do not know. Of course, relaxation is certainly possible if the convergence result is to be established only for a smaller class of functions T (e.g., Assumption 2.2 or 2.2* can be completely dropped for continuous T).
Suppose the convergence result (2.3) holds for a function H and suppose the function T satisfies T(λx) = g(λ)H(x) for all λ > 0 and all

with a suitable function g (e.g., T is homogenous of degree α and H = T). Then (2.3) applied to H can be rewritten as
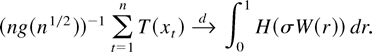
Now, if T does not satisfy a decomposition as before but does so approximately in a suitable sense, relation (4.1) can still be established. This then provides convergence results for nonlinear functions of unnormalized integrated processes. Section 5 of Park and Phillips (1999) carries through this program under the assumption that the function H appearing in the approximation is “regular” in their sense. De Jong and Wang (2002) obtain analogous results when H satisfies the “regularity” conditions of de Jong (2002). Based on the results of the present paper, both of these results can be extended to the situation where the function H in the approximation is locally integrable but does not satisfy the regularity conditions in Park and Phillips (1999) or de Jong (2002).
APPENDIX A: PROOFS FOR SECTION 2
LEMMA A.1. Suppose

is continuous and Assumption 2.1 holds with the requirement σ ≠ 0 omitted. Then (1.1) holds.
Proof. Define
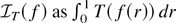
for every f ∈ D[0,1]. Because each f ∈ D[0,1] is bounded and measurable (Billingsley, 1968, p. 110) and because T is continuous,

is well defined and finite. Observe that (1.1) can be rewritten as
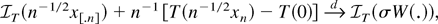
where the second term on the l.h.s. is op(1) because T is continuous and n−1/2xn converges in distribution. It hence suffices to establish that

converges to

in distribution. Suppose now that fk ∈ D[0,1] converges to f ∈ C[0,1] (the subset of all continuous functions on [0,1]) w.r.t. the Skorohod topology. Then this convergence is in fact uniform (Billingsley, 1968, p. 112). In particular, it follows that fk and f are uniformly bounded (w.r.t. r ∈ [0,1] and k ≥ 1) by a finite positive constant, say, M. Because T restricted to [−M, M] is uniformly continuous, it follows that T(fk(r)) converges to T(f (r)) uniformly on [0,1]. Thus,

converges to

. It follows that the set of continuity points of

contains C[0,1] . Because almost every sample path of Brownian motion is an element of C[0,1] , it follows that the set of continuity points of

is a set of measure one under the measure induced by σW(.). Applying the continuous mapping theorem in its extended form (e.g., Billingsley, 1968, Theorem 5.1) then establishes (1.1). █
LEMMA A.2. Let

be a locally integrable function. For every ε > 0 there exists a continuous function

such that
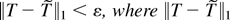
denotes
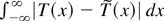
.
Proof. For any

define Tm(x) = T(x)1[m, m+1)(x). Because T is locally integrable, the function Tm is certainly Lebesgue-integrable over [m, m+1] . Hence, there exists a continuous function
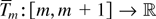
such that

(cf. Bauer, 1978, (43.6) and (44.2)). Extend Tm to a function on all of

by setting Tm(x) = 0 for x ∉ [m, m + 1] . Obviously then ∥Tm − Tm∥1 < (ε/3)2−|m|−1 holds. Note that Tm is continuous on

except possibly at x = m and x = m + 1. For 0 < η < ½ let gm, η denote the “trapezoidal” function given by gm, η(x) = 1 for m + η ≤ x ≤ m + 1 − η, gm, η(x) = 0 for x ≤ m and for x ≥ m + 1 and that linearly interpolates between x = m and x = m + η and also between x = m + 1 − η and x = m + 1. Then the function Tm gm, η is continuous on all of

and vanishes outside of (m, m + 1). By choosing η(m) small enough (depending on T and ε) we obtain ∥Tm − Tm gm, η(m)∥1 < (ε/3)2−|m|−1. Define
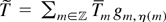
and note that

is continuous on

. Since clearly

holds, we arrive at
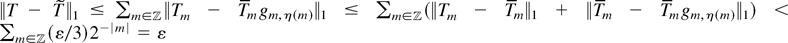
. █
Proof of Theorem 2.1. The idea of the proof is to use Lemma A.2 to reduce the case of locally integrable T to the case of continuous T and then to appeal to Lemma A.1, which in turn rests on the continuous mapping theorem.
Step 1. Let ε > 0 and let

be the continuous function guaranteed by Lemma A.2. Then for all n ≥ 1 we have

Step 2. Let ε > 0 and let

be as in step 1. Observing that

is locally integrable we may apply Corollary 7.4 in Chung and Williams (1990) to obtain

For the last equality in (A.2) we have used Fubini's theorem. This is justified because the functions involved are nonnegative and because L(1, x) is a measurable stochastic process. (That is, the map (ω, x) → L(1, x)(ω) is measurable w.r.t. the product σ-field

where

is the σ-field on the probability space supporting

is the Borel-σ-field on

. This is true because L has continuous sample paths; cf. Chung and Williams, 1990, p. 146; Karatzas and Shreve, 1991, Remark 1.14.) Now, for every

, the local time L(1, x) has a distribution that has point mass 2Φ(|x|) − 1 at the origin and otherwise has a density given by k(y) = (2/π)1/2 exp[−0.5(y + |x|)2] for y > 0 and k(y) = 0 else (cf. Borodin and Salminen, 1996, p. 127, eq. (1.3.4)). Consequently,
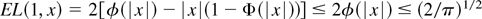
for all

, and hence the r.h.s. of (A.2) is not less than
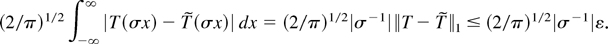
Step 3. It follows from steps 1 and 2 that for every η > 0 we can find a continuous function

such that
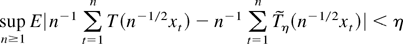
and
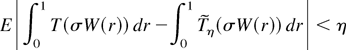
hold. By Lemma A.1 we have

Relations (A.4)–(A.6) establish the result (2.3) by a standard argument (cf. Anderson, 1971, Theorem 7.7.1). █
Proof of Theorem 2.2. The proof of (2.5) is identical to the proof of Theorem 2.1 apart from mainly notational differences. (For step 3 observe that because of continuity of

the first a − 1 terms in (A.6) are op(1) and hence can be omitted.) The second claim then follows from (2.5) and (2.6). █
Proof of Proposition 2.3. That (ii) implies (i) is seen as follows. Because of the monotonicity property we have for 0 < x < ε the inequality
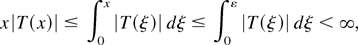
the final integral being finite because of integrability in a neighborhood of zero. Hence, x|T(x)| → 0 for x → 0, x > 0. A similar argument for −ε < x < 0 then shows that T(x) = o(|x|−1) and hence is o(|x|−2) for x → 0 and x ≠ 0. The implication (v) ⇒ (i) is trivial. The implications (iii) ⇒ (i) and (iv) ⇒ (i) follow by combining the arguments for the proofs of (ii) ⇒ (i) and (v) ⇒ (i). It remains to prove (i) ⇒ (2.6), and for this it suffices to show that n−1T(n−1/2xt) → 0 as n → ∞ for any given t and any value of xt. If xt = 0, this follows trivially, because T(0) is a real number. Otherwise, we obtain n−1T(n−1/2xt) = xt−2o(1) = o(1) as n → ∞. █
APPENDIX B: PROOFS FOR SECTION 3
LEMMA B.1. Let ψ be the characteristic function of a distribution with mean zero and variance 1. Then there exists Δ, 0 < Δ < 1, such that |ψ(s)| ≤ exp(−s2/8) holds for −Δ ≤ s ≤ Δ.
Proof. Theorem 2.3.3 in Lukacs (1970) implies that ψ(s) = 1 − s2/2 + ζ(s) where ζ(s) = o(s2) as s → 0 and ζ(0) = 0. Hence, there exists Δ′, 0 < Δ′ < 1, such that |ζ(s)| ≤ s2/4 for −Δ′ ≤ s ≤ Δ′. It follows that |ψ(s)| ≤ |1 − s2/2| + |ζ(s)| ≤ 1 − s2/2 + s2/4 = 1 − s2/4 for −Δ′ ≤ s ≤ Δ′. Since ψ(0) = 1 and ψ is continuous, it follows that there exists Δ″, 0 < Δ″ ≤ Δ′, such that |ψ(s)| > 0 holds for −Δ″ ≤ s ≤ Δ″. Hence, log|ψ(s)| is well defined on −Δ″ ≤ s ≤ Δ″ and satisfies log|ψ(s)| ≤ log(1 − s2/4) on that interval. A Taylor series expansion of log(1 + x) around x = 0 then shows that for −Δ″ ≤ s ≤ Δ″
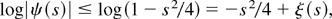
where ξ(s) = o(s2) for s → 0 and ξ(0) = 0. Choosing Δ, 0 < Δ ≤ Δ″ < 1, small enough we obtain |ξ(s)| ≤ s2/8 for −Δ ≤ s ≤ Δ. This implies log|ψ(s)| ≤ −s2/8 for −Δ ≤ s ≤ Δ. █
We note that a more careful choice of constant in the preceding proof establishes that for any 0 < δ < ½ there exists a Δ = Δ(δ) as in the lemma such that |ψ(s)| ≤ exp(−δs2) holds for −Δ ≤ s ≤ Δ.
Proof of Lemma 3.1. It follows from Theorem 3.2.2. of Lukacs (1970) that ∥hn∥∞ ≤ (2π)−1∥Ψn∥1 provided the latter is finite, where Ψn denotes the characteristic function of n−1/2xn and ∥.∥1 denotes the L1-norm w.r.t. Lebesgue measure on

. It hence suffices to bound ∥Ψn∥1.
(i) Note that x0 is independent of the term in brackets in the representation (3.3) and that both sums in the brackets are independent of each other. Hence,
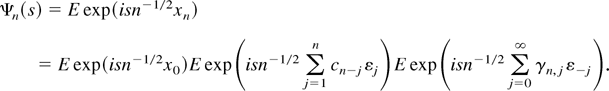
Consequently,
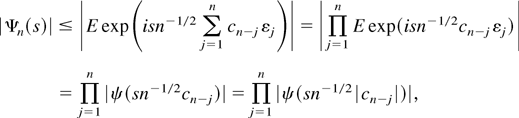
the final equality following from |ψ(−s)| = |ψ(s)|.
Now,
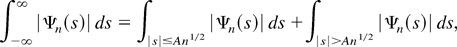
for every A > 0. Performing the substitution s → sn−1/2 and using (B.1), the first integral on the r.h.s. of (B.2) can be bounded by
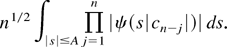
Choose A = (2|c|)−1Δ > 0, where Δ is as in Lemma B.1 and where

, which is nonzero by assumption. Note that the coefficients ck converge to c. Hence there is a

such that |c|/2 ≤ |ck| ≤ 2|c| whenever k ≥ K. Because every characteristic function is bounded by one in absolute value, and because −A ≤ s ≤ A implies −Δ ≤ s|cn−j| ≤ Δ for n − j ≥ K, the expression in (B.3) for n > K is in view of Lemma B.1 bounded by

Because (B.3) for 1 ≤ n ≤ K is clearly bounded by 2An1/2 ≤ |c|−1ΔK1/2, the expression in (B.3) is bounded by C1 = max((32π)1/2(K + 1)1/2, ΔK1/2)/|c| < ∞ for all n ≥ 1.
To deal with the second term on the r.h.s. of (B.2), perform the same substitution as before and use (B.1) to obtain
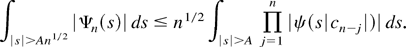
With K as defined after (B.3), we can then for n > K bound (B.4) by
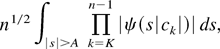
because |ψ(.)| ≤ 1. Applying Hölder's inequality successively n − K times, (B.5) can for n ≥ K + ν be bounded by

Because A|c|/2 = Δ/4 > 0 and ψ is the characteristic function of an absolutely continuous distribution, the supremum in (B.6) is less than one. In view of (3.4), the r.h.s. of (B.6) is therefore bounded by a finite constant for n ≥ K + ν. This completes the proof of part (i).
(ii) In view of part (i) it suffices to show that ∥Ψn∥1 < ∞ holds for 1 ≤ n < K + ν. Note that
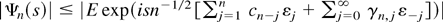
. The result then follows from Lemma B.2, which is given subsequently.
(iii) This follows from part (ii), observing that the maintained assumption

implies that at least one coefficient in the representation (3.3) is nonzero for every n ≥ 1. █
LEMMA B.2. Suppose
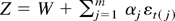
with αj ≠ 0 for 1 ≤ j ≤ m and W is independent of

. Then
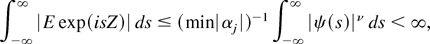
provided (3.4) with ν ≤ m holds.
Proof. Observe that
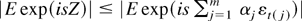
. Hence

where the second inequality follows from Hölder's inequality. █
Proof of Corollary 3.2. This follows from Theorem 2.1, Remark 2.1, and the discussion in Sections 3.1 and 3.2, in particular, Lemma 3.1 and Remark 3.1. █
Proof of Corollary 3.3. This follows from Theorem 2.2, Proposition 2.3, Remarks 2.4 and 2.5 (note that each xt has an absolutely continuous distribution), and the discussion in Sections 3.1 and 3.2, in particular, Lemma 3.1. █
References
REFERENCES
Anderson, T.W.
(1971)
The Statistical Analysis of Time Series.
Wiley.
Bauer, H.
(1978)
Wahrscheinlichkeitstheorie und Grundzuege der Masstheorie.
3rd ed.
DeGruyter.
Billingsley, P.
(1968)
Convergence of Probability Measures.
Wiley.
Borodin, A.N. &
I.A. Ibragimov
(1995)
Limit Theorems for Functionals of Random Walks.
Proceedings of the Steklov Institute of Mathematics
195(2).Google Scholar
Borodin, A.N. &
P. Salminen
(1996)
Handbook of Brownian Motion: Facts and Formulae.
Birkhäuser.
Chung, K.L. &
R.J. Williams
(1990)
Introduction to Stochastic Integration.
2nd ed.
Birkhäuser.
de Jong, R.
(2002)
Addendum to “Asymptotics for Nonlinear Transformations of
Integrated Time Series.”
Working paper,
Department of Economics, Michigan State University.
de Jong, R. &
C.H. Wang
(2002)
Further Results on the Asymptotics for Nonlinear Transformations of
Integrated Time Series.
Working paper,
Department of Economics, Michigan State University.
Ibragimov, I.A. &
Yu.V. Linnik
(1971)
Independent and Stationary Sequences of Random Variables.
Wolters-Noordhoff.
Jeganathan, P.
(2002)
Convergence of Functionals of Weighted Sums of Independent Random
Variables to Local Times of Fractional Brownian and Stable Motions.
Working paper,
ISI,
Bangalore.
Karatzas, I. &
S.E. Shreve
(1991)
Brownian Motion and Stochastic Calculus.
2nd ed.
Springer-Verlag.
Lukacs, E.
(1970)
Characteristic Functions.
2nd ed.
Griffin.
Park, J.Y. &
P.C.B. Phillips
(1999)
Asymptotics for nonlinear transformations of integrated time
series,
Econometric Theory
15,
269–298.Google Scholar
Park, J.Y. &
P.C.B. Phillips
(2001)
Nonlinear regressions with integrated time series,
Econometrica
69,
117–161.Google Scholar
Phillips, P.C.B. &
V. Solo
(1992)
Asymptotics for linear processes,
Annals of Statistics
20,
971–1001.Google Scholar
 You have
Access
- 36
- Cited by