


1. INTRODUCTION
He and Terasvirta (1999) defined the following general class of GARCH(1,1) model:

and

where P(htδ > 0) = 1, zt is a sequence of independent and identically distributed (i.i.d.) random variables with mean zero and variance 1, and it is assumed that zt is independent of εt−1,εt−2,…, and g(x) is a positive function and c(x) is a nonnegative function. As indicated by these authors, this family of generalized autoregressive conditionally heteroskedastic (GARCH) processes includes many models, among them the GARCH(1,1) model of Engle (1982) and Bollerslev (1986), the absolute value GARCH(1,1) model of Taylor (1986, pp. 78–79) and Schwert (1989), the asymmetric GJR-GARCH(1,1) model of Glosten, Jagannathan, and Runkle (1993), the nonlinear GARCH(1,1) model of Engle (1990), the volatility switching GARCH(1,1) model of Fornari and Mele (1997), the threshold GARCH(1,1) model of Zakoïan (1994), the fourth-order nonlinear generalized moving-average conditional heteroskedasticity model of Yang and Bewley (1995), and the generalized quadratic ARCH(1,1) model of Sentana (1995) (see the list of models in He and Terasvirta, 1999).
The necessary and sufficient condition for the mδth unconditional moment of model (1.1) and (1.2) to exist is given by He and Terasvirta (1999), where m is a positive integer and δ = 1 or 2. Further, Ling and McAleer (2002) provided the sufficient conditions for αδ-order stationarity of model (1.1) and (1.2). In the present paper, a sufficient and necessary condition for the strict stationarity of this family of GARCH processes defined by (1.1) and (1.2) will be given. Moreover, some simple conditions for the existence of moments of the family of GARCH processes are also derived. In addition, the tail properties of the stationary time series model are very important in applications, in particular in financial risk analysis; see Embrechts, Kluppelberg, and Mikosch (1997). Heavy tail is a well-known empirical feature in financial time series. A number of studies show that Gaussian or light-tailed innovations cannot describe the tail behaviors of these time series; see Adler, Feldaman, and Taqqu (1997). More and more people are interested in time series models with heavy-tailed innovations. The tail behaviors of linear models and bilinear models were studied by Resnick (1987) and Davis and Resnick (1996), respectively. The tails of ARCH and GARCH were studied by De Haan, Resnick, Rootzen, and De Vries (1989), Mikosch and Starica (2000), Borkovec and Kluppelberg (2001), and Basrak, Davis, and Mikosch (2002). Thus, we will consider the tail of the marginal distribution of the family of GARCH processes defined as in (1.1) and (1.2) in this paper. The result of this paper provides an extension of the tail behaviors of GARCH(1,1) processes investigated by Mikosch and Starica (2000).
The organization of this paper is as follows. In Section 2, the sufficient and necessary condition for the strict stationarity of the family of GARCH processes defined as in (1.1) and (1.2) is given. Moreover, some simple conditions for the existence of the moments of the family of GARCH processes are also derived. We describe the tail of the marginal distribution of the family of GARCH processes defined by (1.1) and (1.2) in Section 3. It gives a precise meaning to the statement “light-tailed input causes heavy-tailed output.”
2. STATIONARITY AND ERGODICITY OF A FAMILY OF GARCH PROCESSES
In this paper, we always write z = z0.
THEOREM 2.1. Assume that E ln+(g(z)) < ∞ and E ln+(c(z)) < ∞. Then the family of GARCH processes defined by (1.1) and (1.2) has a unique strictly stationary and ergodic solution if and only if E ln(c(z)) < 0.
Proof. We assume that E ln(c(z)) < 0. Because

is an i.i.d. random variable sequence with zero mean and unit variance, applying the strong law of large numbers, we can obtain that

as n → ∞, where →a.s. denotes the convergence with probability 1. Hence,

as n → ∞. Moreover, note that {g(zt−1−n),n ≥ 1} is i.i.d. and E ln+(g(z)) < ∞; hence

It follows that

for some b ∈ (0,|E ln(c(z))|) and sufficiently large n, with probability 1. Therefore,

Thus,

is well defined. Moreover,

i.e., htδ defined as in (2.5) is a solution of (1.2). Let

Then εt = zt ht is a strictly stationary and ergodic solution of the family of GARCH processes defined by (1.1) and (1.2).
For uniqueness, assume that et is an arbitrary stationary solution to the family of GARCH processes defined by (1.1) and (1.2) and that ht(e) satisfying zt ht(e) = et is a solution of equation (1.2). Iterating equation (1.2) yields

Note that the distribution of (h−mδ(e) − h−mδ) is independent of m; combining this with (2.2) and (2.7) implies

as m → ∞. Because of the stationarity of htδ and htδ(e), we conclude that htδ = htδ(e), a.s. This shows uniqueness. The “if” part of the theorem is completed.
Conversely, suppose that there exists a strictly stationary solution

of the family of GARCH processes defined as in (1.1) and (1.2). Iterating equation (1.2), we have, for any m > 0, that

Therefore, for any m > 0,

This shows that the series

converges a.s. Thus,

as n → ∞. Because {g(z−n−1),n ≥ 1} is i.i.d., then (2.8) implies

as n → ∞. Moreover, noting that E ln+(c(z)) < ∞ and applying Lemma 2.1 in Bougerol and Picard (1992), we know that E ln(c(z)) < 0. This completes the proof of the theorem.
COROLLARY 2.1 (Ling and McAleer, 2002, Thm. 2.1). If E|z|αδ < ∞, E [g(z)]α < ∞, and E [c(z)]α < 1 for some α ∈ (0,1], then there exists a unique αδ-order stationary solution to (1.1) and (1.2).
Proof. Note that E [c(z)]α < 1 yields E ln(c(z)) < 0. Again according to E [g(z)]α < ∞ and E [c(z)]α < 1, we have E ln+(g(z)) < ∞ and E ln+(c(z)) < ∞. Thus, by Theorem 2.1, there exists a unique stationary solution to (1.1) and (1.2); i.e., (2.6) holds. Moreover, using (2.6),

where

. This concludes the proof.
In what follows we are concerned with the conditions for the existence of the moments of the family of GARCH processes defined by (1.1) and (1.2).
LEMMA 2.1. Assume that E ln(c(z)) < 0, P(c(z) > 1) > 0, and there exists u0 ≤ ∞ such that E [c(z)]u < ∞ for all u < u0 and E [c(z)]u0 = ∞. Define

Then the function f is strictly convex in u, and there is a unique solution κ > 0 to the equation f (u) = 1.
Proof. Notice that the function f (u) = E [c(z)]u is continuous and convex in u ≥ 0 and f (0) = 1. Because E ln(c(z)) < 0 it assumes values smaller than 1 in some neighborhood of the origin. Moreover, for sufficiently large u, because P(c(z) > 1) > 0 and f (u0) = ∞, f (u) ≥ 1. Hence f (u) = 1 has a unique positive solution.
THEOREM 2.2. Let

be the GARCH process defined as in (1.1) and (1.2). Assume that the conditions in Lemma 2.1 are satisfied. Moreover, let κ be the unique positive solution of the equation f (u) = 1, where f is defined as in (2.9). Then, for 0 ≤ u < κ, if E|z|δu < ∞ and E [g(z)]u < ∞, we have that

Denote by p the largest integer strictly less than κ; then, for m = 1,2,…, p, if E|z|δm < ∞ and E [g(z)]m < ∞, we can obtain that

Proof. Write ∥ζ∥q = (E|ζ|q)1/q, where ζ is any random variable and q ≥ 1. By Lemma 2.1, the function f (u) is strictly convex and satisfies f (κ) = f (0) = 1. Hence f (u) < 1 for 0 < u < κ. Moreover, note that the conditions in Theorem 2.1 are satisfied; thus (2.6) holds. For 0 < u < κ, if u ≥ 1, by (2.6),

if u < 1,

implies (2.10).
Finally, note that htδ =d g(zt) + c(zt)htδ, where =d denotes equality in distribution. By the binomial expression, it is easy to obtain

Thus, (2.12) and E|εt|δl = E|zt|δlEhtδl, l = 1,…, m, yield (2.11).
3. TAIL BEHAVIORS OF A FAMILY OF GARCH PROCESSES
First recall that a random variable X (resp., its law) is said to be arithmetic (lattice) if there exist a,d ≥ 0 such that

.
In the following result we describe the tail of the marginal distribution of a family of processes. It gives a precise meaning to the statement “light-tailed input causes heavy-tailed output.”
THEOREM 3.1. Let

be the GARCH process defined by (1.1) and (1.2). Assume that the law of ln(c(z)) is nonarithmetic and the conditions in Lemma 2.1 are satisfied and let κ be the unique positive solution of the equation f (u) = 1, where f is defined by (2.9). Moreover, suppose that E [g(z)]κ+σ < ∞ and E|z|δκ+σ < ∞ for some σ > 0; then

where

Before we can prove this result we have to ensure that the constant c0 in (3.2) is well defined. Indeed, its numerator is the expected difference of two quantities each of which has infinite expectation.
LEMMA 3.1. Under the assumptions of Theorem 3.1,

Proof. Because f (x) = (g(z) + x)κ − xκ is a decreasing function for κ ≤ 1 and x ≥ 0, then
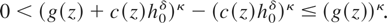
Thus (3.3) holds for κ ≤ 1. For κ > 1, the function f (x) = xκ is strictly convex on

, and hence

Taking p = κ + σ > 1 and q = (κ − 1 + σ)−1(κ + σ) and applying Hölder's inequality, we know that

Note that (κ − 1 + σ)−1(κ − 1)(κ + σ) < κ; by the preceding inequality and Theorem 2.2, (3.3) is true.
We also need the following two lemmas.
LEMMA 3.2. Let X ≥ Y a.s. be nonnegative random variables. Then

for the right-hand side finite or infinite.
Proof.

LEMMA 3.3. Assume that X and Y are independent nonnegative random variables such that P(X > x) = L(x)x−κ for some slowly varying function L and EYκ+σ < ∞ for some σ > 0. Then

Lemma 3.3 is a consequence of Proposition 3 in Breiman (1965) and can be also found in Mikosch and Starica (2000, p. 1433).
Proof of Theorem 3.1. Define the random walk

generated by the i.i.d. sequence

:

Now consider

Define the measures νn by

and write

Because htδ ≥ c(zt−1)ht−1δ, hence m is nonnegative. Moreover, we have

where * denotes the convolution. Also, define the measure ξ by

Furthermore, by the definition of κ, we have

Therefore, ξ defines a probability measure on

(not lattice) with mean

Let ν be the renewal measure corresponding to ξ, i.e.,

Note that

for

, where νn is defined in (3.4).
By Lemmas 3.1 and 3.2, it is easy to prove that m is integrable and bounded and limx→∞ m(x) = 0.
Because of μ(ξ) > 0, the renewal measure ν has the property

But,

Moreover, note that E ln(c(z)) < 0. Therefore Sn has a negative drift and

Combined with (3.5) and (3.6), this implies that

Note that m is integrable and bounded, limx→∞ m(x) = 0, and ξ is absolutely continuous; these conditions allow us to apply a version of the key renewal theorem (Alsmeyer, 1991, Satz 3.1.7), which in turn, together with Lemma 3.2, leads to the relation

with c0 as in (3.2). Therefore, we get that

i.e.,

Moreover, note that εt = zt ht. Applying Lemma 3.3, we can obtain that

This completes the proof.
COROLLARY 3.1. Under the assumptions of Theorem 3.1,

Proof. Notice that P(|εt| > x) ∼ c0 E|z|δκx−δκ as x → ∞; the conclusion is obvious.


