


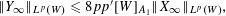

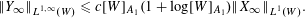
1 Introduction
Suppose that
 $w$
is a weight, i.e. a non-negative, locally integrable function on
 $\mathbb{R}^{d}$
, and let
 $M$
stand for the Hardy–Littlewood maximal operator. In 1971, Fefferman and Stein [Reference Fefferman and Stein4] proved the existence of a finite constant
 $c_{d}$
, depending only on the dimension, such that
 $$\begin{eqnarray}w(\{x\in \mathbb{R}^{d}:Mf(x)\geqslant 1\})\leqslant c_{d}\Vert f\Vert _{L^{1}(Mw)}.\end{eqnarray}$$
Here and below, we use the standard notation
 $w(E)=\int _{E}w(x)\,dx$
and
 $\Vert f\Vert _{L^{p}(w)}=(\int _{\mathbb{R}^{d}}|f(x)|^{p}w(x)\,dx)^{1/p}$
,
 $1\leqslant p<\infty$
. This result led to the following natural conjecture, formulated by Muckenhoupt and Wheeden in the 1970s. Namely, for any Calderón–Zygmund singular integral operator
 $T$
, there is a constant
 $c_{T,d}$
, depending only on
 $T$
and
 $d$
, such that
 $$\begin{eqnarray}w(\{x\in \mathbb{R}^{d}:|Tf(x)|\geqslant 1\})\leqslant c_{T,d}\Vert f\Vert _{L^{1}(Mw)}.\end{eqnarray}$$
This problem admits a weaker version. Recall that
 $w$
satisfies Muckenhoupt’s condition
 $A_{1}$
if there is a constant
 $c>0$
such that
 $Mw\leqslant cw$
almost everywhere; the smallest
 $c$
with this property is denoted by
 $[w]_{A_{1}}$
and called the
 $A_{1}$
characteristics of
 $w$
. The weaker conjecture is the following: for any Calderón–Zygmund operator
 $T$
there is a constant
 $c_{T,d}^{\prime }$
such that for any
 $A_{1}$
weight
 $w$
,
 $$\begin{eqnarray}w(\{x\in \mathbb{R}^{d}:|Tf(x)|\geqslant 1\})\leqslant c_{T,d}^{\prime }[w]_{A_{1}}\Vert f\Vert _{L^{1}(w)}.\end{eqnarray}$$
This statement is indeed weaker than the preceding: the validity of (1.1) would imply (1.2) with
 $c_{T,d}^{\prime }=c_{T,d}$
.
Both conjectures (1.1) and (1.2) remained open for a long time, and finally, a few years ago, they were both proved to be false: see the counterexamples for the Hilbert transform provided by Reguera, Thiele, Nazarov, Reznikov, Vasyunin and Volberg in [Reference Nazarov, Reznikov, Vasyunin and Volberg9, Reference Reguera15, Reference Reguera and Thiele16]. In the mean-time, many partial or related results in this direction were obtained. In particular, Buckley [Reference Buckley1] showed that the strong conjecture is true for the weights
 $w_{\unicode[STIX]{x1D6FF}}(x)=|x|^{-d(1-\unicode[STIX]{x1D6FF})}$
,
 $0<\unicode[STIX]{x1D6FF}<1$
. Lerner, Ombrosi and Pérez established the following weaker versions of (1.2). In [Reference Lerner, Ombrosi and Pérez7] they proved the existence of an absolute
 $c$
such that
 $$\begin{eqnarray}\Vert Tf\Vert _{L^{1,\infty }(w)}\leqslant c\unicode[STIX]{x1D711}([w]_{A_{1}})\Vert f\Vert _{L^{1}(w)},\end{eqnarray}$$
where
 $\unicode[STIX]{x1D711}(t)=t(1+\log t)(1+\log ^{+}\log t)$
; then, in [Reference Lerner, Ombrosi and Pérez8], they improved the estimate to the form
 $$\begin{eqnarray}\Vert Tf\Vert _{L^{1,\infty }(w)}\leqslant c[w]_{A_{1}}(1+\log [w]_{A_{1}})\Vert f\Vert _{L^{1}(w)},\end{eqnarray}$$
where, as above,
 $c$
is a certain finite universal constant. To obtain these results, they first established the
 $L^{p}$
estimates
 $$\begin{eqnarray}\Vert Tf\Vert _{L^{p}(w)}\leqslant cpp^{\prime }[w]_{A_{1}}\Vert f\Vert _{L^{p}(w)},\quad 1<p<\infty ,\end{eqnarray}$$
in which the linear dependence on the
 $A_{1}$
characteristics is optimal. Then, using some extrapolation arguments, they managed to deduce the above weak-type bounds. The improvement in the appropriate LlogL term came from the fact that the
 $L^{p}$
-constant
 $c_{p}$
obtained in [Reference Lerner, Ombrosi and Pérez8] is better than that in [Reference Lerner, Ombrosi and Pérez7].
The purpose of this paper is to study analogs of (1.3) arising in the dyadic context of Haar multipliers. Actually, it will be more convenient for us to inspect the inequalities in an even wider, probabilistic setting. Let us introduce the necessary background and notation. We assume that
 $(\unicode[STIX]{x1D6FA},{\mathcal{F}},\mathbb{P})$
is a complete probability space, equipped with the Brownian filtration
 $({\mathcal{F}}_{t})_{t\geqslant 0}$
; in what follows, we will use the well-known property of this filtration that all adapted martingales have continuous trajectories. This rather restrictive assumption on the regularity of processes is typical in the context of weighted estimates (cf. Kazamaki [Reference Kazamaki6]). Let
 $X=(X_{t})_{t\geqslant 0}$
be an adapted uniformly integrable martingale taking values in
 $\mathbb{R}$
. Denote by
 $[X]=([X]_{t})_{t\geqslant 0}$
the square bracket (quadratic variation) associated to
 $X$
; see Dellacherie and Meyer [Reference Dellacherie and Meyer3] for the appropriate definition and basic properties of this object. Given a predictable process
 $H$
, we will write
 $Y=H\cdot X$
for the stochastic integral of
 $H$
with respect to
 $X$
:
 $$\begin{eqnarray}Y_{t}=H_{0}X_{0}+\int _{0+}^{t}H_{s}\,dX_{s},\quad t\geqslant 0.\end{eqnarray}$$
Next, let
 $W$
be a weight, i.e. a non-negative, integrable random variable; this object gives rise to a continuous-path and uniformly integrable martingale
 $(W_{t})_{t\geqslant 0}$
given by
 $W_{t}=\mathbb{E}(W|{\mathcal{F}}_{t})$
; sometimes we will identify
 $W$
with
 $W_{\infty }$
. Let
 $W^{\ast }=\sup _{s\geqslant 0}W_{s}$
,
 $W_{t}^{\ast }=\sup _{0\leqslant s\leqslant t}W_{s}$
be the maximal and truncated maximal functions of
 $W$
. More generally, for any
 $r>1$
, we define the
 $r$
-maximal function by
 $M_{r}W=[(W^{r})^{\ast }]^{1/r}$
. In analogy to the analytic context, a weight
 $W$
is said to satisfy Muckenhoupt’s
 $A_{1}$
condition, if there is an absolute constant
 $c$
such that
 $W_{t}^{\ast }\leqslant cW_{t}$
almost surely for all
 $t$
. The least
 $c$
with this property is denoted by
 $[W]_{A_{1}}$
and called the
 $A_{1}$
characteristics of
 $W$
. See Ikeda and Kazamaki [Reference Izumisawa and Kazamaki5] and Kazamaki [Reference Kazamaki6] for more information on the subject.
We are ready to formulate the main results of this paper. As in the analytic setting, we define the weighted
 $p$
th norm of
 $X$
by
 $\Vert X\Vert _{L^{p}(W)}=(\mathbb{E}|X_{\infty }|^{p}W_{\infty })^{1/p}$
for all
 $1\leqslant p<\infty$
. Furthermore, given such a
 $p$
, we let
 $p^{\prime }=p/(p-1)$
denote its harmonic conjugate, with the usual convention
 $1^{\prime }=+\infty$
.
Theorem 1.1. Suppose that
 $W$
is a weight,
 $X$
is a martingale and
 $Y=H\cdot X$
, where
 $H$
is a predictable process taking values in
 $[-1,1]$
.
-
(i) For any
 $1<r\leqslant 2$
we have (1.4)where
$$\begin{eqnarray}\Vert Y\Vert _{L^{p}(W)}\leqslant \frac{c_{p}(r)}{(r-1)^{1/p^{\prime }}}\Vert X\Vert _{L^{p}(M_{r}W)},\quad 1<p<\infty ,\end{eqnarray}$$
(1.5)
$$\begin{eqnarray}\displaystyle c_{p}(r) & = & \displaystyle \left\{\begin{array}{@{}ll@{}}\displaystyle 4^{1-2/p^{\prime }}(p^{\prime })^{1+1/p^{\prime }}r^{1/p^{\prime }}\quad & \text{if }1<p<2,\\ \displaystyle (2(p^{\prime }+r-1)/(p^{\prime }-1))^{1/p^{\prime }}\quad & \text{if }2\leqslant p<\infty \end{array}\right.\nonumber\\ \displaystyle & {\leqslant} & \displaystyle 8pp^{\prime }.\end{eqnarray}$$
-
(ii) If
$W$
belongs to the class
$A_{1}$
, then (1.6)
$$\begin{eqnarray}\Vert Y\Vert _{L^{p}(W)}\leqslant 16pp^{\prime }[W]_{A_{1}}\Vert X\Vert _{L^{p}(W)}.\end{eqnarray}$$


The above estimates will allow us to obtain the following weak-type bound for probabilistic
 $A_{1}$
weights. We define the weak first norm of
 $Y$
by the formula
 $\Vert Y\Vert _{L^{1,\infty }(W)}=\sup _{\unicode[STIX]{x1D706}>0}\unicode[STIX]{x1D706}\mathbb{E}(1_{\{|Y_{\infty }|>\unicode[STIX]{x1D706}\}}W_{\infty })$
.
Theorem 1.2. There is an absolute constant
 $c$
such that the following holds. If
 $W$
is an
 $A_{1}$
weight,
 $X$
is a martingale and
 $Y=H\cdot X$
, where
 $H$
is a predictable process with values in
 $[-1,1]$
, then
 $$\begin{eqnarray}\Vert Y\Vert _{L^{1,\infty }(W)}\leqslant c[W]_{A_{1}}\log (1+[W]_{A_{1}})\Vert X\Vert _{L^{1}(W)}.\end{eqnarray}$$
A few comments on the proof are in order. Lerner, Ombrosi and Pérez exploit extrapolation methods and the Rubio de Francia algorithm combined with boundedness properties of the maximal operator. Our passage from (1.4) and (1.6) to (1.7) also involves an extrapolation-type argument, but the approach leading to (1.4) is completely different. We will exploit the so-called Bellman function method: the inequality (1.4) (or rather its dual version) will be deduced from the existence of a certain special function, enjoying appropriate majorization and concavity. This type of approach has turned out to be extremely efficient in the study of various problems in probability and harmonic analysis (cf. [Reference Burkholder2, Reference Nazarov and Treil10, Reference Nazarov, Treil and Volberg11, Reference Osȩkowski13, Reference Petermichl and Wittwer14, Reference Slavin and Vasyunin17, Reference Vasyunin and Volberg18] to cite just a few works out of a huge literature on the subject). One of the novel aspects of this paper is that we will manage to apply the method directly to the estimate (1.4) (or rather its dual version); in many situations, Bellman-function proofs of weighted inequalities involve also some additional reduction or decomposition arguments. We believe that the special function we construct, or at least a part of it, will be useful in other related results arising in the area.
We will require a probabilistic version of the method, which is described in the next section. Section 3 contains the proof of (1.4) and then in §4 we show how the
 $L^{p}$
bound leads to (1.6) and the weak-type estimate (1.7). The final part of the paper comes back to the analytic context: we show how the martingale results obtained in the preceding sections imply the corresponding statements for Haar multipliers (or rather more general objects arising in the setting of probability spaces equipped with a tree-like structure).
2 On the method of proof
Consider the domain
 $$\begin{eqnarray}\mathfrak{D}=\{(x,y,u,v)\in \mathbb{R}^{2}\times (0,\infty )^{2}:u\leqslant v\}.\end{eqnarray}$$
Suppose
 $V:\mathfrak{D}\rightarrow \mathbb{R}$
is a given Borel function and assume that we want to establish the inequality
 $$\begin{eqnarray}\mathbb{E}V(X_{t},Y_{t},W_{t},W_{t}^{\ast })\leqslant 0,\quad t\geqslant 0,\end{eqnarray}$$
for all triples
 $(X,Y,W)$
, where
 $X$
,
 $Y$
are bounded martingales such that
 $Y=H\cdot X$
for some predictable process
 $H$
taking values in
 $[-1,1]$
, and
 $W$
is a bounded positive weight (recall that the underlying filtration is Brownian, and hence
 $X$
,
 $Y$
and
 $W$
have continuous paths). To study this problem, consider the family
 ${\mathcal{U}}(V)$
which consists of all continuous functions
 $U:\mathfrak{D}\rightarrow \mathbb{R}$
satisfying the following properties:
- 1
$^{\circ }$
-
for any
$x,y\in \mathbb{R}$
such that
$|y|\leqslant |x|$
and any
$u>0$
we have (2.2)
$$\begin{eqnarray}U(x,y,u,u)\leqslant 0;\end{eqnarray}$$
- 2
$^{\circ }$
-
for any
$(x,y,u,v)\in \mathfrak{D}$
we have (2.3)
$$\begin{eqnarray}U(x,y,u,v)\geqslant V(x,y,u,v);\end{eqnarray}$$
- 3
$^{\circ }$
-
the function
$U$
is non-increasing with respect to its fourth variable, that is, for any
$x,y\in \mathbb{R}$
and any
$u\leqslant v_{1}\leqslant v_{2}$
, we have (2.4)
$$\begin{eqnarray}U(x,y,u,v_{1})\geqslant U(x,y,u,v_{2});\end{eqnarray}$$
- 4
$^{\circ }$
-
for any
$(x,y,u,v)\in \mathfrak{D}$
and any
$h,k,\ell \in \mathbb{R}$
satisfying
$|k|\leqslant |h|$
, the function
$G=G_{x,y,u,v,h,k,\ell }$
, given by (2.5)
$$\begin{eqnarray}G(t)=U(x+th,y+tk,u+t\ell ,v),\end{eqnarray}$$
is concave on the interval
$\{t:0<u+t\ell \leqslant v\}$
.


Theorem 2.1. If the class
 ${\mathcal{U}}(V)$
is non-empty, then the inequality (2.1) holds true.
Proof. Essentially, the argument rests on Itô’s formula applied to the function
 $U$
and the process
 $(X,Y,W,W^{\ast })$
. However, the function
 $U$
need not have the necessary regularity, which forces us to use an additional mollification. Let
 $g:\mathbb{R}^{4}\rightarrow [0,\infty )$
be a
 $C^{\infty }$
function, supported on the unit ball of
 $\mathbb{R}^{4}$
and satisfying
 $\int _{\mathbb{R}^{4}}g\,dx=1$
. Given
 $\unicode[STIX]{x1D700}>0$
and a number
 $\unicode[STIX]{x1D6FF}\in (0,\unicode[STIX]{x1D700})$
, define a function
 $U^{\unicode[STIX]{x1D6FF}}:\{(x,y,u,v)\in \mathfrak{D}:\unicode[STIX]{x1D6FF}\leqslant u\leqslant v-2\unicode[STIX]{x1D6FF}\}\rightarrow \mathbb{R}$
by the convolution
 $$\begin{eqnarray}\displaystyle U^{\unicode[STIX]{x1D6FF}}(x,y,u,v) & = & \displaystyle \int _{[-1,1]^{4}}U(x+\unicode[STIX]{x1D6FF}s_{1},y+\unicode[STIX]{x1D6FF}s_{2},u+\unicode[STIX]{x1D6FF}s_{3},v+\unicode[STIX]{x1D6FF}s_{4})\nonumber\\ \displaystyle & & \displaystyle \times \,g(s_{1},s_{2},s_{3},s_{4})\,ds_{1}\,ds_{2}\,ds_{3}\,ds_{4}.\nonumber\end{eqnarray}$$
This function is of class
 $C^{\infty }$
and inherits the properties 3
 $^{\circ }$
and 4
 $^{\circ }$
(with some obvious modifications: the inequality (2.4) holds for
 $u+2\unicode[STIX]{x1D6FF}\leqslant v_{1}\leqslant v_{2}$
; the function
 $G$
appearing in 4
 $^{\circ }$
is concave on
 $\{t:\unicode[STIX]{x1D6FF}\leqslant u+t\ell \leqslant v-2\unicode[STIX]{x1D6FF}\}$
). Introduce the process
 $Z_{t}^{\unicode[STIX]{x1D700}}=(X_{t},Y_{t},W_{t}+\unicode[STIX]{x1D700},W_{t}^{\ast }+3\unicode[STIX]{x1D700})$
,
 $t\geqslant 0$
. This process takes values in the domain of
 $U^{\unicode[STIX]{x1D6FF}}$
, so the composition
 $U^{\unicode[STIX]{x1D6FF}}(Z_{t}^{\unicode[STIX]{x1D700}})$
makes sense. So, if we fix
 $t\geqslant 0$
and apply Itô’s formula, we get
 $$\begin{eqnarray}U^{\unicode[STIX]{x1D6FF}}(Z_{t}^{\unicode[STIX]{x1D700}})=U^{\unicode[STIX]{x1D6FF}}(Z_{0}^{\unicode[STIX]{x1D700}})+I_{1}+I_{2}+I_{3}/2,\end{eqnarray}$$
where
 $$\begin{eqnarray}\displaystyle I_{1} & = & \displaystyle \int _{0}^{t}U_{x}^{\unicode[STIX]{x1D6FF}}(Z_{s}^{\unicode[STIX]{x1D700}})\,dX_{s}+\int _{0}^{t}U_{y}^{\unicode[STIX]{x1D6FF}}(Z_{s}^{\unicode[STIX]{x1D700}})\,dY_{s}+\int _{0}^{t}U_{u}^{\unicode[STIX]{x1D6FF}}(Z_{s}^{\unicode[STIX]{x1D700}})\,dW_{s},\nonumber\\ \displaystyle I_{2} & = & \displaystyle \int _{0}^{t}U_{v}^{\unicode[STIX]{x1D6FF}}(Z_{s}^{\unicode[STIX]{x1D700}})\,dW_{s}^{\ast },\nonumber\\ \displaystyle I_{3} & = & \displaystyle \int _{0}^{t}D_{xyu}^{2}U^{\unicode[STIX]{x1D6FF}}(Z_{s}^{\unicode[STIX]{x1D700}})\,d[X,Y,W]_{s}.\nonumber\end{eqnarray}$$
Here the integral in
 $I_{3}$
is the shortened notation for the sum of all the second-order terms, i.e.
 $$\begin{eqnarray}I_{3}=\int _{0}^{t}U_{xx}^{\unicode[STIX]{x1D6FF}}(Z_{s}^{\unicode[STIX]{x1D700}})\,d[X,X]_{s}+2\int _{0}^{t}U_{xy}^{\unicode[STIX]{x1D6FF}}(Z_{s}^{\unicode[STIX]{x1D700}})\,d[X,Y]_{s}+\cdots \,.\end{eqnarray}$$
Note that the process
 $W^{\ast }$
and partial derivatives with respect to
 $v$
do not appear in
 $I_{3}$
: this is due to the fact that
 $W^{\ast }$
is a process of bounded variation and hence any square bracket involving it must vanish.
Let us look at the terms
 $I_{1}$
,
 $I_{2}$
and
 $I_{3}$
separately. By properties of the stochastic integrals, the first term is a mean-zero martingale, since
 $X$
,
 $Y$
and
 $W$
are assumed to be bounded. The second term is non-positive, by 3
 $^{\circ }$
and the fact that the process
 $W^{\ast }$
is non-decreasing. Finally,
 $I_{3}$
is also non-positive, which follows directly from 4
 $^{\circ }$
. Indeed, pick an arbitrary partition
 $0=s_{0}<s_{1}<s_{2}<\cdots <s_{N}=t$
and an integer
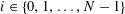 $i\in \{0,1,\ldots ,N-1\}$
. Next, set
 $\unicode[STIX]{x1D6E5}X=X_{s_{i+1}}-X_{s_{i}}$
,
 $\unicode[STIX]{x1D6E5}Y=H_{s_{i}}\unicode[STIX]{x1D6E5}X$
,
 $\unicode[STIX]{x1D6E5}W=W_{s_{i+1}}-W_{s_{i}}$
and note that
 $$\begin{eqnarray}\displaystyle 0 & {\geqslant} & \displaystyle \frac{d^{2}}{dt^{2}}U(X_{s_{i}}+t\unicode[STIX]{x1D6E5}X,Y_{s_{i}}+t\unicode[STIX]{x1D6E5}Y,W_{s_{i}}+t\unicode[STIX]{x1D6E5}W+\unicode[STIX]{x1D700},W_{s_{i}}^{\ast }+2\unicode[STIX]{x1D700})\biggr|_{t=0}\nonumber\\ \displaystyle & = & \displaystyle \langle D_{xyu}^{2}U(X_{s_{i}},Y_{s_{i}},W_{s_{i}}+\unicode[STIX]{x1D700},W_{s_{i}}^{\ast }+2\unicode[STIX]{x1D700})(\unicode[STIX]{x1D6E5}X,\unicode[STIX]{x1D6E5}Y,\unicode[STIX]{x1D6E5}W),(\unicode[STIX]{x1D6E5}X,\unicode[STIX]{x1D6E5}Y,\unicode[STIX]{x1D6E5}W)\rangle .\nonumber\end{eqnarray}$$
It remains to sum these inequalities over
 $i$
and let the diameter of the partition
 $(s_{i})$
go to zero; as the result, one obtains
 $I_{3}\leqslant 0$
.
Putting all of the above facts together and taking the expectation in (2.6), we obtain
 $$\begin{eqnarray}\mathbb{E}U^{\unicode[STIX]{x1D6FF}}(Z_{t}^{\unicode[STIX]{x1D700}})\leqslant \mathbb{E}U^{\unicode[STIX]{x1D6FF}}(Z_{0}^{\unicode[STIX]{x1D700}}).\end{eqnarray}$$
Now we carry out an appropriate two-step limiting procedure. First, recall that
 $U$
is continuous, and hence
 $U^{\unicode[STIX]{x1D6FF}}\rightarrow U$
pointwise as
 $\unicode[STIX]{x1D6FF}\rightarrow 0$
. Therefore, if we combine this with the boundedness of the process
 $Z^{\unicode[STIX]{x1D700}}$
, we obtain
 $$\begin{eqnarray}\mathbb{E}U(Z_{t}^{\unicode[STIX]{x1D700}})\leqslant \mathbb{E}U(Z_{0}^{\unicode[STIX]{x1D700}}),\end{eqnarray}$$
in the light of Lebesgue’s dominated convergence theorem. Next, we let
 $\unicode[STIX]{x1D700}\rightarrow 0$
and use the (uniform) boundedness of
 $Z^{\unicode[STIX]{x1D700}}$
and continuity of
 $U$
to obtain
 $$\begin{eqnarray}\mathbb{E}U(X_{t},Y_{t},W_{t},W_{t}^{\ast })\leqslant \mathbb{E}U(X_{0},Y_{0},W_{0},W_{0}^{\ast }).\end{eqnarray}$$
However, we have
 $|Y_{0}|=|H_{0}X_{0}|\leqslant |X_{0}|$
and
 $W_{0}^{\ast }=W_{0}$
; thus, by (2.2), the right-hand side above is non-positive. It remains to apply the majorization (2.3) to get the desired estimate (2.1).◻
Remark 2.2. There is a question which arises naturally in all contexts exploiting Bellman functions. Namely, suppose that we know a priori that the inequality (2.1) holds true. Can it be proved with the use of the above method, i.e. is there a function
 $U$
possessing all of the required properties? The positive answer would enable, in particular, the search for the optimal constants involved in the estimates. It is not difficult to prove that the answer is indeed positive, at least if we impose some additional structural properties on
 $V$
. Suppose that
 $V$
is continuous and non-increasing with respect to its fourth variable. Define
 $U:\mathfrak{D}\rightarrow \mathbb{R}$
by the abstract formula
 $$\begin{eqnarray}U(x,y,u,v)=\sup \mathbb{E}V(X_{t},Y_{t},W_{t},\max \{W_{t}^{\ast },v\}),\end{eqnarray}$$
where the supremum is taken over all bounded martingales
 $X$
starting from
 $x$
, all bounded martingales
 $Y$
satisfying
 $$\begin{eqnarray}Y_{t}=y+\int _{0+}^{t}H_{s}\,dX_{s},\end{eqnarray}$$
for some predictable process
 $H$
bounded in absolute value by
 $1$
, and all bounded weights
 $W$
with
 $W_{0}=u$
. One shows that
 $U$
satisfies all of the required conditions with the standard use of Markov property.
Unfortunately, we have been unable to identify the “optimal” Bellman functions
 $U$
mentioned in the remark above (i.e. leading to a sharp version of (1.4)). Still, we have managed to find functions which yield constants of optimal order: as we shall see, these special objects have quite a complicated structure and their analysis will require a certain amount of work.
3 The
$L^{p}$
estimates

Now we will show how the above method can be used to yield the weighted
 $L^{p}$
estimates for martingales, announced in the introduction.
3.1 Dual bounds
Actually, it will be more convenient for us to establish a dual estimate to (1.4). Let us formulate the result in a separate statement.
Theorem 3.1. Suppose that
 $W$
is a weight,
 $X$
is a martingale and
 $Y=H\cdot X$
, where
 $H$
is a predictable process with values in
 $[-1,1]$
. Then
 $$\begin{eqnarray}\biggl\|\frac{Y_{\infty }}{M_{r}W}\biggr\|_{L^{p}(M_{r}W)}\leqslant \frac{c_{p^{\prime }}(r)}{(r-1)^{1/p}}\biggl\|\frac{X_{\infty }}{W_{\infty }}\biggr\|_{L^{p}(W)},\quad 1<p<\infty ,\end{eqnarray}$$
where
 $c_{p}(r)$
is given in (1.5).
To see that the above statement is indeed dual to (1.4), let
 $\unicode[STIX]{x1D701}$
be an arbitrary random variable belonging to
 $L^{p^{\prime }}$
and let
 $V=(\mathbb{E}(W_{\infty }^{1/p}\unicode[STIX]{x1D701}|{\mathcal{F}}_{t}))_{t\geqslant 0}$
be the martingale generated by the variable
 $W_{\infty }^{1/p}\unicode[STIX]{x1D701}$
(which is integrable, by Hölder’s inequality). We have, by basic properties of stochastic integrals,
 $$\begin{eqnarray}\displaystyle \mathbb{E}Y_{\infty }W_{\infty }^{1/p}\unicode[STIX]{x1D701} & = & \displaystyle \mathbb{E}(H\cdot X)_{\infty }V_{\infty }\nonumber\\ \displaystyle & = & \displaystyle \mathbb{E}X_{\infty }(H\cdot V)_{\infty }\nonumber\\ \displaystyle & = & \displaystyle \mathbb{E}X_{\infty }(M_{r}W)^{1/p}\cdot (H\cdot V)_{\infty }(M_{r}W)^{-1/p}\nonumber\\ \displaystyle & {\leqslant} & \displaystyle \Vert X\Vert _{L^{p}(M_{r}W)}\Vert (H\cdot V)_{\infty }(M_{r}W)^{-1/p}\Vert _{L^{p^{\prime }}}\nonumber\\ \displaystyle & = & \displaystyle \Vert X\Vert _{L^{p}(M_{r}W)}\biggl\|\frac{(H\cdot V)_{\infty }}{M_{r}W}\biggr\|_{L^{p^{\prime }}(M_{r}W)}\nonumber\\ \displaystyle & {\leqslant} & \displaystyle \Vert X\Vert _{L^{p}(M_{r}W)}\cdot \frac{c_{p}(r)}{(r-1)^{1/p^{\prime }}}\biggl\|\frac{V_{\infty }}{W}\biggr\|_{L^{p^{\prime }}(W)}\nonumber\\ \displaystyle & = & \displaystyle \frac{c_{p}(r)}{(r-1)^{1/p^{\prime }}}\Vert X\Vert _{L^{p}(M_{r}W)}\Vert \unicode[STIX]{x1D701}\Vert _{L^{p^{\prime }}}.\nonumber\end{eqnarray}$$
Since
 $\unicode[STIX]{x1D701}\in L^{p^{\prime }}$
was arbitrary, (1.4) follows.
In the next two subsections, we prove the validity of (3.1) for
 $p<2$
and
 $p\geqslant 2$
. Before we do this, let us quickly show that
 $c_{p}(r)\leqslant 8pp^{\prime }$
, which we have declared in (1.5) above. If
 $1<p<2$
, we have
 $$\begin{eqnarray}\frac{c_{p}(r)}{4pp^{\prime }}=\frac{(p^{\prime }r/16)^{1/p^{\prime }}}{p}\leqslant \frac{(p^{\prime }/8)^{1/p^{\prime }}}{p}\leqslant 2,\end{eqnarray}$$
since
 $x^{1/x}\leqslant 2$
for any
 $x>0$
. On the other hand, if
 $p\geqslant 2$
, then
 $$\begin{eqnarray}c_{p}(r)\leqslant \frac{2(p^{\prime }+1)}{p^{\prime }-1}=\frac{2(p^{\prime }+1)}{(p^{\prime })^{2}}\cdot pp^{\prime }\leqslant 4pp^{\prime }.\end{eqnarray}$$
3.2 The case
$1<p\leqslant 2$

Since
 $M_{r}W=[(W^{r})^{\ast }]^{1/r}$
, the inequality (3.1) can be rewritten in the form
 $$\begin{eqnarray}\mathbb{E}|Y_{\infty }|^{p}[(W^{r})^{\ast }]^{(1-p)/r}\leqslant \frac{2(p+r-1)}{(r-1)(p-1)}\mathbb{E}|X_{\infty }|^{p}W_{\infty }^{1-p},\end{eqnarray}$$
or, if we introduce an auxiliary weight
 $\tilde{W}=W^{r}$
and set
 $\unicode[STIX]{x1D6FC}=1/r$
,
 $$\begin{eqnarray}\mathbb{E}|Y_{\infty }|^{p}[\tilde{W}^{\ast }]^{-\unicode[STIX]{x1D6FC}(p-1)}\leqslant \frac{2(\unicode[STIX]{x1D6FC}(p-1)+1)}{(1-\unicode[STIX]{x1D6FC})(p-1)}\mathbb{E}|X_{\infty }|^{p}\tilde{W}_{\infty }^{-\unicode[STIX]{x1D6FC}(p-1)}.\end{eqnarray}$$
For convenience, let us write
 $W$
instead of
 $\tilde{W}$
; then we see that the above inequality is of the form (2.1), with
 $$\begin{eqnarray}V_{p}(x,y,u,v)=|y|^{p}v^{-\unicode[STIX]{x1D6FC}(p-1)}-\frac{2(\unicode[STIX]{x1D6FC}(p-1)+1)}{(1-\unicode[STIX]{x1D6FC})(p-1)}|x|^{p}u^{-\unicode[STIX]{x1D6FC}(p-1)}.\end{eqnarray}$$
The special function
 $U_{p}:\mathfrak{D}\rightarrow \mathbb{R}$
is given by the formula
 $$\begin{eqnarray}U_{p}(x,y,u,v)=(x^{2}+y^{2})^{p/2}v^{-\unicode[STIX]{x1D6FC}(p-1)}-\frac{2(\unicode[STIX]{x1D6FC}(p-1)+1)}{(1-\unicode[STIX]{x1D6FC})(p-1)}|x|^{p}u^{-\unicode[STIX]{x1D6FC}(p-1)}.\end{eqnarray}$$
Let us now verify that this special object enjoys all of the required properties.
Lemma 3.2. The function
 $U_{p}$
belongs to the class
 ${\mathcal{U}}(V_{p})$
.
Proof. The property 1
 $^{\circ }$
is equivalent to the estimate
 $$\begin{eqnarray}2^{p/2}-\frac{2(\unicode[STIX]{x1D6FC}(p-1)+1)}{(1-\unicode[STIX]{x1D6FC})(p-1)}\leqslant 0,\end{eqnarray}$$
which is evident: we have
 $$\begin{eqnarray}\frac{2(\unicode[STIX]{x1D6FC}(p-1)+1)}{(1-\unicode[STIX]{x1D6FC})(p-1)}\geqslant \frac{2}{p-1}\geqslant 2^{p/2}.\end{eqnarray}$$
The majorization 2
 $^{\circ }$
and the property 3
 $^{\circ }$
are trivial. The main technical difficulty lies in checking the concavity condition 4
 $^{\circ }$
. Fix
 $x,y,u,v,h,k,\ell$
as in the statement of this condition; since
 $U$
is of class
 $C^{1}$
, it is enough to check that
 $G^{\prime \prime }(t)\leqslant 0$
for all
 $t$
such that
 $x+th\neq 0$
. Actually, since
 $$\begin{eqnarray}G_{x,y,u,v,h,k,\ell }(t+s)=G_{x+th,y+tk,u+t\ell ,v,h,k}(s),\end{eqnarray}$$
it suffices to verify the estimate
 $G^{\prime \prime }(0)\leqslant 0$
. The function
 $G$
is a difference of two terms; we study the contribution of each term separately. We compute that
 $$\begin{eqnarray}\frac{d^{2}}{dt^{2}}((x+th)^{2}+(y+tk)^{2})^{p/2}\biggr|_{t=0}=K_{1}+K_{2}+K_{3},\end{eqnarray}$$
where
 $$\begin{eqnarray}\displaystyle K_{1} & = & \displaystyle p(x^{2}+y^{2})^{p/2-2}((p-1)x^{2}+y^{2})h^{2},\nonumber\\ \displaystyle K_{2} & = & \displaystyle 2p(p-2)xy(x^{2}+y^{2})^{p/2-2}hk\leqslant p(2-p)(x^{2}+y^{2})^{p/2-1}h^{2},\nonumber\\ \displaystyle K_{3} & = & \displaystyle p(x^{2}+y^{2})^{p/2-2}(x^{2}+(p-1)y^{2})k^{2}\nonumber\\ \displaystyle & {\leqslant} & \displaystyle p(x^{2}+y^{2})^{p/2-2}(x^{2}+(p-1)y^{2})h^{2}.\nonumber\end{eqnarray}$$
This implies
 $$\begin{eqnarray}\displaystyle & & \displaystyle \frac{d^{2}}{dt^{2}}((x+th)^{2}+(y+tk)^{2})^{p/2}v^{-\unicode[STIX]{x1D6FC}(p-1)}\biggr|_{t=0}\nonumber\\ \displaystyle & & \displaystyle \quad \leqslant 2p(x^{2}+y^{2})^{p/2-1}u^{-\unicode[STIX]{x1D6FC}(p-1)}h^{2}.\end{eqnarray}$$
Next, if
 $x\neq 0$
, we derive that
 $$\begin{eqnarray}\displaystyle \frac{d^{2}}{dt^{2}}(|x+th|^{p}(u+t\ell )^{-\unicode[STIX]{x1D6FC}(p-1)})\biggr|_{t=0}=\langle A(h,\ell ),(h,\ell )\rangle , & & \displaystyle \nonumber\end{eqnarray}$$
where the matrix
 $A$
is given by
 $$\begin{eqnarray}\left[\begin{array}{@{}cc@{}}p(p-1)|x|^{p-2}u^{-\unicode[STIX]{x1D6FC}(p-1)} & -\unicode[STIX]{x1D6FC}p(p-1)|x|^{p-1}u^{-\unicode[STIX]{x1D6FC}(p-1)-1}\operatorname{sgn}x\\ -\unicode[STIX]{x1D6FC}p(p-1)|x|^{p-1}u^{-\unicode[STIX]{x1D6FC}(p-1)-1}\operatorname{sgn}x & \unicode[STIX]{x1D6FC}(p-1)(\unicode[STIX]{x1D6FC}(p-1)+1)|x|^{p}u^{-\unicode[STIX]{x1D6FC}(p-1)-2}\end{array}\right].\end{eqnarray}$$
We easily check that
 $A$
is non-negative-definite; actually, this will still be true if we multiply the number in the upper-left corner by
 $$\begin{eqnarray}\unicode[STIX]{x1D6FE}=\frac{\unicode[STIX]{x1D6FC}p}{\unicode[STIX]{x1D6FC}(p-1)+1}\end{eqnarray}$$
(after this multiplication, the determinant of the resulting matrix vanishes). Therefore, we have
 $$\begin{eqnarray}\displaystyle \frac{d^{2}}{dt^{2}}(|x+th|^{p}(u+t\ell )^{-\unicode[STIX]{x1D6FC}(p-1)})\bigg|_{t=0} & {\geqslant} & \displaystyle (1-\unicode[STIX]{x1D6FE})p(p-1)|x|^{p-2}u^{-\unicode[STIX]{x1D6FC}(p-1)}h^{2}\nonumber\\ \displaystyle & = & \displaystyle \frac{p(p-1)(1-\unicode[STIX]{x1D6FC})}{\unicode[STIX]{x1D6FC}(p-1)+1}|x|^{p-2}u^{-\unicode[STIX]{x1D6FC}(p-1)}h^{2}.\nonumber\\ \displaystyle & & \displaystyle\end{eqnarray}$$
Combining this inequality with (3.3), we obtain the desired bound
 $G^{\prime \prime }(0)\leqslant 0$
. This proves the claim.◻
Proof of (3.1).
As we have already observed above, it is enough to establish (3.2). The method described in §2 allows us to deduce the inequality for bounded processes, so we need some straightforward auxiliary limiting arguments to get the claim in full generality. Take an arbitrary continuous-path, uniformly integrable martingale
 $X$
and let
 $Y=H\cdot X$
for some predictable process
 $H$
with values in
 $[-1,1]$
. Furthermore, let
 $W$
be an arbitrary non-negative weight. For a given integer
 $N$
, consider the stopping time
 $$\begin{eqnarray}\unicode[STIX]{x1D70F}_{N}=\{t\geqslant 0:|X_{t}|+|Y_{t}|+W_{t}\geqslant N\}.\end{eqnarray}$$
Apply the method of §2 to the bounded martingales
 $X_{t}^{(N)}=X_{\unicode[STIX]{x1D70F}_{N}\wedge t}1_{\{\unicode[STIX]{x1D70F}_{N}>0\}}$
,
 $Y_{t}^{(N)}=Y_{\unicode[STIX]{x1D70F}_{N}\wedge t}1_{\{\unicode[STIX]{x1D70F}_{N}>0\}}$
and
 $W_{t}^{(N)}=N^{-1}+W_{\unicode[STIX]{x1D70F}_{N}\wedge t}1_{\{\unicode[STIX]{x1D70F}_{N}>0\}}$
; note that
 $Y^{(N)}=H\cdot X^{(N)}$
with unchanged process
 $H$
. We get that for each
 $t\geqslant 0$
,
 $$\begin{eqnarray}\mathbb{E}|Y^{(N)}|^{p}(W^{(N)\ast })^{-\unicode[STIX]{x1D6FC}(p-1)}\leqslant \frac{2(\unicode[STIX]{x1D6FC}(p-1)+1)}{(1-\unicode[STIX]{x1D6FC})(p-1)}\mathbb{E}|X^{(N)}|^{p}(W^{(N)})^{-\unicode[STIX]{x1D6FC}(p-1)}.\end{eqnarray}$$
Clearly, we have
 $$\begin{eqnarray}\mathbb{E}|Y^{(N)}|^{p}(N^{-1}+W^{\ast })^{-\unicode[STIX]{x1D6FC}(p-1)}\leqslant \mathbb{E}|Y^{(N)}|^{p}(W^{(N)\ast })^{-\unicode[STIX]{x1D6FC}(p-1)}.\end{eqnarray}$$
Furthermore, the function
 $(x,u)\mapsto |x|^{p}u^{-\unicode[STIX]{x1D6FC}(p-1)}$
is convex on
 $\mathbb{R}\times (0,\infty )$
: this follows at once from the fact that the matrix
 $A$
, considered above in the proof of the property 4
 $^{\circ }$
, is non-negative-definite. Moreover, we have
 $(X_{\unicode[STIX]{x1D70F}_{N}\wedge t},W_{\unicode[STIX]{x1D70F}_{N}\wedge t})=\mathbb{E}[(X_{\infty },W_{\infty })|{\mathcal{F}}_{\unicode[STIX]{x1D70F}_{N}\wedge t}]$
; hence, by the conditional Jensen’s inequality, we get
 $$\begin{eqnarray}\mathbb{E}|X^{(N)}|^{p}(W^{(N)})^{-\unicode[STIX]{x1D6FC}(p-1)}\leqslant \mathbb{E}|X_{\infty }|^{p}(N^{-1}+W_{\infty })^{-\unicode[STIX]{x1D6FC}(p-1)}1_{\{\unicode[STIX]{x1D70F}_{N}>0\}}.\end{eqnarray}$$
Combining the above two observations with (3.5) gives
 $$\begin{eqnarray}\displaystyle & & \displaystyle \mathbb{E}|Y^{(N)}|^{p}(N^{-1}+W^{\ast })^{-\unicode[STIX]{x1D6FC}(p-1)}\nonumber\\ \displaystyle & & \displaystyle \quad \leqslant \frac{2(\unicode[STIX]{x1D6FC}(p-1)+1)}{(1-\unicode[STIX]{x1D6FC})(p-1)}\mathbb{E}|X_{\infty }|^{p}(N^{-1}+W_{\infty })^{-\unicode[STIX]{x1D6FC}(p-1)}1_{\{\unicode[STIX]{x1D70F}_{N}>0\}}\nonumber\end{eqnarray}$$
and it remains to let
 $N\rightarrow \infty$
to obtain the assertion, by virtue of Lebesgue’s monotone convergence theorem and Fatou’s lemma.◻
3.3 The case
$p>2$

Here the calculations will be more involved. Arguing as in the preceding case, we see that (3.1) is equivalent to the following version of (3.2):
 $$\begin{eqnarray}\mathbb{E}|Y_{\infty }|^{p}[W^{\ast }]^{-\unicode[STIX]{x1D6FC}(p-1)}\leqslant \frac{4^{p-2}p^{p+1}}{1-\unicode[STIX]{x1D6FC}}\mathbb{E}|X_{\infty }|^{p}W_{\infty }^{-\unicode[STIX]{x1D6FC}(p-1)}.\end{eqnarray}$$
This estimate is of the form (2.1), with
 $V=V_{p}:\mathfrak{D}\rightarrow \mathbb{R}$
given by
 $$\begin{eqnarray}V_{p}(x,y,u,v)=|y|^{p}v^{-\unicode[STIX]{x1D6FC}(p-1)}-\frac{4^{p-2}p^{p+1}}{1-\unicode[STIX]{x1D6FC}}|x|^{p}u^{-\unicode[STIX]{x1D6FC}(p-1)}.\end{eqnarray}$$
The special function
 $U_{p}:\mathfrak{D}\rightarrow \mathbb{R}$
is defined by
 $$\begin{eqnarray}U_{p}(x,y,u,v)=2|y|^{p}v^{-\unicode[STIX]{x1D6FC}(p-1)}-2\cdot \frac{4^{p-2}p^{p+1}}{1-\unicode[STIX]{x1D6FC}}|x|^{p}u^{-\unicode[STIX]{x1D6FC}(p-1)}\end{eqnarray}$$
if
 $|y|\leqslant 4p|x|$
, and
 $$\begin{eqnarray}\displaystyle U_{p}(x,y,u,v) & = & \displaystyle 2(|y|^{p}-p^{2}x^{2}|y|^{p-2}+4^{p-2}p^{p}|x|^{p})v^{-\unicode[STIX]{x1D6FC}(p-1)}\nonumber\\ \displaystyle & & \displaystyle -2\cdot \frac{4^{p-2}p^{p+1}}{1-\unicode[STIX]{x1D6FC}}|x|^{p}u^{-\unicode[STIX]{x1D6FC}(p-1)}\nonumber\end{eqnarray}$$
otherwise. Actually, one can write the definition with the use of a single formula:
 $$\begin{eqnarray}\displaystyle U_{p}(x,y,u,v) & = & \displaystyle 2\min \{|y|^{p},|y|^{p}-p^{2}x^{2}|y|^{p-2}+4^{p-2}p^{p}|x|^{p}\}v^{-\unicode[STIX]{x1D6FC}(p-1)}\nonumber\\ \displaystyle & & \displaystyle -\,2\cdot \frac{4^{p-2}p^{p+1}}{1-\unicode[STIX]{x1D6FC}}|x|^{p}u^{-\unicode[STIX]{x1D6FC}(p-1)}.\end{eqnarray}$$
Now we will prove that
 $U_{p}$
,
 $V_{p}$
enjoy the required properties.
Lemma 3.3. The function
 $U_{p}$
belongs to the class
 ${\mathcal{U}}(V_{p})$
.
Proof. It is clear that
 $U_{p}$
is continuous. The inequality (2.2) is equivalent to
 $$\begin{eqnarray}1-4^{p-2}p^{p+1}/(1-\unicode[STIX]{x1D6FC})\leqslant 0,\end{eqnarray}$$
which is evident. The proof of the majorization 2
 $^{\circ }$
is also easy: it suffices to add the trivial inequalities
 $$\begin{eqnarray}\displaystyle 2\min \{|y|^{p},|y|^{p}-p^{2}x^{2}|y|^{p-2}+4^{p-2}p^{p}|x|^{p}\}v^{-\unicode[STIX]{x1D6FC}(p-1)}\geqslant |y|^{p}v^{-\unicode[STIX]{x1D6FC}(p-1)} & & \displaystyle \nonumber\end{eqnarray}$$
and
 $$\begin{eqnarray}\frac{4^{p}p^{p+1}}{1-\unicode[STIX]{x1D6FC}}|x|^{p}u^{-\unicode[STIX]{x1D6FC}(p-1)}\geqslant 2\cdot \frac{4^{p-2}p^{p+1}}{1-\unicode[STIX]{x1D6FC}}|x|^{p}u^{-\unicode[STIX]{x1D6FC}(p-1)}\end{eqnarray}$$
to obtain (2.3). The property 3
 $^{\circ }$
holds trivially. So, it remains to establish the concavity condition 4
 $^{\circ }$
, which will be done in a similar fashion as in the case
 $1<p\leqslant 2$
. First, note that we may use (3.4): this inequality holds true in the full range
 $1<p<\infty$
. Therefore, if
 $|y|<4p|x|$
, then
 $$\begin{eqnarray}\displaystyle & & \displaystyle G_{x,y,u,v,h,k,\ell }^{\prime \prime }(0)/2\nonumber\\ \displaystyle & & \displaystyle \quad \!\leqslant p(p-1)|y|^{p-2}k^{2}v^{-\unicode[STIX]{x1D6FC}(p-1)}-\frac{4^{p-2}p^{p+1}}{1-\unicode[STIX]{x1D6FC}}\cdot \frac{p(p-1)(1-\unicode[STIX]{x1D6FC})}{\unicode[STIX]{x1D6FC}(p-1)+1}|x|^{p-2}u^{-\unicode[STIX]{x1D6FC}(p-1)}h^{2}\nonumber\\ \displaystyle & & \displaystyle \quad \!\leqslant p(p-1)(4p|x|)^{p-2}u^{-\unicode[STIX]{x1D6FC}(p-1)}h^{2}\biggl(1-\frac{p^{3}}{\unicode[STIX]{x1D6FC}(p-1)+1}\biggr)\leqslant 0.\nonumber\end{eqnarray}$$
So, suppose that
 $|y|>4p|x|>0$
and set
 $N(x,y)=|y|^{p}-p^{2}x^{2}|y|^{p-2}+4^{p-2}p^{p}|x|^{p}.$
We compute that
 $$\begin{eqnarray}\displaystyle & N_{xx}(x,y)h^{2}=(-2p^{2}|y|^{p-2}+4^{p-2}p^{p}\cdot p(p-1)|x|^{p-2})h^{2}, & \displaystyle \nonumber\\ \displaystyle & N_{xy}(x,y)hk=-2p^{2}(p-2)x|y|^{p-4}yhk\leqslant 2p^{2}(p-2)|x\Vert y|^{p-3}h^{2} & \displaystyle \nonumber\end{eqnarray}$$
and
 $$\begin{eqnarray}\displaystyle N_{yy}(x,y)k^{2} & = & \displaystyle [p(p-1)|y|^{p-2}-p^{2}(p-2)(p-3)|y|^{p-4}x^{2}]k^{2}\nonumber\\ \displaystyle & {\leqslant} & \displaystyle [p(p-1)|y|^{p-2}-p^{2}(p-2)(p-3)|y|^{p-4}x^{2}]h^{2}\nonumber\end{eqnarray}$$
(clearly, the expression in the square brackets is non-negative). Combining these estimates with (3.4), we get
 $$\begin{eqnarray}\displaystyle G_{x,y,u,v,h,k,\ell }^{\prime \prime }(0)/2\leqslant J_{1}+J_{2}+J_{3}, & & \displaystyle \nonumber\end{eqnarray}$$
where
 $$\begin{eqnarray}\displaystyle J_{1} & = & \displaystyle 4^{p-2}p^{p}\cdot p(p-1)|x|^{p-2}\biggl[v^{-\unicode[STIX]{x1D6FC}(p-1)}-\frac{p}{\unicode[STIX]{x1D6FC}(p-1)+1}u^{-\unicode[STIX]{x1D6FC}(p-1)}\biggr]h^{2}\leqslant 0,\nonumber\\ \displaystyle J_{2} & = & \displaystyle p(p-2)|y|^{p-3}(-|y|+4p|x|)v^{-\unicode[STIX]{x1D6FC}(p-1)}h^{2}\leqslant 0,\nonumber\\ \displaystyle J_{3} & = & \displaystyle p|y|^{p-4}(-3y^{2}-p(p-2)(p-3)x^{2})v^{-\unicode[STIX]{x1D6FC}(p-1)}h^{2}\leqslant 0.\nonumber\end{eqnarray}$$
So, we have checked 4
 $^{\circ }$
, “locally”, i.e. we have proved the concavity of
 $G$
on the set
 $\{t:x+th\neq 0,|y+tk|\neq 4p|x+th|\}$
. To obtain the concavity on the whole domain, it suffices to use the fact that
 $U_{p}$
is of class
 $C^{1}$
on
 $\mathfrak{D}\setminus \{|y|=4p|x|\}$
(which handles the troublesome points
 $t$
for which
 $x+th=0$
) and use (3.6) (which guarantees that for
 $|y|=4p|x|$
, the one-sided derivatives of
 $G$
behave appropriately:
 $G^{\prime }(0+)\leqslant G^{\prime }(0-)$
).
This completes the proof of the lemma. ◻
Proof of (3.1),
$p>2$
.

The argument is word-by-word the same as for
 $p\leqslant 2$
.◻
4 Inequalities for
$A_{1}$
weights

Now we will deduce the validity of (1.6) and (1.7). We start with an auxiliary result, which is of independent interest.
Lemma 4.1. Suppose that
 $W$
is an
 $A_{1}$
weight. Then for any
 $1<r<(1-[W]_{A_{1}}^{-1})^{-1}$
, we have
 $$\begin{eqnarray}M_{r}W\leqslant (1+r([W]_{A_{1}}^{-1}-1))^{-1/r}W\end{eqnarray}$$
almost surely. In particular, if
 $r=1+(2[W]_{A_{1}})^{-1}$
, then
 $$\begin{eqnarray}M_{r}W\leqslant 2[W]_{A_{1}}W\end{eqnarray}$$
with probability
 $1$
.
Proof. We will again use the method of special functions; this time the argument will be more direct. Set
 $c=[W]_{A_{1}}$
and consider the function
 $U:[0,\infty )^{2}\rightarrow \mathbb{R}$
given by the expression
 $$\begin{eqnarray}U(x,y)=\frac{(rx-(r-1)y)y^{r-1}}{(r-(r-1)c)c^{r-1}}.\end{eqnarray}$$
Clearly, this function is of class
 $C^{\infty }$
and satisfies
 $U_{xx}(x,y)=0$
,
 $U_{y}(y,y)=0$
for all
 $x,y>0$
. Therefore, if
 $t\geqslant s$
, then, by Itô’s formula,
 $$\begin{eqnarray}U(W_{t},W_{t}^{\ast })=U(W_{s},W_{s}^{\ast })+\int _{s}^{t}U_{x}(W_{u},W_{u}^{\ast })\,dW_{u}\end{eqnarray}$$
(all of the second-order terms vanish, due to the above conditions on
 $U_{xx}$
and
 $U_{y}$
). Now we would like to apply the conditional expectation with respect to
 ${\mathcal{F}}_{s}$
(which would remove the stochastic integral on the right). However, to ensure that both sides have appropriate integrability, we need an additional localizing argument. Fix a large integer
 $N$
and consider the stopping time
 $\unicode[STIX]{x1D70F}_{N}=\inf \{r:W_{r}\geqslant N\}$
. Multiply both sides above by
 $1_{\{\unicode[STIX]{x1D70F}_{N}>s\}}$
and replace
 $t$
by
 $\unicode[STIX]{x1D70F}_{N}\wedge t$
. Then the integrand and the integrator are bounded, and the application of the conditional expectation with respect to
 ${\mathcal{F}}_{s}$
gives
 $$\begin{eqnarray}\mathbb{E}[U(W_{\unicode[STIX]{x1D70F}_{N}\wedge t},W_{\unicode[STIX]{x1D70F}_{N}\wedge t}^{\ast })|{\mathcal{F}}_{s}]\leqslant U(W_{s},W_{s}^{\ast })\end{eqnarray}$$
on the set
 $\{\unicode[STIX]{x1D70F}_{N}>s\}$
. However, one easily checks that if
 $x\leqslant y\leqslant cx$
, then we have the pointwise bound
 $$\begin{eqnarray}x^{r}\leqslant U(x,y)\leqslant (r-(r-1)c)^{-1}c^{1-r}y^{r}.\end{eqnarray}$$
Combining this with the previous estimate and the definition of the
 $A_{1}$
weight yields
 $$\begin{eqnarray}\displaystyle \mathbb{E}[W_{\unicode[STIX]{x1D70F}_{N}\wedge t}^{r}|{\mathcal{F}}_{s}] & {\leqslant} & \displaystyle (r-(r-1)c)^{-1}c^{1-r}(W_{s}^{\ast })^{r}\nonumber\\ \displaystyle & {\leqslant} & \displaystyle (r-(r-1)c)^{-1}c^{1-r}(W^{\ast })^{r}\leqslant (r-(r-1)c)^{-1}cW_{\infty }^{r}\nonumber\end{eqnarray}$$
(still on the set
 $\{\unicode[STIX]{x1D70F}_{N}>s\}$
). If we let
 $N\rightarrow \infty$
and then
 $t\rightarrow \infty$
, Fatou’s lemma gives
 $$\begin{eqnarray}\mathbb{E}[W_{\infty }^{r}|{\mathcal{F}}_{s}]\leqslant (1+r(c^{-1}-1))^{-1}W_{\infty }^{r}\end{eqnarray}$$
almost surely. Now, the martingale
 $(\mathbb{E}[W_{\infty }^{r}|{\mathcal{F}}_{s}])_{s\geqslant 0}$
has continuous trajectories (by the assumption on the filtration). Consequently,
 $$\begin{eqnarray}(W^{r})^{\ast }=\sup _{s\geqslant 0}\mathbb{E}[W_{\infty }^{r}|{\mathcal{F}}_{s}]=\sup _{s\geqslant 0,s\in \mathbb{Q}}\mathbb{E}[W_{\infty }^{r}|{\mathcal{F}}_{s}]\leqslant (1+r(c^{-1}-1))^{-1}W_{\infty }^{r}\end{eqnarray}$$
with probability
 $1$
. This is exactly the claim.◻
Proof of (1.6).
This follows at once from (1.4) and the second part of the above lemma (we get the bound with the constant
 $2^{1/p^{\prime }}\cdot 8pp^{\prime }<16pp^{\prime }$
).◻
Proof of (1.7).
By homogeneity, it is enough to show the estimate
 $$\begin{eqnarray}\mathbb{E}1_{\{|Y_{\infty }|>1\}}W_{\infty }\leqslant c[W]_{A_{1}}\log (1+[W]_{A_{1}})\Vert X_{\infty }\Vert _{L^{1}(W)}.\end{eqnarray}$$
We will actually establish the somewhat stronger bound
 $$\begin{eqnarray}\mathbb{E}1_{\{Y^{\ast }>1\}}W_{\infty }\leqslant c[W]_{A_{1}}\log (1+[W]_{A_{1}})\Vert X_{\infty }\Vert _{L^{1}(W)}.\end{eqnarray}$$
To this end, we will exploit an extrapolation-type argument. Let
 $W$
be an
 $A_{1}$
weight. Fix
 $X$
and
 $Y$
as in the statement and write
 $$\begin{eqnarray}\mathbb{E}W_{\infty }1_{\{Y^{\ast }\geqslant 1\}}\leqslant \mathbb{E}W_{\infty }1_{\{X^{\ast }>1\}}+\mathbb{E}W_{\infty }1_{\{Y^{\ast }>1,X^{\ast }\leqslant 1\}}=I+\mathit{II}.\end{eqnarray}$$
We analyze
 $I$
and
 $\mathit{II}$
separately.
The term
 $I$
. Let
 $\unicode[STIX]{x1D702}=\inf \{t\geqslant 0:|X_{t}|>1\}$
, with the usual convention
 $\inf \emptyset =\infty$
. We have
 $\unicode[STIX]{x1D702}<\infty$
on the set
 $\{X^{\ast }>1\}$
, so
 $$\begin{eqnarray}I=\mathbb{E}W_{\infty }1_{\{X^{\ast }>1\}}\leqslant \lim _{t\rightarrow \infty }\mathbb{E}W_{\infty }1_{\{|X_{\unicode[STIX]{x1D702}\wedge t}|>1\}}.\end{eqnarray}$$
But for any
 $t\geqslant 0$
,
 $$\begin{eqnarray}\displaystyle \mathbb{E}W_{\infty }1_{\{|X_{\unicode[STIX]{x1D702}\wedge t}|>1\}} & =\mathbb{E}W_{\unicode[STIX]{x1D702}\wedge t}1_{\{|X_{\unicode[STIX]{x1D702}\wedge t}|>1\}}\leqslant \mathbb{E}W_{\unicode[STIX]{x1D702}\wedge t}|X_{\unicode[STIX]{x1D702}\wedge t}|\leqslant \mathbb{E}W_{\unicode[STIX]{x1D702}\wedge t}|X_{\infty }|\leqslant \mathbb{E}|X_{\infty }|W^{\ast }. & \displaystyle \nonumber\end{eqnarray}$$
This yields
 $I\leqslant \mathbb{E}|X_{\infty }|W^{\ast }\leqslant [W]_{A_{1}}\Vert X_{\infty }\Vert _{L^{1}(W)}$
.
The term
 $\mathit{II}$
. Look at the stopped martingales
 $X^{\unicode[STIX]{x1D702}}=(X_{\unicode[STIX]{x1D702}\wedge t})_{t\geqslant 0}$
,
 $Y^{\unicode[STIX]{x1D702}}=(Y_{\unicode[STIX]{x1D702}\wedge t})_{t\geqslant 0}$
and
 $W^{\unicode[STIX]{x1D702}}=(W_{\unicode[STIX]{x1D702}\wedge t})_{t\geqslant 0}$
. Note that
 $$\begin{eqnarray}\mathit{II}=\mathbb{E}W_{\infty }1_{\{Y^{\ast }\geqslant 1,\unicode[STIX]{x1D702}=\infty \}}\leqslant \mathbb{E}W_{\infty }1_{\{(Y^{\unicode[STIX]{x1D702}})^{\ast }\geqslant 1\}}=\mathbb{E}W_{\infty }^{\unicode[STIX]{x1D702}}1_{\{(Y^{\unicode[STIX]{x1D702}})^{\ast }\geqslant 1\}},\end{eqnarray}$$
where the latter follows from the fact that
 $(Y^{\unicode[STIX]{x1D702}})^{\ast }$
is
 ${\mathcal{F}}_{\unicode[STIX]{x1D702}}$
-measurable and
 $W_{\infty }^{\unicode[STIX]{x1D702}}=\mathbb{E}(W_{\infty }|{\mathcal{F}}_{\unicode[STIX]{x1D702}})$
. Now, introduce the stopping time
 $\unicode[STIX]{x1D70E}=\inf \{t:|Y_{t}^{\unicode[STIX]{x1D702}}|>1\}$
. By (1.4), for any
 $1<p<\infty$
we have
 $$\begin{eqnarray}\displaystyle \mathbb{E}W_{\infty }^{\unicode[STIX]{x1D702}}1_{\{|Y_{\unicode[STIX]{x1D70E}}^{\unicode[STIX]{x1D702}}|>1\}}\leqslant \mathbb{E}W_{\infty }^{\unicode[STIX]{x1D702}}|Y_{\unicode[STIX]{x1D70E}}^{\unicode[STIX]{x1D702}}|^{p} & {\leqslant} & \displaystyle \frac{(8pp^{\prime })^{p}}{(r-1)^{p-1}}\mathbb{E}|X_{\unicode[STIX]{x1D70E}}^{\unicode[STIX]{x1D702}}|^{p}M_{r}W_{\infty }^{\unicode[STIX]{x1D702}}\nonumber\\ \displaystyle & {\leqslant} & \displaystyle \frac{(8pp^{\prime })^{p}}{(r-1)^{p-1}}\mathbb{E}|X_{\unicode[STIX]{x1D70E}}^{\unicode[STIX]{x1D702}}|M_{r}W_{\infty }^{\unicode[STIX]{x1D702}}\nonumber\\ \displaystyle & {\leqslant} & \displaystyle \frac{(8pp^{\prime })^{p}}{(r-1)^{p-1}}\mathbb{E}|X_{\infty }|M_{r}W_{\infty }^{\unicode[STIX]{x1D702}}\nonumber\\ \displaystyle & {\leqslant} & \displaystyle \frac{(8pp^{\prime })^{p}}{(r-1)^{p-1}}\mathbb{E}|X_{\infty }|M_{r}W_{\infty }.\nonumber\end{eqnarray}$$
Here in the third passage we have used the estimate
 $|X_{\unicode[STIX]{x1D70E}}^{\unicode[STIX]{x1D702}}|\leqslant 1$
(which follows directly from the definition of
 $\unicode[STIX]{x1D702}$
), in the fourth bound we used Jensen’s inequality, while the last one follows from the pointwise bound
 $M_{r}W_{\infty }^{\unicode[STIX]{x1D702}}\leqslant M_{r}W_{\infty }$
. To see that the latter statement is true, write, for any
 $t\geqslant 0$
,
 $$\begin{eqnarray}\displaystyle \mathbb{E}((W_{\infty }^{\unicode[STIX]{x1D702}})^{r}|{\mathcal{F}}_{t}) & = & \displaystyle \mathbb{E}((\mathbb{E}(W_{\infty }|{\mathcal{F}}_{\unicode[STIX]{x1D702}}))^{r}|{\mathcal{F}}_{t})\nonumber\\ \displaystyle & {\leqslant} & \displaystyle \mathbb{E}(\mathbb{E}(W_{\infty }^{r}|{\mathcal{F}}_{\unicode[STIX]{x1D702}})|{\mathcal{F}}_{t})\nonumber\\ \displaystyle & = & \displaystyle \mathbb{E}(W_{\infty }^{r}|{\mathcal{F}}_{\unicode[STIX]{x1D702}})1_{\{\unicode[STIX]{x1D702}\leqslant t\}}+\mathbb{E}(W_{\infty }^{r}|{\mathcal{F}}_{t})1_{\{\unicode[STIX]{x1D702}>t\}}\nonumber\\ \displaystyle & {\leqslant} & \displaystyle (W_{\infty }^{r})^{\ast }1_{\{\unicode[STIX]{x1D702}\leqslant t\}}+(W_{\infty }^{r})^{\ast }1_{\{\unicode[STIX]{x1D702}>t\}}=(W_{\infty }^{r})^{\ast }.\nonumber\end{eqnarray}$$
Taking the supremum over all
 $t\geqslant 0$
gives the bound for the
 $r$
-maximal functions.
We return to the preceding chain of inequalities. Take
 $r=1+(2[W]_{A_{1}})^{-1}$
(then
 $M_{r}W_{\infty }\leqslant 2[W]_{A_{1}}W_{\infty }$
, by the previous lemma) to get
 $$\begin{eqnarray}\mathbb{E}W_{\infty }^{\unicode[STIX]{x1D702}}1_{\{|Y_{\unicode[STIX]{x1D70E}}^{\unicode[STIX]{x1D702}}|>1\}}\leqslant 2(8pp^{\prime })^{p}[W]_{A_{1}}^{p}\mathbb{E}|X_{\infty }|W_{\infty }.\end{eqnarray}$$
Putting
 $p=1+(\log (1+[W]_{A_{1}}))^{-1}$
gives
 $$\begin{eqnarray}\mathbb{E}W_{\infty }^{\unicode[STIX]{x1D702}}1_{\{|Y_{\unicode[STIX]{x1D70E}}^{\unicode[STIX]{x1D702}}|>1\}}\leqslant c[W]_{A_{1}}(1+\log [W]_{A_{1}})\mathbb{E}|X_{\infty }|W_{\infty },\end{eqnarray}$$
for some universal
 $c$
. It remains to observe that
 $\mathbb{E}W_{\infty }^{\unicode[STIX]{x1D702}}1_{\{(Y^{\unicode[STIX]{x1D702}})^{\ast }>1\}}=\mathbb{E}W_{\infty }^{\unicode[STIX]{x1D702}}1_{\{|Y_{\unicode[STIX]{x1D70E}}^{\unicode[STIX]{x1D702}}|>1\}}$
; thus we have shown that
 $$\begin{eqnarray}\mathit{II}\leqslant c[W]_{A_{1}}(1+\log [W]_{A_{1}})\Vert X_{\infty }\Vert _{L^{1}(W)}.\end{eqnarray}$$
This completes the proof. ◻
5 Applications
Now we will show how to extend the results of the previous sections to the discrete setting, which is perhaps more natural for applications in harmonic analysis. Suppose that
 $(\unicode[STIX]{x1D6FA},{\mathcal{F}},\mathbb{P})$
is a fixed, non-atomic probability space.
Definition 5.1. A set
 ${\mathcal{T}}$
of measurable subsets of
 $\unicode[STIX]{x1D6FA}$
will be called a tree if the following conditions are satisfied.
-
(i) We have
$\unicode[STIX]{x1D6FA}\in {\mathcal{T}}$
and for every
$J\in {\mathcal{T}}$
, we have
$\mathbb{P}(J)>0$
. -
(ii) For every
$J\in {\mathcal{T}}$
there is a finite subset
$C(J)\subset {\mathcal{T}}$
containing at least two elements such that:-
(a) the elements of
$C(J)$
are pairwise disjoint subsets of
$J$
; and -
(b)
$J=\bigcup C(J)$
.
-
-
(iii) We have
${\mathcal{T}}=\bigcup _{m\geqslant 0}{\mathcal{T}}^{m}$
, where
${\mathcal{T}}^{0}=\{\unicode[STIX]{x1D6FA}\}$
and
$T^{m+1}=\bigcup _{J\in {\mathcal{T}}^{m}}C(J)$
.


In what follows, we will need to work with trees satisfying certain regularity-type property.
Definition 5.2. Let
 $\unicode[STIX]{x1D6FD}\geqslant 1$
be a given number. A tree
 ${\mathcal{T}}$
is called
 $\unicode[STIX]{x1D6FD}$
-regular, if for any non-negative integer
 $n$
and any
 $J_{1}\in {\mathcal{T}}^{n}$
,
 $J_{2}\in C(J_{1})$
we have
 $\mathbb{P}(J_{2})/\mathbb{P}(J_{1})\in [2^{-\unicode[STIX]{x1D6FD}},1-2^{-\unicode[STIX]{x1D6FD}}]$
.
A classical example which illustrates the above notions, is the cube
 $[0,1)^{d}$
with its Borel subsets and Lebesgue’s measure, equipped with the tree of dyadic subcubes. Clearly, in such a case one may take
 $\unicode[STIX]{x1D6FD}=d$
and hence, in general, the parameter
 $\unicode[STIX]{x1D6FD}$
(or rather the smallest value allowed in the definition) can be regarded as a dimension of the tree
 ${\mathcal{T}}$
.
Any tree-like structure gives rise to the corresponding filtration
 $({\mathcal{F}}_{n})_{n\geqslant 0}$
, given by
 ${\mathcal{F}}_{n}=\unicode[STIX]{x1D70E}(J:J\in {\mathcal{T}}^{n})$
. Given an integrable random variable
 $f$
, one can consider the associated martingale given by
 $(\mathbb{E}(f|{\mathcal{F}}_{n}))_{n\geqslant 0}$
; this sequence will be denoted by
 $(f_{n})_{n\geqslant 0}$
or, with a slight abuse of notation, again by the letter
 $f$
. Note that such martingales are simple, i.e. for any non-negative integer
 $n$
, the random variable
 $f_{n}$
takes only a finite number of values. This follows at once from the fact that
 ${\mathcal{F}}_{n}$
consists of finite number of sets. For a given martingale
 $f=(f_{n})_{n\geqslant 0}$
, we introduce its maximal function and truncated maximal function by
 $f^{\ast }=\sup _{k\geqslant 0}|f_{k}|$
and
 $f_{n}^{\ast }=\sup _{0\leqslant k\leqslant n}|f_{k}|$
,
 $n=0,1,2,\ldots \,$
. Furthermore, the difference sequence
 $df=(df_{n})_{n\geqslant 0}$
associated with a martingale
 $(f_{n})_{n\geqslant 0}$
is defined by
 $df_{0}=f_{0}$
and
 $df_{n}=f_{n}-f_{n-1}$
for
 $n\geqslant 1$
. Given any predictable sequence
 $v=(v_{n})_{n\geqslant 0}$
, we say that
 $g$
is the transform of
 $f$
by
 $v$
, if for any
 $n\geqslant 0$
we have
 $dg_{n}=v_{n}df_{n}$
; equivalently, we have the identities
 $$\begin{eqnarray}g_{n}=\mathop{\sum }_{k=0}^{n}v_{k}\,df_{k},\quad n=0,1,2,\ldots .\end{eqnarray}$$
In the context when
 $(\unicode[STIX]{x1D6FA},{\mathcal{F}},\mathbb{P})$
is the interval
 $[0,1)$
with its Borel subsets and Lebesgue measure, equipped with the dyadic tree, the martingale
 $(f_{n})_{n\geqslant 0}$
corresponds to the expansion of
 $f$
into the standard Haar system and
 $g=(g_{n})_{n\geqslant 0}$
reduces to the Haar multiplier of
 $f$
with respect to the sequence
 $v$
.
Finally, a non-negative, integrable random variable will be called a weight; we will say that a weight
 $w$
satisfies Muckenhoupt’s condition
 $A_{1}$
if there is an absolute constant
 $c$
such that
 $\mathbb{P}(w_{n}^{\ast }\leqslant cw_{n})=1$
for all
 $n$
.
We are ready to establish our main results in this direction.
Theorem 5.3. Suppose that
 $(\unicode[STIX]{x1D6FA},{\mathcal{F}},\mathbb{P})$
is a probability space equipped with a
 $\unicode[STIX]{x1D6FD}$
-regular tree
 ${\mathcal{T}}$
and let
 $w$
be an
 $A_{1}$
weight. If
 $g$
is a transform of
 $f$
by a predictable sequence
 $v$
satisfying
 $\Vert v\Vert _{\infty }=\sup _{n\geqslant 0}\Vert v_{n}\Vert _{\infty }\leqslant 1$
, then
 $$\begin{eqnarray}\Vert g\Vert _{L^{p}(w)}\leqslant 2^{\unicode[STIX]{x1D6FD}}\cdot 16pp^{\prime }[w]_{A_{1}}\Vert f\Vert _{L^{p}(w)},\quad 1<p<\infty ,\end{eqnarray}$$
and, for some universal constant
 $c$
,
 $$\begin{eqnarray}\Vert g\Vert _{L^{1,\infty }(w)}\leqslant c2^{\unicode[STIX]{x1D6FD}}[w]_{A_{1}}(1+\log (2^{\unicode[STIX]{x1D6FD}}[w]_{A_{1}}))\Vert f\Vert _{L^{1}(w)}.\end{eqnarray}$$
Proof. Let us assume first that the martingales
 $f$
and
 $w$
terminate after
 $N$
steps. Furthermore, by a simple approximation argument, we may assume that
 $f$
takes different values on different elements of
 ${\mathcal{T}}^{m}$
,
 $m=0,1,\ldots ,N$
; then, in particular, the variable
 $v_{n}$
is a function of
 $f_{n-1}$
: say,
 $v_{n}=F_{n}(f_{n-1})$
for some function
 $F_{n}$
with values in
 $[-1,1]$
,
 $n=1,2,\ldots ,N$
.
Using standard Skorokhod embedding theorems (cf. [Reference Obłój12]), there is a probability space
 $(\unicode[STIX]{x1D6FA}^{\prime },{\mathcal{F}}^{\prime },\mathbb{P}^{\prime })$
equipped with a filtration generated by a standard Brownian motion
 $B$
and a sequence
 $\unicode[STIX]{x1D70F}_{0},\unicode[STIX]{x1D70F}_{1},\ldots ,\unicode[STIX]{x1D70F}_{N}$
of stopping times and predictable processes
 $K^{w}$
,
 $K^{f}$
such that
 $$\begin{eqnarray}(w_{n})_{n=0}^{N}\sim \biggl(\mathbb{E}w_{N}+\int _{0+}^{\unicode[STIX]{x1D70F}_{n}}K_{s}^{w}\,dB_{s}\biggr)_{n=0}^{N},\qquad (f_{n})_{n=0}^{N}\sim \biggl(\mathbb{E}f_{N}+\int _{0+}^{\unicode[STIX]{x1D70F}_{n}}K_{s}^{f}\,dB_{s}\biggr)_{n=0}^{N}.\end{eqnarray}$$
Here
 ${\sim}$
means the equality in law. Introduce the martingales
 $$\begin{eqnarray}X_{t}=\mathbb{E}f_{N}+\int _{0+}^{t}K_{s}^{f}\,dB_{s},\qquad W_{t}=\mathbb{E}w_{N}+\int _{0+}^{t}K_{s}^{w}\,dB_{s}.\end{eqnarray}$$
Since
 $v_{n}=F_{n}(f_{n-1})$
for each
 $n$
(see the beginning of the proof), we see that there is a predictable process
 $H$
with values in
 $[-1,1]$
such that
 $(g_{n})_{n=0}^{N}\sim ((H\cdot X)_{\unicode[STIX]{x1D70F}_{n}})_{n=0}^{N}$
. Indeed, it is enough to take
 $H_{t}=F_{n}(X_{\unicode[STIX]{x1D70F}_{n-1}})$
when
 $t\in [\unicode[STIX]{x1D70F}_{n-1},\unicode[STIX]{x1D70F}_{n})$
.
Let us compare the characteristics
 $[w]_{A_{1}}$
and
 $[W]_{A_{1}}$
. Let
 $A$
be an element of
 ${\mathcal{T}}^{n}$
and let
 $A_{1},A_{2},\ldots ,A_{k}$
be its children from
 ${\mathcal{T}}^{n+1}$
. By
 $\unicode[STIX]{x1D6FD}$
-regularity of
 ${\mathcal{T}}$
, we see that
 $\mathbb{P}(A_{i})\geqslant 2^{-\unicode[STIX]{x1D6FD}}\mathbb{P}(A)$
and, hence,
 $$\begin{eqnarray}w_{n+1}|_{A_{i}}=\frac{1}{\mathbb{P}(A_{i})}\int _{A_{i}}w\,d\mathbb{P}\leqslant \frac{1}{\mathbb{P}(A_{i})}\int _{A}w\,d\mathbb{P}\leqslant 2^{\unicode[STIX]{x1D6FD}}\frac{1}{\mathbb{P}(A)}\int _{A}w\,d\mathbb{P}=2^{\unicode[STIX]{x1D6FD}}w_{n}|_{A}.\end{eqnarray}$$
This yields the estimate
 $w_{n+1}\leqslant 2^{\unicode[STIX]{x1D6FD}}w_{n}$
on
 $A$
, and since
 $A$
was arbitrary, this pointwise bound is true on the whole
 $\unicode[STIX]{x1D6FA}$
. Consequently, for any
 $n=0,1,\ldots ,N-1$
we have
 $W_{\unicode[STIX]{x1D70F}_{n+1}}\leqslant 2^{\unicode[STIX]{x1D6FD}}W_{\unicode[STIX]{x1D70F}_{n}}$
. Now, fix an arbitrary
 $t\geqslant 0$
. On the set
 $\{t\in [\unicode[STIX]{x1D70F}_{n},\unicode[STIX]{x1D70F}_{n+1}]\}$
we have
 $$\begin{eqnarray}W_{t}=\mathbb{E}(W_{\unicode[STIX]{x1D70F}_{n+1}}|{\mathcal{F}}_{t})\leqslant 2^{\unicode[STIX]{x1D6FD}}\mathbb{E}(W_{\unicode[STIX]{x1D70F}_{n}}|{\mathcal{F}}_{t})=2^{\unicode[STIX]{x1D6FD}}W_{\unicode[STIX]{x1D70F}_{n}}\end{eqnarray}$$
and hence
 $W_{t}^{\ast }\leqslant 2^{\unicode[STIX]{x1D6FD}}\max _{0\leqslant k\leqslant n}W_{\unicode[STIX]{x1D70F}_{k}}.$
On the other hand, the condition
 $w\in A_{1}$
implies
 $[w]_{A_{1}}w_{n+1}\geqslant w_{n+1}^{\ast }\geqslant w_{n}^{\ast }$
almost surely. Therefore, if
 $t\in [\unicode[STIX]{x1D70F}_{n},\unicode[STIX]{x1D70F}_{n+1})$
, we have
 $$\begin{eqnarray}W_{t}=\mathbb{E}(W_{\unicode[STIX]{x1D70F}_{n+1}}|{\mathcal{F}}_{t})\geqslant [w]_{A_{1}}^{-1}\mathbb{E}\Bigl(\max _{0\leqslant k\leqslant n}W_{\unicode[STIX]{x1D70F}_{k}}|{\mathcal{F}}_{t}\Bigr)=[w]_{A_{1}}^{-1}\max _{0\leqslant k\leqslant n}W_{\unicode[STIX]{x1D70F}_{k}}.\end{eqnarray}$$
Combining the above two observations, we get
 $W_{t}^{\ast }\leqslant 2^{\unicode[STIX]{x1D6FD}}[w]_{A_{1}}W_{t}$
on the set
 $t\leqslant \unicode[STIX]{x1D70F}_{N}$
. But
 $W$
is constant on
 $[\unicode[STIX]{x1D70F}_{N},\infty )$
, so this inequality is also true for
 $t>\unicode[STIX]{x1D70F}_{N}$
. This proves that
 $[W]_{A_{1}}\leqslant 2^{\unicode[STIX]{x1D6FD}}[w]_{A_{1}}$
. It remains to apply Theorems 1.1 and 1.2 to get the claim.◻
Acknowledgements
The author would like to thank anonymous referees for the careful reading of the first version of the paper and many helpful suggestions.



