Governments everywhere are amassing large pools of resources held by and managed for the public sector. The media calls these asset pools variously ‘future funds’, ‘sovereign wealth funds (SWFs)’, and ‘government investment funds’, and these entities afford their sponsoring nations both opportunities and risks depending on how these national endowments are managed. As these publicly held wealth funds grow, they are assuming an increasingly prominent role in news-making international investments, including providing support to some of the world's most important and often-troubled financial institutions (Scheherazade and Blitz, Reference Scheherazade and James2007). Analysts regularly comment on the size and potential international clout of these financial behemoths (Morgan Stanley Global, 2007), and some of the investment choices made by these funds have prompted policymakers including the governments of France and Germany to worry publicly about the potential economic impact of these funds' global reach (Economist, 2008). In parallel, international agencies including the OECD and the International Monetary Fund have begun to ask questions publicly about what these funds are and how they should be managed.Footnote 1
Our paper analyzes new information about ‘best practice’ management techniques for such publicly managed investment pools, focusing particularly on governance and reporting patterns along with how one might seek to protect the assets from political interference. We do so to glean lessons on which governance and accountability approaches appear to be well suited in the case of these publicly held wealth funds, and we also draw out policy inferences regarding governance reform. We show that these publicly managed investment funds have many different historical roots, including a purposeful buildup of fiscal surplus against future economic shocks (e.g. Australia and New Zealand); a focused effort to mitigate the effects of demographic disequilibrium on the social security balance (e.g. Japan); or a desire to set aside some portion of revenue associated with the exploitation of natural resources (e.g. Norway). In value terms, the Japanese public pension reserve is among the largest, with some US$912 billion in accumulated funds (Matsui and Suzuki, Reference Matsui and Makiko2007). Other large funds include that of the United Arab Emirates (US$875B), Singapore's GIC fund ($330B), and Norway's Pension Fund (US$300B); see the Economist (2007).
In what follows, we take up several questions of key importance to public investment funds. First, we ask what constitutes ‘good management practice’, by which we mean the protocols and practices regarding fund governance, accountability, and investment (GAI) policies (below we outline what we mean by each of these). Second, we ask how good management of public investment funds affects fund performance. In order to do so, it is necessary to evaluate what types of performance metrics exist and whether they might depend on the type of fund. We also review the literature regarding the effect of management practice on performance of public investment funds. Third, we explore whether good management practices for public investment funds for GAI policies appear to be linked to key aspects of a nation's economic, political, and social conditions. In particular, we evaluate the association between a nation's publicly run asset pools and its management practices, economic environment, political/legal structure, and practice regarding transparency/reporting/accountability. We also assess whether the size of future calls on resources, measured here by the aged dependency ratio, influences management practices. As nations become aware of promises made in the form of aged-care benefits, and as financial market upheaval provides these public investment pools with new opportunities and challenges, there will surely be stronger calls for better public fund investment performance.
1 The nature and variety of public investment pools
In this paper, we refer to public investment funds as those investible assets under the control of the public sector. In practice, these take three main forms: foreign exchange reserve funds held for stabilization purposes; SWFs accumulated from natural resource taxes or fiscal surpluses; and public pension funds built up either through an explicitly funded arrangement or the result of an excess of contributions over benefits during a demographic transition.
From the perspective of investment discretion, we place currency stabilization funds at one end of the spectrum. These assets must be liquid and are usually held in the form of short term paper or commodities. Moving along the spectrum, SWFs are government investment vehicles that manage their assets separately from official foreign exchange reserves. As a rule, their assets tend to be invested internationally, though sometimes they have been used for domestic investments (e.g. infrastructure). Some analysts are quite specific in what they refer to as SWFs: for example, Jen (Reference Jen2007) specifies that the pool must be managed by a government (sovereign entity); it must have high foreign currency exposure; it must have no explicit liabilities; it must have high-risk tolerance; and it must have a long investment horizon. In what follows, we take a broader view in encompassing investible publicly managed funds more generally.
A third type of publicly managed money consists of reserves built up for public pension purposes. Due to their long-term nature of their liabilities, these funds are typically less constrained by the need for immediate liquidity. Nevertheless, also because of their liability profile, the asset allocations in these funds are often weighted toward domestic currency assets as this is the currency of the pension promises. In particular, public pension funds are often concentrated in government bonds as a result of explicit policy or institutional tradition. For instance, the US Social Security Trust Fund of almost US$2 trillion is held entirely in special-issue nonnegotiable US government bonds.
Of the three types of public investment funds, SWFs seem to be growing most rapidly and have been permitted the greatest investment flexibility. Some SWFs were established to manage the intertemporal allocation of resources generated by the discovery and exploitation of a non-renewable natural resource, while others were set up to absorb government fiscal surpluses expected to be spent in the future. One way or another, both pension funds and SWFs have an intertemporal or even an inter-generational dimension in their objectives. We explore the form and function of each, in what follows.
1.1 Currency stabilization funds
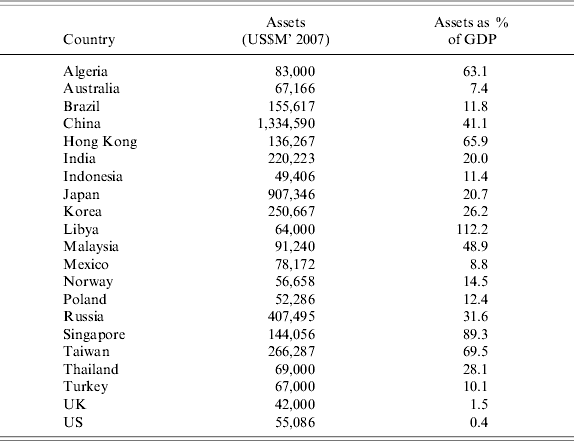
Though currency stabilization funds are not the central focus of the present paper, it is worth noting that they are the largest of the three categories of public investment funds. Available estimates place the total at around US$4.5 trillion (see Table 1). These have been rationalized by perhaps the oldest and most conventional explanation for government-held funds, namely the central monetary authority's desire to smooth currency fluctuations. In practice, it is often stated that three months' of reserves is a prudent cushion for exchange rate shocks (Rietveld and Pringle, Reference Gray, Johnson-Calari and Rietveld2007). In point of fact, many nations hold far more than the minimum level of assets required to manage currency stabilization, giving rise to more aggressive investments via SWFs. For example, in China, Russia, and Singapore, SWFs are responsible for both foreign exchange reserves and fiscal surpluses. An important stimulus behind the recent growth in SWFs has been the rising central bank reserves in rapidly growing countries, such as South Korea and Taiwan. Official reserves in such funds have expanded at US$600 billion per year over the past half-decade (Patelis, Reference Patelis2007), and reserves held for currency stabilization are expected to rise in the future. Nevertheless, as our present concern is with asset pools held for the long run, we do not further consider stabilization pools below.
List of currency stabilization funds by Nationality and size
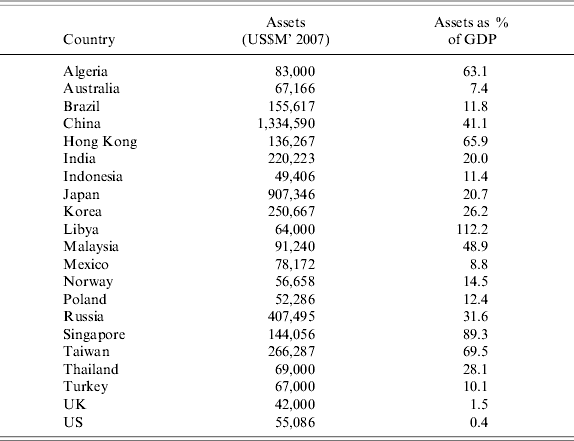
Sources: Merrill Lynch (Reference Merrill2007), Truman (Reference Truman2007a, Reference Trumanb), and World Bank (2008).
1.2 SWFs
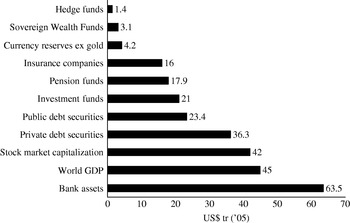
Despite substantial media and policymaker interest in SWFs of late, their precise magnitude is unknown for reasons to be discussed below. One estimate suggests they hold between US$1.5–3.1 trillion (Kern, Reference Kern2007; Patelis, Reference Patelis2007). Truman (Reference Truman2007a, Reference Trumanb) identifies around two dozen SWFs which he contends control around US$2 trillion in assets; he also separately lists foreign exchange reserves held by governments totalling about US$4 trillion and he includes Japan's approximately US$800 billion pension fund. Conservative estimates from Watson Wyatt Worldwide (2006, 2007) suggest that SWFs and public pensions together hold about US$4 trillion. Figure 1 provides a comparison of assets held by both public and private funds, and it indicates that currency stabilization and pension funds are far larger than SWFs, while SWFs in turn are larger than hedge funds in the global capital market.
Relative size of global assect pools Source: Kern (Reference Kern2007).

Many of the early SWFs were set up in countries holding natural resources (e.g. petroleum) which then became exposed to unpredictable revenues due to 0commodity price volatility. As an example, if a country's oil revenue represented 20% of its gross domestic product, then a one standard deviation shock to oil prices would create a revenue decrease equivalent to 6% of GDP (Hausmann and Rigobon, cited in Devlin and Titman, Reference Devlin and Sheridan2004). Chile's Economic and Social Stabilization Fund and the Venezuela Macroeconomic Stabilization Fund are examples of stabilization funds designed to offset such commodity price fluctuations. One way that governments might seek to handle commodity price risk could be to transfer risk to international capital markets so as to smooth economic performance over the relatively short term (Arrau and Claessens, Reference Arrau and Claessens1992). But the thinness of international insurance markets and apparent borrowing constraints are believed to make self-insurance a more natural choice for oil-producers to protect themselves against such price volatility. Indeed, self-insurance is recommended by Shabsigh and Ilahi (Reference Shabsigh and Nadeem2007), who contend that the benefits from public expenditures on lumpy investments when oil prices are high exceed the costs of shutting them down when oil prices are low. Commodity-exporting countries may self-insure against volatile commodity prices either by diversifying their export structure or by accumulating financial assets. Since diversifying export structure requires long-term structural reform and may reduce comparative advantage, financial asset accumulation can be a better choice given available alternatives.Footnote 2
There is some controversy about the economic rationale for such stabilization funds. For instance Davis et al. (Reference Davis, Rolando, James and Steven2001) find that fiscal stabilization funds may be less efficient than the sound fiscal policy in protecting against commodity price volatility. On the other hand, Shabsigh and Ilahi (Reference Shabsigh and Nadeem2007) analyze the effects of stabilization funds not only in terms of fiscal but also in terms of macroeconomic stability. The latter study concludes that inflation and price volatility prove to be lower when countries keep stabilization funds, and it weakly supports the proposition that commodity funds could be useful macroeconomic stabilizers. On the whole, the economics literature suggests that commodity funds will be small when motivated by commodity price fluctuations, since larger funds distort the domestic economy and can trigger suspicions about the fund's activities in international financial markets (Devlin and Titman, Reference Devlin and Sheridan2004).
A separate justification for SWFs is that they permit nations to set aside money for future generations derived from exploiting exhaustible resources today. For instance, the first commodity SWF was the oil fund established by the Kuwait Government in 1953; shortly thereafter the nation of Kiribati established a commodity fund in 1956 in order to manage revenues from phosphate deposits (Petelis, Reference Patelis2007; Truman, Reference Truman2007b). More recent examples include the state of Alaska which has put 2.5% of its oil royalties into its Alaska Fund. This practice is thought to improve intergenerational equity, smoothing the time path of revenues generated by nonrenewable resources (Olters, Reference Olters2007).
A theoretical grounding for this conclusion is offered by Gerlagh and Keyzer (Reference Gerlagh and Keyzer2001), who use a model of a government-run ‘trust fund’ that pays future generations claims for revenues generated by the natural resource. They construct a simple pure exchange overlapping generations (OLG) setup with an exhaustible resource. Exhaustibility is the irreversible degeneration of the resource, while the resource's ‘amenity value’ refers to the services provided by exploiting it. Inasmuch as natural resource extraction today reduces the resource's amenity value tomorrow, a regulatory mechanism is required to promote intergenerational equity. Agents maximize lifetime utility by selecting consumption levels of private and public goods, and aggregate welfare is the summation of individual lifetime utilities. The model considers three alternative regulatory scenarios. In the first scenario, there is zero extraction preventing the use of natural resources for all generations, akin to keeping an oil field idle. The second scenario, termed ‘grandfathering,’ leaves the ownership of the natural resource to the first generation, while future generations pay to mitigate pollution. This is equivalent to the distribution of all oil or mineral revenues to the first generation. The third scenario introduces a trust fund which entitles all generations to an equal claim over the natural resource. The authors consider the trust fund as an independent institution that can ensure future generations receive their claims; it is like a saving fund to keep some of the revenues generated by an exhaustible resource for future generations. A comparison of the three scenarios in terms of social welfare indicates that grandfathering improves efficiency compared with the zero extraction policy, but it favors the first generation over others. By comparison, establishing the trust fund improves welfare for subsequent generations.
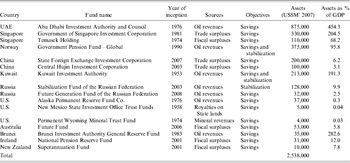
An alternative, though related, model of a SWF fund has been termed a financing fund, built up when a government has a budget surplus that it wishes to dedicate to investment instead of current spending. Some argue that this sort of investment pool is more likely to constitute true ‘saving’, as compared with a stabilization fund, because the latter tends to be paid for via borrowing (often implicitly; cf. Fasano, Reference Fasano2000). Of course, such financing funds are often seen as promoting intergenerational equity and fiscal stability; examples include the Norway Government Pension Fund-Global (GPFG), the Kuwait General Reserve Fund, and the Timor-Leste Petroleum Fund. Table 2 provides a listing of the major SWFs and their asset holdings, as well as their stated objectives and sources assembled from a variety of recent sources.
Sovereign Wealth Funds by name, year of inception, source, stated objective, and size
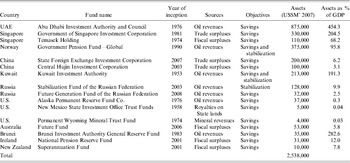
Sources: Das (Reference Das2007), Kern (Reference Kern2007), Truman (Reference Truman2008a, Reference Trumanb), Watson Wyatt Worldwide (2007), Ireland National Pension Reserve (2006), and World Bank (2008).
There is also much interest regarding SWF investments, a topic of particular salience of late as key global financial institutions receive massive inflows from important Asian funds including the Singaporean Government Investment Corporation and the Chinese Government Investment Fund. One reason these transactions have garnered so much public comment is that public investment pools have traditionally not revealed much about their holdings or governance structure. Such non-transparency has been justified on grounds that it preserves investment flexibility and protects business opportunities, but of course this also means that one cannot obtain much useful information regarding the majority of SWF funds' asset allocation patterns. Furthermore, inasmuch as most SWFs do not acknowledge specific liability profiles, they rarely do finance any specific time path of benefits or cash flows denominated in domestic currency.
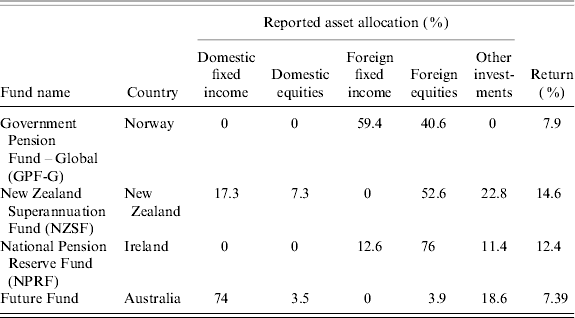
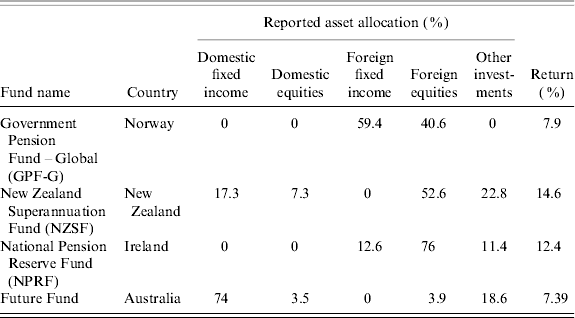
How SWF asset managers tend to invest their government-managed pools is difficult to ascertain. Some information for four of the more transparent funds is reported in Table 3. Here, we see that Norway's SWF has a 100% global portfolio with a roughly 40–60 split between equities and bonds. New Zealand's fund holds about half its assets in international equities; it holds no foreign bonds but has nearly a quarter of its portfolio in ‘other investments’, which may include domestic real estate. Ireland's SWF holds nearly 90% of its assets in international securities, mostly equities. Australia's very new public investment pool is unique in holding mainly domestic securities but this is changing as procedures are established for global diversification.
Reported asset allocation and return for four SWFs
Sources: Australia Future Fund (Reference Auerbach and Ronald2008), Norges Bank Investment Management (2006), New Zealand Superannuation Fund (2008), and Ireland National Pension Reserve Fund Commission (2006).
Notes: 1. In Norway, the GPF-G invests only in global markets. The other wealth fund of the Norwegian Government GPF-Norway invests only in local markets. The table reports the nominal return from the whole portfolio in 2006. The portfolio real return (adjusted for inflation) in 2006 was 5.65%. Nominal returns from equities and fixed income instruments in 2006 were 17.04 and 1.93%, respectively. The annualized nominal return from the portfolio between 1997 and 2006 was 6.49%. The actual asset allocation refers to the situation at the end of 2006.
2. In New Zealand, the NZSF annual reports do not separately report the portfolio share of domestic and foreign fixed income securities, and hence, the portfolio share of domestic bonds (both in benchmark and actual assert allocation cases) includes the portfolio share of the foreign bonds. The remainder of the NZSF portfolio is held in other asset classes such as local and global property, commodities, and private markets. The table reports the nominal return (adjusted for fees but not for inflation) between June 2006 and June 2007. The annualized nominal return from the whole portfolio was 14.81% between 2003 and 2007. The actual asset allocation refers to end June 2006.
3. In Ireland, the NPRF does not hold Irish government bonds. The portfolio is heavy in alternative asset classes such as property and commodity investments. Foreign bonds consist of only Eurozone bonds and Eurozone equities (including Irish equities); the latter total about 45% of the portfolio. Since Ireland is a member of the European Union, one might consider Eurozone bonds and equities as domestic for Ireland. The table presents the 2006 nominal rate of return; annualized it was 6.5%. The asset allocation refers to end 2006.
4. Australia's Future Fund investment program started in June 2007; the benchmark portfolio has not yet been declared and to date the majority of the portfolio has been kept in cash (the table reports the portfolio share of the cash in the cell of domestic fixed income securities) and Telstra shares (this is an Australian telecommunication company). The portfolio share of Telstra Corporation, which is 18.6%, is not reported in the table. The nominal return from the portfolio from June 2006 to June 2007 is reported in the table. The real return (the nominal return after the price inflation adjustment) is 5.29 in the same period. Actual asset allocation is as of June 2007.
1.3 Sovereign pension funds
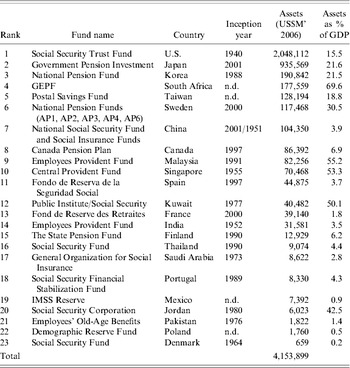
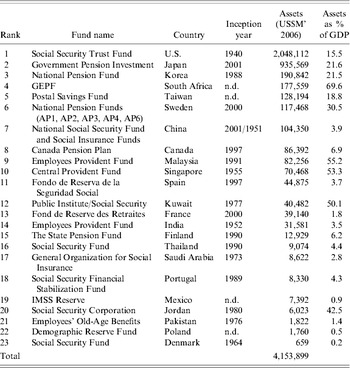
The third category of government-controlled asset pools, we scrutinize here, consists of the reserves held by government-run public pension funds where, in principle at least, the assets that are earmarked for the payment of current and future retiree benefits. These reserves might be generated through an intentionally funded pension scheme, or they can alternatively be built up as ‘transitional’ reserves generated by population aging where contributions from a large cohort of workers result in a temporary flow of funds in excess of current benefits payouts. A number of countries have well-funded national pension schemes, and several of them have accumulated substantial assets associated in their future fund accounts. According to Watson Wyatt Worldwide (2007), public pension funds around the world are 1.7 times as large as the total estimated size of SWFs. Iglesias and Palacios (Reference Iglesias and Palacios2000) document most of the publicly mandated pension funds and the amount of assets held by these funds as a percentage of GDP. Table 4 lists the major sovereign pension funds and their asset holdings.
Publicly managed pension asset pools by size
Sources: OECD (2007), Canada Pension Plan Investment Board (2008), Watson Wyatt Worldwide (2006), World Bank (2008), India Employees' Provident Fund Organisation (2008), Singapore Central Provident Fund (2008), Malaysia Employees' Provident Fund (2008), and Kuwait International Social Security Review (1998).
Note: n.d.=no date.
What usually characterizes public pensions is that contributions and payouts tend to be linked through some implicit or explicit contractual arrangement to pay old-age benefits.Footnote 3 In such a circumstance, a public pension fund may build up assets to cover future pension liabilities without necessarily changing the fundamental tax and benefit structure of a pay-as-you-go (PAYG) system. Many economists see a pure PAYG system as welfare-reducing, since it tends to decrease an economy's capital stock by taxing the young generation with a high propensity to save, so as to pay retiree pensions to those with a high propensity to consume (Kumru and Thanopoulos, Reference Kumru and Thanopoulos2008). By contrast, a funded public pension can invest excess contributions for future generations which can prove useful in the face of demographic aging (Abel, Reference Abel, Campbell and Feldstein2001). Building up ‘future funds’ in this context can mitigate the negative welfare effects of a pure PAYG system, though they can also increase intergenerational inequality in a closed economy by benefiting one cohort over another (Lucas, Reference Lucas2001; Oshio, Reference Oshio2004; Auerbach and Lee, Reference Auerbach and Ronald2008). In other words, saving excess contributions in a future fund may still be less desirable from a welfare standpoint, to lowering taxes on younger generations.
Recognizing that public pension pools of assets do exist in many nations, it is of interest to examine how such schemes invest their assets. Economists look at this issue in various ways. Some use actuarial or asset liability management (ALM) perspectives to link fund assets and liabilities, while others employ a general equilibrium framework to consider the effects of an investment change on the whole economy. For instance, MaCurdy and Shoven (Reference MaCurdy, John, Campbell and Feldstein2001) adopt an actuarial framework to explore the consequences of an asset reallocation from bonds to stocks in the US Social Security Trust Fund. Specifically they examine whether selling government bonds and buying corporate stocks would improve the finances of the mainly PAYGO old-age system. The conclude, using historical return data, that such a reallocation would carry significant risk to participants (i.e. the relocation might yield lower returns than expected). Using a general equilibrium framework, Abel (Reference Abel, Campbell and Feldstein2001) analyzes the effects of asset reallocation in Social Security on the equilibrium equity premium and the equilibrium growth rate of the capital stock. He concludes that when a national pension fund moves into equities, the expected income of the trust fund will rise but the welfare consequences are ambiguous.Footnote 4 Similarly, Bohn (Reference Bohn1999, Reference Bohn2002) shows that welfare effects of the asset reallocation depend largely on the specific pattern of macroeconomic shocks, the risk characteristics of equities, and individual preferences. In general, it is not assured that intergenerational equity results from increasing assets held by the public pension.Footnote 5
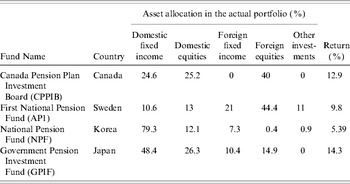
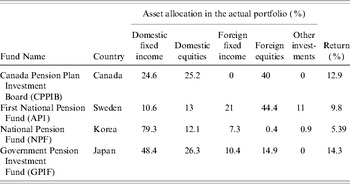
Various empirical studies have analyzed publicly managed pension fund performance and governance structures (Iglesias and Palacios, Reference Iglesias and Palacios2000; Carmichael and Palacios, 2003; Hustead and Mitchell, Reference Hustead, Mitchell, Mitchell and Hustead2000), and there are also several empirical studies analyzing the investment performance of public pension funds (Mitchell and Hsin, Reference Mitchell, Ping-Lung, Shoven and Schieber1997a, Reference Mitchell, Ping-Lung and SedSalvadorb; Mitchell and Smith, Reference Mitchell and Robert1994; Useem and Mitchell, Reference Useem and Mitchell2000). Nonetheless, relatively little has been written on how one might link public sector pension investments to the specific structure of pension obligations that the funds face. Table 5 provides a comparison of the asset allocations of four publicly held pension funds that do report their data in a public manner. The first two of these, the Canadian and Swedish plans, are essentially funded add-ons to national social security programs; this drives their relatively heavy portfolio concentration in foreign equities. The Korean and Japanese funds, by contrast, represent a demographically driven temporary accumulation of contributions held mainly in domestic securities. This latter pattern is consistent with the fact that these funds' liabilities are also denominated in domestic currencies though it is unclear whether a formal portfolio optimization reflecting this aspect of the liability profile has been undertaken. In the case of Japan, publicly held pension resources amount to about 30% of GDP, a substantial amount responsive to the rapid aging of the Japanese population. Yet the fund falls far short of what is needed to pay future liabilities: KNH (Employees' Pension System) liabilities of 550 trillion yen are several times larger than the government's old-age system reserve fund of around 179 trillion yen (Takayama, Reference Takayama, Holzmann and Palmer2006). Also, estimates suggest that the future shortfall might be substantially reduced through superior investment of these resources.Footnote 6
Reported asset allocation and return for four publicly managed pension funds
Sources: Canada Pension Plan Investment Board (2008) ; Sweden First AP Fund (Reference Sweden2008) ; Korea National Pension Fund (2008) ; Japan Government Pension Investment Fund (2008).
Notes: 1. For Canada, the table shows the nominal rate of return at the end of fiscal 2007. The annualized nominal rate of return between 2004 and 2007 was 13.6%. The actual asset allocation refers to the situation in 2007.
2. For Sweden, the table shows nominal returns in 2006. The annualized nominal return between 2001 and 2006 was 5.3%. The actual asset allocation refers to 2006. The asset holdings of the other AP funds (AP2, AP3, and AP4) are pretty much same as those of AP1. Fund AP6 is very small and invests only in small and medium Swedish companies; it is excluded from the table.
3. For Korea, the benchmark portfolio was not available; the table shows nominal returns in 2005. The annualized nominal return between 2003 and 2005 was 7.27. The actual asset allocation refers to 2005.
4. For Japan, the table indicates nominal returns in 2005. The annualized nominal return between 2001 and 2005 was 4.1. Actual asset allocation refers to 2007.
1.3.1 Public pension fund asset/liability considerations
Many analysts who work on private-sector pensions have concluded that some form of asset–liability joint management works best if one links investment policy and payout promises (cf. Blake, Reference Blake2006). It is striking, therefore, that the vast majority of discussions of SWFs as well as publicly managed pensions are silent about the need to link portfolio management goals to any particular obligation stream. One recent study by Maurer et al. (Reference Maurer, Mitchell, Ralph, Broeders, Eijffinger and Houben2008) investigates how a tax-sponsored public pension fund might invest pension contributions to relieve government budgets taking into account the risk and rewards from capital market diversification. While the analysis is a case study of a German civil servant pension, the more general contribution of the work is that it explicitly models the pension fund manager's appetite for risk and reward.
An outcome of that study is that it provides recommendations for portfolio investments which control the expected economic costs of providing the promised pensions, while at the same time controlling investment risk. Both the expectation and the Conditional Value-at-Risk of economic pension costs are simulated using a stochastic simulation process for pension plan assets, allowing the authors to simultaneously set both the optimal contribution rate and the optimal capital market allocation. Of key importance is the fact that the plan sponsor may occasionally be forced to make supplementary contributions, which, as in the real world, brings with it a penalty. Conversely, the authors also prohibit the public pension from being used as a hedge fund, so excess assets are withdrawn according to a pre-set rule. In the German case, the authors demonstrate that the optimal pension fund investment strategy given a 20% of salary contribution rate requires investing the public fund 30% equities and 70% in bonds.Footnote 7
Naturally specific portfolio allocations must vary with capital market parameters, but the general approach is useful in making explicit a public fund manager's performance objectives when developing fund investment policies. Furthermore, given the nature of publicly managed funds, when managers make their portfolio allocation decisions, the objective function must surely include intergenerational considerations (Weinberger and Golub, Reference Weinberger, Bennett, Johnson-Calari and Rietveld2007).Footnote 8 Just as in the case of corporate pensions, this will require developing dynamic multi-period simulation models which take into account both the risks and returns associated with risky investment including Value-at-Risk models.Footnote 9
2 Good management practice in public investment funds
The literature on what constitutes good management in public investment funds has thus far focused primarily on public sector pensions rather than publicly managed asset pools more generally. One reason is that, until fairly recently, public pensions were the main form of publicly managed funds. For instance, Palacios (Reference Palacios2002) estimated that such reserves amounted to around one-quarter of world GDP, mainly held in the US. Another reason is that there is a paucity of data on SWFs, which we will discuss in greater detail below. In any event, we will argue in this section that many of the same governance principles apply to all forms of publicly managed investment pools (Impavido, Reference Impavido2005).
Management practice in the public sector context can be described using three sets of standards initially proposed by the World Bank: Governance, Accountability, and Investment practices, referred to here as the GAI scores. Of these three components, governance refers to ‘the systems and processes by which [an entity] manages its affairs with the objective of maximizing the welfare of and resolving the conflicts of interest among its stakeholders’ (Carmichael and Palacios, 2003: p. 7). Accountability refers to the process by which governance outcomes and decisions are reported and disclosed to stakeholders. For instance, a public pool invested in this way would provide access to information about funding shortfalls, conduct publicly reported audits, and disclose consultancies and contractual arrangements. Investment practices refer to the process of developing investment profiles that balance risk and return, taking into account liabilities where these have been made explicit. Naturally in the case of pension reserves, benefit promises constitute the liability profile as noted above.
The literature on corporate governance serves as a useful point of departure in framing the discussion of public fund management, beginning with Jensen and Meckling (Reference Kauffmann, Aart and Massimo1976) and recently surveyed by Shleifer and Vishny (Reference Schleifer and Vishny1997). Generally speaking, the problem is cast in a principal–agent framework where stakeholders must be protected against possible strategic actions by managers who may act in their own best interest unless they are constrained. Empirical evidence has demonstrated the key role of good management practices in corporate performance: for example, Gompers et al. (Reference Gompers, Ishii and Andrew2003), using a US database of some 1500 firms through the 1990s, show that firms with stronger shareholder rights have higher market value, higher profits, and higher sales growth, as well as lower capital expenditure and fewer corporate acquisitions. In the emerging market context, Klapper and Love (Reference Klapper and Inessa2004) analyze firm level data across 14 emerging markets and find that better corporate governance is associated with better operating performance and market valuation. Importantly in the present context, they also find that governance provisions matter more in countries having weak legal environments.
In the corporate sector, controls to handle the principal–agent conflict revolve around clarity of objective, appropriate rules about conflict of interest, clear incentives/accountability for each player, and disclosure of decisions and performance. By contrast in the public sector, the challenge is that there is frequently no agreed-on metric by which agents (taxpayers and public sector employees) can readily measure the long-term performance of the principals acting on their behalf (policymakers). However, if fund manager objectives are clear, corporate-type governance, accounting, and investment principles can still be applied and will go a long way in providing adequate information about performance. On the other hand, experience shows that government involvement in the financial sector is also susceptible to conflicts of interest and therefore, from a governance perspective, in need of special attention. Such conflicts can arise from the extensive participation of government in financial systems through its role as regulator and owner of financial institutions; as a (non-atomistic) market participant and fiduciary agent; and through direct interventions in the operations of the market.
2.1 Public pension plan management
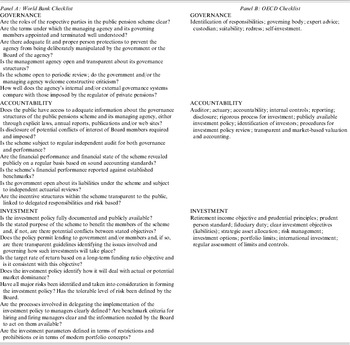
To illustrate how good management practices apply to publicly managed asset pools, Panel A of Table 6 reports a World Bank-developed checklist for GAI criteria pertinent to public pension managers (Carmichael and Palacios, 2003). The governance questions are designed to avoid undisclosed conflicts of interest, ensure autonomy from political intervention, secure staff competence, and in general make the criteria comparable with private sector rules. The accountability scoresheet focuses on information communication, information credibility, and process transparency. And the investment criteria focus on potential conflict of interest issues, along with the dilemmas created by market dominance in particular sectors, or overall in a country. It is also worth nothing that, though this GAI checklist was developed specifically for public pension funds, it makes no explicit mention of the public plan's liability profile.Footnote 10
International guidelines for public pension fund management

Source: Carmichael and Palacios (2003). Source: OECD (2005).
An alternative set of guidelines devised by the OECD (2005, 2006, 2007) for pension managers is also summarized in Panel B of Table 6, reorganized here under our three GAI headings to emphasize the commonalities and differences. Clearly defined responsibilities for various members of management, suitability of personnel, and control over conflict of interest, appear on both lists, while the OECD offers some useful additional performance benchmarks that do not appear in the World Bank guidelines. One relates to redress, or what happens when promises made are not kept. A second pertains to ‘self-investment’, which the OECD sees as contrary to sensible diversification of investment risk.Footnote 11 Third, the OECD explicitly recognizes the importance of a fund's liability profile in developing investment strategies and fund objectives. In this sense, these guidelines bring together the purpose and conduct of the fund, more in keeping with the advice offered in the corporate sector.Footnote 12
2.2 SWF management principles
The need for strong public sector governance in SWFs arises from the same sources that call for strong corporate governance (Carmichael, Reference Carmichael, Litan, Pomerleano and Sunderajan2002). Of particular note is recent research by the Peterson Institute (PI) on public fund management which proposes a ‘scoreboard’ for comparing management practices of SWFs (Truman, Reference Truman2008a, Reference Trumanb). This approach identifies four categories of SWF management practice focusing on fund: (1) structure, (2) governance, (3) transparency/accountability, and (4) behavior. The structure and transparency/accountability categories are further divided into subcategories, such that in total, there is a total of 33 yes/no questions where either a 1, 0.50, or 0.75. Using this formulation the author ranks SWFs across 31 countries. This tally shows that New Zealand's Superannuation Fund tops the list followed by Alaska's Permanent Fund, while at the bottom are the Abu Dhabi Investment Authority and Corporation of UAE and the Qatar Investment Authority of Qatar.
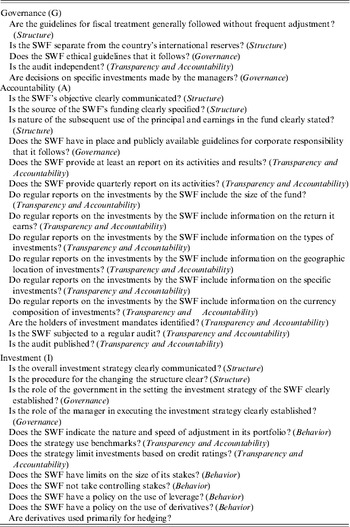
This approach offers a useful way to systematize thinking about this relatively new corpus of public sector activity (a full list of variables and funds by name appears in Appendices I and II). To elaborate somewhat on how the scoring works, under the heading structure, the rubric identifies SWF clarity of objective, source of funding, and investment strategy. Topics addressed cover communication of the fund's objective, the specification of both sources and uses of funds, whether there is frequent intervention in source and use (presumably an indicator of multiple or expedient objectives in fund use), and the fund's relationship with the broader government budget. Clarity of investment strategy and separation from international reserves are also considered. From these elements, the picture that emerges has a ‘good’ SWF being the public investment fund that has long-term objectives other than strictly currency stabilization, explicitly or implicitly linked to some intertemporal allocation and/or distributional objective. Relating this to the elements of good management we have already identified, structure in the PI terminology encompasses some elements of governance along with investment strategy. The question of the fund's objective, and its scoring, is subject to caveat. This is because most funds examined in the PI study scored positively on this, but there was no attempt to link the stated objective with any other practice. Therefore the tally neither gives credit to a fund that explicitly lists its objectives, but it does not then additionally credit funds where other aspects of management practice support the stated objective, nor does it penalize funds where they do not.
In the PI formulation, the second heading, governance, speaks to the independence of the fund's investment strategy and the independence of the role of manager in executing investment strategy. Also under these rubric indicators for the existence of corporate responsibility and ethical guidelines are included, as well as indicators of whether the policies are publicly announced and followed. The notion of governance falls somewhat short of what might be expected given the corporate governance literature. For instance, there is no inquiry about the role of the governing board, or about the incentives available to operational roles in the organization.
The third major category proposed in the PI index pertains to how the SWF behaves in terms of transparency/accountability. Matters considered include reporting on activities and performance, public disclosure of investment portfolios, geographic location of direct investments, specific investments, currency of investments, and the identity of investment agents. The category also includes information about audits, regularity, public availability, and independence. The final PI category, behavior, asks about the nature and speed of adjustment of the SWF portfolio, and this is the least clearly explained. It should be noted that of the 33 PI questions, 14 fall under the transparency heading, and several of the questions listed under the structure heading could also plausibly be placed there as well. While this is an important component of overall fund management, the fact that only five items are included under the governance heading is rather arbitrary and most likely incomplete.
Below we will use these scoreboard measures as a way to begin to link SWF performance measures to factors that might drive these outcomes. It must be noted again here that the PI scoreboard is again silent on the links between management of assets and liabilities, which could be deleterious to fund performance inasmuch as investment policy is likely to vary depending on the objectives of the funds. This is generally because most SWFs funds do not explicitly state their objectives, whereas for public pensions, the benefit streams that consist of the funds' liabilities can be (more or less) valued cleanly. Even then, it is often the case that pension system liabilities tend not to be well integrated into investment policy.
3 Do public management practices affect performance?
Next we turn to a review of studies seeking to show how public fund management practices shape key outcomes. Inasmuch as most of the work on management practices focuses on corporate performance, we begin with an overview of this topic, and then we turn to a discussion of what is known about management of public sector funds.
Empirical research tying corporate management practices to firm-level outcomes is extensive. Much of the research through the mid-1990s is reviewed by Schleifer and Vishny (Reference Schleifer and Vishny1997); since then, additional studies have emerged in response to the 2002 Sarbanes–Oxley Act (SOX) requiring the US public companies to institute a range of procedural and structural reforms intended to enhance stakeholder confidence in the post-Enron era. The range of outcomes addressed in this literature is vast, including the corporation's return on assets, market valuation, stock returns, success at making acquisitions, and Tobin's Q (or the firm's market value of assets as a proportion of the replacement value of its assets), among others.Footnote 13 The measures of ‘good managerial practice’ used by empirical analysts are several, and include most prominently key metrics of corporate governance. This, as per Schliefer and Vishny (Reference Scheherazade and James1997: p. 737), refers to the ‘ways in which suppliers of finance to corporations assure themselves of getting a return’. In particular, the literature emphasizes how investors may gain power through legal protection (e.g. via protection of minority rights and limits on managerial self-dealing), and also via large investor blocks which control managerial behavior directly. Accordingly, the literature has found important relationships between countries' legal efficacy scores, which indicate whether an enterprise is founded on common or civil law, and variables indicative of shareholder control rights. Many studies also examine policies regarding transparency and accountability, on the argument that rules enhancing financial reporting are likely to result in better protection for the investor.
The literature on public enterprise management builds on this private sector foundation in seeking to craft indicators of good-quality management and relates them to successful public firm outcomes. One problem is that public entities often do not conform to private-sector accounting and reporting standards, and another is that output measures used in the private sector frequently have no counterpart in the public sector. Nevertheless analysts have found it natural to use for public sector entities the same principal-agent framework mentioned above and popularized in the corporate world. In this context, the taxpayer and other members of the public represent the principals, whereas the agents are the government managers guiding the public enterprise (cf. Ambachtsheer, Reference Ambachtsheer2007b; Coronado et al., Reference Coronado, Engen and Brian2003). Thus in theory it would be feasible to evaluate whether particular management practices can shape outcomes of public sector enterprises, though with some adaptations depending on the type of public firm in question. In the specific case of public entities of key interest here – namely public pension plans and SWFs – the conventional measures of corporate outcomes, such as shareholder wealth, firm profitability, and market share do not readily apply. For this reason, analysts have turned to other metrics to determine whether public sector enterprise performance is enhanced as a result of particular management practices. For instance one outcome of interest might be investment-related. In the simplest case, for instance, public pension funds which hold some assets can report their target annual return (e.g. 3.2% in the case of the Japanese GPIF). More elaborately perhaps, some public plan managers may indicate their risk-adjusted returns vis-a-vis some benchmark. Relatively few focus on the dynamic path of liabilities as well as assets, about which we say more below.
The few existing studies linking public pension plan investment strategies and investment returns tend to show that these are often influenced by governance factors, such as board composition (Mitchell and Hsin, Reference Mitchell, Ping-Lung, Shoven and Schieber1997a, Reference Mitchell, Ping-Lung and SedSalvadorb). For instance, having more retirees tends to lower performance due to greater weighting toward a fixed income portfolio. Again in public pensions, Useem and Mitchell (Reference Useem and Mitchell2000) show that governance variables account for over 20% of the cross-pension plan variation in investment strategies, which in turn are positively associated with subsequent investment return performance on the pension fund assets. Yang and Mitchell (Reference Yang, Mitchell, John and John2008) examine how pension plans' funded status (or the ratio of plan assets to liabilities) and investment returns respond to measures of pension board composition, management practice, reporting practice, and investment practice. They show that many pension boards have political appointees as well as active and/or retired workers on the roster, both of which can be problematic when these board members may not be particularly financially expert.
Another issue is that sometimes public entity trustees have used fund assets to further their own (or their party's) political/social objectives. Hsin and Mitchell (Reference Hsin, Mitchell, Arrau and Schmidt-Hebbel1997) find that several pension management factors are statistically significant and economically important. For instance, ceteris paribus, having more plan participants on the pension board, whether retired or active, reduces plan funding levels and the point estimates imply that adding an additional active member reduced stock funding by 0.7 percentage points, while adding one more retired member decreases funding by 1.7 percentage points. Further, investment yields on the public pension plan assets appear significantly lower when retiree representation increases, perhaps due to lack of investment expertise. Enhanced pension reporting, including making annual reports on financial, actuarial, statistical, and investment information to stakeholders, can improve returns by 2.1 percentage points annually.
Research on public pensions and mutual funds by Ambachtsheer (Reference Ambachtsheer2007a, Reference Ambachtsheerb) uses as the dependent variable ‘net value added’ or the fund's gross investment return minus its benchmark return and the fund's total expenses. This outcome proves statistically related to a lengthy list of 45 measures of governance quality obtained by interviewing public fund CEOs. Ambachtsheer (Reference Ambachtsheer, Olivia and Robert2005: pp. 196–197) reports that of the entire lengthy list of indicators, six governance-related and five management-related measures in his CEO survey are significant. In that author's words, ‘statistically significant governance statements (are) … related mainly to effective fiduciary behavior and selection processes, clarity in delegation of authority, and a high level of trust between the governing and managing fiduciaries. The statistically significant management statements (are) related mainly to clear strategic positioning and to the effective development and execution of the fund's strategic plan’.
3.1 How can fund objectives be incorporated?
The studies of public funds mentioned above focus primarily on asset-related outcomes, such as returns and funding patterns.Footnote 14 Yet as we have argued above, one should also consider integrating the asset/investment management effort with the evolution of plan liabilities. For instance, in the case of a public pension system, the goal is generally agreed to ensure that retiree benefits can be paid without large and unexpected increases in the cost of maintaining the solvency of the system. Nevertheless, as Ambachtsheer (Reference Ambachtsheer, Olivia and Robert2005: p. 198) emphasizes, ‘fund managers of late have made no measurable effort to take into account the financial characteristics of their liabilities when structuring their fund policy portfolios’. Indeed, a reason that managers may have found it difficult to do so is that it may be troublesome to convert the broad objective of ‘paying pension benefits’ into specific fund management rules and performance criteria. Sometimes the liability path will be difficult to model and simulate. Or public pension plan investment policy may be set independently of liability paths on purpose; for instance this is the case for the US Social Security Trust Fund, which is permitted to hold only special issue government bonds.Footnote 15 Still an additional reason that ALM is not undertaken in a concerted, coherent form may be because policymakers may not wish to make explicit what their risk appetite is in terms of shortfalls and surpluses.
Nevertheless, in the last several decades, great strides have been made in analysts' ability to model and solve for ways to implement asset–liability models, and this could be even more useful in the future. Of course, to select an appropriate investment strategy in the face of these stochastic liability patterns, policymakers must make explicit their risk budgets, or how they balance the unavoidable and dynamic tensions between investment returns, benefit payments, and contribution requirements. Such risk budgets must take into account both the uncertainty of system revenues, including investment returns earned on pension fund assets, and stochastic pension liabilities as discussed above. Recent discussion on these points includes Moore (Reference Moore2007) and Boender et al. (Reference Boender, van Aaslst, Heernserk, William and John2001), the latter of whom implement this approach for Dutch pension funds. Maurer et al. (Reference Maurer, Mitchell, Ralph, Broeders, Eijffinger and Houben2008) examine public sector employee pensions in Germany. In general, these evaluations must specify how plan outlays will depend on projections of earnings, patterns of labor market attachment, retirement trends, longevity forecasts, and many other factors.Footnote 16 In turn, investment portfolios can be optimized to take liability variations into the decision of how to structure the asset mix given capital market trends. Other examples of ALM in the public pension fund arena include the work of Bogentoft et al. (Reference Bogentoft, Romeijn and Uryasev2001) and several of the excellent papers in Ziemba and Mulvey (Reference Ziemba and Mulvey2001).
One of the most clearly exposited papers in this vein is by Merton (Reference Merton, William and John2001), who implements this approach in the case of a university endowment fund. His model is relevant to the present research as it recognizes that such entities draw not only on their endowment pools but may also count on other cash flows including contributions from donors, tuition and other business income, and grants. He makes the crucial point that these revenue flows are also volatile and so should be modeled as part of the plan's resources. This approach has a logical parallel in the case of public pension funds and SWFs which may receive contributions from a variety of sources, while they can also draw down their investment pools to meet specific obligations. Insofar as some of the contribution sources have the same risk characteristics as equities, for instance, the entity may decide to invest less in stock. In its simplest form, the Board's preference structure for the university is taken to be a lifetime utility function of the form:
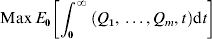
where Q j(t) is the quantity of the preferred activity j=1,…,m (e.g. education, research, etc) in which the firm engages at time t and the utility function is well behaved. The entity is assumed to live indefinitely, making the upper limit on the integral infinity. (Other more complex formulations can be permitted). The remainder of the model specifies cost functions for producing the firm's outputs, and dynamics for cash flows for contributions and investment earnings. Over time the university selects a vector of activities Q, and a portfolio allocation in its endowment fund, to achieve maximum utility (1). Similarly, a pension fund can also be modeled as seeking to pay benefits, subject to constraints over revenue, investment patterns, and perhaps some risk aversion regarding extreme cash shortfalls that would otherwise require massive transfusions of new cash. To the extent that a university (in Merton's case) or a pension fund (in our case) faces different risk profiles for its revenue streams and different cost profiles, this will produce different optimal investment strategies for the endowment pools.
The important lesson that emerges from these analyses is that good management practice has a material positive impact on corporate performance, but this cannot yet be shown for publicly managed funds in view of the dearth of data on this topic.Footnote 17 Furthermore, most studies of public fund management have emphasized only financial or actuarial outcomes such as net returns, funding, or investment expenses. Only a handful have constructed clearly formulated models that link fund contributions and investments to measures of anticipated future benefits that these funds seek to deliver. So the challenge is to ‘determine a jointly optimal dynamic strategy for the asset and liability instruments which balances the interests and requirements of all agents involved’ (Boender et al., Reference Boender, van Aaslst, Heernserk, William and John2001: p. 564). In particular, public fund managers must take into account the ability of the fund to meet other objectives (e.g. not raising taxes too sharply on any given generation in the event of a revenue shortfall).
4 Empirical analysis of determinants of public investment fund management
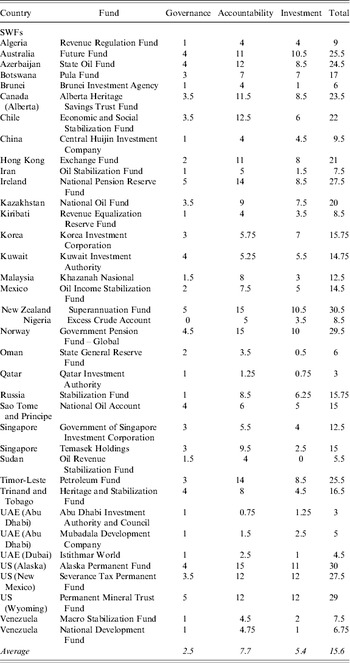
Next we turn to a brief empirical examination of key factors associated with variation in observed SWF management attributes. We focus on the measures of GAI described above and explore what might influence how these asset pools function along these dimensions. A first implementation step requires us to group the multiplicity of scores reported on SWFs in the PI scoreboard into our three preferred headings. We do so by computing the G, A, and I scores by summing the subcomponents for each of the SWFs, and then we add these to form an aggregate GAI index.Footnote 18 Next, we link the GAI indicator using multivariate regression models to factors descriptive of the national environments in which these publicly managed funds are found, following the empirical strategy outlined in the corporate governance literature described above. Our particular focus is on indicators of country-specific governance and political participation, human capital and the business environment, and demographic controls to be described in more detail below. We report OLS regression coefficients for the aggregate GAI scores using the following framework:

The national governance and political participation variables employed in this formulation are derived from the World Bank Governance Indicators (WBGI; see Kauffman et al., Reference Kauffmann, Aart and Massimo2007) which include six factors relating to different aspects of governance: Voice and Accountability, Political Stability, Government Effectiveness, Regulatory Quality, Rule of Law, and Control of Corruption. Country-specific measures of the quality of human capital and the efficacy of the business environment are taken from World Economic Forum indices of global competitiveness (GCI; see Sala-i-Martin et al., Reference Sala-i-Martin, Blanke, Hanouz, Geiger, Mia and Paua2007). The GCI indicators focus on economic performance including macroeconomic stability, as well as education and business sophistication. To render the many World Bank and GCI indices more tractable, we use Principal Component Analysis (Hamilton, Reference Hamilton2006) to combine them into a Modified World Bank Governance Index (MWBGI) and Modified Global Competitive Index (MGCI). In alternative models, we substitute some of the underlying factors indicative of the political environment for the overall indexes; these include ‘Voice and Accountability’ measuring participation in government and freedom of expression, and ‘Government Effectiveness’, which measures civil service quality. The rationale is that freedom of expression should enhance all dimensions of the GAI score because of the greater risk of public exposure for incompetence or fraud. Similarly, high quality public service should be able to deliver better public sector management. Market efficiency can be proxied by a business sophistication metric, on the grounds that this would be positively associated with public investment fund accountability. A nation's legal environment can be represented by regulatory quality (by which we mean policies that enhance private sector performance) or rule of law (by which we mean a strong judicial system), following Klapper and Love (Reference Klapper and Inessa2004) and Shleifer and Vishny (Reference Schleifer and Vishny1997) who show that better legal systems help protect shareholder rights.
To this reasonably conventional list of control variables we add a measure of a nation's old-age dependency ratio, to test whether the performance indicators are related to intertemporal objectives even if these are implied rather than explicit. In a few cases, some countries had multiple SWFs with differing GAI scores. To handle this, we compute an asset-weighted average of the GAI scores to come up with a single combined fund metric for that country. Also a few small countries had exceptionally high GAI scores along with very low GCI and Governance scores.Footnote 19 Inasmuch as these developing/emerging market funds are probably influenced by international organizations' views of good fund management practice, we control on the log of SWF assets to reflect this diversity. Variable definitions and descriptive statistics on our empirical variables are reported in Appendix III.
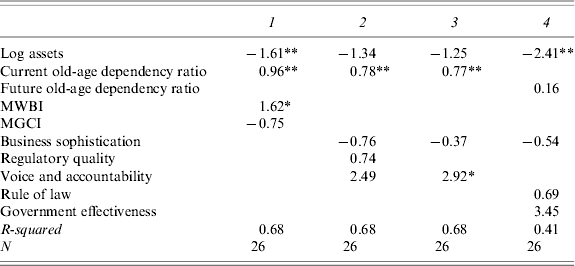
The multivariate coefficient estimates for the GAI model appear in Table 7. As there are only 26 SWFs for which full data are available, we are parsimonious in selecting which explanatory variables to include. We see that larger funds tend to score lower on the GAI ranking when statistically significant. We also see that better governance is associated with a higher old-age dependency ratio in columns 1–3, suggesting that when the elderly grow relatively more numerous, their voice tends to be reflected in larger economic claims driving better SWF management. Curiously, however, only the current dependency ratio is statistically significant, while projected old-age ratios tend not to be.
Empirical estimates of aggregate GAI scores
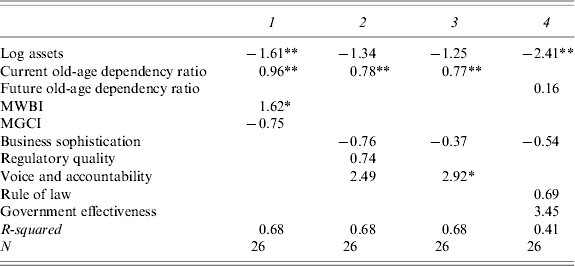
Note: * Significant at 10% level; **significant at 5% level. For data sources see Appendices I and II, and for variable definitions see Appendix III.
Turning next to the governance and economic variables, column 1 indicates that the World Bank governance index is positive and significant at only the 10% level, while the GCI index is not significant and negative. Columns 2–4 further explore the relationship between relevant national characteristics and the GAI scores, where we see not much statistical association between good SWF governance and business sophistication, regulatory quality, and rule of law. Only the Voice and Accountability factor is positively associated with good fund governance.
Our results thus differ from one recent study on private pension funds by Servaes and Khorana (Reference Servaes and Ajay2007), who argue that more efficient mutual funds are found in countries with better-functioning judicial systems and more educated populations. Overall we find little evidence that national characteristics strongly shape the GAI structures of national SWFs.
5 Conclusions
We have examined management practices for publicly managed asset pools, seeking to draw lessons about how these institutions might better manage their funds. Our review of the main types of public investment pools having long-term objectives indicates that pension fund and SWFs share many commonalities with regard to their objectives and rationales. Nevertheless, empirical evidence on these outcomes for publicly managed asset pools is scarce, and what there is tends to be silent on the structure of liabilities implicitly or explicitly associated with these funds. Building on prior studies, we devise performance criteria regarding fund GAI policies. When we relate these GAI measures for SWFs to a range of national governance and political participation indicators, measures of human capital and business environment, and demographic controls, we find that the current aged dependency ratio appears to be a consistently important explanatory factor associated with good management. This suggests that nations subject to the most pressure from population ageing tend to be more careful with SWF governance.
Policy analysts would benefit from better understanding of what constitutes best practice for the management of the substantial global reserves held in SWFs and public pensions. To this end, information is needed linking performance indicators to goals, presumably including good measures of intertemporal and intergenerational objectives. Unfortunately, as SWFs have grown, they appear to be demonstrating an increasing risk appetite with little transparency, and virtually no clarity of objectives. As a result, their growth is spurring debate in recipient countries and among financial market intermediaries, along with calls for regulatory reform in the international sphere and a move toward financial protectionism or even the explicit prohibition of SWF investments. For instance, the European Commission is drafting a plan to prohibit non-European Union members from investing in the European energy business. German Chancellor Angela Merkel has mentioned designing a system similar to that implemented in the US where a governmental Committee on Foreign Investment must review and approve foreign-based investments that might be deemed a threat to national security (EurActive.com, 2007). Such financial protectionism might be avoided if these publicly managed investment pools were made more transparent, clearer in their objectives, and more accountable to the many stakeholders in these funds.
Appendix I. Governance, accountability, and investment (GAI) scores
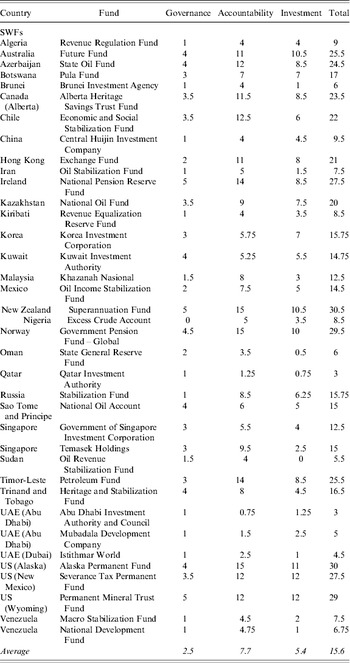
Sources: Truman (Reference Truman2008a, Reference Trumanb) and authors' calculations; see Appendix II.
Appendix II. Criteria for SWF management practices
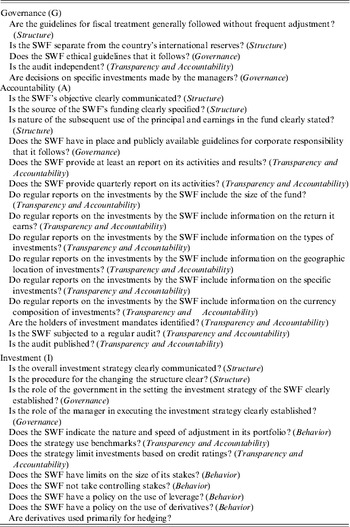
Notes: Authors' re-classification of Truman's (Reference Truman2008a, Reference Trumanb) PI scores for SWF structure, governance, transparency and accountability, and behavior variables into our measures of governance, accountability, and transparency. The PI scoreboard question is shown in italics.
Appendix III. Variable definitions and sources for empirical analysis of public fund management practices

Source: As indicated and authors' calculations; see text.
Appendix IV. Correlation matrix for empirical variables

Source: Authors' calculations; see text and Appendix III.