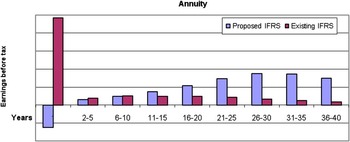
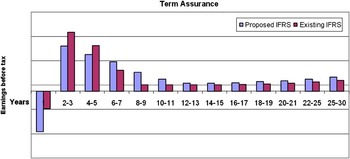
1. Introduction
1.1 Insurance accounting has for many years proved a challenging topic for standard setters, preparers and users, often described as a “black box”. The International Accounting Standards Board (IASB, 2010d) attempted to address these challenges by publishing an exposure draft of a new Insurance Contracts standard on 30 July 2010 (referred to in the remainder of this paper as the ED or Insurance Contracts ED).
1.2 The purpose of this paper is to:
– provide an overview of the existing accounting for UK insurers;
– describe recent IASB developments, covering both the Insurance Contracts ED; and other developments affecting insurers;
– set out key issues affecting life insurers arising from recent developments;
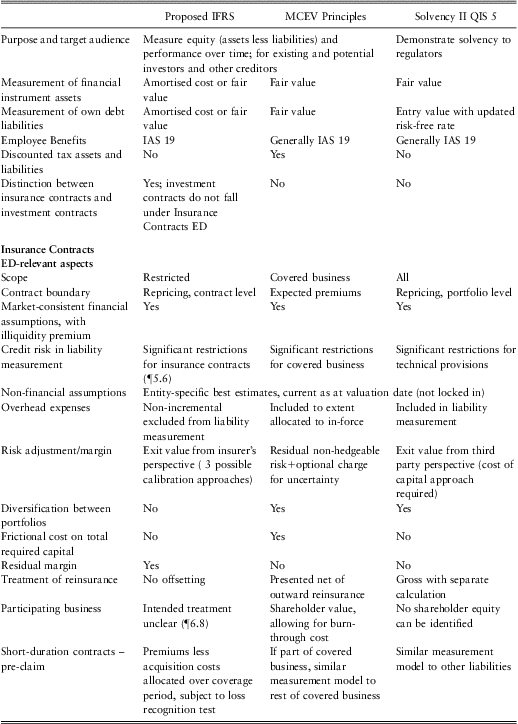
– provide a comparison of the measurement models found within the Proposed IFRSFootnote 1, market-consistent embedded values (MCEV) and Solvency II QIS 5Footnote 2;
– consider a possible future role for supplementary reporting.
1.3 The working party responsible for this paper was set up by the UK Actuarial Profession's Life Practice Executive Committee. The paper is written from a life insurance perspective, although much is also relevant to non-life insurance.
1.4 The structure of the remainder of this paper is as follows. Section 2 summarises a history of the IASB and existing accounting standards relevant to insurance company practitioners. Section 3 briefly describes the ED and sets out several specific issues arising. Section 4 describes the development by the IASB of standards other than the ED which will affect insurance companies. The ED measurement model is reviewed in section 5; this review takes into account other relevant IASB developments. Section 6 sets out other key issues for UK insurers arising from the ED. Section 7 sets out the presentation and disclosure requirements arising from the ED, and section 8 sets out a possible future role for supplementary information. Section 9 describes the working party's conclusions. A comparison of Proposed IFRS, MCEV and Solvency II QIS 5 is set out in Appendix A. Appendix B sets out potential impacts of the ED on some typical UK products.
1.5 This paper takes into account IASB developments occurring up to 31 January 2011.
1.6 The views expressed in this paper are the collective views of the IFRS Working Party, unless otherwise stated. These views are not necessarily those of the employers for whom the individual members work, the bodies they represent or the UK Actuarial Profession's Life Practice Executive Committee.
2. Background
2.1 Introduction
This section begins with a brief history of the IASB (¶2.2), followed by discussion of standards relevant to the work of actuaries in insurance companies: these are summarised in ¶2.3; with detail on the existing standard on insurance contracts in ¶2.4 and other standards in ¶2.5. Some specific background on insurance accounting measurement models is provided separately in ¶5.2. Note that ¶2.4 and ¶2.5 below are intended purely to be a high level overview and not a detailed guide to application.
2.2 A Brief History of the IASB
2.2.1 This sub-section describes the history and development of the IASB, using material drawn from the IASB website, http://www.ifrs.org/Home.htm
2.2.2 The IASB was created in 2001, following a strategic review carried out by the Board of the International Accounting Standards Committee (IASC) over 1997–99.
2.2.3 The IASC had been set up in 1973 following agreement by accountancy bodies in Australia, Canada, France, Germany, Japan, Mexico, the Netherlands, the UK and Ireland, and the United States. It was responsible for developing international accounting standards (IAS) and promoting their use.
2.2.4 In 2000, IASC member bodies approved the IASC's restructuring and a new constitution. This led to the formation in 2001 of the IASC Foundation, an independent non-profit organisation with two main bodies: the Trustees and the IASB.
2.2.5 The IASB took on the responsibilities for setting accounting standards from 1 April 2001, adopting existing IAS and developing new standards, now labelled International Financial Reporting Standards (IFRS). IASB members are appointed by the Trustees, who exercise oversight and raise the funds needed. The IASC Foundation also has a Standards Advisory Council and the International Financial Reporting Interpretations Committee.
2.2.6 In 1989, the IASC published a ‘Framework for the preparation and presentation of financial statements’ (IASC, 1989), adopted by the IASB when it took on its new role in 2001. The IASB is updating this to produce a new ‘Conceptual Framework for Financial Reporting’. This revision is not yet complete, the latest version being IASB (2010a). It describes the objective of general purpose financial reporting as “to provide financial information about the reporting entity that is useful to existing and potential investors, lenders and other creditors in making decisions about providing resources to the entity”. This means that solvency regulators and tax authorities are not part of the constituency at whom the financial statements are aimed. The assessment of financial performance uses ‘accrual accounting’, which reflects the effects of transactions and other events as they occur even if cash receipts and payments take place in a different period. There is also an underlying assumption that the firm is a going concern and will continue in operation for the foreseeable future.
2.2.7 The Conceptual Framework refers to two fundamental qualitative characteristics of useful financial information: relevance and ‘faithful representation’. An important aspect of relevance is to help readers of financial reports assess the value of the entity; another is to help monitor management in their stewardship role. To be a perfectly faithful representation, the depiction of financial information should be complete, neutral and free from bias (perfection is seldom, if ever, achievable). Other qualitative characteristics that enhance the usefulness of information are comparability, verifiability, timeliness and understandability.
2.2.8 Two of the elements of financial statements are assets and liabilities, which have been defined as (IASC, 1989):
– An asset is a resource controlled by the entity as a result of past events and from which future economic benefits are expected to flow to the entity.
– A liability is a present obligation of the entity arising from past events, the settlement of which is expected to result in an outflow from the entity of resources embodying economic benefits.
2.2.9 New definitions tentatively adopted in the Conceptual Framework (IASB, 2010a) are:
– An asset of an entity is a present economic resource to which the entity has a right or access that others do not have.
– A liability of an entity is a present economic obligation for which the entity is the obligor.
– Equity is defined as the residual interest in the assets of the entity after deducting all its liabilities.
2.2.10 Another element of financial statements is the measurement of performance over time. A key aspect is ‘comprehensive income’: the increase in equity, excluding transactions with owners (i.e. capital injections and dividends or other distributions). This may not, however, be regarded as a good indicator of management performance and perhaps should not be equated with ‘profit or loss’. The IASB has a project on financial statement presentation which is concerned with how entities separately present ‘profit or loss’ (P&L) and ‘other comprehensive income’ (OCI; consists of items that affect equity without affecting the P&L). It remains to be seen whether this project leads to new agreed principles on what OCI should comprise. Certain existing IFRS such as IFRS 9 prescribe specific items to be included within OCI, while the latest proposals set out in IASB (2010f) provide some flexibility. The outcome of the IASB's financial statement presentation project is not clear, but could be that firms report:
– ‘operating profit’; then
– after finance costs, ‘profit’; and then
– items of OCI (such as actuarial gains on pension schemes) the total being comprehensive income.
2.2.11 The Framework refers to two further issues: recognition and measurement (IASC, 1989). Briefly, assets and liabilities are to be recognised in the balance sheet if it is probable that there will be economic benefits (for an asset) or an outflow of resources embodying economic benefits (for a liability) and that the asset/liability can be measured reliably: one outcome of the reliability requirement is that some components of shareholder value, such as self-generated franchise value, may not be recognised. The Framework indicates that a number of different measurement bases are used in standards, including historical cost, current cost, realisable value and present value. Fair value was not mentioned in the Framework but has been used in a number of standards developed more recently. The requirements regarding recognition and measurement of assets and liabilities set by the IASB may differ from those set by regulators.
2.2.12 Individual standards specify in more detail the recognition criteria and measurement rules to apply to particular situations and also set out what disclosures are required, such as the assumptions made in valuing liabilities.
2.2.13 In 2002 the IASB and the US Financial Accounting Standards Board (FASB) agreed to work together, in consultation with other bodies, to achieve ‘convergence’ by, among other considerations, removing differences between international standards and US GAAP (Generally Accepted Accounting Principles). Much of the IASB's work is carried out in conjunction with the FASB.
2.2.14 All listed European Union (EU) companies have been required to use international standards since 2005 although, to be approved for use in the EU, standards must be endorsed by the Accounting Regulatory Committee of the EU. Endorsement is not automatic: the EU has not yet endorsed IFRS 9 Financial Instruments as issued by the IASB. (See ¶4.2 for a description of IFRS 9.) Outside the EU, many other countries around the world have adopted, or have announced the intention to adopt, IFRS.
2.2.15 UK companies have to prepare accounts as laid down under the Companies Act 1985 (CA85), amended in 2006 (CA06). While CA06 requires listed companies to use international standards, subject to EU endorsement, non-listed companies have the choice of whether to report using international standards or UK GAAP. Where a parent company prepares group companies’ accounts using international standards, companies in the same group may still, in some circumstances, be able to continue using UK GAAP.
2.2.16 UK GAAP reflects the standards set by the Accounting Standards Board (ASB). The ASB, having expressed concern that the current UK standards are complex and unwieldy, has proposed changes (ASB, 2010). Under its suggestions, insurance companies would be regarded as ‘publicly accountable entities’ and, as a result, required to report under IFRS, with an exception for small companies, i.e. with fewer than 50 staff, turnover under £6.5 million and assets of less than £3.26 million. Those small companies would be permitted to report under ‘FRSME’, a proposed new UK standard adapted from the international standard for small and medium-sized entities (IFRS for SMEs). The ASB's plan is that the proposals would apply from 2013.
2.2.17 Feedback on the ASB consultation paper was general agreement that UK GAAP had run its course, although views diverged on the way ahead. Some expressed concern at the wide range of financial businesses, including pure reinsurers and Lloyd's syndicates, which would be regarded as publicly accountable and hence required to use IFRS. The ASB tentatively agreed to research the possibility that subsidiaries of publicly accountable entities, which would use international standards for recognition and measurement, should be allowed to make reduced disclosures.
2.3 Existing International Financial Reporting Standards
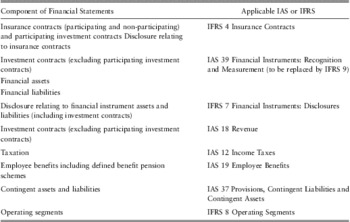
2.3.1 There is a wide variety of accounting standards which affect how insurance companies and groups report. Table 1 lists those likely to be encountered by actuaries within insurance companies.
Summary of IFRS relevant to insurance companies

2.3.2 A number of actuaries will also have to be familiar with IFRS 3 Business Combinations and IAS 40 Investment Property.
2.4 IFRS 4 Insurance Contracts
2.4.1 A project to develop a financial reporting standard for insurance contracts was instigated by the IASC in 1997. In 2002, the IASB decided to split the project into two phases, so that limited improvements to financial reporting for insurance contracts could be made within the first phase, before IFRS became mandatory for listed companies in the EU in 2005.
2.4.2 In March 2004 the IASB issued IFRS 4, the culmination of “Phase I” of the insurance contracts project. IFRS 4 has been applicable to reporting periods from 1 January 2005. It was accompanied by both a Basis for Conclusions and Implementation Guidance.
2.4.3 IFRS 4's definition of insurance contracts applies to insurance and reinsurance contracts issued, and reinsurance contracts held, by entities adopting IFRS.
2.4.4 IFRS 4 permits the continuation of many existing practices, subject to certain additional requirements which include a liability adequacy test, separation of certain embedded derivatives and removal of catastrophe provisions. As a result, there are currently substantial variations in the financial reporting for insurance contracts throughout the world.
2.4.5 IFRS 4 also requires (para. 21–23) that changes from current accounting policies must make accounts either more relevant (and no less reliable) or more reliable (and no less relevant), as judged under IAS 8. Changes in accounting policy would normally be applied retrospectively, whereas changes in accounting estimates are recognised in the period of change.
2.4.6 As well as covering “insurance contracts”, IFRS 4 is also applicable to most with-profits contracts (those with ‘discretionary participation featuresFootnote 3’ or ‘DPF’), whether they meet the definition of insurance contracts or not. Most other liabilities typically defined by regulators as insurance business, for example unit-linked contracts with insignificant insurance risks, are generally labelled “investment contracts” within IFRS reporting. These are typically treated as either financial instruments accounted for under IAS 39, or service contracts under IAS 18, or both (see ¶2.5).
2.4.7 The following are specifically encouraged by IFRS 4:
– use of current market interest rates (para. 24 of IFRS 4);
– discounting liabilities, measuring investment management fees at fair value; using uniform accounting policies across subsidiaries (para. 25);
– eliminating excessive prudence (para. 26);
– eliminating future investment margins (para. 27–28); and
– allowing shadow accounting where asset and liability measurement are inconsistent regarding unrealised gains/losses (para. 29).
2.4.8 IFRS 4 requires an insurer to disclose, in its accounts, information explaining amounts relating to insurance contracts. In particular, it has to disclose the process used to determine assumptions to which liabilities are most sensitive, the effect of changes in assumptions, and a reconciliation of changes in insurance liabilities, reinsurance assets and any deferred acquisition costs (DAC; see ¶2.4.10 below).
2.4.9 IFRS 4 also requires insurers to disclose information that enables users of the accounts to evaluate the nature and extent of risks arising from insurance contracts. This includes information on the insurer's objectives, policies and processes for managing risks. A sensitivity analysis is required, showing how P&L or equity would have been affected by changes in the relevant risk variables (or qualitative information about sensitivity).
2.4.10 For UK companies (other than bancassurers) writing insurance contracts, adopting ‘existing accounting policies’ (‘UK GAAP’) under IFRS 4 has generally resulted in those companies using the UK regulatory measurement basis for liability accounting, with the following amendments:
– the removal of amounts held for contingencies and considered to be regulatory reserves and not accounting provisions, for example certain investment reserves, resilience reserves and the reserve held for the cost of closure to new business;
– the deferral and amortisation of certain new business acquisition costs (DAC);
– setting up a liability item in the balance sheet, comprising of funds whose allocation between policyholders and shareholders has not been determined at the end of the financial year, commonly referred to as the fund for future appropriations (FFA) under UK GAAP reporting and ‘unallocated divisible surplus’ under IFRS reporting. IFRS 4 requires that this be allocated between equity and liability.
2.4.11 For banks with insurance company subsidiaries, continuation of reporting profit and equity using an embedded value method is permitted in the IFRS accounts in respect of their contracts classified as insurance contracts. Bancassurers have tended to use either the Achieved Profits guidance on supplementary reporting published by the Association of British Insurers (ABI, 2001) or the CFO Forum's European Embedded Value Principles (CFO Forum, 2004). This involves including an asset which is the value of in-force business (VIF), although the amount recognisable is restricted by IAS 39 and subsequent changes after initial adoption of IFRS are restricted under IFRS 4, which place limits on the measurement of future investment margins and rights to future investment management fees.
2.4.12 The ASB (2004) published Financial Reporting Standard 27 (FRS 27) in December 2004. A memorandum of understanding was then signed by the ASB, ABI and major life insurers/bancassurers in order to ensure that this would be grandfathered within IFRS 4, given that the effective date of FRS 27 was 1 January 2005, the same date as adoption of IFRS for listed EU entities.
2.4.13 FRS 27 stated that, for companies containing with-profits business above a certain size that consequently fall within the remit of the FSA's ‘realistic’ reporting regime, measurement of with-profits liabilities in their CA85 accounts would be reported as in the FSA ‘realistic’ reports, subject to certain modifications such as:
– removing from the liability the shareholders’ share of the cost of projected future bonuses, including associated tax charges;
– restricting the VIF asset for non-participating business in with-profits funds, in particular removing future investment margins in excess of risk-free rates, consistent with IAS 39 as applicable to investment contracts (there would be no separate DAC asset for non-participating contracts);
– measuring embedded financial options and guarantees using market-consistent methods;
– changes in the above also had consequential impacts on the FFA such that although FRS 27 changed the presentation of the balance sheet it did not change the profile of shareholder profit recognition from with-profits funds.
2.5 Other IFRS relevant to life insurers
2.5.1 This section summarises key points from a number of relevant standards issued by the IASB.
2.5.2 Accounting for “investment contracts” sold by life insurers uses IAS 39 and/or IAS 18, according to the following classification:
(i) Investment contracts with DPF are accounted for in accordance with IFRS 4.
(ii) Unit-linked investment contracts without DPF are, where relevant, separated into an investment management services component (accounted for under IAS 18) and a financial liability (accounted for under IAS 39).
(iii) Non-linked investment contracts without DPF generally provide no investment management service to the client. Therefore fees and costs in respect of these contracts are generally deemed to be associated with issuing the financial liability and accounted for under IAS 39.
2.5.3 IAS 39 Financial Instruments: Recognition and Measurement
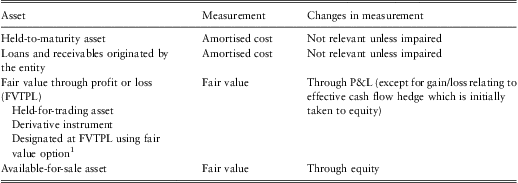
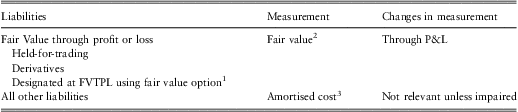
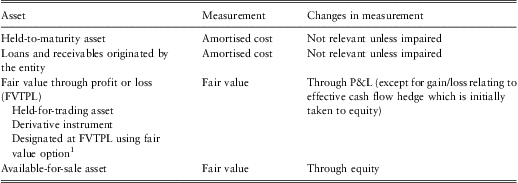
2.5.3.1 Accounting for financial instrument assets and liabilities under IAS 39 is summarised in Tables 2 and 3 respectively. Where financial instruments are measured at amortised cost, embedded derivatives that are not closely related to the host instrument must be separated and measured at fair value.
Accounting for financial instrument assets under IAS 39
Accounting for financial instrument liabilities under IAS 39
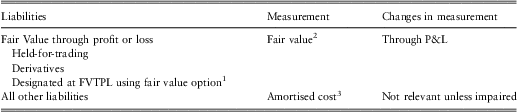
1. (Note to both tables 2 and 3) Financial instruments can be designated as being at fair value through P&L as long as they satisfy one of the following criteria: (i) the designation eliminates an accounting mismatch or (ii) the group of assets/ liabilities is managed on a fair value basis.
2. (Note to table 3 only) The fair value method must be designated at inception, the initial amount of liability being the consideration received (transaction costs must be immediately expensed). Subsequently, the liability is measured as the amount for which it could be settled between “knowledgeable willing parties in an arm's length transaction”. Offer price is to be used if there is an active market; otherwise, a valuation technique is used. There is a requirement to value financial liabilities with a demand feature at no less than the discounted amount payable on demand; this is known as the ‘deposit floor’.
3. (Note to table 3 only) Amortised cost is the accumulation of cash flows at a locked-in interest rate, being a passive valuation but subject to regular impairment tests. The rate used is the internal rate of return that equates the value of the expected cash flows to the consideration received (net of any fees paid) less transaction costs.
In practice, unit-linked investment contract liabilities are usually accounted for using fair value; non-linked non-participating contracts at amortised cost.
2.5.3.2 The held-to-maturity asset measurement category can only be used if the entity has both the ability and the intent to hold the financial instrument assets to maturity.
2.5.3.3 While under the amortised cost approach transaction costs are effectively deferred, it is noted that this is not possible under fair value. In order to defer acquisition costs under investment contracts using fair value, the transaction cost has to be assigned to the investment management service.
2.5.4 IAS 18 Revenue Recognition
2.5.4.1 This applies to revenues and costs of the investment management services component of unit-linked investment contracts without DPF.
2.5.4.2 Front-end fees are deferred and recognised as services are provided. Administration fees (fixed or varying with amounts being managed) and fund management fees are recognised as revenue as the services are provided.
2.5.4.3 Origination costs that are incremental at the contract level (for example initial commissions) are deferred, the DAC asset being amortised over the contract lifetime as the related revenue is recognised. All other costs (such as overhead costs and renewal commissions) are expensed to the income statement when incurred.
2.5.5 IFRS 7 Financial Instruments: Disclosures
2.5.5.1 The two main categories of disclosures required by IFRS 7 are:
(i) information about the significance of financial instruments;
(ii) information about the nature and extent of risks arising from financial instruments.
2.5.5.2 Information required to be disclosed about the significance of financial instruments includes:Footnote 4
– the significance of financial instruments for an entity's financial position and performance. This includes disclosures for each of the categories of asset and liability under IAS 39;
– other balance sheet-related disclosures including disclosures on credit and market risk, reclassifications, and derecognition;
– items of income, expense, gains, and losses, with separate disclosure of gains and losses from different asset categories and financial liabilities;
– other income statement-related disclosures such as interest income and expense, fee income and expense and impairment losses;
– accounting policies for financial instruments;
– detailed information about hedge accounting, including fair value hedges; and
– information about the fair values of each class of financial asset and financial liabilities.
2.5.5.3 IFRS 7 includes the requirement to disclose a three-level hierarchy for fair value measurement and some specific quantitative disclosures for financial instruments at the lowest level in the hierarchy.
2.5.5.4 Each class of financial instrument is categorised into one level of the hierarchy, determined on the basis of the lowest level input that is significant to the fair value measurement. The three levels of the hierarchy are:
Level 1: Quoted prices (unadjusted) in active markets for identical assets or liabilities.
Level 2: Inputs other than quoted prices included within level 1 that are observable for the asset or liability, either directly (that is, prices) or indirectly (that is, derived from prices).
Level 3: Inputs for the asset or the liability that are not based on observable market data.
2.5.5.5 Information required to be disclosed about the nature and extent of exposure to risks arising from financial instruments includes:
– qualitative disclosures describing risk exposures for each type of financial instrument, management's objectives, policies, and processes for managing those risks and changes from the prior period;
– quantitative disclosures including summary quantitative data about exposure to each risk at the reporting date, disclosures about credit risk, liquidity risk, and market risk and how these risks are managed. These disclosures include a sensitivity analysis of each type of market risk to which the entity is exposed with additional information if the sensitivity analysis is not representative of the entity's risk exposure (for example because exposures during the year were different to exposures at year-end).
2.5.6 IAS 12 Income Taxes
2.5.6.1 Current income tax (corporation tax in the UK) is recognised as a liability to the extent it is unpaid or as an asset if the tax paid exceeds the amount due.
2.5.6.2 IAS 12 also requires the recognition of deferred tax assets and liabilities. Deferred tax assets are recognised to the extent that it is probable that future taxable profits will be available against which the assets can be realised. In the measurement discounting is explicitly prohibited.
2.5.7 IAS 19 Employee Benefits
This standard prescribes the accounting and disclosure for employee benefits. It is mostly concerned with post-employment benefits and defined benefit pension plans. Firms should measure these liabilities using best estimates with a discount rate determined by reference to market yields on high quality corporate bonds.
2.5.8 IAS 37 Provisions, Contingent Liabilities and Contingent Assets
The objective of IAS 37 is to ensure that appropriate recognition criteria and measurement bases are applied to provisions, contingent liabilities and contingent assets and that information is disclosed to enable users to understand their nature, timing and amount.
2.5.9 IFRS 8 Operating Segments
Operating segments are components of an entity that are regularly used by the entity's chief decision maker to allocate resources and to assess performance. Operating segments have to be separately reported if they meet the definition of a reportable segment, which is when an operating segment or group of operating segments exceeds specified quantitative thresholds. An entity may, however, choose to disclose any additional operating segment.
3. Summary of Insurance Contracts Exposure Draft
3.1 This section provides a summary of the proposals contained in the ED, excluding the disclosure requirements which are covered in section 7. Brief comments on the implications of the proposals for UK life insurers are included in italicised text, taking into account views in some ED comment letters to the IASB. A review of the ED measurement model is provided in section 5 and a description of other key issues for UK life insurers is provided in section 6. The paragraph references contained in this section refer to those in the ED.
3.2 The material in this section is drawn from a variety of sources including the ED and other IASB material, Coughlan et al. (Reference Coughlan, Daguer, Hancorn, Jupe, Lynn, Mbatha, Williams, Woolley and Vickery2010), Deloitte (2010), Dollhopf et al. (Reference Dollhopf, Foroughi and Whitlock2010), Foroughi (Reference Foroughi2010), International Actuarial Association (2010), Institute and Faculty of Actuaries (2010a), PricewaterhouseCoopers (2010) and Towers Watson (2010).
3.3 Definition of an Insurance Contract (ED Appendix A, para. B2-B33)
3.3.1 Consistent with the definition in IFRS 4, the ED defines an insurance contract as a contract under which one party (the insurer) accepts significant insurance risk (defined as risk other than financial risk) from another party (the policyholder) by agreeing to compensate the policyholder if a specified uncertain future event (the insured event) adversely affects the policyholder.
3.3.2 The definition has been amended slightly from that found in IFRS 4, to clarify the role of timing in insurance risk, and to add the condition that a contract only transfers insurance risk if there are scenarios where the present value of net cash outflows can exceed the present value of premiums. These conditions are unlikely to lead to much change from the current classification of contracts for UK life insurers.
3.4 Scope of ED (ED para. 2–7)
3.4.1 The ED proposals apply to all insurance and reinsurance contracts that an entity issues and reinsurance contracts that an entity holds. Like IFRS 4, the proposals also apply to financial instruments with a DPF (see ¶2.4.6 for a description and ¶3.14 for further details). However, the ED has amended the definition of DPF to include the condition that the financial instruments with DPF must participate with insurance DPF contracts in the same pool of assets or the P&L of the same company, fund or other entity.
3.4.2 The ED contains a list of exclusions from scope. The ED does not address other aspects of accounting by insurance entities, such as accounting for financial instruments.
3.5 Unbundling (ED para. 8–11)
3.5.1 An insurer is required by the ED to unbundle components of a contract (for example investment or service components) that are not closely related to the insurance coverage, and apply the relevant IFRS appropriate to that component. The ED cites the following as the most common examples of components that should be unbundled:
(i) An investment component reflecting an account balance that is credited with an explicit return where the crediting rate is based on the performance of a specified pool of assets. The crediting rate must pass on all investment performance, net of contract fees and assessments, and so the imposition of a ceiling on the return would not meet these criteria;
(ii) An embedded derivative that is separated from its host in accordance with IAS 39; and
(iii) Contractual terms relating to goods and services that are not closely related to the insurance coverage but have been combined with the insurance coverage for reasons that have no commercial substance.
3.5.2 When unbundling an account balance, an insurer shall regard all charges and fees assessed against the account balance as belonging to either the insurance component or another component, but are not part of the investment component. The crediting rate used to determine the account balance is calculated after eliminating any cross-subsidy between that rate and the charges or fees assessed against the account balance.
3.5.3 An insurer shall not unbundle components of a contract that are closely related to the insurance coverage specified in the insurance contract.
3.5.4 The unbundling proposals as currently drafted could introduce significant uncertainty and complexity into financial reporting. This issue is discussed further in ¶6.6.
3.6 Recognition and Derecognition (ED para. 13–15, 67–68)
3.6.1 An insurer recognises an insurance contract at the earlier of:
– when the insurer is bound by the terms of the contract, and
– when the insurer is first exposed to the risk under the contract (which is the point in time when the insurer can no longer withdraw from its obligation to provide insurance coverage and no longer has the right to reassess the risk of the particular policyholder).
3.6.2 An insurer derecognises an insurance contract liability (or part of an insurance contract liability) when it is extinguished, i.e. when the obligations in the contract are discharged, cancelled or expire.
3.6.3 The period an insurer is exposed to the risk under the contract is not necessarily the same as the insurance coverage period. Hence insurers may need to change the way they account for contracts, which will be recognised earlier than the date on which the insurance coverage commences. For example, reinsurers that write treaties covering a cedant's insurance contracts to be issued in the upcoming year or years at a constrained price will be required to recognise the expected cash flows for underlying direct contracts that have not yet been written. In general, there are likely to be practical problems for insurers since administration systems may not yet contain the policy records at the time when the contract needs to be recognised.
3.7 Basic Measurement Approach (ED para. 16–22, 54–60)
3.7.1 The ED proposes a comprehensive measurement approach for all types of insurance contracts issued by entities (and reinsurance contracts held by entities), with a modified approach for some short-duration contracts. The approach is based on the principle that insurance contracts create a bundle of rights and obligations that work together to generate a package of cash inflows (for example premiums) and outflows (for example benefits, claims and recognised expenses). An insurer shall measure the insurance contract as the sum of the following building blocks:
– an explicit, unbiased and probability-weighted estimate (i.e. expected value) of the future cash outflows less the future cash inflows that will arise as the insurer fulfils the insurance contract (discussed further in ¶3.9), adjusted for the time value of money (¶3.11);
– a risk adjustment that allows for the effects of uncertainty about the amount and timing of those future cash flows (¶3.12); and
– a residual margin that eliminates any gains at inception of the contract (¶3.13).
3.7.2 The first two of these building blocks are referred to as the ‘present value of the fulfilment cash flows’ and are subject to full re-assessment of assumptions at each valuation date.
3.7.3 The present value of the fulfilment cash flows shall not reflect the risk of non-performance by the insurer, either at initial recognition or subsequently. The concept of non-performance risk or own credit risk is discussed in ¶5.6.
3.7.4 There is no deposit or surrender floor applicable when measuring insurance contracts. This is likely to lead to inconsistent treatment between contracts classified as “insurance contracts” and those classified as “investment contracts”. The financial instruments component of the latter is subject to a deposit floor (i.e. the minimum liability being the surrender value payable to the policyholder).
3.7.5 There are circumstances in which a separate risk adjustment does not have to be calculated. The application guidance (para. B45) states that if a replicating portfolio of assets exists for some or all of the cash flows arising from an insurance contract liability, the insurer can, for those contractual cash flows, simply include the fair value of those assets in the present value of the fulfilment cash flows, instead of explicitly estimating the expected present value of those particular cash flows and the associated risk adjustment. However, it is unlikely that replicating assets (as defined in the ED) exist in practice for most insurance risk-related cash flows and so the ability to avoid having to calculate a risk adjustment may be limited in practice.
3.8 Short-duration Contracts (ED para. 54–60)
3.8.1 For short-duration contracts a different measurement approach is required. Short-duration contracts are those where the coverage period is approximately one year or less and they do not contain embedded derivatives or options. For such contracts, pre-claims liabilities are required to be calculated based on unearned premiums less an initial deduction for incremental acquisition costs, subject to a liability adequacy test. However, liabilities for incurred claims are based on the ‘present value of the fulfilment cash flows’.
3.8.2 The requirement to apply two different measurement models to short-duration contracts will create complexity for insurers. A proposal which was intended to be a simplification for insurers is therefore unlikely to reduce their workload.
3.9 Cash Flows (ED para. 23–25, B61-B64)
3.9.1 Cash flows included in the measurement of a contract should include those which are incremental at a portfolio level, except for acquisition expenses where only expenses incremental at contract level are included. (A portfolio of insurance contracts is defined as insurance contracts that are subject to broadly similar risks and managed together as a single pool.) Hence cash flows will include direct costs and systematic allocations of costs that relate directly to the contract or contract activities (with the exception of acquisition expenses that are not incremental at a contract level). These cash flows will include policy administration and maintenance costs but will exclude general overheads and income tax payments and receipts which are recognised and measured under IAS 12 ‘Income taxes’. The application guidance, para. B61 to B64, sets out in more detail the cash flows which can and cannot be included in the measurement of a contract.
3.9.2 Since the cash flows included in the liability measurement do not include general overheads or non-incremental acquisition expenses, the initial residual margin includes components representing these items. The issues arising from this are discussed in ¶6.5.
3.9.3 In some territories policyholder benefits depend on future net of tax investment returns. The proposals will not allow these expected future tax flows to be reflected in the measurement of the liability. This appears to be an unintended consequence of the ED and differs from current UK practice.
3.9.4 Estimates of cash flows shall be current, unbiased and reflect the perspective of the entity, and market variables should be consistent with observable market data.
3.9.5 Cash flows shall also include those that will result from options and guarantees embedded in the contract. For example, guarantees of minimum investment returns, maximum charges for mortality, surrender options or options for the policyholder to reduce or extend coverage. The proposed measurement model requires the present value of the fulfilment cash flows to reflect expected policyholder behaviour including features that allow policyholders to take actions to change the amount, timing or nature of their benefits.
3.10 Contract Boundary (ED para. 26–29)
3.10.1 In the measurement model, cash flows are included only to the extent that they are within the boundary of the contract. The ED defines the boundary of the contract as the point when:
(i) an entity is no longer required to provide coverage, or
(ii) has the right (or practical ability) to reassess the risk of the particular policyholder, and has the ability to set a price that fully reflects that risk.
3.10.2 Options and guarantees that are not related to the existing coverage under the insurance contract would not be included within the contract boundary, but would be recognised and measured as and when they give rise to a new contract.
3.10.3 The contract boundary for an investment contract with DPF is the point at which the policyholder no longer has a contractual right to benefits arising from the DPF.
3.10.4 Contract boundary issues are discussed further in ¶6.7.
3.11 Time Value of Money and Discount Rates (ED para. 30–34)
3.11.1 An insurer shall adjust the future cash flows for the time value of money, using discount rates that are consistent with observable current market prices for instruments with cash flows whose characteristics reflect those of the insurance contract liability, in terms of timing, currency and liquidity. Any factors present in the instrument for which the market price is observed but not present in the insurance contract liability should be excluded.
3.11.2 Where the cash flows of an insurance contract depend on the performance of specific assets the valuation should reflect this dependence. The IASB staff (2010a) subsequently prepared a paper ‘Discount rate for participating contracts’ to clarify that this did not imply the use of asset-based discount rates. Instead, this ED proposal was intended to reflect the market-consistent valuation principle that each cash flow is discounted at a rate reflecting the level of risk in that cash flow.
3.11.3 Where the cash flows of an insurance contract do not depend on the performance of specific assets the discount rate shall reflect the yield curve in the appropriate currency for instruments that expose the holder to no or negligible credit risk, with an adjustment for illiquidity. The illiquidity premium reflects the liability's illiquidity from the policyholder's point of view.
3.11.4 There is little guidance on the calibration of the discount rate or when an adjustment should be made for illiquidity and how much adjustment for illiquidity there should be. (The IAA is currently preparing a monograph on Discounting.) In para. BC100 the Board notes “there is no consensus on how best to measure those effects, for example how to separate liquidity effects from credit effects”. Given the subjectivity in deriving the illiquidity premium, it would seem sensible for this to be separately disclosed. The illiquidity premium is discussed further in ¶5.7.
3.11.5 The requirement to calibrate to an instrument that exposes the holder to no or negligible credit risk allows a limited implicit allowance for own credit risk to be made. The concept of ‘own credit risk’ is discussed further in ¶5.6.
3.12 Risk Adjustment (ED para. 35–37, B67-103)
3.12.1 The risk adjustment is defined as “the maximum amount the insurer would rationally pay to be relieved of the risk that the ultimate fulfilment cash flows exceed those expected”. The risk adjustment applies at the portfolio level and hence only the effects of diversification within that portfolio can be reflected.
3.12.2 There are three permitted techniques for calculating the risk adjustment: confidence level, conditional tail expectation and cost of capital. There is a requirement to disclose the confidence level to which the calculated risk adjustment corresponds, even if a technique other than the confidence level is chosen.
3.12.3 The ED risk adjustment is different to the Solvency II risk margin where according to the Directive (European Commission, 2009):
– the purpose of the risk margin is to ensure that the value of the technical provisions is equal to a current exit value;
– a prescribed cost of capital approach is required;
– the cost of capital rate is prescribed and is the same for all insurers;
– the underlying capital to which the cost is applied is defined.
3.12.4 The risk adjustment reflects all the risks arising from the insurance contract only. It shall not reflect risks that do not arise from that contract, such as investment risk (except where it affects the payments to policyholders), asset-liability mismatch risk or general operational risk relating to future transactions.
3.12.5 A number of issues with the risk adjustment are discussed in ¶5.9.
3.13 Residual Margin (ED para. 17–22, 47–53, 65)
3.13.1 The residual margin eliminates any gain at inception of the contract. It cannot be used to eliminate losses which must be immediately recognised through P&L. The residual margin is determined at a portfolio level and, within a portfolio, by similar date of inception of the contract and by similar coverage period.
3.13.2 An insurer recognises the residual margin determined at initial recognition as income through P&L over the coverage period on the basis of the passage of time or, if it differs significantly, the expected timing of incurred claims and benefits. The release of the residual margin for a financial instrument with a DPF differs; it should be recognised in a way that best reflects the asset management services rather than the exposure from providing insurance coverage. Hence it is amortised through P&L on the basis of the passage of time or, if it differs significantly, on the basis of the fair value of assets under management.
3.13.3 The residual margin is determined at inception and not subsequently reassessed to reflect market movements or revised expectations about future estimates. It accretes interest at a rate also determined at inception and not subsequently adjusted. The interest rate used is the discount rate used to discount the cash flows in the measurement of the liability. There may be practical difficulties in identifying the relevant interest rate, for example if liabilities were measured using more than one discount rate or via a replicating portfolio.
3.13.4 If persistency is worse than expected then an adjustment to the amount of residual margin recognised through P&L shall be calculated to eliminate the portion of residual margin that relates to contracts no longer in force. No adjustment is made if persistency is better than expected.
3.13.5 A number of issues with the residual margin are discussed in ¶5.10.
3.14 Participating Contracts (ED para. 62–66)
3.14.1 The criteria for defining a DPF in the context of an insurance contract are little changed compared to the existing IFRS 4 (see ¶2.4.6).
3.14.2 Should an investment contract participate in the same investment pool as insurance contracts meeting the DPF criterion, the investment contract would fall within the scope of the insurance contracts ED.
3.14.3 The measurement model for participating contracts that fall within the scope of the ED is the same as for other insurance contracts. All cash flows arising from the participating feature are included in the same way as other contractual cash flows. In the UK, therefore, regular and terminal bonuses on with-profits policies should be included in the liability measurement.
3.14.4 The definition of the contract boundary for participating insurance contracts is the same as for other insurance contracts. For investment DPF contracts, the contract boundary is the point at which the policyholder no longer has a contractual right to receive the participating benefits.
3.14.5 The ED also requires the inclusion of payments to future policyholders as a result of a participation feature that provides policyholders with participation in the performance of a portfolio of insurance contracts or pool of assets (para. B61(j)). This appears to contradict the contract boundary requirements (see ¶6.8).
3.15 Reinsurance (ED para. 2, 43–46, B36)
3.15.1 A reinsurer accounts for reinsurance contracts it issues using the recognition and measurement approach for insurance contracts. A cedant measures a reinsurance contract at its initial recognition as the sum of the present value of fulfilment cash flows (between the insurer and the reinsurer) and a residual margin. The cedant should also consider the risk of non-performance by the reinsurer when estimating the present value of the fulfilment cash flows.
3.15.2 If the present value of the fulfilment cash flows on initial recognition of the reinsurance contract is negative, then the residual margin is assigned an equal and opposite positive amount such that the insurance contract liability is set equal to nil. If the present value of the fulfilment cash flows is positive, then that amount is recognised as a gain at initial recognition with the residual margin set equal to nil. This means companies are able to recognise a gain at initial recognition of outward reinsurance business but cannot recognise a gain at initial recognition of direct insurance business. This may create accounting arbitrage opportunities.
3.15.3 Reinsurance balances are not offset against the related direct insurance balances in either the statement of financial position or the statement of comprehensive income.
3.16 Transitional Arrangements (ED para. 98–100)
3.16.1 From the beginning of the earliest period presented in the accounts, each portfolio of existing in-force insurance contracts is to be measured as the present value of the fulfilment cash flows, without the inclusion of a residual margin. In addition, existing balances of deferred acquisition costs and other relevant intangible assets are to be derecognised.
3.16.2 The impact of these changes will be reflected by appropriate adjustments to retained earnings.
3.16.3 The measurement of insurance contracts in existence at the date of transition will not include a residual margin, both at transition and subsequently. The residual margin, which would otherwise have existed had the ED's measurement approach been used since contract inception, will under the ED proposals be in equity instead of being available to release into P&L post-transition.
3.16.4 The transition requirements in the ED apply both to an insurer already reporting under IFRS and to an insurer that applies IFRS for the first time (a first-time adopter).
3.16.5 Transitional arrangement issues are discussed further in ¶6.9.
3.17 Differences Between IASB and FASB Proposals
3.17.1 The accounting for insurance contracts is already addressed in US GAAP and has evolved over many years as a result of new insurance products, terms and features of the US insurance market. US GAAP requires the application of different models depending on the nature of the insurance contract, one for short-duration insurance contracts (that is, for most property and casualty contracts) and others for long-duration insurance contracts (that is, most life and annuity contracts).
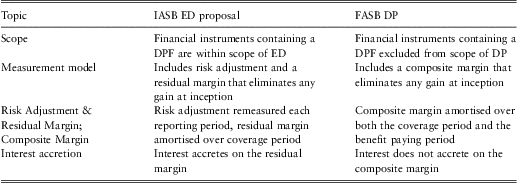
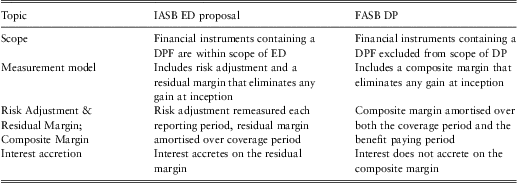
3.17.2 Since October 2008, the insurance contracts project has been a joint one between the IASB and the FASB. The IASB published its ED in July 2010 while the FASB published its discussion paper (‘DP’) in September 2010 (FASB, 2010). They reached the same conclusions in most areas, although there are still some different outcomes and conclusions as outlined in Table 4.
Summary of main differences between the IASB ED and the FASB DP proposals
3.18 Process for Finalising the ED
3.18.1 The comment period closed on 30 November 2010. During the comment period, the IASB and FASB undertook a number of outreach activities to gather preliminary feedback on the ED proposals from various stakeholders. A summary of this feedback was presented at the IASB/FASB board meeting in December 2010 (IASB & FASB staff, 2010). In addition, feedback was sought at roundtable meetings held in December 2010 in Japan, the UK and the USA. The IASB and FASB staff (2011) issued a summary of the comment letters received on the ED.
3.18.2 During the feedback process the IASB has shown its willingness to consider changing the ED proposals before finalisation of the standard, provided the insurance industry presents credible reasons for change and viable alternatives. The IASB has already indicated that the ED's proposed transitional arrangements will be amended.
3.18.3 The IASB has been conducting a second round of field tests with 15 insurers. The aim of the field testing includes understanding how the proposed approach would operate in practice, identifying where more detailed implementation guidance may be required and assessing how the proposed approach will help insurers to communicate with users of their financial statements.
3.18.4 IASB & FASB staff (2010) set out a proposed project timetable that would enable the IASB to finalise a standard on insurance contracts, and the FASB to finalise an exposure draft, both by June 2011. The timetable sets out, for each month from January to May 2011, the issues that will be discussed, for example, the discount rate, unbundling and transition.
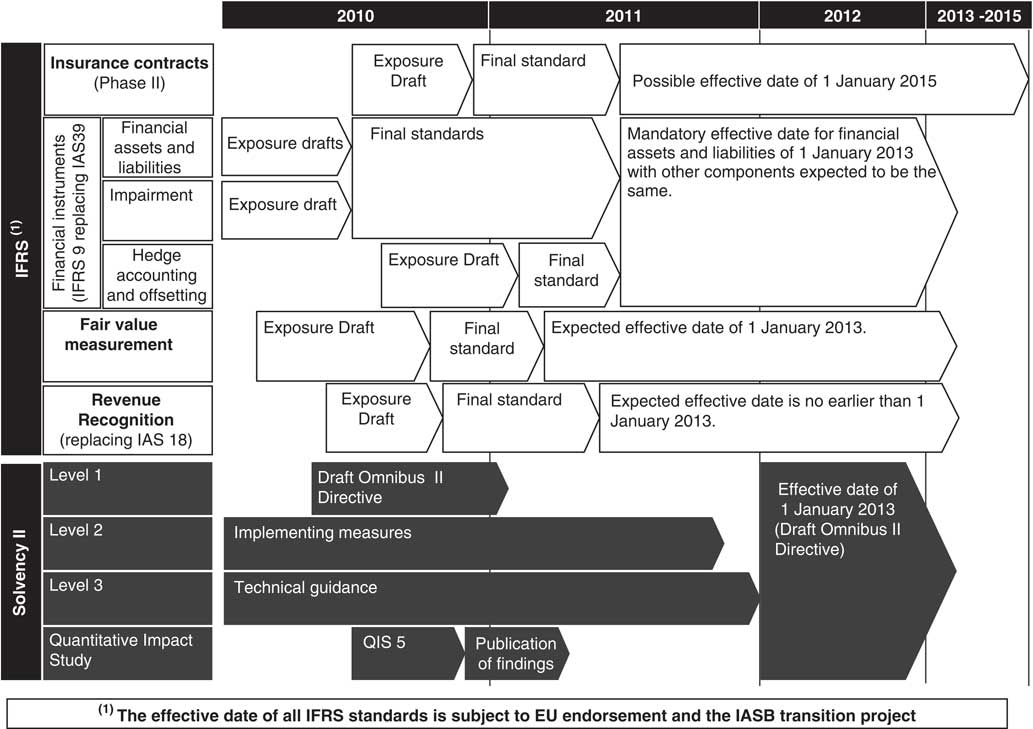
3.18.5 The IASB is aiming to publish a final standard by the summer of 2011 and recognises this is a tight timetable. The IASB staff recently provided tentative recommendations to the Board that the date of mandatory adoption of the standard should not be before 1 January 2015.
4. Other Recent IASB Developments Affecting Insurers
4.1 This section discusses some recent and imminent changes to IFRS which affect insurers, other than the Insurance Contracts ED. These include changes to the treatment of financial assets and liabilities (IFRS 9), and proposed changes to the fair value measurement framework and the revenue recognition standard (the latter impacting investment contracts in particular). There are other changes to IFRS not covered in this section which will also affect listed insurers, for example changes in the accounting treatment of consolidations, joint ventures, leases and post employment benefits.
4.2 IFRS 9
4.2.1 The development of IFRS 9 to replace the current IAS 39 is probably the most significant accounting standard development for insurers after the changes to IFRS 4, as it affects the classification and measurement of many assets held by insurers. This project is divided into three phases:
– Classification and Measurement.
– Amortised Cost and Impairment.
– Hedge Accounting.
4.2.2 In the first phase of the project, the standards relating to the classification and measurement of financial assets were put on an accelerated timetable as a response to the financial crisis, resulting in the publication of those chapters of IFRS 9 relating to classification and measurement of financial assets in November 2009 (IASB, 2009c). This was updated in October 2010 to cover the classification and measurement of both financial assets and liabilities (IASB, 2010h), completing the first phase of this project.
4.2.3 The mandatory adoption date for the entirety of IFRS 9 is proposed to be January 2013, although it is possible that delays to other related projects (including the insurance contracts accounting standard) impact this date.
4.2.4 Financial Assets – Classification and Measurement
4.2.4.1 A key change in IFRS 9 is an overhaul of the system of classification and measurement of IAS 39 which was summarised in Table 2 in section 2. For debt instruments, the only measurement approaches allowable will be “Fair Value through P&L” and “Amortised Cost”. Companies classifying assets on an amortised cost basis will need to ensure that they:
– are managed on a contractual yield basis;
– have “basic loan features”.
4.2.4.2 For equity instruments, two classifications are available: “Fair Value through P&L” and “Fair Value Recorded Through OCI”. For the latter category, changes in value, including those realised on a sale of the asset, will run through OCI, whereas dividend income will be recognised in P&L.
4.2.4.3 For all assets, a fair value option will still apply where it eliminates or significantly reduces a measurement inconsistency. Reclassifications between fair value and amortised cost basis are possible if and only if an entity's business model changes (and after meeting the relevant criteria) and are otherwise prohibited.
4.2.5 Financial Liabilities – Classification and Measurement
4.2.5.1 Financial liabilities were ultimately excluded from the text of IFRS 9 published in November 2009 and an exposure draft on the fair value option for financial liabilities was published in May 2010 (IASB, 2010b).
4.2.5.2 As a result of feedback received by the IASB, the vast majority of the eligibility criteria for designating liabilities at fair value through P&L, as well as the bifurcation for embedded derivatives, have been retained from IAS 39.
4.2.5.3 IASB (2010b) retained the requirement to allow for non-performance risk (i.e. risk of default) in the measurement of financial instrument liabilities held at fair value through P&L. However, the change in fair value attributable to changes in own credit risk was proposed to be presented in OCI instead of through P&L.
4.2.5.4 This led to the publication of a new version of IFRS 9 in October 2010 (IASB, 2010h). IASB (2010h) incorporates changes to IASB (2010b) to reflect feedback received. An amendment was made to incorporate an exception to the requirement to present the change in fair value attributable to changes in own credit risk in OCI instead of through P&L. The exception “relates to those circumstances where recognising the own credit amount directly in OCI would create an accounting mismatch”. In such circumstances “IFRS 9 requires the entire fair value change (including the own credit amount) to be recognised in P&L rather than OCI”.
4.2.5.5 IASB (2010h) retains the requirement from IAS 39 to value financial liabilities with a demand feature at no less than the deposit floor (see ¶2.5.3.2 Table 2 Note 2).
4.2.6 Financial Assets – Amortised Cost and Impairment
The second phase of the IFRS 9 project proposes changes to the impairment of assets measured at amortised cost. An exposure draft covering those changes was published in November 2009 (IASB, 2009b), with a supplement published in January 2011 (IASB, 2011). This mainly covers the interest revenue recognition on bank loans. The key change proposed is the switch to an expected loss model, rather than incurred losses for impairment. The change is intended to address the criticism of the incurred loss model that interest revenue recognition is overly high until actual evidence of a trigger event occurs, as well as inconsistent practice on the recognition and treatment of trigger events.
4.2.7 Hedge Accounting
An exposure draft on changes to hedge accounting rules was published on 13 December 2010 (IASB, 2010c). Key changes proposed are:
– The range of hedges allowable is broader, such as hedging of groups of assets and liabilities on a net basis. Components of non-financial items can be hedged, although it will not be possible to get hedge accounting on components of financial items (e.g., hedging the credit risk component of a bond with a credit default swap).
– The hedge effectiveness requirements have been relaxed.
– Options receive more favourable treatment than under IAS 39 as the time value component of the premium can be treated as a cost of hedging.
4.3 Fair Value Measurement
4.3.1 The fair value measurement project aims to:
– establish a single source of guidance for all fair value measurements
– clarify the definition of fair value;
– provide a clear framework for measuring fair value; and
– enhance disclosures around fair value measurement.
4.3.2 In May 2009 the IASB published an exposure draft of a Fair Value Measurement standard (IASB, 2009a) and, in August 2010, the IASB staff (2010b) issued its Staff Draft IFRS Fair Value Measurement. Much of this was consistent with the report of the IASB Expert Advisory Panel (2008). The final IFRS is expected to be published in the first half of 2011.
4.3.3 The Staff Draft IFRS Fair Value Measurement defines the core principle for fair value measurement as “the price that would be received to sell an asset or transfer a liability in an orderly transaction between market participants at the measurement date”.
4.3.4 Where observed market prices are deemed to represent orderly transactions, observed market prices should be used in determining fair value. For financial instruments with no observable market price, a mark-to-model approach should be used.
4.3.5 Judgement is required for financial instruments where market prices are observable, but the presence of a number of conditions suggest disorderly markets. An illustrative example may be the corporate bond market in late 2008, where observed bid prices fell significantly over a short time period. At that time, companies found that volumes of trades fell significantly, with both buyers and sellers unable to transact meaningful-sized trades at the observed prices. The Draft IFRS would require companies to judge whether fair value using the core principle would differ from the observed market price. Guidance is also provided on what constitutes an orderly transaction and how to mark-to-model.
4.3.6 Other aspects of the Draft IFRS include:
– When determining fair value, all available and relevant market prices should be considered.
– The use of bid prices in the measurement of financial instrument assets is not required.
– The fair value of a liability should reflect the effect of non-performance risk (i.e. risk of default).
– The fair value measurement should consider the most advantageous market, which maximises the value of the asset or minimises the value of the liability.
4.4 Revenue Recognition Project
4.4.1 On 24 June 2010 the IASB and FASB published the joint exposure draft Revenue from Contracts with Customers (IASB, 2010g). The proposed standard will replace IAS 18 Revenue, IAS 11 Construction Contracts and related interpretations. A final standard is expected to be published in the summer of 2011.
4.4.2 The proposals are applicable to non-participating investment contracts (e.g. unit-linked and non-unit-linked investment products with no significant insurance component) and retail fund management contracts that provide investment management services.
4.4.3 Acquisition costs are specifically covered by para. 59 of IASB (2010g):
“An entity shall recognise the following costs as expenses when incurred: (a) costs of obtaining a contract (for example, the costs of selling, marketing, advertising, bid and proposal, and negotiations)….”
4.4.4 It is unclear whether fees will need to be recognised when incurred or deferred.
4.4.5 It is noted that at the time of writing, the IASB is reconsidering the proposals set out in IASB (2010g) following comments received.
5. Review of The Exposure Draft Measurement Model
5.1 This section considers aspects of the ED's proposed measurement model.
5.2 Measurement Approach – Background
5.2.1 Most existing insurance accounting measurement models have elements of both a deferral-and-matching approach and an economic value approach. The measurement model proposed in the ED also contains elements of both approaches.
5.2.2 A deferral-and-matching approach allocates revenue and expenses to periods after day one in accordance with the provision of risk coverage or services. This approach does not permit a day one profit and usually requires a liability adequacy test. It is typically considered in conjunction with a book value or amortised cost measurement of financial instrument assets backing the insurance liabilities, where an asset impairment test usually applies.
5.2.3 An economic value approach measures the value generation to shareholders arising from the sale of a contract. It typically attempts to measure blocks of business in line with how shareholders would in principle value the underlying cash flows, using a subset of the economic balance sheet. (See O'Keeffe et al., Reference O'keeffe, Desai, Foroughi, Hibbett, Maxwell, Sharp, Taverner, Ward and Willis2005, Appendix B for a detailed description of the economic balance sheet; further references are provided in that document.) This approach permits a day one profit. It is typically considered in conjunction with a fair value measurement of financial instrument assets. This approach typically forms the building blocks of MCEV reporting.
5.2.4 A deferral-and-matching approach focuses on the measurement of P&L items; an economic value approach focuses on the measurement of balance sheet items.
5.2.5 The deferral-and-matching and the economic value measurement approaches can be considered as two ends of a spectrum of possible measurement approaches.
5.2.6 A number of advantages can be put forward for a deferral-and-matching approach, including the following:
– It can satisfy better than the economic value approach the ‘verifiability’ characteristic of useful financial information, as typically less judgement is required in measurement than the economic value approach.
– It aligns with aspects of existing accounting standards in many jurisdictions around the world, in particular US GAAP reporting.
– It aligns with revenue recognition project developments and the likely direction of the future accounting of banks.
– There is less impact from short term market movements and hence less pro-cyclicality.
– The assumptions setting process is more reliable.
– The approach may be preferred by insurers as a basis for measuring taxable profits.
5.2.7 However, a deferral-and-matching approach raises some issues, in particular:
– Two insurers with identical assets and liabilities could show different values, depending on when the assets and liabilities were acquired.
– Its relevance is reduced by not using all current information about assets and liabilities in their measurement.
5.2.8 A number of advantages can be put forward for an economic value approach, including the following:
– The measure satisfies (better than the deferral-and-matching approach) the following characteristics of useful financial information: relevance (particularly from a value perspective) and faithful representation (in that the measure is likely to be more complete, neutral and free from bias than the deferral-and-matching approach).
– By permitting a day one profit, there is no need for a residual margin, and therefore no need to consider how to amortise such a margin.
– It values cash flows in line with financial market practice.
– It recognises changes in experience when they happen rather than those being drip fed through future reporting periods.
– It avoids accounting volatility and instead shows economic impacts from asset-liability mismatching (economic volatility).
– Management performance during the period is recognised with greater transparency.
– There is less need for supplementary value-based reporting such as embedded values.
– It is closer to the Solvency II model and much more familiar to practitioners in Europe.
5.2.9 However, an economic value approach raises some issues, in particular the fair value measurement approach has been criticised for not producing reliable answers where markets are inactive or illiquid.
5.3 Measurement Approach – Review of ED
5.3.1 The IASB Framework does not prescribe a method for measuring assets and liabilities and therefore the IASB has had to develop a specific approach to measure insurance liabilities for the new standard. The IASB has moved away from the suggestion in its Discussion Paper (IASB, 2007) of measuring liabilities at current exit value (which was taken to be equivalent to fair value), reflecting the feedback received from many stakeholders.
5.3.2 As insurance liabilities are typically not traded, the use of current exit value would have required significant interpretation by preparers, which would have raised questions about its reliability. Further, as insurers expect in practice to fulfil rather than transfer their obligations, an approach based on fulfilment value may be more consistent with ‘faithful representation’, one of the qualitative characteristics of financial statements referred to in the IASB Framework (see ¶2).
5.3.3 A fulfilment value contains two important elements common to a fair value. First, it uses ‘expected value’, i.e. a probability-weighted average of future cash flows which, in particular, enables the value of options and guarantees to be included. Second, it uses current estimates, at the valuation date, which is designed to help consistency with assets measured at fair value (although note ¶5.5).
5.3.4 The residual margin to eliminate upfront profits is consistent with the ideas that the IASB has used in its project on revenue recognition (IASB, 2010g), although it may be unfamiliar to many UK and continental European financial reporting practitioners. The residual margin effectively moves the overall accounting model away from an economic value approach and closer towards a deferral-and-matching approach.
5.3.5 Horton et al. (Reference Horton, Macve and Serafeim2010) conclude that the IASB approach is consistent with a method of valuing liabilities put forward in the accounting literature, namely the ‘relief value’ (see Lennard, Reference Lennard2002; Macve, Reference Macve2010). This indicates that the value of a liability is the amount by which a firm would be better off if relieved of its liability, to which the suggested answer (in most cases) is the value that the customer places on the contract. This includes the firm's profit margin and is therefore – initially – part of the liability (as is the residual margin in the ED). With time, the firm fulfils its obligations and the residual margin is released into profit.
5.3.6 However, by using a hybrid measurement model that combines elements of both the deferral-and-matching approach and the economic value approach, it may be difficult for users to interpret the results without significant additional information and analysis (Dollhopf et al., Reference Dollhopf, Foroughi and Whitlock2010). A number of comments on the ED suggested amendments that move the measurement model closer to either a deferral-and-matching or economic value model.
5.3.7 For example, the following amendments would move the measurement model closer to a deferral-and-matching approach (these are discussed further in the subsections shown in brackets):
– allow a locked-in discount rate, for consistency with the amortised cost approach to the measurement of financial instrument assets as set out in IFRS 9 (¶5.4);
– unlock the residual margin recalibration at future accounting dates, either for non-financial assumptions only or for both financial and non-financial assumptions (¶5.10).
5.3.8 The following amendments would move the measurement model closer to an economic value approach (these are discussed further in the subsections shown in brackets):
– allow gains at inception (¶5.10);
– include the cash flows such as overheads and non-incremental acquisition costs that are excluded from the ED in order to reflect fully the expenses expected to be incurred in fulfilling the insurer's obligations (¶6.5);
– allow a greater diversification effect to be taken into account in the calculation of the risk adjustment (¶5.9);
– align the economic calibration more closely with fair value measurement proposals (¶5.5);
– remove any possible requirement to unbundle unit-linked contracts (¶6.6).
5.4 Volatility and Discount Rates
5.4.1 A variety of respondents to the ED have expressed concern that its adoption may lead to unwanted or unrepresentative short-term fluctuations (i.e. volatility) in the reported profitability of life insurance companies, as well as counterintuitive balance sheet impacts.
5.4.2 Volatility can broadly be considered as a mixture of accounting mismatches and economic mismatches. Accounting mismatches can arise from different asset and liability measurement approaches under IFRS, some of which could be addressed by adopting available measurement options. For example, where assets are measured at amortised cost, and insurance contract liabilities are measured using current interest rates, there will be an accounting mismatch as current interest rates move away from those ‘locked in’ by the amortised cost measurement basis. This accounting mismatch can largely be removed by taking up the option to measure financial instrument assets at fair value, although in such circumstances remaining economic mismatches would likely lead to more volatile results, year on year, than for ‘investment contracts’ with liabilities measured using a deferral-and-matching approach and backing assets measured consistently at amortised cost.
5.4.3 The CFO Forum & CEA (2010) put forward a proposal to allow a “cost” option to measure insurance contracts, including a locked-in discount rate set at policy inception, for consistency with the amortised cost approach to the measurement of financial instrument assets as set out in IFRS 9.
5.4.4 Economic mismatches can be addressed either by additional disclosures to explain the results, or by reducing the level of economic mismatching between insurance contract liabilities and backing assets.
5.4.5 Volatility in the results may also need explaining where there are differences in the measurement and profit profile of insurance contracts compared with similar business carried out by companies in other sectors.
5.4.6 ¶5.5–5.8 describe the following possible accounting mismatches:
– mismatch between the fair value measurement of assets and the economic calibration within the ED measurement of the insurance contract;
– the use or otherwise of own credit risk in the ED measurement of the insurance contract;
– the illiquidity premium within the ED measurement of the insurance contract compared with the illiquidity premium of viable investment strategies;
– taxation mismatches that could arise from inconsistencies between the ED and IAS 12 in the measurement of related cash flows.
5.5 Fair Value Measurement
5.5.1 The IASB's fair value measurement proposals define the core principle of fair value measurement as “the price that would be received to sell an asset or transfer a liability in an orderly transaction between market participants at the measurement date”. This “orderly transaction” aspect of the core principle appears inconsistent with the ED requirement to calibrate the market variables underlying the measurement to observable market prices (ED para. 23 (b)) in circumstances where market prices do not reflect an orderly transaction. The ED approach could lead to new types of accounting mismatches between the insurers’ assets and liabilities that have not been observed in companies’ accounts to date. This accounting mismatch could be addressed by aligning the Insurance Contracts ED with the fair value measurement proposals.
5.5.2 It is also noteworthy that the QIS 5 economic calibration does not seem to have considered the IASB's fair value measurement developments. Foroughi & Murray (Reference Foroughi and Murray2011) set out proposals to reduce potential accounting mismatches under a possible future Solvency II Pillar 1 standard, the following of which are also relevant when considering IFRS proposals:
– Assets held to match insurance contract liabilities should be measured using mid-prices.
– The economic calibration of insurance liabilities should use all available and reliable market data.
– The economic calibration of insurance liabilities should use the most advantageous market.
– The economic calibration of insurance liabilities should permit a small amount of credit risk in the calibration instrument (Foroughi & Murray, Reference Foroughi and Murray2011, recognise that this is contentious).
5.6 Own Credit Risk
5.6.1 Shareholders of limited liability companies are generally not required to invest additional capital if the prudential or accounting liabilities of the company exceed the assets. The ability to walk away from the obligations of a company at times of financial distress is, effectively, a put option which has value to the shareholders of the company. This is generally referred to as ‘own credit risk’ or the ‘limited liability put option’.
5.6.2 The recent financial crisis has made the role of own credit risk in the measurement of accounting liabilities more prominent.
5.6.3 The ED does not permit the insurance contract liabilities to be reduced to reflect own credit risk or the risk of non-performance by the insurer (para. 38), except:
– in the case of a reinsurance asset, where the reinsurer's credit risk must be taken into account (ED para. 44);
– indirectly as the discount rate calibration shall reflect “no or negligible credit risk” (ED para. 31).
5.6.4 The question of whether to allow for own credit risk in liability measurements has been subject to much debate. A Discussion Paper issued by the IASB staff (2009) set out the advantages and disadvantages.
5.6.5 Specifically for insurance liabilities, a number of respondents have suggested that the IASB look again at this aspect of the measurement model.
5.6.6 Reasons why the IASB excluded own credit risk from the insurance liability measurement may include the following:
– While the credit risk associated with existing policyholders can lead to a reduction in the existing liability, it can also lead to a reduction in the franchise value of an insurance company's balance sheet. However, the franchise value is generally made up of the value associated with selling future new business and is not normally permitted as an accounting asset.
– It reflects feedback from the insurance industry on the IASB's Insurance Contracts Discussion Paper (received prior to the recent financial crisis) and earlier lobbying; for example see CFO Forum (2006).
– It is perceived as more consistent with the fulfilment value model underlying the ED's present value of fulfilment cash flows building blocks.
– It is perceived to lead to counterintuitive results, in that a decline in the creditworthiness of insurance liabilities can lead to a reduction in the liability or an increase in IFRS equity.
– The insurance regulatory regime in many countries, including the UK, may lead to a negligible allowance in certain circumstances.
– The risk of non-performance by any one specific insurer is difficult to measure.
5.6.7 Reasons why respondents have suggested that the IASB look again at own credit risk may include the following:
– The exclusion of credit risk in the measurement of insurance liabilities, together with the full allowance in the measurement of backing assets, arguably creates an accounting mismatch.
– Such a mismatch may well be negligible in benign financial markets and strongly regulated insurance industries, but may be much more significant in extreme financial conditions or for insurance contracts issued in industries with weak or non-existent regulation. In such circumstances the mismatch could lead to counterintuitive results, such as negative equity.
– In extreme financial conditions, it may be challenging to identify any calibration asset that fulfils the “no or negligible credit risk” condition (para. 31) at a time when regulators may be encouraging insurers to reduce asset liability mismatch risk. This may therefore lead to financial instability and unstable markets as insurers struggle to identify matching assets.
– This aspect is not consistent with the measurement of non-insurance liabilities, such as financial instrument liabilities or pension scheme promises. It is noted though that it is often easier to buy back financial instrument debt or renegotiate pension scheme promises than negotiate not to meet policyholder promises.
– Insurance industries have at times been unable to meet guaranteed promises to policyholders, in particular at times of financial crisis. For example consider the Japanese insurance industry in the 1990s and early 2000s.
– This aspect may be inconsistent with regulation or legislation in specific industries where insurance companies are permitted to renegotiate policyholder promises in specific extreme circumstances without triggering bankruptcy.
– In the preceding two examples, the ED's proposals would lead to a significant discontinuity in reported results over time as insurers declare bankruptcy or renegotiate policyholder promises.
– This aspect may make it more challenging to meet the risk adjustment principle in para. 35, given that insurers may otherwise rationally take into account own credit risk as a partial offset to financial distress costs.
– It is possible to consider and develop further the concept of an industry-wide own credit risk adjustment, while still excluding the possibility of an insurer-specific adjustment.
5.7 Illiquidity Premium and Viable Investment Strategies
5.7.1 The ED states the following with respect to the illiquidity premium:
– Para. 31: “…the discount rate shall reflect the yield curve…with an adjustment for illiquidity (see para. 34).”
– Para. 34: “Many insurance liabilities do not have the same liquidity characteristics as assets traded in financial markets. For example, some government bonds are traded in deep and liquid markets and the holder can typically sell them readily at any time without incurring significant costs. In contrast, policyholders cannot liquidate their investment in some insurance contract liabilities without incurring significant costs, and in some cases they have no contractual right to liquidate their holding at all. Thus, in estimating discount rates for an insurance contract, an insurer shall take account of any differences between the liquidity characteristics of the instruments underlying the rates observed in the market and the liquidity characteristics of the insurance contract.”
5.7.2 This interpretation of the term “illiquidity premium” appears to measure an insurance liability as an equivalent hypothetical asset which produces broadly similar cash flows, with similar levels of liquidity or illiquidity to the liability. A similar interpretation can be found within Solvency II QIS 5.
5.7.3 However, this interpretation ignores the point of view that the term “illiquidity” in this context relates to assets, not liabilities. Liabilities are often by nature illiquid from the perspective of the liability holder, as in most circumstances the liability holder does not have the right to force the asset holder to trade.
5.7.4 A mismatch can arise in extreme financial conditions where illiquidity premia may be much higher. If an insurer chooses not to hold illiquid assets, then in more benign market conditions (where illiquidity premia are typically much smaller) that is a reversible investment management decision. However, in more extreme market conditions where illiquidity premia can be much larger and the impact on measurement more significant, insurers who do not already own illiquid assets may be forced to recognise the accounting benefit in the measurement of the liabilities without being able to capture the illiquidity premium in practice. It is debatable whether this is an accounting or economic mismatch. (See Foroughi, Reference Foroughi2010, for further discussion and additional references.)
5.7.5 A similar issue can arise within IAS 19 accounting, impacting UK companies’ defined benefit pension schemes. During the recent financial crisis the deficit of a number of pension schemes fell significantly, as a result of being forced to apply a high quality corporate bond rate to measure all pension liabilities, while holding a significant proportion of backing assets in government bonds or collateralised swaps.
5.8 Taxation Accounting Mismatches
5.8.1 Several taxation accounting mismatches can arise as a result of the ED measurement model.
5.8.2 There are two aspects of IAS 12's approach to measuring deferred tax assets and liabilities that are inconsistent with the ED measurement model (Foroughi, Reference Foroughi2010):
– no discounting is permitted;
– a deferred tax asset or liability should only be set up if the future cash flow is probable to arise i.e. greater than 50% probability (although there are proposals to amend this to an expected value approach).
5.8.3 The Institute and Faculty of Actuaries (2010a) provided one specific taxation accounting mismatch example, in the context of unit-linked business:
“We were pleased that the exposure draft addressed some accounting mismatches for this business. However, we were disappointed that one such mismatch was not dealt with, namely that associated with the requirement to cover a deposit floor (surrender value) in the policyholder liability combined with the need to establish a deferred tax charge on a full undiscounted basis. In the UK the allowance within a unit fund for capital gains tax may be less than the full undiscounted amount for reasons associated with treating policyholders fairly and this can lead to some wide, artificial swings in reported profit. We appreciate the IASB's desire not to change IAS 12 merely on account of an issue largely confined to UK unit-linked business. However, it would be helpful if, say, the Basis for Conclusions could record that the deposit floor for unit-linked business need not be the actual surrender value but rather could reflect the IAS 12 deferred tax liability where this adjustment removes an accounting mismatch.”
5.9 Risk Adjustment
5.9.1 The risk adjustment and the three techniques permitted to measure it are described in ¶3.12. As insurers are in the business of taking risks, information about the implications of those risks should in principle be helpful; however, the risk adjustment as proposed raises several concerns set out in ¶5.9.2–5.9.7 below.
5.9.2 The risk adjustment as drafted is concerned with the risk that cash flows exceed those expected. This is different from the risk adjustment proposed for liabilities subject to IAS 37 (IASB, 2010e), which referred to outflows of resources differing from those expected, i.e. covering the risk that there are favourable as well as unfavourable outcomes. This wording change was requested in a number of comment letters to the ED.
5.9.3 The risk adjustment is calculated at the level of a portfolio of insurance contracts, excluding the effect of diversification between portfolios, so that the impact of risk on the insurer itself will not be apparent.
5.9.4 The phrase “the maximum amount the insurer would rationally pay to be relieved of the risk” in the risk adjustment principle appears to introduce an exit value concept, albeit based on the insurer's own perspective rather than that of a third party.
5.9.5 It is not clear from whose perspective the risk adjustment is meant to be calculated. If an insurer were to report a risk adjustment of X, it could be inferred that the directors regard the cost of risk to the insurer as X, suggesting the risk adjustment is calculated from the directors’ perspective. However, there is little guidance in the ED provided to help the directors make this judgement. An alternative approach may be to reflect a shareholder perspective, taking into account the ability (or otherwise) of shareholders to diversify away the risks in the measurement. This is similar to the suggestion set out in para. 83 of the Basis of Conclusions of the European Insurance CFO Forum Market Consistent Embedded Value Principles ©Footnote 5 when calculating MCEVs, in the context of the Cost of residual non-hedgeable risk component (CFO Forum, 2009a and 2009b). This suggestion may help avoid agency risk, the risk that the interests of management and shareholders are misaligned.
5.9.6 The measurement of the risk adjustment is not permitted to take into account own credit risk, due to ED para. 38. This appears inconsistent with the “rational” aspect of the risk adjustment principle.
5.9.7 The IASB proposes that only the three specified methods (cost of capital, confidence interval and conditional tail expectation) be used to measure the risk adjustment. A number of comment letters to the IASB suggested that this is undesirable as it rules out new and possibly better methods that may be developed. A principles-based approach to permissible methods may be more appropriate, recognising that none of the three prescribed methods were originally designed for the purpose of calculating the ED's proposed risk adjustment.
5.10 Residual Margin
5.10.1 The unit of measurement of the residual margin calculation will increase the likelihood and potential level of day one losses, due to its level of granularity.
5.10.2 Since the fulfilment cash flows exclude an allocation of general overheads or non-incremental acquisition expenses, the initial residual margin reflects the expected lifetime shareholder profits on the contract plus components representing the future general overheads and non-incremental acquisition costs reasonably allocated to the contract.
5.10.3 There are a number of aspects of the residual margin calculation post day one that will create conceptual and practical challenges for insurers. In particular:
– The detailed definition of the pattern for release of the residual margin is contrary to a principles-based approach.
– For certain products such as whole life, the amortisation pattern based on incurred claims and benefits will be back-ended, and significantly different to the pattern of the provision of services or the emergence of overhead costs.
– The unit of account will differ from that used for the risk adjustment calculation.
– Tracking the residual margin and its release over time will be complex and will require systems developments.
– The run-off of the residual margin is determined without reference to the timing of the charges that the insurer makes. Hence, if an insurer changes the pricing of a product so that charges are more front-end-loaded, but with the overall residual margin unchanged, that would have no effect on the time-profile of reported profits. This is an odd result and arguably inconsistent with faithful representation.
5.10.4 The fact that the residual margin is not recalibrated, particularly for changes in non-economic assumptions, is conceptually incoherent with the deferral-and-matching rationale for a residual margin. A way of moving closer to a deferral-and-matching model would be to require the residual margin to be recalibrated for changes in future assumptions, and to act as a shock-absorber, subject to a loss recognition test. This change may only apply to non-economic assumptions if insurers measure the backing assets at fair value. Recalibration of the residual margin would reduce the impact on net income of volatility relating to changes in future non-economic assumptions and hence mitigate pressure on insurers to leave non-economic assumptions unchanged. The approach under the Australian Margin on Services method (Australian Accounting Standards Board, 2009) provides a case study for a practical method for recalibrating the residual margin.
5.10.5 Alternatively, a move closer to an economic value approach would require the residual margin to be removed, permitting a day one profit. This would imply a major change to the proposed measurement model.
6. Issues Arising for UK Life Insurers
6.1 Introduction
6.1.1 The Insurance Contracts Exposure Draft and other current IFRS developments will have major implications for insurance companies. Section 5 set out issues related to the measurement model. This section describes other key issues for UK life insurers. This includes the following commercial, practical and reporting issues:
– timeline and interaction with Solvency II;
– systems and data development;
– new business profit recognition and distribution channels;
– excluded expense cash flows;
– unbundling;
– contract boundaries;
– participating business;
– transitional arrangements.
The presentation requirements of the ED are considered further in section 7, and resulting implications are discussed in section 8.
6.1.2 The material in this section is drawn from a variety of sources including the ED and other IASB material, Coughlan et al. (Reference Coughlan, Daguer, Hancorn, Jupe, Lynn, Mbatha, Williams, Woolley and Vickery2010), Deloitte (2010), Dollhopf et al. (Reference Dollhopf, Foroughi and Whitlock2010), Foroughi (Reference Foroughi2010), Institute and Faculty of Actuaries (2010a), KPMG (2010), PricewaterhouseCoopers (2010) and Towers Watson (2010).
6.2 Timeline and Interaction with Solvency II
6.2.1 During 2011 it is expected that the Solvency II Level 2 implementing measures and the new IFRS for insurance contracts, financial instruments and revenue recognition will be finalised.
6.2.2 The European Commission (2011) published a provisional version of the draft text of the Omnibus II Directive on 19 January 2011. This directive will, if adopted, amend the Solvency II Directive. It is proposed that Article 311 of the Solvency II Directive is replaced by: “Articles … and Annexes … shall apply from 1 January 2013.” As widely anticipated, this introduces a two-month delay to the implementation of Solvency II.
6.2.3 The effective dates of the various Proposed IFRS are still to be finalised and the IASB is consulting on this matter. There is therefore a risk that the various Proposed IFRS may become effective at different times resulting in multiple transitions and restatements.
6.2.4 It is noted in ¶3.18.5 that the mandatory date of adoption of a new insurance contracts IFRS may not be before 1 January 2015. This means that it is likely that Solvency II will be implemented before a new insurance contracts IFRS.
6.2.5 These timing issues present a range of practical challenges and considerations, as the current IFRS reporting requirements for insurance contracts are often based on Solvency I or US GAAP methods.
6.2.6 An expected timeline of Proposed IFRS and Solvency II developments in set out in Figure 1.
Expected timeline of Proposed IFRS and Solvency II developments
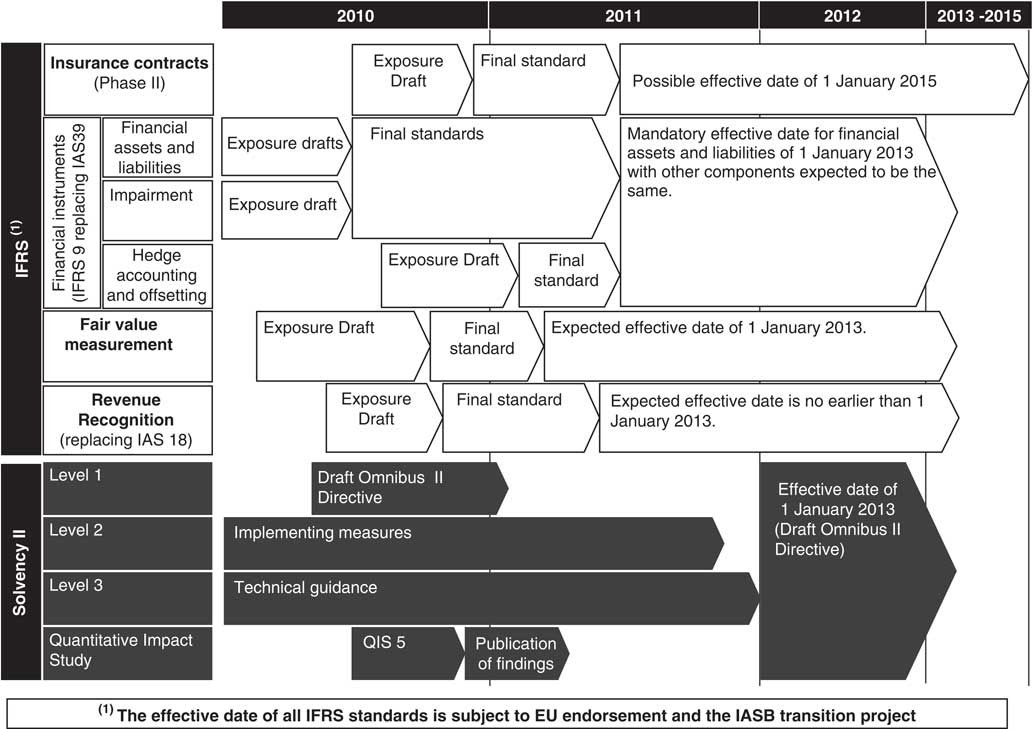
6.2.7 Given the likelihood that Solvency II is applicable prior to the effective date of the new IFRS insurance standard, insurers may have a number of IFRS reporting options for insurance contracts in the interim period, including:
– Maintain current approach. This would require the parallel running of current models and processes in addition to those required by Solvency II.
– Adopt Solvency II (or a modified version). This would require a careful assessment of the current IFRS 4 and IAS 8 requirements to check whether such an approach is permitted. A further change would then be required to adopt the new insurance contracts standard, once it becomes mandatory.
– Adopt the requirements of the new insurance contract standard. Insurers might adopt the requirements of the insurance contract standard either through early implementation of the standard itself (subject to its endorsement by the European Commission) or possibly by adopting some of its requirements as a way of improving existing accounting policies under IFRS 4.
6.2.8 In addition, the required changes by HMRC to the taxation regime for UK life insurers will be another significant consideration in the interim period. The current tax regime for UK life insurers is based on the FSA regulatory return. Under Solvency II, there will be no equivalent regulatory return. HMRC entered into consultation process in 2010 to examine the tax basis for insurance companies, both life and non-life insurers (Treasury & HMRC, 2010). At an early stage during the consultation process, it was proposed that life insurers would move to be taxed based on the IFRS profit disclosed in the statutory accounts. A response to the taxation proposals was provided by the UK Actuarial Profession Taxation Working Party (Institute and Faculty of Actuaries, 2010b); this included the following:
– If IFRS profit is selected as the basis for tax, then it is important that fiscal adjustments are included in the tax computation to reduce any disconnect between the timing of tax payments and the emergence of capital (under Solvency II).
– A suitable mechanism to provide a smooth transition process should be developed.
– Major reform of the “I minus E” UK taxation system is not required for the implementation of Solvency II.
The consultation process continues in respect of the more detailed aspects of life company taxation in a statutory accounts based regime. A Ministerial Statement is expected to be published on Budget Day (23 March 2011) with further clarification of the proposed changes.
6.2.9 Overall, insurers are likely to face significant challenges in delivering to both the Proposed IFRS and Solvency II timetables.
6.3 Systems and Data Development
When compared to requirements for current IFRS reporting, the proposals as they stand are likely to require significant data gathering and systems/modelling changes, including:
– a modelling platform to cater for all financial and regulatory reporting requirements, including Solvency II;
– stochastic modelling of embedded options and guarantees, likely in many cases to be Monte Carlo simulation modelling;
– earnings forecasting and analysis models;
– capability to process large quantities of information efficiently;
– use of judgment and additional modelling to measure the risk adjustment (three methods allowed under current proposals);
– residual margin calculation and amortisation (granularity and unit of measurement may create challenges) and
– unbundling.
Many of these changes are in addition to those required under Solvency II reporting.
6.4 New Business Profit Recognition and Distribution Channels
6.4.1 The timing of new business profit recognition may change significantly between current IFRS reporting and the Insurance Contracts ED. The impact may vary between different product lines and between different insurers, even for contracts where the underlying features are similar. Appendix B shows some examples of earnings pattern for two typical UK products, an immediate annuity and a term assurance product.
6.4.2 Under the proposals, there will be at most nil profit recognised at the point of issue (except for reinsurance contracts), while losses will have to be recognised immediately. Expected profits will be deferred over the life of the contract, and recognised as experience emerges and margins are released.
6.4.3 Non-incremental acquisition costs cannot be deferred under the proposed model. These are likely to come through as losses at the point of issue. These proposals are likely to be more restrictive than the definition of deferrable acquisition costs generally adopted by UK life insurers. This generally implies recognising a bigger loss at inception relative to current practice.
6.4.4 Given the basis used to release the residual margin is changing, reported profit drivers will also change.
6.4.5 Insurers need to consider the implications of the ED on their distribution models as those that are directly funded by attributable incremental expenses (intermediaries or on a commission basis) will receive an accelerated profit recognition compared with direct marketing or salaried sales forces models.
6.4.6 In the UK, this new accounting for insurance may be introduced soon after the changes to insurers’ distribution models arising from the implementation of Retail Distribution Review.
6.4.7 In summary, the implications of the current proposals on new business profitability and distribution channels could be significant for the industry. For example, the proposals (in particular the proposals to expense non-incremental acquisition expense cash flows) may encourage:
– repricing and product restructuring;
– change of pay structures for sales staff;
– driving down acquisition costs;
– outsourcing of activities.
6.5 Excluded Expense Cash Flows
6.5.1 The ED proposes to exclude from the measurement all acquisition expenses that are not incremental at a contract level and general overheads.
6.5.2 The IASB opted for a narrow definition of incremental acquisition expenses at a contract level to reduce the impact of subjectivity when allocating costs and to improve consistency with the financial instruments standard's treatment of transaction costs. The definition is also consistent with the approach currently adopted under IAS 18 when deferring costs relating to investment management services for investment contracts. Under the Revenue Recognition proposals (IASB, 2010g), however, acquisition expenses would be expensed and no DAC asset recognised.
6.5.3 Furthermore, treatment of “incremental and directly attributable costs” and/or their interpretation may differ from one insurer to another because of the limited amount of guidance provided. Judgement will be required when deciding whether non-commission acquisition costs, such as policy issue, marketing and underwriting, are incremental at a contract or portfolio level. There could even be an incentive for insurers to outsource certain functions to third parties, with costs charged on a per-policy basis, to be able to treat those costs as incremental at the contract level.
6.5.4 The exclusion of general recurring overheads in the fulfilment cash flows will mean that liabilities are understated in this respect. In most cases this will be offset by an increase in the residual margin.
6.5.5 There is a strong case for including in the fulfilment cash flows those overheads and acquisition expenses that can reasonably be allocated to contracts at a portfolio level. This would help avoid distortions in profit emergence and improve consistency between insurers. Many respondents to the ED argued for widening the definition to include acquisition expenses incremental at a portfolio level.
6.5.6 The ED also requires insurers to exclude from the fulfilment cash flows those “arising from abnormal amounts of wasted labour or abnormal amounts of other resources used to fulfil the contract” (ED para. B62(e)). Identifying any such cash flows is likely to require significant judgment and therefore make it more difficult to verify and audit. Those “excluded” cash flows are expected to be incurred, therefore it is questionable whether this exclusion is consistent with a ‘faithful representation’.
6.6 Unbundling
6.6.1 The ED does not define “closely related” and so the unbundling proposals as currently drafted could be subject to different interpretation.
6.6.2 The measurement approach will depend on whether a contract is unbundled and which components are unbundled, since different accounting standards will be applicable to different components. For example, if an unbundled account balance is valued under IAS 39 using an amortised cost approach then the liability measurement may be significantly different from that obtained using the ED proposals. The liabilities, and hence earnings profile, for the same contract may be very different for two insurers who interpret “closely related” differently. In addition, the cost and administration of implementation could vary significantly depending on the approach taken to unbundling.
6.6.3 As currently drafted, the specific examples provided may take precedence over the principle of “not closely related”. It is not clear whether this was the intention of the ED.
6.6.4 When unbundling an account balance, the ED is not clear on:
– how to unbundle the remaining non account balance items;
– how the allocation of charges and expenses (including acquisition expenses); between the bundled and unbundled components is performed.
6.7 Contract Boundaries
6.7.1 For the contract boundary to be triggered, the pricing reassessment has to be done at the ‘policyholder’ level, rather than at the ‘portfolio’ level. This would mean for example that, for many unit-linked style contracts with variable expense, mortality or other charges applied at the portfolio level, depending on emerging experience, the contract boundary would still be the full term of the contract.
6.7.2 The Solvency II QIS 5 definition differs from the ED proposals, in particular the reassessment applies at the portfolio level under QIS 5. In certain cases this may lead to a different contract boundary between the ED proposals and Solvency II, which could cause measurement differences leading to practical and communication challenges. However, CEIOPS (2010) noted in its response to the IASB:
“For the above reasons [para. 51–55] CEIOPS is convinced that the ability to assess the risk and to re-price at the portfolio level should be considered consistent with, rather than distinct from the Board's proposed contract boundary principle.”
6.7.3 The Institute and Faculty of Actuaries (2010a) describe a specific contract boundary issue with respect to medical expense insurance, stating:
“Medical expense insurance is a major line of business in the UK. It is generally written on an annually renewable basis but an individual is guaranteed renewal regardless of his or her claims experience. The premium on renewal is set having regard to the expected experience of the entire portfolio. A strict interpretation of the rules on contract boundaries would require a major change in systems to value the impact of future (unknown) premiums for very little practical benefit. This is because the profits expected to arise on these future premiums would, under the proposals in the exposure draft, be balanced by an increased residual margin, the run-off of which is essentially arbitrary. Nothing seems to be gained by not treating this business as short duration – although a loss recognition test on a recurring premium approach would seem appropriate.”
6.8 Participating Business
6.8.1 In its response to the IASB on the ED, the Institute and Faculty of Actuaries (2010a) commented that “the intended treatment of assets within a participating fund which are surplus to the requirements of current policyholders needs clarification. In para. B61(j) [of the ED] there is a reference to liabilities being included in respect of future policyholders but this is contradicted in a number of places elsewhere”. This response concluded that “it is appropriate to split the surplus into its shareholder and policyholder components. The latter could be identified as a separate item from the liability for in-force policyholders and perhaps labelled ‘members’ interest’ in a mutual. In a 90/10 proprietary company, the shareholders interest would need to allow for what is commonly referred to as the ‘burn through’ cost, representing the market-consistent mean value of any future shareholder support to the fund needed to make benefit payments”.
6.8.2 If the estate is to be treated as a liability, this would affect the mutual business model since for mutual insurers, the estate is the main source of capital. In addition, the lack of clarity in the treatment of the estate may also mean that different treatments are adopted by different mutuals, leading to inconsistency across the industry.
6.9 Transitional Arrangements
6.9.1 The ED states that, at transition, liabilities in respect of the in-force portfolio of insurance contracts at the start of the period reported on are to be measured as the present value of fulfilment cash flows, without any residual margin. At that point existing balances of DAC or intangible assets arising from business combinations (e.g. an acquired value of in-force business asset) are to be derecognised, except where the intangibles relate to possible future contracts. The difference in measurement is taken directly to retained earnings, not through the P&L.
6.9.2 The extent of the opening retained earnings adjustment on transition will be affected by many factors including the profitability of business written as well as the previous accounting policies applied.
6.9.3 Determination of the risk adjustment for transition business will therefore be a critical activity as it will provide the primary source of future profits from that business. This might encourage a conservative assessment of the risk adjustment, with the release of margins in the risk adjustment expected to emerge in future earnings rather than being taken to equity at transition.
6.9.4 The absence of a residual margin on in-force business at transition will cause different patterns of profit recognition for in-force and new (post-transition) business. Residual margin that might have existed on the transition book will be released to retained earnings at transition, whereas profit on post-transition new business will include the release of residual margin. This will require careful communication to users of the accounts.
6.9.5 The IASB considered it problematic to determine retrospectively a residual margin on existing business at transition as this would require estimation of the fulfilment cash flows at contract inception, which would be burdensome, costly and subject to bias through the use of hindsight. The Board considered that this cost would outweigh the benefit for users of financial reporting and would potentially be contrary to IAS 8, which prohibits the retrospective application of an accounting policy to the extent that this would be impractical.
6.9.6 However, as IASB & FASB staff (2011) note, there was widespread objection to excluding the residual margin on business in-force at transition, mainly because recognised profit would be lower and less comparable both from year to year and between companies. Several approaches have been suggested in comment letters, and one of the more popular suggestions was to allow inclusion of a residual margin on the in-force business on a best endeavours basis.
6.9.7 Insurers are permitted to redesignate financial assets to be measured at fair value through P&L under IFRS 9, to the extent that this would reduce an accounting mismatch. Some insurers may wish to redesignate assets currently measured at fair value through P&L to amortised cost, if the requirement to unbundle account balances from the insurance contract would allow the account balance to be on an amortised cost basis, but this is not permitted.
7. Presentation and Disclosure Requirements
7.1 Introduction
The presentation and disclosure requirements of the ED are considered in this section. In many cases, the ED requirements are much more detailed than existing IFRS disclosure requirements and with practical consequences for reporting systems and processes.
7.2 Presentation – Statement of Financial Position (ED para. 69–71)
7.2.1 Insurance contract liabilities are required to be presented as a single line on the Statement of financial position (balance sheet). The only exception is for unit-linked assets and liabilities relating to insurance contracts which are shown as two separate lines on the Statement of financial position and are not commingled with other insurance contract lines. Further, there is no offsetting of reinsurance assets against contract liabilities on the Statement of financial position.
7.2.2 This is similar to current UK practice. There is no requirement to present separately the underlying components of the contract liability (for example, the residual margin) in the Statement of financial position. These components would be disclosed elsewhere in the financial statements, for example in the reconciliation of contract balances as considered under the disclosure requirements later in this section.
7.3 Presentation – Statement of Comprehensive Income (ED para. 72–78)
7.3.1 The Exposure Draft proposes a summarised presentation model for reporting income and expenses arising from insurance contracts in the Statement of comprehensive income (income statement), based on a margin analysis as illustrated in Table 5. This is a significant change from the cash flow revenue account presentation found in existing IFRS reporting. The margin-based approach was selected to be consistent with the measurement model for insurance contracts by reporting changes in the building blocks that make up the model.
Statement of comprehensive income – an example

Note: sub-totals can be disaggregated in either the Statement of comprehensive income or in the notes to the financial statements.
7.3.2 The margin-based approach is considered by the IASB to be a more useful explanation of the drivers of an insurer's financial performance than a traditional revenue account.
7.3.3 The income and expense from unit-linked contracts and the pool of assets underlying unit-linked contracts are presented as single line items on the face of the Statement of comprehensive income.
7.3.4 A consequence of the approach is that the premiums received and claims paid are treated as deposits and so do not form part of the margin analysis, but can be disclosed in the notes to the financial statements.
7.3.5 Management, analysts and investors will need to be educated in the new presentation format and it is likely to take time for users to become accustomed to not having items such as premiums and claims presented. A number of comment letters to the ED noted that providing the amounts of such cash flows was valuable.
7.3.6 The proposed Statement of comprehensive income is more akin to an embedded value earnings analysis presented in supplementary reporting by many UK insurers. However, the minimum standard is more focused on the liability side of the balance sheet rather than capturing the full interactions between assets and liabilities, hence leading to a risk that the users of the financial statements will not be able to understand fully the results. Consequently, there may be a continuing role for supplementary information.
7.3.7 In the presentation of the underwriting margin there is no distinction between pre-transition and post-transition business. This will impact the risk adjustment only as the residual margin is zero on pre-transition business. It may be expected that further supplementary disclosure of the risk adjustment would capture this feature.
7.3.8 Further, there are a number of aspects where additional clarity would be helpful, notably:
– It is uncertain how the interest rate in the explanatory line ‘interest on insurance liability’ is to be determined.
– The changes in discount rates and the interest on insurance liabilities are required to be presented or disclosed in a way that highlights their relationship with the investment return on the assets backing those liabilities (ED para. 73). It is unclear how to interpret this requirement, and why only these line items require such treatment.
– For unit-linked contracts, it is not clear how the single line presentation for insurance contracts will interact with the approach to disclosure adopted for unit-linked investment contracts and the impact of unbundling the account balance which may be undertaken for some unit-linked contracts.
– It is unclear how the presentation approach applies to contract elements based on a replicating portfolio.
– It is unclear where the accretion of interest on the residual margin is presented.
7.3.9 All income and expenses relating to insurance contracts are included in the Statement of comprehensive income and not in other comprehensive income.
7.3.10 Together with the measurement model, the result is that the impact of mismatches between assets and liabilities (whether mismatching by duration, by taking equity or credit risk in the assets, or otherwise) will be shown in the Statement of comprehensive income. This is similar to current practice for UK-based insurers where insurance contract liabilities are typically valued based on market rates of interest and supporting financial assets are at fair value. However, the approach is significantly different to that adopted in Continental Europe or in the US where Other Comprehensive Income is commonly used to eliminate some mismatches between assets and liabilities. In the UK, it is commonplace to explain the impact of market movements on the results through the use of non-GAAP measures such as an underlying (or operating) result, which excludes the effects of short-term fluctuations in investment returns. Such supplementary measures may continue to be used should the Insurance Standard be implemented in line with the Exposure Draft.
7.3.11 For short-duration contracts subject to the modified measurement approach (that is the unearned premium approach), the underwriting margin is disaggregated into line items, reflecting some traditional revenue items, either on the face of the Statement of comprehensive income or in the notes to the financial statements:
– premium revenues (grossed up for the amortisation of incremental acquisition costs);
– claims incurred;
– expenses incurred;
– amortisation of incremental acquisition costs;
– for onerous contracts, changes in additional liabilities.
7.3.12 For short-duration contracts, the disclosure of more traditional revenue items may allow the users of the financial statements to continue calculating ratios such as combined ratios and expense ratios.
7.4 Disclosures (ED para. 79–97, 101)
7.4.1 Disclosure requirements build on the current IFRS 4 and IFRS 7 requirements, but in many cases are more detailed and have the potential to impact reporting systems and processes for insurers.
7.4.2 The overarching principle in the Exposure Draft is to help users of financial statements to understand the amount, timing and uncertainty of future cash flows arising from insurance contracts. To meet this principle, there are qualitative and quantitative disclosures required for the amount recognised and nature and extent of risks arising from insurance contracts. If, in a particular situation, the disclosures do not meet this principle then the insurer should disclose additional information to ensure this principle is met.
7.4.3 Further, the level of aggregation or disaggregation for information is principles-based so that “useful information is not obscured.” However, different reporting segments, as defined in IFRS 8, are not permitted to be aggregated in the disclosures.
7.4.4 The disclosure requirements in the ED include:
– Reconciliations of contract balances between opening and closing as a result of the new measurement model.
– A more detailed disclosure of methods and processes for estimating inputs compared with IFRS 4.
– The discount rates used and estimates of policyholder dividends. The term policyholder dividend is not defined in the ED, but in the context of UK contracts is assumed to refer to with-profits bonuses.
– The confidence level to which the risk adjustment corresponds, whichever of the three techniques is used. This disclosure requirement is analysed in ¶7.4.11.
– Expanded disclosure of measurement uncertainty analysis. A measurement uncertainty analysis is a disclosure of the impact of using different inputs in the measurement model. The ED requires single input changes and all scenarios that could reasonably have been used in the circumstances and which have a material impact to be considered. Remote scenarios are not required to be considered, but the effect of correlations between inputs, if relevant, should be considered.
– Information on the regulatory framework in which the insurer operates, for example minimum capital requirements or required interest rate guarantees.
– Quantitative information on sensitivity to insurance risk gross and net of risk mitigation, whereas IFRS 4 currently permits a choice of qualitative or quantitative disclosure.
– Claims development tables, initially for at least 5 years. After adoption of the standard claims development tables will be built up to 10 years. The requirement does not apply to the development of claims for which uncertainty about the amount and timing of claim payments is typically resolved within one year. The requirements on claims development tables (para. 92(e)(iii)) are unchanged from IFRS 4 para. 39(c)(iii). Para. 60 of the implementation guidance to IFRS 4 clarifies that claims development disclosures are not normally required for most life insurance contracts as there is typically certainty about the amount and timing of claim payments within one year. Furthermore, it is clarified that claims development disclosures are not normally needed for annuity contracts because each periodic payment arises, in effect, from a separate claim about which there is no uncertainty. Para. 251 of the ED's Basis for Conclusion proposes to carry forward this exemption for life insurance contracts.
– Exposures to risk and how they arise as well as changes from the previous period.
– An insurer's objectives, policies and processes for managing risks arising from insurance contracts and the methods used to manage those risks.
– Similar disclosures to IFRS 4 for credit, liquidity and market risks.
7.4.5 The proposed disclosure requirements will be onerous to produce. It is important that the disclosure requirements are considered in the light of disclosure requirements within Solvency II. In Solvency II, there will likely be extensive quantitative and qualitative disclosure requirements in the annual and publicly available Solvency Financial Condition Report (SFCR) and the private Regular Supervisory Report (RSR). The Solvency II disclosure requirements are significantly more detailed than those within the ED, and in a number of areas there is little overlap, but some alignment should be possible (for example, risk and capital disclosures).
7.4.6 Insurers will face significant challenges in setting up efficient internal processes to generate the required disclosures and in ensuring that both sets of disclosures convey similar messages and provide sufficient information on the key value driving activities of the business.
7.4.7 Many listed insurers have a good understanding of the disclosures that are valued by users. These include information that is provided in the financial statements and in other supplementary sources and investor briefings. It would be helpful if IFRS disclosures align better with existing best practice, subject to also satisfying certain mandatory minimum requirements.
7.4.8 For example, several analysts have noted the benefits in providing an analysis of free surplus, typically found within the supplementary embedded value analysis of movement. The disclosure requirements in the ED do not consider such an analysis. This is likely to be an area where insurers would prepare supplementary information if the final standard is consistent with the ED. The potential future role of supplementary information is considered in section 8.
7.4.9 Reconciliation of contract balances (ED para. 86–88)
7.4.9.1 This subsection describes the requirement within the ED for a reconciliation of contract balances to be calculated and disclosed.
7.4.9.2 Reconciliation is required from the opening to the closing aggregate insurance and reinsurance balances for each of the following:
(a) Insurance contract liabilities and, separately, insurance contract assets.
(b) Risk adjustments included in (a).
(c) Residual margins included in (a).
(d) Reinsurance assets arising from reinsurance contracts held as cedant.
(e) Risk adjustments included in (d).
(f) Residual margins included in (d).
(g) Impairment losses recognised on reinsurance assets.
7.4.9.3 For short-duration contracts the reconciliation is required separately for pre-claims liabilities, additional liabilities for onerous insurance contracts and claims liabilities.
7.4.9.4 Table 6 displays the minimum presentation for the reconciliation where the line items are applicable; further explanatory lines can be included.
Example reconciliation of contract balances
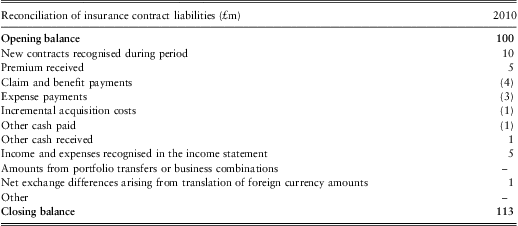
7.4.9.5 The reconciliation of contract balances will provide the users of the financial statements with useful information. IFRS 4 para. 37(e) currently requires a reconciliation of changes in insurance liabilities, reinsurance assets and, if any, related deferred acquisition costs. However, IFRS 4 does not specify the format of the reconciliation and a variety of presentations are adopted by insurers in the UK.
7.4.9.6 However, the following is noted:
– The format of the reconciliation of contract balances mixes two distinct analysis approaches: an analysis by source of surplus (impact of new contracts recognised during the period) and an analysis by source of cash flow (premiums, claims, expenses etc.). The interpretation of this requirement is unclear for certain cash flows. For example, on which line item should premiums arising from new contracts recognised during the period be included?
– There is limited guidance as to how the explanatory items in the reconciliation should be determined and in which order. The order of the analysis will impact the presentation of the reconciliation.
– The requirement to perform the reconciliation at the component level, for example, the risk adjustment, will introduce a number of practical data and system challenges for insurers.
7.4.10 Confidence interval disclosure for the risk adjustment (ED para. 90b(i))
7.4.10.1 The risk adjustment can be determined through one of three techniques in the ED. If the insurer uses a cost of capital or conditional tail expectation technique, then there is a requirement to disclose the confidence level to which the risk adjustment estimated under those methods corresponds. The ED notes as an example: “The risk adjustment was estimated at conditional tail expectation (Y) and this corresponds to a confidence level of Z per cent.”
7.4.10.2 The concept of introducing comparability in the disclosure of the risk adjustment is to be welcomed. However, the proposal in the ED is unlikely to achieve this objective for the following reasons:
– The focus on the confidence level may lead users of the financial statements to the view that the present value of fulfilment cash flows is calibrated to the indicated level of sufficiency, which will not be the case. For financial risk, the use of a market-consistent calibration builds in a margin of unknown confidence level above an unknown medium result. It is unlikely that users of the financial statements will understand the treatment of financial risks in the measurement model when viewing the risk adjustment confidence level disclosure (Dollhopf et al., Reference Dollhopf, Foroughi and Whitlock2010).
– The theoretical benefit is questionable given the limitations of the confidence level method when probability distributions are skewed (Institute and Faculty of Actuaries, 2010a).
In addition, the proposal would require stochastic modelling for many companies that otherwise would have no need for such a technique (Institute and Faculty of Actuaries, 2010a).
8. Possible Future Role of Supplementary Information
8.1 Background
8.1.1 Supplementary information currently plays an important role for UK insurers by providing information on how shareholder value is created in the business and how it is subsequently used by the business or paid out to shareholders. Supplementary information is needed because the primary financial statements under IFRS 4 allow a variety of accounting practices to continue, particularly for multinational insurers where the group level IFRS accounts will be a mix of different countries local GAAP. In addition to this inconsistency in the underlying figures, the local GAAP is often based on a modified solvency basis which normally does not provide a good measure of shareholder value.
8.1.2 The most common form of supplementary information provided by UK based insurers is embedded value (EV), under either the European Embedded Value (EEV) Principles (CFO Forum, 2004) or the Market Consistent Embedded Value (MCEV) Principles (CFO Forum, 2009). The EV supplementary information is usually included with the financial statements in the Annual Report and Accounts, presented in a similar format to the primary accounts and is normally audited. The EV disclosures can be extensive and typically include the EV balance sheet, analysis of EV earnings, value of new business, sensitivity analyses and methodology and assumption disclosures. For Continental European insurers, EV supplementary information is generally published in a separate disclosure document. Following IFRS 7 risk management disclosure requirements, there is typically some limited EV information in the Annual Report and Accounts.
8.1.3 In addition, other supplementary information, for example additional IFRS disclosures and an analysis of the Insurance Groups Directive surplus, is common in the Annual Report and Accounts.
8.2 Recent Trends in Supplementary Reporting
8.2.1 In recent years, there has been a change in reporting emphasis for several large UK based insurers with greater focus on IFRS earnings as a headline metric in disclosures compared to EV earnings. In addition, a number of insurers developed additional IFRS supplementary information, making it clearer where IFRS earnings arise. The change in emphasis perhaps reflects in part the volatility observed in embedded value during the credit crisis of 2008, with IFRS results perceived as being more stable.
8.2.2 Over the same period, there has been increased investor focus on the amount and timing of cash flows. In response to this, many insurers introduced wider supplementary embedded value metrics based on distributable earnings, including:
– Information on projected free cash flows to help the assessment of the insurer's dividend-paying ability, capital-raising needs and ability to support new business growth.
– Information on new business strain, internal rates of return and payback periods.
These wider supplementary metrics are generally derived from the models underlying the supplementary embedded value disclosures.
8.2.3 With the introduction of the new IFRS Insurance Contracts standard and Solvency II, the future role of supplementary information, in particular EV, is called into question: Will these new standards provide the kind of measures and disclosures that are useful to users of financial statements?
8.3 Measurement Model
8.3.1 The current role of supplementary reporting indicates the importance that users place on value-based measurement models. The typical characteristics of a supplementary value-based model would include:
– a prospective discounted cash flow model;
– shareholders’ perspective on the value of existing business, allowing for the risk to shareholders associated with that business;
– comparability between insurers or sufficient sensitivities to aid comparison;
– a model used by management in making business decisions;
– consistency with market values where these are available and reliable;
– current assumptions, updated frequently for recent experience and not ‘locked in’
– internal consistency of the measurement model, for example, between different types of business and between assets and liabilities;
– ability to identify sources of changes in value, distinguishing between economic and non-economic sources and between changes in the measurement of start-period in-force business and the impact of sales during the period, and split by components of value.
8.3.2 How does the measurement model in the ED compare against these characteristics? The ‘present value of fulfilment cash flows’ ED building blocks, with active assumptions and market-consistent financial risks, go a long way to addressing several of these characteristics. The ED also provides a common measurement approach for all insurance contracts whereas, for example, EV is usually applied only to long-term life and savings contracts.
8.3.3 However, the ED's measurement model also exhibits limitations in meeting the characteristics set out in ¶8.3.1, including:
– It addresses measurement of insurance contract liabilities but not related assets or investment contract liabilities, or unbundled components all of which might be subject to inconsistent measurement approaches (noted in sections 5 and 6).
– The exclusion of general overheads and non-incremental acquisition costs from the cash flows measured is not consistent with a shareholders’ view of the business or how management make business decisions.
– Limiting the value of new business to a maximum of zero by introducing a residual margin is not consistent with a shareholders’ view of the business or how management make business decisions.
– The risk adjustment is calculated at the level of a portfolio of insurance contracts, excluding the effect of diversification between portfolios; this is also not consistent with a shareholders’ view of the business or how management make business decisions.
8.3.4 How do the measurement proposals in Solvency II compare against these characteristics?
As for the ED, some of the characteristics are addressed in the proposed Solvency II technical provisions, notably:
– comparability between companies through a single framework for insurance entities;
– best estimate discounted cash flow model;
– financial risk incorporated on a market-consistent basis.
8.3.5 However, the Solvency II model, as proposed in QIS 5, also exhibits limitations in meeting the characteristics, including:
– There is no concept of “equity”.
– There is no requirement (as yet) to publish an analysis of movement or P&L.
– There is no consideration of the IASB's fair value project developments in the measurement of financial instrument assets.
– Allowing for financial risk in the measurement of technical provisions on a market-consistent basis is restricted to a narrow definition of a ‘deep, liquid and transparent’ market; it is not clear how this aligns with the IASB's fair value project developments.
– The calibration of the risk-free interest rate term structure raises issues; for example, the failure to consider all available and reliable market information (¶5.5) and the derivation and application of the illiquidity premium (¶5.7).
– The 6% risk margin cost of capital charge appears to contain a significant prudential margin (CRO Forum 2008, Foroughi Reference Foroughi2010 and accompanying references)
– The QIS 5 contract boundary definition may lead to prudence in the technical provisions.
– The measurement of participating business makes no distinction between with-profits fund capital and shareholder capital.
– The measurement of financial instrument liabilities prescribed in QIS 5 can differ significantly from a fair value approach.
– The measurement of deferred tax assets and liabilities follows the requirements of IAS 12, inconsistent with an economic approach (see ¶5.8).
8.3.6 The assessment of the ED and Solvency II measurement models compared to the typical characteristics of a value based measure illustrates that, if the final standards are unchanged, it would be worthwhile for insurers to continue produce supplementary value-based information reflecting a more realistic measure of shareholder equity. In addition, a reconciliation between IFRS equity, Solvency II own funds and this other value based measure including explanation and reconciliation of the earnings arising under the various measures is likely to be of benefit to users.
8.4 Disclosures
8.4.1 As part of supplementary reporting in the UK, many insurers prepare disclosures in addition to the requirements of current IFRS and regulatory (FSA return) reporting. The preparation of these disclosures can be seen as best practice and highlights their importance to users of financial information. The additional disclosures would typically include:
– information on expected future distributable earnings, to aid assessment of the timing and amounts of capital released from the business
– information on new business, including volumes, capital requirements/new business strain, expected internal rates of return, payback periods, and value added.
– identifying sources of changes in value at a granular level capturing the whole business, interactions between asset and liabilities and the split as set out in ¶8.3.1. For example, an analysis of change in EV earnings (CFO Forum, 2009a, Appendix A)
– sensitivity and scenario analysis on the key drivers of value to aid comparability.
8.4.2 How do the disclosure requirements in the ED compare to current supplementary disclosures? As described in section 7, the ED requires a variety of disclosures covering inter alia measurement methods, ‘measurement uncertainty analysis’ and risk sensitivities, risk exposures/management/mitigation and concentrations under various risk classes, and claims development. The disclosures build on the current IFRS 4 and IFRS 7 requirements, which is to be welcomed.
8.4.3 However, the ED disclosures exhibit a number of limitations compared to the typical additional disclosures, including:
– no information on free cash flows;
– no meaningful new business value information due to the ED measurement model
– the focus on risks arising from insurance contracts in isolation from other contracts. To best inform users regarding risks to the whole balance sheet, insurers will need to find some way to provide a picture that combines related risks arising from insurance contract liabilities, financial assets and investment contract liabilities, each with their own disclosure requirements under IFRS;
– limitations in the minimum required standard for the statement of comprehensive income and reconciliation of contract balances as described in section 7.
8.4.4 How do the disclosure requirements in Solvency II compare to current supplementary disclosures? In Solvency II, there will likely be extensive quantitative and qualitative disclosure requirements in the annual and publicly available SFCR and the private RSR.
8.4.5 The Solvency II disclosure requirements will be significantly more detailed than those of the ED and are expected to include:
– qualitative information on business performance, systems of government, risk management, accounting policies for the regulatory balance sheet, own funds, minimum capital requirement, solvency capital requirement and differences between standard formula and any internal models used;
– quantitative information on the regulatory balance sheet, assets held by the entity, technical provisions at a granular level, risk profile, capital contributions by risk, variation analysis (change in own funds) and reinsurance loss profile.
8.4.6 The Solvency II disclosure requirements will provide valuable information to the users of financial information. However, their focus is on the regulatory balance sheet (in particular own funds) and regulatory required capital, with no requirement to publish an earnings statement or analysis of surplus. It is therefore unlikely that the Solvency II perspective in isolation would meet the current supplementary disclosure requirements.
8.4.7 This assessment illustrates that, as currently proposed, disclosure requirements within IFRS and Solvency II would not provide an alternative to existing supplementary information prepared by insurers. Consequently, if the final standards are unchanged this working party expects that insurers continue to prepare supplementary disclosures focusing on shareholder value (presented as adjustments to either IFRS equity or Solvency II Own Funds) and the amounts and timings of expected distributable earnings.
9. Working Party Conclusions
9.1 This working party recognises the considerable challenges in designing a reliable insurance accounting framework. All existing frameworks contain known deficiencies, and a wide variety of views exist in the global insurance industry as to how to tackle these deficiencies. These are to some extent addressed by appropriate presentation and disclosure requirements.
9.2 In this context, we congratulate the IASB in publishing the Insurance Contract Exposure Draft and welcome many aspects, including:
– development of a single accounting practice and measurement model;
– potential for greater consistency and transparency;
– inclusion of expected cash flows and an explicit risk adjustment;
– explicit margins shown;
– a measurement model using current estimates based on observable prices for market variables and entity-specific assumptions for non-market variables;
– the potential for fewer accounting mismatches.
9.3 However, in the process of drafting this paper we have identified a number of significant issues with the ED measurement model, set out in section 5. These include the following:
– Users may face challenges in understanding the hybrid nature of the model proposed.
– Significant volatility may arise; in some areas it may be hard to distinguish between accounting and economic mismatches.
– A number of accounting mismatches may remain.
– The risk adjustment and the residual margin proposals raise a number of concerns.
9.4 In addition, we have identified a number of other issues likely to affect UK insurers, set out in section 6. One of the most significant appears to be the practical challenge arising from implementing Proposed IFRS and Solvency II in similar timescales.
9.5 We welcome several aspects of the ED's presentation and disclosure requirements, in particular:
– the principle to help users of financial statements understand the amount, timing and uncertainty of future cash flows;
– the standard presentation format of the statement of comprehensive income and the reconciliation of contract balances.
9.6 However, other aspects of the ED's presentation and disclosure requirements may not be sufficient to meet the needs of users. Section 7 sets out some areas where the final insurance contracts standard may benefit from revision to the ED. Section 8 sets out a number of areas where the need for supplementary reporting for insurers is likely to remain, given the scope and likely direction of both Proposed IFRS and Solvency II.
9.7 Many of the issues highlighted in this paper have also been highlighted in comment letters to the IASB, and a number appear to be unintended consequences of the ED.
9.8 We hope that the IASB tackles the issues set out in this paper and in the comment letters, such that the final insurance contracts standard contains fewer issues. This would help the IASB more closely meet the laudable aims of its insurance contract project and its Conceptual Framework. It may also help ensure that the IASB's proposed developments truly herald a new era for insurance accounting.
9.9 We hope that the IASB considers a period of further exposure before the standard is finalised, limited to aspects of significant change. This would help ensure good governance, and avoid future unintended consequences arising.
Acknowledgements
We would like to thank Nick Dexter, Derek Wright and Peter Wright for their suggestions for improvements to this paper. We would also like to thank staff at the Institute and Faculty of Actuaries for providing logistical support.
Notes:
– existing international accounting standards are included in: INTERNATIONAL ACCOUNTING STANDARDS BOARD (2010). International Financial Reporting Standards IFRS 2010. London: International Accounting Standards Board.
– the web references were correct as at 31 January 2011.
Comparison of proposed IFRS, MCEV principles & Solvency II
Table A1 below summarises key similarities and differences between:
Comparison of Proposed IFRS, MCEV Principles and Solvency II QIS 5
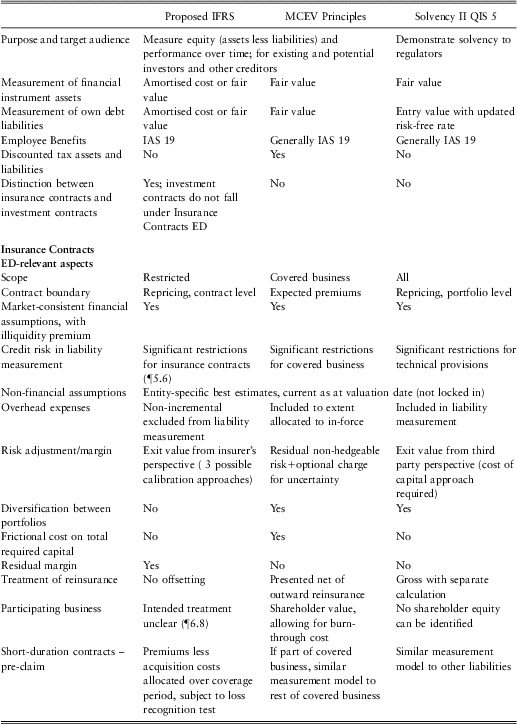
– Proposed IFRS (defined in ¶1.2);
– the MCEV Principles (CFO Forum, 2009a);
– Solvency II QIS 5 Technical Specifications, considering the valuation of assets and liabilities underlying the “own funds” calculations, and ignoring the capital requirement calculations.
It is noted that this is a brief high level summary only, ignoring much of the detail.
Potential impact on some typical UK products
B.1 This appendix provides a comparison of illustrative projected earnings between Existing IFRS (as typically applied by UK life insurers) and Proposed IFRS (specifically the Insurance Contracts ED) for two typical UK life insurance products: an immediate annuity and a term assurance. A simple profit test model was used for these illustrations. It is noted that a similar pre-tax accounting result would be achieved over the lifetime of these contracts; proposed changes only alter the timing of profit recognition.
B.2 Immediate annuity
On contracts of longer duration, such as immediate annuities, consequences from the proposals are likely to be more important in relation to gain or loss at inception. Assuming pricing incorporates some of the anticipated investment spreads (less an allowance for credit risk), discounting using a risk free rate plus illiquidity premium would likely lead to reduced profits (pre-residual margin) and potentially losses on day one. Our illustrative example, Figure B1, uses a proportion of expenses attributable to overheads of 40%.
Earnings profile of an annuity

The key differences, comparing projected earnings (before tax) for this portfolio of immediate annuity contracts between Proposed IFRS and Existing IFRS, come from the different discount rates and non allowable acquisition costs. In particular:
– The year 1 profit shown in Existing IFRS will disappear under Proposed IFRS as a result of the residual margin. The present value of fulfilment cash flows calculation underlying this specific Proposed IFRS example provides a small profit, which is zeroised by the residual margin. (It is possible that in practice the present value of fulfilment cash flows calculation could lead to a day one loss, given potential differences between the ED discount rate and the pricing discount rate.).
– The non-incremental acquisition costs and overheads are excluded from the present value of fulfilment cash flows calculation and so are expensed at inception, creating a day one loss.
– The profits are deferred over the life of the contract, and are released with the residual margin over the life of the contract.
B.3 Term Assurance
For a portfolio of term assurance contracts, the example in Figure B2 shows a small day one loss at outset under Existing IFRS. The day one loss increases under Proposed IFRS, due to the exclusion of non-incremental acquisition costs and overheads.
Earnings profile of a term assurance policy