


Introduction
When deciding whether or not to implement a project or regulatory intervention aimed at maintaining public safety or safety in the workplace, decision-makers must effectively confront three different types of question. In particular:
-
• What are the key features of the potential hazard or harmful event under consideration and what is the nature of the damage that might be caused if it were to occur? How well is the hazard understood and to what extent can the risk and uncertainty associated with the hazard be quantified?
-
• What safety improvement options are available for reducing the probability of occurrence of the potential hazard and what are the economic and/or social costs of implementing these options?
-
• To what extent will each of the various safety improvement options actually reduce the probability of occurrence of the hazardous event – or mitigate its potentially harmful consequences – and how should the benefits of these risk reductions be valued so that they can be weighed against the cost of implementation in order to decide whether or not the safety improvement should be carried out?
In addressing the first two types of question, it is clear that the decision-making body will have to rely largely on scientific and technical expertise backed up by well-informed judgement, particularly when dealing with the uncertainty associated with new technologies or as-yet poorly understood environmental phenomena.
However, when it comes to assessing the benefits associated with risk reduction and safety improvement, matters are less clear-cut. In particular, given that the costs of carrying out a safety improvement will ultimately be borne by members of the public – either through taxation, price increases or regulatory restrictions (such as motorway speed limits) – it seems important that the decision-making body should try to take at least some account of the public's preferences and attitudes to risk in valuing a safety improvement in order to decide whether the benefits of the improvement are sufficient to justify incurring the costs of implementing it. Given that the costs of implementing a safety improvement are most naturally measured in monetary units, there is therefore clearly a strong case on both ethical and practical grounds for basing the valuation of safety on the public's willingness to pay for it. More specifically, provided that an individual is well informed about the properties of a good or service and the prices of alternative objects of expenditure, then it seems reasonable to argue that his/her maximum willingness to pay for the good or service provides an indication of the individual's strength of preference for it, relative to other potential objects of expenditure, bearing in mind his/her overall budget constraints. Under what is naturally referred to as the ‘willingness-to-pay’ (WTP) approach, one therefore attempts to determine the maximum amounts that people would individually be willing to pay for (typically small) improvements in their own and (possibly others') safety – see, for example, Jones-Lee (Reference Jones-Lee1976) and Viscusi (Reference Viscusi1978). Given that the aim is to determine people's willingness to pay for typically small reductions in physical risk, the principal focus of WTP-based studies has naturally been on the rate at which members of the public are willing to trade off wealth against risk of death or injury at the margin.
But how, in practice, should a decision-making body set about determining the maximum amount that an affected individual would actually be willing to pay for a given safety improvement – particularly if the latter is to be provided in the form of a public good – and how should these individual amounts be aggregated into an overall benefit measure? More specifically, are members of the public sufficiently well informed about the risks of death and injury that they face for it to be possible to infer a reliable estimate of their valuation of safety from their occupational choices and everyday actions in a revealed preference study? Or is it reasonable to expect people to be able to provide reliable answers to questions concerning their willingness to pay for reductions in the risk of death or injury expressed as small reductions in already very small probabilities in a stated preference study? And even if we can obtain reasonably reliable estimates of individual willingness to pay, as argued in Cameron (Reference Cameron2010) and Hauer (Reference Hauer2011), there remain serious questions concerning the way in which these amounts should be aggregated into an overall benefit measure, given that the amounts concerned – and/or the individual risk reductions afforded by a safety improvement – may well vary somewhat across the group affected. Should we focus upon the group's mean willingness to pay or the median or some other central tendency measure, and should we apply distributional weights in the aggregation process?
The purpose of the present paper is twofold. First, we consider some of the more significant conceptual and practical problems that have been encountered in defining and estimating WTP-based values of safety and offer some suggestions concerning the way in which these problems might be dealt with. We then examine the approach that would appear to be the obvious alternative to basing the valuation of safety on the public's willingness to pay and instead involves exclusive reliance on the judgement of public sector decision-makers in setting the value to be accorded to safety improvement in the appraisal of proposed allocative or regulatory adjustments, thereby avoiding the necessity to confront the problems posed by estimation of WTP-based values.
WTP-based values of safety
As indicated in the ‘Introduction’ section, the basic aim of the WTP approach to the valuation of safety is to define and estimate the benefits of a safety improvement in such a way as to reflect the amounts that people would each individually be willing to pay for the (typically small) reductions in the risk of death or injury afforded by the safety improvement. To this would normally be added a component reflecting the direct economic costs that the safety improvement could be expected to avoid, such as damage to vehicles and property, as well as police and medical costs.
Thus, suppose that a large group of n people enjoy a safety improvement that reduces the probability of premature death during the forthcoming period by, on average, 1/n for each individual in the group. The arithmetic mean (or statistical expectation) of the number of deaths prevented is then precisely 1, and the safety improvement can therefore naturally be described as involving the prevention of one ‘statistical fatality’ – see, for example, Jones-Lee (Reference Jones-Lee1989) and Viscusi (Reference Viscusi1998). Aggregate willingness to pay for the safety improvement (plus avoided direct costs) is hence referred to as the WTP-based value of statistical life (VSL) or the value of preventing a statistical fatality for the group concerned. Given this definition of the VSL, it is extremely important to appreciate the fact that it is a measure of aggregate willingness to pay for very small risk reductions – which are what most safety improvements will actually provide for those affected – and is definitely not intended to reflect the amount that the typical individual would be willing to pay to avoid the certainty of immediate death or would be prepared to accept as compensation for the prospect. Clearly, an individual's willingness to pay is ultimately subject to his/her overall wealth constraints (i.e. ability to pay) and, as far as willingness to accept is concerned, for most of us, no sum (however large) would compensate for the prospect of immediate death.
While the standard definition of the VSL is based on aggregate willingness to pay for marginal reductions in the risk of death during the forthcoming period, it is clearly also possible to derive a VSL based on aggregate willingness to pay for marginal reductions in the risk of death that will only be effective at a later stage in affected individuals' lives. However, the resultant VSL would only be applicable to the valuation of these delayed risk reductions. It is also worth noting that a reduction of 1/n in an individual's probability of death during the forthcoming period would increase his/her life expectancy by E/n, where E is the individual's current remaining life expectancy. Summed over the group of n affected individuals, the total gain in life expectancy would therefore be equal to the average remaining life expectancy for individuals in the group. Since aggregate willingness to pay for the risk reductions (plus avoided direct costs) is equal to the VSL, it is therefore natural to define the value of a statistical life year as the VSL divided by average remaining life expectancy for the affected group.
However, as already noted, in order to apply the WTP approach in practice, two fundamental questions must be addressed. First, how can one best set about obtaining an unbiased and reliable measure of individual willingness to pay for small reductions in the probability of death or injury by a particular cause? Second, given that individual willingness to pay can be expected to vary significantly as a result of differences in preferences, age, attitudes to risk and ability to pay – and given that the risk reductions themselves may also vary across the affected group – how should individual willingness to pay be aggregated in order to arrive at an overall measure of benefit? In fact, the answer to the second question will depend to some extent on the answer to the first and, in particular, on the degree of confidence that the decision-maker has concerning the effectiveness of the empirical estimation procedure or preference elicitation method adopted as a means of obtaining estimates of individual willingness to pay for a safety improvement.
For example, suppose that it is decided to proceed on the basis of a stated preference survey of members of the public and suppose that – as is almost invariably the case in practice – the frequency distribution of responses in the stated preference WTP survey includes a few extreme upper- and lower-tail outliers – see, for example, Jones-Lee (Reference Jones-Lee1989: Ch. 4). In the case of lower-tail outliers, which usually take the form of zero responses, it is clearly possible that at least some of these are ‘protest bids’ reflecting the fact that, for whatever reason, the respondent objected to the nature of the question being asked. In particular, in past studies, having been asked why they had indicated that they would not be prepared to pay anything at all for a reduction in the probability of death or injury in a road accident during the coming year, some respondents have indicated that this was because they viewed the maintenance of road safety as the government's responsibility and that it should be funded from tax revenues to which the respondent was already contributing. At the other end of the distribution of responses, upper-tail outliers standing at several multiples of the ‘typical’ response are not uncommon, and one is bound to wonder whether, in reality, these amounts would be realistic or even affordable for the person concerned, the suspicion being that such responses are either ‘off the cuff’ and poorly thought out or deliberately set at what the respondent realises is an excessive level as a reflection of his/her distaste and objection to being asked a question of this nature.
In the next two sections, we set out in more detail the key issues related to the question of preference elicitation and aggregation and offer some suggestions concerning the way in which some of the difficulties encountered in the process might be resolved.
Estimating individual willingness to pay
Viewed from an international perspective, two broad avenues of approach have been applied in the empirical estimation of WTP-based values of safety, namely the ‘hedonic pricing’ (or revealed preference) approach – typically based on observed labour market wage/risk trade-offs – and the ‘contingent valuation’ (or stated preference) approach, which relies on respondents' answers to hypothetical WTP questions put to members of the public in representative sample surveys. For summaries of the findings of the two approaches, see Viscusi and Aldy (Reference Viscusi and Aldy2003) and Blaeij et al. (Reference Blaeij, Florax, Rietveld and Verhoef2003).
Both approaches have clear strengths and weaknesses and are arguably more appropriately seen as complementary rather than competing estimation procedures. However, whereas the hedonic pricing approach has been the principal means of obtaining empirical estimates of the VSL in the USA and Canada, the main focus in the UK and other European countries has been on the stated preference approach. In the UK, for example, this occurred at least in part as a result of the fact that some members of the Department of Transport (which was the first UK government agency to show an interest in WTP-based values of safety) were initially somewhat sceptical about the ability of members of the public to comprehend the key concepts underpinning WTP-based values and, as a result, pressed for an investigation of the public's understanding via direct questioning in a sample survey-based study – see Jones-Lee et al. (Reference Jones-lee, Hammerton and Philips1985).
In comparing the two approaches, it must be said that the obvious advantage of the hedonic pricing approach is that it is based on actual rather than hypothetical choices. On the other hand, the approach presupposes that workers are well informed about job risks and that market forces, rather than union pressure, are the main determinants of wage rates. The approach also requires the application of fairly complex statistical procedures in order to disentangle the wage/risk trade-off from the many other factors that are likely to influence wage rates, such as job skills, job location, industrial context and so on. In addition, the hedonic pricing approach would appear to be incapable of providing any information concerning the rates at which those employed in ‘safe’ occupations (such as lawyers or teachers) or, indeed, those not in paid employment (such as housewives/househusbands) are willing to trade income or wealth for risk. Finally – and perhaps most significantly – given that it is typically based on labour market data, while the hedonic pricing approach can certainly be expected to provide estimates of the value of workplace and industrial safety, it is far from obvious that these values will also be applicable in other contexts, such as transport, environmental pollution or domestic accidents.
In the case of the stated preference approach, its great advantages are that it allows the researcher to focus on the wealth/risk trade-off directly, ensuring that the sample upon which the analysis is based is adequately representative of the population as a whole and dealing with a wide variety of different types of risk, rather than just those arising in a labour market context. However, the disadvantages of the approach are equally obvious and include the fact that it is inevitably dealing with hypothetical rather than actual choices and that it presupposes that respondents understand the questions that are being put to them and that they will provide truthful and carefully considered answers.
Indeed, it has been argued that one of the most serious limitations of the stated preference approach when applied to the valuation of safety is a consequence of at least some respondents' limited understanding of the questions put to them and their resultant provision of spontaneous responses that are insufficiently carefully thought out – see, for example, Loomes (Reference Loomes2006). Critics of the stated preference approach have argued that this is clearly reflected in what is referred to as ‘scope insensitivity’, which occurs when a respondent either reports exactly the same willingness to pay for two different risk reductions or gives amounts that do not differ to the extent that might be expected.
In fact, one of the earliest and starkest examples of scope insensitivity in responses to WTP questions related to safety improvement is embodied in the results of a UK national sample survey reported in Jones-Lee et al. (Reference Jones-lee, Hammerton and Philips1985) and Jones-Lee (Reference Jones-Lee1989). In particular, in a nationally representative sample of over 1000 respondents, roughly 35% of the sample gave the same non-zero willingness to pay for a reduction of 5 in 100,000 in the annual probability of being killed in an automobile accident as for a 2 in 100,000 reduction. In addition, the sample mean response for the larger risk reduction was less than 50% more than the mean response for the smaller risk reduction, rather than being – as one might have expected – roughly twice that figure.
Broadly speaking, there would appear to be two ways of dealing explicitly with the scope insensitivity problem in stated preference studies aimed at estimating WTP-based values of safety. The first of these two approaches – which, as far as we are aware, has not so far been suggested in the literature, but we believe might at least constitute a partial resolution to the problem – attempts to avoid treating scope insensitivity as necessarily constituting evidence of irrationality and relies instead on a recognition of the fact that an individual's willingness to pay will increase strictly in proportion to the magnitude of risk reduction only if his/her underlying utility of wealth function is linear. If, as seems very much more likely to be the case, the utility of wealth function is strictly concave, then standard theory indicates quite clearly that willingness to pay will also be an increasing and strictly concave function of risk reduction – see, for example, Jones-Lee (Reference Jones-Lee1976: Ch. 5). In fact, it then turns out than any degree of scope insensitivity (other than complete insensitivity) can actually be accommodated by appropriate specification of the key underlying parameters of the utility of wealth function. Thus, suppose that an individual is asked to value two different risk reductions and, while he/she is willing to pay more for the larger risk reduction, his/her willingness to pay does not increase in proportion to the size of the risk reduction. As shown in Appendix A, it then transpires that provided the individual has a strictly concave underlying utility of wealth function, then he/she will have a well-defined, unique ‘marginal rate of substitution’ (MRS) of wealth for risk (i.e. the rate at which the individual is willing to trade-off wealth against risk at the margin), and this MRS will actually be larger than either of the willingness to pay/risk reduction ratios taken individually. In addition, the implied MRS of wealth for risk will be larger with smaller differences between the two willingness to pay amounts, given that the smaller the difference between these two amounts, the more concave will be the implied underlying valuation function.
By way of illustration, consider an individual whose WTP response for a 1 in 100,000 reduction in the risk of immediate death is, say, £10 and whose WTP response for a 1 in 1000 reduction is only £20. According to the result derived in Appendix A, the individual would in fact have a well-defined, unique MRS of wealth for risk of immediate death of £1.98 million. Thus, whereas the standard reaction to responses such as those specified in this example would be to regard them as displaying a high degree of scope insensitivity – thereby raising serious doubts about their credibility and reliability – by contrast, the procedure developed in Appendix A is quite capable of accommodating them as perfectly rational responses from someone with highly non-linear, but basically conventional preferences.
However, it has to be admitted that our suggested approach is subject to two potentially serious limitations. In the first place, while in principle it can accommodate any degree of scope insensitivity, it cannot deal with complete insensitivity (i.e. a situation in which a respondent reports precisely the same willingness to pay for two different risk reductions). In addition, it is important to appreciate that the results produced by this approach are highly sensitive to the degree of scope insensitivity actually displayed by a respondent. Thus, for example, for an individual whose WTP response for a 1 in 100,000 reduction in the probability of immediate death is £10 and whose WTP response for a 2 in 100,000 reduction is only £11, based on the result derived in Appendix A, the implied MRS of wealth for probability of immediate death would be £5.5 million. Given that exclusive reliance on the WTP response of £10 for the risk reduction of 1 in 100,000 would imply a MRS of £10 ÷ (1 ÷ 100,000) = £1 million, while exclusive reliance on the WTP response of £11 for the 2 in 100,000 risk reduction would yield a MRS of only £11 ÷ (2 ÷ 100,000) = £550,000, the figure of £5.5 million seems, to say the least, surprisingly large and would, in fact, be legitimately applicable in the computation of the individual's willingness to pay only for extremely small reductions in the risk of death (i.e. reductions well below 1 in 100,000).
It would therefore appear that while our proposal might constitute a possible resolution to the scope insensitivity problem, it should be applied with some caution. Our argument does, however, clearly indicate that if an individual's carefully thought out WTP responses do display scope insensitivity, then estimating his/her MRS of wealth for risk of death exclusively on the basis of willingness to pay for the smaller risk reduction will necessarily produce a conservative estimate.
In fact, the way in which those working in this area have actually attempted to deal with the scope-insensitivity problem – as well as other problems associated with respondents' difficulties in dealing with questions involving direct wealth/risk trade-offs – is by framing the questions put to respondents in such a way as to avoid the necessity to make a direct trade-off between wealth and probability of death. More specifically – and to take a concrete example – the VSL currently used by the UK Department for Transport, the Rail Safety and Standards Board and other UK public sector agencies was obtained by what has come to be known as the ‘chained approach’ – see Carthy et al. (Reference Carthy, Chilton, Covey, Hopkins, Jones-Lee, Loomes, Pidgeon and Spencer1998). Essentially, this approach involves breaking the trade-off between wealth and probability of death down into a number of conceptually more manageable stages than are required in a direct trade-off. More specifically, the stages are as follows:
-
• The respondent is first asked to specify his/her maximum willingness to pay for a complete and quick cure for a lesser severity of non-fatal injury and minimum willingness to accept compensation (WTA) for the certainty of sustaining the injury. From these WTP and WTA responses, it is then possible to infer – to a close approximation – the individual's MRS of wealth for risk of the non-fatal injury.
-
• The respondent is then asked to specify the maximum probability of treatment failure at which he/she would just be prepared to undergo a medical treatment that, if successful, would completely cure the injury, but if unsuccessful would result in immediate death. From this, it is then possible to estimate the individual's MRS of probability of the non-fatal injury for probability of death.
-
• By chaining together the estimated MRS of wealth for probability of the non-fatal injury and the estimated MRS of probability of the non-fatal injury for probability of death, it is then possible to derive the implied MRS of wealth for risk of death.
Notice first that at no stage in this process is the respondent required to make a direct trade-off between wealth and the probability of death or injury. Instead, he/she is asked about willingness to pay for a cure and willingness to accept compensation for the certainty of suffering the injury. Insofar as a risk trade-off is involved, this takes the form of a trade-off between probability of death and the certainty of suffering the consequences of the injury. Furthermore, the decisions with which respondents are actually confronted under the chained approach are of a type that is not particularly uncommon in everyday life. For example, most of us will at some time have had to make up our minds as to whether or not a particular medical treatment or medication is worth paying for, and anyone who has undergone an operation involving a general anaesthetic will almost certainly have had the possibility of a fatal outcome explained to them by the doctor or surgeon concerned.
A further point that it would seem important to address in the estimation of WTP-based values of safety is that there is by now extensive empirical evidence confirming the intuitively plausible hypothesis that, for many of us, the prospect of death or injury by some causes is viewed with a considerably greater degree of fear or dread than other causes – see, for example, Slovic et al. (Reference Slovic, Fischoff, Lichtenstein and Warner1981). Not surprisingly, therefore, it has been argued that WTP-based values of safety for more highly dreaded causes of death can be expected to stand at a significant premium in relation to the corresponding figures for less fearsome causes of death – see, for example, Sunstein (Reference Sunstein1997). However, recent work suggests that, in many cases, high-dread effects are, to all intents and purposes, largely offset by the impact of either low baseline risk, as in the case of rail accidents or fires in public places – see Chilton et al. (Reference Chilton, Jones-Lee, Kiraly, Metcalf and Pang2006, Reference Chilton, Jones-Lee, Metcalf, Loomes, Robinson, Covey, Spencer and Spackman2007) – or latency (i.e. delay in the onset of symptoms) in the case of cancer risks – see Cropper et al. (Reference Cropper, Aydede and Portney1994), Hammitt and Liu (Reference Hammitt and Liu2004) and McDonald et al. (Reference McDonald, Chilton, Jones-Lee and Metcalf2016).
Aggregating individual willingness to pay
Consider a large group of n individuals each enjoying a 1/n reduction in the probability of death by a particular cause during the coming year. The mathematical expectation of the number of deaths prevented by the risk reduction will then be precisely 1 and, as noted above, is hence referred to as the prevention of one statistical fatality. Given that an individual's MRS of wealth for risk of death is the rate at which he/she is willing to trade-off wealth against the risk of death at the margin, it follows that the individual's willingness to pay for a small reduction in the risk of death will be equal to his/her MRS multiplied by the risk reduction. Thus, provided that n is large – and hence 1/n is small – then the ith individual's willingness to pay for the 1/n reduction in the risk of death will be equal to m i × (1/n), where m i is the ith individual's MRS of wealth for risk of death. Aggregate willingness to pay for the prevention of one statistical fatality will therefore be equal to the sum of m i × (1/n) taken across all of the n affected individuals, which is by definition the arithmetic mean of m i for the group concerned.
It is therefore clear that provided all of those affected enjoy the same reduction in the risk of death and one is prepared to accord equal weight to all affected individuals' willingness to pay, then the VSL will be given by the arithmetic mean of m i plus an appropriate allowance for avoided direct costs, although the latter will usually be very small in relation to m̅.
But, of course, the argument just developed does depend crucially on the assumption of equal risk reductions and the accordance of equal weight to all affected individuals' willingness to pay. This therefore naturally raises the question of how the argument would be affected if, in fact, the risk reductions afforded by a safety improvement were to vary across the group affected and/or it was felt to be appropriate to apply distributional weights in the aggregation of individual willingness to pay.
Varying risk reductions
If, rather than being constant, the magnitude of the individual risk reductions afforded by a safety improvement actually varies across the group of individuals affected, then it seems fairly obvious that the aggregate WTP component of the VSL can be expected to differ somewhat from the arithmetic mean MRS of wealth for risk of death for the group concerned. More specifically, if those members of the group enjoying larger risk reductions also tend to have higher marginal rates of substitution, then it seems reasonable to expect that the WTP component of the VSL will exceed the mean of m i , and vice versa. Appendix B provides a formal proof of this result and specification of the extent to which the WTP component will actually differ from the arithmetic mean of m i .
A particular case in which varying risk reductions provide grounds for setting the WTP component of the VSL at a level that is in fact strictly less than the arithmetic mean of m i is that in which all affected individuals will be required to make the same financial contribution to funding the improvement. It could then be argued that the VSL should be defined on the basis of the minimum size that the individual risk reductions would need to be in order to make the safety improvement worthwhile to all of those affected, or at least make some better off and none worse off. As shown in Appendix B, it then transpires that the WTP component of the VSL should be set equal to the harmonic mean of m i , where the harmonic mean of a variable is the inverse of the arithmetic mean of the inverse of the variable and, as originally demonstrated by Augustin-Louis Cauchy, is necessarily smaller than the arithmetic mean for a sample of non-constant, non-negative variables.
According to the argument developed so far, it is therefore clear that if a safety improvement is such that all of those affected will enjoy the same reduction in the risk of death, then it would seem appropriate to set the WTP component of the VSL equal to the arithmetic mean of m i . By contrast, if the risk reductions are not constant and individuals with higher levels of m i tend to enjoy larger risk reductions, then there would appear to be an argument in favour of setting the WTP component of the VSL at a level that actually exceeds the arithmetic mean, m̅. In turn, if all of those affected will be required to pay the same tax in order to finance the safety improvement, then it would seem appropriate to set the WTP component of the VSL equal to the harmonic mean of m i , which will necessarily be less than the arithmetic mean if m i varies across the affected group.
A further reason why the WTP component of the VSL might be set at a level that differs from the arithmetic mean of m i is based on the suggestion that at least some attention should be paid to the median value of m i for the affected group of individuals. More specifically, in a report prepared for the UK Inter-Departmental Group for the Valuation of Life and Health, Wolff and Orr (Reference Wolff and Orr2009) argue that since the distribution of m i across the affected population is typically highly right-skewed, the exclusive reliance on the arithmetic mean of m i in determining the level at which the VSL should be set could result in a situation in which a majority of those affected are paying more in, say, taxes to finance a safety improvement than the risk reduction afforded by the improvement is really worth to them. If, by contrast, the VSL were to be based on the median of m i , then provided that all affected individuals enjoyed more or less the same risk reduction and made roughly the same contribution to financing the safety improvement, then it would be far more likely that at least 50% of those affected would enjoy a positive net benefit. An additional argument in favour of paying careful attention to the median of m i – and not relying exclusively on the arithmetic mean in estimating the VSL – is that this can be expected to result in considerably less variability in the estimates derived from different studies, quite simply because the effect of outliers is thereby greatly reduced. Given that critics of the WTP-based approach to the valuation of safety have tended to identify the variability of the estimates of the VSL obtained from different studies as casting serious doubt on the reliability of the approach as a decision-making tool – see, for example, Kornhauser (Reference Kornhauser2000) or Hauer (Reference Hauer2011) – any reduction in variability clearly attenuates such criticism.
Distributional weighting
The first and most obvious reason for applying non-uniform weights to individual willingness to pay is that wealthier individuals are able – and hence typically willing – to pay more for a given safety improvement than those who are less well-off. Unweighted aggregation of individual willingness to pay would therefore almost certainly result in a VSL for the prevention of a fatality in a high-income section of society that was significantly larger than the corresponding figure for a lower-income group. In view of this, there is clearly an essentially egalitarian argument in favour of computing the VSL as the distributionally weighted mean of m i (rather than the straightforward arithmetic mean), with weights that are inversely related to individual income or wealth. This is effectively what happens when a single VSL – computed as the arithmetic mean of m i derived from a nationally representative sample – is applied in all cases, whatever the income level of the group affected by a safety improvement, which is tantamount to the application of distributional weights that are inversely related to income or wealth.
The second reason for avoiding exclusive reliance on the unweighted arithmetic mean of m i in the computation of the VSL is the possibility that, as already noted, in a stated preference study, some respondents may have provided poorly thought out or even deliberately misleading answers. As a result, the distribution of WTP responses in a stated preference study will almost invariably include a few ‘suspect’ top- and bottom-end outliers. There is therefore clearly an argument in favour of basing policy decisions on a VSL computed from the ‘trimmed mean’ of individual WTP responses, with these dubious top- and bottom-end outliers omitted from the calculation. This does, however, inevitably require a significant element of judgement in deciding which responses should be omitted.
Exclusive reliance on the judgement of public sector decision-makers
While the preceding sections have focused on the WTP approach as a means of capturing and quantifying the public's strength of preference for safety improvement, we have still not addressed the fundamental question of whether, on balance, it would instead be preferable to rely exclusively on the judgement of public sector decision-makers in determining the value to be accorded to any given safety improvement. In particular, as noted in the ‘Introduction’ section, it could be argued that given the complexity and somewhat abstract nature of the question, it would actually be more appropriate to leave the task of setting a specific value on safety benefits to the well-informed and balanced judgement of public sector decision-makers, given that these decision-makers are ultimately answerable to the government that has been elected to represent the interests of the public.
However, care has to be shown in following such an approach. For example, as argued in Jones-Lee (Reference Jones-Lee1989), exclusive reliance on the judgement of public sector decision-makers in the valuation of safety improvement is likely to result in serious inconsistency in the treatment of safety effects both between different decision-makers and on the part of a given decision-maker in relation to different safety projects. In particular, evidence from both the UK and USA revealed widely divergent implicit values of safety from past safety investment and regulatory decisions – see Carlson (Reference Carlson1963) and Card and Mooney (Reference Card and Mooney1977). For example, in decisions taken prior to the 1980s in the UK, these implicit values ranged from less than £1000 per life saved (from a decision not to legislate for the child-proofing of drug containers) to more than £20,000,000 (from high-rise apartment safety standards introduced following the Ronan Point disaster, which involved the partial collapse of a multi-storey tower block in East London). The clear implication of this is that a simple transference of resources from high-rise apartment safety to the child-proofing of drug containers would, on balance, have saved lives at no additional overall resource cost.
Indeed, it was at least in part these apparent inconsistencies – as well as the difficulties posed by the question of how to determine the appropriate value to place on safety improvement in different contexts – that originally led government agencies in the UK, USA and some other developed countries to commission research explicitly aimed at estimating the public's willingness to pay for safety improvement – see, for example, Spackman et al. (Reference Spackman, Evans, Jones-lee, Loomes, Holder, Webb and Sugden2011).
However, one is still bound to wonder how members of the public can be expected to place a well-considered value on a safety improvement if the potential causes and possible consequences of the hazard concerned are subject to the degree of uncertainty and relatively limited understanding currently associated with phenomena such as global warming, the outbreak of a pandemic or the failure of a newly developed technology. The answer to this question would appear to be that, in such cases, it is very important to draw on the insights afforded by both so-called ‘risk analysis' and research aimed at revealing the public's valuation of safety in the decision-making process. More specifically, given the inherent complexity of the process, in cases such as these, it would seem to be essential to break the decision concerning the acceptability of a proposed safety improvement down into two separate components, namely:
-
• A risk analysis examining the nature and extent of the risk reduction that may be afforded by the safety improvement under consideration, together with a clear specification of the strength of knowledge supporting the likelihoods used in the analysis. In particular, a carefully conducted risk analysis will make due allowance for the possibly limited nature of the technical and scientific understanding of the hazard to which the safety improvement will be applied, as well as the degree of uncertainty associated with the actual effectiveness of the safety improvement itself – see, for example, Aven (Reference Aven2012).
-
• Specification of the value that should be accorded to each of the possible outcomes identified in the risk analysis.
Thus, while it is clear that a substantial degree of technical expertise will be required in order to carry out an effective risk analysis, it is equally clear that if public sector and government decisions are to reflect the preferences and attitudes to risk of members of the public, then it is essential that the decision-maker should have access to information concerning at least the broad order of magnitude of the value that members of the public would place on each of the different levels of risk reduction that the safety improvement may be judged to be capable of generating. Given this information concerning the public's valuation of different levels of risk reduction, the decision-maker will then be in a position to place the appropriate value on whatever figure it actually arrives at concerning the magnitude of the risk reduction following a carefully conducted risk analysis.
More specifically, in considering the relationship between risk analysis and the valuation of safety, it is important to appreciate that in stated preference studies aimed at determining WTP-based values, respondents are typically asked to value clearly specified probability reductions, with no reference being made to the uncertainty that may, in reality, be associated with the background knowledge on which such probabilities are actually based. The reason for proceeding in this way is that since most members of the public appear to find even well-specified probabilities rather difficult to deal with from a conceptual point of view, it seems unlikely that they would be able to cope adequately with the idea that the probabilities themselves are not fixed, but rather depend on the background knowledge of the assessor. It might therefore reasonably be argued that WTP-based values should be viewed as being effectively ‘conditional’ figures reflecting the public's willingness to pay for a safety improvement conditional on the assumption that the improvement will provide a clearly specified reduction in the probability of death or injury.
Thus, whereas the probabilities involved in the typical safety improvement decision are, in reality, subjective figures based on limited background information and therefore reflect knowledge-based (or ‘epistemic’) uncertainty, in stated preference studies, these probabilities are typically presented to respondents as if they were objective relative frequencies reflecting only stochastic (or ‘aleatory’) uncertainty – see Aven (Reference Aven2012). Much the same applies to revealed preference studies based on observed wage/risk trade-offs in labour markets, in that the probabilities of work-related death or injury used in such studies are typically specified on the basis of historical relative frequencies and then treated as if they were essentially objective data.
As argued in Jones-Lee and Aven (Reference Jones-Lee and Aven2009), it is therefore essential that, in practice, WTP-based values should be viewed as constituting only part of a decision-making apparatus that also includes a risk analysis aimed at taking account of the uncertainty associated with the background knowledge and data upon which probabilities and the predicted outcomes of decisions are actually based.
Conclusions
In summary, it is clear that any valuation of safety using WTP figures should be interpreted as decision support aimed at informing the decision-maker, rather than providing the ‘final answer’. The tool has weaknesses and limitations as discussed above, and these need to be reflected at the final stage of the decision-making process. Nonetheless, in spite of these limitations, all things considered, there appear to be very persuasive ethical and practical arguments in favour of ensuring that, so far as possible, public sector allocative and regulatory decisions should take full account of the public's valuation of safety.
All of this having been said, one must of course recognise the possibility that the results of a cost–benefit analysis based on WTP values of safety may turn out to sit uncomfortably with other objectives set by the decision-making body concerned. For example, it is entirely possible that the European Commission's Road Safety Target (which has been endorsed by the European Transport Safety Council), aimed at halving the road fatality rate by 2020, could be achieved only by undertaking some road safety improvements that do not pass a strict cost–benefit test based on WTP values of safety. Under such circumstances, it is clearly necessary for the decision-making body to weigh the desirability of meeting its target against the net cost of implementing some projects that do not satisfy the standard cost/benefit criterion. But this does not mean that the results of the cost–benefit analysis are irrelevant. Indeed, we would argue that they are extremely important, in that they provide the decision-making body with a clear cautionary reminder of what might reasonably be regarded as the effective cost of meeting its pre-set target.
Appendix A
A possible resolution to the problem of scope insensitivity
Suppose that an individual's cardinal utility of wealth function, U(w), conditional on survival of the forthcoming period, takes the homogeneous form:
 $$U\left( w \right) = \alpha - \left( {w - \beta} \right)^{ - 1}, {\rm} \alpha \gt 0,{\rm} 0 \le \beta \lt \bar w$$
where
 $\bar w$
denotes the individual's current level of wealth.
This utility function is clearly well behaved in that it is increasing in wealth, strictly concave and also meets the standard conditions of being bounded above and implying decreasing absolute financial risk aversion – see Arrow (Reference Arrow1971: Ch. 3). In addition, suppose that the individual's cardinal utility of wealth function, D(w), conditional on death during the coming period, takes the form:
 $$D\left( w \right) = - k\left( {w - \beta} \right)^{ - 1}, {\rm} 0 \le k \le 1$$
Clearly, the magnitude of
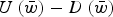 $U\left( {\bar w} \right) - D\left( {\bar w} \right)$
captures the extent of the individual's aversion to the prospect of his/her own premature death, while the magnitude of the constant, k, reflects the degree of the individual's concern for the financial wellbeing of his/her surviving dependents.
Assuming that the individual behaves as an expected utility maximiser, then by the standard argument – see, for example, Jones-Lee (Reference Jones-Lee1989, Ch. 3) – his/her MRS, m, of wealth for risk of death during the coming period is given by:
 $$m = \displaystyle{{U\left( {\bar w} \right) - D\left( {\bar w} \right)} \over {\left( {1 - \bar p} \right)U^{\prime}\left( {\bar w} \right) + \bar pD^{\prime}\left( {\bar w} \right)}}$$
where
 $\bar p$
is the individual's current probability of death during the coming period and
 $U'\left( {\bar w} \right)$
and
 $D'\left( {\bar w} \right)$
denote the first derivatives of U(w) and D(w) evaluated at
 $w = \bar w$
.
Denoting
 $\bar w - \beta $
by γ, it then follows from equations (1), (2) and (3) that:
 $$m = \displaystyle{{\alpha \gamma ^2 - \left( {1 - k} \right)\gamma} \over {1 - \left( {1 - k} \right)\bar p}}$$
In turn, let x denote the individual's maximum willingness to pay for a reduction δp in
 $\bar p$
. It then follows from expected utility theory that x and δp will satisfy the following condition:
 $$\eqalign{& \left( {1 - \bar p + \delta p} \right)\left[ {\alpha - \left( {\gamma - x} \right)^{ - 1}} \right] - \left( {\bar p - \delta p} \right)k\left( {\gamma - x} \right)^{ - 1} \cr & \quad = \left( {1 - \bar p} \right)\left( {\alpha - \gamma ^{ - 1}} \right) - \bar pk\gamma ^{ - 1} }$$
Solving for α from equation (5) and substituting in equation (4) then gives:
 $$m = \displaystyle{{x\gamma \left[ {1 - \left( {1 - k} \right)\left( {\bar p - \delta p} \right)} \right]} \over {\delta p\left( {\gamma - x} \right)\left[ {1 - \left( {1 - k} \right)\bar p} \right]}}$$
From equation (6), it then follows that the WTP responses x 1 and x 2 for two different risk reductions δp 1 and δp 2 will satisfy the following condition:
 $$\displaystyle{{x_1 \left[ {1 - \left( {1 - k} \right)\left( {\bar p - \delta p_1} \right)} \right]} \over {\delta p_1 \left( {\gamma - x_1} \right)}} = \displaystyle{{x_2 \left[ {1 - \left( {1 - k} \right)\left( {\bar p - \delta p_2} \right)} \right]} \over {\delta p_2 \left( {\gamma - x_2} \right)}}$$
Solving for γ from equation (7), substituting into equation (6) and rearranging then gives:
 $$m = \displaystyle{{x_1 x_2 \left( {\delta p_2 - \delta p_1} \right)} \over {\delta p_1 \delta p_2 \left( {x_2 - x_1} \right)}}$$
Given the strict concavity of U(w) and the relationship between D(w) and U(w), it follows that x will be an increasing and strictly concave function of δp – see, for example, Jones-Lee (Reference Jones-Lee1976 Ch. 5). Hence, if δp 2 > δp 1 , then x 2 > x 1 and x 1 /δp1 > x 2 /δp2, which would be regarded as constituting a degree of scope insensitivity. Nonetheless, it is clear from the argument developed that the individual's MRS, m, is well defined. In addition, given that x 1 /δp1 > x2/δp2 , it follows from equation (8) that m > x 1 /δp1 > x2/δp2 .
An argument similar to that just developed can, in principle, also be applied to other specifications of the underlying utility of wealth function – such as the logarithmic, negative exponential or nth-root forms – in order to estimate the MRS of wealth for risk of death on the basis of WTP responses for different risk reductions.
Appendix B
Varying risk reductions
Suppose that a large group of n individuals each enjoy a reduction of 1/n in the risk of death during the forthcoming period, thereby resulting in the prevention of one statistical fatality. Since n is large – and hence 1/n is small – the ith individual's willingness to pay for his/her risk reduction will be equal to m i × (1/n), where m i is his/her MRS of wealth for risk of death. It therefore follows that, summed across the group affected, aggregate willingness to pay, V, will be:
 $$V = \sum m_i \left( {1/n} \right)$$
 $$= {\rm} \left( {1/n} \right)\sum m_i $$
 $$= \bar m$$
where
 $\bar m$
denotes the arithmetic mean of m
i
.
Now suppose that, rather than being constant, the individual risk reductions in fact vary across the group affected by a safety improvement. Provided that the individual risk reductions, δp i , are small, then, when summing across all n affected individuals, aggregate willingness to pay, V, will be given by:
 $$V = \sum {\rm} m_i \;\delta p_i $$
 $$= n\;{\rm} \overline m {\rm} \;\delta \overline p + n{\rm} \;cov{\rm} \;(m_i, {\rm} \delta p_i )$$
where δp̅ is the mean of δp i and cov (m i , δpi) denotes the covariance between m i and δp i .
But if the safety improvement is expected to prevent one statistical fatality, then n δp̅ = 1, so that from equation (13), it follows that aggregate willingness to pay for the prevention of one statistical fatality is given by:
 $$V = \overline m + n\;{\rm} cov{\rm} \;(m_i, {\rm} \delta p_i )$$
Equation (14) therefore indicates that the WTP component of the VSL will be equal to the arithmetic mean of m i if and only if m i and δp i are uncorrelated. If, by contrast, m i and δp i are positively correlated, then the WTP component of the VSL will exceed m̅, while if they are negatively correlated, then it will be strictly less than m̅ with, in both cases, the extent to which the aggregate WTP component differs from m̅ being equal to the magnitude of the covariance between m i and δp i .
Next, suppose that the total cost of a proposed safety improvement is C and that the affected group of n individuals will each be required to make an equal contribution of C/n to finance the improvement. In order that the ith individual will be made no worse off, then his/her reduction in the probability of death, δp i , will have to be such that:
 $$m_i \,\delta pi \ge \displaystyle{C \over n}$$
where m i again denotes the ith individual's MRS of wealth for probability of death. Given that m i can be expected to vary across the affected group, it is therefore clear that the minimum level at which the risk reductions will have to be set in order to satisfy this condition will also vary across the group.
From equation (15), it then follows that:
 $$\delta p_i \ge \displaystyle{C \over {nm_i}} $$
Hence, from equation (16), it follows that in order to justify the overall expenditure, C, the expected number of fatalities prevented (i.e. ∑ δp i , with the summation taken over all of the n affected individuals) must be such that:
 $$\sum \delta p_i \ge \sum \displaystyle{C \over {nm_i}} $$
Now suppose that the safety improvement is expected to prevent one statistical fatality so that ∑ δp i = 1. In this case, it follows from equation (17) that if none of those affected by the safety improvement are to be made worse off, then the cost of financing the improvement must be such that:
 $${C \le }\displaystyle{n \over {\mathop \sum \nolimits \displaystyle{1 \over {m_i}}}} $$
Since C is the cost of preventing one statistical fatality and since the value of preventing a statistical fatality can naturally be regarded as the level that this cost must lie below if at least some of those affected are to enjoy a net benefit and none are to be made worse off, then it follows from equation (18) that the WTP component of the VSL is given by n/∑ 1/m i , which is, by definition, the harmonic mean, m̂, of m i . This, as originally demonstrated by Augustin-Louis Cauchy, is necessarily smaller than the arithmetic mean for a sample of non-constant, non-negative variables.


