1. Introduction
Let
 $X=\{ X_t, t\in T \}$
be a stationary random field on an unbounded index subset T of
 $\mathbb{R}^d$
,
 $d\ge 1$
, defined on an abstract probability space
 $(\Omega, \mathcal{F}, \mathbb P)$
. If
 $X_0$
is square-integrable then the classical definition of long range dependence is
 \begin{equation}\int_T |C_X(t)|\, {\textrm{d}} t=+\infty,\end{equation}
where
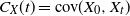 $C_X(t)=\textrm{cov}(X_0, X_t)$
,
 $t\in T$
. There are also other definitions, for example in terms of spectral density of X being unbounded at zero, growth comparison of partial sums (Allan sample variance), the order of the variance of sums going to infinity, etc.; see the recent reviews [Reference Giraitis, Koul and Surgailis15], [Reference Beran, Feng, Ghosh and Kulik5], and [Reference Samorodnitsky35] for processes and [Reference Lavancier20] for random fields. These approaches are not equivalent.
More importantly, there is no unified approach to defining the long memory property if X is heavy-tailed, i.e. with infinite variance. Many authors use the phenomenon of phase transition in certain parameters of the field (such as the stability index, Hurst index, heaviness of the tails, etc.) to consider the different limiting behaviour. To give just a few examples, we mention [Reference Sly and Heyde40] for the subordinated heavy-tailed Gaussian time series whereas [Reference Samorodnitsky34], [Reference Roy and Samorodnitsky32], [Reference Roy31], [Reference Owada and Samorodnitsky27], and [Reference Samorodnitsky and Wang37] consider the extreme value behaviour of partial maxima of stable random processes and fields and a connection with their ergodic properties. In [Reference Dehling and Philipp12, page 76], the short or long memory for stationary time series is defined by using different limits in functional limit theorems. The papers [Reference Damarackas and Paulauskas10] and [Reference Paulauskas28] analyse different measures of dependence (such as
 $\alpha$
-spectral covariance) for linear random fields with infinite variance lying in the domain of attraction of a stable law. These are used to define various types of memory and prove corresponding limit theorems for partial sums.
The main goal of our paper is to give a simple, uniform view of long range dependence that applies to any stationary (light- or heavy-tailed) random field X; see Definition 1. In Section 3.2 we show that all rapidly mixing random fields are short range dependent in the sense of the new definition. No moment assumptions are needed there. In Section 3.3 we give sufficient conditions for a subordinated Gaussian (possibly heavy-tailed) random field to be short or long range dependent. We show that the transition from short to long memory occurs at the same boundary for both finite and infinite variance random fields; see Theorem 2 and Example 1. This cannot be achieved using the classical definitions based on second-order properties. In the next section the same is done for stochastic volatility random fields of the form
 $X_t=G(Y_t)Z_t$
. Different sources of long range dependence are described. Conditions for long or short memory of
 $\alpha$
-stable moving averages and certain max-stable processes are discussed in the forthcoming paper [Reference Makogin, Oesting, Rapp and Spodarev25].
As indicated above, one can approach long memory from two different perspectives: through the distributional properties of the process or the limiting behaviour of suitable statistics. Our definition falls into the first category. Thus, as the next step, we attempt to link the definition with limit theorems. In this context, the appropriate statistic to study appears to be the volume of level sets of the field. This is done in Section 4. First, we consider subordinated Gaussian random fields and show the agreement between our definition and the limiting behaviour. See Section 4.1.1. In the following section we indicate that our definition is not suitable for capturing the limiting behaviour of the empirical mean. In Section 4.2 we consider the corresponding problems for random volatility models. In order to do so, we have to develop limiting theory for integral functionals of random volatility models, including the case of limit theorems for the volume of level sets of X. These results are of independent interest.
For better readability, proofs of the most of results are moved to the Appendix.
2. Preliminaries
Recall that T is an unbounded subset of
 $\mathbb{R}^d$
. Let
 $\mathbb N_0=\mathbb N\cup \{ 0 \}$
, and let
 $\nu_d(\cdot)$
be the d-dimensional Lebesgue measure. We let
 $\mathbb{R}_\pm$
denote either
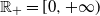 $\mathbb{R}_+=[0,+\infty)$
or
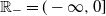 $\mathbb{R}_-=(-\infty,0]$
, depending on the context. For instance,
 $G\colon \mathbb{R}\to \mathbb{R}_\pm$
means that G maps
 $\mathbb{R}$
either to
 $\mathbb{R}_+$
or to
 $\mathbb{R}_-$
. Let
 $\|\cdot\|$
be a norm in the Euclidean space
 $\mathbb{R}^d$
. For two functions
 $f,g\colon \mathbb{R}\to \mathbb{R} $
we write
 $f(x) \sim g(x)$
,
 $x\to a$
if
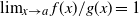 $\lim_{x\to a} f(x)/g(x)=1$
, where
 $g(x)\neq 0$
in a neighbourhood of a. Let
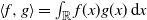 $\langle f, g\rangle = \int_{\mathbb{R}} f(x)g(x) \, {\textrm{d}} x$
be the inner product in the space
 $L^2(\mathbb{R})$
of square-integrable functions. Further, we shall make use of the inner product
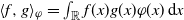 $\langle f, g\rangle_{\varphi} = \int_{\mathbb{R}} f(x)g(x)\varphi(x) \, {\textrm{d}} x$
in the space
 $L^2_{\varphi}(\mathbb{R})$
of functions which are square-integrable with the weight
 $\varphi$
, where
 $\varphi$
is the standard normal density. For a finite measure
 $\mu$
on
 $\mathbb{R}$
, let
 $\textrm{supp} (\mu)$
be its support, i.e. the complement of the largest measurable subset of
 $\mu$
-measure zero in
 $\mathbb{R}$
.
Let
 $(\Omega, \mathcal{F}, \mathbb P)$
be a probability space. We say that
 $\{ X_t, \; t\in T \}$
is white noise if it consists of independent and identically distributed (i.i.d.) random variables
 $X_t$
.
For any random variable X, let
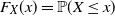 $F_X(x)=\mathbb P(X\le x)$
and
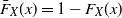 $\bar{F}_X(x)=1-F_X(x)$
be the cumulative distribution function and the tail distribution function of X, respectively. Let
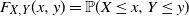 $F_{X,Y}(x,y)=\mathbb P(X\le x, Y\le y)$
,
 $x,y\in \mathbb{R}$
be the bivariate distribution function of a random vector (X,Y). Later on we make use of the formula
 \begin{equation} \textrm{cov}(X,Y)=\mathbb E ( \textrm{cov}(X,Y|\mathcal{A}) ) + \textrm{cov} ( \mathbb E(X|\mathcal{A}), \mathbb E(Y|\mathcal{A}) )\end{equation}
for any
 $\sigma$
-algebra
 $\mathcal{A}\subset \mathcal{F}$
.
A random field
 $X=\{X_t,t\in T\}$
is called associated (A) if
 \[\textrm{cov} (f (X_I) ,g (X_I) ) ) \ge 0 \]
for any finite subset
 $I\subset T$
and for any bounded coordinate-wise non-decreasing Borel functions
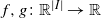 $f,g\colon \mathbb{R}^{|I|}\rightarrow\mathbb{R}$
, where
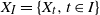 $X_I=\{X_t,t\in I \}$
. X is called positively associated (PA) or negatively associated (NA) if
 \[\textrm{cov} (f (X_I) ,g (X_J) ) ) \ge 0 \ (\le 0),\]
respectively, for all finite disjoint subsets
 $I,J\subset T$
, and for any bounded coordinate-wise non-decreasing Borel functions
 $f\colon \mathbb{R}^{|I|}\rightarrow\mathbb{R}$
,
 $g\colon \mathbb{R}^{|J|}\rightarrow\mathbb{R}$
; see e.g. [Reference Bulinski and Shashkin7].
We use the notation
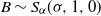 $B\sim S_{\alpha} (\sigma,1,0 ) $
for an
 $\alpha$
-stable subordinator B with scale parameter
 $\sigma>0$
; see [Reference Samorodnitsky and Taqqu36].
3. Long range dependence
Consider a real-valued stationary random field
 $X=\{X_t,t\in T\}$
. Introduce
 \[\textrm{cov}_X(t,u,v)=\textrm{cov} ({\bf 1}(X_0>u),{\bf 1}(X_t>v) ) , \quad t\in T, \ x,v\in \mathbb{R}.\]
It is always defined, as the indicators involved are bounded functions.
Definition 1. A random field
 $X=\{X_t,t\in T\}$
is called short range dependent (s.r.d.) if, for any finite measure
 $\mu$
on
 $\mathbb{R}$
,
 \[\sigma^2_{\mu,X}:=\int_T\int_{\mathbb{R}^2}|{\textrm{cov}}_X(t,u,v)|\, \mu({\textrm{d}} u)\, \mu({\textrm{d}} v)\,{\textrm{d}} t<+\infty ;\]
X is long range dependent (l.r.d.) if there exists a finite measure
 $\mu$
on
 $\mathbb{R}$
such that
 $\sigma^2_{\mu,X}=+\infty.$
For discrete parameter random fields (say, if
 $T\subseteq \mathbb Z^d$
), the
 $\int_T \,{\textrm{d}} t$
above should be replaced by
 $\sum_{t\in T\colon t\neq 0}$
.
3.1. Motivation
Assume that X is stationary with marginal distribution function
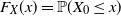 $F_X(x)=\mathbb P(X_0\le x)$
,
 $x\in\mathbb{R}$
, covariance function
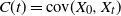 $C(t)=\textrm{cov}(X_0, X_t)$
,
 $t\in T$
, and moreover
 \begin{equation} \textrm{cov}_X(t,u,v)\ge 0 \mbox{ or } \le 0\quad \text{for all } t\in T, \ u,v\in\mathbb{R}.\end{equation}
Examples of X with this property are all PA or NA random functions. Applying [Reference Lehmann21, Lemma 2], we have (the equality is originally attributed to Hoeffding (1940))
 \begin{equation*} C_X(t)=\int_{\mathbb{R}^2} \textrm{cov}_X(t,u,v) \, {\textrm{d}} u\,{\textrm{d}} v.\end{equation*}
Then X is long range dependent if
 \begin{equation}\int_T |C_X(t)|\, {\textrm{d}} t=\int_T\int_{\mathbb{R}^2}|\textrm{cov}_X(t,u,v)|\, {\textrm{d}} u\,{\textrm{d}} v\,{\textrm{d}} t=+\infty,\end{equation}
which agrees with the classical definition.
However, in Definition 1 we integrate
 $|\textrm{cov}_X(t,u,v)|$
with respect to a finite measure
 $\mu\times\mu$
instead of Lebesgue measure
 ${\textrm{d}} u \, {\textrm{d}} v$
. First, for infinite variance the right-hand side of (4) is often infinite, regardless of any dependence structure. As such, the classical definition of long memory is irrelevant in the infinite variance case. Second, our definition will have a natural link with the asymptotic behaviour of volumes of excursions of X above levels u, v. Recall the functional central limit theorem (CLT) for normed volumes of excursion sets of X at level u proved in [Reference Meschenmoser and Shashkin26] (see also [Reference Spodarev41, Theorem 9] for a generalization of this result to fields without a finite second moment). Namely, for a large class of weakly dependent stationary random fields X on
 $\mathbb{R}^d$
, the function
 \[\int_{\mathbb{R}^d}\textrm{cov}_X(t,u,v)\,{\textrm{d}} t, \quad u,v\in\mathbb{R}\]
is the covariance function of the centred Gaussian process which appears as a limit of
 \begin{equation}\dfrac{\nu_d (\{ t\in [0,n]^d\colon X_t>u \}) -n^d \bar{F}_{X}(u) }{n^{d/2}}, \quad u\in\mathbb{R},\ n\to\infty\end{equation}
in
 $\mathcal{D}(\mathbb{R})$
equipped with the
 $J_1$
Skorokhod topology. If, in particular, the random field is PA or NA, then by the continuous mapping theorem we have
 \begin{equation}\dfrac{\int_{\mathbb{R}} \nu_d (\{ t\in [0,n]^d\colon X_t>u \}) \mu({\textrm{d}} u) -n^d \int_{\mathbb{R}} \bar{F}_{X}(u)\mu({\textrm{d}} u) }{n^{d/2}}\stackrel{d}{\longrightarrow} N(0,\sigma^2_{\mu,X})\end{equation}
as
 $n\to\infty$
for any finite measure
 $\mu$
with
 $\sigma^2_{\mu,X} $
as in Definition 1. So X is s.r.d. if the asymptotic covariance
 $\sigma^2_{\mu,X} $
in the central limit theorem (6) is finite for any finite integration measure
 $\mu$
prescribing the choice of levels u. In contrast,
 \begin{equation*} \sigma^2_{\mu,X}=+\infty\end{equation*}
for
 $\mu=\delta_{\{ u_0 \}}$
means that a different normalization is needed in (5) and a non-Gaussian limit may arise.
Let us point out one possible interpretation of Definition 1 in a financial context. Assume
 $X=\{ X_t, t\in \mathbb Z\}$
to be a time series representing the stock price for which an American option at price
 $u_0>0$
,
 $t\in [0,n]$
,
 $n\in\mathbb N$
is issued. The customer may buy a call at price
 $u_0$
whenever
 $X_t>u_0$
for some
 $t\in[0,n]$
. Relation (6) with
 $\mu=\delta_{\{ u_0 \}}$
is written as
 \[\dfrac{ \nu_1 (\{ t\in [0,n]\colon X_t>u_0 \}) -n \bar{F}_{X}(u_0) }{\sqrt{n}}\stackrel{d}{\longrightarrow} N(0,\sigma^2_{\delta_{\{ u_0 \}},X}),n \to \infty .\]
Then the long range dependence in the sense of Definition 1 of the stock price X (i.e.
 $\sigma^2_{\delta_{\{ u_0 \}},X} =+\infty$
) means that the amount of time within [0,n] at which the option may be exercised is not asymptotically normal for large time horizons n. In contrast, the short range dependence of stock X means asymptotic normality of this time span for any price
 $u_0$
for which the option was issued, provided that X satisfies the conditions of [Reference Meschenmoser and Shashkin26] or [Reference Spodarev41].
In terms of potential theory, the value
 $\sigma^2_{\mu,X}$
in Definition 1 is the energy of measure
 $\mu$
with symmetric kernel
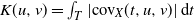 $K(u,v)=\int_T |\textrm{cov}_X(t,u,v)|\,{\textrm{d}} t$
; see [Reference Landkof19, page 77 ff.].
Self-similar random fields. We conclude this section with the formulation of long range dependence in a special case of self-similarity.
Let
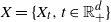 $X=\{X_t,t\in \mathbb{R}^d_+\}$
be a real-valued multi-self-similar random field. By definition, it is stochastically continuous and there exist numbers
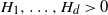 $H_1,\ldots,H_d>0$
such that, for a diagonal matrix
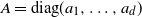 $A=\mbox{diag}(a_1,\ldots,a_d)$
with
 $a_1,\ldots,a_d>0$
, we have
 \[\{ X_{At}, \; t\in\mathbb{R}^d_+\} \stackrel{d}{=} \{ a_1^{H_1}\ldots a_d^{H_d} X_t, \; t\in\mathbb{R}^d_+\} .\]
Introduce the notation
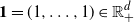 ${\bf 1}=(1,\ldots, 1)\in\mathbb{R}^d_+$
and
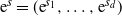 ${\textrm{e}}^s=({\textrm{e}}^{s_1}, \ldots, {\textrm{e}}^{s_d} )$
for
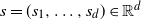 $s=(s_1,\ldots, s_d)\in\mathbb{R}^d$
. By [Reference Davydov and Paulauskas11, Proposition 6], the field
 \[Y=\{ Y_s= {\textrm{e}}^{-\sum_{j=1}^d s_j H_j } X_{{\textrm{e}}^s}, \; s\in\mathbb{R}^d\}\]
is stationary. Using Definition 1 for Y together with the substitution
 $t_i={\textrm{e}}^{s_i}$
,
 $i=1,\ldots, d$
, we say that X is s.r.d. if, for any finite measure
 $\mu$
on
 $\mathbb{R}$
,
 \[\int_{\mathbb{R}^d_+}\int_{\mathbb{R}^2} \biggl| {\textrm{cov}}\biggl({\bf 1} (X_{\bf 1}>u),{\bf 1}\biggl(X_{\bf t}>v\cdot \prod_{j=1}^d t_j^{H_j}\biggr) \biggr) \biggr|\, \dfrac{\mu({\textrm{d}} u)\, \mu({\textrm{d}} v)\, {\textrm{d}} t}{\prod_{j=1}^d t_j } <+\infty,\]
where
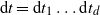 ${\textrm{d}} t={\textrm{d}} t_1\ldots {\textrm{d}} t_d$
means integration with respect to Lebesgue measure in
 $\mathbb{R}^d_+$
. Conversely, X is l.r.d. if the above integral is infinite for some finite measure
 $\mu$
on
 $\mathbb{R}$
.
3.2. Checking the short or long range dependence
Let
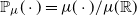 $\mathbb P_{\mu}(\cdot)=\mu(\cdot)/\mu(\mathbb{R})$
denote the probability measure associated with the finite measure
 $\mu$
on
 $\mathbb{R}$
. Let U,V be two independent random variables with distribution
 $\mathbb P_\mu$
. Then the variance
 $\sigma^2_{\mu,X}$
from Definition 1 becomes
 \begin{equation}\dfrac{\sigma^2_{\mu,X}}{\mu^2(\mathbb{R})}= \int_T \mathbb E |{\textrm{cov}}_X(t,U,V)|\,{\textrm{d}} t= \int_T \mathbb E |F_{X_0,X_t}(U,V)-F_{X_0}(U)F_{X_t}(V)|\,{\textrm{d}} t.\end{equation}
This relation is useful for checking the short range dependence of X by showing the finiteness of
 $\sigma^2_{\mu,X}$
for any i.i.d. random variables U and V. Definition 1 is equivalent to the following lemma.
Lemma 1. A stationary real-valued random field X with marginal distribution function
 $F_X$
is s.r.d. in the sense of Definition 1 if
 \[\int_T\int_{{(\operatorname{Im} F_X)^2}}| C_{0,t}(x,y)-xy |\, \mathbb P_0({\textrm{d}} x)\, \mathbb P_0({\textrm{d}} y)\,{\textrm{d}} t<+\infty\]
for any probability measure
 $\mathbb P_0$
on
 ${\operatorname{Im} F_X}$
, where
 $C_{0,t}$
is the copula of the bivariate distribution of
 $(X_0, X_t)$
,
 $t\in T$
, and
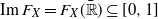 $\operatorname{Im} F_X=F_X(\bar{\mathbb{R}})\subseteq [0,1]$
is the range of
 $F_X$
on
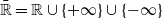 $\bar{\mathbb{R}}=\mathbb{R}\cup\{+\infty\}\cup\{-\infty\}$
; X is l.r.d. in the sense of Definition 1 if there exists a probability measure
 $\mathbb P_0$
on
 $\operatorname{Im} F_X$
such that the above integral is infinite.
Proof. By relation (7) and Sklar’s theorem (see e.g. [Reference Durante and Sempi14, Theorem 2.2.1]) we have, for any definite measure
 $\mu$
on
 $\mathbb{R}$
,
 \[\sigma^2_{\mu,X}={\mu^2(\mathbb{R})} \int_T\int_{\mathbb{R}^2}|C_{0,t}(F_X(u),F_X(v))-F_X(u)F_X(v)|\, \mathbb P_{\mu}({\textrm{d}} u)\, \mathbb P_{\mu}({\textrm{d}} v) \,{\textrm{d}} t.\]
The choice of
 $C_{0,t}$
is unique on
 $\operatorname{Im} F_X$
; see [Reference Durante and Sempi14, Lemma 2.2.9]. Applying the substitution
 $x=F_X(u)$
,
 $y=F_X(v)$
, we get
 \[\sigma^2_{\mu,X}={\mu^2(\mathbb{R})} \int_T\int_{(\operatorname{Im} F_X)^2}| C_{0,t}(x,y)-xy |\, \mathbb P_0({\textrm{d}} x)\, \mathbb P_0({\textrm{d}} y)\,{\textrm{d}} t,\]
where the probability measure
 $ \mathbb P_0$
has a cumulative distribution function
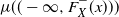 $\mu ( (-\infty, F_X^-(x)) ) $
,
 $x\in[0,1]$
, and
 $F_X^-$
is the generalized inverse for
 $F_X$
.

Lemma 1 implies that the new definition of memory is marginal-free, i.e. independent of the distribution of marginals
 $F_X$
if
 $\operatorname{Im} F_X=[0,1]$
, which is the case for absolutely continuous
 $F_X$
. It essentially involves only the bivariate dependence structure encoded in the copula
 $C_{0,t}$
.
If condition (3) holds, then application of the Fubini–Tonelli theorem leads to
 \begin{equation*}\sigma^2_{\mu,X}=\mu^2(\mathbb{R}) \int_T \textrm{cov} ( F_\mu (X_0), F_\mu (X_t) ) \, {\textrm{d}} t,\end{equation*}
where
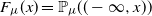 $F_\mu (x)=\mathbb P_\mu((-\infty, x))$
is the (left-side continuous) distribution function of probability measure
 $\mathbb P_\mu$
. In this case the s.r.d. condition
 $\sigma^2_{\mu,X}<+\infty$
reads as a classical covariance summability property of the subordinated random field
 $Y_t=F_\mu (X_t)$
,
 $t\in T$
.
By stationarity of X, we have
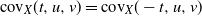 $\textrm{cov}_X(t,u,v)=\textrm{cov}_X(-t,u,v)$
for any
 $t,-t\in T$
,
 $u,v\in\mathbb{R}$
. Hence, in order to show long range dependence for
 $T=\mathbb{R}$
, it is enough to check that
 \[\int_0^\infty |\textrm{cov}_X(t,u_0,u_0)|\,{\textrm{d}} t=+\infty \]
for some
 $u_0\in\mathbb{R}$
. For
 $T=\mathbb Z$
it is sufficient to consider
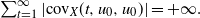 $\sum_{t=1}^\infty |\textrm{cov}_X(t,u_0,u_0)| =+\infty. $
3.2.1. Short range dependence for mixing random fields
Let
 $\mathcal{U}, \mathcal{V}$
be two sub-
 $\sigma$
-algebras of
 $\mathcal{F}$
. Introduce the z-mixing coefficient
 $z(\mathcal{U},\mathcal{V})$
(where
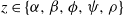 $z\in\{\alpha,\beta,\phi, \psi, \rho \}$
) as in [Reference Doukhan13, page 3]. For instance, it is given for
 $z=\alpha$
by
 \[\alpha(\mathcal{U},\mathcal{V}) = \sup\{ | \mathbb P(U \cap V)-\mathbb P(U)\mathbb P(V) |\colon U\in \mathcal{U}, \;V\in \mathcal{V} \}.\]
Let
 $X=\{X_t, t\in T\}$
be a random field. Let
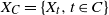 $X_C=\{X_t, t\in C\}$
,
 $C\subset T$
, and let
 $\sigma_{X_\mathcal{C}}$
be the
 $\sigma$
-algebra generated by
 $X_C$
. If
 $|C|$
is the cardinality of a finite set C, then the z-mixing coefficient of X is given by
 \[ z_X(k, u, v) = \sup\{z(\sigma_{X_A},\sigma_{X_B})\colon d(A,B) \geq k,\; |A| \leq u, |B| \leq v\},\]
where
 $ u,v \in \mathbb N $
and d(A,B) is the Hausdorff distance between finite subsets A and B generated by the metric on
 $\mathbb{R}^d$
. The interrelations between different mixing coefficients
 $z_X$
,
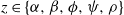 $z\in\{\alpha,\beta,\phi, \psi, \rho \}$
are given in [Reference Doukhan13, Proposition 1], for example.
We state the result that links mixing properties and the short range dependence. The field X may be non-Gaussian and have infinite variance.
Theorem 1. Let
 $X = \{X_t, t\in T\}$
be a stationary random field with z-mixing rate satisfying
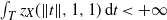 $\int_T z_X(\|t\|,1,1) \, {\textrm{d}} t < +\infty$
, where
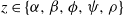 $z\in\{\alpha,\beta,\phi, \psi, \rho \}$
. Then X is s.r.d. in the sense of Definition 1 with
 \[\int_T\int_{\mathbb{R}^2} |\textrm{cov}_X(t, u, v)| \, {\mu}({\textrm{d}} u) \, {\mu}({\textrm{d}} v) \, {\textrm{d}} t \leq 8\int_T z_X(\|t\|,1,1) \, {\textrm{d}} t \cdot \mu^2(\mathbb{R})
< +\infty.\]
Proof. Without loss of generality, we prove the result for
 $\alpha$
-mixing X. Introduce random variables
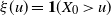 $\xi(u)={\bf 1}(X_0>u)$
,
 $\eta(v)={\bf 1}(X_t>v)$
, where
 $t \in T$
,
 $u,v \in \mathbb{R}.$
Then, by the covariance inequality in [Reference Doukhan13, Theorem 3] connecting the covariance of random variables with their mixing rates, we have
 \begin{align*} &\int_T\int_{\mathbb{R}^2} |\textrm{cov}_X(t, u, v)| \mu(\textrm{d} u) \mu( \textrm{d} v) \,\textrm{d} t = \int_T\int_{\mathbb{R}^2} |\textrm{cov}(\xi(u), \eta(v))| \mu(\textrm{d} u) \mu( \textrm{d} v) \,\textrm{d} t \\[3pt] &\quad \le 8 \int_T \alpha (\sigma_{X_0},\sigma_{X_t})\,\textrm{d} t \int_{\mathbb{R}^2 } \| \xi(u) \|_{\infty} \| \eta(v)\|_{\infty} \mu ({\textrm{d}} u) \mu ({\textrm{d}} v) \\[3pt] &\quad \leq 8\int_T \alpha_X(\|t\|,1,1)\,\textrm{d} t \cdot \mu^2(\mathbb{R})
< +\infty,\end{align*}
where
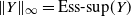 $ \| Y \|_{\infty} = \mbox{Ess-sup} (Y)$
.
To illustrate the above theorem, we let
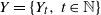 $Y=\{ Y_t, \, t\in \mathbb N \}$
denote a stationary almost surely (a.s.) non-negative
 $\psi$
-mixing random sequence with univariate cumulative distribution function
 $F_Y$
and
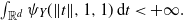 $\int_{\mathbb{R}^d} \psi_Y(\|t\|,1,1) \, {\textrm{d}} t < +\infty.$
Examples of
 $\psi$
-mixing random sequences can be found for example in [Reference Doukhan13, Example 4] (see also references therein), [Reference Heinrich16, Theorem 2.2], [Reference Rapaport29, Proof of Claim 2.5], [Reference Bradley6], and [Reference Samur38, pages 54–55]. Let
 $F^{-1}_Z$
be the quantile function of a random variable Z with
 $\mathbb E Z^2=+\infty$
. Set
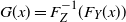 $G(x)=F^{-1}_Z(F_Y(x))$
,
 $x\ge 0$
; then
 $X_t=G(Y_t)$
,
 $t\in \mathbb N$
is
 $\psi$
-mixing as well. Moreover, it is s.r.d. by the last theorem and has infinite variance because of
 $X_0\stackrel{d}{=} Z$
.
Remark 1. For a Gaussian
 $\phi$
-mixing random field X, the statement of Theorem 1 is trivial, since such an X is m-dependent [Reference Ibragimov and Linnik17, Theorem 17.3.2], and the integral
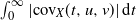 $\int_0^\infty |\textrm{cov}_X(t,u,v)|\,{\textrm{d}} t$
in Definition 1 is bounded by 2m for any
 $u,v\in\mathbb{R}$
.
3.3. Subordinated Gaussian random fields
Recall that
 $\varphi(x) $
is the density of the standard normal law. We use the notation
 $\Phi(x)$
for its cumulative distribution function. Introduce the Hermite polynomials
 $H_n$
of degree
 $n\in \mathbb N_0$
by
 \[H_n(x)=(-1)^n \varphi^{(n)}(x) / \varphi (x),\]
where
 $\varphi^{(n)}$
is the nth derivative of
 $\varphi$
. Clearly
 \[H_0(x)=1,\quad H_1(x)=x,\quad\ H_2(x)=x^2-1,\quad H_3(x)=x^3-3x, \quad \ldots . \]
For even orders n, Hermite polynomials are even functions, whereas for odd n they are odd functions. It is well known that Hermite polynomials form an orthogonal basis in
 $L^2_{\varphi}(\mathbb{R})$
. For any function
 $f\in L^2_{\varphi}(\mathbb{R})$
with
 $\langle f, 1\rangle_{\varphi} = 0$
, let
 \[\operatorname{rank} (f)=\min\{n\in\mathbb N\colon \langle f, H_n\rangle_{\varphi} \neq 0 \}\]
be the Hermite rank of f. Furthermore, the Hermite rank can also be defined for functions
 $f\not\in L^2_{\varphi}(\mathbb{R})$
, as long as
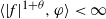 $\langle |f|^{1+\theta}, \varphi\rangle<\infty$
for some
 $\theta\in (0,1)$
; see [Reference Sly and Heyde40] or [Reference Beran, Feng, Ghosh and Kulik5, Section 4.3.5].
Let
 $Y = \{Y_t, t\in T\}$
be a stationary centred Gaussian real-valued random field with
 $\textrm{var}\, Y_t=1$
and
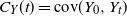 $C_Y(t)=\textrm{cov}(Y_0,Y_t)$
,
 $t\in T$
. The subordinated Gaussian random field X is defined by
 $X_t=G(Y_t)$
,
 $ t\in T$
, where
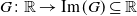 $G\colon \mathbb{R}\rightarrow \operatorname{Im}(G)\subseteq\mathbb{R}$
is a measurable function.
Assume first that X is square-integrable. The following lemma is proved in [Reference Rozanov33, Lemma 10.2].
Lemma 2. Let
 $Z_1, Z_2$
be standard normal random variables with
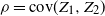 $\rho = \textrm{cov}(Z_1,Z_2)$
, and let F, G be functions satisfying
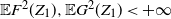 $\mathbb E F^2(Z_1), \mathbb E G^2(Z_1) < +\infty$
. Then
 \[\textrm{cov}(F(Z_1), G(Z_2)) = \sum_{k=1}^{\infty}\dfrac{\langle F, H_k\rangle_{\varphi} \langle G, H_k\rangle_{\varphi} }{k!}\rho^k . \]
Let
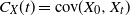 $C_X(t)=\textrm{cov}(X_0,X_t)$
,
 $t\in T$
. Assuming
 $C_Y(t)\ge 0$
for all
 $t\in T$
and applying this lemma to our subordinated process
 $X=G(Y)$
we get that it is s.r.d. in the sense of Definition 1 if
 \begin{equation} \int_T|C_X(t)| \, {\textrm{d}} t = \sum_{k=1}^{\infty}\dfrac{\langle G, H_k\rangle_{\varphi}^2}{k!}\int_T C_Y^k(t)\, {\textrm{d}} t <+\infty.\end{equation}
We shall see that an analogous result holds also if X has no finite second moment. Introduce the condition
(
 $\boldsymbol{\rho}$
)
 $ |C_Y(t)|<1$
for all
 $t\neq 0$
if T is countable, and for
 $\nu_d$
-almost every
 $t\in T$
if T is uncountable.
The following result gives the conditions for short range dependence of a subordinated Gaussian random field, without a moment assumption. Its proof is given in the Appendix.
Theorem 2. Let Y be the Gaussian random field introduced above. Let X be a subordinated Gaussian random field defined by
 $X_t=G(Y_t)$
,
 $t\in T$
, where G is a right-continuous strictly monotone (increasing or decreasing) function. Assume that condition (
 $\boldsymbol{\rho}$
) holds. Let
 \begin{equation}b_k(\mu)=\biggl(\int_{\operatorname{Im}(G)}H_{k}(G^-(u))\varphi(G^-(u)) \, \mu({\textrm{d}} u)\biggr)^2,\end{equation}
where
 $G^-$
is the generalized inverse of G if G is increasing or the generalized inverse of
 $-G$
if G is decreasing. Then X is s.r.d. in the sense of Definition 1 if and only if
 \begin{equation}\sum_{k=1}^{\infty}\dfrac{b_{k-1}(\mu)}{k!} \int_T |C_Y(t)| C_Y^{k-1}(t) \, {\textrm{d}} t <+\infty\end{equation}
for any finite measure
 $\mu$
on
 $\mathbb{R}$
.
Corollary 1. Assume that the conditions of Theorem 2 hold.
-
(i) Let
 $\mu({\textrm{d}} x)=f(x) \, {\textrm{d}} x$
for
$f\in L^1(\mathbb{R})$
such that
$f(x)\ge 0$
for all
$x\in\mathbb{R}$
. If
$G\in C^1(\mathbb{R})$
and
$\operatorname{Im}(G)=\mathbb{R}$
, then
$b_k (\mu)= \langle G^\prime f(G), H_k\rangle_{\varphi}^2$
,
$k\in \mathbb N$
. In this case all coefficients
$b_k(\mu)$
are finite if, for some
$\theta \in (0,1)$
, we have
$E[|G^\prime (Y_0)f(G(Y_0))|^{1+\theta}] < +\infty.$
If
$G^\prime f(G)$
is an even function then
$b_k(\mu)=0$
for all natural odd k.
-
(ii) If
$X_t=G(|Y_t|)$
,
$t\in T$
, then the s.r.d. condition (10) simplifies to
(11)
\begin{equation}\sum_{k=1}^{\infty}\dfrac{b_{2k-1}(\mu)}{(2k)!} \int_T C_Y^{2k}(t) \, {\textrm{d}} t <+\infty.\end{equation}
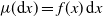


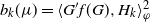


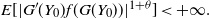


Remark 2. Based on Theorem 2 and Corollary 1, the long range dependence in the sense of Definition 1 can also be formulated as follows.
-
(i)
$X=G(Y)$
is l.r.d. if there exists
$ u_0\in\mathbb{R}$
such that
$ b_k(\delta_{\{u_0\}})<+\infty$
for all k and the series (10) diverges to
$+\infty$
. -
(ii) If the initial process Y is s.r.d. then all powers of
$C_Y$
are integrable on T and the long memory of
$X=G(|Y|)$
can only come from function G. This can happen, for example, if its coefficients
$b_k(\mu)$
decrease to zero slowly enough. Conversely, assume that Y is l.r.d.,
$ 0 < b_{2k-1}(\mu)< +\infty$
for all
$k \in \mathbb{N}$
and some finite measure
$\mu$
. If there exists
$ k\in \mathbb{N}$
such that
$\int_T C_Y^{2k}(t) \, {\textrm{d}} t = +\infty $
, then X is l.r.d.


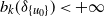


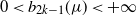


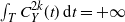
Let us illustrate the last point of Remark 2 with an example.
Example 1. Let
 $G(x)={\textrm{e}}^{x^2/(2\alpha)}$
,
 $\alpha>0$
,
 $T=\mathbb{R}^d$
. Then it is easy to see that
 \[\mathbb P (|X_0|>x)=L(x) x^{-\alpha},\]
where
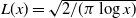 $L(x)=\sqrt{ 2/(\pi \log x) } $
. For
 $\alpha\in(1,2]$
,
 $\mathbb E \, X_0<\infty$
,
 $\mathbb E \, X_0^2=+\infty$
.
To compute
 $b_{2k-1}(\mu)$
, we notice that
 \[\sqrt{b_{2k-1}(\mu)}=\dfrac{1}{\sqrt{2\pi}}\int_1^\infty u^{-\alpha} H_{2k-1} (\sqrt{2\alpha \log u}) \, \mu({\textrm{d}} u), \quad k\in \mathbb N.\]
Using the upper bound
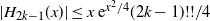 $ | H_{2k-1}(x) | \le x \,{\textrm{e}}^{x^2/4} (2k-1)!! /4$
,
 $x\ge 0$
from [Reference Abramowitz and Stegun1, page 787], one can show that
 \begin{align*}b_{2k-1}(\mu) &\le \dfrac{ \alpha}{16\pi} [(2k-1)!!]^2 \biggl( \int_1^\infty u^{-\alpha/2} \sqrt{\log u} \, \mu({\textrm{d}} u) \biggr)^2 \\[3pt] &\le \dfrac{ \alpha }{ 4\pi } \mu^2 ([1,+\infty)) [ (2k-1)!!]^2 \\[3pt] &<+\infty\end{align*}
for all
 $ k\in\mathbb N.$
We note that the use of the finite measure
 $\mu$
is crucial here, since for the Lebesgue measure the integral
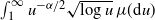 $\int_1^\infty u^{-\alpha/2} \sqrt{\log u} \, \mu({\textrm{d}} u)$
is infinite for
 $\alpha\leq2$
.
Now, by Stirling’s formula [Reference Andrews, Askey and Roy4, Theorem 1.4.2], we get
 \begin{equation*} \dfrac{[(2k-1)!!]^2 }{ (2k)! } \sim \dfrac{c_3}{\sqrt{k}}, \quad k\to +\infty\end{equation*}
for
 $c_3>0$
, so
 \begin{equation}\dfrac{b_{2k-1}(\mu)}{(2k)!}= O( \dfrac{1}{\sqrt{k} }) , \quad k\to +\infty.\end{equation}
Assume that
 $C_Y(t)\sim \|t\|^{-\eta}$
as
 $\|t\|\to +\infty$
,
 $\eta>0$
. Then
 $X={\textrm{e}}^{Y^2/(2\alpha)}$
,
 $\alpha >0$
, is
-
• l.r.d. if
$\eta\in (0, d/2]$
, since then
\begin{equation*}\sum_{k=1}^{\infty}\dfrac{b_{2k-1}(\mu)}{(2k)!} \int_T C_Y^{2k}(t) \, {\textrm{d}} t =+\infty;\end{equation*}
-
• s.r.d. if
$\eta> d/2$
, since then we have
and the series (11) behaves like
\[\int_{\mathbb{R}^d} C_Y^{2k}(t)\, {\textrm{d}} t =O(k^{-1}) \quad \text{as } k\to +\infty,\]
${\sum_{k=1}^\infty k^{-3/2} <+\infty.}$


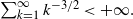
Here the source of long memory of X is the l.r.d. field Y. If
 $\alpha>2$
the variance of
 $X_0$
is finite, and our results agree with the definition in (1) by relation (8) if we note that
 $\operatorname{rank} (G)=2$
. However, the main point of this example is that we have the same transition from short to long memory (i.e.
 $\eta=d/2$
) for both finite and infinite variance fields.
Note that for
 $\eta\in (d/2, d)$
the Gaussian field Y is l.r.d. but the subordinated field
 $X={\textrm{e}}^{Y^2/(2\alpha)}$
is s.r.d. This agrees with the classical theory for finite variance, but is novel for infinite variance.
3.4. Stochastic volatility models
We present a way of constructing random fields with long memory by introducing a random volatility
 $G(Y_t)$
(being a deterministic function of a random scaling field
 $Y=\{ Y_t, t\in T \}$
) of a random field
 $Z=\{ Z_t, t\in T \}$
. We assume that Y and Z are independent. An overview of random volatility models and their applications in finance can be found in [Reference Shephard39] and [Reference Andersen, Davis and Mikosch3, Part II], for example. For each
 $t\in T$
,
 $X_t=G(Y_t)Z_t$
is a scale mixture of
 $G(Y_t)$
and
 $Z_t$
; see [Reference Steutel and van Harn42, Chapter VI, page 345]. Let
 $\bar{F}_Z=1-F_Z$
be the marginal tail distribution function of
 $Z_t$
for stationary Z.
For a finite measure
 $\mu$
, introduce the functional
 \[{D_{\mu}} (G(Y),Z_0) =\int_T\int_{\mathbb{R}^2}\textrm{cov} ( \bar{F}_Z (u/G(Y_0)),\bar{F}_Z (v/G(Y_t)) ) \mu(\textrm{d} u) \mu( \textrm{d} v)\,{\textrm{d}} t.\]
The next lemma follows trivially from relation (2), independence of Y and Z, and Tonelli’s theorem.
Lemma 3. Let a random field
 $X=\{ X_t, t\in T \}$
be given by
 $X_t=G(Y_t)Z_t$
, where
 $Y=\{ Y_t, t\in T \}$
and
 $Z=\{ Z_t, t\in T \}$
are independent stationary random fields, Z has property (3),
 $G\colon \mathbb{R}\to\mathbb{R}_{\pm}$
and
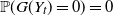 $\mathbb P (G(Y_t)=0)=0$
for all
 $t\in T$
. Then
 \begin{align}&\int_T \int_{\mathbb{R}^2}\textrm{cov}_X(t,u,v)\, \mu({\textrm{d}} u)\,\mu({\textrm{d}} v)\,{\textrm{d}} t \notag\\[3pt] &\quad = D_{\mu} (G(Y),Z_0) + \int_T \int_{\mathbb{R}^2}\mathbb E [ \textrm{cov}_Z(t,u/G(Y_0),v/G(Y_t))]\, \mu({\textrm{d}} u)\,\mu({\textrm{d}} v)\,{\textrm{d}} t.\end{align}
Let us illustrate the use of Lemma 3.
Corollary 2. Let the random field X be given by
 $X_t=A Z_t$
,
 $t\in T$
,
 $|T|=+\infty$
, where
 $A>0$
a.s., A and Z are independent, and
 $$Z \in {\bf{PA}}$$
is stationary. Then X is l.r.d. in the sense of Definition 1 if there exists
 $u_0\in \mathbb{R}$
such that
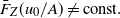 $\bar{F}_Z (u_0/A)\neq \textrm{const.}$
a.s.
The above corollary evidently holds true if, for example,
 $Z_0\sim \textrm{Exp}(\lambda)$
,
 $$A \sim $$
Fréchet(1) for any
 $\lambda>0$
. It also clearly applies to a sub-Gaussian random field X, where
 $A=\sqrt{B}$
,
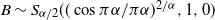 $B\sim S_{\alpha/2} ( ( \cos {{\pi\alpha}/{\pi\alpha}}) ^{2/\alpha},1,0 ) $
,
 $\alpha \in (0,2)$
, and Z is a centred stationary Gaussian random field with covariance function
 $C(t)\ge 0$
for all
 $t\in T$
and a non-degenerate tail
 $\bar{F}_Z$
.
The following corollary describes the situation where a light-tailed Y is responsible for the long range dependence of X while Z is responsible for heavy tails.
Corollary 3. For the random field
 $X=\{ X_t, t\in T\}$
given by
 $X_t=Y_t Z_t$
,
 $t\in T$
, assume that random fields
 $Y=\{ Y_t, t\in T\}$
and
 $Z=\{ Z_t, t\in T\}$
are stationary and independent. Assume that
 $Z_0$
has a regularly varying tail, that is,
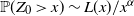 $\mathbb P(Z_0>x)\sim L(x)/x^\alpha$
as
 $x\to +\infty$
for some
 $\alpha>0$
, where the function L is slowly varying at
 $+\infty$
. For
 $Y_0>0$
a.s. assume that
 $\mathbb E Y_0^{\delta}<\infty$
and
 $\mathbb E ( Y_0^{\delta}Y_t^{\delta} ) <\infty$
for some
 $\delta>\alpha$
and all
 $t\in T$
. Let
 $Y, Z\in$
PA(NA). Then X is l.r.d. if
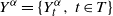 $Y^\alpha=\{Y_t^\alpha, \,t\in T\}$
is l.r.d.
Now we scale a l.r.d. (possibly heavy-tailed) random field Z by a random volatility G(Y) being a subordinated Gaussian random field.
Lemma 4. Let
 $X_t=G(Y_t) Z_t$
be a random field as in Lemma 3. Assume further that Y is a centred Gaussian random field with unit variance and covariance function
 $\rho(t)\ge 0$
satisfying condition (
 $\boldsymbol{\rho}$
). Then
 \begin{equation*}D_{\mu} (G(Y),Z_0) = \sum_{k=1}^\infty \dfrac{ \bigl( \int_{\mathbb{R}} \langle \bar{F}_Z (u/G(\cdot)), H_k(\cdot) \rangle_\varphi \, \mu({\textrm{d}} u) \bigr)^2 }{k!}\int_T \rho^k(t) \, {\textrm{d}} t .\end{equation*}
The following example illustrates our definition of long range dependence in the context of a popular long memory stochastic volatility model that is used in econometrics to model log-returns of stocks; see [Reference Beran, Feng, Ghosh and Kulik5, page 70 ff.] and references therein.
Example 2. Assume that
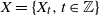 $X=\{X_t,t\in\mathbb Z\}$
has a form
 $X_t={\textrm{e}}^{Y_t^2 /4}Z_t$
, where
 $Z_t$
is a sequence of i.i.d. random variables with finite moment of order
 $2+\delta$
for some
 $\delta>0$
, while
 $Y_t$
is a centred stationary Gaussian PA long memory sequence with unit variance and covariance function
 $C_Y$
satisfying condition (
 $\boldsymbol{\rho}$
). Both sequences
 $Z_t$
and
 $Y_t$
are assumed to be independent of each other. From Example 1 we know that
 ${\textrm{e}}^{Y_0^2 /4}$
is regularly varying with index
 $\alpha=2$
. By Breiman’s lemma the tail distribution function of
 $|X_0|$
is also regularly varying with index
 $\alpha =2$
, and hence
 $X_0$
has infinite variance. Choose
 $\mu=\delta_{\{ u_0\}} $
for some
 $u_0\in\mathbb{R}$
. Lemmas 3 and 4 yield
 \begin{equation}\sum_{t=1}^{\infty} \int_{\mathbb{R}^2} {\textrm{cov}}_X(t,u,v) \mu({\textrm{d}} u)\mu({\textrm{d}} v) = \sum_{k=1}^\infty \dfrac{ \langle \bar{F}_Z(u_0/G), H_k\rangle_\varphi^2 }{k!} \sum_{t=1}^{\infty} C_Y^k(t) ,\end{equation}
where
 $G(x)={\textrm{e}}^{x^2/4}$
. Since
 $\bar{F}_Z(u_0/G)$
is symmetric, monotone non-decreasing, and bounded, we get
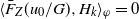 $\langle \bar{F}_Z(u_0/G), H_{k}\rangle_\varphi=0$
for all odd k, and it is finite for all even
 $k\in\mathbb N$
. Moreover, by Lemma 5(ii) we have
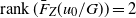 $\operatorname{rank}(\bar{F}_Z(u_0/G) )=2$
. It is clear that X is l.r.d. if
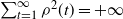 $\sum_{t=1}^\infty\rho^2(t)=+\infty$
. In particular, if
 $C_Y(t)\sim |t|^{-\eta}$
as
 $|t|\to\infty$
, then long range dependence occurs if
 $\eta\in (0,1/2]$
. Again, similarly to Example 1, the point here is that we obtain long memory for both finite and infinite variance.
4. Limit theorems
In this section we investigate connections between Definition 1 and limit theorems for random volatility and subordinated Gaussian random fields. In order to do so, we have to specify the statistic whose limiting behaviour we consider. We focus on the volume of the excursion sets.
In Section 4.1 we consider subordinated Gaussian random fields. In Section 4.1.1 we show by a natural example that our definition of long memory is in agreement with the existing limiting behaviour of the volume of excursions of X over some levels u. On the other hand, in Section 4.1.2 we will indicate that the limiting behaviour of the empirical mean cannot be directly related to our definition. The latter is not surprising.
In Section 4.2 we consider related problems for stochastic volatility random fields.
From now on we assume the random field X to be measurable. In what follows, L will indicate a slowly varying function at infinity, that can be different at each of its occurrences.
We start with the following lemma, which will play a major role.
Lemma 5. Let Y, Z be independent random variables such that
 $Y\sim N(0,1)$
. For any monotone right-continuous non-constant function
 $G\colon \mathbb{R}\to\mathbb{R}_\pm$
with
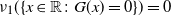 $\nu_1 (\{x\in\mathbb{R}\colon G(x)=0\} ) =0 $
, consider the functions
 $\widetilde{G}(y)=G(|y|)$
and
 \begin{equation}\zeta_{G,Z,u}(y)= \mathbb E[{\bf 1} \{G(y)Z>u\} ]-\mathbb P ( G(Y)Z>u) , \quad y\in \mathbb{R}\end{equation}
for a fixed
 $u> 0$
if
 $G\ge 0$
and
 $u<0$
if
 $G\le 0$
. Then the following hold.
-
(i) Let
$G\colon \mathbb{R}\to\mathbb{R}_\pm$
be as above such that
$\mathbb E |G(Y)|^{1+\theta}<+\infty $
for some
$\theta\in(0,1]$
. Then
\[ \operatorname{rank} (G)= \operatorname{rank}( \zeta_{G,1,u}) = \operatorname{rank}( \zeta_{G,Z,u})=1. \]
-
(ii) Let
$G\colon \mathbb{R}_+\to\mathbb{R}_\pm$
be as above such that
$\mathbb E |\widetilde{G}(Y)|^{1+\theta}<+\infty $
for some
$\theta\in(0,1]$
,
$G^-(u)\neq 0$
, where
$G^{-}$
is the generalized inverse of G. Then
\[ \operatorname{rank} (\widetilde{G})=\operatorname{rank}( {\zeta}_{\widetilde{G},1,u})= \operatorname{rank}( {\zeta}_{\widetilde{G},Z,u})=2. \]

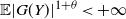


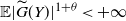


Remark 3.
-
(i) If
$Z\equiv 1$
, then the assertion of Lemma 5(i) holds under milder assumptions on G and u. Thus let
$G\colon \mathbb{R}\to\mathbb{R}$
be a monotone right-continuous non-constant function such that
$\mathbb E |G(Y)|^{1+\theta}<+\infty $
for some
$\theta\in(0,1]$
. Then, for any
$u\in\mathbb{R}$
,
$\operatorname{rank} ( G) =\operatorname{rank} ( \zeta_{G,1,u})=1$
. -
(ii) The assumption of non-negative or non-positive G is essential to the rank condition
$ \operatorname{rank} ( \zeta_{G,Z,u})=1$
of Lemma 5(i), since for
$G(y)=y$
and symmetric Z we have
$\mathbb E[Y {\bf 1} \{ YZ >u \}] =0,$
so the Hermite rank of
$\zeta_{G,Z,u} $
is greater than 1. Similarly, one can construct examples of functions G with
$\operatorname{rank} ( \zeta_{\widetilde{G},Z,u})>2$
for some
$u\in\mathbb{R}$
if the assumptions of Lemma 5(ii) do not hold. For instance,
$G^-(u)=0$
means that
$\operatorname{rank} ( \zeta_{\widetilde{G},Z,u})\ge 4$
. -
(iii) If G is non-negative or non-positive and
$u=0$
, then it is easily seen that
$\zeta_{G,Z,0}\equiv 0$
and, formally speaking, its Hermite rank is infinite.


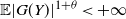


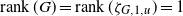
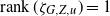

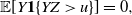


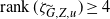


4.1. Limit theorems for subordinated Gaussian processes
Let
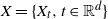 $X=\{ X_t, t\in\mathbb{R}^d \}$
, where
 $X_t= G(Y_t)$
and
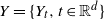 $Y=\{ Y_t, t\in \mathbb{R}^d \}$
is a stationary isotropic l.r.d. centred Gaussian random field with covariance function
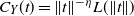 $C_Y(t)= \|t\|^{-\eta}L(\|t\|)$
,
 $\eta\in (0,d/q)$
(see [Reference Ivanov and Leonenko18], [Reference Leonenko22], and [Reference Leonenko and Olenko23]). Here
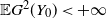 $\mathbb E G^2(Y_0)<+\infty$
and q is the Hermite rank of G. Under some technical assumptions on the spectral density
 $f(\lambda)$
of Y (see [Reference Leonenko and Olenko23, Assumption 2]),
 \begin{align*} n^{q\eta/2-d}L^{-q/2}(n)\int_{W_n}G(Y_t)\, {\textrm{d}} t \stackrel{d}{\longrightarrow} R, \quad n\to+\infty,\end{align*}
where
 \begin{align} R &= ( \gamma(d,\eta) ) ^{q/2}\int^\prime_{\mathbb{R}^{dq}} \int_W \,{\textrm{e}}^{{\textrm{i}}\langle \lambda_1+\ldots+\lambda_q,u\rangle} \,{\textrm{d}} u \dfrac{\tilde{B}(d\lambda_1) \ldots \tilde{B} (d\lambda_q)}{ ( \| \lambda_1\| \cdot \ldots \cdot \| \lambda_q\| ) ^{(d-\eta)/2}},\nonumber\\[3pt] \gamma(d,\eta) &=\dfrac{\Gamma ( (d-\eta)/2 ) }{2^\eta \pi^{d/2} \Gamma(\eta/2)},\end{align}
and
 $\int^\prime_{\mathbb{R}^{dq}} $
is the multiple Wiener–ItÔ integral with respect to a complex Gaussian white noise measure
 $\tilde{B}$
(with structural measure being the spectral measure of Y; see [Reference Ivanov and Leonenko18, Section 2.9]). It is easy to see that for
 $q=1$
the distribution of R is Gaussian. However, the normalization
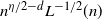 $n^{\eta/2-d} L^{-1/2}(n)$
differs from the usual CLT normalizing factor
 $n^{-d/2}$
, which agrees with the fact that X is l.r.d. in the sense of the usual definition as in (1). For
 $q\ge 2$
, we get a q-Rosenblatt-type distribution for R; see [Reference Veillette and Taqqu43] and [Reference Leonenko, Ruiz-Medina and Taqqu24] and references therein for its properties in the case
 $q=2$
.
4.1.1 Volume of level sets
We apply the above observations to level sets. Assume
 $G\colon \mathbb{R}\to\mathbb{R}$
to be a monotone right-continuous function such that
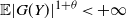 $\mathbb E |G(Y)|^{1+\theta}<+\infty $
with
 $\theta\in(0,1)$
. Let the variance of
 $X_0$
be infinite. For any
 $u\in\mathbb{R}$
introduce the function
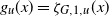 $g_u(x)=\zeta_{G,1,u} (x)$
, where
 $\zeta_{G,1,u} $
is given in (15). By Remark 3(i), the Hermite ranks of G and
 $g_u$
are equal to one. If
 $\eta\in (0,d)$
then
 \begin{align*}\dfrac{\int_{W_n}g_u(Y_t)\, {\textrm{d}} t}{n^{d-\eta/2}L^{1/2}(n)} = \dfrac{ \int_{W_n} {\bf 1} (G(Y_t)>u) \, {\textrm{d}} t - \nu_d(W_n) \mathbb P (G(Y_0)>u)}{n^{d-\eta/2}L^{1/2}(n)} \stackrel{d}{\longrightarrow} R\end{align*}
as
 $n\to+\infty$
, where R is given in (16). The normalization in this limit theorem is not of CLT type
 $n^{-d/2}$
, which should be attributed to the l.r.d. case. Let us compare this behaviour with Definition 1. As an example, we consider
 \[G(x)=\textrm{sign} (x) ( {\textrm{e}}^{x^2/\beta^2}-1) , \quad x\in\mathbb{R}\]
for some
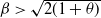 $\beta>\sqrt{2(1+\theta)}$
. Note that it is possible that the variance of
 $X=G(Y)$
is infinite. Set
 $\mu=\delta_{\{ 0 \} }$
. By Remark 2(i) we get
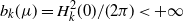 $b_k(\mu)=H_k^2(0)/(2\pi)<+\infty$
for any
 $k\ge 0$
,
 $b_0>0$
,
 $b_1= 0$
, etc. By the choice
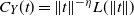 $ C_Y(t)= \|t\|^{-\eta}L(\|t\|)$
,
 $\eta\in (0,d)$
we get that
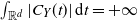 $\int_{\mathbb{R}^d} |C_Y(t)|\, {\textrm{d}} t = +\infty$
, and the series (10) diverges. Then X is l.r.d. in the sense of Definition 1 for
 $\eta\in (0,d)$
, which is in accordance with the above limit theorem.
4.1.2. Empirical mean: infinite variance case
In this section we show that Definition 1 cannot be linked to the behaviour of integrals or partial sums of the field X if X has infinite variance. For that, we use the framework of time series
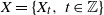 $X=\{ X_t, \ t\in\mathbb Z \}$
, where many more models have been widely explored, as compared to (continuous-time) random fields.
Consider (as in Section 3.3) a subordinated time series
 $X_t=G(|Y_t|)$
,
 $t\in\mathbb Z$
, where
 $\{Y_t, \: t\in\mathbb Z\}$
is a centred Gaussian long memory linear time series with non-decreasing covariance function
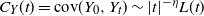 $C_Y(t)=\textrm{cov}(Y_0,Y_t)\sim |t|^{-\eta}L(t) $
,
 $t\to+\infty$
,
 $\eta\in(0,1)$
, and such that
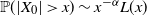 $\mathbb P(|X_0|>x)\sim x^{-\alpha}L(x)$
,
 $\alpha\in (0,2)$
. It is further assumed that G has Hermite rank q. By Corollary 1(ii), X is short range dependent in the sense of Definition 1 whenever, for any finite measure
 $\mu$
on
 $\mathbb{R}$
,
 \begin{equation*} \sum_{k=1}^{\infty}\dfrac{b_{2k-1}(\mu)}{(2k)!} \sum_{t=1}^{\infty} C_Y^{2k}(t) <+\infty.\end{equation*}
We note that
 \begin{equation} \sum_{t=1}^{\infty} C_Y^{2k}(t) \le c_0 \int_{1}^{\infty} \dfrac{L^{2k}(t)}{ t^{2k\eta}}\, {\textrm{d}} t \le \int_{1}^{\infty} \dfrac{c_1 \, {\textrm{d}} t}{ t^{2k(\eta-\delta)}}, \quad k\in \mathbb N, \end{equation}
where
 $\delta>0$
is arbitrary and
 $c_0, c_1>0$
are some constants. The second inequality holds since
 $L(t)\le c_2 t^\delta$
for
 $t\ge t_0$
, where
 $t_0>0$
is large enough and
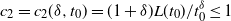 $c_2=c_2(\delta,t_0)=(1+\delta) L(t_0)/t_0^\delta \le 1$
for large
 $t_0$
; see [Reference Resnick30, Proposition 2.6]. The right-hand side of (17) is finite and equal to
 $O(1/k)$
whenever
 $\eta\in(1/2,1)$
, since
 $\delta>0$
can be chosen arbitrarily small. The series in (17) diverges if
 $\eta\in (0,1/2)$
. If
 $\eta=1/2$
, the summability of the series in (17) depends on the particular form of the slowly varying function L and will not be discussed here.
Thus, for
 $\eta\in(1/2,1)$
, X is s.r.d. whenever
 \begin{equation}\sum_{k=1}^{\infty}\dfrac{b_{2k-1}(\mu)}{(2k)! k} <+\infty \end{equation}
for any finite measure
 $\mu$
.
Now we have to consider a special example of function G in order to get more explicit results for the s.r.d. case. As in Example 1, set
 $G(x)={\textrm{e}}^{x^2/(2\alpha)}$
,
 $\alpha\in(0,2]$
. By relation (12), condition (18) is satisfied for
 $\eta\in(1/2,1)$
, hence X is s.r.d. in the sense of Definition 1 if
 $\eta\in(1/2,1)$
and l.r.d. if
 $\eta\in (0,1/2)$
.
Let us compare this result with the limiting behaviour of the partial sums
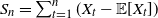 $S_n=\sum_{t=1}^n (X_t-\mathbb E[X_t])$
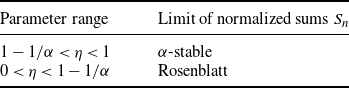
as given in [Reference Sly and Heyde40] and [Reference Beran, Feng, Ghosh and Kulik5, Section 4.3.5]; see Table 1. There some discrepancies are seen, that is, Definition 1 does not agree with the asymptotic behaviour of
 $S_n$
.
Short or long memory of
 $X_t={\textrm{e}}^{Y_t^2/(2\alpha)}$
in the infinite variance case
 $\alpha\in(1,2)$
depending on the long memory parameter
 $\eta$
of Y according to [Reference Sly and Heyde40].

4.2. Limit theorems for the integrals of functionals of l.r.d. random volatility fields
In this section we will justify that our definition of long range dependence is in agreement with limit theorems for volumes of level sets for random volatility models. Unlike the subordinated Gaussian case, where the limiting results are known, a general asymptotic theory has to be developed.
Let X be a random volatility field of the form
 $X_t=G(Y_t)Z_t$
,
 $t\in \mathbb Z^d$
, where
-
•
$\{G(Y_t),t\in \mathbb{R}^d\}$
is a subordinated Gaussian measurable random field, which is sampled at points
$t\in\mathbb Z^d$
, -
•
$\{Z_t,t\in \mathbb Z^d\}$
is white noise, -
• the random fields Y and Z are independent.


Our goal is to prove limit theorems for
 $\sum_{t\in W_n}g(X_t)$
as
 $n\to\infty$
, where
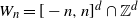 $W_n=[-n,n]^d \cap \mathbb Z^d$
and g is a real-valued Borel-measurable function such that
 \begin{align}\mathbb E [g(X_0)]=0,\quad \mathbb E [g^2(X_0)]>0 .\end{align}
Introduce the function
 \[\xi(y)= \mathbb E [g(G(y) Z_0)] .\]
It follows from (19) that for
 $\nu_1$
-almost every
 $y\in \mathbb{R}$
 \begin{align}\xi(y)<\infty.\end{align}
By (19) we also have
 $\mathbb E[\xi(Y_0)]=0$
. Let
 \[J(m)=\langle \xi, H_m\rangle_\varphi = \mathbb E[H_m(Y_0) \, g(G(Y_0)Z_0)]\;\]
be the mth Hermite coefficient of
 $\xi$
. We recall that a sufficient condition for the finiteness of J(m) is
 \begin{align}\mathbb E [|g(X_0) |^{1+\theta}]= \mathbb E [|\xi(Y_0) |^{1+\theta}]=\mathbb E[| \mathbb E[g(G(Y_0)Z_0)\mid \mathcal{Y}]|^{1+\theta}]<\infty\end{align}
for some
 $\theta\in(0,1]$
, where
 $\mathcal{Y}$
is a sigma-field generated by the entire sequence Y. Let
 $\operatorname{rank} (\xi)= q$
. Furthermore, set
 \[m(y,Z_t)=g(G(y)Z_t) - \mathbb E[g(G(y)Z_t)]=g(G(y)Z_t) - \xi(y),\]
which is almost everywhere finite by (20), and
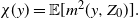 $\chi(y)=\mathbb E[m^2(y,Z_0)].$
We also assume
 \begin{align}\mathbb E[\chi^3(Y_0)]<\infty.\end{align}
Note that under (22), using the Lyapunov inequality on a space of finite measure and the stationarity of
 $Y_t$
, we have for any finite subset
 $I\subset \mathbb Z^d$
 \begin{align*}\mathbb E\biggl[\biggl(\sum_{t\in I}\chi(Y_t)\biggr)^3\biggr]<\infty.\end{align*}
The following result shows that the limiting behaviour is primarily determined by the function
 $\xi$
, with
 $\xi\equiv 0$
being the boundary case.
Theorem 3. Assume that the random field
 $X_t=G(Y_t)Z_t$
,
 $t\in\mathbb Z^d$
, is as above, and satisfies the following:
-
• Y is a homogeneous isotropic centred Gaussian random field with the covariance function
$C_Y(t)=\mathbb E [Y_0Y_t]= \|t\|^{-\eta}L(\|t\|)$
,
$\eta\in (0,d/q)$
and L is slowly varying at infinity, -
• Y has a spectral density
$f(\lambda)$
which is continuous for all
$\lambda\neq 0$
and decreasing in a neighbourhood of 0.
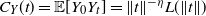


Assume that (19), (21) with
 $\theta=1$
, and (22) hold.
-
(i) If
$\xi(y)\equiv 0$
, then
(23)where
\begin{align}n^{-d/2}\sum_{t\in W_n}g(X_t) \stackrel{d}{\longrightarrow} \mathcal{N}(0,\sigma^2), \quad n\to+\infty,\end{align}
$\sigma^2=\mathbb E[g^2(X_0)] 2^d>0$
.
-
(ii) If
$\xi(y)\not\equiv 0$
, then
(24)where the random variable R is given in (16) with
\begin{align}n^{q\eta/2-d}L^{-q/2}(n)\sum_{t\in W_n} g(X_t) \stackrel{d}{\longrightarrow} R, \quad n\to+\infty,\end{align}
$W=[-1,1]^d$
.


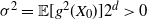


Example 3. Assume that
 $g(y)=y$
,
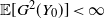 $\mathbb E[G^2(Y_0)]<\infty$
, and
 $\mathbb E[Z_0]=0$
. Then
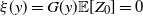 $\xi(y)=G(y) \mathbb E[Z_0]= 0$
and (23) always holds. In this case there is no contribution from the long memory of the random field
 $Y_t$
.
Example 4. Assume that
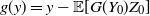 $g(y)=y-\mathbb E[G(Y_0)Z_0]$
and
 $\mathbb E[Z_0]\not=0$
. Then
 $\xi(y)=\mathbb E[Z_0]\{ G(y)- \mathbb E[G(Y_0)]\}$
. Condition (22) is satisfied if
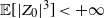 $\mathbb E[|Z_0|^3]<+\infty$
and
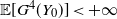 $\mathbb E[G^4(Y_0)]<+\infty$
. In this case
 $\xi(y)\not\equiv 0$
, and (24) always holds.
Example 5. Assume that
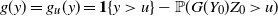 $g(y)=g_u(y)={\bf 1} \{y>u\}-\mathbb P ( G(Y_0)Z_0>u) $
, where G is non-negative or non-positive
 $\nu_1$
-a.e. Then
 \[\xi(y)= \mathbb E[{\bf 1} \{G(y)Z_0>u\} ]-\mathbb P ( G(Y_0)Z_0>u) \not\equiv 0\]
if
 $u\neq 0$
, so case (24) applies. If
 $u=0$
, then
 $\xi(y)\equiv 0$
(compare Remark 3(iii)), so case (23) holds true.
Example 6. Let the random volatility field
 $X_t=G(|Y_t|)Z_t$
,
 $t\in\mathbb Z^d$
be as in Lemma 4, where
 $\{ Z_t\}$
is heavy-tailed white noise,
 $\mathbb E Z_0^2=+\infty$
. Let Y satisfy the assumptions of Theorem 3. Choose
 $G(x)\ge 0$
as in Lemma 5(ii), and let
 $C_Y(t)\sim \|t\|^{-\eta}$
as
 $ \|t\|\to+\infty$
be non-negative. Similarly to Example 2, an analogue of relation (14) holds true: for
 $\mu=\delta_{\{u_0\}}$
,
 $u_0>0$
we have
 \begin{equation*}\sum_{t\in \mathbb Z^d, \, t\neq 0}\int_{\mathbb{R}^2} {\textrm{cov}}_X(t,u,v) \mu({\textrm{d}} u)\mu({\textrm{d}} v) = \sum_{k=1}^\infty \dfrac{ \langle \bar{F}_Z(u_0/\widetilde{G}), H_k\rangle_\varphi^2 }{k!} \sum_{t\in \mathbb Z^d, \, t\neq 0}\ C_Y^k(t) ,\end{equation*}
where
 $\widetilde{G}(y)=G(|y|)$
,
 $y\in\mathbb{R}$
. Since
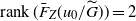 $\operatorname{rank} (\bar{F}_Z(u_0/\widetilde{G}) )=2$
, X is l.r.d. in the sense of Definition 1 if
 $\sum_{t\in \mathbb Z^d, \, t\neq 0} C_Y^{2}(t) =+\infty$
, i.e. if
 $\eta<d/2$
.
Consider function
 $\xi $
from Example 5 with
 $u=u_0>0$
and
 $\widetilde{G}$
instead of G. By Lemma 5(ii),
 $\operatorname{rank} (\xi )=2$
. By Theorem 3 and Example 5, the asymptotic behaviour of the cardinality of the level sets of X at level
 $u_0$
is of l.r.d. type if
 $\eta\in(0,d/2)$
, which is in agreement with our definition.
Remark 4. We would like to connect the assumption
 $\xi\equiv 0$
to our definition. Let g,h be functions such that
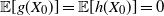 $\mathbb E[g(X_0)]=\mathbb E[h(X_0)]=0$
. If
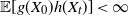 $\mathbb E [g(X_0)h(X_t)]<\infty$
for all t, and
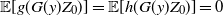 $\mathbb E[g(G(y)Z_0)]=\mathbb E[h(G(y)Z_0)]=0$
for all y, then for
 $t\not=0$
 \begin{align*} \textrm{cov}(g(X_0),h(X_t))=\int\int\mathbb E [g(G(y_0)Z_0)] \mathbb E[h(G(y_t)Z_t)] \mathbb P_{Y_0,Y_t}({\textrm{d}} y_0,{\textrm{d}} y_t)=0 ,\end{align*}
where
 $\mathbb P_{Y_0,Y_t}$
is the joint law of
 $(Y_0,Y_t)$
. In particular, take
 \[g(x)=g_u(x)={\bf 1}(x>u)-\mathbb P(X_0>u), \quad h(x)=h_v(x)={\bf 1}(x>v)-\mathbb P(X>v).\]
Then
 \[\sigma_{\mu,X}^2=\sum_{t\in\mathbb Z^d, \, t\neq 0} \int_{\mathbb{R}^2} |\textrm{cov}(g_u(X_0),h_v(X_t))|\, {\textrm{d}} u \, {\textrm{d}} v=0,\]
and the random field X is s.r.d. according to Definition 1 for
 $\xi\equiv 0$
.
5. Summary and outlook
We proposed a new definition of long memory for stationary random fields X indexed by any set
 $T\subset \mathbb{R}^d$
, which works also for heavy-tailed X. We showed that this definition is a good fit to the asymptotic behaviour of the volume of the excursion set of X at a level
 $u\in\mathbb{R}$
in an unboundedly growing observation window
 $W_n$
. This connection to non-central limit theorems was proved for a class of random volatility fields with subordinated l.r.d. Gaussian volatility.
Appendix A Proofs
Proof of Theorem 2. If X is a centred stationary unit variance Gaussian random field with covariance function
 $C_Y(t)$
,
 \begin{equation} \textrm{cov}_X(t,u,v) = \dfrac{1}{2\pi}\int_{0}^{C_Y(t)} \dfrac{1}{\sqrt{1-r^2}}\, \exp\biggl\{-\dfrac{u^2 -2r uv + v^2}{2 (1-r^2) } \biggr\}\,{\textrm{d}} r;\end{equation}
see [Reference Bulinski, Spodarev and Timmermann8, Lemma 2].
Consider representation (25). Since the density
 $f_{(U,V)}$
of a bivariate normal distribution with zero mean, unit variances, and correlation coefficient
 $\mp r$
equals
 \[\dfrac{1}{2\pi \sqrt{1-r^2}}\exp\biggl\{-\dfrac{x^2\pm2rxy+y^2}{2(1-r^2)}\biggr\} \geq 0,\]
then it is easy to see that
 \begin{equation*} |\textrm{cov}_Y(t, x, y)| = \dfrac{1}{2\pi}\int_{0}^{|C_Y(t)|}\dfrac{1}{\sqrt{1-r^2}}\exp\biggl\{-\dfrac{x^2-2\operatorname{sign}(C_Y(t))rxy+y^2}{2(1-r^2)}\biggr\} \,\textrm{d} r.\end{equation*}
Since G is strictly monotone, by properties of the generalized inverse of G we have
 \begin{align*} &\int_T\int_{-\infty}^{+\infty}\int_{-\infty}^{+\infty}|\textrm{cov}_X(t, u, v)| \mu(\textrm{d} u) \mu (\textrm{d} v) \,\textrm{d} t \\[3pt]&\quad = \int_T\!\!\! \int_{(\operatorname{Im}(G))^2} |\textrm{cov}_Y(t, G^-(u), G^-(v))| \mu(\textrm{d} u) \mu (\textrm{d} v) \,\textrm{d} t \\[3pt] &\quad = \int_T\!\!\! \int_{(\operatorname{Im}(G))^2} \!\!\! \int_{0}^{|C_Y(t)|} \exp\biggl( -\dfrac{(G^-(u))^2-2\operatorname{sign}(C_Y(t))rG^-(u)G^-(v)+(G^-(v))^2}{2(1-r^2)}\biggr)\\[3pt] &\quad \quad\ \dfrac{\textrm{d} r \mu(\textrm{d} u) \mu (\textrm{d} v) \,\textrm{d} t}{2\pi \sqrt{1-r^2}}.\end{align*}
By [Reference CramÉr9, formula (21.12.5)] for the density
 $f_{(U,V)}$
with correlation coefficient
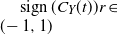 $\operatorname{sign}(C_Y(t))r\in(-1,1)$
, we have
 \begin{equation}f_{U,V}(x,y) = \sum_{k=0}^{\infty}\dfrac{\Phi^{(k+1)}(x)\Phi^{(k+1)}(y)}{k!}(\operatorname{sign}(C_Y(t))r)^k ,\quad x,y \in \mathbb{R}.\end{equation}
By condition
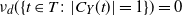 $\nu_d(\{t\in T\colon |C_Y(t)|=1\})=0$
, the above series converges uniformly for
 $r \in (-1,1)$
, so integration over
 $r\in [0; |C_Y(t)|]$
and summation with respect to k can be interchanged. Then the above triple integral reads
 \begin{align*}& \int_T\int_{\operatorname{Im}(G)^2}\int_{0}^{|C_Y(t)|}\sum_{k=0}^{\infty}\dfrac{\Phi^{(k+1)}(G^-(u))\Phi^{(k+1)}(G^-(v))}{k!}(\operatorname{sign}(C_Y(t))r)^k \,\textrm{d} r\mu(\textrm{d} u) \mu (\textrm{d} v) \,\textrm{d} t\\[3pt] &\quad = \int_T\int_{\operatorname{Im}(G)^2}\varphi(G^-(u))\varphi(G^-(v))\sum_{k=0}^{\infty}\dfrac{H_k(G^-(u))H_k(G^-(v))}{k!}\operatorname{sign}(C_Y(t))^k \\[3pt] &\quad\quad \times \dfrac{|C_Y(t)|^{k+1}}{k+1} \mu(\textrm{d} u) \mu (\textrm{d} v) \,\textrm{d} t\\[3pt] &\quad =\int_T\int_{\operatorname{Im}(G)^2} |C_Y(t)|\varphi(G^-(u))\varphi(G^-(v))\sum_{k=0}^{\infty}\dfrac{H_k(G^-(u))H_k(G^-(v))}{(k+1)k!}C_Y(t)^k \mu(\textrm{d} u) \mu (\textrm{d} v) \,\textrm{d} t.\end{align*}
Abel’s uniform convergence test allows us to interchange the sum and the integral over
 $\operatorname{Im}(G)^2 $
. Since
 $b_k\geq 0$
, we get
 \begin{align*} & \int_T\sum_{k=0}^{\infty}\int_{\operatorname{Im}(G)^2} \varphi(G^-(u))\varphi(G^-(v))\dfrac{H_k(G^-(u))H_k(G^-(v))}{(k+1)!}|C_Y(t)|C_Y(t)^k \,\textrm{d} r \mu(\textrm{d} u) \mu (\textrm{d} v) \,\textrm{d} t \nonumber \\[3pt] &\quad =\int_T\sum_{k=0}^{\infty}\dfrac{1}{(k+1)!}\biggl(\int_{\operatorname{Im}(G)}\varphi(G^-(u))H_k(G^-(u)) \mu(\textrm{d} u)\biggr)^2 |C_Y(t)|C_Y(t)^k \,\textrm{d} t\nonumber \\[3pt] &\quad = \int_T\sum_{k=0}^{\infty}\dfrac{b_k(\mu)}{(k+1)!}|C_Y(t)|C_Y(t)^k \,\textrm{d} t = \sum_{k=1}^{\infty}\dfrac{b_{k-1}(\mu)}{k!}\int_{T}|C_Y(t)|\rho^{k-1}(t)\,\textrm{d} t ,\end{align*}
where the integral over T and the sum are interchangeable by Tonelli’s theorem subdividing T into parts
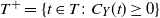 $T^+ = \{t\in T\colon C_Y(t)\geq 0\}$
and
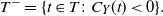 $T^- = \{t\in T\colon C_Y(t)< 0\}.$
Then
 $X=G(Y)$
has short memory if
 \[ \sum_{k=1}^{\infty}\dfrac{b_{k-1}(\mu)}{k!}\int_{T}|C_Y(t)|\rho^{k-1}(t)\,\textrm{d} t
< +\infty\]
for any finite measure
 $\mu$
on
 $\mathbb{R}$
.
Proof of Corollary 1. (i) It follows from relation (9) using the change of variables
 $u=G(x)$
and by [Reference Beran, Feng, Ghosh and Kulik5, Lemma 4.21].
(ii) Without loss of generality, assume G is an increasing function. Since the probability density of the centred univariate and bivariate Gaussian distribution is invariant under transformation
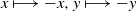 $x\longmapsto-x,y\longmapsto-y$
, we get
 \begin{align*} \textrm{cov}_X(t, u, v) & = \mathbb P(|Y_0|>G^{-}(u),|Y_t|>G^{-}(v)) -\mathbb P(|Y_0|>G^{-}(u))\mathbb P(|Y_t|>G^{-}(v))\\[3pt] &= 2 ( \mathbb P(Y_0>G^{-}(u),Y_t>G^{-}(v))-\mathbb P(Y_0>G^{-}(u))\mathbb P(Y_t>G^{-}(v))\\[3pt] &\quad + \mathbb P(Y_0>G^{-}(u),Y_t<-G^{-}(v))-\mathbb P(Y_0>G^{-}(u))\mathbb P(Y_t<-G^{-}(v)) ) .\end{align*}
Let
 $Z=-Y_t$
,
 $x=G^-(u)$
, and
 $y=G^-(v)$
. Thus
 \begin{align*} \mathbb P(Y_0>x,Y_t>y)-\mathbb P(Y_0>x)\mathbb P(Y_t>y)& = \textrm{cov}({\bf 1}(Y_0\ge x), {\bf 1}(Y_t\ge y)) , \\[3pt] \mathbb P(Y_0>x,Y_t<-y)-\mathbb P(Y_0>x)\mathbb P(Y_t<-y)& = \textrm{cov}({\bf 1}(Y_0>x), {\bf 1}(Z>y)) . \end{align*}
Since
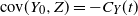 $\textrm{cov}(Y_0,Z) = -C_Y(t) $
and
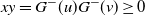 $xy=G^{-}(u)G^{-}(v)\ge 0$
, we have by formula (25) that
 \begin{align*} & |\textrm{cov}_X(t, u, v)| \\[3pt] & \quad =\dfrac{2}{2\pi} \biggl|\int_{0}^{C_Y(t)}\dfrac{1}{\sqrt{1-r^2}}\exp\biggl(-\dfrac{x^2-2rxy+y^2}{2(1-r^2)}\biggr) \,\textrm{d} r \\[3pt] &\quad\quad + \int_{0}^{-C_Y(t)}\dfrac{1}{\sqrt{1-r^2}}\exp\biggl(-\dfrac{x^2-2rxy+y^2}{2(1-r^2)}\biggr) \,\textrm{d} r \biggr| \\[3pt] & \quad = \int_{0}^{|C_Y(t)|} \biggl(\exp\biggl(-\dfrac{x^2-2rxy+y^2}{2(1-r^2)}\biggr) - \exp\biggl(-\dfrac{x^2+2rxy+y^2}{2(1-r^2)}\biggr)\biggr) \dfrac{\textrm{d} r}{\pi \sqrt{1-r^2}}.\end{align*}
Similarly to the proof of Theorem 2, we use representation (26) to write
 \begin{align*} & \int_T\int_{-\infty}^{+\infty}\int_{-\infty}^{+\infty} |\textrm{cov}_X(t, u, v)| \mu(\textrm{d} u) \mu( \textrm{d} v) \,\textrm{d} t \\[3pt] &\quad = 2\int_T\int_{\operatorname{Im}(G)^2} \sum_{k=0}^{\infty}\dfrac{1-(-1)^k}{(k+1)!}H_{k}(x)H_{k}(y)\varphi(x)\varphi(y)|C_Y(t)|^{k+1} \mu(\textrm{d} u) \mu( \textrm{d} v) \,\textrm{d} t\\[3pt] &\quad =\int_T \sum_{k=1}^{\infty}\dfrac{4}{(2k)!}\biggl(\int_{\operatorname{Im}(G)}H_{2k-1}(G^-(u))\varphi(G^-(u)) \mu(\textrm{d} u) \biggr)^2|C_Y(t)|^{2k} \,\textrm{d} t \\[3pt] &\quad =4\sum_{k=1}^{\infty}\dfrac{b_{2k-1}(\mu)}{(2k)!}\int_T \rho^{2k}(t) \,\textrm{d} t.\end{align*}
Proof of Corollary 2. Choose
 $\mu=\delta_{\{ u_0\}}$
,
 $u_0\in\mathbb{R}$
and write
 \begin{align*}& \int_T\int_{\mathbb{R}^2}\textrm{cov}_X(t,u,v)\, \mu({\textrm{d}} u)\,\mu({\textrm{d}} v)\,{\textrm{d}} t \\[3pt] &\quad = \int_T\textrm{cov} ( \bar{F}_Z(u_0/A),\bar{F}_Z(u_0/A) ) \,{\textrm{d}} t + \int_T \mathbb E [ \textrm{cov}_Z(t,u_0/A,u_0/A)] \,{\textrm{d}} t\\[3pt] &\quad \ge \int_T \textrm{var}( \bar{F}_Z (u_0/A)) \,{\textrm{d}} t\\[3pt] &\quad = +\infty ,\end{align*}
since
 $$Z \in {\bf{PA}}$$
,
 $\bar{F}_Z (u_0/A)$
is non-degenerate and bounded.
Proof of Corollary \refcor:rvt0. Without loss of generality assume
 $Z, Y\in$
PA. Then
 $Y^\alpha\in$
PA too, and the second term in (13) is non-negative. Let
 \[A_{u,v}(t)=\textrm{cov} ( \bar{F}_Z (u/Y_0),\bar{F}_Z(v/Y_t) ) , \quad u,v\in\mathbb{R}_+, \ t\in T . \]
Since
 $Y\in$
PA and the function
 $\bar{F}_Z(u/\cdot)$
is bounded and non-decreasing for
 $u>0$
, we get
 $A_{u,v}(t)\ge 0$
for all
 $u,v\in\mathbb{R}_+$
,
 $t\in T .$
Using the regular variation of the tail of
 $Z_0$
, the independence of Y and Z, and Potter’s bound [Reference Resnick30, Proposition 2.6], one can easily show that under the above assumptions on the integrability of Y we obtain
 \begin{equation*}A_{u,v}(t)\sim\ \bar{F}_Z(u)\bar{F}_Z(v) \textrm{cov} ( Y_0^\alpha, Y_t^\alpha ) , \quad u,v\to+\infty,\end{equation*}
for any
 $t\in T$
. Then, for sufficiently large
 $N>0$
, there exists
 $u_0>N$
such that for the Dirac measure
 $\mu=\delta_{\{ u_0 \}}$
and some
 $\varepsilon\in(0,1)$
, we have
 \begin{equation*}\int_T \int_{\mathbb{R}^2}\textrm{cov}_X(t,u,v) \mu({\textrm{d}} u)\mu({\textrm{d}} v)\,{\textrm{d}} t\ge \int_T A_{u_0,u_0}(t) \,{\textrm{d}} t\ge \varepsilon \bar{F}_{Z}^2 (u_0) \! \! \int_T \! \! \textrm{cov} ( Y_0^\alpha, Y_t^\alpha ) \,{\textrm{d}} t ,\end{equation*}
which is infinite if
 $Y^\alpha$
is l.r.d. Thus
 $X=Y Z$
is l.r.d. if
 $Y^\alpha$
is l.r.d.
Proof of Lemma 4. Without loss of generality, assume G is non-negative. By Lemma 2, and the Fubini and Tonelli theorems for
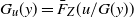 $G_u(y)=\bar{F}_Z (u/G(y)) $
, we get
 \begin{align*}D_{\mu} (G(Y),Z_0) &=\int_T\int_{\mathbb{R}^2} \textrm{cov} ( G_u(Y_0), G_v(Y_t)) \mu({\textrm{d}} u) \mu({\textrm{d}} v) \, {\textrm{d}} t \\[3pt] &= \sum_{k=1}^\infty \dfrac{\bigl( \int_\mathbb{R} \langle G_u, H_k\rangle_\varphi \, \mu({\textrm{d}} u) \bigr)^2 }{k!}\int_T \rho^k(t) \, {\textrm{d}} t .\end{align*}
The change of order of the sum and integrals is justified by the Weierstrass uniform convergence test since, for almost all
 $t\in T$
,
 \[\sum_{k=1}^\infty \dfrac{| \langle G_u, H_k\rangle_\varphi \langle G_v, H_k\rangle_\varphi | }{k!}\rho^k(t) \le\sum_{k=1}^\infty \dfrac{ \langle 1, |H_k|\rangle_\varphi^2 }{k!}\rho^k(t) \le\sum_{k=1}^\infty \rho^k(t) <\infty\]
due to
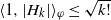 $\langle 1, |H_k|\rangle_\varphi \le \sqrt{k!}$
, by the Cauchy–Schwarz inequality and due to condition (
 $\boldsymbol{\rho}$
).
Proof of Lemma 5. (i) If
 $G\colon \mathbb{R}\to\mathbb{R} $
is monotone, then
 $\operatorname{rank} (G)=1$
due to
 \begin{equation}\langle G , H_1\rangle_\varphi=\mathbb E[Y G(Y)] = \int_0^\infty ( G(y)- G(-y)) y \varphi(y)\,{\textrm{d}} y \neq 0.\end{equation}
What is the Hermite rank of
 $\zeta_{G,Z,u} $
? First consider
 $Z\equiv 1$
. Since the Hermite rank of
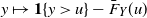 $y\mapsto {\bf 1} \{ y>u \} - \bar{F}_Y(u)$
is one, we can write
 \[\langle \zeta_{G,1,u} , H_1\rangle_\varphi=\mathbb E[Y {\bf 1} \{ G(Y) >u \}] = \mathbb E[Y {\bf 1} \{ Y >G^-(u) \}] \neq 0,\]
where G is non-decreasing without loss of generality. Hence
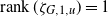 $\operatorname{rank} ( \zeta_{G,1,u})=1 $
for any
 $u\in \mathbb{R}$
. Now let
 $G\colon \mathbb{R}\to\mathbb{R}_\pm$
and Z be arbitrary. Without loss of generality, assume G is non-negative. Then
 \[\langle \zeta_{G,Z,u} , H_1\rangle_\varphi=\int_\mathbb{R} \bar{F}_Z( u/G(y)) y \varphi (y)\, {\textrm{d}} y \neq 0,\]
since for any
 $u\neq 0$
the function
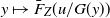 $y\mapsto \bar{F}_Z (u/G(y)) $
is monotone, and we can use the reasoning (27). For non-positive G replace
 $ \bar{F}_Z$
above with
 $ {F}_Z$
.
(ii)Without loss of generality, assume that G is non-negative and non-decreasing. We prove that
 $\operatorname{rank} (\widetilde{G})=2$
.
Clearly, since
 $y\mapsto G(|y|)$
is even, we have
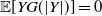 $\mathbb E[Y G(|Y|)]=0$
. Now
 \begin{align*}\mathbb E[H_2(Y)G(|Y|)]=2\int_0^\infty G(y)(y^2-1)\varphi(y)\,{\textrm{d}} y.\end{align*}
We note that
 \begin{equation}\int_0^\infty (y^2-1)\varphi(y)\,{\textrm{d}} y=0 ,\end{equation}
and hence by symmetry
 \[\int_0^1(y^2-1)\varphi(y)\,{\textrm{d}} y=-\int_1^\infty(y^2-1)\varphi(y)\,{\textrm{d}} y.\]
Also, by the mean value theorem, due to monotonicity of non-constant G, there exists
 $y_0\in [0,1)$
such that
 \begin{align*}\int_0^1 G(y)(y^2-1)\varphi(y)\,{\textrm{d}} y=G(y_0)\int_0^1(y^2-1)\varphi(y)\,{\textrm{d}} y.\end{align*}
Therefore
 \begin{align*}& \int_0^\infty G(y)(y^2-1)\varphi(y)\,{\textrm{d}} y \\[3pt] &\quad \geq G(y_0) \int_0^1 (y^2-1)\varphi(y)\,{\textrm{d}} y + G(1)\int_1^\infty (y^2-1)\varphi(y)\,{\textrm{d}} y\\[3pt] &\quad = -G(y_0) \int_1^\infty (y^2-1)\varphi(y)\,{\textrm{d}} y +G(1)\int_1^\infty (y^2-1)\varphi(y)\,{\textrm{d}} y\\[3pt] &\quad =(G(1)-G(y_0)) \int_1^\infty (y^2-1)\varphi(y)\,{\textrm{d}} > 0.\end{align*}
For non-negative non-increasing G, we can use the estimate
 \begin{align*}\int_0^\infty G(y)(y^2-1)\varphi(y)\,{\textrm{d}} y & \leq G(y_0) \int_0^1 (y^2-1)\varphi(y)\,{\textrm{d}} y + G(1)\int_1^\infty (y^2-1)\varphi(y)\,{\textrm{d}} y\\[3pt] & =(G(y_0)-G(1)) \int_0^1 (y^2-1)\varphi(y)\,{\textrm{d}} y < 0.\end{align*}
If
 $G(y)\le 0$
just multiply it by
 $-1$
. This proves that the Hermite rank of
 $G(|y|)$
is 2.
Now compute the Hermite rank of
 $\zeta_{\widetilde{G},1,u} $
for any
 $u\in\mathbb{R}$
. Since
 $\zeta_{\widetilde{G},1,u} $
is even,
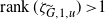 $\operatorname{rank} (\zeta_{\widetilde{G},1,u})>1$
. Assuming without loss of generality that G is non-negative and non-decreasing, we calculate
 \begin{align*}\langle \zeta_{\widetilde{G},1,u}, H_2 \rangle_\varphi & =\mathbb E[(Y^2-1){\bf 1} \{G(|Y|)>u\}] \\[3pt] &= \int_{\mathbb{R}}(y^2-1){\bf 1} \{|y|>G^-(u)\} \varphi(y)\, {\textrm{d}} y\\[3pt] & =2\int_{G^-(u)}^\infty (y^2-1) \varphi(y)\, {\textrm{d}} y \neq 0\end{align*}
due to (28) and
 $G^-(u)\neq 0$
. So
 $\operatorname{rank} \zeta_{\widetilde{G},1,u}=2$
. For general Z, we note that
 $\zeta_{\widetilde{G},Z,u}$
is even, so
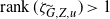 $\operatorname{rank} (\zeta_{\widetilde{G},Z,u})>1$
. If G is non-negative, then
 \[\langle \zeta_{\widetilde{G},Z,u} , H_2\rangle_\varphi=\int_\mathbb{R} \bar{F}_Z( u/G(|y|)) H_{2}(y) \varphi (y)\, {\textrm{d}} y\neq 0\]
by the first part of the proof of (ii), since
 $\bar{F}_Z( u/G(|y|))$
is a monotone even function of y. Modifications of the proof for
 $G\le 0 $
or G non-increasing are obvious.
Proof of Theorem 3. Let
 $\mathcal{Y}$
be the
 $\sigma$
-algebra generated by the entire random field
 $\{Y_t,t\in \mathbb Z^d\}$
. Then
 \begin{equation*}\sum_{t\in W_n}g(X_t) =\sum_{t\in W_n} (g(X_t)-\mathbb E[g(X_t)\mid \mathcal{Y}]) +\sum_{t\in W_n}\mathbb E[g(X_t)\mid \mathcal{Y}]= M_n+K_n,\end{equation*}
where
 \[M_n=\sum_{t\in W_n} (g(X_t)-\mathbb E[g(X_t)\mid \mathcal{Y}]) =\sum_{t\in W_n} m(Y_t,Z_t)\]
and
 \[K_n=\sum_{t\in W_n}\mathbb E[g(X_t)\mid \mathcal{Y}] =\sum_{t\in W_n}\xi(Y_t) .\]
The above decomposition is allowed by (20). The limiting behaviour of the sum depends on interplay between
 $M_n$
and
 $K_n$
. First we state the limiting results for
 $M_n$
and
 $K_n$
separately.
Lemma 6. Under the assumptions of Theorem 3,
 \begin{align*}\tilde M_n:=n^{-d/2}M_n\stackrel{d}{\longrightarrow} \mathcal{N}(0,\sigma^2),\end{align*}
where
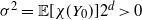 $\sigma^2=\mathbb E[\chi(Y_0)]2^d>0$
.
Proof. We calculate
 \begin{equation*}\mathbb E[\exp\{{\textrm{i}} z \tilde M_n\}\mid \mathcal{Y}] =\mathbb E\biggl[\exp\biggl\{\dfrac{{\textrm{i}} z }{n^{d/2}} \sum_{t\in W_n} m(Y_t,Z_t)\biggr\}\mid \mathcal{Y}\biggr]=:\mathbb E\biggl[\exp\biggl\{\dfrac{{\textrm{i}} z }{n^{d/2}} \sum_{t\in W_n}V_{t}\biggr\}\mid \mathcal{Y}\biggr],\end{equation*}
where
 $V_{t}=m(Y_t,Z_t).$
Note that, due to stationarity of Y and Z, the random variables
 $V_{t}$
are identically distributed and conditionally independent, given
 $\mathcal{Y}$
. Therefore
 \begin{equation*}\mathbb E[\exp\{{\textrm{i}} z \tilde M_n\}\mid \mathcal{Y}] =\mathbb E\biggl[\exp\biggl\{\dfrac{{\textrm{i}} z }{n^{d/2}} \sum_{t\in W_n}V_{t}\biggr\}\mid \mathcal{Y}\biggr]= \prod_{t\in W_n}\mathbb E\biggl[\exp\biggl\{\dfrac{{\textrm{i}} z }{n^{d/2}} V_{t}\biggr\}\mid \mathcal{Y}\biggr].\end{equation*}
The standard inequality,
 \begin{align*}|\exp({\textrm{i}} t z)-(1+{\textrm{i}} tz-t^2z^2/2)|\leq \min\{|tz|^2,|tz|^3\},\end{align*}
yields
 \begin{align*}\biggl|\mathbb E\biggl[\exp\biggl\{\dfrac{{\textrm{i}} z }{n^{d/2}} V_{t}\biggr\}\mid {\mathcal Y}\biggr]-\mathbb E\biggl[\biggl(1+\dfrac{{\textrm{i}} z V_t}{n^{d/2}}-\dfrac{1}{2}\dfrac{z^2V_t}{n^d}\biggr)\mid {\mathcal Y}\biggr]\biggr|&\leq \mathbb E\biggl[\min\biggl\{\dfrac{|z|^2V_t^2}{n^d}, \dfrac{|z|^3|V_t|^3}{n^{3d/2}} \biggr\}\mid {\mathcal Y}\biggr]\\[3pt] &=:\mathbb E[V_{t,n}\mid {\mathcal Y}].\end{align*}
For complex numbers
 $z_1,\ldots,z_m$
,
 $w_1,\ldots,w_m$
of modulus at most 1, we have
 \begin{align*}\biggl|\prod_{i=1}^mz_i-\prod_{i=1}^mw_i\biggr|\leq \sum_{i=1}^m|z_i-w_i|.\end{align*}
Hence
 \begin{align*}A_n({\mathcal Y})& :=\biggl|\prod_{t\in W_n}\mathbb E\biggl[\exp\biggl\{\dfrac{{\textrm{i}} z }{n^{d/2}} V_{t}\biggr\}\mid \mathcal{Y}\biggr]-\prod_{t\in W_n}\mathbb E\biggl[\biggl(1+\dfrac{{\textrm{i}} z V_t}{n^{d/2}}-\dfrac{1}{2}\dfrac{z^2V_t^2}{n^d}\biggr)\mid {\mathcal Y}\biggr]\biggr|\\[3pt] &\leq \sum_{t\in W_n}\biggl|\mathbb E\biggl[\exp\biggl\{\dfrac{{\textrm{i}} z }{n^{d/2}} V_{t}\biggr\}\mid \mathcal{Y}\biggr]-\mathbb E\biggl[\biggl(1+\dfrac{{\textrm{i}} z V_t}{n^{d/2}}-\dfrac{1}{2}\dfrac{z^2V_t^2}{n^d}\biggr)\mid {\mathcal Y}\biggr]\biggr|\\[3pt] &\leq \sum_{t\in W_n}\mathbb E[V_{t,n}\mid {\mathcal Y}].\end{align*}
We argue that
 \begin{align*} A_n({\mathcal Y})\to 0\end{align*}
in probability. If this is the case, then the conditional characteristic function
 \begin{align*}\mathbb E[\exp\{{\textrm{i}} z \tilde M_n\}\mid \mathcal{Y}]\end{align*}
and
 \begin{align*}B_n({\mathcal Y}):=\prod_{t\in W_n}\mathbb E\biggl[\biggl(1+\dfrac{{\textrm{i}} z V_t}{n^{d/2}}-\dfrac{1}{2}\dfrac{z^2V_t^2}{n^d}\biggr)\mid {\mathcal Y}\biggr]\end{align*}
have the same limit in probability. Applying the
 $\log$
to the above expression and
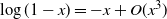 $\log(1-x)=-x+O(x^3)$
, we have
 \begin{align*}\log B_n({\mathcal Y}) & =\sum_{t\in W_n}\log\mathbb E\biggl[1+\dfrac{{\textrm{i}} z V_{t}}{n^{d/2}}- \dfrac{z^2 V_{t}^2}{2 n^{d}}\mid \mathcal{Y}\biggr]\\[3pt] & =\dfrac{{\textrm{i}} z }{n^{d/2}}\sum_{t\in W_n}\mathbb E[V_t\mid {\mathcal Y}]-\dfrac{z^2}{2n^{d}}\sum_{t\in W_n} \mathbb E[V_{t}^2\mid \mathcal{Y}]\\[3pt] &\quad + O(1)\dfrac{|z|^3}{n^{3d/2}}\sum_{t\in W_n} (|\mathbb E[V_t\mid {\mathcal Y}]|) ^3+O(1)\dfrac{z^6}{n^{3d}}\sum_{t\in W_n} (\mathbb E[V_{t}^2\mid \mathcal{Y}]) ^3.\end{align*}
The expression in the last line is
 $o_P(1)$
by (22). By the definition,
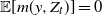 $\mathbb E[m(y,Z_t)]=0$
and hence
 $\mathbb E[V_{t}\mid \mathcal{Y}]=0$
. We have
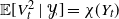 $\mathbb E[V_{t}^2\mid \mathcal{Y}]=\chi(Y_t)$
and therefore
 \begin{align*}&\log B_n (\mathcal{Y}) = -\dfrac{z^2}{2 n^{d}}\sum_{t\in W_n} \chi(Y_t)+o_p(1).\end{align*}
Since
 $\chi$
is measurable, the ergodic theorem [Reference Yaglom44, page 339] implies that
 \begin{align*}\dfrac{1}{n^{d}}\sum_{t\in W_n} \chi(Y_t) \stackrel{P}{\longrightarrow}\mathbb E[\chi(Y_0)] 2^d, \quad n\to +\infty,\end{align*}
whenever the covariance of the field
 $\chi(Y_t)$
goes to zero as
 $\|t\|\to +\infty$
. To check the latter property, we use Lemma 2 to conclude
 \begin{align*}|\textrm{cov}(\chi(Y_0),\chi(Y_t))|\leq |C_Y(t)|\sum_{k=1}^\infty \dfrac{\langle\chi, H_k \rangle_{\varphi}^2}{k!}\to 0\end{align*}
as
 $\|t\|\to +\infty$
, since the infinite series in the last expression is finite due to
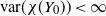 $\textrm{var}(\chi(Y_0))<\infty$
; see (22). Hence
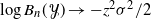 $\log B_n(\mathcal{Y})\to -z^2\sigma^2/2$
in probability. By the continuous mapping theorem,
 \begin{align*}& \mathbb E[\exp\{{\textrm{i}} z \tilde{M}_n\}\mid \mathcal{Y}] \stackrel{P}{\longrightarrow} {\textrm{e}}^{-z^2 \sigma^2/2}, \quad n\to +\infty.\end{align*}
Since
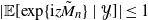 $| \mathbb E[\exp\{{\textrm{i}} z \tilde{M}_n\}\mid \mathcal{Y}] |\le 1$
for all
 $n\in\mathbb N$
, this sequence is uniformly integrable. Using the property of
 $L^1$
-convergence of uniformly integrable sequences, we get
 \[\mathbb E[\exp\{{\textrm{i}} z \tilde{M}_n\}] \to {\textrm{e}}^{-z^2 \sigma^2/2}, \quad n\to +\infty,\]
and we are done.
Lemma 7. Under the assumptions of Theorem 3,
 \[n^{q\eta/2-d}L^{-q/2}(n)K_n\stackrel{d}{\longrightarrow} R, \quad n\to\infty.\]
Proof. Consider the random variable
 \[K_n(q)=\sum_{m=q}^{\infty}\dfrac{J(m)}{m!}\int_{[-n,n]^d}H_m(Y_t)\,{\textrm{d}} t.\]
According to [Reference Leonenko and Olenko23, Theorem 4] and [Reference Alodat and Olenko2, Theorem 4.3], the random variables
 \[\dfrac{K_n}{\sqrt{\textrm{var}K_n}}, \quad\dfrac{K_n(q)}{\sqrt{\textrm{var}K_n(q)}}\]
have the same limiting distributions as
 $n\to+\infty$
. Furthermore, if
 $\eta\in (0,d/q)$
we have by [Reference Leonenko and Olenko23, Theorem 5] that
 \[n^{q\eta/2-d}L^{-q/2}(n)\int_{[-n,n]^d}H_q(Y_t)\,{\textrm{d}} t\]
converges in distribution to random variable R.
If
 $\xi(y)\equiv 0$
, the long memory part
 $K_n$
is not present and we apply Lemma 6. If
 $\xi(y)\not\equiv 0$
, we note that the rate of convergence in Lemma 7 is slower than in Lemma 6, whenever
 $\eta\in (0,d/q)$
.
Acknowledgements
We thank P. Doukhan for his remarks on
 $\psi$
-mixing. E. Spodarev is grateful to the German Academic Exchange Service (DAAD) for supporting his research visit to Ottawa in late 2015.