




No CrossRef data available.
A NOTE ON TESTING RESTRICTIONS FOR THE COINTEGRATION PARAMETERS OF A VAR WITH I(2) VARIABLES
Published online by Cambridge University Press: 22 April 2005
Abstract
We give a brief introduction to the vector autoregressive model for cointegrated I(2) variables and show how some plausible economic relations can be formulated in the I(2) framework in such a way that likelihood ratio tests for their validity are asymptotically χ2 distributed.The authors thank Paolo Paruolo for helpful comments and the ESF for financial support in the framework of the EMM network.
Information
- Type
- NOTES AND PROBLEMS
- Information
- Copyright
- © 2005 Cambridge University Press
1. INTRODUCTION AND MOTIVATION
The p-dimensional cointegrated vector autoregressive (VAR) model for I(2) variables, without deterministic terms and just two lags, is given by the error correction model
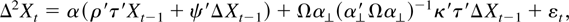
where the εt are independent and identically distributed (i.i.d.) (0,Ω). The freely varying parameters are
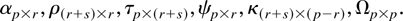
As usual, α⊥ denotes an orthogonal complement of α, and we define the p × r matrix β = τρ. Notice that the column dimension r of β is between 0 and p and the same holds for the row dimension r + s of ρ. Hence, s < p − r. In the analysis of the I(2) model it will be important to specify r and s such that r = rk(αβ′) and s = rk(τρ⊥). Under suitable conditions on the parameters (see Johansen, 1997), the equations in (1) have a solution of the form
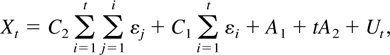
where Ut is stationary and the coefficient matrices satisfy the relations
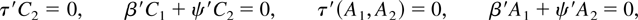
so that the processes Δ2Xt = C2εt + C1 Δεt + Δ2Ut and τ′ΔXt = τ′C1εt + τ′ΔUt are stationary. Thus the solution is an I(2) process, and there are r + s cointegrating relations given by the I(1) process τ′Xt. The model also allows for multicointegration (see Engle and Yoo, 1991), that is, cointegration between the levels and the differences because β′Xt + ψ′ΔXt = β′Ut + ψ′C1εt + ψ′ΔUt is stationary. Equivalently one can show, because τ′ΔXt is stationary, that β′Xt + δτ⊥′ΔXt is stationary, where δ = ψ′τ⊥(τ⊥′τ⊥)−1 is the so-called multicointegration parameter.
The theory of the I(2) model is developed by Boswijk (2000), Johansen (1997, 2005), Kongsted (2005), Paruolo (1996), Paruolo and Rahbek (1999), and Rahbek, Kongsted, and Jørgensen (1999).
It has been shown that the likelihood ratio test for the ranks r and s has an asymptotic distribution that can be expressed in terms of Brownian motions and integrated Brownian motions and that has to be tabulated by simulation. Moreover, the asymptotic distribution of the maximum likelihood estimator of the cointegrating parameters τ, ρ, and β is quite involved, as it is not mixed Gaussian. However, many hypotheses on these parameters can be tested using asymptotic χ2 tests (see Boswijk, 2000; Johansen, 2005). We give subsequently an example of such hypotheses that can be formulated and tested in the I(2) model.
2. AN EXAMPLE OF HYPOTHESES ALLOWING FOR ASYMPTOTIC χ2 TESTS
Denote by mt the log nominal money stock, by pt the log price level, by yt log real income, and by Rt a long-term interest rate and define Xt = (mt,pt,yt,Rt)′. Suppose mt ∼ I(2), pt ∼ I(2), yt ∼ I(1), and Rt ∼ I(1). Moreover consider the following cointegration relations:
- mt − pt ∼ I(1) (i.e., log real money is I(1))
- mt − pt − yt + βR Rt ∼ I(0) (i.e., there exists a stationary money demand relation with unit income elasticity)
- Rt − Δpt ∼ I(0) (i.e., the “Fisher effect” holds, meaning that the real interest rate is stationary)
The unit root and cointegration properties of the variables are in line with those found in Lütkepohl and Wolters (2003) for a system of German quarterly data except for some of the values assumed for the cointegration parameters. Therefore one may wish to formulate these hypotheses in the cointegrated model for I(2) variables and develop the likelihood ratio test to check whether the structure is compatible with the data.
We want to show that the hypotheses discussed earlier can be formulated as hypotheses on the parameters ρ, τ, and ψ that have the property that likelihood ratio tests of the restrictions are asymptotically χ2.
Under the assumption that the process Xt is I(2) it holds that ρ′τ′Xt−1 + δτ⊥′ΔXt−1 and τ′ΔXt are I(0). Therefore we want to express the preceding relations in terms of the parameters τ, β = τρ, ψ, and δ = ψ′τ⊥(τ⊥′τ⊥)−1. For our system p = 4, and from the cointegrating relations
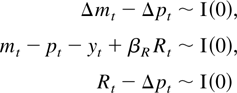
we find that τ is 4 × 3, so that r + s = 3. We see that there are two relations that involve levels, so that r = 2, and β has dimension 4 × 2 and is given by
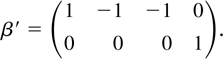
This shows that the hypotheses formulated previously imply that
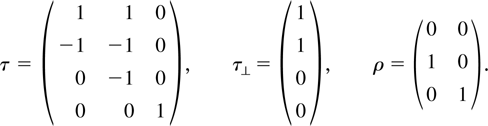
Hence the relations fully specify the matrices τ, ρ, and β = τρ in this case. We denote the specific τ, ρ, and β matrices by τ0, ρ0, and β0, respectively. With this notation the model reduces to
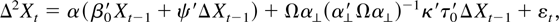
and we next find the implications of the assumptions for the 4 × 2 parameter ψ.
Because τ0′ΔXt−1 is stationary we decompose ψ′ΔXt−1 as
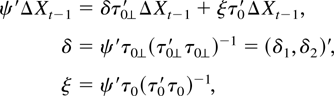
where we used that δ is 2 × 1 and that τ0(τ0′τ0)−1τ0′ + τ0⊥(τ0⊥′τ0⊥)−1τ0⊥′ is equal to the identity matrix. Hence we can rewrite the equations in (1) as
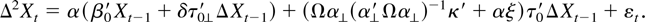
Notice that the coefficients δ are identified by the choice of β = β0 and τ⊥ = τ0⊥ and that
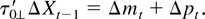
Now consider the stationary (multicointegrating) relation
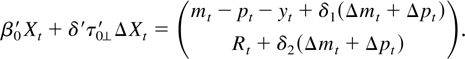
By a linear transformation of the rows, which can be absorbed in α, we can eliminate δ1(Δmt + Δpt) from the first equation and find that the model implies stationarity of the linear combinations
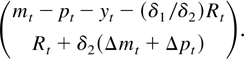
Because Δmt + Δpt = 2Δpt + Δmt − Δpt and Δmt − Δpt is stationary, we have that the model, with τ0 and β0 as given before, allows the stationary relations
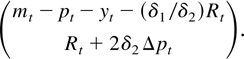
Hence we see that we can define βR = −δ1 /δ2, and the only extra restriction we need to test is the hypothesis δ2 = −0.5. Thus the restrictions formulated previously can be tested successively as the hypotheses
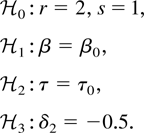
The first hypothesis is a test on cointegrating ranks, and the asymptotic distribution is nonstandard and tabulated by simulation (see Johansen, 1997). It follows from the results in the same paper (see also Boswijk, 2000; Johansen, 2005) that
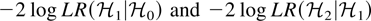
are asymptotically distributed as χ2(4) and χ2(1), respectively. In general one cannot expect hypotheses on the coefficient δ to give asymptotic χ2 tests (see Paruolo, 2000), but

specifies τ⊥ completely, and when that is the case, one can in fact show that a test on δ, and hence
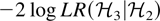
, is asymptotically distributed as χ2(1).
This can be seen by the “nominal-to-real” transformation (see Kongsted, 2005),
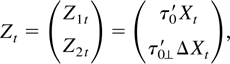
which satisfies a model of the form
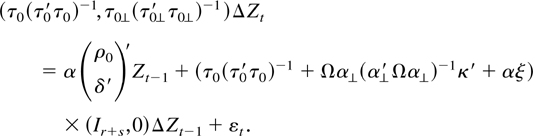
Premultiplying with (τ0,τ0⊥)′ gives the I(1) cointegration model
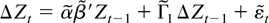
with parameters

and
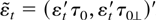
. Thus the transformed model is an I(1) model with linear restrictions on

partly known. A hypothesis on δ is therefore a hypothesis on

in an I(1) model, which is known to give asymptotic χ2 tests (see Johansen, 1991).
References
REFERENCES
Boswijk, P.
(2000)
Mixed normality and ancillarity in I(2) systems.
Econometric Theory
16,
878–904.Google Scholar
Engle, R.F. &
B.S. Yoo
(1991)
Cointegrated economic time series: A survey with new
results. In
C.W.J. Granger &
R.F. Engle (eds.),
Long-Run Economic Relations: Readings in Cointegration, pp.
237–266.
Oxford University Press.
Johansen, S.
(1991)
Estimation and hypothesis testing of cointegration vectors in
Gaussian vector autoregressive models.
Econometrica
59,
1551–1580.Google Scholar
Johansen, S.
(1997)
Likelihood analysis of the I(2) model.
Scandinavian Journal of Statistics
24,
433–462.Google Scholar
Johansen, S.
(2005)
The statistical analysis of hypotheses on the cointegrating
relations in the I(2) model.
Journal of Econometrics,
forthcoming.Google Scholar
Kongsted, H.C.
(2005)
Testing the nominal-to-real transformation.
Journal of Econometrics
124,
205–225.Google Scholar
Lütkepohl, H. &
J. Wolters
(2003)
The transmission of German monetary policy in the pre-euro
period.
Macroeconomic Dynamics
7,
711–733.Google Scholar
Paruolo, P.
(1996)
On the determination of integration indices in I(2) systems.
Journal of Econometrics
72,
313–356.Google Scholar
Paruolo, P.
(2000)
Asymptotic efficiency of the two stage estimator in I(2)
systems.
Econometric Theory
16,
524–550.Google Scholar
Paruolo, P. &
A.C. Rahbek
(1999)
Weak exogeneity in I(2) VAR systems.
Journal of Econometrics
93,
281–308.Google Scholar
Rahbek, A.C.,
H.C. Kongsted, &
C. Jørgensen
(1999)
Trend-stationarity in the I(2) cointegration model.
Journal of Econometrics
90,
265–289.Google Scholar
 You have
Access
- 4
- Cited by