1. Introduction
The optimal dividend problem, a cornerstone of stochastic control theory aimed at maximizing expected discounted dividend payments until ruin, has been extensively explored. For Brownian motion with drift, the optimal dividend problem has been analyzed by Gerber and Shiu [Reference Gerber and Shiu16], yielding barrier optimality. More generally, Shreve et al. [Reference Shreve, Lehoczky and Gaver35] studied optimal consumption for Itô diffusions with absorbing and reflecting boundaries and a discounted penalty at absorption. Paulsen [Reference Paulsen29] analyzed optimal dividend policies for Itô diffusions under solvency constraints with Lipschitz-continuous drift and diffusion coefficients. Asmussen et al. [Reference Asmussen, Højgaard and Taksar4] solved a joint control problem of dividends and excess-of-loss reinsurance for a diffusion process whose drift and volatility depend on the retention level. Décamps and Villeneuve [Reference Décamps and Villeneuve11] examined the interaction between dividends and the timing of a growth investment in a diffusion model with piecewise-constant drift that switches endogenously at a stopping time. These diffusion-based formulations typically lead to barrier-type (or band-type, in joint control) optimal policies.
For the Cramér–Lundberg risk process, Gerber [Reference Gerber15] showed that the optimal dividend strategy is the so-called band strategy by discrete approximation and limiting argument, and for the particular case of exponentially distributed claim amounts, the band strategy collapses to a barrier strategy. This result was rederived by means of viscosity theory in [Reference Azcue and Muler8]. Albrecher and Thonhauser [Reference Albrecher and Thonhauser2] derived the optimal dividend strategy for the Cramér–Lundberg risk model with interest, which is again of band-type and for exponential claim sizes collapses to a barrier strategy. For a more general risk process, namely the spectrally negative Lévy process (SNLP) (see [Reference Bertoin9]), in [Reference Avram, Palmowski and Pistorius6] a sufficient condition was given involving the generator of the Lévy process for the optimality of the barrier strategy. Loeffen [Reference Loeffen27] showed that the optimal strategy is a barrier strategy if the Lévy measure has a completely monotone density. Kyprianou et al. [Reference Kyprianou, Rivero and Song24] further showed that the optimal strategy is a barrier strategy whenever the Lévy measure has a density that is log-convex. Avram et al. [Reference Avram, Palmowski and Pistorius7] identified necessary and sufficient conditions for optimality of single and impulse-band dividend strategies under a general ruin penalty, allowing for the presence or absence of fixed per-dividend transaction costs. In addition, Avanzi [Reference Avanzi5] provided a review of dividend strategies.
Most dividend-control models are interface-free: there are no fixed thresholds that trigger a change in the dynamics (no skew or refraction). Typically, the models encode state dependence by smooth coefficients rather than threshold-driven regime switches. However, real-world market frictions, cumulative shocks and regulatory interventions generate threshold effects that interface-free models cannot capture. This motivates a threshold-based, state-dependent specification with an interface as the driver of regime changes.
We therefore propose a skew Brownian surplus process with a two-valued drift, called refracted skew Brownian motion, that couples skew transmission at a fixed threshold with refraction. More specifically, the model introduces a fixed threshold (interface) at which the dynamics change: The drift is refracted across the threshold (yielding piecewise drift), and asymmetric transmission (skew) is implemented via a local-time term that assigns unequal up- and down-crossing tendencies. Such a two-valued drift encodes transitions between low- and high-risk states, offering a regime-switching mechanism. Moreover, we use this framework to characterize optimal payout policies and to quantify how skew and regime-specific drifts influence the resulting optimal strategies.
We first introduce the skew Brownian motion. Let process
 $X\equiv(X_t)_{t\geq0}$
, defined on a filtered probability space
 $(\mathcal{F}, (\mathcal{F}_t)_{t\geq 0}, \textrm{P}) $
, be a solution to the following stochastic differential equation (SDE) with a singular drift:
 \begin{align} X_t=X_0+\int_0^{t} \sigma (X_s) \, \mathrm{d}B_s+\int_{\mathbb{R}} \nu(\mathrm{d} x) L^X(t, x),\quad t\geq 0,\end{align}
where
 $\sigma\,:\, \mathbb{R}\rightarrow \mathbb{R}$
is a non-negative bounded measurable function, B denotes a standard one-dimensional Brownian motion with initial value 0,
 $\nu(\mathrm{d} x)$
is a bounded measure on
 $\mathbb{R}$
,
 $L^X(t, x)$
is the symmetric local time at level x up to time
 $t\in\mathbb{R}_+$
of process X, i.e.
 \begin{align} L^X(t,x)\,:\!=\,\lim_{\varepsilon\to 0+}\frac{1}{2\varepsilon}\mathrm{Lebesgue}(s\leq t \,:\, |X_s-x|\leq\varepsilon).\end{align}
SDEs of type (1.1) have been studied in [Reference Engelbert and Schmidt12, Reference Étoré and Martinez13, Reference Le Gall25], where existence and uniqueness of a strong solution is proved under conditions such that
 $\sigma$
is uniformly elliptic, bounded and of finite variation, and
 $\nu$
has a finite mass with
 $|\nu(\{x\})| \lt 1$
for any
 $x\in\mathbb{R}$
. More generally, a value x such that
 $|\nu(\{x\})|=1$
corresponds to a reflection of the process over or below this point depending on the sign of
 $\nu(\{x\})$
. For a given real constant
 $\beta$
and Dirac measure
 $\delta_0$
at 0, when
 $\sigma\equiv1$
and
 $\nu(\mathrm{d} x)=\beta \delta_0(\mathrm{d}x)$
, we obtain
 \begin{align} X_t=X_0+B_t+\beta L^X(t, 0),\quad t\geq 0,\end{align}
the so-called skew Brownian motion that was initially studied in [Reference Itô and McKean21, Reference Walsh36]. It is shown in [Reference Harrison and Shepp18] that SDE (1.3) has a unique strong solution if and only if
 $\left| \beta \right|\leq1$
where
 $\left| \beta \right|=1$
corresponds to the reflected Brownian motion. We refer to [Reference Lejay26] and references therein for a review on skew Brownian motion.
Skew Brownian motion, as an extension of standard Brownian motion, introduces asymmetries in its transition probabilities and boundary behaviors, making it a useful tool for modeling systems with inherent directional biases or state-dependent interactions. It also finds many applications in mathematical finance. Rossello [Reference Rossello34] studied the arbitrage under skew Brownian motion. Gairat and Shcherbakov [Reference Gairat and Shcherbakov14] pointed out that in a driftless two-valued local volatility model, the underlying price, after rescaling, follows the dynamic of skew Brownian motion with two-valued drift. They further obtained formulas for pricing of European options using joint density for the skew Brownian motion. Alvarez and Salminen [Reference Alvarez and Salminen3] studied the optimal stopping problem arising in the timing of an irreversible investment when the underlying follows a skew Brownian motion. Hussain et al. [Reference Hussain, Arif, Noorullah and Pantelous20] considered the pricing of American options and the corresponding optimal stopping problem with asset price dynamic following the Azzalini Itô–McKean skew Brownian motion, which is a specific case of skew Brownian motions represented as the sum of a standard Brownian motion and an independent reflecting Brownian motion. Hussain et al. [Reference Hussain, Soomro, Dahri, Memon, Bano, Awwad, Ismail and Ahmad19] investigated the probabilistic distribution functions of the maximum of skew Brownian motion and stock price process driven by the maximum of skew Brownian motion.
Refracted Brownian motion extends the standard Brownian motion by introducing a state-dependent drift that changes at a specified threshold, making it a versatile tool for modeling surplus dynamics in risk theory. This model is particularly suited to scenarios where premium rates or other key parameters adjust based on reserve levels, and was introduced in [Reference Gerber and Shiu17] as the so-called refracted diffusion risk process. Renaud and Simard [Reference Renaud and Simard31] showed that imposing a linear bound on the dividend rate yields refracted-diffusion surplus process and a mean-reverting optimal policy. The refracted Brownian motion also constitutes a special case of refracted spectrally negative Lévy processes introduced in [Reference Kyprianou and Loeffen23].
We now introduce the refracted skew Brownian motion. For
 $\sigma\equiv 1$
and
 $$\nu(\mathrm{d} x)= \beta \delta_a(\mathrm{d}x)+(\mu_+\mathbf{1}_{\{x \gt a\}}+\mu_-\mathbf{1}_{\{x \lt a\}})\,\mathrm{d} x,$$
where
 $\mu_+, \mu_-\in \mathbb{R}$
,
 $\mathbf{1}_{\cdot}$
denotes the indicator function and
 $\delta_a$
denotes the Dirac measure at
 $a> 0$
, the SDE (1.1) becomes
 \begin{eqnarray} X_t=X_0+B_t+\beta L^X(t, a)+\mu_+\int_0^t \mathbf{1}_{\{X_s \gt a\}}\,\mathrm{d} s +\mu_-\int_0^t \mathbf{1}_{\{X_s \lt a\}}\,\mathrm{d} s,\quad t\geq 0.\end{eqnarray}
If
 $\beta\in(\!-1,1)$
then SDE (1.4) has a unique solution (see [Reference Le Gall25]) the refracted skew Brownian motion, that is the focus of this paper. If
 $\beta=0$
, process X becomes the so-called refracted diffusion risk process. We refer to [Reference Mazzonetto28] for numerical issues involving refracted skew Brownian motion.
The refracted skew Brownian motion can be used as a toy model of endogenous regime-switching process in which the process has distinct dynamics depending on whether it takes a value above or below threshold a where the local time term can be interpreted as the cost or reward associated to the switching of regimes. This simple model already allows the optimality of a class of barrier and band strategies together with their variants, and the fewer model parameters helps to better understand the interplay between them. More sophisticated and realistic models with a state-dependent diffusion coefficient and (or) jumps can also be proposed and studied in the future.
Our approach is a modification of previous work on the optimal dividend problem in the risk theory literature. To identify the optimal strategies, we first prove the corresponding Hamilton–Jacobi–Bellman (HJB) inequalities that characterize the value function. Since barrier dividend strategies often serve as the optimal strategies for various surplus processes, we then propose different versions of barrier strategies and for each barrier strategy find an explicit expression of the associated value function. Applying the HJB inequalities we identify conditions for each of the barrier strategies to be optimal.
In another interesting finding, we show that a band strategy can be optimal in a broad class of settings, whether band or barrier is optimal depends on the interaction among interface skew, regime-specific drifts, and other model parameters. Sufficient conditions are identified for different versions of band strategies to be optimal. The above setup of the model allows us to analyze how the phase transition of different optimal strategies is affected by the skew and different regimes, which addresses key challenges and contributes to the broader understanding of the stochastic systems with endogenous regime switching.
The rest of the paper is arranged as follows. The two-sided exit problem is solved in Section 2 for the refracted skew Brownian risk process. The HJB inequalities are shown in Section 3. In Sections 4 and 5 we find conditions for barrier strategy and band strategy to be optimal, respectively. Numerical illustrations are provided in Section 6.
2. Solutions to the exit problems
In this section, we derive explicit expressions of the Laplace transforms of exit times for the refracted skew Brownian motion, which provides a theoretical basis for the follow-up study. The law and the expectation with respect to X issued at
 $x\in \mathbb{R}$
are denoted as
 $\textrm{P}_x$
and
 $\textrm{E}_x$
, respectively. For any
 $y\in\mathbb{R}$
, define the first hitting time for process X by
 \begin{eqnarray*}&\tau_{y}\,:\!=\,\inf\{t\geq 0, X_t=y\},\end{eqnarray*}
with the convention
 $\inf\emptyset=\infty$
. For any
 $y \lt x \lt z$
, define the first exit time of the interval (y,z) for the process X by
 \begin{eqnarray*}&\tau_{y, z}\,:\!=\,\tau_y\wedge \tau_{z}=\min\{\tau_{y}, \tau_{z}\}.\end{eqnarray*}
To obtain the Laplace transforms, we first find the general solutions
 $g_{1,q}(x)$
and
 $g_{2,q}(x)$
in
 $C(\mathbb{R})\cap C^{2}(\mathbb{R}\backslash \{a\})$
to the following differential equation:
 \begin{align}&\frac{1}{2}g''(x)+\mu_+\mathbf{1}_{\{x \gt a\}}g'(x)+\mu_-\mathbf{1}_{\{x \lt a\}}g'(x)=qg(x),\end{align}
with
 $(1+\beta) g'(a+\!)=(1-\beta)g'(a-\!)$
for
 $\beta\in (\!-1, 1)$
and
 $q\geq 0$
. For
 $q\geq 0$
, let
 \begin{align}g_{1,q}(x)\,:\!=\,e^{\rho_{1}^+(x-a)} {\mathbf{1}_{\{x \gt a\}}}+{\Big(c_1(q)e^{\rho_{2}^-{(x-a)}}+\big(1-c_1(q)\big) e^{\rho_{1}^-{(x-a)}} \Big)}{\mathbf{1}_{\{x\leq a\}}}, \end{align}
 \begin{align} g_{2,q}(x)\,:\!=\,\Big(\big(1-c_2(q)\big)e^{\rho_{2}^+(x-a)}+c_2(q) e^{\rho_{1}^+(x-a)} \Big){1_{\{x \gt a\}}}{+e^{\rho_{2}^-(x-a)}}{1_{\{x\leq a\}}},\end{align}
where both
 $\rho_1^- \lt 0$
and
 $\rho_2^->0$
satisfy
 \begin{align}&\frac{1}{2}{\rho_i^-}^2+\mu_-\rho_i^{-} -q=0,\quad i=1,2,\end{align}
and both
 $\rho_{1}^+ \lt 0$
and
 $\rho_{2}^+>0$
satisfy
 \begin{align}&\frac{1}{2}{\rho_i^+}^2+\mu_+\rho_i^{+} -q=0,\quad i=1,2,\end{align}
i.e.
 \begin{align}&\rho_{1}^{\pm}\,:\!=\,-(\mu_{\pm}+\sqrt{\mu_{\pm}^2+2q}), \quad \rho_{2}^{\pm}\,:\!=\,-\mu_{\pm}+\sqrt{\mu_{\pm}^2+2q}.\end{align}
Since
 \begin{eqnarray}&&(1+\beta) g_{i,q}'(a+\!)=(1-\beta)g_{i,q}'(a-\!),\quad i=1,2,\end{eqnarray}
we have
 \begin{align}c_1(q)\,:\!=\,\frac{(1+\beta) \rho_{1}^+-(1-\beta)\rho_{1}^-}{(1-\beta)(\rho_{2}^{-}-\rho_{1}^-)},\quad c_2(q)\,:\!=\,\frac{(1+\beta) \rho_{2}^+-(1-\beta)\rho_{2}^-}{(1+\beta)(\rho_{2}^+-\rho_{1}^+)}.\end{align}
In particular, for
 $\mu_-=\mu_+=0$
, we have
 $c_1(q)=\frac{-\beta}{1-\beta}$
and
 $c_2(q)=\frac{\beta}{1+\beta}$
. The range of
 $c_i(q),\ $
 $i=1, 2$
is provided below, with the proof in Appendix A.1.
Lemma 2.1. We have
 $c_i(q) \lt 1$
for all
 $q>0$
and
 $i=1, 2$
. Further, we have
 $c_i(q) \lt 0$
if and only if
 $(1+\beta) \rho_{i}^+<(1-\beta)\rho_{i}^-$
.
Theorem 2.1. For any
 $q>0$
,
 $x, y, z\in\mathbb{R}$
and
 $x\in(y, z)$
, we have
 \begin{align} \textrm{E}_{x}[e^{-q \tau_{z}}; \tau_{z}<\tau_{y}]= \frac{w(x,y)}{w(z,y)},\\[-28pt] \nonumber \end{align}
 \begin{align}\textrm{E}_{x}[e^{-q \tau_{y}}; \tau_{y}<\tau_{z}]=\frac{w(x,z)}{w(y,z)},\end{align}
where
 $g_{1,q}(x)$
and
 $g_{2,q}(x)$
are defined in (2.2) and (2.3), respectively, and
 \begin{eqnarray}&&w(x,y)\,:\!=\,g_{2,q}(x)g_{1,q}(y)-g_{1,q}(x)g_{2,q}(y).\end{eqnarray}
Proof. For
 $q>0$
and
 $i=1,2$
, applying the Itô–Tanaka–Meyer formula (cf. [Reference Lejay26], Section 6, and [Reference Protter30], Theorem 70) to
 $\big(e^{-q t}g_{i,q}(X_{t})\big)_{t\geq 0}$
, we have
 \begin{align*}&e^{-q t} g_{i,q}(X_{t})=g_{i,q}(x) + M_t^{(i)}+ \left(\frac{1+\beta}{2} g_{i,q}'(a+\!)-\frac{1-\beta}{2}g_{i,q}'(a-\!)\right)\int_0^{t}e^{-q s} L^{X}(\mathrm{d}s, a)\\& \quad + \int_0^{t} e^{-q s}\left(\frac{1}{2}g_{i,q}''(X_{s-})+ (\mu_+\mathbf{1}_{\{X_{s-} \gt a\}} +\mu_-\mathbf{1}_{\{X_{s-} \lt a\}})g_{i,q}'(X_{s-})-q g_{i,q}(X_{s-})\right) \, \mathrm{d}s,\end{align*}
where
 $M_{t}^{(i)} \,:\!=\, \int_0^t e^{-q s}g_{i,q}'(X_{s-})\, \mathrm{d} B_s$
,
 $i = 1, 2$
are local martingales with quadratic variations
 $\langle M^{(i)} \rangle_t=\int_0^t \bigl(e^{-qs}g_{i,q}'(X_{s})\bigr)^2\,\mathrm{d}s$
. By (2.1) and (2.7), these reduce to
 $e^{-q t} g_{i,q}(X_{t})=g_{i,q}(x)+ M_t^{(i)}$
, and then
 $e^{-qt}g_{i,q}(X_t)$
are local martingales.
Let
 $t_n \,:\!=\, \inf\{t\geq 0: |X_t|\geq n\}$
. Since
 $g_{i,q}'$
is continuous on the compact set
 $[y,z]\cap [-n, n]$
, it is bounded there:
 $\sup_{x\in[y, z]\cap[-n, n]} |g_{i,q}'(x)| \,:\!=\, C_n<\infty$
. Then,
 \begin{align*} \textrm{E}[\langle M^{(i)} \rangle_{t_n \wedge \tau_{y,z}}] = \textrm{E}\bigg[\int_0^{t_n\wedge \tau_{y,z}} \left(e^{-qs}g_{i,q}'(X_{s})\right)^2\,\mathrm{d}s \bigg] \le C_n^2 \, \frac{1 - e^{-2q t_n}}{2q} \le \frac{C_n^2}{2q} \lt \infty.\end{align*}
By Itô isometry (cf. [Reference Karatzas and Shreve22], Proposition 3.2.10), the stochastic integrals
 $M_{t_n \wedge \tau_{y,z}}^{(i)}$
are square integrable, therefore there are martingales. Equivalently, let
 $n\uparrow \infty$
, for
 $x\in(y,z)$
, we have
 \[g_{1,q}(x)=\textrm{E}_x [e^{-q(\tau_y\wedge \tau_z)}g_{1,q}(X_{\tau_y\wedge \tau_z})]=g_{1,q}(y)\textrm{E}_x [e^{-q\tau_y}; \tau_y<\tau_z]+g_{1,q}(z)\textrm{E}_x [e^{-q\tau_z}; \tau_z<\tau_y], \\[-6pt] \nonumber \]
 \[g_{2,q}(x)=\textrm{E}_x [e^{-q(\tau_y\wedge \tau_z)}g_{2,q}(X_{\tau_y\wedge \tau_z})]=g_{2,q}(y)\textrm{E}_x [e^{-q\tau_y}; \tau_y<\tau_z]+g_{2,q}(z)\textrm{E}_x [e^{-q\tau_z}; \tau_z<\tau_y]. \]
The results in (2.9) and (2.10) are derived by solving the above system of equations.
Note that
 $\textrm{E}_{x}[e^{-q \tau_{y, z}}]=\textrm{E}_{x}[e^{-q \tau_{y}}; \tau_{y}<\tau_{z}]+\textrm{E}_{x}[e^{-q \tau_{z}}; \tau_{z}<\tau_{y}]$
.
Theorem 2.2. For any
 $q>0$
,
 $x, y, z\in\mathbb{R}$
and
 $x\in(y, z)$
, we have
 \begin{align}\textrm{E}_{x}[e^{-q \tau_{y, z}}]=\frac{w(x,y)-w(x,z)}{w(z,y)}.\end{align}
In addition,
 $\textrm{E}_{y}[e^{-q \tau_{y, z}}]=1$
and
 $\textrm{E}_{z}[e^{-q \tau_{y, z}}]=1$
.
Taking the limit as
 $z\uparrow\infty$
or
 $y\downarrow-\infty$
in (2.12), we obtain the following theorem.
Theorem 2.3. Given
 $q>0$
and
 $x,r\in\mathbb{R}$
, we have for any
 $x\geq r$
,
 \begin{eqnarray} \textrm{E}_{x}[e^{-q \tau_{r}}]=e^{\rho_1^+ (x-r)}\mathbf{1}_{\{r \gt a\}}+ \frac{g_{1,q}(x)}{c_1(q)e^{\rho_2^-(r-a)}+\big{(}1-c_1(q)\big{)}e^{\rho_1^-(r-a)}} \mathbf{1}_{\{r\leq a\}},\end{eqnarray}
and for
 $x \lt r$
,
 \begin{eqnarray} \textrm{E}_{x}[e^{-q \tau_{r}}]=e^{\rho_2^- (x-r)}\mathbf{1}_{\{r\leq a\}}+ \frac{g_{2,q}(x)}{\big{(}1-c_2(q)\big{)}e^{\rho_2^+(r-a)}+c_2(q)e^{\rho_1^+(r-a)}} \mathbf{1}_{\{r \gt a\}}.\end{eqnarray}
Proof. For
 $x\geq r$
, letting
 $y=r$
and
 $z\uparrow\infty$
in (2.12), by L’Hôpital’s rule we have
 \begin{align*}\textrm{E}_{x}[e^{-q \tau_{r}}]&=\lim_{z\uparrow\infty}\textrm{E}_{x}[e^{-q \tau_{r, z}}]=\lim_{z\uparrow\infty}\frac{g_{2,q}'(z)g_{1,q}(x)-g_{1,q}'(z)g_{2,q}(x)}{g_{2,q}'(z)g_{1,q}(r)-g_{1,q}'(z)g_{2,q}(r)}\\&=\lim_{z\uparrow\infty}\frac{\big((1-c_2)\rho_2^+e^{\rho_2^+ (z-a)}+c_2 \rho_1^+e^{\rho_1^+ (z-a)}\big)g_{1,q}(x)-\rho_{1}^+e^{\rho_{1}^+(z-a)} g_{2,q}(x)}{\big((1-c_2)\rho_2^+e^{\rho_2^+ (z-a)}+c_2 \rho_1^+e^{\rho_1^+ (z-a)}\big)g_{1,q}(r)-\rho_{1}^+e^{\rho_{1}^+(z-a)} g_{2,q}(r)}.\end{align*}
Dividing both the numerator and denominator by
 $e^{\rho_2^+(z-a)}$
in the above equation yields
 \begin{align*}\textrm{E}_{x}[e^{-q \tau_{r}}]&=\lim_{z\uparrow\infty}\frac{\big((1-c_2)\rho_2^++c_2 \rho_1^+e^{(\rho_1^+-\rho_{2}^+) (z-a)}\big)g_{1,q}(x)-\rho_{1}^+e^{(\rho_{1}^+-\rho_{2}^+)(z-a)} g_{2,q}(x)}{\big((1-c_2)\rho_2^++c_2 \rho_1^+e^{(\rho_1^+-\rho_{2}^+) (z-a)}\big)g_{1,q}(r)-\rho_{1}^+e^{(\rho_{1}^+-\rho_{2}^+)(z-a)} g_{2,q}(r)}\\&=\frac{g_{1,q}(x)}{g_{1,q}(r)}.\end{align*}
Then (2.13) follows from (2.2). Laplace transform (2.14) can be obtained similarly.
Remark 2.1. For any
 $q>0$
,
 $y \lt z \lt a$
and
 $x\in(y,z)$
, we have
 \begin{eqnarray*} &&\textrm{E}_{x}[e^{-q \tau_{z}}; \tau_{z}<\tau_{y}]= \frac{e^{\rho_2^-(x-y)}-e^{\rho_1^-(x-y)}}{e^{\rho_2^-(z-y)}-e^{\rho_1^-(z-y)}},\quad \textrm{E}_{x}[e^{-q \tau_{y}}; \tau_{y}<\tau_{z}]=\frac{e^{\rho_2^-(x-z)}-e^{\rho_1^-(x-z)}}{e^{\rho_2^-(y-z)}-e^{\rho_1^-(y-z)}}.\nonumber\end{eqnarray*}
Remark 2.2. For
 $\beta=0$
and
 $\mu_+=\mu_-=\mu$
, X in (1.4) reduces to Brownian motion with drift
 $\mu$
. In this case, for
 $q>0$
and
 $x\in(y,z)$
, we have
 \begin{eqnarray*} &&\textrm{E}_x[e^{-q \tau_z}; \tau_z<\tau_y]=\frac{e^{\rho_2 (x-y)}-e^{\rho_1(x-y)}}{e^{\rho_2(z-y)}-e^{\rho_1(z-y)}},\quad\textrm{E}_x[e^{-q \tau_y}; \tau_y<\tau_z]=\frac{e^{\rho_2(x-z)}-e^{\rho_1(x-z)}}{e^{\rho_2(y-z)}-e^{\rho_1(y-z)}},\end{eqnarray*}
where
 $\rho_2=\rho_2^-=\rho_2^+$
and
 $\rho_1=\rho_1^-=\rho_1^+$
. In addition, for
 $q>0$
and
 $x, r\in \mathbb{R}$
we have
 \begin{eqnarray*}&&\textrm{E}_x[e^{-q \tau_r}]=e^{\rho_2(x-r)}\mathbf{1}_{\{x \lt r\}}+e^{\rho_1(x-r)}\mathbf{1}_{\{x\geq r\}}.\end{eqnarray*}
These results are consistent with those presented in Part II, Section 2 of [Reference Borodin and Salminen10].
3. Conditions for optimal dividend strategies
In this section, we first present the optimal dividend problem for refracted skew Brownian risk process, and then prove the corresponding HJB inequalities.
A dividend strategy
 $\pi\equiv (D_t^{\pi})_{t\geq 0}$
is a
 $(\mathcal{F}_t)$
-adapted process starting at 0 with sample paths that are non-decreasing and right continuous with left limits, where
 $D_t^{\pi}$
represents the cumulated dividends up to time t under the strategy
 $\pi$
. Define a controlled risk process
 $U^{\pi}\equiv(U_t^{\pi})_{t\geq 0}$
with
 $U_0^{\pi}=x$
by
 \begin{eqnarray} \mathrm{d} U_t^{\pi}\,:\!=\,\mathrm{d} B_t+\beta L^{U^{\pi}}(\mathrm{d}t, a)+(\mu_+\mathbf{1}_{\{U_t^{\pi} \gt a\}}+\mu_-\mathbf{1}_{\{U_t^{\pi} \lt a\}})\,\mathrm{d} t- \mathrm{d} D_t^{\pi},\end{eqnarray}
where
 $L^{U^{\pi}}(\mathrm{d}t, a)$
is defined as the local time in (1.2). Let
 $T^{\pi}\,:\!=\,\inf\{t\geq 0\,:\, U_t^{\pi}\leq0\}$
be the ruin time. For initial capital
 $x\in\mathbb{R}_+$
, the expected total amount of dividends (discounted at rate
 $q>0$
) until ruin associated to
 $\pi$
is given by
 \begin{eqnarray*} V_{\pi}(x)\,:\!=\,\textrm{E}_x\Big[\int_0^{T^{\pi}} e^{-q t} \,\mathrm{d} D_t^{\pi}\Big].\end{eqnarray*}
A strategy
 $\pi$
is called admissible if ruin does not occur due to dividend payments, i.e.
 $\Delta D_t^{\pi}=D_{t}^{\pi}-D_{t-}^{\pi}\leq U_{t-}^{\pi} \vee 0$
for any
 $0\leq t \lt T^{\pi}$
, and
 $\Delta D_t^{\pi}=0$
for
 $t\geq T^{\pi}$
, and
 $b\vee x=\max\{b,x\}$
, and SDE (3.1) has a unique strong solution. Let
 $\Pi$
be the set of all admissible dividend strategies. Define a value function
 $V_*$
by
 $$V_*(x)\,:\!=\,\sup_{\pi\in\Pi}V_{\pi}(x), \quad x\geq 0.$$
A dividend strategy
 $\pi_*\in\Pi$
is optimal if
 $V_{\pi_*}(x)=V_*(x)$
for all
 $x\in \mathbb{R_+}$
.
Write
 $\mathcal{P}\,:\!=\,\{p_k, k=1,\ldots,N\}$
for a fixed finite subset of
 $(0, \infty)\backslash \{a\}$
. Let function
 $f\,:\, \mathbb{R}_+\rightarrow \mathbb{R}$
be right continuous at 0 and continuous on
 $(0, \infty)$
. Suppose that derivatives f
′ and f
′′ on
 $\mathbb{R}_+\backslash (\mathcal{P}\cup\{a\})$
are locally bounded, and both the left and right derivative at each
 $y\in \mathcal{P}\cup\{a\}$
exist. For
 $y\in \mathbb{R}_+\backslash (\mathcal{P}\cup\{a\})$
, define the operator
 $\mathcal{A}$
by
 \begin{eqnarray} &&\mathcal{A} f(y)\,:\!=\,\frac{1}{2}f''(y)+(\mu_+\mathbf{1}_{\{y \gt a\}}+\mu_-\mathbf{1}_{\{y \lt a\}})f'(y).\end{eqnarray}
Lemma 3.1. (Verification lemma.)
-
(i) Suppose that
 $V\in C^{2}\big(\mathbb{R}_+ \backslash (\mathcal{P}\cup\{a\})\big)\cap C(\mathbb{R}_{+})$
and its first derivative has finite left and right limits at each
$p_{k}\in\mathcal{P}$
denoted by
$V'(p_{k}-)$
and
$V'(p_{k}+)$
, respectively. If V satisfies the following HJB inequalities (3.3)
\begin{align}&(\mathcal{A}-q)V(x)\leq 0 \qquad & \mathrm{for}\ x\in \mathbb{R_+}\backslash (\mathcal{P}\cup\{a\}); \\[-12pt] \nonumber \end{align}
(3.4)
\begin{align} &1-V'(x)\leq 0 \qquad & \mathrm{for}\ x\in \mathbb{R_+}\backslash (\mathcal{P}\cup\{a\}); \\[-12pt] \nonumber\end{align}
(3.5)
\begin{align}&(1+\beta) V'(a+\!)-(1-\beta)V'(a-\!)\leq 0; \\[-12pt] \nonumber\end{align}
(3.6)then
\begin{align} &V'(x+)-V'(x-)\leq 0 &\mathrm{for}\ x\in \mathcal{P}; \\[9pt] \nonumber\end{align}
$V(x)\geq V_*(x)$
for all
$x\in \mathbb{R_+}$
.
-
(ii) If
$\hat{\pi}$
is an admissible dividend strategy with the associated expected discounted dividend function,
$V_{\hat{\pi}}$
, satisfying the smoothness condition and the HJB inequalities (3.3)–(3.6) in (i), then
$V_{\hat{\pi}}(x)=V_*(x)$
.


Proof. We only prove (i). Note that V can be expressed as the difference of two convex functions, cf. Section 6 of [Reference Lejay26]. Then V is locally Lipschitz on
 $\mathbb{R}_+$
and differentiable almost everywhere (a.e.), and its derivative
 $V'$
has locally bounded variation. Subsequently, by standard bounded variation theory,
 $V'$
is regulated, that is, the one-sided limits
 $V'(p\pm)$
exist and are finite for each
 $p\in \mathbb{R}_+ \cup\{a\}$
(cf. Section 10 of [Reference Rockafellar and Wets33]). Under our regularity assumptions
 $V'(p\pm)$
coincide with the one-sided derivatives of V at p. The second generalized derivative of V is given by
 \begin{eqnarray*}\mu(\mathrm{d}y)=V{''}(y)\,\mathrm{d}y+\sum_{p\in\mathcal{P}\cup\{a\}}(V'(p+)-V'(p-))\delta_p(\mathrm{d}y),\end{eqnarray*}
where
 $\delta_p$
denotes a Dirac mass at p. Define
 $T_n\,:\!=\,\inf\{t>0\,:\, U_t^{\pi}\notin (0, n) \}$
. Applying the Itô–Tanaka–Meyer formula to
 $\big(e^{-q(t\wedge T_n)}V(U_{t\wedge T_n}^{\pi})\big)_{t\geq 0}$
, we have that under
 $\textrm{P}_x$
,
 \begin{align*}&e^{-q(t\wedge T_n)}V(U_{t\wedge T_n}^{\pi}) =V(x)-\int_0^{t\wedge T_n}q e^{-q s} V(U_{s-}^{\pi})\,\mathrm{d}s+\int_0^{t\wedge T_n}e^{-q s}V'(U_{s-}^{\pi})\,\mathrm{d}U_{s}^{\pi}\\ & +\frac{1}{2}\int_0^{t\wedge T_n}e^{-qs}\int_\mathbb{R_+}\mu(\mathrm{d}y)L^{U^{\pi}}(\mathrm{d}s, y)+\sum_{0\leq s \leq t\wedge T_n}e^{-q s}\big(V(U_{s}^{\pi})-V(U_{s-}^{\pi})-V'(U_{s-}^{\pi})\Delta U_{s}^{\pi}\big)\\ &=V(x)-\int_0^{t\wedge T_n}q e^{-q s} V(U_{s-}^{\pi})\,\mathrm{d}s+\int_0^{t\wedge T_n} e^{-q s}(\mu_+\mathbf{1}_{\{U_{s-}^{\pi} \gt a\}}+\mu_-\mathbf{1}_{\{U_{s-}^{\pi} \lt a\}})V'(U_{s-}^{\pi})\,\mathrm{d}s\\ & +\int_0^{t\wedge T_n}e^{-q s}V'(U_{s-}^{\pi})\,\mathrm{d}B_{s}-\int_0^{t\wedge T_n}e^{-q s}V'(U_{s-}^{\pi})\,\mathrm{d}D^{\pi, c}_{s}-\sum_{0\leq s \leq t\wedge T_n}e^{-q s}V'(U_{s-}^{\pi})\Delta D_{s}^{\pi}\\ & +\frac{\beta}{2} (V '(a+\!)+V'(a-\!))\int_0^{t\wedge T_n}e^{-q s} L^{U^{\pi}}(\mathrm{d}s, a)+ \frac{1}{2}\int_0^{t\wedge T_n}e^{-qs}\int_\mathbb{R_+}V{''}(y)L^{U^{\pi}}(\mathrm{d}s, y)\,\mathrm{d}y\\ &+ \frac{1}{2}\sum_{p\in \mathcal{P}\cup\{a\}}\big(V'(p+)-V'(p-)\big)\int_0^{t\wedge T_n}e^{-q s} L^{U^{\pi}}(\mathrm{d}s, p)\\ &+\sum_{0\leq s \leq t\wedge T_n}e^{-q s}\big(V(U_{s}^{\pi})-V(U_{s-}^{\pi})-V'(U_{s-}^{\pi})\Delta U_{s}^{\pi}\big). \end{align*}
By the occupation time formula (cf. [Reference Lejay26], (34)), for
 $t \lt T^{\pi}$
, we have
 \[\int_\mathbb{R_+}V{''}(y)L^{U^{\pi}}(t, y)\,\mathrm{d}y=\int_0^t V{''}(U_{s-}^\pi)\,\mathrm{d}s\quad\mathrm{and}\quad \Delta U_{s}^{\pi}=-\Delta D_{s}^{\pi}.\]
Then, by (3.2) we have
 \begin{align*}e^{-q(t\wedge T_n)}V(U_{t\wedge T_n}^{\pi})&=V(x)+\int_0^{t\wedge T_n}e^{-q s}(\mathcal{A}-q) V(U_{s-}^{\pi})\,\mathrm{d}s +M_{t\wedge T_n}\\& -\int_0^{t\wedge T_n}e^{-q s}V'(U_{s-}^{\pi})\mathrm{d}D^{\pi, c}_{s}+\sum_{0\leq s \leq t\wedge T_n}e^{-q s}\big(V(U_{s}^{\pi})-V(U_{s-}^{\pi})\big)\\& +\bigg(\frac{1+\beta}{2} V'(a+\!)-\frac{1-\beta}{2}V'(a-\!)\bigg)\int_0^{t\wedge T_n}e^{-q s} L^{U^{\pi}}(\mathrm{d}s, a)\\& + \frac{1}{2}\sum_{p\in \mathcal{P}}\big(V'(p+)-V'(p-)\big)\int_0^{t\wedge T_n}e^{-q s} L^{U^{\pi}}(\mathrm{d}s, p),\end{align*}
where
 $(D_t^{\pi,c})_{t\geq 0}$
denotes the continuous part of the process
 $(D_t^{\pi})_{t\geq 0}$
and
 $M_{t}\,:\!=\,\int_0^t e^{-q s}V'$
 $(U_{s-}^{\pi})\,\mathrm{d} B_s$
for
 $t\geq 0$
is a local martingale with
 $M_0=0$
.
For any
 $x_1, x_2\in\mathbb{R}_+$
with
 $x_1 \lt x_2$
, if
 $V\in C^1([x_1, x_2])$
then by (3.4) we have
 $V'(x)\geq 1$
for
 $x\in[x_1, x_2]$
, and by the mean value theorem, we have
 $V(x_2)-V(x_1)\geq x_2-x_1$
. Similarly, if
 $V\in C^1([x_1, p)\cup(p, x_2])$
for
 $p\in\mathcal{P}\cup\{a\}$
then
 \begin{equation*}V(x_2)-V(x_1)=V(x_2)-V(p)+V(p)-V(x_1)\geq x_2-p+p-x_1=x_2-x_1.\end{equation*}
Thus,
 $V(U_s^{\pi})-V(U_{s-}^{\pi})=-(V(U_{s-}^{\pi})-V(U_s^{\pi}))\leq -(U_{s-}^{\pi}- U_s^{\pi})=\Delta U_s^{\pi}=-\Delta D_s^{\pi}.$
Combin ing (3.3), (3.5), and (3.6) we have
 \begin{align*} V(x)&=e^{-q(t\wedge T_n)}V(U_{t\wedge T_n}^{\pi})-\int_0^{t\wedge T_n}e^{-q s}(\mathcal{A}-q) V(U_{s-}^{\pi})\,\mathrm{d}s-M_{t\wedge T_n}\\&+\int_0^{t\wedge T_n}e^{-q s}V'(U_{s-}^{\pi})\,\mathrm{d}D^{\pi, c}_{s}-\sum_{0\leq s \leq t\wedge T_n}e^{-q s}\big(V(U_{s}^{\pi})-V(U_{s-}^{\pi})\big)\\& -\bigg(\frac{1+\beta}{2} V'(a+\!)-\frac{1-\beta}{2}V'(a-\!)\bigg)\int_0^{t\wedge T_n}e^{-q s} L^{U^{\pi}}(\mathrm{d}s, a)\\& -\frac{1}{2}\sum_{p\in \mathcal{P}}\big(V'(p+)-V'(p-)\big)\int_0^{t\wedge T_n}e^{-q s} L^{U^{\pi}}(\mathrm{d}s, p)\\& \geq e^{-q(t\wedge T_n)}V(U_{t\wedge T_n}^{\pi})+\int_0^{t\wedge T_n}e^{-q s}\,\mathrm{d} D^{\pi, c}_{s}+\sum_{0\leq s \leq t\wedge T_n}e^{-q s}\Delta D_s^{\pi}-M_{t\wedge T_n}\\& = e^{-q(t\wedge T_n)}V(U_{t\wedge T_n}^{\pi})+\int_0^{t\wedge T_n}e^{-q s}\,\mathrm{d} D_s^{\pi}-M_{t\wedge T_n}. \end{align*}
Note that
 ${T_n}{\longrightarrow}T^\pi$
for
 $\textrm{P}_x$
-almost surely (a.s.). Taking expectation on both sides of the inequality above and letting
 $t, n\uparrow\infty$
, since
 $V\geq 0$
on
 $\mathbb{R}_+$
, by the monotone convergence theorem
 \[V(x) \geq \lim_{t,n\uparrow\infty}\textrm{E}_x\Big[\int_0^{t\wedge T_n}e^{-q s}\,\mathrm{d} D_s^{\pi}\Big]=\textrm{E}_x\Big[\int_0^{T^{\pi}}e^{-q s}\,\mathrm{d} D_s^{\pi}\Big]= V_{\pi}(x).\]
This completes the proof.
Definition 3.1. For
 $\pi\in\Pi$
, suppose that
 $V_\pi$
is piecewise
 $C^1$
on
 $\mathbb{R}_+$
with at most finitely many non-
 $C^1$
points. Define
 $\mathcal{P}_\pi\,:\!=\,\{ y \in \mathbb{R}_+ \setminus\{a\}\,:\, V_\pi \text{ is not } C^1 \text{ at } y \}$
. Then,
 $\mathcal{P}_\pi$
is a finite (possibly empty) subset of
 $\mathbb{R}_+\setminus\{a\}$
.
4. Optimal barrier strategies
In this section, we consider the barrier strategy for dividend payment. According to such a strategy
 $\pi_b$
for
 $b\geq0$
, intuitively a minimal amount of dividend is paid whenever the surplus process is going to upcross level b to keep the controlled surplus below level b. If the underlying surplus process is a Brownian motion with drift, the controlled process is described by the drifted Brownian motion reflected at level b and the accumulated dividends is represented by the local time for the reflected process. For
 $b \gt a$
, the refracted skew Brownian surplus process follows the dynamics of a drifted Brownian motion near b. Therefore, the dividend process
 $ (D_t^{\pi_b})_{t\geq 0}$
is well defined and the controlled process
 $U^{\pi_b}$
is the unique solution to (3.1) with
 $\pi$
replaced by
 $\pi_b$
.
4.1. Expected discounted dividend function for barrier strategies
Denote by
 $\hat{\tau}_y$
the time at which process
 $U^{\pi_b}$
first hits the boundary y,
 \begin{align*} &\hat{\tau}_{y}\,:\!=\,\inf\{t\geq 0, U_t^{\pi_b}\leq y\}.\end{align*}
The time of ruin
 $T^{\pi_b}$
is equal to
 $\hat{\tau}_{0}$
. We write
 $V_b$
for
 $V_{\pi_b}$
and present an expression
 $V_{b}$
for a general barrier dividend strategy
 $\pi_b$
whose proof is deferred to Appendix A.2.
Lemma 4.1. For any
 $0\leq a_0 \lt b$
and
 $b\in\mathbb{R}_+\backslash\{a\}$
, we have
 \begin{align} &V_{b}(b,a_0)\,:\!=\,\textrm{E}_b\Big[\int_0^{\hat{\tau}_{a_0}} e^{-q t} \, \mathrm{d} D_t^{\pi_{b}}\Big]=\frac{w(b, a_0)}{w_{b}(b, a_0)}, \end{align}
where w(x,y) is given by (2.11) and
 \begin{align} &w_{x}(x,y)\,:\!=\,\partial w(x,y)/\partial x. \end{align}
Further, for
 $x\in\mathbb{R}_+$
and
 $b\in\mathbb{R}_+\backslash\{a\}$
, we have
 \begin{eqnarray} &V_b(x)=\left \{ \begin{array}{l@{\qquad}l} \dfrac{W(x)}{W'(b)} & \mathrm{for}\ 0\leq x\leq b, \\[8pt]x-b+\dfrac{W(b)}{W'(b)} & \mathrm{for}\ x \gt b, \end{array} \right. \end{eqnarray}
where
 \begin{eqnarray} &&W(x)\,:\!=\,w(x,0)=g_{2,q}(x)g_{1,q}(0)-g_{1,q}(x)g_{2,q}(0). \end{eqnarray}
Note that, for
 $0\leq x \lt a$
and
 $\beta=0$
, by (4.4) and (A1) we have
 \begin{align*}&W(x)=\big(1-c_1(q)\big)e^{-(\rho_1^-+\rho_2^-)a}(e^{\rho_2^-x}-e^{\rho_1^-x})=\frac{(\rho_2^- -\rho_1^+)e^{2\mu_-a}}{\rho_2^{-}-\rho_1^-} (e^{\rho_2^- x}-e^{\rho_1^- x}),\end{align*}
which is proportional to the scale function
 $\frac{2}{\rho_2^{-}-\rho_1^-}(e^{\rho_2^- x}-e^{\rho_1^- x})$
of the classical Brownian motion with a drift
 $\mu_-$
. In addition,
 $V_{a-}$
and
 $V_{a+}$
denote the limits as b approaches a from the left and right, respectively, i.e.
 $V_{a-}=\lim_{b\rightarrow a-} V_b$
and
 $V_{a+}=\lim_{b\rightarrow a+} V_b$
.
Remark 4.1. Because the skew Brownian motion has a singular drift at level a, its behavior at a is very different from the standard diffusion. For example, its transition density function is not continuous at a; see [Reference Ahmadi and Zhou1]. Due to the skewness, the scale function W is continuous, but not differentiable at a, and as a result,
 $V_{a-}\neq V_{a+}$
in general.
Remark 4.2. For
 $\beta=0$
and
 $\mu_+=\mu_-=\mu$
, X in (1.4) reduces to Brownian motion with drift
 $\mu$
. In this case, the function (4.3) simplifies to
 \begin{eqnarray*} &V_b(x)=\left \{ \begin{array}{l@{\qquad}l} \dfrac{e^{\rho_2 x}-e^{\rho_1 x}}{\rho_2 e^{\rho_2 b}- \rho_1 e^{\rho_1 b}} & \mathrm{for}\ 0\leq x\leq b, \\[8pt]x-b+\dfrac{e^{\rho_2 b}-e^{\rho_1 b}}{\rho_2 e^{\rho_2 b}- \rho_1 e^{\rho_1 b}} & \mathrm{for}\ x \gt b, \end{array} \right. \end{eqnarray*}
where
 $\rho_2=\rho_2^-=\rho_2^+$
and
 $\rho_1=\rho_1^-=\rho_1^+$
, consistent with (2.11) of [Reference Gerber and Shiu16].
4.2. Optimal barrier strategies
By (4.3), to identify the optimal barrier strategy
 $\pi_*$
that maximizes
 $V_b$
for any given
 $x\geq 0$
, one needs to discuss the convexity and extreme behavior of the function
 $W'$
. We next present expressions of
 $W'$
(x) for
 $x\geq 0$
. Its proof is deferred to Appendix A.3.
Proposition 4.1. For any
 $0\leq x \lt a$
, we have
 \begin{align}&W'(x)=\big(1-c_1(q)\big)e^{-(\rho_1^-+\rho_2^-)a}(\rho_2^-e^{\rho_2^-x}-\rho_1^-e^{\rho_1^-x}).\end{align}
For any
 $x>a>0$
, we have
 \begin{align}W'(x)&=\rho_2^+\Big(c_1(q)e^{-\rho_2^-a}+\big(1-c_1(q)\big)e^{-\rho_1^-a}\Big)\big(1-c_2(q)\big)e^{\rho_2^+(x-a)}\\&\ \ -\rho_1^+\Big(\big(1-c_1(q)c_2(q)\big)e^{-\rho_2^-a}-c_2(q)\big(1-c_1(q)\big)e^{-\rho_1^-a}\Big)e^{\rho_1^+(x-a)}.\nonumber\end{align}
In particular,
 \begin{align}(1-\beta)W'(a-\!)=(1+\beta) W'(a+\!).\end{align}
Since
 $\lim_{b\uparrow\infty}W'(b)=\infty$
, we have
 $\lim_{b\uparrow\infty}V_b(x)=0$
, and then
 $V_b(x)$
attains its maximum for a finite value of
 $b\geq 0$
. To determine the extreme behavior of
 $W'$
over intervals (0,a) and
 $(a,\infty)$
, we consider the possible solutions of equation
 $W''(x)=0$
in the two intervals. For
 $0\leq x \lt a$
,
 \begin{eqnarray}&&W''(x)=\big(1-c_1(q)\big)e^{-(\rho_1^-+\rho_2^-)a}\Big({\rho_2^-}^2e^{\rho_2^-x}-{\rho_1^-}^2e^{\rho_1^-x}\Big),\end{eqnarray}
and for
 $x>a>0$
,
 \begin{align}W''(x)&={\rho_2^+}^2\big(1-c_2(q)\big)\Big(c_1(q)e^{-\rho_2^-a}+\big(1-c_1(q)\big)e^{-\rho_1^-a}\Big)e^{\rho_2^+(x-a)}\\&\ \ -{\rho_1^+}^2 \Big(\big(1-c_1(q)c_2(q)\big)e^{-\rho_2^-a}-c_2(q)\big(1-c_1(q)\big)e^{-\rho_1^-a}\Big)e^{\rho_1^+(x-a)}.\nonumber\end{align}
Proposition 4.2. Equation
 $W''(x)=0, x\in\mathbb{R}$
, has a unique solution
 $b_-$
for W′′ given by (4.8), and a unique solution
 $b_+$
if
 $K(\beta)>0$
for W′′ given by (4.9), where
 \begin{align} b_- & \,:\!=\,\frac{2}{\rho_2^{-}-\rho_1^-}\ln\frac{-\rho_1^-}{\rho_2^-},\\[-12pt] \nonumber \end{align}
 \begin{align} b_+ & \,:\!=\,a+\frac{1}{\rho_2^+-\rho_1^+}\ln K(\beta), \\[-12pt] \nonumber \end{align}
 \begin{align} K(\beta)& \,:\!=\,\frac{{\rho_1^+}^2\big((1-c_1(q)c_2(q))e^{-\rho_2^-a}-c_2(q)(1-c_1(q))e^{-\rho_1^-a}\big)}{{\rho_2^+}^2(1-c_2(q))(c_1(q)e^{-\rho_2^-a}+(1-c_1(q))e^{-\rho_1^-a})} . \\[9pt] \nonumber \end{align}
Its proof is deferred to Appendix A.4. Note that
 $b_-$
and
 $b_+$
do not depend on the initial surplus
 $x\geq0$
. In addition, we have the following proposition. Its proof is deferred to Appendix A.5.
Proposition 4.3. We have:
-
(i)
$b_-\leq0$
if and only if
$\mu_-\leq 0$
; -
(ii)
$b_+>a$
if and only if
$K(\beta)>1$
.


We are interested in those solutions such that
 $b_-\in (0, a)$
and
 $b_+\in (a, \infty)$
. The following Lemma summarizes the monotone and convex behaviors of
 $W'$
. Its proof is deferred to Appendix A.6.
Lemma 4.2. (Monotonicity and convexity for W and
 $W'$
.) For any
 $\beta\in(\!-1,1)$
, the function W is a non-negative continuous increasing function on
 $\mathbb{R}_+$
that is further twice continuously differentiable on
 $\mathbb{R}_+\backslash\{a\}$
. Its derivative
 $W'$
satisfies
 $W'(x)>0$
for
 $x\in \mathbb{R}_+\backslash\{a\}$
, and its convexity and monotonicity is summarized below.
-
(I) For
$0\leq x \lt a$
, we have:-
(i)
$W'(x)$
is strictly increasing if and only if
$b_-\leq0$
; -
(ii)
$W'(x)$
is non-monotone convex if and only if
$0 \lt b_- \lt a$
; -
(iii)
$W'(x)$
is strictly decreasing if and only if
$a\leq b_-$
.
-
-
(II) For
$x>a>0$
, we have:-
(i)
$W'(x)$
is strictly increasing if
$K(\beta)\leq1 $
; -
(ii)
$W'(x)$
is non-monotone convex if
$K(\beta)>1$
.
-


In conclusion, the restriction of
 $W'$
to (0, a) has a unique local minimum at
 $b_-$
if and only if
 $\mu_-> 0$
and
 $b_- \lt a$
, and the restriction of
 $W'$
to
 $(a,\infty)$
has a unique local minimum at
 $b_+$
if and only if
 $K(\beta)>1$
.
Combining Lemmas 4.1 and 4.2, we obtain the following results on continuity and differentiability of function
 $V_b$
.
Remark 4.3. For
 $b \lt a$
we have
 $V_b\in C(\mathbb{R_+})\cap C^2(\mathbb{R_+})$
. For
 $b>a$
we have
 $V_b\in C(\mathbb{R_+})\cap C^2(\mathbb{R_+}\backslash \{a\})$
. Further,
 $\mathcal{P}_{\pi_b}=\emptyset$
for both
 $b \lt a$
and
 $b>a$
.
Lemma 4.2 suggests that
 $W'$
(x) may have its minimum at
 \begin{align}&\mathcal M\,:\!=\,\operatorname*{arg\,min}_{x\in\mathbb R_+\setminus\{a\}} W'(x)\in\{0+, b_-, a-, a+, b_+\}.\end{align}
We thus propose five corresponding barrier strategies, and apply Lemma 3.1 to identify conditions for each of the above barrier strategies to be optimal. We next introduce a proposition concerning
 $W'$
as function of
 $\beta$
, and write
 $W_{\beta}'$
for
 $W'$
to stress its dependence on
 $\beta$
. Its proof can be found in Appendix A.7.
Proposition 4.4. We have
 $W_{0}'(a-\!)=W_{0}'(a+\!)$
and for
 $\beta\neq 0$
,
 $W_{\beta}'(a-\!) \lt W_{\beta}'(a+\!)$
if and only if
 $\beta\in(\!-1, 0)$
.
We now present the main results of this section.
Theorem 4.1. (Optimality of 0-barrier.) If all of the following three conditions hold
(i)
 $\mu_-\leq0$
, (ii)
 $\mu_+\leq q a$
, (iii)
 $\beta\in(\!-1, 0]$
,
then the function
 $V_{0}$
satisfies the HJB inequalities (3.3)–(3.6), and
 $V_*=V_{0}$
and
 $\pi_*=\pi_{0}$
.
Proof. By (4.3) we have
 $V_{0}(x)=x$
, and then
 $V_{0}'(x)=1$
and
 $V_{0}''(x)=0$
for
 $x\in\mathbb{R}_+$
. We next verify the HJB inequalities (3.3)–(3.6). For
 $0 \leq x \lt a$
, by condition (i) we obtain that
 $$\frac{1}{2}V_{0}''(x)+\mu_-V_{0}'(x)-q V_{0}(x)=\mu_{-} -q x\leq \mu_-\leq 0.$$
For
 $x>a$
, by condition (ii) we get
 $$\frac{1}{2}V_{0}''(x)+\mu_+V_{0}'(x)-q V_{0}(x)=\mu_{+}-q x \lt \mu_+-q a\leq0.$$
Combining the above we have (3.3) holds. Since
 $V_{0}'(x)=1$
, we have
 $1-V_{0}'(x)=0$
for
 $x\geq 0$
, and then (3.4) holds. In addition, by condition (iii) we have
 $$(1+\beta)V_{0}'(a+\!)-(1-\beta)V_{0}'(a-\!)=2\beta\leq0.$$
Thus, (3.5) holds. Since
 $\mathcal{P}_{\pi_0}=\emptyset$
, we have (3.6) holds. Therefore,
 $V_0$
satisfies the HJB inequalities (3.3)–(3.6) under conditions (i)–(iii).
Remark 4.4. (Necessary condition for optimal 0-barrier.) The optimality of
 $V_{0}$
implies that
 $W'$
attains its minimum at 0. By Lemma 4.2 (I) we have that the necessary condition for this is
 $b_-\leq0$
under which
 $W'$
(x) is strictly increasing for
 $x\in[0,a)$
, and then by Proposition 4.3(i) we get
 $\mu_-\leq0$
.
Theorem 4.2. (Optimality of
 $b_-$
-barrier.) If all of the following three conditions hold:
-
(i)
$b_-\in(0, a)$
; -
(ii)
$\big(\mu_+-q(a-b_-)\big)W'(b_-)\leq qW(b_-)$
; -
(iii)
$\beta\in(\!-1, 0]$
;


then the function
 $V_{b_-}$
satisfies the HJB inequalities (3.3)–(3.6), and
 $V_*=V_{b_-}$
and
 $\pi_*=\pi_{b_-}$
.
Proof. We now show that
 $V_{b_-}$
satisfies the HJB inequality (3.3). For
 $0 \leq x \leq b_-$
,
 \begin{eqnarray*}&&W(x)=\big(1-c_1(q)\big)e^{-(\rho_1^-+\rho_2^-)a}(e^{\rho_2^-x}-e^{\rho_1^-x}),\end{eqnarray*}
and then, by (2.4), (4.5), and (4.8) we have
 \begin{eqnarray*}&&\frac{1}{2}V_{b_-}''(x)+\mu_-V_{b_-}'(x)-qV_{b_-}(x)\\&&=\frac{\big(1-c_1(q)\big)e^{-(\rho_1^-+\rho_2^-)a}}{W'(b_-)}\left(\left(\frac{1}{2}{\rho_2^-}^2+\mu_-\rho_2^{-}-q\right)e^{\rho_2^-x}-\left(\frac{1}{2}{\rho_1^-}^2+\mu_-{\rho_1^-}-q\right)e^{\rho_1^-x}\right)=0.\nonumber\end{eqnarray*}
In particular,
 $V_{b_-}'(b_-)=1$
. By condition (i) and the definition of
 $b_-$
, we have
 $W''(b_-)=0$
and then
 $V_{b_-}''(b_-)=0$
. Thus, we have
 \begin{align}&V_{b_-}(b_-)=\frac{\mu_-}{q}.\end{align}
For
 $b_- \lt x \lt a$
, combining the fact that
 $V_{b_-}'(x)=1$
,
 $V_{b_-}''(x)=0$
and
 $V_{b_-}(x)>V_{b_-}(b_-)$
, we get
 $$\frac{1}{2}V_{b_-}''(x)+\mu_-V_{b_-}'(x)-q V_{b_-}(x)=\mu_{-}-q V_{b_-}(x)\leq \mu_{-}-q V_{b_-}(b_-)=0.$$
For
 $x \gt a$
, by (4.3) we get
 $V_{b_-}'(x)=1$
and
 $V_{b_-}''(x)=0$
, and since
 $V_{b_-}(x)>V_{b_-}(a)$
, by condition (ii) we have
 \begin{align*}\frac{1}{2} V_{b_-}''(x)+\mu_+V_{b_-}'(x)-q V_{b_-}(x)&=\mu_+-q V_{b_-}(x)<\mu_+-q V_{b_-}(a)\leq0.\end{align*}
So, (3.3) holds. To prove (3.4), for
 $0 \leq x \leq b_-$
, by condition (i), from Lemma 4.2(I) it follows that
 $W'$
(x) is non-monotone convex for
 $x\in[0, a)$
and
 $\inf_{x\in[0,a)} W'(x)=W'(b_-)$
, then,
 $$1-V_{b_-}'(x)=1-\frac{W'(x)}{W'(b_-)}\leq 1-\frac{W'(b_-)}{W'(b_-)}=0.$$
For
 $x\in(b_-, a)\cup(a, \infty)$
, from
 $V_{b_-}'(x)=1$
we can directly obtain
 $1-V_{b_-}'(x)=0$
. Thus, (3.4) holds. In addition, since
 $V_{b_-}'(a+\!)=V_{b_-}'(a-\!)=1$
, by condition (iii) we have
 $$(1+\beta)V_{b_-}'(a+\!)-(1-\beta)V_{b_-}'(a-\!)=2\beta\leq0.$$
Thus, (3.5) holds. Since
 $\mathcal{P}_{\pi_{b_-}}=\emptyset$
, we have (3.6) holds. Therefore,
 $V_{b_-}$
satisfies the HJB inequalities (3.3)–(3.6) under conditions (i)–(iii).
Remark 4.5. (Sufficient condition for optimal
 $b_-$
-barrier.) If
 $0 \lt b_- \lt a$
,
 $\mu_+\leq0$
and
 $\beta\in(\!-1, 0]$
then conditions (i)–(iii) in Theorem 4.2 are satisfied, and
 $V_*=V_{b_-}$
.
Proof. Conditions (i) and (iii) in Theorem 4.2 are satisfied. By Lemma 4.2 we have
 $W(b_-), W'(b_-)>0$
. Since
 $a-b_{-} > 0$
, if
 $\mu_+\leq 0$
then
 $\big(\mu_+-q(a-b_-)\big)W'(b_-) \lt 0 \lt qW(b_-)$
, and condition (ii) in Theorem 4.2 holds. Therefore,
 $V_*=V_{b_-}$
.
Remark 4.6. (Necessary condition for optimal
 $b_-$
-barrier.) The optimality of
 $V_{b_-}$
requires that
 $W'$
attains its minimum at
 $b_-$
. By Lemma 4.2(I) we have, the necessary condition for this is
 $0 \lt b_- \lt a$
under which
 $W'$
(x) is non-monotone convex for
 $x\in[0, a)$
.
Theorem 4.3. (Optimality of
 $V_{a-}$
.) If all of the following three conditions hold,
-
(i)
$b_-\geq a$
, (ii)
$\mu_+W'(a-\!)\leq qW(a)$
, (iii)
$\beta\in(\!-1, 0]$
,


then the function
 $V_{a-}$
satisfies the HJB inequalities (3.3)–(3.6), and
 $V_*=V_{a-}$
.
Proof. We now verify whether
 $V_{a-}$
satisfies the HJB inequality (3.3). For
 $0\leq x \lt a$
, using a similar method to the proof in Theorem 4.2 for
 $0\leq x \leq b_-$
, we can obtain
 \begin{eqnarray*}&&\frac{1}{2}V_{a-}''(x)+\mu_-V_{a-}'(x)-qV_{a-}(x)=0.\end{eqnarray*}
Clearly
 $V_{a-}'(a-\!)=1$
. For
 $x>a$
, from (4.3) it follows that
 $V_{a-}'(x)=1$
,
 $V_{a-}''(x)=0$
and
 $V_{a-}(x)>V_{a-}(a)$
, and then by condition (ii) we have
 $$\frac{1}{2}V_{a-}''(x)+\mu_+V_{a-}'(x)-q V_{a-}(x)=\mu_+-q V_{a-}(x)\leq \mu_+-q V_{a-}(a)=\mu_+-q \frac{W(a)}{W'(a-\!)}\leq 0.$$
Thus, (3.3) holds. Next, we proceed to prove (3.4). For
 $0\leq x \lt a$
, by condition (i), from Lemma 4.2(I) it follows that
 $W'$
(x) is strictly decreasing for
 $x\in[0, a)$
and
 $\inf_{x\in[0,a)} W'(x)=W'(a-\!)$
, and then
 $$1-V_{a-}'(x)=1-\frac{W'(x)}{W'(a-\!)}\leq 1-\frac{W'(a-\!)}{W'(a-\!)}=0.$$
For
 $x>a$
, from
 $V_{a-}'(x)=1$
, we can directly obtain
 $1-V_{a-}'(x)=0$
. Thus, (3.4) holds. Moreover, since
 $V_{a-}'(a-\!)=V_{a-}'(a+\!)=1$
, by condition (iii) we get
 $$(1+\beta)V_{a-}'(a+\!)-(1-\beta)V_{a-}'(a-\!)=(1+\beta)-(1-\beta)=2\beta\leq0.$$
Then, (3.5) holds. Since
 $\mathcal{P}_{\pi_{a-}}=\emptyset$
, we have (3.6) holds. Therefore, the HJB inequalities (3.3)–(3.6) hold for
 $V_{a-}$
under conditions (i)–(iii).
Remark 4.7. Although
 $V_*=V_{a-}$
in Theorem 4.3, we can not find the corresponding optimal strategy
 $\pi_*$
. Instead, the collection of barrier strategies
 $(\pi_{a-1/n})_n$
is ‘asymptotically optimal’ in the sense that
 $V_{a-}=\lim_{n\to\infty}V(a-1/n)$
.
Remark 4.8. (Sufficient condition for optimality of
 $V_{a-}$
.) If
 $b_-\geq a$
,
 $\mu_+\leq0$
and
 $\beta\in(\!-1, 0]$
then conditions (i)–(iii) in Theorem 4.3 are satisfied, and
 $V_*=V_{a-}$
.
Remark 4.9. (Necessary condition for optimality of
 $V_{a-}$
.) The optimality of
 $V_{a-}$
indicate that
 $W'(a-\!)=\inf_{x\in[0, a)}W'(x)$
. By Lemma 4.2(I) we have that the necessary condition for this is
 $a \leq b_-$
under which
 $W'$
(x) is strictly decreasing for
 $x\in[0,a)$
.
Theorem 4.4. (Optimality of
 $V_{a+}$
.) If both of the following two conditions hold,
-
(i)
$\inf_{x\in[0,a)} W'(x)\geq W'(a+\!)$
, (ii)
$\mu_+W'(a+\!)\leq qW(a)$
,


then the function
 $V_{a+}(x)$
satisfies the HJB inequalities (3.3)–(3.6), and
 $V_*=V_{a+}$
.
Proof. We now consider whether
 $V_{a+}$
satisfies the HJB inequality (3.3). For
 $0\leq x \lt a$
, following the proof used in Theorem 4.2 for
 $0\leq x \leq b_-$
, we have
 $$\frac{1}{2}V_{a+}''(x)+\mu_-V_{a+}'(x)-qV_{a+}(x)=0.$$
For
 $x>a$
, from (4.3) it follows that
 $V_{a+}'(x)=1$
,
 $V_{a+}''(x)=0$
and
 $V_{a+}(x)>V_{a+}(a)$
. Particularly
 $V_{a+}'(a+\!)=1$
and
 $V_{a+}''(a+\!)=0$
. By condition (ii) we have
 $$\frac{1}{2}V_{a+}''(x)+\mu_+V_{a+}'(x)-q V_{a+}(x)=\mu_+-q V_{a+}(x)\leq \mu_+-q V_{a+}(a+\!)=\mu_+-q \frac{W(a)}{W'(a+\!)}\leq0.$$
So (3.3) holds. We next show that (3.4) holds. For
 $0\leq x \lt a$
, condition (i) implies that
 $W'(x)\geq W'(a+\!)$
, and then,
 $$1-V_{a+}'(x)=1-\frac{W'(x)}{W'(a+\!)}\leq 1-\frac{W'(a+\!)}{W'(a+\!)}=0.$$
For
 $x>a$
, since
 $V_{a+}'(x)=1$
, we have
 $1-V_{a+}'(x)=0$
. Thus, (3.4) holds. In addition, by (4.7) we have
 $(1+\beta)V_{a+}'(a+\!)-(1-\beta)V_{a+}'(a-\!)=(1+\beta)-(1+\beta)=0.$
Thus, (3.5) holds. Since
 $\mathcal{P}_{\pi_{a+}}=\emptyset$
, we have (3.6) holds. Therefore, the HJB inequalities (3.3)–(3.6) hold for
 $V_{a+}$
under conditions (i)–(ii).
Remark 4.10. (Sufficient condition for optimality of
 $V_{a+}$
.) If
 $a\leq b_-$
,
 $\mu_+\leq0$
, and
 $\beta\in[0, 1)$
then conditions (i)–(ii) in Theorem 4.4 are satisfied, and
 $V_*=V_{a+}$
.
Proof. When
 $a\leq b_-$
, by Lemma 4.2(I) we have,
 $W'$
(x) is strictly decreasing for
 $x\in [0, a)$
, and then
 $W'(a-\!)=\inf_{x\in[0,a)}W'(x)$
. By Proposition 4.4 we get
 $W'(a+\!)\leq W'(a-\!)$
for
 $\beta\in[0, 1)$
. Thus,
 $W'(a+\!)\leq\inf_{x\in[0,a)}W'(x)$
, i.e. condition (i) in Theorem 4.4 holds. By Lemma 4.2 we have
 $W(a), W'(a+\!)>0$
. If
 $\mu_+\leq 0$
then
 $\mu_+W'(a+\!)\leq0 \lt qW(a)$
, and condition (ii) in Theorem 4.4 holds. Therefore,
 $V_*=V_{a+}$
.
Remark 4.11. (Necessary condition for optimality of
 $V_{a+}$
.) The optimality of
 $V_{a+}$
implies
 $W'(a+\!)\leq \inf_{x\in[0, a)}W'(x)$
, and then
 $W'(a+\!)\leq W'(a-\!)$
. By Proposition 4.4 we have, the necessary condition for this is
 $\beta\in[0, 1)$
.
Theorem 4.5. (Optimality of
 $b_+$
-barrier.) If both of the following two conditions hold,
-
(i)
$b_+>a$
, (ii)
$\inf_{x\in\mathbb{R_+}\backslash\{a\}} W'(x)=W'(b_+)$
,


then the function
 $V_{b_+}$
satisfies the HJB inequalities (3.3)–(3.6) with
 $V_*=V_{b_+}$
and
 $\pi_*=\pi_{b_+}$
.
Proof. We now show that
 $V_{b_+}$
satisfies the HJB inequality (3.3). For
 $0\leq x \lt a$
, similar to the proof in Theorem 4.2 for
 $0\leq x \leq b_-$
, we can obtain
 \begin{eqnarray*}&&\frac{1}{2}V_{b_+}''(x)+\mu_-V_{b_+}'(x)-qV_{b_+}(x)=0.\end{eqnarray*}
For
 $a \lt x \leq b_+$
,
 \begin{align*}W(x)&=\big(c_1(q) e^{-\rho_2^-a}+(1-c_1(q)) e^{-\rho_1^-a}\big)(1-c_2(q))e^{\rho_2^+(x-a)}\\&\ \ \ -\big((1-c_1(q)c_2(q))e^{-\rho_2^-a}-c_2(q) (1-c_1(q)) e^{-\rho_1^-a}\big)e^{\rho_1^+(x-a)}.\end{align*}
By (2.5), (4.6), and (4.9) we have
 \begin{eqnarray*}&&\frac{1}{2}V_{b_+}''(x)+\mu_+V_{b_+}'(x)-qV_{b_+}(x)=0.\end{eqnarray*}
By condition (i) and the definition of
 $b_+$
, we get
 $W''(b_+)=0$
, and then
 $V_{b_+}''(b_+)=0$
. From
 $V_{b_+}'(b_+)=1$
it follows that
 $V_{b_+}(b_+)=\frac{\mu_+}{q}$
. For
 $x>b_+$
, based on
 $V_{b_+}'(x)=1$
and
 $V_{b_+}''(x)=0$
, using the fact that
 $V_{b_+}(x)>V_{b_+}(b_+)$
, we get
 \begin{eqnarray*}\frac{1}{2}V_{b_+}''(x)+\mu_+V_{b_+}'(x)-q V_{b_+}(x)=\mu_+-q V_{b_+}(x) \lt \mu_+-q V_{b_+}(b_+)=0.\end{eqnarray*}
So, (3.3) holds. Besides that, by condition (ii), for
 $x\in[0,a)\cup(a,b_+]$
, we have
 $$1-V_{b_+}'(x)=1-\frac{W'(x)}{W'(b_+)}\leq 1-\frac{W'(b_+)}{W'(b_+)}=0.$$
For
 $x>b_+$
, since
 $V_{b_+}'(x)=1$
, we have
 $1-V_{b_+}'(x)=0$
. Thus, (3.4) holds. By (4.7) we get
 $$(1+\beta) V_{b_+}'(a+\!)-(1-\beta) V_{b_+}'(a-\!)={(W'(b_+))}^{-1}\big((1+\beta) W'(a+\!)-(1-\beta)W'(a-\!)\big)=0.$$
Thus, (3.5) holds. Since
 $\mathcal{P}_{\pi_{b_+}}=\emptyset$
, we have (3.6) holds. Therefore, the HJB inequalities (3.3)–(3.6) hold for
 $V_{b_+}$
under conditions (i)–(ii).
5. Optimal band strategies
In this section we consider a class of band strategies, denoted by
 $\pi_{b_1, a_1, b_2}$
for
 $0 \leq b_1 \leq a_1 \leq b_2$
, that involve two dividend barriers at levels
 $b_1$
and
 $b_2$
, respectively. Such a dividend strategy can be described as follows. If the surplus level is above
 $b_2$
, a lump-sum payment is made to bring the surplus level to
 $b_2$
. If the surplus takes values in
 $(a_1, b_2]$
, a dividend barrier at level
 $b_2$
is imposed until the surplus first reaches level
 $a_1$
. If the surplus takes values in
 $(b_1, a_1]$
, a lump-sum payment is made to bring the surplus to
 $b_1$
. If the surplus takes values in
 $(0, b_1]$
, a dividend barrier at level
 $b_1$
is imposed until ruin occurs. We refer to [Reference Azcue and Muler8] for introductions on band strategies. Write
 $V_{b_1, a_1, b_2}(x)$
for the expected total amount of discounted dividends before ruin with band strategy
 $\pi_{b_1, a_1, b_2}$
and
 $X_0=x$
, and replace
 $\mathcal{P}_{\pi}$
as defined in Definition 3.1, with
 $\mathcal{P}_{\pi_{b_1, a_1, b_2}}$
.
5.1. Expected discounted dividend function for band strategies
Lemma 5.1. For
 $x\in\mathbb{R}_+$
,
 $0\leq b_1 \lt a \lt b_2$
and
 $0 \leq b_1 \leq a_1\leq b_2$
, we have
 \begin{eqnarray*} &V_{b_1,a_1, b_2}(x)=\left \{ \begin{array}{l@{\qquad}l} \frac{W(x)}{W'(b_1)} & \mathrm{for}\ x\in[0, b_1), \\[8pt]x-b_1+\frac{W(b_1)}{W'(b_1)} & \mathrm{for}\ x\in[b_1, a_1), \\[8pt]\frac{w(x, a_1)}{w_{b_2}(b_2, a_1)}+\big(a_1-b_1+\frac{W(b_1)}{W'(b_1)}\big) \frac{w_{b_2}(b_2, x)}{w_{b_2}(b_2, a_1)} & \mathrm{for}\ x\in[a_1, b_2), \\[8pt]x-b_2+\frac{w(b_2, a_1)}{w_{b_2}(b_2, a_1)}+\big(a_1-b_1+\frac{W(b_1)}{W'(b_1)}\big) \frac{w_{b_2}(b_2, b_2)}{w_{b_2}(b_2, a_1)} & \mathrm{for}\ x\in[b_2, \infty),\end{array} \right.\end{eqnarray*}
where w(x,y),
 $w_x(x,y)$
, and W(x) are defined by (2.11), (4.2), and (4.4), respectively.
Its proof is deferred to Appendix A.8. For
 $x\in[0,a_1 \wedge a)$
, the monotonicity of
 $W'$
(x) has been described in Lemma 4.2(I), and then, the monotonicity of
 $V_{b_1,a_1, b_2}'(x)$
for
 $x\in[0,a_1)$
is determined. We first present the following proposition, which will be used in the subsequent analysis of the monotonicity of
 $V_{b_1,a_1, b_2}'(x)$
for
 $x\in(a_1, \infty)$
. Its proof is deferred to Appendix A.9.
Proposition 5.1. For any
 $0 \lt a \lt a_1\leq b_2$
, we have
 \begin{align}w_{b_2}(b_2, a_1)&=\big(1-c_{2}(q)\big)e^{(\rho_2^++\rho_1^+)(a_1-a)}\left(\rho_2^+ e^{\rho_2^+(b_2-a_1)}-\rho_1^+ e^{\rho_1^+(b_2-a_1)}\right).\end{align}
For any
 $0\leq a_1\leq a \lt b_2$
, we have
 \begin{align}w_{b_2}(b_2, a_1)&=\rho_2^+ \big(1-c_{2}(q)\big)\Big(c_{1}(q)e^{\rho_2^-(a_1-a)}+\big(1-c_{1}(q)\big)e^{\rho_1^-(a_1-a)}\Big)e^{\rho_2^+(b_2-a)}\\&\ \ -\rho_1^+\Big(\big(1-c_{1}(q)c_{2}(q)\big)e^{\rho_2^-(a_1-a)}-c_{2}(q)\big(1-c_{1}(q)\big)e^{\rho_1^-(a_1-a)}\Big) e^{\rho_1^+(b_2-a)}.\nonumber\end{align}
Further,
 $w_{b_2}(b_2, a_1)>0$
for any
 $0 \lt a \lt b_2$
and
 $0\leq a_1\leq b_2$
.
5.2. Optimal band strategies
We now seek to identify the optimal band strategy. For
 $x\in[0, b_1)$
, by Lemma 5.1 we have
 \begin{align*} V_{b_1,a_1, b_2}''(x)&=\frac{W''(x)}{W'(b_1)}.\end{align*}
For
 $x\in[a_1\wedge a, a)$
, by Lemma 5.1 we have
 \begin{align}V_{b_1,a_1, b_2}'(x) &=\frac{\tilde{K}_{2}(b_1, a_1, b_2){\rho_2^-}e^{\rho_2^-(x-a)}-\tilde{K}_{1}(b_1, a_1, b_2){\rho_1^-}e^{\rho_1^-(x-a)}}{w_{b_2}(b_2, a_1)},\\[-12pt] \nonumber \end{align}
 \begin{align}V_{b_1, a_1, b_2}''(x)&=\frac{\tilde{K}_{2}(b_1, a_1, b_2){\rho_2^-}^2e^{\rho_2^-(x-a)}-\tilde{K}_{1}(b_1, a_1, b_2){\rho_1^-}^2e^{\rho_1^-(x-a)}}{w_{b_2}(b_2, a_1)}, \\[9pt] \nonumber \end{align}
where
 $g_{1,q}(x)$
and
 $g_{2,q}(x)$
are given by (2.2) and (2.3), respectively, and
 \begin{align}& \tilde{K}_{1}(b_1, a_1, b_2)\,:\!=\,(1-c_{1}(q))\big(g_{2,q}(a_1)-g_{2,q}'(b_2)V_{b_1,a_1, b_2}(a_1)\big),\\[-12pt] \nonumber \end{align}
 \begin{align} & \tilde{K}_{2}(b_1, a_1, b_2)\,:\!=\,g_{1,q}(a_1)-g_{1,q}'(b_2)V_{b_1,a_1, b_2}(a_1)-c_{1}(q)\big(g_{2,q}(a_1)-g_{2,q}'(b_2)V_{b_1,a_1, b_2}(a_1)\big).\\[9pt] \nonumber \end{align}
For
 $x\in(a_1 \vee a, b_2)$
, by Lemma 5.1 we have
 \begin{align}V_{b_1,a_1, b_2}''(x) &=\frac{\hat{K}_{2}(b_1, a_1, b_2){\rho_2^+}^2e^{\rho_2^+(x-a)}-\hat{K}_{1}(b_1, a_1, b_2){\rho_1^+}^2e^{\rho_1^+(x-a)}}{w_{b_2}(b_2, a_1)},\end{align}
where
 \begin{align}&\hat{K}_{1}(b_1, a_1, b_2)\,:\!=\,g_{2,q}(a_1)-g_{2,q}'(b_2)V_{b_1,a_1, b_2}(a_1)-c_{2}(q)\big(g_{1,q}(a_1)-g_{1,q}'(b_2)V_{b_1,a_1, b_2}(a_1)\big),\nonumber\\&\hat{K}_{2}(b_1, a_1, b_2)\,:\!=\,\big(1-c_{2}(q)\big)\big(g_{1,q}(a_1)-g_{1,q}'(b_2)V_{b_1,a_1, b_2}(a_1)\big).\end{align}
The proof for the next proposition is deferred to Appendix A.10.
Proposition 5.2. For any
 $0\leq b_1 \lt a \lt b_2$
and
 $0\leq b_1\leq a_1\leq b_2$
, we have
 \[V_{b_1,a_1, b_2}'(a_1-)=1 \quad \mathrm{and} \quad V_{b_1,a_1, b_2}'(b_2)=1.\]
Note that
 $V_{b_1,a_1, b_2}'(a_1-\!)=1$
by Proposition 5.2. Then the HJB inequality (3.6) requires that
 $V_{b_1,a_1, b_2}'(a_1+)\leq1$
, and (3.4) further requires that
 $V_{b_1,a_1, b_2}'(a_1+)=1$
, leading to
 $V_{b_1,a_1, b_2}'(a_1)=1$
. On the other hand, since
 $V_{b_1,a_1, b_2}'(x)=1$
for
 $x\in[b_2, \infty)$
by definition, (3.4) requires that
 $V_{b_1,a_1, b_2}'(x)\geq1$
for
 $x\in(a, b_2)$
, which implies that
 $b_2$
is a local minimum of
 $V_{b_1,a_1, b_2}'(x)$
for
 $x\in(a, \infty)$
, leading to
 $V_{b_1,a_1, b_2}''(b_2)=0$
. Therefore, to obtain the optimal band strategy we first consider
 $a_1$
and
 $b_2$
satisfying the following equations and then identify additional conditions for all the HJB inequalities to hold:
 \begin{align}& V_{b_1,a_1, b_2}'(a_1)=1, \\[-12pt] \nonumber \end{align}
 \begin{align} & V_{b_1,a_1, b_2}''(b_2)=0. \\[9pt] \nonumber \end{align}
Also note that if
 $b_2=a+$
then
 $V_{b_1,a_1, b_2}(x)$
is not differentiable at
 $x=a$
and (5.10) is not relevant.
To analyze the monotonicity of
 $V_{b_1,a_1, b_2}'(x)$
for
 $x\in(a_1, \infty)$
, we present three lemmas. Their proofs are deferred to Appendices A.11, A.12, and A.13, respectively. Recall that, for W
′′(x) given by (4.8),
 $W''(x)=0$
has a unique solution
 $b_-\in \mathbb{R}$
given in (4.10). By Lemma 4.2(I), for
 $0\leq x \lt a_1\leq a$
, if
 $b_-\leq0$
then
 $W'$
(x) has a unique minimum at 0, whereas if
 $0 \lt b_- \lt a_1$
then
 $W'$
(x) has a unique minimum at
 $b_-$
.
Lemma 5.2. For fixed
 $b_1$
and
 $b_2$
satisfying
 $0\leq b_1 \lt a \lt b_2$
, if there exists
 $a_1\in[b_1, a)$
such that
 $V_{b_1,a_1, b_2}'(a_1)=1$
then we have
 \begin{align}\tilde{K}_{1}(b_1, a_1, b_2)&=\frac{1-\rho_2^-V_{b_1, a_1, b_2}(a_1)}{\rho_2^- -\rho_1^-}w_{b_2}(b_2, a_1) e^{-\rho_1^-(a_1-a)}, \\[-12pt] \nonumber\end{align}
 \begin{align} \tilde{K}_{2}(b_1, a_1, b_2)&=\frac{1-\rho_1^-V_{b_1, a_1, b_2}(a_1)}{\rho_2^- -\rho_1^-}w_{b_2}(b_2, a_1) e^{-\rho_2^-(a_1-a)}, \\[-12pt] \nonumber\end{align}
 \begin{align} V_{b_1, a_1, b_2}''(a_1)&=2\big(-\mu_-+qV_{b_1, a_1, b_2}(a_1)\big),\\[9pt] \nonumber\end{align}
where
 $w_{b_2}(b_2, a_1)$
is defined in (5.2).
Lemma 5.3. For fixed
 $b_1$
and
 $b_2$
satisfying
 $0\leq b_1 \lt a \lt b_2$
, where
 $b_1=b_-$
for
 $b_-\in(0,a)$
and
 $b_1=0$
for
 $b_-\leq 0$
, if there exists
 $a_1\in[b_1, a)$
such that
 $V_{b_1,a_1, b_2}'(a_1)=1$
then
 $V_{b_1, a_1, b_2}'(x)$
is strictly increasing for
 $x\in(a_1, a)$
.
Lemma 5.4. For fixed
 $b_1$
and
 $a_1$
with
 $0\leq b_1 \lt a$
and
 $0\leq b_1 \leq a_1$
, if there exists
 $b_2>(a_1 \vee a)$
such that
 $V_{b_1,a_1, b_2}''(b_2)=0$
then
 $V_{b_1,a_1, b_2}'(x)$
is strictly decreasing for
 $x\in[a_1, b_{2})\cap (a, b_2)$
.
The remark below compares the expected present value of dividends for the barrier and band strategies, its proof is deferred to Appendix A.14. Let
 $\mathcal M$
be as in (4.13).
Remark 5.1. Let
 $b_1=b_-$
for
 $0 \lt b_- \lt a$
,
 $b_1=a-$
for
 $a\leq b_-$
and
 $b_1=0$
for
 $b_-\leq 0$
. For
 $0\le b_1 \lt a \lt b_2$
, the following results hold.
-
(i) If
$\mathcal M\in \{a+, b_+\}$
then for every
$x\in[0,b_1)$
one has
$V_{b_1,a_1,b_2}(x)\leq \max\{V_{a+}(x), V_{b_+}(x)\}$
, hence no
$(b_1,a_1,b_2)$
-band is optimal. Optimality of
$(b_1, a_1, b_2)$
-band can occur only if
$\mathcal M\in \{0+, b_-, a-\}$
. -
(ii) If
$\mathcal M\in\{0+, b_-, a-\}$
, and for some
$a_1\in[b_1, a)$
with
$V_{b_1,a_1, b_2}'(a_1)=1$
, then for every
$x\in(a_1, a)$
one has
$V_{b_1,a_1,b_2}(x)\;> V_{b_1}(x)>\max\{V_{a+}(x),V_{b_+}(x)\}$
, hence no barrier is optimal. -
(iii) If
$\mathcal M\in\{0+, b_-, a-\}$
, and for some
$b_2> a_1 \geq a$
with
$V_{b_1,a_1,b_2}''(b_2)=0$
, then for every
$x\in(a_1, b_2)$
one has
$V_{b_1,a_1,b_2}(x) \gt V_{b_1}(x) \gt \max\{V_{a+}(x),V_{b_+}(x)\}$
, hence no barrier is optimal.


5.2.1. The case
$b_1\leq a_1 \lt a$
.

Theorem 5.1. Let
 $b_1=b_-$
for
 $0 \lt b_- \lt a$
and
 $b_1=0$
for
 $b_-\leq 0$
.
-
(I) (Optimality of
$(b_1, a_1, b_2)$
-band.) If there exists
$(a_1, b_2)$
for
$a_1\in [b_1, a)\cap(0,a)$
and
$b_2\in (a,\infty)$
such that
$V_{b_1,a_1, b_2}$
satisfies (5.9)–(5.10), then
$V_*=V_{b_1,a_1, b_2}$
and
$\pi_*=\pi_{b_1,a_1, b_2}$
. -
(II) (Optimality of
$V_{b_1, a_1, a+}$
.) If there exists
$a_1 \in [b_1, a)\cap(0,a)$
such that
$V_{b_1, a_1, a+}$
satisfies (5.9) and
$\mu_+-q V_{b_1, a_1, a+}(a)\leq 0$
, then
$V_*=V_{b_1,a_1, a+}$
.


Proof. By Lemma 5.1 and the definitions of
 $b_-$
,
 $a_1$
and
 $b_2$
, we get
 $V_{b_-,a_1, b_2}\in C(\mathbb{R_+})\cap C^2(\mathbb{R}_+\backslash\{a_1, a\})$
with
 $\mathcal{P}_{\pi_{b_-,a_1, b_2}}=\{a_1\}$
. For
 $x\in[0, a_1)$
, it follows from (4.3) and Lemma 5.1 that
 $V_{b_1}=V_{b_1,a_1, b_2}$
, and the HJB inequalities (3.3)–(3.6) are verified for
 $b_1=0$
and
 $b_1=b_-$
in Theorems 4.1 and 4.2, respectively. Notably,
 $V_{b_-, a_1, b_2}(b_-)=V_{b_-}(b_-)=\mu_-/{q}$
. Here, we focus on the case
 $x\in[a_1, \infty)$
, and consider
 $b_1 = b_-$
as an example, since the proof for
 $b_1 = 0$
follows similarly.
First, we prove case (I) beginning with (3.3). For
 $x\in[a_1, a)\cup (a, b_2)$
, by (2.11)
 \begin{align*}&w(x, a_1)+w_{b_2}(b_2, x)V_{b_-,a_1, b_2}(a_1)\\&=\Big(g_{1,q}(a_1)-g_{1,q}'(b_2)V_{b_-,a_1, b_2}(a_1)\Big)g_{2,q}(x)-\Big(g_{2,q}(a_1)-g_{2,q}'(b_2)V_{b_-,a_1, b_2}(a_1)\Big)g_{1,q}(x),\end{align*}
where
 $g_{i,q}(x), i=1,2$
are given by (2.2) and (2.3), respectively. Then by (2.1) we have
 \begin{eqnarray*}&&\frac{1}{2}V_{b_-,a_1, b_2}''(x)+(\mu_+\mathbf{1}_{\{x \gt a\}}+\mu_-\mathbf{1}_{\{x \lt a\}})V_{b_-,a_1, b_2}'(x)-qV_{b_-,a_1, b_2}(x)=0.\end{eqnarray*}
By the definition of
 $b_2$
we get
 $V_{b_-, a_1, b_2}''(b_2)=0$
, and by Proposition 5.2 we have
 $V_{b_-, a_1, b_2}'(b_2)=1$
. Then
 $V_{b_-, a_1, b_2}(b_2)={\mu_+}/{q}$
. For
 $x\in[b_2, \infty)$
, since
 $V_{b_-, a_1, b_2}'(x)=1$
,
 $V_{b_-, a_1, b_2}''(x)=0$
and
 $V_{b_-, a_1, b_2}(x)\geq V_{b_-, a_1, b_2}(b_2)={\mu_+}/{q}$
, we have
 \begin{eqnarray*}&&\frac{1}{2}V_{b_-, a_1, b_2}''(x)+\mu_+V_{b_-, a_1, b_2}'(x)-q V_{b_-, a_1, b_2}(x)\leq \mu_+-q V_{b_-, a_1, b_2}(b_2)=0.\end{eqnarray*}
Thus, (3.3) holds.
We then prove (3.4). By the definition of
 $a_1$
we get
 $V_{b_-,a_1, b_2}'(a_1)=1$
. For
 $x\in(a_1, a)$
, by Lemma 5.3 we obtain that
 $V_{b_-,a_1, b_2}'(x)$
is strictly increasing in x, and then
 $V_{b_-,a_1, b_2}'(x)> V_{b_-,a_1, b_2}'(a_1)=1$
. For
 $x\in(a, b_2)$
, by Proposition 5.2 and Lemma 5.4 we have
 $V_{b_-, a_1, b_2}'(x)> V_{b_-, a_1, b_2}'(b_2)=1$
. For
 $x\in [b_2, \infty)$
,
 $V_{b_-,a_1, b_2}'(x)=1$
. Therefore,
 $1-V_{b_-,a_1, b_2}'(x)\leq0$
for
 $x\in\mathbb{R}_+\backslash\{a\}$
, i.e. (3.4) holds. We then verify (3.5). Since
 \begin{align*}V_{b_-, a_1, b_2}'(a\pm)={\big(w_{b_2}(b_2, a_1)\big)^{-1}} & \Big(\big(g_{1,q}(a_1)-g_{1,q}'(b_2)V_{b_-, a_1, b_2}(a_1)\big)g_{2,q}'(a\pm)\\& -\big(g_{2,q}(a_1)-g_{2,q}'(b_2)V_{b_-, a_1, b_2}(a_1)\big)g_{1,q}'(a\pm)\Big),\end{align*}
by (2.7) we have
 $(1+\beta) V_{b_-, a_1, b_2}'(a+\!)-(1-\beta) V_{b_-, a_1, b_2}'(a-\!)=0$
, i.e. (3.5) holds. Finally, recalling that
 $V_{b_-, a_1, b_2}'(a_1-)=V_{b_-, a_1, b_2}'(a_1+)=1$
, since
 $\mathcal{P}_{\pi_{b_-, a_1, b_2}}=\{a_1\}$
, we have (3.6).
Now, we prove case (II). The proofs of (3.3) and (3.4) for
 $x\in[a_1, a)$
are omitted as they are similar to case (I). We proceed with the proof for
 $x>a$
. Combining
 $\mu_+-q V_{b_-, a_1, a+}(a)\leq 0$
,
 $V_{b_-, a_1, a+}'(x)=1$
,
 $V_{b_-, a_1, a+}''(x)=0$
, and
 $V_{b_-, a_1, a+}(x)> V_{b_-, a_1, a+}(a)$
, we have
 \begin{align*}&\frac{1}{2}V_{b_-, a_1, a+}''(x)+\mu_+V_{b_-, a_1, a+}'(x)-q V_{b_-, a_1, a+}(x) \lt \mu_+-q V_{b_-, a_1, a+}(a)\leq0.\end{align*}
Thus, (3.3) holds. By Lemma 5.1 we get
 $V_{b_-, a_1, a+}'(x)=1$
and (3.4) holds. To show (3.5), by
 $V_{b_-, a_1, a+}'(a+\!)=1$
and
 $w_{a+, a+}(a+, a+)\,:\!=\,w_{x, y}(x, y)|_{x=y=a+}=0$
we have
 \begin{align*}&(1+\beta) V_{b_-, a_1, a+}'(a+\!)-(1-\beta) V_{b_-, a_1, a+}'(a-\!)=(1+\beta)\\&-(1-\beta)\frac{1+\beta}{1-\beta}\frac{w_{a+}(a+, a_1)+w_{a+, a+}(a+, a+)V_{b_-, a_1, a+}(a_1)}{w_{a+}(a+, a_1)}=(1+\beta)-(1+\beta)=0,\end{align*}
i.e. (3.5) holds. Since
 $\mathcal{P}_{\pi_{b_-, a_1, a+}}=\{a_1\}$
and
 $V_{b_-, a_1, a+}'(a_1)=1$
, we have (3.6) holds.
5.2.2. The case
$b_1 \lt a \leq a_1$
.

Let
 $a\leq a_1$
in Lemma 5.1, we obtain the following lemma, with a detailed proof provided in Appendix A.15.
Lemma 5.5. For
 $0\leq b_1 \lt a\leq a_1 \lt b_2$
, we have
 \begin{align*} V_{b_1, a_1, b_2}(x) =\!\left \{ \begin{array}{l@{\hspace*{12pt}}l} \frac{W(x)}{W'(b_1)} & \mathrm{for}\ x\in[0, b_1), \\[6pt]x-b_1+\frac{W(b_1)}{W'(b_1)} & \mathrm{for}\ x\in[b_1, a_1), \\\frac{W_+(x-a_1)}{W_+'(b_2-a_1)}+\big(a_1-b_1+\frac{W(b_1)}{W'(b_1)}\big)\frac{W_+'(b_2-x)e^{(\rho_2^++\rho_1^+)(x-a_1)}}{W_+'(b_2-a_1)} & \mathrm{for}\ x\in[a_1, b_2), \\[6pt]x-b_2+\frac{W_+(b_2-a_1)}{W_+'(b_2-a_1)}+\big(a_1-b_1+\frac{W(b_1)}{W'(b_1)}\big) \frac{W_+'(0)e^{(\rho_2^++\rho_1^+)(b_2-a_1)}}{W_+'(b_2-a_1)} & \mathrm{for}\ x\in[b_2, \infty), \end{array} \right. \end{align*}
where W(x) is given by (4.4) and
 \begin{align}&W_+(x)\,:\!=\,e^{\rho_2^+x}-e^{\rho_1^+x}.\end{align}
Remark 5.2. Under the condition
 $V_{b_1, a_1, b_2}''(b_2)=0$
for
 $a \lt a_1 \lt b_2$
, it is necessary that
 $V_{b_1, a_1, b_2}'(a_1)=1$
for both (3.4) and (3.6) to hold, which fails to agree with Lemma 5.4. Therefore, the HJB inequalities (3.3)–(3.6) cannot all be satisfied for
 $a \lt a_1 \lt b_2$
, and we only consider the case of
 $a=a_1 \lt b_2$
.
To determine the values of
 $\beta\in(\!-1,1)$
for which the left and right derivatives of
 $V_{b_1,a, b_2}(x)$
at
 $x=a$
satisfy the HJB inequality (3.5), we provide the lemma below. Its proof is deferred to Appendix A.16.
Lemma 5.6. If
 $V_{b_1,a, b_2}''(b_2)=0$
for
 $0\leq b_1 \lt a \lt b_2$
then
 \begin{align*}& S(\beta)\,:\!=\,(1+\beta) V_{b_1, a, b_2}'(a+\!)-(1-\beta), \, \beta\in(\!-1,1),\end{align*}
is strictly increasing. Further, there exists a unique
 $\beta^*\in(\!-1,0)$
such that
 $S(\beta^*)=0$
, and
 $S(\beta)\leq 0$
if and only if
 $\beta\in(\!-1, \beta^*]$
where
 \begin{align}\beta^*:&=\frac{1-V_{b_1, a, b_{2}}'(a+\!)}{1+V_{b_1, a, b_{2}}'(a+\!)}.\end{align}
Theorem 5.2. (Optimality of
 $(b_1, a, b_2)$
-band.) Let
 $b_1=b_-$
for
 $0 \lt b_- \lt a$
,
 $b_1=a-$
for
 $a\leq b_-$
and
 $b_1=0$
for
 $b_-\leq 0$
. If there exists
 $b_2\in(a,\infty)$
such that
 $V_{b_1,a, b_2}$
satisfies (5.10) and
 $\beta\in(\!-1, \beta^*]$
, then
 $V_*=V_{b_1, a, b_2}$
.
Proof. By Lemma 5.5 and the definitions of
 $b_1$
and
 $b_2$
, we get
 $V_{b_1,a, b_2}\in C(\mathbb{R_+})\cap C^2(\mathbb{R}_+\backslash\{ a\})$
with
 $\mathcal{P}_{\pi_{b_1,a, b_2}}=\emptyset$
. For
 $x\in[0, a)$
, it follows from (4.3) and Lemma 5.5 that
 $V_{b_1}=V_{b_1,a, b_2}$
, and the HJB inequalities (3.3)–(3.6) are verified for
 $b_1=\{0, b_-, a-\}$
in Theorems 4.1–4.3. We now consider
 $x\in(a, \infty)$
.
For the proof of (3.3), the cases where
 $b_1=b_-$
and
 $b_1=0$
are omitted since they follow similarly to Theorem 5.1, and we consider the case
 $b_1 = a-$
. For
 $x\in(a, b_2)$
, since
 \begin{align*}&W_+(x-a)+\frac{W(a)}{W'(a-\!)}W_+'(b_2-x)e^{(\rho_2^++\rho_1^+)(x-a)}\\&=\left(1-\frac{W(a)}{W'(a-\!)} \rho_1^+ e^{\rho_1^+(b_2-a)}\right) e^{\rho_2^+(x-a)}-\left(1-\frac{W(a)}{W'(a-\!)} \rho_2^+ e^{\rho_2^+(b_2-a)}\right) e^{\rho_1^+(x-a)},\end{align*}
by (2.5) we have
 \begin{eqnarray*}&&\frac{1}{2}V_{a-,a, b_2}''(x)+\mu_+ V_{a-,a, b_2}'(x)-qV_{a-,a, b_2}(x)=0.\end{eqnarray*}
By the definition of
 $b_2$
we get
 $V_{a-, a, b_2}''(b_2)=0$
, and by Proposition 5.2 we have
 $V_{a-, a, b_2}'(b_2)=1$
. Then
 $V_{a-, a, b_2}(b_2)={\mu_+}/{q}$
. For
 $x\in[b_2, \infty)$
, since
 $V_{a-, a, b_2}'(x)=1$
,
 $V_{a-, a, b_2}''(x)=0$
and
 $V_{a-, a, b_2}(x)\geq V_{a-, a, b_2}(b_2)={\mu_+}/{q}$
, we have
 \begin{eqnarray*}&&\frac{1}{2}V_{a-, a, b_2}''(x)+\mu_+V_{a-, a, b_2}'(x)-q V_{a-, a, b_2}(x)\leq \mu_+-q V_{a-, a, b_2}(b_2)=0.\end{eqnarray*}
Thus, (3.3) holds.
We next prove (3.4). For
 $x\in(a, b_2)$
, by Proposition 5.2 and Lemma 5.4 we have
 $V_{b_1, a, b_2}'(x)> V_{b_1, a, b_2}'(b_2)=1$
. For
 $x\in[b_2, \infty)$
,
 $V_{b_1, a, b_2}'(x)=1$
. Thus, (3.4) holds. In addition, since
 $V_{b_1,a,b_2}'(a-\!)=1$
, under the condition
 $\beta\in(\!-1, \beta^*]$
, by Lemma 5.6 we have
 $$(1+\beta)V_{b_1,a,b_2}'(a+\!)-(1-\beta)V_{b_1,a,b_2}'(a-\!)=(1+\beta)V_{b_1,a,b_2}'(a+\!)-(1-\beta)\leq 0,$$
i.e. (3.5) holds. Since
 $\mathcal{P}_{\pi_{b_1, a, b_2}}=\emptyset$
, we have (3.6).
Combining the analysis in the barrier and band Sections 4–5, we obtain the following barrier-band optimality decision rule, with proof given in Appendix A.17. Let
 $b_1=b_-$
for
 $0 \lt b_- \lt a$
,
 $b_1=a-$
for
 $a\leq b_-$
, and
 $b_1=0$
for
 $b_-\leq 0$
, and
 $\mathcal{M}$
be as defined in (4.13). For brevity, write HJB for (3.3)–(3.6).
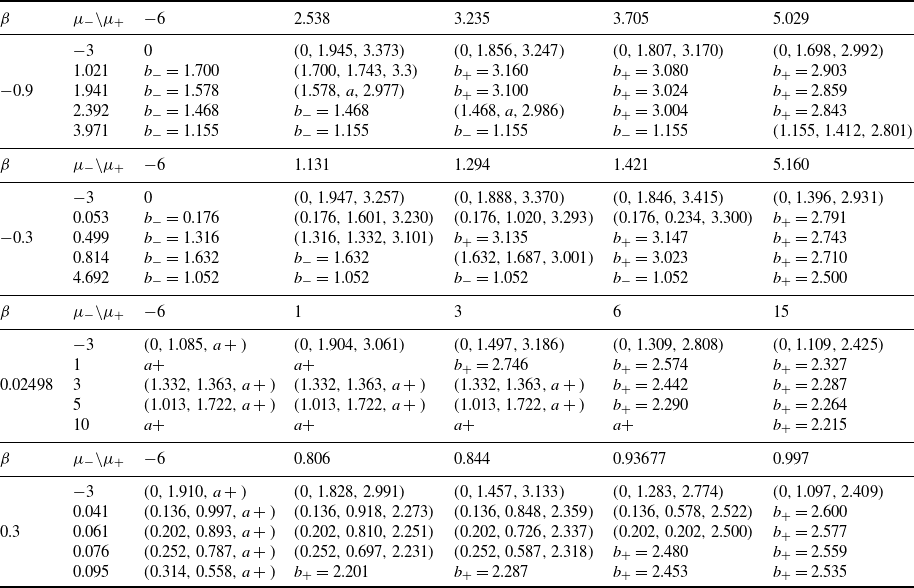
The optimal dividend strategies for
 $q=0.1$
and
 $a=1$
.

Note: Optimal strategies include types 0,
 $b_{\pm}$
,
 $a{\pm}$
,
 $(0,a_1,b_2)$
,
 $(0, a_1,a+)$
,
 $(0, a, b_2)$
,
 $(b_-, a, b_2)$
, and
 $(a-, a, b_2)$
.
The optimal dividend strategies for
 $q=0.3$
and
 $a=2$
.

Note: Optimal strategies include types 0,
 $b_-$
,
 $a+$
,
 $b_+$
,
 $(b_-,a_1,b_2)$
,
 $(b_-,a_1,a+)$
,
 $(0,a_1,b_2)$
,
 $(0, a_1,a+)$
, and
 $(b_-, a, b_2)$
.
Remark 5.3. (Barrier versus band: decision rule.) With
 $\mathcal{M}\in\{a+,\,b_+\}$
, the optimal policy is a barrier strategy:
 $b_+$
if
 $b_+>a$
, and
 $a+$
if
 $b_+\leq a$
. With
 $\mathcal{M}\in\{0+,\,b_-,\,a-\}$
, for
 $0\leq b_1\leq a_1, a\le b_2$
and
 $a_1>0$
, the optimal policy is determined by the following case-wise rules.
(C1) Case
 $a_1\in[b_1,\,a)$
.
-
(i) If
$V'_{b_1,a_1,b_2}(a_1)=1$
then the
$b_1$
-barrier fails to be optimal, and further


-
• If
$b_2>a$
and
$V''_{b_1,a_1,b_2}(b_2)=0$
, the
$(b_1,a_1,b_2)$
-band is optimal. -
• If
$b_2=a$
and
$\mu_+-q\,V_{b_1,a_1,a+}(a)\le 0$
, the
$(b_1,a_1,a+)$
-band is optimal.


-
(ii) If
$V'_{b_1,a_1,b_2}(a_1)\neq1$
then the
$(b_1,a_1,b_2)$
-band fails to satisfy HJB, and further


-
• If
$\beta\in(\!-1,0]$
and
$\mu_+ - q V_{b_1}(a)\leq 0$
, the
$b_1$
-barrier is optimal.


(C2) Case
 $a_1=a$
.
-
(i) If
$b_2>a$
then

-
• If
$V''_{b_1,a,b_2}(b_2)=0$
and
$\beta\in(\!-1,\beta^*]$
, the
$(b_1,a,b_2)$
-band is optimal. -
• If
$V''_{b_1,a,b_2}(b_2)\neq0$
, the
$(b_1,a,b_2)$
-band fails to satisfy HJB, and further


-
• If
$\beta\in(\!-1,0]$
and
$\mu_+ - q V_{b_1}(a)\leq 0$
, the
$b_1$
-barrier is optimal.


-
(ii) If
$b_2=a$
then

-
• If
$\beta\in(\!-1,0]$
and
$\mu_+ - q V_{b_1}(a)\leq 0$
, the
$b_1$
-barrier is optimal.


(C3) Case
 $a_1>a$
. The
 $(b_1,a_1,b_2)$
-band fails to satisfy HJB.
6. Examples
Applying Theorems 4.1–4.5 and 5.1–5.2, we summarize in Tables 1 and 2 the optimal strategies for different choices of (numerical) values for
 $\beta, \mu_-$
, and
 $\mu_+$
, respectively.
From Tables 1 and 2 one can observe that, for
 $\beta\in(\!-1,0)$
, if
 $\mu_+ \lt 0$
then the optimal dividend strategy is the
 $b_1$
-barrier strategy, where
 $b_1=b_-$
for
 $0 \lt b_- \lt a$
,
 $b_1=a-$
for
 $b_-\geq a$
and
 $b_1=0$
for
 $b_-\leq 0$
, as mentioned in Theorem 4.1 and Remarks 4.5 and 4.8. This suggests that a constrained drift associated to the dynamics above
 $a>0$
makes it more challenging for surplus to reach high levels. Therefore, a dividend should be paid before the surplus reached level a, and if
 $b_-\leq 0$
, it is also meaningful to set the barrier at 0 even though ruin immediately occurs as a result.
Furthermore, for fixed moderate
 $\beta\in(\!-1,0)$
and moderate
 $\mu_-$
, as
 $\mu_+$
gradually increases from negative to positive, the optimal strategy undergoes a transition from a
 $b_1$
-barrier strategy to a
 $(b_1, a_1,b_2)$
-band strategy and ultimately to a
 $b_+$
-barrier strategy. On the other hand, if
 $\mu_-$
takes an extreme negative value then the
 $(0,a_1,b_2)$
-band strategy tends to be optimal for large positive
 $\mu_+$
values, which agrees with the intuition that when the surplus is close to 0, a dividend should be paid as soon as possible in the presence of negative trend.
In addition, for
 $\beta\in(0, 1)$
, if either
 $b_-\geq a$
or
 $0 \lt b_- \lt a$
and
 $W'(b_-)> W'(a+\!)$
then the optimal strategy transitions from a
 $a+$
-barrier strategy to a
 $b_+$
-barrier strategy as
 $\mu_+$
increases; otherwise, it shifts from a
 $(b_1, a_1,a+)$
-band strategy to a
 $(b_1, a_1,b_2)$
-band strategy and then to a
 $b_+$
-barrier strategy as
 $\mu_+$
increases.
Fixing
 $\beta\in(\!-1,0)$
and
 $\mu_-$
, once the optimal strategy becomes a
 $b_+$
-barrier, for sufficiently large values of
 $\mu_+>0$
, the optimal barrier level
 $b_+$
exhibits a decreasing trend as
 $\mu_+$
increases. This is due to the fact that to maximize the expected total amount of discounted dividends, the large value of
 $\mu+$
reduces the ruin probability and allows to set the barrier lower so that the dividend is paid earlier to reduce the effect of discounting.
To conclude, the tables suggest that either a barrier or a band strategy is optimal depending on the joint effect of
 $\beta$
,
 $\mu_{\pm}$
and other model parameters. A band strategy may also be optimal when the drift switches its sign from negative to positive, i.e.
 $\mu_-< 0<\mu_+$
or when the skewness below a intensifies, i.e.
 $\beta\downarrow -1$
; in the latter case, a band strategy can remain optimal even for relatively small (or even zero) drift gap
 $|\mu_+ - \mu_-|$
. For example, Table 1 reports that for
 $\beta= -0.9$
and
 $\mu_- = \mu_+ = 5$
, the
 $(a-, a, 1.718)$
-band is optimal.
Appendix A. Proofs
In the following we provide proofs of lemmas and propositions for completeness. Recall that
 $\rho_1^-<0<\rho_2^-, \rho_1^+<0<\rho_2^+$
, and
 $\beta\in(\!-1,1)$
.
A.1. Proof of Lemma 2.1
Proof. From the definition of
 $c_i(q)$
for
 $i=1,2$
in (2.8), it follows that
 \begin{align}1-c_1(q)=\frac{(1-\beta)\rho_2^{-}-(1+\beta)\rho_1^+}{(1-\beta)(\rho_2^{-}-\rho_1^-)},\end{align}
 \begin{align}&1-c_2(q)=\frac{(1-\beta)\rho_2^{-}-(1+\beta)\rho_1^+}{(1+\beta)(\rho_2^+-\rho_1^+)}.\nonumber\end{align}
Since both the numerator and denominator of
 $1-c_i(q)$
for
 $i=1,2$
are positive, we have
 \begin{align}&1-c_i(q)>0.\end{align}
Further, since
 $(1\pm \beta)(\rho_{2}^{\pm}-\rho_{1}^{\pm})>0$
holds for the denominators of
 $c_i(q)$
for
 $i=1,2$
, by (2.8) it is straightforward to obtain the necessary and sufficient conditions for
 $c_i(q) \lt 0$
, as outlined in Lemma 2.1.
A.2. Proof of Lemma 4.1
Proof. For
 $0\leq a_0 \lt b$
and
 $b\in\mathbb{R}_+\backslash\{a\}$
, we consider three different scenarios:
 $a_0 \lt a \lt b$
,
 $a\leq a_0 \lt b$
, and
 $a_0 \lt b \lt a$
. For the case
 $a_0 \lt a \lt b$
, applying the strong Markov property, we have
 \begin{align}V_{b}(b, a_0)&= \textrm{E}_{b}\Bigg[\int_0^{\hat{\tau}_a} e^{-q t}\mathrm{d}D_t^{\pi_b}\Bigg]+\textrm{E}_b[e^{-q \hat{\tau}_a}] \textrm{E}_a[e^{-q \tau_b}; \tau_b<\tau_{a_0}] V_{b}(b, a_0). \end{align}
Considering that the process
 $(U_t^{\pi_b})_{0\leq t\leq \hat{\tau}_a}$
is simply a reflected Brownian motion with drift
 $\mu_+$
, i.e.
 $U_t^{\pi_b}=x+B_t+\mu_+t-D_t^{\pi_b}$
, by Proposition 1 in [Reference Renaud and Zhou32], we have
 \begin{align}\textrm{E}_{b}\Bigg[\int_0^{\hat{\tau}_a} e^{-q t}\mathrm{d}D_t^{\pi_b}\Bigg]=\frac{e^{\rho_2^+(b-a)}-e^{\rho_1^+(b-a)}}{\rho_2^+e^{\rho_2^+(b-a)}-\rho_1^+e^{\rho_1^+(b-a)}}=\frac{w(b,a)}{w_b(b,a)},\end{align}
where
 $w_{x}(x,y)$
is given by (4.2).
We now determine
 $\textrm{E}_b[e^{-q \hat{\tau}_a}]$
with
 $a \lt b$
. Fix
 $x\in(a, b]$
and consider X on
 $[0, \hat{\tau}_a]$
. Define the running maximum process by
 $\overline{X}_t\,:\!=\,\max\limits_{0\leq s\leq t}X_s,\, t\geq 0$
. Then the aggregate dividends paid up to time t is
 $D_t^{\pi_b}\,:\!=\,(\overline{X}_t-b)\vee 0$
, with
 $D_{0}^{\pi_b}=0$
. Let
 $S_t\,:\!=\,0\vee \overline{X}_t$
, define
 $Y_t\,:\!=\,S_t-X_t$
as the Brownian motion
 $X_t$
with drift
 $\mu_+$
reflected at its past running maximum
 $S_t$
. Denote by
 $\tilde{\tau}_y$
the time at which process
 $(Y_t)_{t\geq 0}$
first hits the boundary y, i.e.
 $\tilde{\tau}_{y}\,:\!=\,\inf\{t\geq 0, Y_t\geq y\}$
. By construction,
 $U_t^{\pi_b} = X_t - D_t^{\pi_b}$
is simply a reflected Brownian motion with drift
 $\mu_+$
, i.e.
 $U_t^{\pi_b}=x+B_t+\mu_+t-D_t^{\pi_b}$
. Then applying the spatial homogeneity of X, it is easy to conclude that
 $\{U^{\pi_b}, D^{\pi_b}, \hat{\tau}_a, U_0^{\pi_b}=x\}$
has the same law as
 $\{b-Y, S, \tilde{\tau}_{b-a}, Y_0=b-x\}$
. For any
 $q>0$
, by Theorem 4.1 and Remark 4.3 of [Reference Zhou37] we have
 \begin{align*}\textrm{E}_{U_0^{\pi_b}=b}[e^{-q \hat{\tau}_a}]=\textrm{E}_{Y_0=0}[e^{-q \tilde{\tau}_{b-a}}]=\frac{K^{(q)}(b-a)}{\widehat{W}^{(q)}{'}(b-a)},\end{align*}
where
 $\widehat W^{(q)}$
denotes the q-scale function of a Brownian motion with drift
 $\mu_+$
, i.e.
 $\widehat W^{(q)}(x) = \frac{2}{\rho_2^+ - \rho_1^+}(e^{\rho_2^+ x} - e^{\rho_1^+ x})$
, and
 \begin{align*}&K^{(q)}(x)\,:\!=\, q \left(\int_0^x \widehat{W}^{(q)}(y) \mathrm{d} y\right) \, \widehat{W}^{(q)}{'}(x)-q \,\big(\widehat{W}^{(q)}(x)\big)^2 + \widehat{W}^{(q)}{'}(x).\end{align*}
Since
 $\rho_1^+ \rho_2^+ = -2q$
, further simplification yields
 \begin{align}\textrm{E}_{b}[e^{-q \hat{\tau}_a}] &=\frac{1}{\rho_2^+ e^{\rho_2^+ (b-a)} - \rho_1^+ e^{\rho_1^+ (b-a)}} \nonumber \\& \quad \cdot \Bigg( \frac{2q}{\rho_2^+ - \rho_1^+}\Bigg( \left(\frac{e^{\rho_2^+ (b-a)} -1}{\rho_2^+} - \frac{e^{\rho_1^+ (b-a)} -1}{\rho_1^+}\right)\left(\rho_2^+ e^{\rho_2^+ (b-a)} - \rho_1^+ e^{\rho_1^+ (b - a) }\right) \nonumber \\& \quad - \left(e^{\rho_2^+ (b-a)} - e^{\rho_1^+(b-a)}\right)^{2} \Bigg) + \rho_2^+ e^{\rho_2^+ (b-a)} - \rho_1^+ e^{\rho_1^+ (b-a)} \Bigg) \nonumber \\& =\frac{(\rho_2^+-\rho_1^+) e^{(\rho_1^+ + \rho_2^+)(b-a)}}{\rho_2^+e^{\rho_2^+(b-a)}-\rho_1^+e^{\rho_1^+(b-a)}}=\frac{\rho_2^+-\rho_1^+}{\rho_2^+e^{\rho_1^+(a-b)}-\rho_1^+e^{\rho_2^+(a-b)}}=\frac{w_b(b,b)}{w_b(b,a)},\end{align}
where
 $w_{x}(x, x)=w_{y}(y, x)|_{y=x}$
.
Thus, substituting (A4) and (A5) into (A3), by (2.9) we obtain
 \begin{align*}&V_{b}(b, a_0)=\frac{w(b,a)w(b,a_0)}{w_b(b,a)w(b, a_0)-w_b(b,b)w(a, a_0)}.\end{align*}
By (2.11),
 \begin{align}&w_b(b,a)w(b, a_0)-w_b(b,b)w(a, a_0) \nonumber\\&=\big(g_{2,q}'(b)g_{1,q}(a)-g_{1,q}'(b)g_{2,q}(a)\big)\big(g_{2,q}(b)g_{1,q}(a_0)-g_{1,q}(b)g_{2,q}(a_0)\big) \nonumber \\&\ \ -\big(g_{2,q}'(b)g_{1,q}(b)-g_{1,q}'(b)g_{2,q}(b)\big)\big(g_{2,q}(a)g_{1,q}(a_0)-g_{1,q}(a)g_{2,q}(a_0)\big) \nonumber \\&=g_{2,q}(b)g_{1,q}(a)\big(g_{2,q}'(b) g_{1,q}(a_0) - g_{1,q}'(b) g_{2,q}(a_0)\big) \nonumber \\&\ \ - g_{1,q}(b) g_{2,q}(a) \big(g_{2,q}'(b)g_{1,q}(a_0) - g_{1,q}'(b) g_{2,q}(a_0)\big) \nonumber \\&= \big(g_{2,q}(b)g_{1,q}(a) - g_{1,q}(b) g_{2,q}(a)\big)\big(g_{2,q}'(b)g_{1,q}(a_0) - g_{1,q}'(b) g_{2,q}(a_0)\big) \nonumber \\&= w(b,a) w_b(b, a_0),\end{align}
which simplifies
 $V_{b}(b, a_0)$
to
 \begin{align*}&V_{b}(b, a_0)=\frac{w(b,a)w(b,a_0)}{w(b, a)w_b(b, a_0)}=\frac{w(b,a_0)}{w_b(b,a_0)}.\end{align*}
Note that for
 $a\leq a_0 \lt b$
and
 $a_0 \lt b \lt a$
,
 $U^{\pi_b}$
also reduces to a reflected Brownian motion with drift. By Proposition 1 in [Reference Renaud and Zhou32] again, we have
 $V_{b}(b, a_0) = \frac{w(b,a_0)}{w_b(b,a_0)}$
. Further, when
 $a_0=0$
, by (4.1) and (4.4) we have
 \begin{align}&V_{b}(b)=\frac{W(b)}{W'(b)}.\end{align}
For
 $0\leq x\leq b$
, applying the strong Markov property together with the fact that no dividends are paid out until the surplus process X exceeds the level b, by (2.9), (4.4), and (A7) we have
 \begin{eqnarray*} &&V_b(x)=\textrm{E}_x[e^{-q \tau_{b}}; \tau_{b}<\tau_0]V_b(b)=\frac{W(x)}{W(b)} V_b(b)=\frac{W(x)}{W'(b)}. \end{eqnarray*}
For
 $x> b> a>0$
, since
 $D^{\pi_b}$
has a jump at
 $t=0$
of size
 $x-b$
to bring
 $U^{\pi_b}$
back to the level b, by (A7) we have
 \begin{eqnarray*} V_b(x)=x-b+V_b(b)=x-b+\frac{W(b)}{W'(b)}. \end{eqnarray*}
This completes the proof.
A.3. Proof of Proposition 4.1
Proof. The first-order derivative of W(x) defined by (4.4) is given by
 \[ W'(x) = g_{2,q}'(x)g_{1,q}(0)-g_{1,q}'(x)g_{2,q}(0). \]
From the forms of
 $g_{1,q}(x)$
and
 $g_{2,q}(x)$
in (2.2) and (2.3), it follows that
 $g_{1,q}(0) = c_1(q)e^{-\rho_2^- a} + \big(1-c_1(q)\big) e^{-\rho_1^- a}$
,
 $g_{2,q}(0) = e^{-\rho_2^- a}$
, and
 \begin{align*}&g_{1,q}'(x)= \rho_{1}^+ e^{\rho_{1}^+(x-a)} {\mathbf{1}_{\{x> a\}}}+{\Big(c_1(q)\rho_{2}^-e^{\rho_{2}^-{(x-a)}}+\big(1-c_1(q)\big) \rho_{1}^- e^{\rho_{1}^-{(x-a)}} \Big)}{\mathbf{1}_{\{x\leq a\}}},\\&g_{2,q}'(x)=\Big(\big(1-c_2(q)\big)\rho_{2}^+e^{\rho_{2}^+(x-a)}+c_2(q)\rho_{1}^+ e^{\rho_{1}^+(x-a)} \Big){1_{\{x> a\}}}{+\rho_{2}^- e^{\rho_{2}^-(x-a)}}{1_{\{x\leq a\}}}.\end{align*}
Substituting
 $g_{i,q}'(x)$
for
 $i=1,2$
into
 $W'$
(x), and incorporating the given
 $g_{i,q}(0)$
, we obtain, for
 $0\leq x \lt a$
,
 \begin{align*}W'(x)& = \rho_{2}^- e^{\rho_{2}^-(x-a)} \Big(c_1(q)e^{-\rho_2^- a} + \big(1-c_1(q)\big) e^{-\rho_1^- a}\Big) \\&\ \ - \Big(c_1(q)\rho_{2}^-e^{\rho_{2}^-{(x-a)}}+\big(1-c_1(q)\big) \rho_{1}^- e^{\rho_{1}^-{(x-a)}}\Big) e^{-\rho_2^- a}\\&=\big(1-c_1(q)\big)e^{-(\rho_1^-+\rho_2^-)a}(\rho_2^-e^{\rho_2^-x}-\rho_1^-e^{\rho_1^-x}),\end{align*}
and for
 $x>a$
,
 \begin{align*}W'(x)&=\Big(\big(1-c_2(q)\big)\rho_{2}^+e^{\rho_{2}^+(x-a)}+c_2(q)\rho_{1}^+ e^{\rho_{1}^+(x-a)} \Big) \Big(c_1(q)e^{-\rho_2^- a} + \big(1-c_1(q)\big) e^{-\rho_1^- a}\Big)\\& - \rho_{1}^+ e^{\rho_{1}^+(x-a)} e^{-\rho_2^- a}\\&=\rho_2^+\Big(c_1(q)e^{-\rho_2^-a}+\big(1-c_1(q)\big)e^{-\rho_1^-a}\Big)\big(1-c_2(q)\big)e^{\rho_2^+(x-a)}\\& -\rho_1^+\Big(\big(1-c_1(q)c_2(q)\big)e^{-\rho_2^-a}-c_2(q)\big(1-c_1(q)\big)e^{-\rho_1^-a}\Big)e^{\rho_1^+(x-a)}.\end{align*}
In particular, by (2.7) we have
 \begin{align*}(1-\beta)W'(a-\!)&=(1-\beta)\big(g_{2,q}'(a-\!)g_{1,q}(0)-g_{1,q}'(a-\!)g_{2,q}(0)\big)\\&=(1+\beta)\big(g_{2,q}'(a+\!)g_{1,q}(0)-g_{1,q}'(a+\!)g_{2,q}(0)\big)\\&=(1+\beta) W'(a+\!).\end{align*}
This completes the proof.
A.4. Proof of Proposition 4.2
Proof. The condition
 $W''(x)=0, x\in\mathbb{R}$
, with W
′′(x) given by (4.8), implies
 \begin{align*}\big(1-c_1(q)\big)e^{-(\rho_1^-+\rho_2^-)a}\big({\rho_2^-}^2e^{\rho_2^-x}-{\rho_1^-}^2e^{\rho_1^-x}\big)=0,\end{align*}
which simplifies to
 $e^{(\rho_2^- - \rho_1^-)x}={\rho_1^-}^2/{\rho_2^-}^2$
. Since
 ${\rho_1^-}^2/{\rho_2^-}^2>0$
, solving for x yields
 $b_-$
in (4.10). The condition
 $W''(x)=0, x\in\mathbb{R}$
implies by (4.9) that
 \begin{align*}&{\rho_2^+}^2\big(1-c_2(q)\big)\Big(c_1(q)e^{-\rho_2^-a}+\big(1-c_1(q)\big)e^{-\rho_1^-a}\Big)e^{\rho_2^+(x-a)}\\& -{\rho_1^+}^2 \Big(\big(1-c_1(q)c_2(q)\big)e^{-\rho_2^-a}-c_2(q)\big(1-c_1(q)\big)e^{-\rho_1^-a}\Big)e^{\rho_1^+(x-a)}=0.\end{align*}
It follows that
 $e^{(\rho_2^+-\rho_1^+)(x-a)}=K(\beta)$
for
 $K(\beta)$
given by (4.12). If
 $K(\beta)>0$
, the expression for
 $b_+$
in (4.11) is obtained.
A.5. Proof of Proposition 4.3
Proof.
-
(i) If
$\mu_-\leq 0$
then (2.6) leads to
$-\rho_1^- \leq \rho_2^-$
, which in turn implies
$\ln(\!-\rho_1^- / \rho_2^-)\leq 0$
, and consequently,
$b_-$
, as defined in (4.10), satisfies
$b_-\leq 0$
. Conversely, if
$b_-\leq 0$
then by (4.10) we get
$\ln\!(\!-\rho_1^- / \rho_2^-)\leq0$
, which further implies
$-\rho_1^-\leq \rho_2^-$
, and then, (2.6) yield
$\mu_-\leq 0$
. -
(ii) If
$K(\beta)>1$
then as
$\ln K(\beta)>0$
, the expression of
$b_+$
in (4.11) implies
$b_+> a$
. Conversely, by (4.11), the necessary condition for
$b_+> a$
is
$\ln K(\beta)>0$
, which further corresponds to
$K(\beta)>1$
.


This completes the proof.
A.6. Proof of Lemma 4.2
Proof. Note that
 \begin{align}& c_1(q) e^{-\rho_2^-a}+\big(1-c_1(q)\big)e^{-\rho_1^- a}>c_1(q) e^{-\rho_2^-a}+\big(1-c_1(q)\big)e^{-\rho_2^- a}=e^{-\rho_2^-a}>0.\end{align}
We first prove that W(x) is a non-negative, continuous increasing function on
 $\mathbb{R}_+$
by considering three cases:
 $0\leq x \lt a$
,
 $x=a$
, and
 $x \gt a \gt 0$
.
For
 $0\leq x \lt a$
, by (4.5) we have
 $W'(x)>0$
.
For
 $x=a$
, by (4.5) we have
 \begin{align*}&W'(a-\!)=\big(1-c_1(q)\big)(\rho_2^-e^{-\rho_1^-a}-\rho_1^-e^{-\rho_2^-a})>0,\end{align*}
and then, by (4.7), we have
 $W'(a+\!)>0$
.
For
 $x \gt a \gt 0$
, the cases
 $c_2(q) \lt 0$
and
 $0\leq c_2(q) \lt 1$
are considered separately.
-
(i) If
$c_2(q) \lt 0$
then by (A8)

 \begin{align*}\rho_2^+ \Big(c_1(q)e^{-\rho_2^-a}+\big(1-c_1(q)\big)e^{-\rho_1^-a}\Big)\big(1-c_2(q)\big)e^{\rho_2^+(x-a)}>\rho_2^+ e^{-\rho_2^-a}\big(1-c_2(q)\big)e^{\rho_2^+(x-a)},\end{align*}
and
 \begin{align*}\rho_1^+ c_2(q)\big(1-c_1(q)\big)e^{-\rho_1^-a}>\rho_1^+ c_2(q)\big(1-c_1(q)\big)e^{-\rho_2^-a}.\end{align*}
Combining the above two inequalities, we obtain
 \begin{align*}W'(x)& >\rho_2^+ e^{-\rho_2^-a}\big(1-c_2(q)\big)e^{\rho_2^+(x-a)}\\ & \ \ -\rho_1^+\Big(\big(1-c_1(q)c_2(q)\big)e^{-\rho_2^-a}-c_2(q)\big(1-c_1(q)\big)e^{-\rho_2^- a}\Big)e^{\rho_1^+(x-a)}\\& =\big(1-c_2(q)\big)e^{-\rho_2^-a}\big(\rho_2^+e^{\rho_2^+(x-a)}-\rho_1^+e^{\rho_1^+(x-a)}\big)>0.\end{align*}
-
(ii) If
$0\leq c_2(q) \lt 1$
then since
$$\rho_2^+\big(1-c_2(q)\big)e^{\rho_2^+(x-a)}+\rho_1^+c_2(q)e^{\rho_1^+(x-a)}>\rho_1^+c_2(q)\big(e^{\rho_1^+(x-a)}-e^{\rho_2^+(x-a)}\big)>0,$$
(A9)
\begin{align}&\rho_2^+\big(1-c_2(q)\big)+\rho_1^+c_2(q)=\rho_2^+ \frac{(1-\beta)\rho_2^{-}-(1+\beta)\rho_1^+}{(1+\beta)(\rho_2^+-\rho_1^+)}+\rho_1^+ \frac{(1+\beta) \rho_{2}^+-(1-\beta)\rho_{2}^-}{(1+\beta)(\rho_{2}^+-\rho_{1}^+)}\nonumber\\&=\frac{(1-\beta)\rho_2^-\rho_{2}^+-(1-\beta)\rho_{2}^-\rho_1^+}{(1+\beta)(\rho_{2}^+-\rho_{1}^+)}=\frac{(1-\beta)\rho_2^-}{(1+\beta)}>0.\end{align}


It follows from (4.6) and (A8) that
 \begin{align*}W'(x)&=\Big(c_1(q)e^{-\rho_2^-a}+\big(1-c_1(q)\big)e^{-\rho_1^-a}\Big)\Big(\rho_2^+\big(1-c_2(q)\big)e^{\rho_2^+(x-a)}+\rho_1^+c_2(q)e^{\rho_1^+(x-a)}\Big)\\& \ \ - \rho_1^+ e^{-(\rho_1^+ +\rho_2^-)a+\rho_1^+x}\\& > e^{-\rho_2^-a}\Big(\rho_2^+\big(1-c_2(q)\big)e^{\rho_2^+(x-a)}+\rho_1^+c_2(q)e^{\rho_1^+(x-a)}\Big)- \rho_1^+e^{-(\rho_1^+ +\rho_2^-)a+\rho_1^+x}\\&>0.\end{align*}
By (2.2) and (2.3) we have
 $g_{1,q}(a\pm)=g_{2,q}(a\pm)=1$
, and then
 \begin{eqnarray*}&&W(a)=W(a-\!)=W(a+\!)=g_{1,q}(0)-g_{2,q}(0)=\big(1-c_1(q)\big)\big(e^{-\rho_1^-a}-e^{-\rho_2^-a}\big)>0.\end{eqnarray*}
In addition,
 $W(0) = g_{2,q}(0)g_{1,q}(0)-g_{1,q}(0)g_{2,q}(0)=0$
. Combining the above, W is a non-negative, continuous increasing function on
 $\mathbb{R}_+$
.
We next discuss the monotonicity and convexity of
 $W'$
(x), which can be divided into two cases:
 $0\leq x \lt a$
and
 $x \gt a \gt 0$
. (I) For
 $0\leq x \lt a$
, taking the derivative of W
′′ defined in (4.8) yields
 \begin{eqnarray*}&&W'''(x)=\big(1-c_1(q)\big)e^{-(\rho_2^-+\rho_1^-)a}\big({\rho_2^-}^3e^{\rho_2^-x}-{\rho_1^-}^3e^{\rho_1^-x}\big) \gt 0.\end{eqnarray*}
Then W
′′(x) is strictly increasing in x. Recall the solution
 $b_-$
in (4.10) of
 $W''(x)=0$
. In the following we consider different values of
 $b_-$
:
-
(i)
$b_-\leq 0$
if and only if
$W^{\prime\prime}(x)>0$
if and only if
$W'$
(x) is strictly increasing in x; -
(ii)
$0 \lt b_- \lt a$
if and only if
$W^{\prime\prime}(x) \lt 0$
for
$x\in[0,b_-)$
and
$W''(x)>0$
for
$x\in(b_-, a)$
if and only if
$W'$
(x) is non-monotone convex; -
(iii)
$a \leq b_-$
if and only if
$W^{\prime\prime}(x) \lt 0$
if and only if
$W'$
(x) is strictly decreasing in x.


(II) For
 $x>a>0$
, we further discuss the monotonicity and convexity of
 $W'$
(x) for
 $K(\beta)\leq 1$
and
 $K(\beta)> 1$
, respectively.
-
(i) If
$K(\beta)\leq 1$
then the numerator and denominator in (4.12) satisfy which leads to W ′′(x), defined by (4.9), satisfying
\begin{align*}&{\rho_1^+}^2\big((1-c_1(q)c_2(q))e^{-\rho_2^-a}-c_2(q)(1-c_1(q))e^{-\rho_1^-a}\big)\\& \leq {\rho_2^+}^2(1-c_2(q))(c_1(q)e^{-\rho_2^-a}+(1-c_1(q))e^{-\rho_1^-a}),\end{align*}
where (A8) is applied for the last inequality. Then
\begin{align*}W{''}(x)&\geq {\rho_2^+}^2\big(1-c_2(q)\big)\Big(c_1(q)e^{-\rho_2^-a}+\big(1-c_1(q)\big)e^{-\rho_1^-a}\Big)e^{\rho_2^+(x-a)}\\&\ \ -{\rho_2^+}^2\big(1-c_2(q)\big)\Big(c_1(q)e^{-\rho_2^-a}+\big(1-c_1(q)\big)e^{-\rho_1^-a}\Big)e^{\rho_1^+(x-a)}\\&= {\rho_2^+}^2\big(1-c_2(q)\big)\Big(c_1(q)e^{-\rho_2^-a}+\big(1-c_1(q)\big)e^{-\rho_1^-a}\Big)(e^{\rho_2^+(x-a)}-e^{\rho_1^+(x-a)})\\&> {\rho_2^+}^2 \big(1-c_2(q)\big) e^{-\rho_2^-a} (e^{\rho_2^+(x-a)}-e^{\rho_1^+(x-a)})>0,\end{align*}
$W'$
(x) is strictly increasing.
-
(ii) By (4.9),
If
\begin{align*} W{'''}(x)&={\rho_2^+}^3\Big(c_1(q)e^{-\rho_2^-a}+\big(1-c_1(q)\big)e^{-\rho_1^-a}\Big) \big(1-c_2(q)\big)e^{\rho_2^+(x-a)}\\ & \ \ -{\rho_1^+}^3\Big(\big(1-c_1(q)c_2(q)\big)e^{-\rho_2^-a}-c_2(q)\big(1-c_1(q)\big) e^{-\rho_1^-a}\Big)e^{\rho_1^+(x-a)}.\end{align*}
$K(\beta)>1$
, since the denominator of
$K(\beta)$
is positive, we have which combined with (A8) implies
\begin{align*}&\big(1-c_1(q)c_2(q)\big)e^{-\rho_2^-a}-c_2(q)\big(1-c_1(q)\big)e^{-\rho_1^-a}>0,\end{align*}
$W{'''}(x)>0$
, i.e. W
′′ is strictly increasing. By Proposition 4.3(ii) we have
$b_+>a$
for
$W{''}(b_+)=0$
. Then
$W''(x) \lt 0$
for
$x\in(a, b_+)$
and
$W''(x)>0$
for
$x\in(b_+, \infty)$
. Thus,
$W'$
is non-monotone convex on
$(a, \infty)$
.


This completes the proof.
A.7. Proof of Proposition 4.4
Proof. We write
 $c_{1,\beta}(q)$
for
 $c_1(q)$
to emphasize its dependence on
 $\beta$
. Then
 \begin{align}&\frac{\mathrm{d} c_{1,\beta}(q)}{\mathrm{d}\beta}=\frac{\mathrm{d}}{\mathrm{d}\beta}\left(\frac{(1+\beta) \rho_{1}^+-(1-\beta)\rho_{1}^-}{(1-\beta)(\rho_{2}^{-}-\rho_{1}^-)}\right)\nonumber\\&=\frac{(\rho_{1}^+ + \rho_{1}^-) (1-\beta)(\rho_{2}^{-}-\rho_{1}^-) + \big((1+\beta)\rho_{1}^+ - (1-\beta)\rho_{1}^-\big)(\rho_{2}^{-}-\rho_{1}^-)}{(1-\beta)^2(\rho_{2}^{-}-\rho_{1}^-)^2}\nonumber\\&= \frac{(\rho_{1}^+ + \rho_{1}^-) (1-\beta) + (1+\beta)\rho_{1}^+ - (1-\beta)\rho_{1}^-}{(1-\beta)^2(\rho_{2}^{-}-\rho_{1}^-)}=\frac{2\rho_1^+}{(1-\beta)^2(\rho_2^{-}-\rho_1^-)}.\end{align}
By (4.5),
 \begin{align}&W_{\beta}'(a-\!)=\big(1-c_{1,\beta}(q)\big)(\rho_2^-e^{-\rho_1^-a}-\rho_1^-e^{-\rho_2^-a}).\end{align}
Then applying (A10) we have
 \begin{align}\frac{\mathrm{d}W_{\beta}'(a-\!)}{\mathrm{d}\beta}&=\frac{-2\rho_1^+}{(1-\beta)^2(\rho_2^{-}-\rho_1^-)}(\rho_2^-e^{-\rho_1^-a}-\rho_1^-e^{-\rho_2^-a})>0,\end{align}
and
 $W_{\beta}'(a-\!)$
is thus strictly increasing in
 $\beta$
for
 $\beta\in(\!-1, 1)$
. By (4.7) we have
 $W_{\beta}'(a+\!)=\frac{1-\beta}{1+\beta} W_{\beta}'(a-\!)$
. Then
 \begin{align*}&\frac{\mathrm{d}W_{\beta}'(a+\!)}{\mathrm{d}\beta}=\frac{\mathrm{d}}{\mathrm{d}\beta}\left(\frac{1-\beta}{1+\beta}\right) W_{\beta}'(a-\!)+\frac{1-\beta}{1+\beta} \frac{\mathrm{d}W_{\beta}'(a-\!)}{\mathrm{d}\beta}.\end{align*}
Plugging (A11) and (A12) into the above expression, we have
 \begin{align*}\frac{\mathrm{d}W_{\beta}'(a+\!)}{\mathrm{d}\beta}&=\frac{-2}{(1+\beta)^2} \cdot \frac{(1-\beta)\rho_2^{-}-(1+\beta)\rho_1^+}{(1-\beta)(\rho_2^{-}-\rho_1^-)} (\rho_2^-e^{-\rho_1^-a}-\rho_1^-e^{-\rho_2^-a})\\&\ \ +\frac{1-\beta}{1+\beta} \cdot \frac{-2\rho_1^+}{(1-\beta)^2(\rho_2^{-}-\rho_1^-)}(\rho_2^-e^{-\rho_1^-a}-\rho_1^-e^{-\rho_2^-a})\\&=\frac{-2\rho_2^-}{(1+\beta)^2(\rho_2^{-}-\rho_1^-)}(\rho_2^-e^{-\rho_1^-a}-\rho_1^-e^{-\rho_2^-a}).\end{align*}
Then
 $\mathrm{d}W_{\beta}'(a+\!)/ \mathrm{d}\beta \lt 0$
and
 $W_{\beta}'(a+\!)$
is strictly decreasing in
 $\beta$
for
 $\beta\in(\!-1, 1)$
.
For
 $\beta=0$
, by (4.5) and (4.6) we obtain
 $$W_{0}'(a-\!)=W_{0}'(a+\!)=\frac{\rho_2^{-}-\rho_1^+}{\rho_2^{-}-\rho_1^-}(\rho_2^-e^{-\rho_1^-a}-\rho_1^-e^{-\rho_2^-a}).$$
By the monotonicity of
 $W_{\beta}'(a-\!)$
and
 $W_{\beta}'(a+\!)$
in
 $\beta$
, we have
 $W_{\beta}'(a-\!) \lt W_{\beta}'(a+\!)$
if and only if
 $\beta\in(\!-1, 0)$
.
A.8. Proof of Lemma 5.1
Proof. In the proof we keep
 $0\leq b_1 \lt a \lt b_2$
and
 $0\leq b_1\leq a_1\leq b_2$
. For
 $x\in[0, a_1]$
, since no dividend is paid before X reaches
 $b_1$
, and dividends are continuously paid while X remains between
 $b_1$
and
 $a_1$
until X decreases to
 $b_1$
,
 $V_{b_1, a_1, b_2}(x)$
is equivalent to
 $V_{b_1}(x)$
, and by (4.3), we have that, for
 $0\leq x\leq b_1$
,
 $V_{b_1, a_1, b_2}(x) = \frac{W(x)}{W'(b_1)}$
, and for
 $b_1 \lt x\leq a_1$
,
 \begin{align*}&V_{b_1, a_1, b_2}(x) = x-b_1+\frac{W(b_1)}{W'(b_1)}.\end{align*}
In particular, for
 $x=a_1$
, we have
 \begin{eqnarray}V_{b_1, a_1, b_2}(a_1)=a_1-b_1+\frac{W(b_1)}{W'(b_1)}.\end{eqnarray}
For
 $a_1 \lt x \lt b_2$
, applying the strong Markov property together with the fact that no dividends are paid out until X exceeds the interval
 $(a_1, b_2)$
, by (2.9), (2.10), and (A13) we have
 \begin{align}V_{b_1, a_1, b_2}(x)&=\textrm{E}_x[e^{-q \tau_{a_1}}; \tau_{a_1}<\tau_{b_2}]V_{b_1, a_1, b_2}(a_1)+\textrm{E}_x[e^{-q \tau_{b_2}}; \tau_{b_2}<\tau_{a_1}]V_{b_1, a_1, b_2}(b_2)\nonumber\\&=\frac{w(x,b_2)}{w(a_1,b_2)}\left(a_1-b_1+\frac{W(b_1)}{W'(b_1)}\right)+\frac{w(x,a_1)}{w(b_2,a_1)}V_{b_1, a_1, b_2}(b_2). \end{align}
We will now determine the expression for
 $V_{b_1, a_1, b_2}(b_2)$
by considering two cases:
 $a\leq a_1$
and
 $a>a_1$
. For
 $a\leq a_1$
, re-applying the strong Markov property, by (A4), (A5), and (A13) we have
 \begin{align}V_{b_1, a_1, b_2}(b_2)&=\textrm{E}_{b_2}\Big[\int_0^{\hat{\tau}_{a_1}}e^{-q t} \,\mathrm{d}D_t^{\pi_{b_1, a_1, b_2}}\Big]+\textrm{E}_{b_2}[e^{-q \hat{\tau}_{a_1}}] V_{b_1, a_1, b_2}(a_1)\nonumber\\&=\frac{w(b_2,a_1)}{w_{b_2}(b_2,a_1)}+\frac{w_{b_2}(b_2, b_2)}{w_{b_2}(b_2,a_1)}\left(a_1-b_1+\frac{W(b_1)}{W'(b_1)}\right). \end{align}
For
 $a> a_1$
, by (A14) we have
 \begin{eqnarray} V_{b_1, a_1, b_2}(a)=\frac{w(a,b_2)}{w(a_1,b_2)}\left(a_1-b_1+\frac{W(b_1)}{W'(b_1)}\right)+\frac{w(a,a_1)}{w(b_2,a_1)}V_{b_1, a_1, b_2}(b_2), \end{eqnarray}
 \begin{align}V_{b_1, a_1, b_2}(b_2)&=\textrm{E}_{b_2}\left[\int_0^{\hat{\tau}_a}e^{-q t} \,\mathrm{d}D_t^{\pi_{b_1, a_1, b_2}}\right]+\textrm{E}_{b_2}[e^{-q \hat{\tau}_a}] V_{b_1, a_1, b_2}(a)\nonumber\\&=\frac{w(b_2,a)}{w_{b_2}(b_2,a)}+\frac{w_{b_2}(b_2, b_2)}{w_{b_2}(b_2,a)}V_{b_1, a_1, b_2}(a), \end{align}
and then, by solving a system of equations in (A16) and (A17), we can also find the expression for
 $V_{b_1, a_1, b_2}(b_2)$
in (A15). Further plugging (A15) into (A14), by
 $w(x, y)= -w(y, x)$
, we get, for
 $a_1 \lt x \lt b_2$
,
 \begin{align*} V_{b_1, a_1, b_2}(x)& = \frac{w(x,a_1)}{w_{b_2}(b_2,a_1)}+ \left(\frac{w(x,b_2)}{w(a_1,b_2)} + \frac{w(x,a_1)w_{b_2}(b_2, b_2)}{w(b_2,a_1)w_{b_2}(b_2,a_1)} \right) \,\left(a_1-b_1+\frac{W(b_1)}{W'(b_1)}\right)\\&= \frac{w(x,a_1)}{w_{b_2}(b_2,a_1)}+ \frac{w(b_2, x)w_{b_2}(b_2,a_1) - w(a_1, x)w_{b_2}(b_2, b_2) }{w(b_2,a_1)w_{b_2}(b_2,a_1)} \,\left(a_1-b_1+\frac{W(b_1)}{W'(b_1)}\right).\end{align*}
In the same manner as (A6), we have
 $$w(b_2, x)w_{b_2}(b_2,a_1) - w(a_1, x)w_{b_2}(b_2, b_2)= w(b_2,a_1) w_{b_2}(b_2, x),$$
and then,
 \begin{align*}& V_{b_1, a_1, b_2}(x)= \frac{w(x, a_1)}{w_{b_2}(b_2, a_1)}+\left(a_1-b_1+\frac{W(b_1)}{W'(b_1)}\right) \frac{w_{b_2}(b_2, x)}{w_{b_2}(b_2, a_1)}.\end{align*}
For
 $b_2 \lt x \lt \infty$
, since no dividends are paid before X reaches
 $b_2$
, by (A15) we have
 \begin{align*}V_{b_1, a_1, b_2}(x)&=x-b_2+\frac{w(b_2, a_1)}{w_{b_2}(b_2, a_1)}+\left(a_1-b_1+\frac{W(b_1)}{W'(b_1)}\right) \frac{w_{b_2}(b_2, b_2)}{w_{b_2}(b_2, a_1)}. \end{align*}
Note that
 $V_{b_1, a_1, b_2}\in C(\mathbb{R_+})$
.
A.9. Proof of Proposition 5.1
Proof. From w(x,y) defined in (2.11) and its partial derivative
 $w_x(x,y)$
in (4.2), together with the associated
 $g_{1,q}(x)$
and
 $g_{2,q}(x)$
given in (2.2) and (2.3), we obtain, for
 $0 \lt a \lt a_1\leq b_2$
, the form of
 $w_{b_2}(b_2, a_1)$
is given by (5.1), which expresses
 $w_{b_2}(b_2, a_1)$
as the product of three positive terms, implying that
 $w_{b_2}(b_2, a_1)>0$
.
For
 $0\leq a_1\leq a \lt b_2$
,
 \begin{align}w_{b_2}(b_2, a_1)&=\left(\rho_2^+\big(1-c_{2}(q)\big) e^{\rho_2^+(b_2-a)}+\rho_1^+c_{2}(q)e^{\rho_1^+(b_2-a)}\right)\\&\ \ \cdot \Big(c_{1}(q)e^{\rho_2^-(a_1-a)}+\big(1-c_{1}(q)\big)e^{\rho_1^-(a_1-a)}\Big)-\rho_1^+ e^{\rho_1^+(b_2-a)}e^{\rho_2^-(a_1-a)}.\nonumber\end{align}
Separating the terms involving
 $e^{\rho_2^+(b_2-a)}$
and
 $e^{\rho_1^+(b_2-a)}$
in (A18), we rewrite
 $w_{b_2}(b_2, a_1)$
for
 $0\leq a_1\leq a \lt b_2$
in the form shown in (5.2). We now prove
 $w_{b_2}(b_2, a_1)>0$
by considering two cases:
 $c_2(q) \lt 0$
and
 $0\leq c_2(q) \lt 1$
. Note that
 \begin{align}&c_1(q)e^{\rho_2^-(a_1-a)}+\big(1-c_1(q)\big)e^{\rho_1^-(a_1-a)}\nonumber\\& \geq c_1(q)e^{\rho_2^-(a_1-a)}+\big(1-c_1(q)\big)e^{\rho_2^- (a_1-a)}=e^{\rho_2^-(a_1-a)}> 0.\end{align}
-
(i) If
$c_2(q) \lt 0$
then by (A2) and
$e^{\rho_1^-(a_1-a)}\geq1\geq e^{\rho_2^-(a_1-a)}$
we have which leads to
$$c_{2}(q)\big(1-c_{1}(q)\big)e^{\rho_1^-(a_1-a)}\leq c_{2}(q)\big(1-c_{1}(q)\big)e^{\rho_2^-(a_1-a)},$$
By combining this with (A2) and (A19), we deduce that
$$\big(1-c_{1}(q)c_{2}(q)\big)e^{\rho_2^-(a_1-a)}-c_{2}(q)\big(1-c_{1}(q)\big)e^{\rho_1^-(a_1-a)}\geq \big(1-c_{2}(q)\big)e^{\rho_2^-(a_1-a)}> 0.$$
$w_{b_2}(b_2, a_1)$
, as given in (5.2), is the sum of two positive terms, implying
$w_{b_2}(b_2, a_1)>0$
.
-
(ii) If
$0\leq c_2(q) \lt 1$
then by (A9) Therefore,
\[\rho_2^+\big(1-c_2(q)\big)e^{\rho_2^+(b_2-a)}+\rho_1^+ c_2(q)e^{\rho_1^+(b_2-a)} \gt \Big(\rho_2^+\big(1-c_2(q)\big)+ \rho_1^+ c_2(q)\Big)e^{\rho_1^+(b_2-a)} \gt 0. \]
$w_{b_2}(b_2, a_1)>0$
.


This completes the proof.
A.10. Proof of Proposition 5.2
Proof. We show the differentiability of
 $V_{b_1, a_1, b_2}(x)$
at
 $x=a_1$
and
 $x=b_{2}$
. By Lemma 5.1 we have
 $V_{b_1, a_1, b_2}'(x)=1$
for
 $x\in[b_1, a_1)$
and then
 $V_{b_1, a_1, b_2}'(a_1-)=1$
. Since
 $w_{b_2,b_2}\big(b_{2}, b_{2}\big)\,:\!=\,w_{x,y}(x, y)|_{x=y=b_2}=0$
, by Lemma 5.1 we obtain
 \begin{align*}&V_{b_1, a_1, b_2}'(b_{2}-)=\frac{w_{b_2}(b_{2}, a_{1})}{w_{b_2}(b_{2}, a_{1})}+ \frac{w_{b_2,b_2}(b_{2}, b_{2})}{w_{b_2}(b_{2}, a_{1})}V_{b_1, a_1, b_2}(a_{1})=1,\\&V_{b_1, a_1, b_2}'(b_{2}+)=1,\end{align*}
which implies
 $V_{b_1, a_1, b_2}'(b_{2})=1$
.
A.11. Proof of Lemma 5.2
Proof. In the proof we keep
 $0\leq b_1\leq a_1 \lt a \lt b_2$
. Preliminarily evaluating
 $V_{b_1, a_1, b_2}'(x)$
and
 $V_{b_1, a_1, b_2}''(x)$
, as defined in (5.3) and (5.4), respectively, at
 $x=a_1$
yields
 \begin{align}&V_{b_1, a_1, b_2}'(a_1)=\frac{\tilde{K}_{2}(b_1, a_1, b_2){\rho_2^-} e^{\rho_2^-(a_1-a)}-\tilde{K}_{1}(b_1, a_1, b_2){\rho_1^-} e^{\rho_1^-(a_1-a)}}{w_{b_2}(b_2, a_1)},\nonumber\\&V_{b_1, a_1, b_2}''(a_1)=\frac{\tilde{K}_{2}(b_1, a_1, b_2){\rho_2^-}^2 e^{\rho_2^-(a_1-a)}-\tilde{K}_{1}(b_1, a_1, b_2){\rho_1^-}^2 e^{\rho_1^-(a_1-a)}}{w_{b_2}(b_2, a_1)}.\end{align}
By referring to the definitions of
 $g_{i,q}(x)$
for
 $i=1, 2$
in (2.2) and (2.3),
 $\tilde{K}_{1}(b_1, a_1, b_2)$
and
 $\tilde{K}_{2}(b_1, a_1, b_2)$
, as given in (5.5) and (5.6), respectively, can be expanded as
 \begin{align}&\tilde{K}_{1}(b_1, a_1, b_2)=\big(1-c_1(q)\big) \nonumber\\&\cdot\Big(e^{\rho_2^- (a_1-a)}-V_{b_1, a_1, b_2}(a_1)\big(\rho_2^+(1-c_2(q)) e^{\rho_2^+(b_2-a)}+\rho_1^+c_2(q) e^{\rho_1^+(b_2-a)}\big)\Big), \\[-28pt] \nonumber \end{align}
 \begin{align}&\tilde{K}_{2}(b_1, a_1, b_2)=\big(1-c_1(q)\big)e^{\rho_1^- (a_1-a)} \nonumber \\& +V_{b_1, a_1, b_2}(a_1)\Big(\rho_2^+ c_1(q)\big(1-c_2(q)\big) e^{\rho_2^+ (b_2-a)}-\rho_1^+ \big(1-c_1(q) c_2(q)\big) e^{\rho_1^+(b_2-a)}\Big). \\[0pt] \nonumber \end{align}
Then, substituting (A21) and (A22) into
 $V_{b_1, a_1, b_2}'(a_1)$
, we obtain
 \begin{align*}&V_{b_1, a_1, b_2}'(a_1) w_{b_2}(b_2, a_1)=({\rho_2^-}-{\rho_1^-})\big(1-c_1(q)\big)e^{(\rho_2^- +\rho_1^-)(a_1-a)}\\& +V_{b_1, a_1, b_2}(a_1) \Big(\rho_2^+ \big(1-c_2(q)\big)\big({\rho_2^-} c_1(q) e^{\rho_2^- (a_1-a)}+{\rho_1^-} (1-c_1(q)) e^{\rho_1^- (a_1-a)}\big)e^{\rho_2^+(b_2-a)}\nonumber\\& -\rho_1^+\big({\rho_2^-} (1-c_1(q)c_2(q)) e^{\rho_2^- (a_1-a)}-{\rho_1^-} c_2(q) (1-c_1(q)) e^{\rho_1^- (a_1-a)}\big)e^{\rho_1^+(b_2-a)}\Big).\nonumber\end{align*}
Since
 $V_{b_1,a_1, b_2}'(a_1)=1$
, by (5.2) we have
 \begin{align}&({\rho_2^-}-{\rho_1^-})\big(1-c_1(q)\big)e^{(\rho_2^- +\rho_1^-)(a_1-a)}\nonumber\\& =\rho_2^+ \big(1-c_{2}(q)\big)\Big(c_{1}(q)e^{\rho_2^-(a_1-a)}+\big(1-c_{1}(q)\big)e^{\rho_1^-(a_1-a)}\Big)e^{\rho_2^+(b_2-a)}\nonumber\\& -\rho_1^+\Big(\big(1-c_{1}(q)c_{2}(q)\big)e^{\rho_2^-(a_1-a)}-c_{2}(q)\big(1-c_{1}(q)\big)e^{\rho_1^-(a_1-a)}\Big) e^{\rho_1^+(b_2-a)}\nonumber\\& \ \ -V_{b_1, a_1, b_2}(a_1)\Big(\rho_2^+ \big(1-c_2(q)\big)\big({\rho_2^-} c_1(q) e^{\rho_2^- (a_1-a)}+{\rho_1^-} (1-c_1(q)) e^{\rho_1^- (a_1-a)}\big)e^{\rho_2^+(b_2-a)}\nonumber\\& -\rho_1^+\big({\rho_2^-} (1-c_1(q)c_2(q)) e^{\rho_2^- (a_1-a)}-{\rho_1^-} c_2(q) (1-c_1(q)) e^{\rho_1^- (a_1-a)}\big)e^{\rho_1^+(b_2-a)}\Big)\nonumber\\&=\rho_2^+\big(1-c_2(q)\big)\Big(c_1(q)\big(1-\rho_2^-V_{b_1,a_1, b_2}(a_1)\big)e^{\rho_2^- (a_1-a)}\nonumber\\& +\big(1-c_1(q)\big)\big(1-\rho_1^-V_{b_1,a_1, b_2}(a_1)\big)e^{\rho_1^- (a_1-a)}\Big)e^{\rho_2^+ (b_2-a)}\nonumber\\& -\rho_1^+\Big(\big(1-c_1(q)c_2(q)\big)\big(1-\rho_2^-V_{b_1,a_1, b_2}(a_1)\big)e^{\rho_2^- (a_1-a)}\nonumber\\& -c_2(q)\big(1-c_1(q)\big)\big(1-\rho_1^-V_{b_1,a_1, b_2}(a_1)\big)e^{\rho_1^- (a_1-a)}\Big)e^{\rho_1^+ (b_2-a)}.\end{align}
For
 $\tilde{K}_{1}(b_1, a_1, b_2)$
as given in (A21), by (A23) we have
 \begin{align*}&\tilde{K}_{1}(b_1, a_1, b_2)\\&=\frac{e^{-\rho_1^- (a_1-a)}}{\rho_2^- -\rho_1^-} \Big(\rho_2^+\big(1-c_2(q)\big)\big(c_1(q)\big(1-\rho_2^-V_{b_1,a_1, b_2}(a_1)\big)e^{\rho_2^- (a_1-a)}\nonumber\\& +\big(1-c_1(q)\big)\big(1-\rho_1^-V_{b_1,a_1, b_2}(a_1)\big)e^{\rho_1^- (a_1-a)}\big)e^{\rho_2^+ (b_2-a)}\nonumber\\& -\rho_1^+\big(\big(1-c_1(q)c_2(q)\big)\big(1-\rho_2^-V_{b_1,a_1, b_2}(a_1)\big)e^{\rho_2^- (a_1-a)}\nonumber\\&-c_2(q)\big(1-c_1(q)\big)\big(1-\rho_1^-V_{b_1,a_1, b_2}(a_1)\big)e^{\rho_1^- (a_1-a)}\big)e^{\rho_1^+ (b_2-a)}\Big)\nonumber\\& - \big(1-c_1(q)\big) V_{b_1, a_1, b_2}(a_1)\Big(\rho_2^+\big(1-c_2(q)\big) e^{\rho_2^+(b_2-a)}+\rho_1^+c_2(q) e^{\rho_1^+(b_2-a)}\Big).\end{align*}
Grouping the terms involving
 $V_{b_1, a_1, b_2}(a_1)$
, the above expression becomes
 \begin{align*}&\tilde{K}_{1}(b_1, a_1, b_2)\nonumber\\&=\frac{1}{\rho_2^- -\rho_1^-}\Big(\rho_2^+\big(1-c_2(q)\big)\big(c_1(q) e^{(\rho_2^- - \rho_1^-) (a_1-a)}+\big(1-c_1(q)\big)\big)e^{\rho_2^+ (b_2-a)}\nonumber\\& -\rho_1^+\big(\big(1-c_1(q)c_2(q)\big) e^{(\rho_2^- -\rho_1^-) (a_1-a)} -c_2(q)\big(1-c_1(q)\big)\big)e^{\rho_1^+ (b_2-a)}\Big)\nonumber\\& - \frac{V_{b_1,a_1, b_2}(a_1)}{\rho_2^- -\rho_1^-} \Big(\rho_2^+\big(1-c_2(q)\big)\big(c_1(q)\rho_2^- e^{(\rho_2^- - \rho_1^-) (a_1-a)}+\big(1-c_1(q)\big)\rho_1^-\big)e^{\rho_2^+ (b_2-a)}\nonumber\\& -\rho_1^+\big(\big(1-c_1(q)c_2(q)\big)\rho_2^- e^{(\rho_2^- -\rho_1^-) (a_1-a)} -c_2(q)\big(1-c_1(q)\big) \rho_1^-\big)e^{\rho_1^+ (b_2-a)}\Big)\nonumber\\& - V_{b_1, a_1, b_2}(a_1) \big(1-c_1(q)\big) \Big(\rho_2^+\big(1-c_2(q)\big) e^{\rho_2^+(b_2-a)}+\rho_1^+c_2(q) e^{\rho_1^+(b_2-a)}\Big)\nonumber\\&=\frac{1-\rho_2^-V_{b_1, a_1, b_2}(a_1)}{\rho_2^- -\rho_1^- }\Big(\rho_2^+\big(1-c_2(q)\big)\big(c_1(q) e^{(\rho_2^{-}-\rho_1^-)(a_1-a)}+(1-c_1(q))\big)e^{\rho_2^+ (b_2-a)}\nonumber\\& -\rho_1^+\big((1-c_1(q)c_2(q)) e^{(\rho_2^{-}-\rho_1^-)(a_1-a)}-c_2(q) (1-c_1(q))\big)e^{\rho_1^+ (b_2-a)}\Big)\nonumber\\&=\frac{1-\rho_2^-V_{b_1, a_1, b_2}(a_1)}{\rho_2^- -\rho_1^-}w_{b_2}(b_2, a_1) e^{-\rho_1^-(a_1-a)}.\nonumber\end{align*}
Similarly, by (A21) and (A23),
 \begin{align*}&\tilde{K}_{2}(b_1, a_1, b_2)\\&=\frac{e^{-\rho_2^- (a_1-a)}}{\rho_2^- -\rho_1^-} \Big(\rho_2^+\big(1-c_2(q)\big)\big(c_1(q)\big(1-\rho_2^-V_{b_1,a_1, b_2}(a_1)\big)e^{\rho_2^- (a_1-a)}\nonumber\\& +\big(1-c_1(q)\big)\big(1-\rho_1^-V_{b_1,a_1, b_2}(a_1)\big)e^{\rho_1^- (a_1-a)}\big)e^{\rho_2^+ (b_2-a)}\nonumber\\& -\rho_1^+\big(\big(1-c_1(q)c_2(q)\big)\big(1-\rho_2^-V_{b_1,a_1, b_2}(a_1)\big)e^{\rho_2^- (a_1-a)}\nonumber\\& -c_2(q)\big(1-c_1(q)\big)\big(1-\rho_1^-V_{b_1,a_1, b_2}(a_1)\big)e^{\rho_1^- (a_1-a)}\big)e^{\rho_1^+ (b_2-a)}\Big)\nonumber\\& +V_{b_1, a_1, b_2}(a_1)\Big(\rho_2^+ c_1(q)\big(1-c_2(q)\big) e^{\rho_2^+ (b_2-a)}-\rho_1^+ \big(1-c_1(q) c_2(q)\big) e^{\rho_1^+(b_2-a)}\Big)\nonumber\\&=\frac{1}{\rho_2^- -\rho_1^-}\Big(\rho_2^+\big(1-c_2(q)\big)\big(c_1(q) +\big(1-c_1(q)\big)e^{(\rho_1^- - \rho_2^-) (a_1-a)}\big)e^{\rho_2^+ (b_2-a)}\nonumber\\& -\rho_1^+\big(\big(1-c_1(q)c_2(q)\big) -c_2(q)\big(1-c_1(q)\big)e^{(\rho_1^- -\rho_2^-) (a_1-a)} \big)e^{\rho_1^+ (b_2-a)}\Big)\nonumber\\& - \frac{V_{b_1,a_1, b_2}(a_1)}{\rho_2^- -\rho_1^-} \Big(\rho_2^+\big(1-c_2(q)\big)\big(c_1(q)\rho_2^-+\big(1-c_1(q)\big)\rho_1^-e^{(\rho_1^- - \rho_2^-) (a_1-a)}\big)e^{\rho_2^+ (b_2-a)}\nonumber\\& -\rho_1^+\big(\big(1-c_1(q)c_2(q)\big)\rho_2^- -c_2(q)\big(1-c_1(q)\big) \rho_1^- e^{(\rho_1^- -\rho_2^-) (a_1-a)} \big)e^{\rho_1^+ (b_2-a)}\Big)\nonumber\\& +V_{b_1, a_1, b_2}(a_1)\Big(\rho_2^+ c_1(q)\big(1-c_2(q)\big) e^{\rho_2^+ (b_2-a)}-\rho_1^+ \big(1-c_1(q) c_2(q)\big) e^{\rho_1^+(b_2-a)}\Big)\\&=\frac{1-\rho_1^-V_{b_1, a_1, b_2}(a_1)}{\rho_2^- -\rho_1^- }\Big(\rho_2^+\big(1-c_2(q)\big)\big(c_1(q) +(1-c_1(q))e^{(\rho_1^{-}-\rho_2^-)(a_1-a)}\big)e^{\rho_2^+ (b_2-a)}\\& -\rho_1^+\big((1-c_1(q)c_2(q)) -c_2(q) (1-c_1(q))e^{(\rho_1^{-}-\rho_2^-)(a_1-a)}\big)e^{\rho_1^+ (b_2-a)}\Big)\nonumber\\&=\frac{1-\rho_1^-V_{b_1, a_1, b_2}(a_1)}{\rho_2^- -\rho_1^-}w_{b_2}(b_2, a_1) e^{-\rho_2^-(a_1-a)}.\end{align*}
Next, we analyze the expression for
 $V_{b_1, a_1, b_2}''(a_1)$
, under the condition that
 $V_{b_1,a_1, b_2}'(a_1)=1$
with
 $a_1\in[b_1, a)$
. By substituting
 $\tilde{K}_{1}(b_1, a_1, b_2)$
with (5.11) and
 $\tilde{K}_{2}(b_1, a_1, b_2)$
with (5.12) in (A20),
 $V_{b_1, a_1, b_2}''(a_1)$
can be reformulated as
 \begin{align*}V_{b_1, a_1, b_2}''(a_1)&=\frac{1-\rho_1^-V_{b_1, a_1, b_2}(a_1)}{\rho_2^- -\rho_1^-}w_{b_2}(b_2, a_1) e^{-\rho_2^-(a_1-a)}\frac{{\rho_2^-}^2 e^{\rho_2^-(a_1-a)}}{w_{b_2}(b_2, a_1)}\\& -\frac{1-\rho_2^-V_{b_1, a_1, b_2}(a_1)}{\rho_2^- -\rho_1^-}w_{b_2}(b_2, a_1) e^{-\rho_1^-(a_1-a)} \frac{{\rho_1^-}^2 e^{\rho_1^-(a_1-a)}}{w_{b_2}(b_2, a_1)}\\&=\frac{{\rho_2^-}^2\big(1-\rho_1^-V_{b_1, a_1, b_2}(a_1)\big)-{\rho_1^-}^2\big(1-\rho_2^-V_{b_1, a_1, b_2}(a_1)\big)}{\rho_2^- -\rho_1^-}\\& = \rho_2^-+\rho_1^{-}-\rho_1^- \rho_2^- V_{b_1, a_1, b_2}(a_1).\end{align*}
Then (5.13) follows from
 $\rho_2^-+\rho_1^-= -2\mu_-$
and
 $\rho_1^- \rho_2^-=-2q$
.
A.12. Proof of Lemma 5.3
Proof. In the proof we keep
 $0\leq b_1\leq a_1 \lt a \lt b_2$
. If
 $V_{b_1,a_1, b_2}'(a_1)=1$
with
 $a_1\in[b_1, a)$
, by (5.13) we have
 $V_{b_1, a_1, b_2}''(a_1)> 0$
if and only if
 $V_{b_1, a_1, b_2}(a_1)> {\mu_-}/{q}$
.
We first prove that
 $V_{b_1, a_1, b_2}''(a_1)\geq 0$
by verifying the above condition. For
 $b_1=b_-\in(0,a_1)$
, it follows from (4.3) and Lemma 5.1 that
 $V_{b_-, a_1, b_2}(b_-)=V_{b_-}(b_-)={\mu_-}/{q}$
by (4.14), and then
 \begin{align*}&V_{b_-, a_1, b_2}(a_1)> V_{b_-, a_1, b_2}(b_-)={\mu_-}/{q},\end{align*}
which implies
 $V_{b_-, a_1, b_2}''(a_1)> 0$
; for
 $b_1=b_-=a_1 \in(0, a)$
, since
 $V_{b_-, b_-, b_2}(a_1)=V_{b_-, b_-, b_2} (b_-)={\mu_-}/{q}$
, by (5.13) we have
 $V_{b_-, b_-, b_2}''(a_1)=0$
; when
 $b_1=0$
for
 $b_-\leq0$
, by Proposition 4.3(i) we have
 $\mu_-\leq0$
, and then we have
 $V_{0, a_1, b_2}''(a_1)>0$
for
 $a_1\in(0, a)$
by (5.13), and
 $V_{0, 0, b_2}''(a_1)=-2\mu_-\geq 0$
for
 $a_1=0$
.
We next show the monotonicity of
 $V_{b_1, a_1, b_2}'(x)$
for
 $x\in(a_1, a)$
by showing
 $V_{b_1, a_1, b_2}''(x)>0$
. Note that
 $w_{b_2}(b_2, a_1)>0$
by Proposition 5.1. Under the condition
 $V_{b_1,a_1, b_2}'(a_1)=1$
for
 $a_1\in[b_1, a)$
, by Lemma 5.2 we have that
 $\tilde{K}_{1}(b_1, a_1, b_2)$
can be either non-positive or positive, and
 \begin{align}&\tilde{K}_{2}(b_1, a_1, b_2)>0.\end{align}
If
 $\tilde{K}_{1}(b_1, a_1, b_2)\leq0$
then by (5.4) and (A24),
 $V_{b_1, a_1, b_2}''(x)>0$
since it is the sum of two positive terms. If
 $\tilde{K}_{1}(b_1, a_1, b_2)>0$
, observing that by (A21) and (A22),
 \begin{align*}&\tilde{K}_{2}(b_1, a_1, b_2)-\tilde{K}_{1}(b_1, a_1, b_2)\nonumber\\&=\big(1-c_1(q)\big)e^{\rho_1^- (a_1-a)}- \big(1-c_1(q)\big) e^{\rho_2^- (a_1-a)}\nonumber\\&\quad +V_{b_1, a_1, b_2}(a_1)\Big(\rho_2^+ c_1(q)\big(1-c_2(q)\big) e^{\rho_2^+ (b_2-a)}-\rho_1^+ \big(1-c_1(q) c_2(q)\big) e^{\rho_1^+(b_2-a)}\Big)\nonumber\\&\quad + V_{b_1, a_1, b_2}(a_1) \big(1-c_1(q)\big) \Big(\rho_2^+\big(1-c_2(q)\big) e^{\rho_2^+(b_2-a)}+\rho_1^+c_2(q) e^{\rho_1^+(b_2-a)}\Big)\nonumber\\&=\big(1-c_{1}(q)\big)\big(e^{\rho_1^-(a_1-a)}-e^{\rho_2^-(a_1-a)}\big)\nonumber\\&\quad +V_{b_1, a_1, b_2}(a_1)\big(1-c_{2}(q)\big)\big(\rho_2^+e^{\rho_2^+(b_2-a)}-\rho_1^+e^{\rho_1^+(b_2-a)}\big)>0,\end{align*}
then by (A24) we have
 $\tilde{K}_{2}(b_1, a_1, b_2)>\tilde{K}_{1}(b_1, a_1, b_2)>0$
and
 \begin{align*}V_{b_1, a_1, b_2}'''(x)&=\frac{\tilde{K}_{2}(b_1, a_1, b_2){\rho_2^-}^3e^{\rho_2^-(x-a)}-\tilde{K}_{1}(b_1, a_1, b_2){\rho_1^-}^3e^{\rho_1^-(x-a)}}{w_{b_2}(b_2, a_1)}\\&>\frac{\tilde{K}_{1}(b_1, a_1, b_2)\big({\rho_2^-}^3e^{\rho_2^-(x-a)}-{\rho_1^-}^3e^{\rho_1^-(x-a)}\big)}{w_{b_2}(b_2, a_1)}>0,\end{align*}
which implies that
 $V_{b_1, a_1, b_2}''(x)$
is strictly increasing in x and satisfies
 $V_{b_1, a_1, b_2}''(x)> V_{b_1, a_1, b_2}''(a_1)\geq 0$
.
A.13. Proof of Lemma 5.4
Proof. In the proof we assume that
 $0\leq b_1 \lt a \lt b_2$
and
 $0\leq b_1\leq a_1 \lt b_2$
and take
 $x\in[a_1, b_{2})\cap (a, b_2)$
unless stated otherwise, while using the fact that
 $w_{b_2}(b_2, a_1)>0$
as shown in Proposition 5.1. By (5.7),
 \begin{align}& V_{b_1,a_1, b_2}''(b_2)=\frac{\hat{K}_{2}(b_1, a_1, b_2){\rho_2^+}^2e^{\rho_2^+(b_2-a)}-\hat{K}_{1}(b_1, a_1, b_2){\rho_1^+}^2e^{\rho_1^+(b_2-a)}}{w_{b_2}(b_2, a_1)}.\end{align}
By (5.8), for
 $a_1 \lt a$
,
 \begin{align*}&\hat{K}_{2}(b_1, a_1, b_2)\\&=\big(1-c_{2}(q)\big)\Big(c_{1}(q)e^{\rho_2^-(a_1-a)}+\big(1-c_{1}(q)\big)e^{\rho_1^-(a_1-a)}-\rho_1^+e^{\rho_1^+(b_2-a)}V_{b_1, a_1, b_2}(a_1)\Big)\nonumber\\&>0,\nonumber\end{align*}
applying (A19), and for
 $a_1\geq a$
,
 \begin{align*}\hat{K}_{2}(b_1, a_1, b_2)&=\big(1-c_{2}(q)\big)\big(e^{\rho_1^+(a_1-a)}-\rho_1^+e^{\rho_1^+(b_2-a)}V_{b_1, a_1, b_2}(a_1)\big)>0,\end{align*}
since it is a product of two positive terms.
If there exists
 $b_2>(a_1 \vee a)$
such that
 $V_{b_1,a_1, b_2}''(b_2)=0$
then by (A25) we have
 \begin{eqnarray*}&&b_{2}\,:\!=\,a+\frac{1}{\rho_2^+-\rho_1^+}\ln \hat{K}(b_1, a_{1}, b_{2}),\end{eqnarray*}
where
 $\hat{K}(b_1, a_{1}, b_{2})\,:\!=\,{\rho_1^+}^2\hat{K}_{1}(b_1, a_{1}, b_{2})/\big({\rho_2^+}^2\hat{K}_{2}(b_1, a_{1}, b_{2})\big)$
. For
 $b_{2}>a$
we have
 $\hat{K}(b_1, a_{1}, b_{2})>1$
, which combined with
 $\hat{K}_{2}(b_1, a_{1}, b_{2})>0$
leads to
 \begin{align*}&\hat{K}_{1}(b_1, a_{1}, b_{2}) >\frac{{\rho_2^+}^2}{{\rho_1^+}^2} \hat{K}_{2}(b_1, a_{1}, b_{2})>0.\end{align*}
Next, we prove that
 $V_{b_1, a_1, b_2}'(x)$
is strictly decreasing under the condition
 $V_{b_1,a_1, b_2}''(b_2)=0$
for
 $b_{2}>a$
. By (5.7),
 \begin{align*}V_{b_1, a_1, b_2}'''(x)&=\frac{\hat{K}_{2}(b_1, a_1, b_2){\rho_2^+}^3e^{\rho_2^+(x-a)}-\hat{K}_{1}(b_1, a_1, b_2){\rho_1^+}^3e^{\rho_1^+(x-a)}}{w_{b_2}(b_2, a_1)}>0.\end{align*}
Then
 $V_{b_1, a_1, b_2}''(x)$
is strictly increasing in x and
 $V_{b_1, a_1, b_2}''(x) \lt V_{b_1, a_1, b_2}''(b_{2})=0$
. Then
 $V_{b_1, a_1, b_2}'(x)$
is strictly decreasing and
 $V_{b_1, a_1, b_2}'(x)>V_{b_1, a_1, b_2}'(b_{2})$
.
A.14. Proof of Remark 5.1
Proof. (i) By (4.3) and Lemma 5.1, the comparison between barrier and band value functions on
 $[0,b_1)$
is determined by the location of
 $\arg\min W'$
. If the minimum of
 $W'$
is attained only at
 $a+$
or
 $b_+$
, the corresponding barrier value strictly exceeds the band value on
 $[0,b_1)$
, hence no
 $(b_1,a_1, b_2)$
-band is optimal. Conversely, a necessary condition for band optimality is that
 $W'$
attain its minimum at one of
 $0+, b_-, a-$
.
(ii) Since
 $\mathcal M\in\{0+, b_-, a-\}$
, it follows directly that
 $V_{b_1}(x)>\max\{V_{a+}(x),V_{b_+}(x)\}$
. Assume
 $V_{b_1,a_1, b_2}'(a_1)=1$
for some
 $a_1\in[b_1, a)$
and consider
 $x\in(a_1, a)$
. By Lemma 5.3 we have
 $V_{b_1, a_1, b_2}'(x)$
is strictly increasing, and then,
 $V_{b_1, a_1, b_2}'(x)> V_{b_1,a_1, b_2}'(a_1)=1$
. From (4.3), we also know that
 $V_{b_1}'(x)=1$
for all
 $x\in(a_1, a)$
. Consequently,
 $V_{b_1, a_1, b_2}'(x)- V_{b_1}'(x)>0$
. Integrating over
 $(a_1, x)$
and using
 $V_{b_1, a_1, b_2}(a_1)=V_{b_1}(a_1)$
yields
 $V_{b_1, a_1, b_2}(x)> V_{b_1}(x)$
for every
 $x\in(a_1, a)$
.
(iii) We omit the proof of (iii), which follows from Lemma 5.4 together with
 $V_{b_1,a_1, b_2}'(b_2)=1$
(proved in Proposition 5.2) by the same argument as in (ii).
A.15. Proof of Lemma 5.5
Proof. For
 $a \leq a_1$
,
 $V_{b_1, a_1, b_2}(x)$
is a special case of Lemma 5.1, and we focus on the case
 $x \geq a_1$
. For
 $x\in[a_1, b_2)$
, by (5.1) and
 \begin{align*}&w(x, a_1)= \big(1-c_{2}(q)\big)e^{(\rho_2^++\rho_1^+)(a_1-a)}\big(e^{\rho_2^+(x-a_1)}- e^{\rho_1^+(x-a_1)}\big),\\&w_{b_2}(b_2, x)= \big(1-c_{2}(q)\big)e^{(\rho_2^++\rho_1^+)(x-a)}\big(\rho_2^+e^{\rho_2^+(b_2-x)}-\rho_1^+ e^{\rho_1^+(b_2-x)}\big),\end{align*}
applying
 $W_+(x)$
given in (5.14), we have
 \begin{align*}&\frac{w(x, a_1)}{w_{b_2}(b_2, a_1)}=\frac{e^{\rho_2^+(x-a_1)}- e^{\rho_1^+(x-a_1)} }{\rho_2^+ e^{\rho_2^+(b_2-a_1)}-\rho_1^+ e^{\rho_1^+(b_2-a_1)}}=\frac{W_+(x-a_1)}{W_+'(b_2-a_1)},\\&\frac{w_{b_2}(b_2, x)}{w_{b_2}(b_2, a_1)}=\frac{e^{(\rho_2^++\rho_1^+)(x-a)}\big(\rho_2^+e^{\rho_2^+(b_2-x)}-\rho_1^+ e^{\rho_1^+(b_2-x)}\big)}{e^{(\rho_2^++\rho_1^+)(a_1-a)}\big(\rho_2^+ e^{\rho_2^+(b_2-a_1)}-\rho_1^+ e^{\rho_1^+(b_2-a_1)}\big)}=\frac{W_+'(b_2-x)e^{(\rho_2^++\rho_1^+)(x-a_1)}}{W_+'(b_2-a_1)}.\end{align*}
In particular, at
 $x=b_2$
, we obtain the following result:
 \begin{align*}&\frac{w(b_2, a_1)}{w_{b_2}(b_2, a_1)}=\frac{W_+(b_2-a_1)}{W_+'(b_2-a_1)} \quad \mathrm{and} \quad\frac{w_{b_2}(b_2, b_2 )}{w_{b_2}(b_2, a_1)}=\frac{W_+'(0)e^{(\rho_2^++\rho_1^+)(b_2-a_1)}}{W_+'(b_2-a_1)}.\end{align*}
A.16. Proof of Lemma 5.6
Proof. Fix
 $0\leq b_1 \lt a \lt b_2$
. By Proposition 5.2, we have
 $V_{b_1, a, b_2}'(b_2)=1$
. If
 $V_{b_1,a, b_2}''(b_2)=0$
then by Lemma 5.4 we have
 $V_{b_1,a_1, b_2}'(x)$
is strictly decreasing for
 $x\in (a, b_2)$
, and then
 $V_{b_1, a, b_2}'(a+\!)> V_{b_1,a, b_2}'(b_2)=1$
. It follows that
 $S'(\beta)= V_{b_1, a, b_2}'(a+\!)+1> 2$
, and then,
 $S(\beta)$
is strictly increasing for
 $\beta\in(\!-1,1)$
.
Since
 $\lim_{\beta\downarrow -1}S(\beta)=-2 \lt 0$
and
 $S(0)=V_{b_1, a, b_2}'(a+\!)-1>0$
, there exists a unique
 $\beta^*\in(\!-1,0)$
, given by (5.15), satisfying
 $S(\beta^*)=0$
and
 $S(\beta)\leq 0$
for
 $\beta\in(\!-1, \beta^*]$
.
A.17. Proof of Remark 5.3
Proof. For
 $\mathcal{M}\in\{a+,\,b_+\}$
, the conclusion follows directly from Theorems 4.4–4.5. Throughout (C1)–(C3) we assume
 $\mathcal M\in\{0+,\,b_-,\,a-\}$
. The justifications are
 $(C1)\text{(i)}$
from Theorem 5.1 together with Remark 5.1(ii);
 $(C1)\text{(ii)}$
from Theorems 4.1–4.3;
 $(C2)\text{(i)}$
with
 $V''_{b_1,a_1,b_2}(b_2)=0$
from Theorem 5.2 and Remark 5.1(iii);
 $(C2)\text{(i)}$
with
 $V''_{b_1,a_1,b_2}(b_2)\neq 0$
and
 $(C2)\text{(ii)}$
from Theorems 4.1–4.3; and (C3) from Remark 5.2.
Acknowledgements
The first author thanks Concordia University where this work was completed during her visit. All authors thank the editor and the reviewers for constructive comments that significantly improved the paper.
Funding information
This research is supported by Natural Sciences and Engineering Research Council of Canada (RGPIN-2021-04100), China Scholarship Council (No. 202206840089), National Natural Science Foundation of China (No. 11671204 and 12471135) and Postgraduate Research and Practice Innovation Program of Jiangsu Province (Project No. KYCX22_0392).
Competing interests
There were no competing interests to declare that arose during the preparation or publication process of this article.