1 Introduction
Working Americans have increasingly relied on employment-based defined contribution (DC) retirement plans as the more traditional defined benefit (DB) pensions have declined over the past 50 years.Footnote 1 A distinguishing feature of DC plans in the USA is that participants must decide how much to contribute and where to invest their retirement assets, instead of holding the employer responsible for plan investments. Employees make these decisions within the menu of investment options offered by plan sponsors, and employers often automatically enroll participants into ‘default’ investments if people do not elect an option.Footnote 2 Recent research in social psychology has argued that too many choices may create confusion, resulting in poorly-informed consumer decisions (e.g., Iyengar and Lepper, Reference Iyengar and Lepper2000).
Relatively little is known about how changing the fund lineup can shape employee investment choices in DC plans.Footnote 3 We seek to fill this gap using administrative data provided by a plan sponsor. The information enables us to examine how participants contributed to a menu of funds and what happened to their fund allocations, along with the costs and risks of the resulting portfolios, as a result of a firm-wide DC plan streamlining effort. In all, the plan menu in the firm was reduced considerably, with almost half of the funds deleted from the lineup. This streamlining process was intended to simplify the fund menu, but it is important to note that the average characteristics of the menu of offered funds (e.g., expense ratio, within-fund turnover, systematic and idiosyncratic risk) were the same before and after the streamlining.
We examine plan participants’ investment choices prior to and after the streamlining event and evaluate what happened to participant fund allocations, risk exposure, and costs as a result of the reform. First, we explore what types of individuals held the deleted funds and how (if at all) they differed from other participants. Based on participant holdings on June 30, 2012, just before the changes were announced in July 2012, we define the holders of these deleted funds as the streamlined participants, and their counterparts as the non-streamlined participants. Second, we evaluate how streamlined participants responded to the changes, and how they reallocated their retirement assets after the reform. Third, we show how the streamlining process affected participants’ portfolio turnover, risk, and expenses.
We find that participants subject to the streamlining proved to be older, more likely to be male, and higher-income; they also held higher balances in riskier funds and lower balances in safer balanced/target date funds (TDFs). Participants holding the deleted funds either (a) reallocated their money to funds kept in the lineup in advance of the deadline to maintain a similar pre- and post-streamlining allocation, or (b) were defaulted into TDFs resulting in an allocation containing, on average, safer assets. Only 9% of the streamlined participants (N = 211) elected the new brokerage window (taking only 0.4% of their assets). Post-streamlining, the streamlined participants adjusted their portfolio holdings, ending up with fewer funds, significantly lower within-fund turnover rates, and lower expense ratios. Based on reasonable assumptions, these portfolio adjustments could lead to potential accumulated savings for these participants over a 20-year period of $20.2 M, or more than $9,400 per participant. Also, after the reform and relative to the non-streamlined participants, streamlined participants’ portfolios generally exhibited lower diversifiable/idiosyncratic risk and less exposure to systematic/non-diversifiable risk factors.
In what follows, we first offer a brief literature review, followed by a discussion of our data and descriptive statistics. We then use multivariate regression models to estimate differences in the changes in portfolio characteristics and risks for participants affected by the streamlining compared with those who were not, controlling for several participant attributes. We conclude with thoughts on how a streamlining intervention such as this might shape employees’ eventual retirement wellbeing.
1.1 Related prior literature
Recent research in social psychology has argued that too many choices can create confusion and distraction, resulting in poorly-informed consumer decisions (e.g., Iyengar and Lepper, Reference Iyengar and Lepper2000). In the context of DC fund menus, Iyengar et al. (Reference Iyengar, Huberman, Jiang, Mitchell and Utkus2004) asked whether such ‘choice overload’ affected participation decisions in the 401(k) environment. They used a 2001 cross-section of participant-level data for 649 DC plans managed by the Vanguard Group to determine whether participation rates were lower in plans when more funds were on the menu. Controlling for a variety of employee attributes (e.g., compensation, gender, age) and plan attributes (e.g., number of employees, whether company stock was offered, number of funds offered), they found that for every ten additional funds on a menu participation rates dropped 2%. While most of the plans examined had 10–30 options, participation rates were actually highest for those with ten or fewer options.
Researchers have also asked whether plan design and complexity affect how participants allocate across funds on the plan menu (e.g., stock vs. bond funds) and the number of funds in which they invest. Financial economics suggests that participants in a pension plan should rationally focus on their own portfolios’ risk-return profiles independent of the number of funds in their pension plan menu. Yet Benartzi and Thaler (Reference Benartzi and Thaler2001) suggested that plan participants actually followed a naïve diversification approach, investing 1/n of their assets in each of the n funds made available in the menu. Similarly, suboptimal investment decisions were reported by Tang et al. (Reference Tang, Mitchell, Mottola and Utkus2010) who showed that even when plan sponsors offered a sufficiently diversified (efficient) menu of funds, participants regularly selected inadequately-diversified portfolios given their selected level of risk.
In a related vein, Brown et al. (Reference Brown, Liang and Weisbenner2007) employed SEC 11-k filings on 891 401(k) plans from 1991–2000 to show that the mix and number of stock and bond funds on a plan menu affect participant investment choices. The panel nature of their dataset (plan-level data for 10 years) permitted the authors to use firm-level fixed-effect regressions. They found that the relative mix of investment options on a 401(k) menu (i.e., the number of equity funds, the number of bond funds, etc., as a percentage of the total number of options offered) is an important predictor of how participants allocate contributions across these asset classes. Put differently, if stock funds make up the largest share of a plan's offerings, participants will allocate the largest share of their contributions to stock funds.
In a more recent study, Morrin et al. (Reference Morrin, Inman, Broniarczyk, Nenkov and Reuter2012) examined how employees covered by the Oregon University System DC plan altered their selection of funds when their plan menu was expanded from 10 to 19 fund choices in July 2007. Both before and after the expansion (the authors’ participant-level data cover February 1998 to March 2010), the default was a money market fund. When the smaller menu was offered, 21% defaulted to the money fund, while with the larger menu, 34% defaulted. Accordingly, the authors concluded that offering more funds (p. 548) ‘may be overwhelming for many investors.’ Of those who did make an election, participants selected on average 37% (3.7 funds) of the funds from the 10-fund menu, and 27% (5.3) from the 19-fund menu. While those results did not support the 1/n heuristic, they were consistent with perhaps a weaker form of the heuristic whereby increasing the number of offered funds led participants to hold more funds. Moreover, the authors (p. 547) concluded that while it may be sensible for plan sponsors to offer a sufficient variety of choices, there is a need to ‘clearly categorize the options to help the [participants] perceive the set of offerings at a higher, more abstract level. Partitioning the funds may enhance asset class diversification while not reducing (and actually increasing) the total number of funds invested in. Subjectively grouping funds by asset class is more likely to assist novice investors than expert investors in their financial decision making.’
Finally, Huberman and Jiang (Reference Huberman and Jiang2006), using the same participant-level 2001 data from 649 DC plans in Iyengar et al. (Reference Iyengar, Huberman, Jiang, Mitchell and Utkus2004), found that (p. 763) ‘the number of funds used [by participants], typically between three and four, is not sensitive to the number of funds offered by the plans, which ranges from 4 to 59.’ They also report that (p. 764) ‘there is little relation between the proportion of contributions that participants allocate to equity funds (equity allocation) and the proportion of equity funds that their plans offer (equity exposure).’ They also said that (p. 765) ‘Once plans offer an abundance of choices (more than 10 funds), there is no correlation between equity allocation and exposure.’ Thus, in contrast to the conclusions in the three studies mentioned above, Huberman and Jiang conclude from their participant-level analysis that participants’ decisions on how to allocate and in how many funds does not appear to be related to the number or mix of plan offerings. However, at the plan level they discovered that (p. 776) ‘the more funds offered, the more funds used.’ They report that when ten (30) funds were offered in a plan, 75% of the dollars invested in the plan were allocated across five (11) funds, a finding that is more consistent with the other papers.
Despite the lack of a consensus, it is reasonable to conclude that prior research confirms that the number and mix of DC fund options can influence investment patterns in retirement accounts. Nevertheless, there is little to no evidence on how differences in the fund options affect costs and risks of participant portfolios.Footnote 4 Moreover, no study has yet examined how participants react to a rather substantial reduction of retirement plan investment choices. In what follows, we explore these issues with a unique new administrative dataset that permits us to follow investor behavior before and after a substantial streamlining in the fund menu and document the effects of the reform on the costs and risks associated with participants’ portfolios.
2 The setting
The employer we study is a large US nonprofit institution. Like its peers, it has long offered a DC structure to cater to participants’ retirement saving needs on a pre-tax basis. Prior to 2013, the plan included almost 90 mutual funds in the investment menu, ranging from equity to target date to bond index funds, as well as Real Estate Investment Trusts (REIT), commodity, and other sector funds. Cognizant of the growing literature on choice overload (see references in Section 1), the firm's investment committee in 2011 determined that a shorter list of offered funds would be easier to administer, explain, and rationalize, compared with the prior menu.
To this end, the committee streamlined the plan menu and arranged the remaining funds into four tiers designed to accommodate participants with differing levels of investment sophistication. Participants who had invested in the funds that would be eliminated from the menu would be allowed to reallocate their assets and contributions to any other fund in the menu, and anyone who did not move his assets out of the funds to be deleted would have his assets automatically transferred to an age-appropriate TDF.Footnote 5 Alternatively, participants who elected to do so could move their assets to a new self-directed brokerage account within the plan, which would give them access to not only the closed funds, but also thousands of other mutual funds.
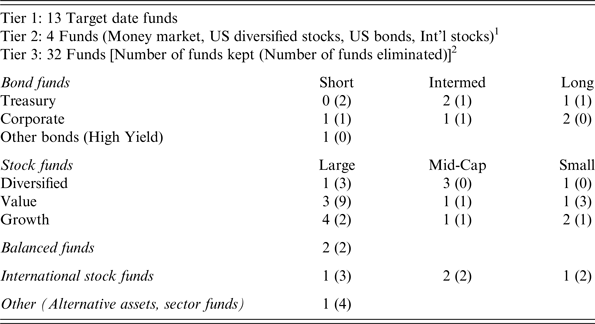
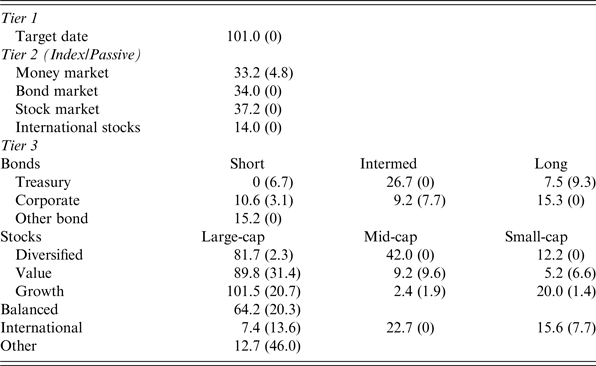
The result was the elimination of 39 funds from the initial lineup, based on the funds’ expense ratios, similarity of return and risk characteristics with retained funds, and the number of participants and aggregate amount invested in each fund.Footnote 6 Remaining funds were allocated across the new four-tier structure, where each successive tier would afford participants additional choice. Tier 1, selected as the default tier for participants not actively electing an investment mix, included 13 low-cost TDFs. Additional tiers offered increasing flexibility of choice for participants seeking to make more customized and sophisticated allocations. Tier 2 included four indexed funds: Money Market, US Diversified Stocks, US Bonds, and Diversified International Stocks. Tier 3 included 32 funds arranged into separate ‘risk’ categories illustrated in more detail in Table 1. The range of categories included: small/mid/large-cap and value/growth stock funds; small/mid/large-cap international stock funds; short/intermediate/long-maturity Treasury and corporate bond funds; balanced funds; and a passive equity REIT fund to provide access to the real estate asset class. Tier 4 constituted the brokerage account. It is evident from Table 1 that much redundancy in fund offerings, and associated potential for confusion, was eliminated from the menu as a result of the streamlining.
Description of fund menu post- (and pre-) streamlining new plan design: post-streamlining # funds = 49

1 Three Money Market funds eliminated.
2 Thirty-nine funds eliminated.
Note: Number of funds retained (and deleted) is as of end-December 2012.
Source: Authors’ calculations.
The plan sponsor announced its streamlined fund lineup in July 2012, with an implementation date of mid-October 2012. In addition to a newsletter sent to all participants, the employer created a custom website, broadcasted online webinars, sent targeted emails, held participant meetings, and sent hard copy mail to explain the changes.
3 Data and descriptive statistics
To analyze the change in behavior post- versus pre-streamlining, we obtained access to information on the retirement plan account balances and periodic contributions of all the (identity-censored) participants. Our administrative dataset included information on contributions, balances, and asset allocation prior to the streamlining, defined in our analysis below as end-June 2012, and after the change, defined as end-December 2012. To this file we appended information from public sources (via ticker and CUSIP numbers) for each fund's equity fraction and style (bond, balanced, stock, etc.), as well as monthly return histories. The fund administrator also provided individual demographic information on participants’ age, sex, education (highest degree from graduate school versus less than graduate school), and, from external sources, imputed household income (assigned according to the participant's zip codes, where low <$50 K, middle $50–100 K, and high >$100 K).Footnote 7
Using the participant balance and contribution data, we identify participants whose holdings were directly affected by the streamlining. Specifically, we separate participants into a Streamlined group – those participants who held funds at end-April 2012 that were subsequently deleted due to streamlining – and a Non-Streamlined group. Additionally, we separate the streamlined participants into two subgroups: ‘Plan-Defaulted & Streamlined’ are the streamlined participants who took no action after the announced streamlining and were defaulted by the Plan into an age-appropriate TDF at the October deadline; and ‘Not-Plan-Defaulted & Streamlined’ are the streamlined participants who exchanged out of the deleted funds prior to the October deadline.
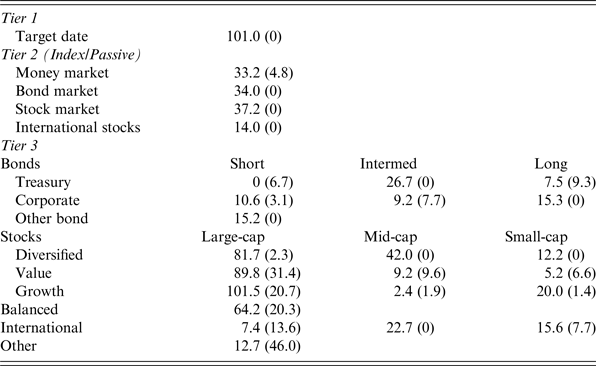
To illustrate how the reform worked, we begin by reviewing descriptive statistics on the balances in the retained and deleted funds by risk category, and we also compare key attributes of participants and their retirement plan investments as of end-June 2012 (our baseline). Table 2 reports aggregate balances held in retained and deleted funds by risk category, where of the almost $1 billion invested at end-June 2012, most of the assets (80%) were held in retained funds. Overall, 20% of the total assets were in funds that were subsequently deleted; of those, about 60% had been in equity (stock, balanced, or international) funds, 24% in alternatives/sector funds, and 14% in bond funds (with the remainder in money market funds).
Total balances in retained (and deleted) funds by risk category (as of end-June 2012; $M)
Source: Authors’ calculations.
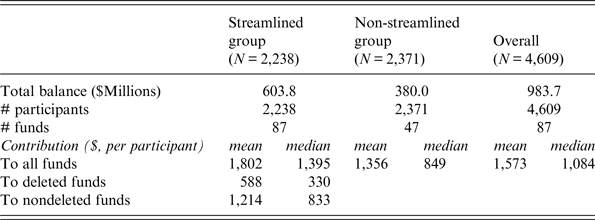
In Table 3 we report aggregate dollar balances, the number of total participants, and the number of funds held by all plan participants at end-June 2012 (rightmost column), along with the same information for the Streamlined participants (who owned at least one deleted fund) and the non-streamlined participants (who owned no deleted funds). The number of participants in each group was roughly similar (2,238 versus 2,371), but the Streamlined group had accumulated almost 60% more in assets ($603.8 versus $380.0 million), contributed 30% more on a monthly basis ($1,802 versus $1,356 per participant), and held more funds overall (87 in total versus 47). On average, about one-third of the contributions of the Streamlined participants were in funds that were subsequently deleted and two-thirds in retained funds.
Balances, number of participants, and number of funds owned: Streamlined vs Non-Streamlined participants (as of end-June 2012)

Source: Authors’ calculations.
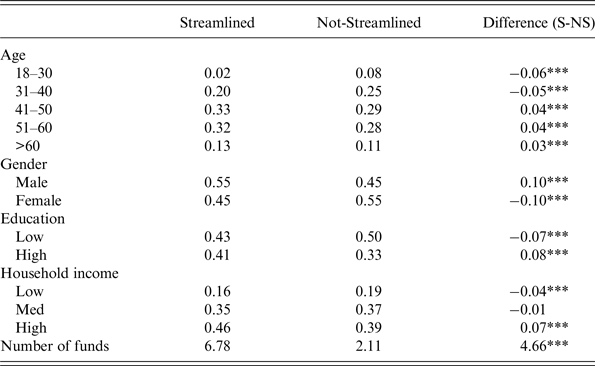
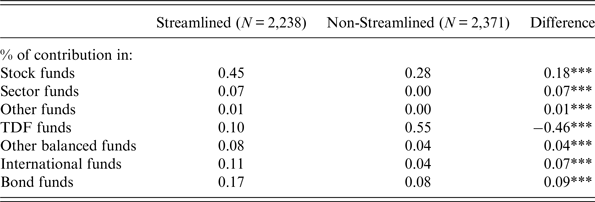
A comparison of characteristics for Streamlined versus Non-Streamlined active participants appears in Table 4. The Streamlined participants were significantly older, more likely to be male, lived in higher-income households, and were more likely to have earned graduate-level degrees. They also owned three times as many funds (an average of 6.8 versus 2.1) compared with the non-streamlined participants. Regarding asset allocations, Table 5 indicates that the Streamlined participants were more likely to contribute directly to stock funds (sector, domestic and international), while the Non-Streamlined participants were more likely to obtain equity exposure (indirectly and in more conservative amounts) via significantly larger allocations to TDFs.Footnote 8 As a result, on average, the Streamlined participants held portfolios containing more equity exposure. One might speculate that these results suggest that Streamlined participants made more sophisticated choices than the younger less-affluent Non-Streamlined participants regarding how to allocate their retirement assets across the various investment options provided by the plan. Yet the fact that most of the Streamlined participants did not open brokerage accounts after the streamlining (see discussion below) in an effort to reproduce these allocations suggests otherwise.
Differences in mean characteristics: Streamlined vs Non-Streamlined participants (as of end-June 2012)

Note: *p < 0.10, **p < 0.05, ***p < 0.01. The low income group is defined to have household income of < $50 K; the middle group $50–$100 K, and the high income group >$100 K.
Source: Authors’ calculations.
Difference in distribution of mean participant asset allocations: Streamlined vs Non-Streamlined participants (as of end-June 2012)

Note: *p < 0.10; **p < 0.05; ***p < 0.01.
Source: Authors’ calculations.
4 Changes in portfolio allocations: a first look
Table 6 reports how participants changed their retirement plan portfolios after the streamlining went into effect. In particular, we compare the allocation of retirement plan assets at two time points: prior to (as of end-June 2012), and after streamlining (as of end-December 2012). Overall, Non-Streamlined participants kept contributions to their retirement accounts virtually unchanged (column 3). Because these participants were not directly affected by the elimination of funds from the lineup, their persistence in the surviving funds refutes the idea that the reorganization and tiering of the surviving funds might have affected all participants’ behavior.Footnote 9
Difference in mean participant asset allocations: post- minus pre-Streamlining (end-December 2012 vs end-June 2012)

Note: *p < 0.10, **p < 0.05, ***p < 0.01.
Source: Authors’ calculations.
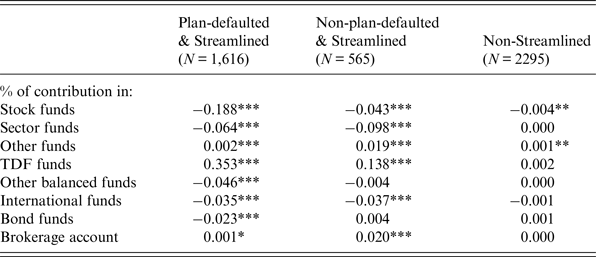
By contrast, streamlining produced statistically significant and economically meaningful changes to allocations made by streamlined participants. To more clearly assess the allocation adjustment process, we separate this group into two sub-samples: (a) those Streamlined participants who did not take advantage of the window between the announcement in July and the deadline for action on October 19 and hence were defaulted by the Plan into age-appropriate TDFs (Plan-Defaulted & Streamlined); and (b) those Streamlined participants who exchanged out of the deleted funds during the July–October 19 window (Not-Plan-Defaulted & Streamlined). The results for both streamlined groups are reported in the first two columns in Table 6. Both types of Streamlined participants significantly reduced allocations to stock, sector, and international funds and they shifted contributions mainly to TDFs. The changes were more pronounced, however, for the Plan-Defaulted members of the Streamlined sample: their allocations to stock, sector, international, balanced and bond funds fell significantly – by a combined 35.6% reduction in contributions, and their allocations to TDFs rose by 35.3%. By contrast, the Not-Plan-Defaulted Streamlined participants significantly decreased allocations to stock, sector and international funds (a combined 17.8% reduction) and significantly increased contributions to TDFs by 13.8%. The Not-Plan-Defaulted group also re-allocated a statistically significant 2% of its contributions to the new brokerage account.Footnote 10 Although we cannot see the transactions in these brokerage accounts, we might surmise that this shift in contributions reflects efforts by the Not-Plan-Defaulted group to continue investing in funds now eliminated from the Plan's menu.Footnote 11
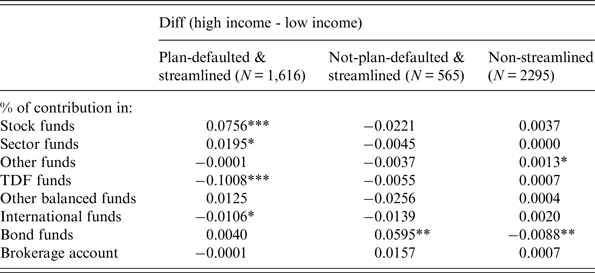
Table 7 helps us examine whether the pre- versus post-streamlining re-allocations were different for high versus low household income participants.Footnote 12 In the Non-Streamlined group there is little evidence of differences by income for pre- versus post-streamlining re-allocations; one exception is that low-income members of the Non-Streamlined group were more likely to shift allocations out of bond funds into the other available funds, although the magnitudes are very small (less than 1%). Within the Streamlined group, significant differences in re-allocations between high and low-income participants are mainly in the Plan-Defaulted sub-group. The most interesting finding, both statistically and economically, is that the overall re-allocations into TDFs seen in Table 6 prove to be 10% larger, and the re-allocations out of stock funds 7.6% larger, for the low-income members of the Plan-Defaulted group.Footnote 13 In other words, the streamlining reform had a larger impact on low-income savers, making their portfolios better balanced and less risky than before.
Difference in mean participant asset allocation by income: post-streamlining minus pre-streamlining (end-December 2012 vs end-June 2012)

Significance levels: *p < 0.10, **p < 0.05, ***p < 0.01.
Source: Authors’ calculations.
5 Changes in participant portfolio characteristics and risks: multivariate analysis
Next we use multivariate regression analyses to analyze in more detail how the reform shaped changes in the portfolio characteristics and risks of Streamlined and Non-Streamlined participants. To measure these differences, we again separate the Streamlined from the non-Streamlined participants, and we further identify the two sub-groups of Streamlined participants with zero-one indicator variables, the Plan-Defaulted-Streamlined and the Not-Plan-Defaulted-Streamlined. Our analysis also controls for various participant attributes including age and age-squared (to test for possible nonlinear effects); male or female; educational level (graduate degree or not); and high versus low household income. We estimate the change in portfolio characteristics over two intervals: end-June 2012 to end-December 2012 (the same time period analyzed in Tables 6 and 7); and also end-June 2012 to end-December 2013 (a longer interval that allows more time for participants to adjust their portfolio allocations post-streamlining).
5.1 Changes in portfolio characteristics
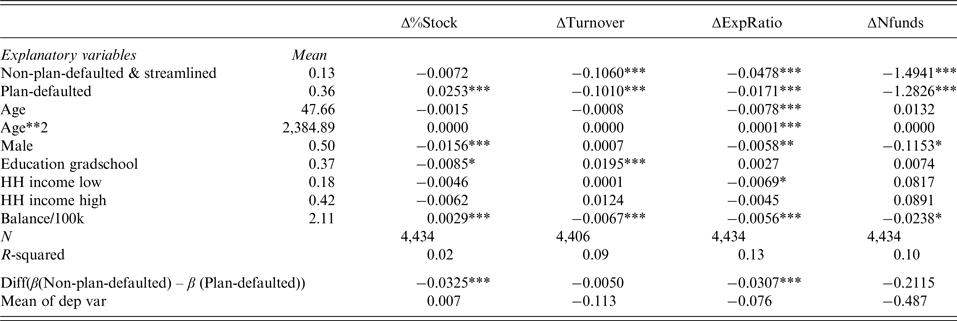
Table 8 compares the effects of the reform on participant portfolio turnover rates, expense ratios, number of funds held, and percentage allocation to stocks, in portfolios held by Streamlined versus Non-Streamlined participants. Panel A (B) reports model estimates for the shorter (longer) post-streamlining period.
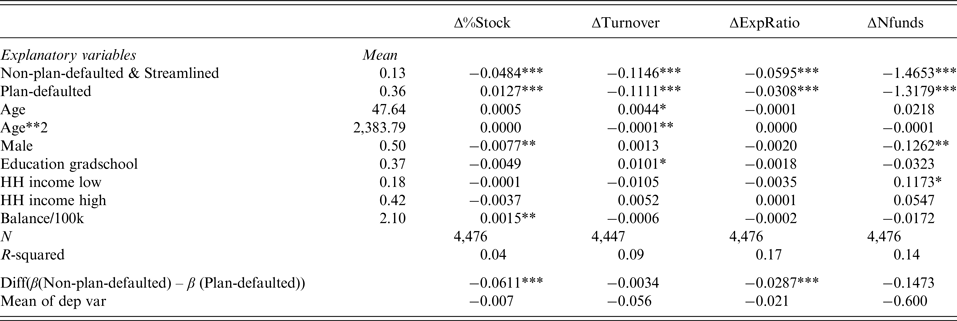
Over the shorter interval (Panel 8A), we find that, relative to Non-Streamlined participants, the Streamlined participants – both the Plan-Defaulted and those that were not defaulted – experienced significantly greater reductions in portfolio turnover, larger reductions in expense ratios, and a larger decline in the number of funds held. Moreover, these reductions were generally larger for the subset of Streamlined participants that were Not-Plan-Defaulted. For example, the reduction in the expense ratio was 6.0 (3.1) bps larger for the Not-Plan-Defaulted (Plan-Defaulted) Streamlined participants than for Non-Streamlined, and the difference of 2.9 bps is significant at the 0.01 level. This last result might be partly due to our inability to observe brokerage window transactions in which these Not-Plan-Defaulted participants might have replicated their prior fund allocations and associated higher expense ratios. That said, recall that very few Not-Plan-Defaulted participants opened brokerage accounts; and virtually none of the Plan-Defaulted participants opened brokerage accounts.
In contrast to the findings for the other characteristics in Table 8A, the changes in the percentage of the portfolio allocated to stocks over the shorter interval were markedly different for the Not-Plan-Defaulted and the Plan-Defaulted streamlined subsamples relative to their non-streamlined counterparts. Specifically, the Plan-Defaulted Streamlined participants significantly increased their stock allocations by 1.3% by the end of December 2012, while the Not-Plan-Defaulted Streamlined group experienced a statistically and economically significant 4.8% reduction in stock allocation as a result of the streamlining. This difference of 6.1% is statistically significant at the 0.01 level, and it is consistent with Table 6 where we found: (a) a significant reduction in stock and sector fund allocations by the Not-Plan-Defaulted Streamlined participants; and (b) a significant increased allocation by the Plan-Defaulted Streamlined participants to TDFs, which contain a much higher percentage of stocksFootnote 14 than the more conservative bond and balanced funds which they dropped, post- streamlining.
Changes in fraction of portfolio invested in stocks, annual turnover, expense ratios, and number funds held (end-December 2012 minus end-June 2012 balances)

Note: *p < 0.10, **p < 0.05, ***p < 0.01. Dependent variables as follows: Δ%Stock is the % of the participant's portfolio of funds invested in common stocks; ΔTurnover measures participant changes in overall annual portfolio turnover (post-pre); ΔExpRatio measures the change in annual participant expense ratios (post-pre) and Δ#funds measures the change in the number of funds held (post-pre). Values computed for each participant using end-December 2012 minus end-June 2012 balances.
Source: Authors’ calculations.
Changes in fraction of portfolio invested in stocks, annual turnover, expense ratios, and number funds held (end-December 2013 minus end-June 2012 balances)

Note: *p < 0.10, **p < 0.05, ***p < 0.01. Dependent variables as follows: Δ%Stock is the % of the participant's portfolio of funds invested in common stocks; ΔTurnover measures participant changes in overall annual portfolio turnover (post-pre); ΔExpRatio measures the change in annual participant expense ratios (post-pre) and Δ#funds measures the change in the number of funds held (post-pre). Values computed for each participant using end-December 2013 minus end-June 2012 balances. Source: Authors’ calculations.
We also find that the reductions in stock allocations and number of funds held were greater for men than for women, consistent with Barber and Odean's (Reference Barber and Odean2001) finding for discount brokerage accounts that individual male investors trade stocks more aggressively than do female investors.
The message of Panel 8B is simple: the changes in portfolio characteristics for the Streamlined participants caused by the reform that were evident over the shorter interval in Panel A largely persisted over the entire 2013 calendar year. That is, their desired portfolio reallocations were quickly established in response to the streamlining announcement, and those new allocations were left intact over the longer term. The one exception is that, during 2013, the Not-Plan-Defaulted Streamlined participants reversed the initial reduction in their stock market exposure (relative to the Non-Streamlined participants), so that by the end of 2013, their stock exposure was not significantly different than beforehand.Footnote 15 Otherwise, the initial effects of the reform (e.g., lower turnover and expense ratios) were not undone by Streamlined participant transactions over the subsequent 12 months.
Not only are these effects statistically significant: they are also economically important. That is, the (unconditional) average reduction in the annual expense ratio for the entire Streamlined group was 4.0 bp (=27.9 bp – 23.9 bp), or a $0.242 M annual cost savings (based on the pre-streamlining balance for the Streamlined group of $603.8 M at end-June 2012). Since the average age of the Streamlined participants was 49 in April 2012, if those savings could be achieved on an ongoing basis over 20 years and reinvested at 5% annually, the accumulated benefit would amount to $8.40 M or around $4,000 per participant. Additionally, the (unconditional) average decline in within-fund annual turnover for the Streamlined group was 11.3% (=35.2% – 23.9%). Based on the Streamlined group balance of $603.8 M at end-June 2012 and assuming round-trip within-fund transaction costs of 0.50%, this could translate into an annual aggregate cost savings of $0.341 M.Footnote 16 If such savings could be achieved on an ongoing basis over 20 years and reinvested at 5% annually, the accumulated additional benefit would be $11.8 M, or $5,400 per participant. In total, then, the per-participant savings could be over $9,400 per participant.
5.2 Changes in portfolio risks
We also examine how participant portfolio risks changed by comparing pre- versus post-streamlining positions. To this end, we first estimate the factor-related systematic risks and diversifiable (idiosyncratic) risks for both retained and deleted funds, using a model similar to Fama and French (Reference Fama and French1993) in which the estimated coefficients measure each fund's exposures to systematic factor risks:
 $$\eqalign{\tilde R_{it} - R_{Ft} & = \alpha + b_1(\tilde R_{Mt} - R_{Ft}) + b_2SmB_t + b_3HmL_t + b_4WmL_t + b_5Term_t + b_6Def_t \cr & \quad + \tilde e_{it}}$$
Here  $\tilde R_{it} - R_{Ft}$ refers to the excess return of fund i over the risk-free rate (the 1-month Treasury bill rate from Ibbotson Associates);
 $\tilde R_{Mt} - R_{Ft}$ refers to the value-weighted return on all NYSE, AMEX, and NASDAQ stocks (from CRSP) minus the risk-free rate; SmB refers to the difference in the performance of small relative to big stocks; HmL to the difference in performance of value stocks to growth stocks; WmL is a momentum factor premium measuring the difference in performance of past winner and past loser stocks (Carhart, Reference Carhart1997); Term measures the difference between the monthly long-term government bond return (from Ibbotson Associates) and the 1-month Treasury bill rate measured at the end of the previous month (from the Center for Research in Security Prices, CRSP); and Def measures the difference between the return on a market portfolio of long-term corporate bonds (the Composite portfolio in the corporate bond module of Ibbotson Associates) and the monthly long-term Treasury bond return. The fund's diversifiable (idiosyncratic) risk is measured as σ(e), the standard deviation of the regression residuals. These regressions are estimated using 10 years of monthly fund and factor returns.
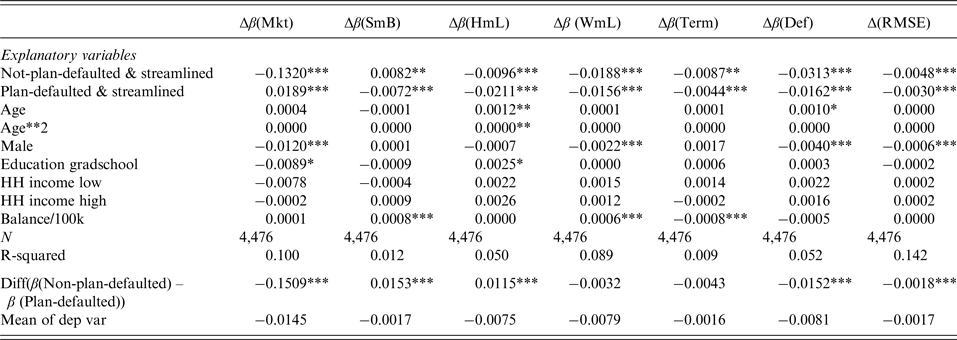
Having estimated the model parameters representing systematic and idiosyncratic risks, we next compute for each participant the systematic and idiosyncratic risks specific to his own portfolio, using his portfolio weights as of end-June 2012 and end-December 2012. Finally, we regress the post−pre changes in systematic and idiosyncratic risks on Not-Plan-Defaulted-Streamlined, Plan-Defaulted-Streamlined, and our control variables. Results appear in Table 9, where Panel A (B) reports model estimates for the shorter (longer) post-streamlining period.
Change in participant portfolio systematic and idiosyncratic risk exposures (end-December 2012 minus end-June 2012 balances)

Note: *p < 0.10, **p < 0.05, ***p < 0.01. Post-Pre dependent variables measured as follows: Δβ(Mkt) measures changes in participants’ exposure to market risk; Δβ(SmB) measures changes in participants’ exposure to the difference in performance of small relative to big stocks; Δβ(HmL) measures changes in participants’ exposure to the difference in performance of value stocks to growth stocks; Δβ(WmL) measures changes in participants’ exposure to the difference in performance of winner stocks to loser stocks; Δβ(Term) refers to changes in participants’ exposure to the difference between the long-term Treasury bond return and the 1-month Treasury bill rate measured at the end of the previous month; Δβ(Def) measures changes in participants’ exposure to the difference in return between a portfolio of long-term corporate bonds and the long-term Treaury bond; and ΔRMSE is the standard deviation of the residuals from the 6-factor model in section 5.2. Values are computed for each participant using end-December 2012 minus end-June 2012 balances. Source: Authors’ calculations; see variable descriptions in text.
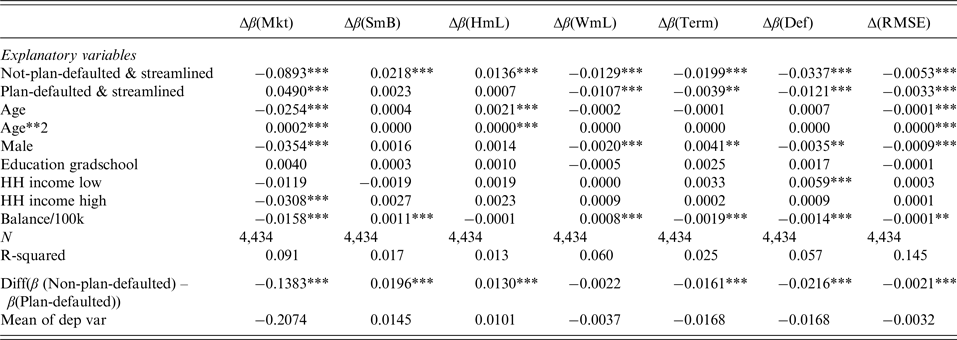
Change in participant portfolio systematic and idiosyncratic risk exposures (end-December 2013 minus end-June 2012 balances)

Note: *p < 0.10, **p < 0.05, ***p < 0.01. Post-Pre dependent variables measured as follows: Δβ(Mkt) measures changes in participants’ exposure to market risk; Δβ(SmB) measures changes in participants’ exposure to the difference in performance of small relative to big stocks; Δβ(HmL) measures changes in participants’ exposure to the difference in performance of value stocks to growth stocks; Δβ(WmL) measures changes in participants’ exposure to the difference in performance of winner stocks to loser stocks; Δβ(Term) refers to changes in participants’ exposure to the difference between the long-term Treasury bond return and the one-month Treasury bill rate measured at the end of the previous month; Δβ(Def) measures changes in participants’ exposure to the difference in return between a portfolio of long-term corporate bonds and the long-term Treaury bond; and ΔRMSE is the standard deviation of the residuals from the 6-factor model in Section 5.2. Values are computed for each participant using end-December 2013 minus end-June 2012 balances. Source: Authors’ calculations; see variable descriptions in text.
Panel A of Table 9 shows that, as a result of the reform, all Streamlined participants’ portfolios (both Plan-Defaulted and Not-Plan-Defaulted) generally exhibited significantly greater reductions in systematic risk relative to the Non-Streamlined participants. Stated differently, there was a larger reduction in portfolio ‘tilt’ toward most systematic sources of variation for the Streamlined participants. There are two exceptions. First, relative to the non-streamlined group, there was a significant increase in market beta for the Plan-Defaulted Streamlined participants, in contrast to the significant decrease in market beta for the Not-Plan-Defaulted Streamlined participants. This tracks the changes in broad stock market exposure for these two streamlined groups shown in Table 8. Second, and again relative to the non-streamlined group, we find a greater increase (reduction) in small-cap risk exposure for the Not-Plan-Defaulted (Plan-Defaulted) Streamlined participants. The reason for this difference is not entirely clear from Tables 6 and 8 where the stock exposures and allocations are reported with insufficient granularity to differentiate the presence of small- versus large-cap stocks. One possible explanation, though, is that many of the deleted sector and international funds, in which the Not-Plan-Defaulted Streamlined group had been invested, had much lower exposures to small-cap risk.
We also find that the reform resulted in a significant reduction in idiosyncratic risk for the Streamlined group relative to its Non-Streamlined peer group, and this reduction was even more notable for the Not-Plan-Defaulted members of the Streamlined group. Moreover, the reduction in idiosyncratic risk was greater for male versus female participants, as were reductions in exposures to the market and momentum stock risk factors, and the default risk bond factor. These last two findings in the retirement plan setting agree with Barber and Odean's results for online brokerage accounts. It is also worth pointing out that many of these changes in risk exposure were most pronounced for participants with larger, versus smaller, portfolio balances.Footnote 17
As was true for the observed portfolio characteristics discussed above, Panel B of Table 9 confirms that the Panel A shorter-period portfolio risk changes wrought by the reform persisted over the entire 2013 calendar year. One exception, consistent with our findings in Table 8, Panel B, is that the Not-Plan-Defaulted Streamlined participants slightly reversed their initial reduction in stock market exposure post-reform, although by the end of 2013 their market beta was still significantly smaller than before the streamlining. It is also worth noting that the reduction in idiosyncratic risk for both streamlined groups reported for the shorter interval remains significant over the longer interval, although the change was smaller. Thus the initial effects of the reform remained largely intact by the end of 2013.
To summarize the results in this section, the streamlining of the DC plan described here had a statistically significant and economically important impact on the characteristics and risk attributes of savers’ accounts. First, within-fund turnover in participants’ retirement portfolios (a significant cause of largely unseen transaction costs) and expense ratios were significantly reduced, thereby enhancing the performance of participants’ investments. This inference is consistent with much research showing that high fees and transactions costs (typically associated with active investment management) can erode the returns that mutual funds pass through to investors (e.g., Fama and French Reference Fama and French2010; Barras et al., Reference Barras, Scaillet and Wermers2010). Recent investor trends in the mutual fund industry appear to reflect this adverse effect of excessive costs and fees – for example, during the first 11 months of 2016, passive US mutual funds saw a net cash inflow of $429 billion, compared with a $285 billion net cash outflow from actively managed US mutual funds (Dietrich, Reference Dietrich2016). Second, the reduction in idiosyncratic risk is also beneficial to participants, an indication that their portfolios are less exposed to unnecessary risks that are diversifiable. Of course, the reduced amount of idiosyncratic risk that we report relies on the assumption that our model of systematic risks is reasonably specified. It is reassuring that much academic research in financial economics confirms the efficacy of the empirical model we employ, even though the existence of a ‘correct’ model remains an open issue. Last, in that the changes in systematic risks that we document are compensated with corresponding changes in expected returns, it is less clear how such changes affect participants’ welfare which will, in the end, be a function of their individual risk preferences. In sum, our results complement and extend previous studies suggesting that plan simplification enhances retirement saving (e.g., Beshears et al., Reference Beshears, Choi, Laibson and Madrian2013), though previous work has focused only on participation and contributions and not on asset allocation outcomes as here.
6 Conclusions
This study has examined the salutary effects of streamlining the DC fund menu by deleting some funds and tiering options in an easier-to-understand format. While recent studies have evaluated how simplification can influence retirement plan participation and contributions, they have not examined how streamlining changes investment patterns. Our analysis examines how halving the fund menu while including a new brokerage account changed investment behavior at a large nonprofit institution. We find that participants who initially held at least one deleted fund were relatively older, more likely to be male, and earned higher incomes; they also held higher balances in riskier funds and lower balances in safer/balanced/TDFs. Interestingly, in response to the changed lineup, only 9% of these participants moved money into the new brokerage window, taking only 0.4% of assets. Moreover, Streamlined participants’ new allocations included significantly fewer funds and had significantly lower exposure to non-market systematic risks; they also contained a lower allocation to stocks. Streamlined participants’ new allocations also led to fund holdings with significantly lower expense ratios and within-fund turnover rates, which, based on reasonable assumptions, could lead to potential accumulated savings for these participants over a 20-year period of $20.2 M, or over $9,400 per participant.
The changes we have discerned are important, particularly given regulators’ growing interest in retirement plan fees and costs, and the growing number of lawsuits citing excessive number of fund options and high fees being brought against 401(k) and 403(b) plans.Footnote 18 As one example, US Department of Labor guidance to plan participants alerts members to the possibility that costs may rise as investment options become more numerous.Footnote 19 Such costs, in turn, can reduce the size of the nest egg available for retirement. Additionally, employers in their plan fiduciary capacity are charged under pension law with managing retirement plans in the best interests of participants.Footnote 20 Our work implies that plan sponsors would do well to recognize that the length and complexity of their plan menus matter. Accordingly, our results should be of substantial interest to those seeking to improve DC retirement plan design, including employers, fund providers, consultants, and regulators.