




No CrossRef data available.
Article contents
TESTING FOR COINTEGRATION IN NONLINEAR SMOOTH TRANSITION ERROR CORRECTION MODELS
Published online by Cambridge University Press: 09 February 2006
Abstract
This paper proposes a new testing procedure to detect the presence of a cointegrating relationship that follows a globally stationary smooth transition process. In the context of nonlinear smooth transition error correction models (ECMs) we provide two simple operational versions of the tests. First, we obtain the associated nonlinear ECM-based tests. Second, we derive the nonlinear analogue of the residual-based test for cointegration in linear models. We derive the asymptotic distributions of the proposed tests. Monte Carlo simulation exercises confirm that our proposed tests have much better power than the linear counterparts against the alternative of a globally stationary nonlinear cointegrating process. In an application to the price-dividend relationship, our test is able to find cointegration, whereas the linear-based tests fail to do so.We are grateful to an associate editor, two anonymous referees, Richard Baillie, In Choi, Atanas Christev, Hira Koul, Richard Harris, Cheng Hsiao, Changjin Kim, Joon Park, Peter Schmidt, Yoonjae Whang, Jeff Wooldridge, and seminar participants at University of Edinburgh, Heriot-Watt University, Korea University, University of Leeds, Michigan State University, University of Newcastle, and Sungkunkwan University for their helpful comments. Partial financial support from the ESRC (grant R000223399) is gratefully acknowledged. The usual disclaimer applies.
Information
- Type
- Research Article
- Information
- Copyright
- © 2006 Cambridge University Press
1. INTRODUCTION
The joint investigation of nonstationarity and nonlinearity in economics has recently assumed great significance. There has also been increasing concern that the information revealed by the analysis of a linear time series model may be insufficient to give definitive inference on important economic hypotheses. In this regard attention has fallen almost exclusively on regime-switching-type models, though there is no established theory suggesting a unique approach for specifying econometric models that embed various types of change in regimes.
Estimation of cointegrated models subject to (regime-switching) nonlinear dynamics has been quite prominent. Balke and Fomby (1997) have popularized an estimation method where the dynamics are subject to three-regime threshold cointegration, the case where a process may follow a unit root in a middle regime while at the same time being globally geometrically ergodic. Another popular nonlinear scheme being applied in conjunction with cointegration is based on the smooth transition regression (STR), following Granger and Teräsvirta (1993). Michael, Nobay, and Peel (1997) analyze nonlinearity in the long-run purchasing power parity (PPP) relationship by adopting a null of a unit root for real exchange rates while taking an alternative hypothesis of nonlinear smooth transition autoregressive (STAR) stationarity. Finally, Psaradakis, Sola, and Spagnolo (2004) consider Markov-switching error correction models (ECMs) in which deviations from the long-run equilibrium follow a process that is nonstationary in one state of nature and mean-reverting in the other. These papers argue forcefully that the assumption of linear adjustment is likely to be too limited in various economic situations, particularly where transaction costs and policy interventions are present. For similar modeling approaches see Granger and Swanson (1996), Corradi, Swanson, and White (2000), Choi and Saikkonen (2004), and Saikkonen and Choi (2004).
With regard to statistical inference, there is a large literature proposing tests for unit roots against threshold autoregressive (TAR) alternatives, e.g., Enders and Granger (1998), Caner and Hansen (2001), Bec, Guay, and Guerre (2004), and Kapetanios and Shin (2006). In particular, Kapetanios, Shin, and Snell (2003) develop the testing framework for a linear unit root null against an exponential STAR alternative and show that their proposed test is more powerful than the Dickey–Fuller (1979) test. See also Kiliç (2003) for its bootstrap-based extension. There is also a growing literature analyzing cointegration subject to nonlinear dynamic adjustment, e.g., Escribano and Pfann (1998), Escribano and Mira (2002), Bec and Rahbek (2004), Escribano (2004), and Saikkonen (2005).
However, studies that directly specify and derive the asymptotic properties of cointegration tests against nonlinear alternatives are still relatively few. For example, although Gallagher and Taylor (2001) and Hansen and Seo (2002) conduct cointegration analysis with nonlinear alternatives in mind, they all adopt linear cointegration tests to establish the existence of cointegration and only allow nonlinearity to enter the analysis at the estimation stage once cointegration has been established. Although such linear tests will have power against nonlinear alternatives, it seems far more sensible to use a test in the first stage that is designed to have power against the alternative of interest, namely, nonlinear dynamic adjustment.
In this paper we address this issue by deriving a cointegration test designed to have power against alternatives where the cointegrating error is stationary and follows STR dynamics. We model an equilibrium process where its error correction adjustment is slower when the cointegrating residual is close to zero and where the change in speed of this adjustment process is assumed smooth rather than sharp (as with TAR models). Therefore, we focus on the case in which the EC term follows a globally stationary process under the STR alternative. In particular, our approach is motivated by the implication of economic theory applied to asset arbitrage under noise trading and transaction costs arising from the bid-ask spread. Campbell and Kyle (1993) develop a model of finite-lived traders some of whom misperceive true fundamental asset values and show that the larger are the pricing errors in these models, the larger is the expected degree of arbitrage and hence the speedier is the price response to disequilibrium. Snell and Tonks (2003) show that in an adapted version of the sequential auction model of Kyle (1985) where informed agents who suffer liquidity costs trade with a risk neutral market maker, the prices offered by the market maker follow an ECM with a speed of adjustment parameter that moves smoothly in response to the conditional variance of the disequilibrium price error. To put it more concisely, higher disequilibrium pricing errors are associated with larger ECM adjustment parameters and faster rates of error correction toward equilibrium.
Using a general nonlinear exponential STR (ESTR) ECM framework and following a pragmatic residual-based two-step procedure in the style of Engle and Granger (1987), we propose that a null hypothesis of no cointegration against an alternative of a globally stationary ESTR cointegration be tested directly by examining the significance of the parameter controlling the degree of nonlinearity in the speed of adjustment. We develop two operational test statistics, denoted FNEC (tNEC) and tNEG, respectively, and derive their asymptotic distributions. The FNEC (tNEC) test refers to the F-type (t-type) statistic obtained directly from the nonlinear ESTR error correction regression, whereas the tNEG test is the nonlinear analogue to the Engle and Granger (EG) statistic for linear cointegration.
The small-sample performance of the suggested tests is compared to that of the linear EG and Johansen (1995) tests via Monte Carlo experiments. We find that our proposed nonlinear tests have good size and superior power properties compared to the linear tests. In particular, both the FNEC and tNEC tests are superior to both linear or nonlinear EG tests when the regressors are weakly exogenous in a cointegrating regression. This supports similar findings made in linear models by Kremers, Ericsson, and Dolado (1992), Hansen (1995), Banerjee, Dolado, and Mestre (1998), Arranz and Escribano (2000), and Pesaran, Shin, and Smith (2001) that the EG test loses power relative to ECM-based cointegration tests because of the loss of potentially valuable information from the correlation between the regressors and the underlying disturbances.
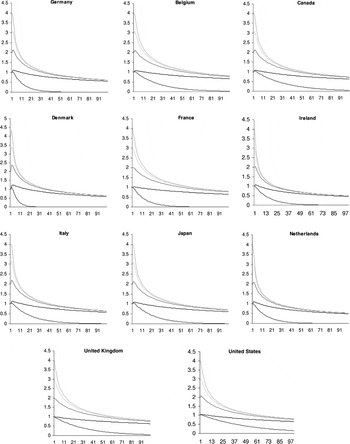
We provide an application to investigating the presence of cointegration of asset prices and dividends for eleven stock portfolios (Germany, Belgium, Canada, Denmark, France, Ireland, Italy, Japan, Netherlands, United Kingdom, and United States) allowing for nonlinear STR adjustment to equilibrium. Interestingly, our new tests are able to reject the null of no cointegration in majority cases, whereas the linear EG test rejects only twice. Given the strength of evidence in favor of ESTR cointegration we also estimate adjustment parameters under the alternative, and we find that these estimates are well defined in all cases. We further evaluate the impulse response functions (IRFs) of the error correction term with respect to initial impulses of one to four standard deviation shocks. The striking finding is that the time taken to recover one-half of a one standard deviation shock varies between 5 and 20 years, whereas the time taken to recover one-half of larger shocks varies between just 4 to 18 months. This implies that data periods dominated by extreme volatility may display substantial reversion of prices toward their NPV (net present value) relationship, although in “calmer” times where the error in the NPV relationship takes on smaller values, the process driving it may well look like a unit root.
The plan of the paper is as follows. Section 2 discusses general modeling issues and derives the nonlinear STR error correction models. Section 3 develops the proposed test statistics and derives their asymptotic distributions. Section 4 evaluates the small-sample performance of the proposed tests that take account of the STR nonlinear nature of the alternative. Section 5 presents an empirical application to price-dividend relationships. Section 6 contains some concluding remarks. Mathematical proofs are collected in the Appendix.
2. NONLINEAR STR ERROR CORRECTION MODELS
We begin with the following general nonlinear vector error correction (VEC) model for the n × 1 vector of I(1) stochastic processes, zt:
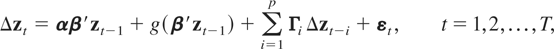
where α(n × r), β (n × r), and Γi (n × n) are parameter matrices with α and β of full column rank and

is a nonlinear function. A conventional linear VEC model is obtained by choosing g(β′zt−1) = 0 or g(β′zt−1) = −αμ′ where μ is an n × 1 vector of level parameters.
Recently, analogues of Granger's representation theorem have been studied in the context of the nonlinear VEC model, (2.1), e.g., Escribano and Mira (2002) and Bec and Rahbek (2004). Here we follow Saikkonen (2005) and make the following assumption.
Assumption 1. (i) The errors εt in (2.1) are iid(0, Σ), with Σ being an n × n positive definite matrix and E|εt|[ell ] < ∞ for some [ell ] > 6. (ii) The distribution of εt in (2.1) is absolutely continuous with respect to the Lebesgue measure and has a density that is bounded away from zero on compact subsets of

. (iii) The initial observations Z0 ≡ (z−p,…,z0) are given. (iv) Let A(z) be given by
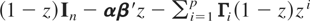
. If det A(z) = 0, then |z| > 1 or z = 1, where the number of unit roots is equal to n − r. (v) g([bull ]) is asymptotically no greater than a linear function of xt.
Assumptions 1(i)–(iv) are standard in the cointegration literature, whereas Assumption 1(v) is imposed to deal with nonlinearity of the underlying model (2.1). Under Assumption 1, Saikkonen (2005, Thm. 2) proves that there exists a choice of initial values z−p,…,z0 such that Δzt and β′zt−1 are strictly stationary.
In this paper we aim to analyze at most one conditional long-run cointegrating relationship between yt and xt, and we focus on the conditional modeling of the scalar variable yt given the k-vector xt (k = n − 1) and the past values of zt and Z0, where we decompose zt = (yt,xt′)′. For this we rewrite (2.1) as
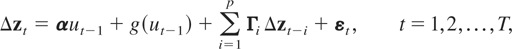
where α is an n × 1 vector of adjustment parameters and

with βx being a k × 1 vector of cointegrating parameters.
We now make the following assumption.
Assumption 2. (i) The nonlinear function g(·) in (2.2) follows the exponential smooth transition functional form

where we assume θ ≥ 0 for identification purposes and c is a transition parameter. (ii) Partition α = (ζ, αx′)′ and φ = (γ, φx′)′ conformably with zt = (yt,xt′)′. Then, αx = φx = 0. (iii) There is no cointegration among the k-vector of I(1) variables, xt. (iv) ζ < 0.
Assumptions 2(ii) and (iii) imply that the process xt is weakly exogenous and therefore the parameters of interest in (2.6) are variation-free from the parameters in (2.7), e.g., Pesaran et al. (2001). Assumptions 2(i) and (iv) imply that Assumption 1(v) is satisfied but also ensure that the underlying (nonlinear) error correction mechanism in (2.2) is globally stationary. In practice various functional forms of g([bull ]) can also be considered to allow for the presence of nonlinear adjustment to the error correction mechanism, but we focus on ESTR here.
Next, partitioning εt conformably with zt as εt = (εyt, εxt′)′ and its variance matrix as
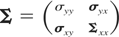
, we may express εyt conditionally in terms of εxt as
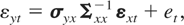
where et ∼ iid(0,σe2), σe2 ≡ σyy − σyx Σxx−1σxy, and et is uncorrelated with εxt by construction. Substituting (2.5) and (2.4) into (2.2), partitioning Γi = (γyi′, Γxi′)′, i = 1,…,p, defining φ = ζ − γ, and under Assumption 2, we obtain the following conditional exponential smooth transition regression error correction model (STR ECM) for Δyt and the marginal vector autoregression (VAR) model for Δxt:1
The exponential transition function in (2.6) is bounded between zero and 1, i.e.,

has the properties F(0) = 0; limx→±∞ F(x) = 1, and is symmetrically U-shaped around zero.
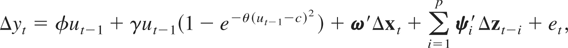
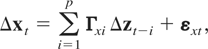
where ω ≡ Σxx−1σxy and ψi′ ≡ γyi − ω′Γxi, i = 1,…,p. We notice that (2.6) is a reparameterization of (2.2) under Assumption 2, which will become more convenient for the construction of the cointegration tests we propose in the next section, and Assumption 2(iv) implies that φ + γ < 0. See also Kapetanios et al. (2003).
We call (2.6) the (conditional) nonlinear STR ECM. The representation (2.6) makes economic sense in that many economic models predict that the underlying system tends to display a dampened behavior toward an attractor when it is (sufficiently far) away from it but shows some instability within the locality of that attractor. We note in passing that Assumption 1 is trivially satisfied for our final model specifications (2.6) and (2.7). Therefore, applying Saikkonen's Theorem 2 directly to our model, we may conclude that there exists a choice of initial values z−p,…,z0 such that ut−1 and Δzt are strictly stationary.2
Kapetanios et al. (2003) show that the ut(= yt − βx′xt) are geometrically ergodic so long as φ + γ < 0 in the univariate context where the cointegrating parameters βx are assumed given.
For a growing literature on the joint analysis of cointegration and STR models see also Gallagher and Taylor (2001), van Dijk, Teräsvirta, and Franses (2002), Choi and Saikkonen (2004), and Saikkonen and Choi (2004). In practice different lag orders for Δyt and Δxt in (2.6) can be selected using standard model selection criteria or significance testing procedures without loss of generality or change in the asymptotic analysis, e.g., Ng and Perron (1995).
3. TESTING FOR NONLINEAR COINTEGRATION UNDER STR ECM
To fix ideas for the motivation of the tests, we follow Kapetanios et al. (2003) and impose φ = 0 in (2.6), implying that ut follows a unit root process in the middle regime; see also Balke and Fomby (1997) in the context of threshold ECMs. Note that for the operational versions of the tests we suggest later we consider both the case φ = 0 and φ ≠ 0. It is then straightforward to show that the test of the null of no cointegration against the alternative of globally stationary cointegration can be based on the single parameter θ. Hence, we set the null hypothesis of no cointegration as3
The null and alternative are expressed alternatively as H0 : θγ = 0 and H1 : θγ < 0. This formulation clearly shows the lack of identification of either θ or γ when the other is zero. It also makes it clearer why we will develop t- or F-type tests that do not depend on the value of the unidentified parameter.

against the alternative of nonlinear ESTR cointegration of H1 : θ > 0, where the positive value of θ determines the stationarity properties of ut. We note in passing that the null hypothesis implies in terms of the preceding model that φ = 0 and θ = 0. Under the alternative hypothesis ut follows a nonlinear but globally stationary process as described in Section 2.
We propose a number of operational versions of the cointegration test under the nonlinear STR ECM framework given by (2.6). To this end we follow Engle and Granger (1987) and take a pragmatic residual-based two-step approach. In the first stage, we obtain the residuals,
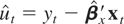
, with

being the ordinary least squares (OLS) estimate of βx. In the second stage and to overcome the Davies (1987) problem that γ in (2.6) is not identified under the null, we follow Luukkonen, Saikkonen, and Teräsvirta (1988) and Kapetanios et al. (2003), approximate (2.6) by a first-order Taylor series approximation to (1 − e−θ(ut−1−c)2), while allowing φ ≠ 0 under the alternative hypothesis, and obtain the following auxiliary testing regression:
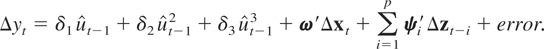
For this model, we consider an F-type test for δ1 = δ2 = δ3 = 0 given by
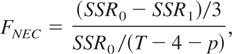
where SSR0 and SSR1 are the sum of squared residuals obtained from the specification with and without imposing the restrictions δ1 = δ2 = δ3 = 0 in (3.2), respectively. It is interesting to note that (3.2), which is called the cubic polynomial nonlinear error correction (NEC) model, has been analyzed by Escribano (1986, 2004) and his coauthors for the estimation of the UK money demand function although it is important to add that these authors did not provide the formal testing framework that we give in this paper.
There are prior theoretical justifications for restricting the switch point, c, to be zero in many economic and financial applications in the ESTR function, in which case we obtain the following (restricted) auxiliary testing regression:
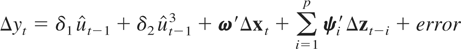
and obtain the following F-type statistic:
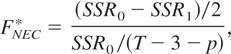
where SSR0 and SSR1 are the sum of squared residuals obtained from the specification with and without imposing δ1 = δ2 = 0 in (3.4), respectively.
Finally, under the further assumption that φ = 0 (which is the maintained assumption made in Kapetanios et al., 2003) (3.4) is simplified to

For this model, we propose a t-type statistic for δ = 0 (no cointegration) against δ < 0 (ESTR cointegration), which is given by
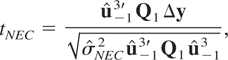
where
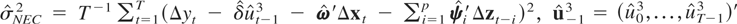
,
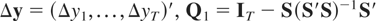
is the T × T idempotent matrix, S = (ΔX,ΔZ−1,…,ΔZ−p) is the T × (k + p(k + 1)) data matrix with ΔX = (Δx1,…,ΔxT)′ and ΔZ−i = (Δz1−i,…,ΔzT−i)′, i = 1,…,p, and
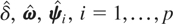
, are the OLS estimates of δ, ω, ψi in (3.6).
Alternatively and in keeping with the tradition in linear cointegration, we propose a companion test statistic, one that is the analogue to the EG statistic for linear cointegration, which is obtained by estimating the following approximate regression:

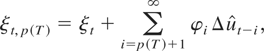
where
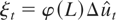
is the error term associated with an infinite autoregressive (AR) representation of
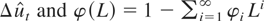
, e.g., Phillips and Ouliaris (1990, (A.14)). This is so even if the underlying process zt follows a finite-order VAR(p) model with p ≥ 2. Hence we now need to allow p(T) to tend to grow with T for consistent estimation of (3.8). We follow Phillips and Ouliaris (1990) and impose the condition p(T) = o(T1/3),
4This upper bound follows from Berk (1974), who shows that this bound is sufficient for the second sample moment matrix to converge to its population counterpart in norm. Therefore, for consistent estimation it is sufficient to impose this upper bound. See also Said and Dickey (1984).
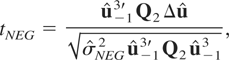
where
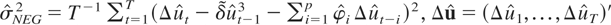
,
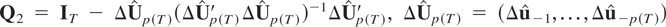
,
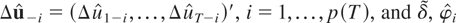
are the OLS estimates of δ and φi in (3.8).
The main asymptotic distributional results for all these tests are described in Theorem 3.1 under the following additional assumption.
Assumption 3. Partition Γxi = (γxyi′, Γxxi′)′ in (2.7) conformably with zt = (yt,xt′)′ and set γxyi = 0.
This assumption states that Δyt does not Granger cause Δxt. Under Assumptions 1(i) and (ii), 2(i) and (ii), and 3, the well-known multivariate invariance principle holds for et and εxt:
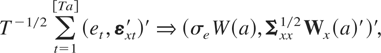
where [Ta] is the integer part of Ta, ⇒ denotes a weak convergence, and W(a) and Wx(a), defined on a ∈ [0,1], are independent scalar and k-vector standard Brownian motions. Without Assumption 3, W(a) and Wx(a) are no longer independent under the null of no cointegration because the weak exogeneity assumption guarantees only that
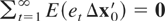
, but not that
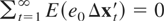
, and therefore the long-run correlation between the partial sums of et and Δxt is possibly nonzero. See also Banerjee et al. (1998) and Pesaran et al. (2001). At the end of this section we discuss a standard extension to the testing procedures that allows us to relax this assumption without affecting asymptotic results.
THEOREM 3.1. Consider the conditional nonlinear ESTR ECM, (2.6), and let Assumptions 1–3 hold. Under the null hypothesis of no cointegration, the FNEC statistic, defined by (3.3), has the following asymptotic distribution:

where B and W are shorthand notations for
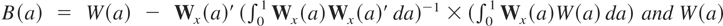
defined on a ∈ [0,1]. Next, imposing c = 0 and under the null of no cointegration, the FNEC* statistic defined by (3.5) has the following asymptotic distribution:

Further, imposing both φ = 0 and c = 0, and under the null of no cointegration (3.1), the tNEC and tNEG statistics defined by (3.7) and (3.10) have the following asymptotic distributions, respectively:5
It is worth noting that the asymptotic distribution of the tNEC statistic is free of any nuisance parameters as proved in the Appendix. In the literature it is well established that the limiting null distribution of an ECM t-test depends on the signal-to-noise ratio, though this dependency is due to the use of known cointegrating parameters. It has been proved in linear models that an ECM t-test obtained using the residuals is free of any nuisance parameters, and a formal proof of this is available upon request.
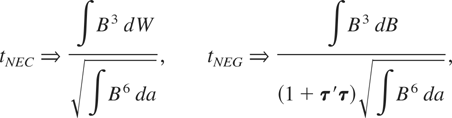
where
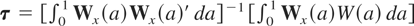
. Under the alternative hypothesis that the cointegrating relationship follows ESTR, all the tests are consistent.
To accommodate deterministic components in (2.3), we extend to consider regressions with an intercept and with an intercept and a linear time trend,

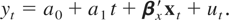
Alternatively, we take a simpler but equivalent approach and reexpress (3.15) and (3.16) as
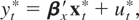
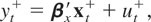
where the superscripts * and + indicate the demeaned and the detrended data, respectively. The respective FNEC, FNEC*, tNEC, and tNEG statistics are then obtained as follows. First, the appropriate residuals are obtained from either (3.17) or (3.18), and then the corresponding regressions are constructed. For example, we have
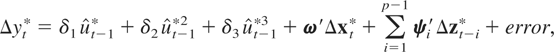
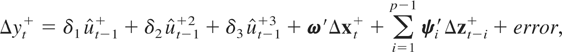
where
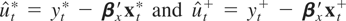
. Then, the FNEC statistics are obtained as the F-statistic for δ1 = δ2 = δ3 = 0 in (3.19) or (3.20), respectively. The corresponding FNEC*, tNEC, and tNEG statistics are obtained in an analogous way. For the regression with a nonzero intercept, (3.15), it is easily seen that the asymptotic distributions of the FNEC, FNEC*, tNEC, and tNEG statistics are the same as in Theorem 3.1, except that W(a) and Wx(a) are replaced by the demeaned Brownian motions, denoted
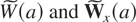
. Similarly, for the regression with nonzero intercept and nonzero linear trend coefficient, (3.16), the associated asymptotic distributions are such that W(a) and Wx(a) are replaced by the demeaned and detrended Brownian motions, denoted
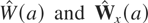
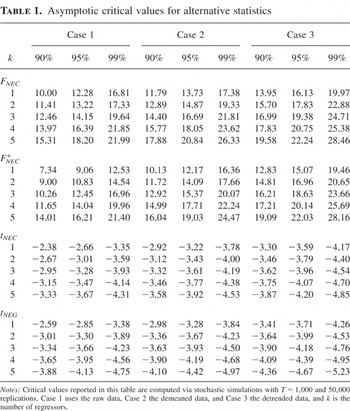
. Asymptotic critical values of the FNEC, FNEC*, tNEC, and tNEG statistics for the preceding three cases have been tabulated for k = 1,…,5, via stochastic simulations with T = 1,000 and 50,000 replications in Table 1.
Asymptotic critical values for alternative statistics

We comment on one further modeling issue. An alternative popular nonlinear STR adjustment scheme to the one favored in this paper is given either by the first-order logistic function, 1 − b/(1 + exp(−θut−1)), or by the second-order logistic function, 1 − b/(1 + exp(−θut−12)), where b < 1 is a scaling constant. We note that the resulting t-type tests against the alternative of the second-order logistic function have exactly the same form as in (3.7) and (3.10). It is also easily seen that adopting the first-order Taylor approximation to the first-order logistic terms as we did before gives the regression
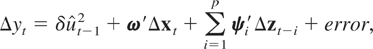
and we could develop a t-type test for δ = 0 in (3.21). Though the asymptotics for this case are straightforwardly obtained via a simple extension of the analysis in this paper, the interpretation of the error correction coefficient in the first-order logistic STR error correction model is problematic. By contrast, in the exponential case the interpretation of this coefficient is both natural and intuitive (for a discussion of this point, see Kapetanios et al., 2003). Therefore, we focus on the exponential case.
Finally, we comment on how to relax Assumption 3 in practice. To purge the potentially nonzero long-run correlation between the partial sums of et and Δxt, we should augment our conditional model (2.6) with leads of Δxt, as is standard in the cointegration literature; see, e.g., Banerjee et al. (1998) and Saikkonen (1991). Then, following Theorem 4.1 of Saikkonen (1991), it is readily seen that the limit distribution of these ECM-based tests will be identical to those derived in Theorem 3.1, under the further condition that the number of leads grows at a rate less than T1/3. We also notice that the asymptotic result for the tNEG test in this situation would be intact too.
4. FINITE-SAMPLE PROPERTIES
In this section we undertake a small-scale Monte Carlo investigation of the finite-sample size and power performance of our proposed tNEC, tNEG, FNEC, and FNEC* tests in conjunction with the linear cointegration tests of Engle and Granger and Johansen denoted tEG and JOH, respectively.
We consider experiments based on a bivariate ECM similar to that adopted by Arranz and Escribano (2000). We generate the data as follows:
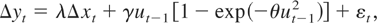
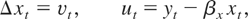
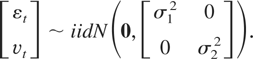
Here we fix βx = 1 and σ12 = 1. In the tabulated experiments we fix φ = 0 but also discuss (rather than tabulate) results for nonzero φ. Under the null we set θ = 0, whereas we consider parameter values for θ = {0.01, 0.1, 1} and γ = {−1,−0.5,−0.3,−0.1} under the alternative. To investigate the impact of the common factor (COMFAC) restriction, λ = 1 and the impact of different signal-to-noise ratios we consider different parameter values for λ = {0.5,1} and σ22 = {1,4}.
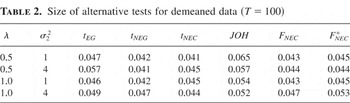
To save space we only report the results for the demeaned case (see (3.17)) with T = 100.6
Overall simulation results for the different sample sizes and for the detrended data are qualitatively similar to the main findings reported in the paper and are available upon request.
Size of alternative tests for demeaned data (T = 100)

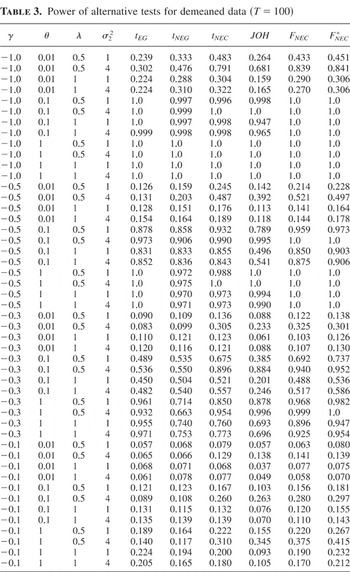
Turning to the power performance of the tests, which is summarized in Table 3, a general finding is that nonlinear-based tests dominate linear counterparts in terms of power for almost all cases considered. As expected, the power gain of our suggested NEC-based tests over the nonlinear analogue of the EG test becomes substantial where the COMFAC restriction (λ = 1) does not hold. The result that when the COMFAC restriction is violated the power superiority of tNEC over tNEG increases with the variance of the innovation in x is both intuitive (a higher variance increases the correlation with the regression error) and a reiteration of what is now well known to occur in the linear case.
Power of alternative tests for demeaned data (T = 100)

Next, we focus on the results for θ = 0.01, because this value is found to be close to empirically plausible estimates.7
Notice in our application that the estimates of θ (which we obtain under the constraint that γ = −1 for convenience; see also Taylor, Peel, and Sarno, 2001) indeed range between 0.007 and 0.017. In general, it is hard to get an exact definition of “small” and “large” θ because it is not a scale-free parameter. But it is easily seen that given the values of σ2 and γ, as θ grows, the ut becomes less persistent, where we note that the term e−θut−12 here measures the root of the series at time t. For example, we find via simulation that for σ2 = 1 and γ = −1 with T = 1,000, the average sample values of e−θut−12 are 0.95, 0.83, and 0.34 for θ = 0.01, 0.1, and 1, respectively.
5. EMPIRICAL APPLICATION TO ASSET PRICING IN THE PRESENCE OF TRANSACTIONS COSTS
In a seminal paper, Campbell and Shiller (1987) investigate the existence of linear cointegration between aggregate U.S. stock prices and U.S. dividends, as predicted by a simple equilibrium model of constant expected asset returns. Their results were ambiguous. A null hypothesis of no (linear) cointegration was marginally rejected in their data, but the implied estimate of long-run asset returns was implausible. Imposing a more credible long-run return caused nonrejection of the null of no cointegration. Subsequent literature has met with similar mixed results, e.g., Campbell and Shiller (1988), Froot and Obstfeld (1991), and Cuthbertson, Hayes, and Nitzsche (1997).
In this section we apply our proposed tests for cointegration to asset prices and dividends for 11 stock portfolios allowing for nonlinear adjustment to equilibrium of the STR variety. The theoretical motivation for STR nonlinearity has already been given in the introduction, and we reemphasize that theoretical reasoning suggests that it is STR adjustment rather than threshold adjustment that is likely to arise in our current application.8
There is also some simulation evidence that shows that even if bid-ask spreads are fixed, aggregation across assets with different fixed spreads will in fact lead to STR-type rather than TAR-type dynamic adjustment.
We collected monthly data from January 1974 to November 2002 on end period real prices and within period real dividend yields for value weighted market portfolio indexes of stocks traded on the main exchanges of the following 11 countries: Germany, Belgium, Canada, Denmark, France, Ireland, Italy, Japan, Netherlands, United Kingdom, and United States. A dividend series was constructed as the product of dividend yield and prices. Although not presented here, augmented Dickey–Fuller (ADF) tests give overwhelming support to the hypothesis that all variates are I(1).
As alluded to before, we test for the existence of a linear cointegrating relationship between dividends and prices of the form
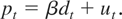
The existence of bid-ask spreads discussed previously motivates the following nonlinear dynamic STR ECM specification:
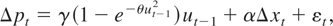
where ut−1 = pt−1 − βdt−1 and εt is a (possibly autocorrelated) error term that captures other microstructure effects such as specific kinds of noise trading and dealer inventory control mechanisms whereby the adjustment of prices to elicit inventory-correcting trades generates autocorrelated price movements, e.g., Snell and Tonks (1998).
We computed three tests. The first two, tEG and tNEG, are the linear EG test and its nonlinear counterpart. The third, tNEC, is the t-ratio on

in the STR ECM formulation (see (3.6)) where

is the residual from the first stage (spurious under the null) regression of pt on dt. The price and dividend series appeared to have an upward trend so that all series were demeaned and detrended before use.
9The issue of whether or not stock prices and dividends contain a deterministic time trend is contentious. However, there is a clearly discernible trend in both dividends and prices in our data, and hence we detrend. It is comforting to note that if we only demean, the results are qualitatively almost identical.
We should note that although further exploration revealed some significant lags beyond twelfth order, the test statistics were not in general very sensitive to the choice of lag length.
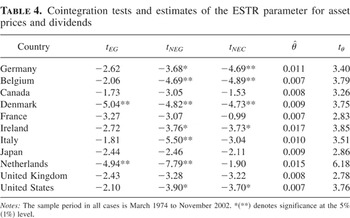
The results for the tests are in columns 2–4 in Table 4. Looking at the results we see that viewed through the “eyes” of linear cointegration tests there is little support for the hypothesis that dividends and prices move together in the long run, with only two of the tEG tests rejecting the null, albeit at the 1% level. Furthermore, none of the remaining nine tEG statistics are significant even at the 10% level. By contrast the nonlinear tNEG test rejects in seven out of eleven stock markets with four of these rejections occurring at the 1% level. A further three statistics are quite close to the 10% critical value. The success in rejecting the null of no cointegration is less marked for tNEC, with only five rejections at standard significance levels, although three of these reject also at the 1%. A further two tNEC statistics are quite close to the 10% critical value. If the alternative is really true then we could interpret this finding as being somewhat at odds with the Monte Carlo evidence presented before, which generally shows that tNEC has more power than tNEG. One possible explanation is that prior empirical investigation of the data suggested that the COMFAC restriction may hold here. If true, a bivariate ECM would lack parsimony compared with the univariate specification, and this may lead to a loss in power when moving from tNEG to tNEC.
Cointegration tests and estimates of the ESTR parameter for asset prices and dividends

Given the strength of evidence against the null and support for the alternative we could obtain estimates of adjustment parameters under the alternative. Focusing on the univariate model we obtained nonlinear least squares estimates of θ from the alternative ESTR model,
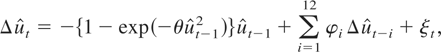
where the model has been specialized compared with the general ESTR considered previously by imposing a unit coefficient on γ. Early attempts to estimate γ jointly with θ foundered on severe identification problems, and our nonlinear algorithm failed to converge in most cases—hence the specialization. Under the alternative (and estimation of (5.3) only makes sense if the alternative is true), θ is scale dependent. To clarify its interpretation and to facilitate numerical convergence, we normalized the

series to have unit sample variance (a procedure that only makes sense under the alternative). The results for

and its t-statistic are given in Table 4. Although we cannot interpret the t-statistic as a significance from zero test (for obvious reasons) we refer to it as “significant” if an asymptotic 95% confidence interval around the estimate excludes zero. We see that

is “significant” in all cases and varies between 0.007 and 0.017.
To get a feel for what such values imply, Figure 1 plots IRFs for the error correction term for initial impulses of one, two, three, and four standard deviation shocks, respectively. To be explicit, we take the univariate specification in (5.3) and perturb its disturbance by one to four standard deviation shocks. We trace the time path implied by (5.3) following each of the four shocks and plot them on a single IRF diagram.11
Alternatively, it would be interesting to further investigate the IRF analysis in the context of nonlinear STR ECMs in which both conditional and marginal models (2.6) and (2.7) should be jointly considered. But this is beyond the current study. For further discussions see van Dijk et al. (2002).

Impulse responses of error correction terms to k (= 1,2,3,4) standard deviation shock for various countries.
6. CONCLUDING REMARKS
The investigation of nonstationarity in conjunction with nonlinear autoregressive modeling has recently assumed a prominent role in econometric study. It is clear that misclassifying a stable nonlinear process as nonstationary can be misleading both in impulse response and forecasting analysis. Similarly, not allowing for the presence of cointegration when the speed of adjustment varies with the position of the system as in the case of nonlinear cointegration can be equally misleading. In this paper we have proposed a simple direct cointegration test procedure that is designed to have power against STR nonlinear error correction specifications. Our proposed tests are shown to have better power than the linear cointegration tests that ignore the nonlinear nature of the alternative. An empirical application clearly shows the potential of our approach. Unlike linear cointegration tests, the nonlinear tests find substantial evidence of cointegration in stock price and dividend systems. Further research to develop similar tests for alternative nonlinear models is currently under way.
APPENDIX: Proof of Theorem 3.1
Under the null δ1 = δ2 = δ3 = 0, the FNEC statistic given by (3.3) can be rewritten as
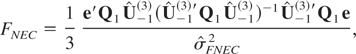
where
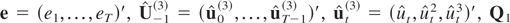
is the T × T idempotent matrix defined following (3.7), and
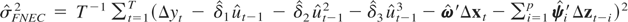
is the estimated variance with
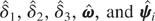
being the OLS estimators obtained from (3.2).
Notice under the null that (2.6) can be written alternatively as the following autoregressive distributed lag (ARDL) specification:

where φ(L) = 1 − φ1 L − ··· − φp Lp and θ(L) = θ0 + θ1 L + ··· + θp Lp. Decomposing ψi′ = (ψyi, ψxi′) in (2.6), and comparing (A.2) with (2.6), we find that φi = ψyi, i = 1,…,p, θ0 = ω′, and θi = ψxi′, i = 1,…,p. Using the Beveridge–Nelson (BN) decomposition (e.g., Phillips and Solo, 1992) we have

where φ*(L) = 1 − φ1*L − ··· − φp−1*Lp−1 and θ*(L) = θ0* + θ1*L + ··· + θp−1*Lp−1. Summing both sides of (A.2) from 1 to t and using (A.3), we obtain

where

. Under Assumptions 1(iii), 2(i) and (ii), and 3 and using (A.4), then it is easily seen that the residual

obtained from the spurious regression of yt on xt becomes
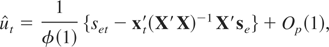
where se = (se1,se2,…,seT)′ and X = (x1,…,xT)′. Therefore, using (3.11) we have
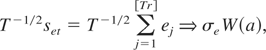
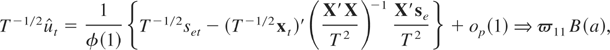
where
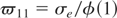
is defined in Theorem 3.1.
Next, noting that the
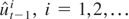
, are a regular transformation of

in the sense of Park and Phillips (2001), we can apply Lemma 2.1 of their paper and obtain

where st are the tth row of S and S is the T × (k + p(k + 1)) I(0) data matrix defined following (3.7). Using the preceding results, and defining the scaling matrix DT = diag(T−1,T−3/2,T−2), it is readily seen that


It is also straightforward to show under the null that
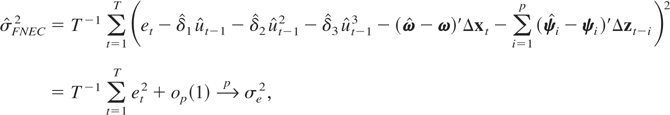
where we have used
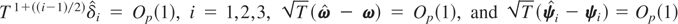
. Using (A.7)–(A.9) in (A.1), we obtain the required asymptotic null distribution of the FNEC test.
Under the alternative hypothesis, FNEC can be expressed as

where
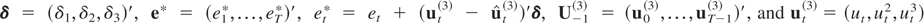
. Because
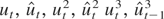
are all I(0) and
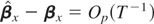
under the alternative, it is easily seen that

where we used that

and all lagged I(0) regressors in S are uncorrelated with et. Next, tedious but straightforward computations can be used to show that
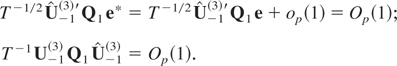
Also, we have
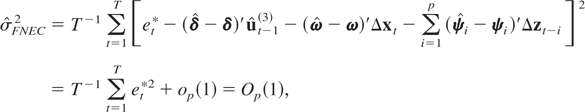
where we used
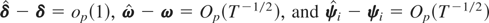
. Therefore, using (A.11)–(A.13) in (A.10), we obtain
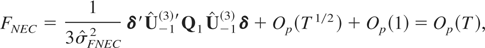
which clearly shows that the FNEC statistic diverges to infinity as T → ∞.
It is trivial to derive the asymptotic distributions of the FNEC* and tNEC tests and prove their consistency as they are special cases of the FNEC test.
We move on to prove results for the tNEG test. Note that the AR representation of

is given by
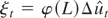
, where
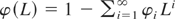
; see (3.9). The tNEG statistic can be written as
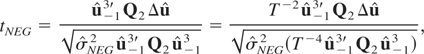
where Q2 is defined following (3.10). Following Phillips and Ouliaris (1990), it is straightforward to show that
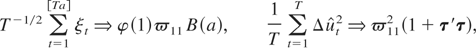
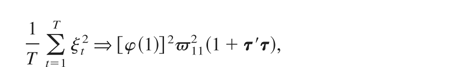
where τ is defined in Theorem 3.1. We also have
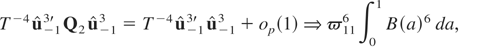
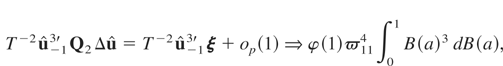
where ξ = (ξ1,…,ξT)′ and the equality in (A.18) and (A.19) follows from the straightforward adaptation of the Said and Dickey (1984) approach as employed in (A.16) of Phillips and Ouliaris (1990) and
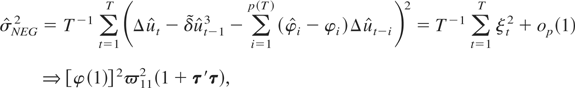
where we used (A.17),
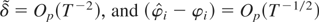
. Using (A.18)–(A.20) in (A.15), we obtain the required results for the asymptotic distribution of the tNEG test.
Next, under the alternative hypothesis, tNEG can be expressed as
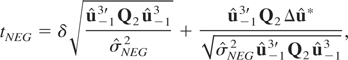
where
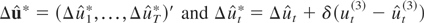
. As before, it is straightforward to show that
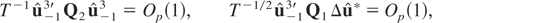
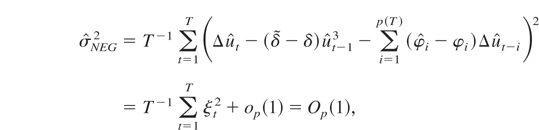
where we used
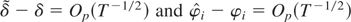
. Using (A.22) and (A.23) in (A.21), we have
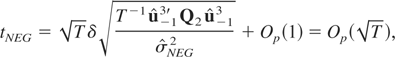
which shows that the tNEG statistic diverges to negative infinity as T → ∞. █
References
REFERENCES
Arranz, M.A. &
A. Escribano
(2000)
Cointegration testing in the presence of structural breaks.
Oxford Bulletin of Economics and Statistics
62,
23–52.CrossRefGoogle Scholar
Balke, N.S. &
T.B. Fomby
(1997)
Threshold cointegration.
International Economic Review
38,
627–645.CrossRefGoogle Scholar
Banerjee, A.,
J.J. Dolado, &
R. Mestre
(1998)
ECM tests for cointegration in a single equation framework.
Journal of Time Series Analysis
19,
267–283.CrossRefGoogle Scholar
Bec, F.,
A. Guay, &
E. Guerre
(2004)
Adaptive Consistent Unit Root Tests Based on Autoregressive
Threshold Model.
Manuscript,
Crest-ENSAE.
Bec, F. &
A. Rahbek
(2004)
Vector equilibrium correction models with nonlinear discontinuous
adjustments.
Econometrics
7,
628–651.CrossRefGoogle Scholar
Berk, K.N.
(1974)
Consistent autoregressive spectral estimates.
Annals of Statistics
2,
489–502.CrossRefGoogle Scholar
Campbell, J.Y. &
A. Kyle
(1993)
Smart money, noise trading and stock price behavior.
Review of Economic Studies
60,
1–34.Google Scholar
Campbell, J.Y. &
R.J. Shiller
(1987)
Cointegration and tests of present value models.
Journal of Political Economy
95,
1062–1088.CrossRefGoogle Scholar
Campbell, J.Y. &
R.J. Shiller
(1988)
Stock prices, earnings and expected dividends.
Journal of Finance
43,
661–676.CrossRefGoogle Scholar
Caner, M. &
B.E. Hansen
(2001)
Threshold autoregression with a unit root.
Econometrica
69,
1555–1596.CrossRefGoogle Scholar
Choi, I. &
P. Saikkonen
(2004)
Testing linearity in cointegrating smooth transition
regressions.
Econometrics Journal
7,
341–365.CrossRefGoogle Scholar
Corradi, V.,
N.R. Swanson, &
H. White
(2000)
Testing for stationarity-ergodicity and for comovement between
nonlinear discrete time Markov processes.
Journal of Econometrics
96,
39–73.CrossRefGoogle Scholar
Cuthbertson, K.,
S. Hayes, &
D. Nitzsche
(1997)
The behavior of the UK stock prices and returns: Is the market
efficient?
Economic Journal
107,
986–1008.Google Scholar
Davies, R.B.
(1987)
Hypothesis testing when a nuisance parameter is present under the
alternative.
Biometrika
74,
33–43.Google Scholar
Dickey, D.A. &
W.A. Fuller
(1979)
Distribution of the estimators for autoregressive time series with a
unit root.
Journal of the American Statistical Association
74,
427–431.Google Scholar
Enders, W. &
C.W.J. Granger
(1998)
Unit root test and asymmetric adjustment with an example using the
term structure of interest rates.
Journal of Business & Economic Statistics
16,
304–311.Google Scholar
Engle, R. &
C.W.J. Granger
(1987)
Cointegration and error correction: Representation, estimation and
testing.
Econometrica
55,
251–276.CrossRefGoogle Scholar
Escribano, A.
(1986)
Identification and modelling of economic relationships in a growing
economy.
Ph.D Dissertation,
University of California, San Diego.
Escribano, A.
(2004)
Nonlinear error correction: The case of money demand in the UK
(1878–2000).
Macroeconomic Dynamics
8,
76–116.CrossRefGoogle Scholar
Escribano, A. &
S. Mira
(2002)
Nonlinear error correction models.
Journal of Time Series Analysis
23,
509–522.CrossRefGoogle Scholar
Escribano, A. &
G. Pfann
(1998)
Nonlinear error correction, asymmetric adjustment and
cointegration.
Economic Modelling
15,
197–216.CrossRefGoogle Scholar
Froot, K. &
M. Obstfeld
(1991)
Intrinsic bubbles: The case of stock prices.
American Economic Review
81,
1189–1214.Google Scholar
Gallagher, L.A. &
M.P. Taylor
(2001)
Risky arbitrage, limits of arbitrage and nonlinear adjustment in the
dividend-price ratio.
Economic Inquiry
39,
524–536.CrossRefGoogle Scholar
Granger, C.W.J. &
N.R. Swanson
(1996)
Further studies in the study of cointegrated variables.
Oxford Bulletin of Economics and Statistics
58,
537–553.Google Scholar
Granger, C.W.J. &
T. Teräsvirta
(1993)
Modelling Nonlinear Economic Relationships.
Oxford University Press.
Hansen, B.E.
(1995)
Rethinking the univariate approach to unit root tests: How to use
covariates to increase power.
Econometric Theory
11,
1148–1171.CrossRefGoogle Scholar
Hansen, B.E. &
B. Seo
(2002)
Testing for two-regime threshold cointegration in vector error
correction models.
Journal of Econometrics
110,
293–318.CrossRefGoogle Scholar
Johansen, S.
(1995)
Likelihood Based Inference in Cointegrated Vector Autoregressive
Models.
Oxford University Press.
Kapetanios, G. &
Y. Shin
(2006)
Unit root tests in three-regime SETAR models.
Econometrics,
in press.Google Scholar
Kapetanios, G.,
Y. Shin, &
A. Snell
(2003)
Testing for a unit root in the nonlinear STAR framework.
Journal of Econometrics
112,
359–379.CrossRefGoogle Scholar
Kiliç, R.
(2003)
A Testing Procedure for a Unit Root in the STAR Model.
Manuscript,
Georgia Institute of Technology.
Kremers, J.J.M.,
K.R. Ericsson, &
J.J. Dolado
(1992)
The power of cointegration tests.
Oxford Bulletin of Economics and Statistics
54,
325–348.CrossRefGoogle Scholar
Kyle, A.S.
(1985)
Continuous auctions and insider trading.
Econometrica
53,
1315–1335.CrossRefGoogle Scholar
Luukkonen, R.,
P. Saikkonen, &
T. Teräsvirta
(1988)
Testing linearity against smooth transition autoregressive
models.
Biometrika
75,
491–499.CrossRefGoogle Scholar
Michael, P.,
R.A. Nobay, &
D.A. Peel
(1997)
Transactions costs and nonlinear adjustment in real exchange rates:
An empirical investigation.
Journal of Political Economy
105,
862–879.CrossRefGoogle Scholar
Ng, S. &
P. Perron
(1995)
Unit root tests in ARMA models with data-dependent methods for the
selection of the truncation lag.
Journal of the American Statistical Association
90,
268–281.CrossRefGoogle Scholar
Park, J.Y. &
P.C.B. Phillips
(2001)
Nonlinear regressions with integrated time series.
Econometrica
69,
117–161.CrossRefGoogle Scholar
Pesaran, M.H.,
Y. Shin, &
R.J. Smith
(2001)
Bounds testing approaches to the analysis of level
relationships.
Journal of Applied Econometrics
16,
289–326.CrossRefGoogle Scholar
Phillips, P.C.B. &
S. Ouliaris
(1990)
Asymptotic properties of residual based tests of
cointegration.
Econometrica
58,
165–193.CrossRefGoogle Scholar
Phillips, P.C.B. &
V. Solo
(1992)
Asymptotics for linear processes.
Annals of Statistics
20,
971–1001.CrossRefGoogle Scholar
Psaradakis, Z.,
M. Sola, &
F. Spagnolo
(2004)
On Markov error correction models with an application to stock
prices and dividends.
Journal of Applied Econometrics
19,
69–88.CrossRefGoogle Scholar
Said, S.E. &
D.A. Dickey
(1984)
Testing for unit roots in ARMA models of unknown order.
Biometrika
71,
599–607.CrossRefGoogle Scholar
Saikkonen, P.
(1991)
Asymptotically efficient estimation of cointegrating
regressions.
Econometric Theory
7,
1–21.Google Scholar
Saikkonen, P.
(2005)
Stability results for nonlinear error correction models.
Journal of Econometrics
127,
69–81.CrossRefGoogle Scholar
Saikkonen, P. &
I. Choi
(2004)
Cointegrating smooth transition regressions.
Econometric Theory
20,
301–340.CrossRefGoogle Scholar
Snell, A. &
I. Tonks
(1998)
Testing for asymmetric information and inventory control effects in
market maker behavior on the London Stock Exchange.
Journal of Empirical Finance
5,
1–25.Google Scholar
Snell, A. &
I. Tonks
(2003)
A theoretical analysis of institutional investors' trading
costs in auction and dealer markets.
Economic Journal
113,
576–598.Google Scholar
Taylor, M.P.,
D.A. Peel, &
L. Sarno
(2001)
Nonlinearity in real exchange rates: Towards a solution of the
purchasing power parity puzzles.
International Economic Review
42,
1015–1042.CrossRefGoogle Scholar
van Dijk, D.,
T. Teräsvirta, &
P.H. Franses
(2002)
Smooth transition autoregressive models—A survey of recent
developments.
Econometric Reviews
21,
1–47.Google Scholar
Asymptotic critical values for alternative statistics
Size of alternative tests for demeaned data (T = 100)
Power of alternative tests for demeaned data (T = 100)
Cointegration tests and estimates of the ESTR parameter for asset prices and dividends
Impulse responses of error correction terms to k (= 1,2,3,4) standard deviation shock for various countries.
 You have
Access
- 174
- Cited by