1 Introduction
A primary objective of pension provision is to insure individuals against post-retirement longevity risk; therefore, it is important to understand how individuals act upon retirement or at the end of the accumulation phase. However, a lack of individual annuity policy data has led to significantly less focus on how policyholders choose between available payout options. Most previous studies have drawn on survey or aggregate data from occupational pension fund statistics (Ameriks, Reference Ameriks2002; Queisser and Whitehouse, Reference Queisser and Whitehouse2003; Mottola and Utkus, Reference Mottola and Utkus2007; Brown et al., Reference Brown, Kling, Mullainathan and Wrobel2008; Benartzi et al., Reference Benartzi, Previtero and Thaler2011; Inkmann et al., Reference Inkmann, Lopes and Michaelides2011; Banerjee, Reference Banerjee2013). To date, only a few researchers have empirically studied the annuitization choice using individual data (Hurd and Pains, Reference Hurd and Panis2006; Bütler and Teppa, Reference Bütler and Ruesch2007; Chalmers and Reuter, Reference Chalmers and Reuter2012; Bütler et al., Reference Bütler, Staubli and Zito2013).
Our paper sets out to improve the understanding of choice between lump-sum and non-lump-sum options such as an annuity certain, a life annuity, and a postponement in an emerging market such as Korea. Korea has a relatively young population and a huge voluntary individual annuity market, and is also undertaking substantial reforms in its retirement pension system. To our knowledge, no prior studies have investigated the payout choices available for voluntary deferred annuities and how different markets affect these choices. In Korea, an individual deferred annuity market has developed that comprises two types of contracts: qualified and non-qualified. The major difference between them is the tax incentives: qualified contracts feature income deduction and are tax free for only non-lump-sum payouts, and are therefore more attractive to employees, whereas non-qualified contracts feature no income deduction and are tax free for lump-sum and non-lump-sum payouts, and are therefore more attractive to self-employed people. The types of tax incentives analysed in this study are important vehicles through which policymakers implement social welfare policies; therefore, policymakers should understand how these incentives affect individual behaviour.
Our study uses administrative records from a large insurance company in Korea, and the data include more than 32,000 individual choices and contract features for policyholders making a choice in the period from 2008 to 2011. Our research methodology is consistent with previous studies, focusing on different occupational plan types (Bütler and Teppa, Reference Bütler and Teppa2007; Mottola and Utkus, Reference Mottola and Utkus2007; Benartzi et al., Reference Benartzi, Previtero and Thaler2011; Banerjee, Reference Banerjee2013) and individual annuity participation (Inkmann et al., Reference Inkmann, Lopes and Michaelides2011).
We examine the determinants of individual decisions over payout choices, with a particular focus on tax incentives and contract-specific features. We find a clear distinction between the qualified and non-qualified contracts; the annuitization rate of qualified contracts is approximately 15 percentage points higher than non-qualified contracts (78.9% versus 63.6%). Compared with non-qualified contracts, an individual with a qualified contract is 1.46 times more likely to choose a life annuity option than a lump-sum payout. Overall, females and older individuals prefer a life annuity, when controlling for other variables. In addition to individual characteristics, contract-specific features including annuity value play a significant role.
This paper is organized as follows. Section 2 provides an overview of the Korean multi-pillar, old-age income system and individual deferred annuity markets, focusing on the regulatory framework for qualified and non-qualified contracts, tax policy, and payout options. Section 3 describes our data, empirical model with related variables, and testable hypotheses. Section 4 reports the payout decisions from actual choices, descriptive analysis, and empirical results. Section 5 presents our conclusions.
2 Voluntary individual deferred annuity markets in Korea
2.1 Role of individual annuity markets in Korea
In common with many other countries, Korea has a three-pillar system of old-age income security: public pension, occupational pension, and voluntary individual annuities. However, the Korean pension system differs from those in other advanced countries in several ways. The Korean National Pension Service is a funded system that provides a basic subsistence-level income to all retirees, but is still in the accumulation stage because of the system's relative newness (it was introduced in 1988). The Korean Government expects the system to cover the entire population, but, to date, the actual coverage ratio is only 50% because it excludes self-employed workers and housewives. The number of pensioners in the National Pension Service is only 110,000 as of July 2012. Furthermore, even though it is a young system, it already suffers from questionable financial sustainability. Its financial vulnerability stems from an imbalance created by low contributions and high benefits. In 1988, the initial benefit level was set at 70% of the lifetime average income for persons with 40 years of contribution. This high level of benefit requires system contribution rates of 22% to 24%, far above the current level of 9%.
Demographic changes strongly affect the Korean National Pension Service, too. Korea has the most rapidly ageing population in the world. It is predicted that, in just 18 years, the ratio of the population aged 65 and above will rise from 7% (in 2000) to 14% (in 2018); that is, from an ageing to an aged society. Furthermore, it is estimated that the transition from an aged to a post-aged society, with 20% aged 65 and above, will take only 8 years (in 2026). Meanwhile, Korea's fertility rate has fallen to the lowest level in the developed world, with a birth rate of 1.2 children per female in 2010. As a result, the aged dependency ratioFootnote 1 will surge from 10.1% in 2000 to 71.0% in 2050. These rapid demographic changes could negatively affect fiscal stability, including that for public pension finance. To handle the rapid demographic changes, the replacement rate of the average earner with 30 years of participation will be lowered from 45% in 2007 to 30% in 2028. Despite this measure, the Korean National Pension Service is forecast to run a deficit in 2044 and be exhausted in 2060. Eventually, it looks likely to transform from a funded system to a pay-as-you-go system akin to that of other developed countries.
The second pillar, an employer-sponsored occupational pension system, was introduced in 2005. At the time, employers were required to guarantee (within a defined benefit plan) or contribute (within a defined contribution plan) at least 1 month of earnings on behalf of their employees. Historically, Korean companies have paid lump-sum retirement benefits when employees leave their companies, similar to Japanese severance payment plans. Even after transferring to the occupational pension system, Korean retirees can elect to take their retirement benefits as a lump sum. Moreover, a lump-sum benefit is taxed separately from composite income, with a deduction of 45% of the income amount and a special deduction scaled to the employment period. However, if received in the form of an annuity, that annuity income is subject to composite income taxation. Because of the long-standing tradition and favourable tax policy for a lump-sum benefit, most retirees choose a lump-sum payment. According to the Korean Financial Supervisory Service (2012a), 96.8% of retirees who are older than 55 chose a lump-sum benefit. This phenomenon reflects retirees’ working capital needs to cover daily living expenses and lack of tax incentives for pension annuity income.
Although the second pillar has been transitioning from the retirement severance pay system to retirement plans, this transition would not affect an individual's payout choice of the third pillar. As noted, most retirees do not choose a life annuity option because of the absence of an annuitization process within the retirement pension plan and considerable tax incentives for taking a lump-sum benefit. Although the new retirement pension system has been introduced, only a funding method for the accumulation phase has been changed. Therefore, we anticipate that a payout practice under the new retirement system will not likely be easily changed in the near future.
Compared with other developed countries, whose average replacement rate provided by the first and second pillars is more than 60–70%, the replacement rate in Korea is relatively low, at less than 50%. As a result, Korean individual annuity markets have become pivotal in supplementing insufficient annuity income from the first and second pillars. Figure 1 compares the reserves of the National Pension Service, retirement pensions, and individual annuities. The reserve size of total individual annuity amounts to 158 trillion KRW (US$ 142 billion). The share of individual annuity in total reserves is over 30% (qualified, 11.8%; non-qualified, 19.2%) as of the end of 2010 (Financial Supervisory Service, 2011). These figures demonstrate the importance of the individual annuity within Korea's three-pillar system of old-age income security.
Reserves sizes of the three-pillar system in Korea (trillion KRW; December 2010).

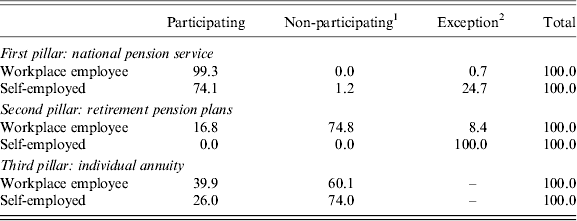
In Korea, coverage of three-pillar retirement income significantly differs between workplace employees and self-employed people.Footnote 2Table 1 details the coverage of pension systems according to survey data published by the Korean Ministry of Health and Welfare (2012). Almost all workplace employees are insured by the National Pension Service, whereas nearly one quarter (24.7%) of self-employed persons are not covered by the public-defined benefit pension. In addition, only workplace employees participate in retirement pension plans sponsored by their employers. Self-employed workers rely much less on the third pillar (39.9% workplace employees versus 26.0% self-employed workers), despite the fact that they have no coverage in the second pillar. This is mainly due to their low level of income, typically lower than that earned by other working groups by roughly 40% (Kim, Reference Kim2012).
Household's ownership of three-pillar retirement income by occupational status
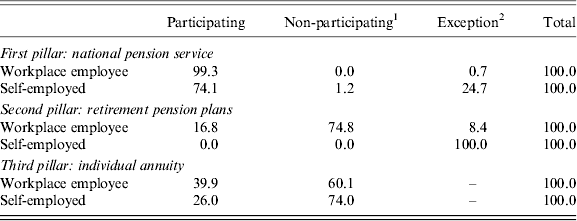
1 ‘Non-participating’ means insured but no contribution due to individuals’ financial difficulties.
2 In the National Pension Service, ‘exception’ means that insured persons are excluded from the coverage, such as persons who are in school or military service. Also, the retirement pension plans only cover permanent employees, excluding self-employed people, unpaid family workers, and temporary or daily workers.
Source: Ministry of Health and Welfare, (2012).
The ownership of the three-pillar retirement income may thus affect the retirement income readiness of Koreans. Figure 2 demonstrates the preparation for retirement income, as categorized by occupational status (Ministry of Health and Welfare, 2012). Over 76% of self-employed workers gave negative responses (20.7% were ‘very unprepared’ and 55.6% ‘somewhat unprepared’), compared with workplace employees who gave 64.8% negative responses (11.4% were ‘very unprepared’ and 53.4% ‘somewhat unprepared’). The low level of retirement readiness of self-employed workers may relate to the vulnerability of the National Pension Service and retirement pension plans, as Table 1 suggests.
Level of retirement readiness by occupational status.
Figure 3 represents the premium volume and market share of individual annuities sold in the Korean life insurance industry (Korea Insurance Development Institute, 2012). In FY2011 (April 2011 to March 2012), total premium income from individual annuities reached almost KRW 29.1 trillion (US$ 27.6 billion), with the qualified market reaching KRW 3.7 trillion (US$ 3.5 billion) and the non-qualified market reaching KRW 25.4 trillion (US$ 24.1 billion). Over the past decade, the annuity market share of the total life insurance premium has increased from 17.2% in 2002 to 33.0% in 2011. In the life insurance industry, non-qualified annuity contracts have grown at much greater rates than qualified contracts because of the industry's exclusive business area of life insurers and the strong tax incentives for taking a lump-sum benefit.
Premium volume and market share of individual annuities (Korean life insurance industry).
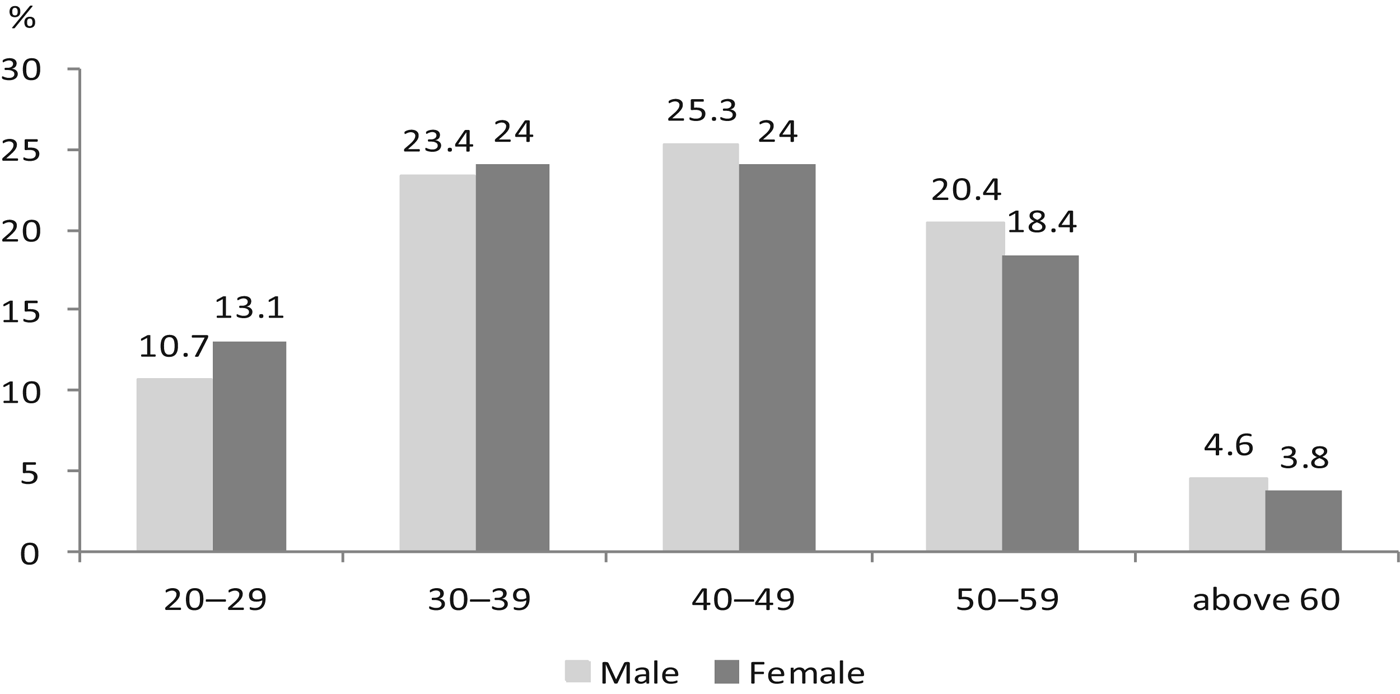
Figure 4 depicts individual annuity ownership for all persons, categorized by age group (Korea Insurance Development Institute, 2011). Approximately 16% of Koreans are covered by individual annuity policies sold through insurance companies. The participation rate of persons aged 60 or above is the lowest level (4.6% males and 3.8% females), which suggests that most contracts are in the accumulation phase.
Percentage of individuals owning individual annuity contracts (December 2010).
2.2 Market type of Korean individual deferred annuities
The Korean individual deferred annuity market contains qualified and non-qualified contracts. Overall, the Korean tax treatment for an individual annuity is similar to that of the USA. A Korean qualified contract corresponds to a US Individual Retirement Account and a non-qualified contract corresponds to a Roth Individual Retirement Arrangement. However, the specific tax options and contract contents are very different from those of the USA, especially for the non-qualified contracts.
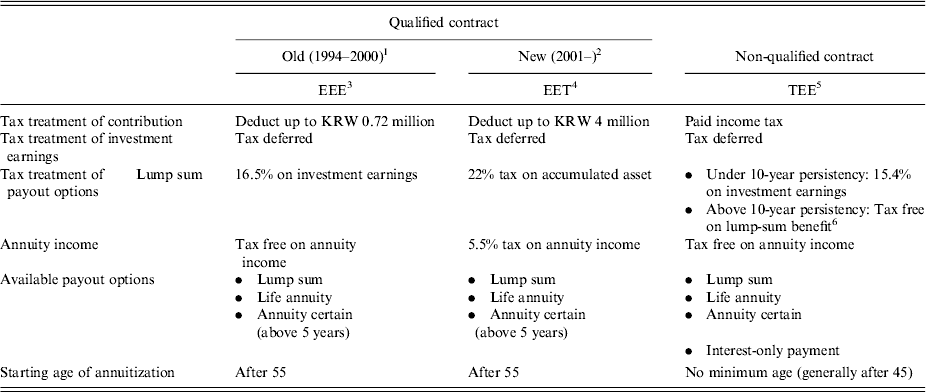
Table 2 describes the key features of the qualified and non-qualified contracts (as at December 2012). Currently, two types of qualified contracts coexist: old and new. Those called ‘old’ are qualified contracts available before December 2000 but since abolished because of excessive tax advantages. These were replaced by ‘new’ qualified contracts with different tax terms. Our study focuses on the old qualifiedFootnote 3 (‘qualified’, hereafter) and non-qualified contracts. The Korean tax system for qualified contracts is exempt–exempt–exempt (EEE; before 2000)Footnote 4 and exempt–exempt–taxed (EET; after 2001),Footnote 5 whereas non-qualified contracts are taxed–exempt–exempt (TEE).Footnote 6 The main differences between the two are the tax on the contributions and payout options, especially lump-sum benefits.
Comparison of qualified and non-qualified contracts in Korea (as at December 2012)
1 Old contracts were sold during June 1994–December 2000, and 40% of the total contribution up to KRW 0.72 million (US$ 670) was deductible from individual income.
2 New contracts were introduced since 2001, and 100% of the contribution up to KRW 4 million (US$ 3,700) is deductible from individual income.
3 Exempt when contributing, exempt (or deferred) when investing, and exempt when receiving benefits.
4 Exempt when contributing, exempt (or deferred) when investing, and taxed when receiving benefits.
5 Taxed when contributing, exempt (or deferred) when investing, and exempt when receiving benefits.
6 Minimum maturity period for tax-free requirement has varied from 0 to 3, 5, 7, and 10 years according to the policies of the Korean Government.
Source: Authors’ calculations.
In qualified contracts, an individual's contributions are tax deductible up to KRW 0.72 million (US$ 670). Generally, the premium size of qualified contracts can be determined by a policyholder's tax bracket, which is a progressive personal income tax. Therefore, the tax deduction for qualified contracts can be important to middle- and high-income individuals who want to save income tax. In contrast, a contribution made into a non-qualified contract has previously paid ordinary income tax.
As a result of the different tax incentives, we can infer that the Korean individual annuity market represents a dichotomy between two groups; the qualified type appeals to workplace employees, whereas the non-qualified type appeals to self-employed workers. Under the Korean income tax system,Footnote 7 as the tax rate is based on income size, most workplace employees drop into a lower tax bracket when they retire. Therefore, workplace employees prefer income deduction rather than exempted withdrawal benefits, and therefore they may buy qualified rather than non-qualified contracts. Contrary to workplace employees, most self-employed workers pay no tax because of low income and a different tax regulation from that of workplace employees.Footnote 8 Therefore, they may have no incentive regarding income deduction, which is available in qualified contracts, and thus self-employed workers are inclined to prefer non-qualified contracts with tax-free withdrawal benefits. This situation suggests that self-employed workers are likely to purchase non-qualified rather than qualified contracts.
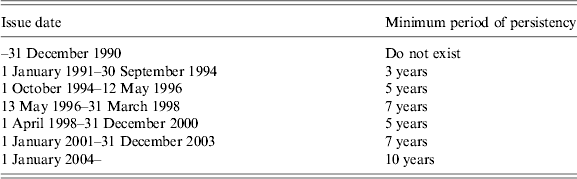
Table 3 presents the changes to legislation for tax-free withdrawals in non-qualified contracts (Korea Life Insurance Association, 2010). Both annuity payments and lump sums are not taxable if the contracts are satisfied for a minimum period of persistency. Before 1990, no minimum period was required for lump-sum withdrawals. The minimum period has been increased from 3 years (January 1991–September 1994) to 10 years (after 2004) by Korean Government policies. A minimum period of 5 years was required from October 1994 to 12 May 1996 and from April 1998 to December 2000; and 7 years from 13 May 1996 to March 1998, as well as from January 2001 to December 2003. In the late 1990s, during the Asian financial crisis, the Korean Government eased the minimum period from 7 to 5 years to encourage long-term savings.
Changes to legislation for tax-free withdrawals (non-qualified type)
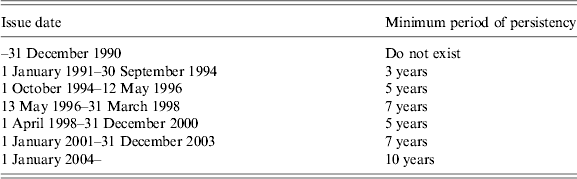
Source: Korea Life Insurance Association (2010).
The tax treatment for non-qualified contracts permits individuals to access their investment earnings without penalties and taxes after the minimum period of persistency. In contrast, lump-sum benefits for qualified contracts are taxed at 16.5% of investment earnings. Of course, annuity payments from qualified contracts are tax free, compared with those from non-qualified contracts. Another crucial difference is the annuity starting age. Qualified contract policyholders can receive annuity benefits after the age of 55. However, non-qualified contract policyholders may start receiving annuity benefits before the age of 55, generally at 45 years old.
In Korea, strong tax incentives for individual deferred annuities have encouraged savings, rather than encouraging policyholders to use these savings to hedge their longevity risk. The tax-exempt status for non-qualified contract lump-sum withdrawals is offered to all policyholders, regardless of age, income, or wealth level, which is uncommon among advanced countries that have established pension and annuity systems. The Korean Government has its reasons for providing tax incentives for lump-sum withdrawals as well as annuity benefits, primarily that such incentives encourage individuals to save for retirement. This is an effective policy for promoting the accumulation of long-term capital in countries with long-term capital scarcity, such as Korea. However, individuals may eschew annuitization for the preferred tax incentives on lump-sum withdrawals. As a result, individuals could be exposed to longevity risk and thereby create an added burden for the country.
2.3 Payout options by market type
As Table 2 reveals, payout options differ between qualified and non-qualified contracts. In the non-qualified contract, four payout options are available: a life annuity, an annuity certain, an interest-only withdrawal, and a lump-sum payment. The qualified contract, however, offers only three payout options – a life annuity, an annuity certain, and a lump-sum payment – but no interest-only withdrawal option. The interest-only withdrawal option pays only the set interest from the policyholder's accumulated assets to an annuitant. This option preserves the principal amount of the accumulation until the date it is withdrawn or the policyholder's death. This option is intended for use by those who prefer receiving some income from their accumulated assets while remaining in control of their assets.
The annuity certain option provides an income stream for a specific period: policyholders determine the number and amount of payments. If the annuitant dies before the end of the payment term, a beneficiary inherits the remaining payments. This option allows an individual to anticipate a specific level of income during the payment period but not necessarily their lifetime. By regulation, qualified contract policyholders must satisfy a requirement for at least 10 years of the accumulation phase and at least 5 years of the decumulation phase to be eligible for a tax exemption.
The life annuity option is a form of longevity insurance whereby the uncertainty of an individual's lifespan is transferred from the individual to the insurance company. With a pure life annuity, annuitants may die before recovering the value of their accumulated assets, and thus policyholders may hesitate to choose this option. To address this concern, a life insurance company may offer a guaranteed period of minimum payment. By regulation, Korean life insurance companies must make annuity payments for at least a 5-year ‘period certain’, and, if the annuitant dies before the expiration of the period certain, the annuitant's estate or beneficiary is entitled to collect the remaining payment certain.
At the time of contract, a policyholder may choose a payout option, but he or she has the authority to change the option before the start of the decumulation phase. The Financial Supervisory Service (2012b) reports that over 80% of policyholders choose a life annuity option at the contract date for both qualified and non-qualified contracts. However, to start the decumulation phase, policyholders must declare the specific payout option at the end of the accumulation phase, regardless of the original choice. The regulation requires the policyholder to declare his or her choice three months prior to the end of the accumulation phase. Those individuals not making a choice are classified as a waiting group and are subject to the same actuarial assumptions appropriate to their accumulation phase. The regulation does not allow the mixed option (a monthly life annuity and lump sum) in the qualified contract, but it does allow partial annuitization in the non-qualified contract. However, the insurance companies report that policyholders rarely choose a partial annuity option. Overall, non-qualified contracts offer more flexible and beneficial payout options and tax features than qualified contracts.
3 Data and empirical model
3.1 Data
We use a unique dataset collected at the individual level from a large insurance company. The insurance company provided contract information on all individual deferred annuities that reached the end of the accumulation phase between 2008 and 2011. Our dataset includes information on 32,867 contracts: 8,402 qualified and 24,465 non-qualified. Qualified contracts were sold from June 1994 to December 2000, and non-qualified contracts were sold from January 1982 to March 2004. Therefore, for non-qualified contracts, the minimum period for the tax exemption of lump-sum benefits ranges from 0 to 10 years, depending on issue date (Table 3).
At the maturity date of the accumulation phase, policyholders can choose a lump sum, an annuity certain, a life annuity, or wait (postpone the decision entirely). For each contract, we have information on age, contract type, maturity date, payout choice, amount of the accumulated asset, premium charged, and specific product features such as the level of assumed interest rate, guaranteed reinvestment risk, and guaranteed mortality. Unfortunately, however, our dataset has a number of shortcomings. Generally, insurance companies do not collect information about the policyholder's socioeconomic characteristics such as education, health, occupational status, marital status, income, non-annuity wealth, and pre-annuity income, which are likely to influence payout choice.
However, our data are unique because they are not survey data but are sourced from administrative records. Although our sample data come from one large insurance company, they are representative of the Korean annuity market in market share, sales platforms, and product features. The Korean life insurance market is heavily dominated by three domestic insurers. Before 2000, the market share of the top three companies exceeded 80% because of market entrance restrictions. Our sample data come from the top three insurers, representing a significant portion of the Korean insurance market.
The Korean life insurance market is the world's eighth largest. Although the premium volume is fairly large, price, and marketing channel deregulation began in the late 1990s, with Korea becoming a member of Organisation for Economic Co-operation and Development (OECD). Before the price liberalization of the Korean insurance market, all life insurance companies applied the same rates for assumed interest rate, mortality rate, and expense loadings. The identical price among insurers caused sales in individual annuity products to entirely depend on the distribution channel. Akin to Japan, Korean insurers have traditionally relied upon an agency-specific sales force, called solicitors. Solicitors work for one company on a commission basis, and thus they recommend the products of only their registered insurance company to consumers. Even after introducing the bank insurance model (bancassurance) in September 2003, in-house sales forces have exercised a strong influence, especially in the top three insurers.
In Korea, because of a lack of customer knowledge and confidence in the life and annuity industry, individual annuity products are sold to customers via solicitors, and so the purchasing decision is not customer driven. Individuals require personal interaction to understand their financial needs and determine which products to buy. In this market environment, individuals are unlikely to select a particular company in the process of purchasing annuity products.Footnote 9
Nevertheless, our information may reflect the data's restriction to those contracts that reached the maturity date of the accumulation phase, not the start date of the contract. Focusing only on contracts that have reached the maturity date may create a selective sample with a bias towards qualified contracts because the persistency rate of qualified contracts is higher than that of non-qualified contracts. We attempted to obtain information about all contracts terminated before the maturity date of the accumulation phase, but the insurance company did not have the related data.
3.2 Model and variables
We use multinomial probit regression because our dependent variable has more than two categories. Our research examines whether and how the different market type alters the payout decision of individual annuities. To evaluate this question, a lump-sum group is chosen as the reference category, and all comparisons are made with a lump-sum distribution.
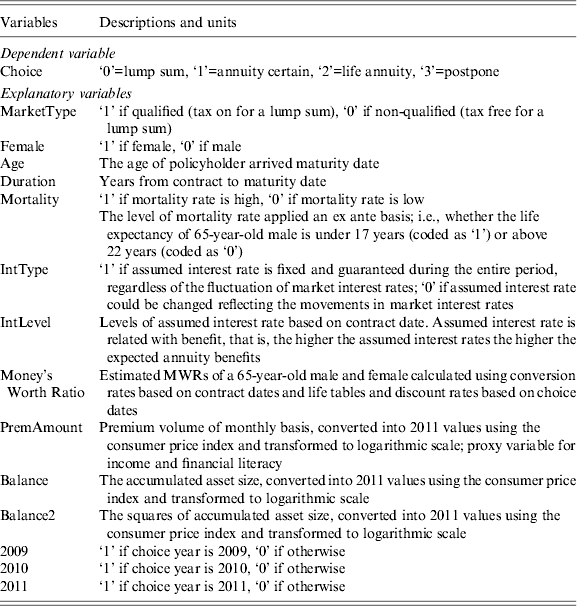
Table 4 lists and describes the variables. The dependent variable ‘Choice’ represents the actual choice of policyholders in four categories: a lump sum (coded as ‘0’), an annuity certain including an interest-only withdrawal (coded as ‘1’), a life annuity (coded as ‘2’), and a postponement (coded as ‘3’). We classify an interest-only withdrawal as an annuity certain option because the proportion of interest-only withdrawals is so small (0.1%; see Figure 5). Moreover, both an interest-only withdrawal and an annuity certain option have in common no function of mortality cross-subsidy.Footnote 10
Payout choices of individual deferred annuity contracts.
List and description of variables in the model
Source: Authors’ data.
We use explanatory variables such as individual characteristics and product features. The personal characteristics variables are limited to ‘gender’ and ‘age’. Gender takes the form of a dummy, whose value is ‘0’ for males and ‘1’ for females. We assume that females and elderly people are more likely to choose a life annuity option, based on risk-averse tendencies (Mottola and Utkus, Reference Mottola and Utkus2007).
We present product features as annuity values to a policyholder. Although we have no information on annuity values, we obtained limited information on the assumed interest rates and mortality rates. In Korea, guaranteed annuity options are very popular in individual annuity contracts issued during the 1980s and 1990s, when long-term interest rates were very high. Entering the 21st century, however, as long-term interest rates began to fall, guaranteed annuity options have proved to be a significant risk for insurance companies, and thus insurers stopped granting these options. As a result, the value of these guarantees has risen since the 2000s. The guaranteed annuity conversion rate is a function of actuarial assumptions such as the assumed interest and mortality rates. Several previous studies demonstrate that the annuity's value is the most important determinant in the payout decision (Bütler and Teppa, Reference Bütler and Teppa2007; Bütler et al., Reference Bütler, Staubli and Zito2010; Bütler et al., Reference Bütler, Staubli and Zito2013). Variables related to the annuity value are as follows.
First, the variable ‘IntType’ represents guaranteed reinvestment risk. Contracts with a fixed rate of assumed interest are guaranteed fixed annuity income streams for the policyholder's lifetime, eliminating reinvestment risk. By contrast, in non-fixed (interest sensitive) contracts, annuity incomes vary with interest rate fluctuations. Considering the sharply falling interest rates in Korea since the 2000s, we expect that having a fixed assumed interest rate contract has a positive effect on the probability of choosing non-lump-sum payout options, especially a life annuity.
Second, the variable ‘IntLevel’ represents conversion rates for investment; that is, the level of assumed interest rates. Higher assumed interest rates result in higher monthly payments for a given accumulated asset than do lower assumed interest rates. The level of assumed interest rates is applied during not only the accumulation phase but also the decumulation phase (accumulated wealth is translated into an annuity payment) with fixed interest rates. In fact, alternative investment opportunities may also influence the payout decision. Individuals may choose a lump-sum option if they can obtain better returns than with annuitization. Many previous studies report the importance of annuity rates on annuitization (Bütler and Ruesch, Reference Bütler and Ruesch2007; Bütler, Reference Bütler2009; Bütler et al., Reference Bütler, Staubli and Zito2010, Reference Bütler, Staubli and Zito2013). Therefore, assumed interest rates that are more beneficial to policyholders than the prevailing market rates, may cause higher annuitization rates.
Third, the variable ‘Mortality’ measures guaranteed mortality. The insurance company has a legal obligation to guarantee the mortality rate offered by the contract date, regardless of future mortality improvement. We expect that policyholders who have insured for a high degree of mortality may not choose the lump-sum option because of a rapid increase in lifespan. We use a proxy variable – that is, applied annuitant life tables – to measure the degree of guaranteed mortality level. The Korean Financial Supervisory Service publishes annuitant life tables every 3 years, and life insurance companies use them for pricing and reserving liabilities. Our dataset has eight life tables; assumed mortality rates have greatly decreased, reflecting the improvement of the general population's life expectancy. Specifically, in the fifth life table, assumed mortality rates significantly decreased; the life expectancy of a 65-year-old male has increased from 16.7 years (fourth life table) to 22.0 years (fifth life table). In this study, ‘mortality’ takes a dummy, whose value is ‘0’ for a relatively lower level (after applying the fifth life table) and ‘1’ for relatively higher level (before applying the fourth life table).
It is theoretically possible for individuals to withdraw accumulated assets and buy new annuity contracts with another insurance company; that is, on the open market. However, conversion rates in the open market have dropped sharply because of the low interest rate and increased life expectancy. For example, an individual who bought an individual annuity product between 1994 and 1997 is subject to very generous conditions such as higher assumed interest rate (7.5% with fixed type) and lower mortality rate (13.0 years of life expectancy for a 65-year-old male).Footnote 11 In contrast, if the individual withdraws the accumulated assets and buys a life annuity in the open market, the conversion rate sharply decreases because of the changed conditions: assumed interest rate decreased to 4.8% with an interest sensitive contract typeFootnote 12 and life expectancy increased to 24 years.Footnote 13 As a result, the conversion rate of 65-year-old males is estimated to have fallen from 17% in the early 1990s to 7.5% in the late 2000s. In the near future, the improvement of life expectancy and the low interest rate environment are expected to continue. Therefore, in price, converting accumulated assets into annuity incomes is a more profitable choice than withdrawing assets and buying a new single premium immediate annuity in the open market.
Finally, we consider the Money's Worth Ratio (MWR) (Mitchell et al., Reference Mitchell, Poterba, Warshawsky and Brown1999) to evaluate the overall values of annuity options. We predict that demand for the annuity option will rise with the level of the annuity's value. To calculate the MWR, we need to know three factors: annuity incomes, survival probabilities, and discount rates. Unfortunately, we have no direct information about the actual annuity incomes at the time of decision. We therefore hypothesize that the conversion ratesFootnote 14 of contract dates determine the annual annuity incomes at the choice dates. We consider 65-year-old males and females. During the sample period, the insurance company has changed its annuity prices 12 times. The assumed conversion rate of a 65-year-old male has been lowered from 25.9% in 1982 to 8.9% in 2004, reflecting changes in the assumed life expectancies and interest rates. To calculate the probabilities that individuals receive life annuity incomes, we use life tables published in 2011 (Statistics Korea, 2011). To determine the present value of the expected annuity incomes, we use the yield on the 3-year corporate bond at the time of choice; that is, during 2008–2011.
The variables ‘Balance’ and ‘Balance2’ test the magnitude effect of the size of the accumulated assets. We use the logarithm and its square for the analysis. As expected, life expectancy is correlated with wealth. Wealthier policyholders are likely to choose a life annuity and poorer policyholders a lump-sum option (Hurd and Panis, Reference Hurd and Panis2006; Bütler and Teppa, Reference Bütler and Teppa2007). Many previous studies (Brown, Reference Brown2007; Hu and Scott, Reference Hu and Scott2007; Benartzi et al., Reference Benartzi, Previtero and Thaler2011) have found that small balances are discounted at a higher rate than large ones, which suggests that policyholders with larger accumulated assets would be more likely to prefer a life annuity option. Also, it is well known that financial literacy correlates positively with wealth (Lusardi and Mitchell, Reference Lusardi and Mitchell2007), and annuitization rates may increase with accumulated assets. Policy duration from issue date to choice date (‘Duration’) and monthly paid premium volumeFootnote 15 (‘PremAmount’) are control variables. Annuitization rates may increase with duration because policyholders with a higher propensity to annuitize will maintain their contracts. Premium volume is a proxy variable for income and financial literacy; we expect relatively high annuitization rates for middle- and high-income individuals (Bütler and Staubli, Reference Bütler and Staubli2010). Finally, we control for economic conditions using dummy variables 2009, 2010, and 2011, which indicate the decision year.
Our key interest is whether the two types of contracts have different factors determining the decision of payout choice. The variable ‘MarketType’ takes a value of ‘1’ for qualified contracts and ‘0’ for non-qualified contracts.
3.3 Hypotheses
We hypothesize that the differences inherent in the two types of individual annuity contracts result from tax incentives and socioeconomic characteristics (Brown et al., Reference Brown, Kling, Mullainathan and Wrobel2008). Considering these factors, we establish two opposing hypotheses.
First, relating to the different tax incentives in the lump-sum benefits, we hypothesize that policyholders of qualified contracts would be more likely to choose the non-lump-sum options to receive a tax exemption. Conversely, policyholders of the non-qualified contracts can obtain a tax-exemption for the lump-sum or non-lump options if the contracts satisfy the minimum period of persistency. Because all contracts except for only 75 contracts are over the minimum period of persistency for tax-free lump sums, non-qualified contracts clearly offer a tax advantage for lump sums. This advantage implies that the non-qualified contracts are considered as savings vehicles rather than as generating retirement income. The tax exemption for the lump sums is especially attractive for asset growth for high net worth individuals who want to avoid composite income tax, ranging from 6.6% to 38.5%.Footnote 16
Second, on the basis of the crowding-out hypothesis, we expect that policyholders with non-qualified contracts are more likely to choose the life annuity option because of their insufficient pension income. The findings in Section 2 suggest that the major buyers of non-qualified contracts – that is, self-employed workers – are willing to generate more retirement income using their accumulated assets to offset an insufficient public pension and occupational pension plans. Public pensions and occupational pensions may be close substitutes for the voluntary annuity market (Attanasio and Rohwedder, Reference Attanasio and Rohwedder2003; Inkmann et al., Reference Inkmann, Lopes and Michaelides2011). Inkmann et al. (Reference Inkmann, Lopes and Michaelides2011) find that voluntary annuity income decreases with other pension income such as public pension and occupational pension in the UK; that is, the other pension income crowds out voluntary annuities.
4 Empirical results
4.1 Payout choice and descriptive analysis
4.1.1 Payout choice
Figure 5 presents the decision on payout choice of individual deferred annuities at the maturity of the accumulation phase. Combining all the types, individuals who made their payout decisions between 2008 and 2011 had an annuitization rate of 67.5%. Comparing selection behaviour between the qualified and non-qualified contracts, policyholders with qualified contracts had higher annuitization rates than non-qualified policyholders; 78.9% of policyholders with qualified contracts selected the life annuity option, whereas only 63.6% of policyholders with non-qualified contracts chose the life annuity option. We find the qualified contract policyholders are less likely to choose the postponement option (10.1%) than are the non-qualified contract policyholders (16.2%). In addition, the probability of choosing the lump-sum option is 4.9% for qualified contracts, which is 9% age points lower than that for non-qualified contracts (13.9%). However, there is no difference in the probability of choosing an annuity certain (including interest-only withdrawal in non-qualified contracts) between qualified and non-qualified contracts.
To illustrate this increase in annuitization rates for those who made their payout decision for qualified contracts, Figure 6 depicts the selection rate of the life annuity option for the study period. In all years between 2008 and 2011, the annuitization rates for qualified contracts are higher than those for non-qualified contracts.
Selection rates of the life annuity option (2008–2011).
Our study finds that annuitization rates vary across different market types. Mottola and Utkus (Reference Mottola and Utkus2007) report a higher annuitization rate in the defined benefit plan (27%) than in the cash balance plan (17%). Benartzi et al. (Reference Benartzi, Previtero and Thaler2011) report a similar result: 53% for the defined benefit plan and 41% for the cash balance plan. Banerjee (Reference Banerjee2013) finds that differences in defined benefit plan rules or features for lump-sum distribution result in very different annuitization rates. For example, the annuitization rate for defined benefit plans with no lump-sum distribution options was 98.8%. By contrast, the annuitization rate for plans with no restrictions on lump-sum distribution ranged from 44.3% for defined benefit plans to 22.3% for cash balance plans. These results indicate that the combined annuitization rates of different plan or market types may be uninformative, and our study is consistent with previous studies (Mottola and Utkus, Reference Mottola and Utkus2007; Benartzi et al., Reference Benartzi, Previtero and Thaler2011; Banerjee, Reference Banerjee2013).
4.1.2 Descriptive analysis
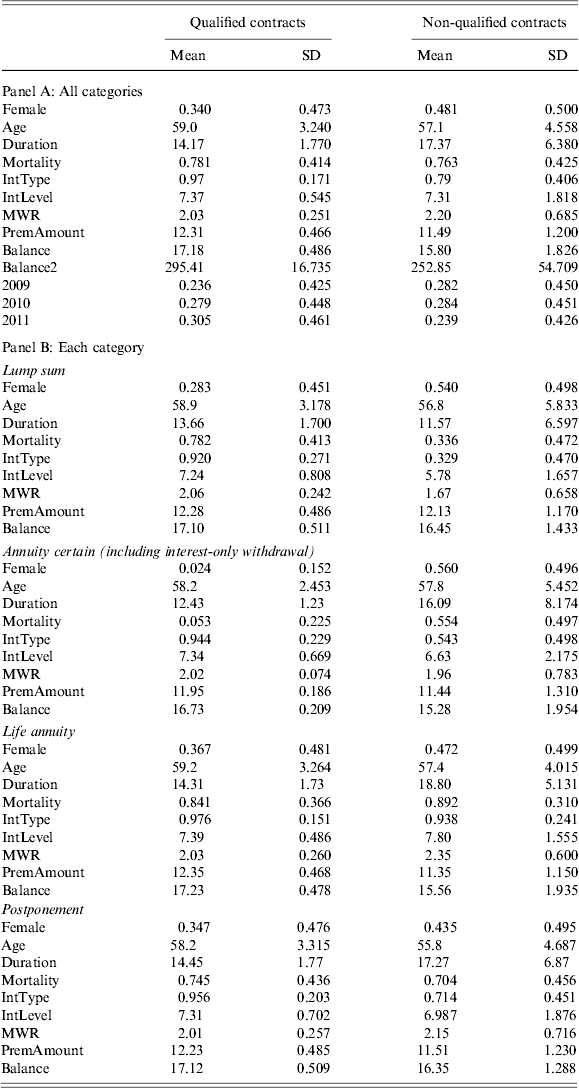
Table 5 provides summary statistics for the variables we use for empirical analysis, categorized by market types. We find that policyholder characteristics differ between two groups: females (34.0% qualified versus 48.1% non-qualified) and policyholders who have maintained longer periods (14.17 years qualified versus 17.37 years non-qualified) tend to have non-qualified contracts.
Descriptive statistics of explanatory variables
Source: Authors’ calculations.
The estimated MWRs range from 1.45 to 2.26 in the qualified and from 1.01 to 3.69Footnote 17 for the non-qualified contracts, implying that the life annuity options of the non-qualified type are more valuable than the qualified type because our non-qualified type contained a high proportion of the old contracts issued from 1982 to 1993. On average, the non-qualified contracts have a much higher value than the qualified contracts (2.20 versus 2.03), and this difference is statistically significant at the 1% level.
The difference in accumulated asset size between qualified and non-qualified contracts and its deviation are noteworthy. On average, the asset size of the non-qualified contracts (KRW 7.3 million or US$ 6,500) is only 25% of the size of qualified contracts (KRW 28.9 million or US$ 25,838); however, the deviation of the non-qualified group is roughly four times larger than that of the qualified group. These findings mean that the non-qualified type has a wide distribution because of the group's heterogeneity. As Section 2 explains, individuals who buy the non-qualified type tend to polarize as either low- or high-earners. In contrast, policyholders with qualified contracts tend to be a homogeneous group comprising middle- and high-income employees. We can infer that (1) non-qualified policyholders with large-scale assets and belonging to the affluent class enjoy tax exemption in investment income for the lump-sum benefit and (2) non-qualified policyholders with small assets probably choose the lump sums because of the means test and need for working capital.
We report descriptive statistics by choice category to identify any systematic difference in the payout choices. Panel B of Table 5 confirms that there is no systematic difference among payout choices. Within the non-qualified contracts, variables related to annuity value differ between life annuities and lump sums. As we expected, contracts converted into lifetime incomes likely have fixed interest types (93.8%), high interest rates (7.80%), and high MWRs (2.35), compared to lump sums (32.9%, 5.78%, and 1.67%, respectively).
4.2 Regression results
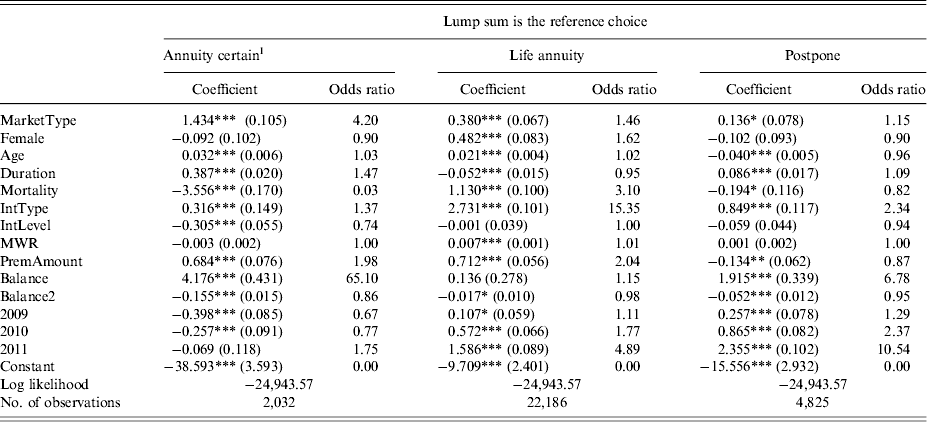
Table 6 presents the multinomial probit estimates for the full sample. The three outcomes in the table are: choosing the annuity certain option (first and second columns), the life annuity option (third and fourth columns), and postponing the choice of specific options (fifth and sixth columns). The omitted outcome is the lump sums. Under each category, Table 6 reports regression coefficients, standard errors, and odds ratio.
Determinants of payout choice
1 Annuity certain includes the interest-only withdrawal of the non-qualified contract.
Source: Authors’ calculations. The figures in parentheses are standard errors. Significance: * = 10%; ** = 5%; *** = 1%. Total N = 32,867.
Annuitization coefficients of market type (‘MarketType’) are statistically significant at the 1% level. Policyholders with qualified contracts are clearly more likely to choose a life annuity than are those with non-qualified contracts; individuals with qualified contracts are 1.46 times more likely to choose the life annuity option than the lump sum. Therefore, our findings do not support the hypothesis that other pension income crowds out voluntary lifetime annuity income. The major reasons for higher annuitization rates in qualified contracts are the tax on lump sums and homogeneity within the policyholders. Although non-qualified contracts have much higher annuity values (2.03 for qualified versus 2.20 for non-qualified), non-qualified contract type policyholders are more likely to choose the lump sums because of the tax incentive. Our result for different tax types is similar to that found in previous research. Banerjee (Reference Banerjee2013) finds that difference in defined benefit plan rules or features result in very different annuitization rates in the USA. He demonstrates that the rate of annuitization varies directly with the degree to which plan rules restrict the ability to choose a lump-sum distribution.
Another important result is that the probability of choosing the annuity certain option increases with the qualified type contract. Individuals with qualified contracts are more likely to choose the annuity certain option than the lump sum. The major reason for the higher choice rate of the annuity certain option in qualified contracts is the tax-free nature of the annuity certain option, compared to the tax on lump sums. In addition to the tax incentive for a regular income stream, the qualified group has strong demand for bridge pensions. Generally, the retirement age of workplace employees is about 55–57 years, but the age of eligibility for public pension is 60 years; therefore, such employees want to bridge the gap between retirement age and pension vesting age using their qualified contracts.
Overall, other variables are consistent with our expectations, except the duration variable. Females are 1.62 times more likely than males to choose annuitization; age increases the likelihood of annuitization by 1.02 times at the 1% level. Coefficients for life annuity prices are positive and significant, except assumed interest levels. These results are similar to those obtained in previous research on how change in the annuity's value affects the annuitization decision in Swiss occupational pension plans (Bütler et al., Reference Bütler, Staubli and Zito2010, Reference Bütler, Staubli and Zito2013). Annuitization rates increase with the monthly premium volumes, as a proxy variable for income and financial literacy. This result suggests that individuals in the high financial literacy group are significantly more likely to choose the annuity option. Accumulated assets strongly affect the decision on the payout option. The accumulated assets amount positively correlates to the probability of choosing the annuity certain option, and it is consistent with the magnitude effect: with a low balance, an annuity does not appear to be considered an option. In addition, we find a non-monotonic relationship between the annuity certain choice and accumulated assets. However, the relationship between the life annuity option choice and accumulated assets is not significant in our sample.
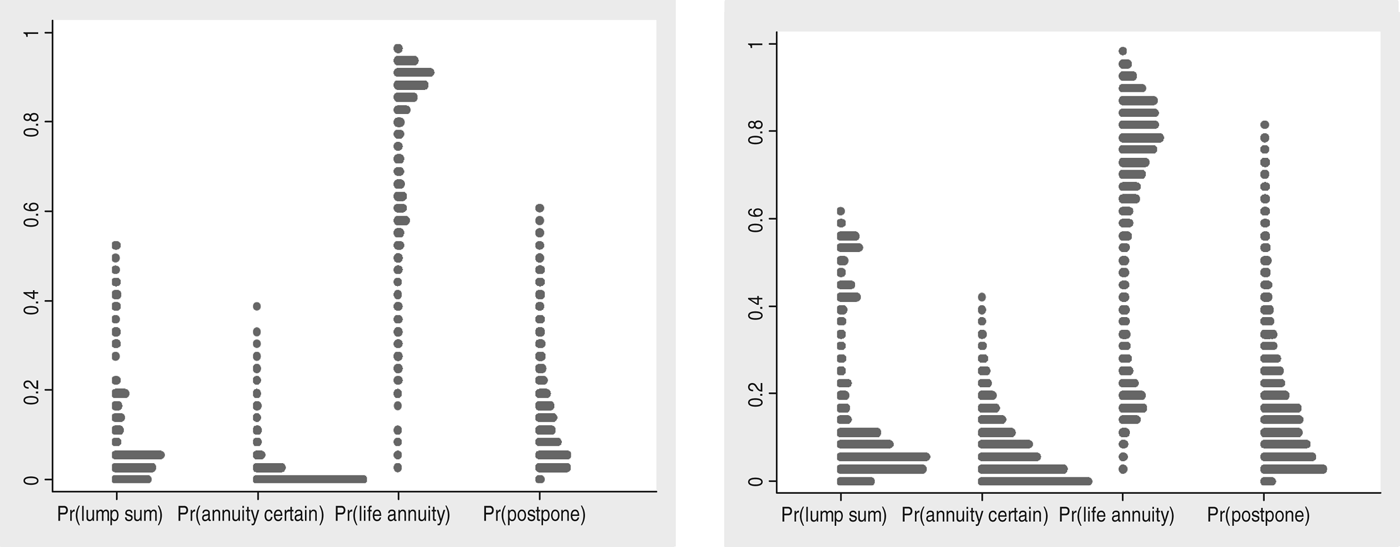
Finally, Figure 7 represents the predicted probabilities for payout choice in our sample. This outcome verifies the different profiles of choice behaviour between the qualified and non-qualified market types.
Predicted probabilities for payout choice by market types.
5 Conclusion
To enhance retirement income security, policymakers, and annuity providers would greatly benefit from understanding the main determinants of individual decision-making during the decumulation phase. Using a unique dataset from Korea containing 32,000 individual accounts at the maturity date of the accumulation phase, this study analyses how the payout choice decision varies across different types of individual annuities. Over 67% of individuals chose the life annuity option; thus, our findings complement existing studies on the choice between life annuities and lump sums.
We find new evidence that payout decisions strongly correlate to tax policy on lump sums. Approximately 79.0% of policyholders with qualified contracts (tax on lump sums) chose the life annuity option, whereas only 63.6% of policyholders with non-qualified contracts (tax free for lump sums) chose the life annuity option. We infer that major purchasers of the non-qualified annuities are self-employed persons and may thus have different characteristics from the qualified policyholders, who are predominantly workplace employees. This finding implies that the non-qualified contracts are primarily used as a tax-efficient investment vehicle in the accumulation phase, rather than as lifetime income sources in the payout phase.
Multinomial probit regression analysis shows that individuals with qualified contracts are 1.46 times more likely to prefer the life annuity option compared to the lump sum. This finding suggests that differences in tax policies for lump sums result in different annuitization rates from individual deferred annuities. Therefore, our study offers useful information for Korean policymakers interested in retirement income security: changes in tax policies are likely to increase annuitization rates in the non-qualified deferred annuity markets.
In addition to the market type, our results show that individual characteristics (gender and age) and contract features (assumed interest rate type and MWRs) significantly affect payout decisions.
To the best of our knowledge, no previous empirical study has examined the Korean individual deferred annuity market. Thus, the present study contributes new findings about how market types affect an individual's payout choice. Nevertheless, future research is needed to address our study's data limitation. Our sample may exhibit a self-selection bias.Footnote 18 If individual characteristics are correlated with the contract type and payout choice, our sample may have the omitted variable bias. This bias would not be a problem if one could perfectly control for all characteristics that determine both payout choice and choice of contract type. However, as we note, relatively little information exists on the background characteristics of the individuals in the data. When information on all contracts before the maturity date and omitted variables are considered, our findings could be generalized safely for the Korean individual annuity market. Future studies investigating this issue should consider the factor of annuity equivalent wealth, which incorporates risk-averse individuals (Brown, Reference Brown2003; Bütler and Teppa, Reference Bütler and Teppa2007).