

The lingering financial crisis has created an opening for reform in national regulation and global economic governance. The Group of Twenty rich and middle-income states (G20) has seamlessly edged out the Group of Seven rich ones (G7) as the indispensable forum for economic policy co-ordination. Long-defeated ideas, from regulating derivatives to a global reserve currency, are basking in policy limelight. The International Monetary Fund (IMF) has reinvented itself after a near-death experience, successfully deflecting challenges from new regulatory and regional fora.
This article explores the place of sovereign wealth funds (SWFs) in the reform moment. SWFs are state-controlled portfolio investment vehicles. The most prominent among them deploy surplus state capital in deficit countries, where they face political opposition and a shifting legal environment. I argue that SWFs began as an externally imposed category defined by their hosts’ fears, but captured public imagination in part thanks to their capacity as a group to reflect so many urgent policy concerns at once, at home and abroad. Efforts to define and govern SWFs reflect the challenge of managing financial integration in diverse markets, cultures, and legal and political systems in the absence of a stable hierarchy among them.
SWFs are diverse and contradictory. They grew dramatically over the past decade, reaching US$3 trillion under management in just a few years by some estimates. Yet commentators are still to agree on a single authoritative definition of the term “SWF”—a consequential debate I detail in Section I of this article. The funds come from all continents, from all along the national income spectrum, and are sponsored by all manner of governments. They adopt a variety of legal forms, reflecting diverse investment goals, strategies, and time horizons. SWFs also harbour internal tensions. Most SWFs are state-owned actors in state-dominated economies; yet when they go abroad, they claim forcefully to act as if they were private firms. Many funds come from countries that had been on the margins of the global financial system, including some that are very poor; yet in recent years, they have found themselves among the largest investors in rich countries that had long ruled this system.
SWFs’ hybrid character makes them, descriptively and prescriptively, all things to all people. They reflect simultaneously the development aspirations of the poor and Wall Street's hopes for rescue from financial crisis; home fears of state corruption and host fears of foreign capture; potential for enlightened global governance and a power shift to authoritarian state control. Unlike the more purely public or private vehicles such as central bank reserves or mutual funds, SWFs formally answer to diverse constituents, with no clear hierarchy among them. As private market actors, SWFs owe duties to their immediate owners and creditors, as well as their investment targets and host regulators. At the same time, SWFs are state actors that must be broadly accountable to the people at home, and subject to a wide range of international legal norms applicable to their home states. I describe these demands for accountability and their institutional implications in Section II of this article.
Studying how SWFs negotiate such demands yields insights for the governance of international finance. Early proposals for formal rules and sanctions to discipline SWFs produced minor changes in domestic law, the effect of which has been uncertain. These gave way to artefacts of soft law such as non-binding principles, private “naming and shaming” indices, informal alliances, and “soft institutions”—voluntary fora that lack legal personality. Most important among these, the non-binding Generally Applicable Principles and Practices announced by a group of SWFs in Santiago in mid-2008 (GAPP, or the Santiago Principles)Footnote 1 have since led to the creation of a standing SWF forum.Footnote 2Section III of this article reviews the public, private, domestic, and international governance efforts that led to the Santiago Principles. These efforts were dynamic and interactive, borrowing one another's methods, and competing for market and political space. Their product was an emphatically soft regime, but one that was acutely aware of its relationship to the prevailing formal institutions.
There are several explanations for the rise of soft measures in SWF governance so far; these lead to different predictions about their likely success and replicability. At one extreme, if SWFs choose a voluntary code to boost the public perception of their law-abiding character with no intention to comply, then the code may be useless at best or help cover up antisocial behaviour. On the other hand, if soft law helps SWFs negotiate the demands of diverse legal and political systems, it frames the way in which these important new actors engage with the existing order—and is important in its own right. With the Santiago Principles not three years old, it is too early to choose between these explanations; the answer is likely in-between. But even if the second explanation is only partly right, the path of SWFs is a valuable case-study of soft ordering as a response to the pluralism of law in international finance, and an experiment in new governance techniques.
This article proceeds as follows: Section I examines the struggle to define SWFs, which helps define the policy and theoretical conundrum they present. Section II situates SWFs at the intersection of accountability demands; Section III describes the search for legal and institutional response to these demands. Section IV concludes with policy and research implications.
I. Identity Politics
This much is agreed: Kuwait established the first SWF in 1953; SWFs grew dramatically in the first decade of the twenty-first century; Andrew Rozanov first used the term “sovereign wealth fund” in 2005;Footnote 3 and there is no universally agreed definition of SWFs.Footnote 4 Contested definitions in turn produce contested figures: leading estimates of the number and size of SWFs range from about seventy to eighty funds managing about US$4 trillion in international assets in 2009 to less than half this number and amount.Footnote 5 Continued struggles to define and measure SWFs are among the oddest and most telling attributes of their recent history.
SWFs flared up in host country politics between the terrorist attacks of September 2001 and the financial collapse of September 2008. They became a rolling reflection of host country fears: the fear of imperial decline and foreign invasion, the fear of debt, and the fear of big money. Yet few of the early public anxieties about SWFs were triggered by entities now defined as SWFs. In the United States, the SWF debate erupted on the heels of mishandled attempts by state-owned enterprises (SOEs), operating companies from China and the Persian Gulf, to buy into US oil and port facilities.Footnote 6 This raised the spectre of strategic takeover by undemocratic, non-market, and potentially unfriendly states. When Dubai Ports, an SOE from the United Arab Emirates, bid for a British firm that operated US ports, US media reports highlighted the fact that two of the 9/11 hijackers came from the UAE.Footnote 7 And even those who said there was no reason to oppose the acquisition of Unocal by China's state oil company noted its state-run economy and its status as creditor to the US government.Footnote 8 In the US and Europe, SWF controversy also followed an inflection of concern with “private pools of capital” (hedge funds and private equity),Footnote 9 to which SWFs were often compared. The “pools” were large, fast-growing, privately owned investment vehicles that variously had short time horizons, profited from market volatility, and took an increasingly active role in managing their investments. Although they had the capacity to transmit risk through the financial system, they seemed impervious to regulation.Footnote 10 In sum, in the public imagination SWFs looked big, hostile, and uncontrollable, if only by analogy.
From the perspective of SWFs and their supporters, host country critics were being wilfully ignorant at best, protectionist and bigoted at worst; regardless, they “had the wrong guy”. To be sure, SWFs were large and state-owned. But most SWFs, unlike SOEs, refrained from active management of their targets. In contrast to hedge funds and private equity, many SWFs were “patient capital”: their very long investment horizons promised to stabilize volatile markets.Footnote 11 By 2008, opponents of sovereign investment also stood accused of biting the hand that fed them: SWFs were among the few still willing to invest in the tottering financial sectors in New York and London.Footnote 12 On all sides of the debate, the essential characteristics of the subject were up for grabs.
Rozanov, an economist with a private investment firm, first described SWFs in the negative as “neither traditional public-pension funds nor reserve assets supporting national currencies”.Footnote 13 To constitute a SWF, a pool of funds would have to be managed separately under guidelines distinct from those applicable to central bank reserves, to achieve “more broadly diversified and risk-tolerant sovereign wealth”.Footnote 14 The IMF's first major public product dedicated to SWFs had an appendix-full of formal definitions, highlighting the magnitude (or futility) of the classification challenge.Footnote 15 Universally shared SWF characteristics were limited to state control and macroeconomic purpose.
Disagreements reflect the competing interests of the definitions’ proponents. The SWF category was launched in 2005 largely unconstrained by the self-perception of the funds’ owners and managers. Instead, early “definers” fell roughly into three groups: market actors whose business was affected by the rise of SWFs;Footnote 16 host country governments managing the political fall-out from SWF investments;Footnote 17 and academic and civil society observers engaged in policy advocacy.Footnote 18 The three groups used the term “sovereign” differently. For market participants, sovereign often meant autonomous, at least partly insulated from market pressures, and therefore freer to take longer-term risks.Footnote 19 For host governments, SWFs’ sovereignty held the promise of diplomatic engagement and responsible public behaviour.Footnote 20 For civil society observers, sovereignty could imply a fiduciary relationship with the people or some subset thereof.Footnote 21
SWFs mattered to each of these groups because, however defined, SWFs were big and growing fast. In just a few years, they went from millions to trillions of dollars in assets under management, surpassing hedge funds; early on, they were expected to triple in five years.Footnote 22 Even after losses from the financial crisis,Footnote 23 SWFs’ size kept them at the heart of national development and investment strategies, and national and global financial stability.
Unlike their hosts, brokers, and observers, SWF sponsors first resisted the category. For them, the term “sovereign wealth fund” purported to describe competitors with little in common, most of which had not interacted (much less collaborated) until they became the target of host country hostility. SWFs come from rich European states like Norway, and new, impoverished ones like Timor Leste, with Azerbaijan, Botswana, Chile, China, Russia, and Singapore in-between. Almost every continent and form of government is represented, though relatively few SWF home states conform to Western notions of representative democracy.Footnote 24 Some funds have decades of investment experience, but more than half are new.Footnote 25 Their stated goals vary widely, from current macroeconomic policy to long-term development. Some invest at home, others abroad; many do both.Footnote 26 Sources of funds range from export revenues to foreign aid inflows.Footnote 27 Some SWFs invest net government savings, others borrow from their central banks; few borrow from the markets.
SWFs only conceded group affinity after three years on the defensive, in late 2008, as they proffered their own definition in the Santiago Principles. This effectively set forth criteria for membership in their club:
SWFs are defined as special purpose investment funds or arrangements, owned by the general government. Created by the general government for macroeconomic purposes, SWFs hold, manage or administer assets to achieve financial objectives, and employ a set of investment strategies which include investing in foreign financial assets.Footnote 28
SWFs thus excluded traditional reserves, state-owned enterprises, purely domestic funds, and pension funds. SWF states retained the flexibility to organize funds as they saw fit under domestic laws, and left unaddressed the tension between SWFs’ policy purposes and market objectives. The new definition also declined to formalize the funds’ role as passive long-term portfolio investors, an aspect of SWF history usually invoked to relieve host anxiety over political interference and volatile capital flows.
As a result, SWFs’ own manifesto reprised the jumble of contradictions that had become their trademark: they were public money that pledged to act private, vast pools of capital that promised not to move markets, non-controlling investors that managed centrally controlled economies, and public fiduciaries that balked at corporate governance of their investment targets. Such contradictions present a stark governance challenge, the subject of the next section.
II. Axes of Accountability
SWFs’ initial response to host fears was fragmented, thanks in part to the diversity among them. Each fund was potentially subject to a unique set of legal and political demands reflecting its provenance, constitution, and investment targets. This made it hard for SWFs to co-ordinate among themselves. It was similarly hard for SWF hosts to devise a unified response to something that was not a unified phenomenon: a framework designed for Norway may not work for China or Abu Dhabi, and vice versa.
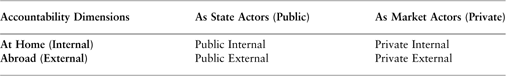
Nevertheless, the funds share a structural challenge: they answer simultaneously to four kinds of constituents. SWFs are accountable to the people at home and abroad; to the public at large, and to a narrower set of stakeholders defined by their organizational form and business practices as market actors. To be sure, SWFs are not unique in juggling conflicting demands. Any firm operating across national boundaries must to some extent answer to home and host state demands. Similarly, public-private hybrids like government-sponsored enterprises must reconcile duties to their shareholders with duties to the public. SWFs are unusual because they must address all four dimensions at once; moreover, with multiple sovereigns involved in multiple capacities, there is no obvious hierarchy among the demands for SWF accountability, as set out in Table 1.
Four kinds of SWF accountability
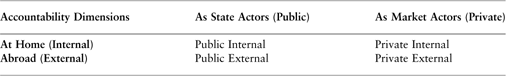
In place of a hierarchy, an effective framework for governing SWFs must enable ongoing negotiation among the different dimensions of accountability, which I elaborate using case-studies in the remainder of this section. The next section explores the evolving institutional response to this challenge. The goal is to understand to whom SWFs answer, so as to decide to whom they should answer and to find ways to resolve conflicts among SWFs’ constituencies.
A. Public Internal Accountability: Russian Experiments and Kuwaiti Scandals
Public internal accountability describes SWFs’ duties as state actors at home—as custodians of public funds answering to their domestic citizenry at large, expressed directly or through formal government structures. Such accountability demands surface most often at the time of SWF establishment, or in crisis, when the people find out either that the fund failed to live up to its mission, or that the mission itself was flawed. Public internal accountability for SWFs is tied up with domestic politics: SWFs are trophies and symbols of national power; they can become focal points for political expression and drive political change. This form of accountability relies on the availability of information that strikes a domestic political nerve. It has played an important role in the newest and oldest SWFs alike. In this section, Russia's repeated attempts to establish a sovereign wealth fund illustrate the role of domestic political pressures in SWF policy; a 1993 scandal involving the world's oldest SWF in Kuwait shows the capacity of SWFs to catalyze public demands for broader political reform.
Russia came late to the SWF scene. As recently as June 2008, Prime Minister Vladimir Putin told the visiting US Treasury Secretary that Russia had no SWF.Footnote 29 This was true in the sense that the state investment vehicles Russia had established in 2004 still held primarily high-quality foreign government paper, much like official reserves.Footnote 30 On the other hand, Russia's plans to run a more aggressive fund on the model of other oil-exporting states made it a poster child for host state fears. Commentators criticized the “semi-authoritarian” habits of Russia's government and pointed to the history of crude political interventions by its SOEs.Footnote 31
Against this background, the vigour of Russian domestic political debates about SWF policy, and the government response, are instructive. Not only were SWF policies hotly contested in the press, but the government reorganized the funds at least twice in their brief history, apparently in response to popular pressure.
Russia had barely recovered from its 1998 financial crisis when it began considering, with IMF support, a fiscal stabilization fund financed from excess oil revenues.Footnote 32 After a fund was established in 2004, the IMF argued that Russia should save more oil revenues to insure itself against future price declines, control government spending, and temper inflation.Footnote 33 However, much of the domestic commentary favoured a development fund model investing in infrastructure and domestic enterprise.Footnote 34 At the outset, Russia formed a basic stabilization fund holding safe foreign government debt; some excess oil revenues were also used to meet pension obligations and pay down Russia's own debt.Footnote 35 But a year later, Russia broke off roughly US$9 billion from the stabilization fund to form a domestic infrastructure and growth fund. In early 2008, the government further divided up the remaining stabilization fund into a US$125 billion Reserve Fund, which continued the original mission, and a US$32 billion Fund for National Well-Being, whose mission was actively contested.Footnote 36 The smaller fund was ultimately given a public pension mandate.Footnote 37 All three funds were on-budget and reported to the finance ministry. In all, the authorities responded to domestic pressure by “splitting the baby” among their public constituents.
By the time financial crisis hit Russia in 2008, the US$9 billion infrastructure fund had invested less than 1 percent of its allocation; it was ultimately raided to cover budget deficits.Footnote 38 While the Reserve Fund was also drawn down to cover the deficits, this was consistent with its fiscal stabilization mandate. At the time of writing, the Reserve Fund stands at less than a third of its pre-crisis levels.Footnote 39 In contrast, the Fund for National Well-Being has grown almost threefold, to about US$90 billion since 2008.Footnote 40 However, its path to growth was unorthodox: during the crisis, the fund was used to defend the rouble, invest in the Russian stock market, and support Russian banks and “strategic” domestic firms; it also funded construction loans for the Olympic village.Footnote 41 The pension-savings fund became a rescue-stimulus fund.
Russia's experience illustrates three aspects of SWF accountability that have relevance beyond Russia. First, old Western democracies do not have a monopoly on public internal accountability. Illiberal governments may alter their SWF investment strategy in response to public pressure. Second, where broad-based domestic crisis response imperatives come into conflict with the fund's formal mission (here, pension funding)—the contest between public and private internal accountability is resolved ad hoc. Domestic legal constraints do not always bind the sovereign.Footnote 42 Third, and related, sovereigns do and must have the capacity to change their minds. If public internal accountability is to be taken seriously, infrastructure or pension SWFs should be used as strategic weapons if the domestic public so wishes.Footnote 43 Whether the public does so is a separate matter.
Public outrage about SWF mismanagement can also channel demands for broader domestic liberalization, altering formal political accountability structures in SWF home countries. A 1993 scandal involving Kuwait's SWF investments in Europe appears to have played such a liberalizing roleFootnote 44 long before SWFs were named, and before the latest round of democratic demands directed at Arab SWFs.
The entity now known as the Kuwait Investment Office (KIO) in London was established in 1953, and is widely recognized as the world's oldest SWF. Like its parent Kuwait Investment Authority (KIA) established in 1982, KIO is an asset manager for the finance ministry; it does not own the assets.Footnote 45 KIA manages the government's General Reserve Fund and the Fund for Future Generations (FFG), which has a common SWF mandate of turning underground wealth into financial assets for intergenerational transfer. The FFG receives 10 percent of Kuwait's annual oil revenues. The 1982 law that established KIA prohibits “disclosure to the public of any information related to KIA's work”, including the value of its assets under management, privately estimated at just over US$200 billion.Footnote 46 Instead, the law mandates reporting to the Council of Ministers.Footnote 47 What limited public awareness there had been of KIA's and KIO's management of FFG diminished after Kuwait's parliament was disbanded in 1986. When Iraq invaded Kuwait in 1990, “KIO's holdings became the national treasury-in-exile”.Footnote 48 By the war's end, at least half of the US$85−100 billion estimated pre-war asset value had gone.Footnote 49
Although much of the money was used for war and reconstruction expenses, when the National Assembly reconvened in mid-1992, it discovered that some of the funds had simply vanished without a trace, others were used to buy bad debts reportedly owed to local banks by well-connected Kuwaitis, yet others were simply mismanaged. KIO's Spanish portfolio, estimated at US$5 billion, had been completely lost to a combination of dubious investments in Spain's declining economy and suspicious fees.Footnote 50 Perhaps coincidentally, KIO's first big Spanish investment of US$900 million came the year parliament had been disbanded.
KIO's new management was installed after losses were uncovered in 1992. The incident became a focal point for debates in the new parliament and catalyzed the passage of a new law requiring KIA to report to the parliament twice a year on “all major state investments”; it also unleashed furious criticisms in the press framed squarely in terms of public oversight and accountability.Footnote 51 The authorities banned local press coverage of the incident in January 1993; however, fears that the parliament would be disbanded again did not materialize.
To be sure, those implicated in the Spanish scandal described their predicament, and the lawsuits against them in the UK, as a postwar political witch hunt.Footnote 52 And even though English judges ruled in Kuwait's favour,Footnote 53 the full story behind the scandals remains murky. It is certain, however, that domestic public demands for SWF accountability had a political impact far beyond the fund itself, and reverberated in host states and international markets.
In sum, SWFs are highly visible domestic political actors. Their survival depends in important part on their ability to answer popular demands; in doing so, they may reflect and even drive political change.
B. Private Internal Accountability: Form Sharing in Singapore and Abu Dhabi
Private internal accountability captures SWFs’ duties to a particular group of domestic constituents, rather than the public in general; it can also describe SWF constraints under a specialized mandate. The simplest example is a pension fund managing particular citizens’ retirement savings. Such a fund might be tightly integrated into state finances and used to supplement budget revenues; even so, it likely owes a distinct set of duties to a designated subset of beneficiaries. The discussion of Russia's SWFs in the previous section points to another feature of private internal accountability: the legal form in which a fund is organized, its mission, and its contracting practices may create demands on SWFs that complement or conflict with broader public needs. Examples from Singapore and Abu Dhabi develop the significance of such factors.
Singapore and Abu Dhabi each use two distinct types of SWFs: a stabilization/savings fund invested exclusively in foreign assets, and a development fund specializing in strategic investments at home and abroad. The stabilization/savings funds—the Government of Singapore Investment Corporation (GIC) and the Abu Dhabi Investment Authority (ADIA)—are financed from budget surpluses and foreign exchange reserves; they do not borrow in the markets. Like KIA, described in the previous section, GIC and ADIA manage, but do not own the assets attributed to them. The SWF entity is organized as a management company for public funds.Footnote 54 In contrast, the development funds—Temasek Holdings in Singapore and the Mubadala Development Company in Abu Dhabi—own the assets they manage; unusually for SWFs, they also engage in limited market borrowing.Footnote 55 When governments use different organizational forms, they shape distinct constituencies for SWFs, which in turn demand distinct disclosure practices of the same government. The use of similar forms across very different legal systems helps illustrate the point.
Cross-country parallels are especially revealing in view of the many differences among the four funds. ADIA, estimated at over US$600 billion, is one of the world's largest SWFs; it is about thirty times the size of Mubadala, valued at just over US$20 billion.Footnote 56 ADIA is also almost thirty years older, formed as a stand-alone legal entity in 1976 to manage the government's oil surpluses;Footnote 57 its current mandate is to invest government funds “to secure and maintain the future welfare of the Emirate”.Footnote 58 Its stated policy is to keep its equity stakes in target firms under 5 percent and to refrain from voting its shares. Mubadala, formed in 2002, is a product of a more recent round of commodity price spikes. It is charged with helping diversify the Emirate's economy by making long-term, capital-intensive investments focusing on Abu Dhabi, the UAE, and the surrounding region; its mission is somewhat more specific than ADIA's and includes delivering both a “strong financial return” and a “tangible social impact”.Footnote 59 Almost two-thirds of its investments are domestic; it takes significant equity stakes and does not shy away from voting them.Footnote 60
GIC's estimated US$250 billion in assets are roughly double Temasek's.Footnote 61 It was founded in 1981 as a reserve management vehicle for the government and the Monetary Authority of Singapore; its current mission is broadly consistent with its origins: “to achieve good long-term returns” on state assets “to preserve and enhance the international purchasing power of Singapore's reserves”.Footnote 62 In contrast, Temasek started as a domestic SOE holding company in 1974; its early history and initial mandate are linked with the post-independence development of Singapore, not reserve management.Footnote 63
Neither Mubadala nor Temasek consider themselves to be SWFs, although they fit the Santiago Principles definition, and outside analysts routinely classify them as SWFs.Footnote 64
All four funds provided very little public disclosure until recently. ADIA was particularly stark in revealing only its address and switchboard number before 2010. This opacity did not seem to pose a problem before the mid-2000s: all but the newly formed Mubadala were well known among international financial market participants;Footnote 65 at home, they generally reported to their government authorities behind closed doors. In response to host country pressure, the funds have all ramped up their public information flow in recent years; all four have also sought to emphasize their commercial character, substantial autonomy from their respective governments in selecting investments, and corporate social responsibility.Footnote 66 Temasek was the first of the group to release an annual report in 2004, including the total size of its holdings, earnings, and portfolio information.Footnote 67 It has since published externally audited financial statements. GIC has released two annual reports since 2008, outlining its governance and investment objectives, though not its size or the details of its portfolio. Mubadala has published annual reports since 2008, and externally audited financial statements since 2009.Footnote 68 ADIA came last; its first “Annual Review” came out in March 2010, broadly addressing the firm's mission and structure, but not its total size or investment details.Footnote 69
The differences between Temasek's and Mubadala's relatively fulsome disclosure and the more measured revelations of their bigger siblings faced with the same host country controversy illustrate a distinct set of demands on the funds, generally associated with private internal accountability. First, Temasek and Mubadala both issue debt securities in the international markets, where investors expect (and many regulators require) standardized financial reporting and narrative disclosure.Footnote 70 Domestic stakeholders can benefit from such disclosure as well. Second, their investment mandates, which contemplate larger stakes held for longer and managed more actively for the sake of domestic development, make it more difficult to keep investments quiet. Third, if the funds abide by their long-term development objectives, this may reduce the immediate macroeconomic policy sensitivity of their disclosure: for example, they are less likely to be used for foreign exchange intervention. On the other hand, their capacity to take bigger stakes in target firms may have a bigger effect in the market.
Inasmuch as Temasek and Mubadala owe duties to their private creditors along with their state shareholders, they commit to accountability practices that may exert continuing disciplineFootnote 71 and engender path dependence. Financial reports and credit ratings will be compared over time, along with their investment track record at home and in different parts of the world. Such private accountability in turn has public implications. Private analysts—and with them, the media—will note and publicize disclosure cutbacks and discrepancies. Similarly, the more narrowly specified the fund's mandate and holdings, the more noticeable the deviations, even where these may serve the public interest broadly. Finally, the smaller funds’ mandate of domestic and foreign asset holdings may prompt domestic and foreign audiences alike to pay attention.
Examples so far suggest that private internal accountability may enhance, overlap, or conflict with public internal accountability, depending on whether the narrower mission or constituency reflects the broader public interest at the time. Similarly, both forms of internal accountability may support or conflict with external demands for accountability, to which I turn next.
C. Public External Accountability: Norwegian Ethics
Much of the early host country criticism of SWFs amounted to this: Why could all SWFs not be like Norway's? Norway's Government Pension Fund–Global (GPFG) began operations in the mid-1990s. At the time of writing, GPFG's market value is estimated at about US$430 billion, of which almost two-thirds is in equities.Footnote 72 A real-time value tracker is prominently displayed on the website of the fund's investment manager, as if to highlight the contrast with Middle Eastern oil exporters, where such disclosure is legally barred.Footnote 73 GPFG was authorized by the Norwegian parliament in 1990, and operates as a finance ministry account at the Norwegian central bank, holding budget surpluses from oil revenues with the twin goal of macroeconomic stabilization and saving for future generations. Unlike Norway's domestic pension fund, GPFG only invests abroad. The fund is subject to independent audits and periodic reports to the legislature, and is required to make public disclosure of its size and investment strategy.Footnote 74 The relationship between GPFG's investment behaviour abroad and its domestic legitimacy makes it an interesting case-study of the link between public internal and public external accountability.
As an international investor, GPFG responds to accountability demands in two ways. First, its transparency practices—including comprehensive disclosure in English, and disclosure of factors such as the use of leverage and derivatives—comport with Norway's frequently voiced commitment to global financial stability (a public good) and its openness to public oversight.Footnote 75 Second, the fund's investments reflect the recommendations of an independent advisory body, formed to advance compliance with Norway's obligations under international law and internationally accepted ethical norms. The advisory body—initially, the Advisory Commission on International Law for the Fund, since replaced by the Council on Ethics—makes non-binding recommendations to the finance ministry, which instructs the central bank to exclude particular investment targets.Footnote 76 The substantive screening methodology is in addition to the central bank's mandate to exercise strong corporate governance in connection with fund investments, so as to maximize sustainable returns for future generations.Footnote 77 This set of institutional mechanisms geared to global citizenship also establishes a process by which the fund's ultimate owners (“the people of Norway, represented by the political authorities”)Footnote 78 ascertain the SWF's domestic legitimacy.Footnote 79 In effect, the domestic public demands international (public external) accountability.
The content of GPFG's external accountability has evolved. In the beginning, the focus was on securing compliance with Norway's formal treaty commitments. With time, the fund became a means of elaborating a broader and more complex ethical regime that included non-binding norms such as the United Nations Global Compact, which advance “public accountability” for private transnational firms,Footnote 80 and labour and environmental standards, as well as anti-corruption norms, which had widely different legal origins and status under national and international law.Footnote 81 In its first two years of existence, following the Council on Ethics recommendations, the finance ministry proceeded to screen out firms for concerns ranging from cluster weapons to poor labour practices.Footnote 82 It has developed novel, quasi-legal notions of complicity to support Norway's practice of ethical investment.Footnote 83 GPFG has also engaged internationally alongside other SWFs and private institutional investors, and directly in investor states, to advance a framework for capital movements that is both “responsible” in the public sense and hospitable to the fund as a profit-seeking investor.Footnote 84
It bears emphasizing that the Norwegian SWF's avowed external responsibilities as a state actor are not the mechanical output of established treaty commitments and customary international law. Instead, they are a complex product of international law, domestic and international politics, and global market socialization. The resulting mix is particular to Norway, and is being projected internationally. It is contested in many quarters, both by countries whose firms have been screened out,Footnote 85 and those who have found themselves on the wrong side of Norway's market positions.Footnote 86 On the other hand, echoing the progressive law-making potential of the Norwegian SWF, scholars have recently proposed using SWFs as vehicles to advance human rights in host countries.Footnote 87
Thus, despite its renown and active international engagement, Norway does not give the definitive answer on the scope of SWFs’ duties to the international system. When observers extol SWFs’ role as “patient capital”,Footnote 88 does it follow that systemically significant SWFs must refrain from aggressive trading for the sake of global stability? When the US asks China to invest commercially, does it expect the China Investment Corporation (CIC) to hold US financial stocks in a crisis? Transparency is a perennial bone of contention: failure to disclose SWF positions can impede macroeconomic surveillance and potentially unsettle the markets; full disclosure might put SWFs at a disadvantage to their more opaque brethren and wholly private competitors.Footnote 89
D. Private External Accountability: Chinese Bank Holdings
While public external accountability captures SWFs’ public duties as state actors operating transnationally, private external accountability keys off SWFs’ claim that they are commercial actors in their hosts’ markets. Private firms investing abroad are subject to a range of legal constraints, from specialized foreign investment and regulatory regimes (corporate, securities, banking, environmental, food and drug) to generally applicable civil and criminal laws of their host states. Regulating sovereigns operating as private players in foreign markets has long been a challenge for host governments. Quite apart from questions of sovereign dignity, host laws make and enforce demands on private market participants in ways that may be ineffective or inappropriate for achieving the same ends with foreign governments. Early vocal concerns about SWF compliance with host country securities laws, along with proposals to adjust the hosts’ tax and corporate laws to address SWF acquisitions,Footnote 90 represent the latest round in a long debate over integrating state actors into private foreign markets. The way in which this debate has evolved in US bank regulation, culminating in a recent controversy over Chinese SWF investments, illustrates the work of private external accountability.
The June 2008 meeting of US-China Strategic Economic Dialogue was stalling over an unlikely issue: a bank licence. Dialogue meetings were launched several years earlier in response to concerns about bilateral imbalances; they had become high-level affairs at which top cabinet ministers sought to advance economic and security matters where US-Chinese co-operation was key. But on the eve of the June meeting, China had publicly expressed alarm over US delays in approving two Chinese banks’ applications to open outposts in New York, suggesting “a political ploy and part of a US negotiating strategy” to gain advantage in the broader dialogue agenda.Footnote 91
From China's perspective, US regulators must have looked meddlesome and parochial. The Federal Reserve (“the Fed”) had balked at what was essentially a domestic bureaucratic reshuffle in China, where the government had decided to make its bank holding SWF, Huijin, a subsidiary of CIC, the newer SWF with a broader mandate.Footnote 92 From the Fed's perspective, this domestic change brought CIC squarely within the purview of the US Bank Holding Company Act of 1956 (BHC Act), which subjects companies controlling US banks to a special regulatory regime, including registration requirements, restrictions on transactions with affiliates, strict limits on non-banking and non-financial activities within the group, and Federal Reserve supervision.Footnote 93 The BHC Act is part of a broader framework of US laws separating banking from commerce, prudential regulations limiting risk to the federal deposit insurance fund, and policies addressing power concentration, conflicts of interest, credit allocation, and community development. This framework tries to insulate the insured depository institution from potential exploitation by the holding company and/or other affiliates, for example, restricting affiliates’ capacity to use the bank as a cheap source of funds for their commercial or securities business. Subjecting CIC to BHC Act constraints presented a problem for China: as a general-purpose SWF reportedly modelled on Temasek,Footnote 94 CIC could hardly refrain from non-financial investments altogether. Moreover, since Huijin was already a bank holding company for US purposes as a result of prior Chinese bank entries, the Fed's need for also regulating CIC was lost on its home authorities.
Contrary to Chinese government suspicions, it is unlikely that the Fed used the bank holding company issue as a pretext to block Chinese bank entry, to gain negotiating leverage, or even as a way to slow the influx of Asian and Gulf interests in the US financial sector.Footnote 95 Regardless, the Fed's approach came out of a thirty-year-old line of administrative decisions about the meaning of the word “company” in the BHC Act, where US regulators struggled with the implications of covering state-owned firms. The plain language of the BHC Act applies to a “company” that controls a US bank or another bank holding company; however, the Act specifically exempts companies majority-owned by the US federal and state governments.Footnote 96 Federal Reserve Board decisions going back to the 1970s affirm that foreign governments are not “companies” for purposes of the BHC Act, but refuse to extend the exemption afforded US government-owned companies to companies owned by foreign governments.Footnote 97 From the Fed's perspective, CIC's predicament was structurally identical to that of an Italian state bank holding company whose subsidiary sought to enter the US twenty years earlier:
[T]he issues raised by foreign government ownership of banks operating in the United States … present complex problems of the compatibility of the broad scope of commercial and industrial activities [of the Italian state holding company] with the stated purposes of the BHC Act—preventing conflicts of interest, avoiding concentration of resources, and maintaining the safety and soundness of banks in the United States.Footnote 98
The policies behind the BHC Act demanded that a separately organized, diversified foreign “company” be regulated presumptively as a private market actor even if it were owned and controlled by a foreign state. However, in deference to diplomatic and functional imperatives, the Fed was prepared to exempt a state-owned company from the strictest rules mandating separation of banking and commerce at the holding level, in exchange for contractual undertakings to restrict transactions with affiliates and to refrain from cross-subsidies and cross-marketing.Footnote 99 In effect, US regulators in 1988 had synthetically replicated the private BHC Act regime in the form of a conditional exemption for foreign state-owned firms, designed to protect US depositors, taxpayers, and markets.
The Fed ultimately granted the disputed Chinese bank applications in August 2008, on much the same terms and using the same exemptive authority as it had used for the Italian state firm in August 1988.Footnote 100 CIC and Huijin would both be bank holding companies, but could continue investing in commercial firms as long as they lived by contractual commitments that walled off the banks operating in the US market. Since the decision, three Chinese banks have entered New York. Together with earlier arrivals from China, they quickly became a force in US corporate lending, partly replacing the newly cautious US banks as credit providers to the host economy.Footnote 101
This relatively happy ending for the contest between internal accountability (SWF organization in China) and external accountability (bank regulation in the US) leaves open the question of enforcement. Enforcement is not a side issue: immune sovereigns may have trouble credibly committing to comply, and have means of evasion unavailable to private firms. Ceremonial promises on the part of SWFs to live by host laws that already apply to them look like feckless political theatre. On the other hand, more muscular proposals to limit SWFs’ capacity to “act private” may have limited practical impact. For example, formally suspending SWF shareholder voting rights to pre-empt non-commercial interference matters less when a SWF can credibly threaten to exit even on non-commercial terms, or when its finance minister can call the CEO or her host government counterparts. Latent capacity to exert influence and get private information through government channels is a defining feature of sovereign investments; modifying corporate voting rules in a sense puts too much stock in SWF claims to private behaviour, and too much faith in the traditional Western methods of private accountability.
Furthermore, if the proposed restrictions were effective on their own terms, the normative assumptions behind them would still merit a closer look. Is disenfranchising public shareholders (and thereby empowering the rest) good for host state corporate governance?Footnote 102 Does it serve government accountability in the home country? More cynically, is depriving Russia of a formal shareholder vote worth giving up Norway's role in advancing international labour rights? Put differently, holding SWFs strictly accountable as market actors in host states may both distort the tools of private accountability (shareholder voting), and detract from other dimensions of accountability.
* * *
In this section, I have described SWFs as subject to four kinds of accountability demands. A core argument of this article is that such “axes of accountability” define the SWF predicament and unite the disparate actors at their intersection. These demands do not stand in a clear hierarchical relationship to one another. Privileging one set may reinforce or undermine the others, depending on the circumstances. When the SWF phenomenon captured public attention at home and abroad, there was no accepted process for resolving the conflicting demands. The next section traces attempts to fill the gap with private, public, and hybrid governance devices.
III. Artefacts of Accountability: Laws, RATINGS, and best practices
Early efforts to govern SWFs came in four basic forms. First, domestic legislation in host states sought to limit SWF entry and secure their compliance with host laws applicable to market participants. These formal measures were deliberately limited. Their priority was shielding the host states and their markets from political interference without driving away much-needed foreign investment or setting off a protectionist response. Second, apparently non-binding statements by host state officials and some joint pronouncements with SWF sponsors articulated an additional layer of expectations, usually in the form of broad guiding principles, whose stated aim was to commit SWFs to apolitical, professional, and law-abiding behaviour.Footnote 103 Third, work by non-government actors to define SWFs often carried an embedded governance agenda. Their products ranged from research reports that sought to shape the category and make up for the lack of SWF disclosureFootnote 104 to more traditional private ratings of government transparency and business climate. Fourth, formal international institutions and instruments had a surprisingly low profile from the start of the SWF debates. This may have been due to the impaired legitimacy and contested jurisdiction of two key actors: the Organisation for Economic Co-operation and Development (OECD) and the IMF. This section analyzes the way in which the different approaches came together in a soft governance regime with the Santiago Principles at its centre.
A. Host Laws and Exhortations
The US investment regime reflects a compromise between openness and national security, shaped in large part by the last influx of petrodollars in the 1970s and a wave of Japanese acquisitions in the 1980s.Footnote 105 Against the presumption of openness, the Committee on Foreign Investment in the United States (CFIUS) in the Executive Branch decides whether an investment poses a national security threat. Where it does, CFIUS recommends changes or blocks the deal. The Dubai Ports bid discussed earlierFootnote 106 was the biggest test for this compromise in the new financial and security environment, where global economic imbalances and terrorism fears ran rampant. CFIUS allowed the acquisition; public outrage framed the legislative response and coloured the subsequent debate on SWFs. CFIUS went from obscurity to celebrity overnight. It became an emblem of the controversy over sovereign investment, a prominent early site of the policy battle, and inspired imitators around the world.Footnote 107
By the summer of 2007, a new law in the US responded to the SOE investment crisis with minor tweaks to the open investment framework established in the 1980s. US Congressional attention then turned to SWFs, possibly reflecting heightened awareness of the many forms and implications of sovereign investment, spreading worries about macroeconomic imbalances and financial stability, and above all a shared need to avoid more damaging political surprises.Footnote 108 Other host legislatures went through similar debates.Footnote 109
For their part, US Treasury officials were determined to avoid a repeat of Dubai Ports as they observed the rise of SWFs in early 2007. In May they hosted a special G20 workshop on SWFs, where the idea of best practices was floated before concerned states, private researchers, and the IMF, perhaps as a way of pre-empting more restrictive investment laws.Footnote 110
The passage of the 2007 investment legislation in the US was a definitive accomplishment in one respect: preserving the open investment status quo in the face of strong opposition in a hostile economic and political climate. Since it was prompted by SOE acquisitions and focused on national security, the law did not aspire to, or achieve, an overall vision for SWF governance. As new legislative initiatives floundered, the affirmative case was left entirely and by design to non-binding pronouncements—such as G8 and G7 communiqués calling for SWF “best practices” while reaffirming the hosts’ commitment to open investmentFootnote 111—and statements of general principles by US Treasury and European Commission officials.Footnote 112 In March 2008, the US, Singapore, and Abu Dhabi issued a joint statement of “policy principles” for SWFs and their hosts, to serve as the basis for the work on “voluntary best practices” pursued in multilateral fora.Footnote 113 The principles called on SWFs to commit to act commercially, to ramp up their public disclosure of market-relevant information, to professionalize their management and internal controls, and to abide by host country laws. In return, host countries would refrain from protectionism, discrimination, and interference. It is hard to assess the political impact of such statements; their goal was to signal co-operation. As a legal matter, they added little if anything to the parties’ existing obligations. And the vagueness did not obscure sensitive detail—rather, the absence thereof.
B. Index Ordering
Much of the operational content for SWF governance first appeared in a “scoreboard” proposed by Edwin M. Truman of the Peterson Institute of International Economics. Truman, formerly a senior US finance official, attended the G20 workshop hosted by the US Treasury in May 2007, and published a series of comments and policy briefs in 2007 and 2008 specifically geared to influence US and international policy design. Truman's treatment of SWFs differed in important ways from other policy and academic writing of the day: he went beyond the security-protectionism quarrelFootnote 114 to articulate the need for broad-based accountability, including recognition of the funds’ duties to “their citizens, the markets, and the general public, including outside the country”.Footnote 115 His first “blueprint” for SWF best practices comprised structure, governance, accountability and transparency, and behaviour prongs; compliance was evaluated based on “Yes/No” answers to thirty-three questions, using publicly available disclosure. His scoreboard based on the blueprint rewarded clear and separate organization, funding and decision-making transparency, regular public reporting, independent audits, and policies relevant to financial stability, such as the use of leverage and derivatives. It ranked SWFs on a hundred-point scale.
By defining SWFs to include Northern and Western government pension funds, Truman sought both to hold SWFs to a higher standard, and to make incipient SWF norms more broadly relevant to all very large global investors. Including pension funds also gave Truman's scoreboard pragmatic credibility: at least one fund could answer “Yes” to at least one of the thirty-three questions, which could then claim to reflect existing practice. Pension funds as a group did better than non-pension funds, but with considerable variation within group scores.Footnote 116
At about the same time, the Sovereign Wealth Fund Institute, an information hub run by US entrepreneurs Carl Linaburg and Michael Maduell, released a SWF transparency index that measured some of the same factors as Truman's scoreboard, but was pitched to a broader market and media audience. The Linaburg-Maduell Transparency Index (LMTI) defined SWFs to include several traditional reserve management vehicles, and scored all funds on a ten-point scale, based on ten equally weighted questions. Like Truman, Linaburg and Maduell rewarded clear organization and regular, independent disclosure. On the other hand, they bundled some factors that Truman had disaggregated (such as disclosure of ethical and investment policies), sought less information in fewer categories (hence no questions on leverage policies or the timing of audit disclosure), and weighted publishing the SWF's address on a par with audited annual reports.Footnote 117 Theirs was broadly accessible transparency shorthand, not a focused policy push or a granular governance device. Funds such as ADIA and Mubadala did much better under LMTI than under the scoreboard; Canada did worse.
Both the scoreboard and the index caught on quickly among market participants, policy-makers, and SWFs alike. They offered the hosts a metric for a category that was anything but unified, yet was publicly perceived as such. They also provided a tangible means to ground or dispel what had been inchoate host country fears: if one bought into the metric, a high-scoring fund should be welcomed, a low-scoring one should be shunned, and host laws should be designed to prod funds to improve their scores. For the SWFs, these private devices finally offered a standard to live up to, contest, or negotiate. Since the scoreboard and index were launched, SWFs have publicized their high rankings, challenged low ones, and engaged with the researchers on inputs and methodology.Footnote 118 Thus both the scoreboard and LMTI took on governance functions. Overall, rankings have gone up since 2008;Footnote 119 whether this is due to materially better practices or ranking arbitrage is an interesting question beyond the scope of this article.
C. Institutional Reinvention
The diffusion of private governance devices did not dispense with the public governance problem. Having charged the OECD and the IMF in 2007 with brokering agreement on conduct norms for SWFs’ hosts and sponsors, the G8 awaited a product that could be publicly accepted as a governance vehicle by the relevant governments and market participants. Neither the OECD nor the IMF was ideally suited to the task.
The dominance of domestic law early in the SWF controversy was partly rooted in the failure of a multilateral investment treaty in the 1990s. Rich states in the OECD tried and failed to produce such a treaty a decade before SWFs attracted attention. The OECD was then the leading broker of global investment norms. But it faced growing criticism as an exclusive club dominated by wealthy capital exporters in Europe and North America. Negotiations of the Multilateral Agreement on Investment (MAI) collapsed for lack of domestic and international legitimacy, under pressure from civil society groups and states on the economic and political periphery that felt shut out. At the time, the US and Europe saw themselves primarily as investors, not investment hosts. In retrospect, this crisis of OECD legitimacy foreshadowed the power shifts to come. Since the MAI failed in 1996, the OECD has struggled to recover credibility in the investment field; meanwhile, the task of regulating investment capital flows fell to domestic laws, bilateral treaties, and industry codes of conduct.
But in the 2000s, domestic laws did not lay the SWF controversy to rest in host states, while the benefits of bilateral treaties remained uncertain.Footnote 120 The financial crisis exacerbated host fears of dependence on foreign governments, but also fears of financial loss on the part of SWF home states.Footnote 121 SWF sponsors saw continuing conflict as both an economic and a political threat. To the people at home, SWFs stood variously for economic security, political autonomy, and global prestige. Even in states where the masses had little knowledge or influence over how public money was invested, governments could lose face by making too many concessions to host country fears, not to mention by losing money.Footnote 122
The OECD's initial reaction to the SWF controversy was as baffled as those of the SWFs themselves. Its earliest statements on SWFs highlighted existing international accords going back to the 1960s, which committed signatories to progressive liberalization, non-discrimination, and transparency, and carved out a narrow exception for “essential national security interests”, to be exercised with restraint and transparency by the investment hosts.Footnote 123 Before it got the specific mandate to come up with rules for SWF hosts, the OECD's public statements implied that SWFs simply did not present a new issue. Government ownership was not an excuse to deviate from investment liberalization or invoke national security exceptions. Existing guidelines for invoking the exceptions were sufficient to accommodate SWFs.Footnote 124 A series of round tables for members and invited guests might help reinforce and disseminate the norms, but would not alter the regime.Footnote 125 In mid-2008, the OECD adopted a declaration on SWFs; later the same year it issued Guidelines for Recipient Country Investment Policies, meant to limit the use of national security exceptionsFootnote 126—both instruments in substance reiterated the OECD position that SWFs presented no new or distinct policy challenge.
This position may have been principled as a formal matter, but it failed to respond to the political imperative, or leverage the process in any way. For better or worse, the public in a growing number of host and home countries had come to see SWFs as new and distinct, if only because they embodied a new financial and security landscape. Moreover, faced with the prospect of broad-based investment restrictions, the SWFs themselves were poised to concede the point to get stable market access.
The IMF was both a natural and an unlikely candidate to come up with norms to govern SWFs. Its macroeconomic and financial stability expertise made the IMF uniquely credible in addressing issues of concern to home and host states alike. It knew all the actors involvedFootnote 127 and had analyzed the advent of SWFs for some time.Footnote 128 Unlike the OECD, the Fund's membership was nearly universal, though its internal governance remained controversial: in particular, some of the new surplus states and SWF sponsors were underrepresented. The IMF had jurisdiction over its members’ exchange rate policies, current account convertibility, and broad macroeconomic and financial policy responsibility. However, its authority over capital flows, including investment, was partial, ambiguous, and the worse for wear since the capital account crises of the 1990s and early 2000s. The Fund's recent macroeconomic surveillance record had been mixed at best: it did little to reduce the trade and savings imbalances that spawned the new wave of SWFs.
In a paradox that would repeat itself in the ensuing months, the Fund's lack of legal and economic power over surplus states with SWFs might have helped make its involvement more palatable to them. It got tagged to help leading SWFs distil “best practices” for going about their business by way of compromise at its 2007 Annual Meetings.Footnote 129 Prodded by the G7, the IMF envisaged something along the lines of its prior forays into best practices for fiscal transparency and reserve management. Yet the new project was quite different. In contrast to its prior code-making experiences, the IMF did not come to the table with the authority to determine the standards, assess compliance, or sanction non-compliance. It dealt with states that by definition did not need its money and were unlikely to need it in the foreseeable future. The IMF's functions were expert, convening, and secretarial. The output was emphatically voluntary. Meanwhile, reports on the SWFs’ enthusiasm for the exercise were not encouraging. Soon after receiving the assignment, one IMF official observed that the word “best” in “best practices” may be too sensitive for the new gathering.
D. Soft Outcomes
The International Working Group (IWG) representing two dozen or so states with SWFsFootnote 130 negotiated the Santiago Principles between May and September 2008. They met three times, in Washington, Singapore, and Chile, and had a drafting session in Norway. The group was chaired by two senior officials, one from ADIA and another from the IMF. Several home and host countries, along with representatives of the OECD, the World Bank, and the European Union, attended IWG meetings as observers. Some major host states, including the US, attended as SWF sponsors in their own right. The group's agreement was announced at the meeting in Santiago on 2 September 2008. The IWG member governments quickly signed off on the Santiago Principles text, whereupon it was presented to the IMF's policy-setting International Monetary and Financial Committee (IMFC) and the general IMF membership.Footnote 131 A ritual welcome followed.
The Principles do not claim to be the “best”, but they do aspire to be “generally accepted”, where “general” means “potentially achievable by countries at all levels of economic development”.Footnote 132 This gesture of solidarity across the income spectrum suggests a governance grouping distinct from the “Gs” that came before. Unlike the old G7 and the G77, which reflected national income and reinforced something like class stratification among states, and even unlike the G20, which was designed to mimic diverse representation of wealthy and middle-income countries, the Principles seem to address a more organically diverse constituency, united by the functional needs of surplus states operating in integrated financial markets.
When they were issued, the Principles projected concern with SWFs’ status at home and abroad, and their competitiveness in the private financial markets. They suggested that SWFs still occupied a contested place in home country politics and policy mix, that SWFs’ decision-making was poorly understood and worrisome to the hosts, and betrayed a suspicion on the part of many funds that they operated on hostile, unfamiliar turf that might tilt in favour of competitors. In response, the IWG product sought to reassure, but not at the expense of losing autonomy or a competitive edge.
Much like Truman's scoreboard, the two dozen GAPP line items address the structure and objectives of SWFs (“legal, institutional, and macroeconomic” factors), their governance practices (especially decision autonomy from the home government), and their investment and risk management policies, focusing on financial stability. The document is suffused with accountability rhetoric, which is cited in support of all but a few of the Principles. At the same time, the Principles take a particular view of accountability that is distinct from earlier public statements by SWFs and host governments, the scoreboard, or any other governance device. Viewed through the framework set out in Section II of this article, the IWG went the furthest in private accountability—internally, answering to SWFs’ stakeholders under the terms of their constitutive arrangements,Footnote 133 and externally, abiding by the laws their hosts made applicable to private investorsFootnote 134—while participating in the global financial markets in the manner of profit-driven private investors.Footnote 135 GAPP Principle 21 takes a forceful stand on SWFs’ shareholder rights. In this view, SWFs’ capacity to exercise shareholder rights in their investments is an essential attribute of accountability to their own stakeholders. The way in which IWG approached this principle illustrates the tension between internal and external private accountability. On balance, GAPP Principle 21 was a clear victory for internal accountability; however, in a nod to the external audience, the SWFs agreed to disclose their voting policies and intentions ex ante and their voting record ex post.
The Principles address public internal accountability primarily through disclosure; however, some of the most significant disclosure is made to the owner, not the domestic public, perhaps relying on general government channels to inform the populace and the world at large.Footnote 136 To the consternation of many long-time observers, and in notable contrast with Truman's scoreboard, the IWG deemed total fund size too sensitive to require disclosure at all—one reason why GAPP as a package scores 76 out of 100 on the scoreboard.Footnote 137 Some of the most forceful language in the Principles is used to disclaim “any intention or obligation to fulfil, directly or indirectly, any geopolitical agenda of the government”Footnote 138—presumably, even if the public at home demands it. It is almost as if the SWFs sought to use the Principles as a commitment device for their own governments and publics, making it harder to appropriate the funds for public purpose distinct from their stated mission.
The treatment of public external accountability is similarly strained. Over half of all the Principles refer to the sentiment most clearly expressed in GAPP Principle 19: SWFs are in the business of maximizing “risk-adjusted returns” and operate solely “based on economic and financial grounds”.Footnote 139 Any social, ethical, or religious motive is a deviation from the group norm (albeit one in which some important members like Kuwait and Norway engage), and must be specifically disclosed. Moreover, many of the disclosure obligations elsewhere in the document are justified in terms of dispelling “concern about potential non-economic or non-financial objectives”.Footnote 140 The funds’ contribution to global financial stability comes not from a sense of public duty, but rather from their capacity and inclination—by virtue of their economic objective and structure—“to take a long-term view in their investments and ride out business cycles”.Footnote 141 However, it is hard to tell what portion of the funds would reliably stick to such a long-term view: for example, some fiscal stabilization funds are committed to spend to offset revenue shortfalls; others might take a long view but change their minds.
When the IWG announced agreement on the Principles, its members were at pains to disassociate them from the IMF surveillance process: they insisted that everything about the Principles was voluntary. Perhaps as a matter of pre-emption, the Principles incorporated a periodic internal review mechanism.Footnote 142 In theory, nothing prevents the IMF from considering GAPP criteria in its assessment of home and host policies implicating SWFs, just as nothing prevents a host government from using GAPP as part of its investment screen.Footnote 143 But doing so may undermine the Principles’ legitimacy in the home countries, and scuttle co-operation between new and old powers and institutions.
The IWG work since the launch in Santiago confirms the view of the forum as an exercise in governance pre-emption. In the autumn of 2008, the IWG secretariat released a SWF survey, reacting to calls for transparency while seizing initiative and asserting control in a field where authoritative information was scarce and analysis was dominated by private investment banks and consultancies.Footnote 144 Six months after presenting the Principles to the IMFC, the group released the Kuwait Declaration, establishing a standing forum of SWFs. The IWG's successor, the International Forum of Sovereign Wealth Funds (IFSWF) is “a voluntary group of SWFs” whose membership is open to funds that meet the GAPP definition of SWF and, significantly, “endorse” the Principles. It is a soft institutional counterpart to the emphatically soft law of the Principles. The IMF has served as the Forum's interim secretariat.Footnote 145 At this writing, the IFSWF has met twice, in Azerbaijan and Australia. It has issued statements advocating open investment, and has brokered a code of “good practices” on investment risk management, conducting member surveys as part of the process.Footnote 146 The current Forum Chair is from Australia; Deputy Chairs represent China's and Kuwait's SWFs.
* * *
GAPP builds on and borrows elements of several established species: best practices produced by and for the public sector (for example, the IMF on fiscal transparency), corporate codes of conduct produced by the private sector to regulate itself, and principles jointly produced by public and private actors to regulate private conduct (for example, the Equator Principles, a collaboration between private banks and the International Finance Corporation). GAPP is unusual because the principles are produced by and for public entities, yet they purport to regulate market activity. Public market actors appear to favour self-regulation.
The IFSWF combines features of a macroeconomic policy co-ordination body (the G7) and a producer's cartel (the Organization of the Petroleum Exporting Countries). It is more like the latter in the sense that group members appear to be SWFs themselves, not their sponsoring governments—and to the extent there is daylight between general government interests and those of the SWFs, the former are rarely represented in regular meetings. But the IFSWF's regulatory and self-regulatory aspirations also evoke the rise of the Financial Stability Board (FSB), a group of public and private standard setters formed in the wake of the Asian Financial Crisis of the late 1990s, which was relaunched and gained prominence in 2008.Footnote 147 Neither has legal personality or much of an infrastructure; yet both have charter-like mandates, norm-generating authority, and enough of an organizational chart to fit somewhere in-between bureaucratic networks and full-fledged international institutions on the Bretton Woods model. Time will tell which analogy fits best, if any. However, the IWG's decision to stick around and morph into the IFSWF is further evidence of the surplus countries’ taking ownership of the SWF category, and using it as a vehicle not just to allay deficit country fears but, more importantly, to advance their own interests and participate in the governance of international finance.
IV. Conclusion: SWF Governance as an Experiment and a Lens
John Maynard Keynes and Harry Dexter White, the architects of the post-World War II economic order, both said that stability and growth depended on getting deficit and surplus countries to act in the common interest.Footnote 148 Although both aspired to symmetry, they came to the Bretton Woods negotiating table with different mandates. Keynes sought to create an international institution with the power to force deficit countries to adjust, but also to tax countries that accumulated excess reserves, pressuring them to revalue.Footnote 149 Because everyone expected the US to remain the world's biggest creditor, US negotiators by and large successfully opposed muscular sanctions against surplus members; they preferred reports and reprimands.Footnote 150 The resulting regime had few tools to influence surplus states; moreover, it was anchored in a national currency (the US dollar) with little power to discipline its issuer.
By 2005—the year the term “sovereign wealth fund” first appeared in print—the US was the world's biggest debtor.Footnote 151 Unlike earlier US and European deficits, which were financed by private investors and governments in closely allied states such as Germany and Japan,Footnote 152 the new deficits were bigger and relied more on funding from China, Russia, and oil producers in the Middle East.Footnote 153 And in contrast to the world in 1944, many capital-exporting states were poor and new to governing international finance. The new creditors accumulated trillions of dollars from export revenues in an effort to self-insure against future shocks and avoid IMF discipline, but also to keep down the value of their currencies.Footnote 154 Experts said that the enormous imbalances put the world in peril: rebalancing was inevitable, and would require painful adjustment for debtors, creditors, and bystanders alike.Footnote 155
Formal Bretton Woods structures were at a loss to deal with this shifting direction of capital flows.Footnote 156 Asian exporters, notably China and Singapore, and a number of oil producers, notably the UAE, were underrepresented in the IMF, and outside the G-groups that dominated macroeconomic policy co-ordination. Meanwhile, the world's biggest debtor continued to dominate international institutions and issue the leading reserve currency, which gave it policy autonomy from the IMF. The dire warnings and the circle of blame brought about no visible change in behaviour on either side. The IMF could no more influence China's exchange rate management than US tax policy.
The sharp spike in the number of SWFs in the 2000s was a symptom of global imbalances, which the existing order looked powerless to address. State holdings initially took the form of central bank purchases of US Treasury and agency securities. Over time, they began moving into riskier, less liquid assets,Footnote 157 such as US and European equities, as well as infrastructure and extraction projects in Africa. New investment strategies begat new institutional forms: various state-owned funds became a prominent source of portfolio investment in G7 economies. Throughout this transformation, the new surplus states and their investment vehicles remained fragmented on the governance periphery. They did not move to take the reins of the Bretton Woods system, nor join forces in an alternative regime.
This article has described how a diverse bunch of outside investors, made salient by host country politics in the mid-2000s, became a vehicle for addressing some of the hardest policy problems in international finance, and a site for international law-making innovation. The funds’ common quality—their hybrid public-private and transnational character—makes them hard to define and govern, but also makes them exceptionally apt reflections of contemporary global capital and its multiple constituents. I have sought to capture this quality in the four-part accountability matrix elaborated in Section II. From this perspective, the task of governing SWFs, just like the task of governing global capital flows, is about negotiating among public, private, internal, and external demands for accountability in the absence of a hierarchy among them. The goal is to establish a dynamic governance process, capable of winning legitimacy simultaneously in radically different political, economic, and cultural settings.
This governance project might draw on, and contribute to, several fields of law scholarship that have struggled with some of its constituent challenges. First, writing on legal pluralism and, more recently, on global legal pluralism, has worked with cultural difference, the simultaneous application of diverse legal regimes to a single subject, and conflicting accountability demands on administrative actors.Footnote 158 However, legal pluralism, and to a lesser extent its global counterpart, often come rooted in colonial hierarchies, and in a sharp distinction between state and non-state law. SWFs offer an example of state-made law dislodged from its privileged position, embracing informality as a core part of their identity as regulators and regulated subjects.
Second, the GAPP and IFSWF projects evoke elements of the large literature on “New Governance”, described in the financial regulatory setting as a regime “that uses innovative, pragmatic, information-based, iterative, and dialogic mechanisms to gather, distil, and leverage industry learning in the service of … more effective and less burdensome … public regulatory mandate”.Footnote 159 The absence of a stable hierarchy, the iterative and information-channelling functions of the IFSWF, the incorporation of private knowledge, methods, and artefacts in GAPP, and the SWFs’ simultaneous struggle for legitimacy in multiple diverse settings, make the comparison fruitful. Here too SWFs enrich the cast of law-making characters, usually conceived of as a dynamic combination of public and private players learning from one another, less often as one set of players “performing” as the other (sovereigns as market actors).
Third, the resurgent literature on soft law, particularly soft law in international finance,Footnote 160 responds to persistent criticisms of the Principles as non-binding.Footnote 161 This scholarship implies that such criticism can be misleading in the light of the weak compliance machinery in the most formally “binding” international legal arrangements, and the impressive compliance pull of embedded market discipline, competition, and process institutionalization. SWFs, which compete vigorously in the market but also increasingly co-finance with one another, exemplify all three features. Moreover, political scientists writing about soft law have praised its unique capacity to deal with uncertainty and diversity of interests, values, and power.Footnote 162 The alternative to soft law in this view is not hard law, but no law.
The list suggests that much more work remains to be done by legal scholars to exploit the theoretical potential of SWFs, and to contribute to their governance. Meanwhile, from the policy perspective, it is tempting to see the Principles as an exercise in technocratic legitimation—a set of light and general rules to help Chinese, Russian, and Arab money look friendlier to its US and European hosts, while maintaining the mandate to invest from the masses at home. This undersells the achievement even with a limited implementation record to date. At a minimum, the negotiation process revealed a new role for the IMF in financial diplomacy: a shift from the hard power of conditionality in the twentieth century to the soft power of persuasion and expertise in the twenty-first. In the world of soft power, brokering an investment compromise is a big step up from technical assistance.
The financial crisis has reinforced the IMF's role as a source of balance-of-payments support, and has more than doubled its resources. On the other hand, the rise of the FSB—a soft institution without the IMF's baggage, charter, and funding constraints, but with a huge mandate from the G20—brought real competition to governing finance. The interactions between the IMF and the IFSWF may reveal new modes of co-operation between formal and informal governance arrangements. More ambitiously, the Santiago experiment may yet launch a durable policy co-ordination regime among surplus states. Ad hoc, interest-based groupings such as the IFSWF, horizontally linked with established institutions such as the IMF, may offer a new model to complement the G20 and further displace the old G7 order.
Just as easily, the Principles could fail. They may turn out to be too vague or too stingy to reassure the hosts, too restrictive to bind a set of very diverse and very rich actors whose interests often conflict, or too radical to co-exist with tightly controlled domestic political regimes. More likely, if the Principles succeed at fostering model corporate governance and transparency, the (still hypothetical) threats that prompted GAPP's creation may assume different form—shifting out of SWFs into reserve pools, state-owned enterprises, or new vehicles as yet unknown. The GAPP model would still be out there, but it would apply to an unimportant fringe of sovereign finance.
Even so, the limited achievement to date is impressive. SWFs have gone from a seemingly incongruous fiction fuelled by worried Western politicians to catalysts for negotiating the terms of integration among different political, social, and economic systems. This path and the institutional innovations it brought merit further study.

 ” [The Cumulative Amount of the National Welfare Fund] (2010), online: Russian MinFin 〈