




1 Introduction
In the first part of this paper, we prove nonperturbative Anderson localization for a family of one-dimensional finite-range quasi-periodic Schrödinger operators, which can also be viewed as an operator on the strip
$\mathbb Z\times \{1,...,d\}$
 or block-valued quasi-periodic Jacobi matrices. Here nonperturbative refers to the positive Lyapunov exponent (half of exponents of the corresponding symplectic cocycles are positive) regime. We also prove almost localization for all
$\theta $
 and any Diophantine
$\alpha $
 (that is,
$\beta (\alpha )=0$
 , see (2.2)). Throughout this paper, by a Diophantine condition we mean
$\beta (\alpha )=0$
 . We denote the classical polynomial Diophantine condition by
$\mathrm {SDC}$
 and refer to it as the strong Diophantine condition. This together with the dual (almost) reducibility techniques developed by Avila-Jitomirskaya in [Reference Avila and JitomirskayaAJ2], proves Avila’s almost reducibility conjecture (ARC) in [Reference AvilaAv3] for Schrödinger operators with trigonometric potentials and all Diophantine
$\alpha $
 . Combined with Avila’s proof of ARC for Liouville
$\alpha $
 (those satisfying
$\beta (\alpha )>0$
 ), this gives a complete proof of ARC for trigonometric potentials. For completeness, we mention that Avila announced a proof of the almost reducibility conjecture for analytic potentials in 2015 in [Reference AvilaAv3]; a preprint presenting the announced proof subsequently appeared in [Reference AvilaAv4].
Let

$v:\mathbb T=\mathbb R/\mathbb Z\to \mathbb R$
 analytic, be a quasi-periodic Schrödinger operator on
$\mathbb Z$
 . Let

be the transfer matrix, and
$(\alpha , A_{E,\varepsilon })$
 be the associated cocycle. Let
$L(\alpha , A_{E,\varepsilon })$
 be the Lyapunov exponent. In his seminal work [Reference AvilaAv3], Avila introduced the acceleration, defined as:

Furthermore, he proved the acceleration is quantized, meaning
$\kappa (\alpha , A_{E,\varepsilon })\in \mathbb Z$
 . Using the quantized acceleration, Avila divides the spectrum
$\sigma (H_{\alpha ,\theta ,0})=\sigma (H_{\alpha })$
 (we restrict to the irrational
$\alpha $
 case, for which the spectrum is independent of
$\theta $
 ) into three regimes: the supercritical regime

the subcritical regime

and the critical regime

In the supercritical regime, nonperturbative proofs of Anderson localization have been developed for the Harper operator with all
$\alpha $
 satisfying the strong Diophantine condition
$\mathrm {SDC}$
 Footnote
1
in [Reference JitomirskayaJ1] (where
$v(\theta )=2\lambda \cos (2\pi \theta )$
 with
$|\lambda |>1$
 ), for general analytic potentials with a.e.
$\alpha $
 in [Reference Bourgain and GoldsteinBG], and for all
$\alpha $
 satisfying the strong Diophantine condition
$\mathrm {SDC}$
 in the first supercritical stratum (where
$\kappa (\alpha , A_{E,0})=1$
 ) in [Reference Han and SchlagHS1]. In the critical regime, the spectrum is conjectured to be singular continuous (see Conjecture 3.1 in [Reference Avila, Jitomirskaya and MarxAJM]). This conjecture has been proved for the critical Harper operator (where
$v(\theta )=2\cos (2\pi \theta )$
 ) in [Reference AvilaAv1, Reference Avila, Jitomirskaya and MarxAJM, Reference JitomirskayaJ2].
In the subcritical regime, Avila formulated the almost reducibility conjecture (ARC), which we shall elaborate on below. A cocycle
$(\alpha ,A)$
 is called (analytically) reducible if there exists
$D\in C^{\omega }(\mathbb T, \mathrm {PSL}(2,\mathbb R))$
 such that the analytic conjugacy
$D^{-1}(\theta +\alpha ) A(\theta ) D(\theta )$
 is a constant. A cocycle is called almost reducible if the closure of its analytic conjugacies contains a constant.
Conjecture 1.1 (ARC by Avila, [Reference AvilaAv3]).
Subcritical cocycles are almost reducible.
As remarked by Avila in [Reference AvilaAv3], “Proving this almost reducibility conjecture would at once provide an almost complete understanding of subcriticality.” This conjecture has thus far been proved in two different cases:
-
• for $\alpha $
 satisfying the strong Diophantine condition
$\mathrm {SDC}$
: (i) for general analytic potentials in the small coupling regime (ii) for the entire subcritical regime of the almost Mathieu (or Harper) operator; both in [Reference Avila and JitomirskayaAJ2]. See also [Reference Ge, You and ZhaoGYZ].
-
• for Liouville $\alpha $
’s (those
$\beta (\alpha )>0$
) in [Reference AvilaAv2].


In this paper, we prove the following nonperturbative quantitative ARC for Schrödinger cocycles with trigonometric potentials and all Diophantine
$\alpha $
 . In the rest of the paper, we assume that
$v(x)=\sum _{1\leq |k|\leq d} \hat {v}_k e^{2\pi i kx}$
 is a real-valued trigonometric polynomial, which implies that for
$1\leq k\leq d$
 ,
$\hat {v}_k=\overline {\hat {v}_{-k}}$
 . Without loss of generality we assume that
$\hat {v}_0=0$
 . We take
$d$
 to be the degree of
$v$
 , so
$\hat {v}_d\neq 0$
 and, since
$v$
 is real-valued, also
$\hat {v}_{-d}\neq 0$
 ; otherwise one simply decreases
$d$
 . For
$h>0$
 ,
$C_h^{\omega }(\mathbb T,X)$
 denotes the space of analytic
$X$
 -valued functions on the strip
$\{x\in \mathbb C/\mathbb Z:\ |\text {Im}x|<h\}$
 . For
$F\in C_h^{\omega }(\mathbb T,X)$
 , we write
$\|F\|_h:=\sup _{|\text {Im} z|<h}\|F(z)\|_X$
 . We also write
$\|x\|_{\mathbb T}=\text {dist}(x,\mathbb Z)$
 . For Lyapunov exponents, superscripts denote partial sums:
$\hat L^m(\alpha ,\hat A_E):=\sum _{\ell =1}^m \hat L_\ell (\alpha ,\hat A_E)$
 ; when
$\alpha $
 is fixed we sometimes abbreviate this as
$\hat L^m(\hat A_E)$
 .
Theorem 1.2. Let
$\beta (\alpha )=0$
 , and
$E\in \Sigma _{\alpha ,0}$
 . Let
$0<\varepsilon _0<\frac {\hat {L}_d(\alpha , \hat {A}_E)}{30\hat {L}^d(\hat {A}_E)+100 C_3d}$
 where
$C_3$
 is the absolute constant in Lemma 3.10, and
$\delta =\min (\frac {\hat {L}_d(\alpha , \hat {A}_E)}{5000}, \frac {\varepsilon _0}{25})$
 . Let
$\theta =\theta (E)$
 be given by Theorem A.1. Let
$\{n_j\}$
 be the sequence of
$\varepsilon _0$
 -resonances of
$\theta $
 and
$L_j:=\|2\theta -n_j\alpha \|_{\mathbb T}$
 . Then there exists an absolute constant
$C>0$
 such that for
$j>j_0(\alpha , v, E, \varepsilon _0)$
 there exists
$W\in C^{\omega }_{\frac {\delta }{2\pi }}(\mathbb T, \mathrm {SL}(2,\mathbb R))$
 such that
$|\mathrm {deg}(W)|\leq C|n_j|$
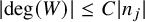 ,
$\|W\|_{\frac {\delta }{2\pi }}\leq L_j^{-C}$
 and

Above,
$\hat {L}_d(\alpha , \hat {A}_E)>0$
 is the
$d$
 -th Lyapunov exponent of the dual operator, see Corollary 1.12. The core of the proof is to establish the almost localization for the dual model (Theorem 3.8 below). Once established, one can combine it with the quantitative duality arguments in [Reference Avila and JitomirskayaAJ2] to prove Theorem 1.2. We include the duality argument in Appendix A in order to keep the paper self-contained.
One example to which Theorem 1.2 applies is the perturbation of the subcritical almost Mathieu operator, which is also subcritical due to the upper semi-continuity of the acceleration.
Example 1.3. Let
$H^{\mathrm {PAMO}}_{\alpha ,\theta ,\nu , w}$
 be the operator with
$v(\theta )=2\lambda \cos (2\pi \theta )+\nu \cdot w(\theta )$
 and
$\varepsilon =0$
 , where
$w(\theta )$
 is a trigonometric polynomial. For
$|\lambda |<1$
 and sufficiently small
$|\nu |<\nu _0(\alpha ,\lambda ,w)$
 ,
$\sigma (H^{\mathrm {PAMO}}_{\alpha ,\theta ,\nu , w})=\Sigma _{\alpha ,0}$
 .
Theorem 1.4. For
$|\lambda |<1$
 ,
$\beta (\alpha )=0$
 , and sufficiently small
$|\nu |<\nu _0(\alpha ,\lambda ,w)$
 , for any
$E\in \sigma (H^{\mathrm {PAMO}}_{\alpha ,\theta ,\nu ,w})$
 , the cocycle
$(\alpha , A_E^{\mathrm {PAMO}})$
 associated to
$H^{\mathrm {PAMO}}_{\alpha ,\theta ,\nu ,w}$
 is quantitatively almost reducible.
Remark 1.5. It is well known that for
$E\notin \sigma (H^{\mathrm {PAMO}}_{\alpha ,\theta ,\nu ,w})$
 ,
$(\alpha , A_E^{\mathrm {PAMO}})$
 is
$\mathrm {PSL}(2,\mathbb R)$
 reducible; see, for example, Theorem 2.1 of [Reference Avila and JitomirskayaAJ2].
As a consequence of Theorem 1.4, we can prove the dry Ten Martini problem for
$H^{\mathrm {PAMO}}_{\alpha ,\theta ,\nu ,w}$
 .
Theorem 1.6. For
$|\lambda |<1$
 ,
$\beta (\alpha )=0$
 , and for sufficiently small
$|\nu |<\nu _0(\alpha ,\lambda ,w)$
 , all the spectral gaps of
$H^{\mathrm {PAMO}}_{\alpha ,\theta ,\nu, w}$
 as predicted by the gap labeling theorem are open.
This is an analogue of Theorem 1.1 of [Reference Avila and JitomirskayaAJ2], we include its proof in the appendix for completeness. Next, we introduce the dual model of
$H_{\alpha ,\theta ,\varepsilon }$
 :

This long-range operator can also be written in terms of a block-valued Jacobi matrix, acting on
$\ell ^2(\mathbb Z, \mathbb C^d)$
 , as follows.

where
$\Phi _n=(\phi _{nd+d-1},...,\phi _{nd+1},\phi _{nd})^T\in \mathbb C^d$
 , and
$B_{\varepsilon }, \tilde {B}_{\varepsilon }$
 , and
$C_{\varepsilon }$
 are defined in Section 2.3. The transfer matrix formulation of the block-valued Hamiltonian eigenvalue equation
$\hat {H}_{\alpha ,\theta ,\varepsilon }\Phi =E\Phi $
 is

where

We denote its Lyapunov exponents by
$\hat {L}_1(\alpha ,M_E^{\varepsilon })\geq ...\geq \hat {L}_{2d}(\alpha ,M_E^{\varepsilon })$
 . The transfer matrix
$M_E^{\varepsilon }$
 can also be viewed as the
$d$
 -step transfer matrix for the scalar-valued Hamiltonian, where

in which the one step transfer matrix
$\hat {A}_E^{\varepsilon }$
 is as in (2.26). It is easy to see by (1.9) that for
$1\leq j\leq 2d$
 ,

The transfer matrix
$M_E^{0}$
 at an arbitrary energy
$E\in \mathbb R$
 is a complex symplectic matrix, see (2.19). Hence

Proving Anderson localization in the nonperturbative
$\hat {L}_d(\alpha ,M_E^0)>0$
 regime has been a long standing problem in quasi-periodic Schrödinger operators, while the Anderson model counterpart has been known for over 40 years, see [Reference GoldsheidG, Reference LacroixL, Reference Klein, Lacroix and SpeisKLS, Reference Macera and SodinMS]. Resolving this problem is one of the main accomplishments of this paper.
Theorem 1.7. Let
$\beta (\alpha )=0$
 and
$\theta $
 be such that

Then
$\hat {H}_{\alpha ,\theta ,0}$
 has pure point spectrum with exponentially decaying eigenfunctions in

We briefly discuss the difficulties. We write
$\hat {L}_j(d\alpha , M_E^0)$
 as
$\hat {L}_j$
 . The proof of Anderson localization in the literature relies on the exponential decay of the Green’s function (with Dirichlet boundary condition). In fact, let
$\hat {H}_{\alpha ,n}(\theta )$
 be the finite volume operator restricted to
$[0,nd-1]$
 , see (2.37). Let
$\tilde {G}_{E,n}(\theta ):=(\hat {H}_{\alpha ,n}(\theta )-E)^{-1}$
 be the resolvent. The key to proving localization is to prove exponential decay of
$|G_{E,n}(\theta +j\alpha ;1,x)|$
 for
$x\sim n/2$
 . By Cramer’s rule, one has

where
$\tilde {f}_{E,n}(\theta )=\det (\hat {H}_{\alpha ,n}(\theta )-E)$
 .
In the scalar-valued case,
$d=1$
 , the numerator
$\hat {\mu }_{n,1,x}(\theta +j\alpha )$
 is equal to
$\tilde {f}_{E,n-x}(\theta +(x+j)\alpha )$
 , which is an element (out of four in total) of
$M_{n-x,E}^0(\theta +(x+j)\alpha )$
 , and can thus be easily controlled by

The key for the
$d=1$
 case is to find a lower bound for the denominator
$|\tilde {f}_{E,n}(\theta +j\alpha )|$
 for a properly chosen
$j$
 . It was proved by Jitomirskaya [Reference JitomirskayaJ1] that
$\tilde {f}_{E,n}(\theta )$
 is a polynomial in
$\cos (2\pi (\theta +(n-1)\alpha /2))$
 of degree
$n$
 , hence if it is uniformly small at
$(n+1)$
 uniformly distributed
$\theta +j\alpha $
 ’s and at three consecutive scales
$n_0-2, n_0-1, n_0$
 , then

However in (and only in) the scalar-valued case, we have

which would lead to a contradiction.
In the block-valued case
$d\geq 1$
 , there are significant difficulties in estimating both the numerator and the denominator. First of all the numerator can no longer be identified with a determinant
$\tilde {f}_{E,n}$
 . In [Reference Bourgain and JitomirskayaBJ, Reference KleinK] and [Reference Avila and JitomirskayaAJ2]Footnote
2
, the numerators are estimated through a random walk type expansion, where the expansion is only efficient in the large coupling regime (replacing
$2\cos $
 with
$2\lambda ^{-1} \cos $
 and
$\lambda $
 small). In the nonperturbative regime, a much tighter upper bound is needed, in fact we prove

uniformly in
$\theta $
 and
$\mu _{n,1,x}(\theta )$
 is the numerator of the Green’s function for the finite volume operator
$P_{\alpha ,n}(\theta )$
 with periodic boundary condition (see (3.1)). We can prove a similar bound for
$\tilde {\mu }_{n,1,x}$
 as well. The reason why we choose the periodic instead of the Dirichlet boundary condition lies in the estimate of the denominator which we elaborate on below.
For the denominator, we only know that
$|\tilde {f}_{E,n}(\theta )|/|\hat {v}_d|^{nd}$
 is the determinant of the upper left
$d\times d$
 corner of
$M_{n,E}^0(\theta )$
 , hence it is unclear why
$\sup _{\theta }|\tilde {f}_{E,n}(\theta )|/|\hat {v}_d|^{nd}$
 is close to

One might attempt to argue that


where
$\hat {\mu }_{n,\alpha ,\theta }$
 is the finite-scale density of states measure (see (2.38)) and the second line is the Thouless formula (2.40) that was proved in the
$d>1$
 case in [Reference Craig and SimonCS2, Reference Kotani and SimonKS, Reference Haro and PuigHP]. However, the finite volume density of states measure
$\hat {\mu }_{n,\alpha ,\theta }$
 only converges in the weak-
$*$
 sense (when integrated against continuous functions of compact support) to the density of states measure
$\widehat {\mathcal {N}}$
 , which does not apply when integrated against
$f(\cdot )=\log |E-\cdot |$
 for
$E\in \mathbb R$
 . Therefore the approach (1.13) does not lead to the desired result when
$E\in \mathbb R$
 . See Remark 3.4, too. We resolve this difficulty by studying the Green’s function
$G_{E,n}(\theta )=(P_{\alpha ,n}(\theta )-E)^{-1}$
 with a periodic boundary condition. Let
$f_{E,n}(\theta )=\det (P_{\alpha ,n}(\theta )-E)$
 be the denominator of the Green’s function
$G_{E,n}(\theta )$
 . We prove that

We then show that for an admissible sequence of
$n$
 , on a large measure set of
$\theta $
 ,

The choice of the admissible sequence relies crucially on Lemma 3.2 of [Reference Goldstein and SchlagGS3], which guarantees that the most expanding
$d$
 -planes of
$M_{n,E}^0$
 , respectively of
$(M_{n,E}^0)^*$
 , are not entirely orthogonal to each other. Our lower bound Lemma 3.2 for the denominator is robust, and can be applied to establish Anderson localization for operators
$\hat {H}_{\alpha ,\theta }$
 on strips with general analytic potentials defined on higher-dimensional tori. We will address this problem in an upcoming work. For the cosine potential which arises in this paper, there is a more elementary argument using Herman’s subharmonic argument, see Lemma 3.5.
A stronger version of almost localization holds for arbitrary
$\theta $
 , see Theorem 3.8. The link between Theorem 3.8 and Theorem 1.2 is provided by Corollary 1.12, which states that if
$E\in \Sigma _{\alpha ,0}$
 , then the dual Lyapunov exponent satisfies
$\hat {L}_d(d\alpha , M_E^0)>0$
 . This was announced in Jitomirskaya’s 2022 ICM talk, and is indeed a consequence of a nonselfadjoint variant of Haro and Puig’s result on dual Lyapunov exponents, which we elaborate on below.
In [Reference Haro and PuigHP], Haro and Puig proved the following remarkable theorem concerning Lyapunov exponents of dual models. The techniques in [Reference Haro and PuigHP] are inspired by Johnson’s parametrization of the stable and unstable subspaces in the uniformly hyperbolic setting via the Weyl-Kodaira
$M$
 -matrix, see [Reference JohnsonJoh, Reference Johnson, Palmer and SellJPS, Reference Johnson, Obaya, Novo, Núñez and FabbriJONNF].
Theorem 1.8 [Reference Haro and PuigHP, Theorem 1.3 and Corollary 1.6].
For any irrational
$\alpha $
 ,

The proof is built on two key ingredients. One is the Thouless formula, that links the Lyapunov exponent to the density of states measure, for both
$H_{\alpha ,\theta ,\varepsilon =0}$
 (the selfadjoint Schrödinger operator) and
$\hat {H}_{\alpha ,\theta ,\varepsilon =0}$
 (the dual model on the strip, which is also selfadjoint). The second is the fact that the two dual selfadjoint operators share the same density of states measure.
The following nonselfadjoint version of the Haro, Puig formula was announced in Jitomirskaya’s ICM talk in 2022.
Theorem 1.9 [Jitomirskaya, ICM talk 2022].
For any irrational
$\alpha $
 ,

Noting that
$\hat {L}_j(\alpha ,\hat {A}_E^\varepsilon )=\hat {L}_j(\alpha ,\hat {A}_E^0)-2\pi \varepsilon $
 , see (2.29), and taking Haro and Puig’s formula (which holds at
$\varepsilon =0$
 ) into account, we see that Theorem 1.9 is the same as a nonselfadjoint version of Haro and Puig’s formula, see Theorem 1.10 below.
Since a proof of Theorem 1.9 was not available in the literature at the time this work was carried out, and because this theorem arises in our resolution of the almost reducibility conjecture, we developed an independent proof in Section 6.
Theorem 1.10. For any irrational
$\alpha $
 ,

A major difficulty in extending Haro and Puig’s formula to the nonselfadjoint case (i.e., when
$\varepsilon \neq 0$
 ) is the lack of spectral theorems. Hence there is no density of states measure, which played a crucial role in Haro and Puig’s original proof. We overcome this problem by establishing the Aubry duality, by means of the characters on cyclic groups, for finite scale operators with periodic boundary conditions and rational frequencies. These finite-scale operators naturally have (finite scale) density of states measures via the normalized counting measures of the eigenvalues. We then prove Thouless formulas for the finite scale rational-frequency operators, which after combining with the duality, lead to (1.17) with rational
$\alpha $
 . Finally, (1.17) for irrational
$\alpha $
 follows from rational approximation and continuity of the Lyapunov exponents at irrational frequencies.
It was also addressed by Jitomirskaya in her ICM talk that Theorem 1.9 leads to the following characterization of Avila’s acceleration.
Corollary 1.11. For irrational
$\alpha $
 , and any
$\varepsilon \ge 0$


We give a proof of this in Section 6. Clearly, Corollary 1.11 and (2.29) lead to the following.
Corollary 1.12. If the acceleration of
$H_{\alpha ,\theta ,\varepsilon }$
 satisfies
$\kappa (\alpha ,A_{E,\varepsilon })\equiv 0$
 for
$|\varepsilon |\leq \varepsilon _1$
 , then

In the rest of the paper, we shall omit the dependence on
$\varepsilon $
 in various notations in the
$\varepsilon =0$
 case.
Shortly after the present paper was posted on arxiv, a different proof of Theorem 1.9 by Ge, Jitomirskaya, You, and Zhou [Reference Ge, Jitomirskaya, You and ZhouGJYZ] appeared. Ge also subsequently published a preprint concerning the almost reducibility conjecture, see [Reference GeGe] for the journal version.
The paper is organized as follows: some preliminary knowledge is recalled in Sec. 2, the proofs of Theorem 1.7 and almost localization are given in Sec. 3 assuming the numerator bound of the Green’s function established in Sec. 4 and the denominator bound in Sec. 5. Finally we present the proof of Theorem 1.10 in Sec. 6.
Notations. for
$x\in \mathbb R$
 , let
$\|x\|_{\mathbb T}:=\mathrm {dist}(x,\mathbb Z)$
 be the torus norm, and
$\lfloor x\rfloor =\sup \{m\in \mathbb Z:\, m\leq x\}$
 be the integer part of
$x$
 . If
$a\leq Cb$
 for some constant
$C>0$
 , we shall write
$a=O(b)$
 . For a matrix
$M\in \mathbb C^{d_1\times d_2}$
 , and the sets of indices
$B_1\subset [1,d_1]\cap \mathbb Z, B_2\subset [1, d_2]\cap \mathbb Z$
 , let
$M_{B_1, B_2}$
 be the submatrix of
$M$
 with row numbers in
$B_1$
 and column numbers in
$B_2$
 .
2 Preliminaries
2.1 Continued fraction expansion
Given
$\alpha \in (0,1)$
 , let
$[a_1,a_2,...]$
 be the continued fraction expansion of
$\alpha $
 . For
$n\geq 1$
 , let
$p_n/q_n=[a_1,a_2,...,a_n]$
 be the continued fraction approximants. The following property is well-known for
$n\geq 1$
 ,

The
$\beta (\alpha )$
 exponent measures the exponential closeness of
$\alpha $
 to rational numbers:

2.2 Lyapunov exponents
Let
$(\alpha , A)\in (\mathbb T, C^{\omega }(\mathbb T, \mathrm {Mat}(k,\mathbb C)))$
 . Let

Let the finite-scale and infinite-scale Lyapunov exponents be defined as

where
$\sigma _j(A)$
 is the
$j$
 -th singular value of
$A$
 , and the
$j$
 -th Lyapunov exponent

It is easy to see that for
$1\leq j\leq k$
 ,

where
$\wedge ^j A$
 is the
$j$
 -th exterior power of
$A$
 . Similarly
$L^j(\alpha ,A)=\sum _{\ell =1}^j L_{\ell }(\alpha , A)$
 . If
$\alpha =p/q\in \mathbb Q$
 , we define

where
$\rho (A)$
 is the spectral radius of
$A$
 . Let
$L_1(p/q,A,\theta )=L^1(p/q,A,\theta )$
 and

and for
$1\leq j\leq k$
 ,

2.3 Transfer matrix of
$\hat {H}_{\alpha ,\theta ,\varepsilon }$

As we mentioned in the introduction,
$\hat {H}_{\alpha ,\theta ,\varepsilon }$
 can be viewed as a block-valued Jacobi matrix:

where
$\Phi _{n}=(\phi _{nd+d-1},...,\phi _{nd+1},\phi _{nd})^T\in \mathbb C^d$
 , the upper triangular matrix

where
$F_{\varepsilon }=\mathrm {diag}(e^{2\pi \varepsilon }, e^{4\pi \varepsilon }, ..., e^{2\pi d\varepsilon })$
 . The lower triangular matrix
$\tilde {B}_{\varepsilon }=e^{-2\pi d\varepsilon } F_{\varepsilon } B_0^*F_{\varepsilon }^{-1}$
 , and


In the rest of the paper, we shall write
$C_{\varepsilon =0}(\theta )$
 and
$B_{\varepsilon =0}$
 as
$C(\theta )$
 and
$B$
 , and
$M_E^{\varepsilon =0}=M_E$
 ,
$\hat {A}_E^{\varepsilon =0}=\hat {A}_E$
 , respectively. The eigenvalue equation
$\hat {H}_{\alpha ,\theta ,\varepsilon }\phi =E\phi $
 can be reformulated as:

where


Clearly this implies that for any
$1\leq j\leq 2d$
 ,

It is easy to see that

where

Hence
$M_E^0$
 is a complex symplectic matrix. This implies that for any
$1\leq j\leq 2d$
 ,

Let

where each
$M_{n,E}^{\star }$
 is a
$d\times d$
 block,
$\star =UL, UR, LL, LR$
 . The following recursive relations hold: for
$n=1$
 ,

and for
$n\geq 2$
 ,

The eigenvalue equation
$\hat {H}_{\alpha ,\theta ,\varepsilon }\phi =E\phi $
 (when viewed as a scalar-valued Hamiltonian) can also be rewritten as:

where

is the 1-step transfer matrix. By (2.25) and (2.14) we have

Recall that
$\hat {A}_d$
 signifies a product of
$d$
 factors of
$\hat {A}$
 matrices. Hence for any
$1\leq m\leq 2d$
 ,

Combining this with (2.18) yields

2.4 Avila’s acceleration
Let
$(\alpha , A)\in (\mathbb T, C^{\omega }(\mathrm {SL}(2, \mathbb R)))$
 , and
$A_{\varepsilon }(\theta ):=A(\theta +i\varepsilon )$
 . The (top) Lyapunov exponent
$L_1(\alpha , A_{\varepsilon })$
 is a convex and even function in
$\varepsilon $
 . Avila defined the acceleration to be the right-derivative as follows:

As a cornerstone of his Global theory [Reference AvilaAv3], he showed that for
$A\in \mathrm {SL}(2,\mathbb R)$
 and irrational
$\alpha $
 ,
$\kappa (\alpha , A_{\varepsilon })\in \mathbb Z$
 is always quantized.
2.5 Uniform upper semi-continuity
The following lemma is an easy corollary of the arguments, essentially a subadditivity argument, in the proof of Lemma 5.1 in [Reference Avila, Jitomirskaya and SadelAJS].
Lemma 2.1. For any small
$\varepsilon>0$
 , there exists
$N=N(\varepsilon , \alpha , v, E,d)$
 such that for any
$1\leq j\leq 2d$
 and
$n\geq N$
 ,

uniformly in
$\theta \in \mathbb T$
 .
2.6 Large deviation estimates
The following large deviation estimates play a crucial role in Section 5. For
$\alpha $
 satisfying the strong Diophantine condition
$\mathrm {SDC}$
 , a stronger form (with a deviation of size
$n^{-\sigma }$
 ) of the following estimate for
$\mathrm {SL}(2,\mathbb R)$
 cocycles was first proved in Lemma 1.1 of [Reference Bourgain and GoldsteinBG] by Bourgain and Goldstein, and further developed in sharp forms in [Reference Goldstein and SchlagGS1, Reference Goldstein and SchlagGS2] by Goldstein and Schlag. In this paper we need the following weaker form, but it holds for any Diophantine
$\alpha $
 .
Lemma 2.2 [Reference Han and ZhangHZ, Theorem 1.1].
Let

be the large deviation set of
$\|\wedge ^d M_{n,E}(\theta )\|$
 . For
$\alpha $
 satisfying the Diophantine condition
$\beta (\alpha )=0$
 , for any small
$\varepsilon>0$
 , there exist
$N=N(\varepsilon , \alpha , \hat {L}_d(d\alpha , M_E),v,d)>0$
 and
$c_1=c_1(v,d)>0$
 , such that for
$n\geq N$
 ,

Remark 2.3. The above large deviation lemma was stated and proved in [Reference Han and ZhangHZ] for
$\mathrm {SL}(2,\mathbb R)$
 cocycles, but it is clear that the same proof applies to
$(d\alpha , \wedge ^d M_E)$
 .
2.7 Avalanche Principle
The Avalanche Principle was first introduced for
$\mathrm {SL}(2,\mathbb R)$
 cocycles by Goldstein and Schlag in [Reference Goldstein and SchlagGS1]. Later it was extended to higher-dimensional cocycles in [Reference SchlagSch1, Reference Duarte and KleinDK]. The following form is from [Reference Duarte and KleinDK].
Theorem 2.4 [Reference Duarte and KleinDK, Proposition 2.42].
There exists
$c_0, \tilde {C}_0>0$
 such that given
$0<\varepsilon <1$
 ,
$0<\kappa <c_0\varepsilon ^2$
 and
$g_0,g_1,...,g_{n-1}\in \mathrm {Mat}(m,\mathbb R)\setminus \{0\}$
 , if


then

2.8 Integrated density of states
Let

be the restriction of the operator to the interval
$[0,nd-1]$
 with Dirichlet boundary condition. Let
$E_{j}(\theta )$
 ,
$j=0,1,...,nd-1$
 be the eigenvalues of
$\hat {H}_{\alpha ,n}(\theta )$
 . Consider the sequence of measures

It is well known that the weak limit exists and is independent of
$\theta $
 (up to measure zero):

The distribution function
$\widehat {\mathcal {N}}(E)$
 is called the integrated density of states.
The integrated density of states
$\mathcal {N}$
 is defined analogously for
$H_{\alpha ,\theta ,\varepsilon =0}$
 (indeed as the
$d=1$
 special case of the above). It is well-known that
$\mathcal {N}=\widehat {\mathcal {N}}$
 ; see, for example, [Reference Haro and PuigHP]
The Thouless formula relates the Lyapunov exponent to the integrated density of states:

The scalar case
$d=1$
 was proved in [Reference Avron and SimonAS, Reference Craig and SimonCS1], and the
$d>1$
 case was proved in [Reference Craig and SimonCS2, Reference Kotani and SimonKS, Reference Haro and PuigHP].
3 Anderson localization and almost localization
3.1 Green’s function
The key to proving Anderson localization is to estimate the decay of Green’s functions. We consider the finite volume Hamiltonian with periodic boundary conditions. To distinguish
$\hat {H}_{\alpha ,n}(\theta )$
 (see (2.37)), which exhibits Dirichlet boundary conditions, from the operator with periodic ones, we denote the latter by
$P_{\alpha ,n}(\theta )$
 . Moreover, for simplicity we shall omit
$\alpha $
 in the notation in the rest of the section. Thus,

Let

and

be the resolvent, which is also called the finite volume Green’s function. It follows from Cramer’s rule that

where
$\mu _{n,x,y}(\theta )$
 is the determinant of the submatrix of
$P_{n}(\theta )-E$
 obtained by deleting the
$x$
 -th row and
$y$
 -th column. Let
$\hat {u}$
 be a solution to the eigenvalue equation
$\hat {H}_{\alpha ,\theta }\hat {u}=E\hat {u}$
 . For any
$k\in \mathbb Z$
 the following Poisson formula holds for all
$k\leq m\leq k+nd-1$
 :


in which
$(M)_y$
 refers to the element of vector
$M$
 in row
$y$
 . This implies


For the remainder of this section, we shall write
$\hat {L}^k(d\alpha , M_E), \hat {L}_k(d\alpha , M_E)$
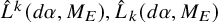 as
$\hat {L}^k, \hat {L}_k$
 , respectively. We split the estimate of the Green’s function into Lemma 3.1 for the numerator, and Lemma 3.2 for the denominator.
Lemma 3.1. Let
$3d\leq y\leq (n-1)d-1$
 and
$0\leq x\leq d-1$
 or
$(n-1)d\leq x\leq nd-1$
 . Then for any
$\varepsilon>0$
 , and uniformly in
$\theta \in \mathbb T$
 , and
$\ell =[y/d]$
 ,

provided
$n>N(\varepsilon ,\alpha ,E,d,v)$
 is large enough. Here
$C_d$
 is a constant depending only on
$d$
 .
We defer the proof to Section 4.
Lemma 3.2. Assume that
$\beta (\alpha )=0$
 . For any
$E\in \mathbb R$
 and any
$0<\varepsilon <\hat L_d/(11\hat L^d)$
 , there exist
$N_0=N_0(\varepsilon ,\alpha ,E,d)$
 and
$\kappa _0=\kappa _0(\varepsilon ,\alpha ,E,d,N_0)>0$
 such that, for every

satisfying
$n\geq N(\varepsilon ,\alpha ,E,d,v)$
 , one has

We call the elements of
$\mathcal N\, \kappa _0$
 -admissible.
We present the proof of Lemma 3.2 in Section 5. Although Lemma 3.2 does not hold for arbitrary
$n$
 , it holds for all
$\kappa _0$
 -admissible
$n$
 ’s, which form a positive density subsequence. Indeed, there exists
$C_{\kappa _0,d,\alpha }$
 such that for any
$n\in \mathbb N$
 , there is a
$\kappa _0$
 -admissible
$\tilde {n}$
 such that
$|n-\tilde {n}|\leq C_{\kappa _0,d,\alpha }$
 . Hence Lemma 3.2 yields the following.
Corollary 3.3. For any
$E\in \mathbb R$
 , for any small
$0<\varepsilon <\hat {L}_d/(11\hat {L}^d)$
 , let
$N_0, \kappa _0$
 be as in Lemma 3.2. There exists
$C_{\kappa _0,d,\alpha }>0$
 such that for any
$n\geq N(\varepsilon ,\alpha ,E,d,v)$
 , there exists
$\kappa _0$
 -admissible
$\tilde {n}$
 ,
$|\tilde {n}-n|\leq C_{\kappa _0,d,\alpha }$
 , so that

Remark 3.4. The reason why we consider
$P_{\alpha ,n}(\theta )$
 with periodic boundary conditions, instead of the finite volume operator
$\hat {H}_{\alpha ,n}$
 on
$[0,nd-1]$
 with Dirichlet boundary conditions, lies with the differences between the denominators of their respective Green’s functions. In fact, as we will show in Lemma 5.1

while

see [Reference Binder, Goldstein and VodaBGV]. To prove nonperturbative Anderson localization, it is crucial to obtain a lower bound

for certain
$\theta $
 ’s, which we establish in Lemma 5.13 along the
$\kappa _0$
 -admissible sequence. It appears to be more difficult to obtain a similar result for
$|\det M_{n,E}^{UL}(\theta )|$
 . One may attempt to derive the inequality

via Thouless’ formula. For
$E\notin \mathbb R$
 , such a lower bound for
$|\det M_{n,E}^{UL}(\theta )|$
 can indeed be deduced directly from the Thouless formula (proved for the scalar case
$(d=1)$
 in [Reference Avron and SimonAS, Reference Craig and SimonCS1], and operators on the strip in [Reference Craig and SimonCS2, Reference Kotani and SimonKS, Reference Haro and PuigHP]). In fact, if
$E\notin \mathbb R$
 , then
$g(E')=\log |E-E'|$
 is a continuous function on
$\mathbb R$
 . By the
$\sigma ^*$
 -convergence of the finite volume density of states measure to the (infinite volume) density of states measure
$\widehat {\mathcal {N}}$
 , it follows that


for a.e.
$\theta $
 . However, this simple proof does not apply to
$E\in \mathbb R$
 , since
$g$
 is not continuous. See also (1.13).
We emphasize the robustness of the lower bound in Lemma 3.2 for the denominator. It can be applied to operators
$\hat {H}_{\alpha ,\theta }$
 on the strip with general analytic potentials on higher-dimensional tori. This approach was subsequently developed in [Reference Han and SchlagHS2] to establish nonperturbative Anderson localization for a general class of quasi-periodic Jacobi block matrix operators. For the special case of the cosine potential considered here, a simpler lower bound can be obtained via Herman’s subharmonic argument.
Lemma 3.5. For any
$n\geq 1$
 , we have

We present the proof at the end of Section 5. Note the equality sign above is exactly Haro-Puig’s theorem (see Theorem 1.8) combined with the subcritical assumption on the Schrödinger cocycle.
3.2 Almost localization
The proof of almost localization follows the scheme of [Reference Avila and JitomirskayaAJ2], combined with our Lemmas 3.1 and 3.2. A minor adjustment is that [Reference Avila and JitomirskayaAJ2] deals with
$\alpha $
 satisfying the strong Diophantine condition
$\mathrm {SDC}$
 while we assume the slightly weaker Diophantine condition
$\beta (\alpha )=0$
 . The almost localization for the
$\beta (\alpha )=0$
 case was previously addressed for the extended Harper’s model in [Reference HanH]. It should be sufficient to assume that
$0\leq \beta (\alpha )<c$
 for some small constant
$c>0$
 , but we do not pursue this improvement here.
Let
$C_3>0$
 be the universal constant in Lemma 3.10 below. Fix

Definition 3.1 (
$\varepsilon _0$
-resonance of
$\theta $
).


Let
$\alpha ,\theta \in \mathbb T$
 and constant
$\varepsilon _0>0$
 . We say
$k\in \mathbb Z$
 is an
$\varepsilon _0$
 -resonance of
$\theta $
 if
$\|2\theta -k\alpha \|_{\mathbb T}\leq e^{-\varepsilon _0 |k|}$
 and
$\|2\theta -k\alpha \|_{\mathbb T}=\min _{|j|\leq {|k|}} \|2\theta -j\alpha \|_{\mathbb T}$
 .
Since
$\beta (\alpha )=0$
 , for all
$\varepsilon _1>0$
 there exists
$C_0=C_0(\alpha ,\varepsilon _1)>0$
 such that for
$n\neq 0$
 ,

In the following we shall fix
$\varepsilon _1=\varepsilon _0/1000$
 . This implies the following.
Lemma 3.6. If
$|k|$
 is large enough, and
$\|2\theta -k\alpha \|_{\mathbb T}\leq e^{-\varepsilon _0 |k|}$
 , then
$\|2\theta -k\alpha \|_{\mathbb T}=\min _{|j|\leq {|k|}} \|2\theta -j\alpha \|_{\mathbb T}$
 .
Proof. In fact, for
$|j|\leq {|k|}$
 and
$j\neq k$
 ,


in which we used (3.15) to estimate
$\|(j-k)\alpha \|_{\mathbb T}$
 .
Definition 3.2. Let
$0=|n_0|\leq |n_1|\leq |n_2|\leq ...$
 be the
$\varepsilon _0$
 -resonances of
$\theta $
 . If this sequence is infinite, we say
$\theta $
 is
$\varepsilon _0$
 -resonant, otherwise we say it is
$\varepsilon _0$
 -nonresonant. Furthermore, if
$\theta $
 is
$\varepsilon _0$
 -nonresonant with a finite sequence of resonances
$0=|n_0|\leq |n_1|\leq ...\leq |n_j|$
 , we let
$n_{j+1}=\infty $
 .
Due to
$\beta (\alpha )=0$
 , we can show the following growth of the infinite sequence of
$\theta $
 resonances.
Lemma 3.7. Let
$\beta (\alpha )=0$
 , then there exists
$N_0=N_0(\alpha ,\varepsilon _0)$
 , such that for
$|n_j|>N_0$
 ,

Proof. By (3.15),


which implies the desired bound.
Definition 3.3 (Almost localization).
We say the family
$\{\hat {H}_{\alpha ,\theta }\}_{\theta \in \mathbb T}$
 is
$(C_1, C_2,\varepsilon _2)$
 -almost localized for some constants
$C_1, C_2, \varepsilon _2>0$
 if for every solution
$\hat {u}$
 of
$\hat {H}_{\alpha ,\theta }\hat {u}=E\hat {u}$
 for some energy
$E\in \mathbb R$
 , satisfying
$\hat {u}_0=1$
 and
$|\hat {u}_k|\leq 1+|k|$
 , and for every
$C_1(1+|n_j|)<|k|<C_1^{-1}|n_{j+1}|$
 , the bound
$|\hat {u}_k|\leq C_2 e^{-\varepsilon _2 |k|}$
 holds, where the
$n_j$
 ’s are the
$\varepsilon _0$
 -resonances of
$\theta $
 .
We will prove the following.
Theorem 3.8. There exists a constant
$C_2=C_2(v,d)>0$
 such that
$\{\hat {H}_{\alpha ,\theta }\}_{\theta \in \mathbb T}$
 is
$(3, C_2, \hat {L}_d/10)$
 -almost localized.
Proof. Let
$f_{E,N}(\theta )$
 be defined as in (3.2), and we omit the dependence on
$E$
 for simplicity. The following observation was made for the Harper operator (with Dirichlet boundary conditions) in [Reference JitomirskayaJ1], and extended to the long-range setting in [Reference Avila and JitomirskayaAJ2]. The extension to the periodic boundary condition setting is immediate.
Fact 3.9.
$f_{N}(\theta )=Q_{dN}(\cos (2\pi (\theta +\frac {dN-1}{2}\alpha )))$
 , where
$Q_k(x)$
 denotes a real polynomial in
$x$
 of degree
$k$
 .
Next we introduce the definition of uniformity, introduced in [Reference JitomirskayaJ1], that measures the evenness of distribution of a set in
$\mathbb T$
 .
Definition 3.4 (Uniformity).
For some
$\kappa>0$
 , we say that a set
$\{\theta _1,\theta _2,...,\theta _{m+1}\}$
 is
$\kappa $
 -uniform if

Without loss of generality, assume
$3(|n_j|+1)<y<|n_{j+1}|/3$
 and
$|n_j|>N_0(\alpha ,\varepsilon _0)$
 . The case of negative
$y$
 can be handled similarly. Choose
$n$
 such that
$dq_n\leq y/8< dq_{n+1}$
 and let
$s$
 be the largest positive integer satisfying
$sd q_n\leq y/8$
 . Define intervals
$I_1, I_2\subset \mathbb Z$
 as follows:

The key in choosing
$I_1, I_2$
 is to guarantee that
$-n_j\notin (I_1\cup I_2)+(I_1\cup I_2)$
 . Let
$6sq_n=N$
 whence
$|I_1|+|I_2|=6dsq_n+1=dN+1$
 .
Lemma 3.10. The set

is
$(C_3d\,\varepsilon _0)$
 -uniform for some absolute constant
$C_3\geq 1$
 and
$y>y_0(\alpha ,\varepsilon _0,C_{\kappa _0})$
 .
For
$d=1$
 , when
$N-1$
 is even, this is Lemma 4.3 of [Reference HanH]. In the general case, the proof requires a slight modification, which we present below.
Proof. We treat the
$n_j>0$
 case in detail and leave the other case to the reader. Note that for
$y$
 large,
$n$
 is also large. Set
$z=\cos (2\pi \xi )$
 , and, for
$r\in I_1\cup I_2$
 , denote

We first consider the Lagrange product

for
$r\neq -1$
 . The case
$r=-1$
 will be treated at the end.
Let

For every
$r\in \mathcal I^*$
 , the Lagrange product over the original set of nodes factors as

To estimate the first factor, note that


We use (3.15) with
$\varepsilon _1=\varepsilon _0/10$
 to estimate

where we used
$y+2sdq_n\leq 18sdq_n=3dN$
 . Regarding the term

we distinguish two cases.
Case 1. Suppose
$\|2\theta +(r-1)\alpha -2\left \lfloor (dN-1)/2 \right \rfloor \alpha +(dN-1)\alpha \|_{\mathbb T}<e^{-\varepsilon _0 |r-1-2\left \lfloor (dN-1)/2\right \rfloor +(dN-1)|}$
 . Then by Lemma 3.6, we have
$-n_j< -1\leq r-1-2\left \lfloor (dN-1)/2\right \rfloor +(dN-1)=-n_p$
 for some
$p\leq n-1$
 . This implies


where in the last inequality we used
$|n_j|<y/3\leq dN$
 .
Case 2. Suppose
$\|2\theta +(r-1)\alpha -2\left \lfloor (dN-1)/2 \right \rfloor \alpha +(dN-1)\alpha \|_{\mathbb T}\geq e^{-\varepsilon _0 |r-1-2\left \lfloor (dN-1)/2\right \rfloor +(dN-1)|}$
 . Then we directly bound


where we used
$r-1-2\left \lfloor (dN-1)/2\right \rfloor +(dN-1)\leq y+2sdq_n\leq 3dN$
 .
It follows from (3.27)–(3.38) that the first factor in the decomposition (3.26) is bounded by
$e^{C\varepsilon _0dN}$
 . Therefore, after enlarging the absolute constant
$C_3$
 if necessary, it remains to estimate the second product, in which the node
$-1$
 no longer appears. Equivalently, for distinguished indices
$r\neq -1$
 , we have reduced the original Lagrange product to the Lagrange product over the shortened node set

which contains
$dN=6sdq_n$
 nodes.
By a slight abuse of notation, for the rest of the proof we write

With
$I_2$
 unchanged, we have

We require the following lemma as part of the proof.
Lemma 3.11 [Reference Avila and JitomirskayaAJ1].
Let
$\alpha \in \mathbb R\backslash \mathbb Q$
 ,
$x\in \mathbb R$
 and
$0\leq r_0\leq q_n-1$
 be such that
$|\sin \pi (x+r_0\alpha )|=\inf _{0\leq r\leq q_n-1}|\sin \pi (x+r\alpha )|$
 , then for some absolute constant
$C_4>0$
 ,

For any
$r\in I_1\cup I_2$
 , it suffices to estimate

Lemma 3.11 reduces this problem to estimating the minimal terms. We first bound
$\sum _1$
 :

We divide
$I_1\cup I_2=\bigcup _{k=1}^{6sd}T_k$
 into
$6sd$
 disjoint small intervals of integers, each of cardinality
$q_n$
 . In fact,

We denote

one has

where we used Lemma 3.11 in the last inequality. Similarly, replacing
$\xi $
 with
$-\xi $
 ,

Combining (3.40) with (3.42) and (3.43), we arrive at

for
$n$
 large. Next, we estimate
$\sum _2$
 :

Let
$T_1=[0, q_n-1]\cap \mathbb Z$
 be the left-most small interval in
$I_1\cup I_2=\cup _{k=1}^{6sd}T_k$
 , and for
$k\geq 1$
 , let
$T_{k+1}$
 be on the right-hand side of
$T_k$
 . Then
$\bigcup _{k=1}^{2sd}T_k=I_1$
 and
$\bigcup _{k=2sd+1}^{6sd}T_k=I_2$
 . We also group
$T_k$
 ’s into intervals of length
$sq_n$
 , for
$1\leq h\leq 6d$
 , by defining

Denote the smallest term in each
$T_k$
 , for
$1\leq k\leq 6sd$
 , by:

and

Denote the smallest term in each
$R_h$
 , for
$1\leq h\leq 6d$
 , by:

and

We now establish the following estimate for
$\sum _{2,+}$
 .
Lemma 3.12. For
$n$
 large,

Proof. We bound


for
$n$
 large, where we used Lemma 3.11 in the second to last inequality, and
$|\sin (\pi x)|\geq 2|x|$
 in the final one. As far as the minimal terms at
$\ell _k^+$
 ,
$1\leq k\leq 6sd$
 are concerned, we now establish the following result.
Lemma 3.13.

Proof. Within the proof, for
$1\leq k\leq 6sd$
 , let

for simplicity. Then
$\tilde {\theta }_r+\tilde {\theta }_{\ell _{k}^+}=2\theta +m_k\alpha $
 . Note that since
$r, \ell _k^+\in I_1\cup I_2$
 , one has

Next, we prove Lemma 3.13 by contradiction. Suppose for some
$k$
 that

Then by (3.58), we conclude that

Furthermore, for any
$0\leq |m|\leq 6sdq_n$
 , by (3.58)

Hence by (3.15) with
$\varepsilon _1=\varepsilon _0/10$
 , one obtains


for
$n$
 large enough. Combining (3.60) with (3.62), we see that
$(-m_k)$
 must be an
$\varepsilon _0$
 -resonance.
Since
$3|n_j|<y<8(s+1)dq_n\leq 16sdq_n$
 , we obtain
$|n_j|\leq 6sdq_n$
 . Hence by (3.62) with
$m=-n_j$
 , we infer that

This implies
$-m_k=n_p$
 for some
$p\geq j+1$
 . However, this leads to a contradiction with (3.58) via
$|m_k|<|n_{j+1}|$
 .
With Lemma 3.13, we conclude the following.
Lemma 3.14. For any
$1\leq h\leq 6d$
 ,

Proof. We divide the argument into two cases.
Case 1. Suppose
$2\|\tilde {\theta }_r+\tilde {\theta }_{\tilde {\ell }_h^+}\|_{\mathbb T}\leq |\sin (\pi (\tilde {\theta }_r+\tilde {\theta }_{\tilde {\ell }_h^+}))|\leq e^{-2\varepsilon _0 q_n}$
 . For
$\ell _k^+, \tilde {\ell }_h^+\in R_h$
 and
$\ell _k^+\neq \tilde {\ell }_h^+$
 , we have
$|\ell _k^+-\tilde {\ell }_h^+|\leq sq_n$
 . Since
$sdq_n\leq y/8<dq_{n+1}$
 , in particular
$sq_n<q_{n+1}$
 , it follows by (2.1) and (3.15) with
$\varepsilon _1=\varepsilon _0$
 that

This implies, by the triangle inequality, that


for
$n$
 large. Combining (3.69) with Lemma 3.13, yields


Case 2. Assume
$\pi \|\tilde {\theta }_r+\tilde {\theta }_{\tilde {\ell }_h^+}\|_{\mathbb T}\geq |\sin (\pi (\tilde {\theta }_r+\tilde {\theta }_{\tilde {\ell }_h^+}))|> e^{-2\varepsilon _0 q_n}$
 . Then for any
$\ell _k^+\in R_h$
 ,

This implies

Lemma 3.14 implies

Lemma 3.12 follows by plugging (3.75) into (3.52), whence

as claimed.
It remains to estimate
$\sum _{2,-}$
 . Similar to (3.52), one has

We will prove the following.
Lemma 3.15. For
$n$
 large,

Proof. We have
Lemma 3.16.

Proof. We split the argument into two different cases depending on whether or not
$r\in R_h$
 .
Case 1. If
$r\in R_h$
 , then
$\tilde {\ell }_h^-=r$
 .
For
$\ell _k^-\in R_h$
 and
$\ell _k^-\neq r$
 , we note that
$0\leq |\ell _k^--r|\leq sq_n<q_{n+1}$
 . Hence by (2.1) and (3.15),

This implies that

Case 2. Assume
$r\notin R_h$
 .
Case 2.1. Assume further that
$2\|\tilde {\theta }_r-\tilde {\theta }_{\tilde {\ell }_h^-}\|\leq |\sin (\pi (\tilde {\theta }_r-\tilde {\theta }_{\tilde {\ell }_h^-}))|\leq e^{-2\varepsilon _0 q_n}$
 .
For
$\ell _k^-\in R_h$
 and
$\ell _k^-\neq \tilde {\ell }_h^-$
 , analogously to (3.80) one has


for
$n$
 large. Also since
$|r-\tilde {\ell }_h^-|\leq y+2sdq_n+1\leq 20dsq_n$
 , we infer by (3.15) that

This implies that

Case 2.2. Suppose
$\pi \|\tilde {\theta }_r-\tilde {\theta }_{\tilde {\ell }_h^-}\|\geq |\sin (\pi (\tilde {\theta }_r-\tilde {\theta }_{\tilde {\ell }_h^-}))|>e^{-2\varepsilon _0 q_n}$
 . Thus, for any
$\ell _k^-\in R_h$
 ,

This implies

Combining the cases above, we have proved Lemma 3.16.
Finally, combining (3.44), (3.45) with Lemmas 3.12 and 3.15, we obtain

This completes the estimate for the original Lagrange product for every
$r\neq -1$
 . For the remaining case
$r=-1$
 , the product over
$\ell $
 ranges over
$\mathcal I^*=I_1\cup I_2$
 , so both its numerator and denominator contain
$dN=6sdq_n$
 factors. The same decomposition into the
$6sd$
 intervals
$T_k$
 , each of cardinality
$q_n$
 , applies, and the restrictions
$\ell \neq r$
 are vacuous. The estimates above apply in the same way, and we omit the repetition.
This establishes Lemma 3.10.
Lemma 3.10 implies the following. Recall that
$\hat {L}^d=\hat {L}(d\alpha ,M_E)=d\cdot \hat {L}^d(\alpha ,\hat {A}_E)$
 .
Lemma 3.17. If
$y>y_1(\alpha ,\varepsilon _0,v,E)$
 , then there exists
$r\in I_1\cup I_2$
 such that

Proof. Assuming the lemma is false, let
$\tilde {\theta }_r$
 be defined as in (3.25). If (3.89) fails for all
$r\in I_1\cup I_2$
 , then


Note that
$Q_{dN}(x)$
 is a polynomial in
$x$
 of degree
$dN\leq dN+1=|I_1|+|I_2|$
 . Hence by the Lagrange interpolation theorem, for any
$x\in [0,1]$
 ,

By Lemma 3.10, we infer that

Combining (3.92) with (3.90) and (3.93), we conclude that

However, combining Lemma 3.5 with (2.28), there exists
$\theta $
 such that

which is a contradiction.
Lemma 3.17 implies the following result.
Corollary 3.18. If
$y>y_1(\alpha ,\varepsilon _0,v,E)$
 , then there exists
$r\in I_2$
 such that

Proof. It suffices to show that (3.96) does not hold for any
$r\in I_1$
 . Thus, assume that (3.96) does hold for some
$r_1\in I_1$
 . Let

We estimate the Green’s function,

for
$0\leq m\leq d-1$
 . By Lemma 3.1, and using
$|\det B|=|\hat {v}_d|^{dN}$
 , one has


Combining this with the lower bound in (3.96) for
$r=r_1$
 yields


Similarly, for any
$0\leq m\leq d-1$
 ,


Using the Poisson formula (3.7), and bounding
$|\hat {u}_k|\leq 1+|k|$
 and
$\|B\|\leq C_v$
 ,
$\|B^{-1}\|\leq C_v |\hat {v}_d|^{-1}$
 , we infer that


Clearly,

Hence, we can further bound (3.105) by

With the choice of
$\varepsilon _0$
 in (3.14), we arrive at a contradiction with the assumption that
$\hat {u}_0=1$
 by sending
$n\to \infty $
 .
Corollary 3.18 implies the following bound:

in which we used (3.14) in the last inequality. The proof is similar to arguments in the proof of Corollary 3.18, after replacing the role of
$\hat {u}_0$
 with
$\hat {u}_y$
 and using
$y\geq 8dsq_n$
 . This finishes the proof of almost localization.
3.3 Localization
Theorem 1.7 follows from Theorem 3.8 by noting that any
$\theta $
 with
$\gamma (\alpha ,\theta )=0$
 is
$\varepsilon _0$
 -nonresonant for any
$\varepsilon _0>0$
 .
Remark 3.19. For
$\alpha $
 satisfying the strong Diophantine condition

one can give another proof of localization by combining the large deviation theorem with the zero count of
$\det (P_{\alpha ,n}(\theta )-E)$
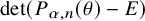 as in [Reference Han and SchlagHS1]. This approach will allow us to prove nonperturbative localization for a.e.
$\alpha $
 satisfying the strong Diophantine condition
$\mathrm {SDC}$
 for a general class of operators obtained by replacing the cosine potential in
$\hat {H}_{\alpha ,\theta }$
 with arbitrary analytic potentials. We will address this problem in an upcoming work.
4 Numerator upper bound for periodic boundary conditions
This section is devoted to the proof of Lemma 3.1. We consider the finite volume Hamiltonian with periodic boundary conditions. To distinguish it from
$\hat {H}_{\alpha ,n}(\theta )$
 , which satisfies Dirichlet boundary conditions, we denote the periodic Hamiltonian by
$P_{\alpha ,n}(\theta )$
 . We shall omit
$\alpha $
 from the notation for simplicity, and denote
$C(\theta +jd\alpha )-E$
 by
$C_j$
 . Thus,

Let
$P_{n}(\theta ;x,y)$
 be the submatrix of
$P_n(\theta )-E$
 obtained by deleting the
$x-$
 th row and
$y-$
 th column. We treat the case
$0\leq x\leq d-1$
 in detail, and briefly go through the other case at the end of this section.
Case 1. Suppose
$0\leq x\leq d-1$
 and
$3d\leq y\leq (n-1)d-1$
 . We write
$y=\ell d+r$
 for some
$\ell \in [3,n-2]$
 and
$r\in [0,d-1]$
 . Let

in which
$\mathbf {e}_{m,j}^*=(\delta _j(m-1),...,\delta _j(1),\delta _j(0))$
 and
$\delta _{j}(k)$
 is the Kronecker delta. Clearly

Next, we carry out elementary row operations to reduce
$R_{x,y}$
 . These operations do not alter
$|\det R_{x,y}|$
 . We have


In this display,
$\mathrm {Row}_1,\ldots ,\mathrm {Row}_n$
 are block rows of height
$d$
 , whereas
$\mathrm {Row}_{n+1}$
 is a scalar row.
In the following we also denote
$M_{E,k}(\theta +jd\alpha )$
 by
$M_k(j)$
 for simplicity. We use the following row operations.
Row operations on
$\text {Row}_1$

Replacing the block-valued
$\text {Row}_1$
 in (4.4),

yields a new row as follows

Appealing to (2.23) and (2.24), it is easy to see that

Replacing

yields the new row

Appealing to (2.23) and (2.24), it is easy to see that

One can iterate this process, and after replacing

we arrive at

Row operations on
$\text {Row}_2$

Replacing

yields the following new row


Repeating this process, and after replacing

we arrive at

Next, we perform row reduction on
$\text {Row}_{n-\ell +1}$
 . Recall that
$3\leq \ell \leq n-2$
 .
Row operations on
$\text {Row}_{n-\ell +1}$
(the row containing
$C_{\ell -1}$
).


Replacing

yields a new row as follows


where the matrix
$B$
 is the
$(n-\ell )-$
 th entry (from the left) of the block-valued vector above, and we have used (2.23) and (2.24) to obtain the second line. Repeating this process, and after replacing

we arrive at

At this point,
$R_{x,y}$
 becomes

The first, second,
$(n-\ell +1)$
 -th,
$n$
 -th, and
$(n+1)$
 -th rows are

in which only columns
$1$
 ,
$n-\ell $
 ,
$n-1$
 ,
$n$
 ,
$n+1$
 are nonvanishing. Let

be the nonvanishing
$(4d+1)\times (4d+1)$
 submatrix of rows
$1$
 ,
$2$
 ,
$n-\ell +1$
 ,
$n$
 , and
$n+1$
 . Let

which is the submatrix of
$R^{(1)}_{x,y}$
 after deleting rows
$1$
 ,
$2$
 ,
$n-\ell +1$
 ,
$n$
 ,
$n+1$
 and columns
$1$
 ,
$n-\ell $
 ,
$n-1$
 ,
$n$
 ,
$n+1$
 . Hence

where we used
$\det S_2=(\det B)^{n-4}$
 . It suffices to compute
$\det S_1$
 . Expanding determinants and using that
$M_{k-2}^{UL}(1)=BM_{k-1}^{LL}(1)$
 ,
$M_{k-2}^{UR}(1)=BM_{k-1}^{LR}(1)$
 , we have

Expanding along the first column this simplifies further to

in which
$M_{\ell -1}^U(1)=(M_{\ell -1}^{UL}(1), M_{\ell -1}^{UR}(1))=(I_d, 0)\cdot M_{\ell -1}(1)$
 . Empty spaces are to be filled in by zeros. We carry out the following row operations on
$S_3$
 that do not alter the determinant of
$S_3$
 . Below
$\text {row}_j$
 refers to the
$j$
 -th (block-valued) row of
$S_3$
 . Replacing

and

we arrive at

Next, multiplying
$\text {col}_3$
 of
$S_3^{(1)}$
 on the right by
$M_1(0)$
 (for which
$\det M_1(0)=1$
 , so
$\det S_3^{(1)}$
 is invariant), yields

Expanding the determinant along the first two columns, and noting that
$\left (\begin {matrix} 0 &B\\ 0 &0\end {matrix}\right ) M_1(0)=\left (\begin {matrix}I_d &0\\ 0 &0\end {matrix}\right )$
 , yields

We expand
$S_3^{(3)}$
 as the following product:


We bound


Suppose that

In order for

to be nonvanishing, necessarily

If it is nonvanishing, then


where we used Lemma 2.1 to bound
$\|\wedge ^{m_0}M_{\ell }(0)\|$
 . Taking (4.29) into account, one has


where we used Lemma 2.1 again. The following estimates are easy to verify:


Combining (4.30), (4.33) with (4.36), one has


where we used that
$\hat {L}^1<...<\hat {L}^{d-1}<\hat {L}^d$
 and
$\hat {L}^d>\hat {L}^{d+1}>...>\hat {L}^{2d}$
 , due to
$\hat {L}_d>0>\hat {L}_{d+1}$
 . Combining the above with (4.15),(4.16) and (4.19) yields the claimed result for Case 1.
Case 2. Suppose
$(n-1)d\leq x\leq nd-1$
 . Again, we write
$y=\ell d+r$
 with
$3\leq \ell \leq n-2$
 and
$0\leq r\leq d-1$
 . We also denote
$x-(n-1)d=\tilde {x}$
 . In analogy to (4.4), we have
$|\mu _{n,x,y}(\theta )|=|\det \tilde {R}_{x,y}|$
 , where

Applying exactly the same row operations on
$\text {Row}_1$
 ,
$\text {Row}_2$
 , and
$\text {Row}_{n-\ell +1}$
 as in Case 1, reduces
$\tilde {R}_{x,y}$
 to the following shape:

This implies, similarly to (4.15), that

where in analogy with (4.16) and (4.19) one has

where


The remainder of the argument is exactly the same as in Case 1.
5 Denominator lower bound for periodic boundary conditions
In this section we prove Lemma 3.2. Throughout, we denote
$B_0$
 by
$B$
 , and
$C_0(\theta +jd\alpha )-E$
 by
$C_j$
 . First, we relate the determinant
$f_{E,n}(\theta )=\det (P_{\alpha ,n}(\theta )-E)$
 to the transfer matrix
$M_{n,E}$
 .
Lemma 5.1. The following identity holds pointwise in
$\theta $


Proof. The proof is similar to, and is in fact simpler than, the one of Lemma 3.1. Indeed, following exactly the same row operations (that do not alter
$f_{E,n}$
 ) applied to
$\text {Row}_1$
 ,
$\text {Row}_2$
 , and
$\text {Row}_{n-\ell +1}$
 of
$P_{\alpha ,n}(\theta )-E$
 , instead of those on
$R_{x,y}$
 in Section 4 (note these operations do not involve the terms
$\mathbf {e}_{d,x}$
 or
$\mathbf {e}_{d,r}^*$
 ), in analogy to (4.11) we arrive at the equality

This implies, similarly to (4.15), that

where

Furthermore, in place of (4.16), we now have

Rewriting this in block form yields

To estimate
$\det (M_{n,E}(\theta )-I_{2d})$
 , we need the following elementary lemma concerning the vector spaces associated with the singular value decomposition of a symplectic matrix. We include the proof for the sake of completeness.
Lemma 5.2. Let
$M\in \mathbb C^{2d\times 2d}$
 be a complex symplectic matrix, that is,
$M^*\Omega M=\Omega $
 . Let
$\sigma _1\geq ...\geq \sigma _{2d}$
 be the singular values of
$M$
 . Let
$\mu _1>...>\mu _k$
 be the nonrepeated singular values and
$V_j$
 ,
$1\leq j\leq k$
 , be the singular vector space of
$M$
 associated to
$\mu _j$
 . Similarly, let
$W_j$
 be the singular vector space of
$M^*$
 associated to
$\mu _j$
 . Then

Proof. Let
$v_j\in V_j$
 be a unit vector, and
$w_j$
 be the unit vector such that

This implies

Since
$M$
 is symplectic, we also have

Combining (5.8), (5.9) with (5.10), yields


This implies that
$\Omega v_j$
 is an eigenvector of
$M^*M$
 associated to the eigenvalue
$\mu _j^{-2}=\mu _{k+1-j}^2$
 , whence
$\Omega v_j\in V_{k+1-j}$
 . Therefore,
$\Omega V_j\subset V_{k+1-j}$
 for any
$1\leq j\leq k$
 , which implies that
$\Omega V_j=V_{k+1-j}$
 . The claim concerning
$W_j$
 can be proved analogously.
Next, we will apply the previous lemma to
$M_{n,E}(\theta )$
 . For simplicity, we shall write
$\hat {L}^j(d\alpha , M_E)$
 ,
$\hat {L}_j(d\alpha , M_E)$
 as
$\hat {L}^j$
 and
$\hat {L}_j$
 , respectively. Recall that the large deviation set
$\mathcal {B}_{n,E,\varepsilon }^d$
 was defined in (2.32). By Lemma 2.2, this set is exponentially small for large enough
$n$
 . We fix
$0<\varepsilon <\frac {\hat {L}_d}{11\hat {L}^d}$
 . Note that for such
$\varepsilon $
 ,

Let
$\theta \in (\mathcal {B}^d_{n,E,\varepsilon })^c$
 , and
$v_{j,n}(\theta )$
 be the normalized singular vector of
$M_{n,E}(\theta )$
 corresponding to the singular value
$\sigma _j(M_{n,E}(\theta ))$
 . Suppose
$w_{j,n}(\theta )$
 is the normalized singular vector of
$M_{n,E}^*(\theta )$
 such that

According to Lemmas 2.1 and 2.2, for
$\theta \in (\mathcal {B}_{n,E,\varepsilon }^d)^c$
 , one has

It follows that

Let
$V_{j,n}(\theta )$
 and
$W_{j,n}(\theta )$
 be as defined in Lemma 5.2 with
$M$
 replaced with
$M_{n,E}(\theta )$
 . Clearly
$k$
 is even. By that lemma, for any
$1\leq j\leq k/2$
 ,

This implies the following relations between the most expanding and most contracting
$d$
 -planes:


and in particular


The following result will play a crucial role in our argument, cf. [Reference Goldstein and SchlagGS3, Lemma 3.2]. It will enable us to show that for a subsequence of
$n$
 , the most expanding
$d$
 -planes of
$M_{n,E}(\theta )$
 and
$M_{n,E}^*(\theta )$
 are not entirely orthogonal.
Lemma 5.3. Assume that
$\beta (\alpha )=0$
 . Then for any small
$\varepsilon>0$
 , there exist
$N_0=N_0(\varepsilon ,\alpha ,E,d)$
 and
$\kappa _0=\kappa _0(\varepsilon ,\alpha ,E,d,N_0)>0$
 such that for any
$\kappa _0$
 -admissible
$N_1$
 (those satisfying
$\|N_1d\alpha \|_{\mathbb T}\leq \kappa _0$
 ), and
$N_1\geq 8N_0$
 , we have

Proof. By Lemma 2.2, we can choose
$N_0:=N_0(\varepsilon ,\alpha ,E,d)$
 so that for
$n\geq N_0$
 , one has
$\mathrm {mes}(\mathcal {B}_{n,E,\varepsilon }^d)\leq e^{-n\varepsilon ^2 \cdot \hat {L}^d(d\alpha ,M_E)}$
 and, furthermore,

where
$c_1$
 is the constant in Lemma 2.2, as well as

where
$\tilde {C}_0, c_0>0$
 are the constants in Theorem 2.4. For the purposes of this proof, we let

omitting the fixed parameters
$E$
 and
$\varepsilon $
 for simplicity. We also denote
$\hat {L}^k(d\alpha , M_E)$
 by
$\hat {L}^k$
 . First, we need the following estimate at the fixed scale
$N_0$
 .
Lemma 5.4. There exists
$\kappa _0=\kappa _0(\varepsilon ,\alpha , E, d, N_0)$
 such that for any
$\|\kappa \|_{\mathbb T}\leq \kappa _0$
 , and for any
$\theta _0$
 satisfying

one has the bound

Proof. We use the following estimate from [Reference Duarte and KleinDK]:
Lemma 5.5 [Reference Duarte and KleinDK, Lemma 2.8].
For
$k\times k$
 complex matrices
$h_1, h_2$
 , for any
$1\leq j\leq k$
 ,

We apply Lemma 5.5 to
$k=2d$
 ,
$j=d$
 , and


By Lemma 2.1, uniformly in
$\theta $
 ,

Hence, Lemma 5.5 implies furthermore that uniformly in
$\theta $
 ,


where in the last step we used a telescoping argument. Hence for
$\|\kappa \|_{\mathbb T}\leq \kappa _0(\varepsilon , \alpha ,E,d,N_0)$
 , one has uniformly in
$\theta $
 ,

This, combined with (5.25) at
$\theta =\theta _0$
 , implies that

which is the claimed result.
Fix
$N_0$
 as chosen above and let
$\kappa _0$
 be given by Lemma 5.4. We pick an arbitrary
$\kappa _0$
 -admissible
$N_1$
 (i.e.,
$\|N_1d\alpha \|_{\mathbb T}\leq \kappa _0$
 ), satisfying
$N_1\geq 8N_0$
 . Let
$k\geq 2$
 be such that
$2^{k+1}N_0\leq N_1<2^{k+2}N_0$
 , and
$n_0=N_1-2^k N_0=N_1-N_0-\sum _{\ell =0}^{k-1}2^{\ell }N_0$
 be the remainder. Clearly

Our goal is to estimate

where
$\kappa =-N_1d\alpha $
 (modulo
$\mathbb Z$
 ) satisfies
$\|\kappa \|_{\mathbb T}\leq \kappa _0$
 . In order to accomplish this, we decompose


Step 1. Recall that
$\mathcal {G}_n=(\mathcal {B}_{n,E,\varepsilon }^d)^c$
 , as in (5.24). Let


We restrict to
$\theta \in \mathcal {G}_{N_0}^{(1)}$
 for the remainder of the proof. Let


The goal of Step 1 is to show the following.
Lemma 5.6. For any
$\theta \in \mathcal {G}_{N_0}^{(1)}$
 , one has

for the constant
$\tilde {C}_0>0$
 in Theorem 2.4 and with

Furthermore,

where
$c_1>0$
 is the constant in Lemma 2.2.
Proof. By Lemma 2.2, for all
$\theta \in \mathcal {G}_{N_0}^{(1)}$
 , we have

and

Note that by definition
$\theta \in \mathcal {G}_{N_0}^{(1)}\subset \mathcal {G}_{2N_0}-(N_1-N_0)d\alpha $
 , hence

Combining the above (which verifies the assumptions of Lemma 5.4 for
$\theta _0=\theta +(N_1-N_0)d\alpha $
 ) with Lemma 5.4 and
$\|\kappa \|_{\mathbb T}\leq \kappa _0$
 , yields


By Lemma 2.1 applied to the matrix
$\wedge ^2 (\wedge ^d M_{N_0,E})$
 and


one has uniformly in
$\theta \in \mathbb T$
 ,

Combining the above with the lower bounds in (5.55), we conclude that

Note that (5.55), (5.63), (5.56) and (5.58) verify the assumptions of Theorem 2.4, the Avalanche Principle. In fact, for
$j=1,2,3,4$
 ,

and for
$j=1,2,3$
 ,

Clearly,

due to (5.23). Therefore, by applying Theorem 2.4 to
$g_{N_0,4}(\theta )\cdots g_{N_0,1}(\theta )$
 , we obtain with the constant
$\tilde {C}_0>0$
 in Theorem 2.4,


Regarding the measure estimate, we note that

where we used that for any
$n\geq N_0$
 ,
$\mathrm {mes}(\mathcal {G}_{n})=1-\mathrm {mes}(\mathcal {B}_{n,E,\varepsilon }^d)\geq 1-e^{-c_1\varepsilon ^2 n\hat {L}^d}$
 , due to Lemma 2.2.
To better illustrate the inductive procedure, we present the second step in detail as well.
Step 2. Let


Note that

Hence by Lemma 5.6, for
$\theta \in \mathcal {G}_{N_0}^{(1)}$
 ,

We further restrict
$\theta $
 to the following subset of
$\mathcal {G}_{N_0}^{(1)}$
 :


The goal of Step 2 is to prove the following:
Lemma 5.7. For
$\theta \in \mathcal {G}_{2N_0}^{(1)}$
 ,

where

Furthermore,

Proof. Since
$\theta \in \mathcal {G}_{2N_0}^{(1)}$
 , by Lemma 2.2 one has for
$j=1,2,3,4$
 that

and for
$j=1,3$
 that

In analogy to (5.63), we have for
$j=1,2,3,4$
 that

We apply the avalanche principle (AP) Theorem 2.4 to
$g_{2N_0,4}(\theta ),...,g_{2N_0,1}(\theta )$
 . The hypotheses of the AP hold since: for
$j=1,2,3,4$
 , by (5.80) and (5.82),

and for
$j=1,2,3$
 , by further taking (5.81) and (5.74) into account,

Clearly,

where we used (5.66) to bound
$\tilde {\kappa }_{N_0}\cdot \tilde {\varepsilon }_{N_0}^{-2}<c_0$
 . Therefore, Theorem 2.4 implies that


Regarding the measure estimate, Lemma 2.2 implies that


This is the claimed result.
Next, we carry out the following inductive procedure. For any
$\ell \geq 0$
 , let


Note this is consistent with the definitions of
$g_{N_0,j}(\theta )$
 and
$g_{2N_0,j}(\theta )$
 in (5.48) and (5.70). For any
$\ell \geq 0$
 , let

and define
$\tilde {\varepsilon }_{2^{\ell }N_0}$
 inductively;
$\tilde {\varepsilon }_{N_0}$
 is defined in (5.53) and for
$\ell \geq 1$
 ,

Note that these definitions are consistent with those in (5.53) and (5.78) for
$\ell =0,1$
 . Clearly, for any
$n\geq 1$
 ,


by (5.23), (5.66), and induction.
Step
$\underline{m}$
 for
$\underline{m=3,...,k}$
 .
Lemma 5.8. Suppose
$\mathcal {G}_{2^{m-2} N_0}^{(1)}$
 is defined and satisfies the following two conditions:
-
1.
(5.98) $$ \begin{align} \mathcal{G}_{2^{m-2}N_0}^{(1)}\subset (\mathcal{G}_{2^{m-1}N_0}-(N_1-2^{m-1}N_0)d\alpha)\cap (\mathcal{G}_{2^{m-1}N_0}-N_1d\alpha-\kappa) \end{align} $$
-
2.
(5.99) $$ \begin{align} \mathrm{mes}(\mathcal{G}_{2^{m-2}N_0}^{(1)})\geq 1-5\sum_{\ell=0}^{m-2}e^{-2^{\ell} c_1\varepsilon^2 N_0 \hat{L}^d}-2e^{-2^{m-1}c_1\varepsilon^2N_0\hat{L}^d}. \end{align} $$


Assume further that for any
$\theta \in \mathcal {G}_{2^{m-2}N_0}^{(1)}$
 the following holds:

Let


Then for any
$\theta \in \mathcal {G}_{2^{m-1}N_0}^{(1)}$
 , one has

Furthermore,
$\mathcal {G}_{2^{m-1}N_0}^{(1)}$
 satisfies the following two conditions:
-
1.
(5.104) $$ \begin{align} \mathcal{G}_{2^{m-1}N_0}^{(1)}\subset (\mathcal{G}_{2^{m}N_0}-(N_1-2^{m}N_0)d\alpha)\cap (\mathcal{G}_{2^{m}N_0}-N_1d\alpha-\kappa) \end{align} $$
-
2.
(5.105) $$ \begin{align} \mathrm{mes}(\mathcal{G}_{2^{m-1}N_0}^{(1)})\geq 1-5\sum_{\ell=0}^{m-1}e^{-2^{\ell} c_1\varepsilon^2 N_0\hat{L}^d}-2e^{-2^{m}c_1\varepsilon^2N_0\hat{L}^d}. \end{align} $$


Proof. For any
$\theta \in \mathcal {G}_{2^{m-1}N_0}^{(1)}$
 , Lemma 2.2 implies for
$j=1,2,3,4$
 that

and for
$j=1,3$
 that

By assumption (5.100), one has


In analogy to (5.63), we infer for
$j=1,2,3,4$
 that

In order to apply Theorem 2.4 to
$g_{2^{m-1}N_0,4}(\theta ),...,g_{2^{m-1}N_0,1}(\theta )$
 , we first check that the assumptions are satisfied. By (5.106) and (5.110), one has for
$j=1,2,3,4$
 that

By (5.106), (5.107) and (5.108) we have that for
$j=1,2,3$
 ,

Clearly,


where we used (5.96). Therefore, Theorem 2.4 implies that


It suffices to prove the measure estimate for
$\mathcal {G}_{2^{m-1}N_0}^{(1)}$
 . Clearly, Lemma 2.2 implies that


as claimed.
We now return to the main argument, that is, the proof of Lemma 5.3. Note that the assumptions on
$\mathcal {G}_{2^{m-2}N_0}^{(1)}$
 are verified in the base case
$m=3$
 by Lemma 5.7. Hence, the inductive scheme applies and therefore (5.103), (5.104) and (5.105) hold for
$m=k$
 .
Step
$\underline{k+1}$
 . Recall that
$n_0=N_1-2^k N_0$
 . Let


By (5.103) with
$m=k$
 , and recalling the definition of
$g_{2^kN_0,j}$
 in (5.90), we note that


where we used (5.96) in the last inequality. Recall also that

Let


In this last step, we are going to apply Theorem 2.4 to the four matrices on the right-hand side of (5.124). We now verify that the hypotheses are satisfied for
$\theta \in \mathcal {G}_{2^kN_0}^{(1)}$
 . By Lemma 2.2, one has for
$j=2,3$
 that

and for
$j=1,4$
 that

We also have


Similarly to (5.63), for
$j=2,3$
 ,

and for
$j=1,4$
 ,

Combining (5.122), (5.127), (5.128), (5.129), (5.131) and (5.132), we conclude that for
$j=2,3$


while for
$j=1,4$
 , the following holds:

where we used
$n_0\geq 2^kN_0$
 as in (5.36). Moreover,


where we used
$2^{k+1}N_0\leq N_1$
 in the first inequality. Clearly,

Therefore, Theorem 2.4 implies that


Finally, to estimate the measure, recall
$n_0\geq 2^k N_0$
 and
$N_1\geq 2^{k+1}N_0$
 whence


where we used (5.105) with
$m=k$
 and (5.22). This proves the claimed result.
As a corollary of Lemma 5.3, we now establish
Corollary 5.9. Under the same conditions as in Lemma 5.3, for large enough
$\kappa _0$
 -admissible
$n$
 , with
$n\geq 8N_0$
 , and for any
$\theta \in (\tilde {\mathcal {B}}^d_{n,E,\varepsilon })^c$
 , we have that

For readability, we record the following two auxiliary estimates before proving Corollary 5.9; in both lemmas the indices are assumed to be strictly increasing.
Lemma 5.10. For
$n$
 large enough, for any
$1\leq k\leq 2d-1$
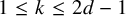 ,
$k\neq d$
 , and for any strictly increasing indices
$1\leq j_1<\cdots <j_k\leq 2d$
 , one has uniformly in
$\theta \in \mathbb T$
 ,

Here
$\varepsilon>0$
 is arbitrary but fixed.
Proof. Clearly, by Lemma 2.1,

where we used that for any
$k\neq d$
 ,
$\hat {L}^k\leq \hat {L}^{d-1}$
 due to
$\hat {L}_d>0$
 and
$\hat {L}_{d+1}<0$
 .
Lemma 5.11. For strictly increasing indices
$1\leq j_1<\cdots <j_d\leq 2d$
 with
$(j_1,...,j_d)\neq (1,...,d)$
 , and for
$n$
 large enough,

uniformly in
$\theta \in \mathbb T$
 .
Proof. If
$\sigma _{j_d}(M_{n,E}(\theta ))<1$
 , then

by Lemma 5.10. On the other hand, if
$\sigma _{j_d}(M_{n,E}(\theta ))\geq 1$
 , then

where we used
$j_d>d$
 and Lemma 5.10.
Proof of Corollary 5.9.
Towards a contradiction, suppose that for some
$\theta \in (\tilde {\mathcal {B}}^d_{n,E,\varepsilon })^c$
 one has


We expand

in which

For arbitrary
$1\leq j_1<...<j_d\leq 2d$
 , there is the trivial bound

By assumption (5.153), one has

We now use the two auxiliary bounds stated before the proof of the corollary. By Lemmas 2.1, 2.2, 5.11 and estimates (5.157) and (5.153), one has for
$n$
 large enough,


where we used (5.14). This leads to a contradiction with
$\theta \in (\tilde {\mathcal {B}}^d_{n,E,\varepsilon })^c$
 .
Combining Corollary 5.9 with (5.19), we infer the following result.
Corollary 5.12. Under the same conditions as in Lemma 5.3, for large enough
$\kappa _0$
 -admissible
$n$
 , with
$n\geq 8N_0$
 , and for any
$\theta \in (\tilde {\mathcal {B}}^d_{n,E,\varepsilon })^c\cap (\mathcal {B}_{n,E,\varepsilon }^d)^c$
 , one has


The goal of the remainder of this section is to prove the following lemma.
Lemma 5.13. Under the same conditions as in Lemma 5.3, for large enough
$\kappa _0$
 -admissible
$n$
 , with
$n\geq 8N_0$
 , for any
$\theta \in (\tilde {\mathcal {B}}^d_{n,E,\varepsilon })^c\cap (\mathcal {B}_{n,E,\varepsilon }^d)^c$
 , one has

Proof. Let
$U_{v,n}(\theta )=(v_{1,n}(\theta ),...,v_{2d,n}(\theta ))$
 and
$U_{w,n}(\theta )=(w_{1,n}(\theta ),...,w_{2d,n}(\theta ))$
 , and

The singular value decomposition
$M_{n,E}(\theta )U_{v,n}(\theta )=U_{w,n}(\theta )D_n(\theta )$
 yields

Note that

Hence,


where we recall that for a matrix
$M$
 ,
$M_{B_1,B_2}$
 refers to the submatrix with row numbers in the set
$B_1$
 and column numbers taken from the set
$B_2$
 . By Hadamard’s inequality,

and

where
$(Q_n(\theta ))_{\ell }$
 refers to the
$\ell $
 -th column of
$Q_n(\theta )$
 . Moreover, we used the following bound

Corollary 5.12 implies that


Combining the estimates (5.173), (5.174), (5.176) with (5.170), and using Lemmas 5.10 and 5.11 and Corollary 5.12, we infer that for
$\theta \in (\tilde {\mathcal {B}}_{n,E,\varepsilon }^d)^c\cap (\mathcal {B}^d_{n,E,\varepsilon })^c$


where we used (5.14). This is the claimed result.
Alternatively, Lemma 5.13 can also be proved via Schur complements. Lemma 3.2 follows immediately from combining Lemmas 5.1 and 5.13 with the measure estimates of
$\tilde {\mathcal {B}}^d_{n,E,\varepsilon }$
 in Lemma 5.3 and
$\mathcal {B}^d_{n,E,\varepsilon }$
 in Lemma 2.2.
5.1 Proof of Lemma 3.5
Let
$z=e^{2\pi i\theta }$
 and
$F_{E,n}(z)=f_{E,n}(\theta )$
 , and
$g_{E,n}(z)=z^{nd} F_{E,n}(z)$
 . It is easy to check that
$|g_{E,n}(0)|=1$
 . Let
$\mathcal {C}$
 be the unit circle. In the following, we use Herman’s subharmonic argument:


It remains to recall that by Haro-Puig’s result, see Theorem 1.8, for
$E\in \sum _{\alpha ,0}$
 in the subcritical regime,

This proves Lemma 3.5.
6 Non-selfadjoint Haro-Puig formula
6.1 Proof of Corollary 1.12
We shall write
$\hat {L}_j(\alpha , \hat {A}_E^{\varepsilon })$
 as
$\hat {L}_j(\varepsilon )$
 for simplicity. By Theorem 1.10 and (2.29) one has that


This can be further simplified in the form:


This implies

whence, in particular,

This is the claimed result.
The remainder of this section consists of a proof of Theorem 1.10.
6.2 Preparation
In the following, let
$(\alpha , A)\in \mathbb T\times C^{\omega }(\mathbb T,\mathrm {Mat}(d,\mathbb C))$
 be an analytic cocycle. The following lemma and theorems from [Reference Avila, Jitomirskaya and SadelAJS] play an important role in our proof. All fractions
$p/q$
 are reduced (in lowest terms), and we may assume in addition that
$d|q$
 (we will need this at some point below). Indeed, if
$|\frac {p_n}{q_n}-\alpha |\to 0$
 as
$n\to \infty $
 for an irrational
$\alpha $
 , then also
$|\frac {dp_n+1}{dq_n}-\alpha |\to 0$
 . No prime dividing
$d$
 can divide
$dp_n+1$
 , so the denominator remains divisible by
$d$
 after removing common factors.
Definition 6.1 [Reference Avila, Jitomirskaya and SadelAJS].
We say
$(\alpha ,A)$
 is
$k$
 -regular if
$t\to L^k (\alpha , A(\cdot +it))$
 is an affine function of
$t$
 in a neighborhood of
$0$
 .
We will only use the definition of
$1$
 -regular for the cocycle
$(\alpha ,A_{E,\varepsilon })\in \mathbb T\times C^{\omega }(\mathbb T, \mathrm {Mat}(2,\mathbb C))$
 .
Lemma 6.1 [Reference Avila, Jitomirskaya and SadelAJS, Lemma 5.1].
If
$L^k(\alpha ,A)>-\infty $
 , then for arbitrarily small
$\varepsilon _0>0$
 and
$p/q$
 sufficiently close to
$\alpha $
 , one has uniformly for all
$\theta $
 that

Theorem 6.2 [Reference Avila, Jitomirskaya and SadelAJS, Theorem 5.2].
Assume
$L^k(\alpha ,A)>-\infty $
 and that
$(\alpha ,A)$
 is
$k$
 -regular. Then for arbitrarily small
$\varepsilon _0>0$
 and
$p/q$
 sufficiently close to
$\alpha $
 , one has uniformly for all
$\theta \in \mathbb T$
 ,

Theorem 6.3 [Reference Avila, Jitomirskaya and SadelAJS, Theorem 1.5].
The functions
$(\mathbb T, C^{\omega }(\mathbb T, \mathrm {Mat}(d,\mathbb C)))\ni (\alpha , A)\to L_k(\alpha ,A)\in [-\infty , \infty )$
 are continuous at any
$(\alpha ', A')$
 with
$\alpha '\in \mathbb R\setminus \mathbb Q$
 .
The case of
$L_k=-\infty $
 does not arise here. Since there are only finitely many
$\varepsilon $
 ’s such that
$(\alpha , A_{E,\varepsilon })$
 is not
$1$
 -regular, it suffices to prove Theorem 1.10 for any
$\varepsilon $
 at which
$(\alpha , A_{E,\varepsilon })$
 is
$1$
 -regular. Also, due to (2.29), there are only finitely many values of
$\varepsilon $
 for which some of the exponents
$\hat {L}_j(\alpha , \hat {A}_E^{\varepsilon })$
 vanish. Hence it suffices to assume that none of the
$\hat {L}_E^{\varepsilon }(\alpha , \hat {A}_E^{\varepsilon })$
 are zero. The identity (1.17) for arbitrary
$\varepsilon $
 will then follow from continuity in
$\varepsilon $
 by Theorem 6.3. We will thus make the following assumption below.
Assumption 6.4. Let
$\varepsilon $
 be such that
$(\alpha , A_{E,\varepsilon })$
 is
$1$
 -regular.
6.3 Proof of Theorem 1.10
The goal is to prove the following rational frequency
$\alpha =p/q$
 version of Theorem 1.10. Let
$k_0\in \{1,...,2d\}$
 be such that

assuming that
$\hat {L}_1(\alpha ,\hat {A}_{E}^{\varepsilon })>0$
 . We allow for all exponents to be positive here. We will deal with the remaining case
$\hat {L}_1(\alpha ,\hat {A}_{E}^{\varepsilon })<0$
 at the end of this section (the vanishing case can be ignored, see above).
Lemma 6.5. For any
$\varepsilon $
 such that
$(\alpha , A_{E}^{\varepsilon })$
 is
$1$
 -regular and for arbitrarily small
$\varepsilon _0$
 such that

the following holds for some constant
$C>0$
 :

Clearly, Theorem 1.10 follows from taking
$\varepsilon _0\to 0^+$
 in Lemma 6.5. For the rest of the proof of Lemma 6.5, the symbol
$\varepsilon _0$
 denotes this fixed auxiliary parameter; all later choices of rational approximants
$p/q$
 are taken sufficiently close to
$\alpha $
 depending on this
$\varepsilon _0$
 and on the fixed data. To prove Lemma 6.5, we consider the following three periodic operators acting on
$\ell ^2(\mathbb Z_q)$
 :


and

It is clear that we have
Fact 6.6.
$H_{p/q,0,\varepsilon }=\tilde {H}_{p/q,0,\varepsilon }$
 .
We will work with the Fourier transform on the cyclic group
$\mathbb Z_q$
 . We write the characters on this finite Abelian group in the form
$\chi _m(n)=e^{-2\pi i mnp/q}$
 , Haar measure being counting measure. Note that
$np$
 for
$1\le n\le q$
 is just a relabeling of the congruence classes modulo
$q$
 . The Fourier transform is thus defined in the form


and gives a unitary transformation on
$\ell ^2(\mathbb Z_q)$
 . Lemma 6.7 establishes Aubry duality for the periodic operators by means of this Fourier transform.
Lemma 6.7.
$ \mathcal {F}\tilde {H}_{p/q,\theta ,\varepsilon }\mathcal {F}^{-1} =\hat {H}_{p/q,\theta ,\varepsilon }. $

Proof. For simplicity, we write
$\hat {H}_{p/q,\theta ,\varepsilon }$
 as
$\hat {H}$
 . Then


as claimed.
For
$E\in \mathbb C$
 , let
$D_{p/q,E,\varepsilon }(\theta ):=\det (H_{p/q,\theta ,\varepsilon }-E)$
 and define
$\tilde {D}$
 ,
$\hat {D}$
 analogously for the operators
$\tilde {H}$
 and
$\hat {H}$
 , respectively. The Aubry duality Lemma 6.7 implies the following invariance property.
Corollary 6.8. For any
$E\in \mathbb C$
 and any
$\theta \in \mathbb T$
 , we have

By inspection we have
Fact 6.9. For any
$E\in \mathbb C$
 ,
$D_{p/q,E,\varepsilon }(\theta )$
 is a
$(p/q)$
 -periodic (hence
$(1/q)$
 -periodic) function in
$\theta $
 . Analogous results hold for
$\tilde {D}$
 and
$\hat {D}$
 .
The following Chambers type formula is an easy consequence of Fact 6.9.
Lemma 6.10. For any
$E\in \mathbb C$
 , we have

where
$a(p/q,E,\varepsilon )$
 is independent of
$\theta $
 . This, combined with Fact 6.6 implies that

Proof. The
$\hat {D}=\tilde {D}$
 part is due to Corollary 6.8. The term of highest degree (in
$e^{2\pi i\theta }$
 ) in
$\tilde {D}_{p/q,E,\varepsilon }(\theta )$
 equals
$(-1)^{q+1}e^{2\pi i q\theta }$
 , and that of lowest degree is
$(-1)^{q+1}e^{-2\pi iq\theta }$
 . The lemma now follows from Fact 6.9.
Combining (6.28), Corollary 6.8 with Jensen’s formula implies the following.
Lemma 6.11. Denote the two zeros of

by
$z_1, z_2$
 , respectively. Then for any
$E\in \mathbb C$
 ,

Next, we compare the right-hand side of (6.29) to
$qL^1(\alpha , A_{E,\varepsilon })$
 for all large
$q$
 . Note that
$A_{E,\varepsilon }\in \mathrm {SL}(2,\mathbb C)$
 implies that
$L^1(\alpha , A_{E,\varepsilon })\ge 0$
 .
Lemma 6.12. If
$(\alpha , A_{E,\varepsilon })$
 is
$1$
 -regular, for some constant
$C>0$
 , we have

provided
$q$
 is large.
Proof. First, simple considerations yield

Hence by Lemma 6.11, we have

Next, we relate
$D_{p/q,E,\varepsilon }(0)$
 to
$L^1(\alpha , A_{E,\varepsilon })$
 . Let

be the eigenvalues of
$A_{q,E,\varepsilon }(p/q,\theta )$
 . Applying (2.7) to
$A=A_{E,\varepsilon }$
 , we have

The following lemma relates
$D_{p/q,E,\varepsilon }(\theta )$
 to
$A_{q,E,\varepsilon }(p/q,\theta )$
 .
Lemma 6.13. We have for all
$\theta \in \mathbb {T}$


Proof. The proof is very similar to that of Lemma 5.1. As in the previous sections, we perform elementary row operations (which leave the determinant invariant), on the
$q\times q$
 matrix

where we write
$v(\theta +i\varepsilon +jp/q)-E$
 as
$v_j$
 for simplicity. We also denote
$A_{n,E,\varepsilon }(p/q,\theta +jp/q):=A_n(j)$
 , and

Our calculations are based on the following recursive relations:

Replacing
$\text {Row}_1$
 with
$\text {Row}_1-v_{q-1}\cdot \text {Row}_2$
 yields


Replacing
$\text {Row}_1^{(1)}$
 with
$\text {Row}_1^{(1)}+A_2^{11}(q-2)\cdot \text {Row}_3$
 yields


We repeat this process until

Next, we carry out an analogous row reduction on the second row. Replacing
$\text {Row}_2$
 with
$\text {Row}_2-v_{q-2}\cdot \text {Row}_3$
 yields

We repeat this process until

Note that the first, second, and last rows, respectively, of the matrix we started with now read

We expand the determinant of the transformed matrix
$H_{p/q,\theta ,\varepsilon }-E$
 along the second column using the identities
$A_{q-2}^{11}(1)=A_{q-1}^{21}(1)$
 ,
$A_{q-2}^{12}(1)=A_{q-1}^{22}(1)$
 . This yields


as claimed.
By Assumption 6.4,
$(\alpha , A_{E,\varepsilon })$
 is 1-regular, hence by Theorem 6.2 and (6.33), for
$p/q$
 sufficiently close to
$\alpha $
 ,

This implies, by
$\lambda _{1,E,\varepsilon }\lambda _{2,E,\varepsilon }= 1$
 , that

Hence by Lemma 6.13, we have for all sufficiently large
$q$


Finally it remains to relate
$\hat {D}_{p/q,E,\varepsilon }$
 to the dual Lyapunov exponents. As stated, the following argument requires
$q$
 to be divisible by
$d$
 (see above why we can assume this).
Lemma 6.14. For
$q=rd$
 with
$r\in \mathbb N$
 , we have


Proof. (6.56) follows from (6.55), due to (2.27). The proof of (6.55) is similar to those of Lemmas 6.13 and 5.1, and is based on elementary row operations. Consider the operator

where
$C_j=C_{\varepsilon }(\theta +jp/r)-E$
 and
$B=B_{\varepsilon }$
 ,
$\tilde {B}=\tilde {B}_{\varepsilon }$
 . Denote
$M_{r,E}^{\varepsilon }(p/r,\theta +jp/r)=:M_r(j)$
 , and

We will use the following recursive relations repeatedly:

Replacing
$\text {Row}_1$
 with
$\text {Row}_1-C_{r-1}B^{-1}\cdot \text {Row}_2$
 yields


Replacing
$\text {Row}_1^{(1)}$
 with
$\text {Row}_1^{(1)}+M_2^{11}(r-2)\cdot \text {Row}_3$
 yields


Repeating this process we arrive at

Next we replace
$\text {Row}_2$
 with
$\text {Row}_2-C_{r-2}B^{-1}\cdot \text {Row}_3$
 , which yields


Repeating this process we obtain

The first, second, and last rows are

Expanding determinants and using that
$M_{r-2}^{11}(1)=BM_{r-1}^{21}(1)$
 ,
$M_{r-2}^{12}(1)=BM_{r-1}^{22}(1)$
 , we have


This implies the claimed result by noting
$|\det B|=|\hat {v}_{-d}e^{2\pi d\varepsilon }|^d$
 .
Taking Lemmas 6.12 and 6.14 into account, Lemma 6.5 will follow from the following.
Lemma 6.15. Under the assumptions of Lemma 6.5 one has


for all sufficiently large
$q$
 .
Proof. Let

be the eigenvalues of
$\hat {A}_{q,E}^{\varepsilon }(p/q,\theta )$
 . We need the following elementary estimate.
Lemma 6.16. For any
$1\leq m\leq 2d$
 , we have

Proof. The eigenvalues of
$\wedge ^m\hat {A}_{q,E}^{\varepsilon }(p/q,\theta )$
 are precisely the products
$\hat {\lambda }_{j_1,E,\varepsilon }(\theta )\cdots \hat {\lambda }_{j_m,E,\varepsilon }(\theta )$
 with
$1\leq j_1<\cdots <j_m\leq 2d$
 . Since the eigenvalues
$\hat {\lambda }_{j,E,\varepsilon }(\theta )$
 are ordered by modulus, the spectral radius of this exterior power is
$\prod _{j=1}^m |\hat {\lambda }_{j,E,\varepsilon }(\theta )|$
 . The identity therefore follows directly from the definition (2.7).
Lemma 6.17. If
$p/q$
 is sufficiently close to
$\alpha $
 , then for any
$1\leq j_1<j_2<...<j_m\leq 2d$
 such that
$(j_1,...,j_{m})\neq (1,...,k_0)$
 , one has

and

Proof.
Case 1. If
$m\neq k_0$
 , we estimate by Lemmas 6.1 and 6.16 that uniformly in
$\theta $


Case 2.1. If
$m=k_0$
 and
$|\hat {\lambda }_{j_{k_0},E,\varepsilon }(\theta )|\leq 1$
 , we estimate

where we used the bound in Case 1.
Case 2.2. If
$m=k_0$
 and
$|\hat {\lambda }_{j_{k_0},E,\varepsilon }(\theta )|>1$
 . We have
$|\hat {\lambda }_{j,E,\varepsilon }(\theta )|>1$
 for any
$1\leq j\leq k_0$
 . Since
$(j_1,...,j_{k_0})\neq (1,...,k_0)$
 , we have
$j_{k_0}\geq k_0+1$
 . We estimate, in this case,

where we used again the estimate in Case 1. Finally, note that due to the definition of
$k_0$
 , we have

which proves (6.79). Finally, (6.80) follows directly from Lemmas 6.16 and 6.1.
Let


and introduce the good set for fixed
$q$


Lemma 6.18. The Lebesgue measure of
$\mathcal {G}$
 satisfies

Proof. By Lemma 6.17, we have

Hence by the definition of
$\mathcal {G}$
 in (6.87) and (6.89), we have


This implies

as desired.
On the good set we have the following approximation result.
Lemma 6.19. If
$p/q$
 is sufficiently close to
$\alpha $
 , then

Proof. For each
$\theta \in \mathcal {G}$
 , for
$q$
 large, we estimate by Lemma 6.17 that


Analogously, for all
$\theta \in \mathcal {G}$
 we have the upper bound

Next, we estimate
Lemma 6.20. Under the assumptions of Lemma 6.5,

Proof. By Lemma 6.17, we have

This implies, after combining with (6.92),


By Lemmas 6.14, 6.10, and (6.92), we have


provided
$|D_{p/q,E,\varepsilon }(0)|\ge 3$
 . On the other hand, if
$|D_{p/q,E,\varepsilon }(0)|\le 3$
 , then


as desired.
We also have
Lemma 6.21.

Proof. For simplicity, we write
$g(\theta ):=\frac {1}{q}\sum _{j=1}^{k_0} \log |\hat {\lambda }_{j,E,\varepsilon }(\theta )|$
 and
$\hat {L}^{k_0}:=\hat {L}^{k_0}(\alpha ,\hat {A}_{E}^{\varepsilon })$
 . By Lemmas 6.16 and 6.17, we have

which implies

We also have by (6.92) and Lemma 6.17 that

This proves the claimed result.
Finally, combining (6.93) with Lemmas 6.20 and 6.21, we have


Combining Lemmas 6.12, 6.14, 6.15, we have proved Lemma 6.5.
It remains to deal with the case
$\hat {L}^{1}(\alpha , \hat {A}_{E}^{\varepsilon })<0$
 . By Lemmas 6.1 and 6.15, there exists
$\delta>0$
 so that uniformly in
$\theta $
 , and provided
$p/q$
 is close to
$\alpha $
 , one has

for all
$1\le m\le 2d$
 . Hence, for all
$1\le j_1\le \ldots \le j_m\le 2d$
 we have

Therefore,

and

We now conclude Theorem 1.10 from Lemmas 6.12 and 6.14 as before.
A Proof of Theorem 1.2
The argument closely follows [Reference Avila and JitomirskayaAJ2], with a simplification from [Reference AvilaAv2]. Throughout this section we write
$\hat {L}^j(\alpha ,\hat {A}_E), \hat {L}_j(\alpha ,\hat {A}_E)$
 as
$\hat {L}^j(\hat {A}_E), \hat {L}_j(\hat {A}_E)$
 for simplicity.
A.1 Preparation
Theorem A.1 [Reference Avila and JitomirskayaAJ2, Theorem 3.3].
If
$E\in \sigma (H_{\alpha ,\theta })$
 , then there exist
$\theta \in \mathbb R$
 and a bounded solution of
$\hat {H}_{\alpha ,\theta }\hat {u}=E\hat {u}$
 with
$\hat {u}_0=1$
 and
$|\hat {u}_n|\leq 1$
 .
Given Fourier coefficients
$\hat {w}=(\hat {w}_k)_{k\in \mathbb Z}$
 and an interval
$I\subset \mathbb Z$
 , we let
$w_I=\sum _{k\in I} \hat {w}_k e^{2\pi i kx}$
 . The length of the interval
$I= [a, b]$
 is
$|I|= b-a$
 . We will say that a trigonometrical polynomial
$p:\mathbb T \to \mathbb C$
 has essential degree at most
$k$
 if its Fourier coefficients outside an interval
$I$
 of length
$k$
 vanish. We let
$\frac {p_n}{q_n}$
 be the convergents of
$\alpha $
 .
Theorem A.2 [Reference Avila and JitomirskayaAJ2, Theorem 6.1].
Let
$1\leq r\leq \lfloor q_{n+1}/q_n\rfloor $
 . If
$p$
 has essential degree at most
$k= rq_n-1$
 and
$x_0\in \mathbb T$
 , then for some absolute constant
$C$


A.2 Proof of Theorem 1.2
Fix
$E\in \sigma (H_{\alpha ,\theta })$
 , and let
$\theta (E)$
 be as in Theorem A.1. Let
$\varepsilon _0$
 be such that
$0<\varepsilon _0<\frac {\hat {L}_d(\hat {A}_E)}{30\hat {L}^d(\hat {A}_E)+100C_3d}$
 where
$C_3$
 is the absolute constant in Lemma 3.10. Finally, let
$\{n_j\}$
 be the
$\varepsilon _0$
 -resonances of
$\theta (E)$
 and
$\hat {u}$
 be the almost localized solution as in Theorem 3.8. Hence for
$3(|n_j|+1)<|n|<|n_{j+1}|/3$
 and some
$C_2=C_2(v,d)>0$
 , one has

For simplicity we shall write
$\theta (E)$
 as
$\theta $
 for the remainder of this appendix.
The cocycle
$(\alpha , A_E)$
 being subcritical, which precisely means that
$L(\alpha , A_{E,\eta })= 0$
 for all
$|\eta |\leq \hat {L}_d/(2\pi )$
 , implies via Lemma 2.1 the following subexponential growth

for arbitrary
$\delta>0$
 . Henceforth, we fix
$\delta =\min (\frac {\hat {L}_d(\hat {A}_E)}{5000}, \frac {\varepsilon _0}{25})$
 . Theorem A.3 improves this subexponential bound to a polynomial one.
Theorem A.3. For some absolute constants
$C_4>0$
 , and
$C_5=C_5(\alpha ,v,E,\varepsilon _0)>0$
 ,

for any
$k\geq 1$
 .
Proof. The proof proceeds by constructing an
$\mathrm {SL}(2,\mathbb C)$
 almost conjugacy of
$A_{E}(x)$
 . Thus, let
$n$
 be such that

To see that such an
$n$
 exists, note that Lemma 3.7 implies that

Moreover, for any
$r,m\geq 1$
 , one has

Let
$I=[x_1,x_2]:=[-\lfloor n/2\rfloor +1, \lfloor n/2\rfloor ]\cap \mathbb Z$
 , and define

By direct computation one obtains

where

We select
$U^I(x)$
 as the first column of our putative conjugacy matrix. In order to construct the second column, we first establish a lower bound on
$\|U^I(x)\|$
 .
Lemma A.4. For
$n>n_0(\alpha ,v,E,\varepsilon _0)$
 satisfying (A.5), we have

Proof. If the lemma fails, then there exists
$x_0$
 with
$|\mathrm {Im}(x_0)|\leq \frac {\hat {L}_d(\hat {A}_E)}{40\pi }$
 so that

Iterating (A.9) yields


Combining the above with (A.3), (A.12) and (A.10), we infer that for
$0\leq \ell \leq n$
 ,

By Theorem A.2, we finally arrive at the uniform bound

where we used that
$q_{m+1}\leq C_{\delta } e^{\delta q_m/(2C)}$
 , see (3.15). Clearly, (A.16) contradicts

for
$n$
 large enough.
We now invoke the following lemma to construct the second column of our conjugacy matrix.
Lemma A.5 [Reference AvilaAv2, Lemma 4.2].
Let
$V: \mathbb T\to \mathbb C^2$
 be analytic in
$|\mathrm {Im}(x)|\leq \eta $
 . Assume
$\delta _1<\|V(x)\|<\delta _2^{-1}$
 holds on
$|\mathrm {Im}(x)|<\eta $
 . Then there exists
$M: \mathbb T\to \mathrm {SL}(2,\mathbb C)$
 analytic on
$|\mathrm {Im}(x)|<\eta $
 with the first column equal to
$V$
 and
$\|M\|_{\eta }\leq C\delta _1^{-2}\delta _2^{-1}(1-\log (\delta _1\delta _2))$
 .
Let
$M^I(x)$
 be the matrix obtained by means of Lemma A.5 whose first column equals
$U^I$
 . By Lemma A.4 and the fact that
$|\hat {u}_k|\leq 1$
 , for any
$|\mathrm {Im}(x)|\leq \frac {\delta }{2\pi }$
 ,

By Lemma A.5,

and by (A.9),

Thus,


whence

Passing to determinants in (A.20), and using (A.21), we conclude that

which implies

Combining the above equation with the bounds in (A.21) and (A.22) implies that

Let

Then by (A.20), (A.21), (A.22) and (A.25),

where


Moreover, by (A.18) and (A.26),

In view of (A.27), this implies that for all
$1\leq s\leq e^{\frac {\hat {L}_d(\hat {A}_E)}{800}n}$
 one has

There exists an absolute constant
$c_4>0$
 , such that for
$s>s(\alpha ,v,E,\varepsilon _0)$
 large enough, there exists
$n$
 , with
$9|n_j|<n<|n_{j+1}|/9$
 , and satisfying the requirement of Lemma A.4, such that
$c_4 n<\frac {800}{\hat {L}_d(\hat {A}_E)}\log s<n$
 . Thus by (A.31), we finally obtain

as claimed.
Next, let
$J=[-\lfloor |n_{j+1}|/9\rfloor , \lfloor |n_{j+1}|/9\rfloor ]\cap \mathbb Z$
 , and define

By the almost localization Theorem 3.8, one has

and

Let
$M_J(x)$
 be the matrix with the first column equal to
$U^J(x)$
 , and the second column equal to
$\overline {U^J(x)}$
 , respectively. By the preceding,

where
$H(x)=\left (\begin {matrix} G(x) & \overline {G(x)}\end {matrix}\right )$
 satisfies
$\|H\|_{\frac {\hat {L}_d}{32\pi }}\leq e^{-\frac {\hat {L}_d(\hat {A}_E)}{150}|n_{j+1}|}.$

We also define
$\tilde {U}^J(x):=e^{\pi in_jx} U^J(x)$
 . When
$n_j$
 is even,
$\tilde {U}^J$
 is well-defined on
$\mathbb T$
 , and when
$n_j$
 is odd,
$\tilde {U}^J(x+1)=-\tilde {U}^J(x)$
 . By (A.34), with
$\tilde {\theta }:=\theta -n_j\alpha /2$
 ,

By Theorem 3.8, we also have

Let
$\tilde {M}_J(x)$
 be the matrix with columns
$\tilde {U}^J(x)$
 and
$\overline {\tilde {U}^J(x)}$
 . Clearly,

Theorem A.6. Let
$L=\|2\theta -n_j\alpha \|_{\mathbb T}^{-1}$
 . Then for
$j>j_0(\alpha ,v,E,\varepsilon _0)$
 ,

where
$C_4$
 is the constant in Theorem A.3.
Proof. We first establish the following estimates on
$L$
 .
Lemma A.7. For
$j>j_0(\alpha ,\hat {L}_d)$
 ,

Proof. For
$\varepsilon _1=\frac {\hat {L}_d(\hat {A}_E)}{4000C_4}$
 , we have by (3.15) that for
$n>N(\alpha ,\hat {L}_d(\hat {A}_E))$
 ,


This implies the claimed result.
We now prove Theorem A.6 by contradiction, based on the next lemma.
Lemma A.8. For any
$\kappa \in \mathbb C$
 such that
$|\kappa |=1$
 ,

Proof. Suppose for some
$x_0$
 ,
$|\mathrm {Im}(x_0)|\leq \frac {\delta }{2\pi }$
 , and some constant
$|\kappa |=1$
 we have

By (A.37), Theorem A.3 and Lemma A.7, for all
$0\leq |\ell |\leq L^2$
 one concludes that


Setting
$\ell =\ell _0=\lfloor L/2\rfloor $
 in (A.46), we conclude that

Writing
$\ell _0=L/2+\delta $
 with
$|\delta |\leq 1/2$
 , and
$2\theta -n_j\alpha =m_0\pm \|2\theta -n_j\alpha \|_{\mathbb T}$
 , we infer that

Plugging (A.49) into (A.48), and combining the resulting estimate with (A.38), yields

For
$|\ell |\leq L^{1/2}$
 , we have in analogy to (A.49) that

Plugging (A.51) into (A.37) yields

Next, we let
$\tilde {n}$
 be such that

Let
$\tilde {I}=[-\lfloor \tilde {n}/2\rfloor +1, \lfloor \tilde {n}/2\rfloor ]\cap \mathbb Z$
 and define

as well as
$\tilde {U}^{\tilde {I}}(x)=e^{\pi in_jx}U^{\tilde {I}}(x)$
 . Then by Theorem 3.8, we have

Combining the above with (A.52) yields

Denoting

we obtain from (A.56) that


for any
$|\ell |\leq L^{1/2}$
 . Lemma A.7 implies that
$L^{1/2}>e^{\varepsilon _0 |n_j|}>\tilde {n}$
 , whence by Theorem A.2,

Here we used that
$q_{m+1}<C_{\varepsilon _0} e^{\varepsilon _0 q_m/350 C}$
 , see (3.15), and
$\tilde {n}=rq_m-1<27|n_j|$
 . This implies

and in particular

Combining (A.50) with (A.55), we have

Finally combining (A.63) with (A.62), we conclude that

This leads to a contradiction with Lemma A.4 which implies

where we used Lemma A.7 and
$\tilde {n}<27|n_j|$
 .
Next, we return to the estimate of
$\det M_J$
 . Combining (A.55) with (A.65), we obtain


For an arbitrary
$x$
 with
$|\mathrm {Im}(x)|\leq \frac {\delta }{2\pi }$
 , suppose we have (the other case is similar)

Setting
$\kappa :=\overline {e^{\pi i n_j x}u^J(x)}/(e^{\pi i n_j x}u^J(x))$
 , which satisfies
$|\kappa |=1$
 , one has


where we used (A.68) and Lemma A.8 in the last line. The claimed result on
$|\det M_J(x)|$
 follows by combining (A.39) with Lemma A.7.
Next, we construct an
$\mathrm {SL}(2,\mathbb R)$
 conjugacy. Let
$S(x)=\mathrm {Re}\, U^J(x)$
 and
$T(x)=\mathrm {Im}\, U^J(x)$
 , and define
$W_1(x)$
 to be the matrix with columns
$S(x)$
 and
$T(x)$
 . Thus

Clearly (A.35) implies

By Theorem A.6,
$\det W_1(x)\neq 0$
 for
$|\mathrm {Im}(x)|\leq \frac {\delta }{2\pi }$
 . Without loss of generality we assume
$\det W_1(x)>0$
 on
$\{x: |\mathrm {Im}(x)|\leq \frac {\delta }{2\pi }\}$
 (otherwise we take
$W_1(x)$
 to be the matrix with columns
$S(x)$
 and
$-T(x)$
 ). By (A.36), we conclude that

Combining this estimate with (A.72), we infer that for
$|\mathrm {Im}(x)|\leq \frac {\delta }{2\pi }$
 ,

By Theorem A.6, Lemma A.7 and (A.74), for all
$|\mathrm {Im}(x)|\leq \frac {\delta }{2\pi }$
 ,

with
$w_0\geq L^{-5C_4}$
 . Combining (A.73) with (3.7), (A.72), (A.75) and Lemma A.7, we have

Define
$W_2(x)=(\det W_1(x))^{-1/2} W_1(x) \in C^{\omega }_{\frac {\delta }{2\pi }}(\mathbb T, \mathrm {SL}(2,\mathbb R))$
 . By (A.76) and (A.75), we have that for
$|\mathrm {Im}(x)|\leq \frac {\delta }{2\pi }$
 ,


Taking (A.72), (A.75) and Lemma A.7 into account, one has

The estimate of
$\mathrm {deg}(W_2)$
 , see Definition B.1, follows the same Rouché argument as the proof of Theorem 3.5 in [Reference Avila and JitomirskayaAJ2]. In fact, in the subcritical case, one should be able to obtain an improved bound
$|\mathrm {deg}(W_2)|\lesssim \log |n_j|$
 . We leave those details to interested readers.
B Proof of Theorem 1.6
B.1 Rotation number
The standard facts recalled in this subsection can be found, for example, in [Reference EliassonE1, Reference Avila and JitomirskayaAJ2, Reference PuigP].
Definition B.1. Any
$A:\mathbb T\to \mathrm {SL}(2,\mathbb R)$
 is homotopic to
$x\to R_{nx}$
 for some integer
$n$
 , called the degree of
$A$
 and denoted
$\mathrm {deg}(A)=n$
 .
Assume that
$A:\mathbb T\to \mathrm {SL}(2,\mathbb R)$
 is homotopic to the identity. There exist
$\psi : \mathbb T^2\to \mathbb R$
 (lift of
$A$
 ) and
$v: \mathbb T^2\to \mathbb R^+$
 such that

Let
$\mu $
 be any probability measure on
$\mathbb T^2$
 that is invariant under the map

projecting over the Lebesgue measure on the first coordinate. Then the number

is independent of
$\psi $
 and
$\mu $
 , and is called the fibered rotation number of
$(\alpha , A)$
 . It is clear from the definition that

If the cocycles
$(\alpha , A^{(1)})$
 and
$(\alpha , A^{(2)})$
 are conjugate to each other, that is,
$B(x+\alpha )^{-1}A^{(1)}(x)B(x)=A^{(2)}(x)$
 for some continuous
$B:\mathbb T\to \mathrm {PSL}(2,\mathbb R)$
 with
$\mathrm {deg}(B)=k$
 , then

The following relation between the rotation number on the one hand, and the integrated density of states (see (2.39)) on the other hand, is well-known (see the references above):

B.2 Almost localization and almost reducibility
The following connection between localization and reducibility was first explored in [Reference PuigP], leading to the proof of the Ten Martini problem for the almost Mathieu operator for all
$\alpha $
 satisfying the strong Diophantine condition
$\mathrm {SDC}$
 . The exact form cited below appeared in [Reference Avila and JitomirskayaAJ2].
Theorem B.1 [Reference Avila and JitomirskayaAJ2].
*Theorem 2.5 For
$\alpha \in \mathbb R\setminus \mathbb Q$
 , let
$H_{\alpha ,\theta ,v}$
 be the Schrödinger operator with a real-valued analytic potential
$v$
 . Let
$\theta ,E\in \mathbb R$
 be such that there exists a nontrivial exponentially decaying solution of the dual operator
$\hat {H}\hat {u}=E\hat {u}$
 . Then
-
• If $2\theta \notin \mathbb Z\alpha +\mathbb Z$
, then there is a
$B: \mathbb T\to \mathrm {SL}(2,\mathbb R)$
analytic such that
$B(x+\alpha )^{-1}A_E(x)B(x)=R_{\pm \theta }$
. -
• If $2\theta -n\alpha \in \mathbb Z$
for some
$n\in \mathbb Z$
, then there exists
$B: \mathbb T\to \mathrm {PSL}(2,\mathbb R)$
and
$w: \mathbb T\to \mathbb R$
analytic such that (B.6) $$ \begin{align} B(x+\alpha)^{-1}A_E(x)B(x)= \left( \begin{matrix} \pm 1\, &w(x)\\ 0 &\pm 1 \end{matrix} \right). \end{align} $$
If moreover $\beta (\alpha )=0$
, then
$w$
can be chosen to be a constant.


In either case,
$\rho (\alpha ,A_E)=\pm \theta +\frac {m}{2}\alpha $
 for some
$m\in \mathbb Z$
 .
B.3 Proof of Theorem 1.6
By Theorem 1.2, we have the following spectral consequence, which is the analogue of Theorem 4.1 in [Reference Avila and JitomirskayaAJ2].
Theorem B.2. For
$\beta (\alpha )=0$
 and
$E\in \Sigma _{\alpha ,0}$
 , there exists a constant
$c>0$
 (depending on
$\hat {L}_d(\alpha , \hat {A}_E)$
 ) with the following properties:
-
1. If $\rho (\alpha , A_E)$
is
$c-$
resonant, then there exists a sequence
$B^{(n)}: \mathbb T\to \mathrm {SL}(2,\mathbb R)$
such that
$B^{(n)}(x+\alpha )^{-1}A_E(x)B^{(n)}(x)$
converges to a constant rotation uniformly in
$\{x: |\mathrm {Im}(x)|<c\}$
. -
2. If $\rho (\alpha , A_E)$
is not
$c-$
resonant and
$2\rho (\alpha , A_E)\notin \mathbb Z\alpha +\mathbb Z$
, then there exists
$B\in C^{\omega }_c(\mathbb T,\mathrm {SL}(2,\mathbb R))$
such that
$B(x+\alpha )^{-1}A_E(x)B(x)$
is a constant rotation. -
3. If $2\rho (\alpha ,A_E)\in \mathbb Z\alpha +\mathbb Z$
, then there exists
$B: \mathbb T\to \mathrm {PSL}(2,\mathbb R)$
analytic such that
$B(x+\alpha )^{-1}A_E(x)B(x)$
is a constant.


Proof. Let
$\varepsilon _0:=\frac {\hat {L}_d(\alpha ,\hat {A}_E)}{50C_3}$
 and
$\theta =\theta (E), \{n_j\}, \delta , L_j, W$
 be defined as in Theorem 1.2. First we show that if
$\theta $
 is resonant, then
$\rho (\alpha ,A_E)$
 must be resonant. Thus suppose that
$\theta $
 is
$\varepsilon _0$
 -resonant. By Theorem 1.2, for
$j>j_0(\alpha ,v,E)$
 there exists
$W_j\in C^{\omega }_{\frac {\delta }{2\pi }}(\mathbb T, \mathrm {SL}(2,\mathbb R))$
 such that

and
$|\mathrm {deg}(W_j)|\leq C_0|n_j|$
 with absolute constant
$C_0>0$
 . By (B.3), (B.4) and (B.7),

This implies, after combining the preceding with Lemma A.7, that


and


Together with (3.16) this implies that
$\rho (\alpha ,A_E)$
 is
$(2C_0+2)^{-1}\varepsilon _0$
 -resonant at
$n_j-2\mathrm {deg}(W_j)$
 . Let
$c=(2C_0+2)^{-1}\varepsilon _0, \frac {\delta }{2\pi }$
 . We divide the analysis into three cases.
Case 1. If
$\rho (\alpha , A_E)$
 is
$c$
 -resonant and
$\theta _0$
 is non-
$\varepsilon _0$
 -resonant, then Theorem 1.7 implies that there is an exponentially decaying eigenfunction. Theorem B.1 applies and yields the claimed result.
Case 2. If
$\rho (\alpha , A_E)$
 is
$c$
 -resonant and
$\theta _0$
 is
$\varepsilon _0$
 -resonant, then (B.7) is the claimed result.
Case 3. If
$\rho (\alpha , A_E)$
 is non-
$c$
 -resonant, then by the arguments above
$\theta $
 is non-
$\varepsilon _0$
 resonant. Theorem B.1 implies the claimed result.
Finally, Theorem 1.6 is the consequence of the following statement.
Theorem B.3. For
$\beta (\alpha )=0$
 ,
$|\lambda |<1$
 and
$|\nu |<\nu _0(\alpha ,\lambda ,w)$
 sufficiently small. Suppose
$E\in \sigma (H^{\mathrm {PAMO}}_{\alpha ,\theta ,\nu ,w})$
 is such that
$\mathcal {N}(E)\in \mathbb Z\alpha +\mathbb Z$
 , then
$E$
 belongs to the boundary of a component of
$\mathbb R\setminus \sigma (H^{\mathrm {PAMO}}_{\alpha ,\theta ,\nu ,w})$
 .
Proof. Due to the arguments in [Reference PuigP], it is enough to show that
$(\alpha , A^{\mathrm {PAMO}}_E)$
 is reducible. Suppose
$(\alpha , A^{\mathrm {PAMO}}_E)$
 is not reducible, then Theorem B.2 implies that
$\rho (\alpha , A_E)$
 is
$c$
 -resonant for some
$c>0$
 . But this contradicts the property
$2\rho (\alpha , A_E)\in \mathbb Z\alpha +\mathbb Z$
 , which follows from (B.5).
Acknowledgments
The authors thank anonymous referees for helpful comments.
Competing interests
The authors have no competing interests to declare.
Funding statement
R.H. was partially supported by the NSF DMS-2143369. W.S. was partially supported by the United States NSF DMS-2350356.


 Open access

