


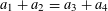


1 Introduction
The metric Poissonian property is a refined notion of the equidistribution of certain sequences on the unit circle. Initially studied in [Reference Rudnick and Sarnak11] for its connections to the Berry–Tabor conjecture in quantum mechanics, the property has recently received renewed interest, owing to the fundamental work of Aistleitner–Larcher–Lewko [Reference Aistleitner, Larcher and Lewko2], who, for the first time, revealed an intimate quantitative connection between this property and the combinatorial notion of additive energy. We continue this quantitative investigation in one of our main theorems (Theorem 1.4).
To state the main result of [Reference Aistleitner, Larcher and Lewko2], let us formally define the relevant notions. Let
 ${\mathcal{A}}\subseteq \mathbb{N}$
be an infinite set. For
 $X\rightarrow \infty$
a parameter, put
 $$\begin{eqnarray}A={\mathcal{A}}\cap [1,X],\quad N=\#A,\quad \unicode[STIX]{x1D6FF}=\unicode[STIX]{x1D6FF}(X)=N/X.\end{eqnarray}$$
For
 $\unicode[STIX]{x1D6FC}\in [0,1)$
, and
 $s>0$
some fixed parameter, we define the pair correlation function
 $$\begin{eqnarray}F(\unicode[STIX]{x1D6FC},s,X,{\mathcal{A}}):=N^{-1}\mathop{\sum }_{\substack{ a,b\in A,a\neq b \\ \Vert \unicode[STIX]{x1D6FC}(a-b)\Vert \leqslant s/N}}1.\end{eqnarray}$$
Here and in the rest of the paper, we will use
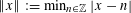 $\Vert x\Vert :=\min _{n\in \mathbb{Z}}|x-n|$
. The parameters
 $s$
,
 $X$
, and the underlying set
 ${\mathcal{A}}$
will often be suppressed, with
 $F(\unicode[STIX]{x1D6FC})$
used to denote the above.
Considering
 $\unicode[STIX]{x1D6FC}A$
as a subset of
 $\mathbb{R}/\mathbb{Z}$
, the average gap length between consecutive elements is
 $1/N$
, at least when
 $\unicode[STIX]{x1D6FC}\notin \mathbb{Q}$
. One can view the function
 $F(\unicode[STIX]{x1D6FC})$
therefore as measuring the proportion of pairs
 $(\unicode[STIX]{x1D6FC}a,\unicode[STIX]{x1D6FC}b)$
of distinct elements such that the difference
 $\unicode[STIX]{x1D6FC}a-\unicode[STIX]{x1D6FC}b\,\,\text{mod}\,\,1$
is on the scale of this average gap length. This scale is determined by the parameter
 $s$
.
The set
 ${\mathcal{A}}$
is said to be metric Poissonian if for almost all
 $\unicode[STIX]{x1D6FC}$
we have
 $$\begin{eqnarray}F(\unicode[STIX]{x1D6FC})\rightarrow 2s\quad (N\rightarrow \infty )\end{eqnarray}$$
for all
 $s>0$
.
If
 ${\mathcal{A}}$
is metric Poissonian, then for almost all
 $\unicode[STIX]{x1D6FC}$
the set
 $\unicode[STIX]{x1D6FC}A\,\,\text{mod}\,\,1$
mimics a certain statistic that holds almost surely for sequences
 $(x_{1},x_{2},\ldots )$
drawn uniformly and independently at random from
 $[0,1]$
. Indeed, if
 $I\subseteq \mathbb{R}/\mathbb{Z}$
is a uniformly chosen random interval of length
 $2s/N$
, let
 $Y_{I}$
denote the random variable
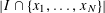 $|I\cap \{x_{1},\ldots ,x_{N}\}|$
. For fixed
 $k$
and large
 $N$
one has
 $$\begin{eqnarray}\displaystyle \mathbb{P}(Y_{I}=k) & = & \displaystyle \frac{N!}{k!(N-k)!}(2s/N)^{k}(1-2s/N)^{N-k}\nonumber\\ \displaystyle & = & \displaystyle (1+o_{k,s}(1))\cdot \exp (-2s)\cdot (2s)^{k}/k!,\nonumber\end{eqnarray}$$
so the limiting distribution of
 $Y_{I}$
is Poisson with parameter
 $2s$
. In particular its variance tends to
 $2s$
as
 $N$
tends to infinity.
When the points
 $x_{1},x_{2},\ldots ,x_{N}$
are deterministic, calculating the variance of
 $Y_{I}$
is more or less equivalent to calculating the pair correlations
 $$\begin{eqnarray}N^{-1}\mathop{\sum }_{\substack{ x_{i},x_{j} \\ x_{i}\neq x_{j} \\ \Vert x_{i}-x_{j}\Vert \leqslant t/N}}1.\end{eqnarray}$$
If for all
 $t>0$
this tends to
 $2t$
as
 $N\rightarrow \infty$
, then one may conclude that
 $\operatorname{Var}(Y_{I})\rightarrow 2s$
. The metric Poissonian property, therefore, is the statement that for almost all
 $\unicode[STIX]{x1D6FC}$
the set
 $\unicode[STIX]{x1D6FC}{\mathcal{A}}\,\,\text{mod}\,\,1$
matches the second-order statistics of a random sequence in
 $\mathbb{R}/\mathbb{Z}$
, regarding distribution in short intervals of length
 $O(1/N)$
. The statistics of a random sequence are Poisson, in the large
 $N$
limit, thus giving some explanation for the name “metric Poissonian”. For more details about this interpretation and connection, we direct the reader to the second section of [Reference Marklof10].
When
 ${\mathcal{A}}$
is the set of squares, or more generally the set of perfect
 $k\text{th}$
powers for
 $k\geqslant 2$
, the set
 ${\mathcal{A}}$
is metric Poissonian, as was shown by Rudnick and Sarnak in [Reference Rudnick and Sarnak11]. General lacunary sequences are also metric Poissonian (a result of [Reference Rudnick and Zaharescu12]). Considerations of continued fractions show that
 ${\mathcal{A}}=\mathbb{N}$
is not metric Poissonian, however. As described at the start of the paper, the situation was greatly clarified in [Reference Aistleitner, Larcher and Lewko2], by the consideration of additive energy
 $$\begin{eqnarray}E=E(X)=\#\{(a,b,c,d)\in A^{4}:a+b=c+d\}.\end{eqnarray}$$
Indeed, the authors of [Reference Aistleitner, Larcher and Lewko2] proved the following theorem.
Theorem 1.1. Assume that
 $E\ll _{\unicode[STIX]{x1D709}}N^{3-\unicode[STIX]{x1D709}}$
for some
 $\unicode[STIX]{x1D709}>0$
. Then
 ${\mathcal{A}}$
is metric Poissonian.
We leave it to the reader to verify that this theorem implies the aforementioned results for perfect powers and lacunary sequences. We remark here that the trivial upper bound on
 $E$
is
 $N^{3}$
, so the required hypothesis here is in some sense rather weak.
This theorem is neatly complemented by the following result of Bourgain, given in the appendix of [Reference Aistleitner, Larcher and Lewko2].
Theorem 1.2. Suppose
 $$\begin{eqnarray}\operatorname{limsup}_{N\rightarrow \infty }\frac{E}{N^{3}}>0.\end{eqnarray}$$
Then
 ${\mathcal{A}}$
is not metric Poissonian.
These two theorems suggest a natural route for further investigation, namely to establish whether there is some threshold for the additive energy
 $E$
that completely determines whether or not
 ${\mathcal{A}}$
is metric Poissonian. Bourgain, in the same appendix of [Reference Aistleitner, Larcher and Lewko2], gave an example of a set
 ${\mathcal{A}}$
with
 $E=o(N^{3})$
that was not metric Poissonian. This demonstrates that, if such a threshold exists, it is not at order
 $N^{3}$
.
The next development was made by the fourth named author in [Reference Walker14], answering a question of Nair concerning the primes.
Theorem 1.3. The set of prime numbers is not metric Poissonian.
In this instance, one has
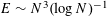 $E\sim N^{3}(\log N)^{-1}$
. The proof of this theorem made use of the divergent part of Khinchin’s theorem on Diophantine approximation, and rested on the divergence of the sum
 $\sum (N\log N)^{-1}$
. At this point, we speculate that if
 $E\sim N^{3}\unicode[STIX]{x1D713}(N)$
, for some decreasing function
 $\unicode[STIX]{x1D713}$
, then
 ${\mathcal{A}}$
is metric Poissonian if and only if
 $\sum \unicode[STIX]{x1D713}(N)/N$
converges.
Lachmann and Technau [Reference Lachmann and Technau8] have recently given examples of sets that are not metric Poissonian and that come within an arbitrary finitely iterated logarithm of this putative threshold. For
 $r\in \mathbb{N}$
, they showed that there exists a set
 ${\mathcal{A}}$
that is not metric Poissonian and that satisfies
 $$\begin{eqnarray}E\asymp \frac{N^{3}}{\log (N)\log _{2}(N)\cdots \log _{r}(N)}.\end{eqnarray}$$
Here
 $\log _{0}(N)=N$
and
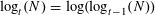 $\log _{t}(N)=\log (\log _{t-1}(N))$
for
 $t\in \mathbb{N}$
. Here and throughout, we assume that
 $N$
is large enough so that any iterated logarithms appearing are well defined and positive.
We now come to the matter of the present paper. Firstly, we offer a large improvement over the results of [Reference Aistleitner, Larcher and Lewko2], albeit under an extra hypothesis. Indeed, a key feature of Lachmann and Technau’s work is that their constructed set is extremely sparse. Assuming instead that
 ${\mathcal{A}}$
is quite dense, we show that if
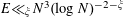 $E\ll _{\unicode[STIX]{x1D709}}N^{3}(\log N)^{-2-\unicode[STIX]{x1D709}}$
then
 ${\mathcal{A}}$
is metric Poissonian. This can be considered a complement to Lachmann and Technau’s construction.
Theorem 1.4. Assume that
 $$\begin{eqnarray}E\ll _{\unicode[STIX]{x1D709}}\frac{N^{3}}{(\log N)^{2+\unicode[STIX]{x1D709}}},\qquad \unicode[STIX]{x1D6FF}\gg _{\unicode[STIX]{x1D709}}\frac{1}{(\log N)^{2+2\unicode[STIX]{x1D709}}},\end{eqnarray}$$
for some constant
 $\unicode[STIX]{x1D709}>0$
. Then
 ${\mathcal{A}}$
is metric Poissonian.
If
 ${\mathcal{A}}$
were “random”, e.g. each element of
 $\{1,2,\ldots ,X\}$
chosen independently at random with probability
 $\unicode[STIX]{x1D6FF}$
, we would expect the energy to be approximately
 $\unicode[STIX]{x1D6FF}N^{3}$
. In the above theorem we permit
 $\unicode[STIX]{x1D6FF}$
to be smaller, by a power of a logarithm. Thus, the theorem holds for all sets of energy
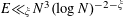 $E\ll _{\unicode[STIX]{x1D709}}N^{3}(\log N)^{-2-\unicode[STIX]{x1D709}}$
bar those that are unexpectedly sparse.
For genuinely random sets
 ${\mathcal{A}}$
, certain technical obstructions in the proof may be removed, and we obtain the following quantitatively stronger result.
Theorem 1.5. Let
 $C>2$
. Let
 ${\mathcal{A}}$
be a random set of natural numbers defined by choosing
 $x\in {\mathcal{A}}$
independently at random with probability
 $$\begin{eqnarray}\left\{\begin{array}{@{}ll@{}}1\quad & \text{if }x\leqslant 20,\\ (\log x)^{-1}(\log \log x)^{-C}\quad & \text{if }x>20.\end{array}\right.\end{eqnarray}$$
Then, with probability 1, the set
 ${\mathcal{A}}$
is metric Poissonian.
In this theorem we have conceded a factor of roughly
 $\log \log N$
from the “Khinchin threshold”. Indeed, we verify in Appendix A that
 $$\begin{eqnarray}E\asymp \frac{N^{3}}{(\log N)\cdot (\log \log N)^{C}}\end{eqnarray}$$
with probability 1.
In the random setting, we can also tackle the divergence side of the problem.
Theorem 1.6. Let
 $0\leqslant C\leqslant 1$
. Let
 ${\mathcal{A}}$
be a random set of natural numbers defined by choosing
 $x\in {\mathcal{A}}$
independently at random with probability
 $$\begin{eqnarray}\left\{\begin{array}{@{}ll@{}}1\quad & \text{if }x\leqslant 20,\\ (\log x)^{-1}(\log \log x)^{-C}\quad & \text{if }x>20.\end{array}\right.\end{eqnarray}$$
Then, with probability 1, the set
 ${\mathcal{A}}$
is not metric Poissonian.
This complements Theorem 1.5. In a way, Theorem 1.6 demonstrates that the examples provided in [Reference Lachmann and Technau8] behave as one should expect.
We return to our fundamental motivating question: is there a universal “additive energy threshold” for the metric Poissonian property?
Fundamental Question 1.7. Is it true that if
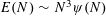 $E(N)\sim N^{3}\unicode[STIX]{x1D713}(N)$
, for some weakly decreasing function
 $\unicode[STIX]{x1D713}:\mathbb{N}\rightarrow [0,1]$
, then
 ${\mathcal{A}}$
is metric Poissonian if and only if
 $\sum \unicode[STIX]{x1D713}(N)/N$
converges?
Theorem 1.5 shows that there are metric Poissonian sets with energy
 $$\begin{eqnarray}\unicode[STIX]{x1D6E9}\biggl(\frac{N^{3}}{(\log N)\cdot (\log \log N)^{2+\unicode[STIX]{x1D700}}}\biggr),\end{eqnarray}$$
whilst Lachmann and Technau [Reference Lachmann and Technau8, Corollary 1] construct sets of energy
 $$\begin{eqnarray}\unicode[STIX]{x1D6E9}\biggl(\frac{N^{3}}{(\log N)\cdot (\log \log N)}\biggr)\end{eqnarray}$$
that are not metric Poissonian. In a way, we are within a doubly logarithmic factor of answering the question. Moreover, there is now strong evidence that the Khinchin threshold is the correct one, if such a threshold exists.
The paper is organized as follows. In §2 we describe our method, introducing an idea of Schmidt that lies at the heart of the approach. The subsequent two sections are devoted to proving the key estimates. In §5 we demonstrate how these estimates may be improved in the setting of Theorem 1.5. In §6, we use a sandwiching idea we learnt from [Reference Aistleitner, Larcher and Lewko2] to finish the proofs of Theorems 1.4 and 1.5. Then, in §7, we use a simplified version of Walker’s method [Reference Walker14] to provide an abridged proof of Theorem 1.6. Finally, in Appendix A, we compute the additive energy in the random setting.
Regarding notation, throughout
 $\unicode[STIX]{x1D707}$
denotes Lebesgue measure. For
 $n\in \mathbb{N}$
write
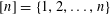 $[n]=\{1,2,\ldots ,n\}$
. We use Vinogradov and Bachmann–Landau notation, and we put
 $\mathbb{T}=[0,1]$
. It is convenient to introduce the notation
 $\widetilde{E}$
for the normalized additive energy
 $E/N^{3}$
, so that
 $\widetilde{E}\in (0,1]$
.
2 Schmidt’s trick
The arguments of Aistleitner, Larcher, and Lewko in [Reference Aistleitner, Larcher and Lewko2] rest upon the bounds of Bondarenko and Seip on greatest common divisor (GCD) sums [Reference Bondarenko and Seip4], which reach their natural limit once
 $\widetilde{E}$
is larger than
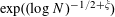 $\exp ((\log N)^{-1/2+\unicode[STIX]{x1D709}})$
. To move above this threshold, we utilize a device of Schmidt from [Reference Schmidt13], which we learnt from Ch. 4 of Harman’s book [Reference Harman7]. The idea is that, when counting integer pairs
 $(n,m)$
such that
 $|\unicode[STIX]{x1D6FC}n-m|$
is small, one can profitably split into two cases, depending on the size of GCD of
 $m$
and
 $n$
. The resulting sum enjoys much better
 $L^{2}$
information than was available in [Reference Aistleitner, Larcher and Lewko2], at a small
 $L^{1}$
cost.
We note at the outset that we will only consider values of
 $s>0$
for which
 $s\asymp 1$
. Let
 $$\begin{eqnarray}r(n)=\#\{(a,b)\in A^{2}:a-b=n,a\neq b\}\end{eqnarray}$$
and
 $$\begin{eqnarray}{\mathcal{E}}_{n}=\mathop{\bigcup }_{\substack{ u\leqslant n \\ (u,n)\leqslant T}}\biggl(\frac{u-s/N}{n},\frac{u+s/N}{n}\biggr)\,\,\text{mod}\,\,1,\end{eqnarray}$$
where
 $T\geqslant 2$
is a threshold to be specified in due course. Observe that
 $$\begin{eqnarray}F(\unicode[STIX]{x1D6FC})=\frac{2}{N}\mathop{\sum }_{\substack{ n\leqslant X \\ \Vert n\unicode[STIX]{x1D6FC}\Vert \leqslant s/N}}r(n).\end{eqnarray}$$
The idea is to replace
 $F(\unicode[STIX]{x1D6FC})$
by
 $$\begin{eqnarray}F^{\ast }(\unicode[STIX]{x1D6FC})=F^{\ast }(\unicode[STIX]{x1D6FC},s,X,{\mathcal{A}})=\frac{2}{N}\mathop{\sum }_{\substack{ n\leqslant X \\ \unicode[STIX]{x1D6FC}\in {\mathcal{E}}_{n}}}r(n).\end{eqnarray}$$
We follow the exposition of Harman very closely, though the inclusion of the weight
 $r(n)$
means we need to redo much of the argument from [Reference Harman7, Ch. 4]. Another difference is that the threshold
 $T$
, as well as the parameter
 $2s/N$
of the intervals, is uniform, depending on
 $N$
rather than
 $n$
. This will actually simplify the proof of several lemmas.
We first establish two useful lemmas on the size of the sets
 ${\mathcal{E}}_{n}$
. To this end, we introduce the quantity
 $$\begin{eqnarray}\unicode[STIX]{x1D6F7}(n)=\#\{u\in [n]:(u,n)\leqslant T\}\end{eqnarray}$$
and observe that
 $$\begin{eqnarray}\unicode[STIX]{x1D707}({\mathcal{E}}_{n})=\frac{2s}{N}\cdot \frac{\unicode[STIX]{x1D6F7}(n)}{n}.\end{eqnarray}$$
The second moment of
 $\unicode[STIX]{x1D6F7}(n)$
will be particularly useful here, but in §5 we will also have use for the first moment, when considering the random case Theorem 1.5.
Lemma 2.1. We have
 $$\begin{eqnarray}\mathop{\sum }_{n\leqslant X}\biggl(1-\frac{\unicode[STIX]{x1D6F7}(n)}{n}\biggr)\ll \frac{X}{T}.\end{eqnarray}$$
Proof. We begin by noting that
 $$\begin{eqnarray}0\leqslant n-\unicode[STIX]{x1D6F7}(n)=\mathop{\sum }_{\substack{ u\leqslant n: \\ (u,n)>T}}1=\mathop{\sum }_{\substack{ d\mid n: \\ d>T}}\unicode[STIX]{x1D719}\biggl(\frac{n}{d}\biggr)\leqslant \mathop{\sum }_{\substack{ d\mid n: \\ d>T}}\frac{n}{d},\end{eqnarray}$$
where
 $m\mapsto \unicode[STIX]{x1D719}(m)$
is the Euler totient function. It follows that
 $$\begin{eqnarray}\displaystyle 0\leqslant \mathop{\sum }_{n\leqslant X}\biggl(1-\frac{\unicode[STIX]{x1D6F7}(n)}{n}\biggr) & {\leqslant} & \displaystyle \mathop{\sum }_{n\leqslant X}\mathop{\sum }_{\substack{ d\mid n: \\ d>T}}\frac{1}{d}=\mathop{\sum }_{T<d\leqslant X}\frac{1}{d}\mathop{\sum }_{\substack{ n\leqslant X: \\ d\mid n}}1\nonumber\\ \displaystyle & {\leqslant} & \displaystyle X\mathop{\sum }_{T<d\leqslant X}d^{-2}\ll \frac{X}{T}.\square\nonumber\end{eqnarray}$$
Lemma 2.2. We have
 $$\begin{eqnarray}\mathop{\sum }_{n\leqslant X}\biggl(1-\frac{\unicode[STIX]{x1D6F7}(n)}{n}\biggr)^{2}\ll \frac{X\log T}{T^{2}}.\end{eqnarray}$$
Proof. Using the same initial manoeuvre as above, we have
 $$\begin{eqnarray}\displaystyle \mathop{\sum }_{n\leqslant X}\biggl(1-\frac{\unicode[STIX]{x1D6F7}(n)}{n}\biggr)^{2} & {\leqslant} & \displaystyle \mathop{\sum }_{n\leqslant X}\mathop{\sum }_{\substack{ d,e\mid n \\ d,e>T}}\frac{1}{de}=\mathop{\sum }_{T<d,e\leqslant X}\frac{1}{de}\mathop{\sum }_{\substack{ n\leqslant X: \\ \text{}[d,e]\mid n}}1\nonumber\\ \displaystyle & {\leqslant} & \displaystyle X\mathop{\sum }_{T<d,e\leqslant X}\frac{(d,e)}{d^{2}e^{2}}.\nonumber\end{eqnarray}$$
Putting
 $$\begin{eqnarray}g=(d,e),\qquad d=gx,\qquad e=gy\end{eqnarray}$$
gives
 $$\begin{eqnarray}\displaystyle \mathop{\sum }_{n\leqslant X}\biggl(1-\frac{\unicode[STIX]{x1D6F7}(n)}{n}\biggr)^{2} & {\leqslant} & \displaystyle X\mathop{\sum }_{g\leqslant X}g^{-3}\mathop{\sum }_{x,y\geqslant T/g}(xy)^{-2}\nonumber\\ \displaystyle & \ll & \displaystyle X\mathop{\sum }_{g\leqslant T}g^{-1}T^{-2}+X\mathop{\sum }_{g>T}g^{-3}\ll \frac{X\log T}{T^{2}}.\square\nonumber\end{eqnarray}$$
With these estimates done, we move on to the main goal of this section, which is to establish the following
 $L^{1}$
estimate. We recall the use of
 $\widetilde{E}$
to denote the normalized additive energy
 $E/N^{3}$
.
Proposition 2.3. We have
 $$\begin{eqnarray}\int _{\mathbb{T}}|F(\unicode[STIX]{x1D6FC})-F^{\ast }(\unicode[STIX]{x1D6FC})|\,d\unicode[STIX]{x1D6FC}\ll \frac{\sqrt{\log T}}{T}(\widetilde{E}\unicode[STIX]{x1D6FF}^{-1})^{1/2}.\end{eqnarray}$$
Proof. Observe that
 $$\begin{eqnarray}0\leqslant F^{\ast }(\unicode[STIX]{x1D6FC})\leqslant F(\unicode[STIX]{x1D6FC}),\end{eqnarray}$$
and that
 $$\begin{eqnarray}\int _{\mathbb{T}}F(\unicode[STIX]{x1D6FC})\,d\unicode[STIX]{x1D6FC}=\frac{2}{N}\mathop{\sum }_{n\leqslant X}r(n)\frac{2s}{N},\qquad \int _{\mathbb{T}}F^{\ast }(\unicode[STIX]{x1D6FC})\,d\unicode[STIX]{x1D6FC}=\frac{2}{N}\mathop{\sum }_{n\leqslant X}r(n)\unicode[STIX]{x1D707}({\mathcal{E}}_{n}).\end{eqnarray}$$
Therefore
 $$\begin{eqnarray}\int _{\mathbb{T}}|F(\unicode[STIX]{x1D6FC})-F^{\ast }(\unicode[STIX]{x1D6FC})|\,d\unicode[STIX]{x1D6FC}=\frac{2}{N}\mathop{\sum }_{n\leqslant X}r(n)\biggl(\frac{2s}{N}-\unicode[STIX]{x1D707}({\mathcal{E}}_{n})\biggr).\end{eqnarray}$$
Using (2.1) it follows that
 $$\begin{eqnarray}\displaystyle \int _{\mathbb{T}}|F(\unicode[STIX]{x1D6FC})-F^{\ast }(\unicode[STIX]{x1D6FC})|\,d\unicode[STIX]{x1D6FC} & = & \displaystyle \frac{2}{N}\mathop{\sum }_{n\leqslant X}r(n)\frac{2s}{N}\biggl(1-\frac{\unicode[STIX]{x1D6F7}(n)}{n}\biggr)\nonumber\\ \displaystyle & \ll _{s}\, & \displaystyle N^{-2}\mathop{\sum }_{n\leqslant X}r(n)\biggl(1-\frac{\unicode[STIX]{x1D6F7}(n)}{n}\biggr).\nonumber\end{eqnarray}$$
Finally, Cauchy’s inequality and Lemma 2.2 yield the desired inequality, since
 $$\begin{eqnarray}E=N^{2}+2\mathop{\sum }_{n\leqslant X}r(n)^{2}.\end{eqnarray}$$
◻
3 An overlap estimate
In this section, preparing for an
 $L^{2}$
argument, we bound the Lebesgue measure of the overlap
 ${\mathcal{E}}_{n}\cap {\mathcal{E}}_{m}$
. For
 $m,n\in \mathbb{N}$
, define
 $$\begin{eqnarray}A(n,m)=\mathop{\sum }_{\substack{ u\leqslant n,v\leqslant m \\ u/n=v/m \\ (u,n),(v,m)\leqslant T}}1.\end{eqnarray}$$
Note by symmetry that
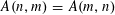 $A(n,m)=A(m,n)$
. The following lemma is a minor adaptation of [Reference Harman7, Lemma 4.4 ], to work with uniform cut-offs.
Lemma 3.1. For
 $n\geqslant m\geqslant 1$
we have
 $$\begin{eqnarray}\unicode[STIX]{x1D707}({\mathcal{E}}_{n}\cap {\mathcal{E}}_{m})\leqslant \frac{4s^{2}}{N^{2}}+\frac{2s}{N}\frac{A(n,m)}{n}.\end{eqnarray}$$
The constant 4 will be important, so we need to be quite precise here.
Proof. Considering separately the contributions from pairs of intervals for which
 $u/n=v/m$
, it is easy to see that
 $$\begin{eqnarray}\unicode[STIX]{x1D707}({\mathcal{E}}_{n}\cap {\mathcal{E}}_{m})\leqslant B_{1}+B_{2},\end{eqnarray}$$
where
 $$\begin{eqnarray}B_{1}=\mathop{\sum }_{\substack{ u\leqslant n,v\leqslant m \\ (u,n),(v,m)\leqslant T \\ u/n=v/m}}\frac{2s}{Nn}=\frac{2s}{N}\frac{A(n,m)}{n}\end{eqnarray}$$
and
 $$\begin{eqnarray}B_{2}=\mathop{\sum }_{\substack{ u\leqslant n,v\leqslant m \\ (u,n),(v,m)\leqslant T \\ u/n\neq v/m}}\unicode[STIX]{x1D707}\biggl(\biggl(\frac{u-s/N}{n},\frac{u+s/N}{n}\biggr)\cap \biggl(\frac{v-s/N}{m},\frac{v+s/N}{m}\biggr)\biggr).\end{eqnarray}$$
It therefore remains to prove that
 $B_{2}\leqslant 4s^{2}/N^{2}$
.
If
 $u/n\neq v/m$
and the intervals
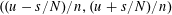 $((u-s/N)/n,(u+s/N)/n)$
and
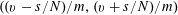 $((v-s/N)/m,(v+s/N)/m)$
intersect then for some integer
 $h$
we have
 $$\begin{eqnarray}0<|h|<(n+m)\frac{s}{N},\qquad \frac{u}{n}-\frac{v}{m}=\frac{h}{mn}.\end{eqnarray}$$
The size of the overlap is bounded above by
 $$\begin{eqnarray}\min \biggl(\frac{2s}{Nn},\frac{s}{N}\biggl(\frac{1}{n}+\frac{1}{m}\biggr)-\frac{|h|}{mn}\biggr).\end{eqnarray}$$
The number of positive integer solutions to
 $um-vn=h$
with
 $u\leqslant n$
and
 $v\leqslant m$
is bounded above by
 $$\begin{eqnarray}\left\{\begin{array}{@{}ll@{}}(m,n)\quad & \text{if }(m,n)\mid h\\ 0,\quad & \text{else.}\end{array}\right.\end{eqnarray}$$
With
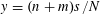 $y=(n+m)s/N$
, we now have
 $$\begin{eqnarray}\displaystyle B_{2} & {\leqslant} & \displaystyle \mathop{\sum }_{\substack{ 0<|h|<y \\ (m,n)\mid h}}(m,n)\min \biggl(\frac{2s}{Nn},\frac{s}{N}\biggl(\frac{1}{n}+\frac{1}{m}\biggr)-\frac{|h|}{mn}\biggr)\nonumber\\ \displaystyle & = & \displaystyle \mathop{\sum }_{0<|t|<y/(m,n)}(m,n)\min \biggl(\frac{2s}{Nn},\frac{s}{N}\biggl(\frac{1}{n}+\frac{1}{m}\biggr)-\frac{(m,n)|t|}{mn}\biggr).\nonumber\end{eqnarray}$$
The summand is non-increasing in
 $|t|$
, so
 $$\begin{eqnarray}\displaystyle B_{2} & {\leqslant} & \displaystyle 2\int _{0}^{y/(m,n)}(m,n)\min \biggl(\frac{2s}{Nn},\frac{s}{N}\biggl(\frac{1}{n}+\frac{1}{m}\biggr)-\frac{(m,n)t}{mn}\biggr)\,dt\nonumber\\ \displaystyle & = & \displaystyle 2\int _{0}^{y}\min \biggl(\frac{2s}{Nn},\frac{s}{N}\biggl(\frac{1}{n}+\frac{1}{m}\biggr)-\frac{h}{mn}\biggr)\,dh.\nonumber\end{eqnarray}$$
Now
 $$\begin{eqnarray}\displaystyle B_{2} & {\leqslant} & \displaystyle 2\int _{0}^{(n-m)s/N}\frac{2s}{Nn}\,dh+2\int _{(n-m)s/N}^{(n+m)s/N}\biggl(\frac{s}{N}\biggl(\frac{1}{n}+\frac{1}{m}\biggr)-\frac{h}{mn}\biggr)\,dh\nonumber\\ \displaystyle & = & \displaystyle \frac{4s^{2}}{N^{2}}\frac{n-m}{n}+\frac{4s^{2}}{N^{2}}m\biggl(\frac{1}{n}+\frac{1}{m}\biggr)-\frac{1}{mn}\frac{s^{2}}{N^{2}}((n+m)^{2}-(n-m)^{2}),\nonumber\end{eqnarray}$$
and finally we obtain
 $$\begin{eqnarray}\hspace{84.0pt}B_{2}\leqslant \frac{4s^{2}}{N^{2}}\biggl(1-\frac{m}{n}+\frac{m}{n}+1-1\biggr)=\frac{4s^{2}}{N^{2}}.\hspace{72.0pt}\square\end{eqnarray}$$
We shall also need to bound the average overlap.
Lemma 3.2. We have
 $$\begin{eqnarray}\mathop{\sum }_{n\leqslant X}\mathop{\sum }_{m\leqslant n}\frac{A(m,n)}{n}\ll X\log T.\end{eqnarray}$$
Proof. We upper bound
 $\sum _{m\leqslant n}A(m,n)$
by neglecting one of the GCD constraints, i.e.
 $$\begin{eqnarray}\mathop{\sum }_{m\leqslant n}A(m,n)\leqslant \mathop{\sum }_{\substack{ 1\leqslant m,u,v\leqslant n \\ u/m=v/n \\ (v,n)\leqslant T}}1.\end{eqnarray}$$
Now, for fixed
 $v$
, there are unique coprime positive integers
 $a$
and
 $b$
such that
 $v/n=a/b$
. The denominator
 $b$
is a divisor of
 $n$
, and
 $a\leqslant b$
. Further, with such an
 $a$
and
 $b$
fixed, the number of solutions to
 $$\begin{eqnarray}\frac{a}{b}=\frac{u}{m},\quad 1\leqslant u,m\leqslant n\end{eqnarray}$$
is exactly
 $n/b$
.
We now consider how many times a particular divisor
 $b$
of
 $n$
can occur, as
 $v$
ranges up to
 $n$
. Indeed, since
 $b=n/(v,n)$
, we see that
 $b$
occurs exactly the number of times that
 $(v,n)=n/b$
. If
 $n/b\leqslant T$
, then this is at most
 $b$
times; if
 $n/b>T$
, then the GCD condition
 $(v,n)\leqslant T$
precludes this from ever occurring.
Therefore
 $$\begin{eqnarray}\mathop{\sum }_{m\leqslant n}A(m,n)\leqslant \mathop{\sum }_{\substack{ b|n \\ n/b\leqslant T}}b\frac{n}{b}=\mathop{\sum }_{\substack{ c|n \\ c\leqslant T}}n.\end{eqnarray}$$
It follows that
 $$\begin{eqnarray}\mathop{\sum }_{n\leqslant X}\mathop{\sum }_{m\leqslant n}\frac{A(m,n)}{n}\leqslant \mathop{\sum }_{n\leqslant X}\mathop{\sum }_{\substack{ c\mid n \\ c\leqslant T}}1\leqslant \mathop{\sum }_{c\leqslant T}\frac{X}{c}\ll X\log T\end{eqnarray}$$
as claimed.◻
4 The variance estimate
Like so much work on metric properties, we aim to show a result for almost all
 $\unicode[STIX]{x1D6FC}$
by bounding the variance (
 $\unicode[STIX]{x1D6FC}$
considered as a uniform random variable on
 $\mathbb{T}$
). Rather than working directly with
 $F$
, however, the objective of this section is instead to establish the following bound on the variance of
 $F^{\ast }$
.
Proposition 4.1. The variance of
 $F^{\ast }$
satisfies
 $$\begin{eqnarray}\text{Var}(F^{\ast })=\int _{\mathbb{ T}}|F^{\ast }(\unicode[STIX]{x1D6FC})-\mathbb{E}F^{\ast }|^{2}\,d\unicode[STIX]{x1D6FC}\ll \frac{\sqrt{\log T}}{T}(\widetilde{E}\unicode[STIX]{x1D6FF}^{-1})^{1/2}+\widetilde{E}T\log T.\end{eqnarray}$$
Proof. For brevity, we introduce the temporary notation
 $$\begin{eqnarray}\unicode[STIX]{x1D70C}=\frac{\sqrt{\log T}}{T}(\widetilde{E}\unicode[STIX]{x1D6FF}^{-1})^{1/2}.\end{eqnarray}$$
We will eventually choose
 $T$
in such a way that
 $N^{-1}\leqslant \unicode[STIX]{x1D70C}\leqslant 1$
.
We begin by replacing
 $\mathbb{E}F^{\ast }$
with a simpler expression. Indeed, by Proposition 2.3 and the fact that
 $F^{\ast }(\unicode[STIX]{x1D6FC})\leqslant F(\unicode[STIX]{x1D6FC})$
, we have
 $$\begin{eqnarray}\mathbb{E}F^{\ast }=\mathbb{E}F+O(\unicode[STIX]{x1D70C}).\end{eqnarray}$$
Since
 $$\begin{eqnarray}\mathbb{E}F=\int _{\mathbb{T}}F(\unicode[STIX]{x1D6FC})\,d\unicode[STIX]{x1D6FC}=\frac{1}{N}\mathop{\sum }_{n\in \mathbb{Z}\backslash \{0\}}r(n)\frac{2s}{N}=2s(1-1/N),\end{eqnarray}$$
we must have
 $$\begin{eqnarray}\mathbb{E}F^{\ast }=2s+O(\unicode[STIX]{x1D70C}).\end{eqnarray}$$
A short calculation then tells us that
 $$\begin{eqnarray}\text{Var}(F^{\ast })=\int _{\mathbb{ T}}(F^{\ast }(\unicode[STIX]{x1D6FC})-2s)^{2}\,d\unicode[STIX]{x1D6FC}+O(\unicode[STIX]{x1D70C}^{2}).\end{eqnarray}$$
Expanding the main term gives
 $$\begin{eqnarray}\frac{4}{N^{2}}\mathop{\sum }_{1\leqslant n,m\leqslant X}r(n)r(m)\unicode[STIX]{x1D707}({\mathcal{E}}_{n}\cap {\mathcal{E}}_{m})-\frac{8s}{N}\mathop{\sum }_{1\leqslant n\leqslant X}r(n)\unicode[STIX]{x1D707}({\mathcal{E}}_{n})+4s^{2}.\end{eqnarray}$$
By (2.1) and Lemma 3.1 this is at most
 $$\begin{eqnarray}\displaystyle & & \displaystyle \frac{16s^{2}}{N^{4}}\mathop{\sum }_{n,m\leqslant X}r(n)r(m)+\frac{16s}{N^{3}}\mathop{\sum }_{m\leqslant n\leqslant X}r(n)r(m)\frac{A(n,m)}{n}\nonumber\\ \displaystyle & & \displaystyle \qquad -\frac{16s^{2}}{N^{2}}\mathop{\sum }_{n\leqslant X}r(n)\frac{\unicode[STIX]{x1D6F7}(n)}{n}+4s^{2}.\end{eqnarray}$$
Now, as
 $$\begin{eqnarray}\mathop{\sum }_{1\leqslant n\leqslant X}r(n)=\frac{N^{2}}{2}+O(N),\end{eqnarray}$$
we have
 $$\begin{eqnarray}\frac{16s^{2}}{N^{4}}\mathop{\sum }_{1\leqslant n,m\leqslant X}r(n)r(m)+4s^{2}=\frac{16s^{2}}{N^{2}}\mathop{\sum }_{1\leqslant n\leqslant X}r(n)+O(N^{-1}).\end{eqnarray}$$
Substituting this into (4.2) and bounding
 $1/n$
by
 $1/\sqrt{mn}$
when
 $m\leqslant n$
yields
 $$\begin{eqnarray}\text{Var}(F^{\ast })\ll S_{1}+S_{2}+N^{-1}+\unicode[STIX]{x1D70C}^{2},\end{eqnarray}$$
where
 $$\begin{eqnarray}S_{1}=\frac{1}{N^{2}}\mathop{\sum }_{n\leqslant X}r(n)\biggl(1-\frac{\unicode[STIX]{x1D6F7}(n)}{n}\biggr)\end{eqnarray}$$
and
 $$\begin{eqnarray}S_{2}=N^{-3}\mathop{\sum }_{m,n\leqslant X}r(m)r(n)\frac{A(m,n)}{\sqrt{mn}}.\end{eqnarray}$$
Observe that the quantity
 $S_{1}$
was studied in the proof of Proposition 2.3, and in view of that calculation, we have
 $S_{1}\ll \unicode[STIX]{x1D70C}$
.
For
 $S_{2}$
, a more sensitive treatment of
 $A(m,n)$
than Lemma 3.2 will be required. We recall that
 $A(m,n)$
counts solutions
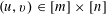 $(u,v)\in [m]\times [n]$
to
 $$\begin{eqnarray}un=vm,\quad (u,m),(v,n)\leqslant T.\end{eqnarray}$$
The solutions are
 $$\begin{eqnarray}u=\unicode[STIX]{x1D706}\frac{m}{(m,n)},\qquad v=\unicode[STIX]{x1D706}\frac{n}{(m,n)}\end{eqnarray}$$
for
 $1\leqslant \unicode[STIX]{x1D706}\leqslant (m,n)$
, subject to the further restriction given by
 $T$
. As
 $$\begin{eqnarray}(u,m)=\frac{m}{(m,n)}(\unicode[STIX]{x1D706},m,n),\qquad (v,n)=\frac{n}{(m,n)}(\unicode[STIX]{x1D706},m,n),\end{eqnarray}$$
we have
 $$\begin{eqnarray}A(m,n)\leqslant \mathop{\sum }_{\substack{ \unicode[STIX]{x1D706}\leqslant (m,n): \\ (\unicode[STIX]{x1D706},m,n)\leqslant {\textstyle \frac{(m,n)}{\max \{m,n\}}}T}}1.\end{eqnarray}$$
From this, we extract two key pieces of information: that
 $$\begin{eqnarray}A(m,n)\leqslant (m,n),\end{eqnarray}$$
and that if
 $A(m,n)\neq 0$
then
 $$\begin{eqnarray}\frac{m}{(m,n)},\frac{n}{(m,n)}\leqslant T.\end{eqnarray}$$
Just using (4.4) along with the GCD sum bounds of [Reference Bondarenko and Seip4], which entirely removes the influence of
 $T$
, we recover an analogous estimate to [Reference Aistleitner, Larcher and Lewko2, Lemma 3] (see Remark 4.2 below). However, if we also use (4.5) and Cauchy–Schwarz, we obtain
 $$\begin{eqnarray}\displaystyle S_{2} & {\leqslant} & \displaystyle \frac{1}{N^{3}}\mathop{\sum }_{\substack{ m,n\leqslant X \\ {\textstyle \frac{m}{(m,n)}},{\textstyle \frac{n}{(m,n)}}\leqslant T}}r(m)r(n)\frac{(m,n)}{\sqrt{mn}}\leqslant \frac{1}{N^{3}}\mathop{\sum }_{g\leqslant X}\biggl(\mathop{\sum }_{y\leqslant T}\frac{r(gy)}{\sqrt{y}}\biggr)^{2}\nonumber\\ \displaystyle & {\leqslant} & \displaystyle \frac{1}{N^{3}}\mathop{\sum }_{g\leqslant X}\biggl(\mathop{\sum }_{y\leqslant T}\frac{1}{y}\biggr)\cdot \mathop{\sum }_{y\leqslant T}r(gy)^{2}\ll \frac{\log T}{N^{3}}\mathop{\sum }_{n\in \mathbb{N}}r(n)^{2}\mathop{\sum }_{\substack{ y\mid n \\ y\leqslant T}}1\ll \widetilde{E}T\log T.\nonumber\end{eqnarray}$$
In view of (4.3), this completes the proof of the proposition.◻
Remark 4.2. There is an alternative approach to bounding
 $S_{2}$
, based on the general theory of GCD sums of the form
 $$\begin{eqnarray}\mathop{\sum }_{k,\ell =1}^{M}\frac{(n_{k},n_{\ell })^{2\unicode[STIX]{x1D6FC}}}{(n_{k}n_{\ell })^{\unicode[STIX]{x1D6FC}}}.\end{eqnarray}$$
At
 $\unicode[STIX]{x1D6FC}=1/2$
we have already mentioned the essentially optimal bounds by Bondarenko and Seip [Reference Bondarenko and Seip4, Reference Bondarenko and Seip5], which were employed in [Reference Aistleitner, Larcher and Lewko2, Lemma 3]. We can pass to
 $\unicode[STIX]{x1D6FC}=1$
by Rankin’s trick, using (4.5); at this exponent there is Gál’s [Reference Gál6] prize-winning upper bound
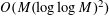 $O(M(\log \log M)^{2})$
. By [Reference Aistleitner, Berkes and Seip1, Lemma 4] and the discussion immediately following it, one can attach real weights to this at little cost, the idea being to apply this with weights
 $r(n)$
. The sharpest version is a recent breakthrough by Lewko and Radziwiłł [Reference Lewko and Radziwiłł9, Theorem 2], by which we obtain the
 $L^{2}$
estimate
 $$\begin{eqnarray}\mathop{\sum }_{k,\ell =1}^{M}c_{k}c_{\ell }\frac{(n_{k},n_{\ell })^{2}}{n_{k}n_{\ell }}\ll (\log \log M)^{2}\mathop{\sum }_{k}c_{k}^{2}.\end{eqnarray}$$
There are at most
 $M=N^{2}$
values of
 $n$
for which
 $r(n)\neq 0$
, so this approach ultimately yields
 $$\begin{eqnarray}\text{Var}(F^{\ast })\ll \frac{\sqrt{\log T}}{T}(\widetilde{E}\unicode[STIX]{x1D6FF}^{-1})^{1/2}+T\widetilde{E}(\log \log N)^{2}.\end{eqnarray}$$
As it happens, for our eventual choice of
 $T$
there is little quantitative difference between the two approaches, and certainly either is sufficient for Theorem 1.4.
5 Improved estimates for the random case
In this section, we consider the setting of Theorem 1.5, and revisit the variance estimate from the preceding section. By a standard application of large deviation inequalities, we can assume that the representation function
 $r(n)$
is essentially constant. This leads to an improvement.
We begin with some easy bounds on
 $N$
and
 $r(n)$
.
Lemma 5.1. Let
 $C>2$
, and let
 $$\begin{eqnarray}\unicode[STIX]{x1D713}(x)=\left\{\begin{array}{@{}ll@{}}1\quad & \text{if }x\leqslant 20,\\ (\log x)^{-1}(\log \log x)^{-C}\quad & \text{if }x>20.\end{array}\right.\end{eqnarray}$$
Let
 ${\mathcal{A}}$
be as defined in the statement of Theorem 1.5, i.e. the random set of natural numbers defined by choosing
 $x\in {\mathcal{A}}$
independently at random with probability
 $\unicode[STIX]{x1D713}(x)$
. Let
 $\unicode[STIX]{x1D700}>0$
, and fix an integer
 $X$
large enough in terms of
 $\unicode[STIX]{x1D700}$
. Consider the following properties.
(1)
 $N$
satisfies $$\begin{eqnarray}1-\unicode[STIX]{x1D700}\leqslant \frac{N}{X(\log X)^{-1}(\log \log X)^{-C}}\leqslant 1+\unicode[STIX]{x1D700}.\end{eqnarray}$$
(2) For all positive integers
$n\leqslant X$
, we have $$\begin{eqnarray}r(n)\leqslant (1+\unicode[STIX]{x1D700})X(\log X)^{-2}(\log \log X)^{-2C}.\end{eqnarray}$$


Then there is a constant
 $c_{\unicode[STIX]{x1D700}}>0$
such that property (1) holds with probability at least
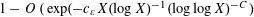 $1-O(\exp (-c_{\unicode[STIX]{x1D700}}X(\log X)^{-1}(\log \log X)^{-C})$
and property (2) holds with probability at least
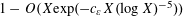 $1-O(X\exp (-c_{\unicode[STIX]{x1D700}}X(\log X)^{-5}))$
.
This is a quantitative version of a lemma that appears in Bourgain’s appendix to [Reference Aistleitner, Larcher and Lewko2], and is no doubt obvious to experts. Yet to keep the paper as self-contained as possible, we feel it is appropriate to provide the full details, particularly for part (2).
Proof. For each
 $x\in \mathbb{N}$
, let
 $\unicode[STIX]{x1D709}_{x}$
denote the Bernoulli random variable such that
 $$\begin{eqnarray}\mathbb{P}(\unicode[STIX]{x1D709}_{x}=1)=\unicode[STIX]{x1D713}(x).\end{eqnarray}$$
Then
 $N=\sum _{x\leqslant X}\unicode[STIX]{x1D709}_{x}$
is a random variable with expectation
 $\sum _{x\leqslant X}\unicode[STIX]{x1D713}(x)$
, which is asymptotic to
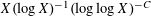 $X(\log X)^{-1}(\log \log X)^{-C}$
. Since the
 $\unicode[STIX]{x1D709}_{x}$
are independent by assumption, one may settle part (1) immediately by applying the Chernoff bound, for instance by applying [Reference Alon and Spencer3, Corollary A.1.14].
For part (2), we first consider each
 $n\leqslant X-1$
separately. Indeed, for
 $x$
in the range
 $1\leqslant x\leqslant X-n$
, let
 $\unicode[STIX]{x1D714}_{x,n}$
denote the random variable
 $\unicode[STIX]{x1D714}_{x,n}=\unicode[STIX]{x1D709}_{x}\unicode[STIX]{x1D709}_{n+x}$
. We have
 $$\begin{eqnarray}r(n)=\mathop{\sum }_{x\leqslant X-n}\unicode[STIX]{x1D714}_{x,n},\end{eqnarray}$$
which is a random variable with expectation
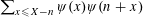 $\sum _{x\leqslant X-n}\unicode[STIX]{x1D713}(x)\unicode[STIX]{x1D713}(n+x)$
. Suppose first that
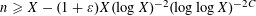 $n\geqslant X-(1+\unicode[STIX]{x1D700})X(\log X)^{-2}(\log \log X)^{-2C}$
. Then by the trivial triangle inequality bound we have
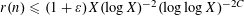 $r(n)\leqslant (1+\unicode[STIX]{x1D700})X(\log X)^{-2}(\log \log X)^{-2C}$
.
It remains to consider the case
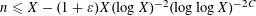 $n\leqslant X-(1+\unicode[STIX]{x1D700})X(\log X)^{-2}(\log \log X)^{-2C}$
. We wish to apply concentration of measure results for sums of independent random variables, and the family of random variables
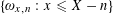 $\{\unicode[STIX]{x1D714}_{x,n}:x\leqslant X-n\}$
is very close to being independent. Methods of splitting this family into groups of genuinely independent random variables are alluded to in the discussion in the appendix of [Reference Aistleitner, Larcher and Lewko2]. Here, we describe an extremely coarse decomposition that nonetheless is strong enough for our purposes.
Split
 $[X-n]$
into two sets,
 ${\mathcal{S}}_{0}$
and
 ${\mathcal{S}}_{1}$
, constructed as follows. If
 $n\leqslant X/3$
, let
 $x\in {\mathcal{S}}_{j}$
if
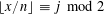 $\lfloor x/n\rfloor \equiv j\,\,\text{mod}\,\,2$
. If
 $n>X/3$
, instead let
 $$\begin{eqnarray}{\mathcal{S}}_{0}=\biggl\{x\in \mathbb{N}:x\leqslant \frac{X-n}{2}\biggr\},\qquad {\mathcal{S}}_{1}=\biggl\{x\in \mathbb{N}:\frac{X-n}{2}<x\leqslant X-n\biggr\}.\end{eqnarray}$$
For each
 $j\in \{0,1\}$
the family
 $\{\unicode[STIX]{x1D714}_{x,n}:x\in {\mathcal{S}}_{j}\}$
is independent, as no two indices differ by
 $n$
. Applying the union bound and then [Reference Alon and Spencer3, Corollary A.1.14] once more, we have
 $$\begin{eqnarray}\displaystyle & & \displaystyle \mathbb{P}\biggl(r(n)\geqslant (1+\unicode[STIX]{x1D700})\mathop{\sum }_{x\leqslant X-n}\unicode[STIX]{x1D713}(x)\unicode[STIX]{x1D713}(n+x)\biggr)\nonumber\\ \displaystyle & & \displaystyle \quad \ll \mathbb{P}\biggl(\mathop{\sum }_{x\in {\mathcal{S}}_{0}}\unicode[STIX]{x1D714}_{x,n}\geqslant (1+\unicode[STIX]{x1D700})\mathop{\sum }_{x\in {\mathcal{S}}_{0}}\unicode[STIX]{x1D713}(x)\unicode[STIX]{x1D713}(n+x)\biggr)\nonumber\\ \displaystyle & & \displaystyle \qquad +\,\mathbb{P}\biggl(\mathop{\sum }_{x\in {\mathcal{S}}_{1}}\unicode[STIX]{x1D714}_{x,n}\geqslant (1+\unicode[STIX]{x1D700})\mathop{\sum }_{x\in {\mathcal{S}}_{1}}\unicode[STIX]{x1D713}(x)\unicode[STIX]{x1D713}(n+x)\biggr)\nonumber\\ \displaystyle & & \displaystyle \quad \ll \exp \biggl(-c_{\unicode[STIX]{x1D700}}\mathop{\sum }_{x\in {\mathcal{S}}_{0}}\unicode[STIX]{x1D713}(x)\unicode[STIX]{x1D713}(n+x)\biggr)+\exp \biggl(-c_{\unicode[STIX]{x1D700}}\mathop{\sum }_{x\in {\mathcal{S}}_{1}}\unicode[STIX]{x1D713}(x)\unicode[STIX]{x1D713}(n+x)\biggr).\qquad\end{eqnarray}$$
It remains to estimate these final quantities. Note that by construction we have
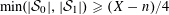 $\min (|{\mathcal{S}}_{0}|,|{\mathcal{S}}_{1}|)\geqslant (X-n)/4$
. So, since
 $\unicode[STIX]{x1D713}(x)$
is weakly decreasing, we deduce from (5.1) that
 $$\begin{eqnarray}\displaystyle \mathbb{P}\biggl(r(n)\geqslant (1+\unicode[STIX]{x1D700})\mathop{\sum }_{x\leqslant X-n}\unicode[STIX]{x1D713}(x)\unicode[STIX]{x1D713}(n+x)\biggr) & \ll & \displaystyle \exp \biggl(-c_{\unicode[STIX]{x1D700}}\mathop{\sum }_{X-{\textstyle \frac{X-n}{4}}<x\leqslant X}\unicode[STIX]{x1D713}(x)^{2}\biggr)\nonumber\\ \displaystyle & \ll & \displaystyle \operatorname{exp}(-c_{\unicode[STIX]{x1D700}}X(\log X)^{-5})\nonumber\end{eqnarray}$$
by a simple calculation, reducing the quantity
 $c_{\unicode[STIX]{x1D700}}$
as necessary.
By a similar monotonicity principle,
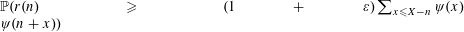 $\mathbb{P}(r(n)\geqslant (1+\unicode[STIX]{x1D700})\sum _{x\leqslant X-n}\unicode[STIX]{x1D713}(x)\unicode[STIX]{x1D713}(n+x))$
is at least
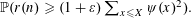 $\mathbb{P}(r(n)\geqslant (1+\unicode[STIX]{x1D700})\sum _{x\leqslant X}\unicode[STIX]{x1D713}(x)^{2}).$
Since
 $$\begin{eqnarray}\mathop{\sum }_{x\leqslant X}\unicode[STIX]{x1D713}(x)^{2}\sim X(\log X)^{-2}(\log \log X)^{-2C},\end{eqnarray}$$
and
 $X$
large enough in terms of
 $\unicode[STIX]{x1D700}$
, we conclude that
 $$\begin{eqnarray}r(n)\leqslant (1+\unicode[STIX]{x1D700})X(\log X)^{-2}(\log \log X)^{-2C}\end{eqnarray}$$
with probability greater than
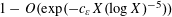 $1-O(\exp (-c_{\unicode[STIX]{x1D700}}X(\log X)^{-5}))$
.
All these calculations were done for a single
 $n$
. But applying a crude union bound over all
 $n\leqslant X-1$
, and noting that
 $r(X)=0$
, part (2) is proved.◻
Corollary 5.2. With probability
 $1$
there exists some
 $X_{0}$
such that properties (1) and (2) hold for all
 $X\geqslant X_{0}$
.
Proof. The sums
 $$\begin{eqnarray}\mathop{\sum }_{X\geqslant 1}\exp (-c_{\unicode[STIX]{x1D700}}X(\log X)^{-1}(\log \log X)^{-C})\end{eqnarray}$$
and
 $$\begin{eqnarray}\mathop{\sum }_{X\geqslant 1}X\exp (-c_{\unicode[STIX]{x1D700}}X(\log X)^{-5})\end{eqnarray}$$
are both convergent. So by the first Borel–Cantelli lemma, the corollary follows.◻
For the rest of this paper, whenever we consider the random case we restrict to the probability
 $1$
event from Corollary 5.2.
To continue this section, we use the above work to get an improved version of Proposition 4.1, in the random case. First, we improve on Proposition 2.3.
Proposition 5.3. In the setting of Theorem 1.5, we have
 $$\begin{eqnarray}\int _{\mathbb{T}}|F(\unicode[STIX]{x1D6FC})-F^{\ast }(\unicode[STIX]{x1D6FC})|\,\,d\unicode[STIX]{x1D6FC}\ll T^{-1}.\end{eqnarray}$$
Proof. Following Proposition 2.3, we establish that
 $$\begin{eqnarray}\int _{\mathbb{T}}|F(\unicode[STIX]{x1D6FC})-F^{\ast }(\unicode[STIX]{x1D6FC})|\,\,d\unicode[STIX]{x1D6FC}=2\mathop{\sum }_{n\leqslant X}\frac{r(n)}{N}\frac{2s}{N}\biggl(1-\frac{\unicode[STIX]{x1D6F7}(n)}{n}\biggr)\ll X^{-1}\mathop{\sum }_{n\leqslant X}\biggl(1-\frac{\unicode[STIX]{x1D6F7}(n)}{n}\biggr).\end{eqnarray}$$
The final inequality follows from Corollary 5.2. Then we apply Lemma 2.1, and the proposition follows.◻
We now go on to improve Proposition 4.1.
Proposition 5.4. Let
 ${\mathcal{A}}$
be as in Theorem 1.5. Then the variance of
 $F^{\ast }$
satisfies
 $$\begin{eqnarray}\text{Var}(F^{\ast })\ll T^{-1}+(\log X)^{-1}(\log \log X)^{-C}\log T.\end{eqnarray}$$
Proof. We will eventually choose
 $T$
in such a way that
 $N^{-1}\leqslant T^{-1}\leqslant 1$
. Following the proof of Proposition 4.1, we thus derive
 $$\begin{eqnarray}\text{Var}(F^{\ast })\ll S_{1}+S_{3}+N^{-1}+T^{-2},\end{eqnarray}$$
where
 $$\begin{eqnarray}S_{3}=N^{-3}\mathop{\sum }_{m\leqslant n\leqslant X}r(n)r(m)\frac{A(m,n)}{n}.\end{eqnarray}$$
Observe that
 $S_{1}$
is the same expression considered in Proposition 5.3, and so
 $S_{1}\ll T^{-1}$
. It remains to bound
 $S_{3}$
, for which we already have all the necessary lemmas in place. Indeed, by Corollary 5.2, and by Lemma 3.2, we have
 $$\begin{eqnarray}\displaystyle S_{3} & \ll & \displaystyle X^{-1}(\log X)^{-1}(\log \log X)^{-C}\mathop{\sum }_{m\leqslant n\leqslant X}\frac{A(m,n)}{n}\nonumber\\ \displaystyle & \ll & \displaystyle (\log X)^{-1}(\log \log X)^{-C}\log T.\nonumber\end{eqnarray}$$
Combining everything together yields the proposition.◻
6 Sandwiching, concentration, and Borel–Cantelli
Here we conclude the proofs of Theorems 1.4 and 1.5. We begin by proving the following assertion, which we will see implies that
 ${\mathcal{A}}$
is metric Poissonian.
Proposition 6.1. Let
 $\unicode[STIX]{x1D700},s>0$
. Let
 ${\mathcal{A}}$
satisfy either the conditions of Theorem 1.4 or 1.5. Then there is a full measure set
 $\unicode[STIX]{x1D6FA}_{\unicode[STIX]{x1D700},s}$
such that if
 $\unicode[STIX]{x1D6FC}\in \unicode[STIX]{x1D6FA}_{\unicode[STIX]{x1D700},s}$
then there exists
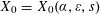 $X_{0}=X_{0}(\unicode[STIX]{x1D6FC},\unicode[STIX]{x1D700},s)$
such that if
 $X\geqslant X_{0}$
then
 $|F(\unicode[STIX]{x1D6FC})-2s|\leqslant \unicode[STIX]{x1D700}$
.
First, let us describe the argument in the deterministic setting of Theorem 1.4.
Proof. Define the sequence
 $N_{j}=\lfloor 2^{j^{1-\unicode[STIX]{x1D702}}}\rfloor$
, where
 $\unicode[STIX]{x1D702}>0$
is small in terms of
 $\unicode[STIX]{x1D709}$
. Note that
 $N_{j+1}/N_{j}\rightarrow 1$
. For
 $j\in \mathbb{N}$
, define
 $X_{j}\in \mathbb{N}$
to be minimal such that
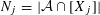 $N_{j}=|{\mathcal{A}}\cap [X_{j}]|$
. Let
 $X$
be large in terms of
 $\unicode[STIX]{x1D700}$
and
 $s$
, and suppose
 $X_{j}\leqslant X<X_{j+1}$
. We begin with the inequalities noted in [Reference Aistleitner, Larcher and Lewko2], namely
 $$\begin{eqnarray}N_{j}F\biggl(\unicode[STIX]{x1D6FC},s\frac{N_{j}}{N_{j+1}},X_{j}\biggr)\leqslant NF(\unicode[STIX]{x1D6FC},s,X)\leqslant N_{j+1}F\biggl(\unicode[STIX]{x1D6FC},s\frac{N_{j+1}}{N_{j}},X_{j+1}\biggr),\end{eqnarray}$$
which follow immediately from the definitions. Note that
 $$\begin{eqnarray}s\frac{N_{j}}{N_{j+1}},s\frac{N_{j+1}}{N_{j}}\asymp 1,\qquad s\frac{N_{j}}{N_{j+1}},s\frac{N_{j+1}}{N_{j}}\rightarrow s.\end{eqnarray}$$
Motivated by Proposition 4.1, we choose
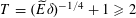 $T=(\widetilde{E}\unicode[STIX]{x1D6FF})^{-1/4}+1\geqslant 2$
. By Proposition 2.3, we thus have
 $$\begin{eqnarray}\int _{\mathbb{T}}|F(\unicode[STIX]{x1D6FC})-F^{\ast }(\unicode[STIX]{x1D6FC})|\,d\unicode[STIX]{x1D6FC}\ll (\log T)^{1/2}\widetilde{E}^{3/4}\unicode[STIX]{x1D6FF}^{-1/4}.\end{eqnarray}$$
At this stage we invoke our hypotheses (1.1): with
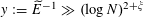 $y:=\widetilde{E}^{-1}\gg (\log N)^{2+\unicode[STIX]{x1D709}}$
, we have
 $$\begin{eqnarray}(\log T)^{1/2}\widetilde{E}^{3/4}\ll \frac{\sqrt{\log y}+\sqrt{\log \log N}}{y^{3/4}}.\end{eqnarray}$$
The right-hand side is decreasing in
 $y$
for
 $y\geqslant 100$
, so by our initial assumptions (1.1) we obtain
 $$\begin{eqnarray}\int _{\mathbb{T}}|F(\unicode[STIX]{x1D6FC})-F^{\ast }(\unicode[STIX]{x1D6FC})|\,d\unicode[STIX]{x1D6FC}\ll \frac{1}{(\log N)^{1+\unicode[STIX]{x1D709}/5}}.\end{eqnarray}$$
The same calculation also shows that
 $N^{-1}\leqslant \unicode[STIX]{x1D70C}\leqslant 1$
, which was assumed in the proof of Proposition 4.1. Applying Proposition 4.1, therefore, we have
 $$\begin{eqnarray}\text{Var}(F^{\ast })\ll \widetilde{E}^{3/4}\unicode[STIX]{x1D6FF}^{-1/4}\log T\ll \frac{1}{(\log N)^{1+\unicode[STIX]{x1D709}/5}}.\end{eqnarray}$$
The
 $L^{1}$
estimate (6.1) implies that if
 $s\asymp 1$
and
 $X$
is large then
 $$\begin{eqnarray}|F(\unicode[STIX]{x1D6FC},s,X)-F^{\ast }(\unicode[STIX]{x1D6FC},s,X)|\leqslant \unicode[STIX]{x1D700}/4\quad (\unicode[STIX]{x1D6FC}\notin E_{X,s}),\end{eqnarray}$$
for some exceptional set
 $E_{X,s}$
with
 $$\begin{eqnarray}\unicode[STIX]{x1D707}(E_{X,s})\,\ll _{\unicode[STIX]{x1D700}}\,\frac{1}{(\log N)^{1+\unicode[STIX]{x1D709}/5}}.\end{eqnarray}$$
In particular
 $$\begin{eqnarray}\mathop{\sum }_{j=1}^{\infty }\unicode[STIX]{x1D707}(E_{X_{j},s(N_{j}/N_{j+1})})\ll \mathop{\sum }_{j=1}^{\infty }j^{(\unicode[STIX]{x1D702}-1)(1+\unicode[STIX]{x1D709}/5)}<\infty ,\end{eqnarray}$$
provided that
 $\unicode[STIX]{x1D702}$
is chosen small enough depending on
 $\unicode[STIX]{x1D709}$
. Now the Borel–Cantelli lemma tells us that for almost all
 $\unicode[STIX]{x1D6FC}\in \mathbb{T}$
, we have
 $$\begin{eqnarray}\biggl|F\biggl(\unicode[STIX]{x1D6FC},s\frac{N_{j}}{N_{j+1}},X_{j}\biggr)-F^{\ast }\biggl(\unicode[STIX]{x1D6FC},s\frac{N_{j}}{N_{j+1}},X_{j}\biggr)\biggr|\leqslant \unicode[STIX]{x1D700}/4\quad (j\geqslant j_{1}(\unicode[STIX]{x1D6FC},\unicode[STIX]{x1D700})),\end{eqnarray}$$
and similarly
 $$\begin{eqnarray}\biggl|F\biggl(\unicode[STIX]{x1D6FC},s\frac{N_{j+1}}{N_{j}},X_{j+1}\biggr)-F^{\ast }\biggl(\unicode[STIX]{x1D6FC},s\frac{N_{j+1}}{N_{j}},X_{j+1}\biggr)\biggr|\leqslant \unicode[STIX]{x1D700}/4\quad (j\geqslant j_{2}(\unicode[STIX]{x1D6FC},\unicode[STIX]{x1D700})).\end{eqnarray}$$
Recalling (4.1), the variance estimate (6.2) on
 $F^{\ast }$
combined with Chebyshev’s inequality implies that
 $$\begin{eqnarray}\unicode[STIX]{x1D707}\biggl(\biggl\{\unicode[STIX]{x1D6FC}\in \mathbb{T}:\biggl|F^{\ast }\biggl(\unicode[STIX]{x1D6FC},s\frac{N_{j}}{N_{j+1}},X_{j}\biggr)-2s\frac{N_{j}}{N_{j+1}}\biggr|>\unicode[STIX]{x1D700}/4\biggr\}\biggr)\ll _{\unicode[STIX]{x1D700}}(\log N_{j})^{-1-\unicode[STIX]{x1D709}/5}.\end{eqnarray}$$
We again apply the Borel–Cantelli lemma, and find that for almost all
 $\unicode[STIX]{x1D6FC}\in \mathbb{T}$
we have
 $$\begin{eqnarray}\biggl|F^{\ast }\biggl(\unicode[STIX]{x1D6FC},s\frac{N_{j}}{N_{j+1}},X_{j}\biggr)-2s\frac{N_{j}}{N_{j+1}}\biggr|\leqslant \unicode[STIX]{x1D700}/4\quad (j\geqslant j_{3}(\unicode[STIX]{x1D6FC},\unicode[STIX]{x1D700})),\end{eqnarray}$$
and similarly
 $$\begin{eqnarray}\biggl|F^{\ast }\biggl(\unicode[STIX]{x1D6FC},s\frac{N_{j+1}}{N_{j}},X_{j+1}\biggr)-2s\frac{N_{j+1}}{N_{j}}\biggr|\leqslant \unicode[STIX]{x1D700}/4\quad (j\geqslant j_{4}(\unicode[STIX]{x1D6FC},\unicode[STIX]{x1D700})).\end{eqnarray}$$
Now the triangle inequality gives, for almost all
 $\unicode[STIX]{x1D6FC}\in \mathbb{T}$
and all
 $j\geqslant j_{5}(\unicode[STIX]{x1D6FC},\unicode[STIX]{x1D700})$
,
 $$\begin{eqnarray}F\biggl(\unicode[STIX]{x1D6FC},s\frac{N_{j}}{N_{j+1}},X_{j}\biggr)\geqslant 2s\frac{N_{j}}{N_{j+1}}-\unicode[STIX]{x1D700}/2\end{eqnarray}$$
and
 $$\begin{eqnarray}F\biggl(\unicode[STIX]{x1D6FC},s\frac{N_{j+1}}{N_{j}},X_{j+1}\biggr)\leqslant 2s\frac{N_{j+1}}{N_{j}}+\unicode[STIX]{x1D700}/2.\end{eqnarray}$$
Since
 $$\begin{eqnarray}F\biggl(\unicode[STIX]{x1D6FC},s\frac{N_{j}}{N_{j+1}},X_{j}\biggr)\leqslant \frac{N}{N_{j}}F(\unicode[STIX]{x1D6FC},s,X)\end{eqnarray}$$
and
 $$\begin{eqnarray}F\biggl(\unicode[STIX]{x1D6FC},s\frac{N_{j+1}}{N_{j}},X_{j+1}\biggr)\geqslant \frac{N}{N_{j+1}}F(\unicode[STIX]{x1D6FC},s,X),\end{eqnarray}$$
we obtain
 $$\begin{eqnarray}\frac{N_{j}}{N}\biggl(2s\frac{N_{j}}{N_{j+1}}-\unicode[STIX]{x1D700}/2\biggr)\leqslant F(\unicode[STIX]{x1D6FC},s,X)\leqslant \frac{N_{j+1}}{N}\biggl(2s\frac{N_{j+1}}{N_{j}}+\unicode[STIX]{x1D700}/2\biggr).\end{eqnarray}$$
As
 $j$
is large and
 $N_{j+1}/N_{j}\rightarrow 1$
, we conclude as claimed that
 $$\begin{eqnarray}|F(\unicode[STIX]{x1D6FC},s,X)-2s|\leqslant \unicode[STIX]{x1D700}.\square\end{eqnarray}$$
Now let us prove Proposition 6.1 in the random setting of Theorem 1.5.
Proof. For some small
 $\unicode[STIX]{x1D702}>0$
, ultimately depending on
 $\unicode[STIX]{x1D700}$
and
 $s$
, define the sequence
 $X_{j}=\lfloor 2^{j\unicode[STIX]{x1D702}}\rfloor$
. Let
 $X$
be large in terms of
 $\unicode[STIX]{x1D700}$
and
 $s$
, and suppose that
 $X_{j}\leqslant X<X_{j+1}$
. We note again the sandwiching inequalities
 $$\begin{eqnarray}N_{j}F\biggl(\unicode[STIX]{x1D6FC},s\frac{N_{j}}{N_{j+1}},X_{j}\biggr)\leqslant NF(\unicode[STIX]{x1D6FC},s,X)\leqslant N_{j+1}F\biggl(\unicode[STIX]{x1D6FC},s\frac{N_{j+1}}{N_{j}},X_{j+1}\biggr).\end{eqnarray}$$
Observe that
 $$\begin{eqnarray}s\frac{N_{j}}{N_{j+1}},\qquad s\frac{N_{j+1}}{N_{j}}\asymp 1,\end{eqnarray}$$
and that for
 $j$
large enough in terms of
 $\unicode[STIX]{x1D702}$
we have
 $$\begin{eqnarray}\frac{N_{j}}{N_{j+1}}\geqslant 2^{-2\unicode[STIX]{x1D702}},\qquad \frac{N_{j+1}}{N_{j}}\leqslant 2^{2\unicode[STIX]{x1D702}}.\end{eqnarray}$$
Motivated by Proposition 5.4, we choose
 $$\begin{eqnarray}T=\log ^{2}X.\end{eqnarray}$$
By Proposition 5.3, we find that if
 $s\asymp 1$
and
 $X$
is large in terms of
 $\unicode[STIX]{x1D702}$
then
 $$\begin{eqnarray}|F(\unicode[STIX]{x1D6FC},s,X)-F^{\ast }(\unicode[STIX]{x1D6FC},s,X)|\leqslant \unicode[STIX]{x1D702}/4\quad (\unicode[STIX]{x1D6FC}\notin E_{X,s}),\end{eqnarray}$$
for some exceptional set
 $E_{X,s}$
with
 $$\begin{eqnarray}\unicode[STIX]{x1D707}(E_{X,s})\ll _{\unicode[STIX]{x1D702}}(\log X)^{-2}.\end{eqnarray}$$
This means that
 $$\begin{eqnarray}\mathop{\sum }_{j=1}^{\infty }\unicode[STIX]{x1D707}(E_{X_{j},s(N_{j}/N_{j+1})})\ll _{\unicode[STIX]{x1D702}}\mathop{\sum }_{j=1}^{\infty }j^{-2}<\infty .\end{eqnarray}$$
We apply the first Borel–Cantelli lemma as in the previous proof, concluding that for almost all
 $\unicode[STIX]{x1D6FC}\in \mathbb{T}$
we have
 $$\begin{eqnarray}\biggl|F\biggl(\unicode[STIX]{x1D6FC},s\frac{N_{j}}{N_{j+1}},X_{j}\biggr)-F^{\ast }\biggl(\unicode[STIX]{x1D6FC},s\frac{N_{j}}{N_{j+1}},X_{j}\biggr)\biggr|\leqslant \unicode[STIX]{x1D702}/4\quad (j\geqslant j_{1}(\unicode[STIX]{x1D6FC},\unicode[STIX]{x1D702})),\end{eqnarray}$$
and similarly
 $$\begin{eqnarray}\biggl|F\biggl(\unicode[STIX]{x1D6FC},s\frac{N_{j+1}}{N_{j}},X_{j+1}\biggr)-F^{\ast }\biggl(\unicode[STIX]{x1D6FC},s\frac{N_{j+1}}{N_{j}},X_{j+1}\biggr)\biggr|\leqslant \unicode[STIX]{x1D702}/4\quad (j\geqslant j_{2}(\unicode[STIX]{x1D6FC},\unicode[STIX]{x1D702})).\end{eqnarray}$$
By Proposition 5.4, the variance of
 $F^{\ast }$
is bounded above by a constant times
 $$\begin{eqnarray}(\log X)^{-2}+(\log X)^{-1}(\log \log X)^{-C+1}.\end{eqnarray}$$
We absorb the first term, and have by Chebyshev’s inequality that
 $$\begin{eqnarray}\displaystyle & & \displaystyle \unicode[STIX]{x1D707}\biggl(\biggl\{\unicode[STIX]{x1D6FC}\in \mathbb{T}:\biggl|F^{\ast }\biggl(\unicode[STIX]{x1D6FC},s\frac{N_{j}}{N_{j+1}},X_{j}\biggr)-2s\frac{N_{j}}{N_{j+1}}\biggr|>\unicode[STIX]{x1D702}/4\biggr\}\biggr)\nonumber\\ \displaystyle & & \displaystyle \qquad \ll _{\unicode[STIX]{x1D702}}\,(\log X_{j})^{-1}(\log \log X_{j})^{-C+1}.\nonumber\end{eqnarray}$$
We again apply the Borel–Cantelli lemma, using the fact that
 $$\begin{eqnarray}\mathop{\sum }_{j=1}^{\infty }(\log X_{j})^{-1}(\log \log X_{j})^{-C+1}\ll \hspace{2.22198pt}\unicode[STIX]{x1D702}^{-1}\mathop{\sum }_{j=1}^{\infty }j^{-1}(\log \unicode[STIX]{x1D702}j)^{-C+1}<\infty\end{eqnarray}$$
since
 $C>2$
. Thus we again find that for almost all
 $\unicode[STIX]{x1D6FC}\in \mathbb{T}$
we have
 $$\begin{eqnarray}\biggl|F^{\ast }\biggl(\unicode[STIX]{x1D6FC},s\frac{N_{j}}{N_{j+1}},X_{j}\biggr)-2s\frac{N_{j}}{N_{j+1}}\biggr|\leqslant \unicode[STIX]{x1D702}/4\quad (j\geqslant j_{3}(\unicode[STIX]{x1D6FC},\unicode[STIX]{x1D702})),\end{eqnarray}$$
and similarly
 $$\begin{eqnarray}\biggl|F^{\ast }\biggl(\unicode[STIX]{x1D6FC},s\frac{N_{j+1}}{N_{j}},X_{j+1}\biggr)-2s\frac{N_{j+1}}{N_{j}}\biggr|\leqslant \unicode[STIX]{x1D702}/4\quad (j\geqslant j_{4}(\unicode[STIX]{x1D6FC},\unicode[STIX]{x1D702})).\end{eqnarray}$$
The rest of the proof proceeds as in the deterministic case, reaching the expression
 $$\begin{eqnarray}\frac{N_{j}}{N}\biggl(2s\frac{N_{j}}{N_{j+1}}-\unicode[STIX]{x1D702}/2\biggr)\leqslant F(\unicode[STIX]{x1D6FC},s,X)\leqslant \frac{N_{j+1}}{N}\biggl(2s\frac{N_{j+1}}{N_{j}}+\unicode[STIX]{x1D702}/2\biggr).\end{eqnarray}$$
It is not true in this setting that
 $N_{j}/N_{j+1}\rightarrow 1$
, but by our earlier observations we may establish
 $$\begin{eqnarray}2^{-2\unicode[STIX]{x1D702}}\biggl(2s\cdot 2^{-2\unicode[STIX]{x1D702}}-\frac{\unicode[STIX]{x1D702}}{2}\biggr)\leqslant F(\unicode[STIX]{x1D6FC},s,X)\leqslant 2^{2\unicode[STIX]{x1D702}}\biggl(2s\cdot 2^{2\unicode[STIX]{x1D702}}+\frac{\unicode[STIX]{x1D702}}{2}\biggr),\end{eqnarray}$$
and therefore
 $$\begin{eqnarray}F(\unicode[STIX]{x1D6FC},s,X)=2s+O_{s}(\unicode[STIX]{x1D702}).\end{eqnarray}$$
Choosing
 $\unicode[STIX]{x1D702}$
small enough, this error is at most
 $\unicode[STIX]{x1D700}$
, thus proving the proposition.◻
To complete the proofs of Theorems 1.4 and 1.5, it remains to deduce the metric Poissonian property from Proposition 6.1. Apply Proposition 6.1 to all
 $s\in \mathbb{Q}_{{>}0}$
simultaneously, with an exceptional set of measure zero. Now let
 $s$
lie in a short interval
 $(s_{1},s_{2})$
, where
 $s_{1},s_{2}\in \mathbb{Q}$
, and the desired conclusion follows.
7 The random divergence theory
In this section, we prove Theorem 1.6. We keep this brief, as the proof is straightforward by combining §5 with the crux of [Reference Walker14].
By Khinchin’s theorem [Reference Harman7, Theorem 2.2], we know that there is a full measure set
 $\unicode[STIX]{x1D6FA}$
such that for all
 $\unicode[STIX]{x1D6FC}\in \unicode[STIX]{x1D6FA}$
there exist arbitrarily large positive integers
 $M$
such that
 $$\begin{eqnarray}\Vert M\unicode[STIX]{x1D6FC}\Vert <(M{\mathcal{L}}(M))^{-1},\end{eqnarray}$$
where
 $$\begin{eqnarray}{\mathcal{L}}(M)=\mathop{\prod }_{i\leqslant 5}\log _{i}(M).\end{eqnarray}$$
We remind the reader that here
 $\log _{0}(M)=M$
and
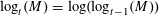 $\log _{t}(M)=\log (\log _{t-1}(M))$
for
 $t\in \mathbb{N}$
.
Now let
 ${\mathcal{A}}$
be as in Theorem 1.6. With negligible alteration, the proofs of Lemma 5.1 and Corollary 5.2 demonstrate that the associated quantities
 $\unicode[STIX]{x1D6FF}$
and
 $r(n)$
(for
 $1\leqslant n\leqslant X/3$
with
 $X$
large) have the expected order of magnitude. We conclude specifically that, with probability
 $1$
, there exists
 $X_{0}$
such that the following hold.
(1) If
$X\geqslant X_{0}$
then $$\begin{eqnarray}{\textstyle \frac{1}{2}}(\log X)^{-1}(\log \log X)^{-C}\leqslant \unicode[STIX]{x1D6FF}\leqslant 2(\log X)^{-1}(\log \log X)^{-C}.\end{eqnarray}$$
(2) If
$X\geqslant X_{0}$
and
$1\leqslant n\leqslant X/3$
then
$r(n)\geqslant \frac{1}{8}\unicode[STIX]{x1D6FF}N$
.


Now let
 $\unicode[STIX]{x1D6FC}$
be a member of
 $\unicode[STIX]{x1D6FA}$
, and suppose that there exists an
 $X_{0}$
satisfying (1) and (2) above. Let
 $s>0$
be constant, let
 $M$
be a large positive integer satisfying (7.1), and put
 $$\begin{eqnarray}N=\lfloor M\log _{3}(M)\rfloor ,\qquad K=\log M(\log \log M)^{C}\log _{4}M.\end{eqnarray}$$
Note that property (1) implies that
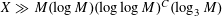 $X\gg M(\log M)(\log \log M)^{C}(\log _{3}M)$
, and in particular that
 $KM\leqslant X/3$
(for large enough
 $M$
).
By considering those
 $n$
of the form
 $n=kM$
(
 $1\leqslant k\leqslant K$
), and using property (2), we have that
 $$\begin{eqnarray}F(N)\geqslant N^{-1}\mathop{\sum }_{\substack{ n\leqslant X/3 \\ \Vert n\unicode[STIX]{x1D6FC}\Vert <s/N}}r(n)\gg \unicode[STIX]{x1D6FF}K\gg \log _{4}(M).\end{eqnarray}$$
In particular, with probability
 $1$
, for all
 $\unicode[STIX]{x1D6FC}\in \unicode[STIX]{x1D6FA}$
there exist arbitrarily large
 $N$
such that
 $F(N)>3s$
. Hence, with probability
 $1$
,
 ${\mathcal{A}}$
is not metric Poissonian.
Acknowledgements
This material is based upon work partially supported by the National Science Foundation under Grant No. DMS-1440140 while three of the authors were in residence at the Mathematical Sciences Research Institute in Berkeley, California, during the Spring 2017 semester. The second and third authors were MSRI Postdocs, and the fourth author a Program Associate, during the Analytic Number Theory Program. The first named author was visiting the Simons Institute for the Theory of Computing, Berkeley, for the Pseudorandomness Program 2017. All four authors are grateful for the working conditions provided by both institutions, at which this work was initiated. The second named author was also supported by EPSRC Programme Grant EP/J018260/1, and the fourth named author by EPSRC grant no. EP/M50659X/1. We thank Ben J. Green and Niclas Technau for helpful conversations. Finally, we thank an anonymous referee for a helpful and detailed report.
A. Appendix. The energy in the random setting
In this appendix, we include the computation of the additive energy in the random setting of Theorem 1.5. Recall (2.2). By Cauchy–Schwarz and Corollary 5.2, we have
 $\log N\asymp \log X$
and
 $$\begin{eqnarray}E\geqslant \mathop{\sum }_{n\leqslant X}r(n)^{2}\geqslant X^{-1}\biggl(\mathop{\sum }_{n\leqslant X}r(n)\biggr)^{2}\asymp \frac{N^{4}}{X}\asymp \frac{N^{3}}{(\log N)\cdot (\log \log N)^{C}}\end{eqnarray}$$
almost surely. Moreover, Corollary 5.2 also yields
 $$\begin{eqnarray}E\ll N^{2}+\mathop{\sum }_{n\leqslant X}(N^{2}/X)^{2}\ll \frac{N^{4}}{X}\asymp \frac{N^{3}}{(\log N)\cdot (\log \log N)^{C}}\end{eqnarray}$$
almost surely. We thus conclude that
 $$\begin{eqnarray}E\asymp \frac{N^{3}}{(\log N)\cdot (\log \log N)^{C}}\end{eqnarray}$$
with probability 1.


