You study history. Can you tell us, then, whether the crisis problem is growing more severe? Lawrence Summer. Former US Deputy Treasury Secretary (quoted in Eichengreen and Bordo (Reference Eichengreen and Bordo2003, p. 72)
1 INTRODUCTION
The financial disturbances that originated in the United States in the second half of 2007, with the collapse of Bear Stearns, and then in 2008 with the catastrophic bankruptcy of Lehman Brothers, are the latest in a series of episodes in various regions of the world in recent years. Financial crises, however, are not unique to current financial systems, history being full of banking and exchange rate crises. For those who have studied the history of money, financial crises are not a surprising phenomenon at all. Financial instability and crises are part of economic life, as stated by Minsky (Reference Minsky1977). Chancellor (Reference Chancellor1999), in his book on financial speculation, documented how financial crises have stretched back at least as far as Ancient Rome, during the 2nd century BC. Kindleberger (Reference Kindleberger2000) provided a list of financial crises from the Dutch tulip mania in 1636 to the Asian crisis in 1997 and the subsequent Russian and Brazilian crises in 1998. Goodhart and Delargy (Reference Goodhart and Delargy1998) created a useful table of international stock exchange shocks between 1873 and 1932 for major countries, characterising each shock according to size and international impact. Bordo (Reference Bordo1986) also provided a catalogue of crises, distinguishing between banking crises that interrupted the internal payment system and currency crises that disrupted external payment relations. More recently, Reinhart and Rogoff (Reference Reinhart and Rogoff2009) constructed an impressive data set of banking and financial crises around the entire world dating back to 1800. From a historical viewpoint, crises are depressingly familiar.
How many crises (banking, currency, stock market crashes) have occurred in Spain? Did they become more frequent, longer lasting or more severe as we moved from the nineteenth into the 20th century? What do we know about Spanish crises? The purpose of this paper is precisely to look into historical records to answer these questions.
Although this study is confined to a single country, we believe it is worth examining a country-specific historical experience in depth. First, it is difficult to compile detailed and high-quality data when a large sample of countries is considered. In contrast, single-country analyses make it possible to use the best available data for a country. Second, a country-specific time-series study can perform in-depth analyses in order to test empirical hypotheses regarding the main determinants of financial crises; moreover, it avoids some of the cross-country study limitations, particularly their inability to control for the idiosyncratic characteristics of countries, such as: institutions, technology, factor endowments, etc. Another unique feature of this paper is that it considers different types of financial crises and their combinations: banking, currency and stock market crises. The study is carried out to ascertain whether one type of crisis has become more or less prevalent and also to detect any possible interaction between crises. This is a new approach in regard to other studies, which consider banking and currency crises and a combination of the two on the one hand, and stock market crises on the otherFootnote 1.
Although there are various monographic studies of the main Spanish financial crises, none of them offer a quantitative measure of frequency, duration or severityFootnote 2. Neither is there any empirical research comparing the different crises. We do not know whether Spanish financial crises in the past were longer and deeper or entailed larger output losses than in more recent times. Nor do we know which of the three types of crises, banking, currency or stock market, were the most frequent or which occurred at the same time (any possible combination) and whether these combinations made crises more disruptive and severe. A systematic and quantitative historical study of this kind can yield lessons which not only help to understand today's financial disturbances better, but also to predict what can be expected in the future. For instance, if history tells us that Spanish crises have become longer and deeper over time, then one may suspect that the country's present financial problems are far from over and will take some years to be solved. Our paper also compares the frequency, length and intensity of Spanish crises with the results obtained in various cross-country studies that have used an ample data sample of international crises. In particular, we contrast our empirical findings with those of the comprehensive research conducted by Bordo et al. (Reference Bordo, Eichengreen, Klingebiel and Martinez-Peria2001).
In order to carry out this study, we gathered a comprehensive long-run data set including financial and stock market variables. The sample covers 150 years, from 1850 to the present time. The sample has been divided into four periods in order to compare the most recent years (1973-2000) with more than a century of financial and stock market crises, distinguishing the Bretton Woods period (1945-1972), the interwar years (1919-1935) and the long second half of the 19th century (1850-1913)Footnote 3.
Our main findings can be summarised as follows. On the whole, Spanish crises have been more frequent than in the rest of the world. Second, crises have been followed by recessions lasting an average of 2-4 years, a slightly longer time span than those recorded for the international economy. Third, Spanish crises have become more severe since 1973. Fourth, banking crises, either on their own or in combination with currency and stock market crises, were more prevalent during the interwar period than in any other. In contrast, currency crises were more frequent during the period 1945-1972, when Spain was in the process of graduating as an industrial economy. Fifth, the most severe crises are a combination of different types of crises, especially the so-called triple crises. Sixth, the majority of Spanish crises have coincided with international crises. Finally, the evidence referring to the post-1973 period suggests, unfortunately, that crises have not only become more frequent, but also more severe.
Section 2 identifies the banking, currency and stock market crashes. Section 3 explores whether crises have become more frequent in Spain under different macroeconomic frameworks and compares the Spanish record to international experiences. We also ascertain whether or not Spanish crises have coincided with international crises. Section 4 examines the duration and depth of Spanish crises and the last section presents the conclusionsFootnote 4.
2 BANKING CRISES, CURRENCY CRISES AND STOCK MARKET CRASHES
Banking crises are difficult to identify empirically, partly because of the nature of the problem and partly due to the lack of relevant data (IMF 1998). Although data on bank deposits are readily available for most countries and could therefore be used to identify crises associated with runs on banks, most banking problems in recent years have not derived from the liability side of bank balance sheets. Banking crises generally stem from the asset side of bank balance sheets — from a protracted deterioration in asset quality. This suggests that variables such as the share of non-performing loans in bank portfolios, large fluctuations in real estate and stock prices and indicators of business failure could be used to identify crisis episodes. For instance, Dermirguc-Kunt and Detragiache (Reference Dermirguc-Kunt and Detragiache1998) consider that there is a banking crisis when the ratio of non-performing assets to total assets in the banking system exceeds 10 per cent or the cost of the rescue operation is at least 2 per cent of GDP; they also identify a banking crisis when banking sector problems result in a large-scale nationalisation of banks, extensive bank runs take place or emergency measures such as deposit freezes, prolonged bank holidays or generalised deposit guarantees are enacted by the government in response to the crisis. The difficulty is that information for such variables is not readily available for many countries or is incompleteFootnote 5. Given these limitations, banking crises have usually been dated by researchers on the basis of a combination of events, such as forced closure, mergers, government takeovers of financial institutions, runs on banks or government assistance to one or more financial institutions.
This paper uses both quantitative and qualitative information in order to identify the main Spanish banking crisesFootnote 6. Although banking crises have differed in nature and severity across countries and time, they typically include one of the following three elements: (i) a high proportion of bank failures; (ii) the failure of a particularly large or important bank; or (iii) extraordinary or direct intervention on behalf of the government to prevent failures. Friedman and Schwartz (Reference Friedman and Schwartz1963) and Schwartz (Reference Schwartz1986) focus on liquidity and assert that banking crises should be defined by changes in the deposits-to-currency ratio. As deposits are withdrawn from banks in favour of currency, banking crises are associated with sharp drops in the deposit-to-currency ratio. Another way to detect a banking crisis is by looking at the real stock prices of banks. For instance, Eichengreen and Portes (Reference Eichengreen and Portes1987) pointed out that disturbances in financial markets are usually associated with falling asset prices.
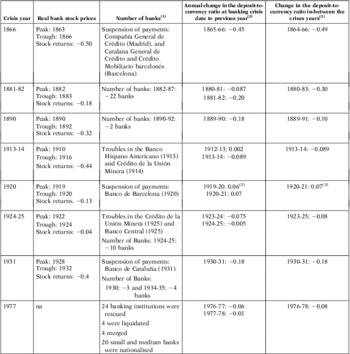
In order to identify the main Spanish banking crises, we have made use of three independent indicators, namely changes in the deposit-to-currency ratio, bank real stock prices and the number of bank failuresFootnote 7. Table 1 shows the results of combining the three indicators. Eight banking crises are identified over the period: three in the 19th century (1866, 1881-1882, 1890) and the other five in the 20th century (1913-14, 1920, 1924-25, 1931 and 1977)Footnote 8. Not surprisingly, many of these years are well known as the approximate dates of international economic and financial crises, emphasising the connection between the small Spanish economy and the international economy.
BANKING CRISES

Notes: na: not available.
(1) Data on number of banks are different according to different sources for most of the period because there is no a banking directory including all the banking institutions.
(2) From 1856 to 1872 we use the banknotes/currency ratio and from 1874 to 2000 the deposit-to-currency ratio.
(3) This indicator does not detect the 1920 crisis because it was caused by the problems of only one bank (Banco de Barcelona).
Source: See text and Data Appendix.
A currency crisis may be said to occur when a speculative attack on the exchange value of a currency results in a devaluation (or sharp depreciation), or forces authorities to defend the currency by spending large amounts of international reserves or by sharply raising interest rates. For example, Frankel and Rose (Reference Frankel and Rose1996) define a «currency crash» as a nominal depreciation of the currency of at least 25 per cent in a year, along with a 10 per cent increase in the rate of depreciation on the previous yearFootnote 9 and Reinhart and Rogoff (Reference Reinhart and Rogoff2009) identify a currency crisis as an annual depreciation of 15 per cent or more of a currency with respect to a relevant anchor currency or a reference country. However, Eichengreen et al. (Reference Eichengreen, Rose and Wypplosz1996, Reference Eichengreen, Rose and Wypplosz1997) argue that currency crises cannot be identified using actual devaluations, revaluations and flotations, because speculative attacks are not always successful and authorities can support the currency by spending central bank reserves or raising interest rates. For this reason, they constructed a more sophisticated index that not only considers exchange rate changes, but also movements in international reserves or interest rate changes. They defined the index of currency pressure as a weighted index made up of relative changes in the nominal exchange rate, international reserves and interest ratesFootnote 10. The index of market pressure is as follows:
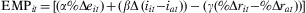 $${\rm{EM}}{{{\rm{P}}}_{it}}\,{\rm{ = }}\,{\rm{[(}}\alpha {\rm{\% \rDelta }}{{e}_{it}}{\rm{)}}\,{\rm{ + }}\,{\rm{(}}\beta {\rm{\rDelta }}\,{\rm{(}}{{i}_{it}}{\rm{ - }}{{i}_{at}}{\rm{)) - (}}\gamma {\rm{(\% \rDelta }}{{r}_{it}}{\rm{ - \% \rDelta }}{{r}_{at}}{\rm{))]}}$$
where eit is the exchange rate of a currency with respect to an anchor currency, it is the short-term interest rate of the country considered, iat is the short-term interest rate of an anchor country, r is the ratio of reserves (R) to narrow money (M1) of the considered country to the anchor country and α, β and γ are the weights. A crisis is defined as an extreme value of the index:
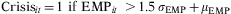 $${\rm{Crisi}}{{{\rm{s}}}_{it}}\,{\rm{ = }}\,{\rm{1}}\,\,{\rm{if}}\,\,{\rm{EM}}{{{\rm{P}}}_{it}}\,{\rm{\>}}\,{\rm{1}}{\rm{.5}}\,{{\sigma }_{{\rm{EMP}}}}\,{\rm{ + }}\,{{\mu }_{{\rm{EMP}}}}$$
where σ EMP and μ EMP are the standard deviation and sample mean of EMP (Exchange Market Pressure), respectively.
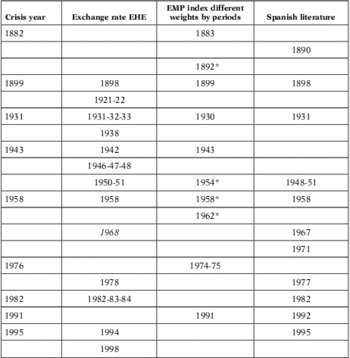
In order to identify the main Spanish currency crises we have computed two alternative indicators: a simple index of exchange rate variations and a weighted EMP indexFootnote 11. As in the case of the banking crises, quantitative data have also been combined with other qualitative information. When using exchange rate variations, a currency crash was considered a nominal depreciation of the currency of at least 15 per cent in a year (Reinhart and Rogoff Reference Reinhart and Rogoff2009). When a currency crisis appears in consecutive years, it is treated as one sole currency crash. According to these criteria, we have detected nine currency crises using the pound sterling/peseta exchange rate from 1850 to 1913 and the US dollar/peseta exchange rate from 1914 to 2000. Furthermore, the weighted EMP also identifies nine currency crises. The list is presented in Table 2, which shows crises in 1882, 1899, 1931, 1943, 1958, 1976, 1982, 1991 and 1995Footnote 12.
CURRENCY CRISES

*Crises on the limit of acceptance.
Source: See text and Data Appendix.
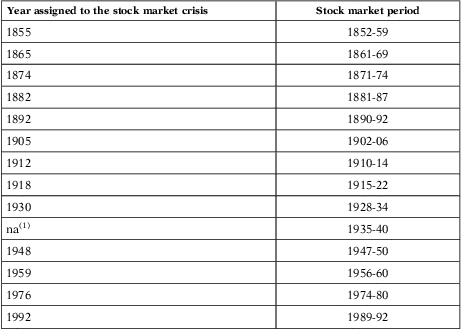
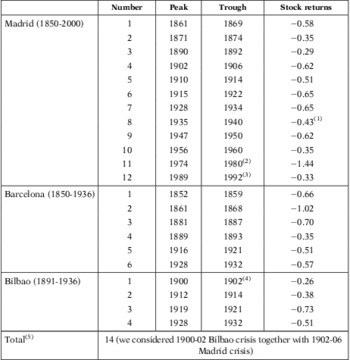
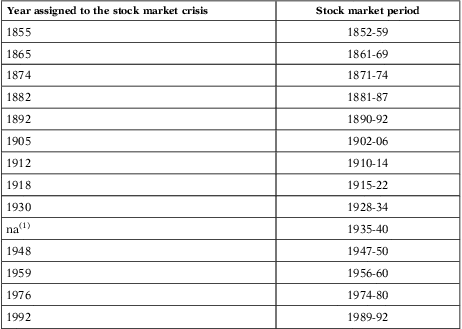
In the case of stock market crashes, there are no clear definitions in the literature. Patel and Sarkar (Reference Patel and Sarkar1998) define a stock market crash as a decline in a stock price index, relative to the historical maximum, of more than 20 per cent for developed markets and more than 35 per cent for emerging markets. Barro and Ursúa (Reference Barro and Ursúa2009) consider there is a stock market crisis when cumulative, multi-year returns are −0.250 or less of the stock price index. The peak-to-trough method is applied to obtain the size of the declinesFootnote 13. We define a stock market crash as a downturn in the stock price index of more than 25 per cent from the nearest historical peak. For the 1850-1940 period we have used a combination of stock prices in Madrid (mainly government securities), Barcelona and Bilbao (basically private industrial and commercial securities). After 1940, the index has been estimated using data from the Madrid market, as it is the largest and also quotes both government debt and shares of the major private industrial and commercial companiesFootnote 14. According to this identification procedure, fourteen stock market crashes have been detected, as shown in Tables 3 and 4.
STOCK MARKET CRISES ACCORDING TO THE PEAK-TO-TROUGH METHOD
Note: (1) Data not available because the stock market was closed throughout the Spanish Civil War.
Source: See text and Data Appendix.
STOCK MARKET CRISES IN MADRID, BARCELONA AND BILBAO, 1850-2000

Notes: Data for Madrid from 1850 to 2000, Barcelona 1850-1913 and Bilbao 1891-1936.
(1) There are no data; the returns are interpolated from Barro and Ursúa (Reference Barro and Ursúa2009).
(2) Could be considered until 1982.
(3) Could be considered until 1994.
(4) Could be considered until 1904 as in the case of Madrid.
(5) Total refers to the crises that are in different years. The same stock market is considered when crises occur in overlapping or adjacent years.
Source: See text and Data Appendix.
As a crisis is always a complex phenomenon that in many instances emerges as a consequence of a combination of events, we have also computed four additional categories or types of crises. The combination of currency and banking crises (twin 1 in our terminology) are the most widely studied and significant of them all and refer to the simultaneous occurrence of banking and balance-of-payments problems. The other two, namely combinations of banking and stock market crises (twin 2) and currency and stock market crises (twin 3), have received less attention, although we find they provide extra information that is useful to understand the length and severity of certain historical episodes. Finally, we believe it would also be of interest to provide what can be labelled a «triple crisis», an unfortunate event that occurs when a country suffers a currency, banking and stock market crisis at the same time.
3 CRISIS FREQUENCY
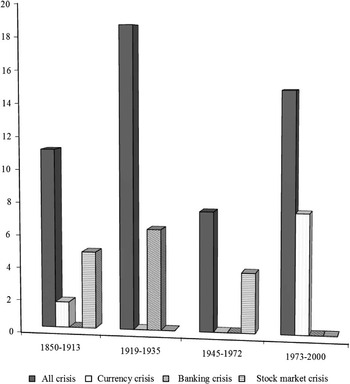
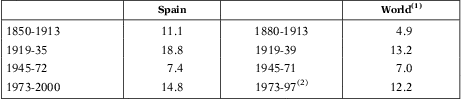
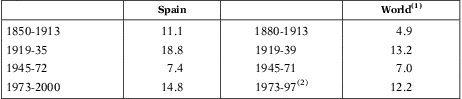
According to the standard definition, the frequency of a crisis is the number of crises divided by the number of year observations, by period. The exercise has been conducted for four periods (1850-1913, 1919-35, 1945-72 and 1973-2000) and the results are summarised in Figures 1 and 2. The bars on the far left in Figure 1 indicate that after 1913, the combination of banking, currency and stock market disruptions became more frequent. For the second part of the 19th century and up to the First World War we found a frequency rate of 11.1 per cent, only slightly more than half of that estimated for the 1919-1935 period (18.2 per cent) and also lower than the figure recorded for 1973-2000 (14.8 per cent). While not entirely comparable, as we have included evidence for stock market crashes, our results are similar to those found by Bordo et al. (Reference Bordo, Eichengreen, Klingebiel and Martinez-Peria2001) for their large sample of 21 countriesFootnote 15.


The interwar period is when the frequency of (all) crises was highest, a conclusion similar to that obtained by Bordo et al. (Reference Bordo, Eichengreen, Klingebiel and Martinez-Peria2001) in their comprehensive study. Moreover, when comparing crisis frequency over the last two periods, namely 1945-1972 and 1973-2000, a stark contrast emerges: an average frequency rate of 7.4 per cent compared with 14.8 per cent, which suggests that, as in the rest of the world, the crisis problem has grown in Spain since 1972. Furthermore, these same data suggest that in any given year between 1919 and 2000, the chance of Spain suffering a currency, banking or stock market crisis, or any combination of them was 1.5 points higher than the world average (12.3 per cent vs. 10.8 per cent).
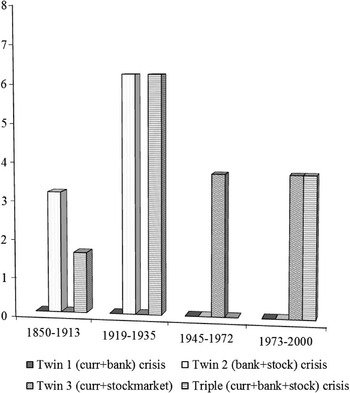
A combination of simultaneous crises rather than the occurrence of a single crisis is what best explains the frequency rate in each period, as Figure 2 demonstrates. Twin 2 (banking and stock market) crises and triple (currency, banking and stock market) crises seem to have been the most common form of economic turmoil in the pre-1913 and also post-1919 periods. This result is consistent with the qualitative evidence and should not surprise researchers who are familiar with the literature on Spanish financial history. Before 1936, bank failures and stock market crashes went hand in hand and causality, in most instances, ran from the latter to the former. In the interwar years, banking crises were frequent, although they occurred in combination with the other two types of crises, causing the overall rate of incidence to increase from 11.1 per cent to 18.2 per cent.
As elsewhere, banking crises were almost non-existent in the so-called Bretton Woods years. One explanation given for this conspicuous absence is that regulations in the Bretton Woods era were so restrictive and capital flows were so low that there were no causes for banking crises (Goodhart Reference Goodhart2007). The situation in Spain was similarFootnote 16. The civil war broke out at a time of financial self-regulation and the Franco regime prompted the imposition of structural controls and a shift in bank supervision away from market discipline and towards government discretion. As Pons (Reference Pons2002, Reference Pons2012) argued, the strong regulatory framework in the Franco era reduced the instability of the banking system by sacrificing competition. Banks and saving banks in difficulty were systematically rescued by the Bank of Spain and financially sound banks with fiscal support and under the auspices of supervisory authorities merged with and acquired banks in trouble. This was the other alternative used to avoid bankruptcies. On the contrary, currency crises emerged as a major source of economic turmoil. This result is obviously similar to that documented for the international economy at large. Moreover, as the repetition of stock market crashes was also common, the twin 3 type of crisis is what explains why the rate of incidence in the years 1945-1972 remained as high as 7.4 per cent, on this occasion close to the world average (7 per cent).
Figure 2 also clarifies that the frequency of currency crises combined with banking and stock market crashes (twin 3 and triple) is responsible for such a high rate of incidence since 1973. This is also consistent with our historical knowledge of recent times. The peseta exchange rate suffered a series of sharp devaluations in the 1970s and 1980s and did not escape the disruption caused by the European exchange rate turbulence of 1992-1993 either.
3.1 Frequency and exchange regime, capital mobility, regulation and economic development
In what follows we have linked the frequency of Spanish financial crises to some factors that may explain it, including the exchange rate regime, the degree of capital mobility, the regulatory framework and the level of economic development. By relating these factors to crisis frequency, we seek to detect any possible regularities and changes over time in order to identify possible determinants of financial distress.
The 1850-1913 years were characterised by a floating exchange rate regime (Spain never adopted the gold standard), the absence of capital controls and a lack of regulation in the financial system. The main features of the interwar period were a (dirty) floating exchange rate regime, capital controls and a weakly regulated banking system. As elsewhere, from 1945-1972 the prevailing elements of the Spanish regime were a fixed exchange rate with capital controls and a strictly regulated financial system. The last period, on the contrary, exhibited completely the opposite characteristics with a flexible exchange rate, no capital controls and a deregulated financial systemFootnote 17.
The evidence suggests two different patterns. The 65 years of nearly clean floating exchange rates from 1850 to 1913 coincided with a period during which (all) crises were relatively less frequent. In contrast, during the dirty floating regime that characterised the interwar years, crisis frequency, whether single or mixed, increased substantially. Furthermore, an increase in crisis frequency is observed in the last two periods, when the peseta exchange rate was left to float. It seems as if the change in the exchange rate regime did not impinge on the frequency of crises. Hence, there are two periods with a floating exchange rate (1850-1913 and 1973-2000) that recorded different results in terms of crisis frequency. A similar situation occurs with capital controls. If we compare the two periods with unrestricted capital mobility (1850-1913 and 1973-2000), we observe relatively high crisis frequency (11.1 and 14.8, respectively). However, the two periods with capital controls (1919-1935 and 1945-1972) witnessed very different frequency rates. In fact, they registered the highest and lowest frequency, respectively.
Results are different when we relate financial regulation with crisis frequency. In this period, four distinct regulatory regimes are identified: «the liberal era» (1856-1920), the «self-regulated era» (1921-1936), when there was a change in regulation and supervision was entrusted to the banks themselves, the «interventionist period» (1939-1975), when there was an abrupt shift in regulation and competition was replaced by government discretion, and the post Bretton Woods era (1975-2000), which was a period of liberalisation and deregulation (Martín-Aceña et al. Reference Martín-Aceña, Betrán and Pons2009). In the «liberal» and «self-regulated» eras, Spain suffered from financial crises more frequently (11.1 per cent and 18.8 per cent, respectively) than in the interventionist period (7.47 per cent). Moreover, the liberalisation that began at the end of the 1960s was also accompanied by an increase in crisis frequency (14.8 per cent in the period 1973-2000). In this sense, we can affirm, as mentioned in the previous section, that a more regulated system can reduce the probability of suffering a financial crisis, especially banking crises.
However, there have not only been changes in the exchange and currency regimes and regulation over these 150 years, but also in the economic position of the country. Spain progressed from underdevelopment, before 1913, becoming an emerging country between 1919 and 1972, before finally being considered an industrial economy thereafter. In the literature, there is no consensus regarding the relationship between economic development and crisis frequency. Bordo et al. (Reference Bordo, Eichengreen, Klingebiel and Martinez-Peria2001) argued that crisis frequency is concentrated in developing countries (which tend to be younger, smaller and less developed). However, they did mention one prominent exception, namely the Great Depression in the 1930s. Now, the 2007 crises can also be added to that exception. Reinhart and Rogoff (Reference Reinhart and Rogoff2009) maintain that emerging countries have more external default crises and inflation crises, but banking crises and currency crises are a recurring phenomenon in both developed and emerging economies.
The pattern of crisis frequency in Spain over these 150 years resembles the international trend and we cannot find a clear relationship between the changes in economic development and crisis frequency. When Spain progressed from its initial backward status in the 19th and very early 20th century to an emerging economy in the early decades of the 20th century, crises became more recurrent, as was the case with the world average. However, during the period 1945-1972 when Spain was still an emerging country, crisis regularity dropped. The opposite happened in the last period when the Spanish economy achieved developed country status, as there was a sharp increase in crisis frequency. Consequently, there does not seem to be a clear-cut relationship between economic development and crisis frequency in Spain.
3.2 Spanish financial crises and contagion
The task of defining international contagion and transmission channels is complex. A number of theoretical and empirical models focus on transmission through trade linkage (Eichengreen et al. Reference Eichengreen, Rose and Wypplosz1996), while others emphasise the significance of financial market linkage, mainly through capital flows (Kaminsky et al. Reference Kaminsky, Reinhart and Vegh2003). Information is a third means of crisis contagion when economic fundamentals are common among markets that share similar features (Allen and Gale Reference Allen and Gale2007; Reinhart and Rogoff Reference Reinhart and Rogoff2009). The empirical results of these models are not conclusiveFootnote 18. For instance, Reinhart and Rogoff (Reference Reinhart and Rogoff2009) argue that crises in the centre do not always affect the global economy. In what follows we have simply attempted to ascertain how many Spanish financial crises have coincided with international financial crises. The dates for the latter have been taken from the well-known studies by Bordo et al. (Reference Bordo, Eichengreen, Klingebiel and Martinez-Peria2001), Neal and Weidenmier (Reference Neal and Weidenmier2003), Reinhart and Rogoff (Reference Reinhart and Rogoff2009) and Marichal (Reference Marichal2010).
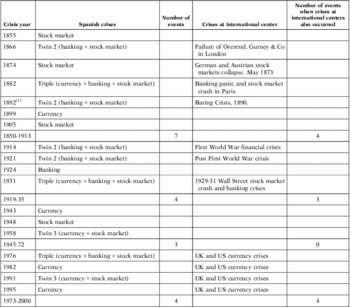
The first column in Table 5 shows the eighteen Spanish financial crises we have identified in this paper and the second column lists the main world financial crises. In the period 1850-1913, we observe that of the seven Spanish crises recorded by our database, four match the international financial crises of 1866, 1874, 1882 and 1892. Hence, it can be said that in this period contagion was relatively common since the probability of a Spanish crisis overlapping with a world crisis was about 57 per cent. In the interwar period, the probability of contagion was even higher at 75 per cent, since three of the Spanish domestic crises, 1914, 1921 and 1931 coincided with the international crises that plagued the world economy around the same time. On the contrary, during the Bretton Woods era, the Spanish crises were entirely domestic and no contagion whatsoever is found. Finally, for the last period, 1973-2000, all Spanish crises coincide with the international crises.
SPANISH CRISES AND CRISES AT INTERNATIONAL CENTER

Note: Twin 1 is a combination of currency and banking crises. Twin 2 is a combination of banking and stock market crises. Twin 3 is a combination of currency and stock market crises. Triple is a combination of currency, banking and stock market crises.
(1) 1892 stock market crisis and 1890 banking crisis. In the period 1919-35 we have included the 1914 crisis and in the 1945-72 period the 1943 crisis.
Sources: for Spain, see text and Data Appendix and for the international crises, Bordo et al. (Reference Bordo, Eichengreen, Klingebiel and Martinez-Peria2001), Neal and Weidenmier (Reference Neal and Weidenmier2003), Reinhart and Rogoff (Reference Reinhart and Rogoff2009) and Marichal (Reference Marichal2010).
All in all, what Table 5 highlights is that, on the one hand, eleven out of the eighteen Spanish financial crises concur with corresponding world financial crises, which is a probability of coincidence of 61 per cent. On the other hand, Table 5 also shows that both in the interwar years and in the most recent period when international crises have been frequent, they have also been recurrent in Spain.
4 DURATION AND DEPTH OF CRISES
Recovery time is defined as the number of years until GDP growth returns to its pre-crisis trend. By definition, minimum recovery time is 1 year. The depth or severity of a crisis is the cumulative loss of output estimated by adding the differences between trend growth and output growth after the crisis until the time when annual output growth returns to its trend.
Quantifying the length and depth of a crisis is not a simple task, as it requires calculating the growth trend of the economy and defining the pre-crisis period (3, 5 or more years of normal growth) to compare with actual growth during the crisis. The IMF (1998) resorts to the GDP growth rate for the 3 years preceding the event, while Bordo et al. (Reference Bordo, Eichengreen, Klingebiel and Martinez-Peria2001) calculates the GDP growth rate over the 5 years preceding the event. As considering 3 or 5 years to determine the pre-crisis trend is an ad hoc solution and, moreover, the years prior to financial crises are in most cases characterised by an expansion or extra-growth, this paper takes a different approach. The growth trend in this case derives directly from the different phases of growth computed by Prados de la Escosura (Reference Prados de la Escosura2003). This author estimated average growth rates for periods delimited by 2 peak years. This alternative was chosen because the 3- or 5-year average growth rate for Spain was not sufficiently representative of the long-term growth rate. Potential growth is better captured by the growth rate of a full cycle, as defined by Prados de la Escosura (Reference Prados de la Escosura2003).
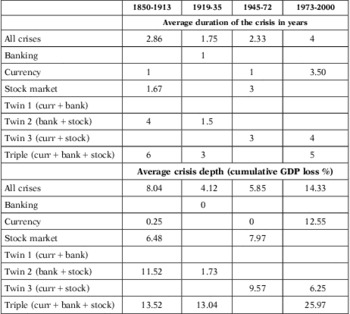
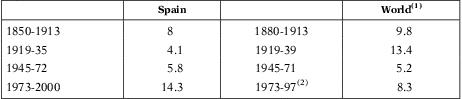
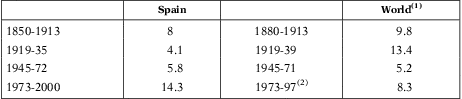
Our calculations are shown in Table 6. For «all crises» it seems obvious that the worst performance was recorded in the last period. The pre-crisis growth rate took longer (double the time) to recover than in any of the other three periods. In fact, recovery took as long as 4 years compared with an average of around 2 years for the other three periods. Moreover, post-1973 crises have not only lasted longer, but have also been more severe, with a cumulative GDP loss as high as 14.3 per cent, nearly twice that of 1850-1813 and nearly three times the output losses in the interwar and Bretton Woods years. This result is in sharp contrast to the conclusions reached by Bordo et al. (Reference Bordo, Eichengreen, Klingebiel and Martinez-Peria2001), for whom crises had grown more frequent but not more severe after 1973 (Tables 7 and 8). The difference can be explained by the extraordinary severity of the crises (currency, twin 3 and triple crises) that occurred in the late 1970s. This was partly due to the impact of the deep industrial recession that took place during the transition from a dictatorship to democracy, and also to the slow adaptation of the Spanish economy to the more open and integrated economy of the former European CommunityFootnote 19.
DURATION AND DEPTH

Notes: Twin 1 is a combination of currency and banking crises. Twin 2 is a combination of banking and stock market crises. Twin 3 is a combination of currency and stock market crises. Triple is a combination of currency, banking and stock market crises.
Source: See text and Data Appendix.
CRISIS FREQUENCY
Notes: (1) Figure for 21-country sample.
(2) Figure for 56-country sample.
Source: See text and Data Appendix.
OUTPUT LOSS (%)
Notes: (1) Figure for 21-country sample.
(2) Figure for 56-country sample.
Source: See text and Data Appendix.
Another salient feature of Table 6 is the relative mildness of the interwar crises in absolute terms and when compared with the international experience (Table 8). Duration was shorter and output losses (all crises) lower than in any of the other three periods. Industrial backwardness, financial isolation and the sharp depreciation of the exchange rate of the peseta against all major international currencies may explain this marked difference. There were three (not very severe) banking crises between 1913 and 1936 and a triple crisis in 1931 (with greater repercussions). However, if only the 1931 triple crisis is considered, findings are similar to those obtained by Bordo et al. (Reference Bordo, Eichengreen, Klingebiel and Martinez-Peria2001).
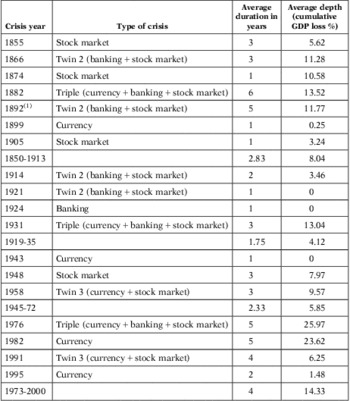
More detailed information is presented in Table 9, which lists the duration and depth of crises by year and type. The longest and deepest were the triple and currency crashes in 1976 and 1982, respectively. Complete recovery required a full decade and cumulative output loss peaked at 25.97 per cent and 23.62 per cent, respectively. The other two major disturbances date back to the 19th century, namely the banking crisis in 1866 and the triple crisis in 1882. Both caused a cumulative GDP loss of around 13 per cent.
DURATION AND DEPTH OF CRISES IN SPAIN BY YEAR AND TYPE OF CRISIS CONSIDERING ALL TYPES OF CRISES

Notes: Twin 1 is a combination of currency and banking crises. Twin 2 is a combination of banking and stock market crises. Twin 3 is a combination of currency and stock market crises. Triple is a combination of currency, banking and stock market crises. In the period 1919-35 we have included the 1914 crisis and in the 1945-72 period the 1943 crisis.
(1) 1892 stock market crisis and 1890 banking crisis.
Source: See text and Data Appendix.
The ranking (in brackets) of crises in terms of the largest output loss is as follows: 1866 (6), 1882 (3), 1892 (5), 1931 (4), 1976 (1) and 1982 (2), triple crises being recorded in 1882, 1931 and 1976 (see Table 9).
As shown above, the most severe Spanish crises have been a combination of different types of crises, mainly triple crises, the only exceptions being the 1874 and 1948 stock market crises and the 1982 currency crisisFootnote 20. According to Kaminsky and Reinhart (Reference Kaminsky and Reinhart1999), banking crises have usually been predated by currency crises, but when both occur together the impact on economic activity is greater than when they happen separately. Moreover, stock market crises are also more severe when they coincide with a currency and/or a banking crisis. The impact of a stock market collapse spreads to the banking sector and finally becomes a currency crisis. Although banking crises often precede currency crises, there are obvious common factors behind both of them and it has been proven that currency problems aggravate banking problems and vice versa. The results obtained in this paper for Spanish financial crises confirm these findings.
5 CONCLUSIONS
This paper presents a wealth of quantitative information in order to identify a large number and various types of financial crises. A total of eighteen crises of various classes and combinations have been detected over the last 150 years. All crises seem to have been more frequent in Spain than in the world sample studied by Bordo et al. (Reference Bordo, Eichengreen, Klingebiel and Martinez-Peria2001). Crises have been followed by recessions lasting on average 2-4 years, which is a slightly longer period than the international average of 2-3 years. Worldwide crises recorded an average cumulative output loss of 9.2 per cent, while in the particular case of Spain the figure was 8.1 per cent, a small difference that can be attributed to the milder impact of the interwar period crises, as shown in Table 6. On the contrary, the losses recorded in the last period were greater in Spain than at international level.
Banking crises, either on their own or in combination with currency and stock market crises, were more prevalent during the interwar period than in any other. In contrast, currency crises took place more often during the period 1945-1972, when Spain was in the process of graduating as an industrial country. The rapid transformation of the economy during the 1950s and 1960s with high import requirements of raw materials and intermediate goods caused repetitive balance of payments disequilibria, exerting strong pressure on the exchange rate. In general, banking and stock market crises and their combinations were more frequent in the first two periods (1850-1913 and 1919-1935), while currency crises and their combinations were more common in the second two periods (1945-1972 and 1973-2000).
The frequency rate of Spanish financial crises has remained high from 1913 onwards. Financial crises have also become more severe as we passed from the 19th to the 20th century, although the explanation lies in the catastrophic impact of the financial crises in 1976-1982. In summary, Spanish crises have become more frequent, more severe and last, on average, longer than in the rest of the world. History thus warns that there is something disturbing about our economy.
Banking crises, currency crises and twin crises are hardy perennial, to echo the celebrated aphorism in Goodhart and Delargy (Reference Goodhart and Delargy1998): plus ça change, plus c′est la meme chose. Spain is not different: we have lived with and through recurrent financial crises for the last 150 years. Crises have occurred under distinctive exchange and currency regimes, with and without capital controls and independently of the level of development of the economy. The only variable that has significantly reduced the frequency of crises is regulation. The most interventionist period (1945-1972) recorded the lowest crisis frequency. There were no banking crises during this period, although competition was sacrificed in favour of stability.
For «all crises» it seems obvious that the worst performance has been recorded in the most recent period. The pre-crisis growth rate has taken longer (double the time) to recover than in any of the other three periods. In fact, recovery took as long as 4 years compared with an average of around 2 years for the other three periods. Moreover, post-1973 crises have not only lasted longer, but have also been more severe, with a cumulative GDP loss as high as 14.3 per cent, nearly twice that of 1850-1813 and nearly three times the output losses in the interwar and Bretton Woods years. This result is in sharp contrast to the conclusions reached by Bordo et al. (Reference Bordo, Eichengreen, Klingebiel and Martinez-Peria2001), for whom crises had grown more frequent but not more severe after 1973 (Table 9). The difference can be explained by the extraordinary severity of the crises (currency, twin 3 and triple crises) that occurred in the late 1970s. Moreover, some of the most severe crises (1976, 1882 and 1931) were combinations of different types of crises; in fact they were triple crises and consequently, this result is in line with Kaminsky and Reinhart (Reference Kaminsky and Reinhart1999), who maintain that when currency and banking crises occurred jointly, their impact on economic activity was greater than when they took place separately. Finally, in QJ;Spain the periods with highest frequency of financial crises coincided with international distress.
Crises have been costly and this conclusion has relevant policy implications. The authorities should be aware of the fact that if crises brought about output losses in the past, future crises will most likely deliver the same poison. The first lesson is that authorities should have a strategy prepared to face (expected and unexpected) economic disturbances and to minimise their cost. Moreover, they should also have policy programmes aimed at shortening the length of crises and speeding up recovery.
The 2007 crisis confirms our results about the rising severity and complexity of Spanish financial crises. We are once again involved in a triple crisis with some peculiar characteristics. First, there has been a very severe banking crisis, although in this case savings banks have played the leading role. Second, although we have not experienced a currency crisis, the crisis in the euro has been one of the main consequences of the 2007 turmoil, revealing some of the weaknesses in the construction of the common currency. In fact, at present the future of the euro is uncertain. Finally, despite not crashing, the stock market has declined sharply since 2007. The stock market index (IBEX) recorded its historical maximum (15,945.7 points) on November 8, 2007, but had fallen by 52 per cent in September 2011 (7,640.7) and the trend has continued over the last few months (around 6,999 points at the end of April 2012). Therefore, the recent evolution of the Spanish financial system shows that the probability of suffering a combination of different kinds of crises is increasing and, consequently, the depth and complexity of financial crises has risen not only in the last part of the 20th century, but also at the beginning of the 21st century.
DATA APPENDIX
Banking crises
For nominal bank stock prices, Hoyo (Reference Hoyo2007). For the number of banks, Tortella (Reference Tortella1973) for the period 1850-1875, Tedde de Lorca (Reference Tedde de Lorca1974) for the period 1875-1913, EHE (Carreras and Tafunell Reference Carreras and Tafunell2005) for the period 1939-1975 and Pueyo (Reference Pueyo2003) for the period 1942-1995. Bankruptcies and other qualitative information in Martín-Aceña et al. (Reference Martín-Aceña, Betrán and Pons2009). Banking profitability, bank deposits and prices in EHE (Carreras and Tafunell Reference Carreras and Tafunell2005).
Currency crises
Exchange rates and interest rates have been taken from EHE (Carreras and Tafunell Reference Carreras and Tafunell2005). Data for the United Kingdom and the United States from Homer and Sylla (Reference Homer and Sylla2005). Reserve variations from Martín-Aceña (Reference Martín-Aceña1985) and Prados de la Escosura (Reference Prados de la Escosura2010). Reserve variations for the United Kingdom, Accominotti et al. (Reference Accominotti, Flandreau and Rezzik's2011) for the period 1881-1911 and 1912-1944, Mitchell (Reference Mitchell1998). Balance of payments data from Mitchell (Reference Mitchell1994) are used for the rest of the years (1912-1994). Finally, for the United States, data from the balance of payments provided by US Historical Statistics (Carter et al. Reference Carter2006) (1874-1998) were used.
Stock market crises
Data sources for Madrid and Barcelona are the EHE (Carreras and Tafunell Reference Carreras and Tafunell2005) (1850-1913) and Hortalá (Reference Hortalá2006) for 1913 to 1936 and Houpt and Rojo-Cagival (Reference Houpt and Rojo-Cagival2010) for Bilbao.