



1. Introduction
Let
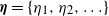 $\boldsymbol{\eta} = \{\eta_1, \eta_2, \ldots\}$
be a sequence of independent and identically distributed (i.i.d.) random variables, where the term
 $\eta_n \in \mathbb{R}$
denotes the random environment at moment n. In addition, consider the family
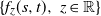 $\{ f_{z}(s, t),\ z \in \mathbb{R} \}$
of probability generating functions, and introduce the mating function
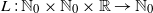 $L\,:\, \mathbb{N}_{0} \times \mathbb{N}_{0} \times \mathbb{R} \rightarrow \mathbb{N}_{0}$
, where
 $\mathbb{N}_0 = \mathbb{N} \cup \{ 0 \}$
.
Using this notation, we define a bisexual branching process in a random environment (BBPRE)
 $\{ N_n,\ n \geq 0 \}$
as a time-homogeneous Markov chain with transition probabilities depending on
 $\boldsymbol{\eta}$
by the rule
 \begin{align*} {{\mathrm{P}}} ( N_{n + 1} = j\, | N_n = i, \boldsymbol{\eta} ) = {\mathrm{P}} ( L( F_{n + 1}, M_{n + 1}, \eta_{n + 1} ) = j\, | \eta_{n + 1} ), \end{align*}
where
 $N_0 = N$
, and the distribution of the random pair
 $(F_{n + 1}, M_{n + 1})$
conditioned on
 $\eta_{n + 1}$
has the probability generating function
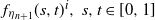 $f_{\eta_{n + 1}}(s, t)^i,\ s, t \in [0, 1]$
.
More intuitively, the process
 $\{ N_n,\ n > 0 \}$
can be defined as follows. Let us consider a sequence
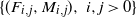 $\{ (F_{i, j}, M_{i, j}),\ i, j > 0 \}$
of two-dimensional random vectors taking values in
 $\mathbb{N}_0 \times \mathbb{N}_0$
. For a fixed environment at moment n, we assume the pairs
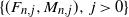 $\{ (F_{n, j}, M_{n, j}),\ j > 0 \}$
to be conditionally i.i.d. with the corresponding probability generating function
 $f_{\eta_n}(s, t)$
. In addition, the vectors
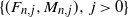 $\{ (F_{n, j}, M_{n, j}),\ j > 0 \}$
are assumed to be independent for different
 $n \in \mathbb{N}$
. Under this notation, we define a BBPRE as the sequence
 \begin{equation} N_0 = N,\quad N_{n + 1} = L\left( \sum_{j = 1}^{N_n} F_{n + 1, j}, \sum_{j = 1}^{N_n} M_{n + 1, j},\eta_{n + 1} \right)\!,\quad n \geq 0. \end{equation}
This definition allows us to consider this process step by step using a biological analogy. For a fixed moment n,
 $N_n$
couples start to produce offspring. The jth couple of the nth generation produces
 $F_{n + 1, j}$
‘female’ and
 $M_{n + 1, j}$
‘male’ descendants, respectively. Then all new ‘female’ and ‘male’ descendants group into
 \begin{align*} N_{n + 1} = L\left( \sum_{j = 1}^{N_n} F_{n + 1, j}, \sum_{j = 1}^{N_n} M_{n + 1, j}, \eta_{n + 1} \right) \end{align*}
couples, which in turn, produce offspring. Under this interpretation, the standard mating functions
 \begin{equation} L(x, y, z) = x \min\!(1, y),\quad L(x, y, z) = \min\!(x, y\, d(z)),\quad d\,:\, \mathbb{R} \rightarrow \mathbb{N}. \end{equation}
describe polygamous and monogamous (
 $d(z) = 1$
) mating schemes, respectively.
Bisexual branching processes are considered to be a natural modification of a standard Galton–Watson branching process. They were first introduced in [Reference Daley1] for the standard mating functions (2).
In that study, the sufficient conditions for process extinction with probability 1 were provided. Further advances in the extinction problem were made in [Reference Hull2, Reference Bruss3] for superadditive mating functions.
Bisexual branching processes in a random environment were introduced in [Reference Ma4], where non-degeneracy conditions of such processes were provided. In [Reference Ma and Molina5], the previous results were generalized to the case where the mating function depends on the environment. Finally, in [Reference Xiao, Liu and Li6], an almost sure convergence rate of a normalized supercritical BBPRE was studied under the condition
 \begin{align*} \prod_{n = 1}^{\infty} {\mathrm{E}} \left( \frac{ \sup_{ k > 0} k^{-1} {\mathrm{E}}_{\boldsymbol{\eta}} \left( \left. N_{n + 1} \right| N_n = k \right) }{ \inf_{ k > 0 } \, k^{-1} {\mathrm{E}}_{\boldsymbol{\eta}} \left( \left. N_{n + 1} \right| N_n = k \right) } \right) < \infty. \end{align*}
Unfortunately, this is too strict for the case of i.i.d. environments, since it implies that
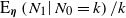 $ {\mathrm{E}}_{\boldsymbol{\eta}} \left( \left. N_1 \right| N_0 = k \right) / k$
does not depend on k, which is not true for a BBPRE with the standard mating function
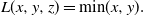 $ L(x, y, z) = \min\!(x, y).$
We consider the much weaker condition that the mating function can be approximated by a Lipschitz function.
Note that for a particular case
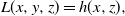 $ L(x, y, z) = h(x, z),$
where
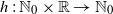 $ h\,:\, \mathbb{N}_0 \times \mathbb{R} \rightarrow \mathbb{N}_0$
is a measurable function, we have a controlled branching process. For a comprehensive review of controlled branching process results, see [Reference Velasco, Del Puerto and Yanev7].
Denote
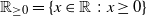 $\mathbb{R}_{\geq 0} = \{x \in \mathbb{R}\ \colon x \geq 0 \}$
, and let
 $\{ N_n,\ n \in \mathbb{N}_0 \}$
be a BBPRE starting with
 $N_0 = N$
pairs. In addition, we will use the notation
 ${\mathrm{P}}_{\boldsymbol{\eta}} \left( \cdot \right)$
and
 ${\mathrm{E}}_{\boldsymbol{\eta}} \left( \cdot \right)$
instead of the conditional probability
 ${\mathrm{P}} \left( \left. \cdot \right| \boldsymbol{\eta} \right)$
and expectation
 ${\mathrm{E}} \left( \left. \cdot \right| \boldsymbol{\eta} \right)$
, respectively. We require the mating function L(x, y, z) to satisfy the following conditions.
-
(C1)
 $L(0, 0, z) = 0$
for all
$z \in \mathbb{R}$
, which ensures that
$x = 0$
,
$y = 0$
is an absorbing state.
-
(C2) L(x, y, z) is superadditive, that is, for any
$x, y, u, v \in \mathbb{N}_0$
and
$z \in \mathbb{R}$
,
\begin{align*} L(x + u, y + v, z) \geq L(x, y, z) + L(u, v, z). \end{align*}
-
(C3) There is a function
$ g(x, y, z)\,:\, \mathbb{R}_{\geq 0} \times \mathbb{R}_{\geq 0} \times \mathbb{R} \rightarrow \mathbb{R}_{\geq 0} $
that is Lipschitz with respect to (x, y), that is, there is a measurable function
$ \lambda(z)\,:\, \mathbb{R} \rightarrow \mathbb{R}_{> 0} $
such that for any
$x, y, u, v \in \mathbb{R}_{\geq 0}$
and
$z \in \mathbb{R}$
,
\begin{align*} \lvert{g(x, y, z) - g(u, v, z)}\rvert \leq \lambda(z) \left( \lvert{x - u}\rvert + \lvert{y - v}\rvert \right)\!. \end{align*}
-
(C4)
$g(t x, t y, z) = t g(x, y, z)$
for all
$t \geq 0$
,
$x, y \in \mathbb{R}_{\geq 0}$
, and
$z \in \mathbb{R}$
. -
(C5) There are a measurable function
$ \rho(z)\,:\, \mathbb{R} \rightarrow \mathbb{R}_{> 0} $
and a constant
$0 < \alpha < 1$
such that
\begin{align*} \lvert{ L\left( x, y, z \right) - g\left( x, y, z \right) }\rvert \leq \rho(z) \left( x + y \right)^{\alpha}\!,\quad x, y \in \mathbb{N}_0,\ z \in \mathbb{R}. \end{align*}


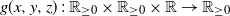
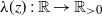
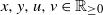


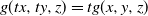


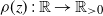


Similar requirements on L(x, y, z) were introduced in [Reference Shklyaev8], where large deviations of BBPRE were studied. Note that the assumptions (C1)–(C5) are quite general and can be satisfied by a wide range of mating functions including the standard ones:
 \begin{align*} L(x, y, z) = \min\!(x\, d_1(z), y\, d_2(z)),\quad d_1, d_2\,:\, \mathbb{R} \rightarrow \mathbb{N}, \end{align*}
with
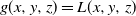 $g(x, y, z) = L(x, y, z)$
.
Let
 $\varphi_n = F_{n, 1}$
and
 $\mu_n = M_{n, 1}$
be the offspring sizes of the first pair. Denote
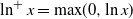 $\ln^+ x = \max\!(0, \ln x)$
,
 $x > 0$
. We now introduce several technical conditions.
-
(C6) There is a constant
$\beta > 1$
such that
$ {\mathrm{E}}_{\boldsymbol{\eta}} \varphi^{\beta}_1, {\mathrm{E}}_{\boldsymbol{\eta}} \mu^{\beta}_1 $
are finite almost surely (a.s.).


Remark 1. Without loss of generality, we assume
 $\alpha$
from (C5) to satisfy the inequality
 $\alpha^{-1} < \beta$
. So, we will use the notation
 $\delta = \alpha^{-1} - 1$
, where
 $1 < 1 + \delta < \beta$
.
-
(C7) For all
$n \geq 1$
, we have
$ {\mathrm{E}} {\left|\xi_n \right|}^{1 + \beta} < \infty $
and
$ {\mathrm{E}} {\left|\zeta_n \right|}^{1 + \beta} < \infty, $
where
\begin{align*} \xi_n &= \ln g \big( {\mathrm{E}}_{\boldsymbol{\eta}} \varphi_n, {\mathrm{E}}_{\boldsymbol{\eta}} \mu_n, \eta_n \big), \quad \zeta_n = \ln^{+} \big( \omega^1_n + \omega^2_n + \omega^3_n \big), \\[3pt] \omega^1_n &= \lambda^{1 + \delta}(\eta_n) + \rho^{1 + \delta}(\eta_n), \quad \omega^2_n = {\mathrm{E}}_{\boldsymbol{\eta}} \varphi_n + {\mathrm{E}}_{\boldsymbol{\eta}} \mu_n, \\[3pt] \omega^3_n &= {\mathrm{E}}_{\boldsymbol{\eta}} \left| { \varphi_n - {\mathrm{E}}_{\boldsymbol{\eta}} \varphi_n }\right|^{1 + \delta} + {\mathrm{E}}_{\boldsymbol{\eta}} \left| \mu_n - {\mathrm{E}}_{\boldsymbol{\eta}} \mu_n\right|^{1 + \delta}. \end{align*}


Remark 2. Note that, due to the Minkowski inequality and non-negativity of the terms included in the definition of
 $\omega_n^1$
,
 $\omega_n^2$
, and
 $\omega_n^3$
,
 $ {\mathrm{E}} {\left|\zeta_n \right|}^{1 + \beta} $
is finite if the moments
 \begin{align*} {\mathrm{E}} \left( \ln^{+} \lambda(\eta_n) \right)^{1 + \beta}, \ {\mathrm{E}} \left( \ln^{+} \rho(\eta_n) \right)^{1 + \beta}, \ &{\mathrm{E}} \left( \ln^{+} {\mathrm{E}}_{\boldsymbol{\eta}} \varphi_n \right)^{1 + \beta}, \ {\mathrm{E}} \left( \ln^{+} {\mathrm{E}}_{\boldsymbol{\eta}} \mu_n \right)^{1 + \beta}, \\[3pt] {\mathrm{E}} \left( \ln^{+} {\mathrm{E}}_{\boldsymbol{\eta}} \left| { \varphi_n - {\mathrm{E}}_{\boldsymbol{\eta}} \varphi_n }\right|^{1 + \delta} \right)^{1 + \beta}, \ &{\mathrm{E}} \left( \ln^{+} {\mathrm{E}}_{\boldsymbol{\eta}} \left| { \mu_n - {\mathrm{E}}_{\boldsymbol{\eta}} \mu_n }\right|^{1 + \delta} \right)^{1 + \beta} \end{align*}
are finite.
Under these conditions, we introduce the notation
 $\sigma^2 = \mathrm{Var} \left( \xi_n \right)$
and consider the random walk
 $S_n = \sum_{i = 1}^{n} \xi_n$
,
 $S_0 = 0$
, associated with the BBPRE. We require its increments to satisfy the following condition.
-
(C8) The process
$N_n$
is critical, that is,
${\mathrm{E}} \xi_n = 0$
.


Remark 3. Under assumptions (C3)–(C6), condition (C8) is equivalent to the classical definition of criticality, that is,
 \begin{align*} \xi_n = \lim_{ k \to \infty } \ln \frac{ {\mathrm{E}} \left( \left. N_n \right| N_{n - 1} = k, \boldsymbol{\eta} \right) }{ k },\quad {\mathrm{E}} \xi_n = 0. \end{align*}
The proof of this fact is given in Section 3.
We are now ready to introduce the extinction moment
 $\tau_N$
of a BBPRE:
 \begin{align*} \tau_N = \min\{ n \in \mathbb{N} \ \colon N_n = 0 \}, \quad N_0 = N. \end{align*}
Further, we will omit the subscript N and denote the extinction moment by
 $\tau = \tau_N$
.
An asymptotic behavior of
 $\tau$
for a bisexual branching process with large initial number of pairs but without environment was provided in [Reference Abdiushev9] for the subcritical case. The critical case of a Galton–Watson branching process was studied in [Reference Lamperti10], while the case with the environment was recently considered in [Reference Afanasev11].
In this work we study the asymptotic behavior of
 $\tau$
for a critical BBPRE starting with a large initial number of pairs
 $N_0 = N$
(Theorem 1). Section 2 contains the proof of Theorem 1. Section 3 provides auxiliary Lemmas 7, 8, and 9 used in the proof, as well as the proof of Remark 3.
2. Main results
Theorem 1. Let
 $N_n$
be a critical BBPRE with
 $N_0 = N$
pairs satisfying conditions (C1)–(C8). Then the extinction moment
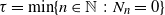 $ \tau = \min\{ n \in \mathbb{N} \ \colon N_n = 0 \} $
satisfies the relation
 \begin{align*} \frac{ \tau }{ \ln^2 N } \xrightarrow[N \rightarrow \infty]{\mathrm{D}} \chi, \end{align*}
where
 $\chi$
is a random variable with density
 \begin{align*} p_{\chi}(t) = \frac{1}{\sqrt{2 \pi \sigma^2 t^3}} \exp\!\left( -\frac{1}{2 \sigma^2 t} \right) I\{ t \geq 0 \},\quad \sigma^2 = \mathrm{Var} ( \xi_n ). \end{align*}
Proof. Consider the random walk
 $S_n = \sum_{i = 1}^n \xi_i$
with
 $S_0 = 0$
. This walk is used to represent the branching process
 $N_n$
by the following recurrent sequence:
 \begin{align*} N_{n} = N_k \mathrm{e}^{S_{n} - S_{k}} + \sum_{i = k + 1}^n R_{i} \mathrm{e}^{S_{n} - S_{i}},\quad 0 \leq k < n, \end{align*}
where
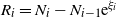 $R_i = N_{i} - N_{i - 1} \mathrm{e}^{\xi_i}$
.
Clearly, the increment
 $S_n - S_i$
is independent of
 $R_i$
for all
 $i \leq n$
. We are now ready to estimate
 $R_n$
using the following lemma. Note that all subsequent statements will be proved under the assumptions of Theorem 1.
Lemma 1. There is a constant
 $c > 0$
such that
 \begin{align*} {\mathrm{E}}_{\boldsymbol{\eta}} \left| { R_n }\right|^{1 + \delta} \leq c\mathrm{e}^{\zeta_n} {\mathrm{E}}_{\boldsymbol{\eta}} N_{n - 1},\quad n \geq 1. \end{align*}
Proof. Let us use the notation
 \begin{align*} F_n = \sum_{i = 1}^{N_{n - 1}} F_{n, i},\quad M_n = \sum_{i = 1}^{N_{n - 1}} M_{n, i}. \end{align*}
Due to (C6)
 ${\mathrm{E}}_{\boldsymbol{\eta}} \varphi_n$
and
 ${\mathrm{E}}_{\boldsymbol{\eta}} \mu_n$
are finite a.s., and
 $R_n$
can be represented as
 \begin{align*} R_n &= L\left( F_n, M_n, \eta_n \right) - g\left( F_n, M_n, \eta_n \right) \\[3pt] &\quad +\ g\left( F_n, M_n, \eta_n \right) - N_{n - 1} g\left( {\mathrm{E}}_{\boldsymbol{\eta}} \varphi_n, {\mathrm{E}}_{\boldsymbol{\eta}} \mu_n, \eta_n \right)\!. \end{align*}
Using (C5), the first difference can be estimated as
 \begin{align*} {\mathrm{E}}_{\boldsymbol{\eta}} \left|{ L\left( F_n, M_n, \eta_n \right) - g\left( F_n, M_n, \eta_n \right) }\right|^{1 + \delta} &\leq \rho^{1 + \delta}(\eta_n) \, {\mathrm{E}}_{\boldsymbol{\eta}} \left( F_n + M_n \right)^{\alpha (1 + \delta)} \\[3pt] &\leq \rho^{1 + \delta}(\eta_n) \, {\mathrm{E}}_{\boldsymbol{\eta}} N_{n - 1} \left( {\mathrm{E}}_{\boldsymbol{\eta}} \varphi_n + {\mathrm{E}}_{\boldsymbol{\eta}} \mu_n \right)\!. \end{align*}
Using (C3) and (C4), we bound the second difference as
 \begin{align*} &{\mathrm{E}}_{\boldsymbol{\eta}} \left|{ g\left( F_n, M_n, \eta_n \right) - N_{n - 1} g\left( {\mathrm{E}}_{\boldsymbol{\eta}} \varphi_n, {\mathrm{E}}_{\boldsymbol{\eta}} \mu_n, \eta_n \right) }\right|^{1 + \delta} \\[3pt] &\qquad \qquad \qquad \qquad \leq \lambda^{1 + \delta}(\eta_n) \, {\mathrm{E}}_{\boldsymbol{\eta}} \left( \left|{ F_n - N_{n - 1} {\mathrm{E}}_{\boldsymbol{\eta}} \varphi_n }\right| + \left| M_n - N_{n - 1} {\mathrm{E}}_{\boldsymbol{\eta}} \mu_n \right| \right)^{1 + \delta}. \end{align*}
Applying Lemma 8, we bound the last expression by
 \begin{align*} \lambda^{1 + \delta}(\eta_n) \, 2^{\delta} \left( {\mathrm{E}}_{\boldsymbol{\eta}} \left| { F_n - N_{n - 1} {\mathrm{E}}_{\boldsymbol{\eta}} \varphi_n }\right|^{1 + \delta} + {\mathrm{E}}_{\boldsymbol{\eta}} \left| { M_n - N_{n - 1} {\mathrm{E}}_{\boldsymbol{\eta}} \mu_n }\right|^{1 + \delta} \right)\!, \end{align*}
which, by (C6) and Lemma 9, is less than
 \begin{align*} \lambda^{1 + \delta}(\eta_n) \, 2^{\delta} c_{1 + \delta}\, {\mathrm{E}}_{\boldsymbol{\eta}} N_{n - 1} \left( {\mathrm{E}}_{\boldsymbol{\eta}} \left|{ \varphi_n - {\mathrm{E}}_{\boldsymbol{\eta}} \varphi_n }\right|^{1 + \delta} + {\mathrm{E}}_{\boldsymbol{\eta}} \left|{ \mu_n - {\mathrm{E}}_{\boldsymbol{\eta}} \mu_n }\right|^{1 + \delta} \right)\!. \end{align*}
Thus, applying Lemma 8, we bound
 ${\mathrm{E}}_{\boldsymbol{\eta}} \left|{ R_n }\right|^{1 + \delta}$
as
 \begin{align*} {\mathrm{E}}_{\boldsymbol{\eta}} \left|{ R_n }\right|^{1 + \delta} \leq c\mathrm{e}^{\zeta_n} {\mathrm{E}}_{\boldsymbol{\eta}} N_{n - 1},\quad n \geq 1, \end{align*}
where
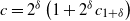 $c = 2^{\delta} \left( 1 + 2^{\delta} c_{1 + \delta} \right)$
.
Lemma 2. The inequality
 \begin{align*} {\mathrm{E}}_{\boldsymbol{\eta}} N_n \leq \mathrm{e}^{\xi_n} {\mathrm{E}}_{\boldsymbol{\eta}} N_{n - 1} \end{align*}
holds for all
 $n \geq 1$
.
Proof. Again, due to (C6), the
 $\xi_n$
are finite a.s. Let us fix
 $\boldsymbol{\eta}$
and consider the sequence
 \begin{align*} b^n_m = \frac{ {\mathrm{E}}_{\boldsymbol{\eta}} \left( \left. N_n \right| N_{n - 1} = m \right) }{ m },\quad m \geq 1. \end{align*}
We will show that
 $b^n_m \leq \mathrm{e}^{\xi_n}$
for all
 $m \geq 1$
.
Let us assume the opposite, that is, there is
 $m' \geq 1$
such that
 $b^n_{m'} > \mathrm{e}^{\xi_n}$
. Similarly to the previous lemma, we will use the notation
 \begin{align*} F_n^m = \sum_{i = 1}^{m} F_{n, i}, \quad M_n^m = \sum_{i = 1}^{m} M_{n, i}. \end{align*}
Then, using (C2), we get
 \begin{align*} {\mathrm{E}} \left( \left. N_n \right| N_{n - 1} = 2m, \boldsymbol{\eta} \right) &= {\mathrm{E}}_{\boldsymbol{\eta}} L\big( F_n^{2m}, M_n^{2m}, \eta_{n} \big) \\[3pt] &\geq {\mathrm{E}}_{\boldsymbol{\eta}} L\left( F_n^m, M_n^m, \eta_{n} \right) \cdot 2,\quad m \geq 1, \end{align*}
and, thus,
 $b^n_{2^k m'} > \mathrm{e}^{\xi_n}$
for all
 $k \geq 1$
, and
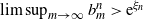 $\limsup_{m \rightarrow \infty} b^n_m > \mathrm{e}^{\xi_n}$
.
At the same time, we will show that
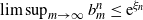 $\limsup_{m \rightarrow \infty} b^n_m \leq \mathrm{e}^{\xi_n}$
, which will lead us to a contradiction. Indeed,
 \begin{align*} b^n_m \leq \frac{ {\mathrm{E}}_{\boldsymbol{\eta}} \left|{ L\left( F_n^m, M_n^m, \eta_n \right) - g\left( F_n^m, M_n^m, \eta_n \right) }\right| }{ m } + \frac{ {\mathrm{E}}_{\boldsymbol{\eta}} g\left( F_n^m, M_n^m, \eta_n \right) }{ m }. \end{align*}
Using (C5) and Jensen’s inequality, the first term can be bounded by
 \begin{align*} \rho(\eta_n) \frac{ {\mathrm{E}}_{\boldsymbol{\eta}} ^{\alpha} \left( F_n^m + M_n^m \right) }{ m } = \rho(\eta_n) \frac{ {\mathrm{E}}_{\boldsymbol{\eta}} ^{\alpha} \left( \varphi_n + \mu_n \right) }{ m^{1 - \alpha} }. \end{align*}
Now, using (C4), the second term can be replaced by
 \begin{align*} \frac{ {\mathrm{E}}_{\boldsymbol{\eta}} g\left( F_n^m, M_n^m, \eta_n \right) - g\left( m {\mathrm{E}}_{\boldsymbol{\eta}} \varphi_n, m {\mathrm{E}}_{\boldsymbol{\eta}} \mu_n, \eta_n \right) }{ m } + g\left( {\mathrm{E}}_{\boldsymbol{\eta}} \varphi_n, {\mathrm{E}}_{\boldsymbol{\eta}} \mu_n, \eta_n \right)\!. \end{align*}
Using (C3), (C6), and Lemma 9, we bound the first part by
 \begin{align*} &\lambda(\eta_n) \frac{ {\mathrm{E}}_{\boldsymbol{\eta}} \left|{ F_n^m - m {\mathrm{E}}_{\boldsymbol{\eta}} \varphi_n }\right| + {\mathrm{E}}_{\boldsymbol{\eta}} \left| { M_n^m - m {\mathrm{E}}_{\boldsymbol{\eta}} \mu_n }\right| }{ m } \\[3pt] &\qquad \qquad \qquad \qquad \leq \frac{ \lambda(\eta_n) c_{1 + \delta}^{\alpha} }{ m^{1 - \alpha} } \left( {\mathrm{E}}_{\boldsymbol{\eta}} ^{\alpha} \lvert{ \varphi_n - {\mathrm{E}}_{\boldsymbol{\eta}} \varphi_n }\rvert^{1 + \delta} + {\mathrm{E}}_{\boldsymbol{\eta}} ^{\alpha} \left|{ \mu_n - {\mathrm{E}}_{\boldsymbol{\eta}} \mu_n }\right|^{1 + \delta} \right)\!. \end{align*}
Finally, combining the previous bounds, we get
 \begin{align*} b^n_m = g\left({\mathrm{E}}_{\boldsymbol{\eta}} \varphi_n , {\mathrm{E}}_{\boldsymbol{\eta}} \mu_n, \eta_n \right) + O( m^{\alpha - 1} ) = \mathrm{e}^{\xi_n} + o(1), \quad m \rightarrow \infty, \end{align*}
which leads us to the contradiction.
We now estimate the accumulated error of approximation of
 $N_n$
by
 $N \mathrm{e}^{S_n}$
using the following lemma.
Lemma 3. There is a constant
 $c > 0$
such that, for all
 $n \geq 1$
,
 \begin{align*} {\mathrm{E}}_{\boldsymbol{\eta}} \left|{ N_n - N \mathrm{e}^{S_n} }\right|^{1 + \delta} \leq cn^{\delta} N \mathrm{e}^{S_n} \sum_{i = 1}^n \mathrm{e}^{ \zeta_i - \xi_i + \delta \left( S_n - S_i \right) }. \end{align*}
Proof. As seen, the difference
 $N_n - N \mathrm{e}^{S_n}$
can be rewritten as
 \begin{align*} N_n - N \mathrm{e}^{S_n} = \sum_{i = 1}^n R_i \mathrm{e}^{S_n - S_i}. \end{align*}
Consequently, using Lemmas 8, 1, and 2, we get
 \begin{align*} {\mathrm{E}}_{\boldsymbol{\eta}} \left| N_{n} - N \mathrm{e}^{S_n} \right|^{1 + \delta} &\leq n^{\delta} \sum_{i = 1}^n {\mathrm{E}}_{\boldsymbol{\eta}} \left(\left| { R_i }\right|^{1 + \delta} \mathrm{e}^{ \left( 1 + \delta \right) \left( S_n - S_i \right) } \right) \\[5pt] &\leq n^{\delta} \sum_{i = 1}^n \mathrm{e}^{ \left( 1 + \delta \right) \left( S_n - S_i \right) } \, {\mathrm{E}}_{\boldsymbol{\eta}} \left| { R_i }\right|^{1 + \delta} \\[5pt] &\leq cn^{\delta} \sum_{i = 1}^n \mathrm{e}^{ \left( 1 + \delta \right) \left( S_n - S_i \right) } \mathrm{e}^{\zeta_i} \, {\mathrm{E}}_{\boldsymbol{\eta}} \left( N_{i - 1} \right) \\[5pt] &\leq cn^{\delta} N \mathrm{e}^{S_n} \sum_{i = 1}^n \mathrm{e}^{\zeta_i - \xi_i + \delta \left( S_n - S_i \right) }. \end{align*}
We are now ready to connect the extinction moment of the process
 $N_n$
with the hitting time of the corresponding random walk. Let
 \begin{align*} \theta_N = \min\left\{ n \geq 1 \, \colon S_n \leq \ln^{\gamma} N - \ln N \right\}\!,\quad \gamma = \frac{ 2 }{ 1 + \beta } < 1. \end{align*}
Further, similarly to the notation of the extinction moment
 $\tau$
, we will omit the subscript N and denote
 $\theta = \theta_N$
. Firstly, we will write a proof of the well-known fact that
 $\theta$
is of order
 $\ln^2 N$
. Secondly, we will show that
 $\theta$
is close to
 $\tau$
.
Lemma 4. As
 $N \rightarrow \infty$
,
 \begin{align*} \frac{ \theta }{ \ln^2 N } \xrightarrow[]{\mathrm{D}} \chi, \end{align*}
where
 $\chi$
is a random variable with density
 \begin{align*} p_{\chi}(t) = \frac{1}{\sqrt{2 \pi \sigma^2 t^3}} \exp\!\left( -\frac{1}{2 \sigma^2 t} \right) I\{ t > 0 \},\quad \sigma^2 = \mathrm{Var} \left( \xi_n \right)\!. \end{align*}
Proof. Due to (C7), the variance
 $\sigma^2$
is finite. By the definition of
 $\theta$
, one can state that
 \begin{align*} {\mathrm{P}} \left(\frac{ \theta }{ \ln^2 N } \leq x \right) = {\mathrm{P}} \left( \frac{ \min_{i \leq x \ln^2 N} S_i }{ \sigma \sqrt{x \ln^2 N} } \leq \frac{ \ln^{\gamma} N - \ln N }{ \sigma \sqrt{x \ln^2 N} } \right)\!, \end{align*}
where
 $x > 0$
. Since
 $\sigma^2 < \infty$
and
 ${\mathrm{E}} \xi_n = 0$
by (C8), applying Donsker’s invariance principle (relation (9.2) of [Reference Billingsley12]) to the random walk
 $\{ S_n,\ n \geq 1 \}$
, we have
 \begin{align*} \frac{ \min_{i \leq n} S_i }{ \sigma \sqrt{n} } \xrightarrow[n \rightarrow \infty]{\mathrm{D}} \inf_{t \in [0, 1]} W_t, \end{align*}
where
 $W_t$
is a standard Brownian motion. At the same time,
 \begin{align*} \frac{ \ln^{\gamma} N - \ln N }{ \sigma \sqrt{x \ln^2 N} } \xrightarrow[N \rightarrow \infty]{} \frac{-1}{\sigma \sqrt{x}}. \end{align*}
Thus, by Slutsky’s theorem, we obtain
 \begin{align*} \frac{ \min_{i \leq x \ln^2 N} S_i }{ \sigma \sqrt{x \ln^2 N} } \frac{ \ln N }{ \ln N - \ln^{\gamma} N } \xrightarrow[N \rightarrow \infty]{\mathrm{D}} \inf_{t \in [0, 1]} W_t, \end{align*}
for any
 $x > 0$
. Since
 $\inf_{t \in [0, 1]} W_t$
is an absolutely continuous random variable with the support
 $(\!-\infty, 0]$
, the weak convergence is equivalent to the pointwise convergence of the cumulative distribution functions, which gives us
 \begin{align*} {\mathrm{P}} \left(\frac{\theta}{\ln^2 N} \leq x \right) \xrightarrow[N \rightarrow \infty]{} {\mathrm{P}} \left( \inf_{t \in [0, 1]} W_t \leq \frac{-1}{\sigma \sqrt{x}} \right)\!, \end{align*}
which is equivalent to the statement of the lemma.
We will now show that
 $\theta$
approximates
 $\tau$
. Namely, we will prove that
 $N_n$
goes extinct soon after the moment
 $\theta$
.
Lemma 5. For any
 $\varepsilon > 0$
and
 $k = \lfloor \varepsilon \ln^2 N \rfloor$
, we have
 \begin{align*} {\mathrm{P}} \left( N_{\theta + k} > 0 \right) \rightarrow 0,\quad N \rightarrow \infty. \end{align*}
Proof. By the law of total probability, we have
 \begin{align} {\mathrm{P}}_{\boldsymbol{\eta}} \big( N_{\theta + k} > 0 \big) &\leq {\mathrm{P}}_{\boldsymbol{\eta}} \big( \left. N_{\theta + k} \geq 1 \right| N_{\theta} > 2 N \mathrm{e}^{S_{\theta}} \big) {\mathrm{P}}_{\boldsymbol{\eta}} \big( N_{\theta} > 2 N \mathrm{e}^{S_{\theta}} \big) \nonumber \\[3pt] &+\, {\mathrm{P}}_{\boldsymbol{\eta}} \big( \left. N_{\theta + k} \geq 1 \right| N_{\theta} \leq 2 N \mathrm{e}^{S_{\theta}} \big) {\mathrm{P}}_{\boldsymbol{\eta}} \big( N_{\theta} \leq 2 N \mathrm{e}^{S_{\theta}} \big) \nonumber \\[3pt] &\leq {\mathrm{P}}_{\boldsymbol{\eta}} \big( N_{\theta} > 2 N \mathrm{e}^{S_{\theta}} \big) + {\mathrm{P}}_{\boldsymbol{\eta}} \big( \left. N_{\theta + k} \geq 1 \right| N_{\theta} = \lfloor 2 N \mathrm{e}^{S_{\theta}} \rfloor \big). \end{align}
Note that
 $S_{\theta} - S_i \leq 0$
for all
 $i \leq \theta$
, due to the definition of
 $\theta$
. Consequently, using Markov’s inequality, Lemma 3 and this fact, we bound the first term of the right-hand side of (3) in the following way:
 \begin{align} \begin{split} {\mathrm{P}}_{\boldsymbol{\eta}} \big( N_{\theta} > 2 N \mathrm{e}^{ S_{\theta} } \big) &\leq {\mathrm{P}}_{\boldsymbol{\eta}} \big( \lvert{ N_{\theta} - N \mathrm{e}^{S_{\theta}} }\rvert^{1 + \delta} > N^{1 + \delta} \mathrm{e}^{ \left( 1 + \delta \right) S_{\theta} } \big) \\[3pt] &\leq \frac{ 1 }{ N^{1 + \delta} \mathrm{e}^{ \left( 1 + \delta \right) S_{\theta}} } {\mathrm{E}}_{\boldsymbol{\eta}} \big| { N_{\theta} - N \mathrm{e}^{S_{\theta}} }\big|^{ 1 + \delta } \\[3pt] &\leq \frac{ c\, \theta^{1 + \delta} }{ N^{\delta} \mathrm{e}^{ \delta S_{\theta} } } \frac{ \sum_{i = 1}^{\theta} \mathrm{e}^{\zeta_i - \xi_i} }{ \theta }. \end{split} \end{align}
By the definition of
 $\theta$
,
 \begin{equation} \mathrm{e}^{ \ln^{\gamma} N + \xi_{\theta} } \leq N \mathrm{e}^{S_{\theta}} \leq \mathrm{e}^{ \ln^{\gamma} N }. \end{equation}
Thus, the right-hand side of (4) can be bounded by
 \begin{align*} c\, \theta^{1 + \delta} \max_{i \leq \theta} \exp\!\left[ \zeta_i - \xi_i - \delta \left( \ln^{\gamma} N + \xi_{\theta} \right) \right]. \end{align*}
Henceforth, we will use the notation
 $\delta' = \delta / 3 > 0$
. Let us prove that
 \begin{equation} {\mathrm{P}} \left( \max_{i \leq \theta} \mathrm{e}^{\zeta_i - \xi_i} > \mathrm{e}^{ \delta' \ln^{\gamma} N } \right) \rightarrow 0,\quad N \rightarrow \infty. \end{equation}
Indeed, let us fix
 $x > 0$
. By the law of total probability, we obtain
 \begin{align*} {\mathrm{P}} \left( \max_{i \leq \theta} \mathrm{e}^{\zeta_i - \xi_i} > \mathrm{e}^{ \delta' \ln^{\gamma} N } \right) &\leq {\mathrm{P}}\, \bigg( \max_{i \leq x \ln^2 N} \mathrm{e}^{\zeta_i - \xi_i} > \mathrm{e}^{ \delta' \ln^{\gamma} N } \bigg) \\[3pt] &\quad + {\mathrm{P}}\, \big( \vphantom{ \max_{i \leq x \ln^2 N} \mathrm{e}^{\zeta_i - \xi_i} } \theta > x \ln^2 N \big). \end{align*}
Due to Lemma 4,
 \begin{equation} {\mathrm{P}} \big( \theta > x \ln^2 N \big) \rightarrow 1 - F_{\chi}(x),\quad N \rightarrow \infty, \end{equation}
where
 $F_{\chi}(x)$
is the cumulative distribution function of
 $\chi$
. Since
 $\zeta_i - \xi_i$
,
 $i \geq 1$
, are i.i.d. random variables,
 \begin{align*} {\mathrm{P}} \left( \max_{i \leq x \ln^2 N} \mathrm{e}^{ \zeta_i - \xi_i } > \mathrm{e}^{ \delta' \ln^{\gamma} N } \right) \leq 1 - {\mathrm{P}} \big( \vphantom{ \max_{i \leq x \ln^2 N} \mathrm{e}^{ \zeta_i - \xi_i } > \mathrm{e}^{ \delta' \ln^{\gamma} N } } \zeta_1 - \xi_1 \leq \delta' \ln^{\gamma} N \big)^{x \ln^2 N}. \end{align*}
Note that, by (C7) and Lemma 7, we have
 \begin{equation} \ln^2 N\ {\mathrm{P}} \left( \zeta_1 - \xi_1 > \delta' \ln^{\gamma} N \right) \rightarrow 0,\quad N \rightarrow \infty. \end{equation}
Thus, for sufficiently large N, we have
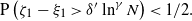 $ {\mathrm{P}} \left( \zeta_1 - \xi_1 > \delta' \ln^{\gamma} N \right) < 1 / 2. $
Thus, applying the bound
 \begin{align*} \ln(1 - p) \geq -2p, \quad p \in [0, 1 / 2] \end{align*}
to
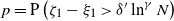 $ p = {\mathrm{P}} \left( \zeta_1 - \xi_1 > \delta' \ln^{\gamma} N \right) $
yields
 \begin{align*} {\mathrm{P}} \left( \max_{i \leq x \ln^2 N} \mathrm{e}^{ \zeta_i - \xi_i } > \mathrm{e}^{ \delta' \ln^{\gamma} N } \right) &\leq 1 - {\mathrm{P}} \big( \vphantom{ \max_{i \leq x \ln^2 N} \mathrm{e}^{ \zeta_i - \xi_i } > \mathrm{e}^{ \delta' \ln^{\gamma} N } } \zeta_1 - \xi_1 \leq \delta' \ln^{\gamma} N \big)^{x \ln^2 N} \\[1pt] &= 1 - \exp\!\left( x \ln^2 N\ \ln\left[ 1 - {\mathrm{P}} \left( \zeta_1 - \xi_1 > \delta' \ln^{\gamma} N \right) \right] \right) \\[3pt] &\leq 1 - \exp\!\left( -2 x \ln^2 N\ {\mathrm{P}} \left( \zeta_1 - \xi_1 > \delta' \ln^{\gamma} N \right) \right)\!, \end{align*}
which, in combination with (8), implies that
 \begin{align*} {\mathrm{P}} \left( \max_{i \leq x \ln^2 N} \mathrm{e}^{ \zeta_i - \xi_i } > \mathrm{e}^{ \delta' \ln^{\gamma} N } \right) \to 0, \ N \to \infty. \end{align*}
Thus,
 \begin{align*} \limsup_{N \rightarrow \infty} {\mathrm{P}} \left( \max_{i \leq \theta} \mathrm{e}^{\zeta_i - \xi_i} > \mathrm{e}^{ \delta' \ln^{\gamma} N } \right) \leq 1 - F_{\chi}(x), \end{align*}
and, taking
 $x > 0$
large enough, we arrive at (6).
Similarly, for any
 $x > 0$
, one can write
 \begin{align*} {\mathrm{P}} \left( \mathrm{e}^{ -\delta \xi_{\theta} } > \mathrm{e}^{ \delta' \ln^{\gamma} N } \right) &\leq {\mathrm{P}} \left( 3 \xi_{\theta} \leq -\ln^{\gamma} N,\, \theta \leq x \ln^2 N \right) \\[3pt] &\quad + {\mathrm{P}} \left( \theta > x \ln^2 N \right)\!. \end{align*}
The first term on the right-hand side can be bounded by
 \begin{align*} \sum_{i = 1}^{x \ln^2 N} {\mathrm{P}} \left( 3 \xi_i \leq -\ln^{\gamma} N \right) \leq x \ln^2 N\ {\mathrm{P}} \left( 3 \xi_1 \leq -\ln^{\gamma} N \right)\!. \end{align*}
Applying Lemma 7 to the last expression and using (7), we get
 \begin{align*} \limsup_{N \rightarrow \infty} {\mathrm{P}} \left( \mathrm{e}^{ -3 \xi_{\theta} } > \mathrm{e}^{ \ln^{\gamma} N } \right) \leq 1 - F_{\chi}(x), \end{align*}
and, taking
 $x > 0$
large enough, we prove that
 \begin{equation} {\mathrm{P}} \left( \mathrm{e}^{ -\delta \xi_{\theta} } > \mathrm{e}^{ \delta' \ln^{\gamma} N } \right) \rightarrow 0,\quad N \rightarrow \infty. \end{equation}
Since
 $\theta$
is of order
 $\ln^2 N$
by Lemma 4, for any
 $x > 0$
, we obtain
 \begin{equation} {\mathrm{P}} \left( \theta^{1 + \delta} > x \, \mathrm{e}^{ \delta' \ln^{\gamma} N } \right) \rightarrow 0,\quad N \rightarrow \infty, \end{equation}
by Slutsky’s theorem. Thus, we have
 \begin{align*} & {\mathrm{P}} \left( \theta^{1 + \delta} \max_{i \leq \theta} \exp\!\left[ \zeta_i - \xi_i - \delta \left( \ln^{\gamma} N + \xi_{\theta} \right) \right] > x \right) \\[3pt] &\quad \leq {\mathrm{P}} \Big( \vphantom{ \max_{i \leq \theta} \mathrm{e}^{\zeta_i - \xi_i} > \mathrm{e}^{ \delta' \ln^{\gamma} N } } \mathrm{e}^{ -\delta \xi_{\theta} } > \mathrm{e}^{ \delta' \ln^{\gamma} N } \Big) + {\mathrm{P}} \Big( \max_{i \leq \theta} \mathrm{e}^{\zeta_i - \xi_i} > \mathrm{e}^{ \delta' \ln^{\gamma} N } \Big) + {\mathrm{P}} \Big( \vphantom{ \max_{i \leq \theta} \mathrm{e}^{\zeta_i - \xi_i} > \mathrm{e}^{ \delta' \ln^{\gamma} N } } \theta^{1 + \delta} > x \, \mathrm{e}^{ \delta' \ln^{\gamma} N } \Big), \end{align*}
which, in combination with (6), (9), and (10), proves the convergence
 \begin{equation} {\mathrm{P}}_{\boldsymbol{\eta}} \left( N_{\theta} > 2 N \mathrm{e}^{ S_{\theta} } \right) \xrightarrow[]{\mathrm{D}} 0,\quad N \rightarrow \infty. \end{equation}
We now consider the second term of the right-hand side of (3). Using Markov’s inequality, Lemma 2 and (5), we obtain
 \begin{align} {\mathrm{P}}_{\boldsymbol{\eta}} \left( \left. N_{\theta + k} \geq 1 \right| N_{\theta} = \lfloor 2 N \mathrm{e}^{S_{\theta}} \rfloor \right) &\leq \min_{i \leq k} {\mathrm{E}}_{\boldsymbol{\eta}} \left( \left. N_{\theta + i} \right| N_{\theta} = \lfloor 2 N \mathrm{e}^{S_{\theta}} \rfloor \right) \nonumber \\[3pt] &\leq cN \mathrm{e}^{S_{\theta}} \exp\Big( \min_{i \leq k} ( S_{\theta + i} - S_{\theta} ) \Big) \\[3pt] &\leq c\exp\Big( \ln^{\gamma} N + \min_{i \leq k} \left( S_{\theta + i} - S_{\theta} \right) \Big). \nonumber \end{align}
We will now prove that
 \begin{equation} \exp\Big( \ln^{\gamma} N + \min_{i \leq k} \left( S_{\theta + i} - S_{\theta} \right) \Big) \xrightarrow[]{\mathrm{D}} 0,\quad N \rightarrow \infty. \end{equation}
Indeed, by Donsker’s invariance principle and the strong Markov property, for
 $x < 0$
, we get
 \begin{align*} {\mathrm{P}} \left( \min_{i \leq k} \left( S_{\theta + i} - S_{\theta} \right) > x \sigma \sqrt{k} \right) \rightarrow 1 - F(x),\quad N \rightarrow \infty, \end{align*}
where F(x) is the cumulative distribution function of
 $\inf_{t \in [0, 1]} W_t$
. But, for any
 $x, t < 0$
, there is N’ such that
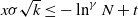 $x \sigma \sqrt{k} \leq - \ln^{\gamma} N + t$
for all
 $N \geq N'$
. Here we used that
 $ k = \lfloor \varepsilon \ln^2 N \rfloor $
and
 $\gamma < 1$
. Therefore,
 \begin{align*} \limsup_{N \rightarrow \infty} {\mathrm{P}} \Big( \ln^{\gamma} N + \min_{i \leq k} \left( S_{\theta + i} - S_{\theta} \right) > t \Big) \leq 1 - \sup_{x < 0} F(x) = 0. \end{align*}
Thus, we arrive at (13), which, in combination with (12), proves the convergence
 \begin{equation} {\mathrm{P}}_{\boldsymbol{\eta}} \left( \left. N_{\theta + k} \geq 1 \right| N_{\theta} = \lfloor 2 N \mathrm{e}^{ S_{\theta} } \rfloor \right) \xrightarrow[]{\mathrm{D}} 0,\quad N \rightarrow \infty. \end{equation}
Thus, summing up (11) and (14), and applying Slutsky’s theorem, we get
 \begin{align*} {\mathrm{P}}_{\boldsymbol{\eta}} \left( N_{\theta + k} > 0 \right) \xrightarrow[]{\mathrm{D}} 0,\quad N \rightarrow \infty. \end{align*}
Therefore, by the definition of weak convergence, we have
 \begin{align*} {\mathrm{P}} \left( N_{\theta + k} > 0\right) = {\mathrm{E}} \left( {\mathrm{P}}_{\boldsymbol{\eta}} \left( N_{\theta + k} > 0 \right) \right) \rightarrow 0,\quad N \rightarrow \infty, \end{align*}
Similarly, we prove that
 $N_n$
is still non-zero at the moment
 $\theta$
.
Lemma 6. The convergence
 \begin{align*} {\mathrm{P}} \left( N_{\theta} > 0 \right) \rightarrow 1,\quad N \rightarrow \infty, \end{align*}
is valid.
Proof. Let us consider the probability of the opposite event. Using Markov’s inequality and Lemma 3, we get
 \begin{align*} {\mathrm{P}}_{\boldsymbol{\eta}} \left( N_{\theta} = 0 \right) &= {\mathrm{P}}_{\boldsymbol{\eta}} \left( N_{\theta} - N \mathrm{e}^{ S_{\theta} } \leq -N \mathrm{e}^{ S_{\theta} } \right) \\[5pt] &\leq {\mathrm{P}}_{\boldsymbol{\eta}} \left( \lvert N_{\theta} - N \mathrm{e}^{S_{\theta}}\rvert^{1 + \delta} \geq N^{1 + \delta} \mathrm{e}^{ \left( 1 + \delta \right) S_{\theta} } \right)\!. \end{align*}
The last expression appears in (4). As seen from the proof of Lemma 5, it converges to zero in distribution. By the same reasoning as before, we have the required convergence.
Finally, we are in a position to complete the proof of Theorem 1. On the one hand, for a fixed
 $x \in \mathbb{R}$
, we obtain
 \begin{align*} {\mathrm{P}} \big( \tau \leq x \ln^2 N\big) &\leq {\mathrm{P}} \big( \big\{ \theta \leq x \ln^2 N \big\} \cup \left\{ \tau \leq \theta \right\} \big) \\[5pt] &\leq {\mathrm{P}} \big( \theta \leq x \ln^2 N \big) + {\mathrm{P}} \left( N_{\theta} = 0 \right)\!.\end{align*}
But, by Lemma 6,
 ${\mathrm{P}} \left( N_{\theta} = 0 \right)$
converges to zero as
 $N \rightarrow \infty$
.
On the other hand, for any
 $\varepsilon > 0$
, we get
 \begin{align*} {\mathrm{P}} \big( \tau \leq x \ln^2 N \big) &\geq {\mathrm{P}} \big( \big\{ \theta \leq (x - \varepsilon) \ln^2 N \big\} \setminus \big\{ \tau \geq \theta + \varepsilon \ln^2 N \big\} \big) \\[3pt] &\geq {\mathrm{P}} \big( \theta \leq (x - \varepsilon) \ln^2 N \big) - {\mathrm{P}} \big( N_{\theta + k} > 0 \big),\end{align*}
where
 $k = \lfloor \varepsilon \ln^2 N \rfloor$
. Again, due to Lemma 5,
 ${\mathrm{P}} \left( N_{\theta + k} > 0 \right)$
converges to zero as
 $N \rightarrow \infty$
.
Thus, taking
 $N \rightarrow \infty$
, and then
 $\varepsilon \rightarrow 0$
, we obtain
 \begin{align*} \lim_{ \varepsilon \to 0 } \lim_{ N \to \infty } {\mathrm{P}} \left(\frac{\theta}{\ln^2 N} \leq x - \varepsilon \right) \leq \lim_{ N \rightarrow \infty } {\mathrm{P}} \left( \frac{ \tau }{ \ln^2 N } \leq x \right) \leq \lim_{ N \rightarrow \infty } {\mathrm{P}} \left( \frac{\theta}{\ln^2 N} \leq x \right)\!, \end{align*}
which proves Theorem 1.
3. Auxiliary results
Lemma 7. (Exercise 1.6.3 of [Reference Durrett13].) Let
 $\xi$
be a random variable with
 ${\mathrm{E}} \xi^{\psi} < \infty$
, where
 $\psi \geq 1$
. Then
 \begin{align*} n^{\psi}\, {\mathrm{P}} \left( \xi > n \right) \rightarrow 0, \end{align*}
as
 $n \rightarrow \infty$
.
Lemma 8. (Minkowski inequality.) For any
 $x_1, \ldots, x_n \geq 0$
and
 $\psi \geq 1$
, the inequality
 \begin{align*} \left(\sum_{i = 1}^n x_i \right)^{\psi} \leq n^{\psi - 1} \sum_{i = 1}^n x_i^{\psi} \end{align*}
holds.
Lemma 9. (Marcinkiewicz–Zygmund inequality, [Reference Marcinkiewicz and Zygmund14].) Let
 $\{ \xi_n \}_{n = 1}^{\infty}$
be a sequence of i.i.d. random variables with
 ${\mathrm{E}} \left|\xi_n\right|^{\psi} < \infty$
, where
 $1 \leq \psi \leq 2$
, and
 ${\mathrm{E}} \xi_n = 0$
for all
 $n \in \mathbb{N}$
. Then there is a constant
 $c_{\psi} > 0$
such that
 \begin{align*} \left( {\mathrm{E}} \left| \sum_{i = 1}^n \xi_i \right| \right)^{\psi} \leq {\mathrm{E}} \left| \sum_{i = 1}^n \xi_i \right|^{\psi} \leq c_{\psi} \sum_{i = 1}^n {\mathrm{E}} \left| \xi_i\right|^{\psi}. \end{align*}
Remark 3. Under assumptions (C3)–(C6), condition (C8) is equivalent to the classical definition of criticality, that is,
 \begin{align*} \xi_n = \lim_{ k \to \infty } \ln \frac{ {\mathrm{E}} \left( \left. N_n \right| N_{n - 1} = k, \boldsymbol{\eta} \right) }{ k },\quad {\mathrm{E}} \xi_n = 0. \end{align*}
Proof. Due to (C6), the
 $\xi_n$
are finite a.s. As Lemma 1 states, under assumptions (C3)–(C5), there is a constant
 $c > 0$
such that
 \begin{align*} {\mathrm{E}}_{\boldsymbol{\eta}} \left|{ R_n }\right|^{1 + \delta} \leq c\mathrm{e}^{\zeta_n} {\mathrm{E}}_{\boldsymbol{\eta}} N_{n - 1},\quad n \geq 1, \end{align*}
where
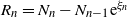 $R_n = N_n - N_{n - 1} \mathrm{e}^{\xi_n}$
. Thus, using Jensen’s inequality and the relation
 $ \delta = \alpha^{-1} - 1, $
we have
 \begin{align*} {\mathrm{E}}_{\boldsymbol{\eta}} \left|{ R_n }\right| \leq \left( c\mathrm{e}^{\zeta_n} {\mathrm{E}}_{\boldsymbol{\eta}} N_{n - 1} \right)^{\alpha}. \end{align*}
As a result, we get
 \begin{align*} \lim_{ k \to \infty } \frac{ {\mathrm{E}} \left(\!\left. R_n \right| N_{n - 1} = k, \boldsymbol{\eta} \right) }{ k } = 0, \end{align*}
which proves that
 \begin{align*} \lim_{ k \to \infty } \frac{ {\mathrm{E}} \left(\!\left. N_n \right| N_{n - 1} = k, \boldsymbol{\eta} \right) }{ k } = \mathrm{e}^{\xi_n}. \end{align*}
Acknowledgements
We wish to thank the anonymous referees for their valuable comments and suggestions that helped to improve the quality of this article.
Funding information
The study was funded within the framework of the HSE University Basic Research Program.
Competing interests
There were no competing interests to declare which arose during the preparation or publication process of this article.



